
Korea Tech Export Deep Dive: Memory Exports +280% YoY, MLCC +31% YoY, and How the AI Hardware Surplus Flows Into Earnings
目录
TL;DR
1. From Surplus Flash Data to Tech Structure: This Report Fills a Critical Gap
2. Memory Exports +280% YoY: Storage Remains the Earnings Backbone of Korean Tech
III. HBM Proxy Indicator: Samsung Electronics’ Ramp Is Starting to Show Up in Materials Flows
IV. MLCC Up 31% YoY: AI Hardware Demand Is Starting to Penetrate Passive Components
V. WFE Exports and Imports Both Strong: Supply Tightness Is Driving Capital Expenditure
VI. Display and Batteries: Providing Breadth, but Not the Pricing Anchor for This Revaluation
7. From “AI Surplus” to “KOSPI Tech EPS”: How Asset Ranking Should Change
8. Three Worldviews: Structural Re-Rating, Strong-Cycle Peak, and Momentum Cooling
9. The 8 Indicators to Watch Next
10. Conclusion: Korea’s Technology Exports Have Moved from Macro Surplus to Hardware Profit Verification
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Goldman Sachs’ Korea tech export tracker fills in the structure behind June’s surplus: memory exports have exceeded 200% YoY for five consecutive months, while DRAM, SSD, MLCC, and WFE are strengthening in tandem. The surplus trade is now moving into earnings verification. The key question is whether AI hardware demand can continue to flow through to pricing, capex, and EPS upgrades.
TL;DR
The core of Korea’s June tech exports is memory strength large enough to reprice earnings. Korea’s memory exports tracked by Goldman Sachs rose 280% YoY in June, exceeding 200% for five consecutive months; DRAM exports rose 385% YoY, NAND chips 301% YoY, and SSDs 355% YoY. This shows AI servers, storage pricing, and product-mix upgrades are simultaneously driving Korean semiconductor revenue. A low base explains only a small part of the YoY elasticity.
HBM verification is starting to move from order slogans into material proxy indicators. Goldman uses imports of plastic film from Japan into Samsung Electronics’ Hwaseong and Pyeongtaek sites as a proxy for TC-NCF materials and HBM shipments. In May, those imports rose 76% YoY, and were up 61% YoY from January to May. This metric cannot be equated directly with Samsung Electronics’ HBM share, but it shows Samsung’s HBM ramp is not merely narrative; material inflows are already visible in customs data.
MLCC +31% YoY is the most important diffusion signal in this report. Korea’s MLCC exports accelerated notably in June and also maintained double-digit growth on a quarterly basis. Goldman expects Samsung Electro-Mechanics’ 2Q26 MLCC revenue to grow 22% YoY, mainly driven by AI server and automotive MLCCs. MLCC exports are far smaller than memory exports, but they prove AI hardware demand is spreading from the main storage chain into power delivery, filtering, signal integrity, and high-reliability components.
WFE exports and imports strengthened together, showing this cycle has capex support. Korea’s WFE equipment exports rose 79% YoY in June, while imports rose 54% YoY; in 2Q26, exports and imports rose 69% and 73% YoY, respectively. Strong imports reflect increased capex by Korean memory makers to ease tight supply; strong exports show global semiconductor capacity buildout is still progressing. As long as WFE does not stall, the storage upcycle looks more like a supply-bottleneck cycle than a one-off pricing pulse.
The implication for KOSPI is a shift from the “AI surplus trade” to a “tech EPS upgrade trade.” June’s total exports and surplus had already opened room for macro re-rating. This Goldman report further shows that the surplus quality comes from high-value-added tech chains. Asset ranking should start with memory leaders, then move to Samsung Electro-Mechanics, WFE equipment and materials, OLED, and battery diffusion elasticity, and only then to index-level KRW strength, foreign inflows, and declining KOSPI risk premium.
The biggest risk is directly extrapolating high YoY growth into a risk-free long cycle. June had 1.5 more working days than last year, and both low base and price increases amplify YoY growth. The HBM proxy only covers material inflows into Samsung Electronics and does not equal full order conversion. Strong WFE imports could also create future supply pressure. Going forward, the key variables to watch are whether July exports, DRAM/NAND contract prices, Samsung HBM qualification, MLCC pricing, WFE orders, and Korea tech EPS revisions continue to move together.
1. From Surplus Flash Data to Tech Structure: This Report Fills a Critical Gap
Korea’s June export data had already delivered the macro conclusion: exports were strong, imports recovered but did not absorb the export increment, and surplus expansion put Korea back into the AI hardware surplus trading framework. The new incremental point is that Goldman breaks down Korea’s tech exports, allowing the market to judge which profit pool this surplus is actually coming from.
Korea Export Deep Dive: June Exports +70.9% YoY, and How the AI Hardware Surplus Opens Room for KOSPI Re-Rating
The headline flash answers “did Korean exports beat expectations?” The tech export structure answers “can this beat enter the income statement?” If export strength mainly comes from one-off ship deliveries or low-margin categories, the market will at most price surplus repair and FX stability. If export strength comes from memory, HBM, SSDs, MLCCs, and WFE, asset pricing will point directly to SK hynix, Samsung Electronics, Samsung Electro-Mechanics, equipment materials, and broader Korean tech EPS.
Goldman’s report title includes two key phrases: ATH memory and MLCC exports. ATH points to memory exports reaching a new high, while MLCC represents AI hardware demand spreading from core chips to passive components. Together, they show Korean tech exports are moving from single-point storage strength toward broader hardware-system strength.
The report also provides one adjustment that needs to be made: June 2026 had 22.5 working days, higher than 21 days in June 2025, adding 1.5 working days. This amplifies YoY growth. When handling this data set, investors should not focus only on the YoY figures themselves, but also on MoM trends, quarterly YoY growth, category breadth, and whether company revenue expectations are consistent. The good news is that June was not only strong on YoY terms; memory, MLCC, and WFE also provided MoM or quarterly validation.
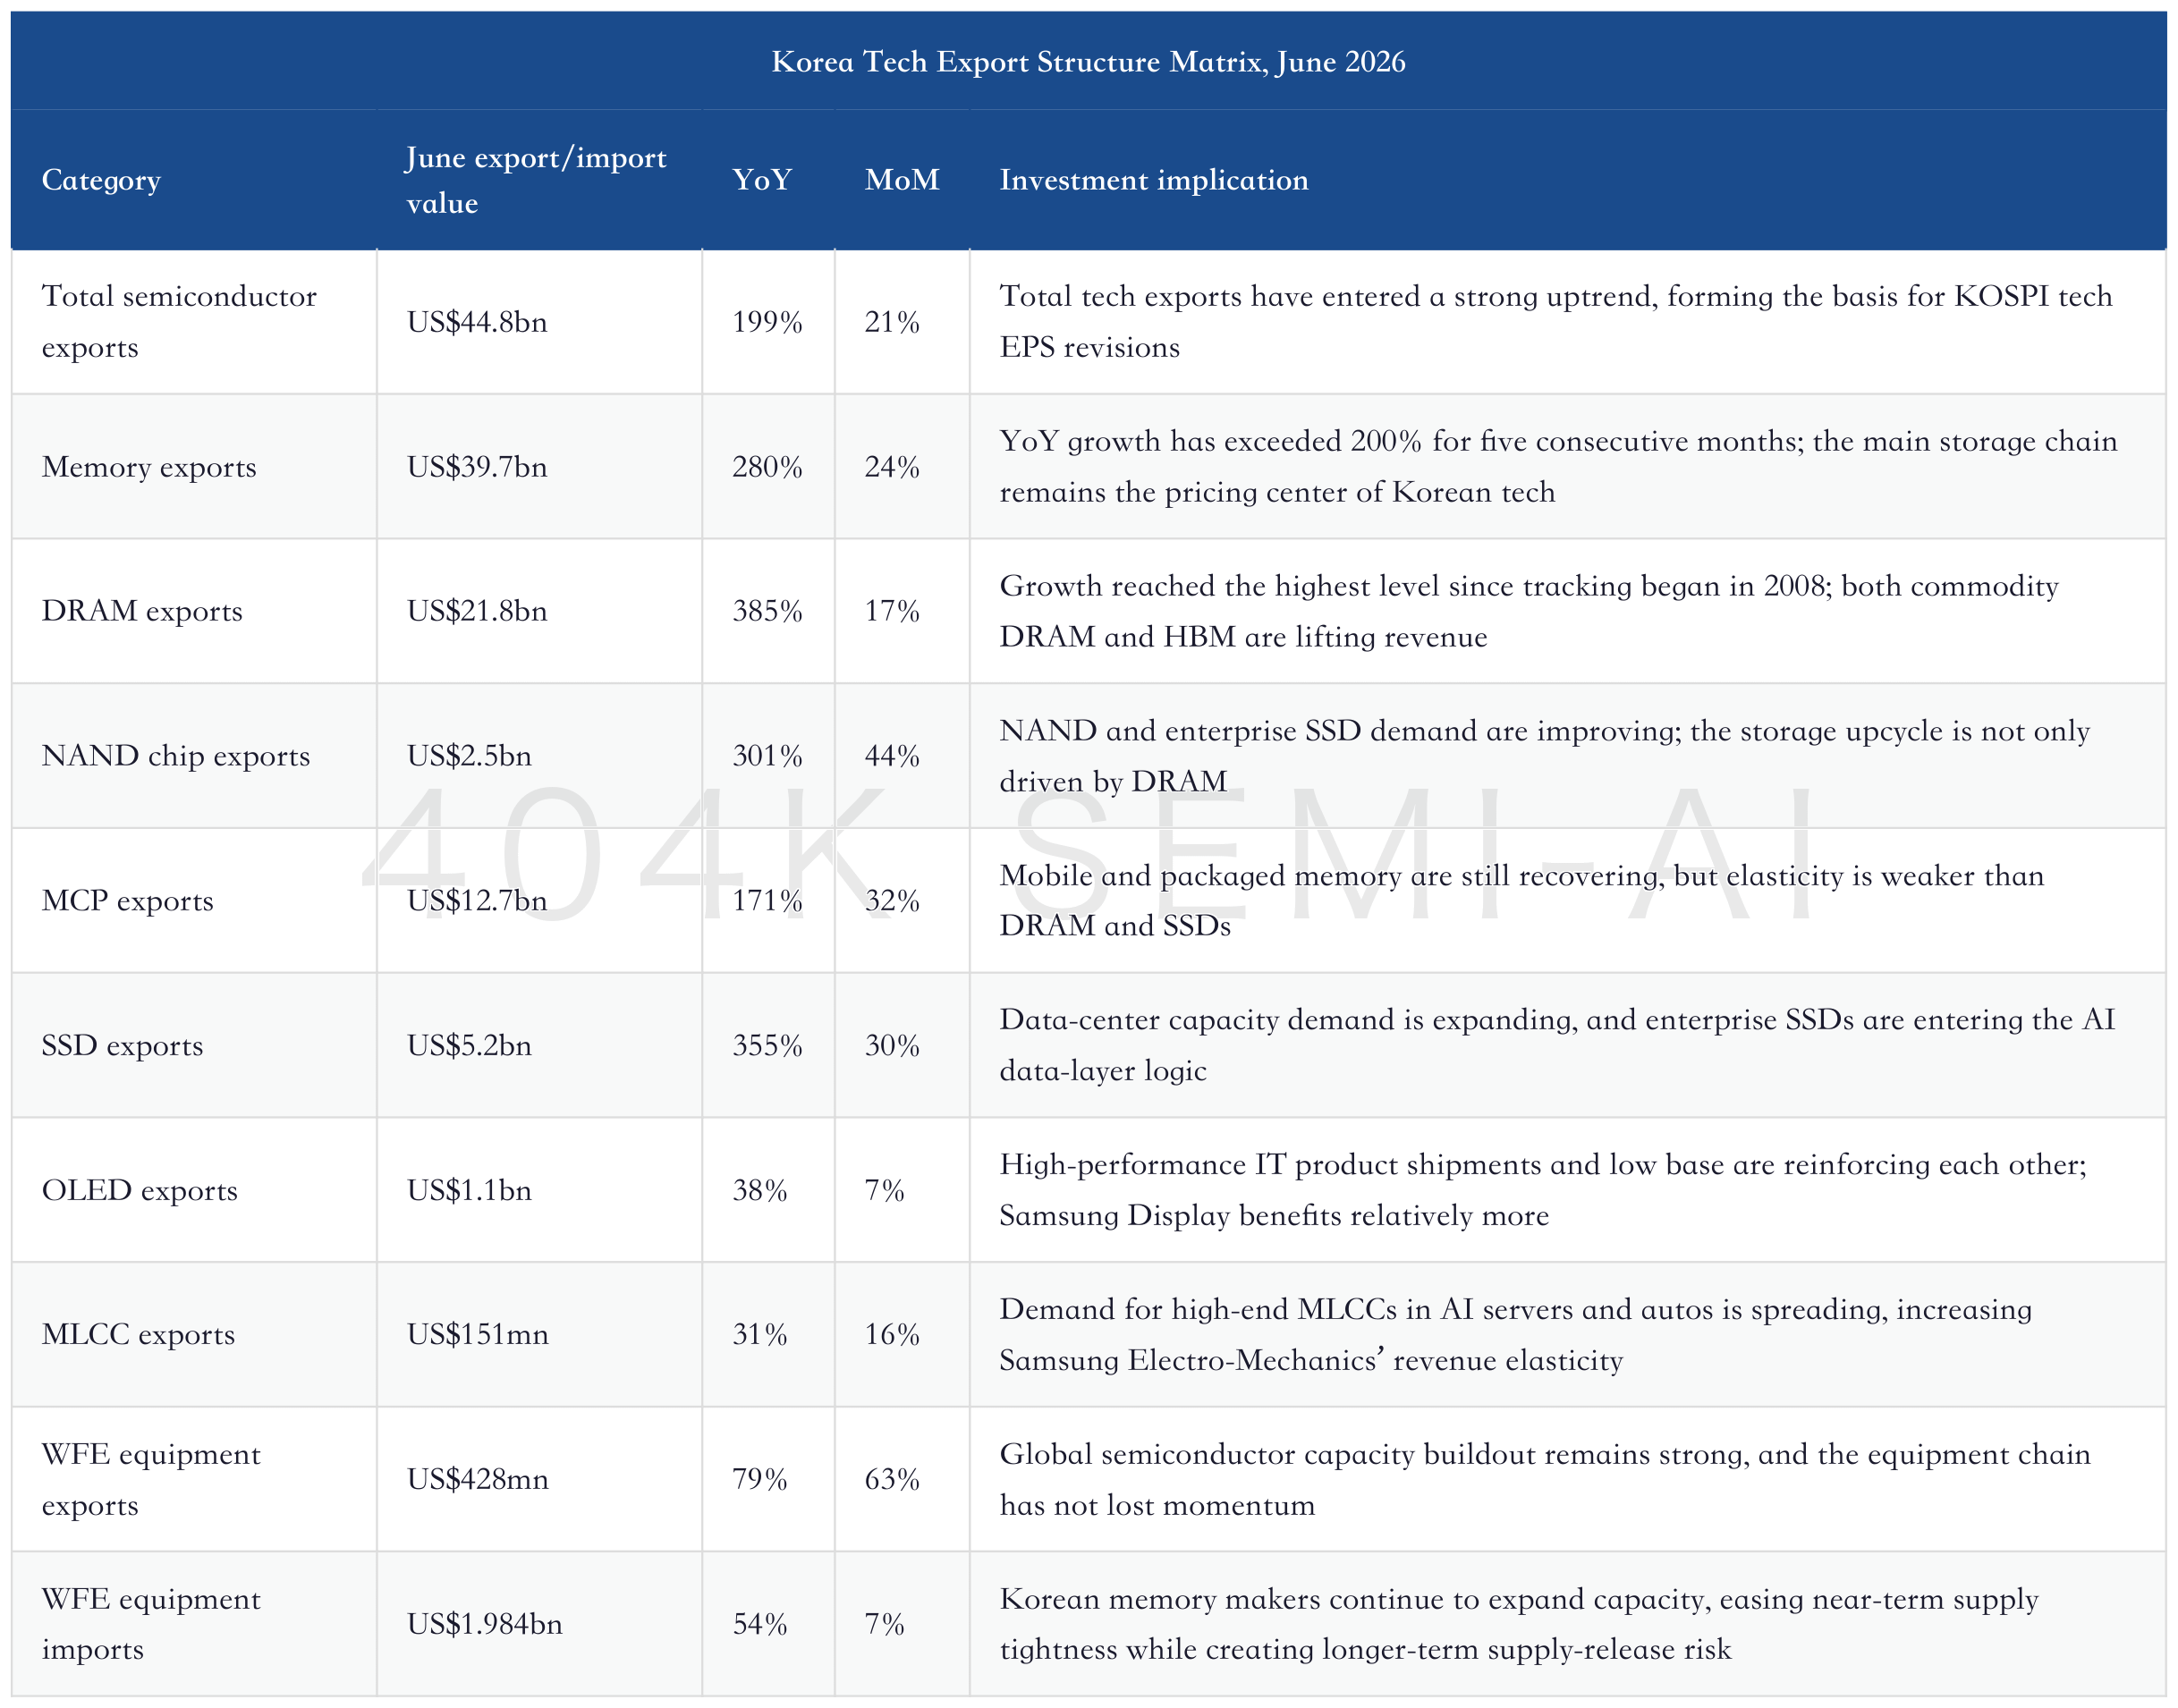
In this table, the most important thing is to separate scale from signal strength. Memory has the largest value and the most direct impact on earnings and index weight. MLCC is small in value but offers a clean signal because it represents diffusion of high-end AI hardware demand. WFE is also not large in value, but it is physical evidence of capex and helps judge whether the upcycle is supported by capacity investment.
2. Memory Exports +280% YoY: Storage Remains the Earnings Backbone of Korean Tech
Memory exports rose 280% YoY and have exceeded 200% for five consecutive months. This is the first main line of the report. Over the past few months, the market has been debating whether storage has already rallied too far. Korean export data gives a direct answer: at least through June, orders, pricing, and mix are still jointly pushing export revenue higher.
DRAM is the strongest single item. June DRAM exports reached US$21.8bn, up 385% YoY. Goldman says this is the highest growth rate since it began tracking the data in 2008. This figure should not simply be read as “DRAM prices rose again.” It is more like the combination of three forces: HBM absorbing advanced capacity, DDR5 and server DRAM benefiting alongside it, and traditional supply discipline allowing price increases to enter export value.
NAND and SSDs are also becoming important. In June, NAND chip exports rose 301% YoY, while SSDs rose 355% YoY. NAND used to be seen as the weaker part of the storage cycle because of poor supply discipline, weaker pricing elasticity, and heavy drag from consumer electronics demand. Now, enterprise SSDs, AI inference, retrieval augmentation, vector databases, data lakes, and nearline storage are all increasing capacity demand. NAND is no longer just the tail end of the consumer electronics inventory cycle.
Storage Deep Dive: Korea’s US$3.1tn AI Investment Plan and How It Re-Rates DRAM, NAND, and the Equipment Chain
Goldman’s forecast for Samsung Electronics’ 2Q26 memory revenue also provides the bridge to the income statement: it expects memory revenue to grow 452% YoY, with DRAM and NAND growing 502% and 355% YoY, respectively. This is not export data itself, but the sell-side model’s landing point for company revenue. It tells investors that the high growth seen in customs data is not an isolated signal; it is already strong enough to enter company revenue forecasts and earnings revisions.
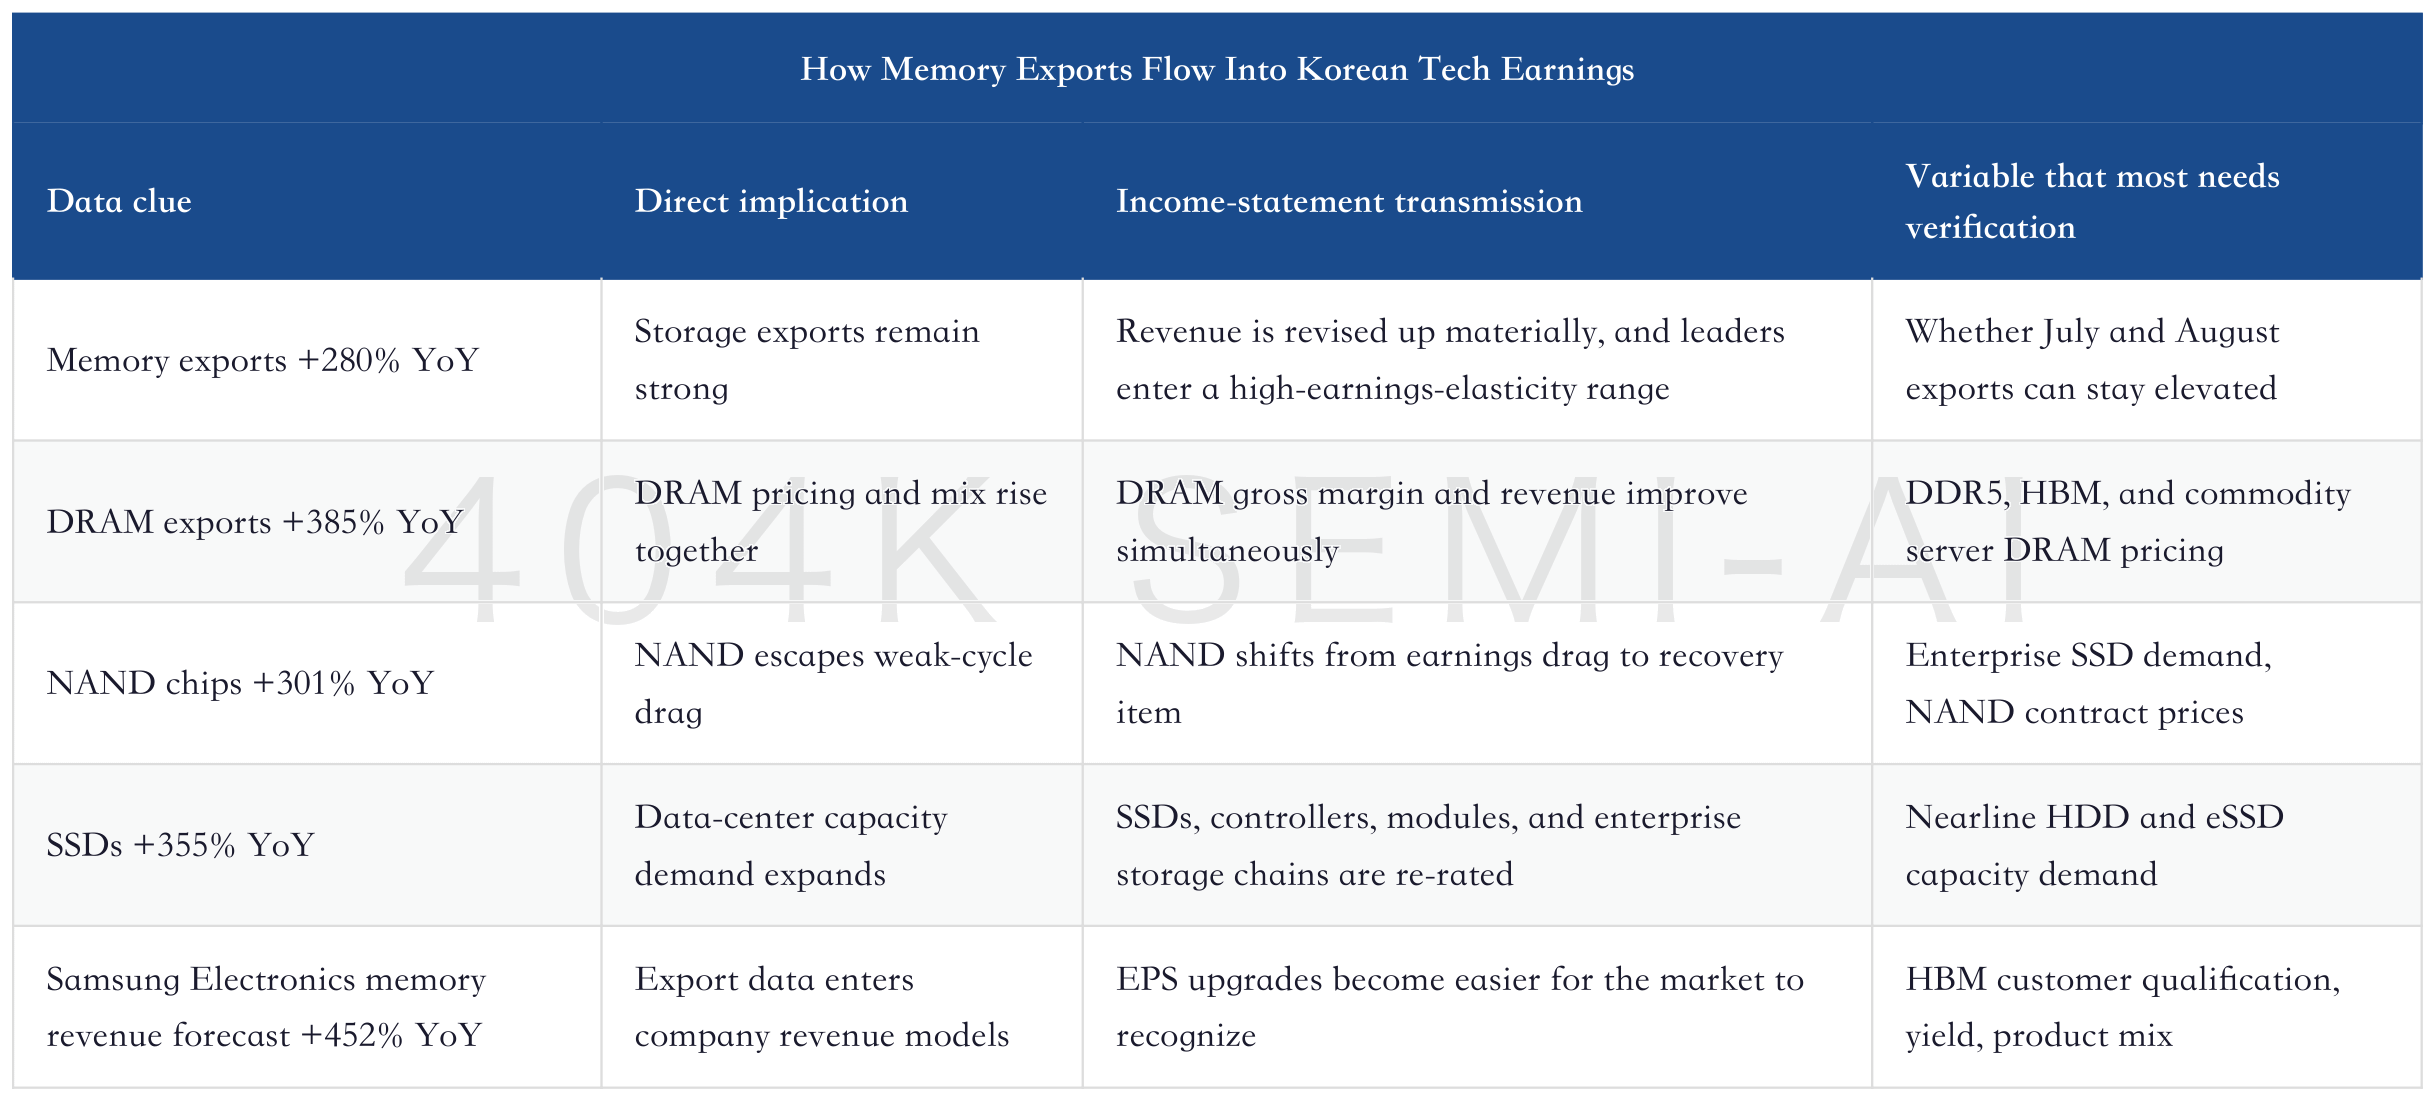
The storage investment conclusion has two layers. The first is near-term earnings delivery: June exports show 2Q26 revenue and gross margin are highly likely to remain in an upgrade phase. The second is a change in the valuation framework. The market will continue to debate whether this is a traditional cyclical peak. If it is only a price rebound, valuation will be capped by peak-cycle discounting. If HBM, DDR5, and enterprise SSDs turn storage into AI infrastructure cash flow, valuation cannot be handled solely under the old-cycle framework.
Goldman DRAM Deep Dive: DDR5 Price Increases, 2027 HBM Repricing, and Samsung’s KRW 2,450tn Investment
The ranking here is also clear. SK hynix still maps most directly to HBM leadership and storage earnings elasticity. Samsung Electronics offers a larger catch-up option: recovery in commodity DRAM and NAND first improves the earnings floor, while HBM qualification and advanced packaging progress determine whether the valuation discount can narrow. Kioxia, Micron, SanDisk, and other global storage names provide cross-checks for NAND, eSSD, and long-term agreement logic.
III. HBM Proxy Indicator: Samsung Electronics’ Ramp Is Starting to Show Up in Materials Flows
Goldman Sachs uses an interesting proxy indicator to track Samsung Electronics’ HBM: the value of plastic film imports from Japan to Hwaseong and Pyeongtaek. The reason is that Samsung Electronics’ HBM production bases are located in these areas, while TC-NCF materials mainly come from the Japanese supplier Resonac. This import data has a strong correlation with Samsung Electronics’ HBM shipments, so it can be used to observe the pace of the HBM ramp.
In May, this indicator rose 76% YoY; from the beginning of the year through May, it rose 61% YoY. This set of numbers is more useful than ordinary order rumors because it comes from material inflows, not just management statements. HBM production requires materials, packaging, yield, and customer qualification to work together. Rising material imports at least indicate that Samsung Electronics’ HBM production preparation and shipment pace are advancing.
The boundaries need to be emphasized: plastic film imports are not Samsung Electronics’ HBM revenue, not customer qualification results, and certainly not changes in SK hynix’s share. It is only a high-frequency proxy indicator. Its value lies in helping the market judge whether Samsung Electronics has moved from a “catch-up narrative” into a “production ramp.” If this indicator continues to rise and Samsung Electronics provides HBM orders, yield, and customer progress in its earnings reports, Samsung’s valuation discount will become easier to narrow.
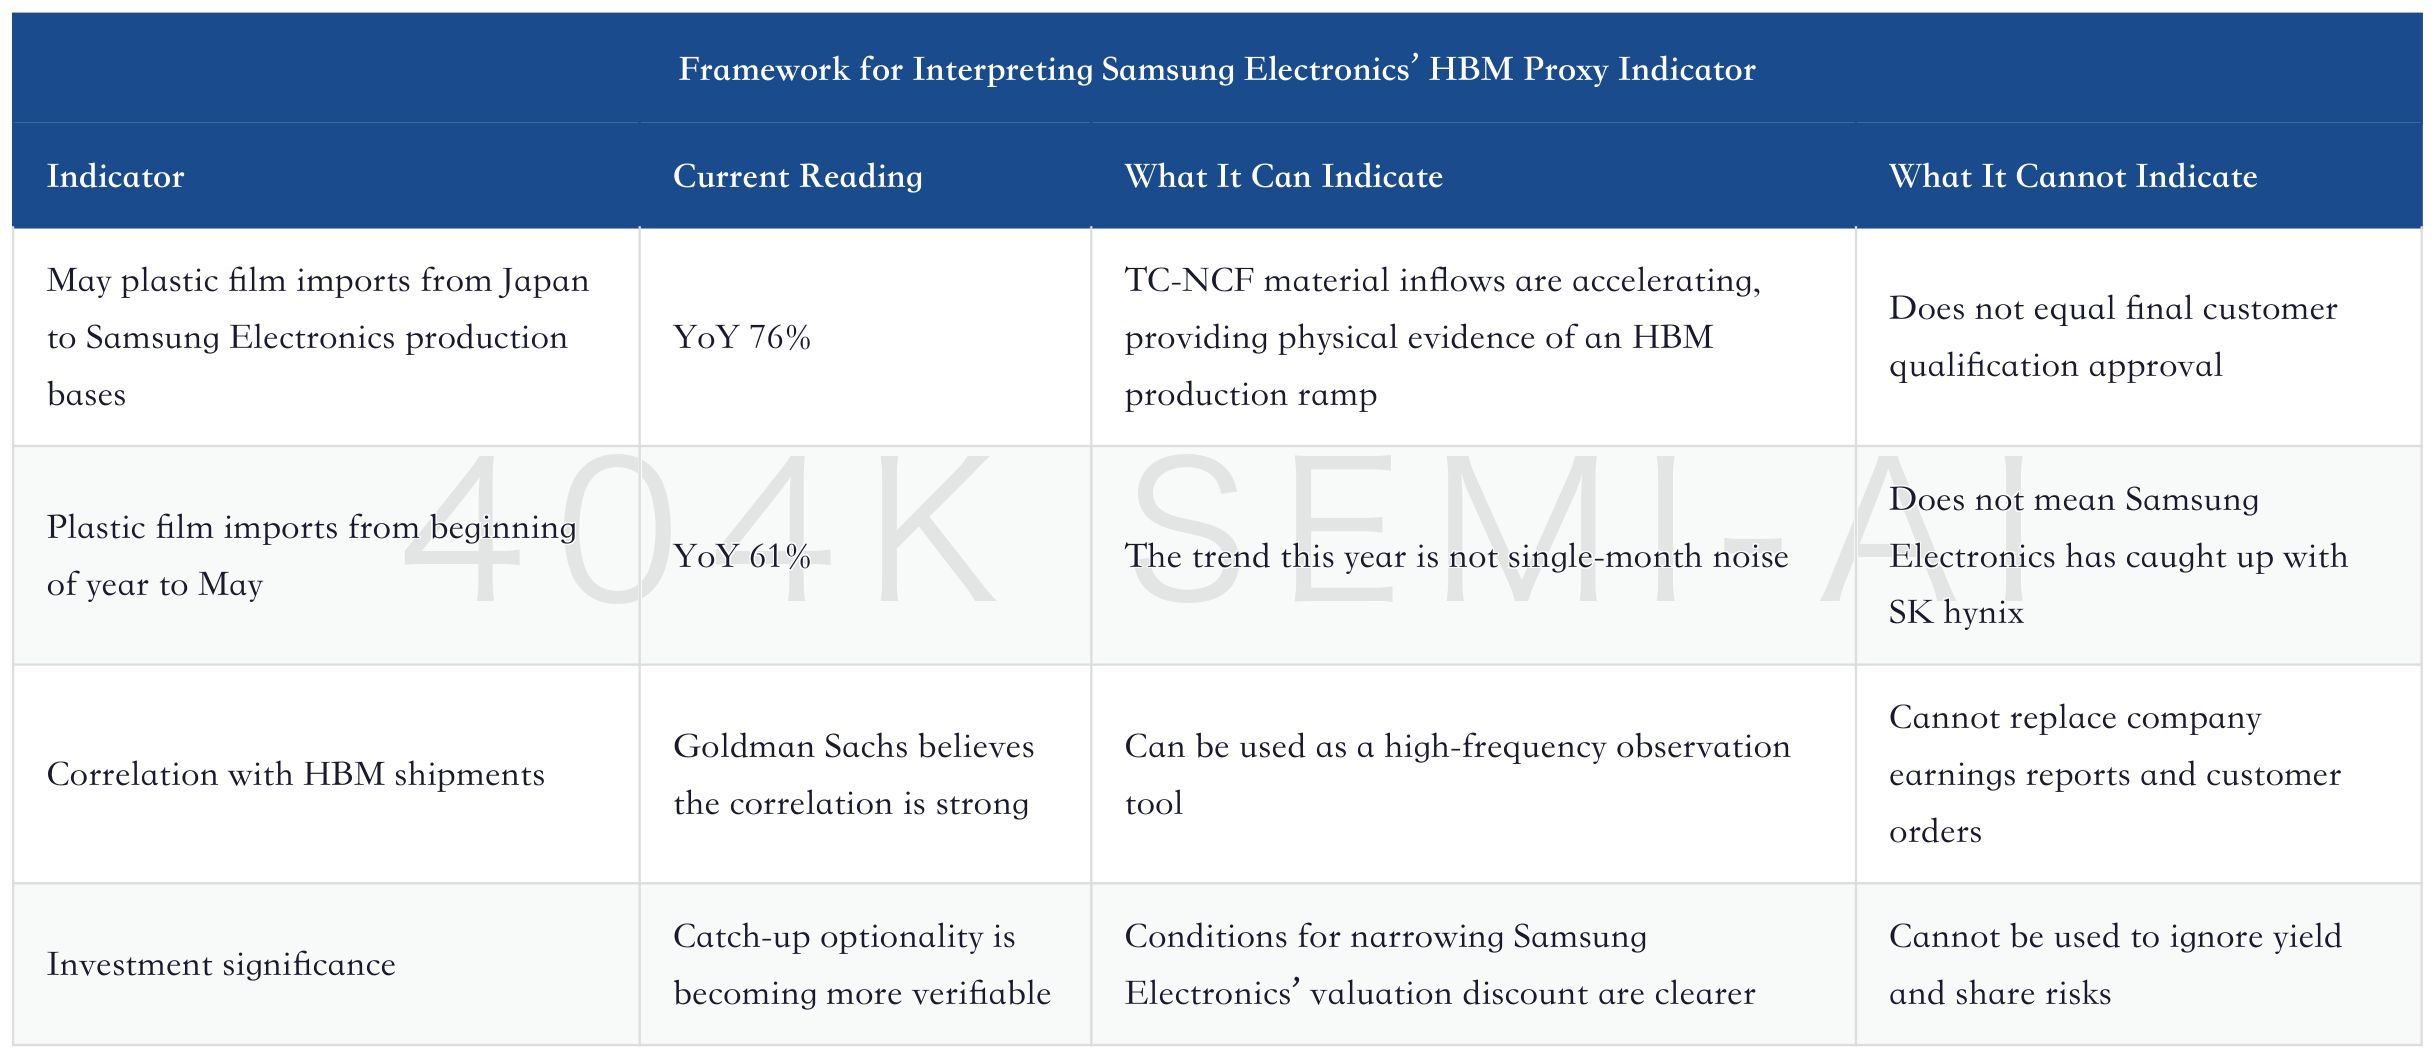
HBM’s impact on Korean technology has already moved beyond memory itself. It consumes advanced DRAM wafers, raises the barriers for packaging and materials, and pulls equipment, testing, substrates, and thermal management into supply constraints. If Samsung Electronics succeeds in catching up, the beneficiaries will not only be Samsung itself, but also Korea’s equipment, materials, packaging, testing, and electronic components chains. If the catch-up is slower than expected, SK hynix’s leadership premium will remain intact.
Korean Technology Deep Dive: How HBM, MLCC, FC-BGA, TCB, and Enterprise AI Are Being Revalued Under the AI Compute and Memory Supercycle
This is also why June export data and the May materials proxy should be viewed together. Export data tells the market that memory revenue is being realized, while the materials proxy tells the market that Samsung’s HBM catch-up has physical traces. The former supports current-period profit, while the latter supports the long-term share-recovery option. Only when the two resonate can Samsung Electronics move from a “normal memory recovery” to an “AI memory platform revaluation.”
IV. MLCC Up 31% YoY: AI Hardware Demand Is Starting to Penetrate Passive Components
In June, MLCC exports rose 31% YoY and 16% MoM, making this the most easily underestimated signal in the entire report. Memory has a larger value, and WFE looks more like capital expenditure, while MLCC represents the spillover of the AI server value chain: as GPUs, ASICs, HBM, and high-end CPUs raise power consumption and signal complexity, power stability, noise filtering, reliability, and miniaturization all become more important.
Goldman Sachs points out that MLCC export growth accelerated from 14% in May to 31% in June, with 2Q26 up 14% YoY and 11% QoQ. For Samsung Electro-Mechanics, it expects 2Q26 MLCC revenue to grow 22% YoY, mainly driven by AI server and automotive MLCCs. This set of data corroborates the previous supply-demand tightness in the Japanese and Taiwanese MLCC chains.
MLCC Deep-Dive Update: AI Servers Are Turning a Cyclical Component into a Power-Supply Bottleneck. Who Can Convert Price Increases into Profit?
The key for MLCC is not per-unit content value, but high-end capacity and customer qualification. The high-capacitance, high-reliability, high-temperature, and high-voltage specifications used in AI servers place requirements on ceramic powders, layering, sintering, reliability testing, and customer adoption. Once AI servers and automobiles absorb high-end capacity at the same time, even without a major recovery in ordinary consumer electronics demand, it may still be difficult to prevent high-end MLCC prices and product mix from improving.
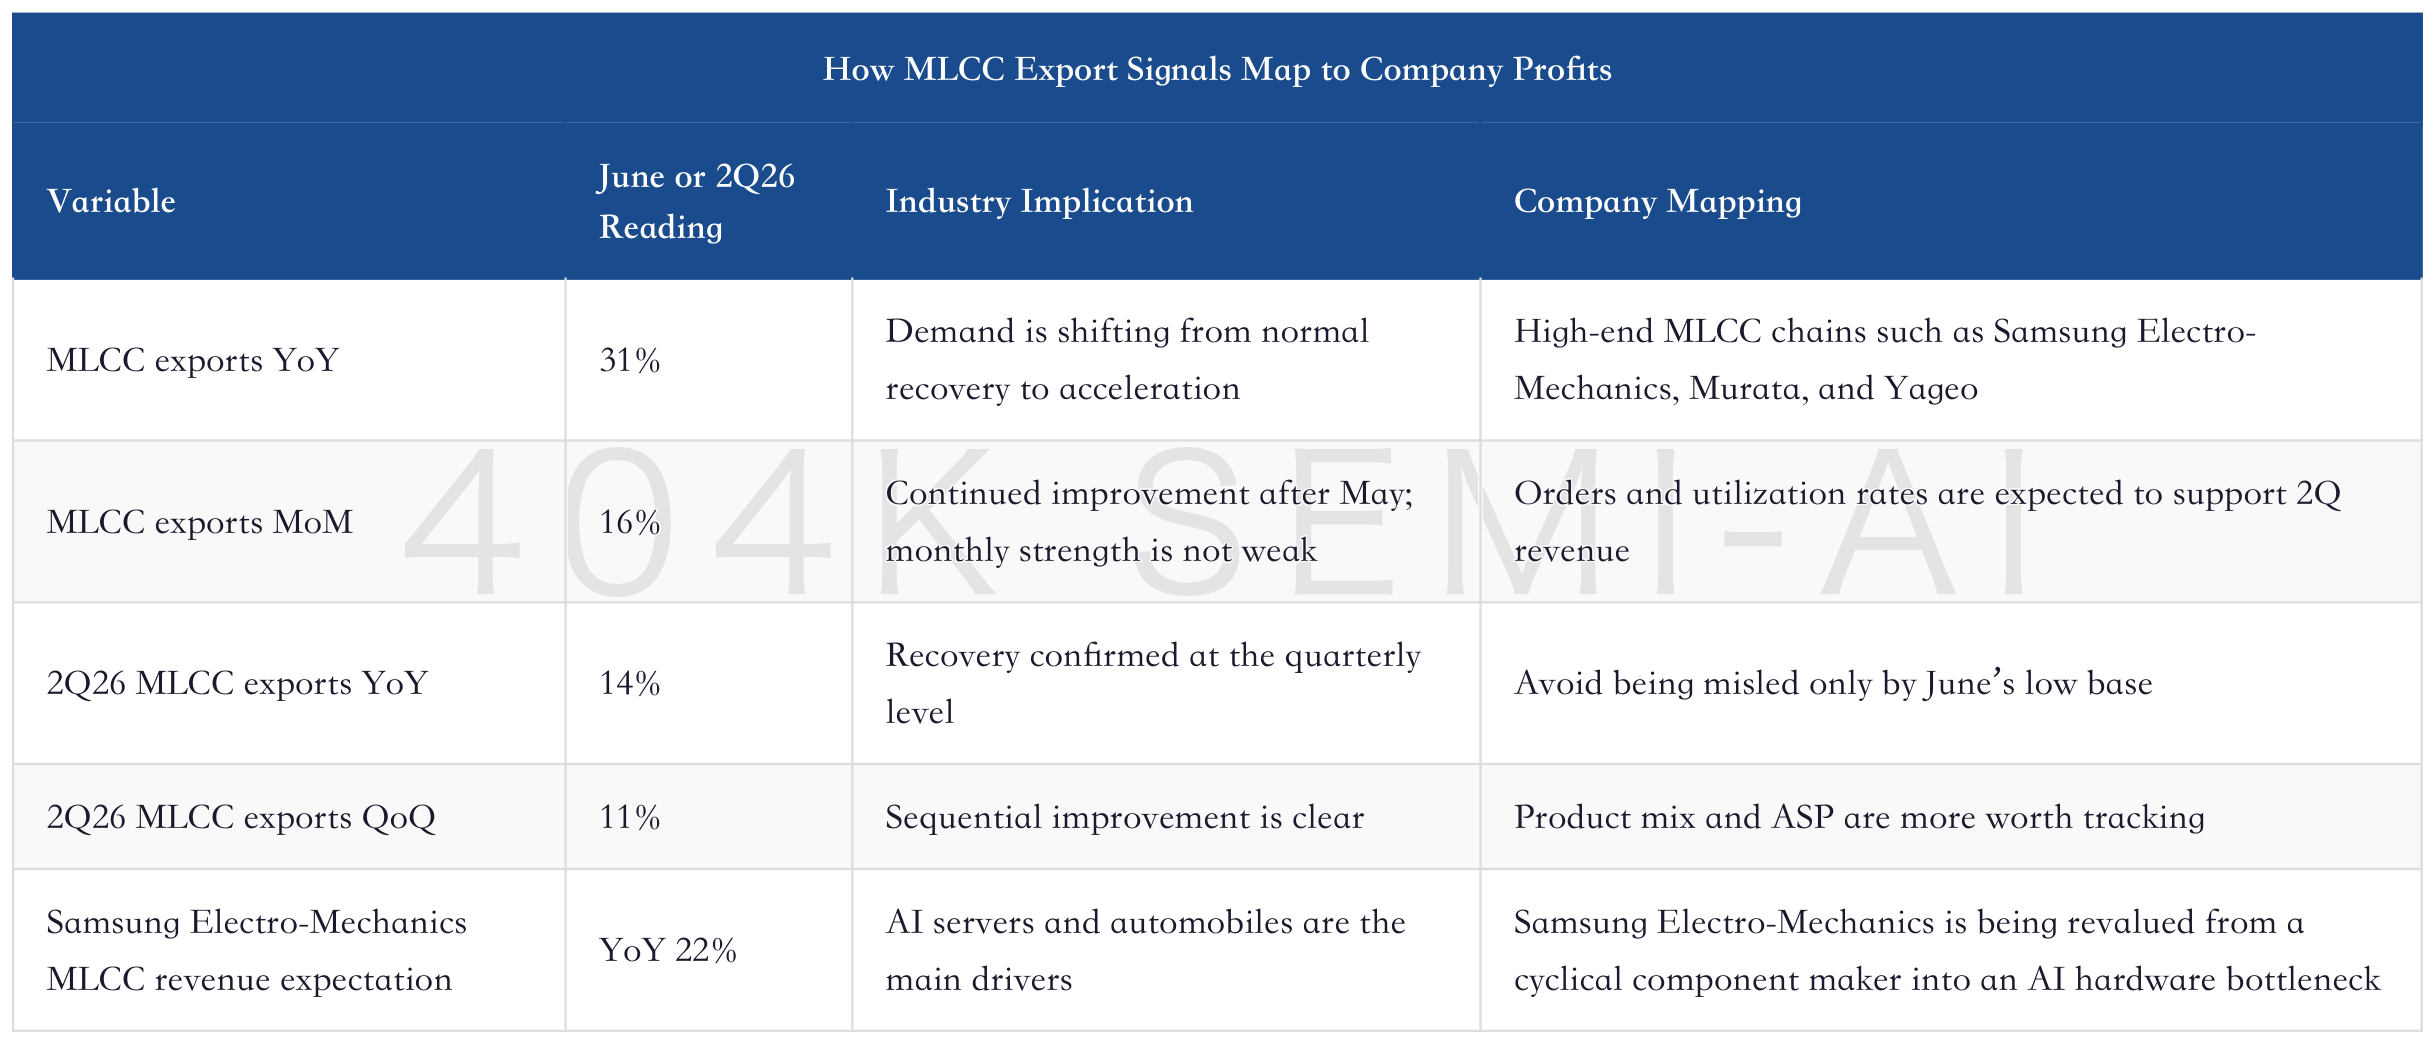
Samsung Electro-Mechanics is the most direct listed-company mapping in Korea’s MLCC logic. Its upside does not come only from MLCCs, but also from FC-BGA, ABF, embedded components, and AI hardware customer adoption. MLCC exports rising 31% YoY can help the market confirm one fact: the spread of AI hardware is not just sitting in research frameworks. It has already begun to enter Korea’s electronic components exports.
Second Upward Revision of the AI Hardware Cycle: Asian Technology Repricing Across Memory, HBM, PCB, and MLCC
For investment, it is necessary to distinguish between two types of MLCC. Ordinary IT and consumer electronics MLCCs are still affected by smartphones, PCs, and channel inventory, and prices may not rise across the board. AI server, automotive, industrial, and high-reliability MLCCs are closer to supply-bottleneck assets. The acceleration in June exports increases confidence in the latter category, but follow-up still depends on orders, ASP, and gross margins in high-end categories at companies such as Samsung Electro-Mechanics, Murata, Taiyo Yuden, and Yageo.
V. WFE Exports and Imports Both Strong: Supply Tightness Is Driving Capital Expenditure
In June, WFE equipment exports rose 79% YoY and imports rose 54% YoY. In 2Q26, exports and imports rose 69% and 73% YoY, respectively. This combination is important because it shows that the strength in Korean technology exports is not only demand-side heat, but is also beginning to drive supply-side investment.
Strong imports generally point to Korean domestic semiconductor companies increasing equipment purchases. Goldman Sachs’ explanation is that memory suppliers are increasing capital expenditure to ease supply tightness. Strong exports indicate that Korean equipment and related supply chains are benefiting from global semiconductor capacity construction. Taken together, the two show that the AI memory cycle is moving from price increases into the expansion phase for capacity, equipment, and materials.
From HBM to WFE: How AI Is Turning the Memory Cycle into an Equipment Supercycle, and How Much Longer Semiconductor Equipment Can Rise
The benefit of equipment data is that it verifies whether companies are truly spending money. Cloud capex can be written into slides, and memory prices can fluctuate with short-term supply and demand, but equipment imports require orders, delivery, and budget execution. Korea’s continued strength in WFE imports shows that memory makers’ judgment on demand durability is already sufficient to support capacity expansion.
