
Korea Market Deep-Dive Update: AI Hardware Repricing After a 4% KOSPI Pullback, 6.65x Forward PE, and Foreign Outflows
目录
Too Long; Didn’t Read
I. Nature of the Pullback: Korea’s Story Has Not Broken; This Is a Post-Rally Stress Test
II. Valuation: 6.65x Forward PE Is Not a Safety Cushion Itself, but the Risk Premium Is Fully Priced
III. Earnings: The Market Is Selling Tech Stocks, but Earnings Revisions Have Not Deteriorated in Tandem
IV. Flows: KRW 19.9 Trillion of Foreign Selling Was Almost Entirely a Technology De-Risking
V. Sector Rotation: Catch-Up in Banks, Securities, and Leisure Does Not Mean the Technology Theme Is Over
VI. Korea Is Still the Macro Proxy for AI Hardware: Exports, Capex, and Policy Remain Intact
VII. Three Worldviews: Pullback Buying Opportunity, Cycle Peak, or Transitional Choppiness
VIII. Allocation Framework: Do Not Chase the Index; Buy Three Verification Chains
IX. Falsification Checklist: When Korea’s Re-Rating Needs to Pause
X. Conclusion: Korea’s Pullback Improves the Odds, but Raises the Validation Bar
XI. Key References
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
This round of Korea’s pullback does not disprove the AI hardware cycle. Rather, gains, foreign positioning, and FX pressure have entered a stress test at the same time. The key is not that the KOSPI fell 4%, but whether 6.65x forward PE, continued EPS upgrades, and foreign outflows from tech can rebalance. If all three stabilize, Korea remains the market with the most compelling risk-reward in North Asia AI hardware.
Too Long; Didn’t Read
This decline looks more like position clearing than an earnings turn. The KOSPI pulled back 3.8% over one week, the tech sector fell 7.6%, and foreign investors sold about KRW 19.9tn over the week, including about KRW 16.5tn of outflows from tech. Yet KOSPI 12-month EPS was still revised up 4.8% over the same period, with tech up 5.5%. This suggests the market is selling crowding and volatility, not an already visible loss of momentum in the income statement.
6.65x forward PE has pushed Korea back into crisis-level valuation territory. Goldman Sachs estimates the KOSPI’s 12-month forward PE at 6.65x, 2.7 standard deviations below its historical average and near lows since the global financial crisis. Even under a stress test using the historical median earnings downgrade of -33%, implied EPS would be about 771. Applying the historical trough PE median of 11.4x gives a KOSPI level of about 8,750, still above the current level near 8,088.
The sharpest market disagreement is in tech: prices are falling while models are being revised higher. Tech had the largest one-week decline, but 2026E and 2027E EPS have been revised up 65% and 98% over the past three months, and 270% and 371% over the past six months. If DDR5, HBM, SSD, and MLCC continue to deliver, the tech selloff is a valuation reset. If earnings revisions stall after 2Q26, 6.65x PE will also become a peak-cycle discount.
Foreign outflows are not a uniform exit, but tech de-risking and defensive rotation. Banks, securities, and leisure rose against the trend, while tech, insurance, and retail led declines. This shows capital has not abandoned Korean assets, but is rotating out of crowded tech into financials, securities, leisure, and other low-positioned or policy-sensitive areas. The next question is whether foreign investors buy tech again, not just whether the index rises or falls.
Korea remains Asia’s most direct macro proxy for AI hardware. Korea’s June tech exports, DRAM sentiment indicators, and government-backed semiconductor investment plans all point in the same direction: AI demand is entering Korea’s income statement through memory, HBM, WFE, MLCC, and capex. The index may be affected by foreign flows and the won in the short term, but medium-term pricing still depends on whether the AI hardware surplus can continue translating into EPS.
Over the next four weeks, watch five numbers rather than guessing the bottom. First, whether KOSPI 12-month EPS continues to be revised higher. Second, whether foreign outflows from tech narrow. Third, whether USDKRW stabilizes near 1,530. Fourth, whether DDR5, HBM, and SSD prices continue to improve. Fifth, whether the KOSPI can reclaim its 50-day moving average. If all five improve together, Korea’s pullback is an entry window. If EPS turns negative and foreign investors keep selling tech, reduce exposure first.
I. Nature of the Pullback: Korea’s Story Has Not Broken; This Is a Post-Rally Stress Test
The Korean market rose too quickly over the past few weeks, so the pullback itself is not surprising. What matters is what was sold during the decline, what is still being revised higher, and which sectors were bought instead. Goldman Sachs’ July 4 weekly report gives a clear answer: foreign investors are selling, especially tech; but earnings have not been revised down in tandem, while valuations have been pushed to extremely low levels.
“KOSPI dropped by 4% amid continued market volatility and foreign outflows.”
This sentence captures the surface volatility, but it is not the investment conclusion. On the surface, the KOSPI fell 3.8% in one week, MSCI Korea fell 5.5%, and tech fell 7.6%. Underneath, Korea has moved from a pro-cyclical narrative of “the index breaking above 9,000” into a validation phase: whether foreign investors are still willing to add after earnings upgrades.
Korean Equity Revaluation: Tech Earnings, Foreign Inflows, and MSCI Reform Validation After the KOSPI Breaks 9,000
The core logic behind the previous rally was the convergence of three forces: AI memory driving Korean tech earnings, foreign underweight positioning creating room for covering, and MSCI plus market-structure reforms offering an option on discount compression. These three forces have not all broken. What has broken is the short-term trading structure. Excessive gains in tech, concentrated foreign selling of Korean tech, and continued volatility in the won are enough to trigger a steep index pullback.
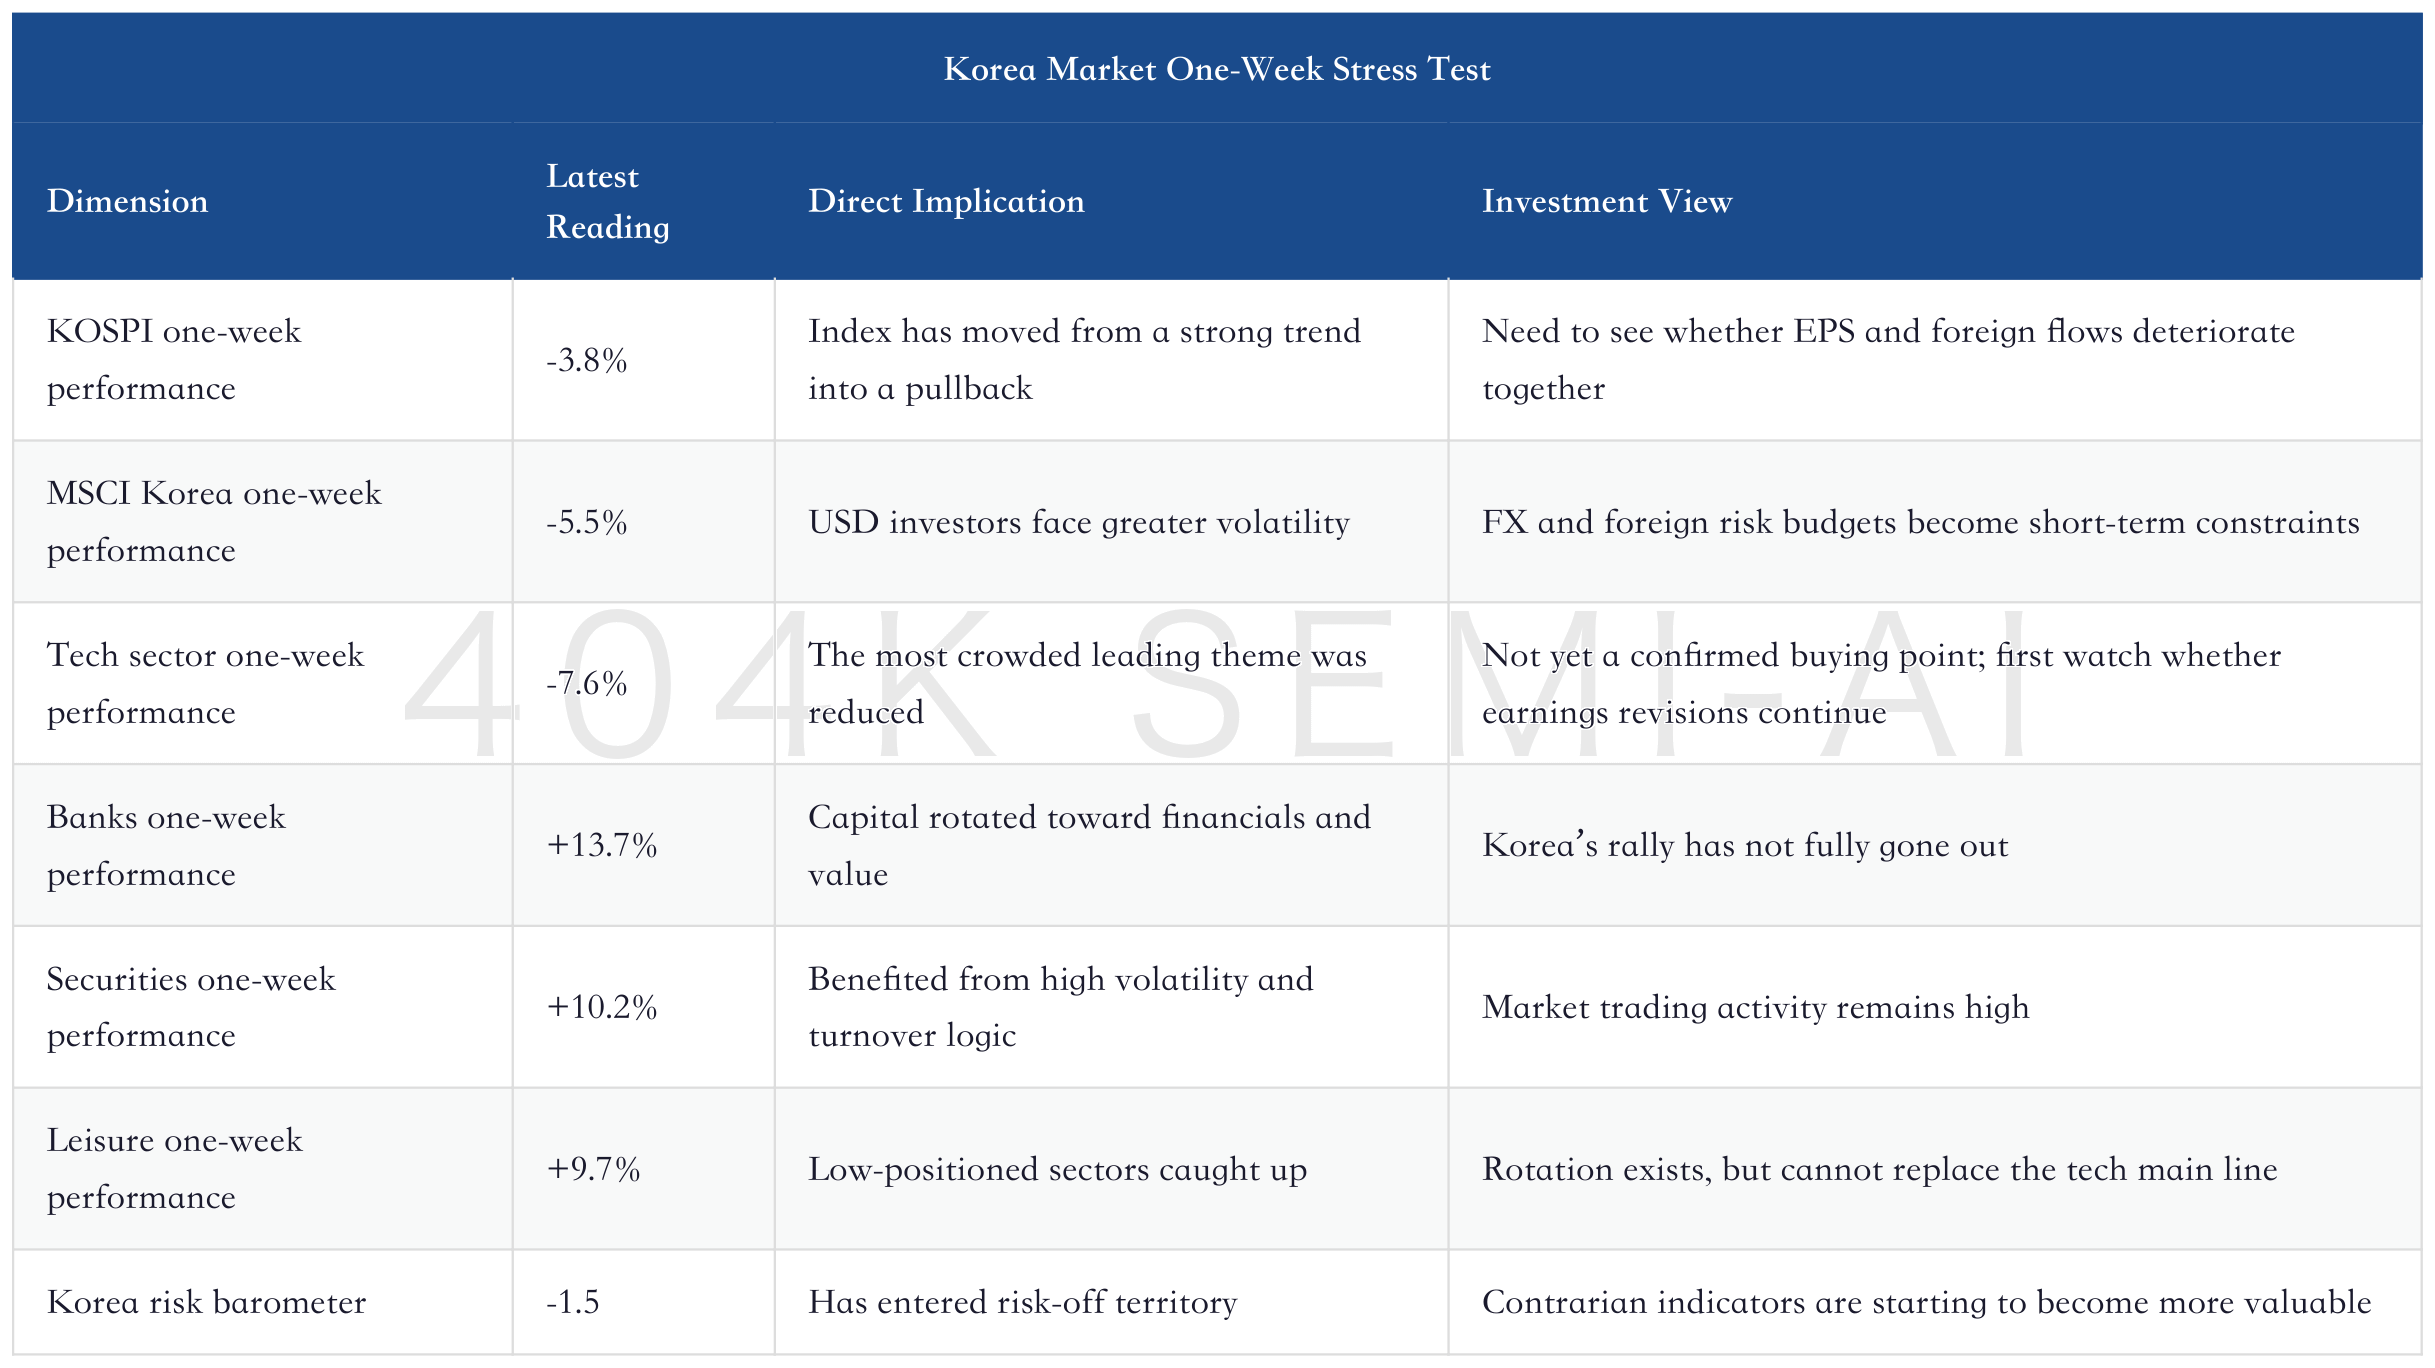
This table shows that the pullback most resembles “internal rebalancing after a strong trend.” If Korea’s fundamentals had already deteriorated, we would usually see EPS downgrades, broad-based foreign selling, financials and cyclicals weakening together, and valuations still not cheap enough. What we see now is a different structure: foreign investors are selling tech, retail investors are buying tech, banks/securities/leisure are catching up, EPS is still being revised higher, and valuations have already been pushed close to crisis levels.
This does not mean bottom-fishing immediately. Korea’s risk is that volatility can hit positioning before earnings validation arrives. Especially when tech has already become the most important profit engine for the index, any disruption around HBM qualification, DRAM prices, AI capex, the won, or global tech stocks will be amplified into index volatility. A better approach is to break this pullback into three layers: first, whether valuation is extreme; second, whether earnings are still being revised higher; third, whether foreign selling is close to ending.
II. Valuation: 6.65x Forward PE Is Not a Safety Cushion Itself, but the Risk Premium Is Fully Priced
The most important chart in Goldman Sachs’ report is not sector performance, but the KOSPI’s 12-month forward PE. The latest reading is 6.65x, 2.7 standard deviations below the historical average and near lows since the global financial crisis. This number matters: the market is no longer pricing Korea as a “normal correction,” but is discounting Korea as if earnings will be materially revised down.
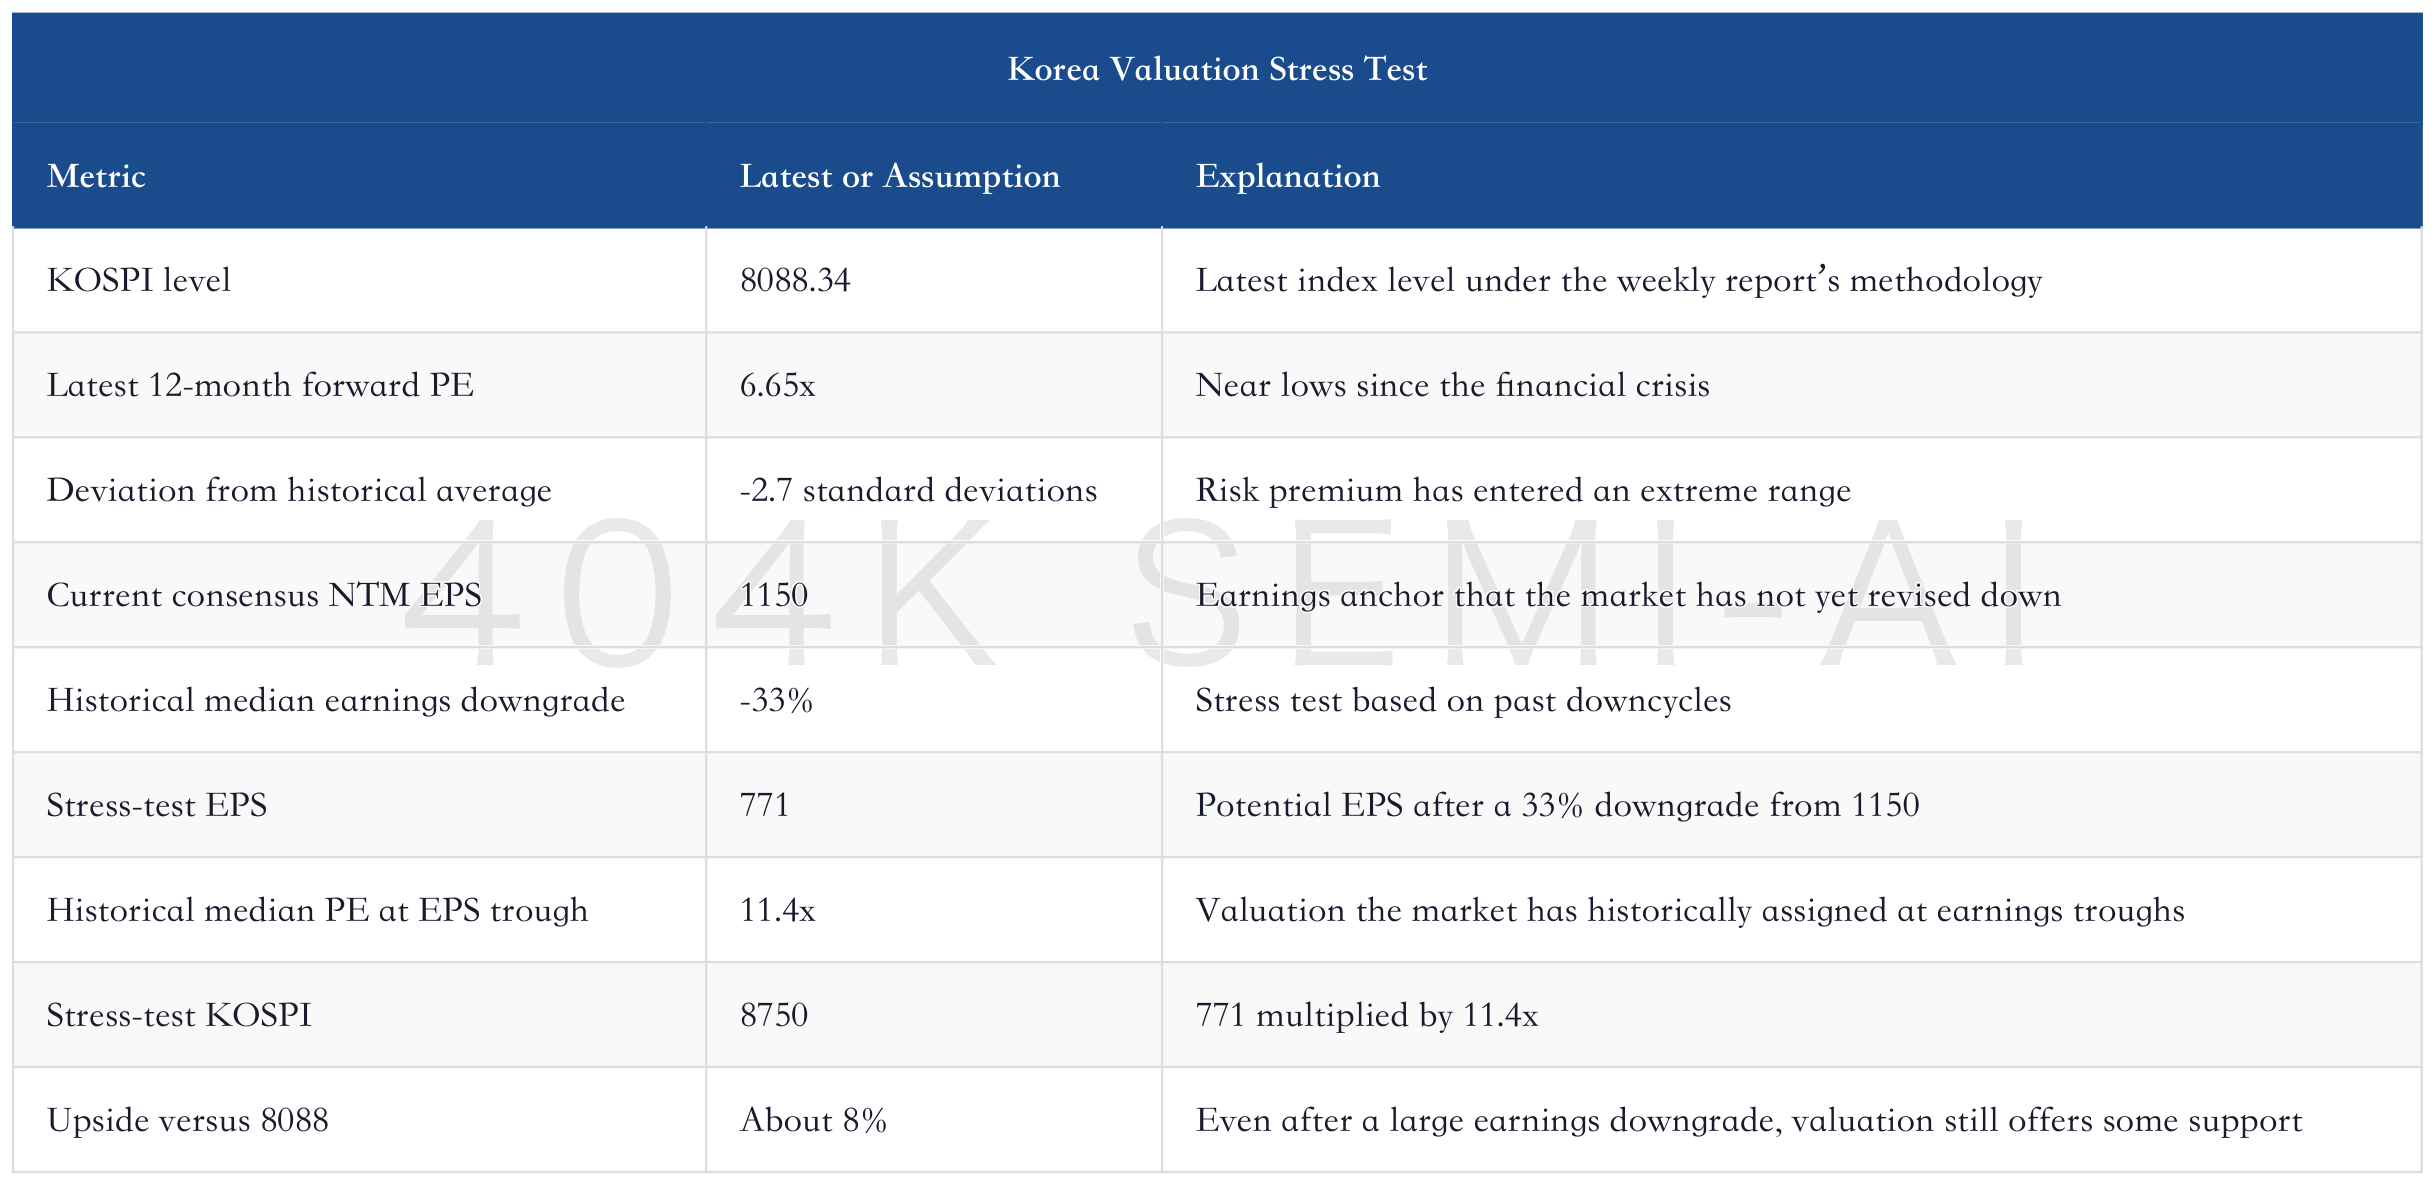
This table is easy to misread. It does not mean Korea must rise to 8,750, nor does it mean there is no downside risk left. What it really shows is this: at current prices, the market has already assumed that future earnings will be cut meaningfully. Yet the same Goldman Sachs weekly report shows that earnings expectations were still being revised higher this week. Price is trading bad news, while models have not yet delivered bad news. That is the core tension after the pullback.
JPMorgan Sees the KOSPI at 15,000: Is Korea’s Rally an AI Bubble or a National Wealth Revaluation?
The larger valuation contradiction appears in cross-market comparison. MSCI Korea trades at about 7.6x 2026E PE and 5.5x 2027E PE, while Japan, Taiwan, India, and other markets remain in higher valuation ranges. Korea is not cheap because it lacks earnings. It is cheap because earnings are highly concentrated in the memory cycle, foreign investors remain concerned about governance and FX, and excessive gains in tech make positioning vulnerable to forced deleveraging.
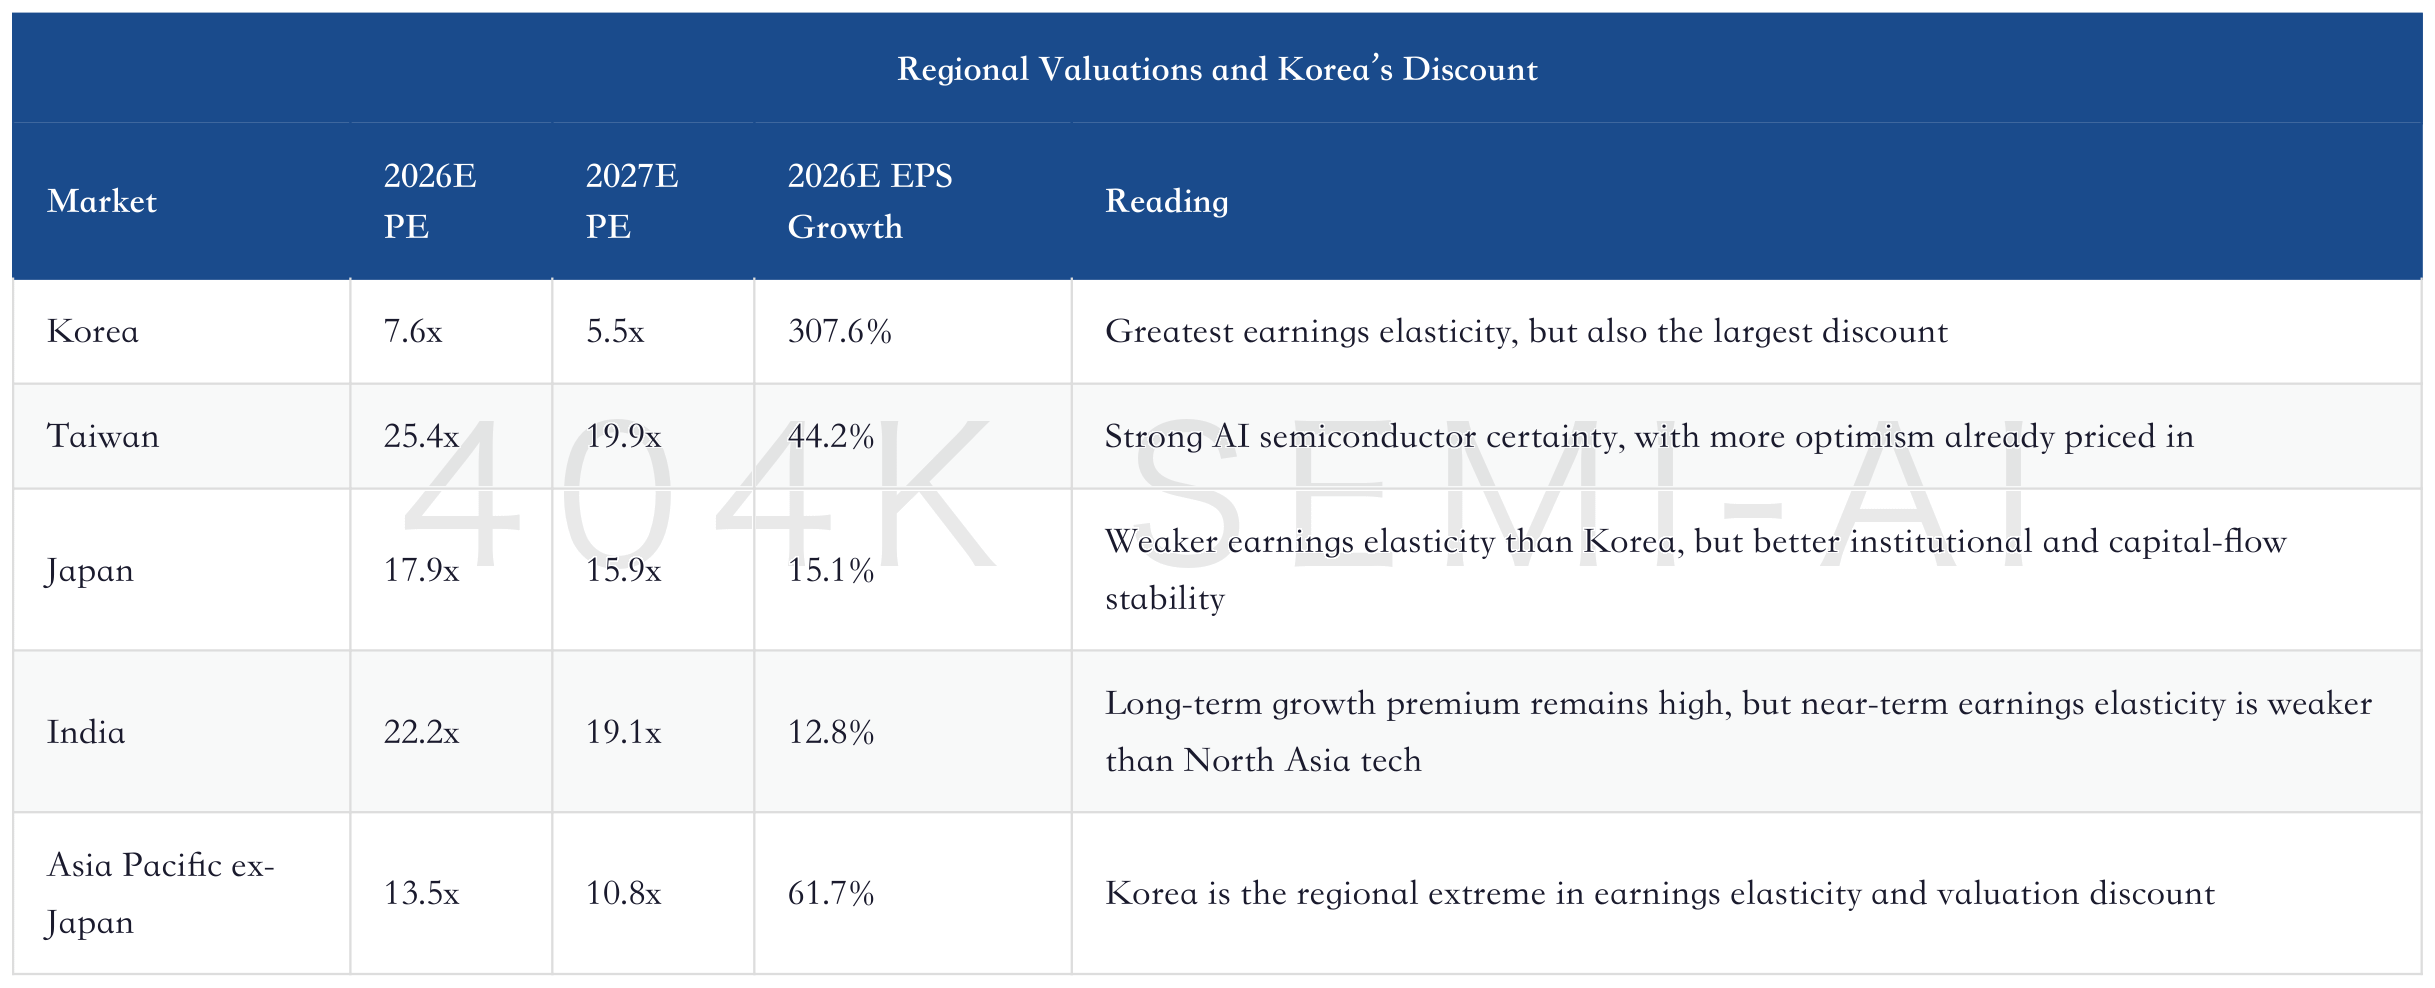
Whether Korea’s discount can narrow depends on whether the causes of the discount are removed. AI memory is removing the “traditional cyclical stock” discount. Shareholder returns and governance reform are removing the “low capital efficiency” discount. MSCI and market accessibility reforms are removing the “hard for overseas capital to buy” discount. But if AI hardware is disproven, or if foreign investors again treat Korea as a high-volatility cyclical asset, low PE can stay low.
III. Earnings: The Market Is Selling Tech Stocks, but Earnings Revisions Have Not Deteriorated in Tandem
The most valuable counter-evidence in this weekly report is that KOSPI 12-month EPS was still revised up 4.8% this week. In a weekly window when the index fell, foreign capital flowed out, and technology sold off sharply, earnings were still being revised higher. This shows that Korea’s fundamental pressure has not deteriorated in sync with price pressure.
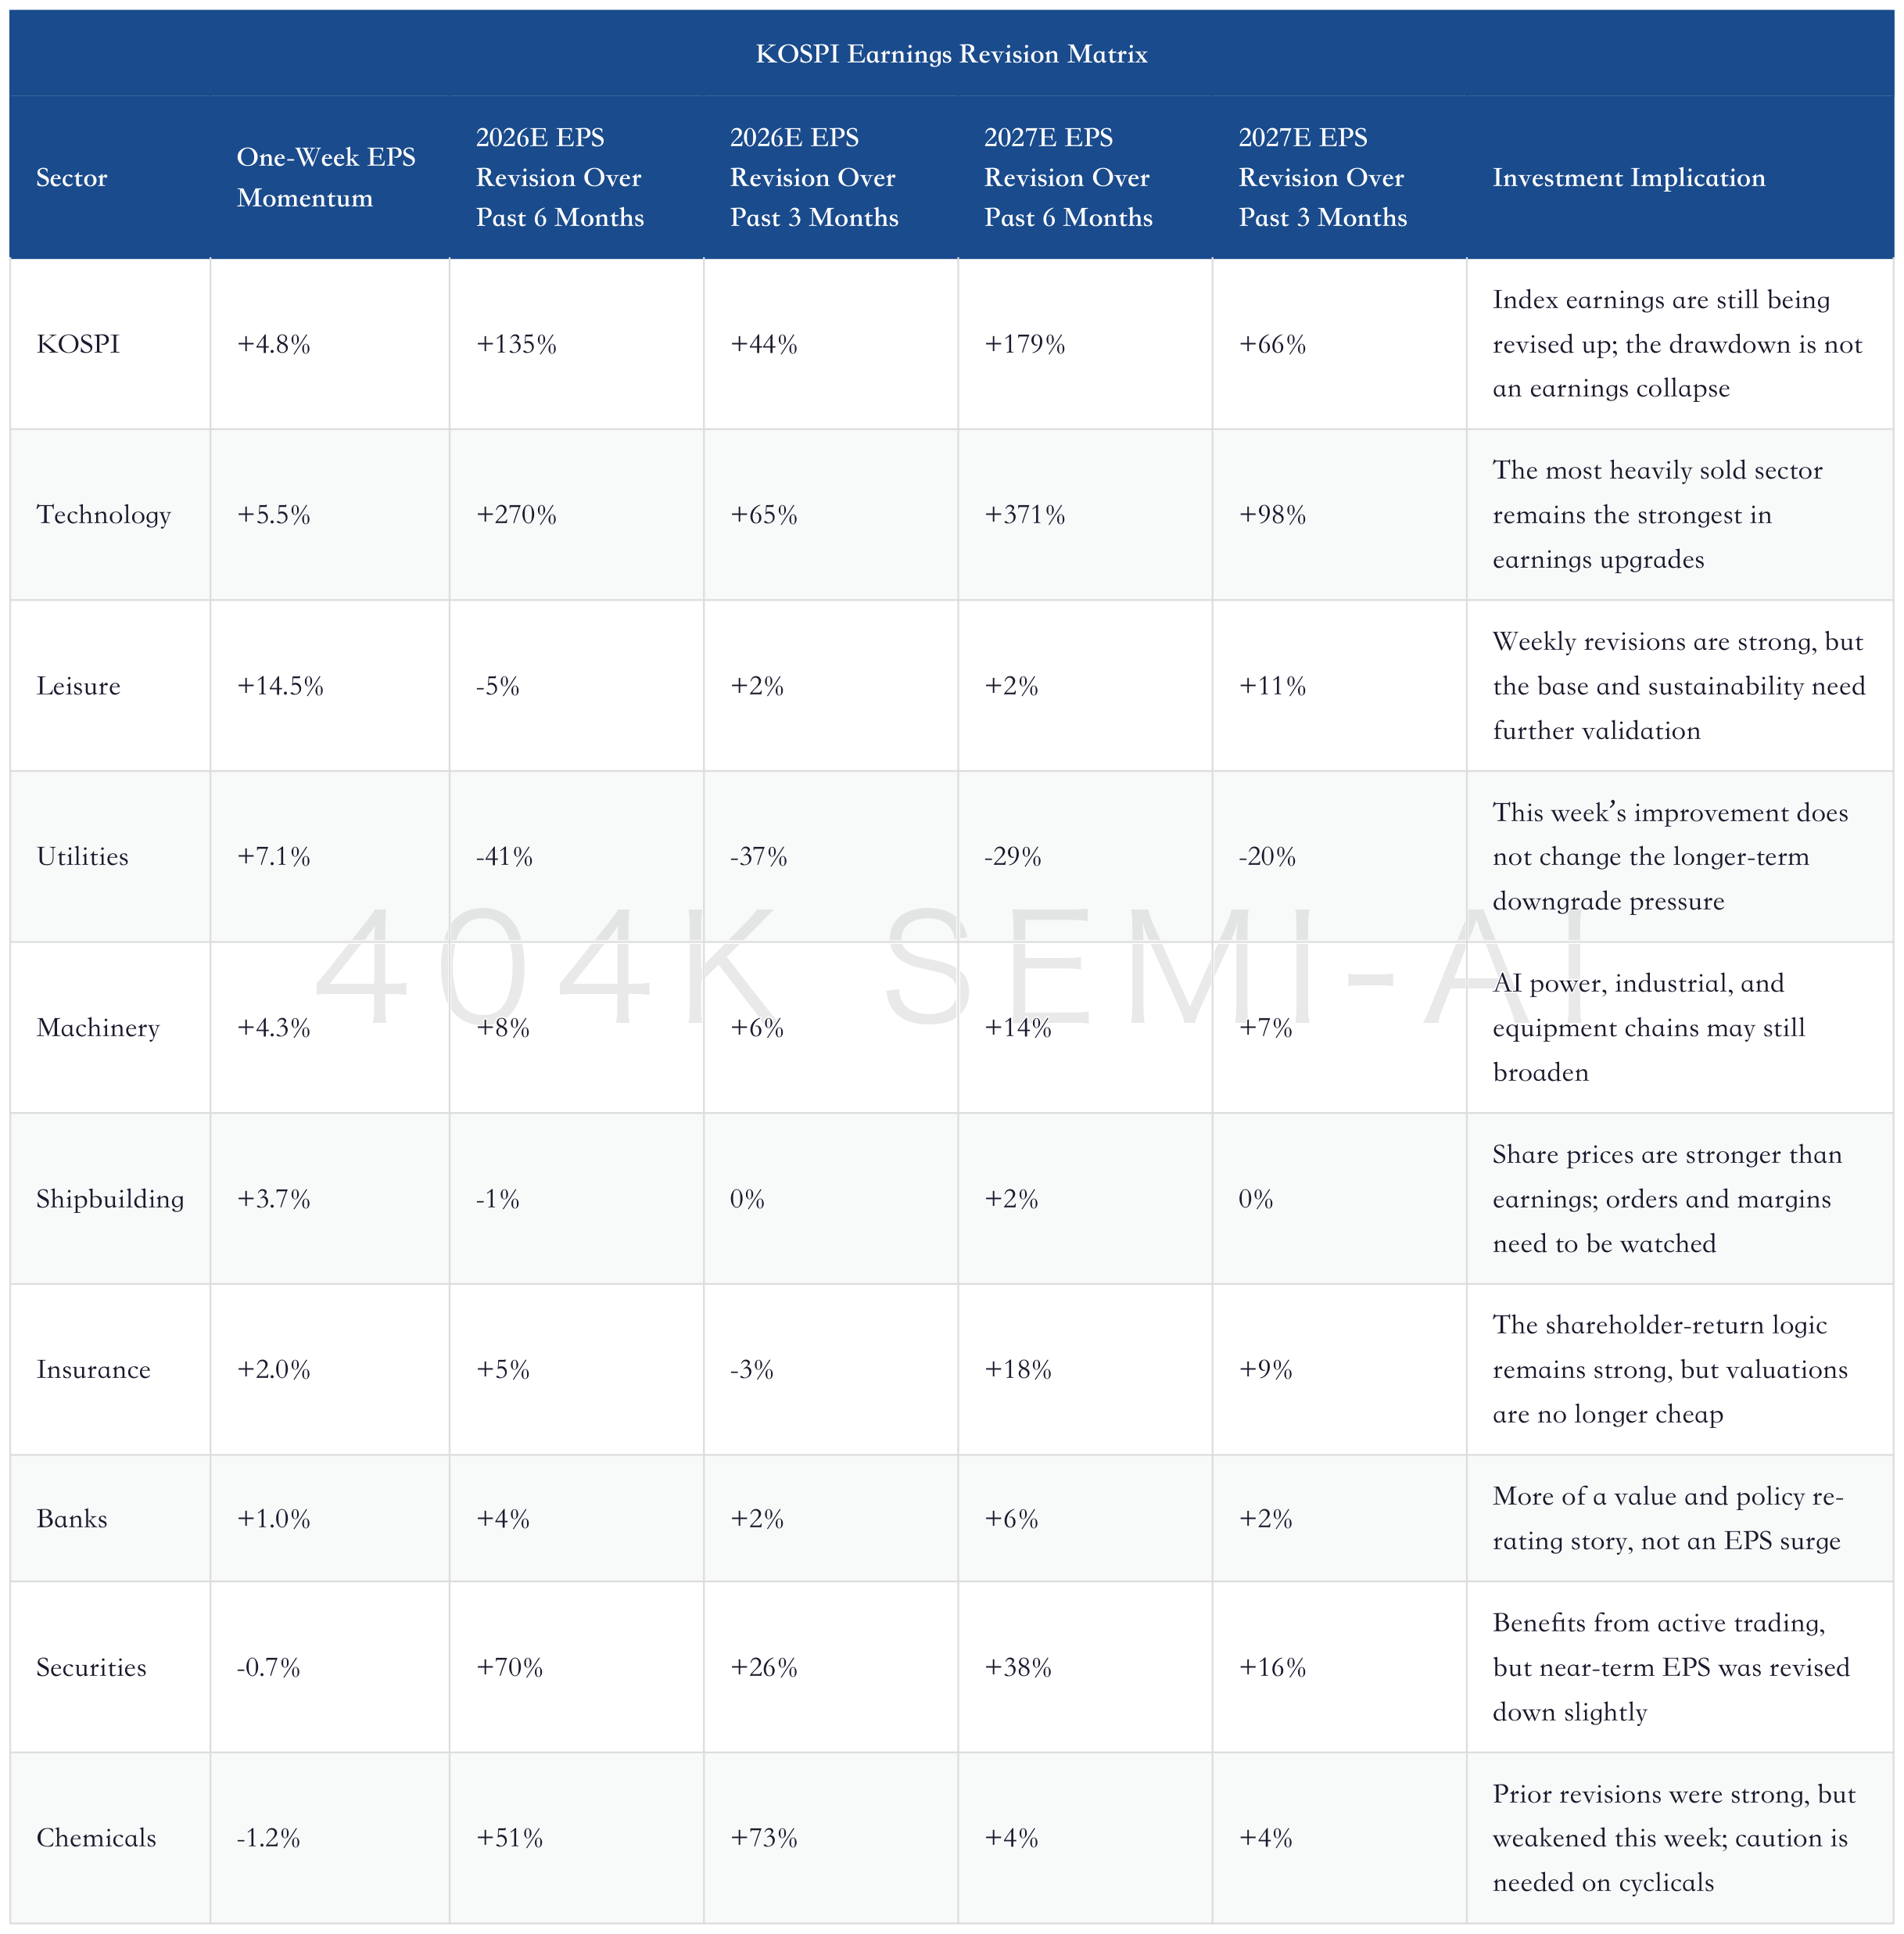
This table provides an asset-ranking framework. The first priority is still technology, because it combines the largest earnings upgrades with the largest valuation discount. The second priority is machinery, selected equipment names, and the power chain, which can absorb the spillover from AI data centers, semiconductor capex, and industrial automation. The third priority is financials and insurance, where the logic is not an earnings breakout but capital efficiency and shareholder returns. The areas requiring the most caution are chemicals, utilities, and segments relying only on low-valuation catch-up. They may have near-term beta, but their long-term narrative is unclear.
Deep Update on Korea Technology Exports: Memory Exports +280% YoY, MLCC +31% YoY, and How the AI Hardware Surplus Flows Into the Income Statement
The divergence in technology is especially sharp. Technology fell 7.6% in one week, but 2026E EPS has been revised up 270% over the past six months, and 2027E EPS has been revised up 371% over the same period. In other words, the market is not selling technology because it cannot see earnings. It is selling because technology positioning is too crowded, the rally has been too steep, and foreign investors need to manage risk budgets. As long as DRAM, HBM, SSD, MLCC, and WFE continue to validate, the technology decline looks more like a reset in valuation and positioning. Once earnings revisions stall, however, the selloff will be reinterpreted as a cycle peak.
IV. Flows: KRW 19.9 Trillion of Foreign Selling Was Almost Entirely a Technology De-Risking
Flows are the second core driver of this drawdown. Foreign investors net sold about KRW 19.9 trillion of KOSPI stocks in one week, reaching -3.1 standard deviations. In the same week, institutions net bought about KRW 8.2 trillion, and retail investors net bought about KRW 11.1 trillion. In other words, the marginal pressure behind the index decline came from foreign investors, while local capital provided the absorption.
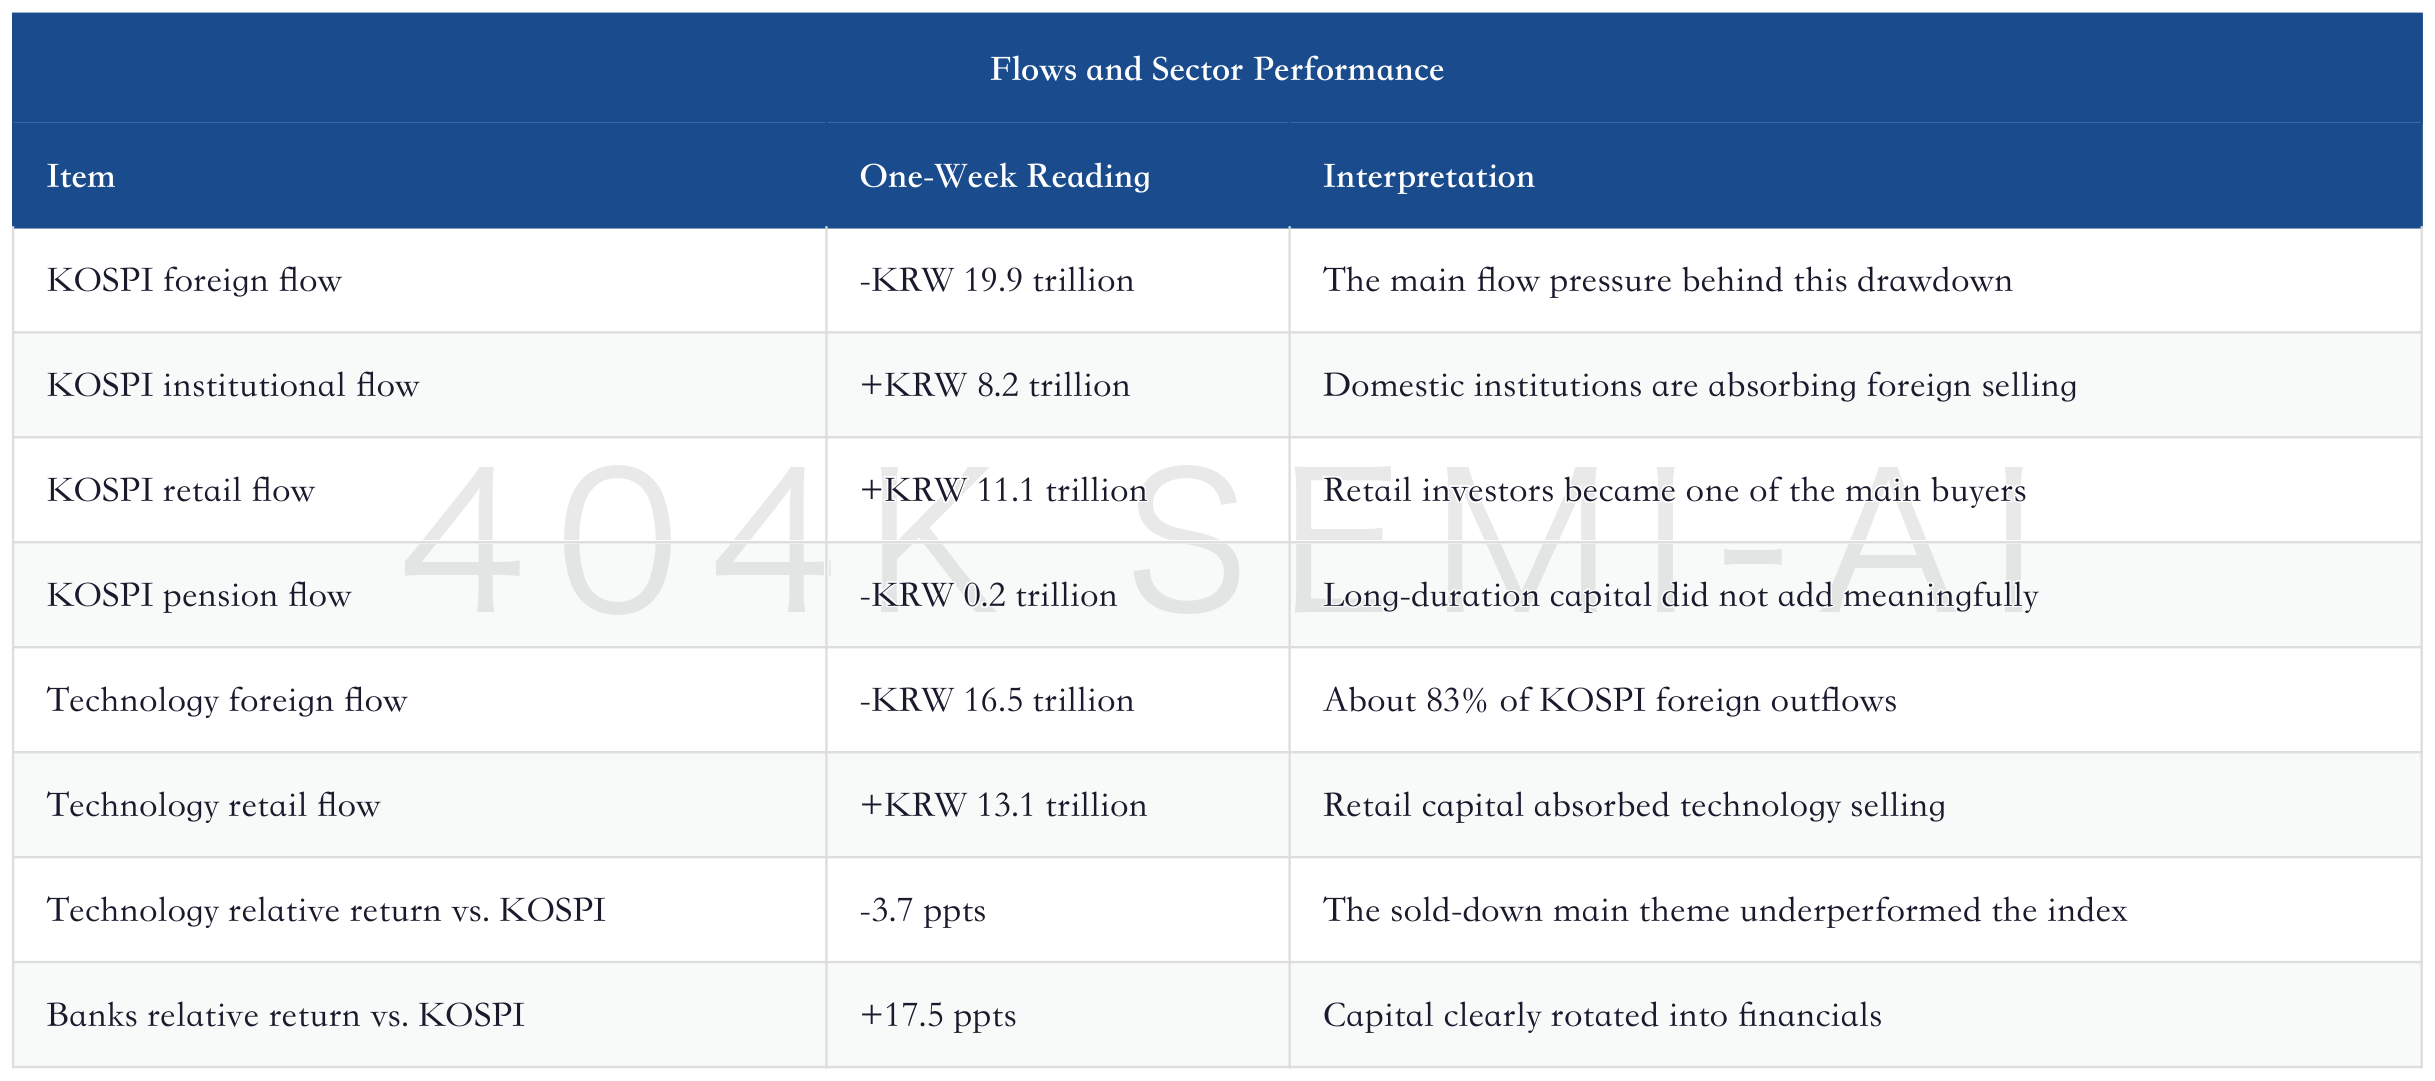
The key signal in this data is not “foreign investors are selling Korea,” but “foreign investors are mainly selling technology.” If foreign investors were retreating across all sectors, banks, securities, and leisure would have struggled to post double-digit positive returns. The current pattern looks more like overseas capital rapidly reducing Korea technology exposure, while domestic capital absorbs the selling and some capital rotates into financials and under-owned sectors.
There are two possible paths from here. The optimistic path is that foreign technology selling narrows, retail capital does not get trapped, technology EPS continues to be revised upward, and the index resumes its uptrend. The pessimistic path is that foreign investors continue selling technology, retail absorbs too much, the pace of technology earnings upgrades slows, and the index shifts from “foreign selling, domestic buying” to “domestic capital cannot absorb it.” Over the next two to three weeks, the most important thing to watch is not whether KOSPI rebounds, but whether foreign net outflows from technology can narrow meaningfully from the KRW 16.5 trillion level.
Foreign ownership also offers a reference point. Foreign ownership is about 40% for KOSPI, about 59% for banks, about 46% for technology, about 42% for telecoms, and about 31% for autos. Foreign ownership in technology remains high, but there is still room for adjustment. Banks have even higher foreign ownership yet rallied sharply, showing that foreign investors are not simply selling by ownership ratio. They are adjusting risk factors. Technology represents AI hardware beta, while banks represent value and policy beta. This week, the market clearly preferred the latter.
Deep Dive on Korea’s AI Surplus: How the Memory Supercycle Re-Rates Fiscal Policy, Rates, and the Won
The won is another key to the flow picture. The weekly report shows USDKRW at about 1531. The won strengthened slightly by 0.3% against the dollar, but the absolute level remains high. Foreign investors buying Korea need to assess both equity returns and FX returns. When global technology volatility rises, pressure on the won amplifies the speed of de-risking. If USDKRW falls back from around 1530, the probability of foreign investors covering technology increases. If the won continues to weaken, Korea’s low valuations may continue to carry an FX discount.
V. Sector Rotation: Catch-Up in Banks, Securities, and Leisure Does Not Mean the Technology Theme Is Over
The strongest sectors this week were banks, securities, and leisure, while the weakest were technology, insurance, and retail. This rotation is highly informative: the market has not moved into broad risk aversion. Instead, it is rotating from technology, which has high crowding, high foreign ownership, and high AI beta, into areas with lower valuations, greater policy sensitivity, and higher trading activity.
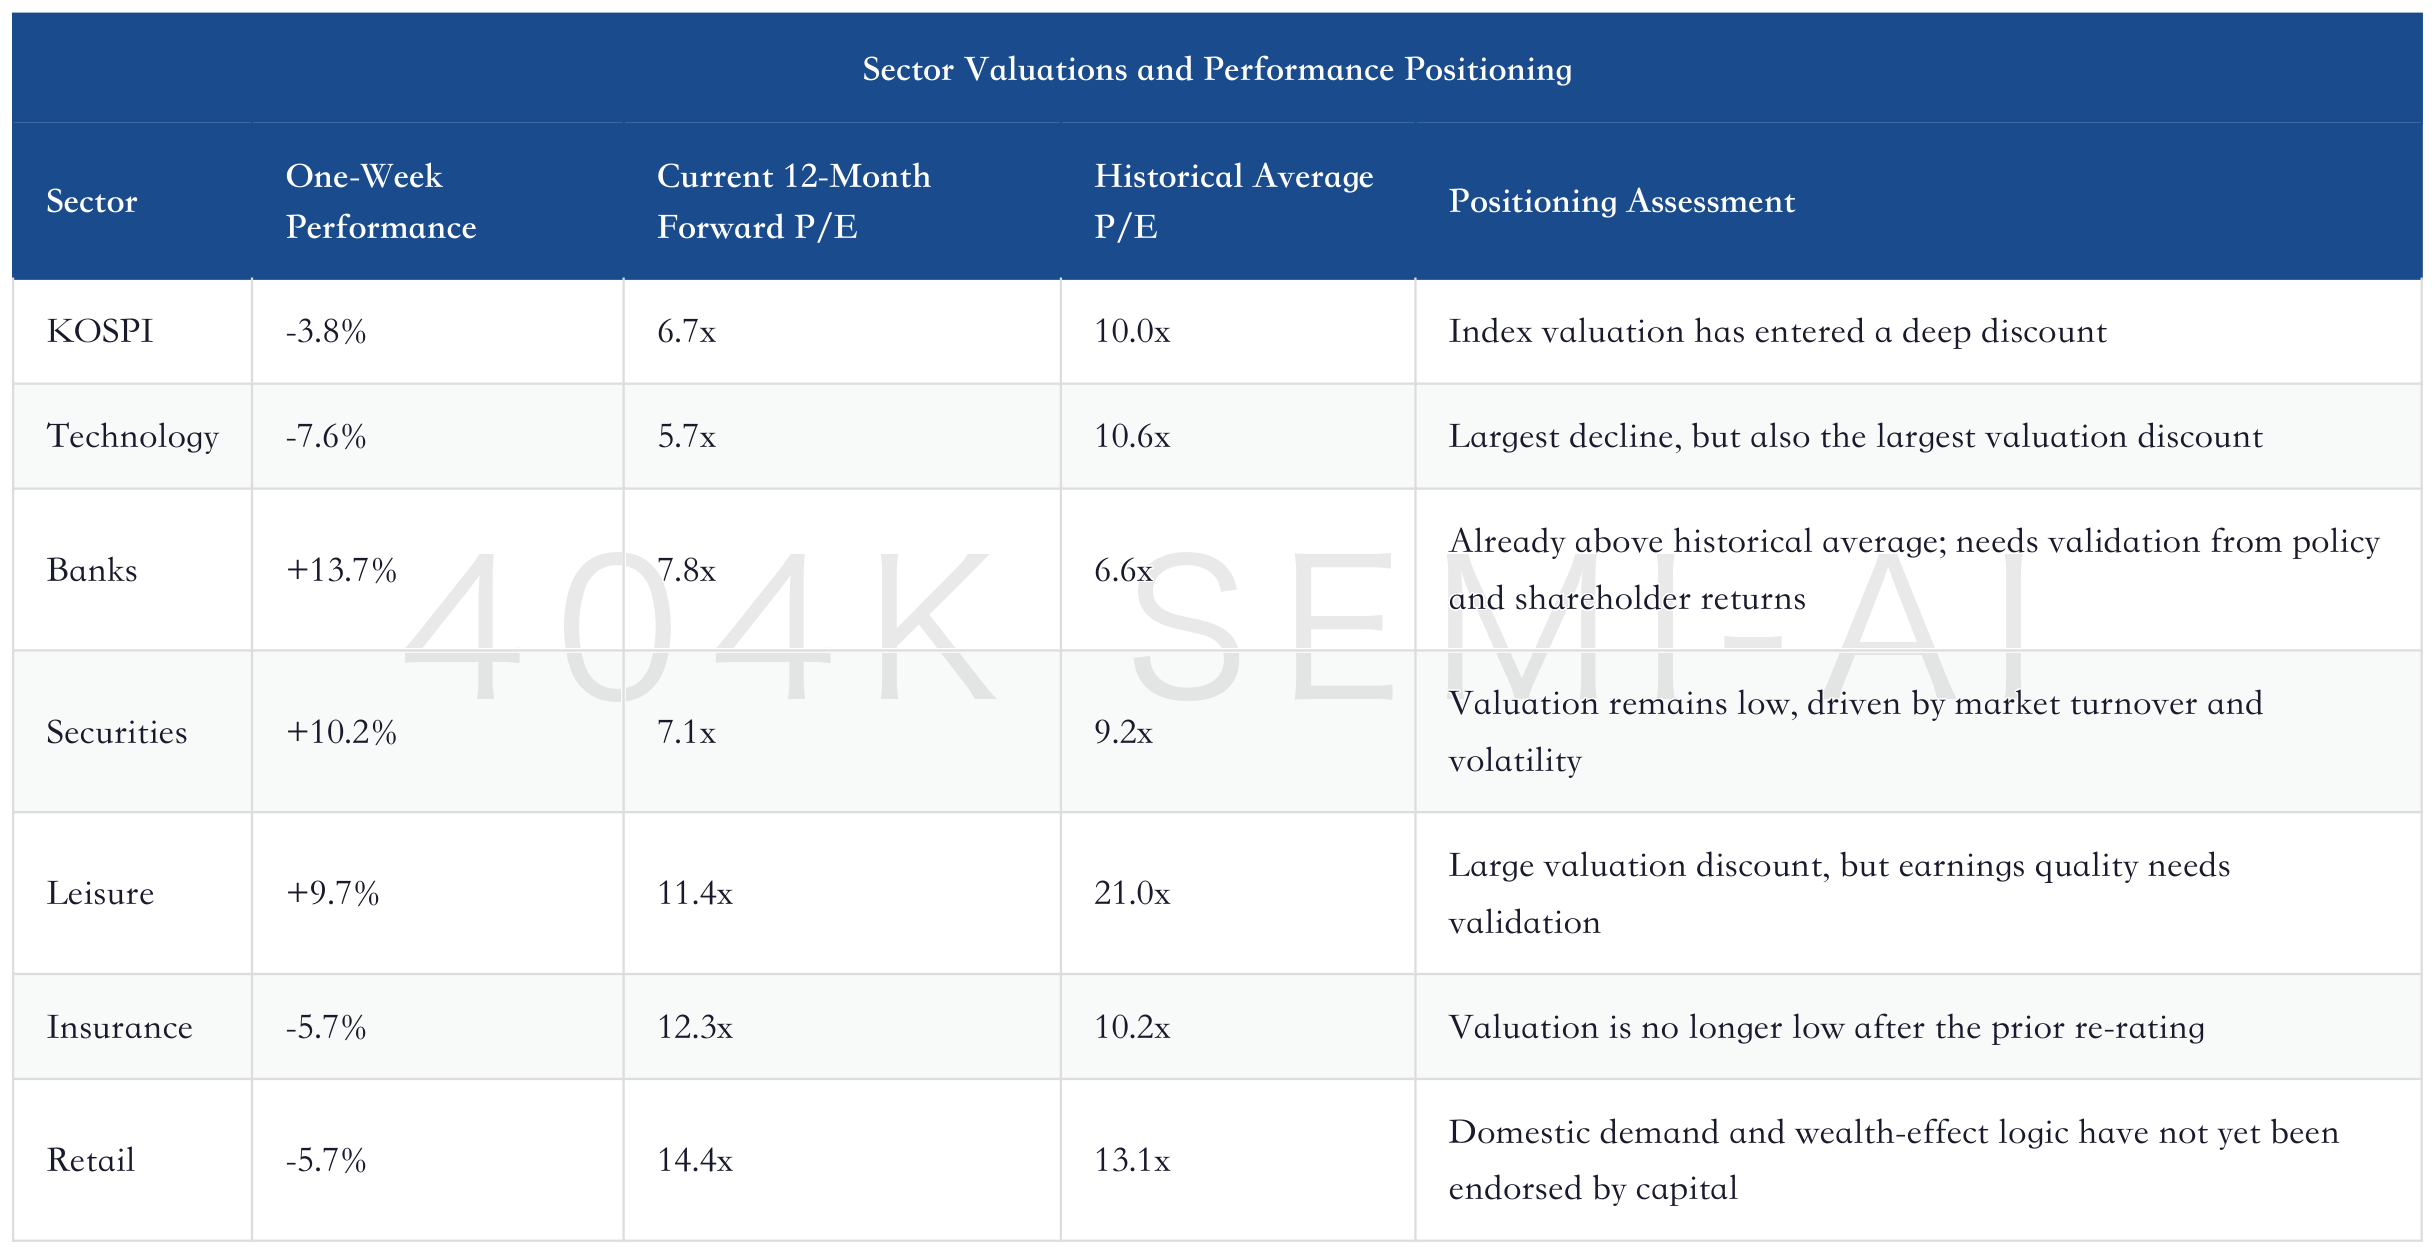
The rally in banks shows that Korea’s “value-up” and financial re-rating logic is still alive, but banks are no longer especially cheap. The rally in securities looks more like a response to market turnover and volatility, with beta more dependent than banks on the trading environment. The rise in leisure may be related to low positioning, policy, and consumption expectations, but it is not Korea’s AI hardware main theme.
Technology had the largest decline, but that does not mean the technology theme is over. Technology’s current 12-month forward P/E is about 5.7x, below its historical average of 10.6x and below the roughly 6.1x level near -1 standard deviation. This valuation means the market has already priced in concerns that “current earnings are unsustainable.” Going forward, as long as earnings are not revised down materially, technology is instead the area with the clearest payoff profile. If earnings are revised down, technology will become the area most vulnerable to further valuation compression.
