
Korea Market Deep Dive: KOSPI Pulls Back 7%, VKOSPI Hits a High. Can AI Memory Earnings Still Support the Re-rating?
目录
TL;DR
1. This Pullback Needs to Be Split Into Three Layers
2. The Market Cut Risk Premium First; the Earnings Anchor Remains
3. Micron’s Results Are an External Stress Test for Korean Semiconductors
4. Retail Has Not Fully Lost Control; Market Fragility Comes from Structural Amplification
5. Foreign Outflows Reflect a Pricing Disagreement, Not Necessarily Deteriorating Fundamentals
6. Valuations Still Provide a Buffer, but Cheapness Does Not Automatically Resolve Volatility
7. AI Memory Remains the Main Line, but the Main Line Is Entering the Delivery Phase
8. The Volatility Spike Shows the Market Is Starting to Price “Speed Risk”
9. Korea’s Macro Base: Strong Exports, Weak Won, and Persistent Rate Constraints
10. Three Scenarios: What Really Matters Is the Earnings Slope
11. Which Assets Can Better Withstand the Stress Test
12. Risk Checklist: The Biggest Concern Is Deteriorating Earnings Signals
13. What to Watch Over the Next Four Quarters
14. Korea’s Re-Rating Also Has a Non-Technology Leg
15. Differences Between Korea, Taiwan, and Japan
16. What Needs to Happen for This Pullback to End
17. Investment Implications of This Report
18. Falsification Paths: What Would Truly Break the Thesis
19. Conclusion: KOSPI Enters an “Earnings Verification Period”
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
This pullback has exposed two main threads at once: AI memory is still lifting Korea’s earnings center of gravity, while Micron’s results and export data continue to support the semiconductor chain; but foreign outflows, retail absorption, and leveraged ETFs amplifying volatility have started to test the quality of the KOSPI re-rating. The key from here is whether earnings upgrades can outweigh the rise in volatility.
TL;DR
Start with the structure. KOSPI is down 7.1% over one week, but forward EPS is still being revised upward. The market has first cut the risk premium; the earnings anchor has not yet broken. The next test is whether semiconductor earnings can keep validating.
Micron provides validation. Micron’s strong results, long-term agreements, and view on supply-demand imbalance push AI memory from quarterly price hikes toward longer visibility. Korea semiconductor earnings upgrades still have external evidence.
The flow structure has become fragile. Foreign investors have sold heavily, retail investors have absorbed supply, and leveraged ETFs and derivatives have amplified volatility. The short-term decline is jointly determined by positioning, volatility, and rebalancing.
Retail has not lost control. Retail ownership is only slightly above average, margin loans as a share of deposits have fallen, and retail turnover share has declined. The risk comes from structural amplification and should not be attributed entirely to retail investors.
Valuation still has a buffer. The Korean market remains in a low-valuation range, and the technology sector has not entered extreme overvaluation. Cheap valuation still needs to be delivered through EPS, cash flow, and capital returns.
Macro remains supportive. Exports, the current account, and AI memory prices are still supporting Korean earnings, but a weaker won and higher rates will affect foreign-investor returns and constrain valuation multiples.
Watch three items next. Track earnings revisions for SK hynix/Samsung Electronics, the retreat in VKOSPI, and foreign flows into technology. If all three improve, the pullback looks more like pressure release; if they weaken together, the re-rating enters a digestion phase.
1. This Pullback Needs to Be Split Into Three Layers
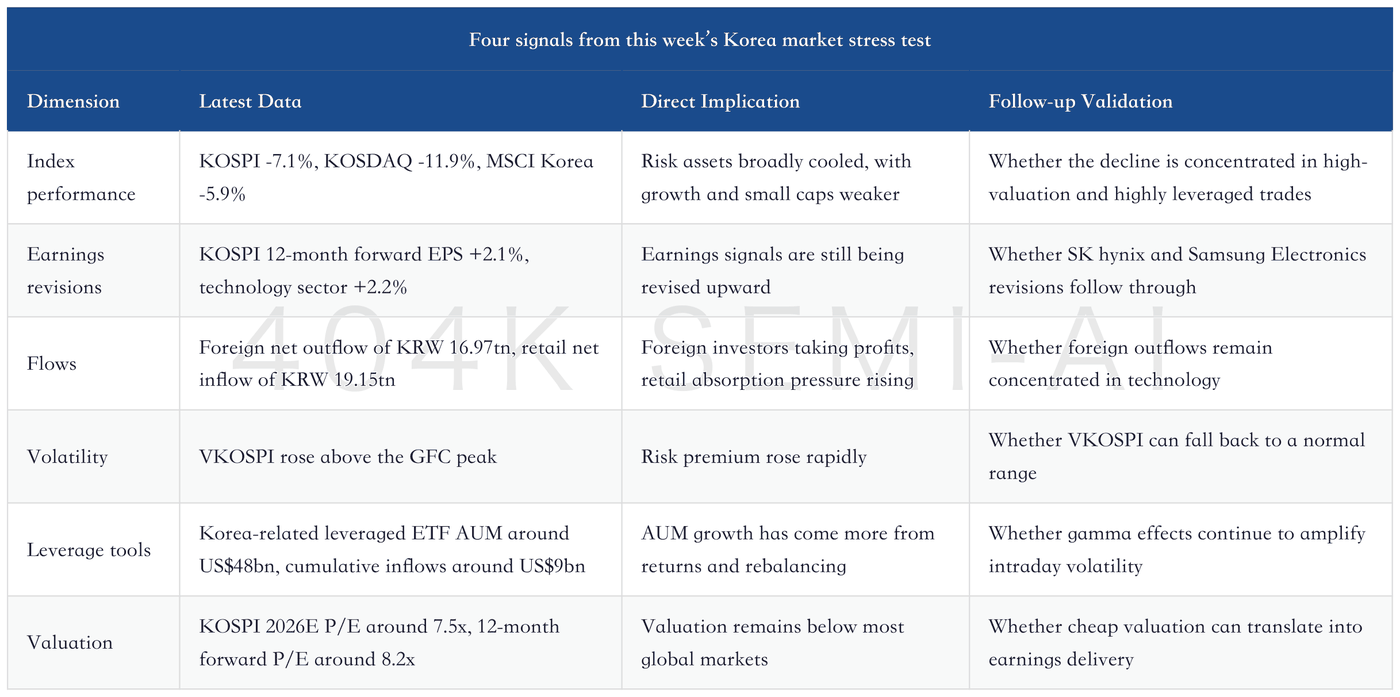
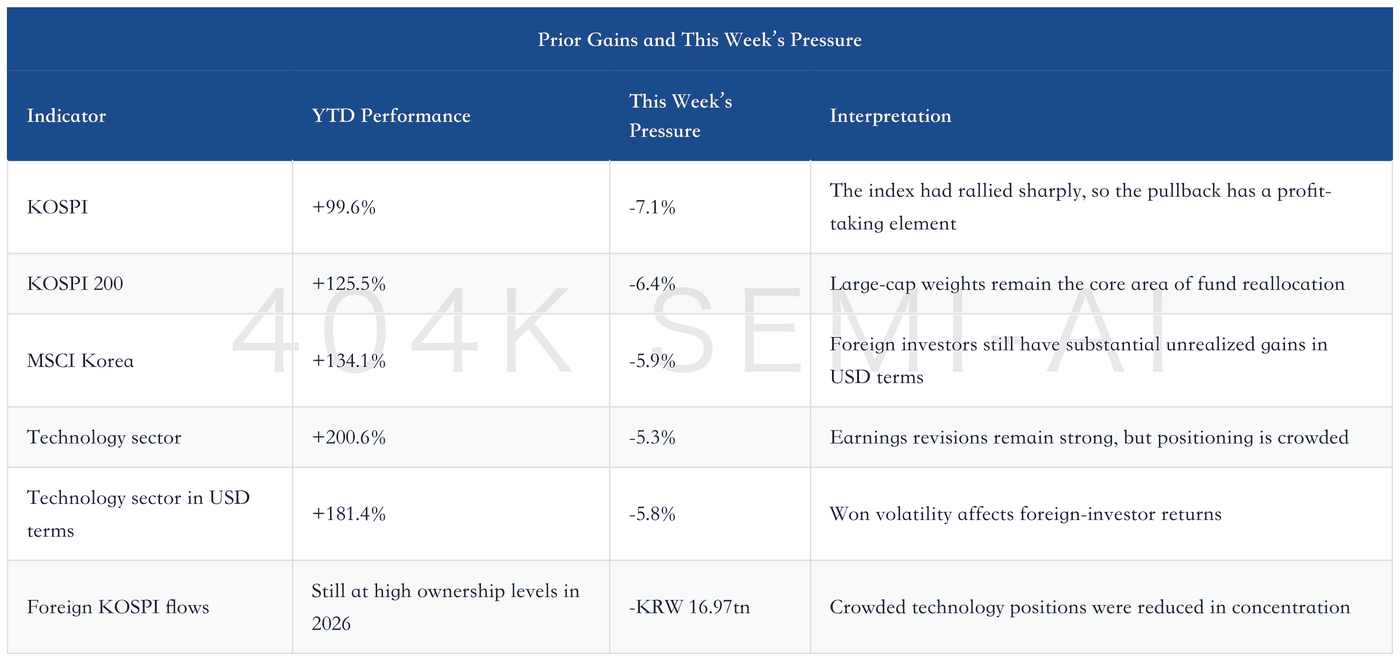
KOSPI has fallen sharply over the past week and needs to be broken down into several variables. The index fell 7.1%, KOSDAQ fell 11.9%, and MSCI Korea fell 5.9%. Autos, shipbuilding, machinery, and other earlier high-beta sectors fell even more. At the same time, while the technology sector also declined 5.3%, it still outperformed KOSPI by 1.8 percentage points. The market is reclassifying “assets whose earnings can still be revised up” versus “assets whose prices had already run too far.”
The most useful part of this Goldman Sachs weekly report is that it puts declines, volatility, flows, and earnings into the same frame. KOSPI pulled back over one week, VKOSPI rose to an area above the global financial crisis peak, foreign investors turned net sellers, and retail investors absorbed substantial outflows. But at the same time, KOSPI 12-month forward EPS was revised up 2.1%, with the technology sector seeing the largest upgrade. This combination is crucial. Market prices are retreating, while earnings expectations are still advancing.
KOSPI declined by 7% amid VKOSPI rising to the highest level despite strong earnings release by Micron Technology. Foreign investors turned to sell the KOSPI market, driven by outflows for KOSPI Tech. KOSPI 12m-forward EPS was revised up by +2.1%.
Put more directly, this does not prove that “the Korea AI story is over.” It looks more like a stress test: when the index has already risen a lot, positioning is crowded, and participation by retail investors and leveraged tools has increased, the market needs to verify what is actually supporting this rally. If the answer is only liquidity, the pullback will become a trend reversal. If the answer is still earnings upgrades, the pullback will force the market to re-rank earnings quality.
This piece addresses four questions: What exactly is KOSPI cutting in this decline? Why can Micron’s results still support Korean semiconductor earnings? Have retail investors and leveraged ETFs pushed the rally into a danger zone? Can the Korean equity re-rating continue to be supported by AI memory, exports, and capital-market reform?
2. The Market Cut Risk Premium First; the Earnings Anchor Remains
When assessing a sharp sell-off, the biggest mistake is to look only at index levels. Index levels tell you prices have changed; they do not tell you why. The combination provided in this Goldman Sachs report is: prices fell sharply, volatility surged, the flow structure deteriorated, but earnings revisions remained positive. This means the market has temporarily cut the risk premium, but has not yet disproved the earnings anchor.
This distinction matters. Risk premium can change very quickly, especially in a market like Korea, where technology weight is high, foreign ownership is high, and derivatives and leveraged products are active. A severe repricing can be completed within a few days. The earnings anchor changes much more slowly and requires shifts in orders, prices, capacity, inventories, exchange rates, and customer capex. As long as the earnings anchor is still being revised upward, an index pullback is more about the market demanding a higher margin of safety. Only when the earnings anchor starts to be revised down does the asset’s character deteriorate.
Goldman Sachs data show that KOSPI 12-month forward EPS was revised up 2.1% this week, the technology sector was revised up 2.2%, chemicals were revised up 0.9%, and retail and brokers were also revised up slightly. Machinery saw the largest downgrade, while autos and shipbuilding also had weak price performance. This structure shows that the market has not indiscriminately rejected Korean earnings. It is reconfirming which earnings thread is more robust and which is more dependent on sentiment and forward order assumptions.
More importantly, earnings revisions in Korean technology are not happening in isolation. Micron’s results provided external validation, and Korea’s exports for the first 20 days of June rose 8.7% month-on-month on a seasonally adjusted working-day basis, a clear acceleration from 3.1% in the previous month. Export data and Micron’s guidance point in the same direction: AI servers, data centers, and memory shortages are still lifting earnings expectations for Korea’s semiconductor chain.
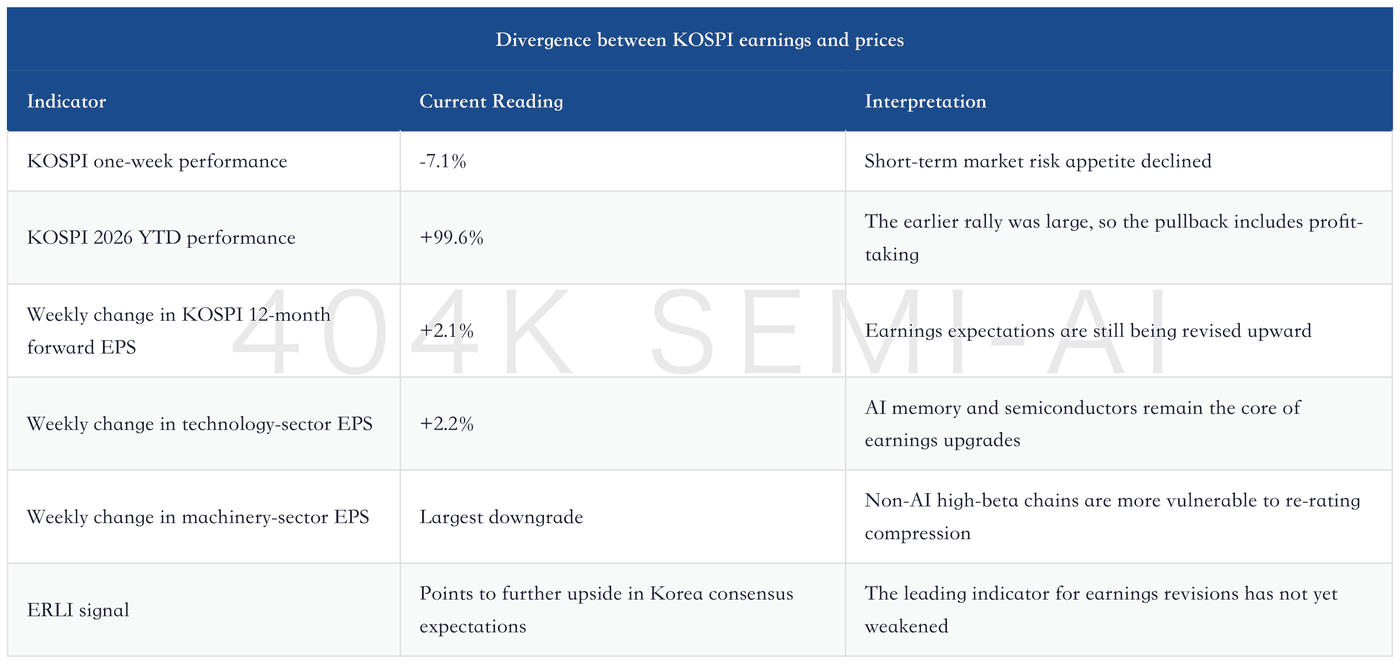
This is also why the report should not be framed as “the Korean market has collapsed.” A more accurate description is: after the first stage of the Korean market re-rating has been completed, the market is entering the phase of “can earnings delivery catch up with valuation and flows?” In the earlier stage, prices could react quickly as long as investors saw AI, memory, foreign inflows, and the reform narrative. Now that prices have already reacted substantially, the market is asking companies to prove the story through EPS, cash flow, orders, and exports.
3. Micron’s Results Are an External Stress Test for Korean Semiconductors
Micron is a U.S. memory vendor, but it is the most useful external anchor for assessing Korean semiconductor earnings. The reason is straightforward: memory supply-demand, pricing, long-term agreements, and capacity timing are globally synchronized. If Micron sees demand materially above supply and expects that imbalance to extend beyond CY27, it is hard for Samsung Electronics’ and SK Hynix’s earnings models to fully decouple.
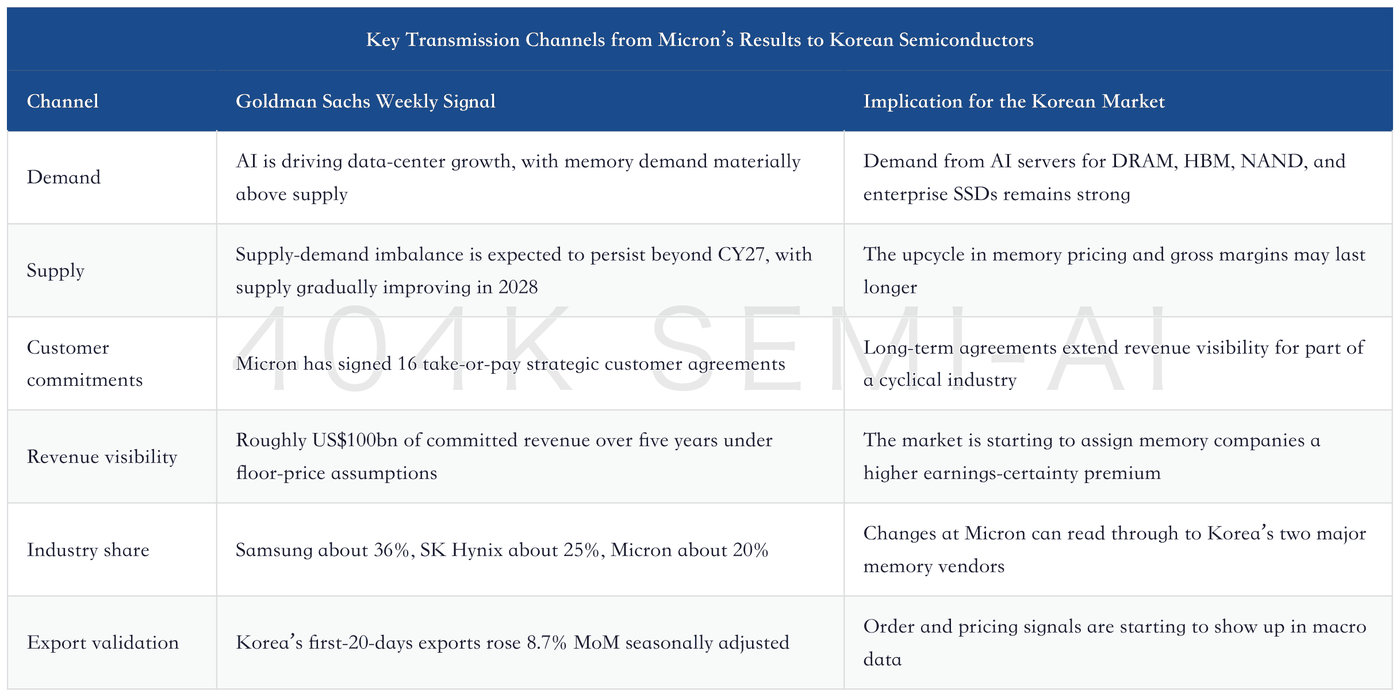
Goldman Sachs highlighted in its weekly report that Micron’s 3QFY26 revenue and next-quarter guidance were both materially above Visible Alpha consensus. More importantly, Micron management explicitly said AI is driving data-center growth, memory demand is materially above supply, the supply-demand imbalance is expected to persist beyond CY27, and supply will only gradually improve in 2028. That shifts the market’s focus from “can prices rise next quarter?” to “how long will memory supply constraints last?”
Micron stated that AI is driving robust growth in DCs, with Memory demand significantly above supply. MU expects this supply-demand imbalance to persist beyond CY27, with supply expected to improve gradually in 2028. In this vein, the company has now signed 16 take-or-pay strategic customer agreements.
This matters a lot for Korea. Technology has a high weight in the Korean market, while Samsung Electronics and SK Hynix are core suppliers in global memory. If Micron’s strong results were only a single-company share story, the read-through to Korea would be limited; if they reflect a broader supply-demand imbalance across memory, then upward revisions to Korean technology EPS have a fundamental basis.
Goldman Sachs’ chart on 1Q26 DRAM and NAND revenue share also supports this view. Samsung’s combined share is about 36%, SK Hynix’s is about 25%, and Micron’s is about 20%, with the three companies together accounting for about 81%. In other words, Micron’s results are a core signal: they represent direct feedback on pricing, customer commitments, and supply-demand from the world’s No. 3 memory supplier. As long as these three companies are serving the same AI server, data-center, and end-customer base, Korean earnings will be influenced by Micron’s results.
That said, investors need to stay clear-eyed. Long-term agreements improve visibility, but they do not eliminate cyclicality. Memory cyclicality comes from pricing, inventories, customer capex, process migration, and capacity additions. Take-or-pay agreements can lock in part of the volume and price floor and reduce extreme downside risk, but they will not make all customer demand grow linearly forever. What the market now needs to price is how much of the traditional cyclical profit in this AI memory upcycle can be converted into sustainable profit through long-term agreements.
For the KOSPI, Micron matters because it provides evidence that “earnings can still hold up.” This week’s decline in the index does not mean Micron’s results have lost relevance. On the contrary, the fact that the market still fell after Micron’s strong results shows investors are no longer satisfied with a single strong earnings print. They need to see Korean local leaders continue to deliver on orders, ASPs, margins, and cash flow.
4. Retail Has Not Fully Lost Control; Market Fragility Comes from Structural Amplification
Another key focus of Goldman Sachs’ weekly report is whether retail activity has overheated. The answer is more complicated than market intuition suggests. Retail money is indeed very active, with individual investors recording net inflows of about KRW19.15tn this week and absorbing large outflows from foreign investors and institutions. But based on ownership share, margin loans relative to deposits, and trading share, retail has not reached the fully bubble-like state seen in 2021.
Is Retail Investor Activity Overheating? Amid strong retail inflows year-to-date and margin loan balances rising to record levels, investors have been questioning whether retail activity is overheating. However, despite robust YTD inflows, retail investors’ ownership of the Korean equity market remains only marginally above its historical average.
Retail ownership is currently about 11.1%, only slightly above its historical average. Foreign ownership is still about 39.7%, 2.1 standard deviations above the average since 2000. This comparison is interesting: even after substantial recent foreign outflows, the Korean market has not become purely retail-driven. Foreign investors remain an important pricing force in Korean equities. This time, retail investors look more like marginal absorbers rather than the dominant force in the market.
Margin also needs to be broken down. Nominal margin-loan balances look high, but investor deposit balances have risen faster, causing the margin-loan/deposit ratio to decline. Retail’s share of trading has also fallen to 37%, while the trading shares of domestic institutions and foreign investors have increased. This suggests retail enthusiasm is indeed high, but the market’s most fragile segment is not necessarily traditional margin lending.
What really needs monitoring is the structure of leveraged ETFs and derivatives. Korea-related leveraged ETF AUM has risen to about US$48bn, but cumulative inflows are only about US$9bn. That gap shows the increase in AUM reflects a combination of new money, underlying asset appreciation, return compounding, and leveraged rebalancing. When the underlying assets rise, leveraged products passively expand risk exposure; when the underlying assets fall, exposure reduction and hedging accelerate volatility.
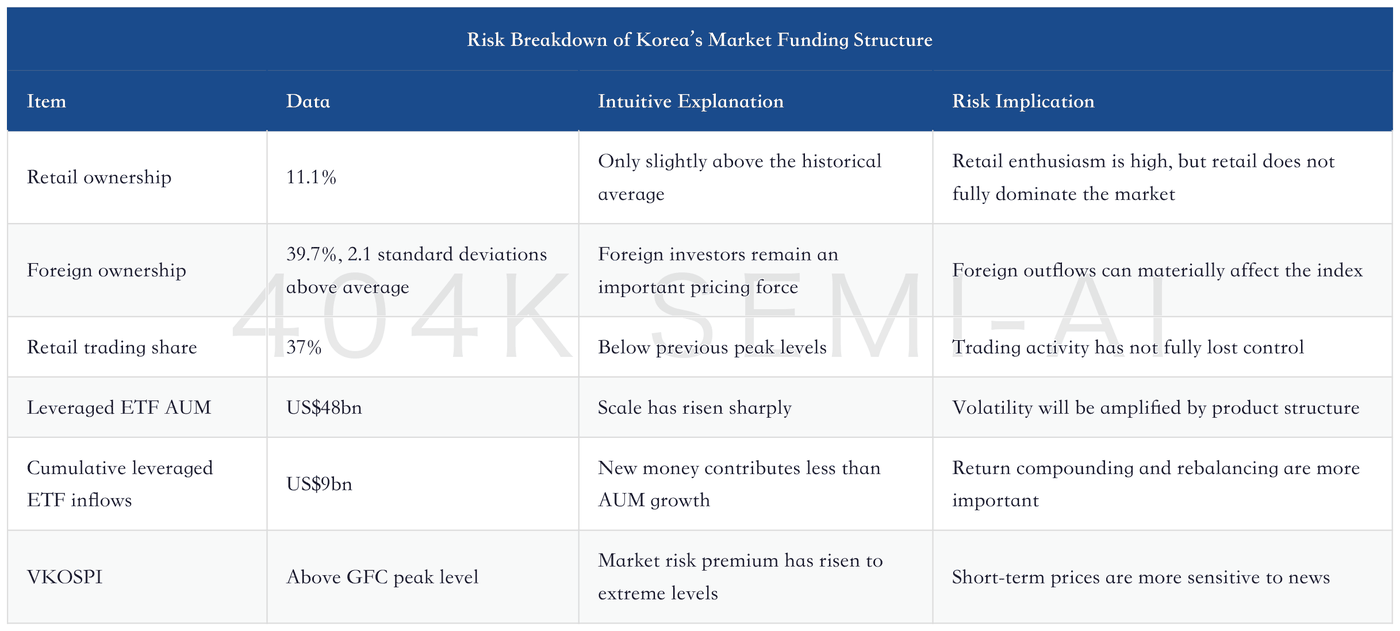
This explains why the KOSPI fell after Micron’s strong results. Positive fundamentals can support earnings expectations, but if the funding structure has already become crowded, any rise in volatility can trigger risk-budget reduction, leveraged-product rebalancing, and profit-taking by foreign investors. Fundamentals determine the medium-term direction; positioning structure determines the short-term magnitude.
5. Foreign Outflows Reflect a Pricing Disagreement, Not Necessarily Deteriorating Fundamentals
Foreign investors recorded net outflows of about KRW 16.97tn from KOSPI this week, with outflow intensity reaching -2.9 standard deviations, mainly driven by outflows from the KOSPI technology sector. The number is alarming, but it does not directly imply that “foreign investors have turned bearish on Korea.” A more reasonable interpretation is that the Korean market has rallied too much this year, the technology chain has contributed too much, and foreign investors first reduced the most crowded positions when volatility spiked.
Judging from prior gains, this round of foreign outflows looks more like concentrated de-risking in previous winners. The market needs to digest the tension between “the rally was too fast” and “earnings remain strong.”
Foreign outflows also need to be viewed in the context of Korea’s external accounts and currency environment. In Goldman Sachs’ macro forecasts, Korea’s 2026 real GDP growth is 2.6%, export growth is 7.2%, and the current account is expected to reach 15.1% of GDP, rising further to 17.9% in 2027. This is a very strong set of external-surplus data. The won weakened 0.5% against the dollar this week, with USDKRW around 1,538. Currency volatility will affect foreign-investor returns, but Korea’s underlying external accounts are not weak.
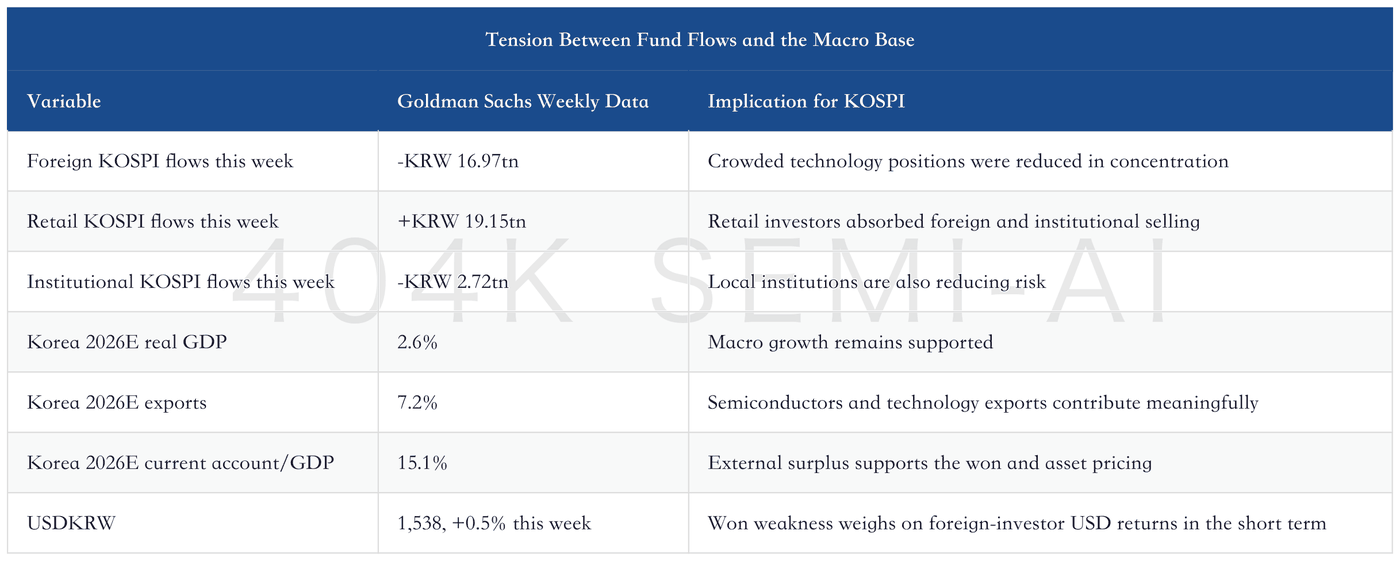
What matters most for foreign outflows is persistence and direction. If foreign investors are merely taking profits in previously crowded technology positions, funds may return to high-earnings-visibility leaders once VKOSPI falls and earnings continue to be revised up. If foreign investors begin to systematically exit all Korean sectors while EPS is revised down, the won remains under pressure, and export data cools, then it would indicate a change in the market’s medium-term pricing of Korean assets.
The core question is who can continue to carry price discovery after foreign outflows. Retail investors can provide liquidity, but without renewed participation from foreign and institutional investors, valuation repair will slow. For the Korean market to continue re-rating, earnings upgrades, foreign inflows, improved index composition, and governance reform need to work together.
6. Valuations Still Provide a Buffer, but Cheapness Does Not Automatically Resolve Volatility
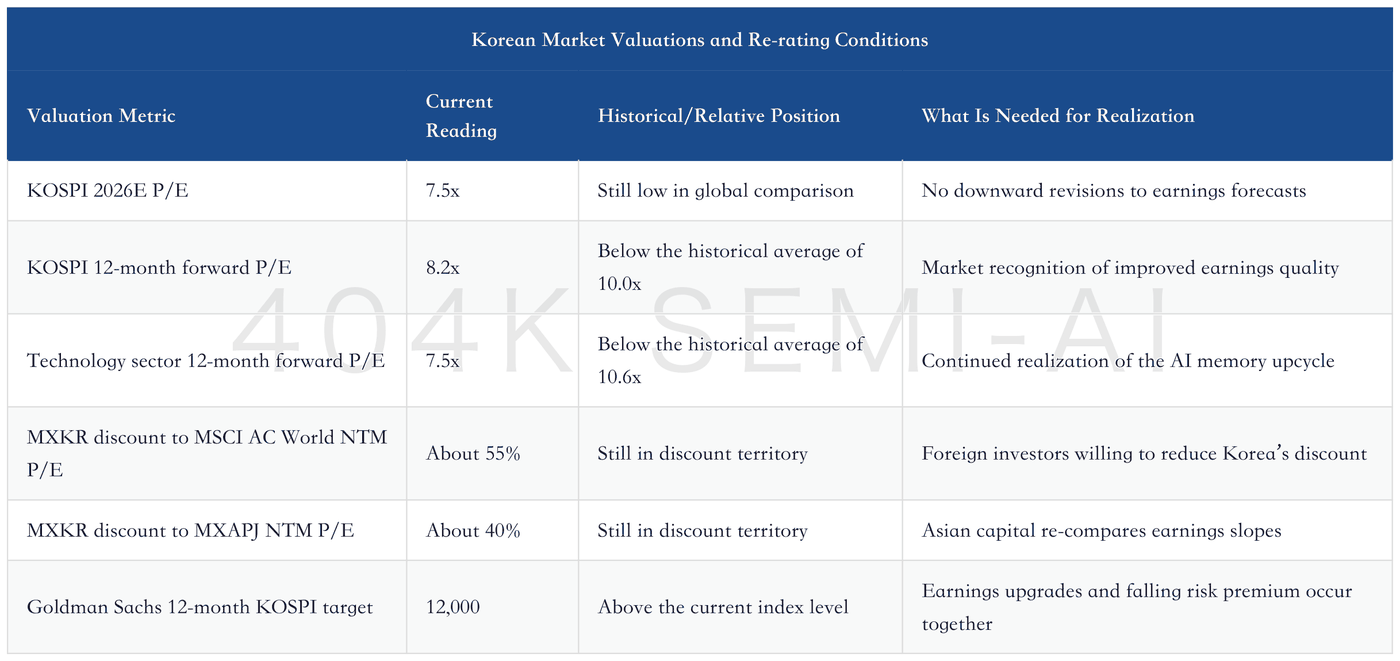
The long-term appeal of the Korean market comes from the coexistence of earnings upgrades and valuation discounts. The specific valuation picture is clearer in the table below than in a long sentence.
This data set shows one fact: Korea has not become the world’s most expensive market simply because of this year’s rally. It remains a low-valuation, high-earnings-beta market. The problem is that low valuation itself does not prevent sharp short-term declines. Low valuation only becomes a real defensive cushion when earnings continue to be revised up, ROE rises, capital returns improve, and foreign investors are willing to assign a higher multiple.
Low valuation can also mean two things. The first is that the market has underestimated earnings quality, which will later be repaired through EPS upgrades and multiple expansion. The second is that the market remains concerned about governance discounts, cyclicality, foreign liquidity, and currency risk, so it is unwilling to assign too high a multiple even when earnings are strong. This round of Korea’s re-rating is testing whether the first explanation can outweigh the second.
Korea’s AI Surplus in Depth: How the Memory Supercycle Is Repricing Fiscal Policy, Interest Rates, and the Won
Goldman Sachs still retains a 12-month KOSPI target of 12,000 in its macro forecast table. This figure shows that, under an earnings-upgrade and valuation-discount framework, institutional reports are still expressing a higher index center of gravity for the re-rating of Korean assets. With KOSPI currently around 8,411, there is still room under this framework, but that room requires three conditions: continued EPS upgrades, lower volatility, and an end to concentrated foreign outflows.
This is also why this sharp decline should not be viewed only as a negative. For a market that has already risen rapidly, a sharp drop forces capital to re-screen. The portion supported by liquidity and narrative will be compressed, while the portion with stronger earnings revisions, still-reasonable valuations, and clearer customer orders will retain a premium. The next phase of dispersion in the Korean market may be more important than the earlier broad rally.
7. AI Memory Remains the Main Line, but the Main Line Is Entering the Delivery Phase
The core logic of the Korean market this year is that AI has pulled memory out of the traditional cyclical industry framework and repositioned it within compute infrastructure. In the past, when the market looked at memory, the focus was inventory, pricing, capacity, and the cyclical bottom. Now it also needs to assess data-center construction, HBM roadmaps, enterprise SSDs, AI inference workloads, long-term customer agreements, and power constraints. Memory is no longer just a tail-end variable of the PC and smartphone cycle. It has become one of the key components determining whether AI capital expenditure can actually be deployed.
AI Drives a Full-Sector Re-rating in Memory: Who Has the Most Pricing Power Across DRAM, NAND, SSD, and HDD, as Samsung, SK Hynix, SanDisk, Western Digital, and Seagate Earnings Cross-Validate Each Other
Korea’s advantage in this chain is clear. Samsung Electronics and SK Hynix are important global suppliers of DRAM, NAND, and HBM; Samsung Electro-Mechanics, materials, equipment, packaging, substrates, and MLCCs also benefit from the AI server hardware upcycle. KOSPI has a high technology weight, so once AI memory earnings are revised up, index beta is very strong. But precisely because the weight is high, once the market starts questioning returns on AI capex, the sustainability of memory price increases, or the quality of long-term customer agreements, the index will also be dragged down quickly.
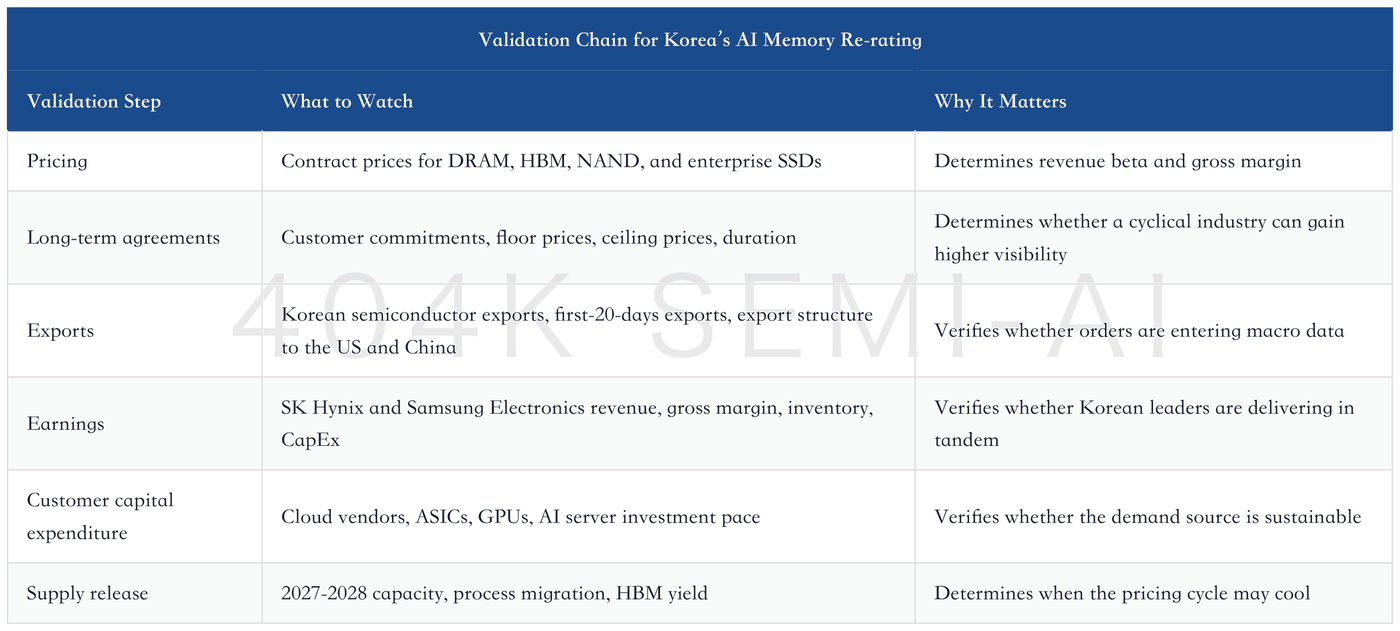
The most important thing to watch in the Goldman Sachs weekly report is the correlation between “Micron earnings revisions” and “KOSPI semiconductor earnings revisions.” The chart shows that after Micron’s strong earnings report, its earnings were revised up sharply, and earnings for the KOSPI semiconductor sector were also revised up in tandem. EPS changes in Korean semiconductors come from the global memory supply-demand mapping and also contain fundamental feedback beyond sentiment transmission from US equities.
Our US semis team highlighted that many of these agreements contain both floor and ceiling prices, and the cumulative amount of committed revenue from these agreements represents c.$100bn over five years at floor prices. As the third largest memory supplier in the world, MU’s earnings are correlated with KOSPI Semi Sector earnings, and were revised up sharply following its strong earnings release. Also, Korea’s per-workday exports in the first 20 days of June rose 8.7% mom sa.
Once the main line enters the delivery phase, however, the market changes the question. Early on, the question was “will AI drive memory?” Now the question is “how much, for how long, who captures the profit, and what multiple should it receive?” At this stage, simply saying AI demand is strong is no longer enough. Three types of evidence are needed: prices continue to rise, orders and long-term agreements convert into revenue, and gross margin and cash flow can withstand fluctuations in customer capital expenditure.
8. The Volatility Spike Shows the Market Is Starting to Price “Speed Risk”
VKOSPI has risen above its global financial crisis peak. This signal should not be dismissed. Volatility directly affects capital behavior. Risk parity, volatility-targeting funds, options market making, leveraged ETFs, margin requirements, and institutional risk budgets all contract when volatility rises.
In other words, the market is now worried about both earnings and the speed of the rally. KOSPI has nearly doubled this year, and the technology sector has risen even more. The larger the prior gain, the more any high-frequency volatility can trigger “protect profits first” behavior. Even if earnings revisions remain positive, capital may still flow out because risk budgets are passively reduced.
This is “speed risk.” It does not necessarily come from negative fundamentals, but it can create short-term drawdowns that fundamentals cannot explain. Micron’s earnings were strong, but the Korean market still fell, because Micron’s earnings explain profits, not all positioning, leverage, and volatility rebalancing.
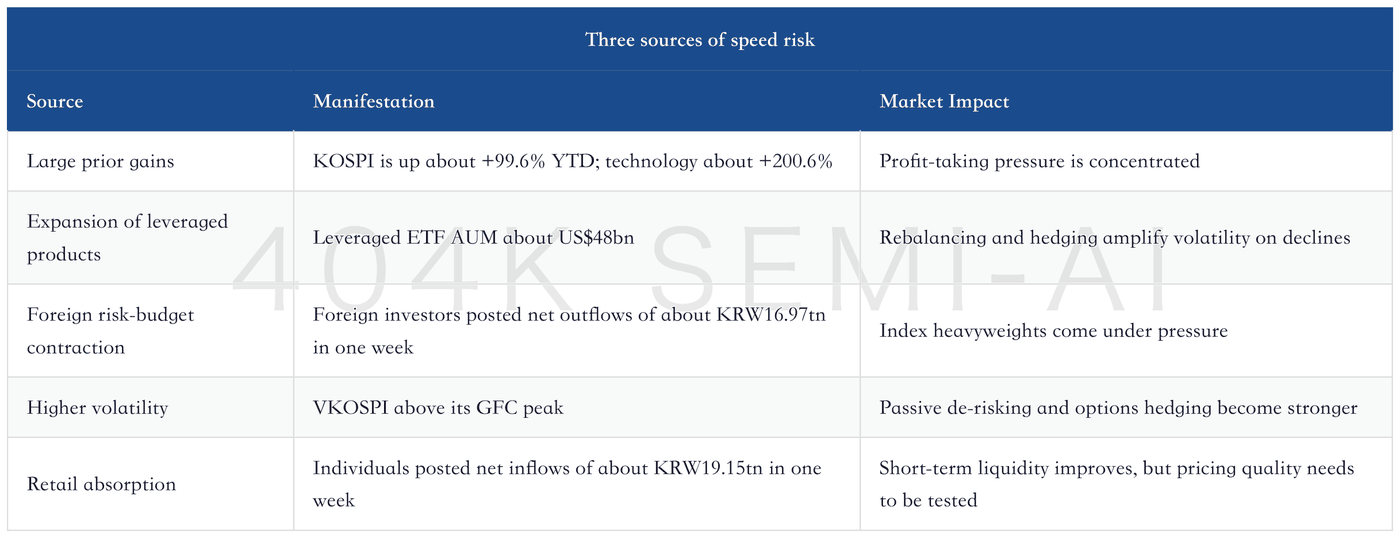
For the market from here, whether VKOSPI can decline matters more than a one-day rebound. If the index rebounds but volatility stays elevated, it means the capital structure remains tight. If VKOSPI falls, foreign selling weakens, and technology EPS continues to be revised up, the market will interpret this pullback as a pressure release.
9. Korea’s Macro Base: Strong Exports, Weak Won, and Persistent Rate Constraints
Korea’s macro base has two sides for this re-rating. The positive side is that exports and the current account are very strong. Goldman Sachs forecasts Korea’s exports to grow 7.2% in 2026, with the current account at 15.1% of GDP, rising further to 17.9% in 2027. If AI storage continues to drive exports, Korea will gain a stronger external surplus, higher corporate profits, and a more stable foundation for asset pricing.
The pressure comes from the won and interest rates. USDKRW was around 1,538 this week, with the won weakening 0.5% against the dollar; YTD, USDKRW is up 6.8%. The Bank of Korea policy rate is around 2.50%, and Goldman Sachs forecasts it will reach 3.00% by year-end. If the won remains under pressure, foreign investors’ dollar returns will be eroded; if rates rise, valuation multiples will also be constrained.
This is also the test that Korea’s AI surplus logic must pass. Higher storage exports can improve trade and the current account, but for the stock market to translate that surplus into higher valuations, it also needs support from the won and capital-market confidence. If export improvement only shows up as higher corporate revenue, the valuation uplift will be limited. If it also brings foreign inflows, household wealth effects, better corporate returns, and governance improvement, the re-rating will be more solid.
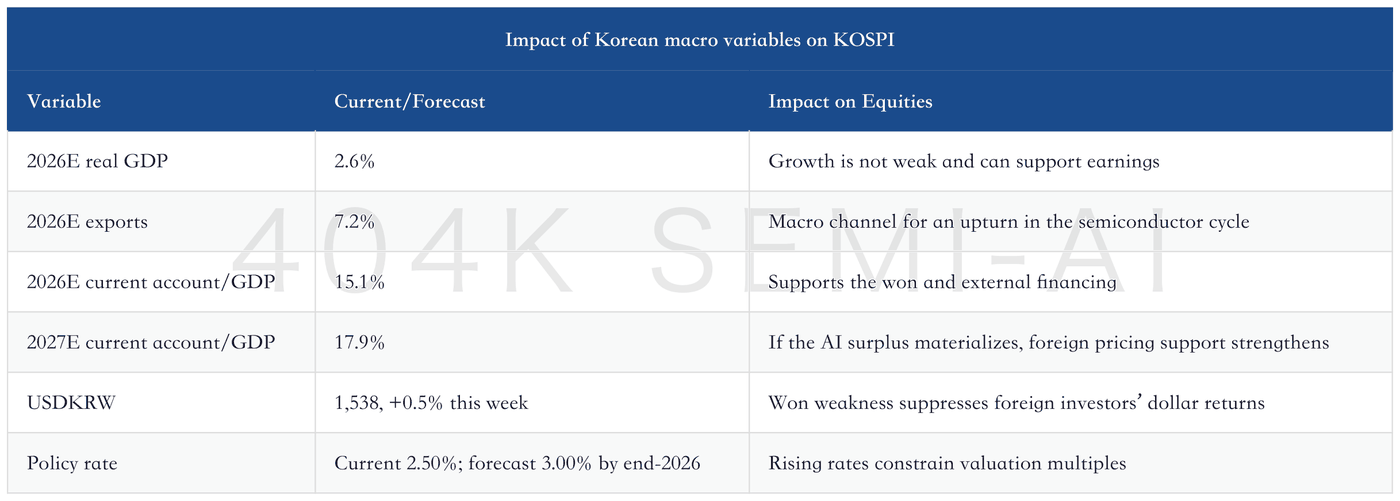
The tension in the Korean market now is that cyclical earnings strength and rate/FX constraints coexist. AI storage brings profits and a surplus; rates and the won affect how many turns of valuation foreign investors are willing to pay. For the index to keep rising, earnings upgrades need to outpace the rise in the risk premium.
10. Three Scenarios: What Really Matters Is the Earnings Slope
After this pullback, KOSPI will most likely enter one of three scenarios. The first is a strong recovery: post-Micron earnings upgrades continue to flow through to Samsung Electronics and SK Hynix, export data remains strong, foreign investors stop concentrated outflows, and VKOSPI falls quickly. The second is high-level consolidation: earnings remain good, but the capital structure is fragile, volatility stays elevated, and the index needs time to digest prior gains. The third is a failed re-rating: storage prices or customer orders fall short of expectations, EPS revisions turn negative, foreign investors continue to sell technology, the won comes under pressure, and the valuation discount widens again.
The key dividing line among these three scenarios is the earnings slope. As long as EPS upgrades persist, the market will look for a new valuation equilibrium. If EPS starts to be revised down, all previous assumptions about index targets, discount convergence, and wealth effects need to be reassessed.
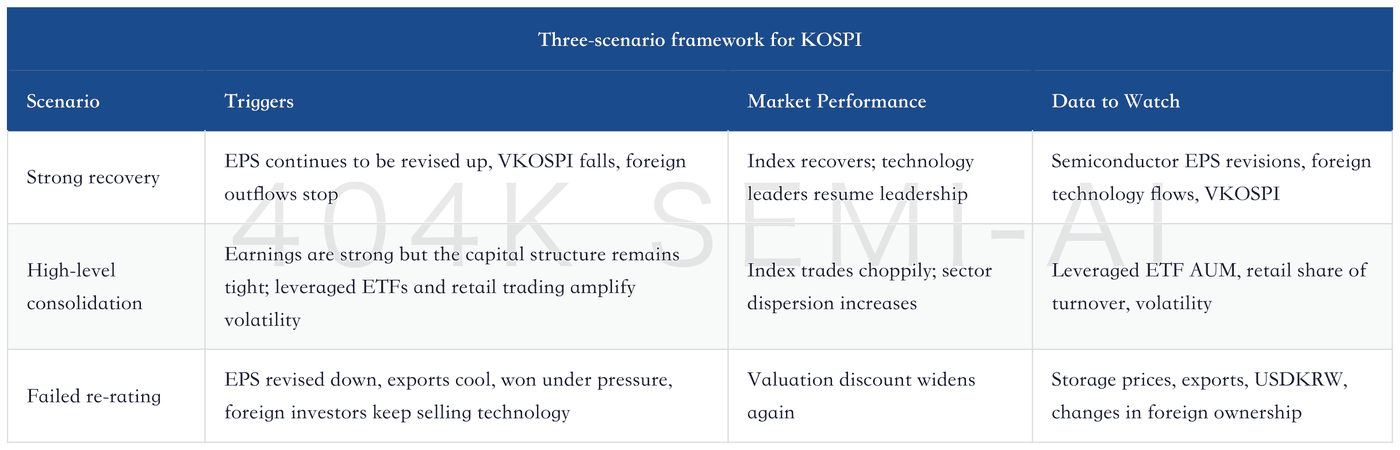
The current stage is closer to a contest between scenario two and scenario one. Earnings data has not deteriorated, but foreign flows and volatility are very poor. The market needs new earnings reports, export data, and fund-flow signals to determine direction. If Korean semiconductor EPS continues to be revised up and VKOSPI falls from extreme levels, the pullback will be reinterpreted as a pressure release during the re-rating. If EPS upgrades stop and volatility stays high, the market will shift to a longer period of sideways digestion.
11. Which Assets Can Better Withstand the Stress Test
This report does not rank individual stocks, but it can separate priorities by asset characteristics. It will be difficult for all themes in the Korean market to keep rising together. After the stress test, what matters more is whose earnings upgrades come from real orders, real pricing, and real cash flow.
The first group is core AI storage supply. Samsung Electronics and SK Hynix represent the earnings anchor of the Korean market. The questions they need to answer are whether HBM, DRAM, NAND, and enterprise SSD prices can continue to improve, whether long-term agreements can raise revenue visibility, and whether customer capex is sufficient to support demand beyond CY27.
The second group is the AI server hardware chain. This includes substrates, MLCCs, advanced packaging, equipment, materials, and testing. The advantage of these assets is broader exposure; the risk is that valuation and order timing are more easily affected by a single customer or a single technology path. After the stress test, the market will care more about order visibility, delivery pace, and capacity utilization.
The third group is the reform and capital-return chain. Korea’s market re-rating does not rely only on technology earnings; it also depends on governance improvement, dividends, buybacks, index inclusion, and capital-market reform. If technology volatility rises, capital may look for financials, telecoms, utilities, and selected consumer names with stable earnings and improving capital returns. In Goldman Sachs’ weekly report, the outperforming sectors this week were retail, utilities, and telecoms.
The fourth group is high-beta non-core chains. Shipbuilding, autos, machinery, software, leisure, and other sectors fell more sharply in this pullback. They are not necessarily lacking fundamentals, but when index volatility rises, the market first compresses valuation and prior gains. A subsequent recovery will require stronger order or earnings evidence.
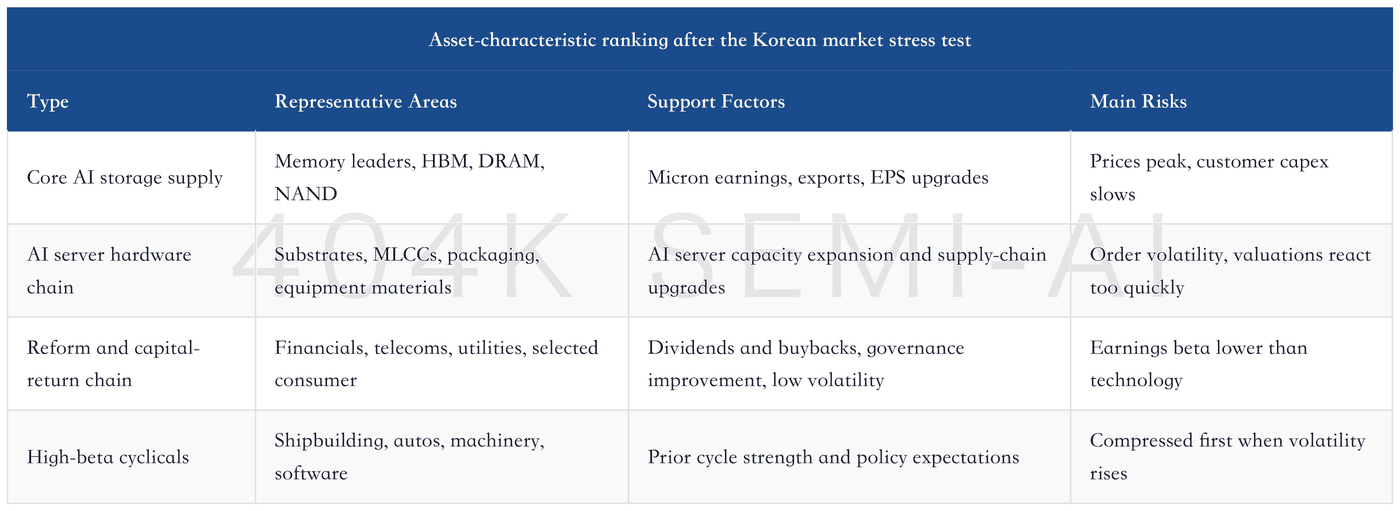
The implication of this ranking is simple: from here, the market will not reward only the label of being “AI-related.” It will reward the segments that can translate AI demand into EPS and cash flow. Micron has already provided positive validation for global storage supply and demand; Korean companies still need to provide their own evidence of delivery.
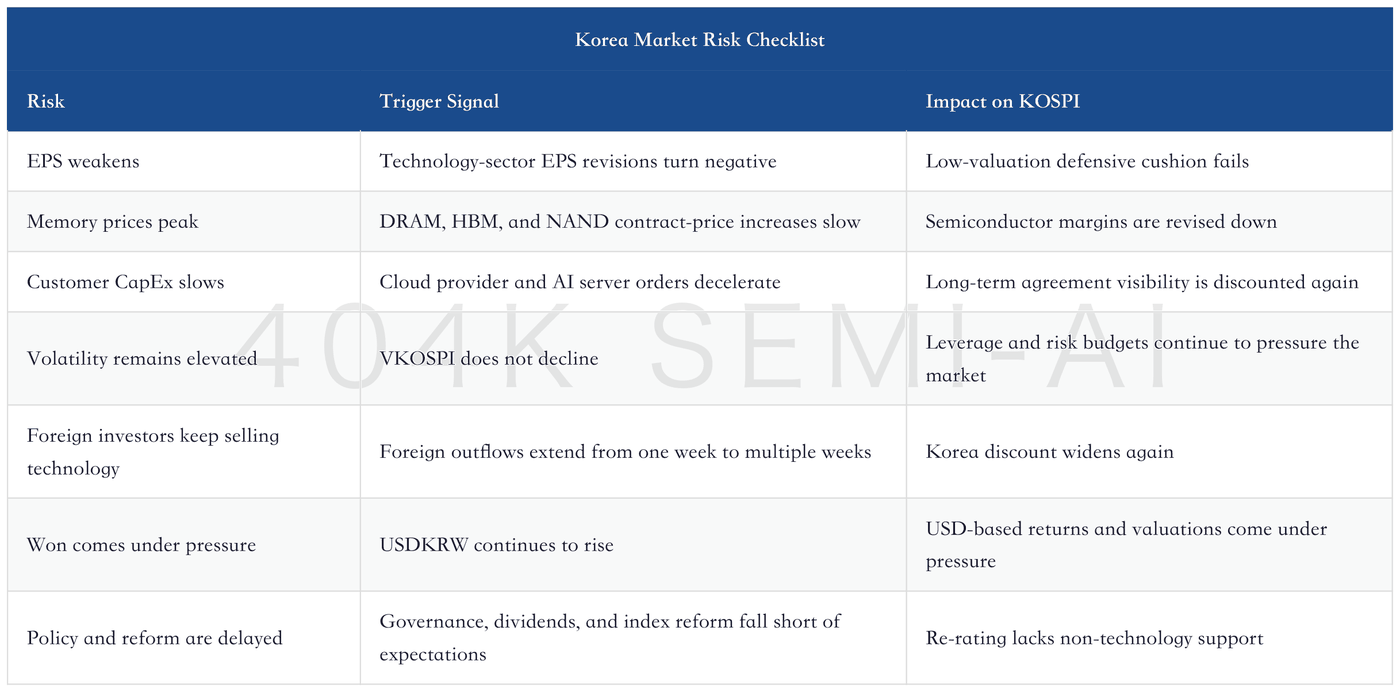
12. Risk Checklist: The Biggest Concern Is Deteriorating Earnings Signals
The current KOSPI pullback has not yet invalidated the AI memory re-rating, but risks have moved from the margins to the foreground. The first risk is weakening earnings revisions. If KOSPI 12-month forward EPS shifts from upward revisions to downward revisions, especially if the technology sector moves from +2.2% into negative territory, the market will reassess whether a 7.5x to 8.2x valuation is genuinely cheap.
The second risk is memory supply recovering earlier than expected. Micron currently expects the supply-demand imbalance to persist beyond CY27, with supply gradually improving in 2028. If capacity releases from Samsung, SK hynix, Micron, and other producers outpace demand growth, prices and gross margins will come under pressure. Even with long-term agreements, the memory industry cannot fully escape the supply-demand cycle.
The third risk is slower customer capital expenditure. AI memory demand comes from cloud providers, model companies, enterprise AI, server OEMs, and automotive/edge devices. If the return on AI capex is questioned, or customer inventories begin to build, both the execution pace of long-term agreements and new orders will slow.
The fourth risk is further deterioration in market positioning. If the VKOSPI remains at extremely elevated levels, leveraged ETFs and options hedging will continue to amplify volatility. Retail buying can provide short-term liquidity, but it cannot repair foreign investors’ risk budgets on its own.
The fifth risk is the won and interest rates. A weaker won weighs on foreign investors’ returns, while rising rates pressure valuation multiples. Korea’s current account is strong, but the equity market remains sensitive to FX and dollar liquidity.
13. What to Watch Over the Next Four Quarters
Over the next four quarters, the key observations for the Korean market are very clear. First, whether earnings revisions at Samsung Electronics and SK hynix can keep pace with Micron. Micron has already provided external evidence of supply-demand imbalance, long-term agreements, and high visibility. Korea’s leaders need to confirm the same trend through earnings.
Second, export data. Korea’s first-20-days exports, adjusted for working days, rose 8.7% sequentially, which is a strong signal. Going forward, the market needs to see whether semiconductor exports can maintain high growth, and whether DRAM, HBM, NAND, equipment, and materials produce a continuous data series. Once exports turn lower, the market will immediately question the quality of EPS upgrades.
Third, the VKOSPI. If volatility falls quickly, it means the market is starting to digest leverage and positioning pressure. If volatility remains above historically extreme ranges, any positive fundamental news may be offset by market structure.
Fourth, foreign investor technology flows. Foreign ownership remains high, and technology is the core of earnings upgrades in the Korean market. If foreign investors stop selling technology, the market will again price in Micron and Korean EPS upgrades. If foreign investors continue to sell in concentrated fashion, the burden on retail buyers will become increasingly heavy.
