
Korea Exports Deep Dive: June Exports Rose 70.9% YoY; How the AI Hardware Surplus Opens Room for KOSPI Re-Rating
目录
Too Long; Didn't Read
I. Triple Confirmation Across Exports, Imports, and the Surplus
Between Flash Data and Monthly Data, the Market Will Trade the Direction First
Surplus Quality Is More Worth Decomposing Than Surplus Size
II. Why Korean Exports Are the Thermometer for the AI Hardware Cycle
III. Surplus Expansion Matters More Than High Export Growth
IV. Structural Breakdown: Four Lines Across Semiconductors, Autos, Ships, and Energy Imports
After the Monthly Report, the Most Important Thing to Watch Is "Contribution Quality"
"Strong Exports" Cannot Be Directly Equated With "All Korean Assets Are Strong"
V. Semiconductor Chain: HBM Is the Core of Surplus Quality
HBM Changes the Entire Memory Profit Pool
SK hynix and Samsung Electronics Represent Two Different Options
Profit Verification Requires Volume, Price, and Structure, Not Just Export Value
VI. Country and Regional View: The US, Asian AI Supply Chain, and China Demand Must Be Separated
VII. How to Trade This Data Set in KOSPI
Index Re-Rating Requires Diffusion From Leaders to the Profit Pool
The Trading Sequence for Korean Assets Should Not Be Reversed
VIII. The Won, Rates, and Foreign Flows: The Surplus Will Change the Macro Narrative
The Won Trades Lower Vulnerability in the External Account
The Surplus Pushes Korea From "Cyclical Exports" Toward "Technology Surplus"
Foreign Buying of Korea Ultimately Buys "Profit Plus Account"
IX. How This Data Set Verifies the Korea and Memory Re-Rating Thesis
X. Disconfirming Checklist: When This Data Set Would Fail
XI. What to Watch Over the Next Four Quarters
Three Scenarios Determine the Payoff for Korean Assets
Tracking Indicators Need to Move From "Macro Numbers" to "Profit Numbers"
Investment Actions Should Be Layered, Not All-In
Korean Exports Must Be Cross-Verified Against Three External Indicator Groups
The Easiest Thing to Misread Is Not the Data, But the Timing
XII. Investment Conclusion: Raise the Weight of Korea's AI Surplus First, Then Wait for Monthly Data to Confirm the Structure
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The Korea Customs Service TradeData flash release shows June exports of 102,251, imports of 66,101, and a surplus of 36,150; the first-half cumulative surplus reached 138,320. The core point is not one month of high growth, but that AI semiconductors are tying Korea's trade surplus, the won, and KOSPI earnings expectations back together.
Too Long; Didn't Read
The most important number in Korea's June export flash is the elasticity of the surplus. The Customs Service page shows exports of 102,251 and imports of 66,101 from June 1 to June 30, for a monthly surplus of 36,150; first-half exports reached 496,712, imports 358,392, and the cumulative surplus 138,320. If the subsequent MOTIE monthly report confirms this direction, the core Korea macro trade is no longer just "export recovery"; it is an AI hardware surplus lifting the current account, the won, and KOSPI earnings expectations at the same time.
External demand elasticity is stronger than import pressure. The gap between export growth of 70.9% YoY and import growth of 30.1% YoY shows that external demand elasticity is clearly stronger than domestic demand and energy import pressure. Korea's past export cycles were often pulled around by oil prices, chemicals, autos, and ships. This one looks more like a renewed acceleration in nominal exports driven by the structural upcycle in semiconductors. Imports are also growing, but import growth has not absorbed the export increment, making the surplus expansion more valuable.
AI semiconductors are the pricing anchor for this surplus cycle. As of the currently public pages, the category-level query database has not yet synchronized the June 2026 detail, so old-year HS data should not be presented as the latest data. But the industrial signals already released by Korea suggest that HBM, DDR5, enterprise SSDs, advanced packaging materials, MLCC, and FC-BGA are jointly explaining the export strength. The more the surplus is concentrated in high-value-added electronics, the more it supports upward earnings revisions for SK hynix, Samsung Electronics, Samsung Electro-Mechanics, and the equipment and materials chain.
This data set will reinforce the trade that "Korea is not an ordinary cyclical equity market." Exports and the surplus rising together will make the market treat Korea as an external thermometer for AI capex: US cloud capex, Nvidia Rubin timing, HBM4 certification, DRAM contract prices, and enterprise NAND demand will all be reflected first in Korean exports and the macro accounts, then transmitted into KOSPI valuation.
The biggest risk is not that exports have already peaked, but a mismatch in definitions and timing. The Customs Service homepage flash data updates first, while the MOTIE monthly report and HS/country breakdowns may lag. Short-term trading can easily extrapolate the aggregate flash number directly into semiconductor profits. The right approach is to price the surplus direction into assets first, then wait for the MOTIE monthly report to verify the contribution from semiconductors, autos, ships, petrochemicals, and major countries and regions.
The trade should unfold along three lines. From an investment perspective, Korean exports should be split into memory and HBM leaders as direct beneficiaries, MLCC/substrate/packaging/equipment chains pulled by AI server demand, and the re-pricing of the won, KOSPI, and Korean financial assets. If exports remain strong in July and August, the market will move from "buy individual-company earnings" to "buy Korea's AI surplus."
I. Triple Confirmation Across Exports, Imports, and the Surplus
Korean export data can easily be read as a macro flash, but what really matters this time is the slope across three numbers. Exports were 102,251, imports 66,101, and the monthly surplus 36,150; first-half exports were 496,712, imports 358,392, and the surplus 138,320. Looking only at export growth of 70.9% YoY, the market can easily dismiss it as a base effect. Once import growth of 30.1% YoY is included, the issue becomes the speed at which Korea's export sector is creating foreign exchange, which is clearly faster than the import side is absorbing foreign exchange.
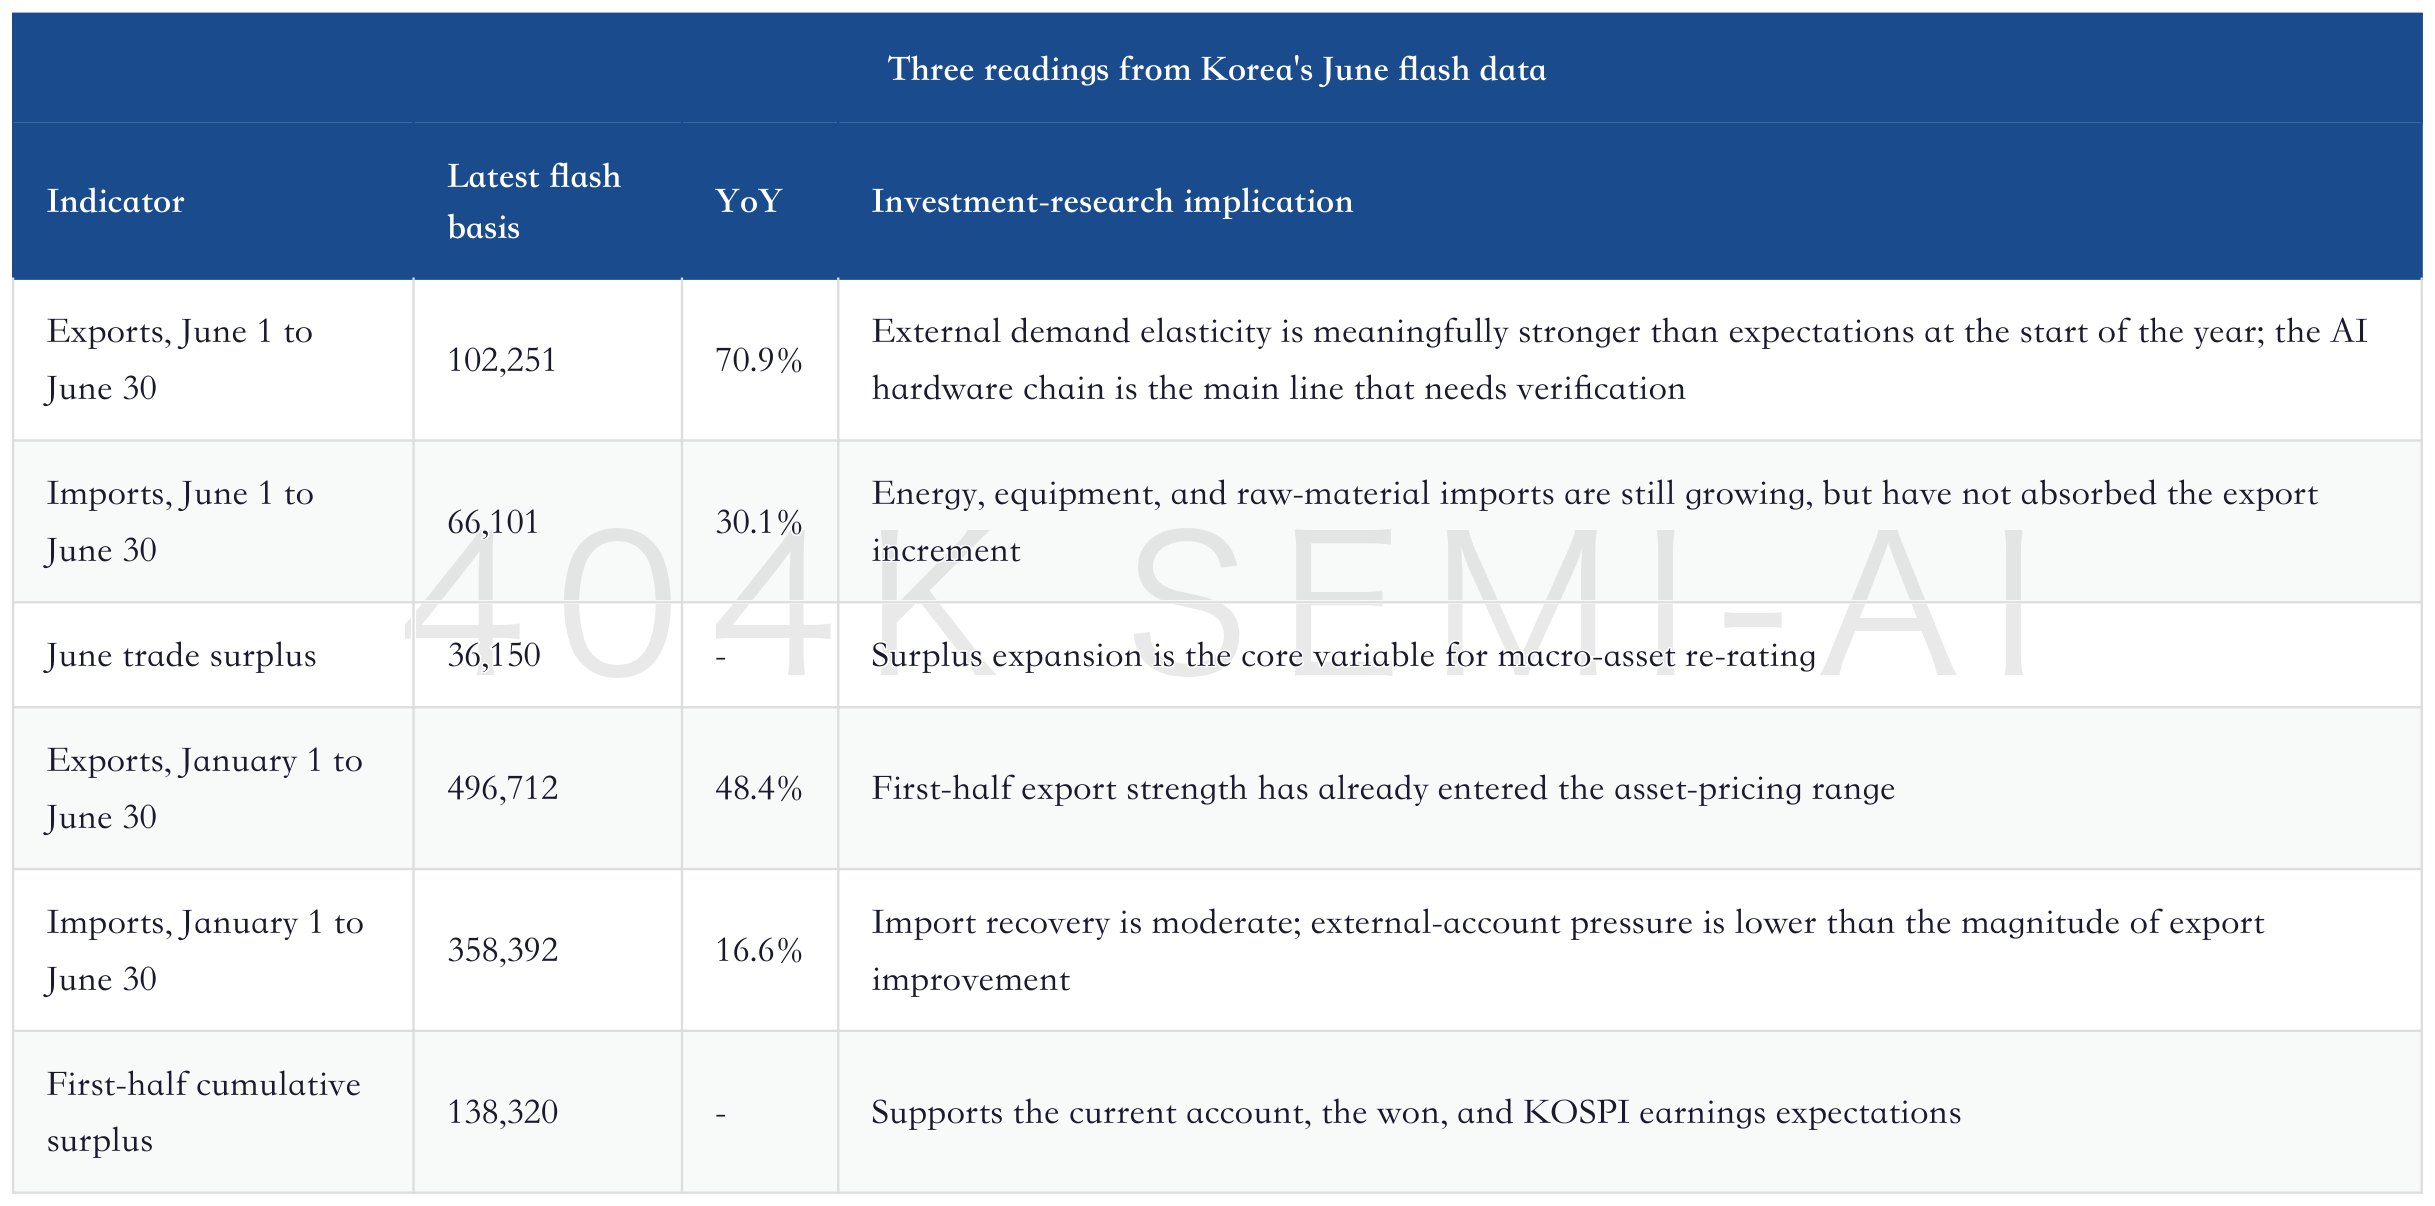
There is one definitional boundary that must be remembered strictly for this table: it comes from the flash table on the Customs Service TradeData homepage, and is an aggregate leading measure. As of the currently public pages, the HS, country, and regional query database has not yet provided June 2026 details, and the latest visible monthly "export and import trends" release in the Ministry of Trade, Industry and Energy press-release list is still May. Therefore, this report uses the latest flash only for aggregate and surplus judgment, and does not force still-unsynchronized breakdown data into the conclusion.
That actually makes the investment judgment clearer. Aggregate data arriving first means the market will first trade whether "Korean exports and the surplus continue to beat expectations." Later category data will determine "who benefits most, and which stocks receive earnings upgrades." In an export-oriented economy like Korea, an inflection in the surplus usually affects asset prices earlier than sales in a single industry: the won, KOSPI, foreign net inflows, semiconductor profit expectations, and rate expectations tend to move first, before the monthly report decomposes the data into semiconductors, autos, ships, petrochemicals, displays, batteries, and other line items.
Korea AI Surplus Deep Dive: How the Memory Supercycle Re-Rates Fiscal Policy, Rates, and the Won
This is also why the question this time cannot be limited to "is export growth high?" The more important question is whether the export strength comes from high-value-added, high-margin, supply-constrained industrial chains. If the answer is AI semiconductors, it changes how Korean assets are priced. If the answer is only restocking in low-margin cyclicals, the surplus expansion is more likely to be treated as an inventory-cycle rebound.
Between Flash Data and Monthly Data, the Market Will Trade the Direction First
Export data have a natural time lag. The flash gives aggregates first, the monthly report then gives the structure, and corporate earnings finally confirm profits. For investors, the difficulty is not waiting until every data point has arrived before drawing a conclusion, but deciding which asset classes should be re-rated first when information is incomplete. Korea's flash data this time already provide three sufficiently clear directions: exports are strong, imports are also recovering but clearly more slowly than exports, and the surplus is expanding. Even without breakdowns, these three together are enough to change first-layer macro-asset pricing.
The first layer is the exchange rate and risk premium. Korea is an energy importer, and its trade account is often pulled between oil prices and the semiconductor cycle. High export growth with even higher import growth is not necessarily positive for the surplus. High export growth with surplus expansion improves foreign-exchange supply and corporate revenue quality. The June flash belongs to the latter case. It does not mean the won must appreciate in a straight line, but it lowers market concern over Korea's external account, especially when global tech risk appetite is still led by AI capex.
The second layer is index earnings. KOSPI is not an evenly distributed index; it is highly sensitive to weights in semiconductors, electronics, autos, industrials, and financials. Export-surplus improvement first raises revenue expectations for technology and manufacturing companies, then affects financial and domestic-demand valuations through foreign positioning, the exchange rate, and rate expectations. This transmission usually does not finish in a single day. The sequence is more like a staircase: first buy semiconductor leaders, then electronic components and equipment/materials, then look at the won and financial assets.
The third layer is industrial margins. Strong aggregate exports only show that orders are moving; margins still depend on product structure. The distinct feature of AI semiconductors is that they can lift both export value and gross margin. HBM, DDR5, enterprise SSDs, advanced packaging materials, MLCC, and substrates are not ordinary low-margin shipments. They are constrained by certification, yield, capacity, and customer lock-in. If the monthly report later confirms a large contribution from the electronics chain, the June flash is not ordinary trade data, but a leading signal that Korea's technology profit pool is expanding.
Surplus Quality Is More Worth Decomposing Than Surplus Size
The first-half cumulative surplus of 138,320 should not be treated merely as a macro accounting item. Behind it are two completely different worldviews. One is the traditional cyclical worldview, where the surplus comes from lower oil prices, autos, and ship deliveries, and sustainability depends on external demand and delivery schedules. The other is the AI hardware worldview, where the surplus comes from memory, advanced packaging, electronic components, and the server chain, and sustainability depends on AI capex, supply bottlenecks, and the pricing cycle. Both types of surplus can make the monthly number look good, but they imply completely different valuation multiples.
If the surplus comes from traditional cyclicals, the market is more willing to assign a one-off recovery valuation. Autos and ships can support exports, but their monthly volatility and order-delivery timing are strong, and capital markets usually will not discount one month of high growth into multi-year profit expansion. Petrochemicals, refining, and general manufacturing require closer attention to spreads and inventories. They can improve macro data, but they do not explain why Korean technology stocks should receive higher valuations.
If the surplus comes from the AI hardware chain, the valuation logic is different. AI servers are not ordinary end-market restocking, but a long-cycle investment driven jointly by cloud capex, GPU platform upgrades, higher memory capacity, rising bandwidth requirements, and data-center deployment. Korea's position in this chain is not as an end-demand buyer, but as a key supplier. Suppliers have stronger pricing power during bottleneck cycles, and export strength is more easily converted into gross margin and cash flow.
So the most valuable part of this flash report is not that it has answered every structural question, but that it has made the subsequent verification questions very specific. The next monthly report only needs to answer three questions: whether semiconductors are the main contributor, whether electronic components are diffusing, and whether the import side has not been reabsorbed by energy costs. As long as these three are broadly true, Korean assets can move from an "export recovery trade" to an "AI surplus re-rating trade."
II. Why Korean Exports Are the Thermometer for the AI Hardware Cycle
The special feature of Korean exports is that they are not directly driven by valuation narratives like US technology stocks, and they are not as broad as Chinese manufacturing. Korea's core exports are concentrated in semiconductors, autos, ships, petrochemicals, displays, batteries, and machinery, with semiconductors directly embedded in the scarcest supply segments of global AI capex. Cloud capex, Nvidia GPU rack timing, HBM certification, DRAM contract prices, enterprise SSD demand, and advanced packaging capacity all enter Korean exports through orders, prices, and shipments.
This means Korean exports are not a lagging indicator, but an intermediate reading for the AI hardware profit chain. US cloud vendors first decide capex, Nvidia, ASIC, and server platforms determine the bill-of-materials structure, memory and packaging-material suppliers determine whether delivery is possible, and Korean exports then convert these orders into customs-basis trade data. As long as exports and the surplus continue to strengthen, the market will raise its tolerance for Korean technology companies' revenue and gross margins over the next few quarters.
Korea Technology Deep Dive: How AI Compute and the Memory Supercycle Re-Rate HBM, MLCC, FC-BGA, TCB, and Enterprise AI
This macro reading is especially useful when placed within three industrial changes.
First, HBM is shifting Korean semiconductor exports from a "volume cycle" to a "structure cycle." The traditional DRAM cycle is mainly driven by PC, handset, and server restocking. Price elasticity is high, but profit durability is weak. HBM is different. It is tied to AI accelerator platforms, with long certification cycles, high packaging and yield barriers, and customers that are more willing to pay a premium for secure supply. As long as HBM3E and HBM4 order visibility continues to be revised higher, the semiconductor portion of Korean exports will be more durable than an ordinary memory cycle.
Second, price increases in DDR5 and older DRAM specifications will spill over. AI pulls advanced DRAM capacity toward HBM, forcing traditional server, PC, handset, and industrial customers to compete for remaining capacity. The result is not only that HBM makes money; DDR5, parts of DDR4, NOR, SLC NAND, and enterprise SSDs may also see price increases. Export data do not show every quarter's contract-pricing detail, but aggregate strength will reflect the outcome of "supply being squeezed away by AI" ahead of time.
Third, Korea's surplus is starting to acquire capital-market attributes. The stronger the export surplus, the easier it is for foreign investors to treat Korea as a macro proxy for the AI hardware chain: buying SK hynix is buying HBM; buying Samsung Electronics is buying memory recovery and advanced-packaging optionality; buying Samsung Electro-Mechanics is buying MLCC and packaging substrates; buying KOSPI is buying Korean technology earnings and external-account improvement.
III. Surplus Expansion Matters More Than High Export Growth
High export growth is certainly positive, but surplus expansion explains asset prices better. If export growth is accompanied by a sharp rise in energy imports, equipment imports, and intermediate-goods imports, little is left for the current account and corporate profits. In Korea's June flash data, exports rose 70.9% YoY and imports 30.1% YoY. The gap is wide enough to show that dollar income created by external demand is clearly outrunning import-side cost pressure.
This matters for the won. The won's past weakness often came from two directions: energy-import shocks and pressure on the trade account caused by a semiconductor downturn. When the export surplus expands, the market reassesses Korea's foreign-exchange supply, especially when US rate expectations, Asian fund flows, and tech risk appetite are changing at the same time. The surplus itself is not a sufficient condition for won appreciation, but it reduces the won's vulnerability to macro short pressure.
For KOSPI, surplus expansion has a second meaning: better quality of dollar revenue in corporate earnings. Korean listed-company index weight is highly concentrated in technology, autos, industrials, and financials. The stronger exports are, the easier it is for foreign investors to see KOSPI as a portfolio of global AI hardware and high-end manufacturing. In earlier discussions about KOSPI re-rating, the core issue was not "can the index rise," but whether Korean corporate earnings and shareholder returns can improve together. The export surplus strengthens the former; governance reform and capital returns determine the latter.
Korea Equity Re-Rating: Technology Earnings, Foreign Inflows, and MSCI Reform Verification After KOSPI Breaks 9,000
This is also why the June data may have a larger market impact than an ordinary monthly report. If investors were previously worried that the AI semiconductor trade was overheated and semiconductor momentum was topping tactically, the strength in Korean exports provides a real-world check: as long as trade data continue to confirm order conversion, valuation drawdowns look more like positioning and timing issues than a break in fundamentals.
IV. Structural Breakdown: Four Lines Across Semiconductors, Autos, Ships, and Energy Imports
Before the detailed monthly report is released, the most prudent approach is to split Korean exports into four verifiable lines rather than assert in advance how many percentage points any category contributed.
The first line is semiconductors. This is Korea's most important high-beta export variable and the direct gateway into the AI cycle. If semiconductor exports remain strong, HBM, server DRAM, NAND, and advanced packaging demand are still pulling. If semiconductor exports are strong but the overall surplus does not expand, import costs or other industry drags are too large. This time, aggregates and the surplus are both strong, suggesting higher quality in technology exports.
The second line is autos. Korean auto exports have been strong in recent years, especially in North America and premium models. But autos have limited explanatory power for the AI surplus; they are more like the base. If the June monthly report shows autos still stable, traditional exports have not become a drag. If autos slow while total exports remain high, that would instead highlight the pull from semiconductors and high-end electronics.
The third line is ships. Ship exports are heavily affected by delivery timing, and monthly volatility can be extreme. They can lift aggregate exports, but do not necessarily mean the AI cycle is strengthening. Therefore, once the monthly report is released, ship deliveries and semiconductor exports must be separated. If surplus expansion is mainly driven by ship deliveries, sustainability deserves a discount. If ships are only auxiliary and semiconductors plus the electronics chain are the main axis, the flash export data become materially more valuable.
The fourth line is energy imports. Korea is an energy importer, and oil and natural-gas prices directly affect the import side. June import growth of 30.1% YoY is not low, but export growth was higher, showing that energy and equipment imports have not overwhelmed the surplus. If oil prices rise later, surplus elasticity will be partly offset. If oil prices are stable, export improvement can enter the external account more cleanly.
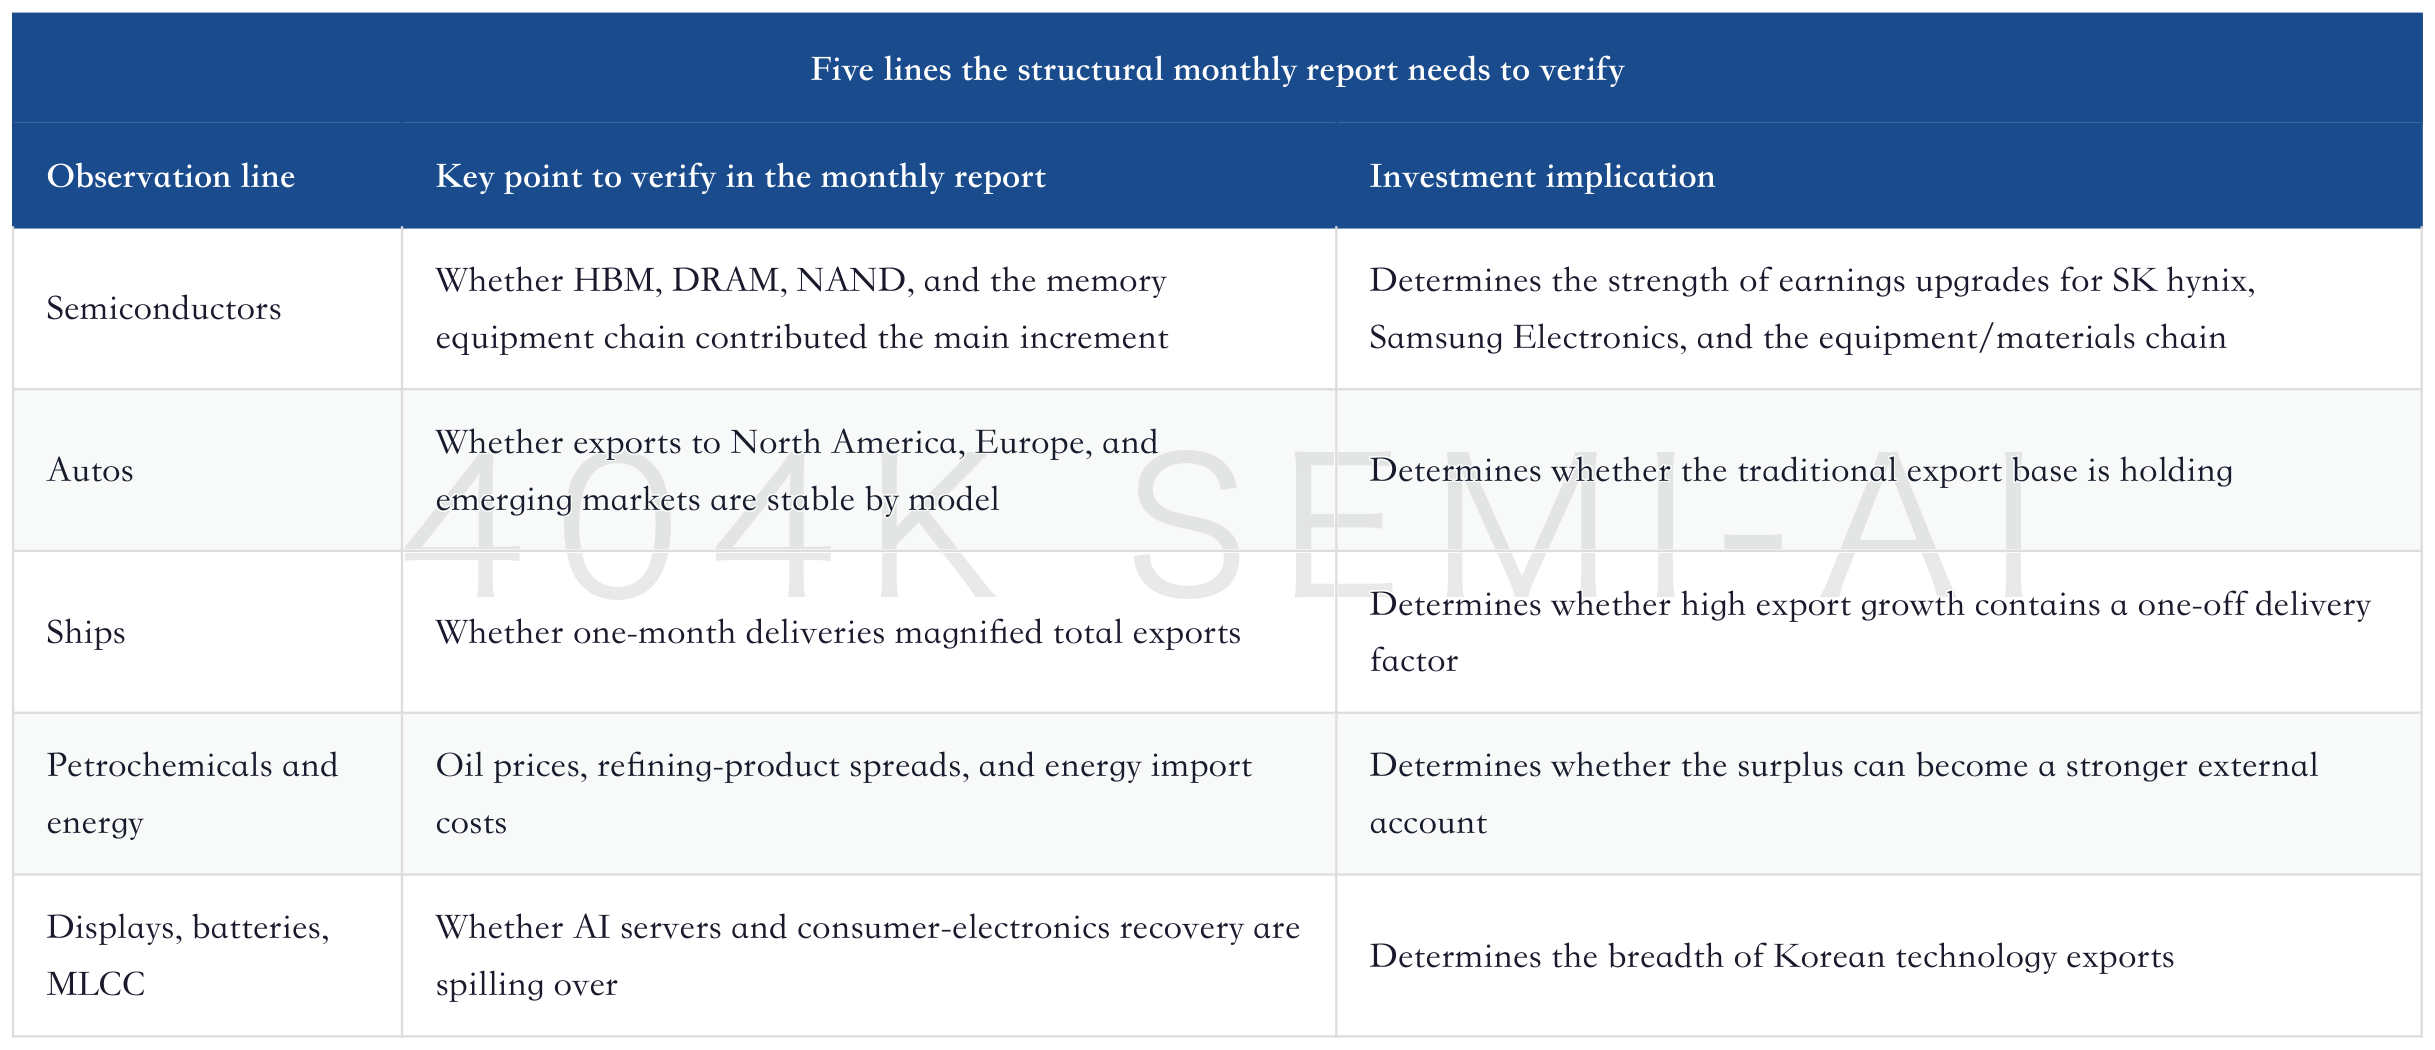
The practical value of this table is that it turns "exports are very good" into tradable questions. To trade Korea's AI chain, export growth alone is not enough. The export structure must point to high-margin, high-barrier, supply-constrained segments. Only when semiconductors and the AI electronics chain become the main contributors can export data transmit into margins and valuation multiples.
After the Monthly Report, the Most Important Thing to Watch Is "Contribution Quality"
Once the MOTIE monthly report and customs breakdowns are synchronized, the easiest mistake is to look only at which category has the highest YoY growth. One-month YoY growth can be distorted easily by bases and delivery timing, especially in ships, petrochemicals, and some machinery. What really matters is not the highest growth rate, but incremental contribution, margin attributes, and sustainability. A high-margin, supply-constrained category that can keep raising prices may deserve a higher valuation than a one-off delivery, even if its growth rate is not the highest.
Semiconductors have the highest contribution quality because they connect export aggregates, corporate profits, and global AI capex at the same time. Once Korean semiconductor exports are strong, the market immediately asks about HBM mix, DRAM contract prices, enterprise NAND demand, packaging-material orders, and equipment utilization. Each variable can enter a financial model: price affects gross margin, shipments affect revenue, product structure affects valuation multiples, and capex affects future supply. This is not isolated trade data, but an entry point into an entire profit chain.
Autos rank in the second layer of contribution quality. Korean auto exports are competitive over the long term, and premium models plus the North American market support revenue, but the valuation logic for autos is more mature. The market already knows autos are a strong export industry. If autos are strong, the export base is stable. If autos are not strong while total exports remain strong, that instead shows semiconductor and electronics-chain revisions. For the index, autos provide stability; for the AI surplus narrative, they are not the core source of elasticity.
Ships need separate treatment. Korea's shipbuilding order cycle is long, and delivery plus revenue recognition can cause large monthly export swings. Strong ship exports are not bad; they improve aggregates and the surplus. But capital markets usually do not treat one month of ship deliveries as the AI hardware cycle. If June's strong exports are mainly from ship deliveries, extrapolation into semiconductor profit elasticity should be reduced. If ships are only a support and semiconductors plus the electronics chain are the main axis, the quality of the export flash improves materially.
Energy imports are the inverse variable for the surplus. Korea is not a resource country; higher oil and gas prices directly erode the trade account. June import growth of 30.1% YoY is not low, but export growth of 70.9% YoY is stronger, and the surplus still expanded, showing that export-side dollar revenue was enough to cover import-side pressure. If oil prices remain stable, more of the export improvement will stay in the surplus. If oil prices jump, surplus elasticity weakens, and the won and index trade both deserve a discount.
Displays, batteries, MLCC, substrates, and equipment/materials are the diffusion layer. They may not become the trading focus as directly as semiconductor leaders, but they can determine market breadth. The AI server value chain is not just GPU and HBM; it also includes high-layer boards, packaging substrates, power, connectivity, thermal management, capacitors, testing, and materials. If the monthly report shows electronic components are also improving, the Korea trade will diffuse from a handful of leaders to a broader technology manufacturing portfolio. If diffusion is not obvious, the trade will remain more concentrated, and index upside will depend more on SK hynix and Samsung Electronics.
"Strong Exports" Cannot Be Directly Equated With "All Korean Assets Are Strong"
Strong Korean exports raise the ceiling for asset allocation, but they do not lift all stocks equally. Export-oriented industries, technology heavyweight stocks, electronic components, and financial assets benefit first. Pure domestic-demand industries, industries heavily affected by import prices, or industries lacking global competitiveness benefit much less. From an investment perspective, three types of exposure must be distinguished: direct export-revenue exposure, AI hardware-chain margin exposure, and macro risk-premium compression exposure.
Direct export-revenue exposure is about orders and shipments. Autos, ships, semiconductors, displays, batteries, and machinery all sit here. AI hardware-chain margin exposure is about supply bottlenecks and product structure. HBM, DDR5, advanced packaging, MLCC, FC-BGA, equipment/materials, and enterprise SSDs are closer to this line. Macro risk-premium compression exposure is about the surplus, the won, and foreign flows. Financials, index ETFs, and some high-dividend value stocks are closer to this line.
The trading rhythm for these three exposures is different. Export-revenue exposure is fastest; it can be traded as soon as the data are released. Margin exposure needs cross-verification from the monthly report, prices, and earnings. Macro risk-premium exposure is slowest; it needs several consecutive months of surplus, foreign net inflows, and won stability to confirm together. The June flash turns on the first light first. The second light must wait for semiconductor and electronics-chain structure, and the third light must wait for continuity.
V. Semiconductor Chain: HBM Is the Core of Surplus Quality
The biggest difference between this Korean export cycle and past cycles is that HBM has turned memory from a cyclical commodity into a ticket into AI infrastructure. In the traditional memory cycle, investors cared about how long prices would rise, where inventories would bottom, and when capex would recover. In the HBM cycle, investors also need to care about certification, stacking, packaging, yield, customer lock-in, and capacity substitution. It is more like a narrow gate: vendors that pass through have stronger pricing power, while vendors that cannot pass remain in the ordinary DRAM pricing cycle.
SK hynix is the most direct beneficiary on this line. The market historically assigned more upside beta to hynix because it was ahead in HBM customer certification and volume-production timing. If export data remain strong, they reinforce the signal that "orders are not PowerPoint; they are already shipping." For Samsung Electronics, the logic is more complex: Samsung has memory recovery beta, HBM catch-up optionality, and pressure to validate advanced packaging. Strong exports do not mean Samsung immediately catches up with hynix, but they lift the whole Korean memory profit pool.
Goldman Sachs DRAM Deep-Dive Update: DDR5 Price Increases, 2027 HBM Re-Pricing, and Samsung's KRW 2,450tn Investment
One point the market easily overlooks should be emphasized here: HBM does not change only high-end product prices; it also changes ordinary DRAM supply. Once advanced capacity, equipment, labor, and packaging resources are absorbed by HBM, marginal supply of ordinary DRAM tightens as well. AI server expansion, rising DDR5 server-memory demand, and restocking by PC and handset customers during recovery all stack onto ordinary DRAM prices. The expansion in the export surplus is exactly the result of this industrial constraint entering the macro account from the order side.
NAND should not be ignored either. The storage hierarchy for AI training and inference is becoming thicker. Enterprise SSDs, nearline storage, caches, data lakes, and model-inference logs all consume more capacity. Korean domestic NAND weight is not as globally central as DRAM/HBM, but strong export data, rising memory prices, and recovering enterprise SSD demand can turn NAND from a drag into a source of profit elasticity.
Memory Deep-Dive Update: How Korea's USD 3.1tn AI Investment Plan Re-Rates DRAM, NAND, and the Equipment Chain
If the semiconductor chain is put into a financial model, the most important variable is not one month's export value but three slopes: the revenue slope, the gross-margin slope, and the capex slope. The revenue slope is determined by orders and prices; the gross-margin slope is determined by HBM mix and ordinary memory price increases; the capex slope determines whether supply will be released too quickly. The stronger Korean exports are, the more the market will believe the first two slopes. But if capex is excessive, supply risk after 2027 will also enter valuation discounting earlier.
HBM Changes the Entire Memory Profit Pool
HBM is discussed so often that it is easy to think of it as only a high-end product line. The real change is deeper. HBM is pushing the memory industry away from the traditional framework of "compete on cost when capacity is excessive, compete on price increases when the cycle turns up" and toward a framework where customer certification, packaging capability, yield curves, and long-term supply rights jointly determine profit. In traditional DRAM, lagging vendors can also benefit as long as prices rise. In the HBM cycle, vendors that obtain customer certification and stable yields take a larger share of profits.
This is especially critical for Korea. Korean memory manufacturers have long had large cyclical elasticity, but valuations were often constrained by the idea that "cycle-peak profits cannot be extrapolated." HBM makes the market consider another question: if part of memory revenue becomes more like a ticket into AI infrastructure rather than an ordinary cyclical product, can peak profits become more durable? Export data cannot answer that question directly, but they can provide external evidence of order conversion. The stronger exports are, the more willing the market is to believe AI demand has entered real delivery rather than remaining in cloud budgets and chip-company guidance.
HBM also squeezes ordinary DRAM supply. Advanced wafers, packaging capacity, testing resources, and engineering teams are not infinite. As more resources are absorbed by HBM, supply growth in ordinary DRAM slows. Server DDR5, PC DRAM, handset memory, and industrial customers compete for remaining capacity, amplifying price elasticity. This is why the AI cycle benefits not only HBM, but may lift the entire memory price curve. The improvement in the export surplus is the macro expression of this structural supply constraint entering the trade account.
The NAND logic arrives later, but should not be ignored. In the past, supply discipline in NAND was weaker than in DRAM, and price elasticity and earnings stability were also worse. After AI data-center expansion, training data, inference logs, caches, retrieval augmentation, vector databases, and hot/cold data tiering all increase storage-capacity demand. If enterprise SSDs continue improving, NAND will shift from a drag to a profit-recovery item. If Korean export data continue to strengthen in the semiconductor breakdown, NAND recovery will become second-layer elasticity rather than the first-layer main line.
Advanced packaging and equipment/materials are the third layer. The bottleneck in AI servers is not only the memory chip itself, but also packaging, substrates, testing, materials, chemicals, equipment, and power integrity. Korean companies' positions in this chain are less concentrated than the memory leaders, but they can be expressed through Samsung Electro-Mechanics, material suppliers, equipment components, and electronic-component companies. If export data are strong and company orders also improve, the market will expand its view of Korea from a "memory country" to an "AI hardware manufacturing country."
SK hynix and Samsung Electronics Represent Two Different Options
SK hynix is more like a "leadership option." Investors buy it for earlier HBM certification, stronger customer relationships, and faster product-mix improvement. For hynix, strong exports turn order visibility into macro data. As long as exports remain strong, investors will be more willing to extrapolate HBM profits over multiple quarters, and even begin discussing the durability of HBM4 and next-generation platforms after 2027. The risks are whether the leadership advantage is caught up with, and whether capex releases future supply too quickly.
Samsung Electronics is more like a "catch-up option." Samsung is larger and more complex. It has ordinary memory and NAND recovery, HBM catch-up, advanced packaging, and foundry-synergy angles. Strong exports first improve Samsung's earnings floor, because improvements in ordinary DRAM and NAND prices matter a lot for Samsung. But whether Samsung can receive a higher valuation still depends on HBM certification, customer orders, and advanced-packaging execution. For Samsung, strong exports are a necessary condition, not a sufficient condition.
Samsung Electro-Mechanics and the electronic-components chain are more like a "diffusion option." AI servers create demand not for one chip only, but for upgrades in system power, signal integrity, board-level connectivity, thermal management, and reliability. MLCC, FC-BGA, high-layer substrates, power-related components, and connectors can all receive higher content value from AI servers and high-end electronics. If the export monthly report shows electronic components improving in tandem, these companies will be re-priced from "consumer-electronics recovery" to "AI hardware diffusion."
Materials and equipment companies are more like a "capex option." When memory manufacturers expand HBM, advanced packaging, and high-end DRAM investment, orders improve for equipment, materials, chemicals, testing, and components. The risk here is cyclical reflexivity: the stronger capex is, the better short-term orders are, but the more likely future supply is to increase. Investors need to distinguish between "expanding bottleneck capacity" and "duplicating ordinary capacity." The former improves long-term competitiveness; the latter can plant the seeds of price downside earlier.
Profit Verification Requires Volume, Price, and Structure, Not Just Export Value
Export value is a nominal revenue clue. Profit requires three further confirmations. The first is price. Whether DRAM, NAND, and HBM contract prices keep rising determines whether export growth enters gross margin. The second is structure. The higher the share of HBM and high-end server memory, the better the margin; the more ordinary-product restocking there is, the more cyclical the profile. The third is cost. Yield, packaging cost, capex depreciation, and material prices determine whether high-end product profit can truly be released.
This is why the June flash should be treated as an "opening signal," not the "final answer." It tells the market that Korean external demand and the surplus are both strong, but the real profit verification still needs the monthly report and company earnings. If later company disclosures on gross margin, order visibility, and capex discipline match the export data, Korean technology stocks will receive stronger valuation support. If exports are strong but margins do not follow, the trade will retreat from fundamental re-rating to short-term momentum.
VI. Country and Regional View: The US, Asian AI Supply Chain, and China Demand Must Be Separated
The June 2026 country and regional breakdowns have not yet been synchronized, but a verification framework for the direction of Korean exports can already be set. First, watch the United States. US demand represents cloud capex, autos, and high-end consumer markets. If exports to the US remain strong, it indicates resilience in AI infrastructure, autos, and high-end equipment orders. Second, watch China. China demand includes semiconductor intermediates, displays, battery materials, and re-export chains. Strong China-related demand would suggest no obvious break in the Asian manufacturing chain. Third, watch Asian nodes such as Vietnam, Taiwan, Hong Kong, and Singapore, which often carry electronics supply-chain and re-export-chain roles.
Not all Asian exports should be simply classified as "China demand." Korea's exports to Vietnam are often linked to Samsung Electronics and electronics assembly chains. Exports to Taiwan may be related to the semiconductor supply chain, equipment/materials, and electronic components. Exports to Hong Kong may include re-export and electronics-trading attributes. Exports to Singapore often have regional trade and electronics supply-chain significance. The real investment judgment is whether these nodes strengthen together.
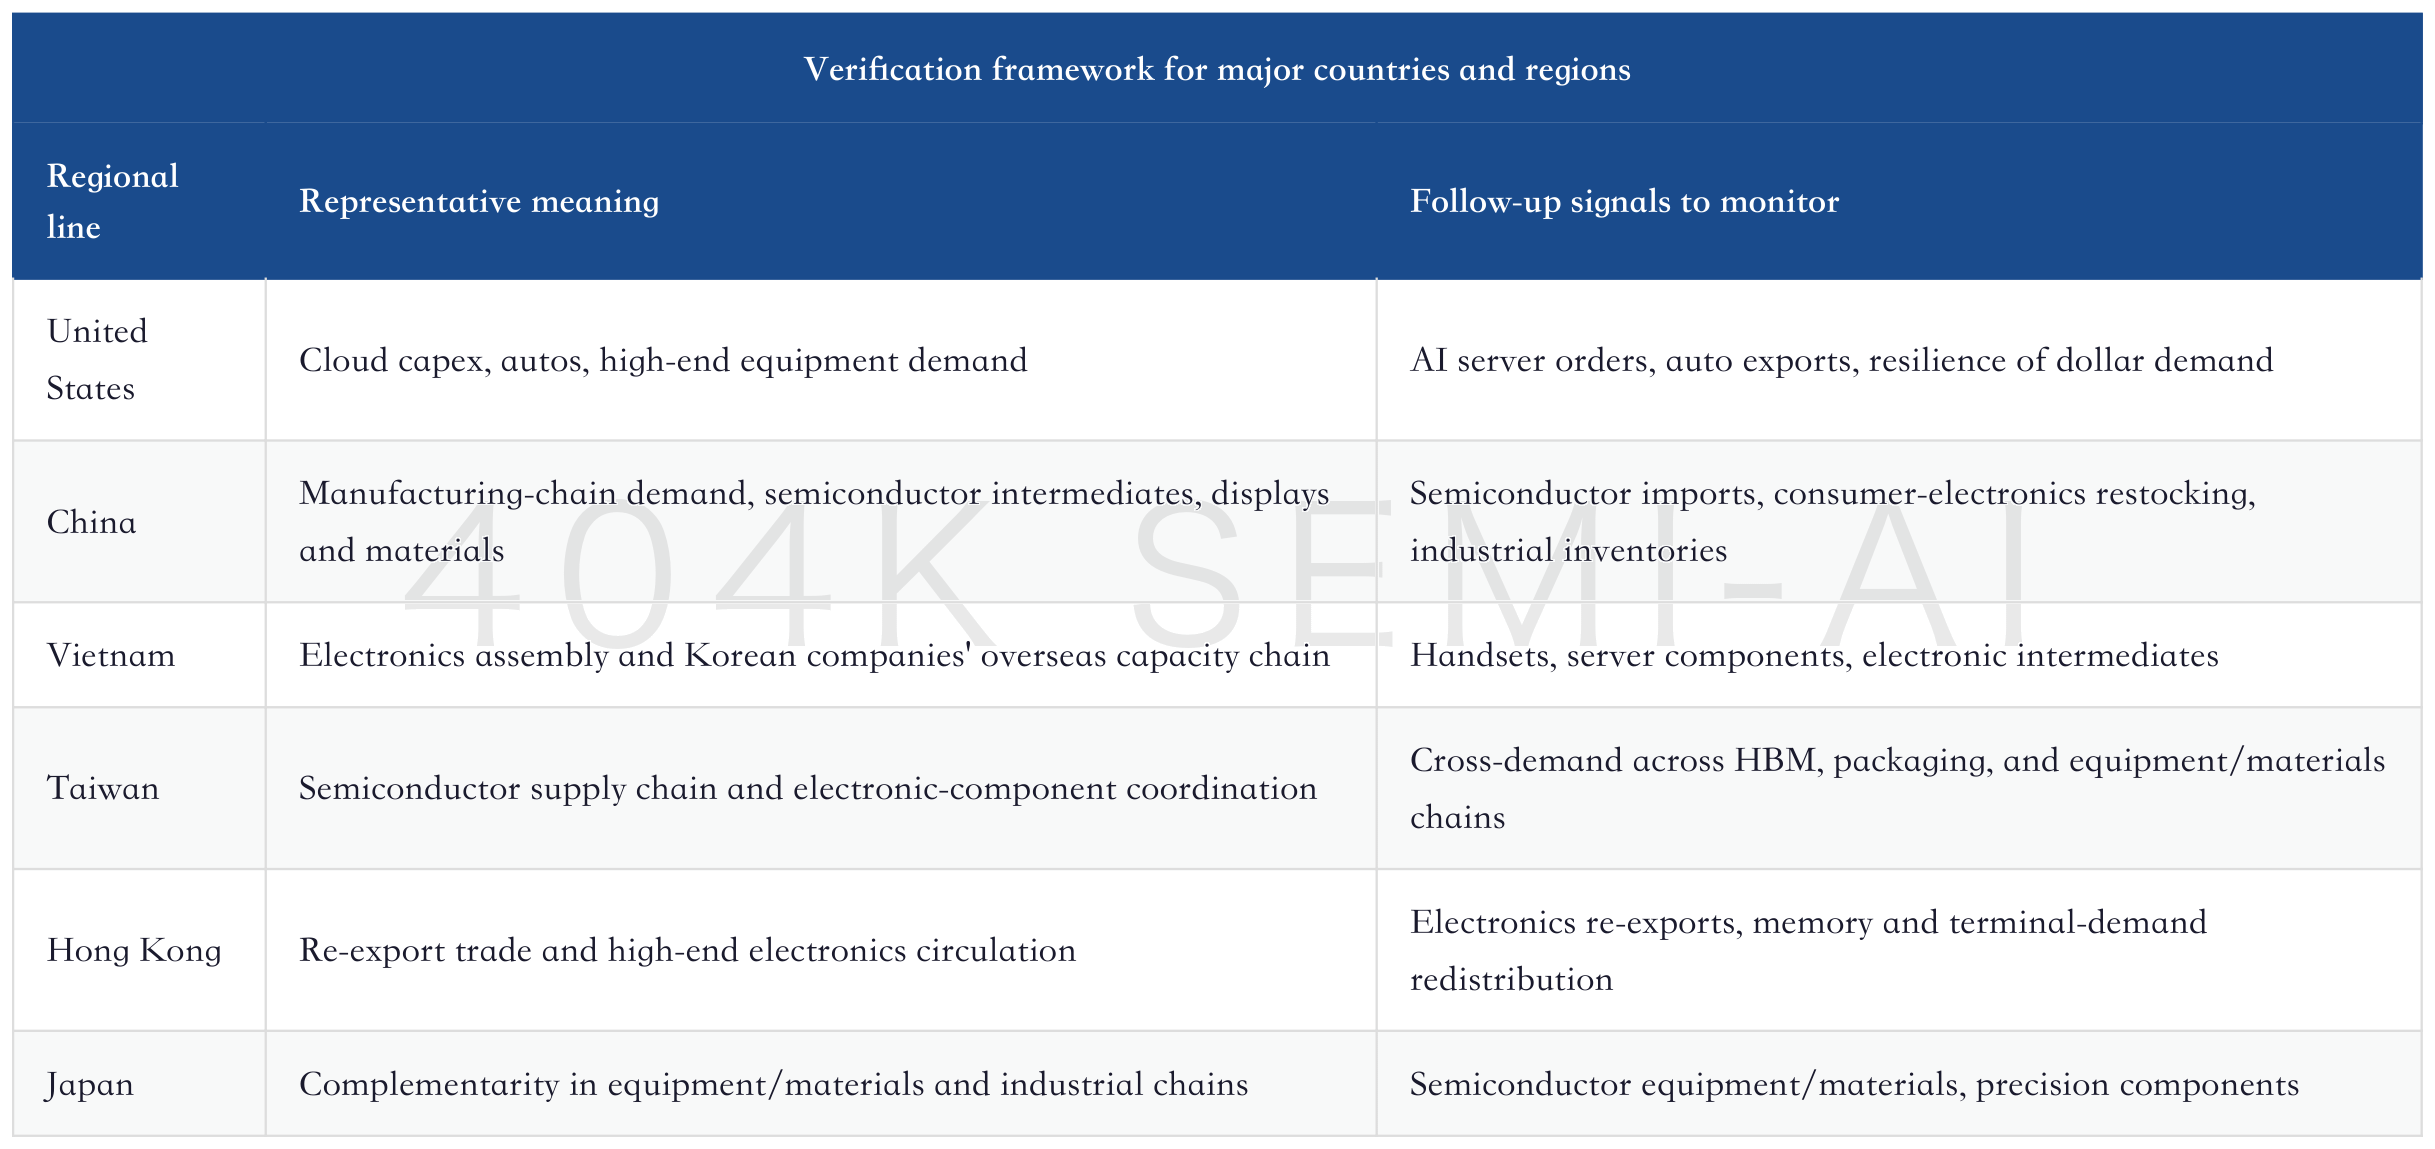
This regional framework matters to the market because Korean exports are not a single end-market demand. The more complex the AI hardware chain becomes, the more export destinations resemble a supply-chain map. Behind a GPU rack sit US cloud demand, Taiwan's chip manufacturing and packaging ecosystem, Korean memory, Japanese equipment and materials, Southeast Asian assembly, and global data-center deployment. Strong Korean export data show this map is still working.
VII. How to Trade This Data Set in KOSPI
The first reaction in KOSPI to this data set will fall on semiconductor heavyweights. The second reaction will spread to electronic components, equipment/materials, and financials. The third reaction is index valuation re-rating. The reason is simple: strong exports first improve earnings expectations, a strong surplus then improves the external account, and foreign inflows finally push up index valuation.
For SK hynix, strong exports correspond to verification of HBM shipments, pricing, and yield. Investors will continue watching customer certification, capacity expansion, and 2027 HBM re-pricing. If exports and company guidance confirm each other, valuation can shift from cycle-peak thinking to AI infrastructure supply-right thinking.
For Samsung Electronics, strong exports provide both opportunity and pressure. The opportunity lies in memory recovery, ordinary DRAM price increases, NAND improvement, and advanced-packaging investment. The pressure is that HBM catch-up progress still needs proof from orders and customer certification. Strong exports lift Samsung's earnings floor, but whether it can narrow the valuation gap with hynix still depends on the HBM roadmap and advanced-packaging execution.
For Samsung Electro-Mechanics, substrates, MLCC, and the electronic-materials chain, strong exports show that the AI server and high-end electronics chain is not stopping at GPUs themselves. Power, motherboards, packaging substrates, capacitors, thermal management, and connectors will all enter upgrade cycles with higher power, higher bandwidth, and higher reliability. These companies are less intuitive than the memory leaders, but they may gradually be re-rated through export monthly reports and order data.
Second Upward Revision in the AI Hardware Cycle: Asia Technology Re-Pricing Across Memory, HBM, PCB, and MLCC
For financials and domestic-demand stocks, the effect of the export surplus is more indirect. Surplus improvement raises macro stability, reduces currency pressure, and improves foreign risk appetite. If Korean equity-market reform, shareholder returns, and valuation-discount repair progress at the same time, the export surplus becomes the macro base for foreign investors to buy Korean financial assets.
Index Re-Rating Requires Diffusion From Leaders to the Profit Pool
For KOSPI to move from strong exports to index-level re-rating, it cannot rely only on one or two semiconductor leaders. It is normal for leaders to rise first because they are the most direct beneficiaries and the easiest for global capital to buy. But an index-level rally requires diffusion of the profit pool: earnings upgrades for semiconductor leaders, improving orders for electronic components, stable exports in autos and industrials, financials benefiting from lower macro risk premiums, and shareholder-return reform providing room for valuation repair. Only when these lines operate together does KOSPI shift from an "AI stock rally" to a "Korean asset re-rating."
This is the value of the June flash. It does not directly prove every industry is strong, but it provides the macro conditions for diffusion. Strong exports show that external demand has not broken. A strong surplus shows external-account improvement. Import growth that has not absorbed the surplus shows cost pressure is manageable. This combination makes foreign investors more willing to expand from a single leader to the index and supply chain. If the later monthly report confirms a large semiconductor contribution and no obvious drag from autos and ships, the probability of diffusion rises.
The Korean market also has an additional governance and shareholder-return variable. In the past, Korean equities were discounted for a long time because of group structures, minority-shareholder returns, capital efficiency, and insufficient dividends and buybacks. Export-surplus improvement cannot solve these issues automatically, but it can improve corporate cash flow and earnings visibility. If earnings upgrades and shareholder-return improvements appear together, index valuation repair will be stronger than a simple earnings cycle. Conversely, if earnings improve but capital returns do not change, index valuation may still be held down by the discount.
Foreign investors will watch three signals. The first is whether semiconductor leaders continue to receive earnings upgrades. The second is whether the won is stable, so that FX losses do not absorb equity returns. The third is whether index gains are accompanied by foreign net inflows rather than short-term local money. Export-surplus improvement supports the first two signals, but the third depends on global risk appetite and Korea's own market appeal.
The Trading Sequence for Korean Assets Should Not Be Reversed
The first stage should focus on memory and HBM. This is where the elasticity is greatest, and where orders, prices, and margins are easiest to verify through export strength. SK hynix, Samsung Electronics, and related equipment/materials chains are the most direct observation targets. The risk at this stage is that valuation has already reflected a lot, so any negative change in customer certification, prices, or capex will amplify volatility.
