
目录
TL;DR
Beneath the 0.9% Decline, Heavyweight Support and Market Breadth Diverged
Foreign Investors Are Still Selling, While Long-Only Active Funds Add Korea Exposure at Low Levels
EPS Estimates Continue to Rise, While Higher Rates Have Not Weakened the Won
Buybacks Must Progress from Announcement to Cancellation to Increase Per-Share Value
The 5.6x Earnings Multiple Is Low, but the Stability of the Earnings Denominator Matters More
Three Sets of Signals Will Determine Whether Stability Can Broaden in the Coming Weeks
Prices Have Partly Stabilized, but Fund Flows Have Yet to Confirm
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The index fell just 0.9% for the week, but selling, earnings and buybacks are sending conflicting signals. Foreign flows and interest rates will determine the near-term direction; medium-term support depends on whether cash is genuinely converted into per-share returns.
TL;DR
The KOSPI’s modest decline masks much weaker market breadth. The KOSPI fell 0.9% for the week, supported by gains in technology and insurance; the KOSDAQ dropped 7.3%, while machinery, shipbuilding and autos declined 10.4%, 9.9% and 9.4%, respectively. The index has moved beyond the sharp selloff of early August, but most sectors have yet to stage a synchronized recovery.
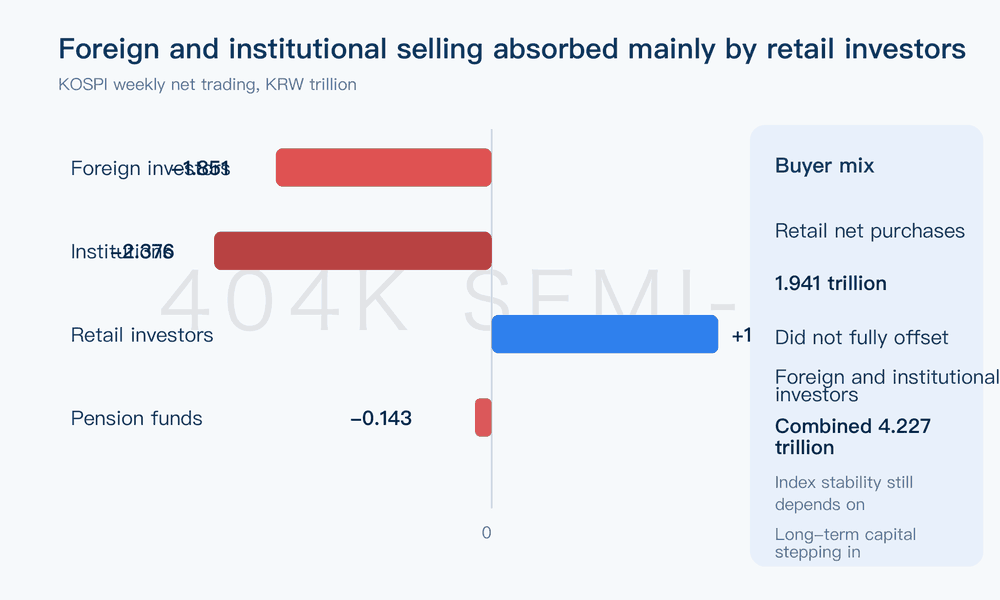
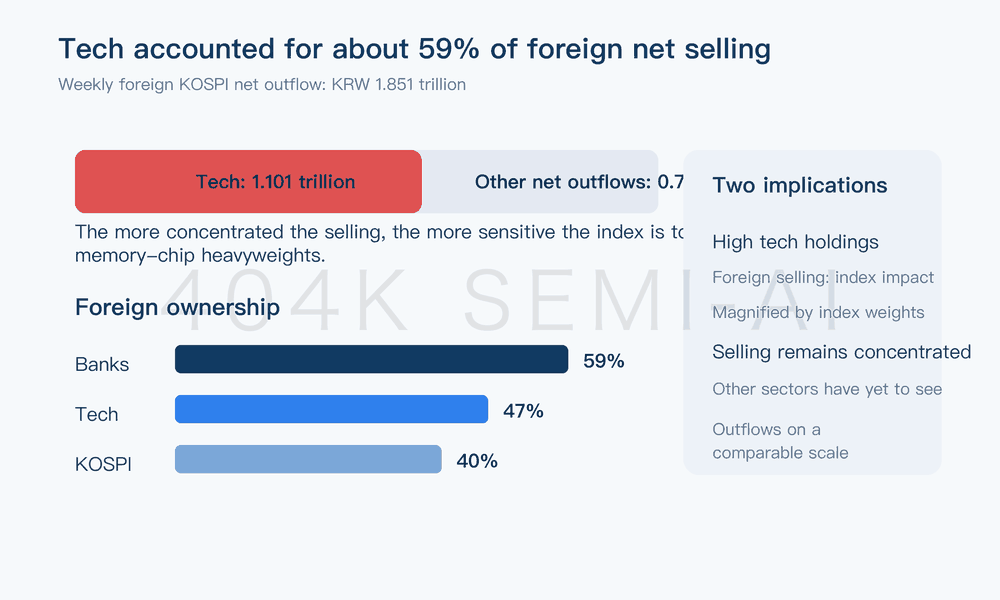
Retail investors absorbed some of the outflows, but long-term capital has yet to take over. Foreign investors recorded net KOSPI outflows of KRW1.851 trillion, institutions KRW2.376 trillion, while retail investors posted net inflows of KRW1.941 trillion. Foreign net selling in technology reached KRW1.101 trillion, approximately 59% of total foreign outflows, leaving the pressure concentrated in the index’s largest-weighted sector.
Neither earnings nor the currency corroborated the deterioration in share prices. KOSPI 12-month forward EPS estimates rose 1.4% over the week, with upgrades across insurance, software, healthcare and technology. The Korean won appreciated 2.2% against the US dollar, even as both 3-year and 10-year Korean government bond yields increased by 6bp. Exports, memory-sector profits and a stronger won provide a buffer, while higher rates continue to constrain multiple expansion.
Buybacks are evolving from individual corporate actions into a market-wide institution. Goldman Sachs characterized SK Hynix’s latest plan as a roughly KRW40 trillion share-repurchase and cancellation program. Announced buybacks by the information technology sector reached KRW36.456 trillion in 2026. Both the value and number of treasury-share cancellations have hit records, indicating that cash is beginning to flow into per-share value through reductions in share count.
A 5.6x 12-month forward earnings multiple is extremely low, but the entire market is not equally cheap. The KOSPI’s current multiple is close to its 5.1x low since 2006 and approximately 44% below its historical average of 10.0x. MSCI Korea trades at a 53% earnings-multiple discount to Asian equities but at a 14% premium on book value. The low earnings multiple depends heavily on expectations for 338% earnings growth in 2026.
Five sets of indicators must be assessed together from here. Foreign technology flows, KOSPI EPS revisions, Korean long-term rates and the won, progress on buybacks and share cancellations, and market breadth alongside the VKOSPI will determine whether this modest decline marks the start of stabilization, a high-volatility range, or merely a pause before the next leg down.
Beneath the 0.9% Decline, Heavyweight Support and Market Breadth Diverged
The KOSPI’s relative stability largely reflected heavyweight support from technology and insurance. The index closed at 6,912.95, down 0.9% for the week; the KOSPI 200 lost just 0.2%, while MSCI Korea gained 0.4% in local-currency terms. Technology rose 1.5%, insurance 6.8% and retail 1.3%, offsetting steep declines in machinery, shipbuilding, autos and construction.
The KOSDAQ’s 7.3% decline provides a clearer gauge of risk appetite toward small- and mid-cap stocks. Its underperformance versus the KOSPI reached 6.4 percentage points. Machinery, shipbuilding and autos posted near-double-digit losses, while banks, securities, chemicals and software also weakened markedly. Focusing only on the KOSPI’s 0.9% decline would understate the severity of the adjustment within sectors.
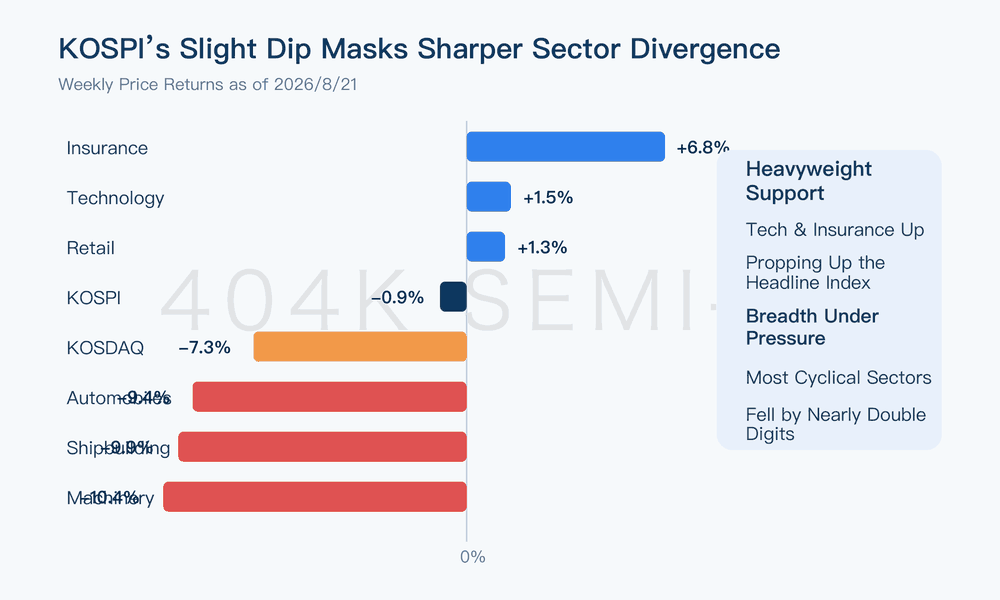
This structure is harder to interpret than an outright selloff. Technology earnings estimates continued to rise, while insurance benefited from both earnings and price support, preserving resilience in the index heavyweights. Cyclical manufacturers, automakers and smaller companies faced greater pressure, indicating that investors remain sensitive to global bond yields, order sustainability and elevated volatility.
The pattern was exactly the opposite in early August. The KOSPI then fell 5.1% in a week, while the KOSDAQ rose 11.0%; construction, software and chemicals materially outperformed, and market breadth improved despite weakness in heavyweight stocks. This week, the KOSPI’s decline narrowed, but the KOSDAQ and most non-technology sectors weakened. Price stability improved, while confirmation from market breadth took a step backward.
In mid-June, the KOSPI gained 11.4% in a week, foreign investors recorded net inflows of KRW2.54 trillion, and EPS estimates rose 1.5%. In early August, foreign net outflows widened to KRW5.931 trillion and the index fell 5.1%, even as EPS estimates increased 2.3%. This week, foreign net outflows narrowed to KRW1.851 trillion, the index declined only 0.9%, and the EPS upgrade moderated to 1.4%.
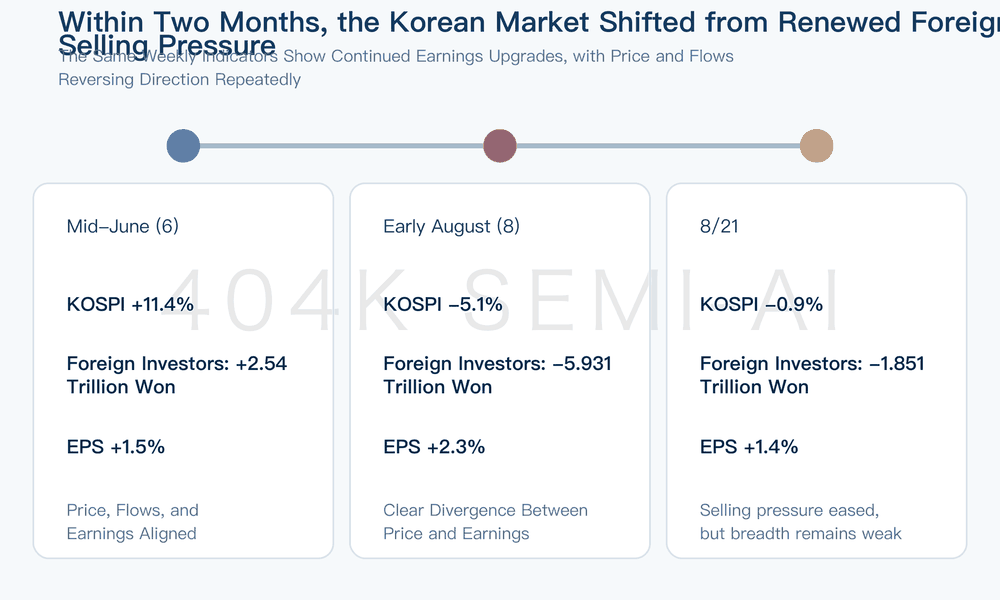
This timeline shows that outflow pressure has eased from early August while the earnings trajectory remains positive. However, the market has not returned to the synchronized improvement in flows, prices and earnings seen in June. Sustained stabilization requires foreign exposure reductions to slow further and gains to broaden across more sectors.
Korean Equity Re-Rating: Testing Technology Earnings, Foreign Inflows and MSCI Reform After the KOSPI Surpassed 9,000
Foreign Investors Are Still Selling, While Long-Only Active Funds Add Korea Exposure at Low Levels
The clearest pressure this week came from the composition of investor flows. Foreign investors recorded net KOSPI outflows of KRW1.851 trillion, institutions KRW2.376 trillion and pension funds KRW143 billion. Retail investors posted net inflows of KRW1.941 trillion and were also the primary buyers in the KOSDAQ.
Retail flows can cushion near-term declines but are generally less stable than foreign and pension capital. Retail positioning is more sensitive to volatility, financing costs and short-term gains or losses. Combined foreign and institutional net outflows reached KRW4.227 trillion, while retail net inflows covered less than half that amount. Other investors and market-price adjustments absorbed the remaining gap.
Foreign selling was concentrated in technology, making the index highly sensitive to these flows. Foreign net outflows from technology reached KRW1.101 trillion, approximately 59% of total foreign KOSPI outflows. Foreign investors own approximately 47% of the technology sector’s market capitalization, above their 40% ownership of the broader KOSPI. Technology is also the most concentrated source of index earnings growth.
Foreign ownership of banks is approximately 59%, higher than in technology, yet the sector did not experience comparable net outflows. Foreign investors also recorded modest net inflows into utilities, chemicals, steel and securities. Selling pressure currently exhibits clear sector concentration, reflecting concerns over the duration of memory-sector earnings and adjustments to technology positioning.
Goldman Sachs prime-brokerage data offer another perspective. Korea has experienced the largest net outflows in Asia since the beginning of 2026. That week, long outflows from Korea were approximately 1.5 times the value of new short positions, indicating that the primary move was a reduction in existing exposure. Korean hedge-fund net exposure fell to 4.2%, while gross exposure declined to 3.2%.
Despite these declines, the two ratios remain at the 91st and 97th percentiles, respectively, of their 5-year historical ranges. Short-term institutional exposure has come down, but absolute positioning has not returned to particularly low levels. If global rates or technology-sector volatility rises again, hedge funds still have room to reduce risk further.
Active mutual funds are sending a more constructive signal. EPFR data covering approximately 60% of assets show that Asia ex-Japan active funds are 80bp underweight Korea, while emerging-market active funds are 135bp underweight. In July, the two groups increased their Korea allocations relative to benchmark by 130bp and 80bp, respectively.
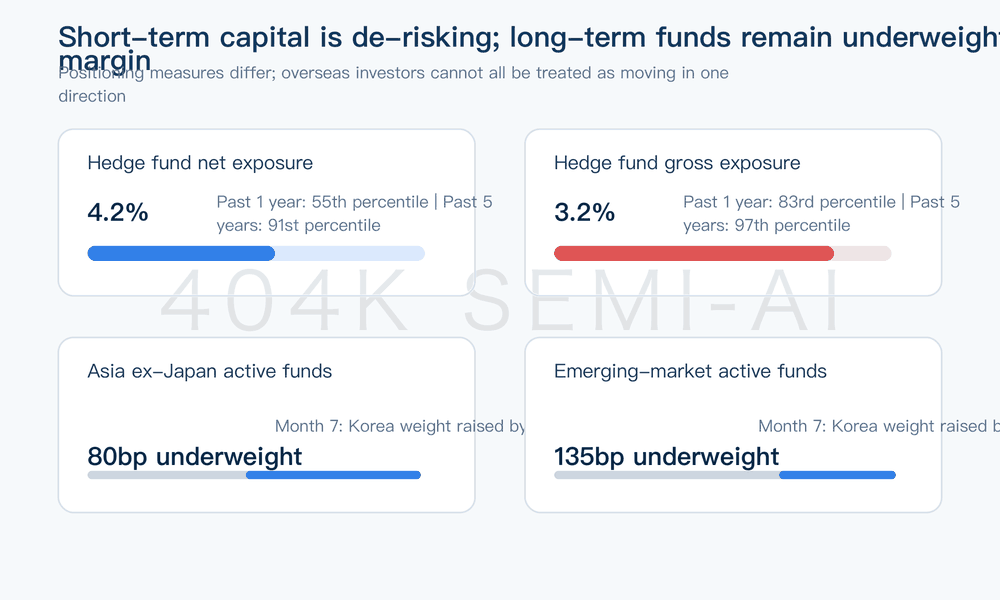
Short-term hedge funds can sell even as underweight long-only active funds increase exposure. The former determine intraday and weekly volatility; the latter determine whether the valuation discount can continue to narrow. Until weekly foreign flows turn positive, active funds’ underweight positions represent potential demand—not realized inflows.
EPS Estimates Continue to Rise, While Higher Rates Have Not Weakened the Won
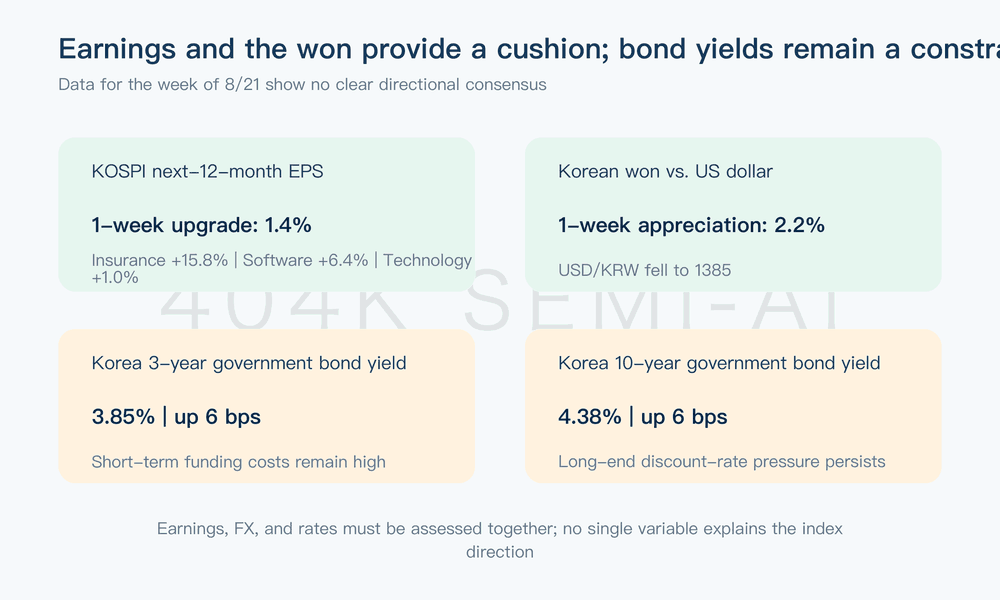
Earnings expectations remain the KOSPI’s strongest buffer. Forward 12-month EPS estimates rose 1.4% over the week. Insurance was revised up 15.8%, software 6.4%, healthcare 4.1%, and technology 1.0%. Leisure was cut 2.8%, utilities 1.6%, and chemicals 0.6%.
Longer-term revisions remain substantial. Over the past 6 months, 2026 EPS estimates rose 117% for technology, 99% for chemicals, 53% for securities, and 82% for the KOSPI overall. For 2027, technology estimates increased 155% and insurance 42%. The earnings denominator underpinning low P/E multiples continues to expand.
The pace of revisions has moderated from extreme levels. This week’s 1.4% increase was below 2.3% in early August, while technology estimates rose only 1.0% for the week. Insurance and software contributed more of the incremental gains. For the index to reduce its dependence on the two heavyweight memory stocks, these non-technology earnings revisions must remain consistently positive.
The won strengthened even as foreign investors sold Korean equities, indicating that equity flows were not driving the currency. USD/KRW fell to 1385, with the won appreciating 2.2% over the week and 6.3% over the past 1 month. Foreign investors nevertheless remained net sellers of Korean equities. The trade surplus, the broader US-dollar environment, and macro expectations offset the impact of equity outflows.
South Korea’s 3-year government bond yield rose to 3.85%, while the 10-year yield reached 4.38%, both up 6 basis points over the week. A stronger won reduces import costs and foreign investors’ currency risk, while higher long-term yields raise equity discount rates. These opposing forces help explain why the index has traded sideways with elevated volatility.
Goldman Sachs forecasts South Korea’s real GDP to grow 2.7% in 2026, exports to increase 8.3%, and the current-account surplus to reach 13.4% of GDP. Consumer prices are projected to rise 2.6%, with the policy rate at 3.0% at year-end. External demand and earnings are strong, but there is little scope for a meaningful easing in monetary conditions.
Memory prices continue to support technology earnings. The report shows that spot prices for two DRAM categories have risen 228.4% and 214.8% year to date, and 61.8% and 73.9% over the past 3 months, respectively. Over the latest week, one fell 0.3% while the other rose 1.3%. Elevated prices are supporting profits, but marginal price gains have become less consistent.
The tension can be reduced to one sentence: earnings can continue to grow, but valuation multiples remain constrained by interest rates and capital flows. If EPS estimates continue to rise, the won remains stable, and long-term yields stop climbing, investors are more likely to view low multiples as a genuine discount. If all three move in the opposite direction, higher risk premiums could offset further earnings upgrades.
Buybacks Must Progress from Announcement to Cancellation to Increase Per-Share Value
The scale of buybacks in 2026 has become a new variable for the Korean market. Goldman Sachs characterizes SK hynix’s latest initiative as an approximately KRW40 trillion share-repurchase-and-cancellation plan, and notes that the company raised its shareholder-return commitment to more than 50% of free cash flow. The plan pushed cumulative announced buybacks across the market to a record high.
By sector, announced buybacks reached KRW36.456 trillion in information technology and KRW5.548 trillion in financials. Consumer discretionary, industrials, and communication services each announced approximately KRW1 trillion. Buybacks are large but highly concentrated, with technology companies still overwhelmingly dominant.
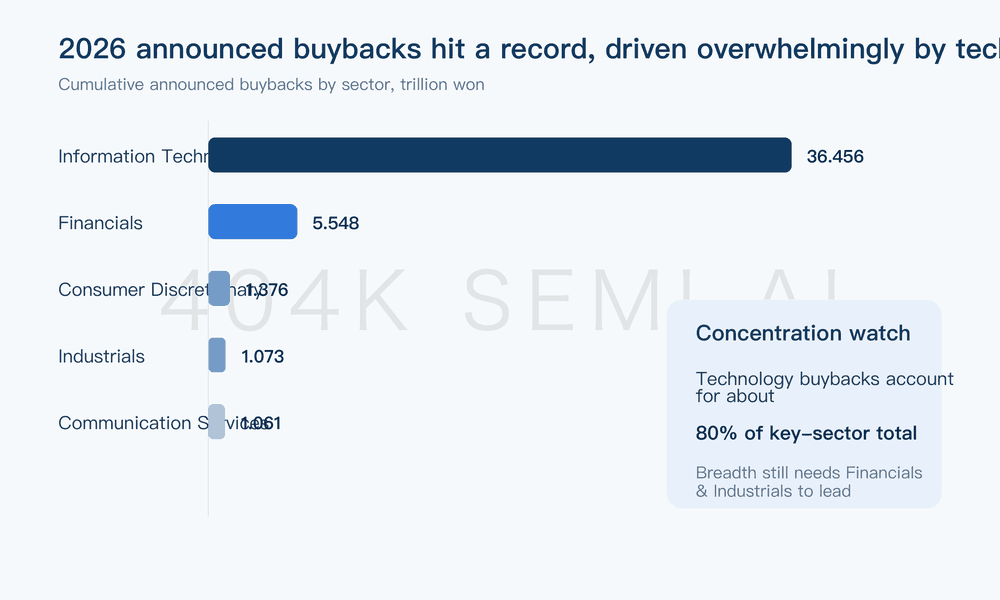
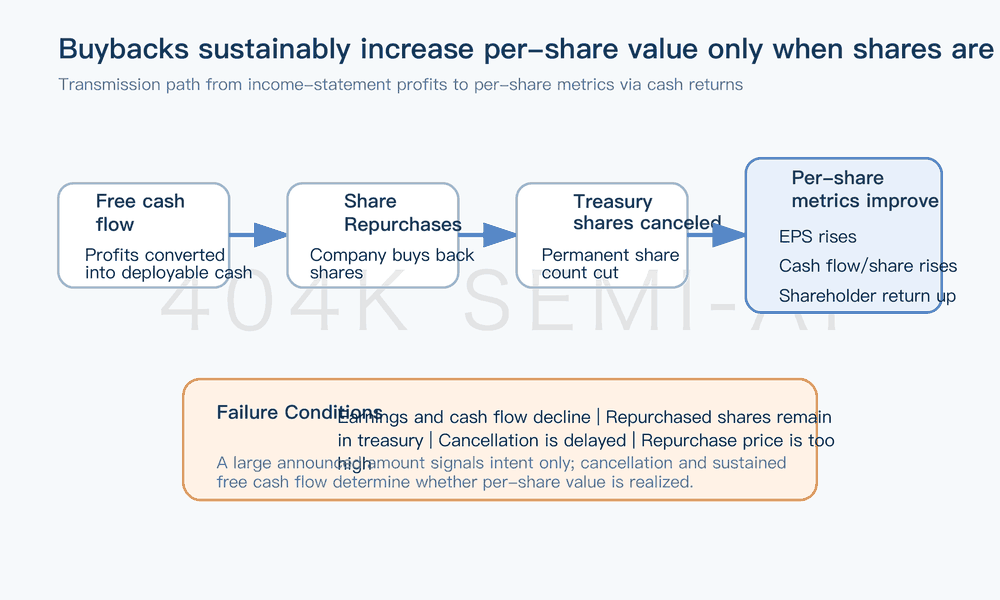
A buyback announcement indicates only an intention to allocate capital. If repurchased shares remain in treasury for an extended period, investors may still worry that they will eventually be reissued. Cancelling treasury shares permanently reduces the share count, increasing EPS and free cash flow per share when earnings and free cash flow are unchanged.
Both the value and number of treasury-share cancellations in Korea reached record highs in 2026, lending greater credibility to the institutional shift. Amendments to South Korea’s Commercial Act have raised expectations for treasury-share cancellation, and corporate-governance reforms are beginning to affect how cash is returned to shareholders. Per-share value improves when the share count falls; an announcement headline alone cannot achieve that.
Goldman Sachs’ sample shows that median returns 2 days, 5 days, 1 month, and 3 months after buyback announcements were all higher in 2024—2026 than in 2021—2023. At the 3-month horizon, the earlier sample’s median return was slightly negative, while the newer sample rose to approximately 2.3%. The market’s pricing of buybacks is beginning to extend beyond short-term sentiment.
Based on FactSet consensus estimates and current shareholder-return policies, the combined shareholder yield of Samsung Electronics and SK hynix is projected to rise from approximately 8% in 2026 to approximately 14% in 2027. An earlier Korea market report also projected that the two companies would contribute 57% of Korean corporate free cash flow in 2027. The latest weekly report more directly links that cash generation to buybacks and share cancellation.
Buybacks also face 3 constraints. First, announced amounts are heavily concentrated in technology, with no comparable scale yet evident in other sectors. Second, a downturn in memory profits would compress free cash flow and reduce shareholder yields. Third, repurchasing shares at excessively high prices reduces the number of shares that can be cancelled for the same cash outlay. Investors should therefore track actual repurchases, cancellation ratios, and free cash flow—not merely cumulative announced amounts.
The 5.6x Earnings Multiple Is Low, but the Stability of the Earnings Denominator Matters More
The KOSPI trades at 5.6x forward 12-month earnings, close to its historical low. Since 2006, the low has been 5.1x, the average 10.0x, and the high 14.6x. The current multiple is 44% below its historical average and remains below most normal ranges despite recovering from approximately 5.2x in early August.
MSCI Korea uses a different index universe and earnings methodology, with 2026 and 2027 P/E multiples of 6.3x and 4.7x, respectively. The two sets of multiples should not be used interchangeably, but they point in exactly the same direction: Korean equities are pricing exceptionally high earnings expectations at very low multiples.
Goldman Sachs forecasts MSCI Korea EPS growth of 338% in 2026 and 34.9% in 2027. Return on equity is projected to jump from 11.1% in 2026 to 37.9% in 2027 and remain at 36.3% in 2028. The price-to-book ratio is projected at 2.0x in 2026, falling to 1.5x in 2027.
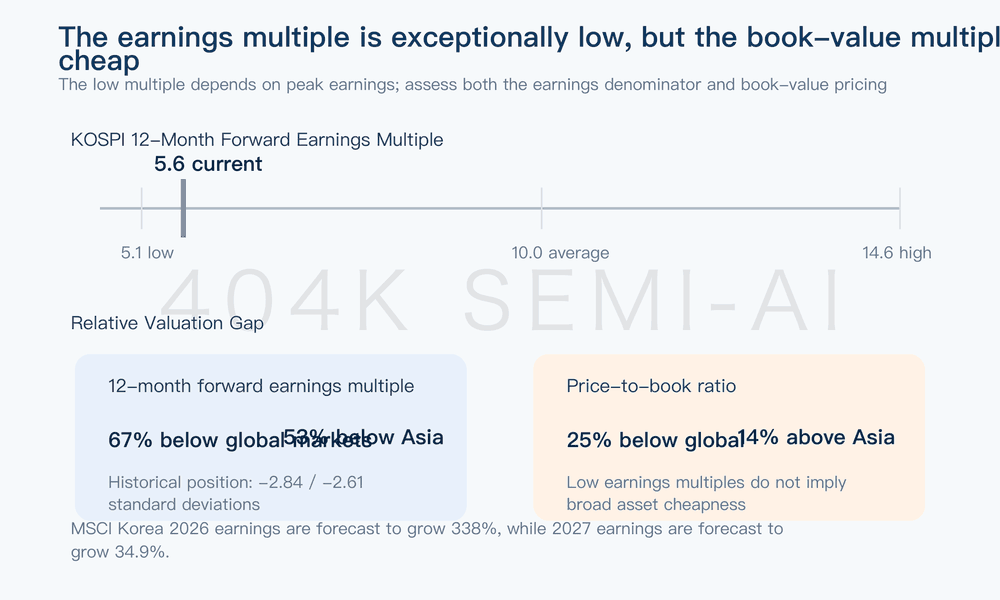
Earnings and book-value multiples tell different stories. MSCI Korea’s forward 12-month P/E is 67% below the global market and 53% below Asia Pacific ex-Japan, placing the relative valuations at negative 2.84 and negative 2.61 standard deviations from their respective 10-year histories. On earnings, Korea is exceptionally cheap.
Its price-to-book ratio is 25% below the global market but 14% above Asia Pacific ex-Japan, corresponding to positive 3.38 and positive 4.20 standard deviations versus historical levels. On book value, Korea is no longer cheap relative to Asia. Investors are willing to pay a higher book-value multiple for the strong ROE generated by memory, but they are unwilling to assign those elevated earnings a long duration.
This defines the risk boundary around the low earnings multiple. If ROE remains close to 38% in 2027, a 4.7x P/E would represent an excessive discount. If profits retreat from their peak, however, the earnings multiple will rise mechanically even if share prices remain unchanged. Multiple expansion need not drive share-price gains; it can also result from a declining earnings denominator.
Goldman Sachs maintains a 12-month KOSPI target of 12000 in its macro forecast table, approximately 74% above 6912.95. Reaching that target requires both earnings delivery and a narrowing valuation discount. Persistent foreign net selling, rising long-term rates, or downward revisions to memory earnings would all delay that path.
Buybacks can increase per-share value but cannot independently eliminate the earnings cycle. If non-technology sectors continue to receive earnings upgrades, the index’s profit base will become more diversified and investors may assign earnings a longer duration. Whether insurance, software, healthcare, industrials, and financials can take over as incremental drivers will determine whether the low earnings multiple evolves from a “peak-earnings discount” into more durable valuation support.
Three Sets of Signals Will Determine Whether Stability Can Broaden in the Coming Weeks
The Korean equity market currently looks more like a high-volatility range-bound market. Outflow pressure has eased markedly from early August, earnings per share are still being revised upward, and share buybacks and cancellations provide downside support. However, foreign investors remain net sellers of technology stocks, market breadth is weak, and long-term interest rates are rising. The three sets of evidence have yet to align.
The Korean equity market risk barometer has fallen to -0.7, entering risk-off territory. The VKOSPI has retreated from an extreme high near 100 but remains well above the norm of recent years. The share of KOSPI constituents trading above their 200-day moving averages has fallen to about 20%, indicating that most stocks remain below their medium-term trends.
The ratio of margin balances to investor deposits has retreated from its previous peak to about 30%, reducing the risk of forced technical liquidations relative to recent months. Foreign ownership and hedge-fund positioning remain high, however, leaving scope for further reductions in offshore exposure. Easing domestic margin pressure and shrinking overseas risk budgets should be assessed separately.
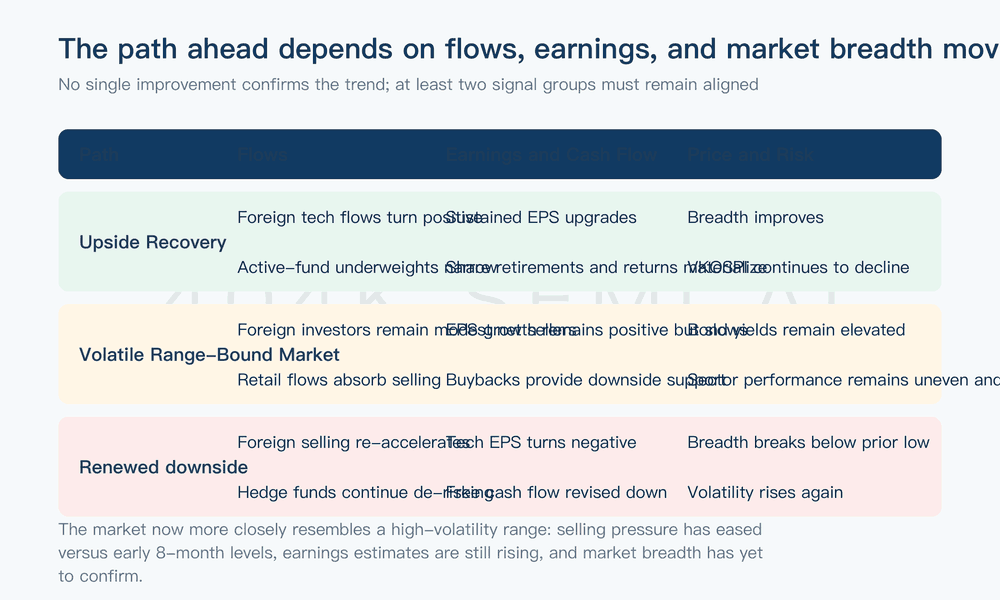
An upside recovery would require sustained positive foreign flows into technology, a further narrowing of active funds’ underweight positions, and continued upward revisions to KOSPI earnings per share. Treasury-share cancellations and shareholder-return targets must also be delivered as planned. Improving market breadth and a further decline in the VKOSPI would confirm that gains are no longer being driven solely by a handful of index heavyweights.
A high-volatility range remains the base case. Modest foreign outflows are being absorbed by retail investors; earnings revisions remain positive but are gradually losing momentum; and buybacks provide support while bond yields cap valuation multiples. The index may remain relatively stable, but sector rotation and week-to-week volatility are likely to remain pronounced.
A renewed downturn would require three signals to converge: foreign net outflows returning toward early-August levels, technology earnings revisions turning negative, and free-cash-flow expectations declining alongside lower memory prices. If market breadth and volatility deteriorate simultaneously, the 5.6x earnings multiple is likely to remain depressed.
Weekly monitoring can be distilled into five groups of public data. First, net foreign flows into technology and the scale of retail absorption. Second, four-week earnings revisions for the KOSPI and technology sector. Third, the 10-year Korean government bond yield and USD/KRW. Fourth, actual buyback and cancellation amounts and shareholder-return ratios. Fifth, the VKOSPI, margin balances, and the share of constituents trading above their 200-day moving averages.
Prices Have Partly Stabilized, but Fund Flows Have Yet to Confirm
The KOSPI fell only 0.9%, indicating greater resilience to interest rates and foreign outflows. Upward earnings revisions, a stronger won, memory prices, and share buybacks and cancellations collectively absorbed selling pressure. Weakness in the KOSDAQ and most non-technology sectors nevertheless shows that stability still depends on a small number of heavyweight sectors.
Buybacks have changed the nature of downside support in the Korean market. Through share cancellations, profits can translate into higher earnings and cash flow per share, providing a tangible path to narrowing the governance discount. However, concentrated earnings, continued reductions in foreign exposure, and a relatively elevated price-to-book ratio limit the certainty of this outcome.
The key question in the coming weeks is whether fund flows, earnings, and market breadth can improve simultaneously. Stability will broaden into a more durable recovery only if foreign outflows cease, earnings per share continue to be revised upward, and more stocks move above their 200-day moving averages. If only one of these conditions materializes, Korean equities will continue to combine high potential returns with high volatility.