
Korea Equities Deep Dive: The Disconnect Between the KOSPI’s 22% Monthly Decline, 4.7x Valuation, and Record One-Day Foreign Inflows
目录
TL;DR
I. Why the Strongest One-Day Rebound Still Belonged to the Worst Month
II. What Exactly Is Cheap About 4.7x?
III. July’s Evolution: Valuations Kept Compressing, While Fund-Flow Confirmation Remained Inconsistent
IV. Why Deleveraging Is Self-Healing—and Why It Cannot Yet Be Declared Over
V. Light Foreign Positioning Is a Spring, Not a Directional Signal
VI. Why Earnings Have Not Deteriorated: Memory Prices Are Still Rising
VII. Growth Is Strong, but the Macro Backdrop Is Not a One-Way Tailwind
VIII. “The KOSPI Still Reaches 9,001 Under Global Financial Crisis-Level Stress” Cannot Be Applied Mechanically
IX. Three Paths: Turning the Reversal Thesis into Verifiable Conditions
X. Conclusion: The Risk-Reward Has Changed, but the Evidentiary Bar Is Even Higher
Key References
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The KOSPI posted its strongest rebound on the final day of its worst month. What determines the next direction will be which factor prevails first: extremely low valuations, strong earnings, or unstable fund flows.
TL;DR
The record rebound on July 31 did not erase July’s liquidation. The KOSPI fell 22% in July, its worst month since the global financial crisis; yet as of July 31, the index was still up 56.5% from end-2025. This is a rapid repricing of a market with enormous prior gains, crowded positioning, and still-strong earnings; the experience of an ordinary bear market or a routine bull-market correction does not apply.
The 4.7x forward P/E is genuinely extreme, but the appearance of being “cheap” depends heavily on the earnings denominator. The KOSPI’s 12-month forward P/E fell to its lowest level since 2001, forward ROE was approximately 25%, and weekly EPS estimates were still revised up 0.9%. Meanwhile, the consensus forecast for MSCI Korea’s 2026 EPS growth is as high as 317.1%. As long as earnings hold, there is enormous room for valuation recovery; if earnings are revised down from their peak, the headline P/E will automatically rise.
Foreign investors returned in record numbers during the final two trading days, but this has not yet developed into a weekly trend. Foreign investors still recorded net KOSPI selling of KRW 1.689 trillion for the week, including KRW 881 billion of net technology-sector selling; cumulative net outflows in 2026 remain substantial. Foreign ownership of semiconductors is approximately 49.4%, 2.1 standard deviations below the average since 2000, indicating ample potential for position rebuilding—but “underweight” cannot be equated directly with “must buy.”
Deleveraging is becoming self-limiting. Margin-financing balances fell from US$25 billion to US$22 billion, equivalent to approximately 0.5%—0.6% of total market capitalization; assets under management in Korean leveraged ETFs fell from US$53 billion to US$26 billion, with leveraged exposure equivalent to approximately 1.9% of free-float market capitalization. Mechanical selling pressure has eased materially, but the decline in scale reflects both redemptions and NAV erosion caused by falling prices, so it cannot be used to declare that positions have been fully cleared.
Earnings remain supported by the memory cycle, but market breadth has not recovered in tandem. Spot prices for two types of DRAM have risen 218.2% and 201.7%, respectively, year to date, while weekly technology-sector EPS estimates were revised up 1.1%; however, only approximately 20% of KOSPI constituents are above their 200-day moving averages, and the VKOSPI remains elevated. Earnings data say “the cycle has not broken,” while trading data say “risk budgets have yet to recover.”
This recovery should be assessed against four concurrent conditions, rather than a single up day. Foreign investors must consistently repurchase technology shares, technology earnings must continue to be revised up, the VKOSPI and market breadth must improve, and leveraged products must no longer re-expand. Only when all four occur simultaneously will the market be close to a trend reversal. The most reasonable characterization at present is that the risk/reward has improved materially, but confirmation remains insufficient.
I. Why the Strongest One-Day Rebound Still Belonged to the Worst Month
Goldman Sachs placed two seemingly contradictory charts on the same page: on July 31, the KOSPI recorded both its largest one-day gain and its largest one-day foreign inflow on record; yet it fell 22% over the full month of July, only slightly better than the 23% decline in October 2008. Both the daily and monthly figures are true; the only difference is the time horizon.
The monthly decline reflects the entire liquidation process: excessive prior gains, reductions in foreign-investor and derivatives positioning, daily rebalancing by leveraged ETFs, and lower risk budgets following a rise in volatility. The powerful rebound on the final day shows that once selling was compressed to an extreme, marginal buying could generate very large price elasticity. It proved that the market “can rebound,” but did not prove that buying “will persist.”
More importantly, the KOSPI still stood at 6,595 as of July 31, up 56.5% in 2026; the KOSPI 200 had gained 72.7% year to date, MSCI Korea had risen 78.4%, and the technology sector had surged 115.0%. The 22% decline in July therefore did not occur in a market suffering from long-term stagnation, but after an enormous rally. Cost bases, profit-taking incentives, index-weight constraints, and leveraged rebalancing will all be more sensitive than in an ordinary market.
This also explains why “the worst month since the global financial crisis” and “extremely strong earnings” can coexist: prices are liquidating the trading structures accumulated earlier, while earnings have not collapsed in tandem. Attributing every decline to deteriorating fundamentals would overlook positioning mechanics; interpreting every rebound as fundamental confirmation would underestimate residual leverage and volatile fund flows.
II. What Exactly Is Cheap About 4.7x?
As of July 30, the KOSPI’s 12-month forward P/E under Goldman Sachs’ methodology was 4.7x, its lowest since 2001 and even below the trough during the global financial crisis. Page 7 of the report showed a P/E of 4.5x based on 2026 earnings, while page 12 showed a 2026 consensus P/E of 5.3x for MSCI Korea. The three figures are not contradictory: the index universes, calculation dates, and earnings methodologies differ, but all point to the same conclusion—the earnings denominator for Korean equities is extremely large, while prices are being discounted rapidly.
The combination of P/B and ROE better illustrates the disconnect. The KOSPI’s forward P/B is approximately 1.37x, with forward ROE of approximately 25%. Based on the historical relationship since 2005, this level of profitability would typically correspond to a higher P/B. The market does not currently disbelieve that Korean companies can generate profits; it is unwilling to pay a normal persistence premium for those profits.
Regional comparisons are equally extreme. MSCI Korea trades at an approximately 67% forward P/E discount to MSCI World and an approximately 53% discount to Asia-Pacific ex-Japan, corresponding to historical z-scores of approximately -2.84 and -2.61, respectively. Yet its P/B discounts to global equities and Asia-Pacific ex-Japan are only 25% and 14%, with historical z-scores as high as +3.38 and +4.20. In other words, Korea is not cheap across every valuation dimension; the extreme is concentrated primarily in the P/E ratio, rather than the price paid per unit of net assets.
This is a critical dividing line. A low P/E may mean that prices are too low, or that the market considers peak-cycle profits unsustainable. Consensus EPS growth for MSCI Korea is projected at 317.1% in 2026 and a further 37.6% in 2027; expected ROE reaches 36.8% in 2027. If such a steep earnings trajectory materializes, 4.7—5.3x is clearly excessively pessimistic; if memory prices, product mix, or customer capital expenditure weaken in 2027, the P/E denominator will fall, and today’s “historical low” will be reinterpreted as a “peak-earnings discount.”
The 4.7x multiple therefore provides a very large margin for error, not a waiver from due diligence. The real pricing question for the Korean market is not whether it is cheap, but how long these profits can be sustained.
III. July’s Evolution: Valuations Kept Compressing, While Fund-Flow Confirmation Remained Inconsistent
Connecting July’s key inflection points provides a clearer view of the market structure than any single week’s data.
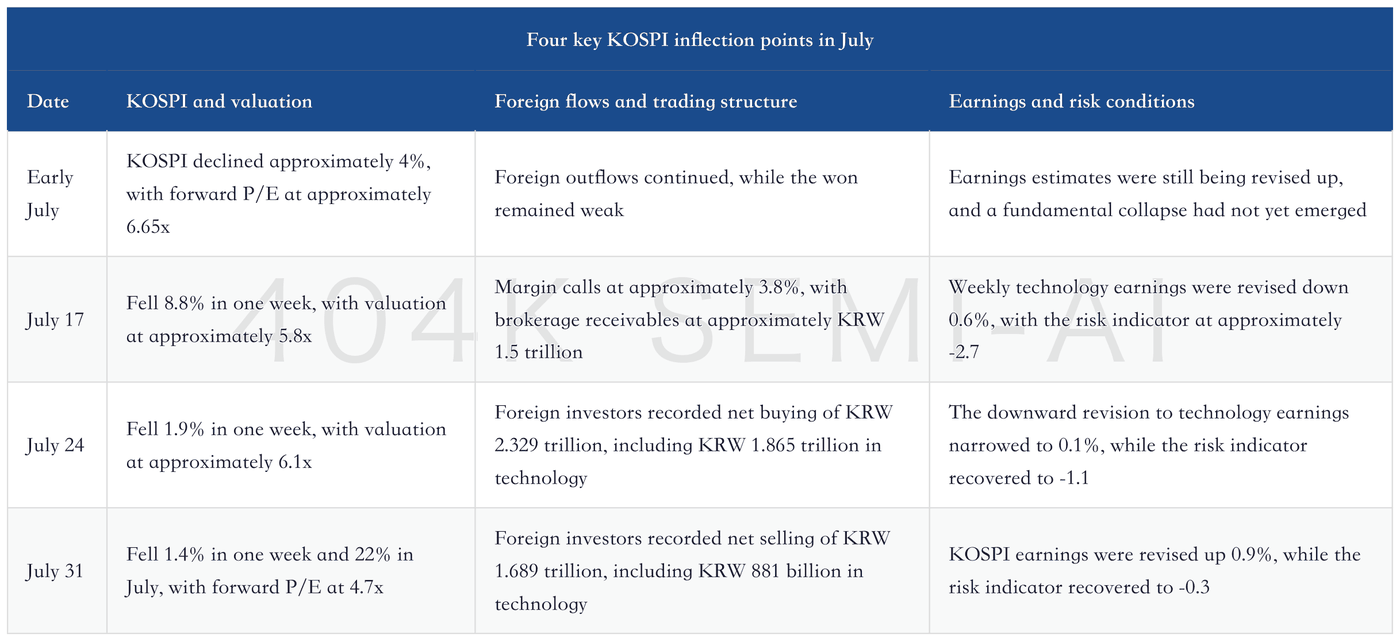
This table reveals three inflection points.
First, the most intense trading pressure emerged around July 17, after which margin and leverage pressures gradually eased. Second, foreign investors did not return in a straight line: they bought technology shares heavily during the week of July 24, then returned to selling during the week of July 31; record inflows over the final two trading days merely reduced the week’s net selling and did not turn weekly flows into net buying. Third, earnings shifted from modest weekly downward revisions back to upward revisions, while the risk indicator continued to improve, showing that prices, fund flows, and earnings were no longer deteriorating in the same direction.
For the earlier full stress test, see “Korea Weekly Review: Can a 5.8x Valuation Withstand the Retreat in Semiconductor Momentum After the KOSPI’s 8.8% Decline?”. Compared with that point, earnings revisions and trading pressure have improved; the weaker aspect is that even after valuations compressed further, foreign investors have still not taken over consistently as buyers.
The Korean market has therefore shifted from “prices, positioning, and earnings deteriorating together” to “low prices, strong earnings, and volatile fund flows.” The latter state offers better risk/reward, but volatility may also be higher because every shift in fund flows will act upon valuations that are already extremely compressed.
IV. Why Deleveraging Is Self-Healing—and Why It Cannot Yet Be Declared Over
Margin-financing balances have fallen from US$25 billion to US$22 billion, equivalent to roughly 0.5%–0.6% of South Korea’s total equity market capitalization. This is not a high ratio, suggesting that traditional margin financing is more a source of localized pressure than a systemic credit event. The real amplifiers of volatility are leveraged ETFs and the associated hedging demand.
Assets under management in South Korean leveraged ETFs have fallen from a peak of US$53 billion to US$26 billion, nearly halving; current leveraged exposure is equivalent to approximately 1.9% of free-float market capitalization. As product assets shrink, the same 1% index move generates less notional rebalancing demand, naturally weakening the “decline–forced passive selling–further decline” feedback loop. The record one-day rebound was partly a result of this nonlinear elasticity.
But a halving of assets does not mean positions have been fully unwound. The decline in assets under management can come from two sources: investor redemptions and NAV erosion caused by declines in underlying assets. Only the former demonstrates that risk capital has genuinely exited; exposure lost through the latter may recover rapidly in notional terms when the market rebounds. If a rebound also attracts subscriptions to leveraged products, mechanical buying will initially amplify the advance and will again amplify selling pressure in the next decline.
At least three types of evidence are needed to identify the endpoint of deleveraging. First, net subscriptions into leveraged ETFs and assets under management should no longer expand in tandem. Second, VKOSPI should decline sustainably and no longer diverge materially from global volatility. Third, market breadth should recover, rather than the index being supported solely by a handful of heavyweight stocks.
The status presented on page 18 remains cautious: the South Korean equity risk barometer stands at -0.3, in risk-off territory; although VKOSPI has retreated from its most extreme level, it remains elevated; and only approximately 20% of KOSPI constituents are above their 200-day moving averages. Prices can rebound sharply despite very weak breadth, but such rebounds depend more heavily on a small number of highly liquid heavyweight stocks and short covering, making them less stable than an advance driven by broad-based improvement.
V. Light Foreign Positioning Is a Spring, Not a Directional Signal
Goldman Sachs data show that foreign ownership of the semiconductor sector is approximately 49.4%, 2.1 standard deviations below its average since 2000. At this level, merely an end to selling by overseas long-term and benchmark-tracking funds could generate meaningful position rebuilding; a renewed shift to overweight would create even greater upside elasticity.
But low positioning describes “how much can be bought,” not “why investors should buy now.” Foreign investors sold a net KRW 1.689 trillion of KOSPI stocks in the final week of July, including KRW 881 billion of technology stocks; over the same period, South Korean financial institutions bought a net KRW 5.474 trillion, pension funds bought a net KRW 921 billion, and retail investors sold a net KRW 3.834 trillion. The market held up not because all investor groups reached a consensus, but because domestic institutions absorbed selling by foreign and retail investors.
Sector flows were also highly divergent. Foreign investors bought KRW 182 billion of autos, KRW 241 billion of shipbuilding, KRW 208 billion of securities firms, and KRW 128 billion of machinery, while selling KRW 191 billion of banks, KRW 157 billion of telecoms, and KRW 881 billion of technology. Technology prices rose 0.1% that week and outperformed the KOSPI by 1.6 percentage points, indicating that the selling was met by strong demand; however, “price resilience” and “foreign investors returning to technology” remain two different things.
The record foreign inflows over the final two trading days should therefore be viewed as an important test: the market has the capacity to absorb supply at extremely depressed valuations, and foreign investors are willing to rebuild positions quickly. Genuine confirmation would not be another large one-day figure, but several consecutive weeks of net buying in technology, a sustained recovery in semiconductor ownership from 49.4%, and inflows that no longer depend on an extreme single-day market move.
If this chain holds, light positioning will become fuel for further gains; if earnings or global risk appetite weakens, light positioning will merely reflect caution that has yet to dissipate.
VI. Why Earnings Have Not Deteriorated: Memory Prices Are Still Rising
This week, 12-month forward EPS estimates were revised up by 0.9% for the KOSPI, 1.1% for technology, 2.6% for software, and 2.2%, 2.0%, and 1.7% for shipbuilding, machinery, and healthcare, respectively; estimates for construction and utilities were revised down by 1.7% and 1.5%, respectively. The sharp price decline did not translate into a market-wide earnings collapse; instead, estimates were revised upward again.
The magnitude over a longer window is substantial. Over the past 6 months, 2026 earnings estimates have risen by 111% for the KOSPI and 189% for technology; 2027 earnings estimates have risen by 147% and 261%, respectively. This is both the source of the low P/E ratio and the largest concentration risk: index earnings are highly dependent on technology, while technology is highly dependent on memory prices, the HBM and high-end DRAM product mix, and global AI infrastructure capital expenditure.
Spot prices continue to support the bullish case. Page 17 of the report shows that two DRAM spot prices stand at US$11.9 and US$13.9, up 4.6% and 4.1% week on week, 63.5% and 93.2% over the past 3 months, and 218.2% and 201.7% since the beginning of 2026. This is not a mild recovery, but a pronounced pricing cycle.
However, spot prices cannot be equated directly with Samsung Electronics’ or SK Hynix’s contractual revenue, much less serve as a substitute for HBM qualification, yields, market share, and supply discipline. The South Korean technology sector currently trades at only 3.7 times forward earnings, an all-time historical low; the market has clearly priced in both “very strong earnings” and “a very short duration.”
The key risk is not a sudden collapse in demand to zero, but earnings growth decelerating from exceptionally high to ordinary levels. At an index P/E of 4.7 times, prices can absorb considerable bad news as long as EPS is not revised down substantially; for a technology sector whose denominator already incorporates several-fold growth, a slowdown alone would be sufficient to change the valuation framework.
Excluding the two semiconductor leaders, the South Korean market trades at approximately 5.3 times forward earnings, still below regional peers and its own historical range. This indicates that the low valuation is not entirely an illusion created by heavyweight stocks, but earnings quality is uneven: construction fell 13.5% that week, telecoms fell 10.9%, and shipbuilding fell 7.2%, while technology rose 0.1%. A cheap index does not mean every sector has the same earnings support.
VII. Growth Is Strong, but the Macro Backdrop Is Not a One-Way Tailwind
Goldman Sachs expects South Korea’s real GDP to grow by 2.7% in 2026, exports by 8.3%, and the current-account surplus to reach 13.4% of GDP; exports excluding ships rose 73.3% year on year in June. The Bank of Korea’s official May forecast was slightly lower, projecting 2026 GDP growth of 2.6%, but it likewise viewed the semiconductor cycle as the main source of support. Both institutions point in the same direction: South Korea is not waiting for a valuation recovery amid recession, but undergoing an asset-price correction alongside strong exports and robust technology earnings.
The problem is that strong growth also creates interest-rate constraints. On July 16, the Bank of Korea raised its policy rate from 2.50% to 2.75%, citing stronger growth driven by exports and investment, inflation remaining above target for an extended period, and financial-stability risks. June CPI rose 3.2% year on year, while core inflation was 2.5%. The monthly policy rate of 2.50% in Goldman Sachs’ weekly report is earlier data and does not represent the actual policy stance as of August 1.
Market rates declined this week but remain high in absolute terms: South Korean 3-year and 10-year government-bond yields stand at 3.76% and 4.26%, respectively, down 20 and 19 basis points over the week. Lower rates support valuations, but also indicate that the market is repricing the outlook for growth, inflation, and policy. Goldman Sachs expects the policy rate to reach 3.0% at the end of 2026 and 3.25% at the end of 2027, implying that if inflation persists, valuation expansion will face a higher risk-free rate.
The currency also cuts both ways. USD/KRW stands at 1,444, with the won appreciating 1.0% over the week and 6.9% over the month. For overseas investors, a stronger won can amplify US-dollar returns; for exporters, it reduces translated revenue but also lowers the cost of imported energy and raw materials. For South Korea, neither “the stronger the won, the better” nor “the weaker the won, the better” is correct. The ideal combination is a stable exchange rate, strong memory prices, and interest rates that are no longer rising rapidly.
The macro backdrop therefore provides a discount-rate constraint between earnings and valuations, rather than an additional bullish argument. Exports and memory support profits, inflation and interest rates constrain multiples, and the won determines foreign investors’ actual returns. All three must be monitored simultaneously.
VIII. “The KOSPI Still Reaches 9,001 Under Global Financial Crisis-Level Stress” Cannot Be Applied Mechanically
Page 5 of Goldman Sachs’ report presents a striking stress scenario: the current consensus estimate for 12-month forward EPS is 1,180; applying the 41% downgrade seen at the worst point of the 2008 global financial crisis reduces EPS to 694; applying the 13 times P/E recorded when EPS bottomed in 2008 then implies a KOSPI level of approximately 9,001. Compared with the current level of 6,595, this still represents approximately 36% upside.
At first glance, this appears to imply that “the index will rise even if earnings collapse.” The actual mathematical implication, however, is that earnings downgrades and multiple expansion occur simultaneously. Multiplying 694 by 13 times gives approximately 9,000; if earnings remain at 1,180 while the multiple returns to 13 times, the index would be far above its current level. This scenario does not assume that earnings are safe; it assumes that the closer earnings come to a trough, the more willing the market becomes to pay a normalized multiple.
Consider the reverse case as a deterministic exercise: if EPS falls to 694 while the P/E remains at 4.7 times, the implied index level is only approximately 3,262, roughly 50% below the current level. This is not Goldman Sachs’ forecast, but a sensitivity result derived from the same set of figures. It demonstrates that the “9,001 stress scenario” is by no means an unconditional floor, and that a 13 times multiple cannot be assumed to materialize automatically.
Historical drawdown statistics require equal caution. After previous severe KOSPI drawdowns, median returns over 3, 6, and 12 months were 16%, 43%, and 59%, respectively, but individual outcomes varied enormously: the 12-month return after the dot-com bubble was negative, while the rebounds after 2009 and 2020 were exceptionally strong. Historical averages show that the odds turn positive after extreme drawdowns; they do not prove that the timing and path can be replicated.
Goldman Sachs also sets a 12-month KOSPI target of 12,000, approximately 82% above the current level. Realizing such substantial upside requires the combination of sustained earnings, renewed foreign inflows, and valuation normalization. Without any one of these, the pace of reaching the target would slow materially; if earnings and multiples decline simultaneously, a low P/E cannot prevent another round of price pressure.
IX. Three Paths: Turning the Reversal Thesis into Verifiable Conditions
Over the next several weeks, there is no need to debate whether “the bull market is over” or “a historic bottom is in.” We only need to observe which combination of data is gaining momentum.
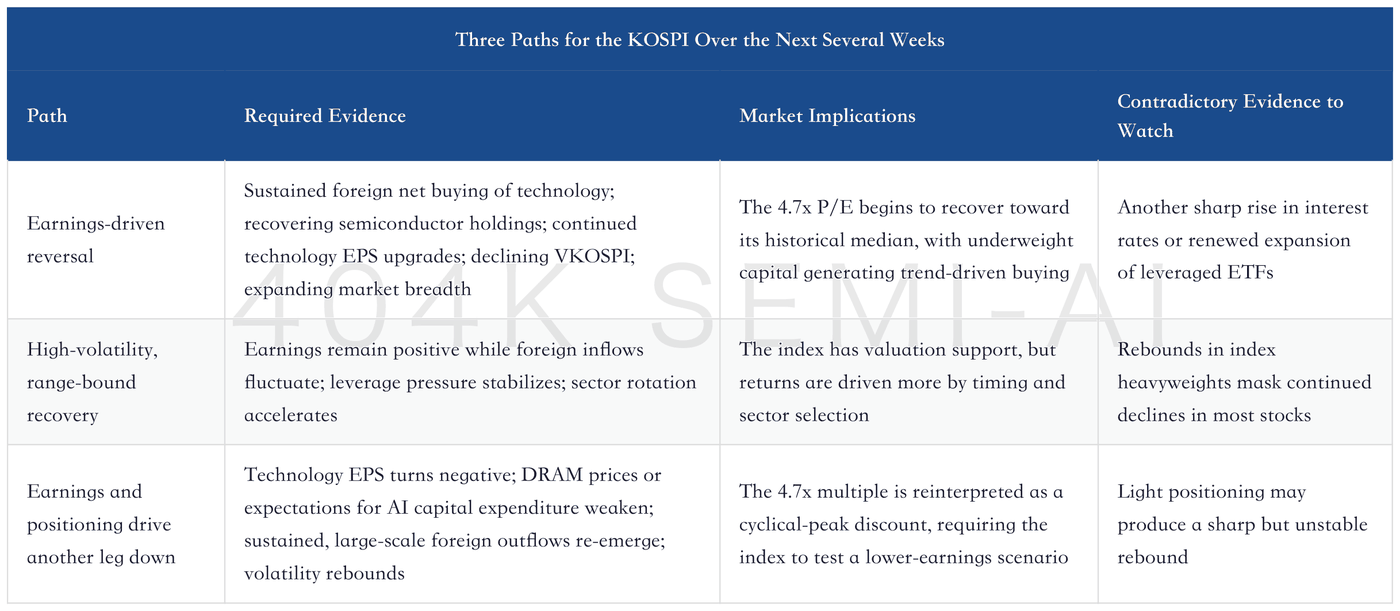
The market is currently closest to the second path and moving toward the first. The rationale is clear: earnings upgrades have resumed, the risk temperature has recovered from -2.7 to -0.3, and margin financing and leveraged ETF assets have declined; however, foreign investors still recorded net technology selling for the week, while VKOSPI and market breadth remain unconfirmed.
The four most important indicators to monitor next, in order, are:
Whether weekly foreign flows into technology can remain positive for consecutive weeks, rather than merely producing a one-day record;
Whether weekly KOSPI and technology EPS estimates continue to be upgraded, with the improvement broadening beyond technology;
Whether VKOSPI and the proportion of constituents trading above their 200-day moving averages improve simultaneously;
When leveraged ETF assets increase, whether the increase reflects ordinary price recovery rather than a new wave of net subscriptions adding leverage.
Of these four, the first two determine earnings and capital flows, while the latter two determine the trading structure. Only if all improve simultaneously can the market progress from “positively skewed risk-reward after a deep decline” to a “sustainable trend.”
X. Conclusion: The Risk-Reward Has Changed, but the Evidentiary Bar Is Even Higher
The most valuable aspect of this Goldman Sachs weekly report is not an aggressive rebound target, but its integration of three curves for the Korean market: the price curve has already suffered a Global Financial Crisis-scale drawdown, the earnings curve is still being revised upward, and the positioning curve lies between deleveraging and light foreign positioning.
A 4.7x forward P/E, 25% forward ROE, foreign semiconductor holdings 2.1 standard deviations below the mean, and a halving of leveraged ETF assets indeed constitute a rare positively skewed setup. Bad news is already priced in, and as long as earnings do not collapse and capital outflows cease, the index may have substantial recovery potential.
However, a record one-day rebound still cannot substitute for evidence of a trend. Foreign investors continued to sell technology during the week, volatility remains high, market breadth is weak, and the macro environment has shifted into a combination of strong growth, high inflation, and restrictive interest rates. The Korean market is not currently “low risk,” but rather “high reward with a high evidentiary bar.”
The most accurate conclusion is therefore neither to buy the dip indiscriminately nor to dismiss AI hardware earnings simply because the market fell 22% in July. Positioning should be divided into two questions: whether investors are willing to retain core exposure at extreme valuations, and when sustained capital flows, broadening earnings improvements, and technical breadth justify increasing the risk budget. The former is determined by risk-reward; the latter must be determined by evidence.
Key References
Goldman Sachs Global Investment Research, Korea Weekly Kickstart: KOSPI Posts Worst Month Since the GFC Despite Record Daily Gain Fueled by The Largest Single-Day Foreign Inflows, August 1, 2026.
Bank of Korea, Economic Outlook (May 2026), May 28, 2026, official source.
Bank of Korea, Monetary Policy Direction (2026.7.16), July 16, 2026, official source.
Related Reading
Qualcomm Q3 Earnings: Autos Grow 61%, but a 20% Handset Decline Creates Transition Pressure
Arm FY2027 Q1 Deep Dive: Data Center Royalties More Than Double, AGI CPU Demand Exceeds $2 Billion