
Korea Deep Dive: After the Peak in Panic, Can the KOSPI Move from a Memory Rally to a Market Re-rating?
目录
Too Long; Didn’t Read
I. The Main Question for Korea Has Changed: From a Memory Rebound to Whether the Market Can Recognize Earnings Diffusion
II. Earnings: Memory Is the Engine, but Upgrades in 15 Sectors Are the Reason for a Second Leg
III. Valuation: Single-Digit P/E Is Not a Get-Out-of-Jail-Free Card, but It Gives Reform Time to Deliver
IV. Positioning: USD 58 Billion of Foreign Outflows Is Pressure, but May Also Be Fuel for the Next Phase
V. Reform: Korea’s Discount Repair Must Move From Slogans to Cash Flow
VI. Technology Theme: 2027 DRAM Demand +36%, Pushing Memory from Cyclical Equity Toward Cash-Flow Asset
VII. Non-Tech Diffusion: Power Equipment, Defense, Shipbuilding, and K-Beauty Are Korea’s Downside Resilience
VIII. Macro: Korea Is Not Risk-Free; the Risks Are Household Debt, the Won, Rates, and Energy
IX. Four Tracking Variables: How the Next Leg Can Be Falsified
X. Three Scenarios: 9,200 Is Not a Point Forecast, but the Combined Result of Earnings, Flows, and Reform
XI. Sector Ranking: From “Who Has Risen the Most” to “Who Can Retain Profits”
XII. From Earnings Season to Policy Implementation: A Four-Quarter Validation Roadmap
XIII. Risk Layering: Which Signals Would Truly Change the Korea View
XIV. Cross-Market Comparison: How Korea Differs from Taiwan and Japan
XV. Conclusion: Korea Is Not Free of Bubble Risk; the Key Is That There Is Still a Fundamental Broadening Window Before the Bubble
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Korea’s equity market has moved beyond a simple bet on rising memory prices and into a harder phase: earnings upgrades need to spread from Samsung Electronics and SK Hynix to non-tech sectors; foreign underweighting needs to shift from pressure into replenishment fuel; and governance reform needs to move from a valuation story into a cash-flow constraint. Whether the KOSPI can hold 9,200 depends on whether these four lines can all materialize at the same time.
Too Long; Didn’t Read
The next leg in Korea depends on earnings breadth. UBS raised its KOSPI target to 9,200 not simply because the index has risen quickly, but because 2026/2027/2028 EPS growth assumptions have been revised up to +258%/+46%/+9%. Memory remains the engine, but earnings upgrades have already appeared in 15 of 24 subsectors. Whether the rally can move to the next level depends on whether non-tech sectors can absorb the valuation pressure created by tech’s excessive index weight.
Foreign underweighting leaves room for replenishment. Foreign investors have sold roughly US$58 billion net in Korea year to date, and Korea’s active weight in emerging-market funds has shifted from overweight to underweight. On the surface, this looks like the worst possible positioning backdrop. The real question is not “whether foreigners have already sold,” but whether EM flows return, pressure from single-tech-stock position limits eases, and foreign investors rotate beyond Samsung Electronics and SK Hynix into holding companies, shipbuilding, power equipment, defense, consumer, and K-beauty.
Cheap valuation must be validated by reform. Even after a sharp rally, the KOSPI still trades at roughly a single-digit forward 12-month P/E, and valuation excluding Samsung Electronics and SK Hynix has not reached an uncontrolled zone. For the Korea discount to close, amendments to the Commercial Act, mandatory treasury-share cancellation, low-PBR value-up measures, dividends, and treasury-share retirements must genuinely transfer corporate cash flow to shareholders, especially for holding companies still trading at 30-40% NAV discounts.
Memory remains the first gate for the income statement. 2027 DRAM bit demand growth has been pushed to +36.1%, while HBM bit demand is expected to reach 58.7bn Gb. AI inference and agentic AI are spreading demand from HBM to DDR5, LPDDR5, NAND, and enterprise SSDs. The divergence between Samsung Electronics and SK Hynix is no longer just about who leads in HBM share, but whether Samsung’s full-category recovery can offset SK Hynix’s HBM purity advantage.
Non-tech diffusion determines the index’s downside resilience. Power equipment, nuclear power, defense, shipbuilding, and K-beauty are the second layer of earnings that Korea’s current rally most needs to validate. They may not contribute the largest index weight, but they can prove Korea has more than one path beyond “memory prices going up.” If orders, gross margins, and cash returns in these sectors improve together, the KOSPI’s valuation discount can be repriced.
The biggest risk is not expensiveness, but single-point failure. The real fragility in Korea lies in the excessive concentration of AI earnings, single-stock leveraged ETFs amplifying volatility, household risk appetite being constrained by debt and housing prices, and pressure from macro rates and energy prices on cyclical-sector profits. The four variables to track from here are memory prices, foreign replenishment, governance reform delivery, and non-tech order margins.
I. The Main Question for Korea Has Changed: From a Memory Rebound to Whether the Market Can Recognize Earnings Diffusion
The previous leg of Korea’s equity rally rested on a very hard fact: AI pushed memory back to the center of global asset pricing. Earnings revisions for Samsung Electronics and SK Hynix were large enough, and their index weights high enough, that the index was naturally pulled up first by tech stocks. But the question behind a 9,200 target is no longer “whether memory can keep rising,” but “whether Korea can move from a memory-cycle trade into a broader earnings-recovery market.”
This is also the most important part of this strategy report. UBS does not simply frame Korea as a memory beta. Instead, it breaks the rally into four layers: first, EPS continues to be revised up; second, foreign underweighting leaves potential replenishment; third, Commercial Act reform, treasury shares, and low-PBR reform compress the Korea discount; fourth, non-tech sectors begin to provide new earnings evidence. No single layer is sufficient on its own. Taken together, the four layers explain why the target can still be raised after the index has already risen substantially.
The Korean market now looks most like a car changing engines. The old engine is exports and the memory cycle. The new engine is AI memory, corporate governance, household asset allocation shifting toward equities, and orders and margins in non-tech sectors such as defense, power equipment, shipbuilding, and K-beauty. The issue is that the old engine is still roaring, the new one is also igniting, and volatility on the dashboard is rising.
This means writing about Korea cannot focus only on the KOSPI level. The index level easily pulls investors into the instinct that “a big rally means danger,” but Korea’s core variables are actually whether numerator-side earnings continue to be revised up and whether denominator-side discounts are reduced by institutional reform. As long as earnings continue to broaden and foreign investors move from underweight back toward neutral, the Korea discount still has room to compress. If earnings revert to a single memory line, foreign replenishment does not happen, and reform remains only rhetoric, volatility at elevated index levels will become very sharp.
Korean Equity Re-rating: Tech Earnings, Foreign Inflows, and MSCI Reform Validation After the KOSPI Breaks 9,000
The earlier article already laid out the three conditions after the KOSPI broke 9,000: tech earnings, foreign inflows, and index-system reform. UBS has now advanced the same line by one step: earnings upgrades have already spread from tech to more sectors; foreign flows have moved from outflow pressure to an underweight state; and governance reform has started to move from a macro narrative to constraints on corporate cash flow. The challenge for the next leg is that these variables must materialize simultaneously.
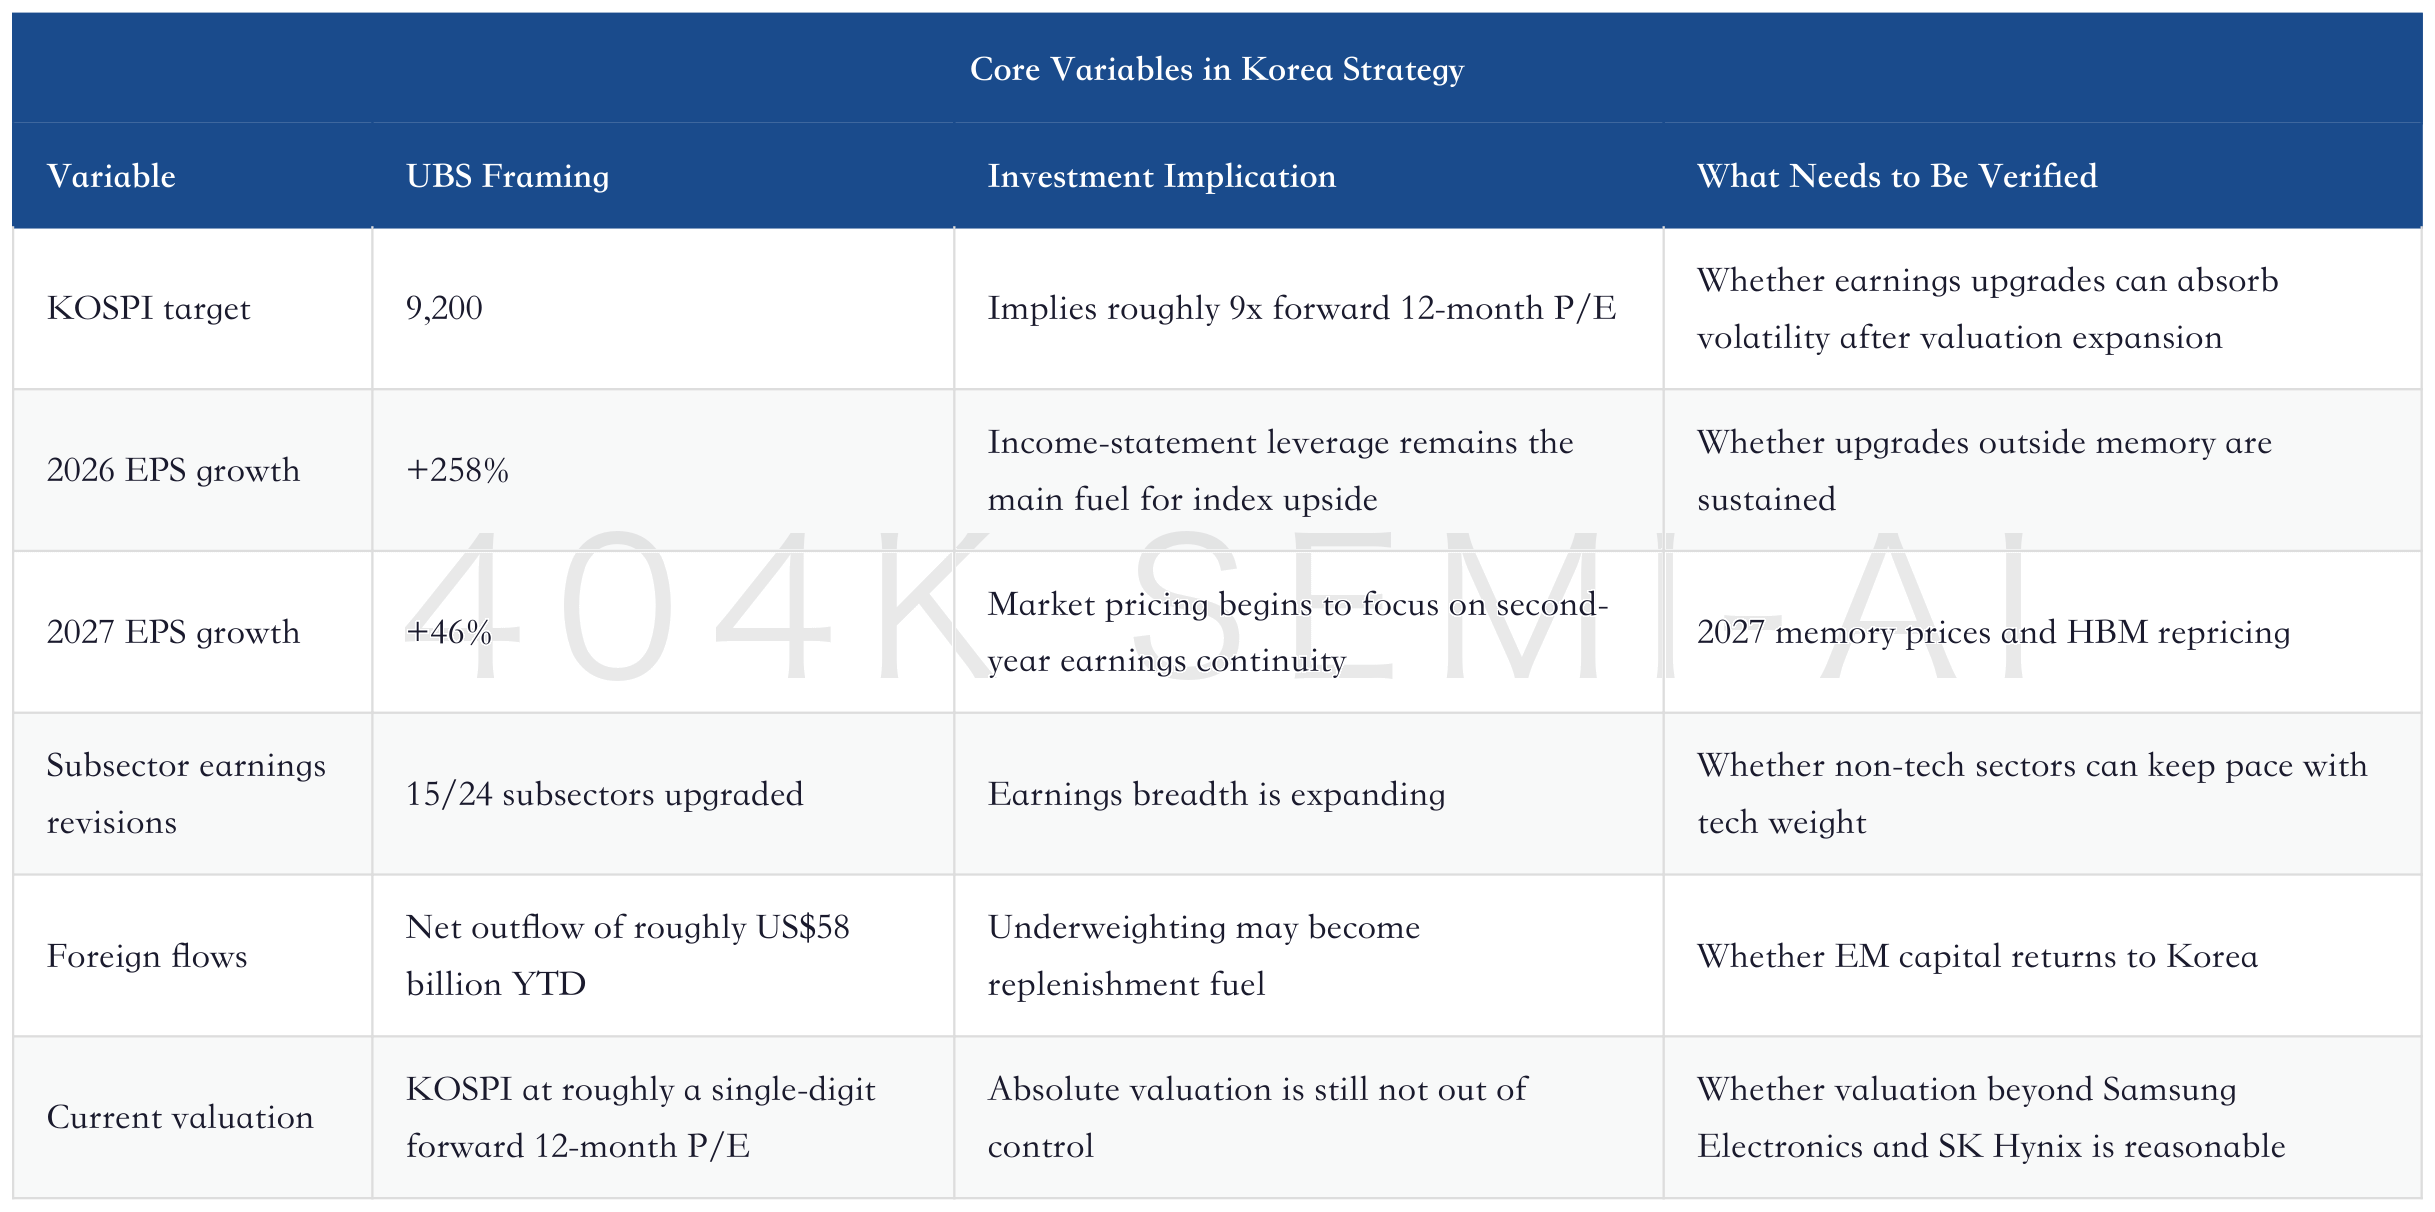
The key point in this table is not any single number, but the transmission sequence between variables. Memory prices and AI demand first drive EPS, then EPS diffusion brings upgrades in more sectors, then foreign underweighting forces investors to reassess Korea, and governance reform then compresses the long-term discount. As long as this chain remains intact, index pullbacks look more like volatility during earnings validation. If any link breaks, especially if memory prices and foreign replenishment both turn in the wrong direction, the KOSPI will quickly switch from an earnings re-rating back to a momentum trade.
II. Earnings: Memory Is the Engine, but Upgrades in 15 Sectors Are the Reason for a Second Leg
The first card in Korea’s current rally is memory. UBS’s 2026 EPS growth estimate is in triple-digit territory, with the source highly concentrated in Samsung Electronics, SK Hynix, and the related supply chain. The tech sector accounts for roughly 60% of market cap, and Samsung Electronics plus SK Hynix together contribute more than half of the index weight. Any strategy framework has to address these two names.
But the second card is what truly matters: earnings revisions have begun to spread. The report notes that since March 2026, 15 of Korea’s 24 subsectors have seen earnings upgrades, covering roughly 83% of market cap, with about 29% coming from non-tech sectors. This sentence matters more than the KOSPI target itself, because for Korea to move from an “AI memory trade” to a “national equity-asset re-rating,” it must first prove that profits are not sitting only with two memory giants.
Earnings diffusion changes the valuation structure the market is willing to assign to Korea. No matter how strong a single memory cycle is, it can easily be labeled high beta, highly cyclical, and reliant on unsustainable peak earnings. If holding companies, power equipment, defense, shipbuilding, consumer, and K-beauty can also sustain upgrades, Korea’s index will no longer be just an amplifier of memory prices. It will become a market with improving earnings breadth.
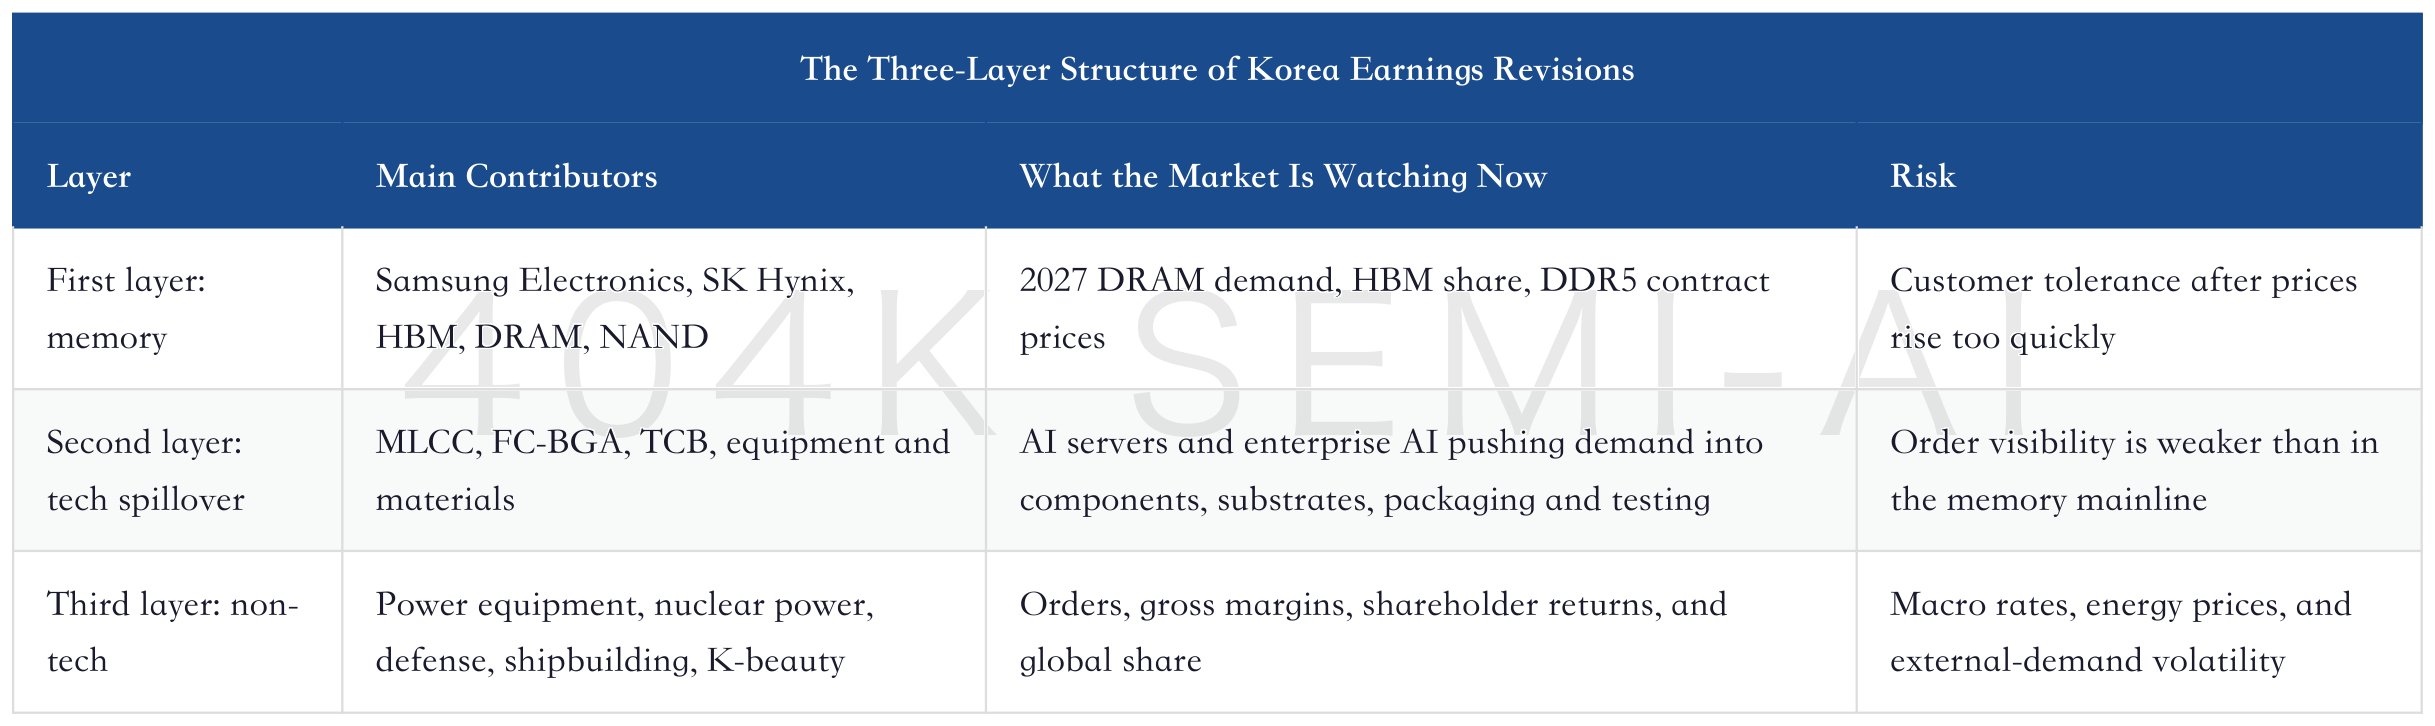
Korea’s advantage is that all three layers have evidence. Memory has prices and bit demand; tech spillover has export data and MLCC, substrate, and equipment imports; non-tech has defense orders, transformer exports, nuclear and shipbuilding orders, and overseas revenue from independent beauty brands. Korea’s pressure is also here: the market has already priced in enough of the memory story, so the second and third layers must now prove this is not an index supported only by two heavyweight stocks.
Korea Export Deep Dive: June Exports Up 70.9% YoY, and How the AI Hardware Surplus Opens Room for KOSPI Re-rating
Export data explains why Korea’s EPS upgrades are not purely an accounting-model exercise. Behind June’s high export growth, memory, MLCC, the equipment chain, and the AI hardware surplus are all improving. Profits are moving from “prices rising” toward a multi-factor resonance across export value, capacity utilization, the inventory cycle, and gross margins. For Korea, exports are not a macro backdrop; they are the entry point to the income statement.
This also explains why UBS does not frame the rally only as Samsung Electronics and SK Hynix. Samsung Electronics and SK Hynix are the first layer of profit, but for Korean equities to remain resilient, more sectors must prove they are not merely “rising with the index.” Power equipment needs to deliver orders from the United States and the Middle East; defense needs to show new contracts for 2026 and 2027; shipbuilding needs to prove that margins from LNG carriers and defense orders can persist; and K-beauty needs to prove that overseas independent brands are not a one-off traffic dividend.
III. Valuation: Single-Digit P/E Is Not a Get-Out-of-Jail-Free Card, but It Gives Reform Time to Deliver
Korean market valuations are easy to misread. A large index rally sounds like valuations must be expensive. But UBS’s framework is that the KOSPI is still trading around a single-digit forward 12-month P/E, and even excluding Samsung Electronics and SK Hynix, market valuation has only returned to a relatively reasonable range. The key point is not “cheap, therefore it must rise,” but rather “cheapness gives reform and earnings broadening time to be validated.”
There are two ways to explain Korea’s cheap valuation. One is constructive: the market has long undervalued corporate governance, shareholder returns, and global technology competitiveness; reform compresses the discount, earnings upgrades lift the numerator, and valuation naturally recovers. The other is negative: memory profits are at a peak, household debt and macro volatility weigh on risk appetite, and shareholder-return improvement is not fast enough, so cheapness is a justified discount. The next phase of the market is essentially a contest between these two explanations.
Valuation cannot be separated from index structure. Samsung Electronics and SK Hynix account for too much market cap, technology has too large a weight, and the KOSPI’s aggregate P/E is heavily affected by the memory profit cycle. When memory profits are revised up, the index P/E can look cheap; when memory profits are revised down, the same index level can suddenly look more expensive. Korea valuation analysis therefore needs two steps: first, assess whether memory profits are real; second, assess whether the ex-memory market can also recover through reform and non-tech profit improvement.
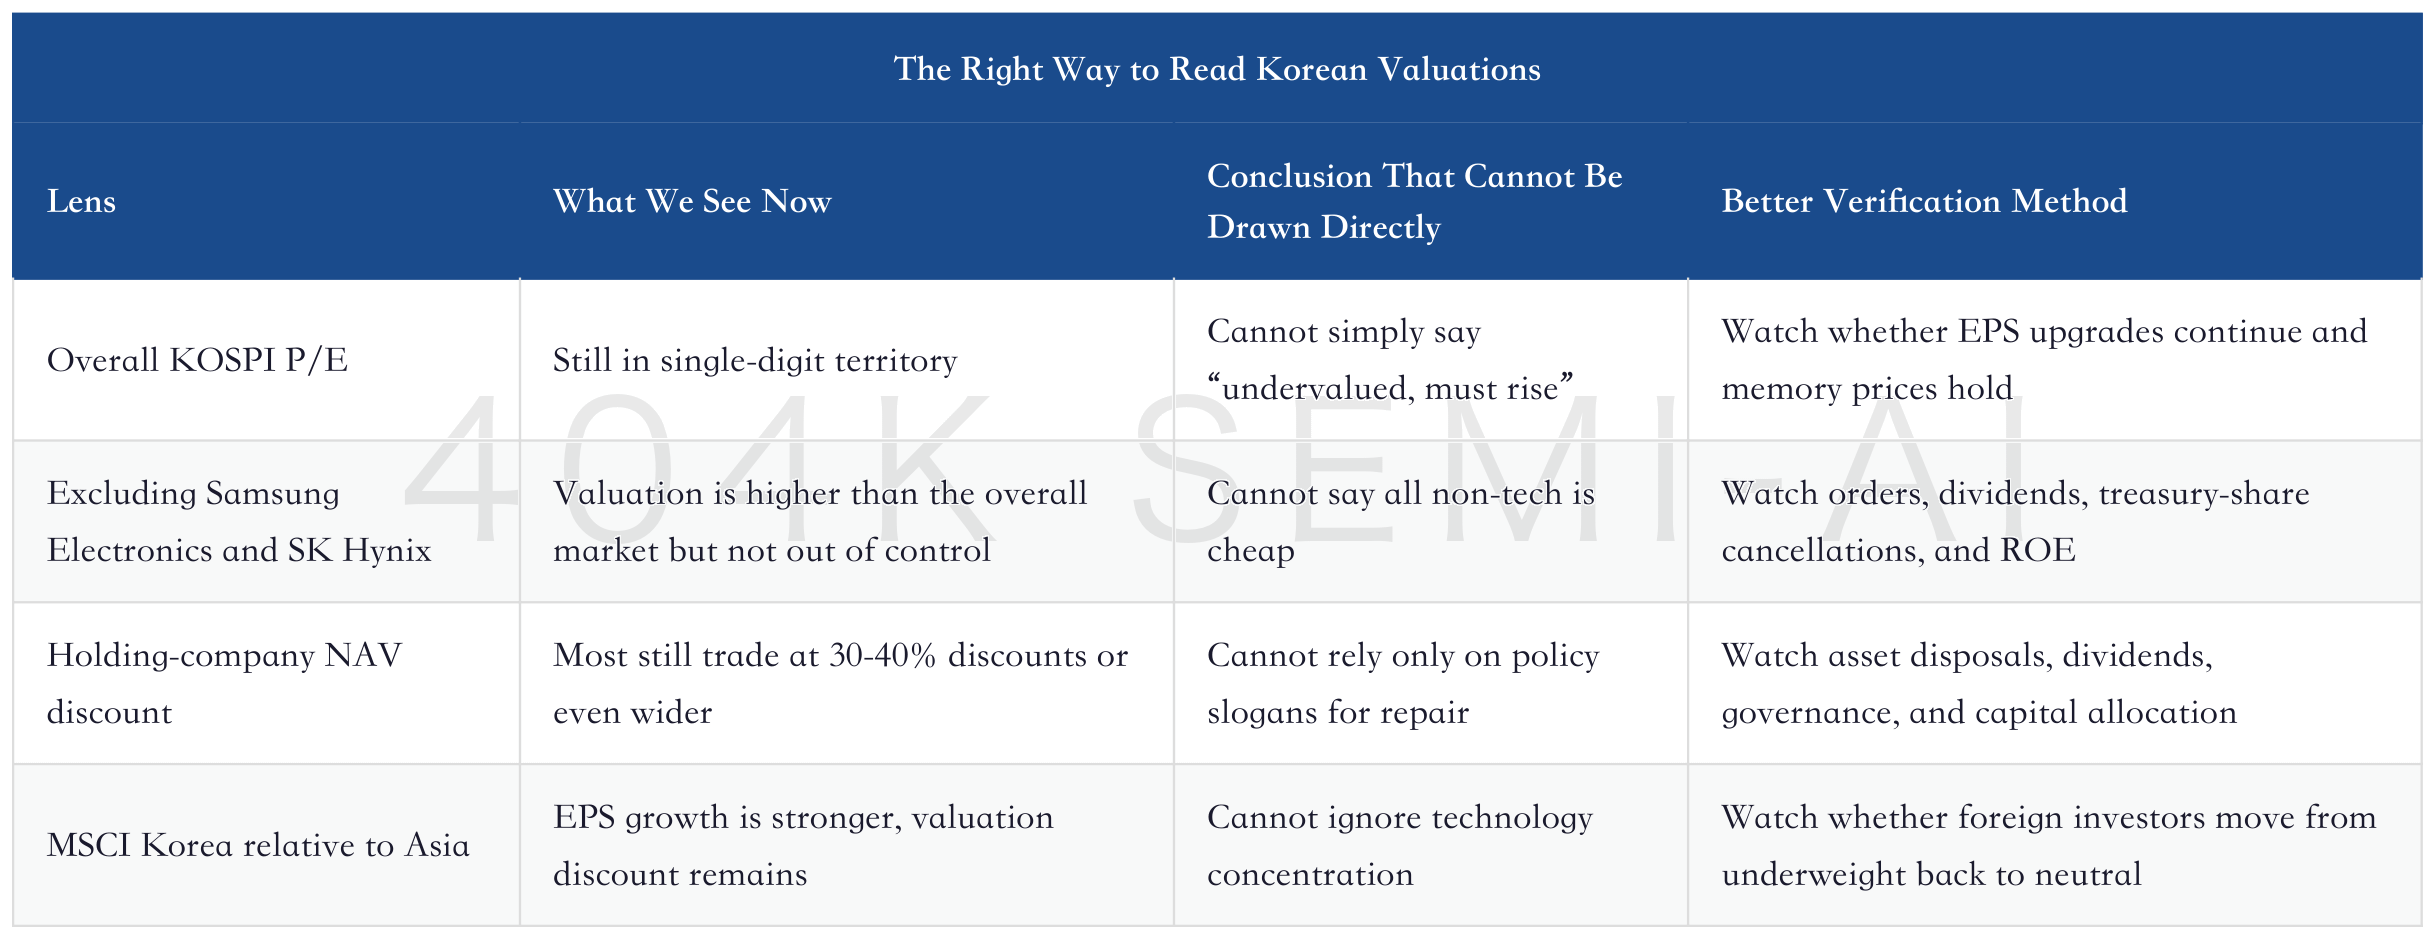
The most elastic part of Korean valuation may not be the technology leaders, but holding companies and traditional industries. Holding-company NAV discounts have existed for a long time. The market has grown used to discounting them for complex ownership, low returns, and weak governance. If Commercial Act amendments, low-PBR policies, treasury-share cancellations, and stronger shareholder litigation rights genuinely change corporate behavior, discount narrowing would not be a simple thematic trade, but a balance-sheet revaluation.
A common misconception should be avoided here: Korean reform is not a one-click valuation uplift for all low-PBR companies. The companies that can truly benefit either have real cash flow to raise dividends and cancel treasury shares, asset structures that can release value, or improving industry cycles. Low-valuation companies with no cash flow, no governance action, and no order or margin improvement will only perform briefly during policy-driven sentiment and are unlikely to become stable contributors to the next leg of the index.
IV. Positioning: USD 58 Billion of Foreign Outflows Is Pressure, but May Also Be Fuel for the Next Phase
Foreign capital is the most contrasting variable in this Korean market cycle. Foreign investors have posted roughly USD 58 billion of net outflows year to date. Korea’s active weight in emerging-market funds has shifted from overweight to underweight, with technology stocks the main source of outflows. Intuitively, this sounds very negative. But strategically, the better question is different: if foreign investors are already underweight, is the marginal pressure from continued large outflows declining?
The answer depends on two things. First, whether EM money itself returns. Korea is not an isolated market. If global emerging-market funds continue to see outflows, Korea’s underweight may not be reversed immediately. If EM flows return, Korea’s combination of earnings upgrades and valuation discount will be hard to ignore. Second, whether foreign investors can shift from a single crowded technology trade to a broader Korean asset allocation. As long as foreign investors still understand Korea as a levered expression of Samsung Electronics and SK Hynix, the room for position rebuilding will be constrained by single-stock exposure limits. If they begin to recognize the profit lines in electrical equipment, defense, shipbuilding, holding companies, and K-beauty, the positioning recovery will be broader.
The most valuable aspect of foreign underweight is that it turns “bad news” into known information. If the market were in a state of foreign overweight, high valuation, and concentrated earnings, any disruption in memory prices would become a large drawdown. The current state is different: foreign investors have already sold, pockets of valuation are not high, and earnings are still being revised up. This turns negative positioning itself into potential fuel. Whether that fuel can ignite depends on whether subsequent fund flows and earnings broadening appear together.
Korea Market Deep-Dive Update: KOSPI’s 4% Pullback, 6.65x Forward P/E, and AI Hardware Repricing After Foreign Outflows
The previous Korea pullback already demonstrated this logic: foreign outflows amplify volatility, but when low valuation and AI hardware profits do not deteriorate at the same time, the market quickly shifts into repricing. Foreign underweight is now deeper, which means each subsequent EM inflow and each non-tech earnings upgrade may become a trigger for position rebuilding.
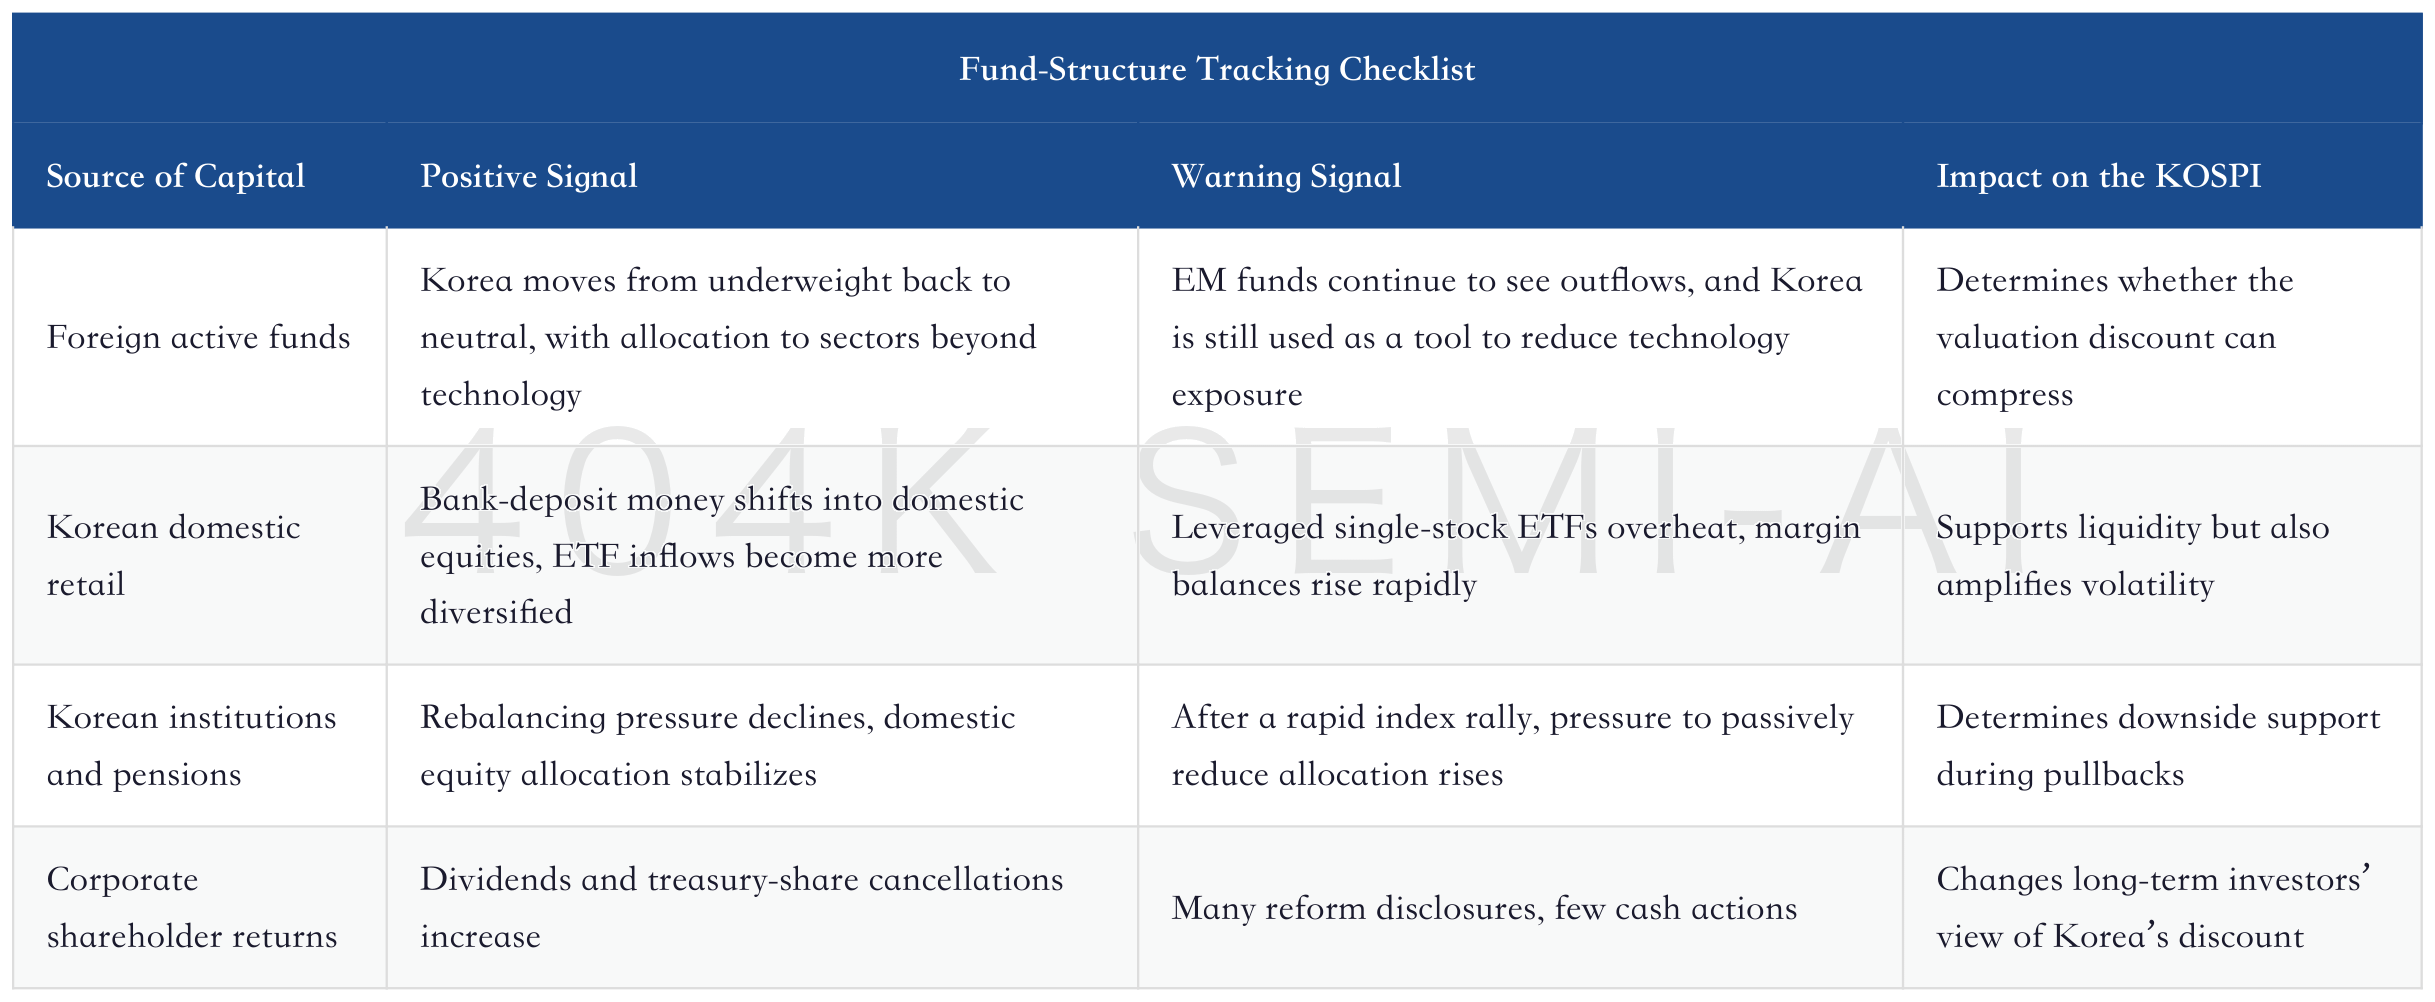
Domestic Korean capital also cannot be ignored. Retail investors’ willingness to allocate to domestic equities has clearly increased, driven by lower bank deposit rates, tighter real-estate transaction and debt constraints, and the wealth effect after the domestic equity rally. Adjustments to the rebalancing rules of Korea’s National Pension Service have also eased concerns about mechanical selling pressure. Retail and institutional investors cannot fully replace foreign capital, but they can provide a buffer during periods of foreign underweight, preventing the index from being driven only by overseas flows.
The risks in positioning are equally clear: single-stock leveraged ETFs and margin trading will amplify volatility. The more the Korean market depends on a small number of index heavyweights, the more leveraged products can sharpen both upside and downside moves. If foreign investors rebuild positions, that is medium-term support; if leveraged money becomes crowded, that is a near-term vulnerability. Korea should not be assessed only by net inflows; the structure of funds also matters.
V. Reform: Korea’s Discount Repair Must Move From Slogans to Cash Flow
Korea’s discount was not formed overnight, and it will not disappear overnight because of one policy. Behind the long-standing discount are issues such as complex ownership structures, low dividends, opaque use of treasury shares, weak minority-shareholder rights, and large holding-company NAV discounts. In the past, the market’s low valuation for Korea was, to some extent, the pricing of these problems.
The change is that reform is moving from “encouraging value enhancement” to “constraining corporate behavior.” Commercial Act amendments extend directors’ duty of loyalty to shareholders, strengthen mechanisms such as independent directors, electronic shareholder meetings, cumulative voting, and independent elections for audit committees; treasury-share cancellation is moving from advocacy to stronger constraint; low-PBR companies are being required to submit value-enhancement plans; and M&A;, spin-off listings, mandatory tender offers, and sharing of control premiums have also entered the policy agenda. If institutional variables continue to advance, Korea’s discount will have an observable path to compression.
The most direct beneficiaries of reform are holding companies. Holding companies typically have assets, cash flow, subsidiary stakes, and complex discounts. The market has long used NAV discounts of 30-40% or even wider to reflect governance problems. As long as reform imposes discipline on treasury shares, dividends, asset disposals, minority-shareholder interests, and M&A; pricing, holding companies may shift from “low-valuation traps” to “discount-compression instruments.”
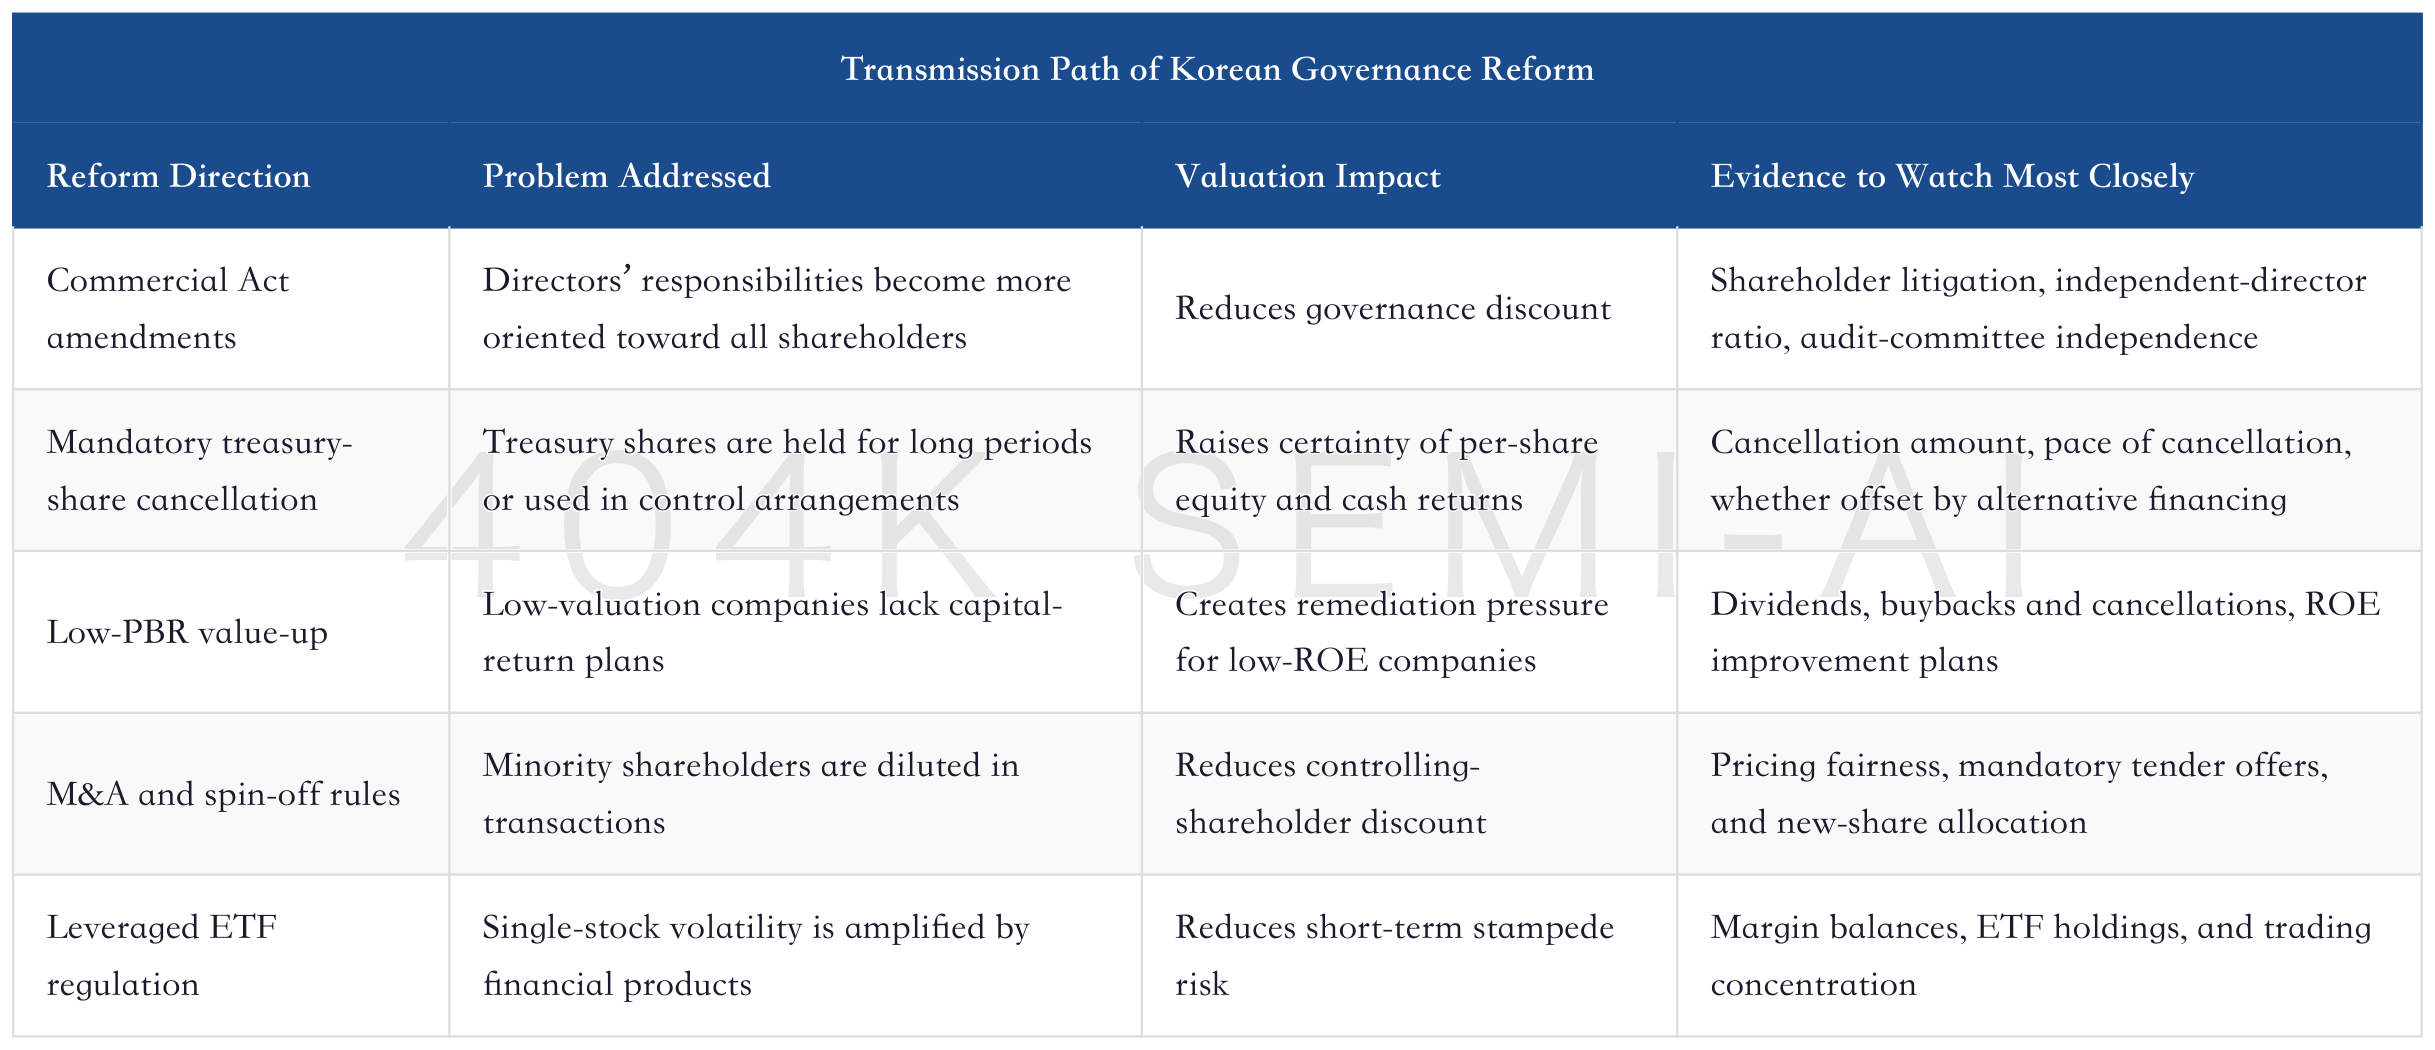
Reform also has disconfirming conditions. First, if companies only disclose value-up plans but take no real action on dividends, cancellations, or asset disposals, the market will quickly recognize them as slogans. Second, if stronger minority-shareholder protection does not improve capital-allocation efficiency, valuation repair will stop at the thematic level. Third, if reform only applies to a handful of star companies, while many low-PBR companies lack cash-flow and ROE improvement, Korea’s overall discount will still struggle to disappear systematically.
The significance of institutional reform for Korea should not be understood simply as “policy stimulus.” It is more like an update to asset-pricing rules: in the past, the market assumed controlling shareholders came first, minority shareholders deserved a discount, and cash flow stayed inside companies; now the market is starting to demand proof that cash flow will return to shareholders in a more transparent way. Whether the valuation discount can compress ultimately depends on corporate behavior, not policy headlines.
J.P. Morgan Sees KOSPI at 15,000: Is This Korean Rally an AI Bubble or a Revaluation of National Wealth?
The most important question in that earlier piece remains valid: is Korea’s rally an AI bubble, or a revaluation of national equity assets? The answer is now somewhat clearer. AI memory accelerates the income statement; reform reduces the discount on equity assets. Both are indispensable. AI without reform leaves valuation capped by a cyclical discount; reform without earnings lacks numerator support for discount repair.
VI. Technology Theme: 2027 DRAM Demand +36%, Pushing Memory from Cyclical Equity Toward Cash-Flow Asset
Memory remains Korea’s strongest profit theme. UBS’s memory data is very direct: 2027 DRAM bit demand growth is expected to reach +36.1%, above +21.1% in 2026; HBM bit demand is expected to rise from 33.1bn Gb in 2026 to 58.7bn Gb in 2027; AI demand is no longer constrained only at HBM, but is spreading into DDR5, LPDDR5, NAND, and enterprise SSDs.
This is the core of the debate over whether memory is at a cyclical peak. If the driver is merely traditional inventory restocking in PCs, smartphones, and servers, the market will treat memory earnings as cyclical. If agentic AI, KV cache, inference memory, enterprise SSDs, and HBM are all changing the demand curve at the same time, the market needs to re-estimate which profits can be capitalized. Cyclical profits deserve low multiples; structural profits can command higher multiples.
UBS’s preference between Samsung Electronics and SK Hynix is also interesting. SK Hynix has higher HBM purity, and the market already fully understands it as an AI bandwidth monetization point. Samsung Electronics has a more complex story: HBM catch-up, DRAM, NAND, smartphones, foundry, and a group-governance discount. If the market only chases pure HBM beta, SK Hynix is cleaner; if it starts to believe memory demand is spreading from HBM to all categories, Samsung Electronics’ breadth asset should have more elasticity.
SK Hynix Deep-Dive Update: Is It Still Expensive? DDR5 Takes Over Price Hikes, Korean Exports Surge, and Samsung Catch-Up Risk
The core question for SK Hynix is not “is it a good company,” but how much pricing the market has already assigned to its HBM purity. As long as DDR5, HBM, and export data continue to provide support, SK Hynix remains the high-purity expression of Korea’s earnings elasticity; once Samsung qualification, price repricing, or customer diversification changes, its valuation crowding will also be repeatedly scrutinized.
Samsung Electronics Deep-Dive Update: DRAM/NAND/HBM Three-Line Repair, Samsung Electronics Moves from Cyclical Rebound to Asset Re-Rating
Samsung Electronics’ significance lies in “breadth.” As AI demand continues to spread from HBM into DDR5, LPDDR5, NAND, eSSD, and device materials, Samsung Electronics’ full-category capability becomes more important. Its disadvantage is that HBM catch-up still needs to be validated; its advantage is that if prices improve across all memory categories, the market may no longer price it solely as a “lagging HBM supplier.”
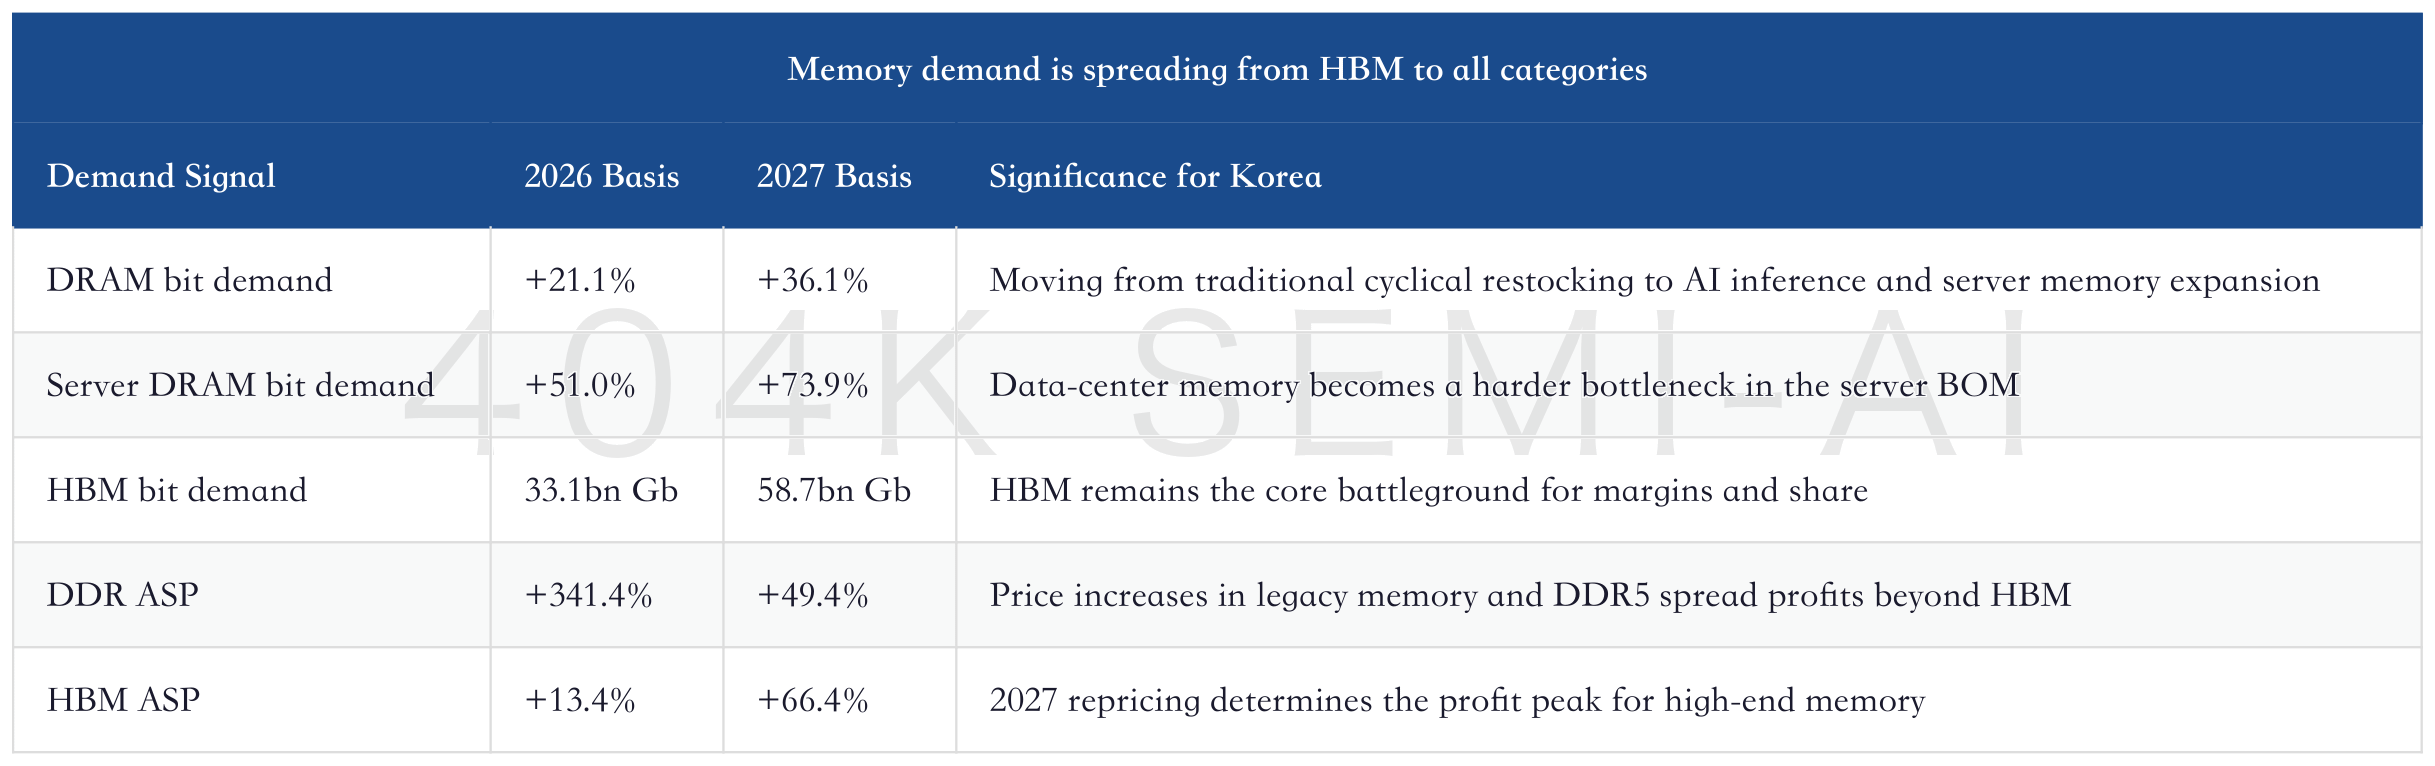
This table shows that the memory debate cannot focus only on HBM. HBM is the highest-margin and highest-attention segment, but demand growth in DDR and server DRAM, NAND’s support for KV cache and storage hierarchy, and enterprise SSD capacity expansion will all affect Samsung Electronics’ and SK Hynix’s total profits. What the Korean market really needs to price is the entire AI data stack, not a single memory product.
Memory Deep-Dive Update: 3Q26 DDR Prices +32%, 2027 DRAM Demand +36%, UBS Monthly Report Calibrates the Memory Supercycle
This memory monthly report already laid out the logic for 2027 DRAM demand at +36%: AI is not merely buying a bit more HBM; it is simultaneously changing supply-demand structure across servers, inference, cache, storage hierarchy, and long-term customer agreements. Korea strategy cites the same set of directional data, showing that memory remains the most fundamental anchor for KOSPI earnings revisions.
The risks to the memory theme also need to be taken seriously. Prices rising too quickly will hurt customer affordability; if HBM capacity expansion is too aggressive, it may create supply pressure after 2027; share redistribution among Samsung, SK Hynix, and Micron will change single-stock earnings elasticity; if hyperscale cloud companies start to constrain AI CapEx returns, memory valuation multiples will be compressed first. For the Korean equity market to keep strengthening, it needs more than memory price hikes; it needs high-quality price increases, durable orders, and customers willing to lock in volume.
VII. Non-Tech Diffusion: Power Equipment, Defense, Shipbuilding, and K-Beauty Are Korea’s Downside Resilience
Non-tech diffusion is the part of this strategy report that is easiest to overlook, but it may matter most for the quality of the rally. A high technology weighting can make the index rise quickly, but it can also make the index fragile. Only when non-tech industries deliver earnings evidence can Korea escape the label of “memory-cycle beta.”
Power equipment is the first non-tech line. AI data centers are pushing up US and global power demand, high-voltage transformer supply is tight, and Korean companies have a place in exports and orders. For the Korean equity market, the significance of transformers and power equipment is not just price increases in one industry, but evidence that AI capital expenditure is spreading from GPUs and HBM into grids and power infrastructure.
Nuclear power and gas turbines are the second line. Korea’s engineering capability, nuclear projects, SMRs, and gas-turbine orders extend power demand from “tight equipment supply” to “long-term power-source construction.” If AI data-center electricity pressure continues to rise, Korea’s power equipment and nuclear chain will become the most direct AI infrastructure assets outside memory.
Defense is the third line. The potential Korean defense orders listed by UBS cover artillery, air defense, armored vehicles, missiles, and military aircraft, across Europe, the Middle East, and multiple Asian markets. The investment logic for defense is not short-term order accumulation, but whether Korea can continue winning orders and converting them into margins through delivery speed, cost-performance, and capacity stability after global security spending rises.
Shipbuilding is the fourth line. The key for Korean shipbuilding is high-value-added vessels, LNG carriers, offshore engineering, and defense orders. As long as newbuild prices, order coverage, delivery cadence, and margins continue to improve, shipbuilding can provide a different cyclical source from memory. Its similarity with memory is concentrated global supply capability; its difference is a longer delivery cycle and higher order visibility.
K-beauty is the fifth line. Independent brands and consumer companies such as APR and d'Alba represent Korean consumer goods moving from domestic brands to overseas channels and social-media traffic. Their contribution to index weight is smaller than technology, but they can prove that the Korean market is not only hard tech and heavy assets. A market that can simultaneously produce profit lines in memory, power equipment, defense, shipbuilding, and consumer brands deserves to be viewed as an earnings-diffusion market.
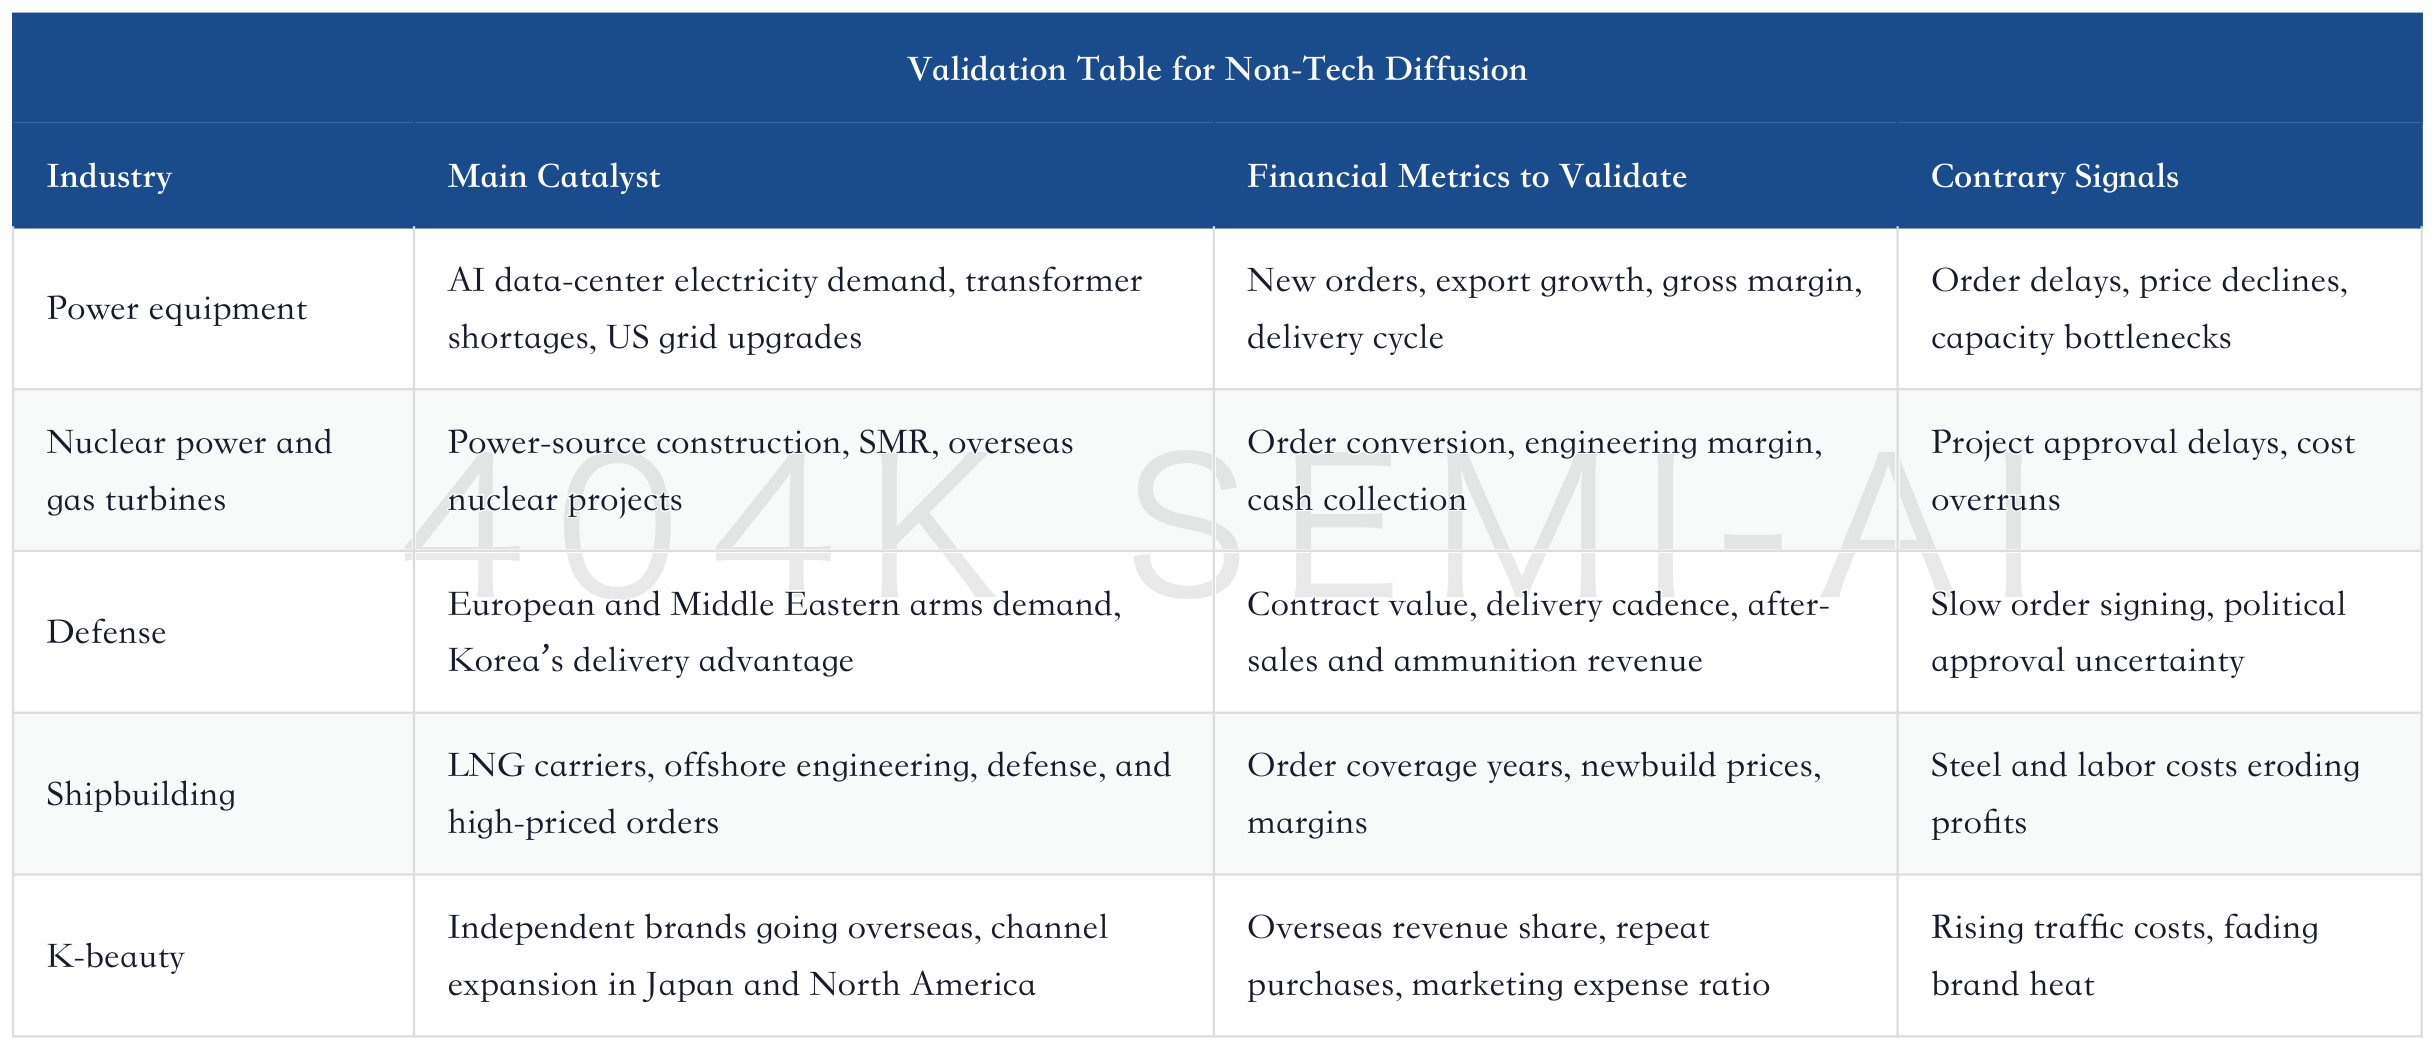
The common point across these lines is that they all explain why Korea is not a single-theme technology market. Their risks are also different: power equipment fears capacity and delivery, defense fears order cadence, shipbuilding fears costs, and K-beauty fears brand lifecycle. If the market is only willing to price technology weights, Korea will remain highly volatile; if these lines simultaneously deliver earnings evidence, the index will have more fundamental support during drawdowns.
VIII. Macro: Korea Is Not Risk-Free; the Risks Are Household Debt, the Won, Rates, and Energy
Korea’s macro backdrop is not a one-way positive. Consumer confidence, industrial production, exports, and retail data are all improving, but household debt remains high; real estate transactions and lending behavior affect household asset allocation; the won and energy prices affect corporate costs; and rates affect the discount rate for risk assets. The strength of Korea’s equity market should not be interpreted as an absence of macro pressure. Rather, earnings upgrades have temporarily outweighed those pressures.
Household asset allocation is a long-term variable. Korean households have historically relied heavily on real estate, with relatively low allocation to equities. If real estate remains constrained by debt and policy while bank deposit rates fall, there is a basis for household capital to migrate toward the domestic equity market. But this line of reasoning cuts both ways: healthy long-term allocation can support the market, while rapid leverage and concentration in single-stock ETFs can amplify drawdowns.
The won and interest rates are another variable. Korean exporters benefit from global demand, but won volatility affects foreign investors’ risk appetite and corporate costs. If inflation reaccelerates, rate expectations will pressure valuations. If energy prices rise, margins in shipbuilding, chemicals, industrials, and consumption may all be squeezed. Korea is not a market driven only by AI; it remains highly exposed to the global cycle.
The macro risk to watch most closely is whether “earnings upgrades are being consumed by costs.” If exports, orders, and pricing are strong, but wages, energy, FX, and rates eat into margins, EPS upgrades will thin out. If the cost side remains benign while revenue continues to be revised up, the market will reprice Korea from a cyclical market into one with improving earnings quality.
IX. Four Tracking Variables: How the Next Leg Can Be Falsified
This round of Korea’s rally can continue to be studied through a positive case, but it must also be prepared for falsification. A good deep-dive report cannot only discuss tailwinds; it must also explain when the main thesis should be acknowledged as wrong. For the KOSPI, the four most important variables are memory pricing, foreign investor covering, governance reform, and non-tech order margins.
First, memory pricing and bit demand are the foundation of the income statement. As long as 2027 DRAM demand, HBM repricing, DDR5 contract prices, and NAND/enterprise SSD demand continue to be revised up, Samsung Electronics and SK Hynix have support for earnings elasticity. Contradictory signals would include customers delaying procurement after prices rise too quickly, excessive HBM capacity expansion, or hyperscalers explicitly compressing returns on AI CapEx.
Second, can foreign underweights be covered? Foreign investors have already seen substantial net outflows, and active Korea weights have shifted to underweight. The most powerful subsequent rallies often come from covering underweights rather than from a new narrative. Contradictory signals would include continued EM outflows, Korea being persistently used as a vehicle to reduce technology exposure, or foreign investors only covering Samsung Electronics and SK Hynix without accepting the spread of earnings into non-tech sectors.
Third, can reform turn into cash actions? The Commercial Act, treasury-share cancellations, low PBR, mandatory tender offers, and spin-off rules all matter, but the market ultimately recognizes only dividends, cancellations, ROE, asset disposals, and minority shareholder protection. Contradictory signals would include companies merely writing value-up plans without cash returns, no narrowing of holding-company discounts, and no real cancellation of treasury shares.
Fourth, can non-tech orders and margins be delivered? Power equipment, defense, shipbuilding, nuclear power, and K-beauty are key to Korea moving beyond a single technology line. Contradictory signals would include slow order signing, delayed delivery, rising costs, weakening gross margins, and slowing overseas growth for consumer brands. Once non-tech cannot take over, Korea will revert to a high-beta memory trade.
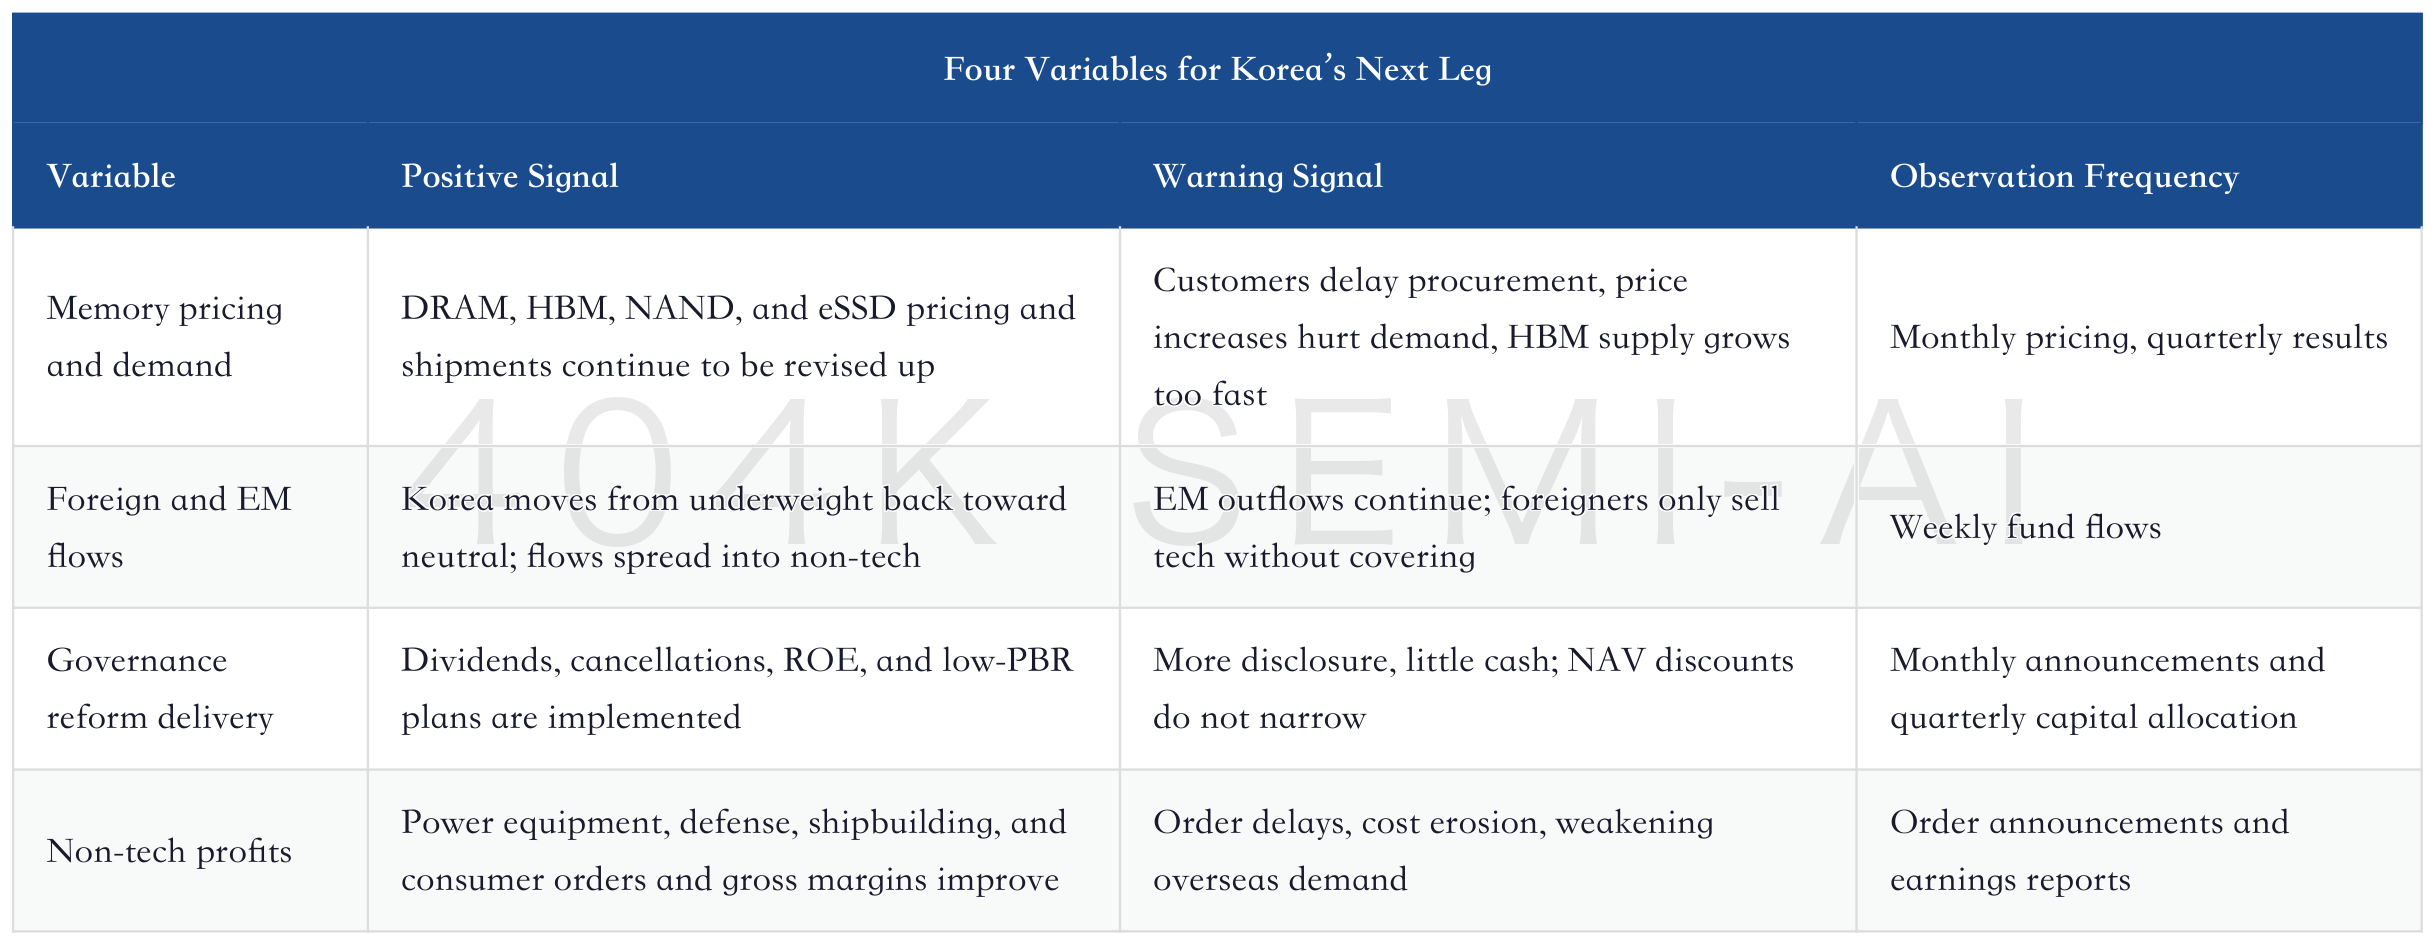
These four variables can pull the Korea debate back from sentiment into a verifiable framework. How much the index has risen is not the most important point. What matters is whether profits, capital flows, reforms, and orders keep up after each leg higher. If three of the four variables remain positive, pullbacks look more like healthy volatility. If two or more turn negative at the same time, investors should be alert to Korea retreating from earnings diffusion back into momentum trading.
X. Three Scenarios: 9,200 Is Not a Point Forecast, but the Combined Result of Earnings, Flows, and Reform
KOSPI 9,200 is easily read as a single target level, but a better approach is to break it into three scenarios. In the base case, memory prices continue to be revised up, non-tech sectors do not fall behind, foreign investors move from underweight toward a more neutral position, and reform delivery is moderate but directionally clear. In the diffusion case, earnings revisions beyond Samsung Electronics and SK Hynix accelerate meaningfully, holding-company discounts compress, and order margins improve simultaneously in defense, power equipment, shipbuilding, and K-beauty. In the pressure case, memory remains strong but flows and reform fail to keep up, leaving the index in a tug-of-war where “earnings are good, but valuations do not expand.”
These three scenarios are not abstract assumptions; they can be verified by data. The biggest advantage of Korea’s equity market is that there is an income statement to observe: DRAM contract prices, HBM share, NAND and eSSD demand, export value, order value, dividends, and treasury-share cancellations all flow into reported accounts. The biggest difficulty is that these data points do not necessarily appear at the same time. Memory prices may lead, while cash reform actions lag. Defense and shipbuilding orders may be signed first, while margins only show up at delivery. Foreign investors may first cover technology, and only gradually accept non-tech diffusion.
In the base case, Korea remains a market with a high technology weight, but the market begins to accept that “things are also improving outside technology.” The corresponding index state is upward movement amid high volatility: every upward revision to memory pricing and EPS pushes the index higher, while each foreign outflow or leveraged-ETF cooling episode brings a drawdown. But drawdowns no longer easily damage the medium-term framework. The base case most needs to see that 2027 EPS is not cut and that non-tech orders and gross margins do not deteriorate meaningfully.
The diffusion case requires more. It needs foreign investors to stop focusing only on Samsung Electronics and SK Hynix and instead treat Korea as a composite market of “AI supply chain + corporate governance + non-tech orders.” Under this scenario, low-PBR names, holding companies, power equipment, defense, and shipbuilding would carry more index elasticity. The market would shift from “Korea is a memory market” to “Korea is an Asian market where earnings repair and discount repair are appearing simultaneously.” The best evidence for this scenario is not a large one-day index gain, but more industries seeing EPS upgrades, more companies cancelling treasury shares, and more non-tech orders entering the income statement.
The pressure case must also be taken seriously. Korea’s vulnerabilities are that technology weight is too concentrated, the funding structure can easily amplify volatility, and excessive memory price increases can trigger customer reactions. If 2027 DRAM demand remains strong, but foreign investors stay underweight, reforms lack cash actions, and non-tech orders cannot convert into profits, the market will fall into a state where “earnings are strong but valuations are unwilling to expand.” At that point, KOSPI may still have structural bright spots, but the overall index will rely more heavily on Samsung Electronics and SK Hynix, and volatility will look more like a single-cycle trade.
