
Korea Assets Deep Dive: Why Is the Won So Weak, and Can KOSPI Hold 9,000?
目录
Too Long; Didn’t Read
I. Korea’s Current Contradiction: The Strongest Fundamentals, the Weakest Currency
II. Why the Won Is Weak: Capital Flows and FX-Conversion Timing Are Overpowering the Trade Surplus
3. Where the Korean Won Goes Next: Mild Appreciation, but with Setbacks Along the Way
4. Where Korea’s Fundamentals Are Strong: AI Exports, Growth Differentials, and a Central Bank Pivot
5. Why the KOSPI Can Rise to 9,000: But the Rally Path Must Shift Gears
6. Why Foreign Investors Are Selling: Overcrowded Positioning Is Overriding Fundamental Optimism
7. Retail Investors and Pension Funds: Can Domestic Korean Capital Keep Absorbing Supply?
8. The Impact of Won Appreciation on Equity Structure: Winners May Shift from Export Leaders to Domestic Demand and Financials
9. Four Variables to Watch Next
X. Key Risks: The Cost of This Bull Market Is Already Becoming Visible
XI. Conclusion: Korean Assets Are Not Done, but the Trade Has Become Harder
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The most important lens for Korean assets now is that the current-account surplus, corporate FX conversion, foreign investor de-risking, retail reallocation, Bank of Korea rate-hike expectations, and policy delivery are all being compressed into the same balance sheet. Behind the weak won is a mismatch in capital flows. Whether KOSPI can hold 9,000 also depends on whether this mismatch can cool down.
Too Long; Didn’t Read
Won weakness reflects capital-flow pressure. Korea’s exports, growth, and trade surplus were all strong in 1H26, yet the won remains among the weaker major Asian currencies outside Japan. The market is now mainly trading the financial account, corporate FX conversion, and changes in foreign investor positioning.
The real drag comes from three capital flows. Foreign investors have trimmed Korean equities after taking profits; companies are keeping dollar revenues offshore or in foreign-currency deposits; and Korean retail investors and institutions have continued buying overseas assets over the past few years. Together, these explain why the current-account surplus has not translated directly into won appreciation.
The won looks more like a modest repair trade. Corporate tax payments in August, repatriation of proceeds from U.S. listings by semiconductor companies, and higher domestic capex in Korea could all lift corporate FX-conversion demand. But foreign investors may still keep selling, and retail overseas investment is also recovering, so in the near term the won looks more like a repair from an extremely weak level than a one-way sharp appreciation trade.
KOSPI 9,000 needs breadth confirmation. Morgan Stanley’s base-case target is 9,000, with a bull-case scenario of 10,500 and a bear-case scenario of 6,500. But KOSPI has already risen 101% in 1H26, chip stocks are up more than 200%, and foreign investors have sold KRW 158 trillion. Whether the index can move higher depends on whether the rally can broaden from Samsung Electronics and SK Hynix into more sectors such as industrials, financials, healthcare, defense, and consumer.
Foreign selling does not equal bearishness on Korea. The more reasonable explanation is rebalancing and risk management: Korea’s weight in MSCI EM rose from 13.3% in December 2025 to 23.1% in May 2026. Chip stocks rose too quickly, leaving many global portfolios passively overweight Korea, overweight IT, and overweight a single leading name. They therefore had to sell to lock in gains and reduce concentration.
The falsification points are AI, property, and policy execution. If AI capex slows, memory pricing causes demand destruction, Korea’s capital-market reforms fail to land, Seoul property prices fall sharply, or leveraged retail capital retreats, KOSPI volatility will rise materially, and the won may return to a weak-currency loop.
I. Korea’s Current Contradiction: The Strongest Fundamentals, the Weakest Currency
The first signal from Korean assets is highly counterintuitive. Under a traditional macro framework, if a country has accelerating exports, a widening trade surplus, a globally leading equity market, and a central bank shifting from rate cuts to rate hikes, its currency usually should not be weak. Yet since 2026, the won has not followed that script. Its weakness looks less like depreciation after a deterioration in economic fundamentals, and more like a mismatch in which the economy has strong cash flow but dollars have not returned home in time.
This mismatch is critical. Korea’s export growth in the first half has been reignited by the AI and semiconductor cycle. GDP, the trade surplus, and central-bank policy expectations are all improving, but these advantages have not automatically translated into won buying.
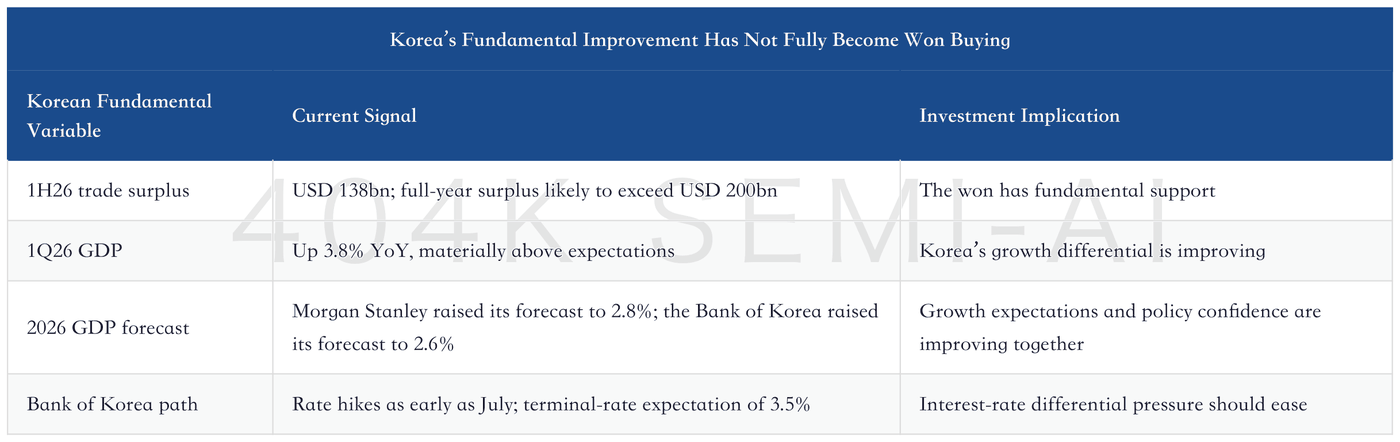
Looking only at these numbers, the won should have a clear appreciation logic: exports generate dollar revenues, the trade surplus widens, and the current account strengthens; growth outperforms the U.S., easing interest-rate differential pressure; the central bank hikes rates, reducing the carry disadvantage; and semiconductor capex expands, requiring companies to convert dollar revenues back into won for domestic spending. In reality, however, USD/KRW remains in a high range, and Morgan Stanley’s short-term view is only for modest appreciation, still far from a large strengthening move.
The real value of this material is that it breaks down the intermediate links behind “Korea’s economy is strong but the won is not.” The trade surplus itself is already very strong. The key question is whether that surplus ultimately settles into central-bank reserves, corporate won deposits, and buying of domestic assets. Korea’s trade account is strong, but the financial account is pushing many dollars back overseas. Corporate FX conversion has not fully kept pace with export improvement, and foreign investors are still selling after making money in the equity market. This is the core of won weakness.
What Korea really lacks now is won demand, not dollar revenue. This judgment also determines how to think about KOSPI: the faster the stock market rises, the more likely foreign portfolios are to become overweight Korea and semiconductors, requiring rebalancing; rebalancing sales then weigh on the won; and a weak won in turn raises FX concerns for foreign investors holding Korean assets. This is a closed loop of mutual constraints.
II. Why the Won Is Weak: Capital Flows and FX-Conversion Timing Are Overpowering the Trade Surplus
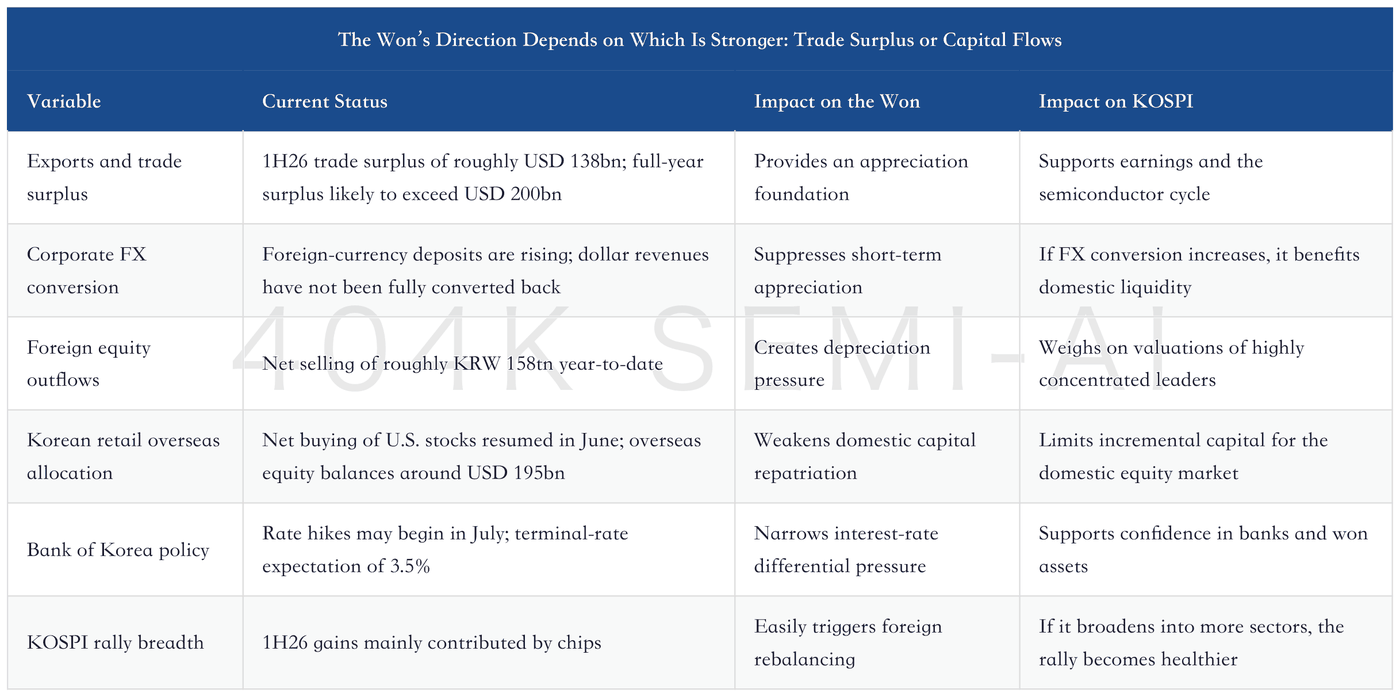
Won weakness can be broken into three variables: foreign equity outflows, delayed corporate FX conversion, and overseas allocation by domestic Korean capital. All three are linked to the financial account and asset allocation. Together, they are enough to explain why the won has not appreciated alongside the surplus.
The first is foreign equity outflows. Korea’s equity market has risen too sharply in 2026, especially the semiconductor leaders. From the start of the year to early July, foreign investors cumulatively net sold roughly KRW 158 trillion of KOSPI equities. This selling should not be simplistically read as “bearish on Korea.” It looks more like global portfolio managers dealing with a position that suddenly became too large: Korea’s weight rose, IT’s weight rose, and the weights of Samsung Electronics and SK Hynix also rose, leaving country, sector, and single-stock concentration close to limits at the same time. Selling is risk management as well as profit-taking.
The second is delayed corporate FX conversion. After Korea’s trade surplus expands, exporters in theory convert dollar revenues into won. In reality, however, overseas foreign-currency deposits held by companies and households have increased, and onshore foreign-currency deposits held by Korean companies rose from USD 74bn in May 2024 to USD 97.4bn in May 2026. Companies may not immediately convert dollars back into won. Some dollars may remain offshore, some may be used for U.S. investment, and some may be reserved for future capex and supply-chain arrangements. In 2025, Korean companies’ direct investment in the U.S. reached USD 25bn, while the U.S. share of Korea’s outward direct investment also rose from 32% in June 2025 to 35% by year-end.
The third is domestic capital going overseas. In 2025, Korean retail investors, asset managers, the National Pension Service, and other long-term capital continued increasing overseas asset allocation. By 2026, foreign de-risking had become the more important source of pressure, but retail overseas investment had not disappeared. Korean retail investors briefly net sold overseas equities in April and May 2026, then turned back to net buying U.S. stocks in June, with net purchases of roughly USD 633mn that month. Domestic retail holdings of U.S. stocks were about USD 195bn at end-June, up roughly 19% from end-2025. This shows domestic capital has not fully returned home just because KOSPI has surged.
When these three capital flows are combined, Korea’s balance-of-payments structure shows an interesting phenomenon: the current account is very strong, but the overall balance-of-payments support for the won is weaker than expected. Morgan Stanley notes that the balance of payments excluding changes in central-bank reserves still has a surplus of 1.2% of GDP, indicating Korea’s external financing pressure is not extreme. But Korea’s reserve assets have turned negative since 2022 and have remained under pressure for several years. This means a sizable share of the dollars created by the trade surplus has been absorbed by financial-account outflows and corporate dollar-hoarding behavior.
This is important for investment judgment. The won has both reasons to appreciate and depreciation pressure. Trade, growth, and interest-rate differentials are improving; but foreign equity selling, corporate dollar retention, and retail purchases of overseas assets are offsetting that improvement. The won’s medium-term direction depends on which side weakens first.
3. Where the Korean Won Goes Next: Mild Appreciation, but with Setbacks Along the Way
The Korean won has several positive short-term catalysts. One is that after large semiconductor companies list in the United States, part of the U.S.-dollar proceeds may be repatriated to Korea for domestic capex, with the FX conversion window potentially lasting from mid-July into August. Another is corporate tax payments in August. Korean companies typically pay taxes in March and August. In March 2026, onshore corporate foreign-currency deposits in Korea fell markedly by US$13 billion, partly due to FX conversion demand from tax payments. If similar behavior appears again in August, the won should receive temporary support.
The longer-term support comes from domestic capex. Recent large-scale domestic investment by Korean semiconductor companies also implies stronger growth and a need for companies to convert part of their U.S.-dollar revenue into Korean won to pay wages, equipment costs, construction expenses, and domestic supply-chain spending. For the won, capex makes dollar revenue more likely to circulate domestically.
This is still not enough to conclude that the won will appreciate sharply. Morgan Stanley’s FX framework is measured: without broader dollar weakness, USD/KRW may remain in the 1,490-1,560 range; to open up more downside, USD/KRW needs to break below around 1,485. The implication is that the won appreciation trade is still a repair trade for now, and a trend reversal requires more evidence from fund flows. Corporate FX conversion can bring buying demand, but foreign equity outflows, retail overseas investment, and global dollar factors will still cap the magnitude.
The logic is similar on rates. Korean bond yields are already close to their 2022 highs, but this time inflation pressure and the rate-hiking cycle may not be as extreme as in 2022. Morgan Stanley’s stance on Korean rates is relatively neutral, arguing that the 2s10s Korean government bond curve is broadly within a reasonable range. The rates market has already priced in some hawkish shift by the Bank of Korea. What matters more from here is whether the central bank can deliver sufficiently hawkish communication at its July meeting without alarming the property market and domestic demand.
A real upside breakout in the won requires two pieces of evidence. First, corporate foreign-currency deposits need to start declining persistently, showing that export dollars are being converted into won. Second, foreign selling pressure in the equity market needs to ease, especially the rebalancing pressure on Samsung Electronics and SK Hynix. If FX conversion improves but foreign investors keep selling heavily, the won can rebound but will struggle to rally sharply. Only if FX conversion improves and foreign selling pressure eases at the same time can the won move from “weakness repair” into “trend appreciation.”
4. Where Korea’s Fundamentals Are Strong: AI Exports, Growth Differentials, and a Central Bank Pivot
Korea’s macro strength comes from the simultaneous reversal of three variables: growth differentials, the export cycle, and policy-rate differentials.
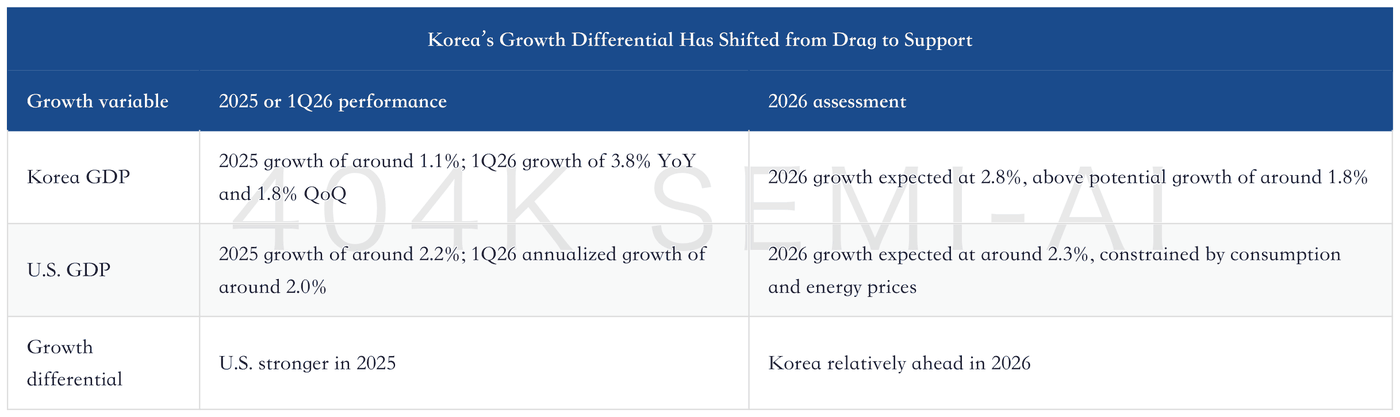
Start with growth differentials. In 2025, Korea grew below potential, as weak domestic demand, shrinking construction investment, and tariff concerns jointly weighed on the economy, while U.S. growth was more resilient. In 2026, that relationship has reversed. Korea’s 1Q26 growth was well above expectations, full-year growth expectations are now above potential, and U.S. growth is slightly weaker than previously expected. The growth differential has shifted from “strong U.S., weak Korea” to “stronger Korea,” which is the first layer of fundamental repair for the won.
Next, exports. Korean exports were relatively weak in 2025. The trade surplus remained, but with insufficient elasticity. By 2026, the AI semiconductor cycle had pulled exports back up, with June exports hitting a monthly record. More importantly, the report argues that the improvement has already spread to non-tech manufacturing, reducing market concerns that demand is excessively concentrated in semiconductors.
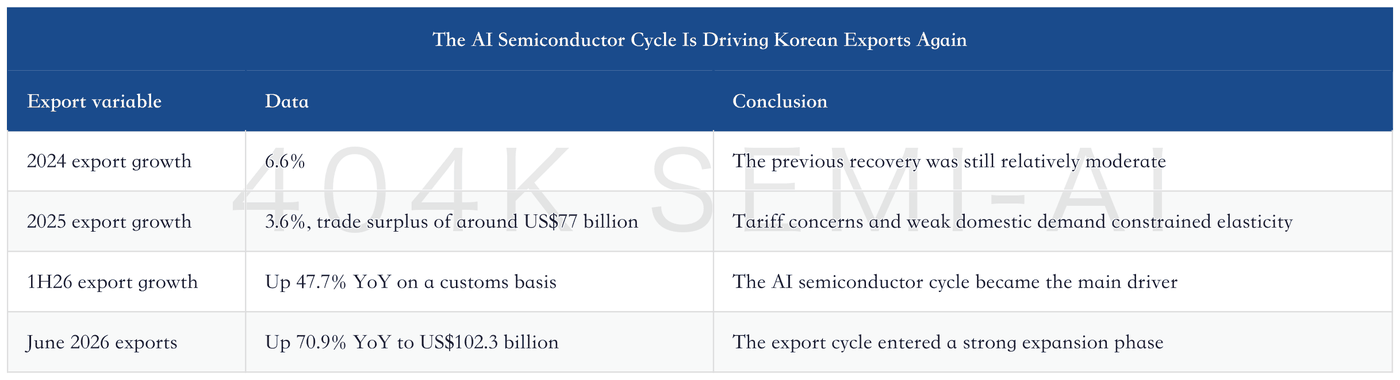
The scale of the trade surplus has also changed. Korea’s trade surplus reached US$138 billion in 1H26, and the full-year figure may exceed US$200 billion, more than twice the 2025 level. This is the most solid fundamental base for the won. As long as this surplus persists, it is hard to simply classify the won as an “externally vulnerable currency.” The key question from here is when dollars return, and in what form.
Third is the central bank pivot. The Bank of Korea was dovish for most of 2025, but its path clearly changed after the May 2026 meeting, sending a signal that rate hikes could begin as soon as July. Morgan Stanley expects two rate hikes in 2026 and another two in 2027, taking the terminal rate to 3.5%. If the Fed keeps rates unchanged this year, the policy-rate differential between Korea and the United States will narrow, weakening the carry factor that previously weighed on the won.
Together, these three variables form the basis for a medium-term repair in the won. But it is also important to acknowledge that they have not yet fully translated into market prices. In the short term, the FX market pays more attention to dollar buying and selling flows, and its response to GDP and export data tends to lag. As long as companies hold foreign currency, foreign investors sell equities, and retail investors buy overseas assets, the won will appear weaker than fundamentals suggest.
5. Why the KOSPI Can Rise to 9,000: But the Rally Path Must Shift Gears
The KOSPI’s rally has already been extraordinary. The report shows that the KOSPI rose 101% in 1H26, chip stocks rose more than 200%, and chip stocks contributed 79% of the market-cap increase. Morgan Stanley still gives a 9,000 base-case target, a 10,500 bull-case scenario, and a 6,500 bear-case scenario. This target is supported by earnings upgrades, domestic liquidity, and capital-market reforms that continue to support the re-rating of Korean assets.
But from here, the KOSPI cannot continue relying only on semiconductor leaders. Korea’s IT and semiconductor weights are very high, the gains in the first half were enormous, and yet foreign investors were concentrated net sellers of IT, with domestic retail investors and institutions absorbing most of the selling. This set of data shows that the market structure is already different from a traditional bull market driven by sustained foreign buying.
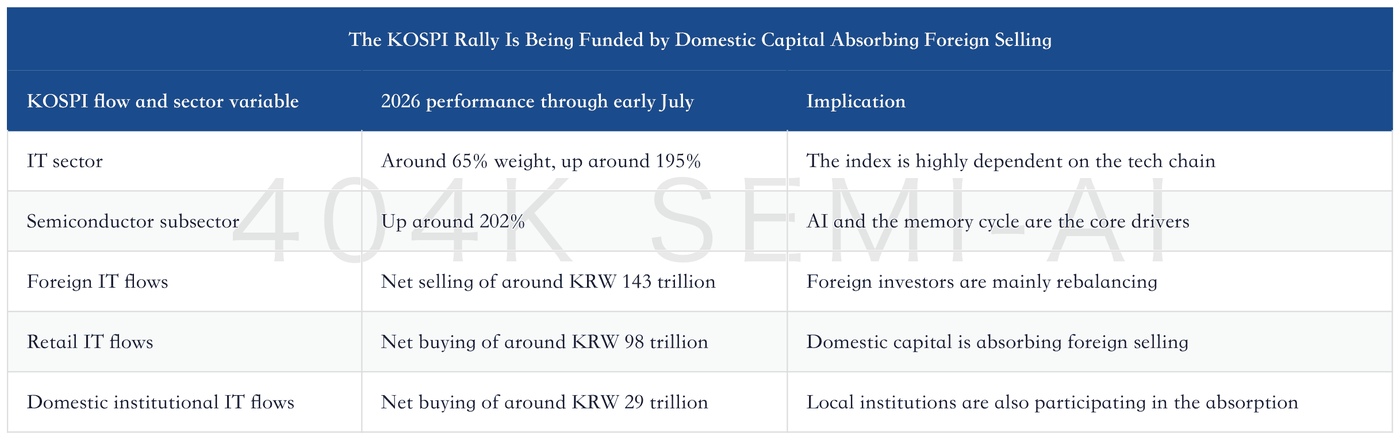
This structure has both benefits and risks. The benefit is that Korean retail and institutional domestic risk appetite has risen sharply and can absorb foreign de-risking. The risk is that the rally is increasingly dependent on domestic liquidity and leveraged products, which will increase volatility. The report notes that Korean retail investors had net inflows of KRW 99 trillion into domestic equities in 1H26, with high interest in ETFs, especially leveraged ETFs. As long as the rally continues, retail confidence will accumulate further. But if the market sees a bear-market-level drawdown of more than 20%, retail confidence could also reverse quickly.
For the 9,000 level to hold, the market needs to shift from being “driven by the two chip leaders” to “rising across more sectors.” Morgan Stanley points to energy security, financials, defense, healthcare, and premium consumption as areas to watch, while the core overweight remains industrials and IT, using healthcare and financials as a barbell. The implication of this allocation is that AI and semiconductors remain the core of the Korean asset re-rating, but not all risk should be placed on memory and AI capex.
Market breadth also matters because of foreign rebalancing pressure. If the KOSPI continues to be driven solely by Samsung Electronics and SK Hynix, foreign investors will keep selling because single-stock, sector, and country weights are too high. If the rally broadens to industrials, financials, defense, healthcare, and other sectors, semiconductor weight will be diluted, and foreign rebalancing pressure may instead decline. For the KOSPI, the healthiest bull-market pattern would be chip stocks moving sideways and digesting gains while other sectors take over.
6. Why Foreign Investors Are Selling: Overcrowded Positioning Is Overriding Fundamental Optimism
Foreign selling in Korean equities is easy to misread. Looking only at the scale of selling, net sales of KRW 158 trillion from the start of the year to early July are indeed intimidating. But in a global portfolio framework, the logic is much clearer: Korea rose too quickly, foreign investors passively became overweight, and they had to rebalance.
Korea’s weight in MSCI EM rose from 13.3% in December 2025 to 23.1% in May 2026. By May 2026, international funds’ Korean portfolio weight was about 25.0%, tied with another semiconductor-heavy market near the high end, representing a 1.9 percentage point overweight versus the MSCI EM benchmark. For global fund managers, Korea is no longer a small-weight market where exposure can be added casually, but one of the largest sources of portfolio risk.
The single-stock picture is even clearer. Samsung Electronics’ weight in MSCI EM is about 8.6%, while long-only active funds’ portfolio weight is about 9.0%; SK Hynix has a benchmark weight of about 6.6% and a portfolio weight of about 8.0%, implying an active overweight of 1.4 percentage points. US funds have an even higher active overweight in SK Hynix, at 1.9 percentage points. Many funds have already bought too much, so trimming is driven more by position constraints and concentration management.
When a market doubles in six months and its core stocks rise more than 200%, selling often comes from risk budgets rather than the end of the story. This is especially true for stocks such as Samsung Electronics and SK Hynix: once they approach limits across country, sector, and single-stock dimensions, portfolio managers are forced to reduce exposure. The more foreign selling is concentrated in IT, the more it suggests rebalancing; its negative implication for the broader Korean economy is actually weaker.
But rebalancing-driven selling still affects the market. It weighs on the won and suppresses valuation elasticity for chip leaders. More importantly, it turns the KOSPI from a “foreign-buying bull market” into a “domestic-funding absorption bull market.” This shift raises volatility. If chips consolidate in the short term and other sectors take over, foreign selling pressure may ease. If the AI narrative remains concentrated in a small number of memory and semiconductor stocks, selling pressure will be hard to eliminate.
7. Retail Investors and Pension Funds: Can Domestic Korean Capital Keep Absorbing Supply?
Domestic Korean capital is an important reason why this KOSPI rally has lasted this long. Retail investors saw net inflows of about KRW 99 trillion in 1H26, while domestic institutions have also been buying, especially absorbing semiconductor positions sold by foreign investors. The report expects equities and equity-equivalent assets to rise to about 34%-35% of Korean household financial assets by end-2026, significantly higher than 26.5% in 2025. This means Korean household asset allocation is shifting from deposits, insurance, and pensions toward equities.
But this trend cannot be extrapolated indefinitely. The strength of retail buying has come from liquidity, AI news flow, leveraged ETFs, and policy incentives. The report believes retail net inflows will continue in 2H26, but another KRW 100 trillion-scale inflow is unrealistic. Regulation may tighten leverage and credit, while investors may also reconsider alternatives such as overseas equities and Korean growth funds. Retail investors can continue to provide a floor, but it will be hard for them to push valuations higher unconditionally as they did in the first half.
Overseas allocation will also divert capital. After RIA accounts were launched in March, they offered capital gains tax incentives to retail investors who sold overseas stocks and repatriated funds into domestic investment: 100% tax exemption before the end of May, falling to 80% from June to July and 50% from August to year-end. As the incentives decline, RIAs become less attractive for capital repatriation. Meanwhile, US equities have performed strongly, Korean retail investors resumed net buying of US stocks in June, and overseas equity balances have continued to rise. For the won, domestic capital repatriation is not secure; for the KOSPI, domestic capital still has overseas equities as an alternative destination.
The impact of the National Pension Service is more complex. As of April 2026, the NPS domestic equity allocation was 25.1%, above its 20.8% strategic target for end-2026, but this does not necessarily mean immediate large-scale selling. Media reports have mentioned that the strategic asset allocation buffer could be temporarily expanded to 6 percentage points, plus an additional 2 percentage point tactical buffer, theoretically allowing domestic equity allocation to be tolerated up to 28.8%. The government and regulators are also aware that pension rebalancing could shock the market, and are discussing more flexible deviation ranges and delayed trading mechanisms.
So the NPS may not dump shares immediately in the short term, but it is also unlikely to become a sustained source of incremental capital. It will cap extreme upside, but may not create immediate downside in the near term. As long as the KOSPI keeps rising, NPS allocation pressure will gradually increase; as long as policy allows a larger buffer, its market impact can be delayed and smoothed. Investors need to watch whether policy allows the NPS to avoid mechanical selling during volatile phases. Looking only at the target number can easily lead to a misread of selling pressure.
8. The Impact of Won Appreciation on Equity Structure: Winners May Shift from Export Leaders to Domestic Demand and Financials
If the won appreciates moderately, the impact at the equity level will diverge. The sensitivities listed in the report show that when the won appreciates 5% against the US dollar, banks, telecoms, utilities, and some healthcare companies may benefit; while export-oriented IT, autos, batteries, industrials, and energy companies may see a 5%-15% negative impact on operating profit. This conclusion is important because the Korean market’s biggest gainers in the first half were precisely semiconductors and export chains that are more sensitive to won appreciation.
This does not mean won appreciation will necessarily interrupt the tech bull market. The main semiconductor story remains AI demand, the memory cycle, pricing leverage, and capital expenditure. But if the won recovers from an extremely weak level, the market will recalculate exporters’ margins, especially for companies that have already risen sharply. The faster the won appreciates, the more easily it becomes a reason for short-term valuation digestion in chips and autos.
By contrast, financial and domestic-demand assets may become more important at this stage. Banks benefit from higher rates and won stability; telecoms and some healthcare companies have a more positive exchange-rate profile; industrials and defense benefit from Korean capital market reform, energy security, and overseas order logic. Morgan Stanley’s sector ranking still keeps industrials and IT as core overweights, while using healthcare and financials as a barbell. The logic is to capture both the AI export theme and domestic-demand/financial elasticity under won repair.
Therefore, the core question for the KOSPI in the second half will shift from “can it keep rising?” to “who rises?” If gains remain concentrated in a few AI and memory stocks, foreign rebalancing, won appreciation, and valuation fatigue will all weigh on these shares. If gains broaden into financials, industrials, defense, healthcare, and premium consumption, the KOSPI can continue rising at the index level while reducing reliance on a single narrative.
9. Four Variables to Watch Next
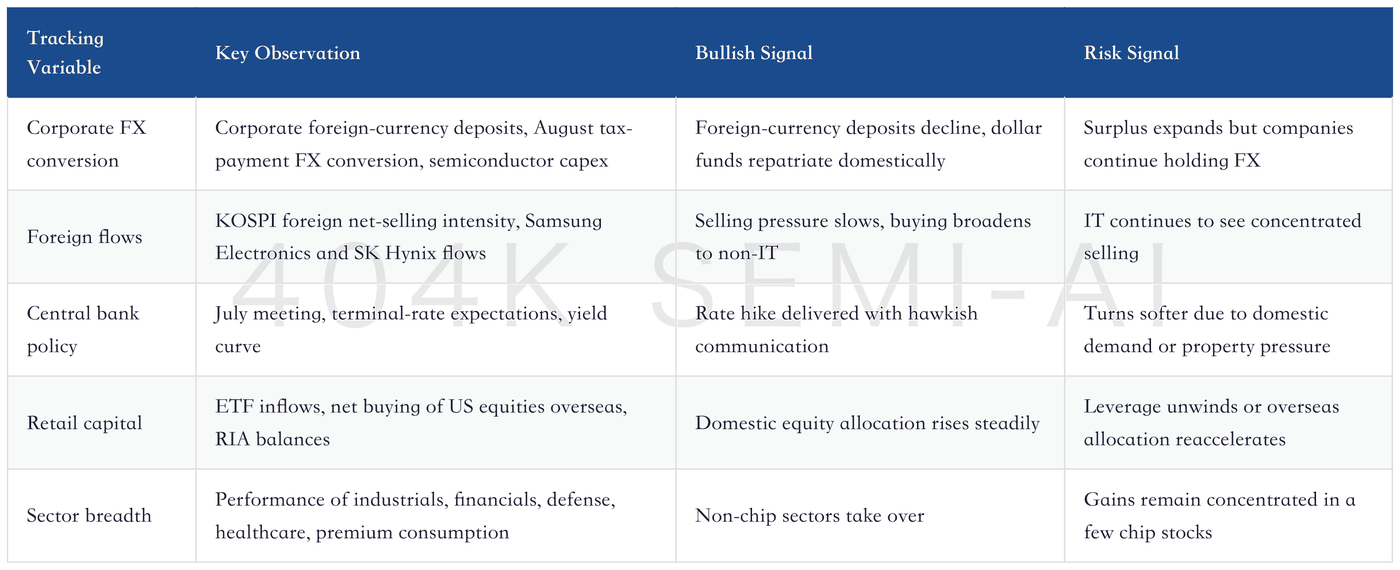
First, watch corporate FX conversion. August tax payments, dollar repatriation by semiconductor companies, and domestic capex are the key short-term indicators for won repair. If corporate foreign-currency deposits continue to decline, it means export dollars are truly starting to flow into the domestic financial system. Conversely, if the trade surplus keeps expanding but foreign-currency deposits also keep rising, the won’s appreciation room will remain constrained.
Second, watch whether foreign selling pressure slows. The focus is whether selling intensity can fall from the highs of May and June; there is no need to wait for foreign investors to resume large-scale buying of Korea. In particular, watch whether stocks beyond Samsung Electronics and SK Hynix can attract capital. If foreign selling mainly comes from chip rebalancing and other sectors begin to receive inflows, the quality of the KOSPI rally will improve.
Third, watch the Bank of Korea’s July meeting. If the central bank raises rates as expected and sends a sustained hawkish signal, the won will gain interest-rate differential support. But if the central bank communicates softly because of real estate, consumption, or financial stability risks, the market will again question the length of the hiking cycle. Rate expectations are already not low; the central bank needs to provide enough confirmation.
Fourth, watch retail leverage and overseas allocation. Whether the KOSPI can hold 9,000 depends largely on whether domestic retail capital can shift from “short-term trading money” to “structural asset-allocation capital.” If leveraged ETFs overheat, regulation tightens, or a market pullback causes retail investors to withdraw, KOSPI volatility will increase. Conversely, if Korean households’ equity allocation continues to rise and sector breadth improves, domestic capital will provide a more durable floor for the KOSPI.
The key areas for follow-up validation are FX conversion, selling pressure, the central bank, retail investors, and sector breadth.
X. Key Risks: The Cost of This Bull Market Is Already Becoming Visible
The first major risk is the AI capex cycle. The core drivers of this Korean equity rally have been AI and memory. If data-center construction is delayed, AI investment returns are questioned, or memory price increases damage demand for PCs, smartphones, and consumer electronics, the earnings-upgrade cycle for Korea’s IT sector will be reassessed. Because index gains and foreign rebalancing pressure are both concentrated in semiconductors, any weakening in the AI narrative would make KOSPI more prone than other markets to amplified volatility.
The second major risk is policy execution. Korea’s capital-market and corporate-governance reforms are an important pillar of KOSPI’s re-rating. If the reform agenda fails to move forward, the market will reapply a discount to Korean assets. For foreign investors, once Korea shifts from a low-valuation market to a high-weight market, institutional improvement becomes more necessary; otherwise, higher valuations and higher volatility will reduce the risk-reward.
The third major risk is geopolitics. Korean assets are sensitive to the regional security environment. Any escalation in Asia-Pacific tensions could push risk premiums higher. This risk may not necessarily change corporate earnings, but it would change the valuation multiple foreign investors are willing to assign to the Korean market and would also increase demand for the U.S. dollar.
The fourth major risk is domestic demand and real estate. A large share of Korea’s current growth comes from exports and semiconductors. If domestic consumption recovers less than expected, Seoul real estate declines materially, and risks rise around construction-company bankruptcies and retail-loan defaults, the central bank’s room to raise rates and the government’s room for fiscal expansion will both be constrained. At that point, the interest-rate support for the won and the domestic-liquidity support for KOSPI would both weaken.
The fifth major risk is a retreat in retail money. Retail buying was very strong in 1H26, but it included leveraged ETFs and high-risk-appetite components. If the market suffers a drawdown of more than 20%, or regulators tighten rules on margin financing and leverage products, retail investors could shift from a stable source of incremental capital into an amplifier of volatility. KOSPI would then face a drawdown faster than fundamentals would imply.
XI. Conclusion: Korean Assets Are Not Done, but the Trade Has Become Harder
The core opportunity in Korean assets remains intact. Exports, growth, central-bank policy, and equity-market earnings are all stronger than in 2025. The won is still weak after a mismatch between fundamentals and capital flows, and KOSPI still has upside represented by the 9,000-point target. But this trade has already moved from “buy Korea’s recovery” to “decompose Korea’s capital flows,” and the difficulty has clearly increased.
The opportunity in the won is that corporate FX conversion and central-bank rate hikes can help it recover from excessive weakness; the constraint is that foreign equity selling and domestic capital outflows will cap the scale of appreciation. The opportunity in KOSPI is that the AI semiconductor cycle, capital-market reform, and domestic asset-allocation migration are still in place; the constraint is that the index has risen too quickly, foreign positioning is too full, retail leverage is too hot, and the rally must broaden into more sectors to reduce fragility.
Therefore, the best scenario for Korean assets requires three moderate shifts to occur at the same time: corporates begin converting FX, foreign selling pressure declines, and KOSPI’s market breadth expands. If these three things happen, the won can move from being a weak currency to a recovery currency, and KOSPI 9,000 would look more like a midpoint than a ceiling. Conversely, if the AI narrative cools, corporates continue to hold FX, foreign investors keep selling semiconductors, and retail leverage retreats, Korean assets will return to the awkward state of “very strong fundamentals, but prices struggle to rise.”Korea Assets Deep Dive: Why Is the Won So Weak, and Can KOSPI Hold 9,000?
目录
Too Long; Didn’t Read
I. Korea’s Current Contradiction: The Strongest Fundamentals, the Weakest Currency
II. Why the Won Is Weak: Capital Flows and FX-Conversion Timing Are Overpowering the Trade Surplus
3. Where the Korean Won Goes Next: Mild Appreciation, but with Setbacks Along the Way
4. Where Korea’s Fundamentals Are Strong: AI Exports, Growth Differentials, and a Central Bank Pivot
5. Why the KOSPI Can Rise to 9,000: But the Rally Path Must Shift Gears
6. Why Foreign Investors Are Selling: Overcrowded Positioning Is Overriding Fundamental Optimism
7. Retail Investors and Pension Funds: Can Domestic Korean Capital Keep Absorbing Supply?
8. The Impact of Won Appreciation on Equity Structure: Winners May Shift from Export Leaders to Domestic Demand and Financials
9. Four Variables to Watch Next
X. Key Risks: The Cost of This Bull Market Is Already Becoming Visible
XI. Conclusion: Korean Assets Are Not Done, but the Trade Has Become Harder
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The most important lens for Korean assets now is that the current-account surplus, corporate FX conversion, foreign investor de-risking, retail reallocation, Bank of Korea rate-hike expectations, and policy delivery are all being compressed into the same balance sheet. Behind the weak won is a mismatch in capital flows. Whether KOSPI can hold 9,000 also depends on whether this mismatch can cool down.
Too Long; Didn’t Read
Won weakness reflects capital-flow pressure. Korea’s exports, growth, and trade surplus were all strong in 1H26, yet the won remains among the weaker major Asian currencies outside Japan. The market is now mainly trading the financial account, corporate FX conversion, and changes in foreign investor positioning.
The real drag comes from three capital flows. Foreign investors have trimmed Korean equities after taking profits; companies are keeping dollar revenues offshore or in foreign-currency deposits; and Korean retail investors and institutions have continued buying overseas assets over the past few years. Together, these explain why the current-account surplus has not translated directly into won appreciation.
The won looks more like a modest repair trade. Corporate tax payments in August, repatriation of proceeds from U.S. listings by semiconductor companies, and higher domestic capex in Korea could all lift corporate FX-conversion demand. But foreign investors may still keep selling, and retail overseas investment is also recovering, so in the near term the won looks more like a repair from an extremely weak level than a one-way sharp appreciation trade.
KOSPI 9,000 needs breadth confirmation. Morgan Stanley’s base-case target is 9,000, with a bull-case scenario of 10,500 and a bear-case scenario of 6,500. But KOSPI has already risen 101% in 1H26, chip stocks are up more than 200%, and foreign investors have sold KRW 158 trillion. Whether the index can move higher depends on whether the rally can broaden from Samsung Electronics and SK Hynix into more sectors such as industrials, financials, healthcare, defense, and consumer.
Foreign selling does not equal bearishness on Korea. The more reasonable explanation is rebalancing and risk management: Korea’s weight in MSCI EM rose from 13.3% in December 2025 to 23.1% in May 2026. Chip stocks rose too quickly, leaving many global portfolios passively overweight Korea, overweight IT, and overweight a single leading name. They therefore had to sell to lock in gains and reduce concentration.
The falsification points are AI, property, and policy execution. If AI capex slows, memory pricing causes demand destruction, Korea’s capital-market reforms fail to land, Seoul property prices fall sharply, or leveraged retail capital retreats, KOSPI volatility will rise materially, and the won may return to a weak-currency loop.
I. Korea’s Current Contradiction: The Strongest Fundamentals, the Weakest Currency
The first signal from Korean assets is highly counterintuitive. Under a traditional macro framework, if a country has accelerating exports, a widening trade surplus, a globally leading equity market, and a central bank shifting from rate cuts to rate hikes, its currency usually should not be weak. Yet since 2026, the won has not followed that script. Its weakness looks less like depreciation after a deterioration in economic fundamentals, and more like a mismatch in which the economy has strong cash flow but dollars have not returned home in time.
This mismatch is critical. Korea’s export growth in the first half has been reignited by the AI and semiconductor cycle. GDP, the trade surplus, and central-bank policy expectations are all improving, but these advantages have not automatically translated into won buying.
Looking only at these numbers, the won should have a clear appreciation logic: exports generate dollar revenues, the trade surplus widens, and the current account strengthens; growth outperforms the U.S., easing interest-rate differential pressure; the central bank hikes rates, reducing the carry disadvantage; and semiconductor capex expands, requiring companies to convert dollar revenues back into won for domestic spending. In reality, however, USD/KRW remains in a high range, and Morgan Stanley’s short-term view is only for modest appreciation, still far from a large strengthening move.
The real value of this material is that it breaks down the intermediate links behind “Korea’s economy is strong but the won is not.” The trade surplus itself is already very strong. The key question is whether that surplus ultimately settles into central-bank reserves, corporate won deposits, and buying of domestic assets. Korea’s trade account is strong, but the financial account is pushing many dollars back overseas. Corporate FX conversion has not fully kept pace with export improvement, and foreign investors are still selling after making money in the equity market. This is the core of won weakness.
What Korea really lacks now is won demand, not dollar revenue. This judgment also determines how to think about KOSPI: the faster the stock market rises, the more likely foreign portfolios are to become overweight Korea and semiconductors, requiring rebalancing; rebalancing sales then weigh on the won; and a weak won in turn raises FX concerns for foreign investors holding Korean assets. This is a closed loop of mutual constraints.
II. Why the Won Is Weak: Capital Flows and FX-Conversion Timing Are Overpowering the Trade Surplus
Won weakness can be broken into three variables: foreign equity outflows, delayed corporate FX conversion, and overseas allocation by domestic Korean capital. All three are linked to the financial account and asset allocation. Together, they are enough to explain why the won has not appreciated alongside the surplus.
The first is foreign equity outflows. Korea’s equity market has risen too sharply in 2026, especially the semiconductor leaders. From the start of the year to early July, foreign investors cumulatively net sold roughly KRW 158 trillion of KOSPI equities. This selling should not be simplistically read as “bearish on Korea.” It looks more like global portfolio managers dealing with a position that suddenly became too large: Korea’s weight rose, IT’s weight rose, and the weights of Samsung Electronics and SK Hynix also rose, leaving country, sector, and single-stock concentration close to limits at the same time. Selling is risk management as well as profit-taking.
The second is delayed corporate FX conversion. After Korea’s trade surplus expands, exporters in theory convert dollar revenues into won. In reality, however, overseas foreign-currency deposits held by companies and households have increased, and onshore foreign-currency deposits held by Korean companies rose from USD 74bn in May 2024 to USD 97.4bn in May 2026. Companies may not immediately convert dollars back into won. Some dollars may remain offshore, some may be used for U.S. investment, and some may be reserved for future capex and supply-chain arrangements. In 2025, Korean companies’ direct investment in the U.S. reached USD 25bn, while the U.S. share of Korea’s outward direct investment also rose from 32% in June 2025 to 35% by year-end.
The third is domestic capital going overseas. In 2025, Korean retail investors, asset managers, the National Pension Service, and other long-term capital continued increasing overseas asset allocation. By 2026, foreign de-risking had become the more important source of pressure, but retail overseas investment had not disappeared. Korean retail investors briefly net sold overseas equities in April and May 2026, then turned back to net buying U.S. stocks in June, with net purchases of roughly USD 633mn that month. Domestic retail holdings of U.S. stocks were about USD 195bn at end-June, up roughly 19% from end-2025. This shows domestic capital has not fully returned home just because KOSPI has surged.
When these three capital flows are combined, Korea’s balance-of-payments structure shows an interesting phenomenon: the current account is very strong, but the overall balance-of-payments support for the won is weaker than expected. Morgan Stanley notes that the balance of payments excluding changes in central-bank reserves still has a surplus of 1.2% of GDP, indicating Korea’s external financing pressure is not extreme. But Korea’s reserve assets have turned negative since 2022 and have remained under pressure for several years. This means a sizable share of the dollars created by the trade surplus has been absorbed by financial-account outflows and corporate dollar-hoarding behavior.
This is important for investment judgment. The won has both reasons to appreciate and depreciation pressure. Trade, growth, and interest-rate differentials are improving; but foreign equity selling, corporate dollar retention, and retail purchases of overseas assets are offsetting that improvement. The won’s medium-term direction depends on which side weakens first.
3. Where the Korean Won Goes Next: Mild Appreciation, but with Setbacks Along the Way
The Korean won has several positive short-term catalysts. One is that after large semiconductor companies list in the United States, part of the U.S.-dollar proceeds may be repatriated to Korea for domestic capex, with the FX conversion window potentially lasting from mid-July into August. Another is corporate tax payments in August. Korean companies typically pay taxes in March and August. In March 2026, onshore corporate foreign-currency deposits in Korea fell markedly by US$13 billion, partly due to FX conversion demand from tax payments. If similar behavior appears again in August, the won should receive temporary support.
The longer-term support comes from domestic capex. Recent large-scale domestic investment by Korean semiconductor companies also implies stronger growth and a need for companies to convert part of their U.S.-dollar revenue into Korean won to pay wages, equipment costs, construction expenses, and domestic supply-chain spending. For the won, capex makes dollar revenue more likely to circulate domestically.
This is still not enough to conclude that the won will appreciate sharply. Morgan Stanley’s FX framework is measured: without broader dollar weakness, USD/KRW may remain in the 1,490-1,560 range; to open up more downside, USD/KRW needs to break below around 1,485. The implication is that the won appreciation trade is still a repair trade for now, and a trend reversal requires more evidence from fund flows. Corporate FX conversion can bring buying demand, but foreign equity outflows, retail overseas investment, and global dollar factors will still cap the magnitude.
The logic is similar on rates. Korean bond yields are already close to their 2022 highs, but this time inflation pressure and the rate-hiking cycle may not be as extreme as in 2022. Morgan Stanley’s stance on Korean rates is relatively neutral, arguing that the 2s10s Korean government bond curve is broadly within a reasonable range. The rates market has already priced in some hawkish shift by the Bank of Korea. What matters more from here is whether the central bank can deliver sufficiently hawkish communication at its July meeting without alarming the property market and domestic demand.
A real upside breakout in the won requires two pieces of evidence. First, corporate foreign-currency deposits need to start declining persistently, showing that export dollars are being converted into won. Second, foreign selling pressure in the equity market needs to ease, especially the rebalancing pressure on Samsung Electronics and SK Hynix. If FX conversion improves but foreign investors keep selling heavily, the won can rebound but will struggle to rally sharply. Only if FX conversion improves and foreign selling pressure eases at the same time can the won move from “weakness repair” into “trend appreciation.”
4. Where Korea’s Fundamentals Are Strong: AI Exports, Growth Differentials, and a Central Bank Pivot
Korea’s macro strength comes from the simultaneous reversal of three variables: growth differentials, the export cycle, and policy-rate differentials.
Start with growth differentials. In 2025, Korea grew below potential, as weak domestic demand, shrinking construction investment, and tariff concerns jointly weighed on the economy, while U.S. growth was more resilient. In 2026, that relationship has reversed. Korea’s 1Q26 growth was well above expectations, full-year growth expectations are now above potential, and U.S. growth is slightly weaker than previously expected. The growth differential has shifted from “strong U.S., weak Korea” to “stronger Korea,” which is the first layer of fundamental repair for the won.
Next, exports. Korean exports were relatively weak in 2025. The trade surplus remained, but with insufficient elasticity. By 2026, the AI semiconductor cycle had pulled exports back up, with June exports hitting a monthly record. More importantly, the report argues that the improvement has already spread to non-tech manufacturing, reducing market concerns that demand is excessively concentrated in semiconductors.
The scale of the trade surplus has also changed. Korea’s trade surplus reached US$138 billion in 1H26, and the full-year figure may exceed US$200 billion, more than twice the 2025 level. This is the most solid fundamental base for the won. As long as this surplus persists, it is hard to simply classify the won as an “externally vulnerable currency.” The key question from here is when dollars return, and in what form.
Third is the central bank pivot. The Bank of Korea was dovish for most of 2025, but its path clearly changed after the May 2026 meeting, sending a signal that rate hikes could begin as soon as July. Morgan Stanley expects two rate hikes in 2026 and another two in 2027, taking the terminal rate to 3.5%. If the Fed keeps rates unchanged this year, the policy-rate differential between Korea and the United States will narrow, weakening the carry factor that previously weighed on the won.
Together, these three variables form the basis for a medium-term repair in the won. But it is also important to acknowledge that they have not yet fully translated into market prices. In the short term, the FX market pays more attention to dollar buying and selling flows, and its response to GDP and export data tends to lag. As long as companies hold foreign currency, foreign investors sell equities, and retail investors buy overseas assets, the won will appear weaker than fundamentals suggest.
5. Why the KOSPI Can Rise to 9,000: But the Rally Path Must Shift Gears
The KOSPI’s rally has already been extraordinary. The report shows that the KOSPI rose 101% in 1H26, chip stocks rose more than 200%, and chip stocks contributed 79% of the market-cap increase. Morgan Stanley still gives a 9,000 base-case target, a 10,500 bull-case scenario, and a 6,500 bear-case scenario. This target is supported by earnings upgrades, domestic liquidity, and capital-market reforms that continue to support the re-rating of Korean assets.
But from here, the KOSPI cannot continue relying only on semiconductor leaders. Korea’s IT and semiconductor weights are very high, the gains in the first half were enormous, and yet foreign investors were concentrated net sellers of IT, with domestic retail investors and institutions absorbing most of the selling. This set of data shows that the market structure is already different from a traditional bull market driven by sustained foreign buying.
This structure has both benefits and risks. The benefit is that Korean retail and institutional domestic risk appetite has risen sharply and can absorb foreign de-risking. The risk is that the rally is increasingly dependent on domestic liquidity and leveraged products, which will increase volatility. The report notes that Korean retail investors had net inflows of KRW 99 trillion into domestic equities in 1H26, with high interest in ETFs, especially leveraged ETFs. As long as the rally continues, retail confidence will accumulate further. But if the market sees a bear-market-level drawdown of more than 20%, retail confidence could also reverse quickly.
For the 9,000 level to hold, the market needs to shift from being “driven by the two chip leaders” to “rising across more sectors.” Morgan Stanley points to energy security, financials, defense, healthcare, and premium consumption as areas to watch, while the core overweight remains industrials and IT, using healthcare and financials as a barbell. The implication of this allocation is that AI and semiconductors remain the core of the Korean asset re-rating, but not all risk should be placed on memory and AI capex.
Market breadth also matters because of foreign rebalancing pressure. If the KOSPI continues to be driven solely by Samsung Electronics and SK Hynix, foreign investors will keep selling because single-stock, sector, and country weights are too high. If the rally broadens to industrials, financials, defense, healthcare, and other sectors, semiconductor weight will be diluted, and foreign rebalancing pressure may instead decline. For the KOSPI, the healthiest bull-market pattern would be chip stocks moving sideways and digesting gains while other sectors take over.
6. Why Foreign Investors Are Selling: Overcrowded Positioning Is Overriding Fundamental Optimism
Foreign selling in Korean equities is easy to misread. Looking only at the scale of selling, net sales of KRW 158 trillion from the start of the year to early July are indeed intimidating. But in a global portfolio framework, the logic is much clearer: Korea rose too quickly, foreign investors passively became overweight, and they had to rebalance.
Korea’s weight in MSCI EM rose from 13.3% in December 2025 to 23.1% in May 2026. By May 2026, international funds’ Korean portfolio weight was about 25.0%, tied with another semiconductor-heavy market near the high end, representing a 1.9 percentage point overweight versus the MSCI EM benchmark. For global fund managers, Korea is no longer a small-weight market where exposure can be added casually, but one of the largest sources of portfolio risk.
The single-stock picture is even clearer. Samsung Electronics’ weight in MSCI EM is about 8.6%, while long-only active funds’ portfolio weight is about 9.0%; SK Hynix has a benchmark weight of about 6.6% and a portfolio weight of about 8.0%, implying an active overweight of 1.4 percentage points. US funds have an even higher active overweight in SK Hynix, at 1.9 percentage points. Many funds have already bought too much, so trimming is driven more by position constraints and concentration management.
When a market doubles in six months and its core stocks rise more than 200%, selling often comes from risk budgets rather than the end of the story. This is especially true for stocks such as Samsung Electronics and SK Hynix: once they approach limits across country, sector, and single-stock dimensions, portfolio managers are forced to reduce exposure. The more foreign selling is concentrated in IT, the more it suggests rebalancing; its negative implication for the broader Korean economy is actually weaker.
But rebalancing-driven selling still affects the market. It weighs on the won and suppresses valuation elasticity for chip leaders. More importantly, it turns the KOSPI from a “foreign-buying bull market” into a “domestic-funding absorption bull market.” This shift raises volatility. If chips consolidate in the short term and other sectors take over, foreign selling pressure may ease. If the AI narrative remains concentrated in a small number of memory and semiconductor stocks, selling pressure will be hard to eliminate.
7. Retail Investors and Pension Funds: Can Domestic Korean Capital Keep Absorbing Supply?
Domestic Korean capital is an important reason why this KOSPI rally has lasted this long. Retail investors saw net inflows of about KRW 99 trillion in 1H26, while domestic institutions have also been buying, especially absorbing semiconductor positions sold by foreign investors. The report expects equities and equity-equivalent assets to rise to about 34%-35% of Korean household financial assets by end-2026, significantly higher than 26.5% in 2025. This means Korean household asset allocation is shifting from deposits, insurance, and pensions toward equities.
But this trend cannot be extrapolated indefinitely. The strength of retail buying has come from liquidity, AI news flow, leveraged ETFs, and policy incentives. The report believes retail net inflows will continue in 2H26, but another KRW 100 trillion-scale inflow is unrealistic. Regulation may tighten leverage and credit, while investors may also reconsider alternatives such as overseas equities and Korean growth funds. Retail investors can continue to provide a floor, but it will be hard for them to push valuations higher unconditionally as they did in the first half.
Overseas allocation will also divert capital. After RIA accounts were launched in March, they offered capital gains tax incentives to retail investors who sold overseas stocks and repatriated funds into domestic investment: 100% tax exemption before the end of May, falling to 80% from June to July and 50% from August to year-end. As the incentives decline, RIAs become less attractive for capital repatriation. Meanwhile, US equities have performed strongly, Korean retail investors resumed net buying of US stocks in June, and overseas equity balances have continued to rise. For the won, domestic capital repatriation is not secure; for the KOSPI, domestic capital still has overseas equities as an alternative destination.
The impact of the National Pension Service is more complex. As of April 2026, the NPS domestic equity allocation was 25.1%, above its 20.8% strategic target for end-2026, but this does not necessarily mean immediate large-scale selling. Media reports have mentioned that the strategic asset allocation buffer could be temporarily expanded to 6 percentage points, plus an additional 2 percentage point tactical buffer, theoretically allowing domestic equity allocation to be tolerated up to 28.8%. The government and regulators are also aware that pension rebalancing could shock the market, and are discussing more flexible deviation ranges and delayed trading mechanisms.
So the NPS may not dump shares immediately in the short term, but it is also unlikely to become a sustained source of incremental capital. It will cap extreme upside, but may not create immediate downside in the near term. As long as the KOSPI keeps rising, NPS allocation pressure will gradually increase; as long as policy allows a larger buffer, its market impact can be delayed and smoothed. Investors need to watch whether policy allows the NPS to avoid mechanical selling during volatile phases. Looking only at the target number can easily lead to a misread of selling pressure.
8. The Impact of Won Appreciation on Equity Structure: Winners May Shift from Export Leaders to Domestic Demand and Financials
If the won appreciates moderately, the impact at the equity level will diverge. The sensitivities listed in the report show that when the won appreciates 5% against the US dollar, banks, telecoms, utilities, and some healthcare companies may benefit; while export-oriented IT, autos, batteries, industrials, and energy companies may see a 5%-15% negative impact on operating profit. This conclusion is important because the Korean market’s biggest gainers in the first half were precisely semiconductors and export chains that are more sensitive to won appreciation.
This does not mean won appreciation will necessarily interrupt the tech bull market. The main semiconductor story remains AI demand, the memory cycle, pricing leverage, and capital expenditure. But if the won recovers from an extremely weak level, the market will recalculate exporters’ margins, especially for companies that have already risen sharply. The faster the won appreciates, the more easily it becomes a reason for short-term valuation digestion in chips and autos.
By contrast, financial and domestic-demand assets may become more important at this stage. Banks benefit from higher rates and won stability; telecoms and some healthcare companies have a more positive exchange-rate profile; industrials and defense benefit from Korean capital market reform, energy security, and overseas order logic. Morgan Stanley’s sector ranking still keeps industrials and IT as core overweights, while using healthcare and financials as a barbell. The logic is to capture both the AI export theme and domestic-demand/financial elasticity under won repair.
Therefore, the core question for the KOSPI in the second half will shift from “can it keep rising?” to “who rises?” If gains remain concentrated in a few AI and memory stocks, foreign rebalancing, won appreciation, and valuation fatigue will all weigh on these shares. If gains broaden into financials, industrials, defense, healthcare, and premium consumption, the KOSPI can continue rising at the index level while reducing reliance on a single narrative.
9. Four Variables to Watch Next
First, watch corporate FX conversion. August tax payments, dollar repatriation by semiconductor companies, and domestic capex are the key short-term indicators for won repair. If corporate foreign-currency deposits continue to decline, it means export dollars are truly starting to flow into the domestic financial system. Conversely, if the trade surplus keeps expanding but foreign-currency deposits also keep rising, the won’s appreciation room will remain constrained.
Second, watch whether foreign selling pressure slows. The focus is whether selling intensity can fall from the highs of May and June; there is no need to wait for foreign investors to resume large-scale buying of Korea. In particular, watch whether stocks beyond Samsung Electronics and SK Hynix can attract capital. If foreign selling mainly comes from chip rebalancing and other sectors begin to receive inflows, the quality of the KOSPI rally will improve.
Third, watch the Bank of Korea’s July meeting. If the central bank raises rates as expected and sends a sustained hawkish signal, the won will gain interest-rate differential support. But if the central bank communicates softly because of real estate, consumption, or financial stability risks, the market will again question the length of the hiking cycle. Rate expectations are already not low; the central bank needs to provide enough confirmation.
Fourth, watch retail leverage and overseas allocation. Whether the KOSPI can hold 9,000 depends largely on whether domestic retail capital can shift from “short-term trading money” to “structural asset-allocation capital.” If leveraged ETFs overheat, regulation tightens, or a market pullback causes retail investors to withdraw, KOSPI volatility will increase. Conversely, if Korean households’ equity allocation continues to rise and sector breadth improves, domestic capital will provide a more durable floor for the KOSPI.
The key areas for follow-up validation are FX conversion, selling pressure, the central bank, retail investors, and sector breadth.
X. Key Risks: The Cost of This Bull Market Is Already Becoming Visible
The first major risk is the AI capex cycle. The core drivers of this Korean equity rally have been AI and memory. If data-center construction is delayed, AI investment returns are questioned, or memory price increases damage demand for PCs, smartphones, and consumer electronics, the earnings-upgrade cycle for Korea’s IT sector will be reassessed. Because index gains and foreign rebalancing pressure are both concentrated in semiconductors, any weakening in the AI narrative would make KOSPI more prone than other markets to amplified volatility.
The second major risk is policy execution. Korea’s capital-market and corporate-governance reforms are an important pillar of KOSPI’s re-rating. If the reform agenda fails to move forward, the market will reapply a discount to Korean assets. For foreign investors, once Korea shifts from a low-valuation market to a high-weight market, institutional improvement becomes more necessary; otherwise, higher valuations and higher volatility will reduce the risk-reward.
The third major risk is geopolitics. Korean assets are sensitive to the regional security environment. Any escalation in Asia-Pacific tensions could push risk premiums higher. This risk may not necessarily change corporate earnings, but it would change the valuation multiple foreign investors are willing to assign to the Korean market and would also increase demand for the U.S. dollar.
The fourth major risk is domestic demand and real estate. A large share of Korea’s current growth comes from exports and semiconductors. If domestic consumption recovers less than expected, Seoul real estate declines materially, and risks rise around construction-company bankruptcies and retail-loan defaults, the central bank’s room to raise rates and the government’s room for fiscal expansion will both be constrained. At that point, the interest-rate support for the won and the domestic-liquidity support for KOSPI would both weaken.
The fifth major risk is a retreat in retail money. Retail buying was very strong in 1H26, but it included leveraged ETFs and high-risk-appetite components. If the market suffers a drawdown of more than 20%, or regulators tighten rules on margin financing and leverage products, retail investors could shift from a stable source of incremental capital into an amplifier of volatility. KOSPI would then face a drawdown faster than fundamentals would imply.
XI. Conclusion: Korean Assets Are Not Done, but the Trade Has Become Harder
The core opportunity in Korean assets remains intact. Exports, growth, central-bank policy, and equity-market earnings are all stronger than in 2025. The won is still weak after a mismatch between fundamentals and capital flows, and KOSPI still has upside represented by the 9,000-point target. But this trade has already moved from “buy Korea’s recovery” to “decompose Korea’s capital flows,” and the difficulty has clearly increased.
The opportunity in the won is that corporate FX conversion and central-bank rate hikes can help it recover from excessive weakness; the constraint is that foreign equity selling and domestic capital outflows will cap the scale of appreciation. The opportunity in KOSPI is that the AI semiconductor cycle, capital-market reform, and domestic asset-allocation migration are still in place; the constraint is that the index has risen too quickly, foreign positioning is too full, retail leverage is too hot, and the rally must broaden into more sectors to reduce fragility.
Therefore, the best scenario for Korean assets requires three moderate shifts to occur at the same time: corporates begin converting FX, foreign selling pressure declines, and KOSPI’s market breadth expands. If these three things happen, the won can move from being a weak currency to a recovery currency, and KOSPI 9,000 would look more like a midpoint than a ceiling. Conversely, if the AI narrative cools, corporates continue to hold FX, foreign investors keep selling semiconductors, and retail leverage retreats, Korean assets will return to the awkward state of “very strong fundamentals, but prices struggle to rise.”