
Kioxia Earnings Deep Dive: Q1 Net Income Misses Expectations, 5.5% Share Buyback, and How to Value the NAND Peak
目录
TL;DR
1. Reconciling the “Miss” With “All Guidance Metrics Exceeded”
2. ASP Rose Approximately 70%: This Quarter Was More a Pricing Cycle Than a Volume Cycle
3. Data Center and Enterprise Exceeded 60%: Mix Upgrade Matters More Than Total Revenue
4. Second-Quarter Profit Continues to Surge, but FX Tailwinds Must Be Valued Separately
5. Core Free Cash Flow of ¥827.2 Billion; Net Cash Turns Positive, but Collections Still Need Monitoring
6. ¥800.0 Billion Share Repurchase: Capital Allocation Is Substantial, but Execution Is What Counts
7. 3-for-1 Share Split and Equity Incentives: Trading Unit Changes Do Not Alter Enterprise Value
8. 2027 Supply-Demand Conditions and 2028 Long-Term Agreements Will Determine Whether Peak Earnings Become a Plateau
9. Pricing the NAND Peak: A Four-Layer Framework Is More Reliable Than a Point-in-Time P/E
10. The Seven Numbers That Actually Matter Next
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Kioxia’s first-quarter net income attributable to owners of the parent was 3.1% below its May outlook, although profit excluding specified items exceeded guidance. With average selling prices rising approximately 70% quarter on quarter and bit shipments growing only at a low-single-digit rate, the real questions are how long peak profitability can last and whether the ¥800 billion buyback can translate into per-share value.
TL;DR
The “net income miss” in the title refers specifically to IFRS net income attributable to owners of the parent. Kioxia Holdings (Tokyo Stock Exchange: 285A) reported FY2026 first-quarter IFRS net income attributable to owners of the parent of ¥842.2 billion, ¥26.8 billion, or 3.1%, below the company’s May outlook of ¥869.0 billion. Management’s statement that “all guidance metrics were exceeded” referred to non-GAAP net income of ¥887.0 billion, versus guidance of ¥870.0 billion. The 2 measures use different accounting bases and are not contradictory.
This quarter’s profit surge was driven primarily by pricing, not volume. Both blended ASP and like-for-like ASP in US dollar terms increased approximately 70% quarter on quarter, while bit shipments grew only at a low-single-digit percentage rate. The high fixed-cost structure of NAND manufacturing creates powerful operating leverage during price upcycles, but it also means margins will contract more rapidly once prices decline.
Data centers have become the key structural variable. SSD and storage revenue reached ¥1.1747 trillion, representing approximately 66% of total revenue. Within the segment, data center and enterprise applications accounted for more than 60%, while PC applications accounted for slightly less than 40%. Eighth-generation BiCS FLASH represented more than 50% of production, with an improved product mix and process migration jointly amplifying profitability.
Second-quarter guidance indicates that the peak is still moving higher. The company expects revenue of ¥2.39 trillion, IFRS operating profit of ¥1.89 trillion, and net income attributable to owners of the parent of ¥1.27 trillion, representing sequential growth of 35.2%, 48.8%, and 50.8%, respectively. However, the guidance assumes an exchange rate of ¥162 per US dollar; each ¥1 movement is expected to affect quarterly revenue and operating profit by approximately ¥14.0 billion and ¥13.0 billion, respectively.
Cash flow and the capital structure have undergone a fundamental shift. First-quarter operating cash flow was ¥866.3 billion, company-defined core free cash flow was ¥827.2 billion, and company-defined net cash at quarter-end was ¥186.7 billion. High profitability provides the foundation for the buyback, but the increase in accounts receivable still consumed ¥472.1 billion of operating cash flow, and the quality of cash collection should not be overlooked.
The 5.5% buyback is a ceiling, not a completed transaction. The company may repurchase up to 30 million shares for no more than ¥800.0 billion during the period from August 3 to October 30, 2026. If completed in full and the shares remain in treasury, EPS would increase mechanically by approximately 5.8%. If insufficient shares are tendered, the average purchase price is too high, or the buyback crowds out necessary investment, the value created will be reduced.
The NAND peak should be valued based on “price level × plateau duration × cash conversion.” The company expects demand to exceed supply in calendar 2027 and is working toward having long-term agreements with key customers cover 50% of sales volume in calendar 2028. These expectations may help extend the profit plateau, but they remain management forecasts; second-quarter profit should not simply be annualized.
1. Reconciling the “Miss” With “All Guidance Metrics Exceeded”
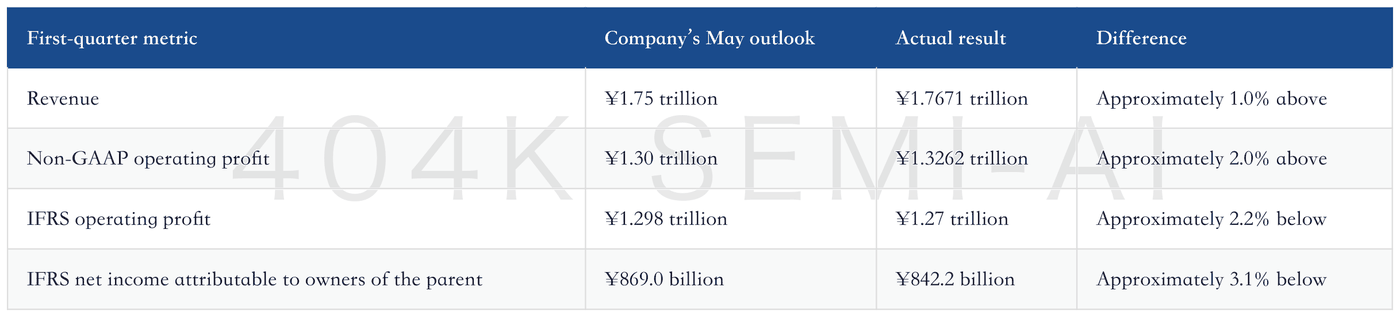
Kioxia’s May outlook for the first quarter called for revenue of ¥1.75 trillion, non-GAAP operating profit of ¥1.30 trillion, IFRS operating profit of ¥1.298 trillion, and IFRS net income attributable to owners of the parent of ¥869.0 billion. Actual results reported on July 31 were ¥1.7671 trillion, ¥1.3262 trillion, ¥1.27 trillion, and ¥842.2 billion, respectively.
First-quarter reported profit fell below initial guidance, while core operating profit exceeded it.
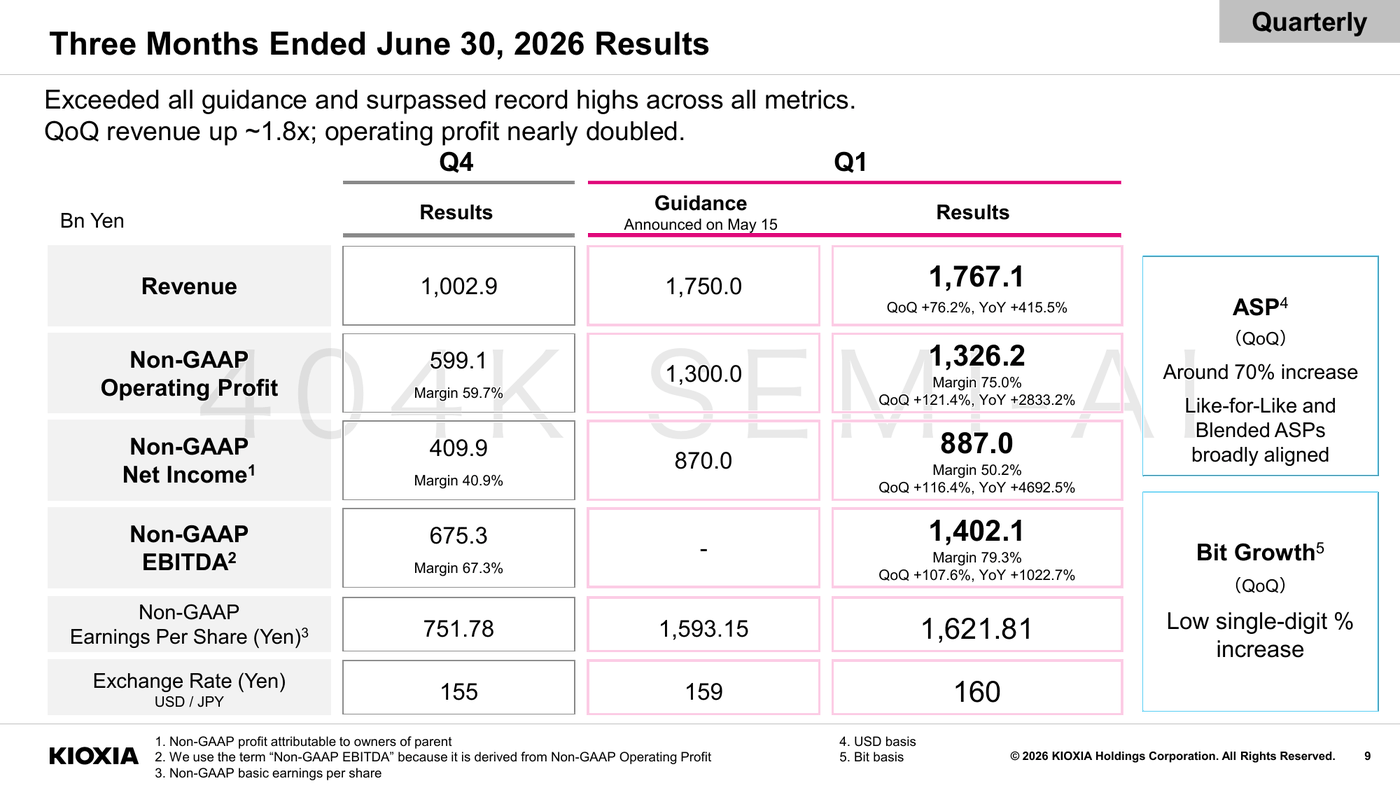
Page 9 of the earnings presentation states that “all guidance metrics were exceeded” because the chart compares revenue, non-GAAP operating profit, non-GAAP net income attributable to owners of the parent, and non-GAAP EPS. Non-GAAP net income attributable to owners of the parent was ¥887.0 billion, indeed above guidance of ¥870.0 billion. The “miss” in the title compares IFRS net income attributable to owners of the parent with the company’s May IFRS outlook. There is no factual conflict as long as the 2 profit measures are not conflated.
The ¥56.2 billion difference between IFRS and non-GAAP operating profit was almost entirely attributable to a ¥36.6 billion provision for litigation losses, ¥19.4 billion of share-based compensation expense, and ¥0.2 billion of purchase price allocation. This indicates that underlying operations were stronger than reported profit, but it does not mean the adjustments can be ignored permanently: litigation provisions affect returns to shareholders, while share-based compensation is also a real economic cost. Even after including all these items, the first-quarter IFRS operating margin was still 71.9%, while the adjusted non-GAAP operating margin was 75.0%, leaving the strength of profitability intact.
The first conclusion is that core operations exceeded initial guidance, while IFRS profit was reduced by one-off and specified costs. The ¥26.8 billion net income shortfall did not alter the strength of the core business; the next step is to assess the volume and pricing sources of profit and their sustainability.
2. ASP Rose Approximately 70%: This Quarter Was More a Pricing Cycle Than a Volume Cycle
First-quarter revenue increased 76.2% from ¥1.0029 trillion in the previous quarter, while IFRS operating profit rose from ¥596.8 billion to ¥1.27 trillion and net income attributable to owners of the parent increased from ¥407.7 billion to ¥842.2 billion. Revenue increased by ¥764.3 billion and operating profit by ¥673.2 billion, implying an exceptionally high conversion of incremental revenue into profit.
The earnings presentation provided the most important breakdown: in US dollar terms, both blended ASP and like-for-like ASP increased approximately 70% quarter on quarter, while bit shipments grew only at a low-single-digit percentage rate. The primary reason revenue nearly doubled was the sharp increase in unit prices; the factories did not sell nearly twice as many bits within a single quarter. The average US dollar-yen exchange rate also rose from ¥155 in the previous quarter to ¥160, further amplifying reported revenue and profit in yen terms.
This is also the source of operating leverage in NAND cycle stocks. Wafer-fab, R&D;, depreciation, and personnel costs are relatively fixed in the short term, so when selling prices rise, a high proportion of incremental revenue can flow through to gross profit. The first-quarter IFRS gross margin therefore reached 78.1%, while the adjusted non-GAAP gross margin excluding joint-venture-related items reached 82%. Conversely, once customer inventory replenishment ends and spot and long-term contract prices weaken, lower unit prices will directly compress profit, while capacity costs will not disappear in parallel.
