
Kioxia Deep-Dive Update: Goldman Sachs Raises Target Price to JPY116,000; How NAND Tightness Revalues the AI Storage Cycle
目录
Too Long; Didn’t Read
1. The Key Point of This Update: Goldman Sachs Completes the “Middle Bull” Case
2. The Underlying Assumption Behind Goldman Sachs’ Revision: Prices Stay High for Longer Than Previously Expected
III. Margin Re-Rating: Kioxia’s Most Attractive Feature Is Also Its Most Dangerous
IV. Why NAND Supply Has Not Immediately Come Back
V. What AI Inference Brings Kioxia Is Not a Capacity Story, but a System Bottleneck Story
VI. LTAs Are the First Gate for Whether Valuation Can Move Up a Level
7. Sell-Side Dispersion: ¥116,000 Sits in a Reasonable Position Between Bull and Bear Cases
8. Cash Flow and Balance Sheet: From Debt Pressure to Return Optionality
9. Risk Framework: The Real Test for Kioxia Comes After CY2028
10. How to Validate Over the Next Four Quarters
11. Placing Kioxia in the Storage Chain: It Is Not the Same NAND Beta
12. Core Model: From Price Trading to Profit Capitalization
13. Tracking Checklist: Four Tables to Watch After the Target Price
14. Investment Conclusion: Kioxia Is No Longer Cheap, But Still Has a Verifiable Upside Path
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Goldman Sachs raised its target price for Kioxia to JPY116,000. This is not the most aggressive bull case, but it clearly lays out the middle path for NAND revaluation: AI demand is still pulling eSSD, DRAM-prioritized capacity expansion is constraining NAND supply, and elevated pricing and margins may last longer than the market previously expected.
Too Long; Didn’t Read
Goldman Sachs has completed the mid-range bull framework. The core of the latest target-price increase is not a one-off price hike, but an upward reset of the entire future profit curve. Goldman Sachs shifts the high-margin cycle from a shortage trade to a cash-flow judgment, offering a verifiable price between JPM’s aggressive bull case and Bernstein’s bear case.
NAND tightness is still being extended. Goldman Sachs continues to raise ASP assumptions, while equipment-channel checks show that major memory makers are still prioritizing DRAM/HBM investment. Incremental new NAND capacity is more likely to arrive with a lag, pushing the price peak further out and lengthening Kioxia’s earnings window.
Kioxia’s profit leverage is extreme. In Goldman Sachs’ model, operating margins enter unusually high territory, while revenue, profit, and net cash all expand in parallel. If pricing, BiCS cost reductions, and the eSSD mix all materialize, the traditional low P/E becomes a cash-flow discount; if the pricing slope weakens, the low P/E turns back into a peak-earnings trap.
Goldman Sachs is not the most aggressive bull. JPM is betting on LTAs, shareholder returns, and higher valuation multiples, while UBS is betting on longer contracts and AI-agent long-context demand. Goldman Sachs is closer to the middle answer: it acknowledges that NAND remains cyclical, but argues peak profits are higher and will last longer.
The bear-case challenge remains valuable. Bernstein’s framework reminds investors that if LTAs do not have sufficient price floors and default costs, customers may still renegotiate when prices fall. Longer-term capacity from China NAND, Micron’s Singapore expansion, Samsung, and SK hynix could all compress long-term gross margins.
Valuation depends on several gates. First, watch whether ASPs in the latest quarter can keep beating guidance; then watch whether LTA coverage and pricing terms become tougher; finally, watch whether cash flow actually returns to shareholders. If any key gate breaks, the low P/E will revert to a peak-earnings trap.
The conclusion is to hold through the validation period. Kioxia has moved from an ordinary NAND price-hike stock to the edge of being an AI inference storage asset, but it has not fully escaped its cyclical identity. The target price is reasonable only if high profits can last until supply recovers, and if subsequent capacity expansion does not get out of control.
1. The Key Point of This Update: Goldman Sachs Completes the “Middle Bull” Case
This round of Kioxia revaluation is easy to misread as a simple NAND price-hike trade.
Prices rose, the target price was raised, the stock has already surged, and the market continues to chase the shortage. That line of reasoning is valid, but it does not explain why several investment banks rewrote their models intensively in June, nor why target prices now range so widely from JPY40,000 to JPY155,000.
The value of Goldman Sachs’ June 30 update is that it provides a non-extreme but very clear middle bull framework. It does not push Kioxia straight to JPY155,000 like JPM, nor does it maintain a long-term bearish stance like Bernstein. Its judgment is more restrained: the NAND market structure has not completely changed, and cyclicality remains; but AI demand, DRAM-prioritized capacity expansion, eSSD, and BiCS cost reductions together raise the profit peak over the next 2-3 years and extend its duration.
That is what the JPY116,000 target price means. It is not “Kioxia should be valued as a perpetual growth stock,” but rather “the traditional cyclical discount needs to be reduced.” If FY3/27-FY3/29 profits are not just one or two quarters of windfall earnings, but a higher-visibility cash-flow window, then roughly 8x FY3/28E P/E is not excessive.
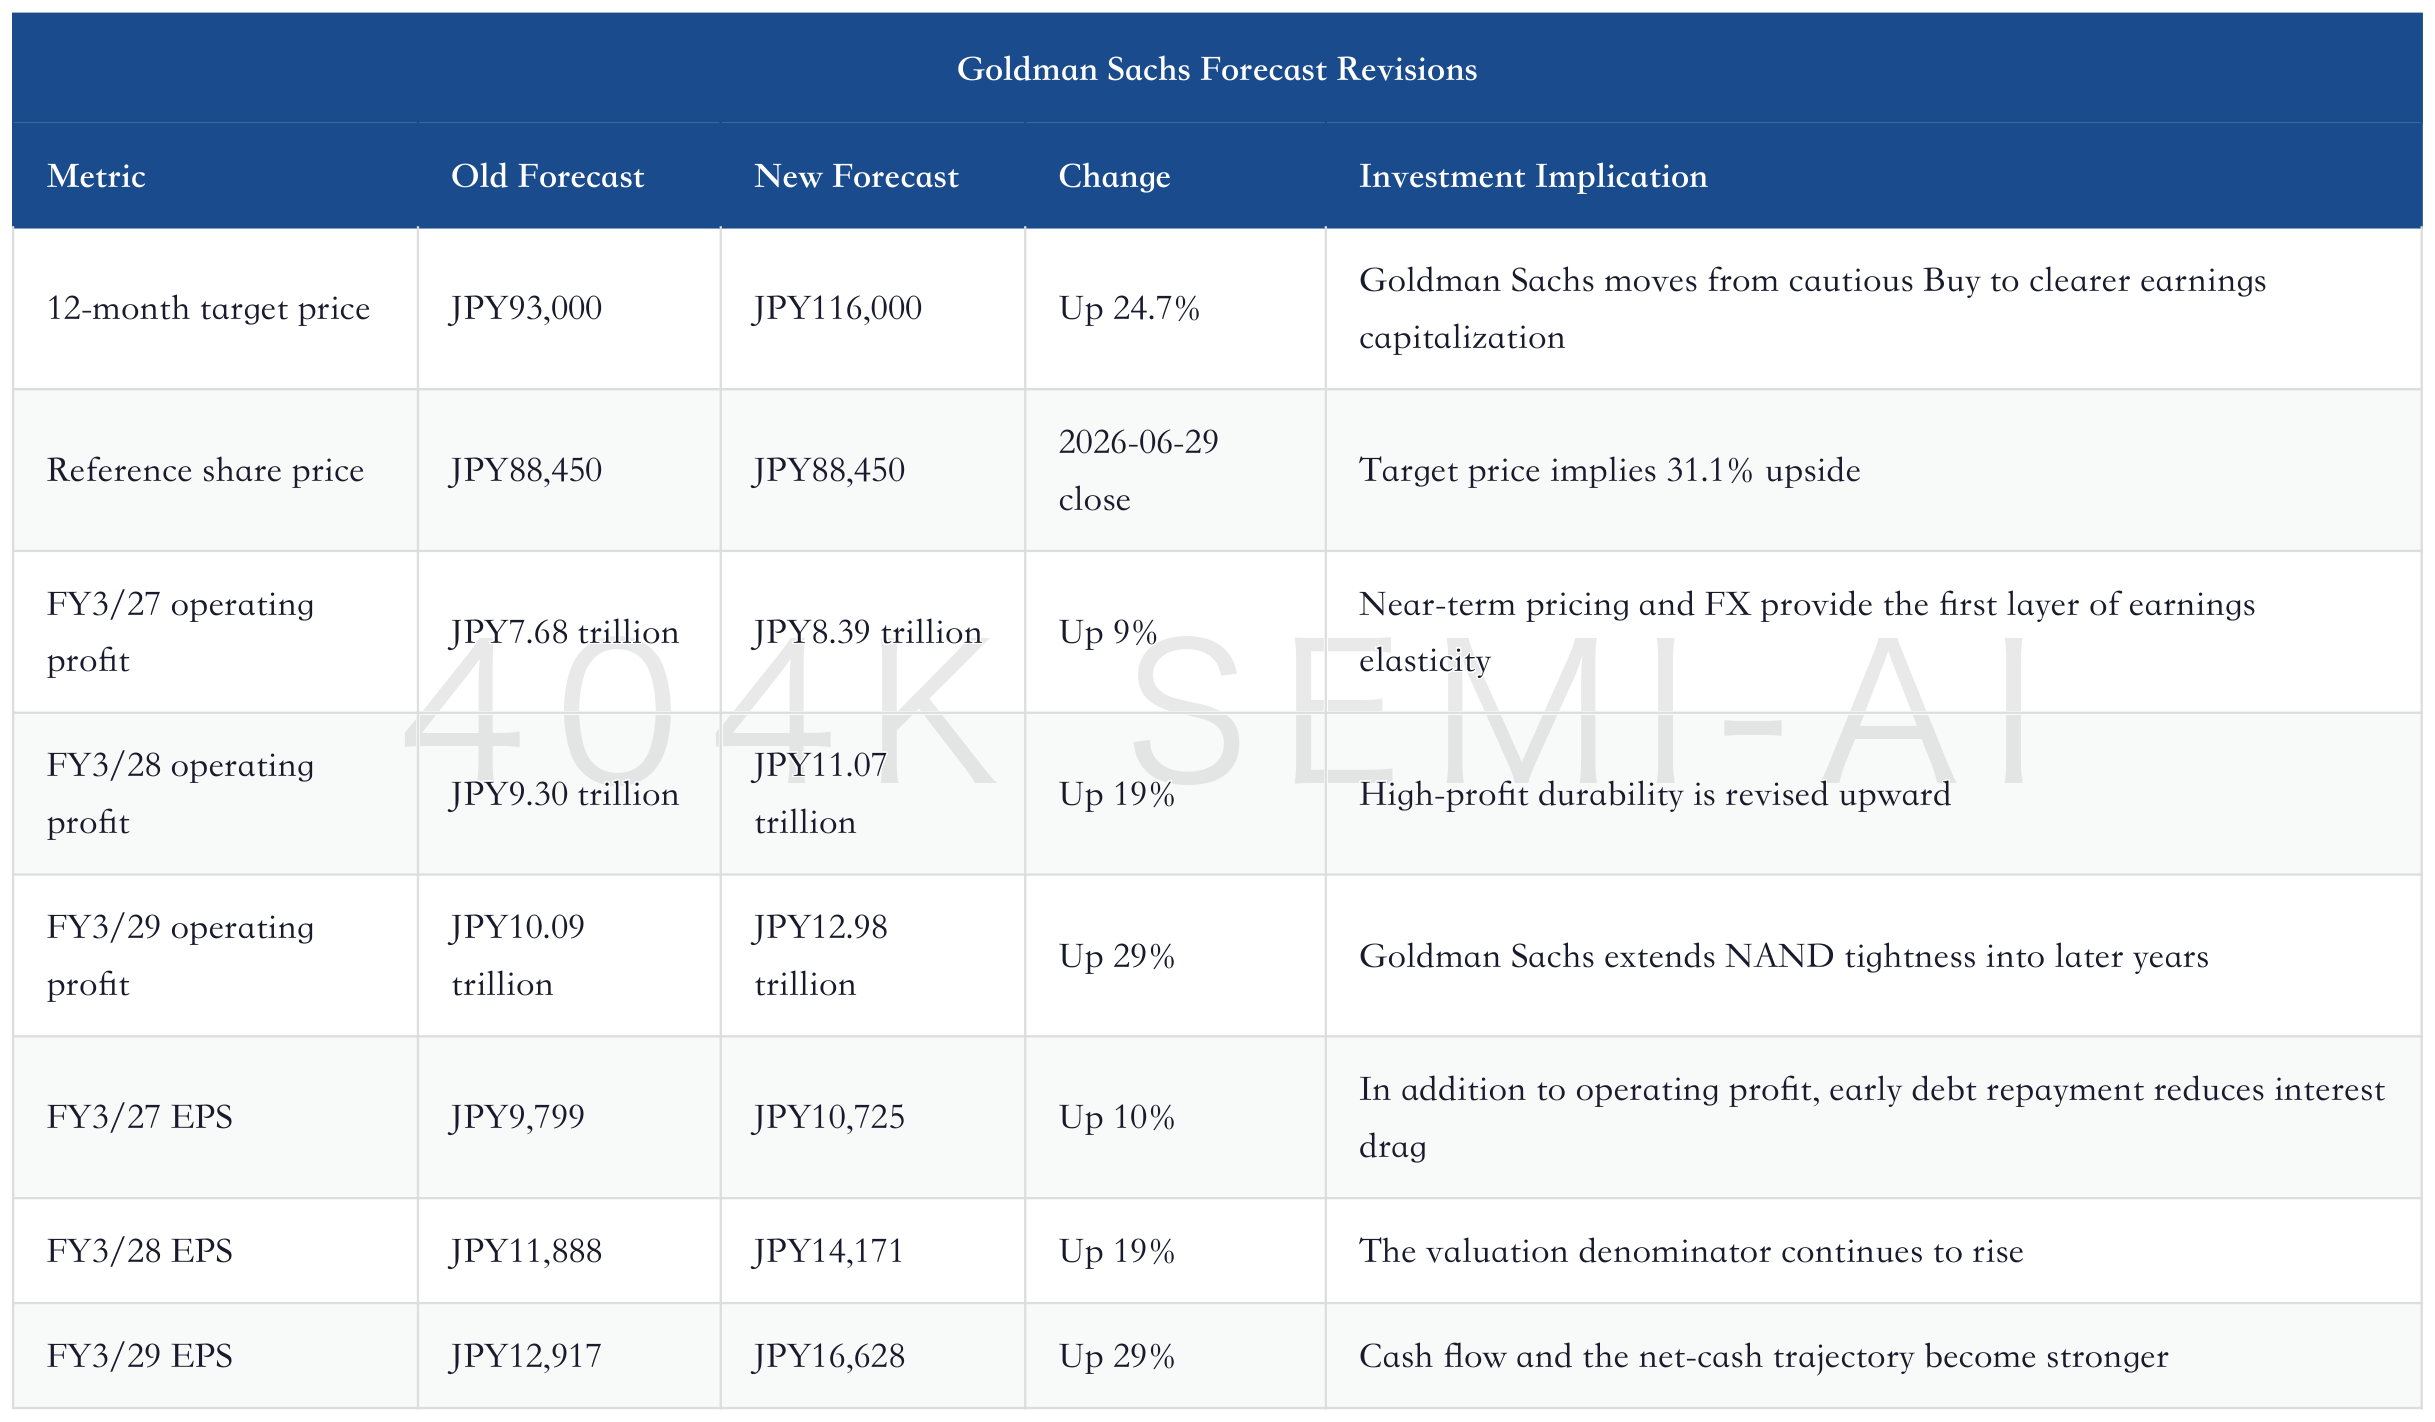
The most important point in this table is not the target price itself, but the slope of the revisions. FY3/27 is revised up 9%, while FY3/29 is revised up 29%. This shows Goldman Sachs is not merely lifting June-quarter or September-quarter ASPs, but rewriting the duration of the NAND cycle.
Kioxia’s core tension now lies here: the income statement is so strong that traditional cyclical valuation starts to distort. Memory stocks often look very cheap at cycle peaks. A low P/E can mean undervaluation, or it can mean a peak trap. Goldman Sachs’ answer this time is that current profits still have cyclical characteristics, but they can no longer be simply discounted using the average of the previous NAND cycle.
Kioxia Deep-Dive Update: JPY155,000 Target Price, NAND Cash Flow, and AI SSD Revaluation
Earlier, JPM set the bull-case ceiling at JPY155,000, so the market already knows how the most optimistic story is told. Goldman Sachs’ update is more useful for judging “if investors do not underwrite the most aggressive scenario, can Kioxia still keep revaluing?” The answer is yes, but investors must watch four numbers: pricing, long-term agreements, capacity, and cash returns.
2. The Underlying Assumption Behind Goldman Sachs’ Revision: Prices Stay High for Longer Than Previously Expected
The first pillar behind Goldman Sachs’ target-price increase is NAND ASP.
It meaningfully raises ASP assumptions for both CY26 and CY27. These numbers are striking, but they are not invented from nothing. Kioxia already saw a sharp step-up in revenue and profit in FY3/26 Q4, and Goldman Sachs’ forecast for FY3/27 Q1 operating profit is above both company guidance and market consensus.
Goldman Sachs believes that when the company issued guidance, price negotiations for about 30% of June-quarter bit shipments had not yet been completed. In other words, if subsequent negotiated prices are stronger, Kioxia’s June-quarter ASP still has room to exceed guidance.
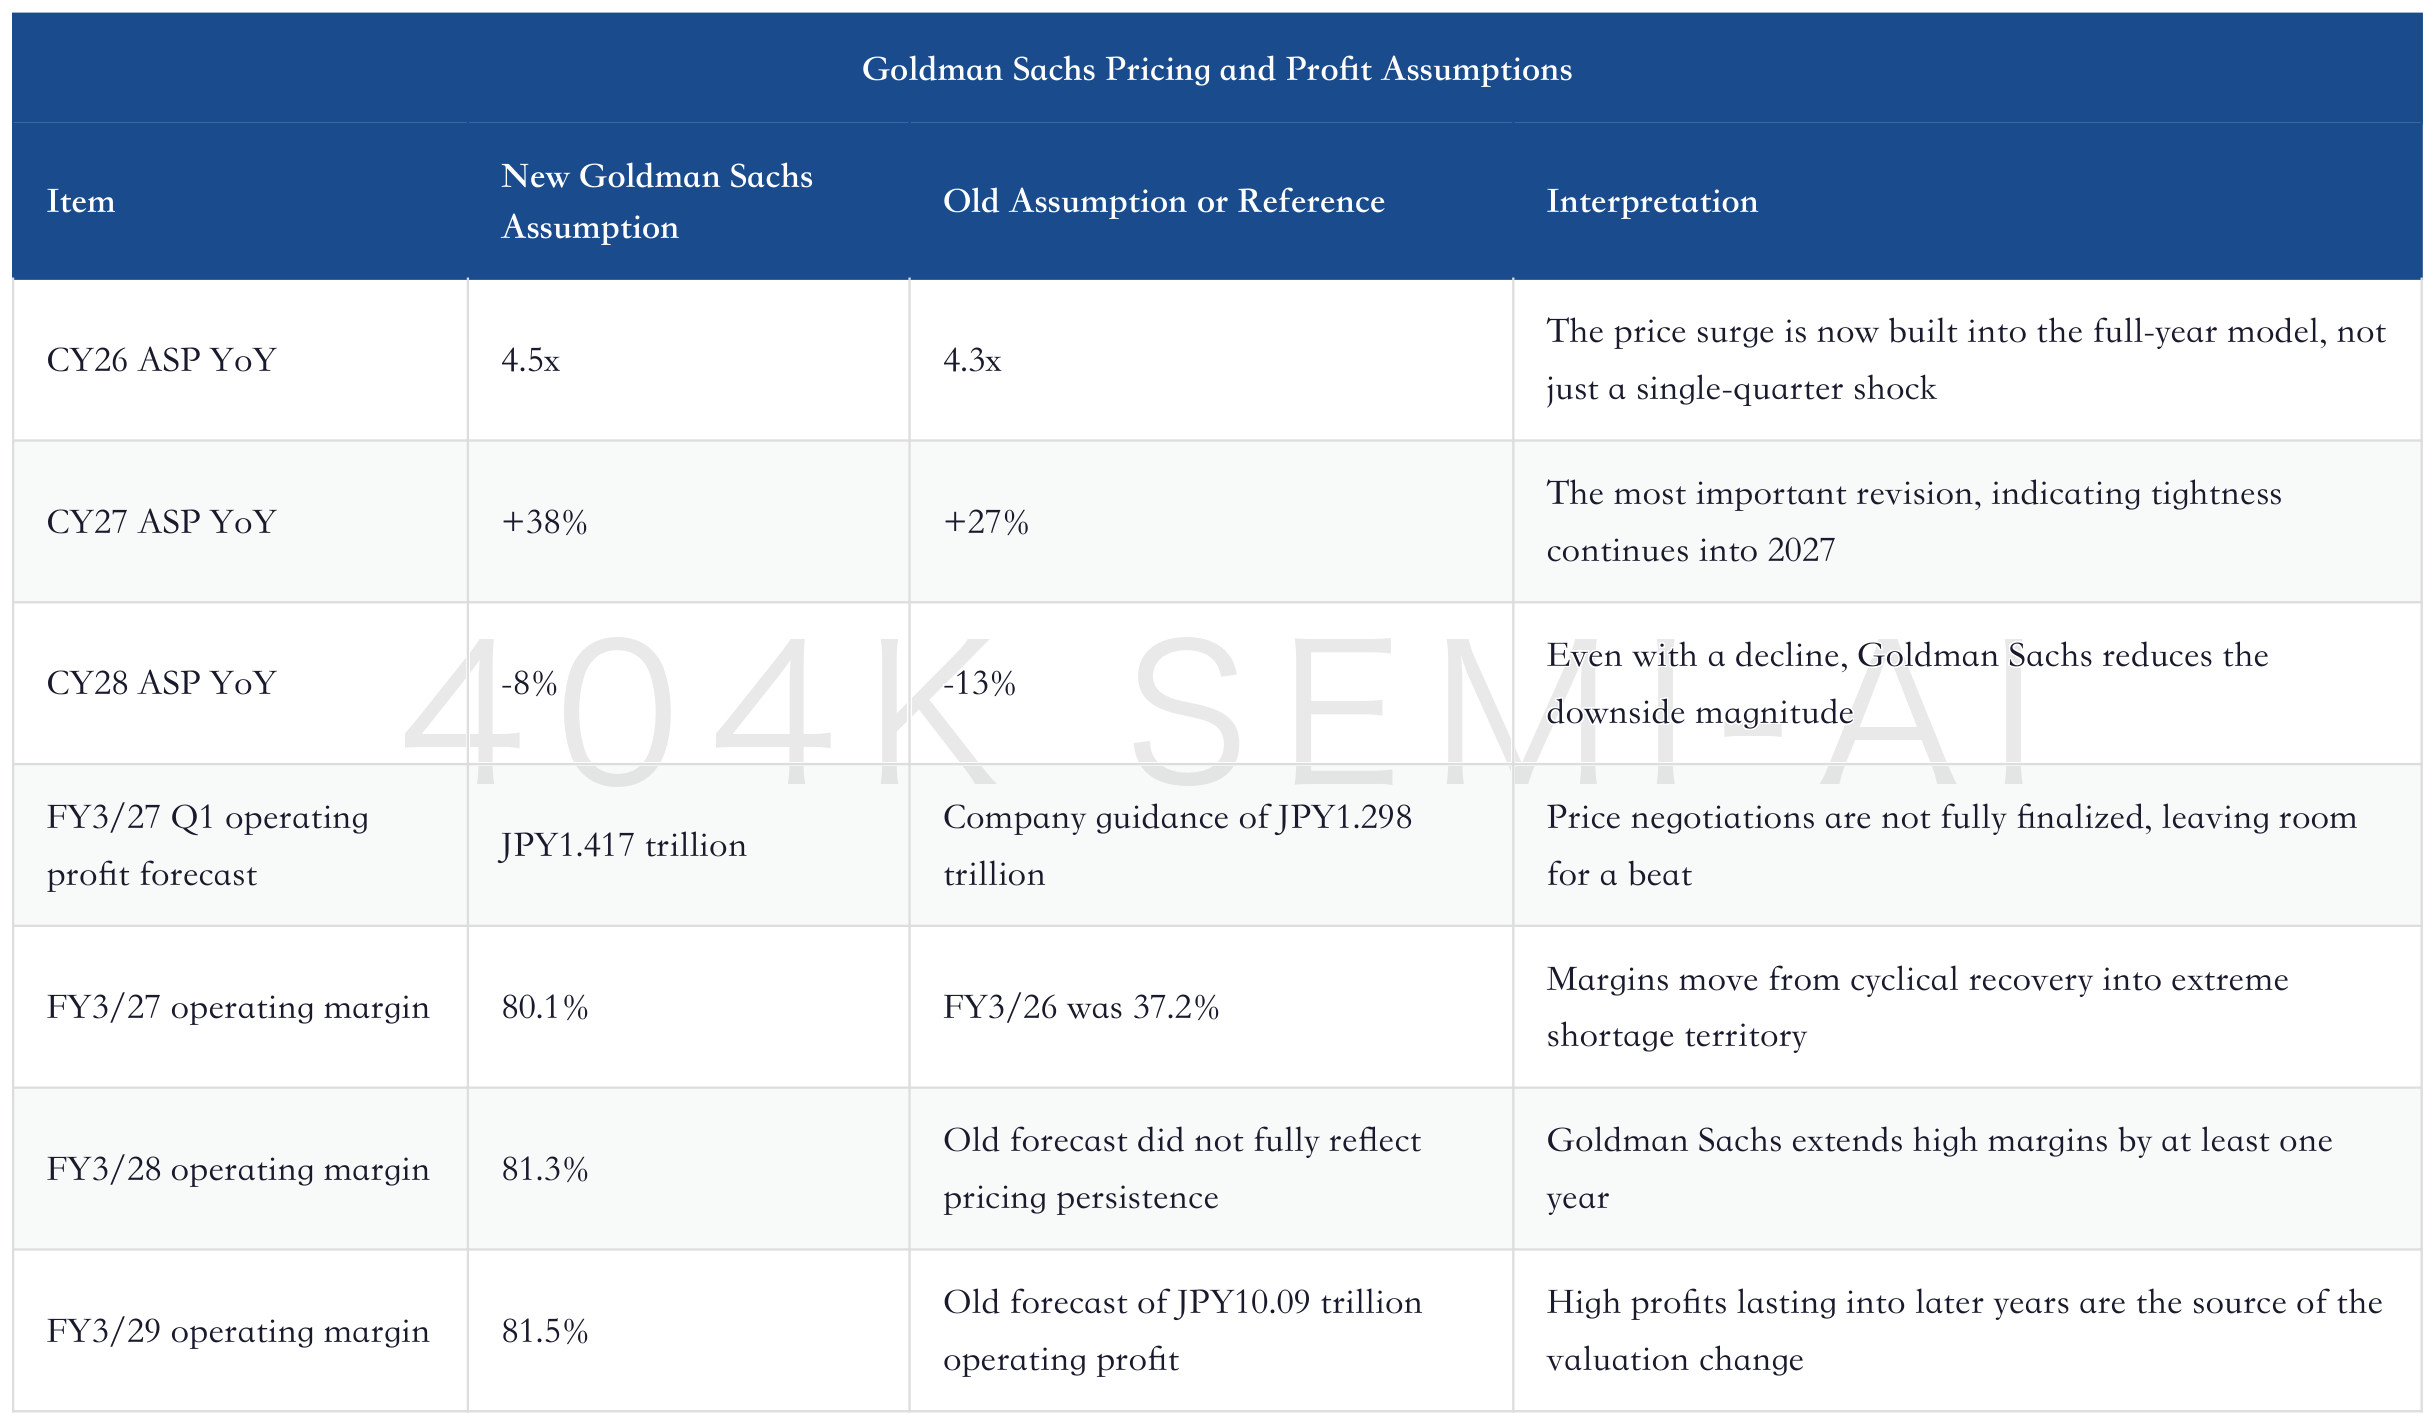
There are two industry judgments behind this.
First, AI data-center storage demand continues to exceed expectations. Enterprise SSDs are no longer just ordinary server components; they are part of AI inference, retrieval, vector databases, state data, and low-latency hot-data layers. HBM and DRAM provide bandwidth closest to the GPU, while NAND provides the higher-capacity, lower-cost, more persistent data layer. The longer inference workloads become and the more complex agent tasks get, the more frequently data moves between DRAM and SSDs.
Second, major memory makers are still prioritizing DRAM/HBM. Samsung, SK hynix, and Micron all have NAND capabilities, but higher-profit DRAM/HBM consumes cleanroom space, equipment, engineering teams, and customer-certification resources. Goldman Sachs’ equipment-channel checks indicate that major memory makers are still prioritizing DRAM investment in the near term, and new NAND capacity will not become more visible until CY28. If supply does not catch up immediately, pricing remains supported.
This is also why Kioxia and SanDisk have been repeatedly revalued in this cycle. They are purer NAND assets, and when prices rise, their profit elasticity is more direct than that of diversified memory makers. Samsung and SK hynix of course also benefit, but their share prices are more affected by HBM, DRAM, foundry, smartphones, and conglomerate discounts. Kioxia and SanDisk are more like high-beta expressions of NAND spot pricing and eSSD demand.
SanDisk Deep-Dive Update: Bernstein’s USD3,000 Target Price and How New Memory LTAs Rewrite the NAND Cycle Discount
The pricing assumptions also carry clear risks. NAND end customers are not all cloud providers; smartphones, PCs, consumer electronics, and module makers are more sensitive to price increases. High prices will force demand destruction, and will also trigger substitution, configuration downgrades, and inventory behavior. Goldman Sachs is willing to revise CY27 upward, but it does not describe NAND as a permanently scarce asset. That restraint is reasonable.
III. Margin Re-Rating: Kioxia’s Most Attractive Feature Is Also Its Most Dangerous
Kioxia’s most attractive number today is margin.
Goldman Sachs expects revenue and operating profit to keep expanding after FY3/27, with operating margin entering the 80%+ range. That level of profitability is extremely rare in traditional NAND history, and it is exactly what makes Kioxia’s valuation so compelling.
That level of profitability is extremely rare in traditional NAND history. It looks like shortage, mix, and cost all compressed into one window: prices surge, data-center and eSSD mix rises, BiCS 8 bits ramp drives cost reduction, while depreciation and capex do not expand sharply at the same time.
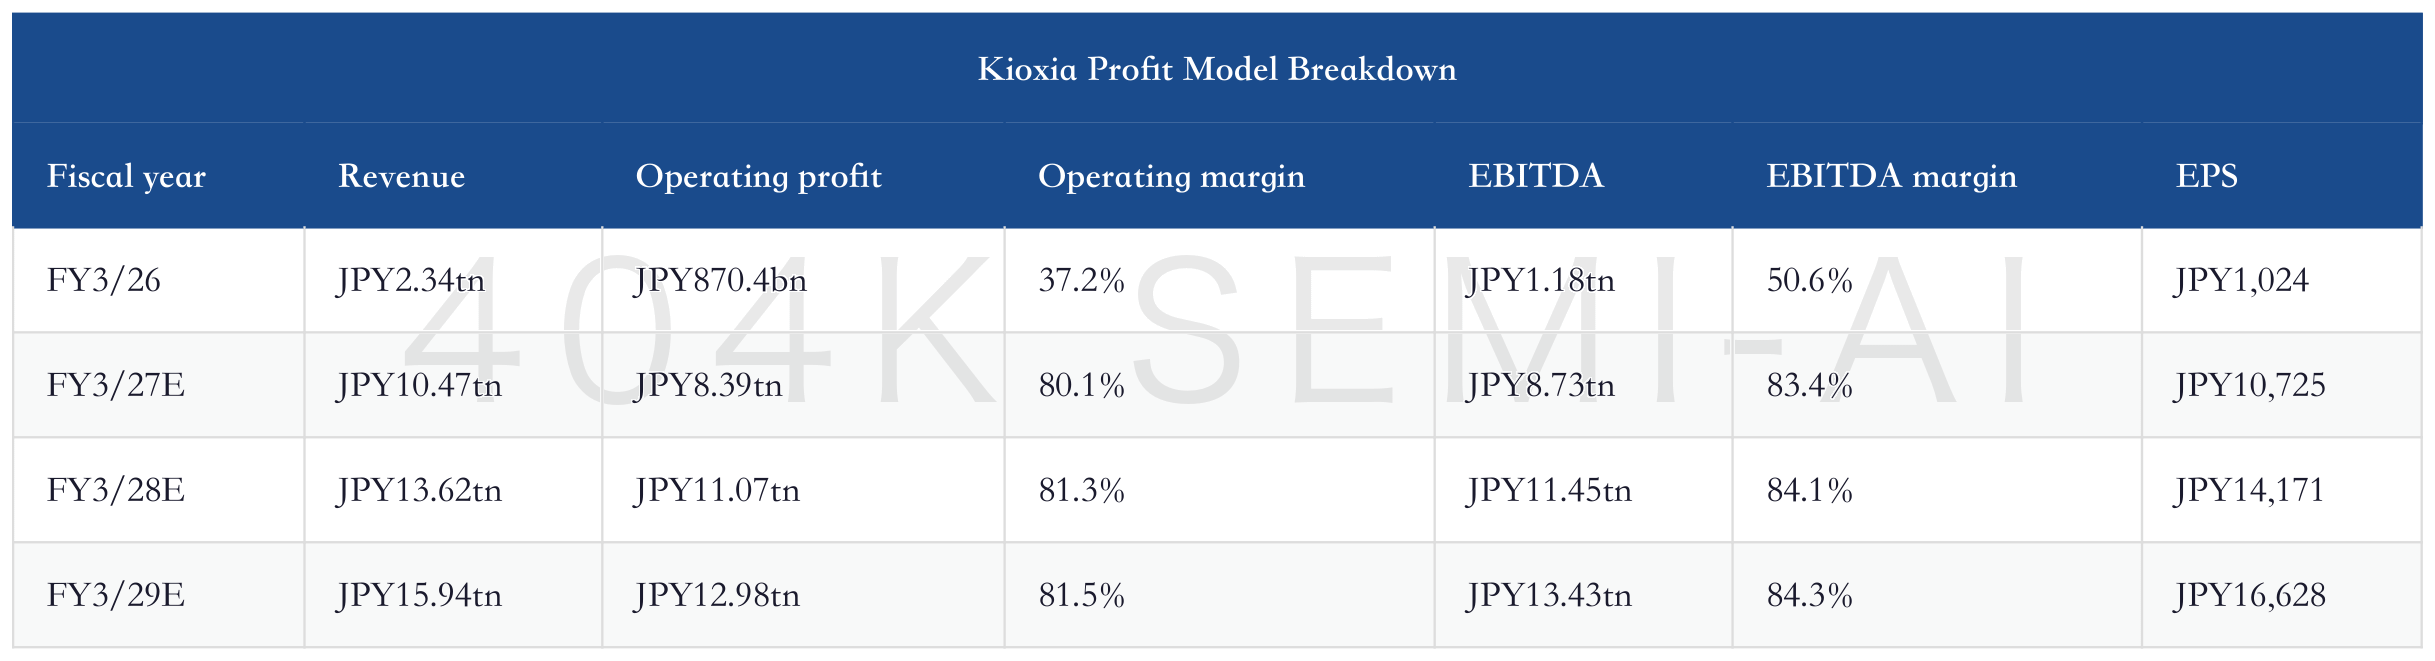
This table looks like “margins stay high forever,” but it should really be broken into three layers.
The first layer is price leverage. When NAND prices rise severalfold, incremental revenue almost flows directly into gross profit and operating profit. Fixed costs are diluted, inventory costs lag, and margins can be lifted quickly. The 80.1% operating margin in FY3/27 mainly comes from this layer.
The second layer is mix leverage. Enterprise SSDs, data-center SSDs, and AI inference-related products have higher price elasticity, customer stickiness, and service requirements than ordinary consumer NAND. As long as the eSSD mix continues to rise, Kioxia’s revenue quality improves. JPM’s bull case raises the eSSD sales mix from roughly 34% in FY2025 to about 67% in FY2028, which is why it is willing to assign a higher multiple.
The third layer is cost leverage. Kioxia’s eighth-generation BiCS has already entered the volume-ramp stage, while the subsequent tenth-generation BiCS should further improve bit density, power consumption, and cost efficiency. Rising prices and falling costs create a second-stage margin expansion. Goldman Sachs also attributes Kioxia’s higher margins versus peers to lower capital intensity and cost declines from expanded sales of eighth-generation BiCS bits.
The issue is that these three layers of leverage cannot all last equally long. Price leverage is the strongest and also the easiest to reverse; mix leverage is slower but more durable; cost leverage requires technology migration to materialize and will gradually be caught up by peers. The investment judgment should not treat an 80% operating margin as a permanent mid-cycle level, but instead assess how many quarters it can be sustained, whether it can extend beyond CY27, and whether the downside can hold a floor higher than the historical level.
Bernstein’s bear case captures exactly this point. It acknowledges strong near-term pricing, but argues that long-term repeatable profit should determine most of the valuation. If NAND supply catches up with demand after CY2028 and long-term gross margin returns to around 35%, the current share price is capitalizing too much peak profit. That judgment may not prove right immediately, but it is the most important counterargument for Kioxia.
So the core of this update is not “Kioxia’s margins are high,” but “Goldman Sachs is willing to let high margins persist for longer.” The valuation re-rating comes from duration, not from a single-quarter margin level itself.
IV. Why NAND Supply Has Not Immediately Come Back
Every memory cycle eventually reaches the same question: high prices bring high supply, and high supply kills high prices.
What Kioxia bulls now need to prove is not that NAND will never expand capacity, but that capacity expansion over the next 6-8 quarters cannot keep up with AI data-center demand. Goldman Sachs’ latest upward revision is built on this timing gap.
There are four sources of supply constraint.
First, DRAM/HBM has higher priority. When integrated memory makers allocate resources, they prioritize DRAM and HBM, which have higher margins, stronger customer lock-in, and higher qualification barriers. AI training and inference continue to push up demand for HBM, DDR5, and high-end DRAM, while cleanroom space and equipment capacity cannot be supplied infinitely at the same time. NAND therefore passively benefits from supply discipline.
Second, adding NAND wafers is not a switch. NAND capacity expansion requires cleanrooms, etch, deposition, inspection, yield ramp, and product qualification. Enterprise SSDs in particular must also go through long customer validation cycles. Even if a capacity decision is made today, it takes time before the product can actually be sold to cloud customers. Goldman Sachs believes new NAND fab supply additions are likely to become more visible only in CY28.
Third, Kioxia’s own capex is disciplined. Investor Day disclosures show the company guiding FY3/27 capex at about JPY450bn, and around JPY470bn after FY3/28. Spending is mainly for BiCS 8 and BiCS 10 equipment at the existing Yokkaichi Y7 and Kitakami K2 sites, plus some infrastructure. It is not suddenly building a large amount of new capacity at the price peak, but migrating technology and improving efficiency within existing fabs.
Fourth, HDD tightness is also helping NAND. AI data lakes, warm and cold data, archiving, and training-data retention are also pushing HDDs into shortage. HDD tightness itself will not shift all demand to NAND, but it raises the price floor across the overall storage hierarchy. Enterprise customers are reallocating budgets among HDDs, QLC SSDs, and TLC SSDs for availability and performance, giving NAND more room for premium pricing.
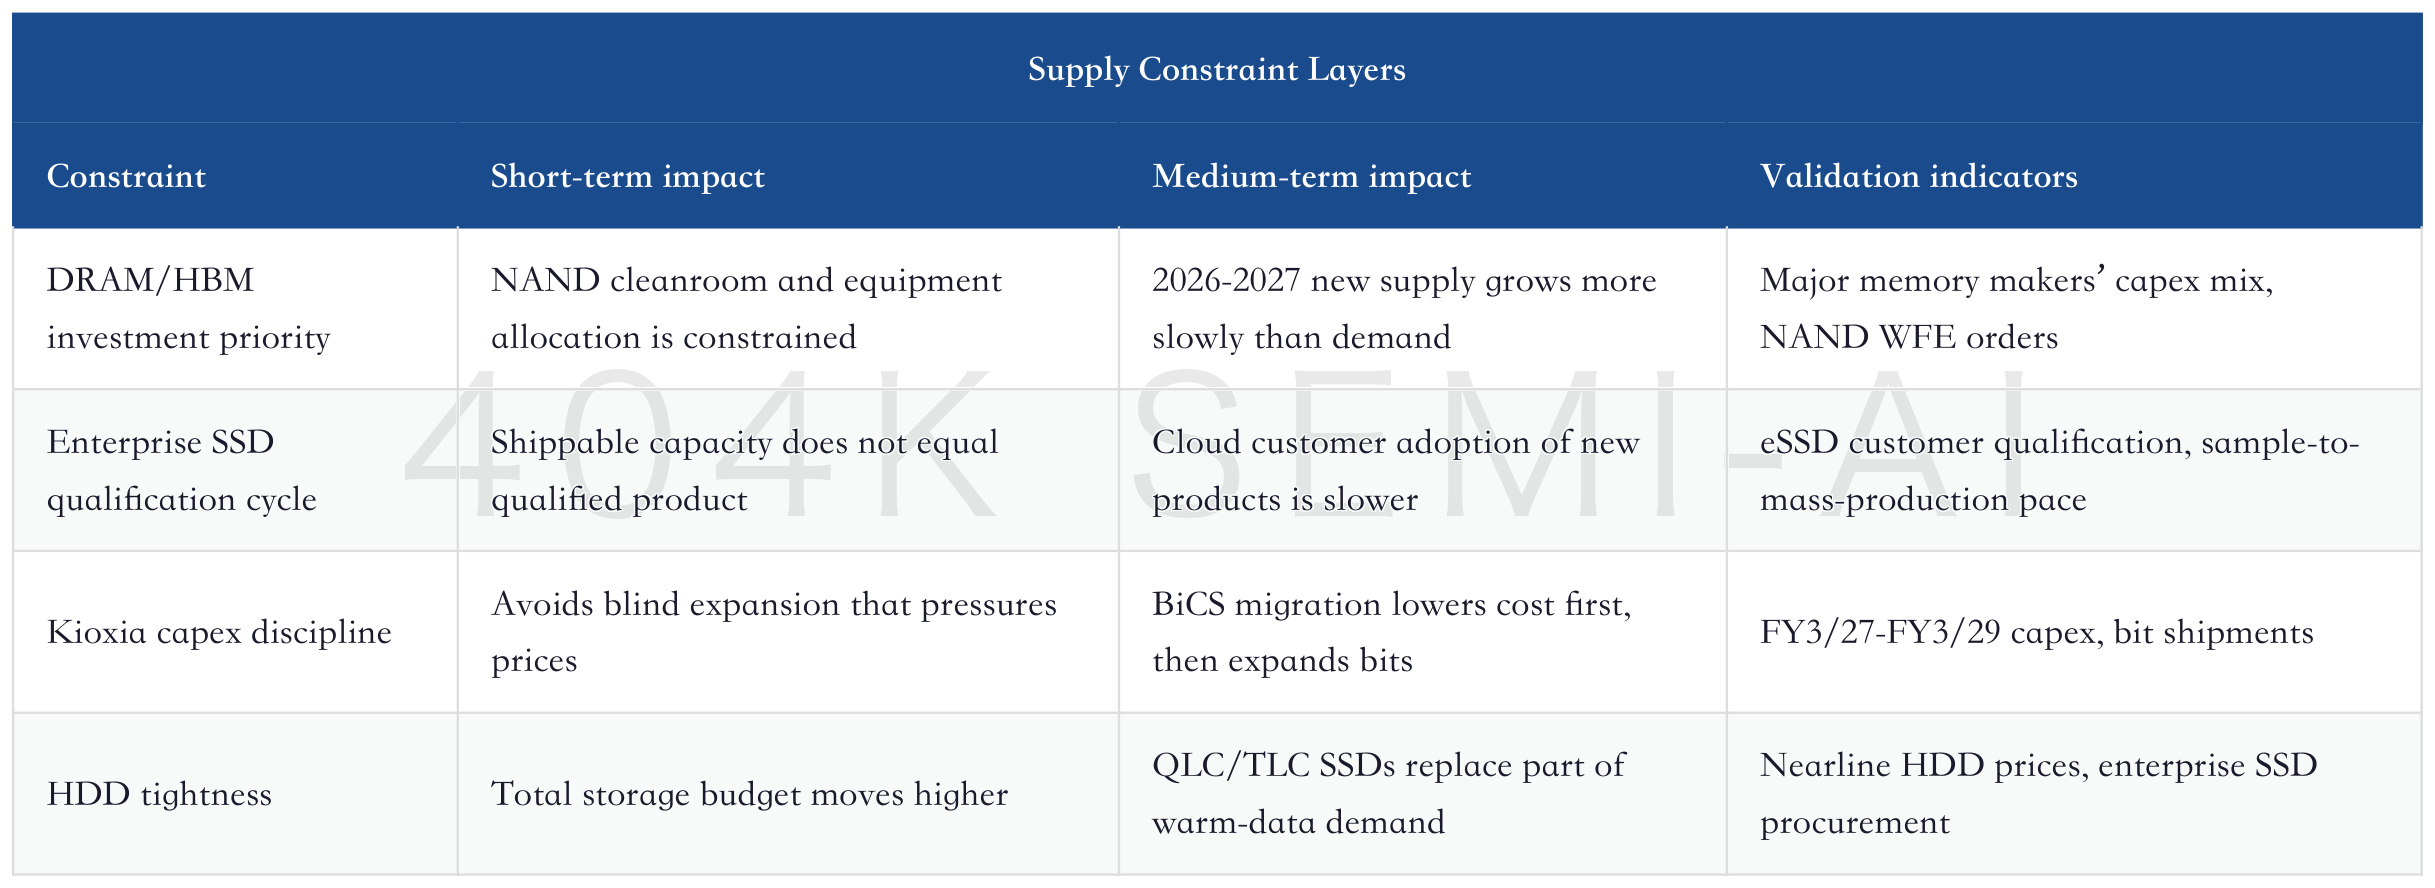
This framework gives Kioxia a very favorable window in 2026-2027. Demand is running ahead, supply is chasing from behind, and prices therefore will not collapse immediately.
But this window is not permanent. CY2028 is the year both bulls and bears are watching. Goldman Sachs believes new NAND supply becomes more visible only in CY28, so CY27 can still be revised upward; Bernstein believes prices will quickly return to normal once supply catches up in CY2028; UBS also warns that sequential price increases may gradually peak after the end of 2026. The difference is not direction, but slope.
The biggest risk for Kioxia investors is not that prices fall from high levels, but that the slope of supply normalization suddenly steepens. If new capacity is released in concentration in CY2028 and AI inference does not continue absorbing the incremental supply, an 80% operating margin will quickly become an outdated number.
V. What AI Inference Brings Kioxia Is Not a Capacity Story, but a System Bottleneck Story
For Kioxia to earn a higher valuation than traditional NAND, it must prove that SSDs are shifting from capacity devices into AI system devices.
Historically, NAND’s core question was “how much per GB.” Smartphones, PCs, and consumer electronics customers cut capacity, delay procurement, or draw down inventory when prices rise. This market is inherently highly cyclical, customers have strong bargaining power, and suppliers struggle to retain excess profits.
AI inference changes the question to “whether each retrieval, each state read, and each long-context task can avoid slowing down the GPU.” As GPUs become increasingly expensive, the system bottleneck is expanding from single-chip compute to memory, storage, networking, and power. SSDs are no longer just warehouses; they are components that affect utilization and TCO.
Kioxia’s Investor Day roadmap is built exactly around this direction.
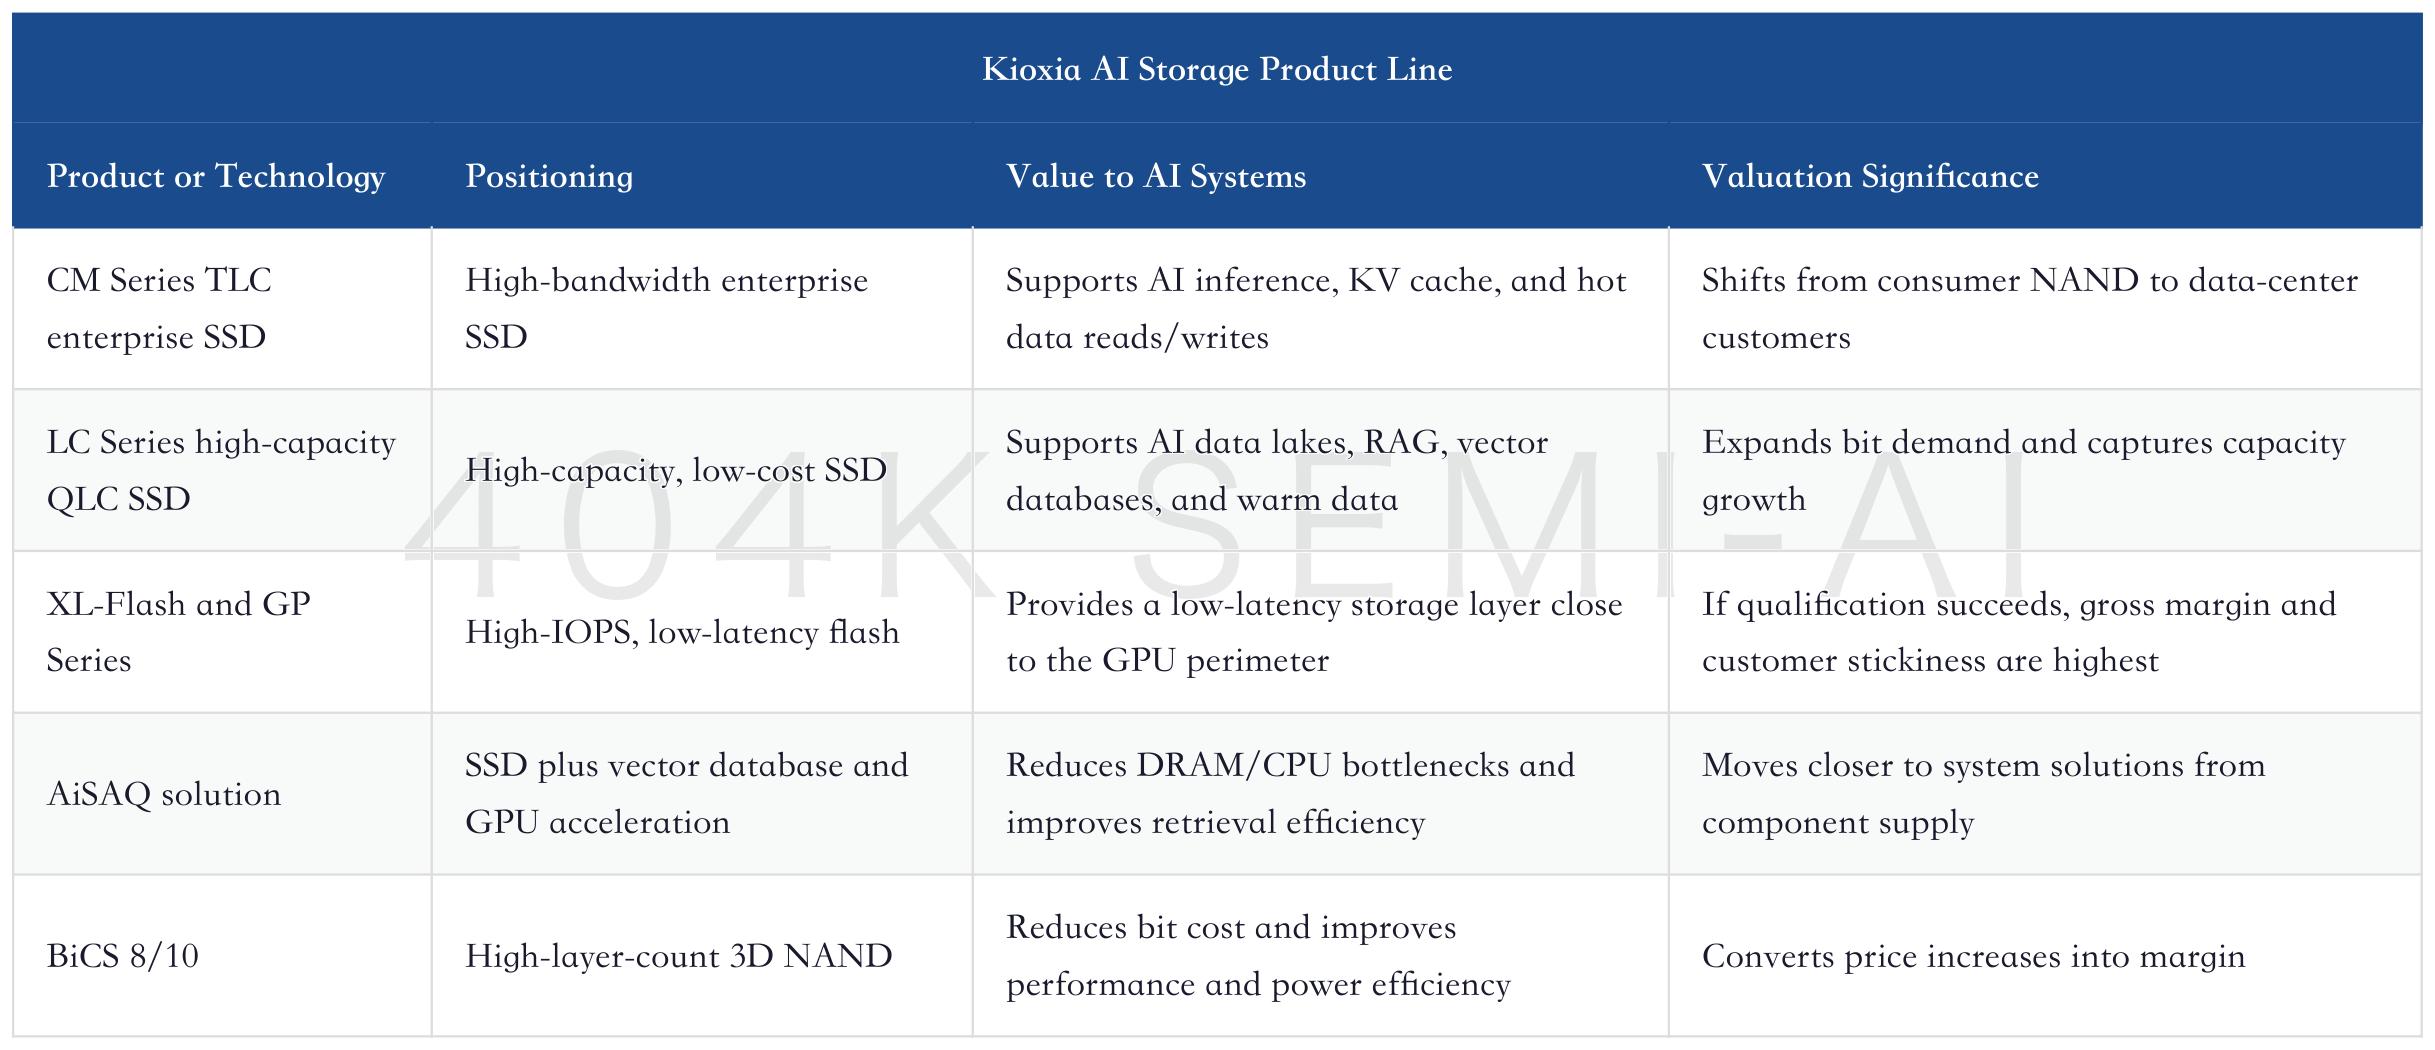
The most important parts of this roadmap are XL-Flash and high-IOPS SSDs. Goldman Sachs previously noted on a conference call that Kioxia plans to sample XL-Flash products with more than 10 million IOPS by the end of CY2026, and launch a second-generation product with further improved processing speed in CY2027. This does not directly replace HBM, nor will it crowd out DRAM, but it can form a lower-latency, higher-capacity, cheaper layer between HBM and mass storage.
Full Text of Kioxia 2026 Investor Day | In the AI Inference Era, SSDs Are Becoming Compute Infrastructure
AI inference creates several specific storage-demand scenarios.
First is long-context and agent tasks. Code agents, office agents, and research agents continuously read historical state, project files, databases, caches, and intermediate results. The longer the model context, the more state data there is, and the greater the pressure on the memory hierarchy.
Second is RAG and vector databases. Enterprise AI does not answer questions only from parameters; it also needs to retrieve enterprise documents, logs, transaction records, knowledge bases, and graph databases. Vector retrieval requires low-latency random reads and high throughput, which ordinary capacity NAND cannot fully satisfy.
Third is KV cache spillover. HBM capacity is expensive and DRAM is also constrained. When inference services face long context, multi-user concurrency, and low-latency requirements, part of the state and cache will look for cheaper tiers. If high-performance SSDs can absorb part of the hot data, they become a TCO optimization tool for AI servers.
Fourth is AI data lakes. Training, fine-tuning, distillation, inference logs, user feedback, and multimodal data all require storage. Data does not disappear because models are compressed; it increases as usage expands.
This is why the investment question for Kioxia has moved from “how long NAND prices rise” to “whether SSDs can enter AI system design.” If customers are only buying NAND to replenish inventory, profits should be discounted as a cyclical peak. If customers sign long-term agreements to ensure GPU utilization, inference latency, and data availability, the valuation multiple should be higher.
How to Bypass the Memory Tax: NAND, CXL, and PIM Are Being Repriced, and the Industrial Logic Behind Storage-Hierarchy Reconstruction
There is also a need to guard against over-narrativization. The AI inference software stack is still changing rapidly. KV cache compression, sparse attention, retrieval optimization, model routing, and context management will all affect storage demand per token. Kioxia must deliver customer qualification, sample-to-mass-production conversion, eSSD share, and product gross margin, rather than relying on AI keywords alone to obtain a higher multiple.
VI. LTAs Are the First Gate for Whether Valuation Can Move Up a Level
Long-term agreements determine whether Kioxia’s high profits can be capitalized.
If LTAs are merely procurement intentions, their valuation significance is weak. The storage industry has never lacked long-term customer relationships, but when prices fall, customers renegotiate, and suppliers struggle to defend peak profits. Truly valuable LTAs need volume, price floors, and exit costs, preferably with prepayments or financial guarantees.
Kioxia is currently in an intermediate state. Its Investor Day and Goldman Sachs conference call show that the company’s LTA coverage for the two years from CY2027 is about 50%, already enough to affect revenue visibility. The company also emphasized that it values pricing and margins and does not want to be fully locked by long-term agreements at the expense of upside flexibility. Management’s stance is not “sacrificing price for coverage,” but “improving downside visibility while preserving market flexibility.”
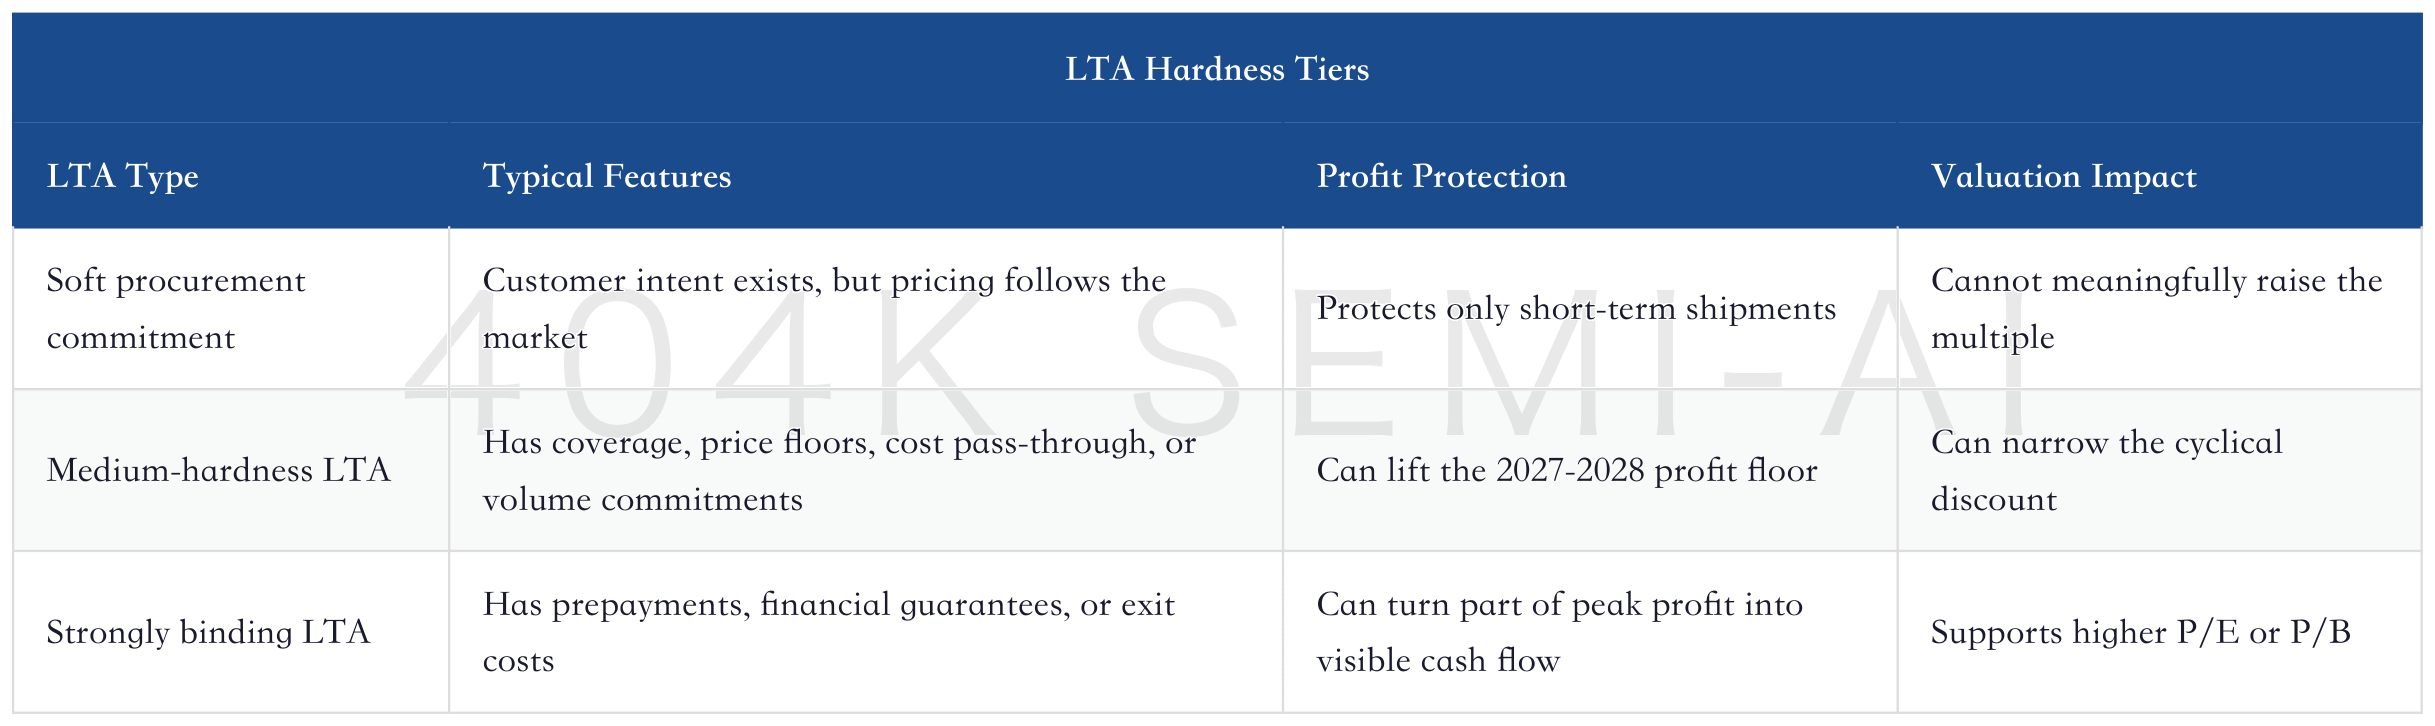
Kioxia currently looks more like the second type. Goldman Sachs’ JPY116,000 target price is the price for the second type of LTA. JPMorgan’s JPY155,000 target price is closer to pricing in the third type in advance. Bernstein’s JPY40,000 target price assumes Kioxia will ultimately return to the first type or a weak second type, with customers renegotiating when prices decline.
This disagreement is highly practical. Going forward, there is no need to debate whether “LTAs are useful”; only three questions need to be tracked.
First, whether coverage can continue rising from 50%. The higher the coverage, the better the revenue visibility, but excessive coverage may also sacrifice upside flexibility. The best state is full signing with core cloud and enterprise customers while retaining flexibility for consumer customers.
Second, whether the terms disclose more hard constraints. Price floors, breach costs, upside price sharing, cost pass-through, and contract duration all affect valuation. Simply saying “long-term agreements have been signed” is not enough.
Third, whether LTAs are tied to AI server and eSSD customers. If long-term agreements mainly come from cloud providers, server OEMs, and enterprise SSD customers, their quality is higher; if they are merely ordinary consumer channels, cyclical protection is weak.
Kioxia Holdings: Conference Call Confirms Tight Supply-Demand and Profit Priority, NAND Profit Center Continues to Move Higher
Goldman Sachs’ wording is subtle: Kioxia prioritizes price and margins, and is not strictly bound to LTA priority. This choice is favorable for bulls in the short term because the company can enjoy price upside; over the long term, however, it still needs to be verified, because without strongly binding LTAs, price declines will also transmit to profits more quickly.
7. Sell-Side Dispersion: ¥116,000 Sits in a Reasonable Position Between Bull and Bear Cases
Since June, Kioxia target prices have been highly dispersed.
JPMorgan is at ¥155,000, UBS at ¥132,000, Goldman Sachs now at ¥116,000, Morgan Stanley was previously around ¥110,000, and Bernstein is at ¥40,000. Because these reports were published around similar dates and all refer to Kioxia common shares in yen terms, they can be used to compare the distribution of assumptions. That said, report dates and valuation bases still differ across firms, so this is not a precise split-adjusted ranking; the focus is on the underlying business assumptions.
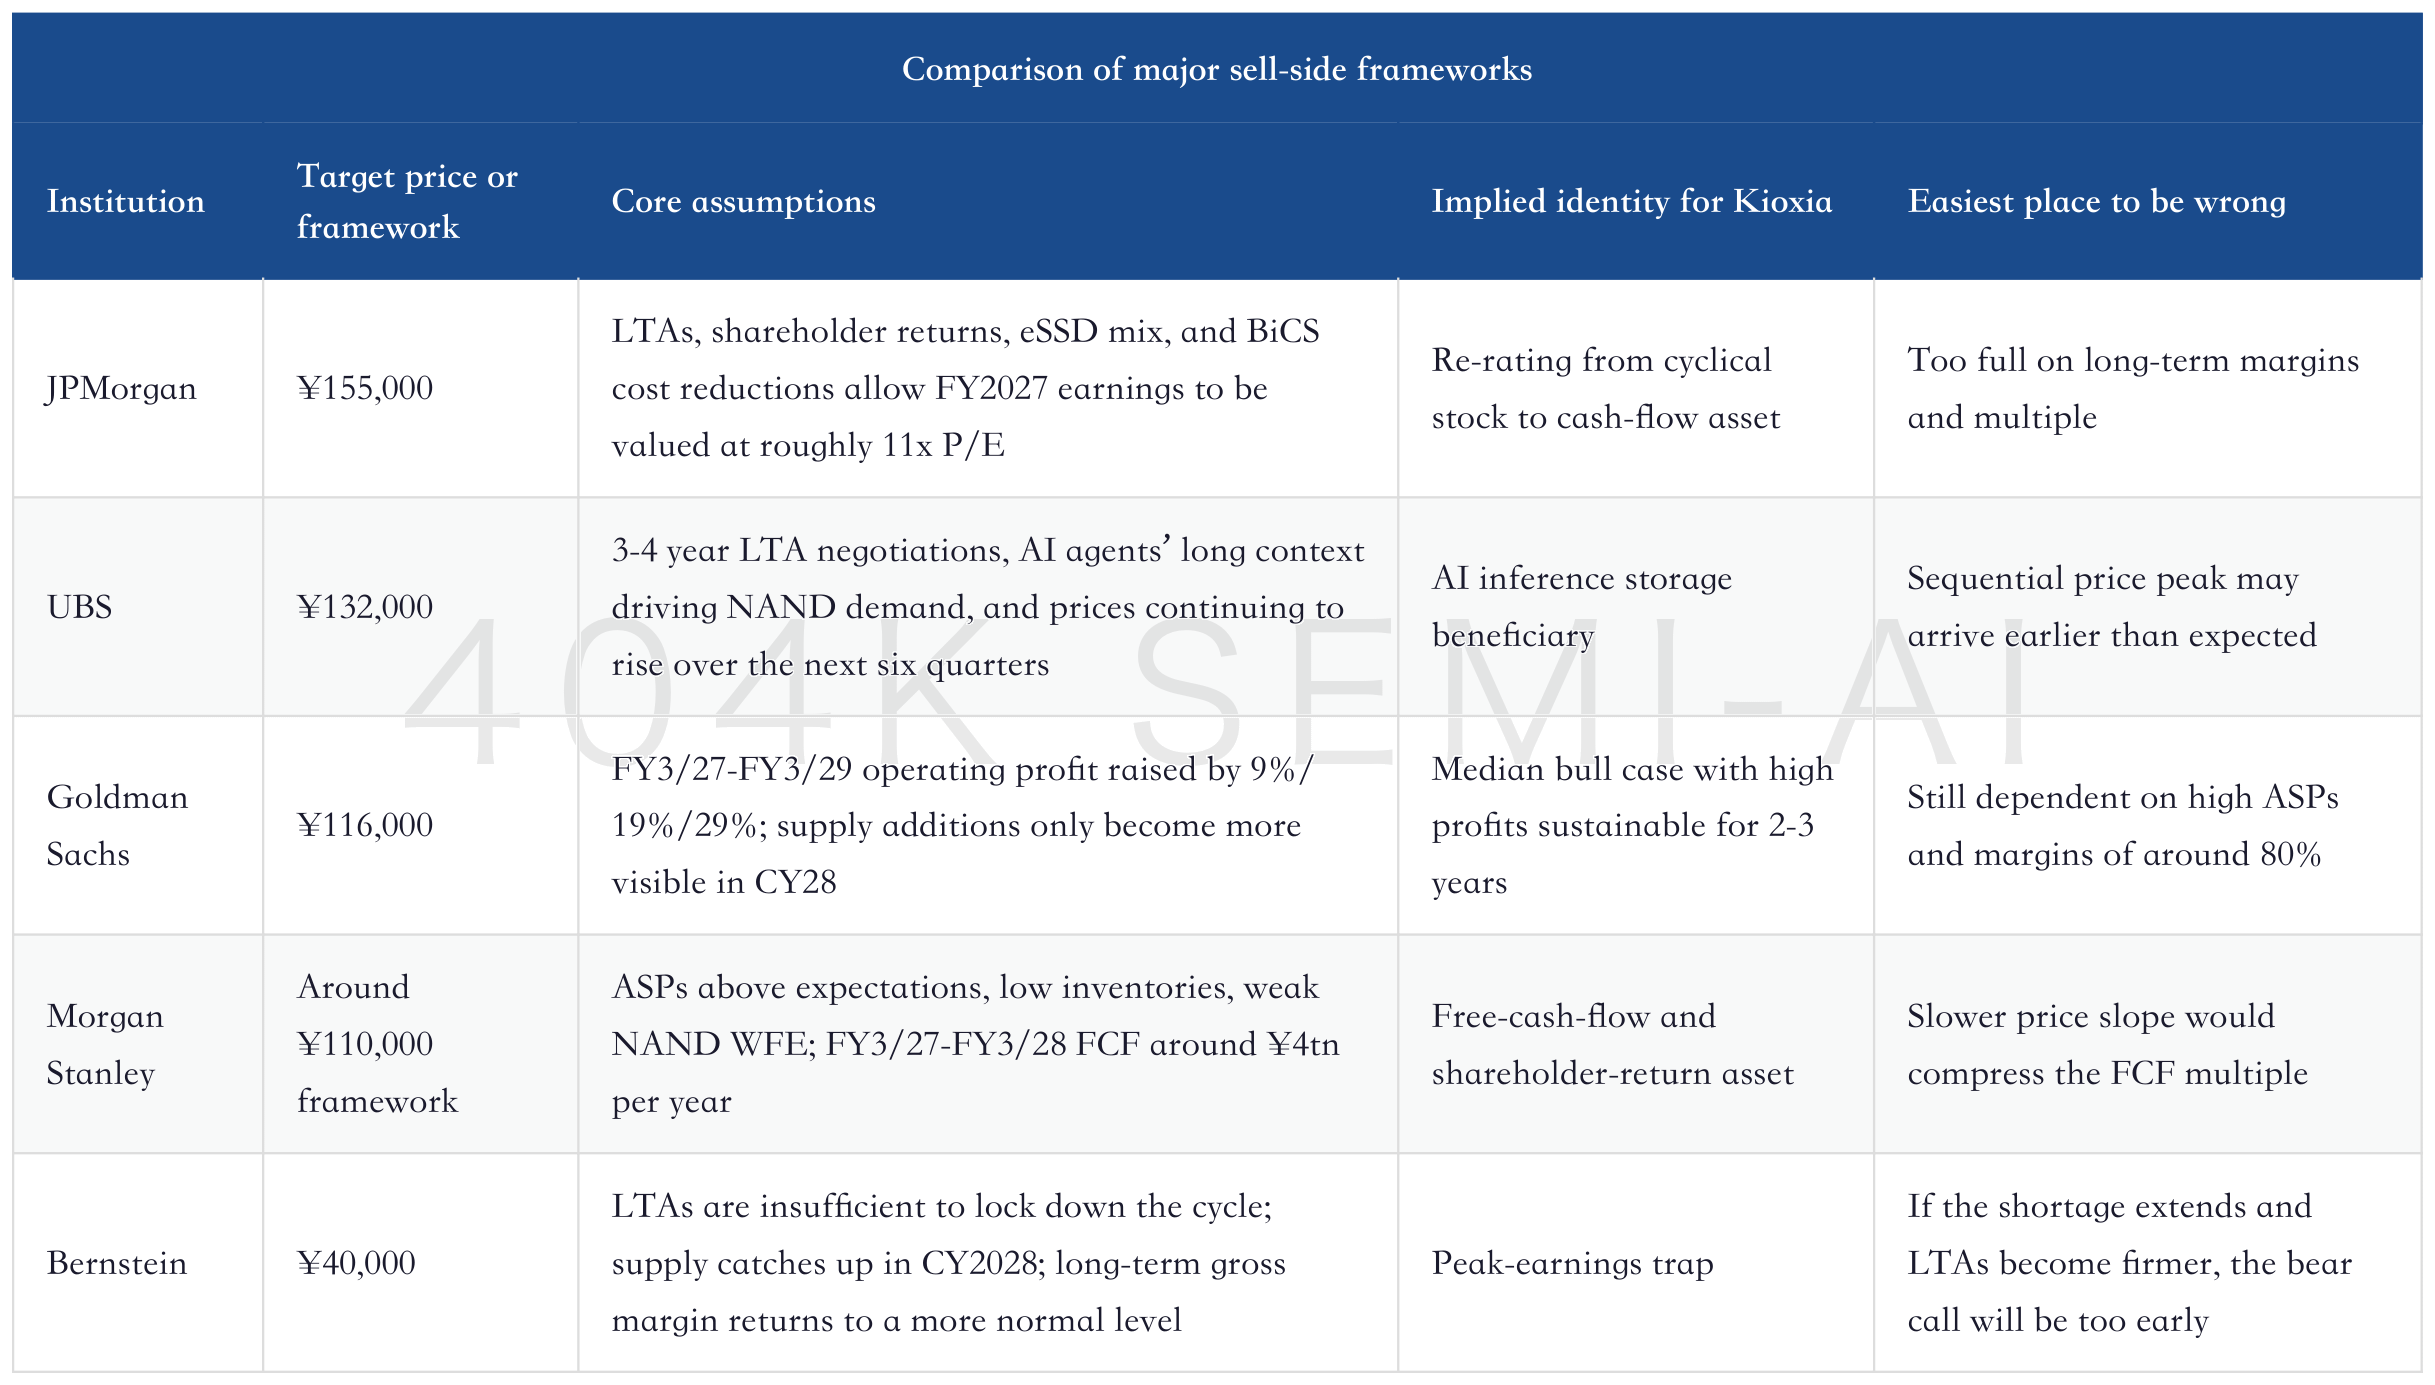
Goldman Sachs’ positioning is important this time. It does not reject JPMorgan’s and UBS’s bull logic, but it also does not fully adopt their valuation aggressiveness. ¥116,000 corresponds to Goldman’s FY3/28E P/E of around 8x and P/B of around 4.5x. That is still a cyclical multiple, just with a smaller cyclical discount than in the past.
This makes the Goldman framework easier to verify.
If June-quarter operating profit exceeds ¥1.417tn and September-quarter ASPs remain above market expectations, there is still room for the ¥116,000 target price to move higher. If LTA terms are disclosed as firmer and shareholder returns become clearer, the market may revisit the JPMorgan and UBS frameworks. Conversely, if the June quarter merely tracks guidance, sequential price increases slow in the September quarter, and customers begin resisting high prices, ¥116,000 would also start to look full.
Behind the sell-side dispersion are essentially three valuation questions.
First, whether FY3/27-FY3/28 EPS can be treated as the cyclical midpoint. Goldman Sachs and JPMorgan are more willing to capitalize part of the earnings, while Bernstein is only willing to treat it as a short-term windfall.
Second, whether LTAs can lift the earnings trough. The firmer the coverage ratio, floor pricing, and breach costs, the higher the multiple; the softer the terms, the lower the multiple.
Third, where gross margin settles after supply returns in CY2028. If the industry’s long-term gross margin can stay above 50%, Kioxia still has valuation upside. If it returns to 30%-35%, the current earnings denominator is too high.
8. Cash Flow and Balance Sheet: From Debt Pressure to Return Optionality
There is another easily overlooked change in this Kioxia re-rating: the balance sheet is improving rapidly.
Goldman Sachs’ model shows Kioxia’s adjusted net debt at around ¥576.9bn in FY3/26. By FY3/27E, the company moves into net cash of ¥2.42tn, then ¥8.44tn in FY3/28E and ¥15.93tn in FY3/29E. Even if these figures are ultimately discounted, the direction is clear: the pricing cycle is moving Kioxia from a highly levered NAND asset toward a net-cash memory asset.
This affects the valuation multiple. In the past, much of Kioxia’s depressed valuation came from high cyclicality, high leverage, shareholder structure, and post-IPO selling pressure. Now that earnings and cash flow are improving, Bain’s selling pressure is easing, and management is starting to discuss dividends and buybacks, a low P/E is no longer merely the superficial appearance of “cheap at a cyclical peak.”
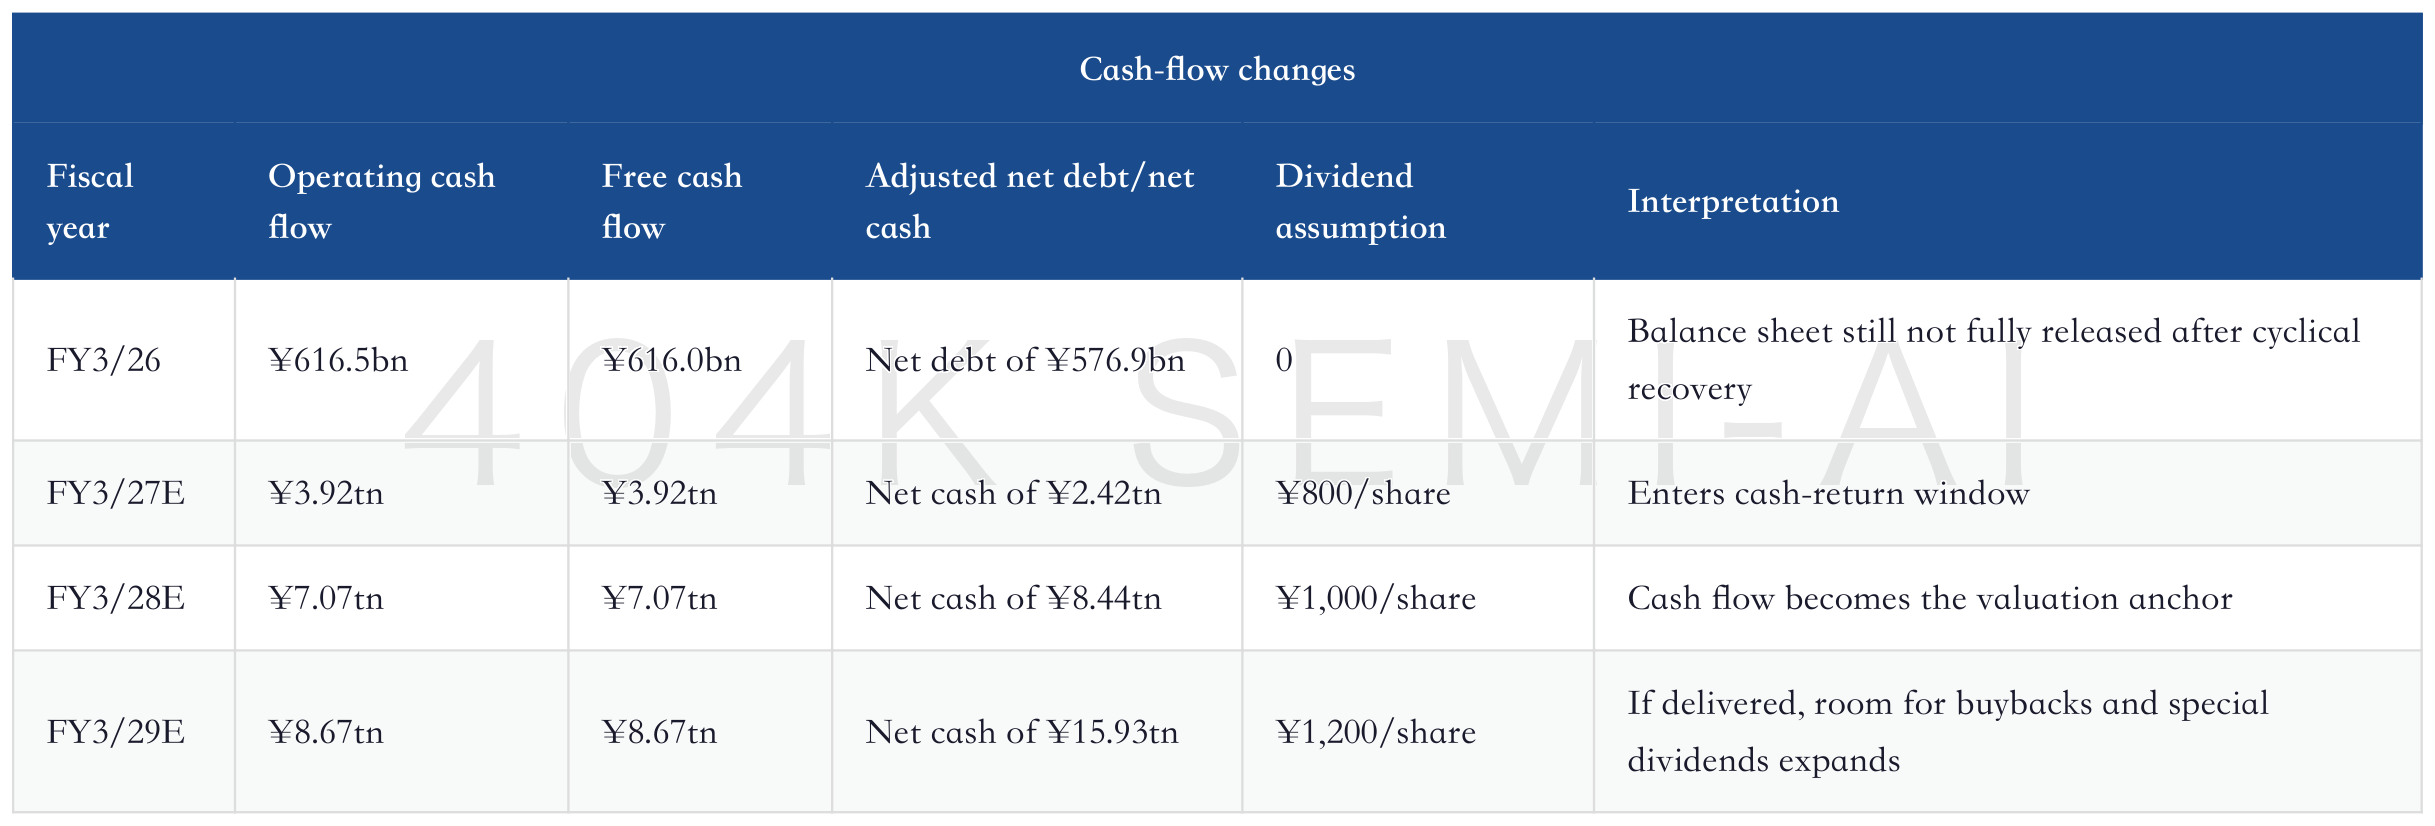
One accounting detail requires caution. The way capital expenditures are presented in Goldman Sachs’ cash-flow statement differs from the gross capex basis in its operating model. One should not look only at headline free cash flow, but rather at the overall combination of operating cash flow, capex guidance, debt repayment, and shareholder returns. For investment purposes, the direction matters more: earnings release is rapidly improving net cash and the interest burden.
Goldman Sachs noted that EPS upgrades come not only from higher operating profit, but also from reduced interest drag due to early repayment of senior loans. FY3/27 net interest expense falls from ¥87.2bn in FY3/26 to ¥24.2bn, then further to ¥15.1bn in FY3/28. For a cyclical stock, lower interest expense is not the main driver, but it reinforces EPS elasticity.
Morgan Stanley had previously also focused on FCF and shareholder returns. It estimated Kioxia’s annualized FCF at around ¥4tn in FY3/27-FY3/28, with a very high implied FCF yield at current levels, and argued that several discount factors were gradually being removed: ASP and LTA concerns, uncertainty around shareholder returns, and equity overhang.
Cash flow is the final proof point for Kioxia to escape the traditional cyclical discount. The income statement can look very strong, but the market will only truly assign a multiple once cash returns to the balance sheet and shareholder accounts. Over the next few quarters, dividend policy, buyback windows, Bain’s subsequent actions, and capex discipline will all affect the valuation ceiling.
