
Kioxia Deep-Dive Update: 75% Margin, ¥800 Billion Buyback, and ¥155,000 Valuation Anchor
目录
TL;DR
First, Consider the Report’s Tone: Why Only “Slightly Positive”?
How the 75% Margin Was Generated: Pricing Contributed Far More Than Shipments
Enterprise SSDs Are Improving Earnings Quality but Have Not Eliminated the Cycle
Second-Quarter Guidance: Volume Begins to Contribute, While Pricing Remains the Main Engine
800 Billion Yen Buyback: The Announced Cap and Actual Purchasing Power Are Not the Same
155000 Yen Price Target: The Hardest Part Is Not 11x, but FY2027 Earnings
What Has Changed—and What Has Not
Eight Numbers to Validate the Report Going Forward
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Record profits have not produced unanimous optimism: JPMorgan accepts that second-quarter revenue guidance is below market expectations but maintains its ¥155,000 price target. The real debate is how much of the 75% margin can persist beyond the cycle.
TL;DR
JPMorgan characterized the results as only “slightly positive.” Kioxia’s first-quarter non-GAAP operating profit of ¥1.3262 trillion was in line with company guidance but below market expectations; second-quarter revenue guidance was also below market expectations, although consistent with JPMorgan’s forecast. The report did not gloss over the expectation gap; it simply viewed continued enterprise SSD volume growth as more important than weak shipments in a single quarter.
The first-quarter profit surge was driven primarily by pricing, not volume. Revenue reached ¥1.7671 trillion, up 76% quarter over quarter; average selling prices rose approximately 70% quarter over quarter, while bit shipments increased only by a low-single-digit percentage, yet the non-GAAP operating margin reached 75%. This demonstrates Kioxia’s substantial operating leverage, while also reminding investors that profits could contract just as rapidly if prices decline.
The second-quarter volume-price mix is healthier than in the first quarter, but profitability remains price-led. The company guided for revenue of ¥2.39 trillion, non-GAAP operating profit of ¥1.9 trillion, and a 79.5% margin. JPMorgan estimates that the potential 35% sequential revenue increase may be driven jointly by double-digit bit growth and an average selling price increase of more than 20%, with some shipments deferred from the end of the first quarter also expected to be recovered.
Data centers and enterprise SSDs are critical to sustaining the valuation premium. SSD and storage revenue reached ¥1.1747 trillion, representing 66% of total revenue; data-center and enterprise applications accounted for more than 60% of the segment. Eighth-generation BiCS FLASH represented more than 50% of production, improving both the product mix and cost curve—closer to sustainable competitiveness than a simple increase in NAND prices.
The ¥800 billion buyback improves the conversion of corporate value into per-share value, but does not provide an unconditional floor for the share price. The official authorization permits the repurchase of up to 30 million shares, approximately 5.5% of total shares outstanding, subject to a ¥800 billion spending cap. At the report-date share price of ¥46,500, the spending cap would purchase only approximately 17.2 million shares; the share-count and spending limits cannot both be reached at the current price, making the actual average purchase price and number of shares repurchased more important than the announced maximums.
The ¥155,000 price target was maintained, not raised this time. JPMorgan continues to value Kioxia using FY2027 earnings per share and a P/E multiple of approximately 11x, 0.5 standard deviations above the approximately 9x average for global memory manufacturers over the past 15 years. The price target was not raised again following the record results, indicating that the positive news largely validates the June rerating framework rather than opening an entirely new valuation range.
First, Consider the Report’s Tone: Why Only “Slightly Positive”?
Viewed solely through year-over-year growth, this is the kind of earnings report that can easily distort one’s sense of scale. Kioxia’s first-quarter revenue increased 415% year over year, while non-GAAP operating profit rose 2,833%. Quarterly operating profit of ¥1.3262 trillion already exceeded the ¥876.2 billion recorded for the whole of FY2025. Figures like these would normally warrant a “significant beat,” yet JPMorgan described the results as only “slightly positive.”
The reason is that sell-side research evaluates results relative to expectations, not merely year-over-year growth. First-quarter operating profit was in line with company guidance but below market expectations; second-quarter revenue guidance was below market expectations but consistent with JPMorgan’s own model. In plain terms, the report’s assessment is that the company earned an exceptional amount, but the market had already expected it to earn even more.
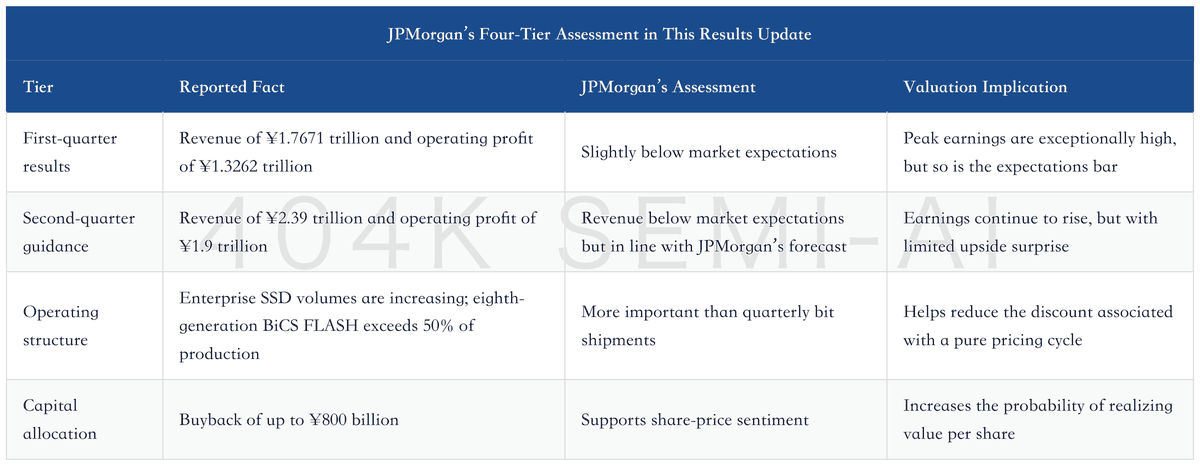
This also explains the seemingly extraordinary gap between the report-date share price and price target. JPMorgan cited a July 31 share price of ¥46,500 while maintaining its ¥155,000 price target, equivalent on the surface to approximately 3.33x. Such a large gap does not mean that one quarter’s profit created more than 2x in incremental value; rather, the share price has already fallen substantially from its previous high, as the market increasingly discounts peak earnings.
This article must answer two questions: how much of the 75% margin comes from sustainable product and cost advantages, and why the market is unwilling to annualize the second quarter’s 79.5% margin directly.
How the 75% Margin Was Generated: Pricing Contributed Far More Than Shipments
First-quarter revenue increased 76% quarter over quarter, average selling prices rose approximately 70% quarter over quarter, and bit shipments increased only by a low-single-digit percentage. The volume-price mathematics behind revenue growth is not entirely additive, but the direction is clear: nearly the entire quarter was driven by pricing, with production expansion playing only a supporting role.
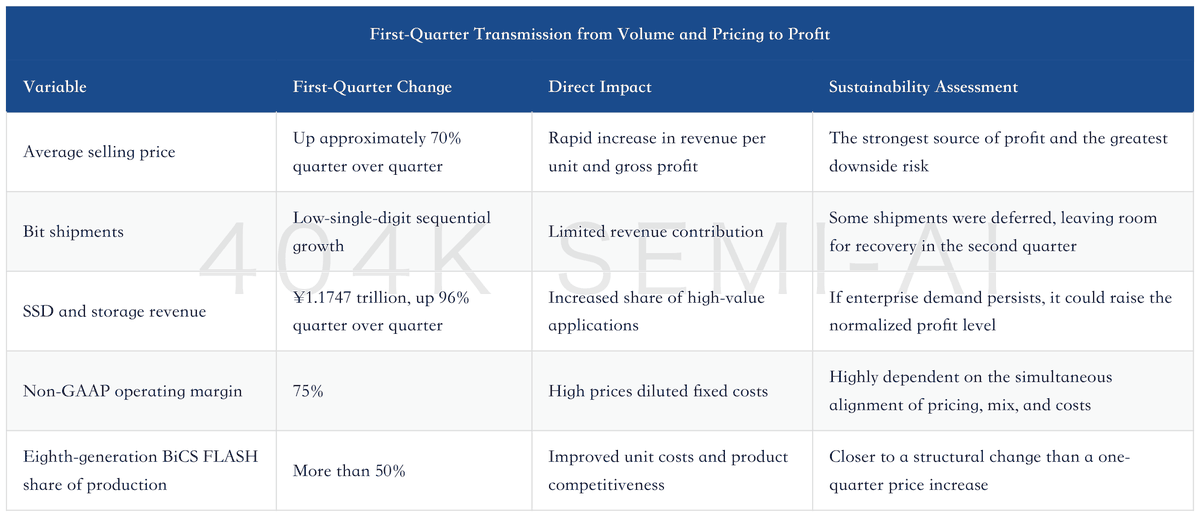
NAND manufacturing has high fixed costs. Fabs, equipment depreciation, R&D;, and staffing do not increase or decrease in tandem with modest quarterly changes in sales volumes. When selling prices rise sharply, a high proportion of incremental revenue flows through to profit; when prices begin to fall, the same operating leverage causes profits to contract in reverse.
Accordingly, the 75% margin cannot be treated as the stable gross-margin story of an ordinary manufacturer. It is closer to a peak outcome produced when pricing, product mix, and cost migration are all favorable simultaneously. JPMorgan’s identification of enterprise SSDs and lower bit costs as long-term drivers reflects an effort to separate part of these earnings from cyclical volatility.
