
Kioxia Deep-Dive Update: 75% Margin, ¥800 Billion Buyback, and ¥155,000 Valuation Anchor
目录
TL;DR
First, Consider the Report’s Tone: Why Only “Slightly Positive”?
How the 75% Margin Was Generated: Pricing Contributed Far More Than Shipments
Enterprise SSDs Are Improving Earnings Quality but Have Not Eliminated the Cycle
Second-Quarter Guidance: Volume Begins to Contribute, While Pricing Remains the Main Engine
800 Billion Yen Buyback: The Announced Cap and Actual Purchasing Power Are Not the Same
155000 Yen Price Target: The Hardest Part Is Not 11x, but FY2027 Earnings
What Has Changed—and What Has Not
Eight Numbers to Validate the Report Going Forward
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Record profits have not produced unanimous optimism: JPMorgan accepts that second-quarter revenue guidance is below market expectations but maintains its ¥155,000 price target. The real debate is how much of the 75% margin can persist beyond the cycle.
TL;DR
JPMorgan characterized the results as only “slightly positive.” Kioxia’s first-quarter non-GAAP operating profit of ¥1.3262 trillion was in line with company guidance but below market expectations; second-quarter revenue guidance was also below market expectations, although consistent with JPMorgan’s forecast. The report did not gloss over the expectation gap; it simply viewed continued enterprise SSD volume growth as more important than weak shipments in a single quarter.
The first-quarter profit surge was driven primarily by pricing, not volume. Revenue reached ¥1.7671 trillion, up 76% quarter over quarter; average selling prices rose approximately 70% quarter over quarter, while bit shipments increased only by a low-single-digit percentage, yet the non-GAAP operating margin reached 75%. This demonstrates Kioxia’s substantial operating leverage, while also reminding investors that profits could contract just as rapidly if prices decline.
The second-quarter volume-price mix is healthier than in the first quarter, but profitability remains price-led. The company guided for revenue of ¥2.39 trillion, non-GAAP operating profit of ¥1.9 trillion, and a 79.5% margin. JPMorgan estimates that the potential 35% sequential revenue increase may be driven jointly by double-digit bit growth and an average selling price increase of more than 20%, with some shipments deferred from the end of the first quarter also expected to be recovered.
Data centers and enterprise SSDs are critical to sustaining the valuation premium. SSD and storage revenue reached ¥1.1747 trillion, representing 66% of total revenue; data-center and enterprise applications accounted for more than 60% of the segment. Eighth-generation BiCS FLASH represented more than 50% of production, improving both the product mix and cost curve—closer to sustainable competitiveness than a simple increase in NAND prices.
The ¥800 billion buyback improves the conversion of corporate value into per-share value, but does not provide an unconditional floor for the share price. The official authorization permits the repurchase of up to 30 million shares, approximately 5.5% of total shares outstanding, subject to a ¥800 billion spending cap. At the report-date share price of ¥46,500, the spending cap would purchase only approximately 17.2 million shares; the share-count and spending limits cannot both be reached at the current price, making the actual average purchase price and number of shares repurchased more important than the announced maximums.
The ¥155,000 price target was maintained, not raised this time. JPMorgan continues to value Kioxia using FY2027 earnings per share and a P/E multiple of approximately 11x, 0.5 standard deviations above the approximately 9x average for global memory manufacturers over the past 15 years. The price target was not raised again following the record results, indicating that the positive news largely validates the June rerating framework rather than opening an entirely new valuation range.
First, Consider the Report’s Tone: Why Only “Slightly Positive”?
Viewed solely through year-over-year growth, this is the kind of earnings report that can easily distort one’s sense of scale. Kioxia’s first-quarter revenue increased 415% year over year, while non-GAAP operating profit rose 2,833%. Quarterly operating profit of ¥1.3262 trillion already exceeded the ¥876.2 billion recorded for the whole of FY2025. Figures like these would normally warrant a “significant beat,” yet JPMorgan described the results as only “slightly positive.”
The reason is that sell-side research evaluates results relative to expectations, not merely year-over-year growth. First-quarter operating profit was in line with company guidance but below market expectations; second-quarter revenue guidance was below market expectations but consistent with JPMorgan’s own model. In plain terms, the report’s assessment is that the company earned an exceptional amount, but the market had already expected it to earn even more.
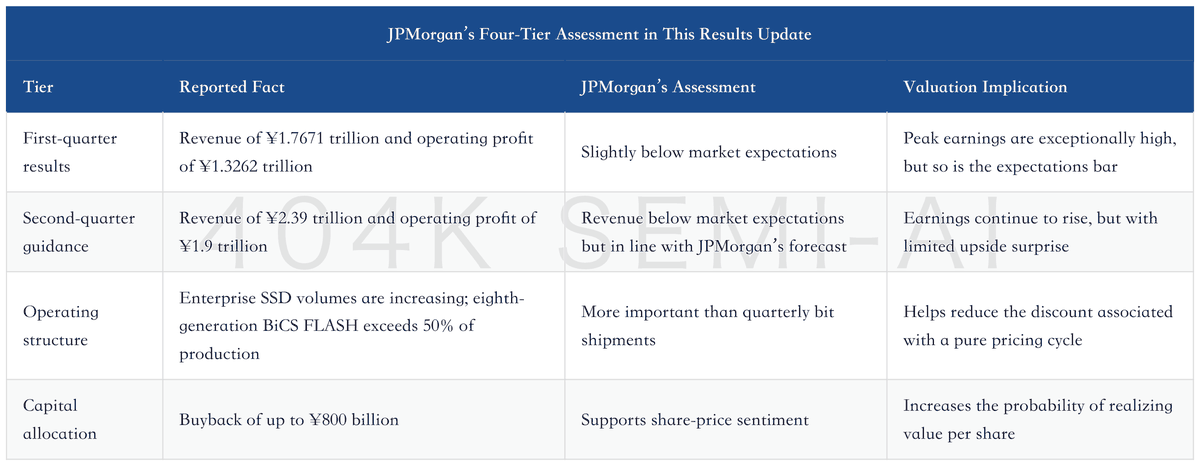
This also explains the seemingly extraordinary gap between the report-date share price and price target. JPMorgan cited a July 31 share price of ¥46,500 while maintaining its ¥155,000 price target, equivalent on the surface to approximately 3.33x. Such a large gap does not mean that one quarter’s profit created more than 2x in incremental value; rather, the share price has already fallen substantially from its previous high, as the market increasingly discounts peak earnings.
This article must answer two questions: how much of the 75% margin comes from sustainable product and cost advantages, and why the market is unwilling to annualize the second quarter’s 79.5% margin directly.
How the 75% Margin Was Generated: Pricing Contributed Far More Than Shipments
First-quarter revenue increased 76% quarter over quarter, average selling prices rose approximately 70% quarter over quarter, and bit shipments increased only by a low-single-digit percentage. The volume-price mathematics behind revenue growth is not entirely additive, but the direction is clear: nearly the entire quarter was driven by pricing, with production expansion playing only a supporting role.
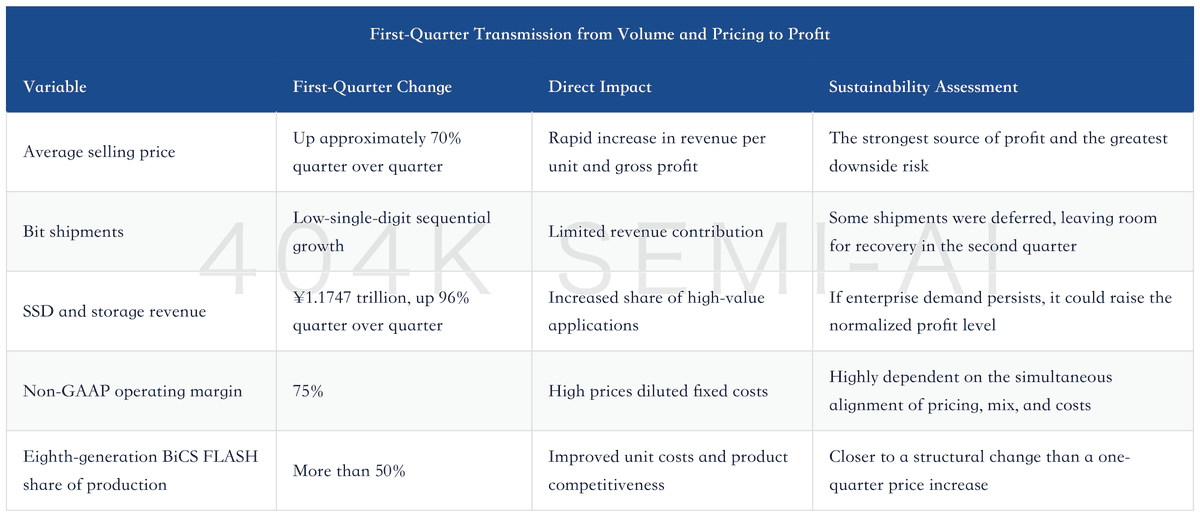
NAND manufacturing has high fixed costs. Fabs, equipment depreciation, R&D;, and staffing do not increase or decrease in tandem with modest quarterly changes in sales volumes. When selling prices rise sharply, a high proportion of incremental revenue flows through to profit; when prices begin to fall, the same operating leverage causes profits to contract in reverse.
Accordingly, the 75% margin cannot be treated as the stable gross-margin story of an ordinary manufacturer. It is closer to a peak outcome produced when pricing, product mix, and cost migration are all favorable simultaneously. JPMorgan’s identification of enterprise SSDs and lower bit costs as long-term drivers reflects an effort to separate part of these earnings from cyclical volatility.
Some shipments were also deferred from the end of the first quarter into the second quarter. This made first-quarter bit growth appear weak and should make second-quarter volume growth easier to improve. The timing mismatch can explain the slope between quarters, but it does not create new end demand. Whether the cycle can be extended will ultimately depend on whether full-year server, enterprise SSD, and consumer-device demand can absorb the industry’s natural bit-supply growth.
Enterprise SSDs Are Improving Earnings Quality but Have Not Eliminated the Cycle
First-quarter SSD and storage revenue accounted for 66% of total revenue, with data-center and enterprise applications representing more than 60% of the segment. On this basis, data-center and enterprise businesses have already become a highly significant component of Kioxia’s total revenue. Their significance is not merely a higher “AI exposure,” but the potential for changes in customer, product, and contract structures.
Enterprise SSDs offer greater capacity and face more demanding requirements for reliability, power consumption, performance, and validation, as well as longer qualification cycles. Once customers complete product qualification, supplier relationships are generally more stable than in consumer electronics. Eighth-generation BiCS FLASH accounting for more than 50% of production indicates that Kioxia is using process migration to improve effective bit output per wafer. One raises selling prices and customer stickiness, while the other reduces unit costs; together, they determine whether high profitability can leave behind a higher floor after NAND prices decline.
JPMorgan reiterated three long-term arguments from its June report: enterprise SSDs are driving a product-mix upgrade; technologies including CBA, OPS architecture, and QLC support lower bit costs; and the joint-venture production system with Sandisk improves the efficiency of large-scale capital expenditure. All three are more deserving of a valuation multiple than “average selling prices rose 70% this quarter.”
Kioxia Deep-Dive Update: ¥155,000 Price Target, NAND Cash Flow, and AI SSD Rerating
However, the report also included a counterpoint that is easy to overlook. Compared with the investor day, management was slightly more cautious about the near-term penetration of QLC into the nearline HDD market. QLC provides higher capacity at lower cost and may eventually address some applications currently served by high-capacity HDDs; if penetration is slower than expected, Kioxia’s incremental opportunity in the nearline storage market will not materialize immediately.
This does not invalidate AI storage demand; it divides the growth path into two stages. The first is already underway: demand for traditional servers and enterprise SSDs is strong, and the data-center revenue mix is increasing. The second still requires validation: new NAND workloads created by agentic AI, QLC substitution for nearline HDDs, and storage-capacity upgrades in consumer devices driven by edge AI. JPMorgan’s view that agentic AI remains at a very early stage means that both the upside potential and forecasting error may be substantial.
Second-Quarter Guidance: Volume Begins to Contribute, While Pricing Remains the Main Engine
Kioxia expects second-quarter revenue of 2.39 trillion yen, non-GAAP operating profit of 1.9 trillion yen, and an operating margin of 79.5%. Compared with the first quarter, revenue is expected to increase by approximately 35%, operating profit by approximately 43%, and the margin by another 4.5 percentage points.
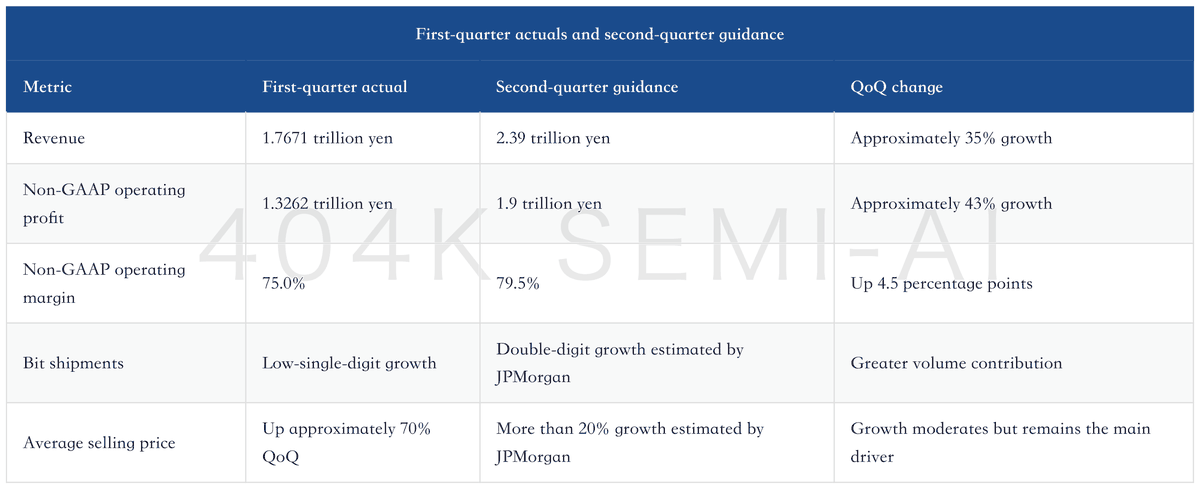
If bit shipments grow by approximately 10% and average selling prices rise by approximately 20%, the combined effect implies revenue growth of nearly 32%, broadly consistent with the overall guidance of 35%. This indicates that the second quarter is no longer entirely dependent on a surge in unit pricing, as volume is also beginning to contribute; however, an average selling-price increase of more than 20% remains far above normal-year levels, and overall profitability is still in a strong pricing cycle.
The company expects high-double-digit industry bit-demand growth in calendar 2026 and believes demand will exceed supply in calendar 2027. This statement provides a longer runway for the valuation framework, but it is not yet an order commitment. Demand forecasts must be assessed alongside three supply-side factors: competitors’ capital expenditure, organic bit growth from advanced process nodes, and whether customers are bringing purchases forward due to concerns about shortages. Looking only at demand while ignoring supply and inventories is the easiest way to double-count shortages at the top of the cycle.
The same applies to long-term agreements. The company reiterated its target of covering 50% of sales in calendar 2028 but did not disclose contract durations, pricing mechanisms, prepayments, or the proportion already signed. Long-term agreements can improve sales visibility, but if prices are still reset quarterly, they primarily reduce volume volatility rather than lock in current high margins. How much of a premium the market is willing to pay depends on what the contracts actually lock in.
800 Billion Yen Buyback: The Announced Cap and Actual Purchasing Power Are Not the Same
JPMorgan described the buyback as the first of its kind in the memory industry and believes it will provide strong support for share-price sentiment. This view is reasonable: cyclical companies are most likely to reinvest cash in capacity at peak profitability, ultimately undermining prices through incremental supply. Kioxia’s decision to repurchase shares at least indicates that capital allocation is shifting from “capacity expansion first” toward “balancing investment and shareholder returns.”
However, the buyback must be assessed against both the monetary cap and the share-count cap. The company authorized purchases of no more than 800 billion yen and no more than 30 million shares, equivalent to approximately 5.5% of total shares outstanding, with execution scheduled from August 3 to October 30, 2026. At the report-date price of 46500 yen, 800 billion yen would purchase only approximately 17.2 million shares, or approximately 3.1% of total shares outstanding; purchasing the full 30 million shares would require an average price of approximately 26667 yen.
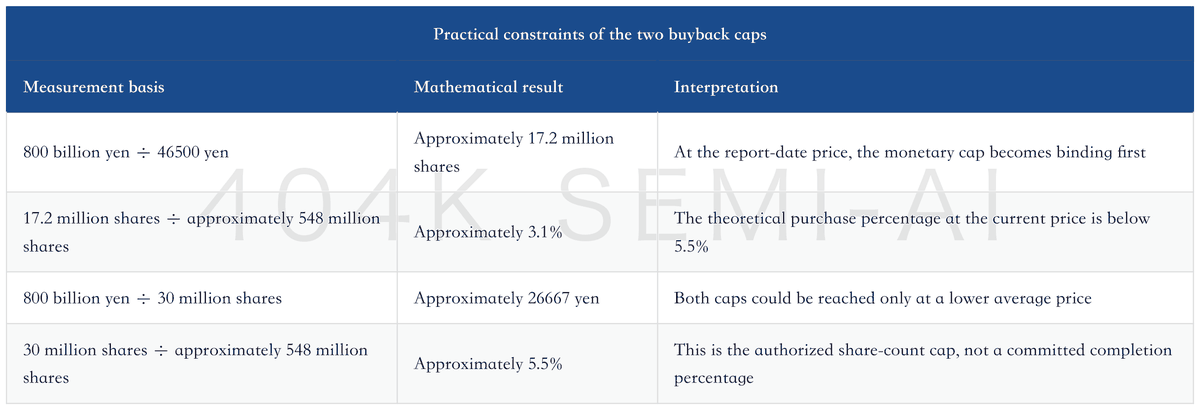
This table is not forecasting the buyback price. It demonstrates that 5.5% cannot be treated directly as a certain level of earnings-per-share accretion. What truly affects shareholder value is the cumulative number of shares purchased each day, the purchase amount, the average price, the subsequent treatment of treasury shares, and the amount of net cash remaining after the buyback.
The buyback also cannot be treated as a floor for the share price. The company’s announcement leaves room for partial execution or no execution depending on market conditions. If the share price exceeds the company’s assessment of intrinsic value, purchasing fewer shares may be more rational; if the share price remains depressed but the company does not execute the buyback, the market will reassess management’s commitment. The analytical value of the buyback lies in testing capital-allocation discipline, not in supporting the shares at any price.
Kioxia Earnings Deep Dive: Q1 Net Profit Misses Expectations, 5.5% Share Buyback, and How to Price the NAND Peak
155000 Yen Price Target: The Hardest Part Is Not 11x, but FY2027 Earnings
JPMorgan maintained its 155000 yen price target, based on FY2027 earnings per share and a price-to-earnings ratio of approximately 11x. The 11x multiple represents 0.5 standard deviations above the approximately 9x average price-to-earnings ratio of global memory manufacturers over the past 15 years. The premium is justified by reduced potential selling pressure from Pangea and improved medium-term earnings stability from long-term agreements.
This valuation incorporates two assumptions. First, FY2027 earnings can remain at a relatively high level. Second, even if earnings reflect a cyclical peak, Kioxia should command a higher multiple than an ordinary memory company. Enterprise SSDs, low bit costs, capital-expenditure efficiency at the joint venture, long-term agreements, and the buyback all provide support for the second assumption.
This 8-page flash report did not restate the full FY2027 earnings-per-share model, so the summary page alone cannot be used to verify every component of the earnings forecast. Mechanically dividing 155000 yen by approximately 11x implies earnings per share of roughly 14100 yen; because 11x is itself an approximation, this can serve only as a valuation reference and must not be presented as JPMorgan’s precise disclosed forecast.
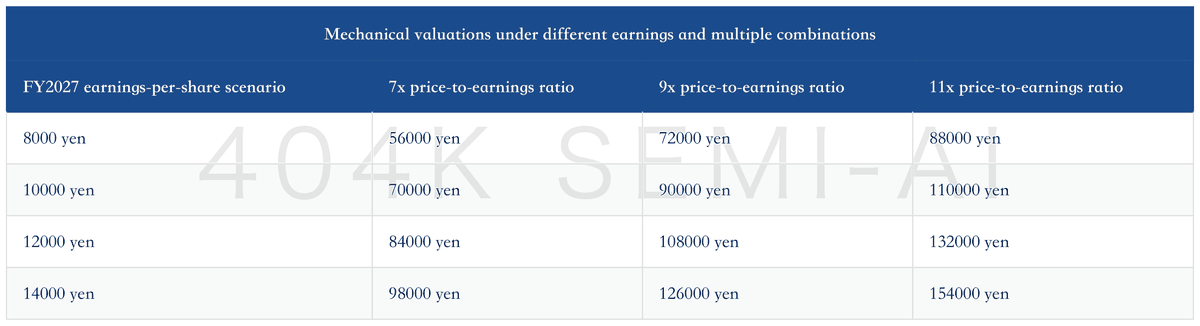
This is only a sensitivity analysis of “earnings per share × price-to-earnings ratio,” not an earnings forecast. It highlights what is required to support the 155000 yen price target: high earnings and a high multiple must both materialize. If FY2027 earnings per share are only 10000 yen, even an 11x multiple yields a valuation of just 110000 yen; if earnings reach 14000 yen but the market is willing to pay only 7x, the valuation is still only 98000 yen.
The theoretical upside from the report-date price of 46500 yen to 155000 yen is approximately 233%, but substantial upside is not synonymous with high certainty. A persistent disconnect between a cyclical stock’s price target and current share price usually has three explanations. First, the market suspects that the forward earnings used by sell-side analysts are at a peak and therefore discounts earnings per share in advance. Second, the market rejects a valuation multiple above the historical average, particularly after spot prices have already surged. Third, investors require tangible results from long-term agreements, the buyback, and capital-expenditure discipline before paying for greater earnings stability.
This means that a share-price recovery requires two levels of evidence. The first is second-quarter revenue, profit, and executed buyback transactions, which can demonstrate that the near-term model has not lost momentum. The second is 2027 orders, the terms of long-term agreements, and industry supply, which will determine whether the market is willing to extend high profitability into FY2027, the year used for the price target. If only the first level is achieved, the shares may rebound but still retain a significant cyclical discount; only if both levels are achieved does 11x have a chance to shift from a research assumption to market consensus.
The time basis must also be considered. The 155000 yen figure is a December 2026 price target, not a declaration of fair value on the current date. During the price-target period, earnings forecasts, the number of shares repurchased, per-share metrics following the stock split, and market multiples may all change. Interpreting it directly as “the current share price will inevitably rise 233%” ignores the model’s path and the conditions that would invalidate it. A more accurate interpretation is that JPMorgan believes the current price does not reflect the corresponding value if both FY2027 earnings and the valuation premium materialize; the market is clearly highly skeptical of at least one of those assumptions.
The price target was not raised this time. The June report had already incorporated enterprise SSDs, long-term agreements, shareholder returns, and reduced shareholder selling pressure into the 155000 yen target; July’s record results primarily validated those assumptions. The absence of another price-target increase means that high second-quarter profitability does not directly increase terminal value unless it provides further evidence that both FY2027 earnings and the valuation premium will be stronger than assumed in the original model.
The 155000 yen target reflects the duration of the earnings plateau, not a direct annualization of second-quarter profit. The market already recognizes that Kioxia is currently highly profitable. The real debate is whether high profitability can persist through 2027 and whether the buyback and long-term agreements can transform the company from a highly volatile cyclical stock into an asset with more stable cash flows.
What Has Changed—and What Has Not
Compared with JPMorgan’s in-depth June report, this update provides validation and partial revisions rather than rewriting the investment thesis.
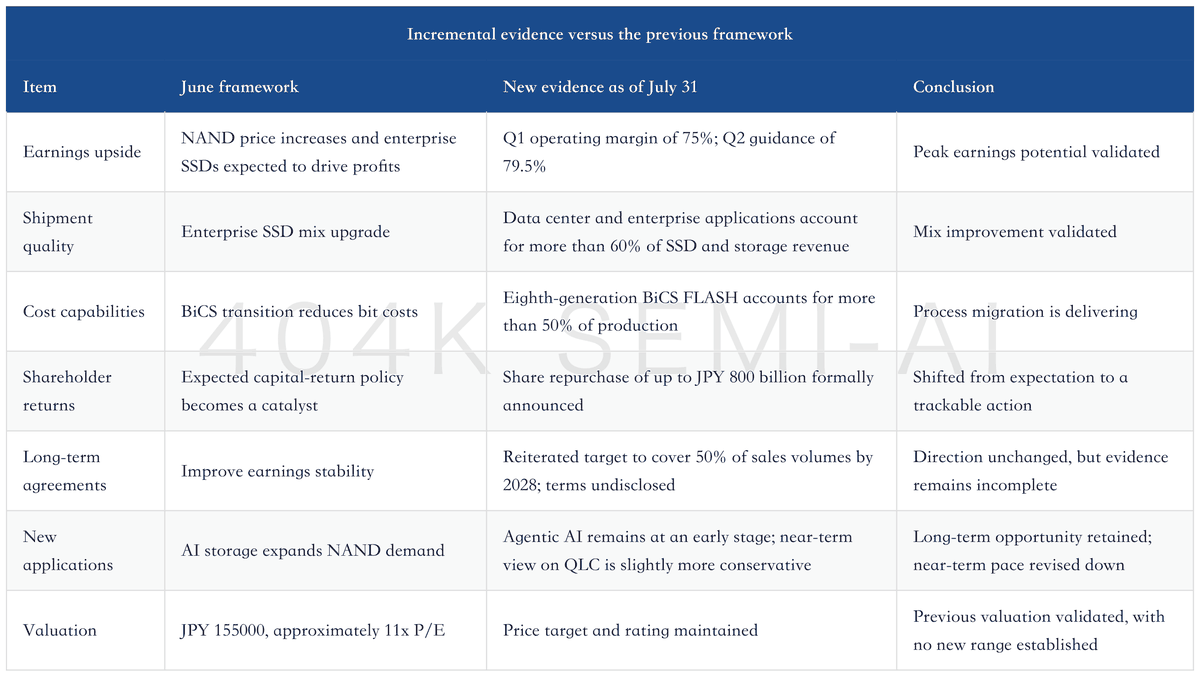
The real upgrades are to “current earnings upside” and “the credibility of capital returns.” There are no meaningful upgrades to the verifiability of long-term agreements, the pace of QLC substitution, or the valuation multiple. If the market trades only on the first two factors, the share price may be highly sensitive to quarterly profits and repurchase progress; only continued delivery on the final three factors may reduce the cyclical discount.
Eight Numbers to Validate the Report Going Forward
First, whether Q2 revenue can reach JPY 2.39 trillion; second, whether non-GAAP operating profit can reach JPY 1.9 trillion; third, after average selling prices increased by approximately 70% in Q1, whether they can rise by more than 20% again in Q2; fourth, whether bit shipments can shift from low-single-digit growth to double-digit growth.
Fifth, whether data center and enterprise applications can remain above 60% of SSD and storage revenue; sixth, whether eighth-generation BiCS FLASH can continue increasing its share of production without abnormal yield or cost issues; seventh, whether the signed coverage ratio, contract durations, and pricing mechanisms of long-term agreements can be disclosed progressively; eighth, whether cumulative repurchased shares, transaction value, and average purchase price can demonstrate that management is genuinely executing at reasonable prices.
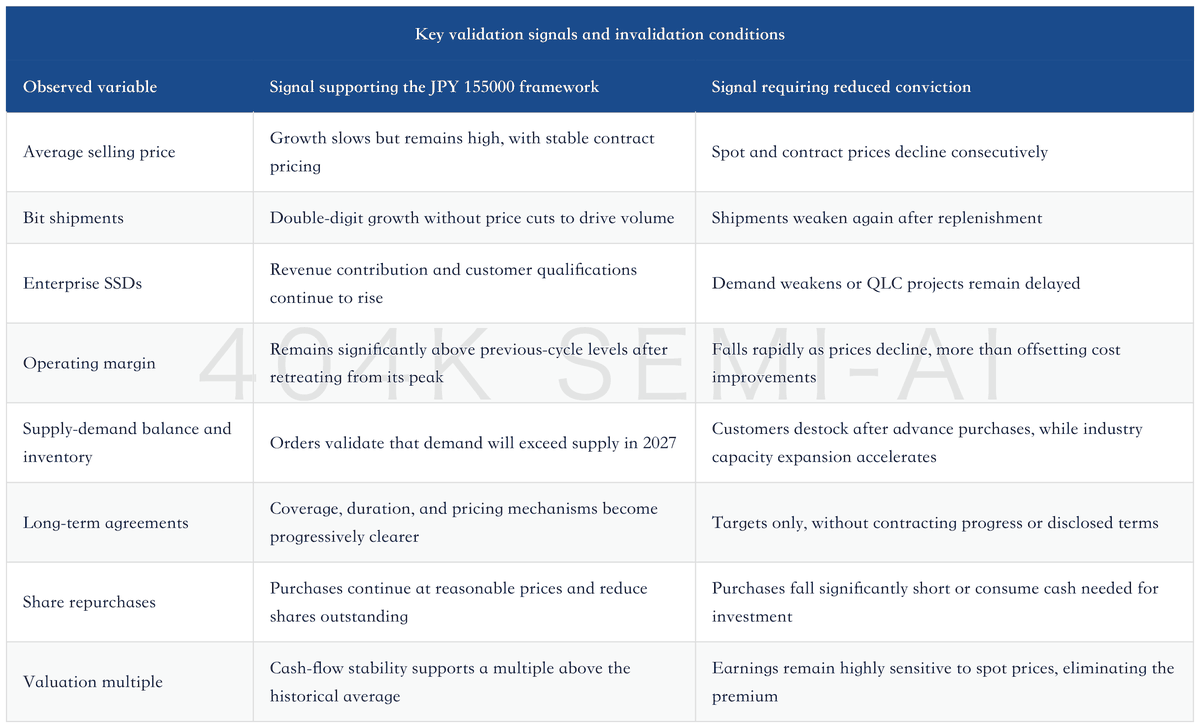
The most valuable aspect of this JPMorgan report is that it separates “strong results” into sustainable and unsustainable components. The approximately 70% increase in average selling prices, 75% margin, and Q2 guidance of 79.5% demonstrate exceptionally strong cyclical operating leverage; enterprise SSDs, BiCS costs, long-term agreements, and share repurchases will determine how much profit can translate into more stable per-share value.
The conclusion can be stated more directly: Kioxia’s earnings peak is still moving higher, but the JPY 155000 price target cannot be supported solely by further price increases in Q2. It requires FY2027 earnings to remain high, the enterprise SSD mix to continue rising, long-term agreements to genuinely reduce volatility, capital expenditure not to disrupt the supply-demand balance, and share repurchases to be executed at reasonable prices. Delivery on any one factor alone is insufficient.
There are two common mistakes at the current stage: treating the 75% margin as permanent, or dismissing the improvements already achieved in enterprise SSDs and the cost curve because that margin appears unsustainable. A more reasonable approach is to separate cyclical profits from structural profits: pricing determines the height of the peak; enterprise SSDs and BiCS determine how much remains after the downturn; long-term agreements determine how long the platform can be sustained; and share repurchases determine how much value ultimately accrues to each share.