
Kingboard Laminates Deep-Dive Update: July E-Glass Fabric Prices Rise by up to RMB1.5/m; Why It Still Looks Better Than Kingboard Holdings
目录
TL;DR
1. July Price Signal: New Capacity Has Not Capped E-Glass Fabric Price Hikes
2. Why New Capacity Still Cannot Cap Prices
3. Why 7628 Is the Detail Thread in This Update
4. Why Kingboard Laminates Still Looks Better Than Kingboard Holdings
5. Valuation Has Not Become Cheap; the Validation Bar Is Higher
6. Tracking Checklist: Watch Six Numbers Next
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
July e-glass fabric prices did not fall after new capacity came online. Instead, they posted the largest monthly increase so far this year. For Kingboard Laminates, the key question has moved from "can the June CCL price hike stick?" to whether ordinary e-glass fabric, 7628-grade tightness, and AI-fabric capacity crowding can continue to support earnings upgrades in 2026-2027.
TL;DR
The July price hike is firmer than June. 1080 and 2116 e-glass fabric prices rose another RMB1.5/m, while 7628 rose another RMB1.2/m. Prices are now up 125%, 121%, and 86% year-to-date, respectively. New capacity has not capped prices, showing that the bottleneck is still effective supply.
Kingboard Laminates remains higher priority than Kingboard Holdings. Kingboard Holdings is more like a basket of materials, PCB, chemicals, and property assets, while Kingboard Laminates has direct exposure to profit elasticity from e-glass fabric, CCL, and AI-fabric. During the ongoing price-upgrade phase, purity matters more than holding-company discount.
7628 is the core variable in this update. 7628 accounts for roughly 65% of Kingboard Laminates' e-glass fabric mix. Management believes 7628 may become even tighter than 1080 going forward. If price hikes continue to spread into thicker fabric, Kingboard's profit elasticity will extend from high-end AI fabric to ordinary e-glass fabric and mainstream FR-4.
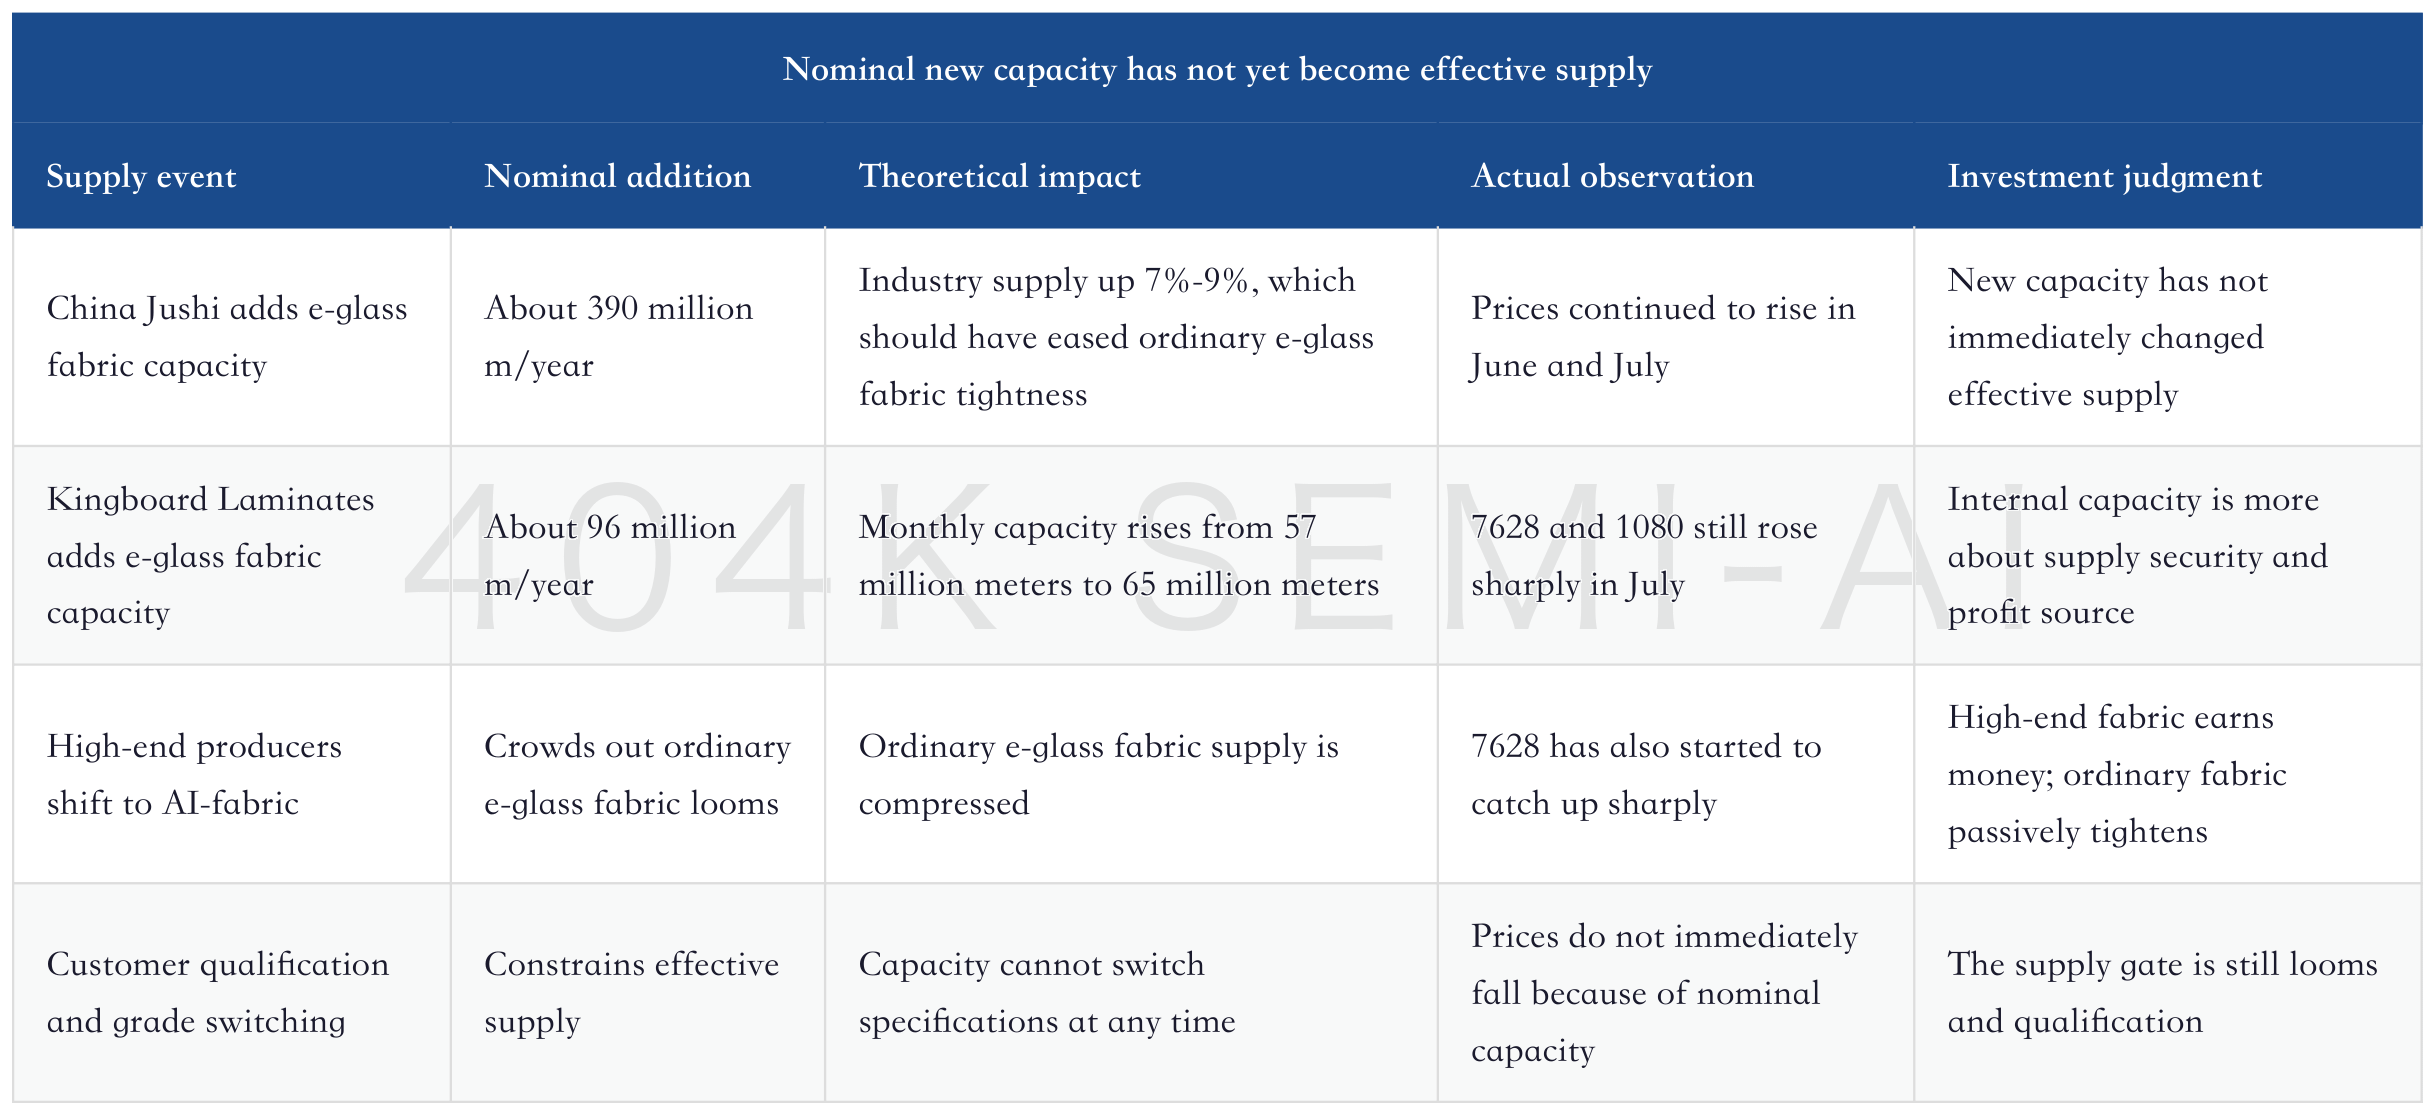
New capacity has not interrupted the price hikes. China Jushi released roughly 390 million meters of annual capacity in May, and Kingboard Laminates added roughly 96 million meters of annual capacity, yet prices remained strong in June and July. This shows that nominal capacity additions do not equal effective supply release; looms, fabric-grade switching, and customer qualification remain the gates.
Valuation risk comes from two lines. Kingboard Laminates' HK$120 target price implies roughly 29x 2027E PE, while Kingboard Holdings' HK$202 target price implies roughly 19x 2027E PE. If concerns over AI infrastructure overbuilding pressure sentiment, if the slope of e-glass fabric price hikes slows, or if Nvidia qualification is slower than expected, valuation will first revert to a cyclical-stock framework and trading elasticity will also contract.
1. July Price Signal: New Capacity Has Not Capped E-Glass Fabric Price Hikes
The most important point in Citi's July update is not that it again reaches a bullish conclusion, but that the price data itself is already stronger than in June. In July, 1080 and 2116 e-glass fabric rose RMB1.5/m, while 7628 rose RMB1.2/m, marking the steepest monthly increases since 2026 began.
This price signal has two implications. First, e-glass fabric shortages have not eased despite new capacity releases in May and June. Second, price hikes are no longer concentrated only in high-end AI-fabric, but are continuing to spread into ordinary e-glass fabric. For Kingboard Laminates, this matters more than simply discussing the AI concept, because what actually flows through the company's income statement is the continuous pass-through of "e-glass fabric price hikes + CCL price increases + integrated cost advantage."
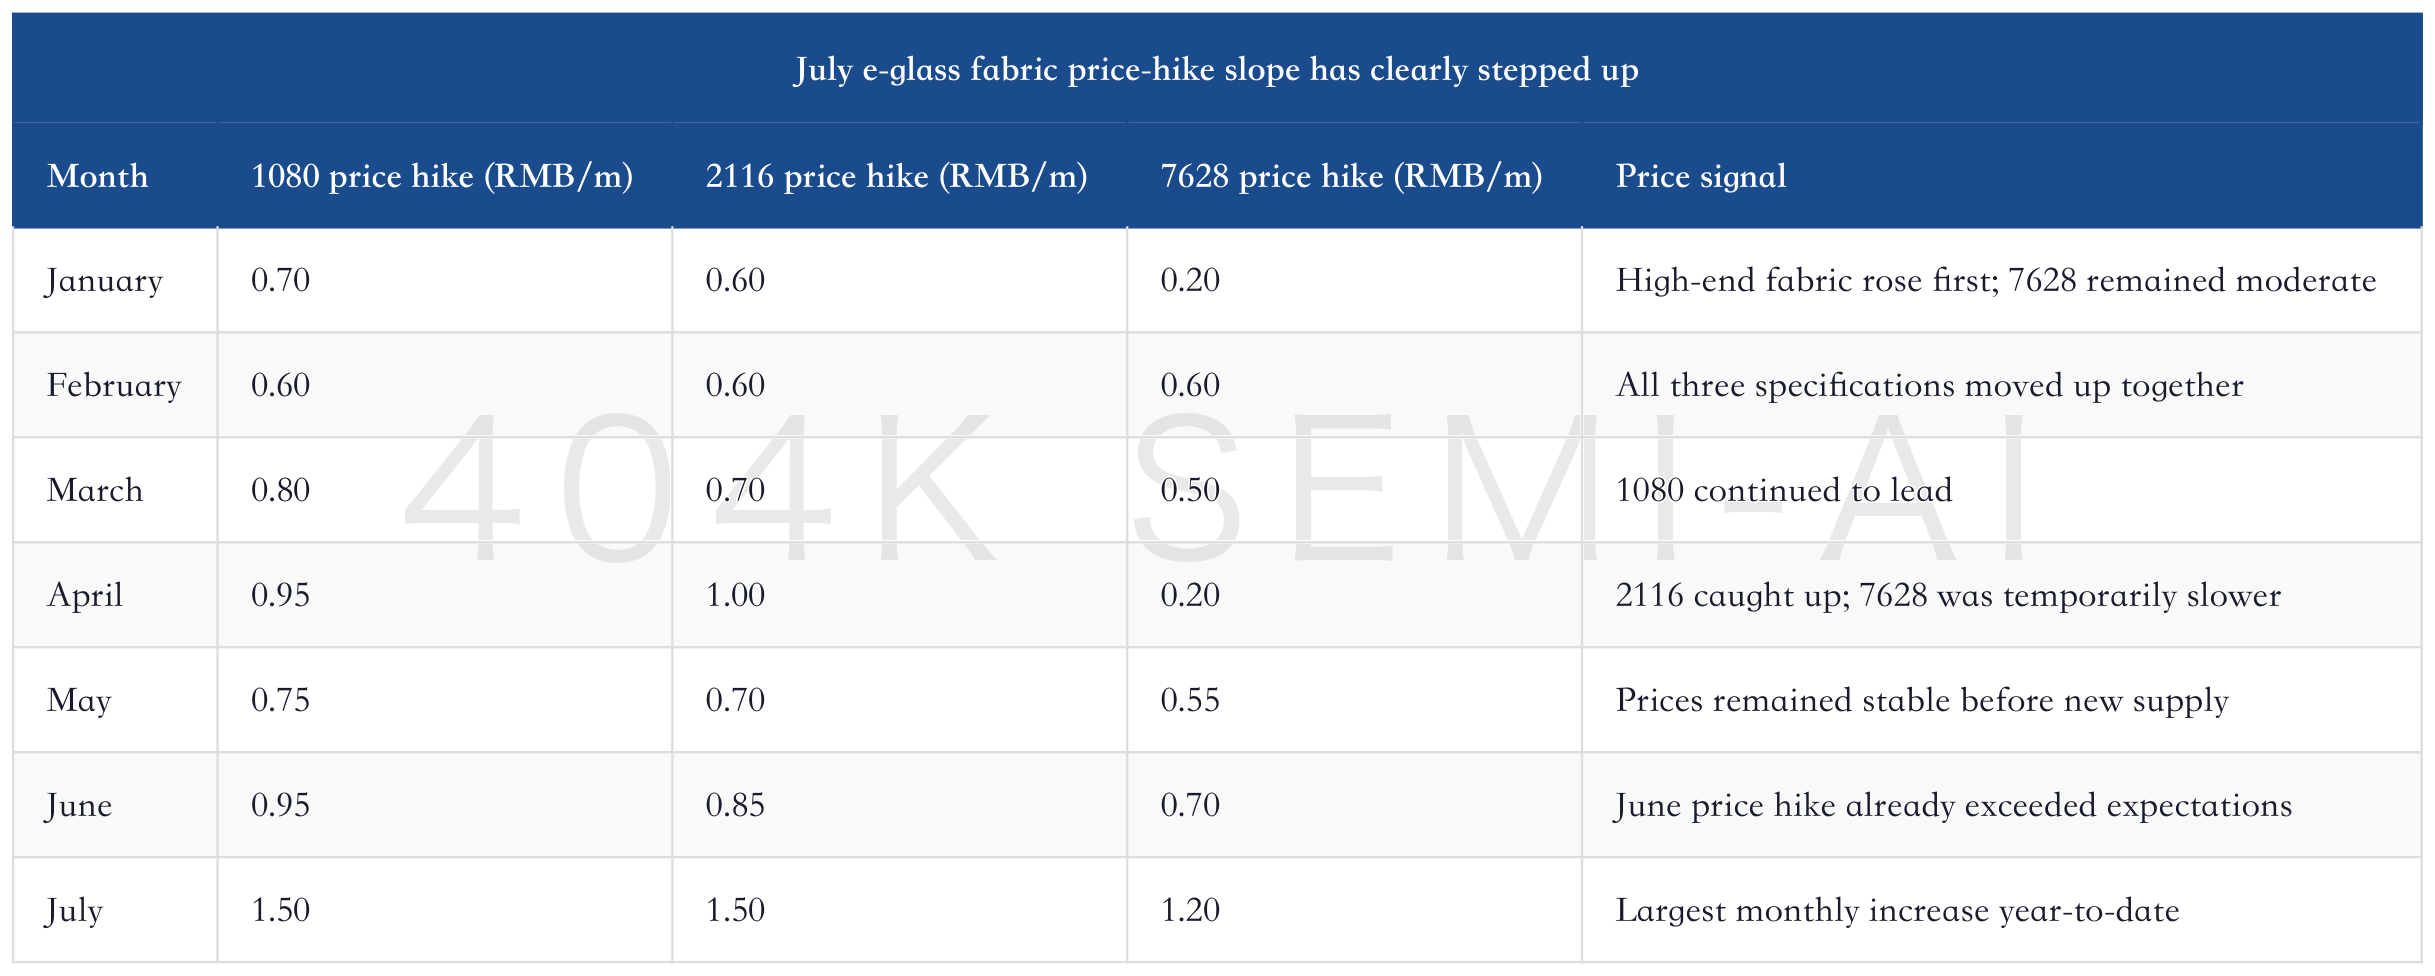
This table shows that July was not a normal continuation, but a step-up in slope. Monthly price increases for 1080 and 2116 expanded from RMB0.95 and RMB0.85 in June to RMB1.5; 7628 also expanded from RMB0.70 to RMB1.2. The widening price increases occurred after China Jushi added e-glass fabric capacity in May and after Kingboard itself added 96 million meters of annual capacity. That combination is critical.
Kingboard Laminates Deep-Dive Update: June CCL Rises Another 15%; Supply Constraints and the Nvidia Option Behind the HK$120 Target Price
The June update focused on another 15% increase in CCL and prepreg prices, showing that downstream copper-clad laminates can pass upstream costs on to customers. The new July evidence goes one step further: the upstream e-glass fabric price slope itself is still accelerating. If upstream prices are still rising, CCL price increases are not a one-off announcement, but a reason to continue re-rating margins.
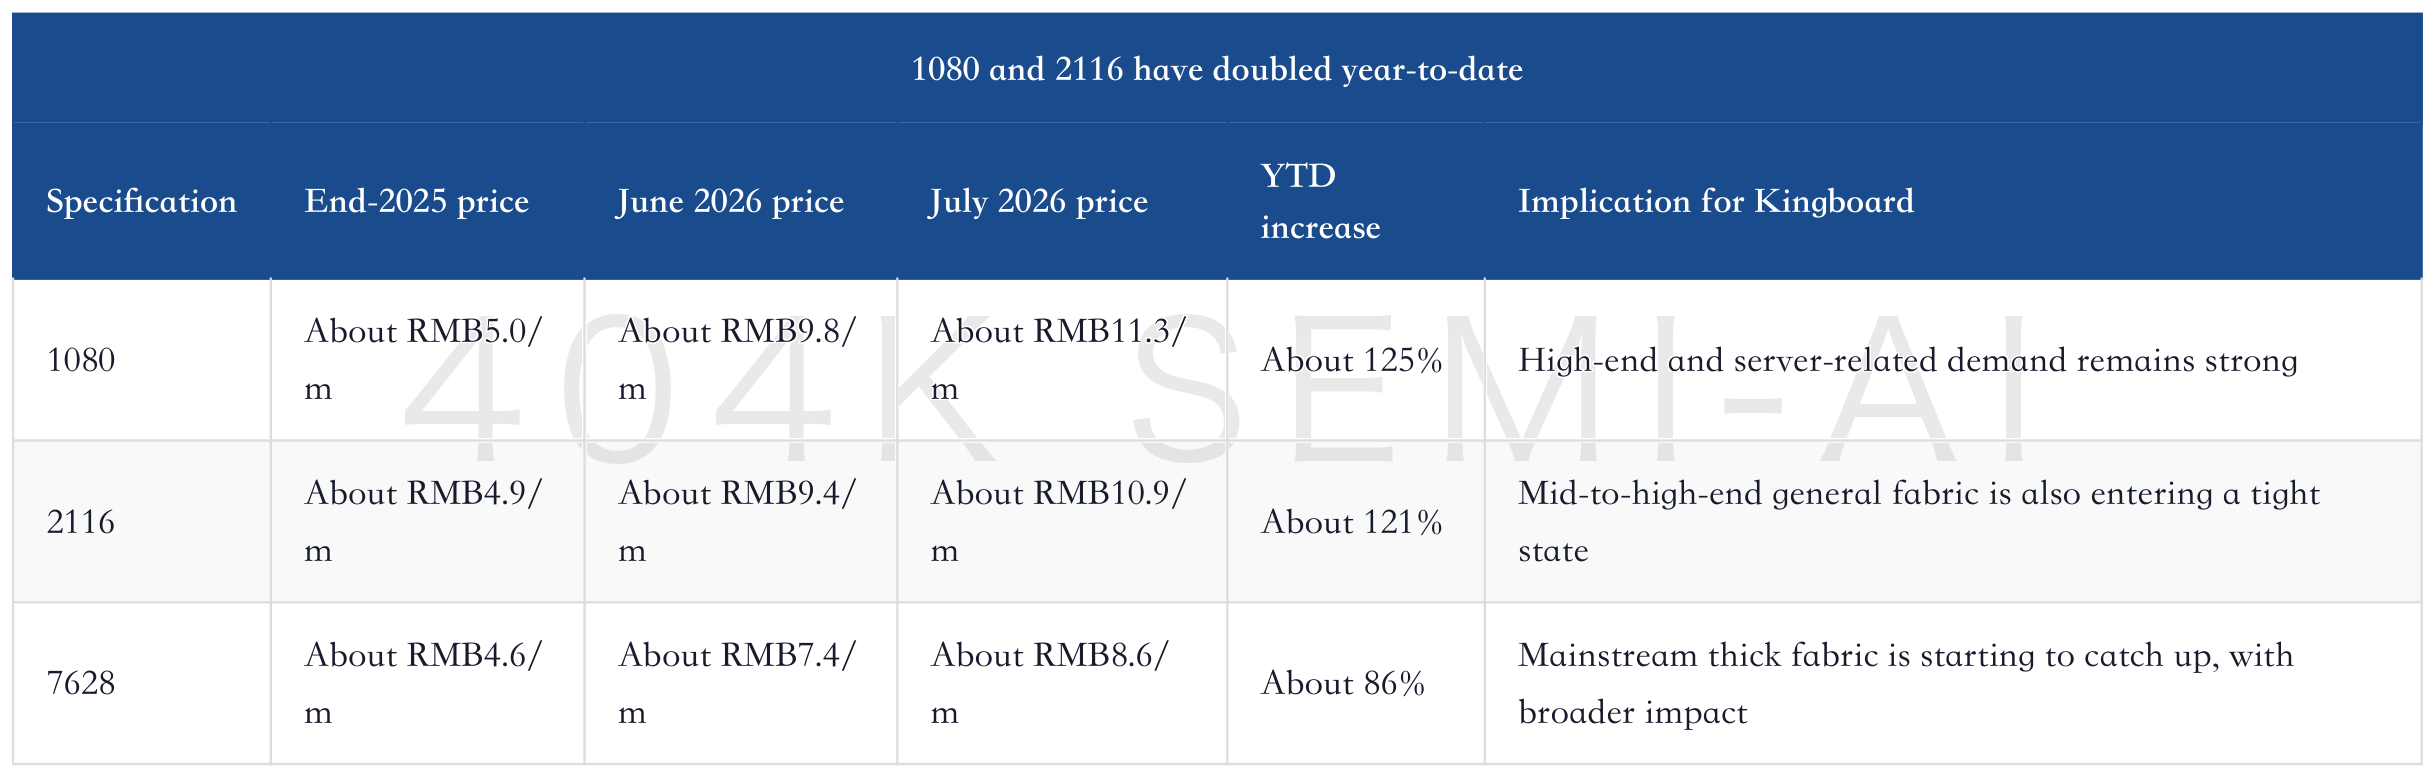
The change in 7628 deserves particular attention. 1080 and 2116 are easier to associate with high-end servers, HDI, and AI-related materials, while 7628 is closer to ordinary thick fabric and mainstream FR-4 systems. Continued price increases in 7628 show that supply tightness is not limited to a small number of high-end specifications, but is creating pressure across more basic grades.
In investment language, the July price signal pulls Kingboard Laminates' earnings elasticity back from a "high-end AI-fabric option" to its "ordinary e-glass fabric and CCL core business." That is actually more solid, because core-business price steps can directly enter revenue, gross margin, and cash flow.
2. Why New Capacity Still Cannot Cap Prices
The market's original biggest concern was a supply reversal. China Jushi started roughly 390 million meters of annual e-glass fabric capacity in May, equivalent to roughly 7%-9% of new industry supply. Kingboard Laminates also recently commissioned roughly 96 million meters of annual capacity, mainly for 7628 and 1080, lifting monthly capacity from roughly 57 million meters to 65 million meters, an increase of about 14% for the company and about 2% for the overall industry.
In a normal cycle, prices should at least slow after new capacity lands. But prices did not fall in June and July; instead, they rose more sharply. This abnormal pattern is more valuable for research than the price hikes themselves, because it shows the constraint is not "whether there are new lines," but "whether new lines can become effective supply that customers actually need."
China Jushi Deep Dive: Re-Rating the E-Glass Fiber Supply Bottleneck; How a Glass-Fiber Leader Becomes an AI PCB Materials Asset
AI PCB Phase Three: Expansion Is Not the Answer; Which Constraints Really Open Supply, from Glass-Fabric Looms, T-Glass, HVLP Copper Foil, Lamination and Drilling to Qualification Cycles
This is also consistent with the earlier judgment in the AI PCB series. The key in the materials chain is not nominal capacity expansion, but whether capacity can pass through looms, fabric grades, formulations, customer qualification, yield, and locked-in orders to become priceable supply. E-glass fabric is not a linear commodity industry where "capacity starts and prices immediately fall." High-end e-glass fabric and AI-fabric are closer to qualification-based materials.
Kingboard Laminates' advantage is also here. When ordinary CCL producers see e-glass fabric prices rising, their first reaction is cost pressure. Because Kingboard Laminates has its own e-glass fabric, copper foil, resin, and CCL systems, it sees both cost pressure and a profit source. As long as downstream customers accept CCL price increases, upstream price hikes can become gross-margin expansion.
3. Why 7628 Is the Detail Thread in This Update
The market can easily understand price increases in 1080 and 2116 because they are closer to high-end applications. The significance of 7628 is subtler and more important.
Kingboard Laminates management disclosed the following structure: 7628 accounts for about 65% of the company's e-glass fabric, 2116 accounts for about 5%-10%, and 1080 accounts for about 25%-30%. In other words, 7628 is the largest specification in Kingboard's e-glass fabric portfolio. Management also believes 7628 may become even tighter than 1080 in the future, because major e-glass fabric suppliers continue to upgrade their product mix and shift resources toward higher-value-added materials.
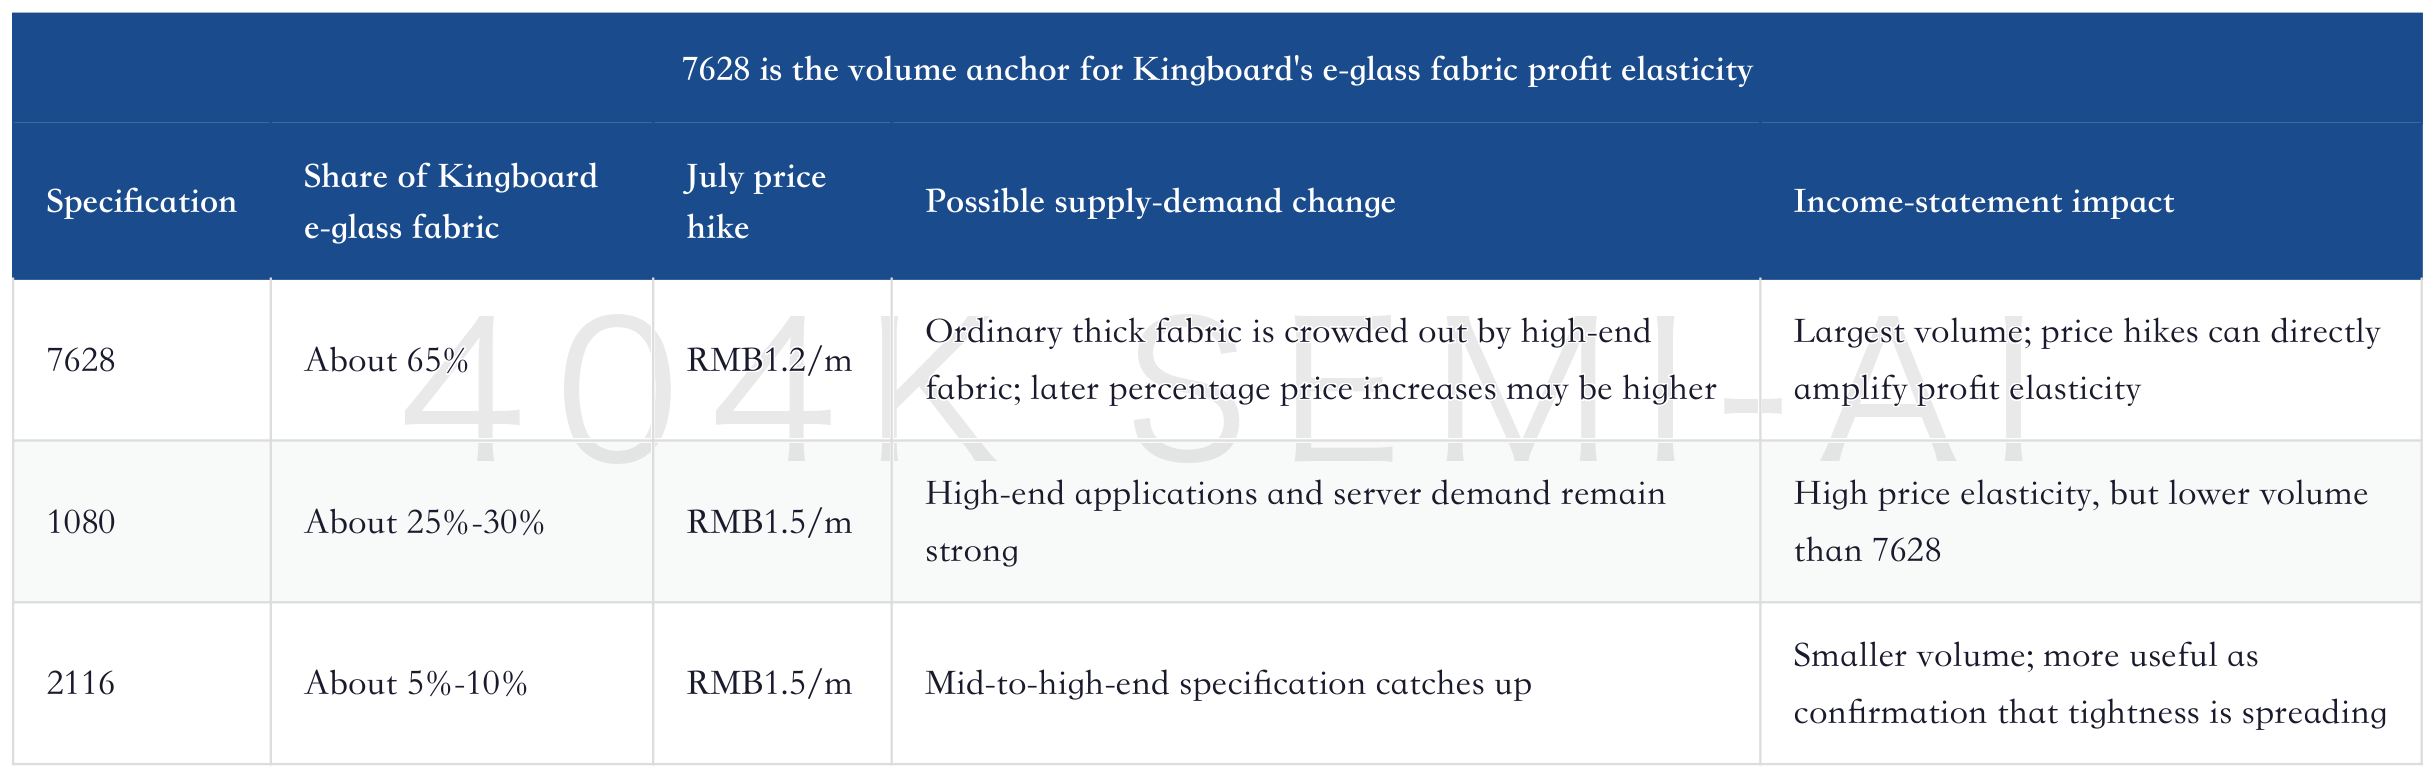
If one only watches 1080, Kingboard is understood as "high-end materials price elasticity." Once 7628 is included, the conclusion becomes "Kingboard's mainstream specifications are also entering a price-hike channel." That is the truly new information in the July update.
For Kingboard Laminates, 7628 has two functions.
First, 7628 is an amplifier for revenue and gross margin. It is not the most attractive AI material, but it is the largest part of Kingboard's e-glass fabric portfolio. The increase in 7628's per-meter price hike from RMB0.70 in June to RMB1.20 in July is more likely to enter the overall income statement than smaller-volume high-end fabric.
Second, 7628 is evidence of supply crowding. If ordinary thick fabric is also short, it means AI-fabric's crowding-out effect on looms and supply-chain resources has already affected basic specifications. High-end fabric price hikes can be explained by local strength in AI servers; when ordinary fabric also rises, it shows that industry supply allocation is being reprioritized.
