
目录
Executive Summary
I. What This Initiation Report Actually Changes
II. Why FR4 Is the Primary Earnings Engine for 2026–2027
III. Electronic Fiberglass Fabric: Nameplate Capacity Is Not AI-Qualified Capacity
IV. Why Toyota Looms Are Scarcer Than Furnaces
V. HVLP Copper Foil and High-End Copper-Clad Laminates: The Second Leg of Earnings Is Still Under Construction
VI. Margin Inflection: The Model’s Strongest—and Most Easily Misread—Element
VII. Cash Flow: The Real Stress Test Beyond the Income Statement
VIII. The Essence of Valuation: Not HK$58, but Whether the Cycle Peak Can Be Sustained
IX. What Has Changed Since the Previous Assessment
10. How to Validate the Thesis Over the Next 12 Months
11. Conclusion: Treat It First as a High-Beta Cyclical Play, Then Wait for Structural Earnings to Prove Themselves
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
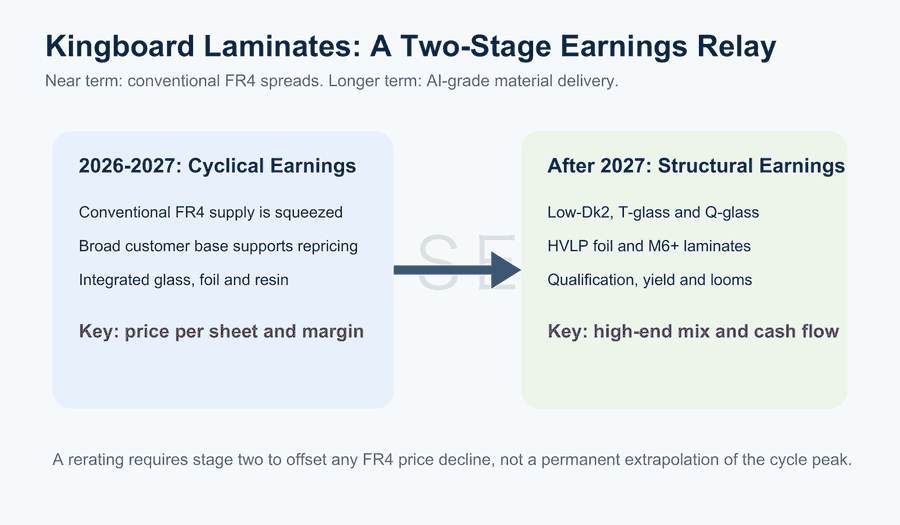
Kingboard Laminates is entering a two-stage earnings cycle: conventional FR4 will deliver the initial cyclical upside, while high-end fiberglass fabric and copper foil will determine whether earnings can hold above the cyclical peak.
Executive Summary
UBS’s initiation report identifies price increases for conventional FR4 copper-clad laminates as the primary earnings driver in 2026–2027, with AI-material contributions ramping thereafter. It forecasts revenue rising from HK$20.4 billion in 2025 to HK$68.75 billion in 2028 and net profit from HK$2.442 billion to HK$13.025 billion, driven by simultaneous improvements in pricing, product mix, and gross margin.
This FR4 upcycle differs from a conventional restocking cycle: more than 30% of global conventional copper-clad laminate capacity has reportedly shifted to high-speed and AI-grade materials, while demand for conventional products remains intact. UBS expects the price of conventional FR4 to rise from approximately HK$120 per sheet in 1Q25 and HK$140 at year-end to approximately HK$420 in 1H27. The more aggressive the price assumption, the greater the model’s dependence on supply discipline and end-market affordability.
AI-grade materials will determine whether the second earnings leg can take over. Low-DK1 is already in mass production, while Low-DK2 and T-glass are scheduled to enter volume production in 3Q26; Q-glass remains under qualification. Nameplate capacity for specialty fiberglass fabric is expected to increase from 10 million meters in 2025 to 56 million meters in 2028. However, qualification, yields, and Toyota looms—not nameplate capacity—are the real constraints on effective supply.
High-end materials offer substantially better unit economics than standard products. UBS estimates monthly gross profit per loom at approximately RMB110,000 for standard 7628 electronic fiberglass fabric, RMB150,000 for Low-DK1, and RMB600,000 for Low-DK2 and T-glass. Meanwhile, HVLP copper foil remains at an early stage of qualification and capacity expansion. AI-related products are expected to contribute only approximately 15% of total gross profit by 2028, so near-term earnings should not be mistaken for evidence that the structural transformation is already complete.
The greatest valuation risk is extrapolating peak-cycle earnings indefinitely. UBS’s base-case price target is HK$58, equivalent to 17x 2027E P/E; its downside and upside scenarios are HK$26.48 and HK$74.50, respectively. Over the next 12 months, investors must validate FR4 pricing, specialty fiberglass-fabric volume production, loom deliveries, yields, and operating cash flow simultaneously.
I. What This Initiation Report Actually Changes
Kingboard Laminates has been widely discussed in recent months, and none of the key themes—electronic fiberglass-fabric price increases, AI-server material upgrades, HVLP copper foil, or vertical integration—is new. The real contribution of UBS’s initiation report, published on August 10, 2026, is that it resequences the earnings narrative. In 2026–2027, earnings are initially driven by contracting supply and higher prices for conventional FR4 copper-clad laminates. From 2027 onward, high-end fiberglass fabric, HVLP copper foil, and higher-grade copper-clad laminates progressively contribute a second, more structural earnings leg.
This sequencing matters. Characterizing Kingboard Laminates simply as an AI-materials company overlooks the fact that conventional products still generate the overwhelming majority of revenue and profit. Treating it solely as an FR4 price-cycle trade, however, ignores the high-end material capabilities now under development. A more accurate framework is to view the company as two businesses: a conventional copper-clad laminate cycle, where capacity migration creates pricing and margin leverage; and an AI-grade material upgrade cycle, where qualification, yields, equipment, and customer mix determine whether higher earnings can be sustained.
UBS forecasts Kingboard Laminates’ revenue increasing from HK$20.4 billion in 2025 to HK$37.272 billion in 2026, HK$56.642 billion in 2027, and HK$68.75 billion in 2028. Over the same period, net profit rises from HK$2.442 billion to HK$6.654 billion, HK$10.465 billion, and HK$13.025 billion. This implies approximately 2.4x revenue growth and 4.3x net-profit growth over three years, with earnings materially outpacing sales. The step-change in profitability is driven primarily by overall gross margin expanding from 19.6% to 29.2%, 30.1%, and 30.4%.
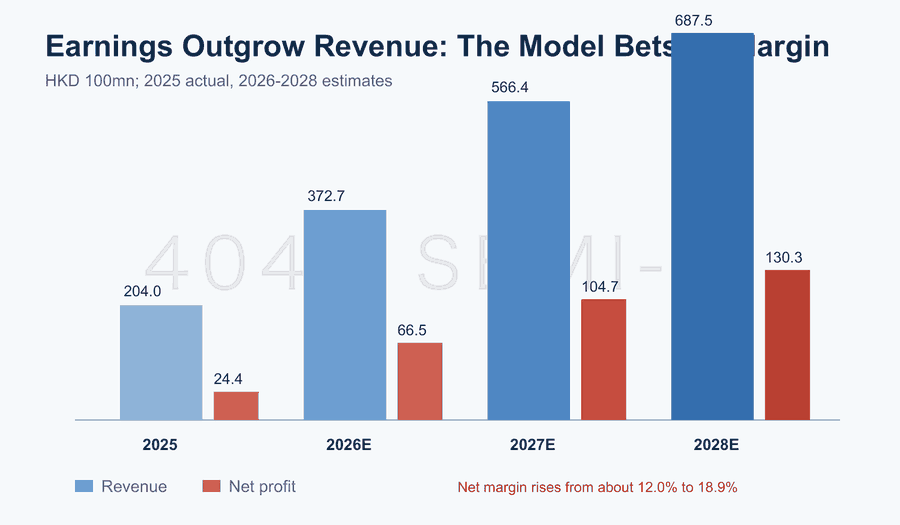
This underpins the report’s central conclusion: there is substantial industry evidence supporting near-term earnings upgrades, but a sustained rerating still requires the second earnings leg to replace the first cyclical upswing. If FR4 prices peak before high-end material shipments, yields, and customer qualifications scale, the company will continue to be valued on peak-cycle earnings. Its asset characteristics will change only when AI-grade materials contribute a steadily rising share of revenue, gross profit, and cash flow.
For an overview of Kingboard Laminates’ vertical integration, see Kingboard Laminates Deep Dive: Electronic Fiberglass Fabric and Copper-Clad Laminates Enter an AI Upcycle—How Should Materials Integration Revalue a CCL Leader?. The incremental value of UBS’s new model lies primarily in its earnings trajectory, supply constraints, and failure conditions.
II. Why FR4 Is the Primary Earnings Engine for 2026–2027
FR4 is the most widely used glass-reinforced epoxy copper-clad laminate. It is found across consumer electronics, home appliances, power supplies, automotive electronics, communications equipment, and servers. Historically, it has behaved more like a scale-manufactured product than a scarce, high-end material. The typical cycle involved recovering end demand, channel restocking, rising upstream material costs, and copper-clad laminate price increases, followed by new supply and slowing demand that pushed prices back down.
What distinguishes the current cycle is the deliberate displacement of conventional capacity by higher-end products. Citing industry research, UBS states that more than 30% of global conventional copper-clad laminate capacity has shifted to high-speed and AI-grade laminates compared with 2021. The production lines have not disappeared; they are now occupied by higher-value products. Meanwhile, conventional FR4 demand from home appliances, power supplies, automobiles, and servers remains intact, creating an unusual supply gap: the stronger the demand for AI materials, the tighter the market becomes for conventional materials.
Industry concentration further amplifies this dynamic. UBS estimates that the world’s ten largest copper-clad laminate producers collectively hold approximately 80% market share, including approximately 12% for Kingboard Laminates, 13% for Shengyi Technology, 16% for Elite Material, and 8% for Nan Ya Plastics. Other leading producers likewise maintain established customer bases and product specializations. High concentration does not give manufacturers unlimited pricing power, but when most leading suppliers redirect resources toward high-speed materials, conventional capacity recovers more slowly than in a normal cycle.
The price trajectory is therefore the model’s most sensitive variable. The report notes that conventional FR4 prices increased from approximately HK$120 per sheet in 1Q25 to approximately HK$140 per sheet at the end of 2025. Prices at least doubled in 2026 and exceeded the 2021 peak; the base-case model further assumes approximately HK$420 per sheet in 1H27. Under the three scenarios, 2027 FR4 prices are HK$206, HK$382, and HK$426 per sheet, respectively—a range of more than 1x.
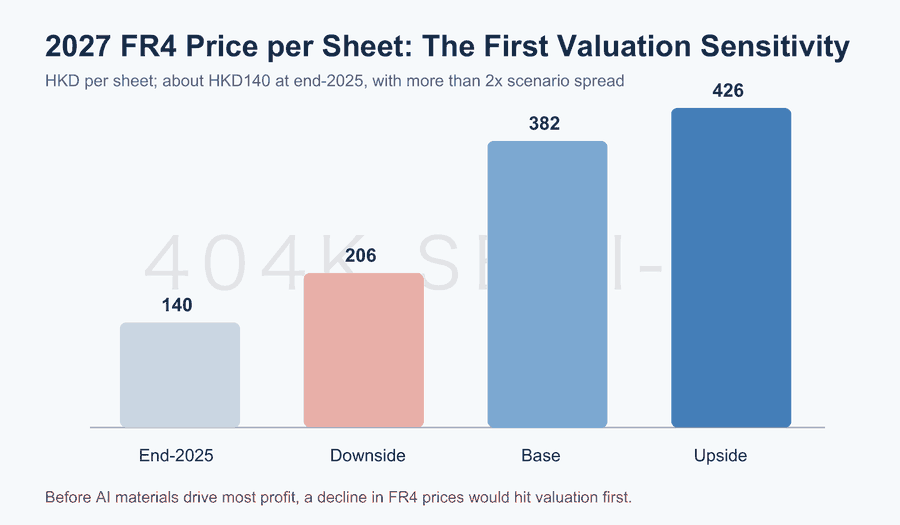
Such a steep pricing assumption requires three conditions to hold simultaneously. First, production lines shifted to AI materials cannot rapidly revert to conventional FR4, or returning supply would end the shortage. Second, end customers must remain able to absorb further increases, particularly home-appliance and mainstream consumer-electronics customers with thinner margins. Third, rising costs for upstream electronic fiberglass fabric, copper foil, and resin cannot consume the pricing gains.
UBS is relatively constructive on the third condition. It estimates that an approximately HK$30-per-sheet price increase in June 2026 corresponded to an increase of approximately HK$5 per sheet in E-glass electronic fiberglass-fabric costs. Assuming no material deterioration in other costs, at least half of the incremental price increase should flow through to gross profit. Kingboard Laminates also owns fiberglass-fabric, copper-foil, resin, and copper-clad laminate capacity, meaning raw-material inflation is not entirely an external cost; part of it is captured as profit by its upstream operations.
This is the near-term value of vertical integration. For a standalone copper-clad laminate producer, higher fiberglass-fabric prices are primarily a cost. For Kingboard Laminates, they raise internal transfer costs but also expand the upstream profit pool and provide justification for finished-product price increases. As long as finished-product prices rise faster and by more than aggregate costs, group gross margin improves. UBS forecasts revenue from the glass-fabric-based copper-clad laminate segment growing 113% in 2026 and 63% in 2027, with segment gross margin increasing from approximately 21% in 2025 to approximately 33% in 2026 and approximately 32% in 2027.
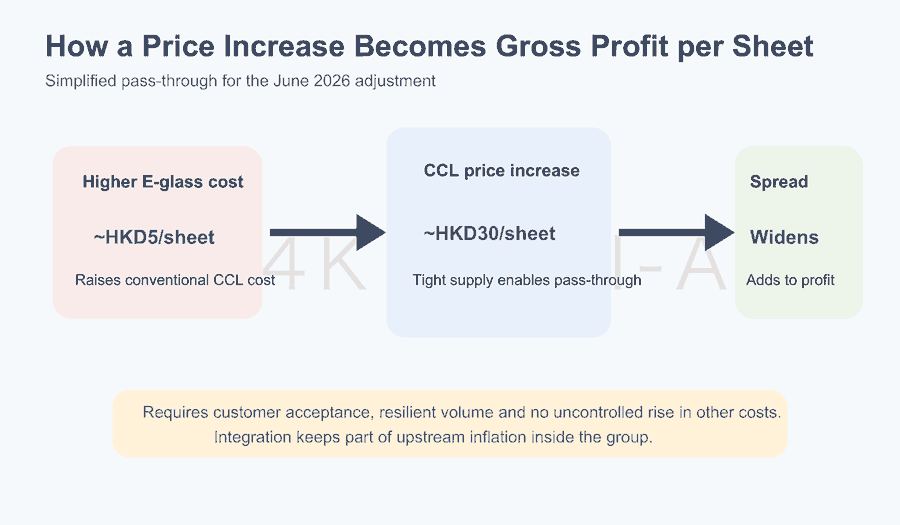
This transmission mechanism should not be interpreted as “the more raw-material prices rise, the better.” If high prices destroy end demand, customers may reduce orders or switch to lower-specification materials, causing volume to fall before pricing gains are realized. If upstream supply recovers, Kingboard Laminates could face declining fiberglass-fabric and FR4 prices simultaneously. Earnings leverage in 2026–2027 is therefore substantial, but it remains cyclical profit created by a supply-demand mismatch—not evidence that the company has already secured permanent pricing power.
