
JX Advanced Metals Deep Dive: 10x InP Substrate Expansion, Semiconductor Target Ramp-Up, and Copper Recycling Earnings Support
目录
TL;DR
I. What Does JX Advanced Metals Actually Sell? Three Earnings Curves
II. InP Substrates: How a Small Business Becomes a Major Earnings Variable
3. Semiconductor Sputtering Targets: A Stable Earnings Foundation Behind Advanced Process Nodes
4. ICT Materials and Tantalum-Niobium: AI Servers Continue to Drive Connector, Copper-Foil, and Capacitor Materials
V. Copper Recycling and Mining: Earnings Support for JX Advanced Metals, but Also Cyclical Volatility
VI. Breaking Down the Valuation: What Supports Nomura’s ¥4,800 Price Target
7. The Key Bear Case: Could InP Become Oversupplied?
8. What to Watch Over the Next Four Quarters: Look Beyond the Target Price
9. Investment Conclusion: JX Advanced Metals’ Value Lies in Materials Bottlenecks, Not Thematic Labels
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The key change at JX Advanced Metals is that InP substrates are moving from a small peripheral business into a core earnings driver. Nomura upgraded the stock to Buy and raised its target price to ¥4,800, reflecting simultaneous revisions to three earnings pillars: a 10x capacity expansion, accelerating semiconductor target sales, and downside support from copper recycling. Sell-side models are already pricing in a widening earnings inflection for FY2027/3 and FY2031/3.
TL;DR
Nomura’s upgrade reflects a wholesale earnings-model reset. Nomura upgraded JX Advanced Metals from Neutral to Buy and raised its target price to ¥4,800, implying approximately 25% upside from the closing price. More importantly, its earnings estimates are materially above company guidance, with the key differences centered on InP substrates, semiconductor targets, copper prices, and foreign exchange.
InP substrates are becoming the largest source of earnings upside. Nomura sees JX Advanced Metals’ InP business as a future earnings lever, based on capacity expanding toward 10x while pricing remains strong. If customer qualifications and the expansion schedule proceed as expected, the Semiconductor Materials segment could shift from an earnings base into the central pillar of the company’s valuation.
Supply bottlenecks give JX pricing power. Third-party merchant supply in the InP substrate market is highly constrained. JX and AXT are the main external suppliers, while Sumitomo Electric’s output is largely consumed internally by its optical-device operations. Chinese export licensing, lengthy customer qualification cycles, and AI data-center optical-interconnect demand are combining to make overseas customers more willing to secure supply from stable vendors such as JX.
The target business underpins the valuation floor. JX Advanced Metals holds a high global share in semiconductor sputtering targets, and its new Hitachinaka plant is taking capacity to 1.6x FY2023 levels. Advanced logic, HBM, TSV, backside power delivery, and additional metal interconnect layers will transform targets from cyclical consumables into process-critical materials. This is the most important earnings foundation outside InP.
Copper recycling provides cash-flow support. Metals & Recycling remains the largest current profit contributor. The company has sold part of its interest in Caserones while retaining its core stake and preferential offtake rights for mine products. This indicates that management is recycling mining capital into semiconductor-material capacity expansion, although copper prices and the yen will continue to affect near-term earnings.
The valuation hinges on three sets of confirmation signals. Nomura’s target price assumes a higher earnings contribution from semiconductor materials. That multiple requires support from the InP expansion, higher target volumes, and copper-business cash flow. Key indicators to monitor are the InP capacity ramp, InP pricing, semiconductor target volumes, and whether company guidance moves progressively closer to sell-side estimates.
I. What Does JX Advanced Metals Actually Sell? Three Earnings Curves
JX Advanced Metals combines three types of assets: InP substrates and semiconductor targets tied to AI optical interconnects; rolled annealed copper foil, copper-titanium alloys, and high-purity tantalum powder used in AI servers; and copper mining, smelting, and recycling operations that underpin cash flow.
The company has already delivered a strong set of FY2026/3 results, with a more diversified quality of growth than a single-theme investment. Earnings sources are broad, with copper prices, the yen, mining interests, and rising AI data-center material volumes all contributing.
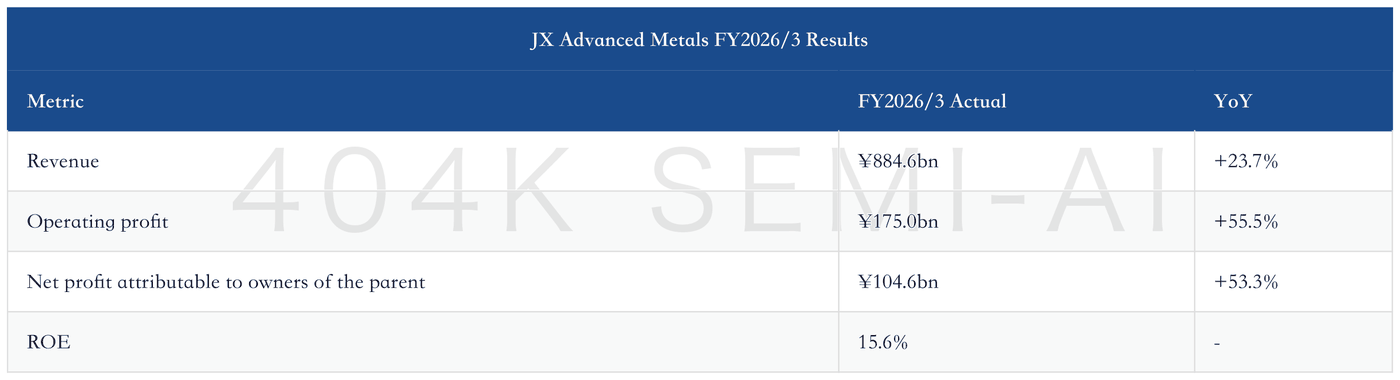
Official guidance for the next fiscal year is clearly conservative, while Nomura’s model is more aggressive. The gap is substantial, reducing the investment debate to one question: should JX Advanced Metals be valued as a cyclical mining and materials stock, or receive a higher multiple as a supplier of bottleneck materials upstream of AI?
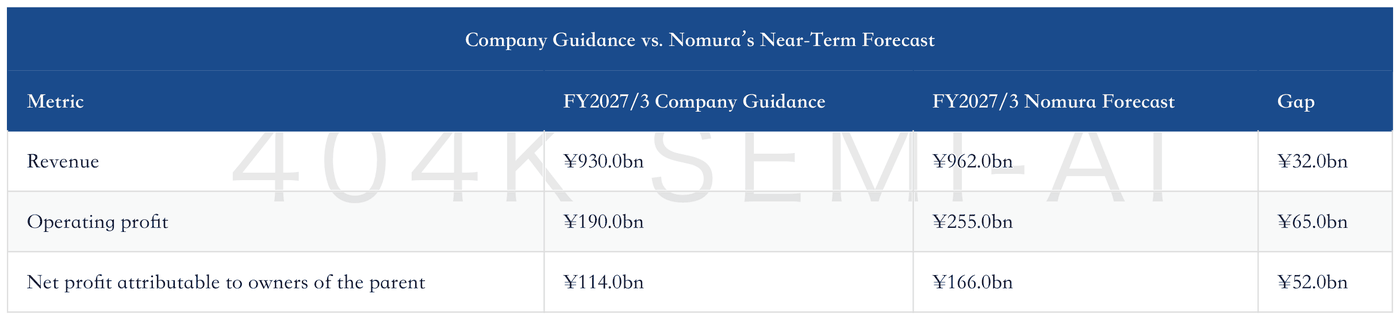
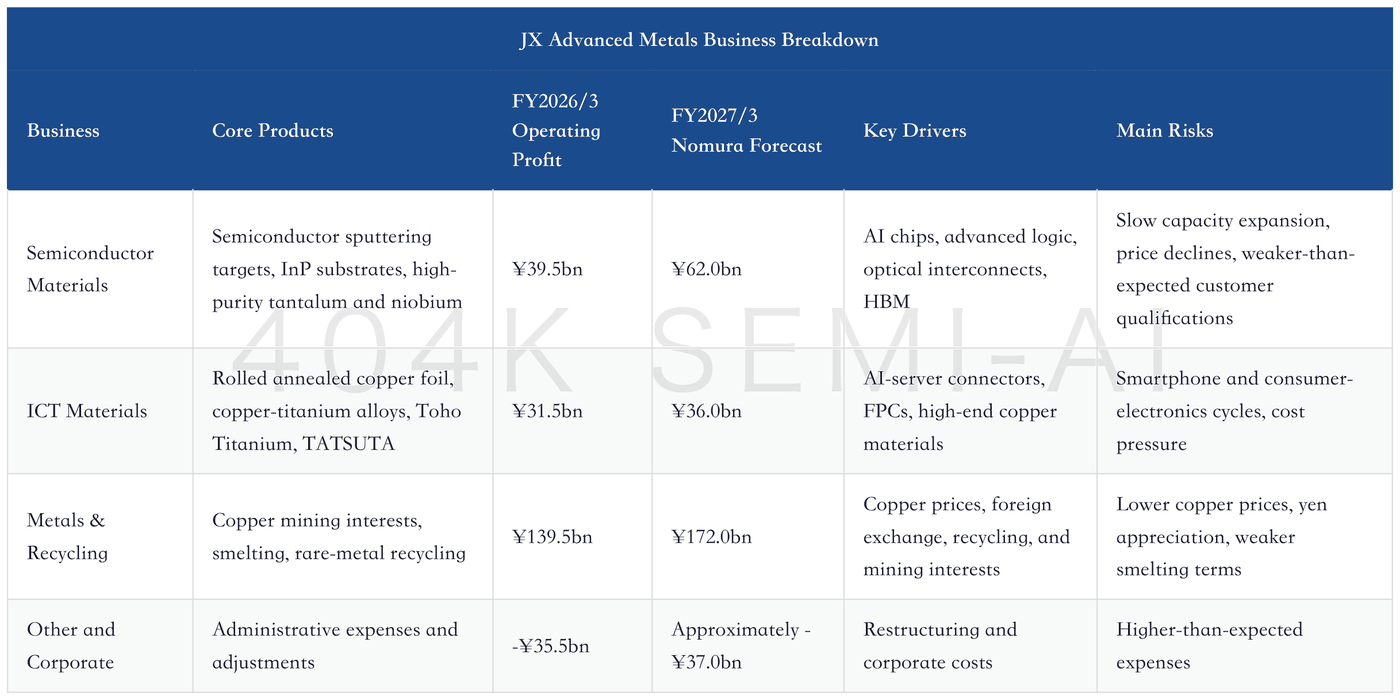
This table explains why the market can easily underestimate JX Advanced Metals. Metals & Recycling remains the largest current profit contributor, but Semiconductor Materials offers the greatest future earnings leverage. Nomura’s upgrade shifts the market’s attention from “how much profit did copper prices contribute?” to “can Semiconductor Materials become a much larger earnings pool?”
From a financial perspective, JX Advanced Metals’ asset mix is shifting from resource-intensive operations toward high-margin materials. On the company’s figures, the Semiconductor Materials operating margin was 22.3% in FY2026/3, while FY2027/3 guidance implies 25.0%. The official long-term target is 25%-30%. Metals & Recycling generates more profit but is more exposed to copper prices, foreign exchange, and changes in mining interests. Semiconductor Materials has higher margins and is also more likely to command a valuation premium.
JX Advanced Metals’ exposure to AI optical interconnects can be traced from upstream materials down the value chain. Optical-module manufacturers require photonic chips; photonic chips require epitaxial wafers; and epitaxial wafers require InP substrates. Advanced-node GPUs, ASICs, and CPUs require more metal interconnects, whose fabrication depends on high-purity sputtering targets. AI-server connectors, cables, FPCs, and capacitor materials also use copper-titanium alloys, rolled annealed copper foil, and high-purity tantalum powder. JX Advanced Metals occupies precisely these critical material nodes.
AI Optical-Module Demand Revised Higher Again: How Morgan Stanley’s May Report Extends the 1.6T, InP, and CPO Bottlenecks Through 2028
The earlier optical-module and CPO series focused on system architecture and module content value. This JX Advanced Metals analysis moves one step further upstream. As optical-interconnect deployment expands, the market is increasingly likely to trace bottlenecks beyond module and optical-component manufacturers to substrates, targets, epitaxy, and critical consumables. JX Advanced Metals’ investment case becomes clearer along this upstream chain.
II. InP Substrates: How a Small Business Becomes a Major Earnings Variable
InP substrates can be understood simply as the “baseplate” for many high-speed optical devices. Optical-device manufacturers grow epitaxial layers and fabricate chips on these substrates, ultimately producing lasers, detectors, modulators, and other devices used in data-center optical modules, base stations, long-haul communications, and, eventually, shorter-reach board-to-board and intra-rack optical links.
JX Advanced Metals’ website lists the applications for InP substrates directly: light-emitting devices, photodetectors, high-speed electronic devices, and infrared detectors, serving optical modules, mobile base stations, and data centers. Nomura links the business to AI data centers because 800G, 1.6T, and 3.2T optical modules, silicon photonics, CPO, and OCS are all increasing demand for high-speed light sources and detectors. As long as electrical signaling remains inadequate within clusters, demand for optical materials will continue to rise.
Nomura’s InP assumptions are aggressive, but the logic is straightforward. JX Advanced Metals plans to expand InP substrate capacity to 7-10x the FY2026/3 baseline by FY2031/3, while Nomura’s model assumes the full 10x. It also raises the ASP index from 6 to 12, implying a doubling in price. The combination of these two variables significantly amplifies revenue and earnings leverage.
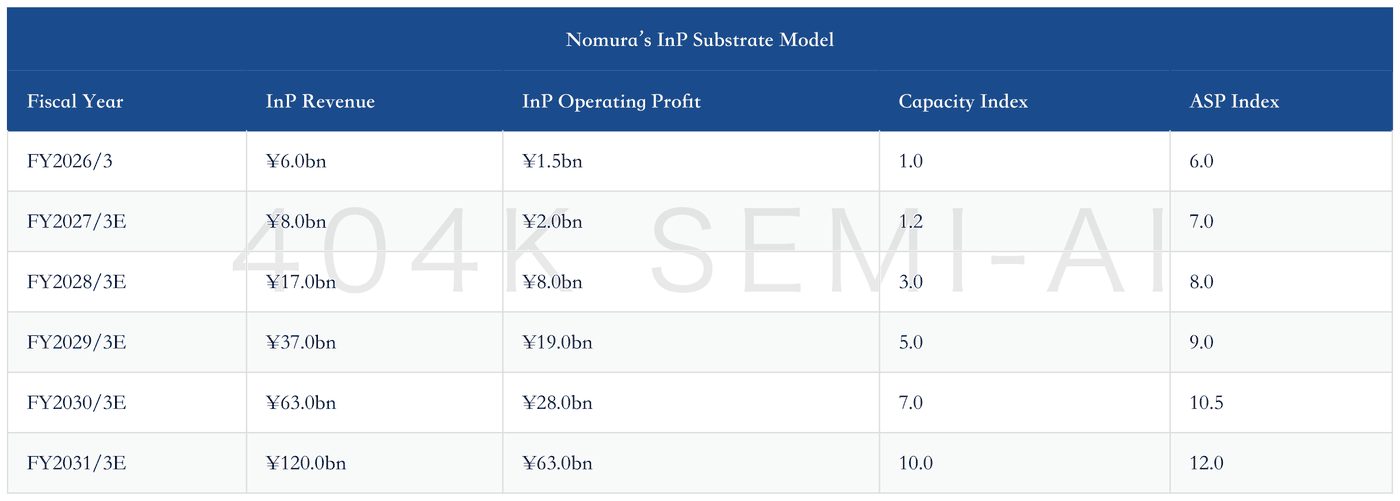
The increase appears dramatic, but the underlying supply-demand logic is relatively clear. First, the merchant market for InP substrates is small, with JX Advanced Metals and AXT serving as the principal third-party suppliers. Although Sumitomo Electric has a high market share, much of its capacity supports internal optical-device demand, leaving limited volumes available to external customers. Second, Chinese export licensing has made deliveries from China-based supply chains such as AXT’s more complex, leading customers to assign a higher security-of-supply premium to non-Chinese sources. Third, optical-device customer qualification typically takes one to two years, so customers are unlikely to switch suppliers casually in response to short-term price fluctuations.
Market tightness is also visible in pricing. Citing expert interviews, Nomura notes that prices for 3-inch InP substrates in China have risen from approximately RMB1,800 at the end of 2025 to around RMB3,200 currently. Prices outside China are higher, with some buyers accepting prices two to three times previous levels. For JX Advanced Metals, price increases flow into earnings faster than capacity expansion. Once fixed-cost absorption and yield ramp-up cross the threshold, incremental ASP gains directly lift gross margins.
The AI Light-Source Battle Is Not a Speed Race: InP, VCSEL, and μLED Address Different Distances
The InP investment case cannot be reduced to the statement that “optical modules are getting faster.” VCSEL is more suited to short-reach applications and specific cost bands, while InP is better suited to long-distance, high-speed, and high-performance light sources and detectors. As AI clusters extend optical connectivity from inter-data-center links to inter-rack, intra-rack, board-level, and eventually near-package connections, each distance segment will adopt different light-source solutions. JX Advanced Metals benefits because it supplies a foundational material that many high-performance solutions cannot avoid.
The timetable in official announcements is more conservative than Nomura’s model. In February 2026, JX Advanced Metals announced approximately ¥20.0bn of additional investment to triple InP substrate capacity by 2030 relative to 2025 levels, with phased production beginning in FY2027. Nomura’s report also incorporates the company’s subsequently more aggressive expansion target of raising capacity to 7-10x by FY2031/3. One point is critical: if the company were merely promoting a thematic narrative, it would not have repeatedly raised its capacity targets in July 2025, October 2025, February 2026, and June 2026. The successive increases indicate clear customer demand for medium- to long-term supply.
Three factors require close monitoring in JX Advanced Metals’ InP business. First, whether expansion capex is deployed on schedule, particularly new-equipment commissioning, yields, and capacity ramp-up. Second, whether major customers are willing to sign long-term supply agreements or pricing frameworks. Even if the company does not disclose customer names, signals may be visible in pricing, customer advances, inventories, and utilization rates. Third, whether Chinese export licensing or competitor capacity constraints ease. If supply restrictions loosen, the market will first challenge JX Advanced Metals’ ASP assumptions.
3. Semiconductor Sputtering Targets: A Stable Earnings Foundation Behind Advanced Process Nodes
InP provides upside elasticity, while semiconductor targets provide the earnings foundation. JX Advanced Metals holds an approximately 64% global share of semiconductor sputtering targets, a core asset highlighted by both Goldman Sachs’ earlier coverage and company materials. Sputtering targets may sound like commodity consumables, but their barriers to entry lie in purity, particle control, process stability, equipment compatibility, and customer qualification. In advanced process nodes, a problem with a single material can affect wafer yields.
Target demand rises with advanced-node complexity. Advanced logic nodes require more interconnect layers and more complex metal materials; HBM drives demand related to TSVs and advanced packaging; and the continued performance scaling of AI ASICs, GPUs, and CPUs increases consumption of high-purity copper, tantalum, titanium, and other targets. Nomura expects JX Advanced Metals’ semiconductor-target sales to grow at a CAGR of approximately 21% from 2026/3 to 2031/3, well above global silicon-wafer shipment growth. This indicates that the company is benefiting from rising material intensity in advanced process nodes.
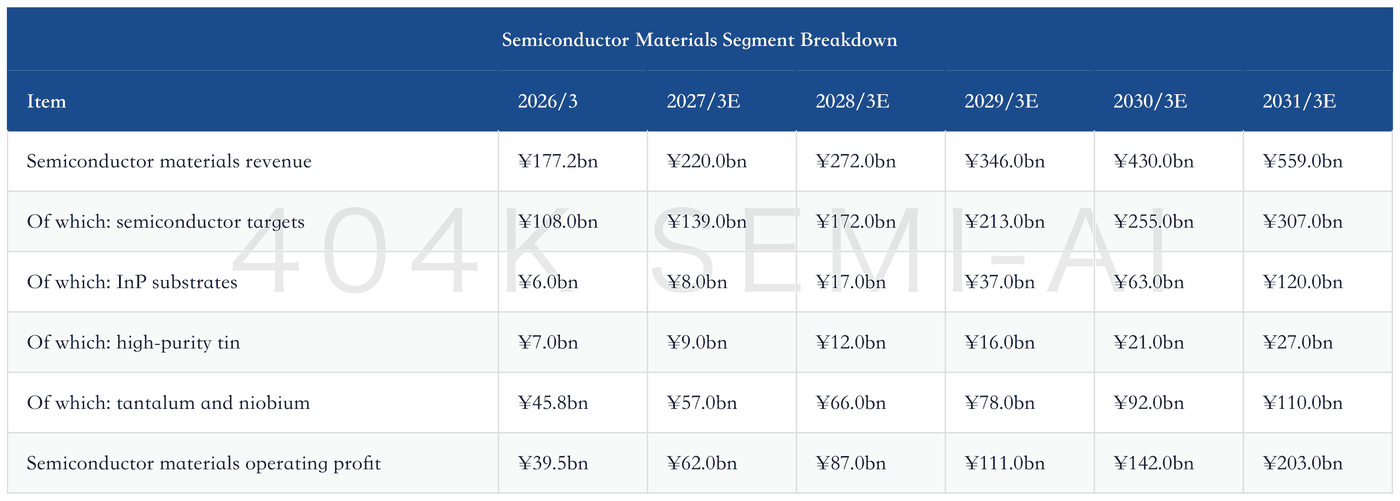
The company’s announced capacity expansion provides visibility for this business. In March 2026, JX Advanced Metals announced an additional investment of approximately ¥23.0bn at its New Hitachi-Naka Plant for semiconductor sputtering targets. This is included in the approximately ¥150.0bn total investment in the new plant announced in March 2024. The company aims to increase semiconductor sputtering-target capacity to 1.6 times the FY2023 level, with operations beginning in the second half of FY2027. This is a concrete expansion plan backed by factories and equipment.
The target business’s greatest strength is its integration with major customers’ processes. Advanced logic foundries will not readily switch target suppliers merely for lower prices, as changing materials requires revalidating process windows and equipment conditions while introducing yield risk. JX Advanced Metals has achieved its high market share through long-term supply relationships, material purity, product breadth, and compatibility with the equipment ecosystem. Goldman Sachs’ earlier report noted the company’s long-standing compatibility with mainstream equipment platforms such as Applied Materials’ Endura. This integration makes incremental demand more likely to flow naturally to incumbent suppliers.
As AI chips continue to concentrate on advanced process nodes, target demand will rise through three channels. First, more front-end interconnect layers mean additional metal-deposition steps. Second, advanced packaging and HBM create material demand for TSVs, RDL, and related applications. Third, new processes such as backside power delivery may alter metal-layer structures and create new target-qualification opportunities. For JX Advanced Metals, each increase in process complexity effectively raises customers’ switching costs.
CPO Bull-Market Expectations Cool: Architectural Competition Cannot Stop Optical Growth as AI Clusters Enter the Optical-Interconnect Era
JX Advanced Metals’ position in system architectures such as CPO, NPO, and OCS lies further upstream in materials. Market discussions of CPO often focus first on optical modules and switches. But when the industry begins building capacity in earnest, capital will look further upstream for bottlenecks in epitaxial wafers, substrates, targets, package-substrate materials, and critical consumables. JX Advanced Metals sits squarely in this position.
4. ICT Materials and Tantalum-Niobium: AI Servers Continue to Drive Connector, Copper-Foil, and Capacitor Materials
JX Advanced Metals’ second AI exposure lies in ICT materials and tantalum-niobium materials. It is less dramatic than InP and less directly tied to advanced process nodes than targets, but it occupies a stable position in the incremental material demand generated by AI servers.
The company reported FY2026/3 ICT materials operating profit of ¥31.5bn, with official FY2027/3 guidance of ¥32.0bn and Nomura forecasting ¥36.0bn. Growth is lower than in semiconductor materials, but two products merit attention: rolled annealed copper foil and copper-titanium alloys. According to Goldman Sachs’ earlier report, JX Advanced Metals holds an approximately 78% global share of rolled copper foil for FPCs and also has a high share in copper-titanium alloys. Upgrades to internal AI-server connections, cabling, connectors, high-speed transmission, and thermal-management structures will continue to consume high-end copper materials.
Company materials also identify AI data centers as a growth driver for ICT materials. In its FY2027/3 guidance, the Functional Materials business benefits from higher sales of rolled annealed copper foil and copper-titanium alloys for AI data centers, although foreign-exchange movements, the situation in the Middle East, and other cost factors will offset part of the earnings contribution. This business lacks InP’s upside elasticity, but it means JX Advanced Metals is not dependent on a single optical-substrate product.
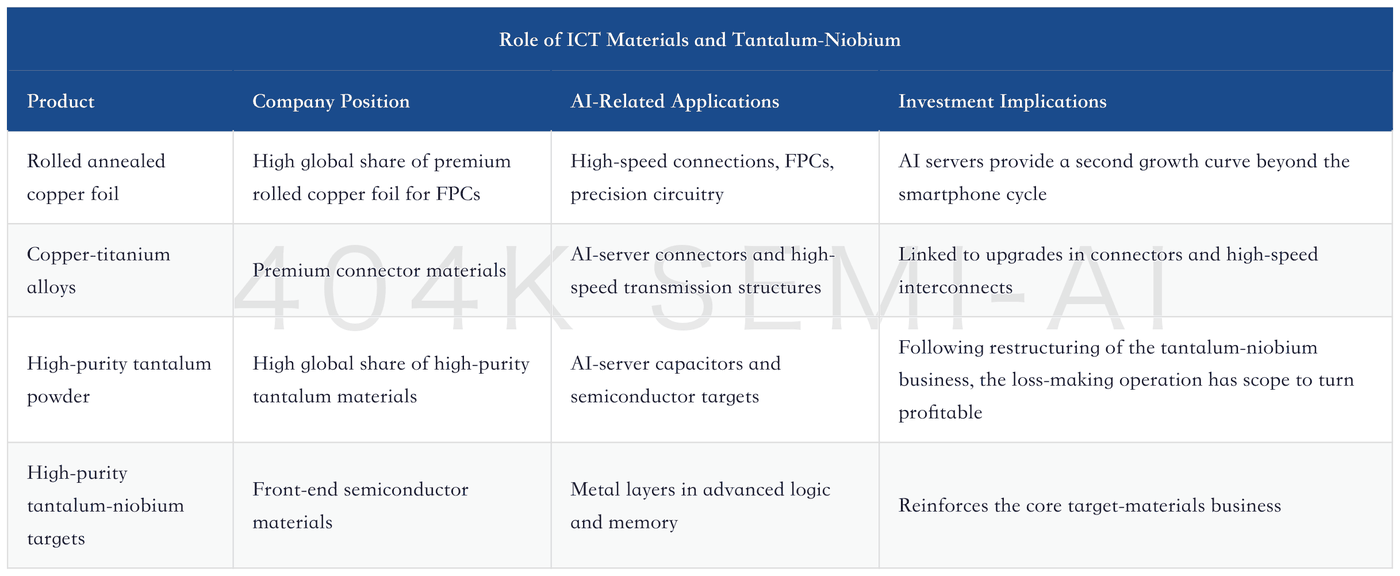
Tantalum-niobium materials are an underappreciated recovery opportunity. Official company guidance already points to a swing from losses to profitability, while Nomura’s model includes the business in its medium- to long-term earnings pool. If this materializes, the semiconductor materials segment will expand from a “targets plus InP” story into a more comprehensive advanced-materials portfolio.
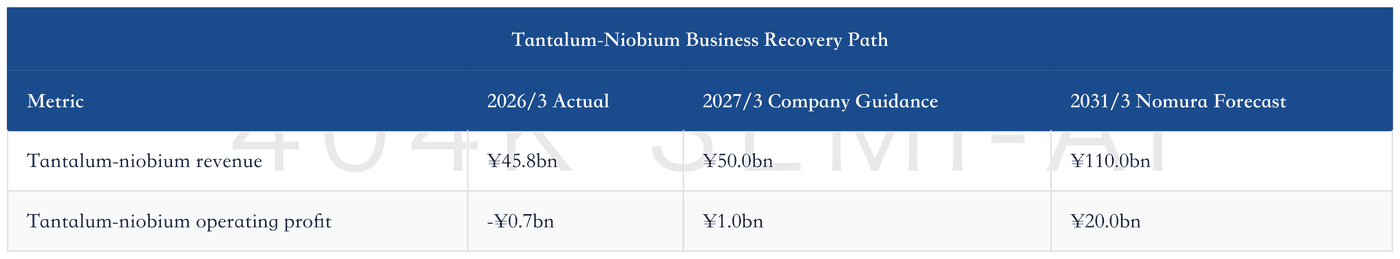
JX Advanced Metals’ advantage lies in its product portfolio. The material demand generated by a single AI server or AI data center may simultaneously extend to InP substrates, targets, tantalum powder, copper foil, copper-titanium alloys, and recycled metals. Individual product prices may fluctuate, but the combined portfolio better positions the company to capture the broadening of hardware capital expenditure.
AI Hardware Deep Dive: How PCBs, CPO, and MLCCs Become the Three Physical Bottlenecks in Rubin Racks
This thesis is connected to the three physical bottlenecks in AI hardware. Rack power, cable density, signal integrity, connector reliability, and board-level materials will extend AI investment beyond GPU processors into materials and foundational components. This is where the value of JX Advanced Metals’ ICT materials becomes evident.
V. Copper Recycling and Mining: Earnings Support for JX Advanced Metals, but Also Cyclical Volatility
Metals and recycling remains the largest earnings contributor in JX Advanced Metals’ current income statement. The segment generated operating profit of ¥139.5 billion in FY3/26, exceeding semiconductor materials and ICT materials combined. Nomura forecasts segment operating profit of ¥172.0 billion in FY3/27, mainly supported by copper prices and yen depreciation. The segment provides cash flow, but also makes it difficult for the market to value the company entirely as a pure-play technology materials stock.
The mining and recycling businesses have two sides. On the positive side, they generate strong cash flow, benefit directly from higher copper prices, and can fund capacity expansion in semiconductor materials. The downside is that copper prices, TC/RCs, exchange rates, mining interests, and one-off items increase earnings volatility. The market typically assigns lower valuations to cyclical earnings, constraining the company’s overall multiple.
JX Advanced Metals’ March 2026 sale of part of its Caserones interest illustrates management’s active reallocation of capital. The company transferred a 5% interest in MLCC and its interest in the Frontera project to Lundin for US$215 million, or approximately ¥34.0 billion. Following the transaction, JX Advanced Metals retains a 25% interest in Caserones and preferential offtake rights for mineral products. The company explicitly stated that the proceeds would be invested in priority businesses, including semiconductor sputtering targets and rare-metal resources.
The investment implications are straightforward: JX Advanced Metals has not relinquished its copper-resource foundation, but is reducing capital tied up in mining and reallocating funds toward semiconductor materials. For shareholders, the best outcome is that the copper business continues to generate cash flow while semiconductor materials drive valuation upside. The worst outcome is that lower copper prices pressure earnings while InP and sputtering-target capacity expansion fails to materialize on schedule.
Metals and recycling also plays an easily overlooked role: providing customers with supply security. The semiconductor materials, ICT materials, and recycling businesses share capabilities across metal resources, refining, purification, recycling, and reuse. As chipmakers and data-center customers place greater emphasis on supply-chain security, rare-metal sourcing, and circular utilization, JX Advanced Metals’ vertically integrated capabilities from resources to advanced materials should become more valuable.
VI. Breaking Down the Valuation: What Supports Nomura’s ¥4,800 Price Target
Nomura’s ¥4,800 price target for JX Advanced Metals is based on an SOTP valuation and a weighted average of segment multiples. The report uses FY3/27 EPS of ¥184.6, implying a P/E of approximately 27x. This multiple may appear high, but Nomura’s rationale is that semiconductor materials should be benchmarked against companies such as Tokyo Ohka Kogyo and Fujimi and assigned a premium; ICT materials should be benchmarked against Mitsui Mining & Smelting, Furukawa Electric, Sumitomo Electric Industries, and Fujikura; and metals and recycling should be benchmarked against Mitsubishi Materials and Sumitomo Metal Mining and assigned a lower multiple. The segment multiples are then weighted by their respective shares of FY3/27 profit.
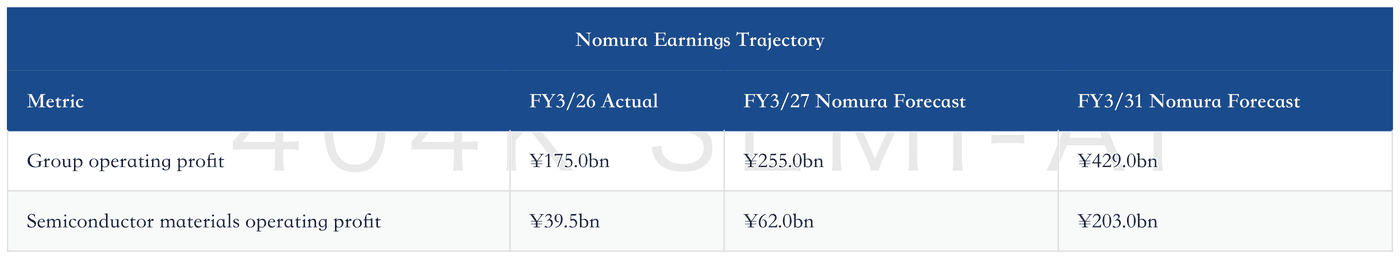
The key to this valuation is not the formula, but whether the earnings mix can change. In Nomura’s FY3/27 forecast, semiconductor materials accounts for 23% of segment profit, ICT materials 13%, and metals and recycling 64%. By FY3/31, semiconductor materials operating profit rises to ¥203.0 billion, already approaching the current scale of the metals and recycling segment. As long as this trajectory remains credible, the market should reduce the discount applied for copper cyclicality and assign greater weight to semiconductor materials.
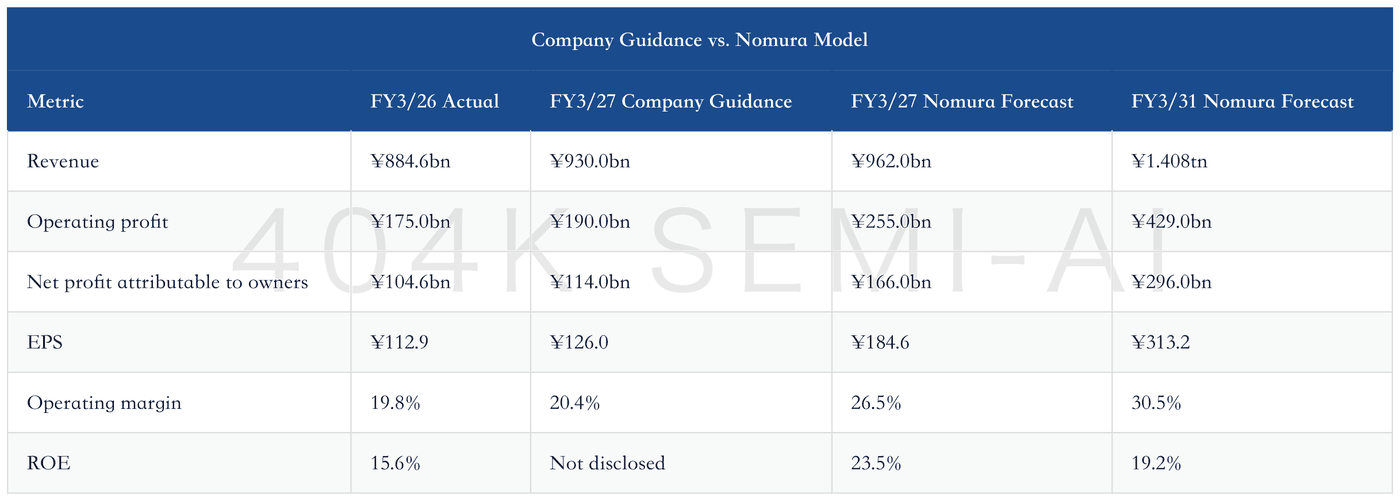
The gap between company guidance and Nomura’s model mainly reflects four variables. First, Nomura is more optimistic on InP pricing and capacity. Second, Nomura assumes stronger semiconductor-target volume growth. Third, Nomura assumes a weaker yen and higher copper prices. Fourth, Nomura has already incorporated share repurchases, convertible bonds, and capital-structure adjustments into future EPS.
Two things pose the greatest risk to the valuation: earnings derived from cyclical factors being assigned a growth multiple, and earnings based on long-term assumptions without visible near-term orders. JX Advanced Metals currently faces both risks, making it inappropriate to apply a single P/E multiple mechanically. A more prudent approach is to assess the company in three parts: “copper and recycling cash flow,” “high-share semiconductor-target assets,” and the “InP substrate bottleneck option.”
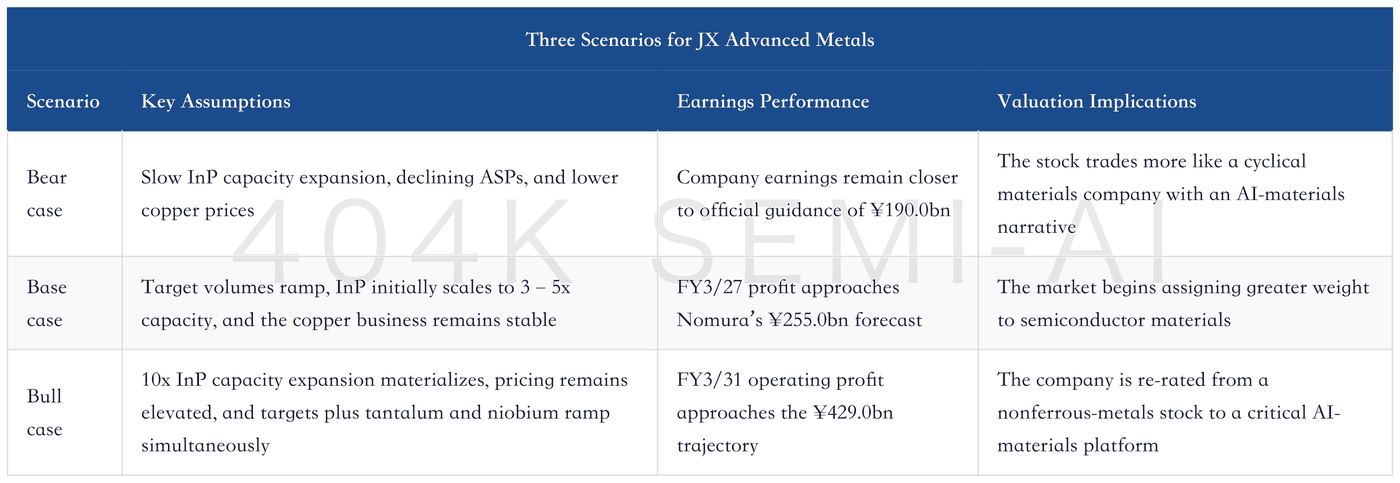
The counter-thesis checklist for JX Advanced Metals’ InP business can be condensed into five points. ASPs below Nomura’s assumptions would indicate that the price-doubling thesis is weakening; a slow capacity ramp would push out the FY3/31 earnings model; delayed customer qualification would indicate that substrate penetration into the supply chain is less straightforward than expected; a recovery in supply from AXT or China would show that third-party supply is beginning to pressure pricing; and increased external sales by Sumitomo Electric Industries would reduce JX Advanced Metals’ scarcity premium.
The debate over semiconductor materials in the next fiscal year centers on two figures. Company guidance calls for revenue of ¥200.0 billion and operating profit of ¥50.0 billion, while Nomura forecasts revenue of ¥220.0 billion and operating profit of ¥62.0 billion. The gap mainly reflects InP, thin-film materials, ASPs, product mix, and capacity utilization.
One point warrants emphasis: a higher price target for JX Advanced Metals does not mean the share price will avoid near-term volatility. The report states that the company delivered an absolute return of 377.8% and an index-relative return of 327.6% over the past 12 months; its 52-week low was ¥799 and its high was ¥5,828. The stock has already undergone an extreme re-rating, and further upside will require stronger operating data rather than thematic momentum alone.
Lumentum Deep Dive: 1.6T, EML, OCS, and CPO Light Sources—What Is Sustaining Lumentum’s CY28 Valuation?
There is a clear valuation transmission mechanism between Lumentum, Coherent, and JX Advanced Metals. Downstream optical-module and optical-component customers see demand first, while upstream substrate and materials suppliers subsequently see the impact on pricing and capacity expansion. Once downstream companies begin signing long-term supply agreements, increasing capital expenditure, and securing epitaxy and substrate supply, earnings visibility for upstream materials companies improves. The current change at JX Advanced Metals is part of this transmission of optical-interconnect strength from device manufacturers to materials suppliers.
7. The Key Bear Case: Could InP Become Oversupplied?
The most important risk in Nomura’s JX Advanced Metals report is whether InP could move from shortage to surplus. Nomura does not sidestep the issue. JX Advanced Metals plans to invest approximately ¥150 billion to expand InP substrate-related capacity, while InP substrate revenue was only ¥6 billion in FY3/26. Given the scale of investment relative to the business’s current revenue base, the market will naturally ask whether customer orders are sufficient, pricing can hold, and the industry will expand capacity in parallel.
This risk should not be glossed over. If InP supply suddenly loosens, the ASP assumption—the most sensitive variable in Nomura’s model—would be the first to come under pressure. An increase in the ASP index from 6 to 12 is one of the key assumptions underpinning ¥63 billion in operating profit. If pricing proves less robust, InP’s profit leverage will decline materially, requiring a downward revision to the Semiconductor Materials segment’s projected FY3/31 operating profit of ¥203 billion.
However, oversupply is unlikely to emerge immediately. InP substrates have long qualification cycles and slow yield ramps, while customers also assess production location, export licensing, quality consistency, and long-term delivery capabilities. If JX Advanced Metals has already discussed long-term demand with major customers before proceeding with successive capacity expansions, upstream investment would be more indicative of order-driven growth.
The most realistic assessment is that InP will neither remain in extreme shortage indefinitely nor rapidly become a commoditized material in the near term. It will enter a validation period of strong industry conditions. During this phase, JX Advanced Metals must provide three types of evidence to convince the market of its high-profit trajectory: sustained pricing, capacity ramp-up, and customer order commitments. As long as two of the three continue to materialize, the market will maintain a higher weighting for InP. If all three weaken simultaneously, valuation will quickly revert to the sputtering-target and copper businesses.
8. What to Watch Over the Next Four Quarters: Look Beyond the Target Price
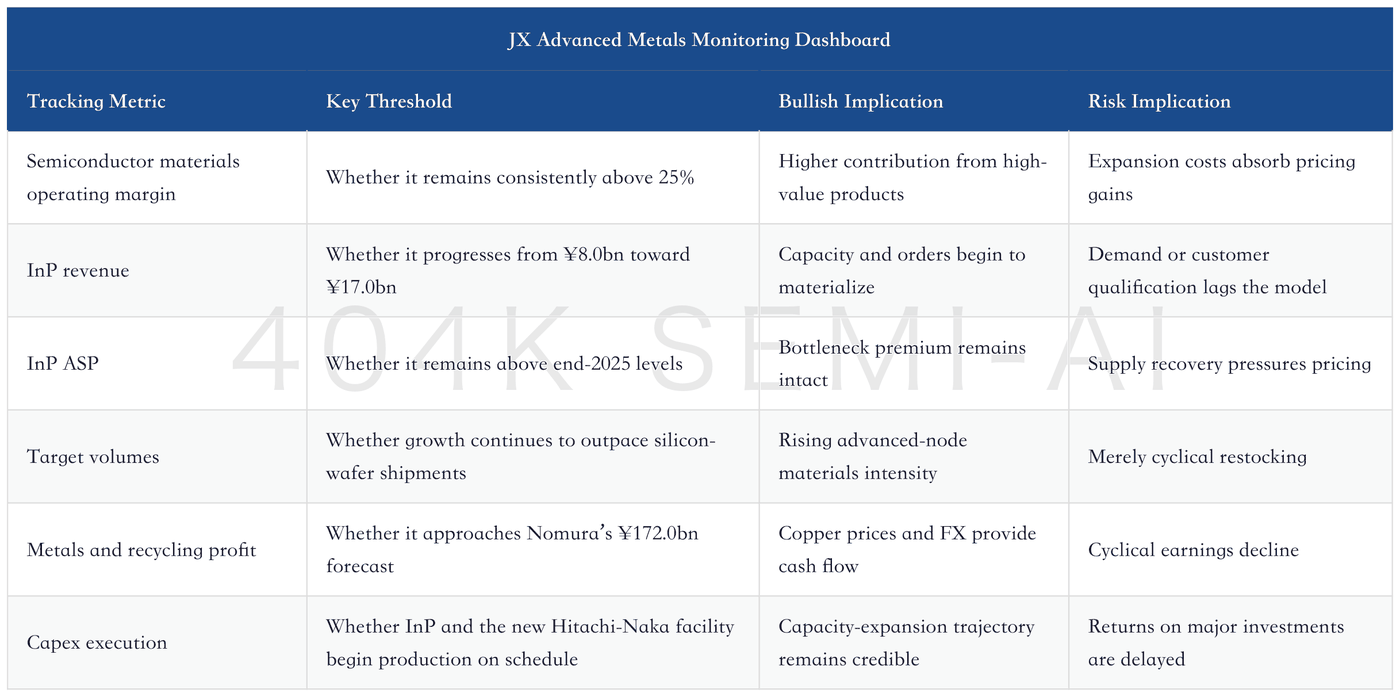
Investors should not focus solely on JX Advanced Metals’ share price and target price; operating metrics must validate Nomura’s model. The first few quarters of FY3/27 will be critical, as there is a ¥65 billion operating-profit gap between company guidance and sell-side forecasts. If quarterly results consistently trend toward Nomura’s trajectory, the market will view management guidance as conservative. If results merely track official guidance, the ¥4,800 target price will become less compelling.
The first metric is Semiconductor Materials revenue and margins. The gap between company guidance and Nomura’s forecast is primarily attributable to thin-film materials and InP. If segment margins continue rising from 22.3% to above 25%, it would indicate an increasing contribution from high-value products.
The second metric is InP capacity and pricing. The officially announced target to triple capacity is already verifiable, while Nomura’s assumption of a tenfold increase still requires support from subsequent announcements, equipment orders, customer demand, and pricing signals. The most useful near-term data points will be specific production-line commissioning dates, mass-production yields, and whether customers are securing supply in advance.
The third metric is semiconductor sputtering-target shipments. Demand from advanced logic, Intel 18A in the US, TSMC A16 in Taiwan, HBM, and TSV applications should gradually translate into material orders. If JX Advanced Metals can sustain sputtering-target shipment growth above global silicon-wafer shipment growth, it would indicate that the company is benefiting from rising advanced-process intensity.
The fourth metric is copper prices, foreign exchange, and metal-recycling profit. Nomura’s model forecasts FY3/27 operating profit of ¥172 billion for the Metals & Recycling segment, materially above company guidance of ¥124 billion. This business is highly sensitive to copper prices and the yen. If copper prices decline or the yen appreciates, near-term profit will be constrained even if Semiconductor Materials continues to grow.
The fifth metric is capital allocation. Viewed together, the partial sale of Caserones, convertible-bond issuance, share buybacks, and investment in new plants show that management is shifting the company away from resource assets and toward strategic materials businesses. Further disposals of non-core assets, a higher share of investment allocated to semiconductor materials, and reduced capital tied up in low-ROIC assets would improve the market’s view of the company’s valuation.
9. Investment Conclusion: JX Advanced Metals’ Value Lies in Materials Bottlenecks, Not Thematic Labels
The most compelling aspect of JX Advanced Metals is that it brings several AI hardware bottlenecks onto a single income statement. InP substrates address upstream material constraints for high-speed optical sources and detectors; semiconductor sputtering targets serve advanced logic and HBM processes; high-end copper and tantalum-niobium materials enter AI server interconnect and power-supply chains; and copper recycling and mining provide cash flow. Looking at any one business in isolation risks understating the portfolio’s combined value.
By upgrading JX Advanced Metals to Buy and raising its target price to ¥4,800, Nomura is effectively outlining a clear path: group profit rises steadily, while the Semiconductor Materials segment becomes the primary valuation driver. As this trajectory becomes more firmly established, JX Advanced Metals’ valuation anchor should migrate from that of a traditional nonferrous-metals company toward that of a critical AI materials supplier.
This trajectory is also fragile. InP requires capacity, pricing, and customer order commitments to align; sputtering targets require continued growth in advanced-node capital expenditure; and Metals & Recycling requires copper prices and foreign exchange not to become adverse headwinds. A problem in any one area could be sufficient to pull the shares back from a high-multiple narrative toward a segment-level discounted cash flow valuation.
The most appropriate monitoring framework is to value JX Advanced Metals in three parts: assess copper and recycling based on cash flow and the cycle; sputtering targets based on market share and exposure to advanced processes; and InP based on supply bottlenecks and pricing leverage. The current share price already reflects substantial optimism around AI materials, and further upside will require continued validation from actual operating data. For this company, the strongest evidence over the next several quarters will be Semiconductor Materials margins, InP order pricing, and capacity-expansion progress.
Coherent Re-Rating: Architectural Debate Cannot Suppress Growth in Optical Content; Gross Margin Is Coherent’s Next Hurdle
InnoLight In-Depth Update: How 2.4T and 3.2T, NPO and CPO Extend the Earnings Anchor Beyond 2028 Behind Nomura’s RMB1,325 Target Price
Related Reading
Sinocera Materials Deep Dive Update: 5,000 Tons of AI-Grade MLCC Powder, a RMB136 Target Price, and New Ceramic Substrate Orders as ValidationJX Advanced Metals Deep Dive: 10x InP Substrate Expansion, Semiconductor Target Ramp-Up, and Copper Recycling Earnings Support
目录
TL;DR
I. What Does JX Advanced Metals Actually Sell? Three Earnings Curves
II. InP Substrates: How a Small Business Becomes a Major Earnings Variable
3. Semiconductor Sputtering Targets: A Stable Earnings Foundation Behind Advanced Process Nodes
4. ICT Materials and Tantalum-Niobium: AI Servers Continue to Drive Connector, Copper-Foil, and Capacitor Materials
V. Copper Recycling and Mining: Earnings Support for JX Advanced Metals, but Also Cyclical Volatility
VI. Breaking Down the Valuation: What Supports Nomura’s ¥4,800 Price Target
7. The Key Bear Case: Could InP Become Oversupplied?
8. What to Watch Over the Next Four Quarters: Look Beyond the Target Price
9. Investment Conclusion: JX Advanced Metals’ Value Lies in Materials Bottlenecks, Not Thematic Labels
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The key change at JX Advanced Metals is that InP substrates are moving from a small peripheral business into a core earnings driver. Nomura upgraded the stock to Buy and raised its target price to ¥4,800, reflecting simultaneous revisions to three earnings pillars: a 10x capacity expansion, accelerating semiconductor target sales, and downside support from copper recycling. Sell-side models are already pricing in a widening earnings inflection for FY2027/3 and FY2031/3.
TL;DR
Nomura’s upgrade reflects a wholesale earnings-model reset. Nomura upgraded JX Advanced Metals from Neutral to Buy and raised its target price to ¥4,800, implying approximately 25% upside from the closing price. More importantly, its earnings estimates are materially above company guidance, with the key differences centered on InP substrates, semiconductor targets, copper prices, and foreign exchange.
InP substrates are becoming the largest source of earnings upside. Nomura sees JX Advanced Metals’ InP business as a future earnings lever, based on capacity expanding toward 10x while pricing remains strong. If customer qualifications and the expansion schedule proceed as expected, the Semiconductor Materials segment could shift from an earnings base into the central pillar of the company’s valuation.
Supply bottlenecks give JX pricing power. Third-party merchant supply in the InP substrate market is highly constrained. JX and AXT are the main external suppliers, while Sumitomo Electric’s output is largely consumed internally by its optical-device operations. Chinese export licensing, lengthy customer qualification cycles, and AI data-center optical-interconnect demand are combining to make overseas customers more willing to secure supply from stable vendors such as JX.
The target business underpins the valuation floor. JX Advanced Metals holds a high global share in semiconductor sputtering targets, and its new Hitachinaka plant is taking capacity to 1.6x FY2023 levels. Advanced logic, HBM, TSV, backside power delivery, and additional metal interconnect layers will transform targets from cyclical consumables into process-critical materials. This is the most important earnings foundation outside InP.
Copper recycling provides cash-flow support. Metals & Recycling remains the largest current profit contributor. The company has sold part of its interest in Caserones while retaining its core stake and preferential offtake rights for mine products. This indicates that management is recycling mining capital into semiconductor-material capacity expansion, although copper prices and the yen will continue to affect near-term earnings.
The valuation hinges on three sets of confirmation signals. Nomura’s target price assumes a higher earnings contribution from semiconductor materials. That multiple requires support from the InP expansion, higher target volumes, and copper-business cash flow. Key indicators to monitor are the InP capacity ramp, InP pricing, semiconductor target volumes, and whether company guidance moves progressively closer to sell-side estimates.
I. What Does JX Advanced Metals Actually Sell? Three Earnings Curves
JX Advanced Metals combines three types of assets: InP substrates and semiconductor targets tied to AI optical interconnects; rolled annealed copper foil, copper-titanium alloys, and high-purity tantalum powder used in AI servers; and copper mining, smelting, and recycling operations that underpin cash flow.
The company has already delivered a strong set of FY2026/3 results, with a more diversified quality of growth than a single-theme investment. Earnings sources are broad, with copper prices, the yen, mining interests, and rising AI data-center material volumes all contributing.
Official guidance for the next fiscal year is clearly conservative, while Nomura’s model is more aggressive. The gap is substantial, reducing the investment debate to one question: should JX Advanced Metals be valued as a cyclical mining and materials stock, or receive a higher multiple as a supplier of bottleneck materials upstream of AI?
This table explains why the market can easily underestimate JX Advanced Metals. Metals & Recycling remains the largest current profit contributor, but Semiconductor Materials offers the greatest future earnings leverage. Nomura’s upgrade shifts the market’s attention from “how much profit did copper prices contribute?” to “can Semiconductor Materials become a much larger earnings pool?”
From a financial perspective, JX Advanced Metals’ asset mix is shifting from resource-intensive operations toward high-margin materials. On the company’s figures, the Semiconductor Materials operating margin was 22.3% in FY2026/3, while FY2027/3 guidance implies 25.0%. The official long-term target is 25%-30%. Metals & Recycling generates more profit but is more exposed to copper prices, foreign exchange, and changes in mining interests. Semiconductor Materials has higher margins and is also more likely to command a valuation premium.
JX Advanced Metals’ exposure to AI optical interconnects can be traced from upstream materials down the value chain. Optical-module manufacturers require photonic chips; photonic chips require epitaxial wafers; and epitaxial wafers require InP substrates. Advanced-node GPUs, ASICs, and CPUs require more metal interconnects, whose fabrication depends on high-purity sputtering targets. AI-server connectors, cables, FPCs, and capacitor materials also use copper-titanium alloys, rolled annealed copper foil, and high-purity tantalum powder. JX Advanced Metals occupies precisely these critical material nodes.
AI Optical-Module Demand Revised Higher Again: How Morgan Stanley’s May Report Extends the 1.6T, InP, and CPO Bottlenecks Through 2028
The earlier optical-module and CPO series focused on system architecture and module content value. This JX Advanced Metals analysis moves one step further upstream. As optical-interconnect deployment expands, the market is increasingly likely to trace bottlenecks beyond module and optical-component manufacturers to substrates, targets, epitaxy, and critical consumables. JX Advanced Metals’ investment case becomes clearer along this upstream chain.
II. InP Substrates: How a Small Business Becomes a Major Earnings Variable
InP substrates can be understood simply as the “baseplate” for many high-speed optical devices. Optical-device manufacturers grow epitaxial layers and fabricate chips on these substrates, ultimately producing lasers, detectors, modulators, and other devices used in data-center optical modules, base stations, long-haul communications, and, eventually, shorter-reach board-to-board and intra-rack optical links.
JX Advanced Metals’ website lists the applications for InP substrates directly: light-emitting devices, photodetectors, high-speed electronic devices, and infrared detectors, serving optical modules, mobile base stations, and data centers. Nomura links the business to AI data centers because 800G, 1.6T, and 3.2T optical modules, silicon photonics, CPO, and OCS are all increasing demand for high-speed light sources and detectors. As long as electrical signaling remains inadequate within clusters, demand for optical materials will continue to rise.
Nomura’s InP assumptions are aggressive, but the logic is straightforward. JX Advanced Metals plans to expand InP substrate capacity to 7-10x the FY2026/3 baseline by FY2031/3, while Nomura’s model assumes the full 10x. It also raises the ASP index from 6 to 12, implying a doubling in price. The combination of these two variables significantly amplifies revenue and earnings leverage.
The increase appears dramatic, but the underlying supply-demand logic is relatively clear. First, the merchant market for InP substrates is small, with JX Advanced Metals and AXT serving as the principal third-party suppliers. Although Sumitomo Electric has a high market share, much of its capacity supports internal optical-device demand, leaving limited volumes available to external customers. Second, Chinese export licensing has made deliveries from China-based supply chains such as AXT’s more complex, leading customers to assign a higher security-of-supply premium to non-Chinese sources. Third, optical-device customer qualification typically takes one to two years, so customers are unlikely to switch suppliers casually in response to short-term price fluctuations.
Market tightness is also visible in pricing. Citing expert interviews, Nomura notes that prices for 3-inch InP substrates in China have risen from approximately RMB1,800 at the end of 2025 to around RMB3,200 currently. Prices outside China are higher, with some buyers accepting prices two to three times previous levels. For JX Advanced Metals, price increases flow into earnings faster than capacity expansion. Once fixed-cost absorption and yield ramp-up cross the threshold, incremental ASP gains directly lift gross margins.
The AI Light-Source Battle Is Not a Speed Race: InP, VCSEL, and μLED Address Different Distances
The InP investment case cannot be reduced to the statement that “optical modules are getting faster.” VCSEL is more suited to short-reach applications and specific cost bands, while InP is better suited to long-distance, high-speed, and high-performance light sources and detectors. As AI clusters extend optical connectivity from inter-data-center links to inter-rack, intra-rack, board-level, and eventually near-package connections, each distance segment will adopt different light-source solutions. JX Advanced Metals benefits because it supplies a foundational material that many high-performance solutions cannot avoid.
The timetable in official announcements is more conservative than Nomura’s model. In February 2026, JX Advanced Metals announced approximately ¥20.0bn of additional investment to triple InP substrate capacity by 2030 relative to 2025 levels, with phased production beginning in FY2027. Nomura’s report also incorporates the company’s subsequently more aggressive expansion target of raising capacity to 7-10x by FY2031/3. One point is critical: if the company were merely promoting a thematic narrative, it would not have repeatedly raised its capacity targets in July 2025, October 2025, February 2026, and June 2026. The successive increases indicate clear customer demand for medium- to long-term supply.
Three factors require close monitoring in JX Advanced Metals’ InP business. First, whether expansion capex is deployed on schedule, particularly new-equipment commissioning, yields, and capacity ramp-up. Second, whether major customers are willing to sign long-term supply agreements or pricing frameworks. Even if the company does not disclose customer names, signals may be visible in pricing, customer advances, inventories, and utilization rates. Third, whether Chinese export licensing or competitor capacity constraints ease. If supply restrictions loosen, the market will first challenge JX Advanced Metals’ ASP assumptions.
3. Semiconductor Sputtering Targets: A Stable Earnings Foundation Behind Advanced Process Nodes
InP provides upside elasticity, while semiconductor targets provide the earnings foundation. JX Advanced Metals holds an approximately 64% global share of semiconductor sputtering targets, a core asset highlighted by both Goldman Sachs’ earlier coverage and company materials. Sputtering targets may sound like commodity consumables, but their barriers to entry lie in purity, particle control, process stability, equipment compatibility, and customer qualification. In advanced process nodes, a problem with a single material can affect wafer yields.
Target demand rises with advanced-node complexity. Advanced logic nodes require more interconnect layers and more complex metal materials; HBM drives demand related to TSVs and advanced packaging; and the continued performance scaling of AI ASICs, GPUs, and CPUs increases consumption of high-purity copper, tantalum, titanium, and other targets. Nomura expects JX Advanced Metals’ semiconductor-target sales to grow at a CAGR of approximately 21% from 2026/3 to 2031/3, well above global silicon-wafer shipment growth. This indicates that the company is benefiting from rising material intensity in advanced process nodes.
The company’s announced capacity expansion provides visibility for this business. In March 2026, JX Advanced Metals announced an additional investment of approximately ¥23.0bn at its New Hitachi-Naka Plant for semiconductor sputtering targets. This is included in the approximately ¥150.0bn total investment in the new plant announced in March 2024. The company aims to increase semiconductor sputtering-target capacity to 1.6 times the FY2023 level, with operations beginning in the second half of FY2027. This is a concrete expansion plan backed by factories and equipment.
The target business’s greatest strength is its integration with major customers’ processes. Advanced logic foundries will not readily switch target suppliers merely for lower prices, as changing materials requires revalidating process windows and equipment conditions while introducing yield risk. JX Advanced Metals has achieved its high market share through long-term supply relationships, material purity, product breadth, and compatibility with the equipment ecosystem. Goldman Sachs’ earlier report noted the company’s long-standing compatibility with mainstream equipment platforms such as Applied Materials’ Endura. This integration makes incremental demand more likely to flow naturally to incumbent suppliers.
As AI chips continue to concentrate on advanced process nodes, target demand will rise through three channels. First, more front-end interconnect layers mean additional metal-deposition steps. Second, advanced packaging and HBM create material demand for TSVs, RDL, and related applications. Third, new processes such as backside power delivery may alter metal-layer structures and create new target-qualification opportunities. For JX Advanced Metals, each increase in process complexity effectively raises customers’ switching costs.
CPO Bull-Market Expectations Cool: Architectural Competition Cannot Stop Optical Growth as AI Clusters Enter the Optical-Interconnect Era
JX Advanced Metals’ position in system architectures such as CPO, NPO, and OCS lies further upstream in materials. Market discussions of CPO often focus first on optical modules and switches. But when the industry begins building capacity in earnest, capital will look further upstream for bottlenecks in epitaxial wafers, substrates, targets, package-substrate materials, and critical consumables. JX Advanced Metals sits squarely in this position.
4. ICT Materials and Tantalum-Niobium: AI Servers Continue to Drive Connector, Copper-Foil, and Capacitor Materials
JX Advanced Metals’ second AI exposure lies in ICT materials and tantalum-niobium materials. It is less dramatic than InP and less directly tied to advanced process nodes than targets, but it occupies a stable position in the incremental material demand generated by AI servers.
The company reported FY2026/3 ICT materials operating profit of ¥31.5bn, with official FY2027/3 guidance of ¥32.0bn and Nomura forecasting ¥36.0bn. Growth is lower than in semiconductor materials, but two products merit attention: rolled annealed copper foil and copper-titanium alloys. According to Goldman Sachs’ earlier report, JX Advanced Metals holds an approximately 78% global share of rolled copper foil for FPCs and also has a high share in copper-titanium alloys. Upgrades to internal AI-server connections, cabling, connectors, high-speed transmission, and thermal-management structures will continue to consume high-end copper materials.
Company materials also identify AI data centers as a growth driver for ICT materials. In its FY2027/3 guidance, the Functional Materials business benefits from higher sales of rolled annealed copper foil and copper-titanium alloys for AI data centers, although foreign-exchange movements, the situation in the Middle East, and other cost factors will offset part of the earnings contribution. This business lacks InP’s upside elasticity, but it means JX Advanced Metals is not dependent on a single optical-substrate product.
Tantalum-niobium materials are an underappreciated recovery opportunity. Official company guidance already points to a swing from losses to profitability, while Nomura’s model includes the business in its medium- to long-term earnings pool. If this materializes, the semiconductor materials segment will expand from a “targets plus InP” story into a more comprehensive advanced-materials portfolio.
JX Advanced Metals’ advantage lies in its product portfolio. The material demand generated by a single AI server or AI data center may simultaneously extend to InP substrates, targets, tantalum powder, copper foil, copper-titanium alloys, and recycled metals. Individual product prices may fluctuate, but the combined portfolio better positions the company to capture the broadening of hardware capital expenditure.
AI Hardware Deep Dive: How PCBs, CPO, and MLCCs Become the Three Physical Bottlenecks in Rubin Racks
This thesis is connected to the three physical bottlenecks in AI hardware. Rack power, cable density, signal integrity, connector reliability, and board-level materials will extend AI investment beyond GPU processors into materials and foundational components. This is where the value of JX Advanced Metals’ ICT materials becomes evident.
V. Copper Recycling and Mining: Earnings Support for JX Advanced Metals, but Also Cyclical Volatility
Metals and recycling remains the largest earnings contributor in JX Advanced Metals’ current income statement. The segment generated operating profit of ¥139.5 billion in FY3/26, exceeding semiconductor materials and ICT materials combined. Nomura forecasts segment operating profit of ¥172.0 billion in FY3/27, mainly supported by copper prices and yen depreciation. The segment provides cash flow, but also makes it difficult for the market to value the company entirely as a pure-play technology materials stock.
The mining and recycling businesses have two sides. On the positive side, they generate strong cash flow, benefit directly from higher copper prices, and can fund capacity expansion in semiconductor materials. The downside is that copper prices, TC/RCs, exchange rates, mining interests, and one-off items increase earnings volatility. The market typically assigns lower valuations to cyclical earnings, constraining the company’s overall multiple.
JX Advanced Metals’ March 2026 sale of part of its Caserones interest illustrates management’s active reallocation of capital. The company transferred a 5% interest in MLCC and its interest in the Frontera project to Lundin for US$215 million, or approximately ¥34.0 billion. Following the transaction, JX Advanced Metals retains a 25% interest in Caserones and preferential offtake rights for mineral products. The company explicitly stated that the proceeds would be invested in priority businesses, including semiconductor sputtering targets and rare-metal resources.
The investment implications are straightforward: JX Advanced Metals has not relinquished its copper-resource foundation, but is reducing capital tied up in mining and reallocating funds toward semiconductor materials. For shareholders, the best outcome is that the copper business continues to generate cash flow while semiconductor materials drive valuation upside. The worst outcome is that lower copper prices pressure earnings while InP and sputtering-target capacity expansion fails to materialize on schedule.
Metals and recycling also plays an easily overlooked role: providing customers with supply security. The semiconductor materials, ICT materials, and recycling businesses share capabilities across metal resources, refining, purification, recycling, and reuse. As chipmakers and data-center customers place greater emphasis on supply-chain security, rare-metal sourcing, and circular utilization, JX Advanced Metals’ vertically integrated capabilities from resources to advanced materials should become more valuable.
VI. Breaking Down the Valuation: What Supports Nomura’s ¥4,800 Price Target
Nomura’s ¥4,800 price target for JX Advanced Metals is based on an SOTP valuation and a weighted average of segment multiples. The report uses FY3/27 EPS of ¥184.6, implying a P/E of approximately 27x. This multiple may appear high, but Nomura’s rationale is that semiconductor materials should be benchmarked against companies such as Tokyo Ohka Kogyo and Fujimi and assigned a premium; ICT materials should be benchmarked against Mitsui Mining & Smelting, Furukawa Electric, Sumitomo Electric Industries, and Fujikura; and metals and recycling should be benchmarked against Mitsubishi Materials and Sumitomo Metal Mining and assigned a lower multiple. The segment multiples are then weighted by their respective shares of FY3/27 profit.
The key to this valuation is not the formula, but whether the earnings mix can change. In Nomura’s FY3/27 forecast, semiconductor materials accounts for 23% of segment profit, ICT materials 13%, and metals and recycling 64%. By FY3/31, semiconductor materials operating profit rises to ¥203.0 billion, already approaching the current scale of the metals and recycling segment. As long as this trajectory remains credible, the market should reduce the discount applied for copper cyclicality and assign greater weight to semiconductor materials.
The gap between company guidance and Nomura’s model mainly reflects four variables. First, Nomura is more optimistic on InP pricing and capacity. Second, Nomura assumes stronger semiconductor-target volume growth. Third, Nomura assumes a weaker yen and higher copper prices. Fourth, Nomura has already incorporated share repurchases, convertible bonds, and capital-structure adjustments into future EPS.
Two things pose the greatest risk to the valuation: earnings derived from cyclical factors being assigned a growth multiple, and earnings based on long-term assumptions without visible near-term orders. JX Advanced Metals currently faces both risks, making it inappropriate to apply a single P/E multiple mechanically. A more prudent approach is to assess the company in three parts: “copper and recycling cash flow,” “high-share semiconductor-target assets,” and the “InP substrate bottleneck option.”
The counter-thesis checklist for JX Advanced Metals’ InP business can be condensed into five points. ASPs below Nomura’s assumptions would indicate that the price-doubling thesis is weakening; a slow capacity ramp would push out the FY3/31 earnings model; delayed customer qualification would indicate that substrate penetration into the supply chain is less straightforward than expected; a recovery in supply from AXT or China would show that third-party supply is beginning to pressure pricing; and increased external sales by Sumitomo Electric Industries would reduce JX Advanced Metals’ scarcity premium.
The debate over semiconductor materials in the next fiscal year centers on two figures. Company guidance calls for revenue of ¥200.0 billion and operating profit of ¥50.0 billion, while Nomura forecasts revenue of ¥220.0 billion and operating profit of ¥62.0 billion. The gap mainly reflects InP, thin-film materials, ASPs, product mix, and capacity utilization.
One point warrants emphasis: a higher price target for JX Advanced Metals does not mean the share price will avoid near-term volatility. The report states that the company delivered an absolute return of 377.8% and an index-relative return of 327.6% over the past 12 months; its 52-week low was ¥799 and its high was ¥5,828. The stock has already undergone an extreme re-rating, and further upside will require stronger operating data rather than thematic momentum alone.
Lumentum Deep Dive: 1.6T, EML, OCS, and CPO Light Sources—What Is Sustaining Lumentum’s CY28 Valuation?
There is a clear valuation transmission mechanism between Lumentum, Coherent, and JX Advanced Metals. Downstream optical-module and optical-component customers see demand first, while upstream substrate and materials suppliers subsequently see the impact on pricing and capacity expansion. Once downstream companies begin signing long-term supply agreements, increasing capital expenditure, and securing epitaxy and substrate supply, earnings visibility for upstream materials companies improves. The current change at JX Advanced Metals is part of this transmission of optical-interconnect strength from device manufacturers to materials suppliers.
7. The Key Bear Case: Could InP Become Oversupplied?
The most important risk in Nomura’s JX Advanced Metals report is whether InP could move from shortage to surplus. Nomura does not sidestep the issue. JX Advanced Metals plans to invest approximately ¥150 billion to expand InP substrate-related capacity, while InP substrate revenue was only ¥6 billion in FY3/26. Given the scale of investment relative to the business’s current revenue base, the market will naturally ask whether customer orders are sufficient, pricing can hold, and the industry will expand capacity in parallel.
This risk should not be glossed over. If InP supply suddenly loosens, the ASP assumption—the most sensitive variable in Nomura’s model—would be the first to come under pressure. An increase in the ASP index from 6 to 12 is one of the key assumptions underpinning ¥63 billion in operating profit. If pricing proves less robust, InP’s profit leverage will decline materially, requiring a downward revision to the Semiconductor Materials segment’s projected FY3/31 operating profit of ¥203 billion.
However, oversupply is unlikely to emerge immediately. InP substrates have long qualification cycles and slow yield ramps, while customers also assess production location, export licensing, quality consistency, and long-term delivery capabilities. If JX Advanced Metals has already discussed long-term demand with major customers before proceeding with successive capacity expansions, upstream investment would be more indicative of order-driven growth.
The most realistic assessment is that InP will neither remain in extreme shortage indefinitely nor rapidly become a commoditized material in the near term. It will enter a validation period of strong industry conditions. During this phase, JX Advanced Metals must provide three types of evidence to convince the market of its high-profit trajectory: sustained pricing, capacity ramp-up, and customer order commitments. As long as two of the three continue to materialize, the market will maintain a higher weighting for InP. If all three weaken simultaneously, valuation will quickly revert to the sputtering-target and copper businesses.
8. What to Watch Over the Next Four Quarters: Look Beyond the Target Price
Investors should not focus solely on JX Advanced Metals’ share price and target price; operating metrics must validate Nomura’s model. The first few quarters of FY3/27 will be critical, as there is a ¥65 billion operating-profit gap between company guidance and sell-side forecasts. If quarterly results consistently trend toward Nomura’s trajectory, the market will view management guidance as conservative. If results merely track official guidance, the ¥4,800 target price will become less compelling.
The first metric is Semiconductor Materials revenue and margins. The gap between company guidance and Nomura’s forecast is primarily attributable to thin-film materials and InP. If segment margins continue rising from 22.3% to above 25%, it would indicate an increasing contribution from high-value products.
The second metric is InP capacity and pricing. The officially announced target to triple capacity is already verifiable, while Nomura’s assumption of a tenfold increase still requires support from subsequent announcements, equipment orders, customer demand, and pricing signals. The most useful near-term data points will be specific production-line commissioning dates, mass-production yields, and whether customers are securing supply in advance.
The third metric is semiconductor sputtering-target shipments. Demand from advanced logic, Intel 18A in the US, TSMC A16 in Taiwan, HBM, and TSV applications should gradually translate into material orders. If JX Advanced Metals can sustain sputtering-target shipment growth above global silicon-wafer shipment growth, it would indicate that the company is benefiting from rising advanced-process intensity.
The fourth metric is copper prices, foreign exchange, and metal-recycling profit. Nomura’s model forecasts FY3/27 operating profit of ¥172 billion for the Metals & Recycling segment, materially above company guidance of ¥124 billion. This business is highly sensitive to copper prices and the yen. If copper prices decline or the yen appreciates, near-term profit will be constrained even if Semiconductor Materials continues to grow.
The fifth metric is capital allocation. Viewed together, the partial sale of Caserones, convertible-bond issuance, share buybacks, and investment in new plants show that management is shifting the company away from resource assets and toward strategic materials businesses. Further disposals of non-core assets, a higher share of investment allocated to semiconductor materials, and reduced capital tied up in low-ROIC assets would improve the market’s view of the company’s valuation.
9. Investment Conclusion: JX Advanced Metals’ Value Lies in Materials Bottlenecks, Not Thematic Labels
The most compelling aspect of JX Advanced Metals is that it brings several AI hardware bottlenecks onto a single income statement. InP substrates address upstream material constraints for high-speed optical sources and detectors; semiconductor sputtering targets serve advanced logic and HBM processes; high-end copper and tantalum-niobium materials enter AI server interconnect and power-supply chains; and copper recycling and mining provide cash flow. Looking at any one business in isolation risks understating the portfolio’s combined value.
By upgrading JX Advanced Metals to Buy and raising its target price to ¥4,800, Nomura is effectively outlining a clear path: group profit rises steadily, while the Semiconductor Materials segment becomes the primary valuation driver. As this trajectory becomes more firmly established, JX Advanced Metals’ valuation anchor should migrate from that of a traditional nonferrous-metals company toward that of a critical AI materials supplier.
This trajectory is also fragile. InP requires capacity, pricing, and customer order commitments to align; sputtering targets require continued growth in advanced-node capital expenditure; and Metals & Recycling requires copper prices and foreign exchange not to become adverse headwinds. A problem in any one area could be sufficient to pull the shares back from a high-multiple narrative toward a segment-level discounted cash flow valuation.
The most appropriate monitoring framework is to value JX Advanced Metals in three parts: assess copper and recycling based on cash flow and the cycle; sputtering targets based on market share and exposure to advanced processes; and InP based on supply bottlenecks and pricing leverage. The current share price already reflects substantial optimism around AI materials, and further upside will require continued validation from actual operating data. For this company, the strongest evidence over the next several quarters will be Semiconductor Materials margins, InP order pricing, and capacity-expansion progress.
Coherent Re-Rating: Architectural Debate Cannot Suppress Growth in Optical Content; Gross Margin Is Coherent’s Next Hurdle
InnoLight In-Depth Update: How 2.4T and 3.2T, NPO and CPO Extend the Earnings Anchor Beyond 2028 Behind Nomura’s RMB1,325 Target Price