
JPM Flow Deep Dive: How Retail Dip-Buying and AI Rotation Will Define the Second Half of the Semiconductor Trade
目录
TL;DR
1. This Is Not a Regular Weekly Flow Report; the Core Question Is How the AI Profit Pool Is Split
2. Semiconductors Are Outperforming Hyperscalers Because of 2026 Capex, but the Risk Is in 2027
3. The Positive Rotation Script: Hyperscaler Monetization Improves, and the AI Profit Pool Spreads from Chips to Customers
IV. Bear Case: Semiconductor Gains Become Customer Costs, Forcing Capex to Slow in 2027
V. Retail Has Not Left; Buying Is Concentrated in Memory and Semis
VI. Retail Buys Cash Equities, Non-Retail Sells Futures: The Market Is Not Uniformly Bullish
VII. Thematic Baskets Show Capital Is Buying AI Infrastructure, Not Just a Few Star Stocks
8. Why Memory Has Become the AI Asset Retail Investors Are Most Willing to Carry Forward
9. Cross-Asset Liquidity Still Supports Risk Assets, But It Is Not an Unconditional Backstop
10. Investment Framework: Four Questions to Judge Whether the AI Trade Has Entered Its Second Phase
11. Portfolio Implications: Stay Bullish on AI Hardware, But Shift from "Chasing Momentum" to "Reconciling the Accounts"
12. Breaking Down Flows: This AI Trade Has Three Types of Money
XIII. Cloud Providers Are the Balance Sheet of This Trade, Not Just the Customers
XIV. Why Memory Assets Are Easier to Re-rate Than Ordinary Semiconductors
XV. Semiconductor Equipment, PCB, and Packaging Are Leading Indicators for 2027 Capex
XVI. Whether AI Software and Cloud Services Can Take the Baton Determines Rotation Quality
XVII. Risk-Invalidation Checklist: Signals That Risk Should Be Reduced
XVIII. Three Scenarios: Rotation, Squeeze, and Clearing
19. How to Track the Next Four Quarters
20. Position Expression: Keep the Main Theme, but Do Not Treat All AI Assets as the Same Risk
21. Conclusion: AI Semiconductors Are Still in the Main Theme, but the Trading Language Has Changed
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The AI semiconductor rally has shifted from an earnings trade to a flow trade: institutions worry that hyperscaler capex could slow in 2027, while retail investors keep buying Micron, SanDisk, and Nvidia. The next variables to watch are compute pricing, hyperscaler cash flow, and whether long-term memory contracts can support valuations together. These will determine whether the second half of the semiconductor trade becomes rotation or clearing.
TL;DR
The semiconductor trade needs rotation. JPM’s flow report frames the issue directly: AI chips and memory manufacturers have continued to outperform hyperscalers since last September, driven by sharp upward revisions to 2026 cloud capex expectations. Yet consensus shows 2027 growth slowing from 100% to 22%. If hyperscaler revenue, earnings, and AI monetization begin to catch up, semiconductors can absorb crowding through rotation; if chip profits squeeze customer cash flow and 2027 capex is cut, the hardware chain will first go through a valuation clearing.
Retail is still buying the dip. JPM Retail Radar shows US retail net inflows of $8.1B over the seven days from June 25 to July 1, above the trailing 12-month weekly average of $6.7B; single-stock inflows are at the 94.8th percentile, while ETF activity is only at the 17.5th percentile. Capital is not buying the market evenly, but is concentrated in AI, memory, and technology hardware, with $897M flowing into Micron, $705M into SanDisk, and $492M into Nvidia.
Institutions and retail are diverging. Over the past seven days, non-retail futures traders net sold about $11.3B, including roughly $7.3B of ES, $2.2B of NQ, and $1.8B of RTY; retail investors continued buying AI data centers, electrification, the Top 30 AI beneficiaries basket, and the AI software monetization basket. This means the short-term market is not simply a risk-appetite rally, but a structure of “reducing risk in futures, buying the core theme in cash equities.”
2027 is the key audit point. Hyperscaler capex consensus rises from $149B in 2023 to $758.1B in 2026 and then to $925B in 2027, but JPM’s semiconductor team uses a higher 2027 figure of $1.15T. This difference determines how the market prices the sustainability of AI supply-chain profits: if 2027 capex is revised higher again, memory, advanced packaging, PCB, and equipment chains still have tailwinds; if the consensus slowdown materializes, the most crowded semiconductor and memory names will be repriced first.
Memory is where retail is taking the handoff. In Retail Radar, the strongest single-stock buying is in Micron and SanDisk, reflecting AI server memory, NAND, eSSD, and long-term contracts moving from industry logic into trading logic. Retail buying is not itself a fundamental thesis, but it shows that the “memory tax” has spread from sell-side reports and supply-chain data into end-investor flows. The next step is cross-checking DRAM/NAND spot prices, eSSD orders, long-term contract volumes, hyperscaler capex, and compute rental prices.
Liquidity is still supporting risk assets. JPM expects US money creation to rise from $1.6T in 2025 to $1.8T in 2026, which remains a baseline support for US equities; but cash allocations are already low, and MicroStrategy introduces two-way Bitcoin selling risk, reminding the market that liquidity is not a one-way variable that only rises. The best-case scenario for AI hardware is a liquidity floor, improved hyperscaler monetization, and semiconductor gains giving way to a broader AI profit pool.
1. This Is Not a Regular Weekly Flow Report; the Core Question Is How the AI Profit Pool Is Split
Reading these two JPM reports together produces more information than reading either one in isolation. Flows & Liquidity discusses AI rotation at the institutional level: semiconductor and memory manufacturers have rallied too quickly, while hyperscaler share prices and credit spreads have started to come under pressure, as the market worries that customers’ capital spending will be squeezed by supply-chain profits. Retail Radar discusses buy-side demand at the trading level: retail investors have not been scared away by AI bubble concerns; instead, they continue to buy dips, with buying concentrated in memory, semiconductors, and AI data-center themes.
The real tension is this: the AI hardware chain needs customers to keep increasing capital spending, but equity prices have already allocated a large share of profits to upstream chips and memory. In the short term, this structure can be pushed forward by orders, price increases, and long-term contracts. In the long term, hyperscalers must sell compute, generate token revenue, and prove cash flow. Otherwise, the higher semiconductor profits rise, the higher customers’ cost of capital becomes, and the easier it is to question the next capex cycle.
Meta Selling Compute: The Last Straw That Breaks the Semiconductor Euphoria?
This is also a continuation of the earlier piece on Meta selling compute. The significance of the Meta event was not the 250MW itself, but that the market for the first time began auditing AI capex as a cash-flow asset. JPM now approaches the issue from another angle: if hyperscalers cannot prove compute monetization fast enough, the faster semiconductors rally, the more pressure cloud companies face in equities and credit, and the more easily supply-chain valuations can shift from “order scarcity” back to “customer stress.”
The conclusion of this report is clear: the semiconductor trade still has fundamental support, but the decisive factor in the second half has shifted from “whether there is AI demand” to “who can turn AI demand into sustainable cash flow.” This divides the trade into three layers: first, memory, which still has supply constraints and long-term contract protection; second, advanced packaging, PCB, equipment, and power interconnects with the highest order visibility; third, hyperscalers and software assets that need AI monetization to justify valuations.
2. Semiconductors Are Outperforming Hyperscalers Because of 2026 Capex, but the Risk Is in 2027
JPM Flows & Liquidity lays out the hyperscaler capex table directly: 2026 consensus expectations have already entered doubling territory, which has fueled semiconductor and memory outperformance; but the second half of the table shows growth slowing significantly after 2027. The market is now trading the 2026 upward revision while worrying about the 2027 slope.
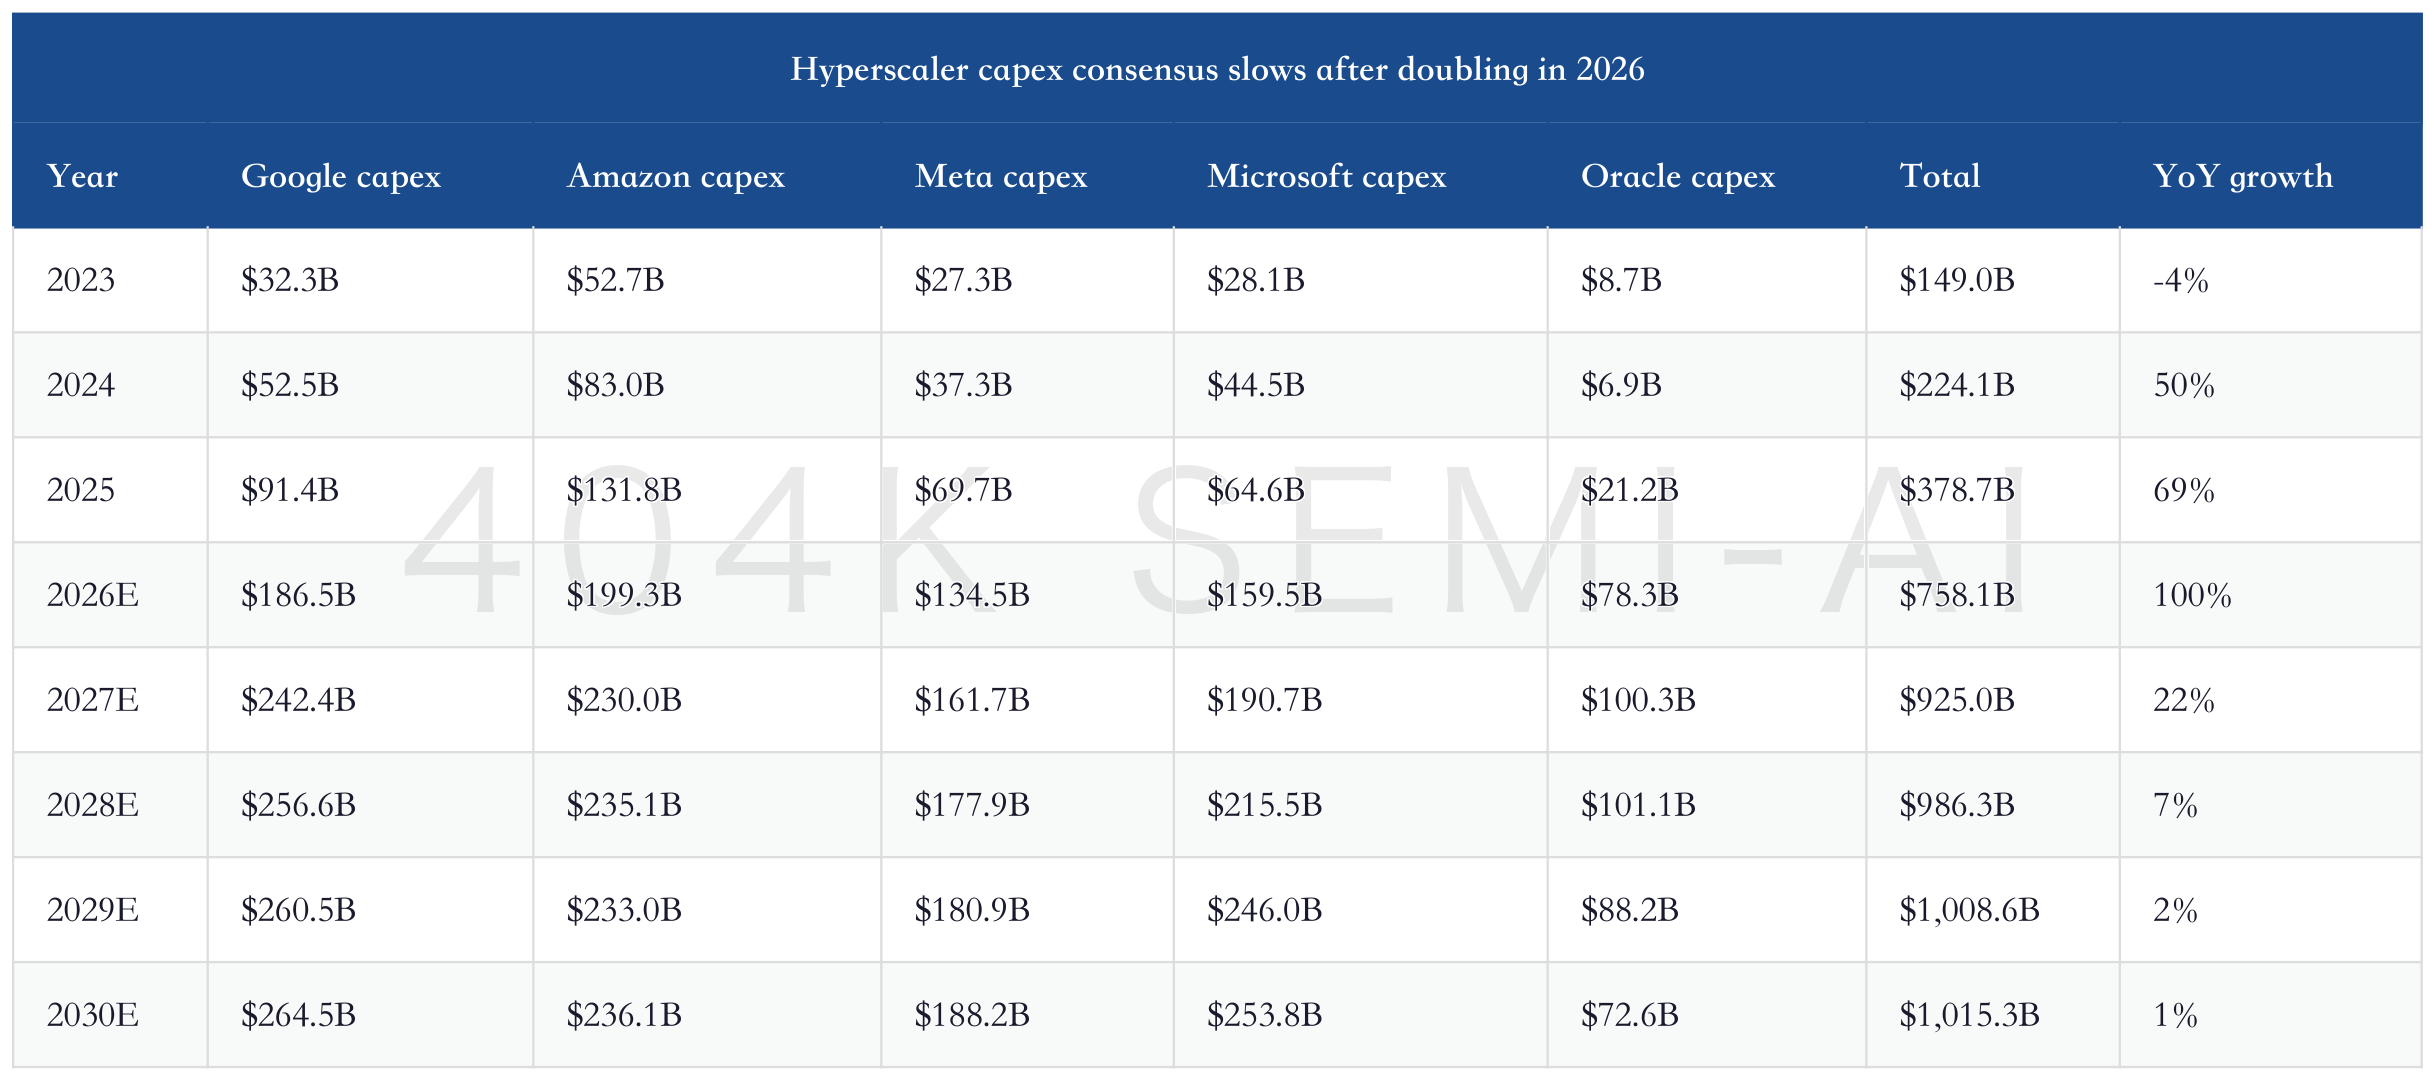
This table is not bearish on semiconductors. It is a reminder that the trading rhythm of semiconductors is now tied to the “second derivative of capex.” The 100% YoY growth in 2026 is enough to explain the strength in semiconductors, memory, and equipment over the past several months; the 22% growth in 2027 means the market will soon ask a different question: if capex no longer doubles, can the supply chain still sustain pricing and margins?
JPM also has a more optimistic figure from its semiconductor team: 2027 hyperscaler capex could reach $1.15T, higher than the $925.0B consensus. This difference is not a rounding issue; it reflects a different pricing worldview. Under the $1.15T figure, 2027 remains a year of AI hardware expansion, and memory, advanced packaging, PCB, equipment, and power chains still have order momentum; under the $925.0B figure, 2027 is the year when high growth shifts into profit verification.
This also explains why semiconductor equipment and materials stocks have continued to rerate recently. The equipment chain is not just looking at this year’s orders, but whether 2027 capacity can be locked in early. If hyperscaler capex keeps being revised higher, WFE, advanced-packaging tools, HBM-related equipment, and PCB equipment remain “picks-and-shovels” assets; if capex is revised lower, the equipment chain will feel changes in order cadence earlier than pure memory.
3. The Positive Rotation Script: Hyperscaler Monetization Improves, and the AI Profit Pool Spreads from Chips to Customers
JPM’s positive script is straightforward: AI monetization at hyperscalers, model companies, and end users begins to improve, revenue and profits catch up, and the AI value pool is no longer captured only by chips and memory. In this scenario, semiconductors do not need to collapse; the trade only needs to rotate from the most crowded upstream assets into cloud, software, applications, and networking layers that still have improving profits.
The key validation metric for this script is not GPU shipments, but compute pricing. JPM cites Compute Desk’s Hopper US Index, noting that H100/H200 rental prices remained under pressure through the end of 2025, improved in April-May 2026, but pulled back again in June. If compute prices can stabilize, hyperscalers’ ability to turn capex into revenue improves; if compute prices keep falling, the more hardware orders grow, the more the market will worry about returns on capital.
The positive AI rotation script needs five validation variables to improve at the same time
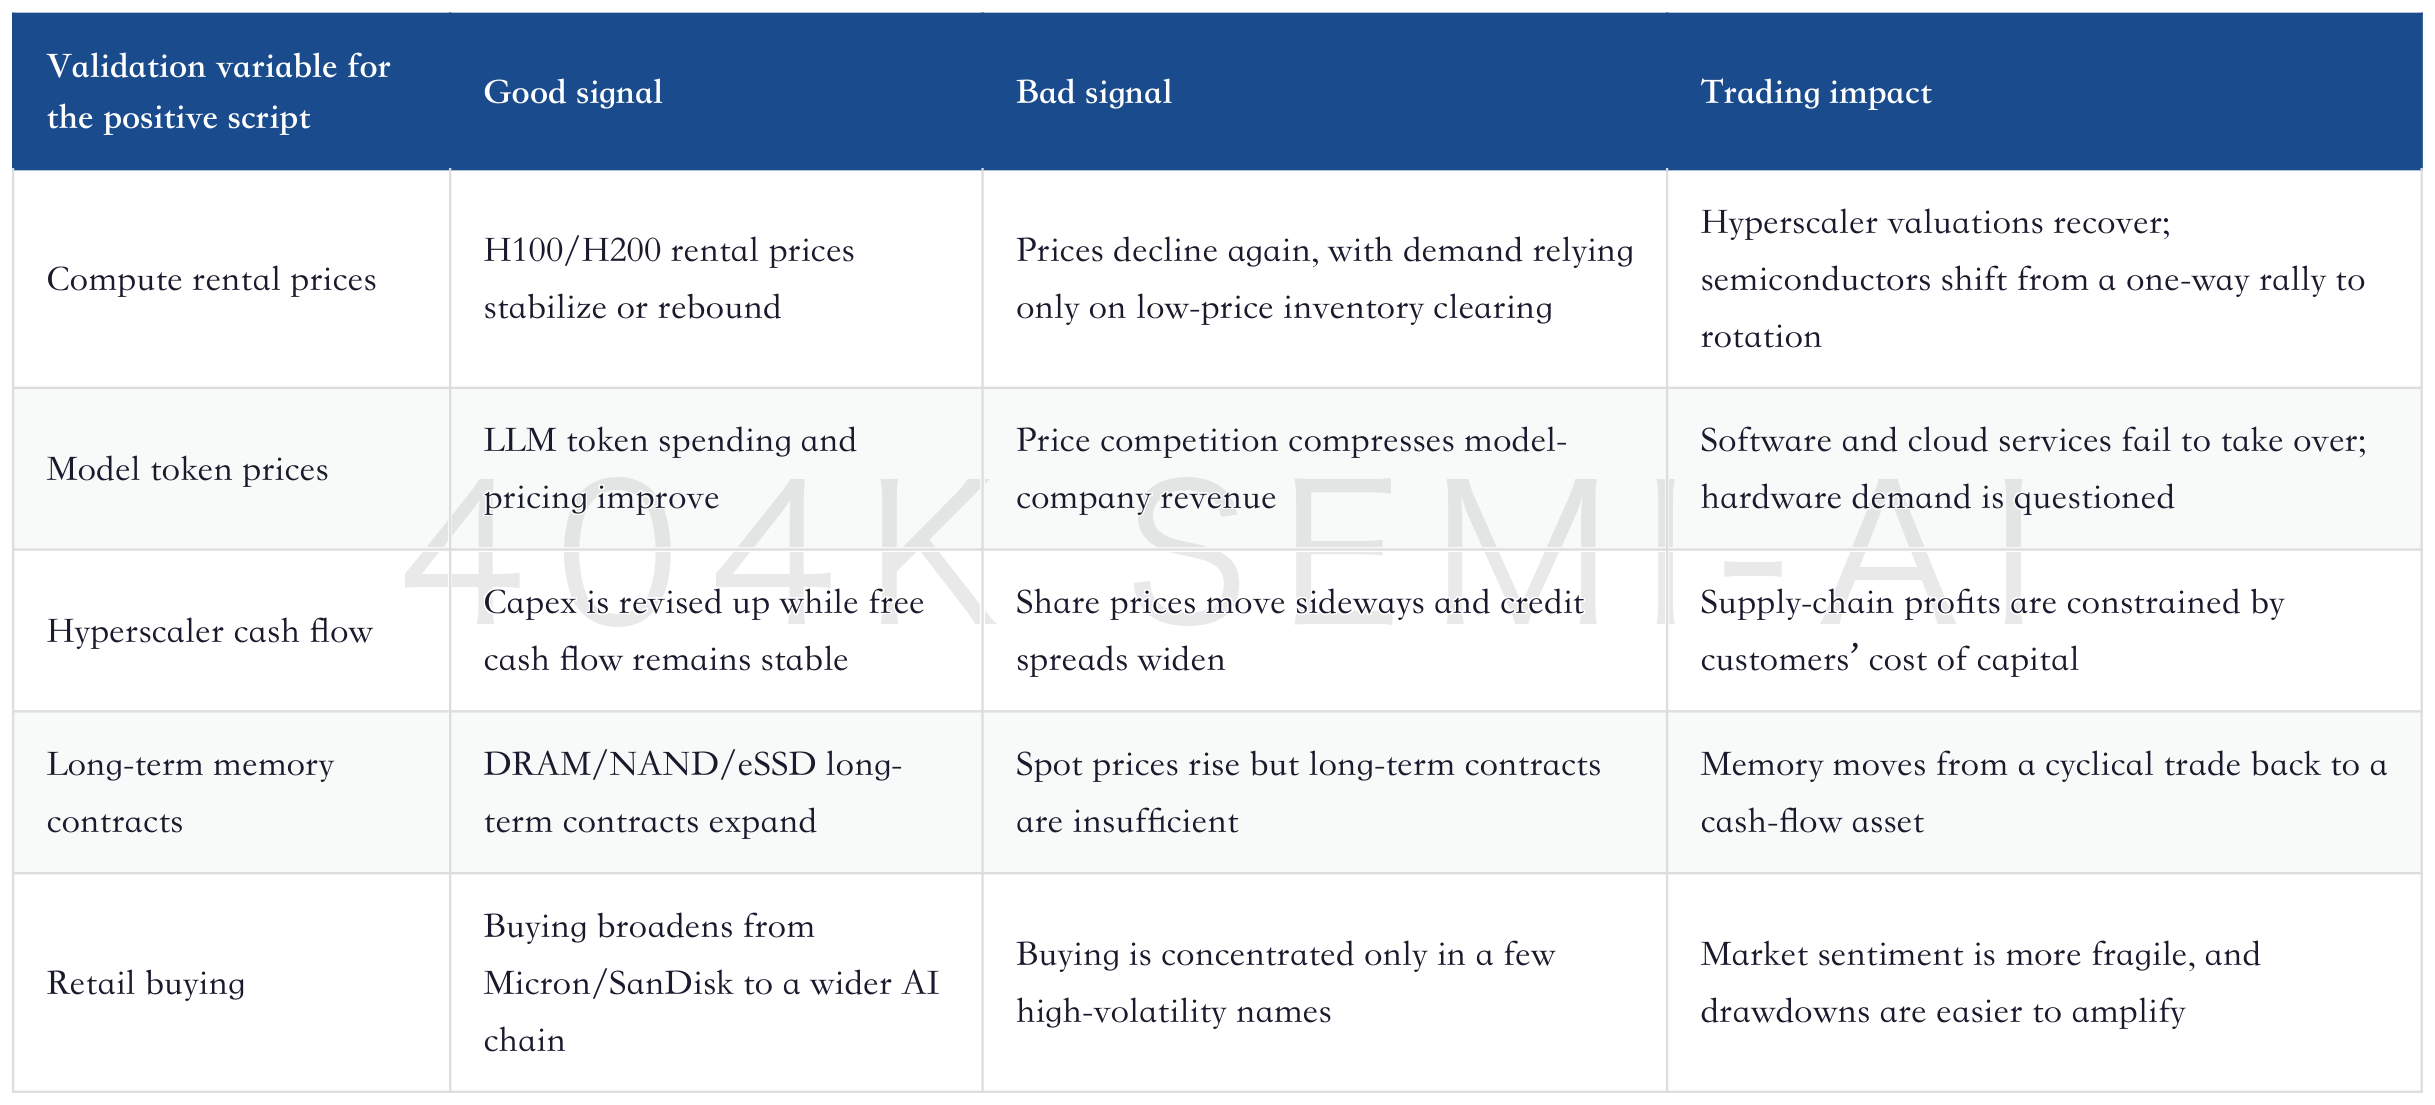
Under the positive script, the best portfolio is not a single-line bet, but a combination of “hardware supply bottlenecks + improved hyperscaler monetization + software commercialization.” Memory remains the segment with the most direct earnings leverage, advanced packaging and PCB are physical bottlenecks, and hyperscalers and AI software are the proof points for whether the profit pool can broaden.
AI Hardware Restocking Deep Dive: Capacitors Hit New Highs, Nearline HDD Capacity Grows 31% YoY, Enterprise SSD Capacity Grows 139% YoY; How Data-Center Demand Is Spreading to Components and Storage
This chain has already appeared in components, HDD, SSD, and capacitor data. As long as AI server buildout continues to broaden, demand will not stop at GPUs and HBM; it will flow through power, connectivity, storage, PCB, passive components, and equipment. The additional piece JPM’s flow report adds this time is that the market is starting to use hyperscaler cash flow to judge how far these orders can run.
IV. Bear Case: Semiconductor Gains Become Customer Costs, Forcing Capex to Slow in 2027
The bear case is also straightforward: semiconductors and memory rise too quickly, upstream suppliers capture too much value, and hyperscalers and model companies begin to face pressure on share prices, credit spreads, and cost of capital. If that pressure affects 2027 capex appetite, the hardware chain will shift first from “not enough supply” to “will customers cut orders?”
JPM observes several risk signals. Hyperscaler share prices have been broadly flat over the past year, with strong profit growth failing to drive valuation expansion. Credit spreads have widened relative to semiconductor companies, implying that debt financing costs are also rising. In short-interest data, hyperscaler short interest has been rising since last October and moved higher again in May-June. Short interest in semiconductors excluding memory also rose in May-June, but has not yet exceeded year-ago levels.
These signals suggest the market is not rejecting AI outright, but is re-segmenting who benefits and who pays within the AI chain. If memory and semiconductor price increases are accompanied by customer monetization, they will be viewed as normal profit redistribution. If they show up only as customer capex pressure and rising cost of capital, they will be viewed as the supply chain taxing customers.
The Bear Case for the AI Hardware Trade Comes From Rising Customer Cost of Capital
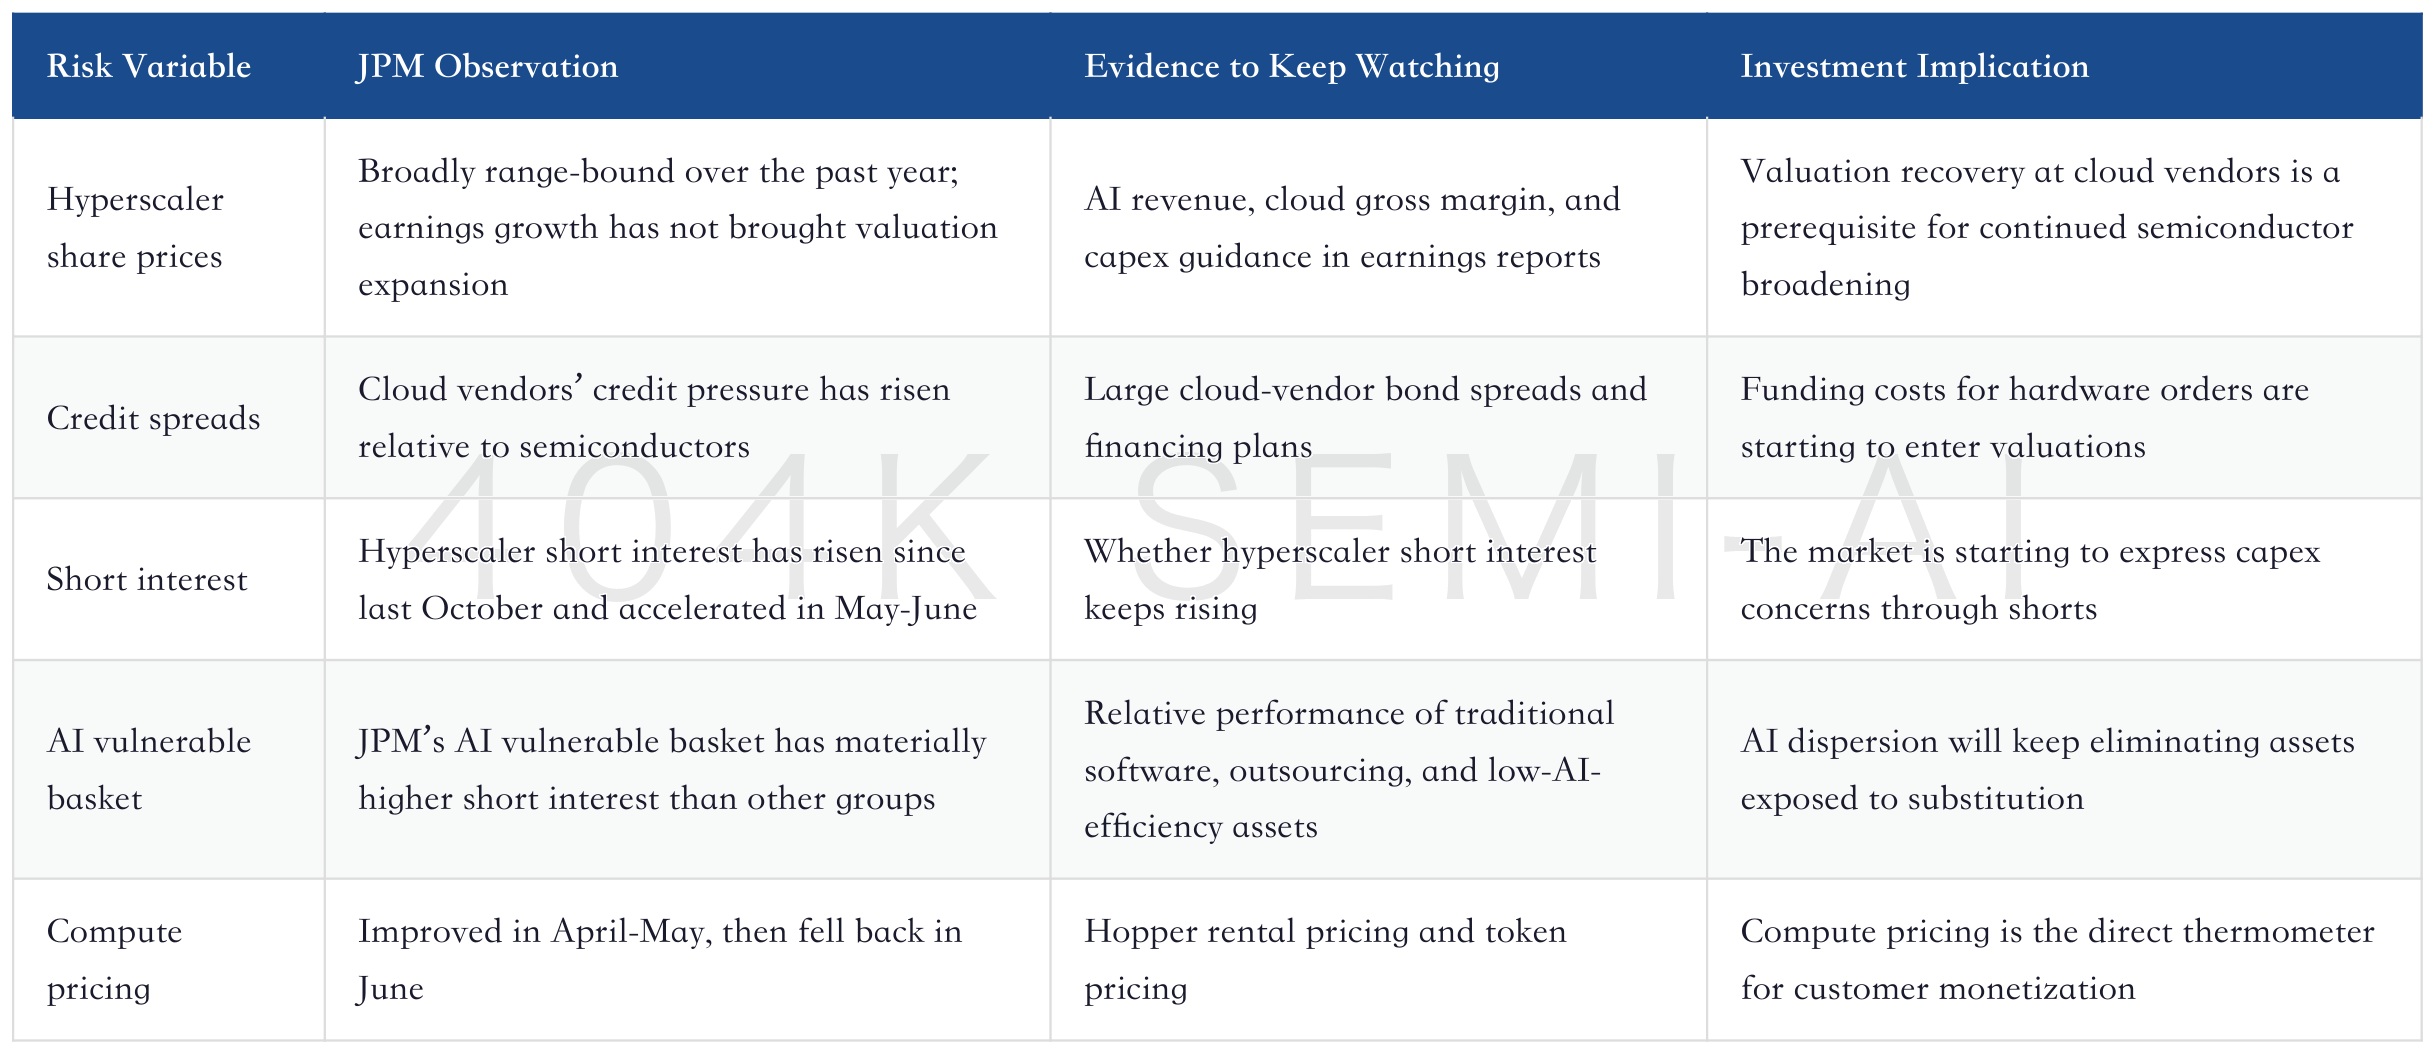
This is also why “semiconductor crowding” cannot simply be read as a sell signal. Crowding itself can be digested through rotation, or extended through continued fundamental delivery. The real danger is when crowding and customer pressure appear at the same time: upstream valuations are high, downstream cash flow has not caught up, and the market begins to demand hard evidence for 2027 orders and capex.
Meta compute subleasing, Hopper rental prices, LLM token spending, and cloud-vendor capex guidance will now become different pieces of evidence for the same question. Together, they answer one thing: is AI capital spending future cash flow, or a short-term scramble for capacity?
V. Retail Has Not Left; Buying Is Concentrated in Memory and Semis
The conclusion from JPM Retail Radar is strong: for the week of June 25 to July 1, retail flows remained highly resilient, with overall inflows at the 75.4th percentile, single-stock inflows at the 94.8th percentile, and ETF activity only at the 17.5th percentile. Wednesday’s one-day buying reached the 93rd percentile. Capital is not buying the market evenly; it is still buying AI, memory, and technology hardware amid high volatility.
Total Retail Inflows Are Above the 12-Month Average, but ETF Activity Is Not High
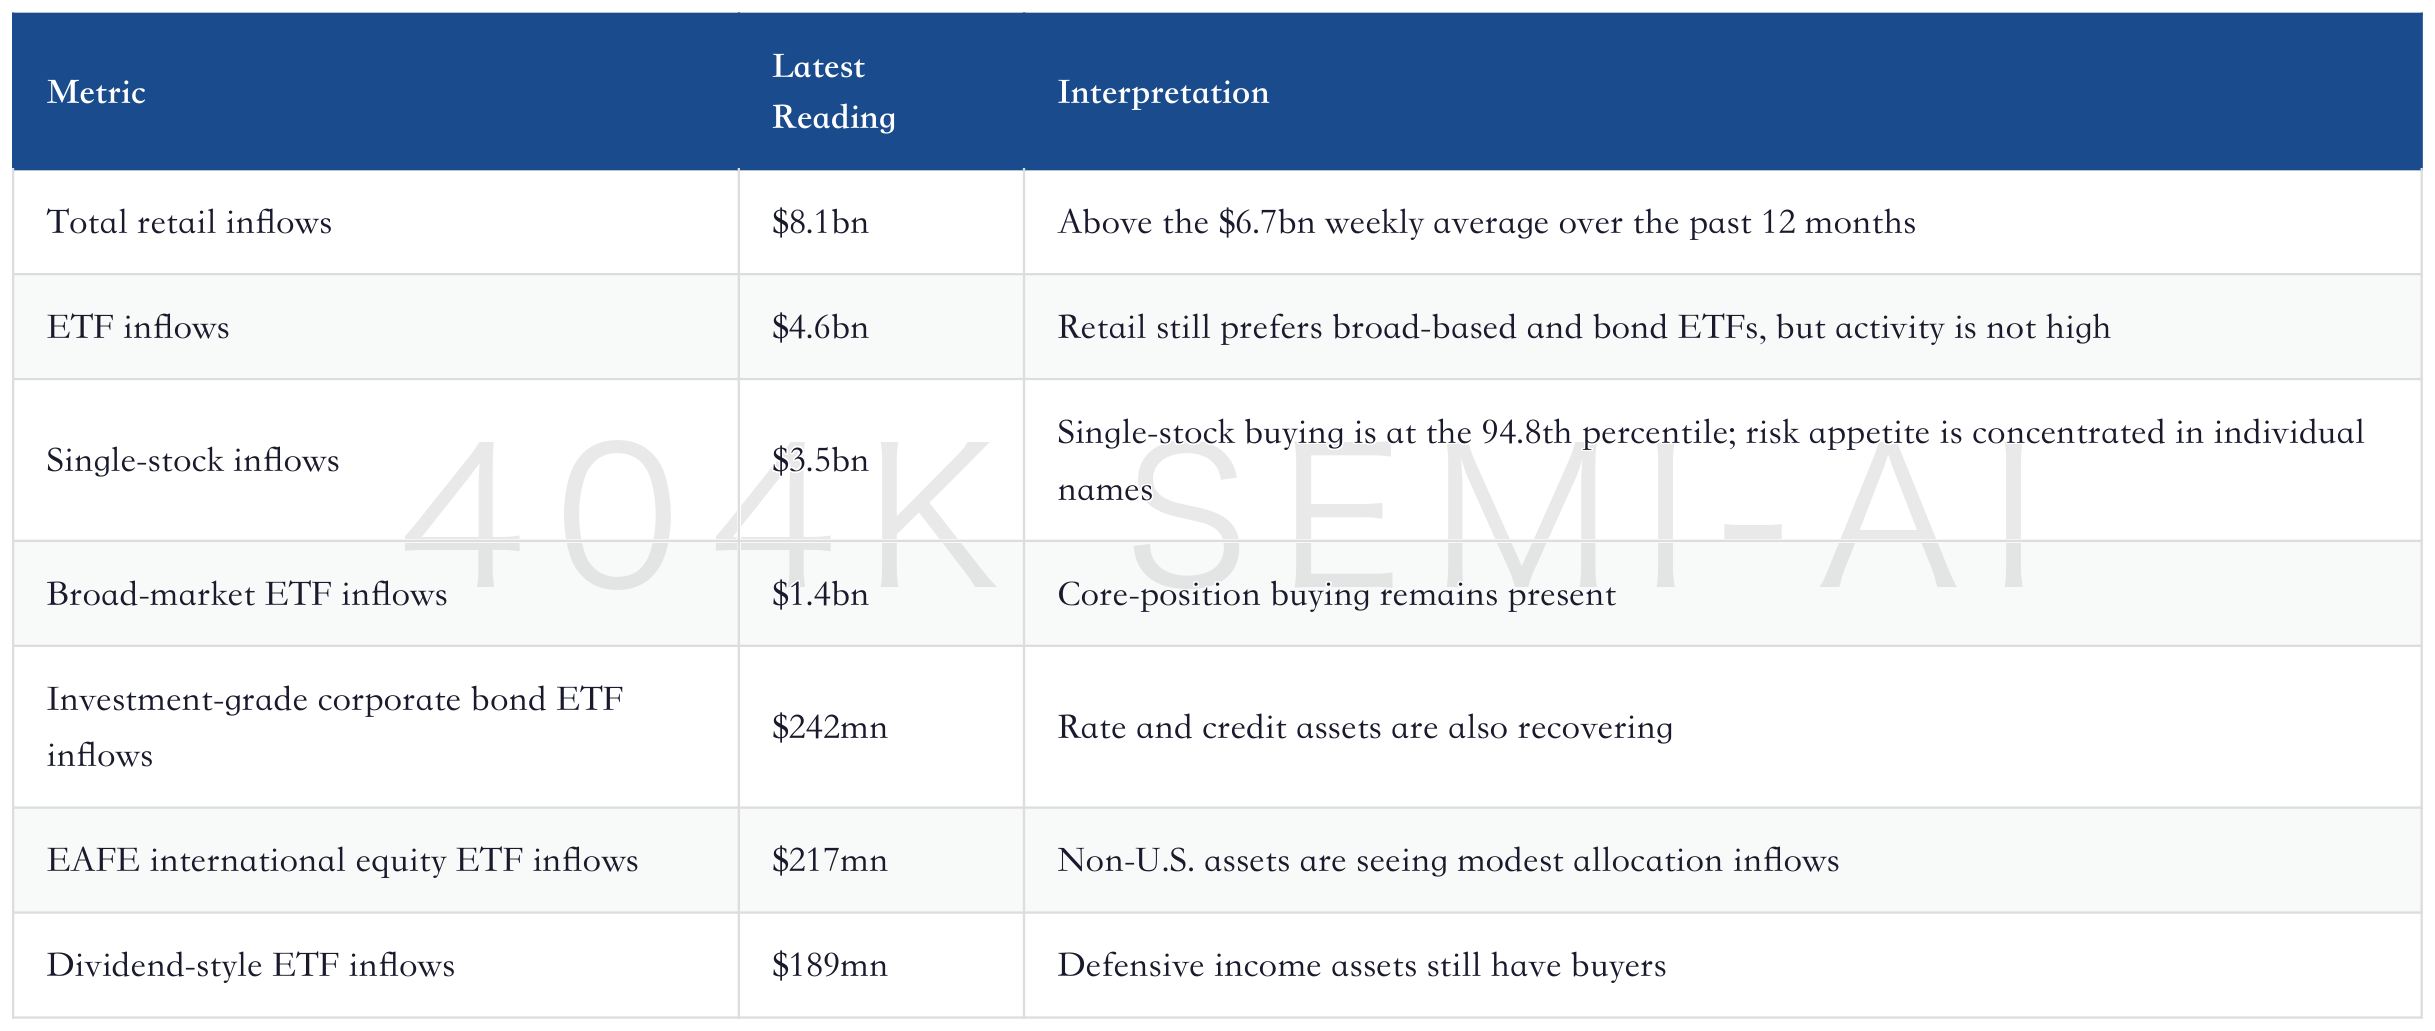
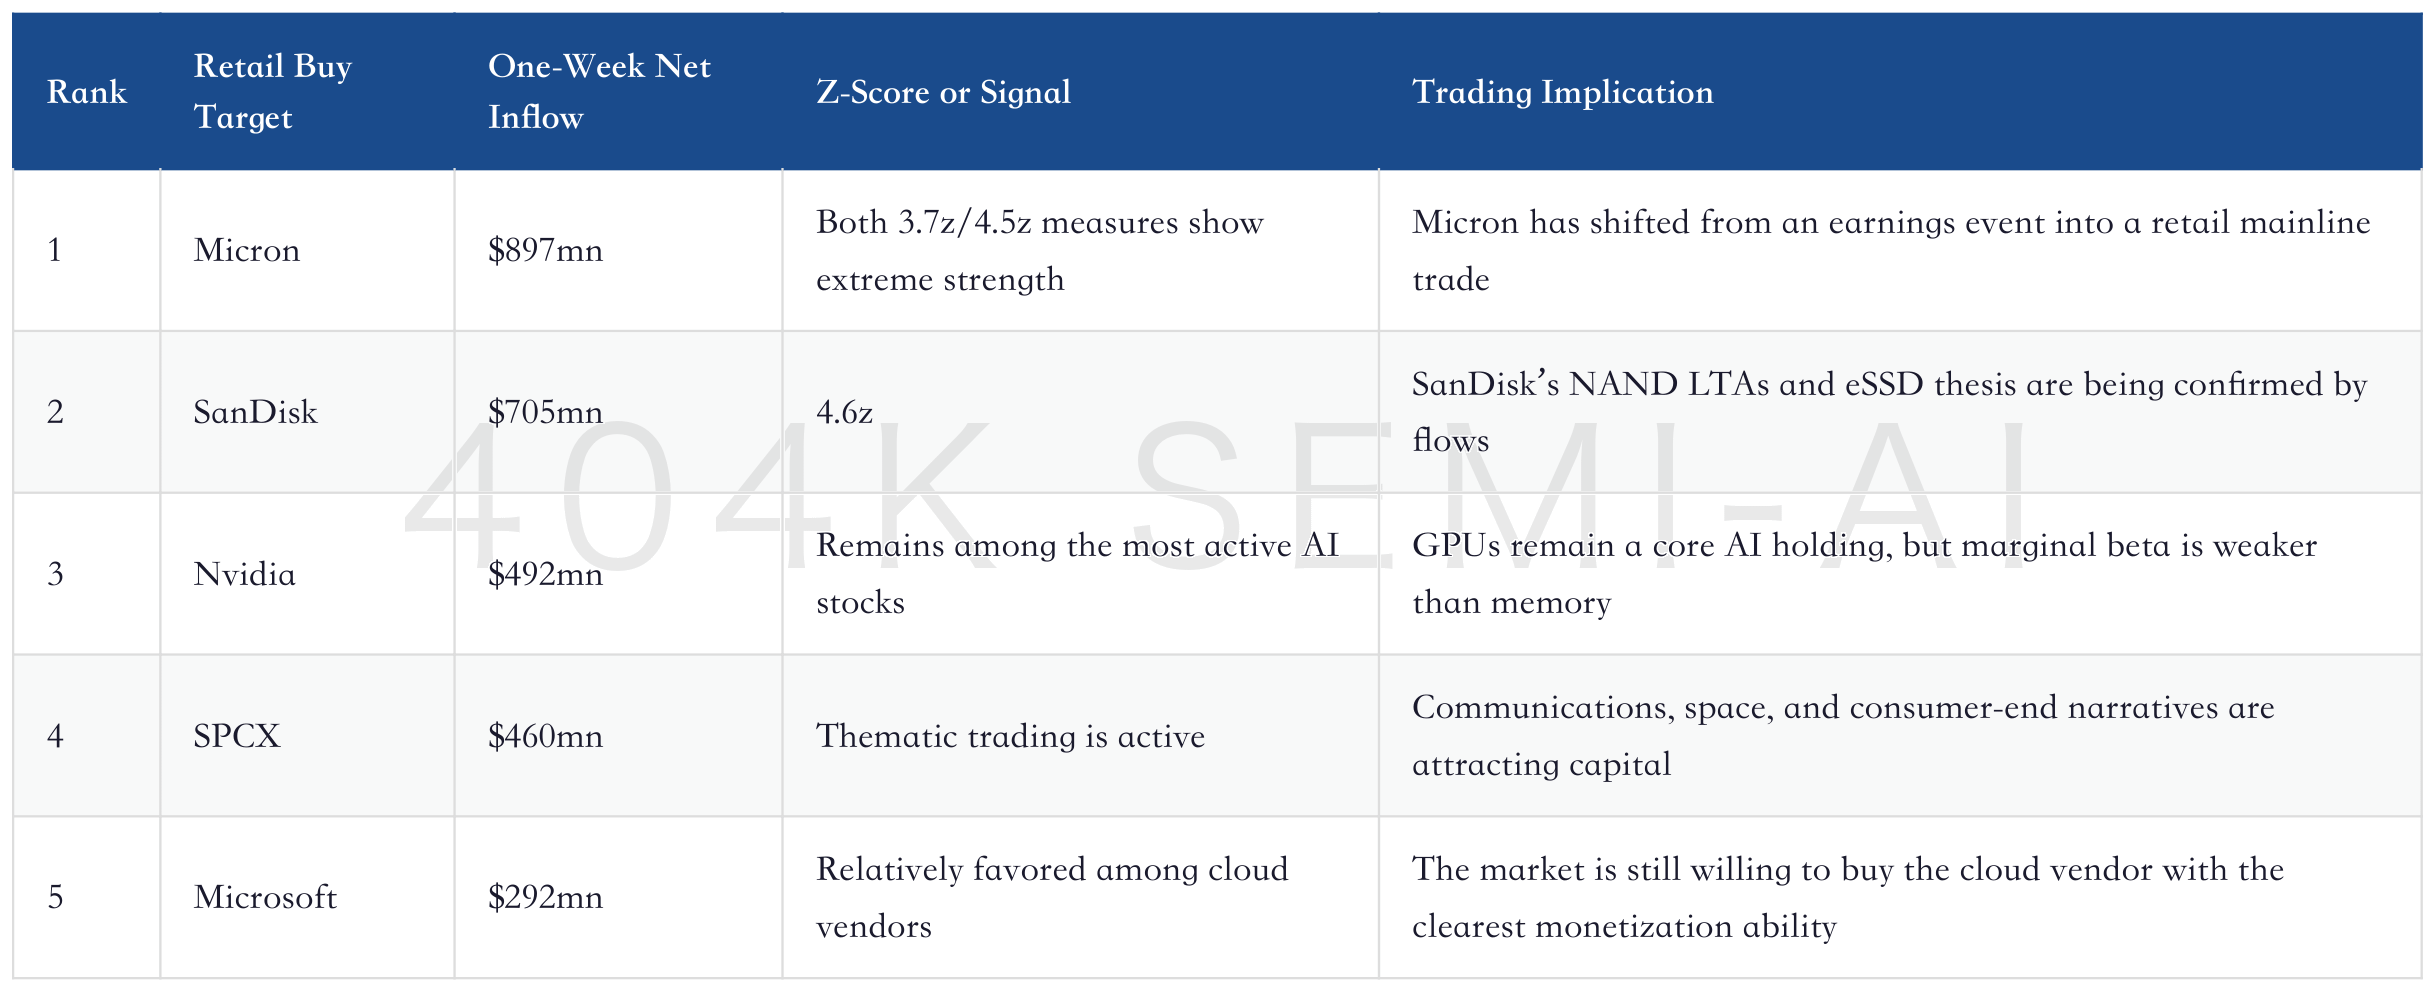
The more important point is the single-stock leaderboard. The names retail bought the most were Micron, SanDisk, Nvidia, SPCX, and Microsoft, with inflows of $897mn, $705mn, $492mn, $460mn, and $292mn, respectively. The most-sold names were Tesla, Oracle, Cisco, Visa, and TDG. The structure is very clear: retail is cutting some consumer, traditional technology, and drawdown names, while adding to memory, semiconductors, space communications, and Microsoft.
Micron and SanDisk Have Become the Most Concentrated AI Hardware Buy-the-Dip Targets for Retail
Micron Re-Rating After Earnings: JPM Calls for $1,540; What Are Four Investment Banks Actually Buying?
Micron’s buying is highly important. It shows retail is not merely buying an “AI concept,” but a more specific change: memory is moving from a high-beta cyclical stock into a cash-flow asset protected by long-term agreements, HBM, eSSD, and data-center capacity demand. JPM also noted in Retail Radar that Micron expanded strategic customer agreements from one five-year contract to 16, which will change the market’s perception of downside risk.
SanDisk Deep-Dive Update: Bernstein’s $3,000 Target Price; How New Memory LTAs Rewrite the NAND Cycle Discount
SanDisk’s buying is also not accidental. NAND was previously seen as a more cyclical asset more prone to oversupply, but eSSD, enterprise storage, and new memory LTAs are changing cash-flow visibility. Retail buying SanDisk to 4.6z is essentially trading the possibility that NAND shifts from an “inventory cycle” to an “AI capacity bottleneck.”
VI. Retail Buys Cash Equities, Non-Retail Sells Futures: The Market Is Not Uniformly Bullish
The easiest mistake is to read Retail Radar as “everyone is chasing AI.” In the same report, non-retail futures traders net sold about $11.3bn over the past week, mainly from roughly $7.3bn in ES, $2.2bn in NQ, and $1.8bn in RTY. In other words, retail continues to buy in cash equities, while non-retail is reducing risk in futures.
Retail Buys AI Hardware in Cash Equities While Non-Retail Futures Reduces Index Risk
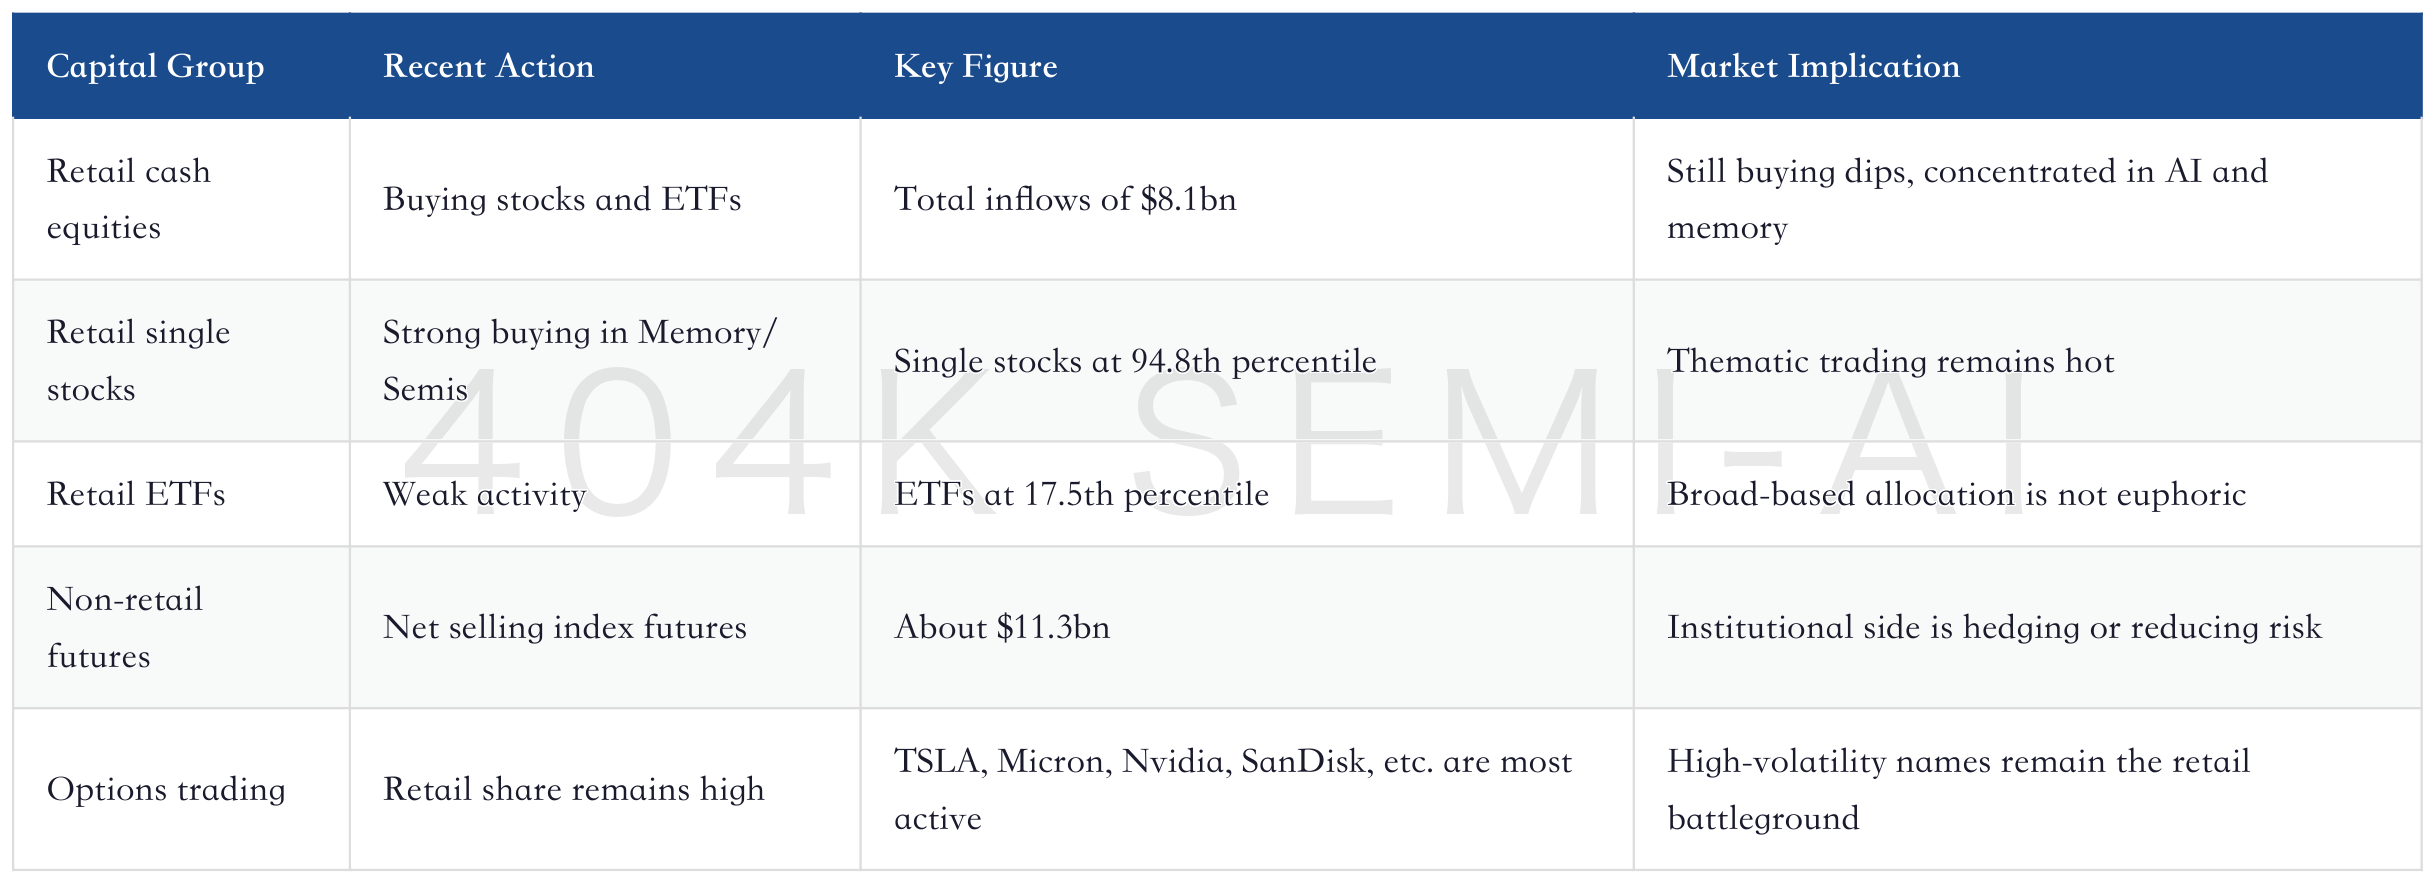
This divergence creates two outcomes. First, an index-level drawdown may not immediately interrupt trading in memory and semiconductor single stocks, because retail cash buying will keep buying dips in strong themes. Second, once memory or AI hardware starts losing fundamental confirmation, concentrated retail buying will amplify volatility in reverse, because buying is crowded, options participation is high, and institutional futures has already been reducing risk.
This is also why this report cannot simply say “retail is still buying.” The more accurate judgment is: the market is using different instruments to express different views. Retail is using cash equities and options to keep buying AI hardware; institutions are using index futures to reduce portfolio risk; JPM’s strategy report is demanding that the AI trade move from a one-way rise in semiconductors toward cloud-vendor monetization and supply-chain profit redistribution.
VII. Thematic Baskets Show Capital Is Buying AI Infrastructure, Not Just a Few Star Stocks
Retail Radar’s thematic baskets better explain capital preferences. The most concentrated buying is in AI data centers, electrification, the largest AI beneficiaries, growth, and AI software monetization, showing that retail is not buying only a few star stocks, but is buying a set of infrastructure assets along the AI capital-spending chain.
Retail Thematic Buying Is Spreading Across Both AI Data Centers and AI Software Monetization
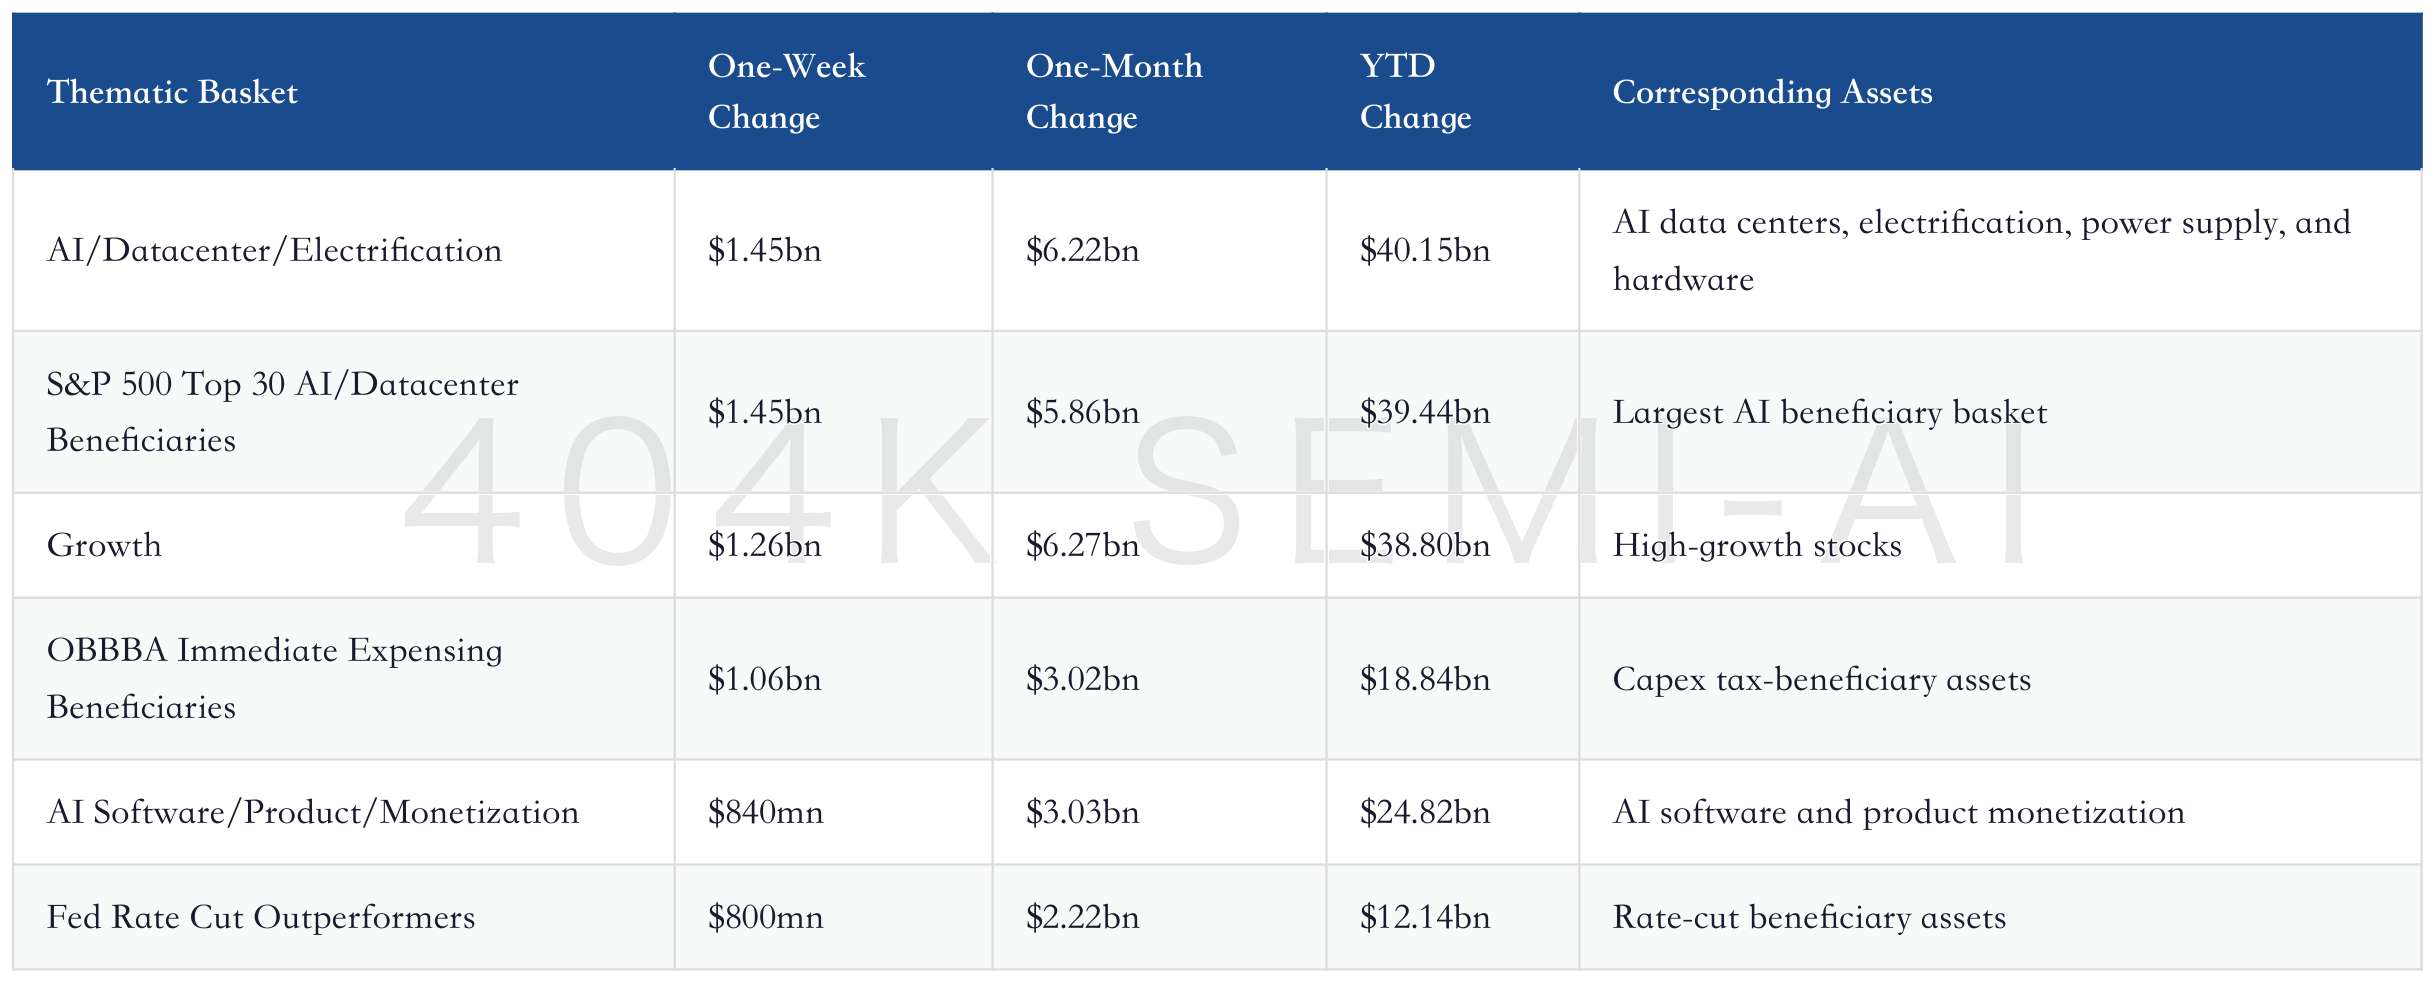
Capital buying AI infrastructure shows this trade has already broadened from “buy Nvidia” into a wider capex-beneficiary chain. This broadening is positive for the hardware chain, because it shows the market is willing to pay for power, networking, storage, PCBs, advanced packaging, and data-center supporting assets. It is also pressure on valuations, because once AI capex is questioned, the affected scope is no longer just GPUs, but the entire AI infrastructure basket.
AI PCB and CCL Deep Dive: From GB300 to Rubin Ultra, Who Runs Short First in High-Layer Boards, M9 Materials, and Electronic Cloth?
AI PCB and CCL are typical examples of this broadening. GPU iteration, HBM bandwidth, Rubin Ultra racks, and higher-layer boards will push hardware bottlenecks from chips into materials and board-level interconnects. Capital flows are now validating this logic: buying is not only in Nvidia, but also in Memory, Semis, AI data centers, and electrification baskets.
8. Why Memory Has Become the AI Asset Retail Investors Are Most Willing to Carry Forward
Memory has become the retail handoff point for three reasons. First, AI server memory and storage demand has moved from a "configuration upgrade" to a "system bottleneck," with HBM, DDR5, eSSD, and NAND all being repriced. Second, long-term agreements are improving cash-flow visibility for cyclical stocks, and the market is beginning to capitalize part of peak earnings. Third, memory stocks are volatile and have a clear price-hike narrative, making them naturally suited to retail dip-buying and options trading.
Goldman Sachs DRAM Deep Dive Update: DDR5 Price Hikes, 2027 HBM Repricing, and Samsung's KRW 2,450 Trillion Investment
The core issue for the DRAM line is whether "prices and long-term agreements can rise together." If only spot prices rise, the market will treat the sector as cyclical. If HBM, DDR5, and server memory enter customer volume lock-ins, the market will mark up earnings stability. Micron's 16 strategic customer agreements are the direct reason retail buyers are willing to step in.
The NAND and SSD line looks more like an "undervalued capacity option." HDD and enterprise SSD data already show that data-center capacity demand remains high. If eSSD and NAND long-term agreements continue to expand, SanDisk, Kioxia Holdings, and related module/controller companies will shift from cyclical beta to cash-flow revaluation. Retail investors buying SanDisk are not buying an ordinary rebound; they are buying improved durability in NAND profits.
But the memory trade is also the easiest to overheat. Retail Radar shows Micron and SanDisk both rank high in social-media attention and retail inflows, while active options names also include Micron, SanDisk, Nvidia, AMD, and others. The more concentrated the buying and the narrative become, the more important it is to cool down the thesis through fundamental verification: DRAM contract prices, NAND contract prices, eSSD orders, HBM capacity allocation, long-term agreement duration, customer prepayments, and cloud capex guidance all matter more than a single day's stock price.
9. Cross-Asset Liquidity Still Supports Risk Assets, But It Is Not an Unconditional Backstop
Flows & Liquidity also contains an underlying macro judgment: U.S. money creation is expected to rise from USD 1.6 trillion in 2025 to USD 1.8 trillion in 2026. This pace is stronger than nominal GDP and remains supportive for U.S. equities. Put simply, as long as the banking system, money-market funds, Fed assets, and credit creation together can still provide liquidity, risk assets are unlikely to enter a liquidity-less selloff easily.
But JPM also notes that cash allocations among global non-bank investors are already low. Low cash does not mean an immediate decline, but it means the market has less new defensive cushion when shocks hit. Historically, the pandemic, inflation shocks, tariff shocks, and geopolitical risks have all pushed investors to rebuild cash. If the AI trade encounters a macro shock while crowded, portfolio rebalancing will amplify volatility.
The MicroStrategy section appears unrelated to AI, but it points to the same liquidity mechanism. After the company began retaining flexibility to sell Bitcoin to pay preferred dividends and interest, the market needed to reprice two-way flow risk in Bitcoin. If an asset holder previously viewed as a one-way buyer becomes a potential seller, the volatility structure of the trade changes. The AI hardware chain is similar: if cloud vendors previously viewed as unconditional capex expanders start emphasizing return on capital, supply-chain valuations need to be repriced.
U.S. money creation is supporting risk assets, but low cash allocations will amplify shocks
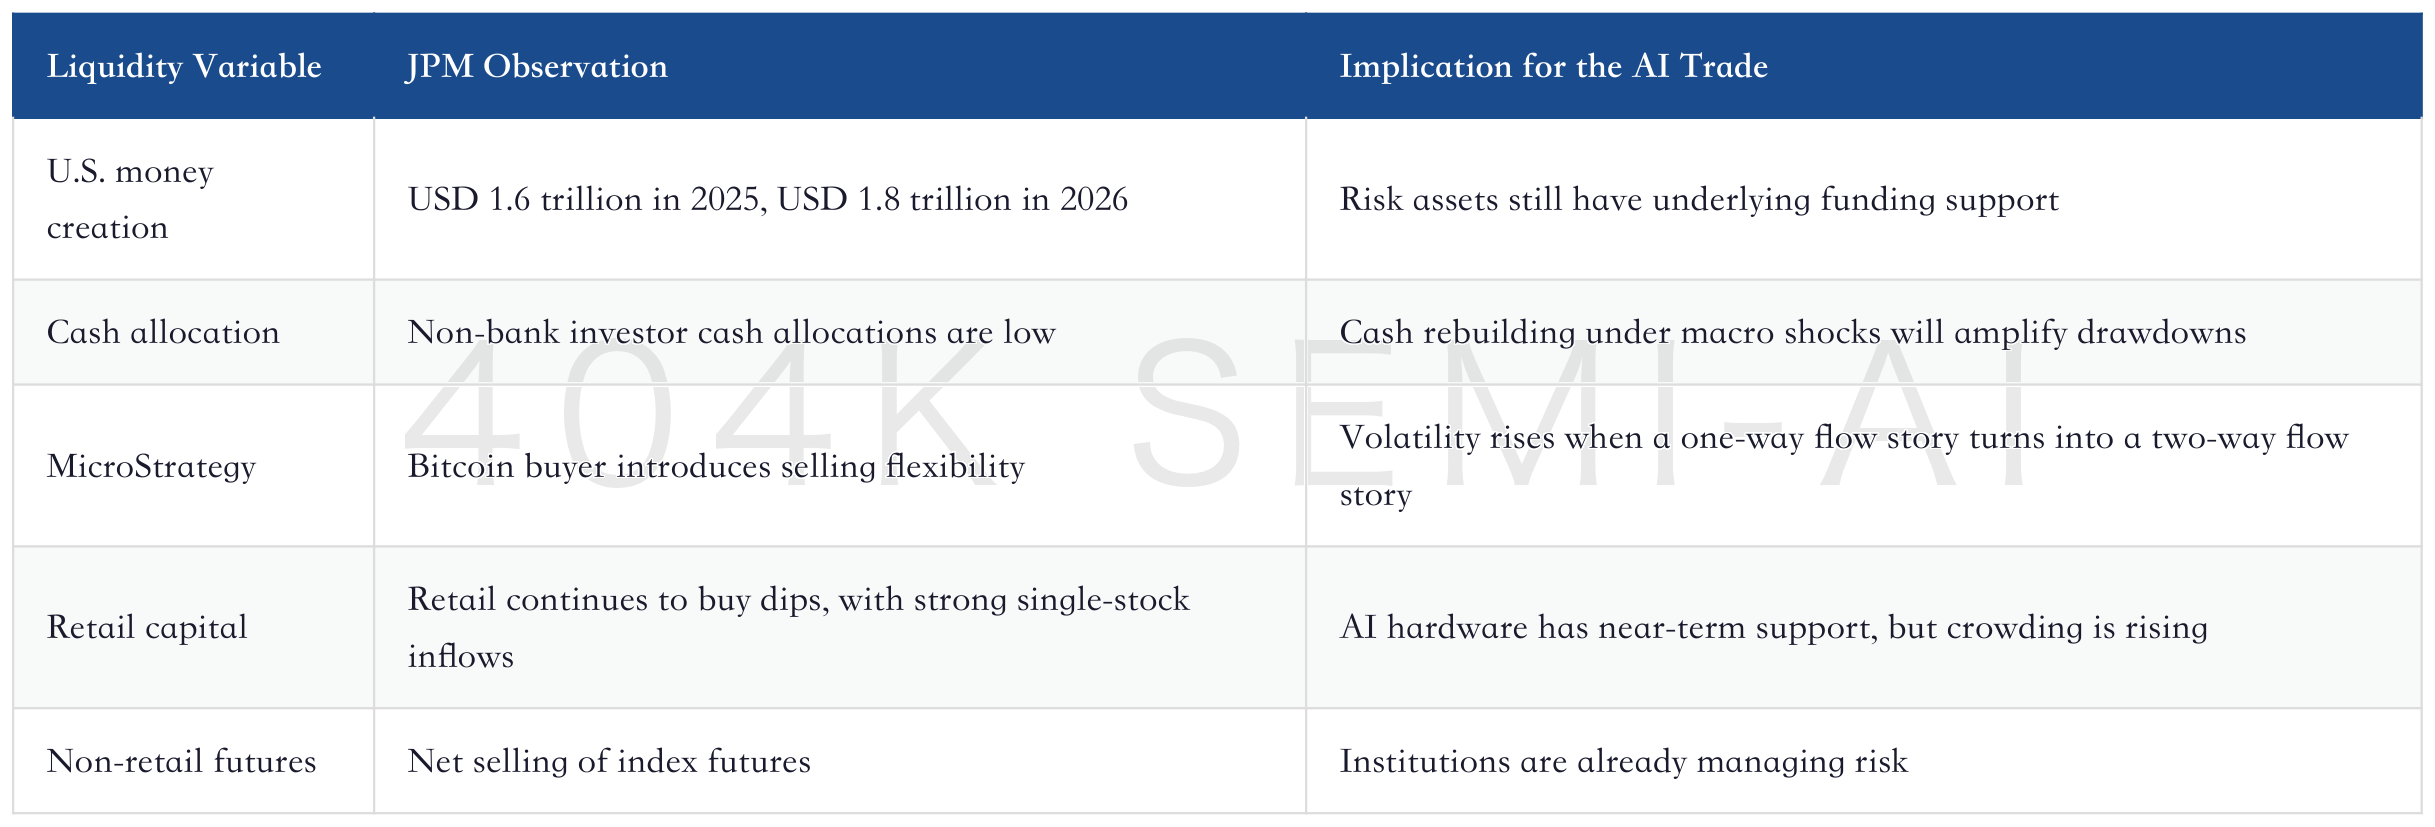
This combination matters for the second half. Liquidity remains, retail is still buying, and AI fundamentals are still strong, but that does not mean all AI assets can continue rising together. Flows will become more selective: cloud vendors that can convert capex into cash flow, memory companies that can convert price hikes into long-term agreements, and PCB/equipment companies that can convert orders into effective capacity will continue to receive premiums; assets relying only on narrative, without price and cash-flow validation, will be left behind by capital flows.
10. Investment Framework: Four Questions to Judge Whether the AI Trade Has Entered Its Second Phase
Taken together, these two reports provide a very practical framework. The first phase of the AI trade focused on orders and capex; the second phase needs to focus on capital flows, customer cash flow, and profit distribution. In the second half, investors do not need to ask every day whether "AI is a bubble." They should ask four more specific questions.
The second phase of the AI trade requires four questions to reconcile the accounts together
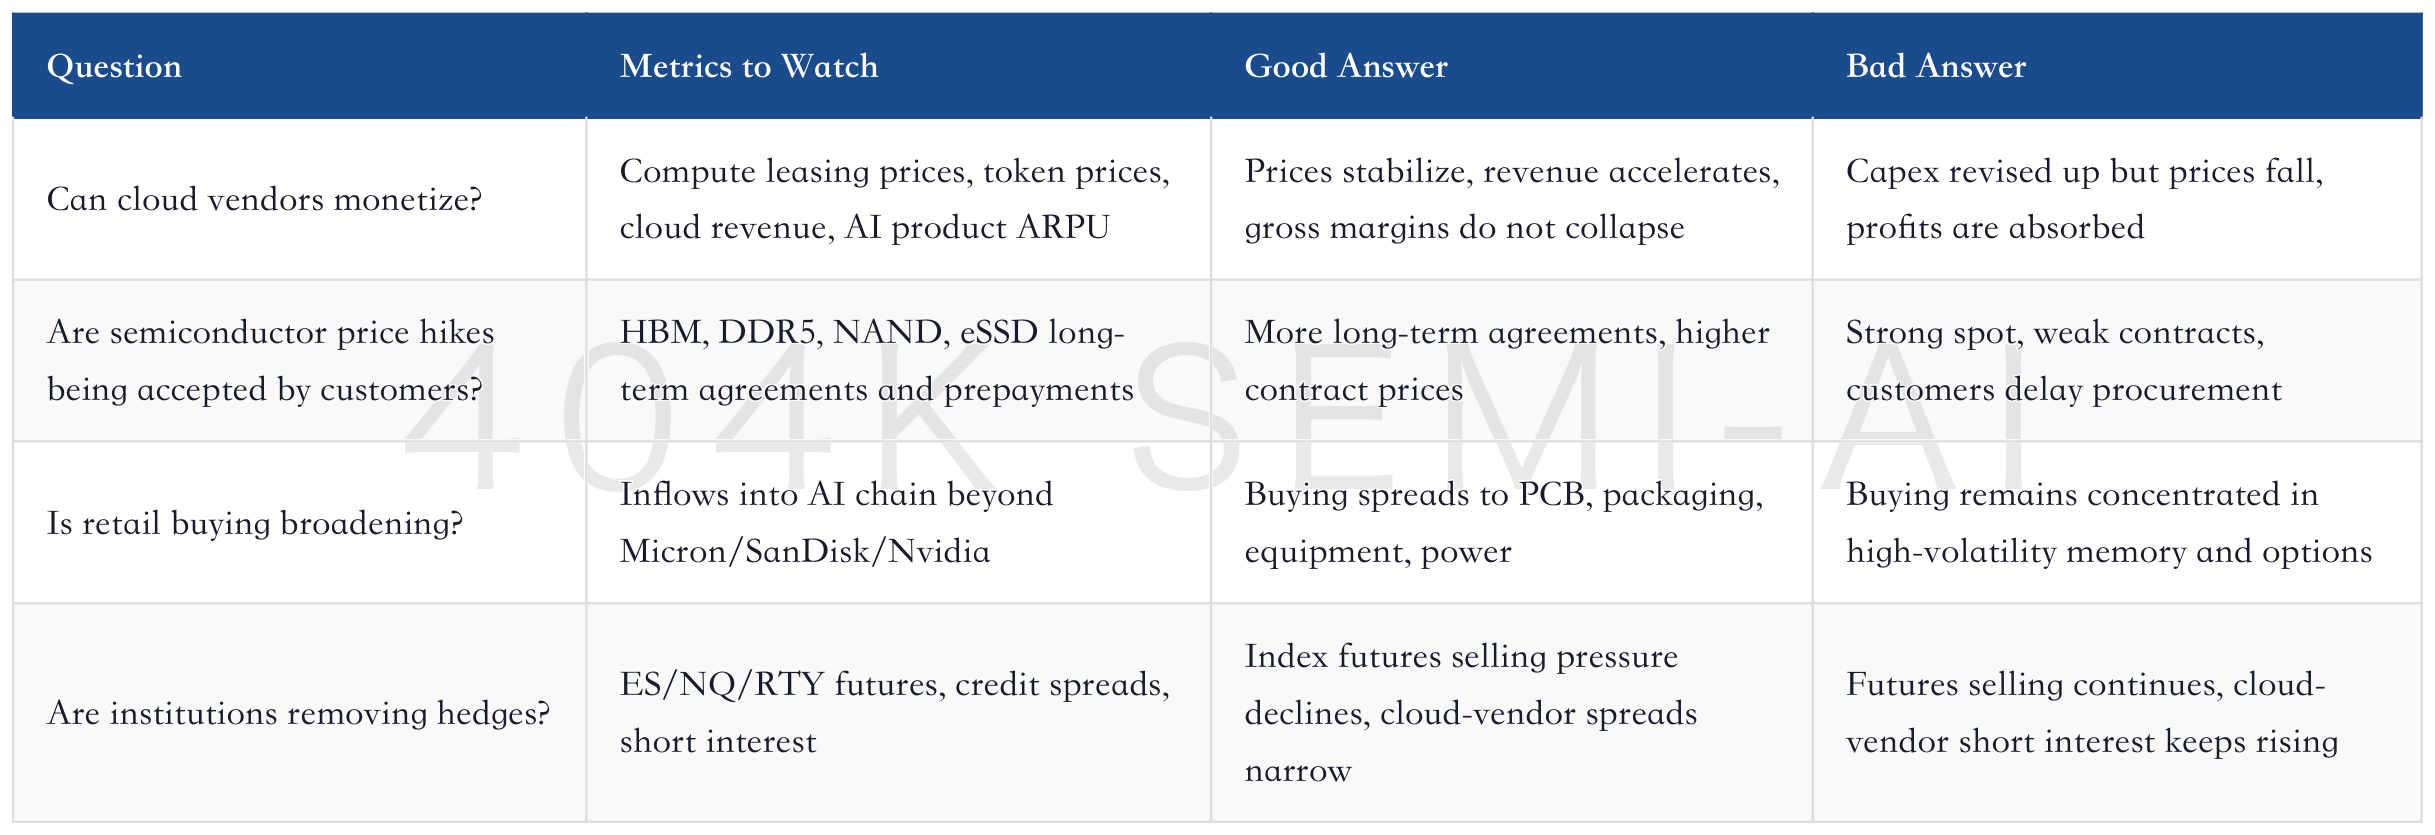
The first question determines cloud-vendor valuations, the second determines memory and semiconductor profits, the third determines whether the trade can broaden, and the fourth determines whether drawdowns will be amplified by institutional selling pressure. Only if all four questions improve will AI hardware move from "crowded strength" into "healthy rotation."
Korea Export Deep Dive: June Exports Up 70.9% YoY, and How the AI Hardware Surplus Opens Room for KOSPI Revaluation
Korea exports and the KOSPI are a strong external validation point. If memory, HBM, and AI hardware have truly entered a cash-flow realization phase, Korean technology exports and foreign inflows will provide a macro signal earlier than any single U.S. stock. JPM's flow report discusses the trading structure of the U.S. market, while Korean data can verify whether hardware demand is spreading globally.
Japan Semiconductor Equipment Deep Dive: Goldman Sachs Raises Target Prices for 10 Companies by 16%, AI WFE Enters Earnings Realization Phase
Japan's equipment chain is likewise a 2027 validation point. If cloud-vendor capex is not cut, orders for advanced packaging, HBM, WFE, and materials will continue to translate into results; if a 2027 capex slowdown starts to enter orders, the equipment chain will reflect it earlier than end-market memory prices.
11. Portfolio Implications: Stay Bullish on AI Hardware, But Shift from "Chasing Momentum" to "Reconciling the Accounts"
The conclusion of this report is not that investors should leave AI hardware, but that AI hardware should shift from a momentum trade to an accounting-verification trade. Retail buying is still there, memory and semiconductor fundamentals remain strong, and liquidity has not withdrawn; but the risk flagged by JPM is already clear: semiconductors have outperformed cloud vendors by too much, and this must be digested through improved cloud-vendor monetization.
The smoothest path is as follows: Hopper leasing prices and token revenue stabilize, cloud-vendor share prices and credit spreads recover, 2027 capex moves from the consensus expectation of USD 925 billion toward JPM's semiconductor team's USD 1.15 trillion, memory long-term agreements continue to increase, and retail buying broadens from Micron and SanDisk to a wider AI chain. Under this path, the AI trade will shift from single-point crowding in semiconductors to rotation across hardware, cloud, software, and applications.
The worst path is also clear: compute prices keep falling, the market demands cloud vendors slow capex, short interest in hyperscalers keeps rising, retail remains concentrated in Micron, SanDisk, and options, and institutional futures selling continues. Under this path, semiconductors will first undergo valuation clearing, and memory stocks will also be pushed back from "long-term-agreement cash-flow assets" into "high-beta cyclicals."
Asset ranking after AI hardware portfolios shift from chasing momentum to account verification
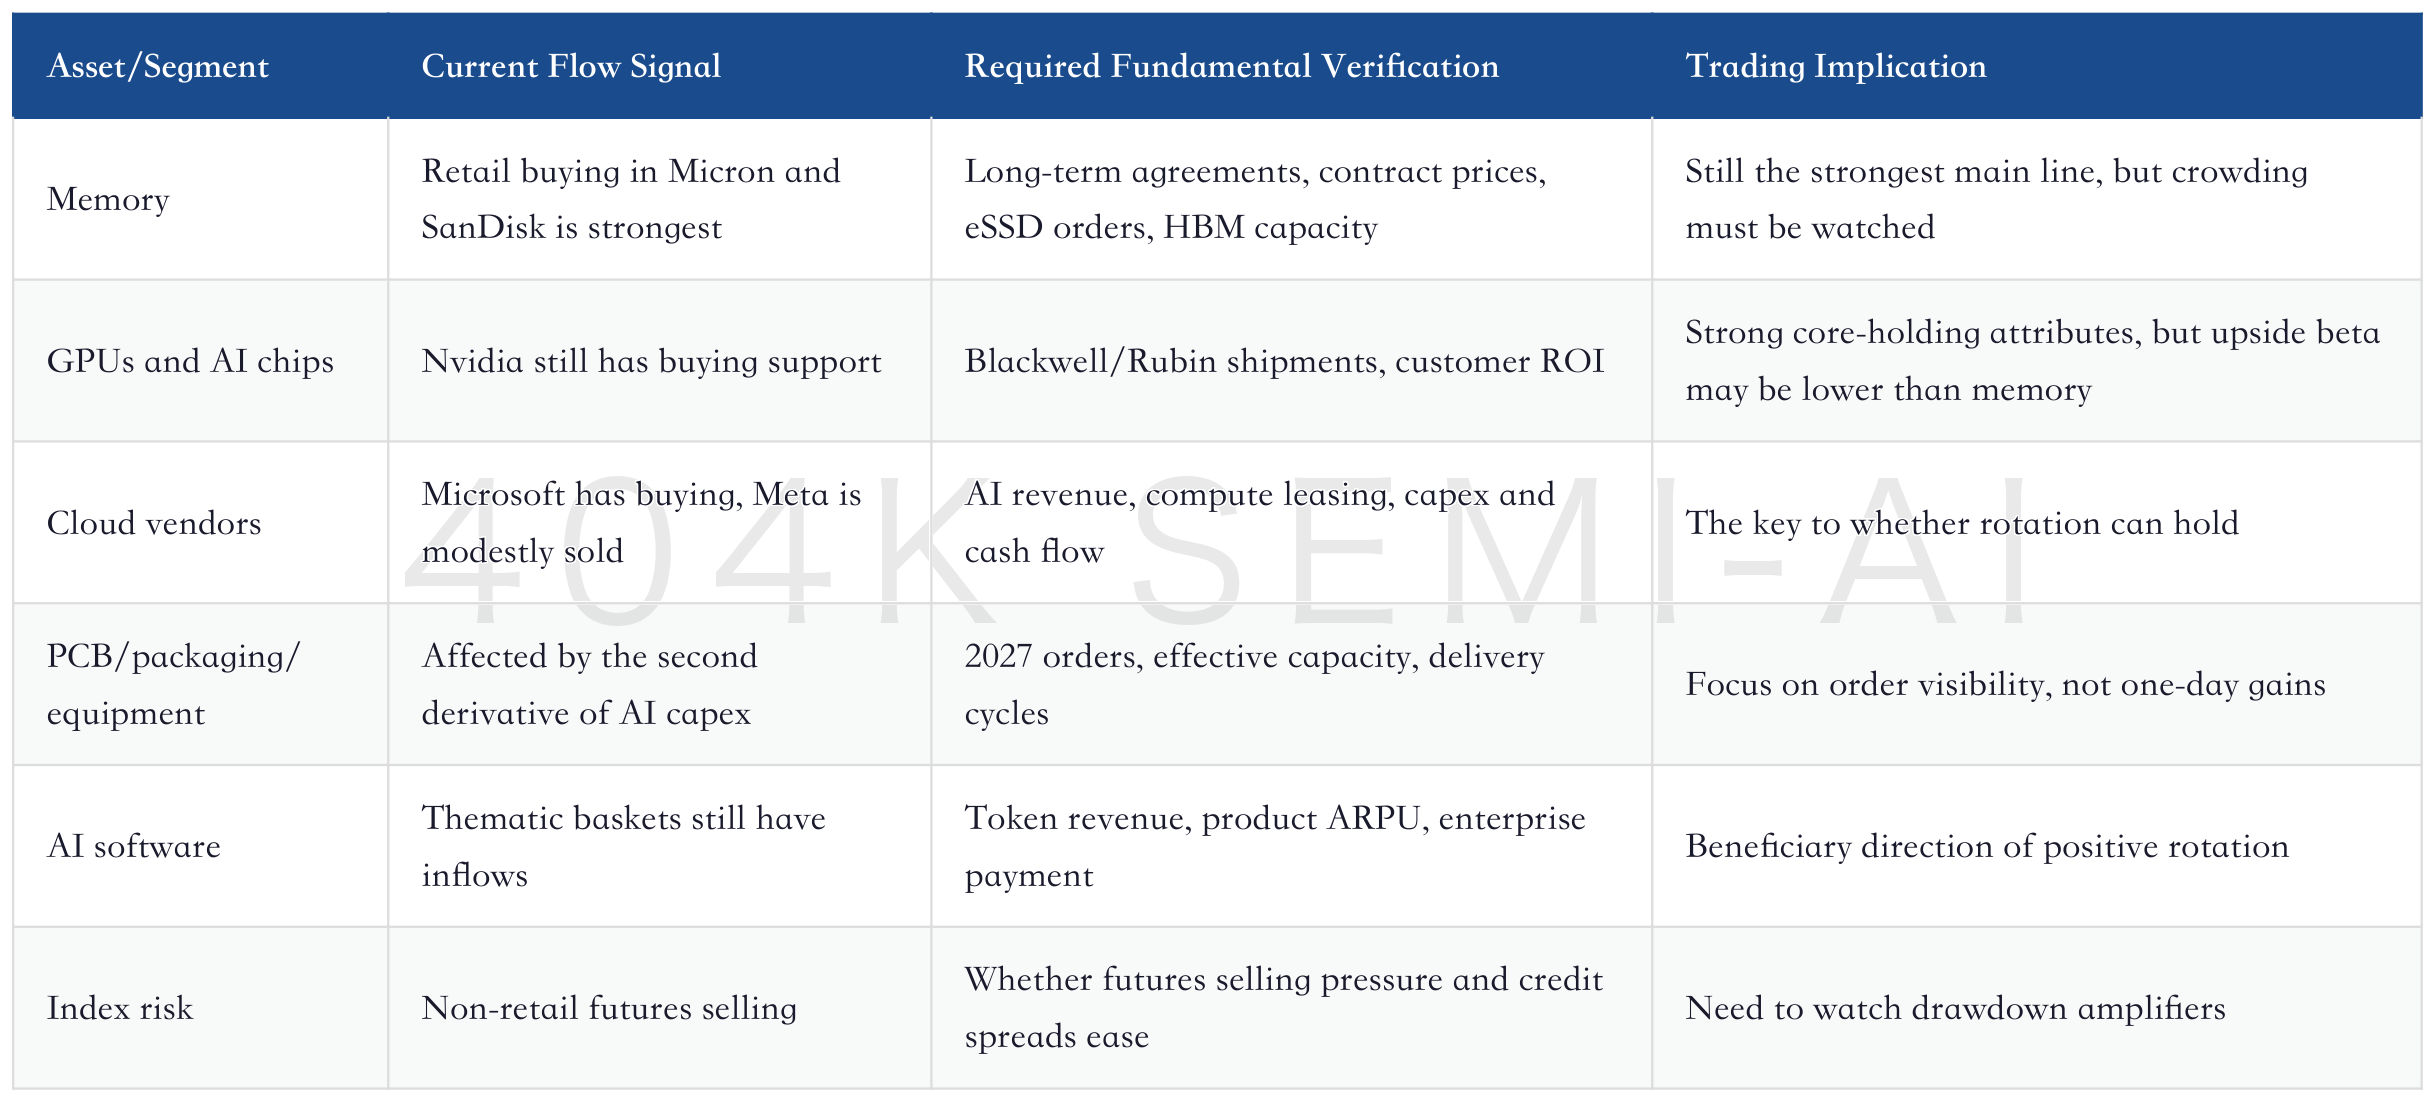
12. Breaking Down Flows: This AI Trade Has Three Types of Money
This round of the AI trade cannot be judged only by index moves. Flows need to be divided into three types of money: first, long-term fundamental capital, which is buying the multi-year slope of AI capex; second, retail and thematic capital, which is buying high beta after pullbacks; third, institutional hedging capital, which is selling index and portfolio volatility. The three types of money are not fully aligned, so the market can show a mixed state of "single stocks strong, indices fragile, cloud vendors under pressure."
Long-term fundamental capital cares most about whether capex can be sustained after 2027. As long as hyperscalers continue to revise up budgets for data centers, GPUs, networking, storage, and power, the semiconductor chain has valuation support. The core issue here is not whether this year's orders are sufficient, but whether 2027 orders can persist. Hardware valuations have been pulled forward this year, and from here they must continue to be confirmed by order realization and customer ROI.
Retail and thematic capital care more about price action. Retail Radar shows that retail investors are not especially euphoric at the index level, but are very active at the single-stock level. This means they are buying "winners within the theme," not the entire market. Names such as Micron, SanDisk, Nvidia, and Microsoft have both AI narratives and near-term catalysts; when they pull back, retail investors are more willing to treat the weakness as a buying opportunity.
Institutional hedging capital focuses on portfolio risk. Non-retail futures selling indicates institutions have not fully followed retail into chasing highs, and have at least managed risk at the index level. This behavior is important: if AI hardware fundamentals continue to materialize, futures shorts will become buyback fuel; if fundamentals start to turn, institutional futures selling pressure will first amplify index risk and then transmit to high-beta single stocks.
The interaction among these three types of money determines the shape of the AI trade. Long-term capital determines the trend, retail capital determines beta, and institutional hedging determines drawdown depth. Only if long-term capital keeps revising up capex, retail buying is not concentrated in just a few stocks, and institutional hedging pressure declines will the AI trade enter healthy rotation. If any one of these links is missing, the market will look strong but unstable.
This is also the value of reading JPM's two reports together. Flows & Liquidity answers questions about long-term capital and institutional concerns, while Retail Radar answers questions about retail buying and thematic broadening. Reading only the former can easily lead to the conclusion that "semiconductors are crowded"; reading only the latter can easily lead to the conclusion that "retail continues to chase AI." Taken together, the market is moving from one-way optimism into structural redistribution.
XIII. Cloud Providers Are the Balance Sheet of This Trade, Not Just the Customers
Semiconductor investors have historically treated cloud providers as a source of demand: they buy GPUs, HBM, networking equipment, and servers, and their orders flow to upstream companies. But JPMorgan is putting cloud providers on the balance sheet side this time: they are not just customers, but also the financing entities and profit-allocation centers for AI capex.
This perspective matters. If cloud-provider share prices are stable, credit spreads are narrowing, and free cash flow is not being crushed by capex, supply-chain price increases will be understood as a normal cost of AI infrastructure expansion. Conversely, if cloud-provider stocks move sideways, debt costs rise, and the market starts questioning capex returns, supply-chain price increases will be interpreted as pressure on customer cash flow.
This is also why compute pricing must sit at the center of the framework. The hardware chain cares most about shipments; cloud providers care most about how much they can charge per unit of compute. If H100/H200 rental prices stabilize, cloud providers can justify capex through higher utilization and better pricing. If rental prices keep falling, even continued hardware purchases will prompt the market to ask harder questions about investment returns.
The same applies to model token pricing. How much model companies and application companies are willing to pay for inference and training determines whether cloud providers can pass AI compute through to end customers. If model token revenue rises, cloud-provider capex will again be viewed as monetizable assets. If token price competition intensifies, cloud providers will be forced to balance pricing, utilization, and capital spending.
For the semiconductor chain, the valuation condition of cloud providers is the quality of the order book. Orders from customers with strong cash flow, recovering share prices, and falling financing costs carry completely different valuation implications from orders from customers under share-price pressure, facing wider credit spreads, and forced to prove returns. The former supports long-term supply-chain profits; the latter only supports near-term shipments.
So the next step is not merely to watch whether cloud providers place orders. More important is to watch their equity and credit performance, the wording of capex guidance, management disclosure of AI revenue, rental prices, and utilization of self-owned compute. If these indicators improve, the positive rotation described by JPMorgan can happen. If they deteriorate, the expected 2027 capex slowdown will move from consensus spreadsheet assumption to tradeable risk.
XIV. Why Memory Assets Are Easier to Re-rate Than Ordinary Semiconductors
Memory has been the strongest segment in this round of fund flows not simply because prices are rising. Price increases are the language of cyclical stocks; long-term agreements and customer volume lock-ins are the language of re-rating. Retail investors buying Micron and SanDisk are effectively buying two things: first, AI servers have turned memory and storage into bottlenecks; second, long-term agreements have improved earnings visibility.
The DRAM story is that high-end capacity is being structurally absorbed by AI. HBM, DDR5, server memory, and high-capacity modules are all consuming wafer and packaging/test resources, making it harder for traditional consumer electronics customers to pressure pricing the way they did in the past. As long as AI customers are willing to lock in volume in advance, DRAM companies can convert what used to be cyclical profits into more stable contract profits.
The NAND story is that data-center capacity demand is redefining “oversupply.” In the traditional NAND cycle, weak consumer electronics demand would directly pressure prices. But if demand for enterprise SSDs, AI data lakes, training datasets, inference cache, and long-term storage keeps growing, NAND is no longer just a smartphone and PC inventory cycle. Concentrated retail buying of SanDisk reflects the fact that this narrative is now entering fund flows.
eSSD is the most important scenario for NAND re-rating. Data-center customers care not only about unit cost, but also capacity, power consumption, reliability, and supply stability. If eSSD orders continue to improve, NAND manufacturers’ margin elasticity will be better than in traditional consumer SSDs, and the market will assign higher cash-flow visibility.
The risks in memory stocks are also more obvious. Their volatility is naturally high, and retail buying plus active options trading can amplify moves in both directions. Once spot prices, contract prices, or long-term agreement data come in below expectations, share-price pullbacks can be rapid. Memory is not a low-risk asset. It is simply the asset within this AI hardware cycle where fundamental elasticity is easiest for fund flows to see.
The real risk is the market buying all memory stocks under the same logic. HBM, DDR5, eSSD, traditional NAND, consumer modules, and controller companies have different profit elasticity, different customer structures, and different speeds of price transmission. If capital continues to pour into memory, investors need to distinguish between “supply-bottleneck assets” and “sympathy-rally assets.”
XV. Semiconductor Equipment, PCB, and Packaging Are Leading Indicators for 2027 Capex
To verify whether 2027 capex will be revised down, the first place to look is not final chip shipments, but equipment, PCB, and advanced-packaging orders. These segments have long delivery cycles, and customers usually send order signals earlier. As long as their orders and capacity plans remain intact, AI infrastructure expansion has not truly slowed.
Semiconductor equipment is the most direct capex proxy. WFE, etch, deposition, metrology, cleaning, advanced-packaging equipment, and HBM-related tools will all reflect customers’ capacity assumptions for 2027 and 2028 in advance. If equipment stocks continue to see upward revisions, it means cloud providers and chipmakers are not treating 2027 as a year of significant deceleration.
