
JCET Deep-Dive Update: Goldman Sachs Raises Target Price to RMB125; How AI Chip OSAT Investment Flows Through R&D; Expense and 2030E Discounted Valuation
目录
Too Long; Didn’t Read
I. What Goldman Sachs Actually Changed This Time: Target Price Doubled, Rating Not Upgraded
II. JCET’s New Asset Attribute: From OSAT Leader to AI Packaging and Testing Delivery Gateway
III. The Base Case from Official Financials: Revenue Is Not Perfect, but the Mix Has Already Shifted
IV. The Handset Cycle Is Not the Answer; AI and Memory Are the Main Line
V. The Domestic Compute Closed Loop: JCET Sits at the “Last Mile of Delivery”
VI. J.P. Morgan’s Bull-Case Model: The Key Is Not the Target Price, but the Profit Bridge
VII. Technology Ticket: How Advanced Packaging Turns into Profit
VIII. JCET Microelectronics: The Variable with the Greatest Valuation Elasticity
IX. STATS, SanDisk Semiconductor, and Automotive Electronics: Not the Main Narrative, but They Determine Profit Depth
X. Competitive Landscape: Platform Breadth Is an Advantage, Profit Elasticity Is the Constraint
XI. Valuation Divergence: Three Worldviews Determine Three Prices
XII. How to Use Sell-Side Divergence: Do Not Simply Take the Most Optimistic Model
XIII. Scenario Analysis: 2027 Is the Real Stress-Test Year
XIV. Risks: The Most Dangerous Outcome Is “Revenue Arrives, Profit Does Not”
XV. What to Watch Most Closely Over the Next Four Quarters
XVI. Conclusion: JCET Has Secured the Ticket; the Profit Answer Sheet Is Not Yet Complete
References
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Goldman Sachs raised its target price for JCET to RMB125 while maintaining a Neutral rating. The core change is not a turn bullish, but a shift in valuation anchor from near-term P/E to discounted 2030E P/E. JCET has entered a re-rating phase as an AI chip OSAT, but whether R&D; expense, depreciation, and high-end capacity ramp can convert into gross margin and cash flow is the decisive issue over the next 12-18 months.
Too Long; Didn’t Read
What Goldman really raised is valuation duration. The new model shifts JCET from a near-term earnings trade to long-duration platform pricing, lifting the target price to RMB125. The rating remains Neutral, indicating the market still needs evidence on expense, depreciation, and gross margin delivery; if advanced packaging gross margin does not rise, this duration will be compressed again.
R&D; expense weighing on profit does not mean the investment is ineffective. Goldman attributes profit pressure over the next two years to AI chip OSAT R&D; and yield investment. The key metric is not revenue growth, but whether advanced packaging can lift gross margin; if high-end capacity only brings depreciation, valuation will revert to the traditional OSAT framework.
The financials already show structural upgrading. 2025 revenue was RMB38.871bn, and 2026Q1 attributable net profit rose 42.74% YoY. This shows product mix improvement is beginning to flow into the income statement, but continuity depends on subsequent quarters.
JCET Microelectronics offers the largest upside. This high-end advanced packaging asset is still moving from customer introduction to ramp-up, with revenue just above RMB0.2bn and still loss-making. If revenue scales while losses narrow, the platform re-rating will be more robust; if investment appears without gross-margin improvement, the market will revert to a heavy-asset OSAT discount.
Sell-side divergence reflects three worldviews. Goldman assigns a long-term valuation but maintains Neutral, J.P. Morgan emphasizes earnings acceleration, and UBS emphasizes localization and overseas business. They are not simply more or less optimistic; they are pricing JCET across different time horizons.
Watch four numbers over the next four quarters. JCET Microelectronics P&L;, advanced packaging gross margin, capex-backed orders, and operating cash-flow quality are the hard evidence for whether JCET can upgrade into an AI advanced packaging platform. Looking only at target prices and themes risks missing the real financial verification points.
I. What Goldman Sachs Actually Changed This Time: Target Price Doubled, Rating Not Upgraded
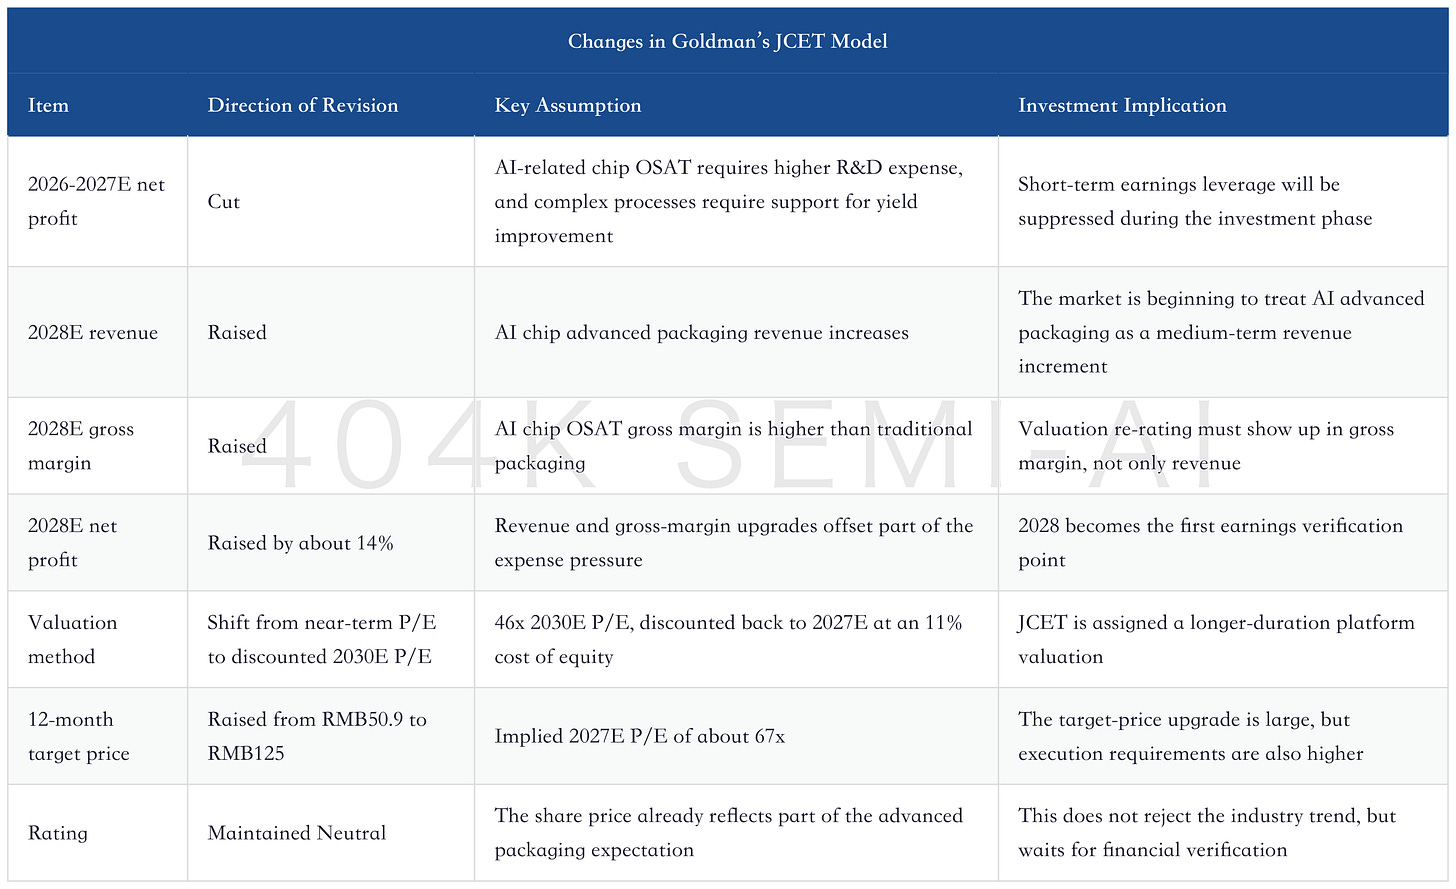
The most interesting part of Goldman’s update is the tension between target price and rating. The target price was raised sharply from RMB50.9 to RMB125, but the rating remains Neutral. This is not simply “bullish but unwilling to say so”; rather, after extending JCET’s valuation duration, Goldman is still restrained on near-term earnings delivery.
JCET Deep Dive: From Cyclical OSAT to AI Advanced Packaging Gateway; How Chiplet, XDFOI, and Domestic Compute Re-rate the OSAT Leader
This is connected to the judgment in the previous deep dive on JCET. JCET should no longer be viewed only as a handset OSAT cycle stock, but it has not yet fully secured the stable valuation of an advanced packaging platform. Goldman’s new model states this intermediate condition more clearly: 2026-2027E profit pressure comes from higher R&D; expense, 2028E profit upgrades come from AI chip advanced packaging revenue and gross-margin improvement, and the valuation method directly shifts to discounted 2030E P/E.
JCET Deep-Dive Update: AI Cycle, Localization, and OSAT Asset Re-rating
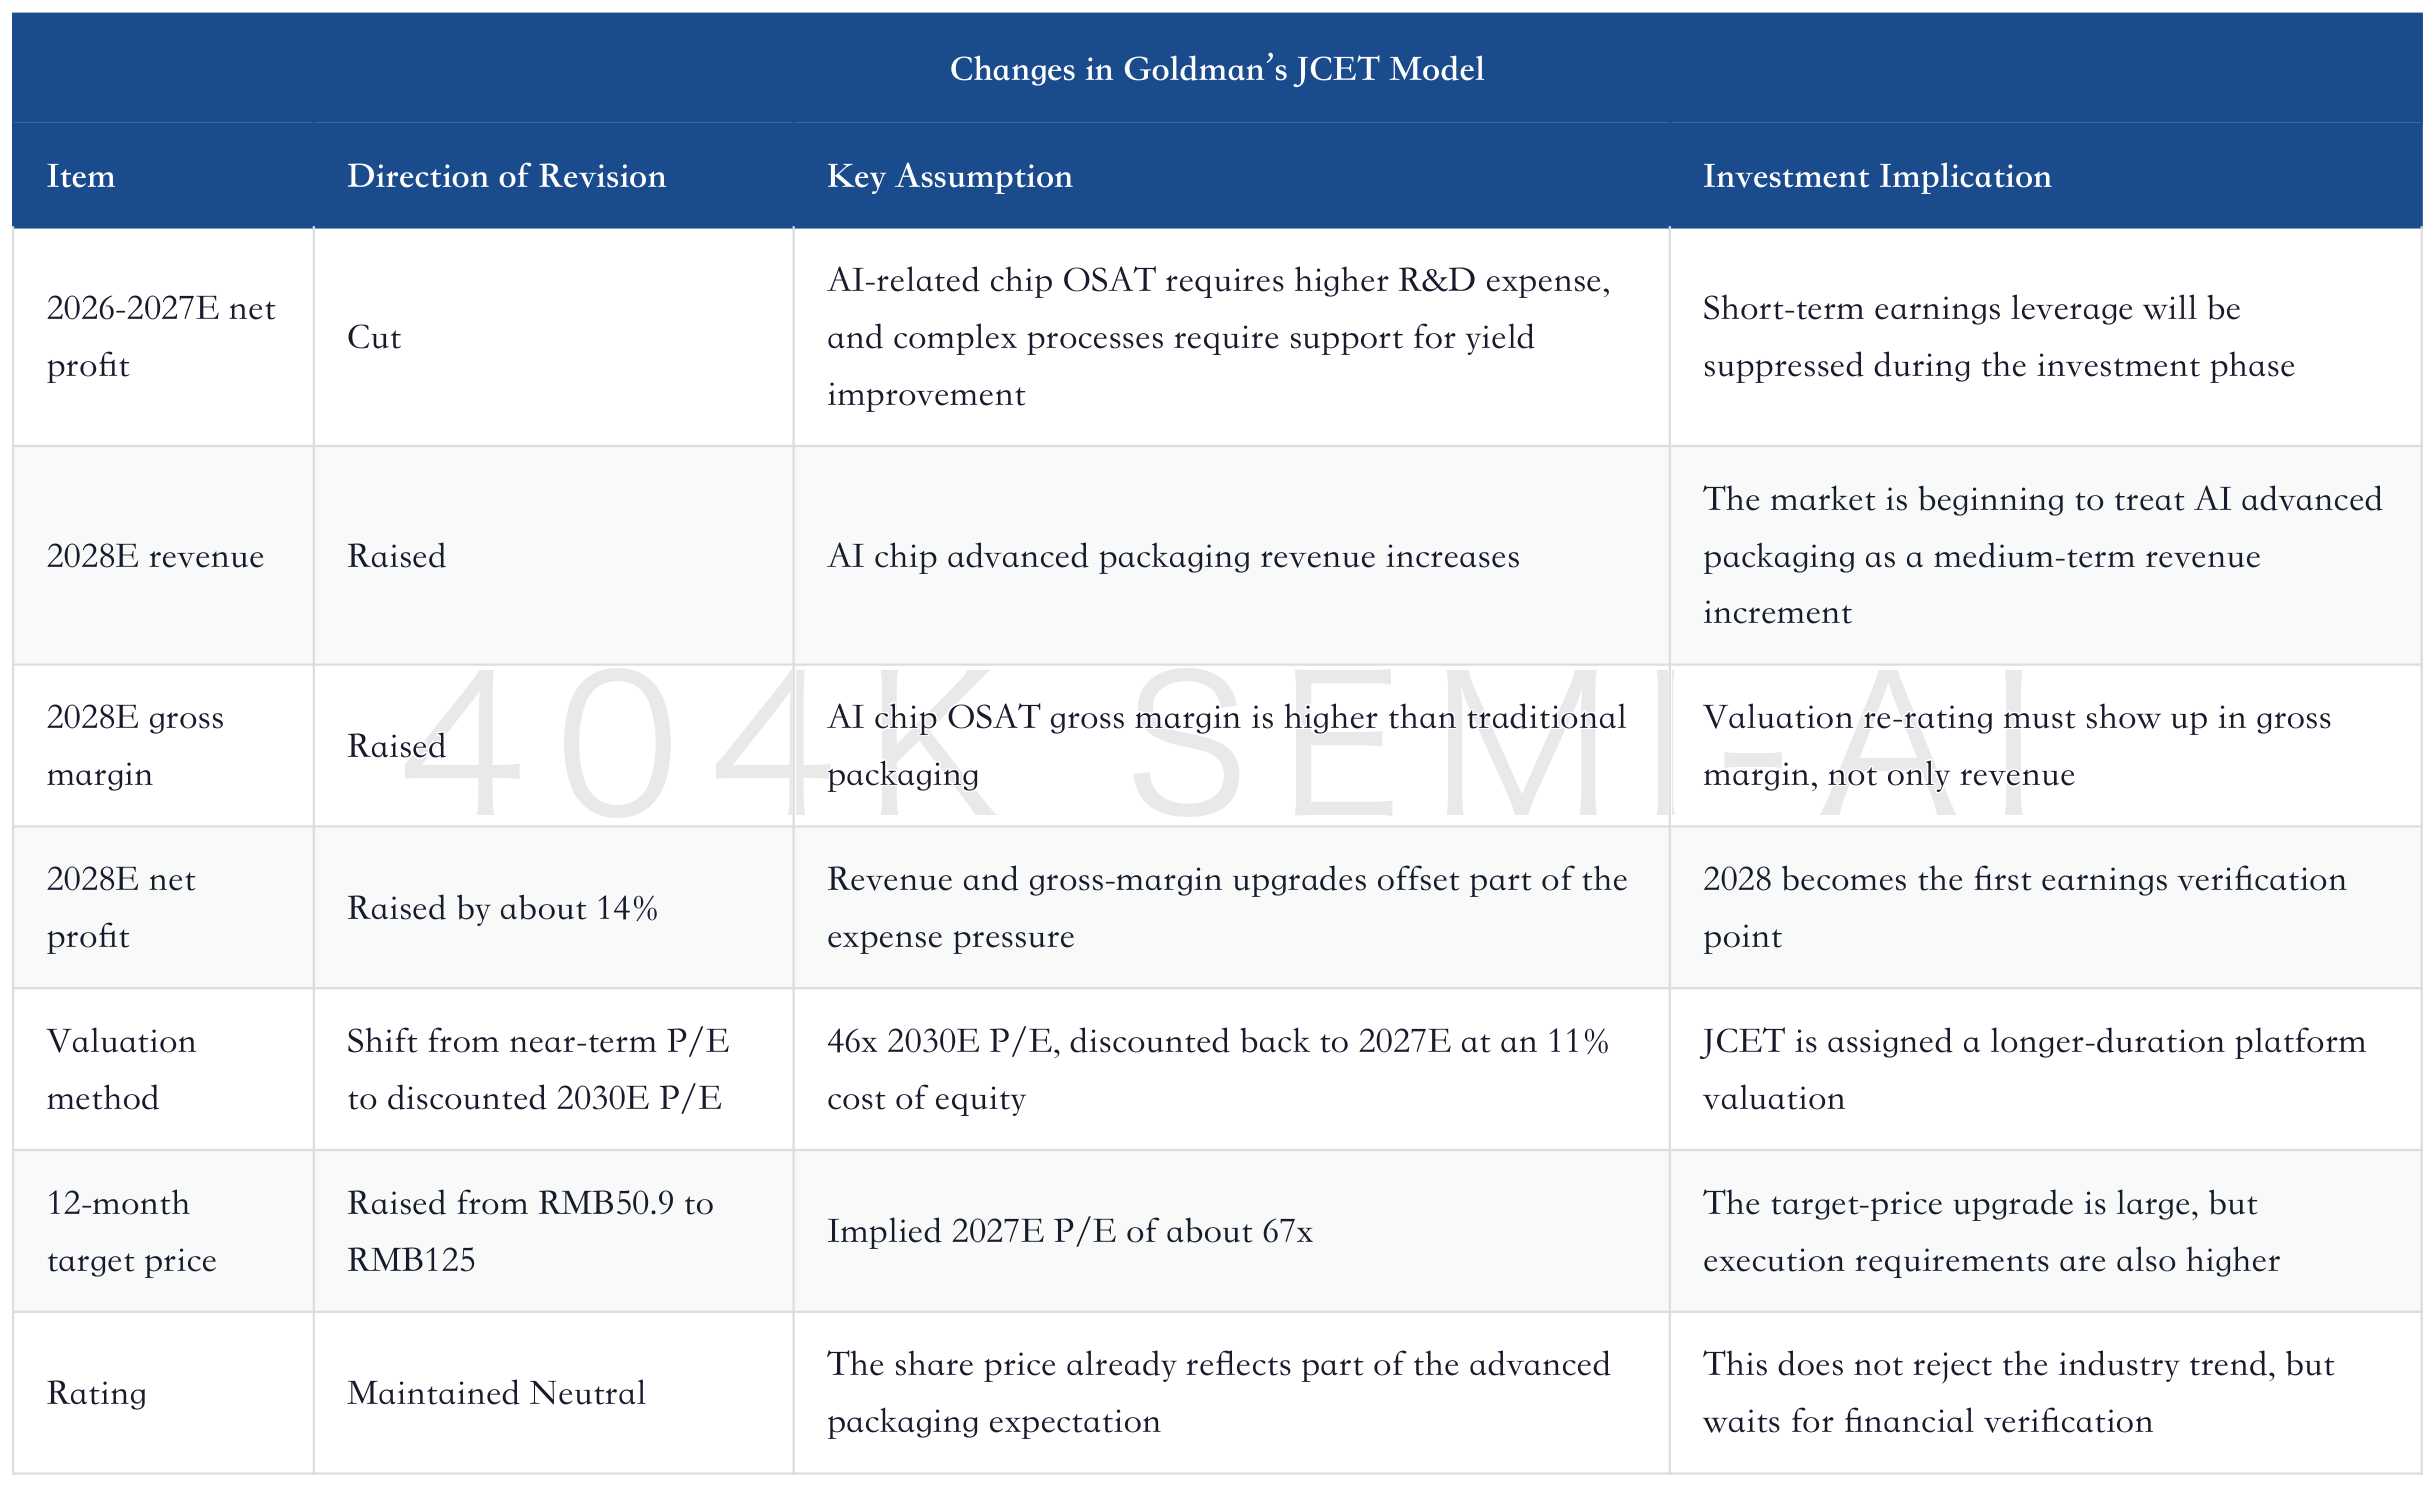
The signal from this table is direct: Goldman has not denied the asset re-rating brought by AI advanced packaging, and has even acknowledged longer duration through discounted 2030E P/E. But it also puts near-term profit pressure upfront, reminding the market that advanced packaging is not an asset-light story. It is a heavy-asset platform jointly determined by R&D;, equipment, materials, yield, customer qualification, and capacity utilization.
This is also JCET’s most realistic current contradiction. Looking only at the RMB125 target price can make it seem Goldman has suddenly turned fully bullish; looking only at the Neutral rating can lead to the mistaken view that Goldman lacks confidence in JCET. A more accurate reading is that Goldman recognizes JCET has entered the core beneficiary chain of AI chip OSAT and domestic semiconductor capacity expansion, but believes this chain must pass through expense and depreciation before becoming a stable high-margin asset.
On valuation, Goldman’s 46x discounted 2030E P/E cannot be directly compared with traditional OSAT P/E. It assumes 2031E net profit growth, operating margin approaching 10%, and a higher share of AI advanced packaging revenue, then applies platform pricing to 2030 profit and discounts it back to 2027. The benefit of this method is that it recognizes the long-term value of an advanced packaging platform. The drawback is also clear: the model is highly sensitive to long-term revenue, gross margin, and expense ratio. Any deviation in one variable can materially change the discounted target price.
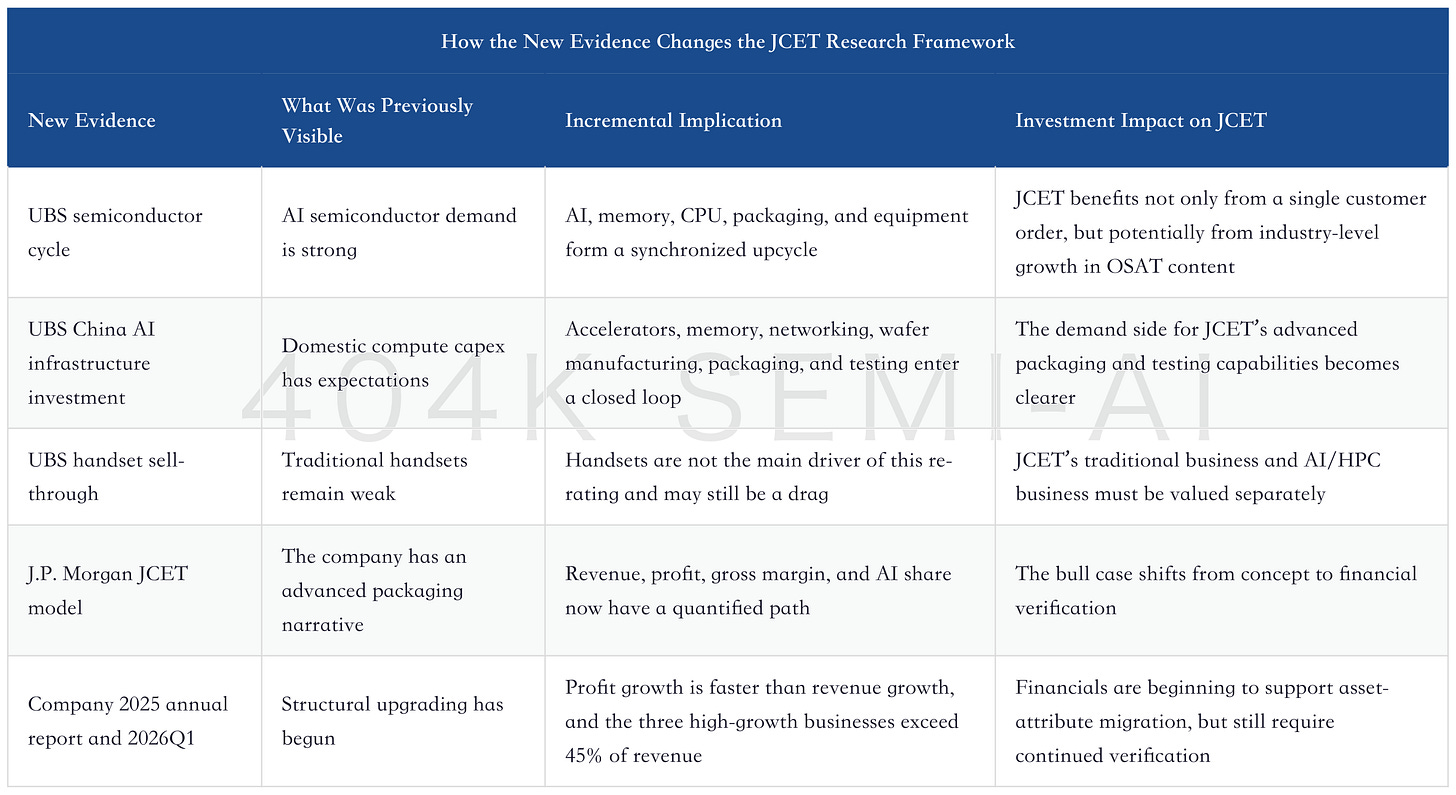
The previous judgment on JCET had already moved the question from “OSAT industry cycle” to “advanced packaging delivery gateway.” The incremental value of this material is not another repetition of XDFOI, Chiplet, or 2.5D, but the connection of four external pieces of evidence: Goldman’s valuation-method shift, J.P. Morgan’s profit bridge, UBS’s localization and overseas-business framework, and the application-mix improvement already visible in the company’s official financials.
The first piece of evidence comes from aggregate semiconductor demand. In its June semiconductor cycle report, UBS shifted the growth focus of global semiconductor revenue from traditional endpoints to AI cloud, memory, and server CPUs, and emphasized that AI cloud-related chips will continue to rise as a share of total semiconductor revenue. The implication of this framework is that AI is no longer just a GPU line; it is pulling HBM, DRAM, NAND, CPU, packaging, testing, and equipment into a new capacity-expansion cycle together.
The second piece of evidence comes from expectations for China’s AI infrastructure investment. UBS’s June First Read on China semiconductors noted the market’s focus on a roughly RMB2tn five-year AI buildout plan. On an annualized basis of about RMB400bn, GPUs/AI accelerators, networking, and storage would constitute the main hardware spending. In UBS’s estimate, if 50% is allocated to GPUs/AI accelerators and 20% to networking and storage, the revenue elasticity would be substantial for major domestic AI accelerator companies and related semiconductor manufacturing chains. JCET is placed within the advanced packaging and testing beneficiary chain, showing that its re-rating is not only about the company’s own capacity expansion, but also connected to the closed-loop mass production of domestic AI chips.
The third piece of evidence comes from J.P. Morgan’s model for JCET itself. Its June 16 company report upgraded JCET from Neutral to Overweight, with the core rationale that AI-related revenue, capex efficiency, and high-end capacity utilization may improve together. The report quantifies the path for revenue, earnings, AI-related revenue share, and gross margin, with specific figures shown later in the model table. The value of this model is not a static target price, but the way it decomposes JCET’s earnings verification path over the next two years.
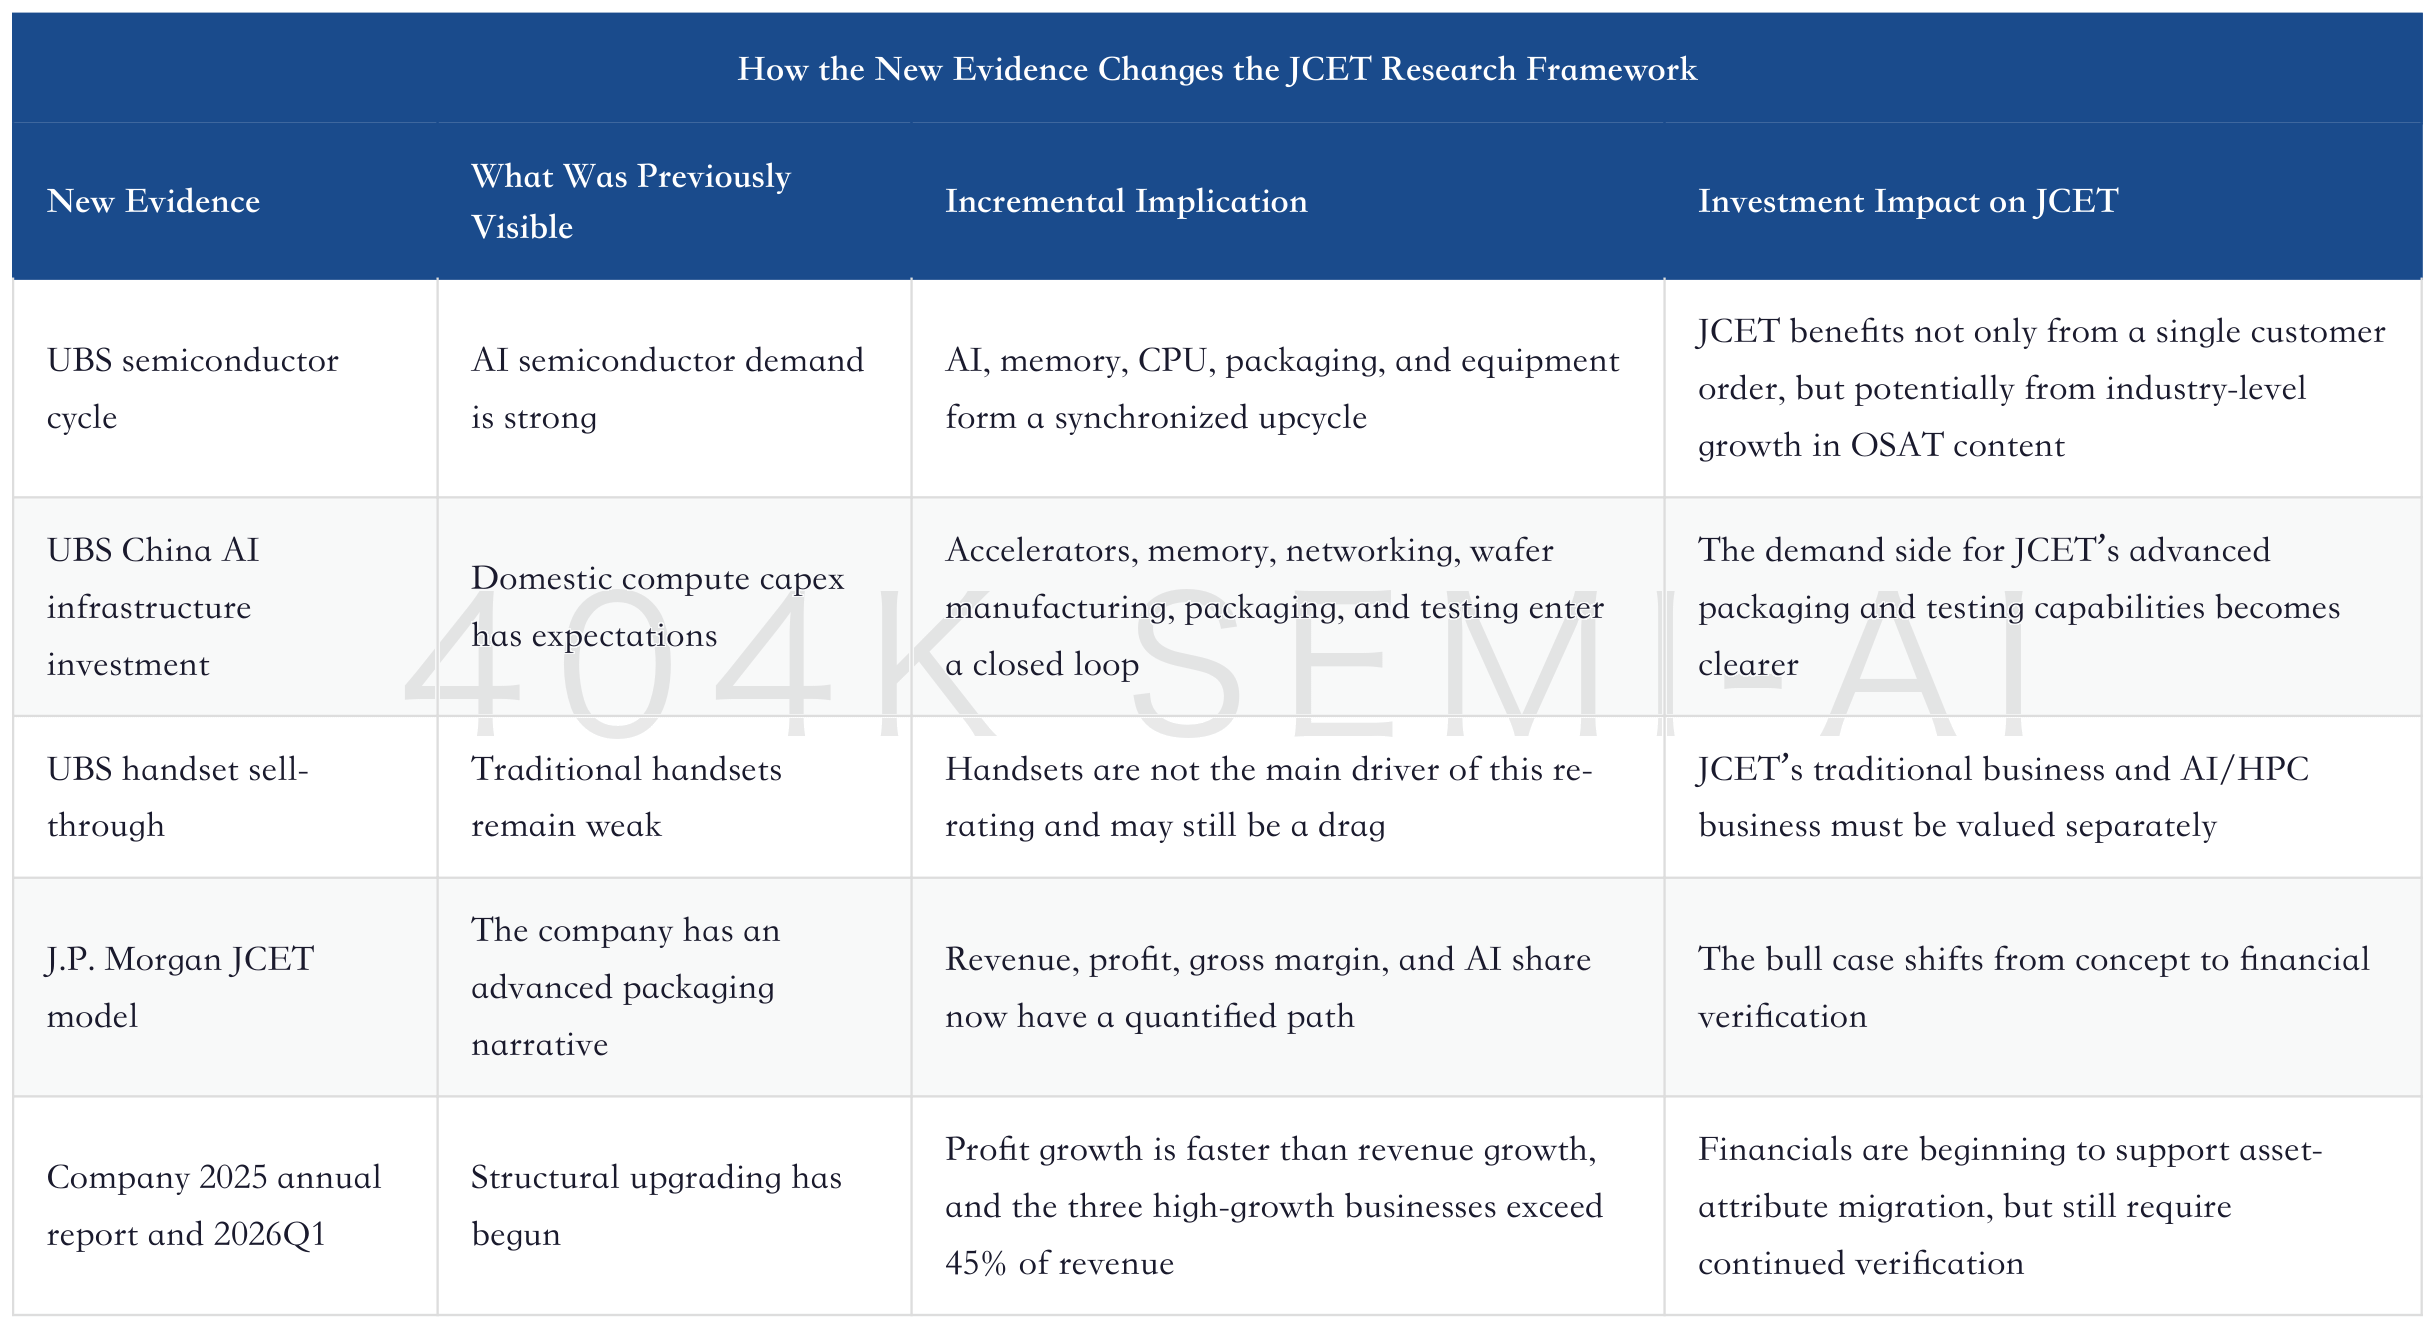
The direction from this table is direct: JCET’s investment question is no longer “whether there is an AI packaging story,” but “whether AI packaging can lift margins and ROE.” Looking only at industry space will underestimate the company’s platform value; looking only at target prices and themes will overestimate earnings leverage during the investment phase.
II. JCET’s New Asset Attribute: From OSAT Leader to AI Packaging and Testing Delivery Gateway
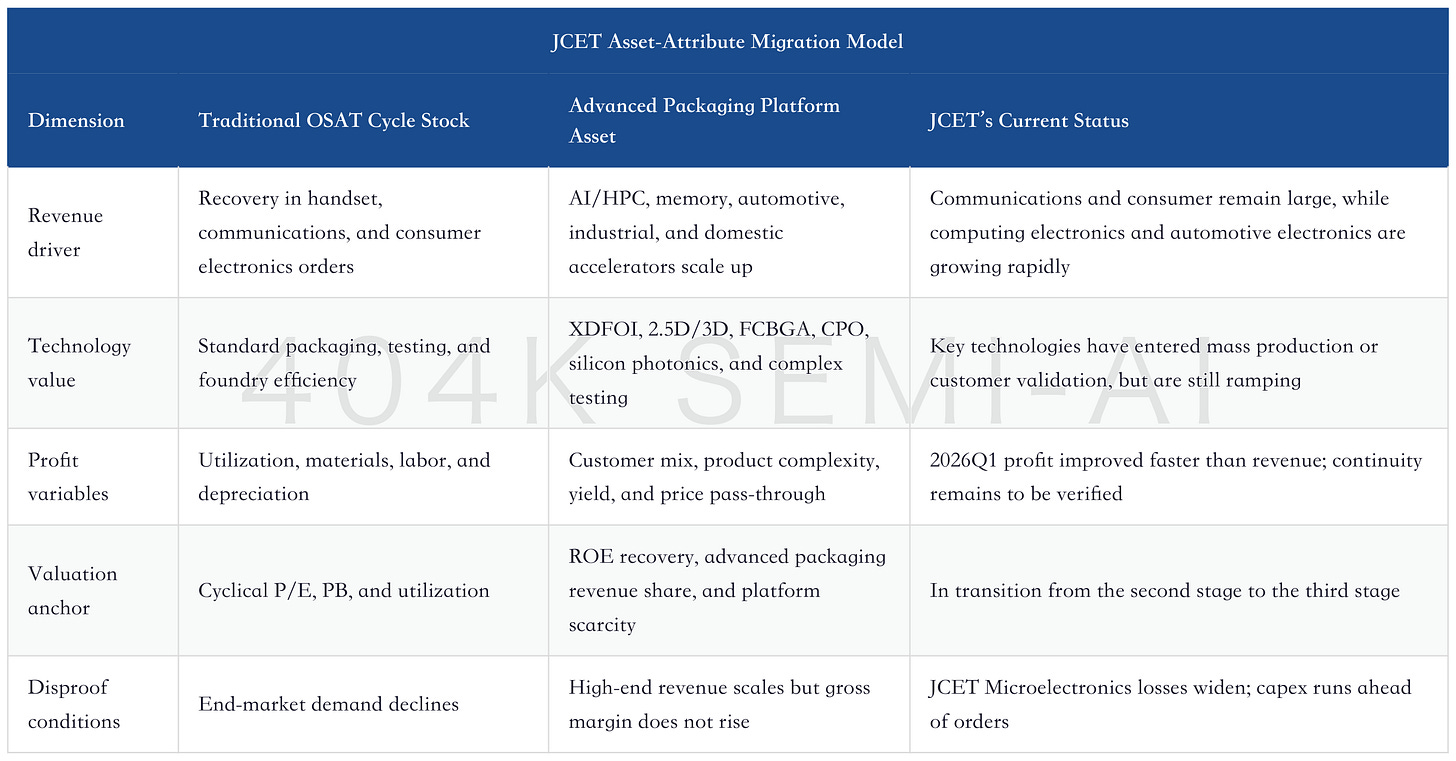
OSAT companies have historically been placed at the back end of the semiconductor value chain, and their valuation logic has also been more cyclical. The reason is practical: OSAT revenue follows customer orders, capacity utilization determines gross margin, equipment depreciation and materials costs determine earnings leverage, and once end markets enter destocking, OSAT companies are the most exposed to order cuts and pricing pressure.
What AI changes is the position of OSAT within the system. High-performance computing chips are no longer a contest of single-die performance, but a coordination of multiple compute dies, HBM, I/O, power delivery, thermal management, substrates, testing, and system yield. Advanced packaging is not simply “wrapping the chip”; it determines bandwidth, power consumption, interconnect length, thermal efficiency, reliability, and delivery time. The higher the compute power, the closer packaging moves to the architecture layer; the more multi-chip heterogeneous integration there is, the closer testing becomes to yield insurance.
JCET deserves to be reassessed because it has four entry points at the same time: first, it is one of the largest OSAT leaders by revenue scale in mainland China; second, STATS ChipPAC brings overseas customers and a global manufacturing footprint; third, XDFOI, 2.5D/3D, FCBGA, CPO, silicon photonics, memory packaging and testing, and testing capabilities form a high-end technology portfolio; fourth, automotive electronics, industrial and medical, and high-performance computing applications are improving the quality of its revenue mix.
This does not mean JCET has already become a TSMC-style advanced packaging platform. TSMC’s CoWoS, SoIC, and wafer-manufacturing coordination provide extremely strong customer stickiness and process-synergy advantages. JCET remains an OSAT company, and it must prove platform value through customer introduction, capacity utilization, yield, gross margin, and cash flow. But it also cannot continue to be viewed as ordinary OSAT capacity, because AI/HPC and domestic compute are turning OSAT from a back-end cost item into a system delivery node.
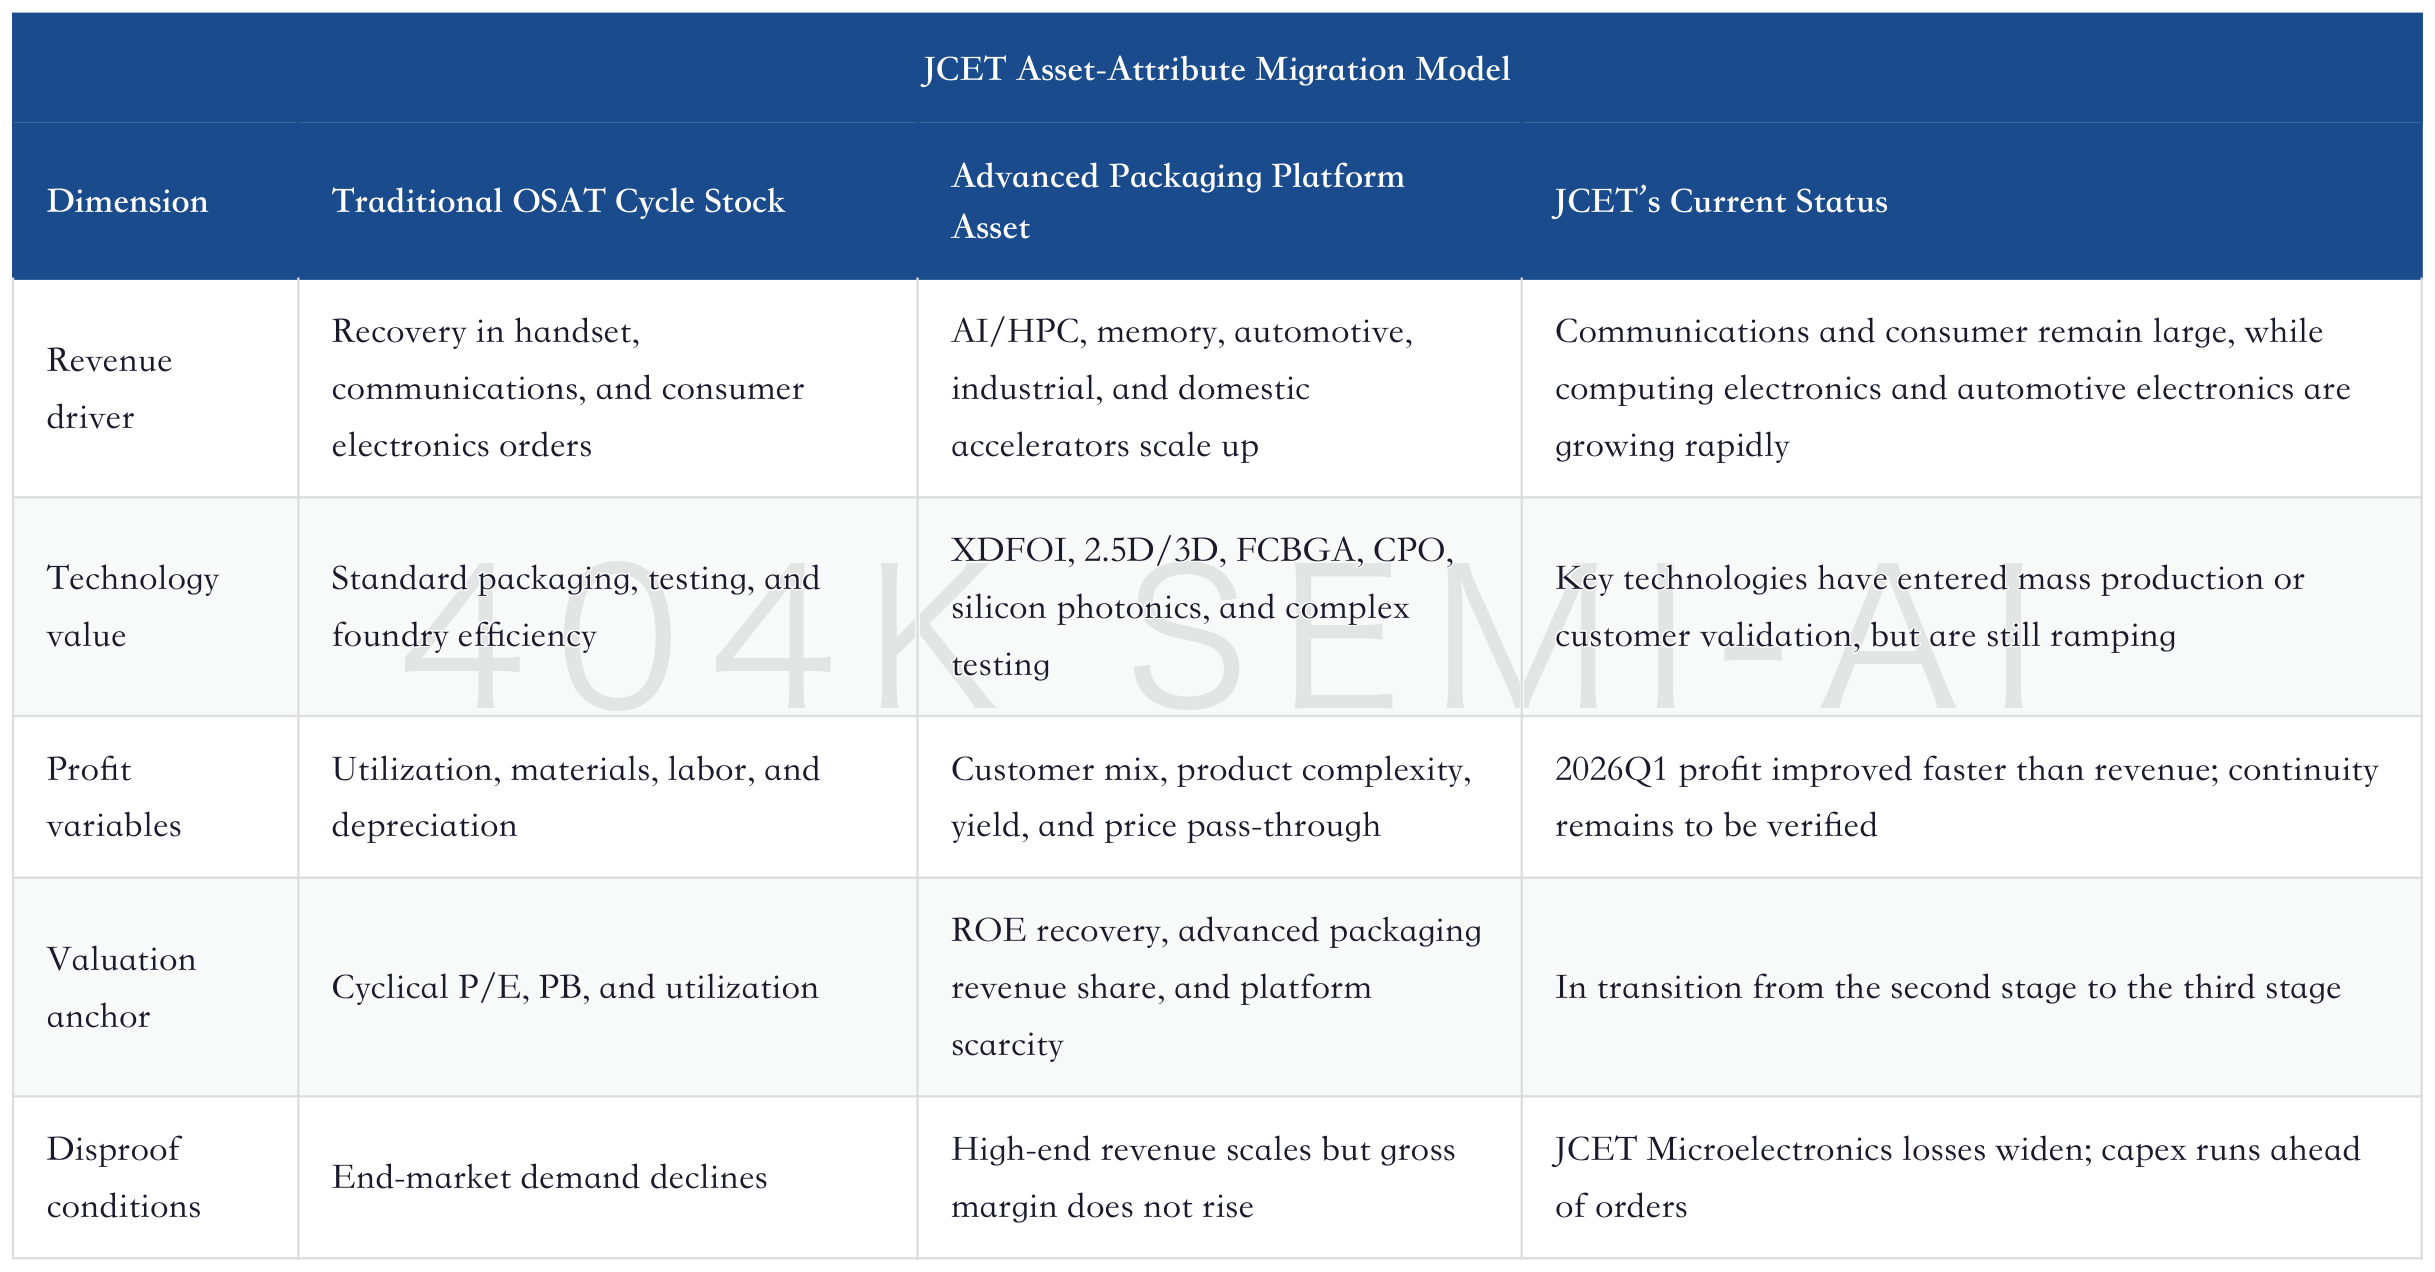
This table also explains why the market is sharply divided on JCET. The conservative camp sees low gross margin, heavy capex, and continued weakness in traditional consumer electronics. The constructive camp sees rising AI-related revenue share, advanced packaging platformization, the domestic compute closed loop, and margin upside. Neither side is entirely wrong. The key is which set of evidence proves stronger over the next few quarters.
III. The Base Case from Official Financials: Revenue Is Not Perfect, but the Mix Has Already Shifted
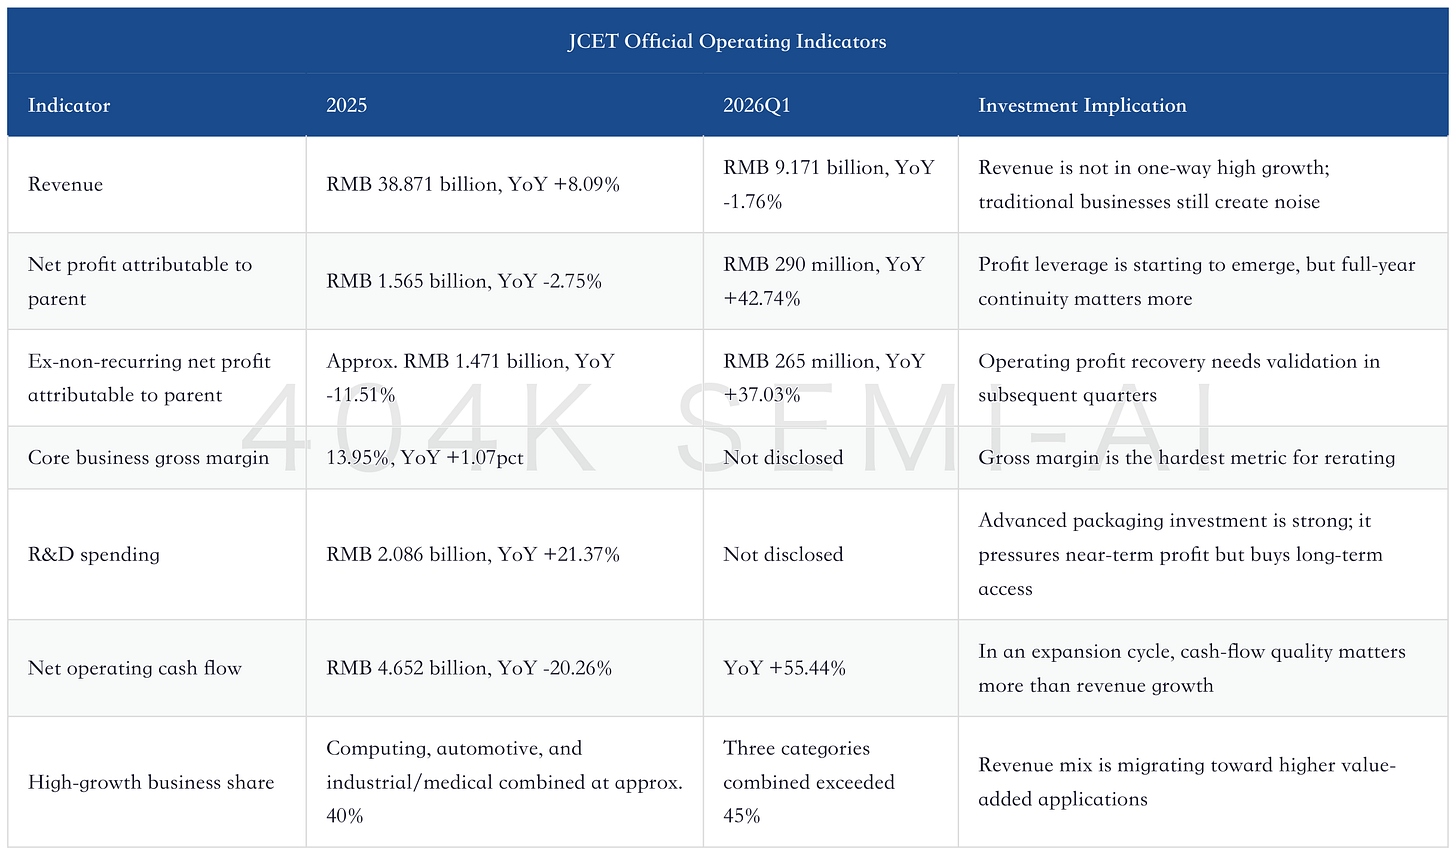
JCET’s 2025 financial performance was not a perfect report card. The company reported revenue of RMB 38.871 billion, up 8.09% YoY; net profit attributable to the parent of RMB 1.565 billion, down 2.75% YoY; core business gross margin of 13.95%, up 1.07 percentage points YoY; and R&D; spending of RMB 2.086 billion, up 21.37% YoY. This shows revenue recovery and margin improvement, but R&D;, depreciation, materials, and new-business ramp-up are still weighing on profit.
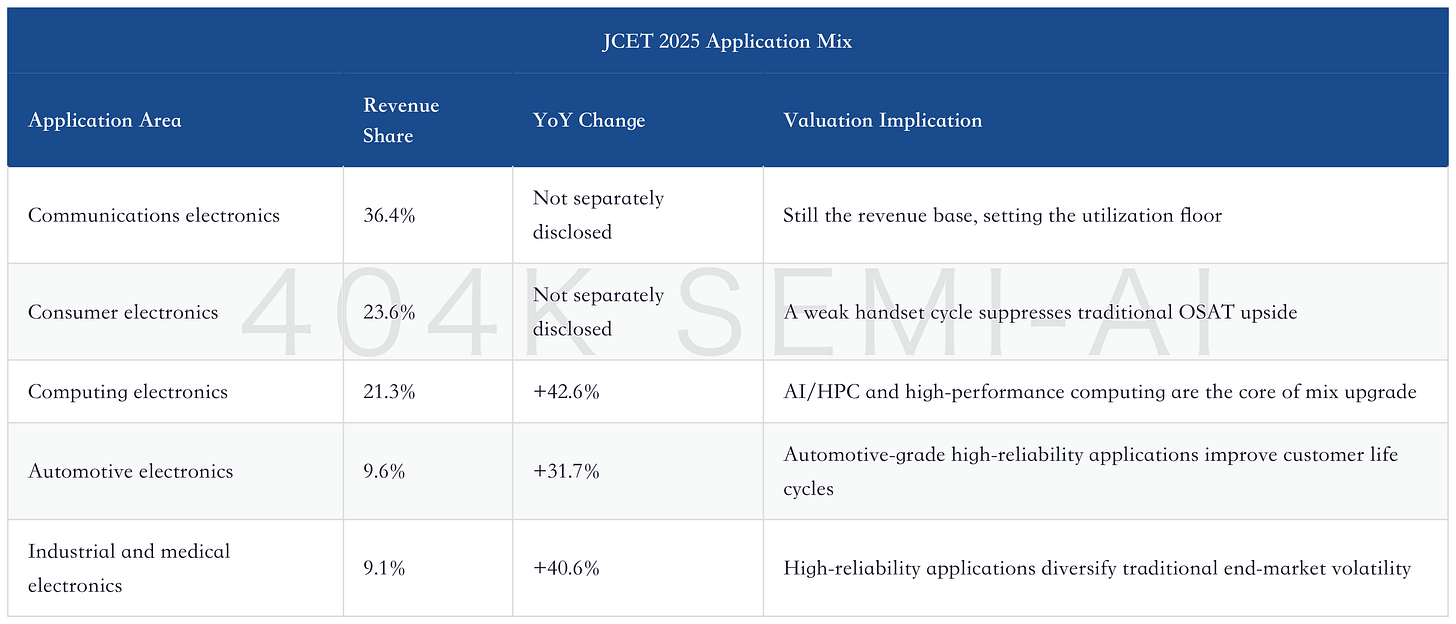
The more valuable signal is the change in mix. Communications and consumer electronics remained JCET’s base in 2025, but the growth slope has shifted to high-performance computing, automotive, and high-reliability applications. The key application-mix figures are better viewed in a table, because they correspond to two very different valuation logics: traditional end markets determine base volatility, while high-growth applications determine the platform premium.
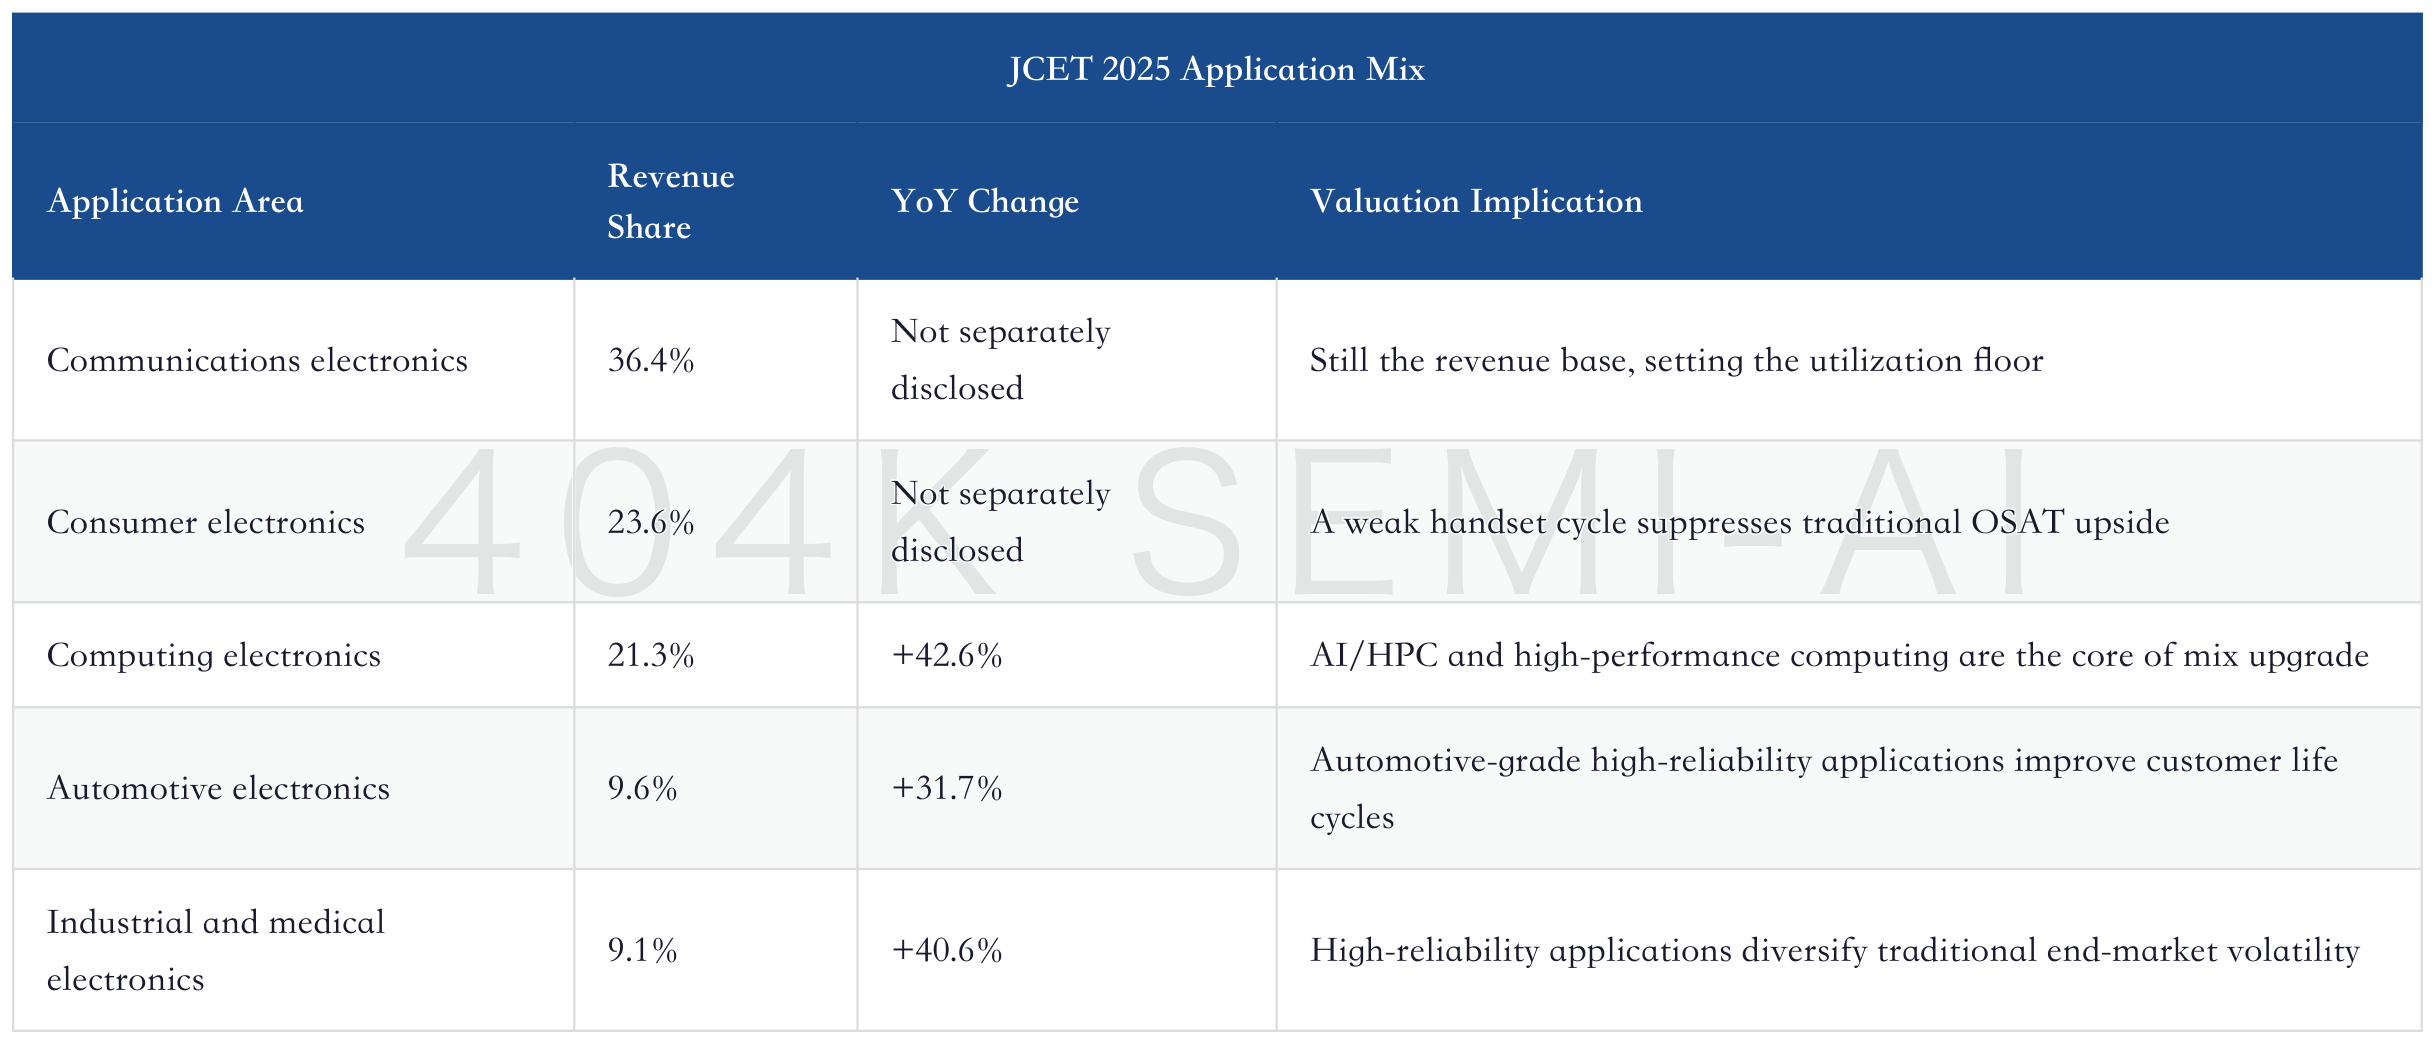
2026Q1 further validated this trajectory. The company reported revenue of RMB 9.171 billion, down 1.76% YoY; net profit attributable to the parent of RMB 290 million, up 42.74% YoY; ex-non-recurring net profit attributable to the parent of RMB 265 million, up 37.03% YoY; and net operating cash flow up 55.44% YoY. More importantly, automotive electronics, computing electronics, and industrial and medical electronics together exceeded 45% of revenue, up 7 percentage points from the same period last year. Slightly lower revenue with materially higher profit indicates that product mix and utilization improvements have started to flow into the income statement.
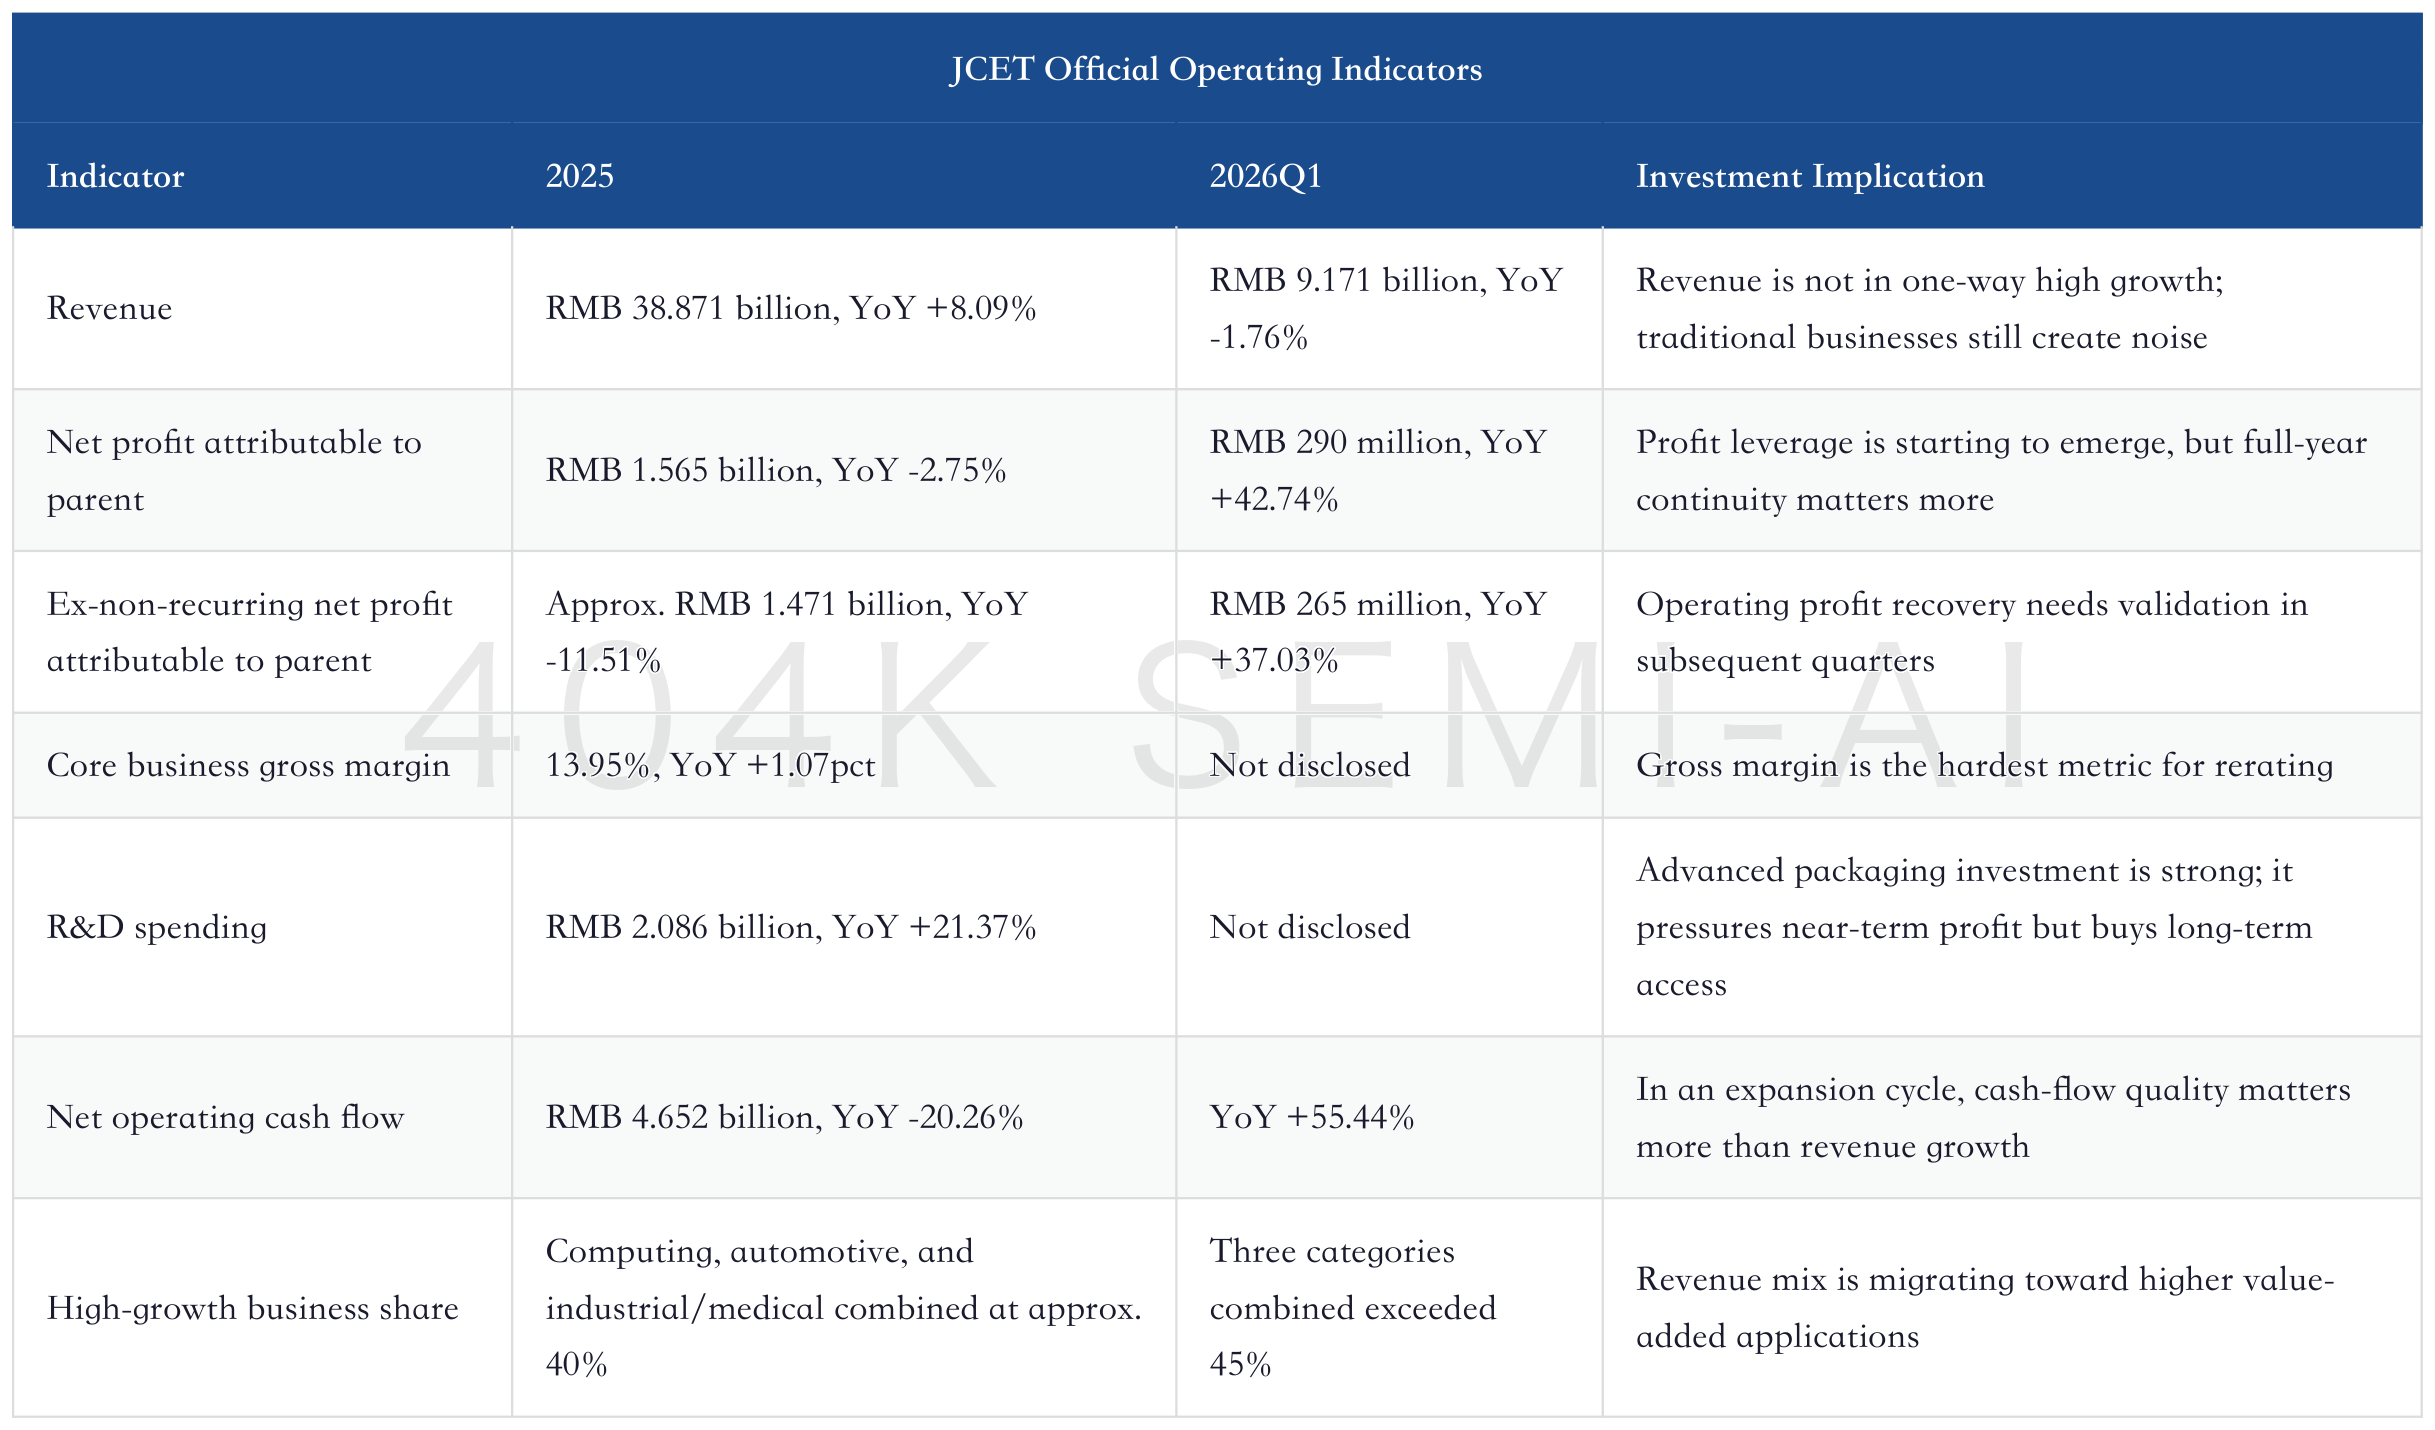
Production and shipment volumes also support this judgment. In 2025, the company sold 18.019 billion advanced-packaging units, up 14.00% YoY; 39.343 billion traditional-packaging units, up 7.80% YoY; and 9.164 billion test units, up 11.25% YoY. Advanced packaging grew faster than traditional packaging, showing the mix upgrade is not just a narrative.
The subsidiary level reveals JCET’s contradiction more clearly. Jiangyin Changdian Advanced Packaging generated 2025 revenue of RMB 2.158 billion and net profit of RMB 585 million. The annual report attributed this to rising customer demand, full orders, higher capacity utilization, and increased value from integrated wafer-level advanced packaging and testing services. Changdian Microelectronics generated revenue of RMB 204 million and a net loss of RMB 192 million, because high-end advanced-packaging products had entered mass production, capacity utilization had begun to ramp, and the company increased R&D; and resource investment for future scaled mass production. Changdian Automotive Electronics was still in the preparation phase in 2025 and generated losses, but its line was formally commissioned at year-end, and product mass-production introductions will accelerate in 2026.
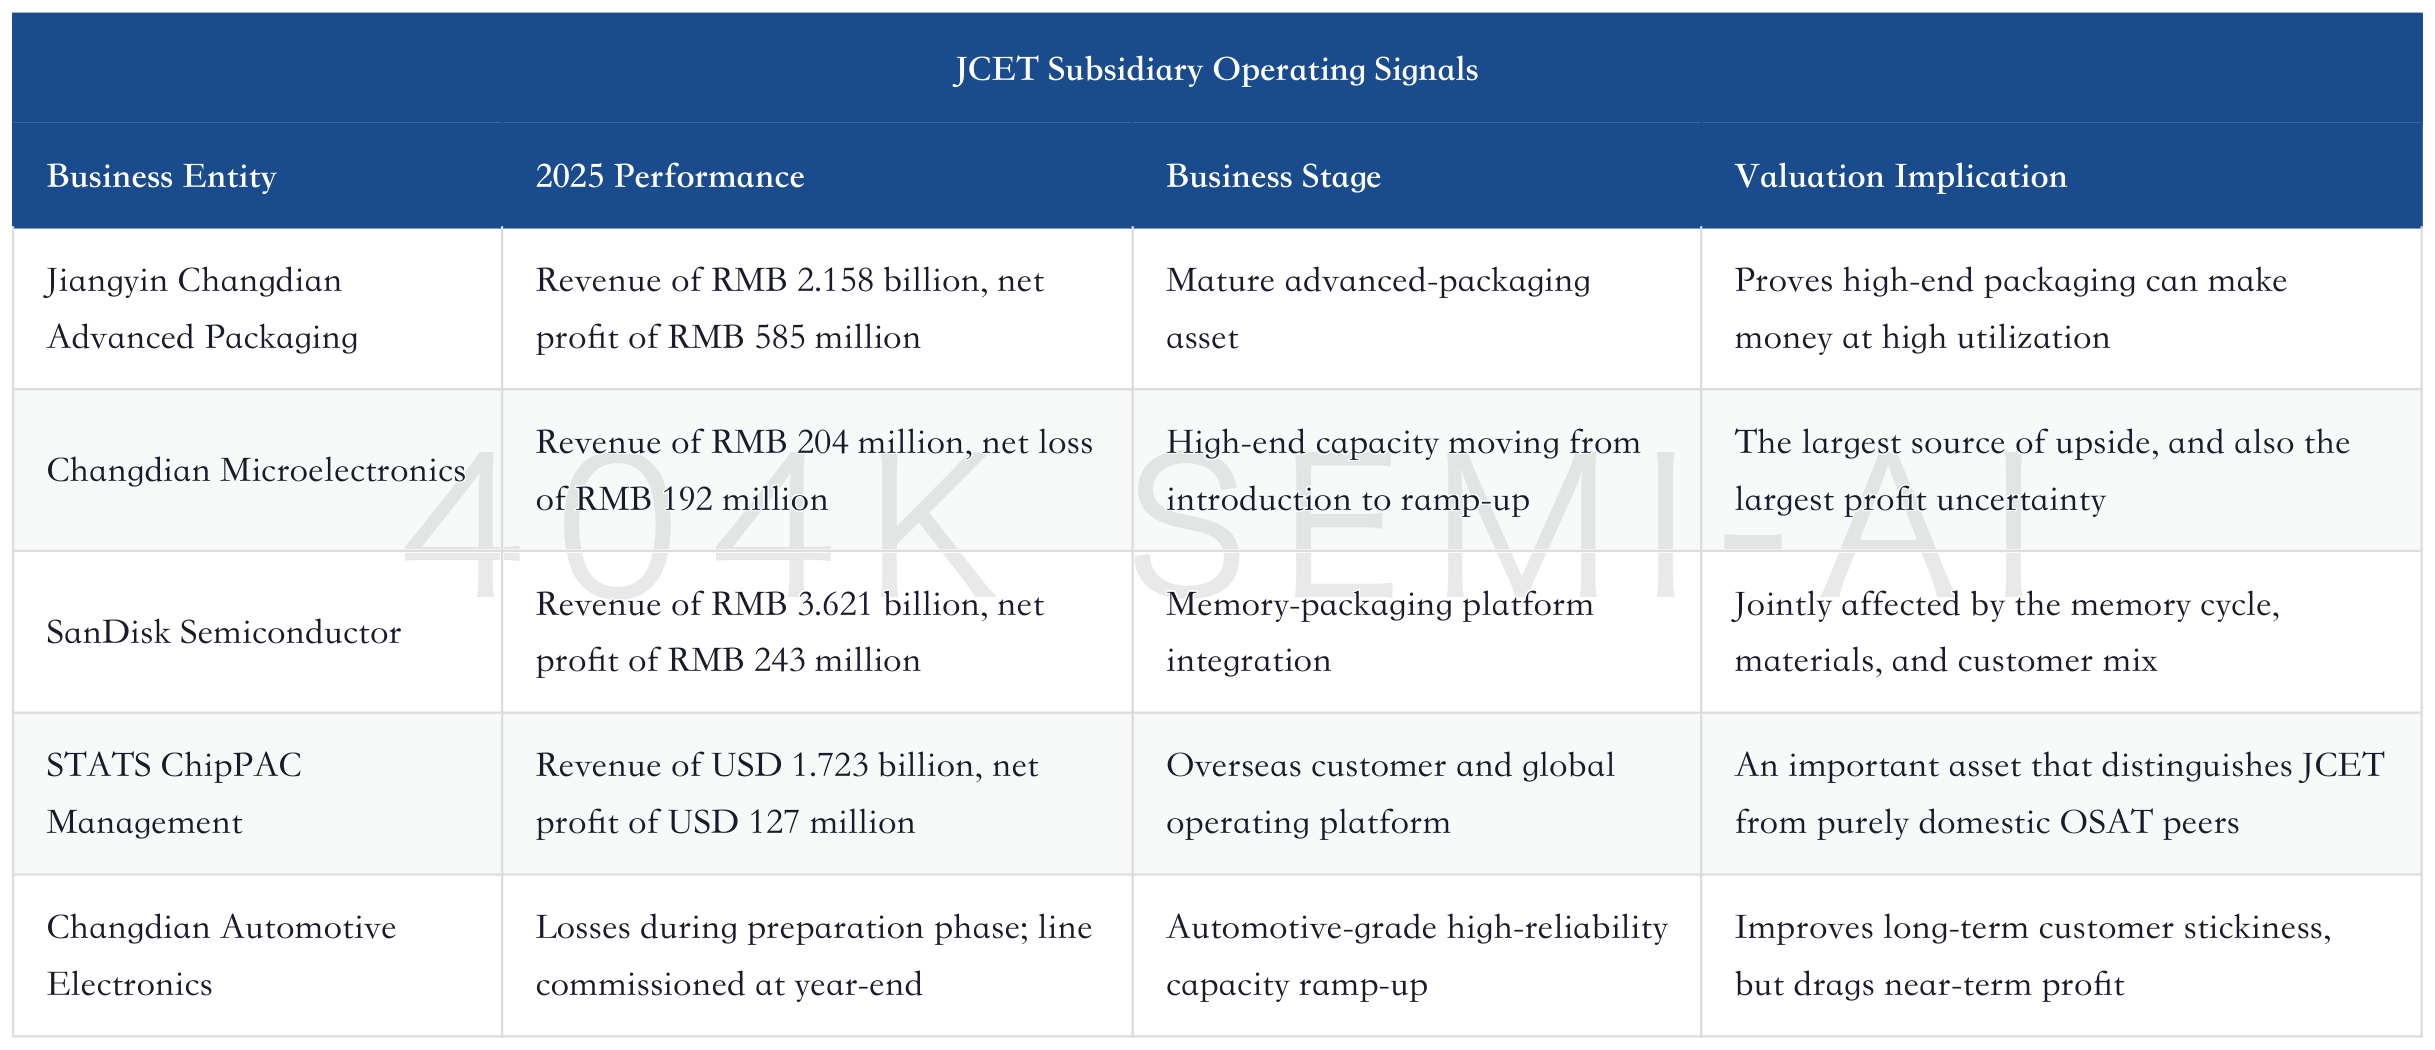
The conclusion from this dataset is: JCET already has profitable advanced-packaging assets, and it also has high-end new capacity that is still burning cash during ramp-up. The market should neither look only at the profit of Changdian Advanced nor focus only on the losses of Changdian Microelectronics. The real question is whether new capacity over the next two years can replicate the profitability curve of mature assets.
IV. The Handset Cycle Is Not the Answer; AI and Memory Are the Main Line
UBS’s smartphone sell-through report provides an important reminder: traditional handset end demand is not strong. In April 2026, global smartphone sell-through was about 87.5 million units, down 8.3% MoM and 9.7% YoY, the lowest level since May 2020 and the fifth consecutive month of YoY decline. China, India, the U.S., Europe, and other regions all declined YoY in April. Apple performed relatively better, but the China Android chain and some emerging-market OEMs were under clear pressure.
This is critical for JCET. Communications and consumer electronics together accounted for about 60% of the company’s 2025 revenue. If handsets and traditional consumer electronics do not recover, the traditional OSAT base will struggle to deliver strong revenue leverage. Precisely because of this, JCET’s current rerating cannot be built on “the handset replacement cycle returning”; it must be built on sustained improvement in higher value-added applications such as AI/HPC, memory, automotive, and industrial/medical.
UBS’s semiconductor cycle report provides evidence from the other side. AI cloud-computing-related chips are expected to rise from about 34% of semiconductor revenue in 2026 to about 48% in 2027; memory revenue has very strong leverage in 2026 and 2027; and non-memory semiconductors will also benefit from AI accelerators, server CPUs, networking, power, and edge computing. For OSAT companies, this is not a simple end-market recovery, but an increase in product complexity and packaging/test content.
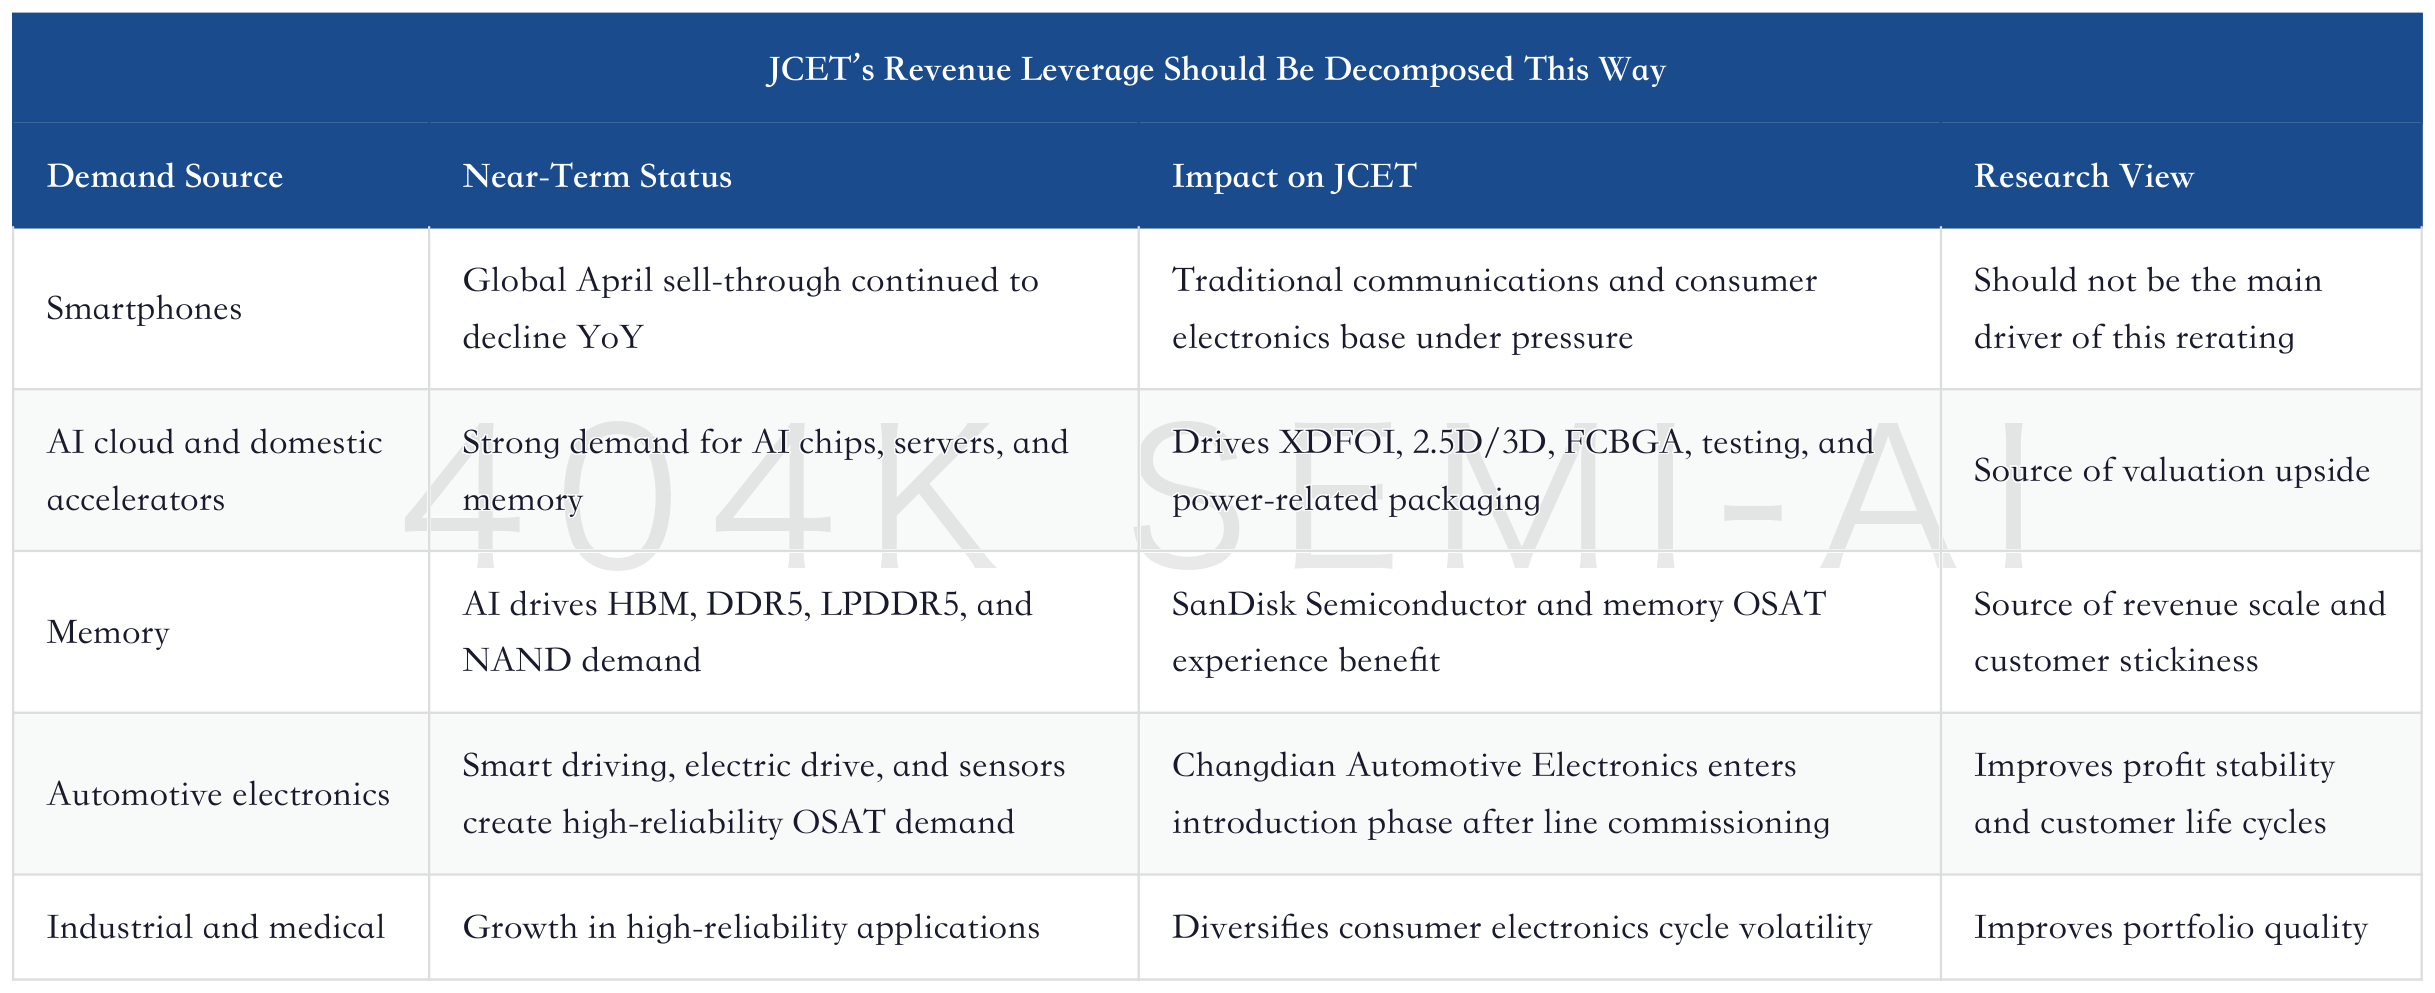
One easily overlooked point is that AI’s pull-through for OSAT does not occur only in GPUs or AI ASICs themselves. It also transmits to memory, PMICs, networking chips, optoelectronic packaging, power modules, test services, and data-center power architectures. JCET’s 2025 R&D; spending referenced directions including high-performance computing, next-generation system-in-package SiP, high-reliability automotive electronics, power energy, CPO, glass substrates, large-size FCBGA, PLP, and 800V HVDC electrical architecture, showing that the company’s technology investment already covers multiple value-migration points around AI systems.
Second Upgrade to the AI Hardware Cycle: The Asian Tech Rerating of Memory, HBM, PCB, and MLCC
From this perspective, JCET is not a single AI accelerator beta, but a composite asset combining “rising AI semiconductor complexity + domestic OSAT supply + spillover from memory and power.” Whether this combination materializes depends on whether the company can integrate multiple lines into profitable capacity, rather than merely running scattered projects.
V. The Domestic Compute Closed Loop: JCET Sits at the “Last Mile of Delivery”
UBS’s China semiconductor report focuses market attention on the industrial implications of China’s AI infrastructure investment plan. Its analytical framework is instructive: if roughly RMB 400 billion in annualized capex allocates half to GPUs/AI accelerators and another 20% to networking and memory, then domestic AI accelerators, wafer manufacturing, packaging and testing, test equipment, memory, networking chips, and power management will all see demand resonance.
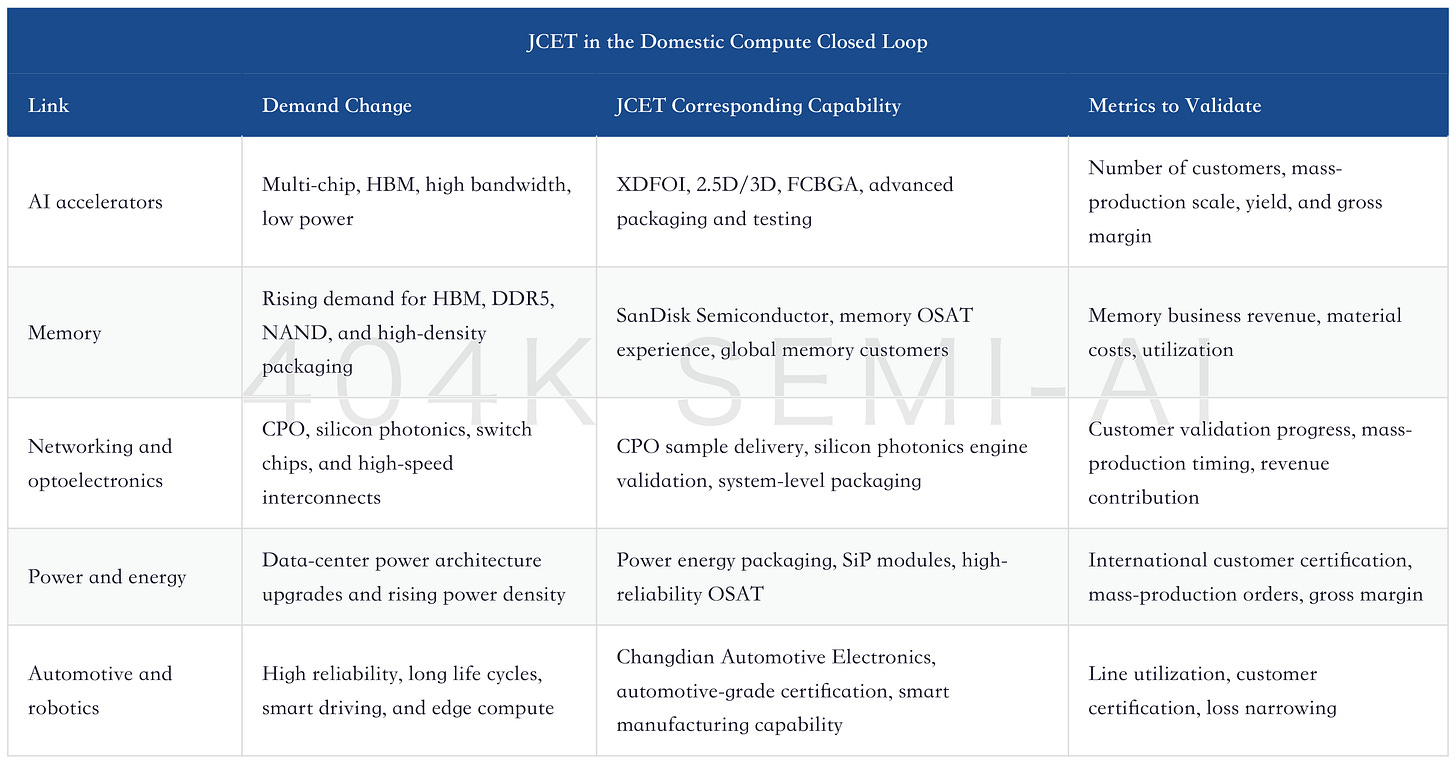
For JCET, the key to this chain is not “how large the planned amount is,” but that mass production of domestic AI accelerators requires complete back-end capability. For domestic AI chips to move from design blueprints to deliverable server components, they must pass through wafer fabrication, bumping, redistribution layers, advanced packaging, reliability validation, testing, system-level validation, and supply-chain coordination. Packaging and testing are not auxiliary steps; they are the last mile that determines whether chips can be delivered reliably.
The Frenzied Philadelphia Semiconductor Index: CoWoS, HBM, CPU, Liquid Cooling, Gas Turbines, A
JCET’s position in this chain can be divided into three layers.
The first layer is domestic high-end packaging supply. The XDFOI chiplet high-density multidimensional heterogeneous integration process series has entered mass production, targeting applications such as high-performance computing, artificial intelligence, communications, and automotive electronics. 2.5D/3D packaging, FCBGA, and high-density system-in-package are capabilities that domestic AI accelerators must fill in as they move from single chips to multi-chip systems.
The second layer is testing and yield management. AI chips have high unit value, and packaging failure costs are even higher. The more complex the advanced packaging, the greater the need for known-good die, post-packaging reliability validation, and system-level testing. JCET’s testing business, integrated wafer-level packaging and testing capability, and global customer experience will amplify in value during high-end product ramp-up.
The third layer is global customers and overseas capacity. Domestic compute demand is incremental, but overseas HPC, memory, and power-related demand is also growing. JCET’s STATS ChipPAC, Korea plants, and Singapore footprint mean the company is not merely an asset in China’s domestic supply chain; it also has the opportunity to absorb spillover from global AI demand.
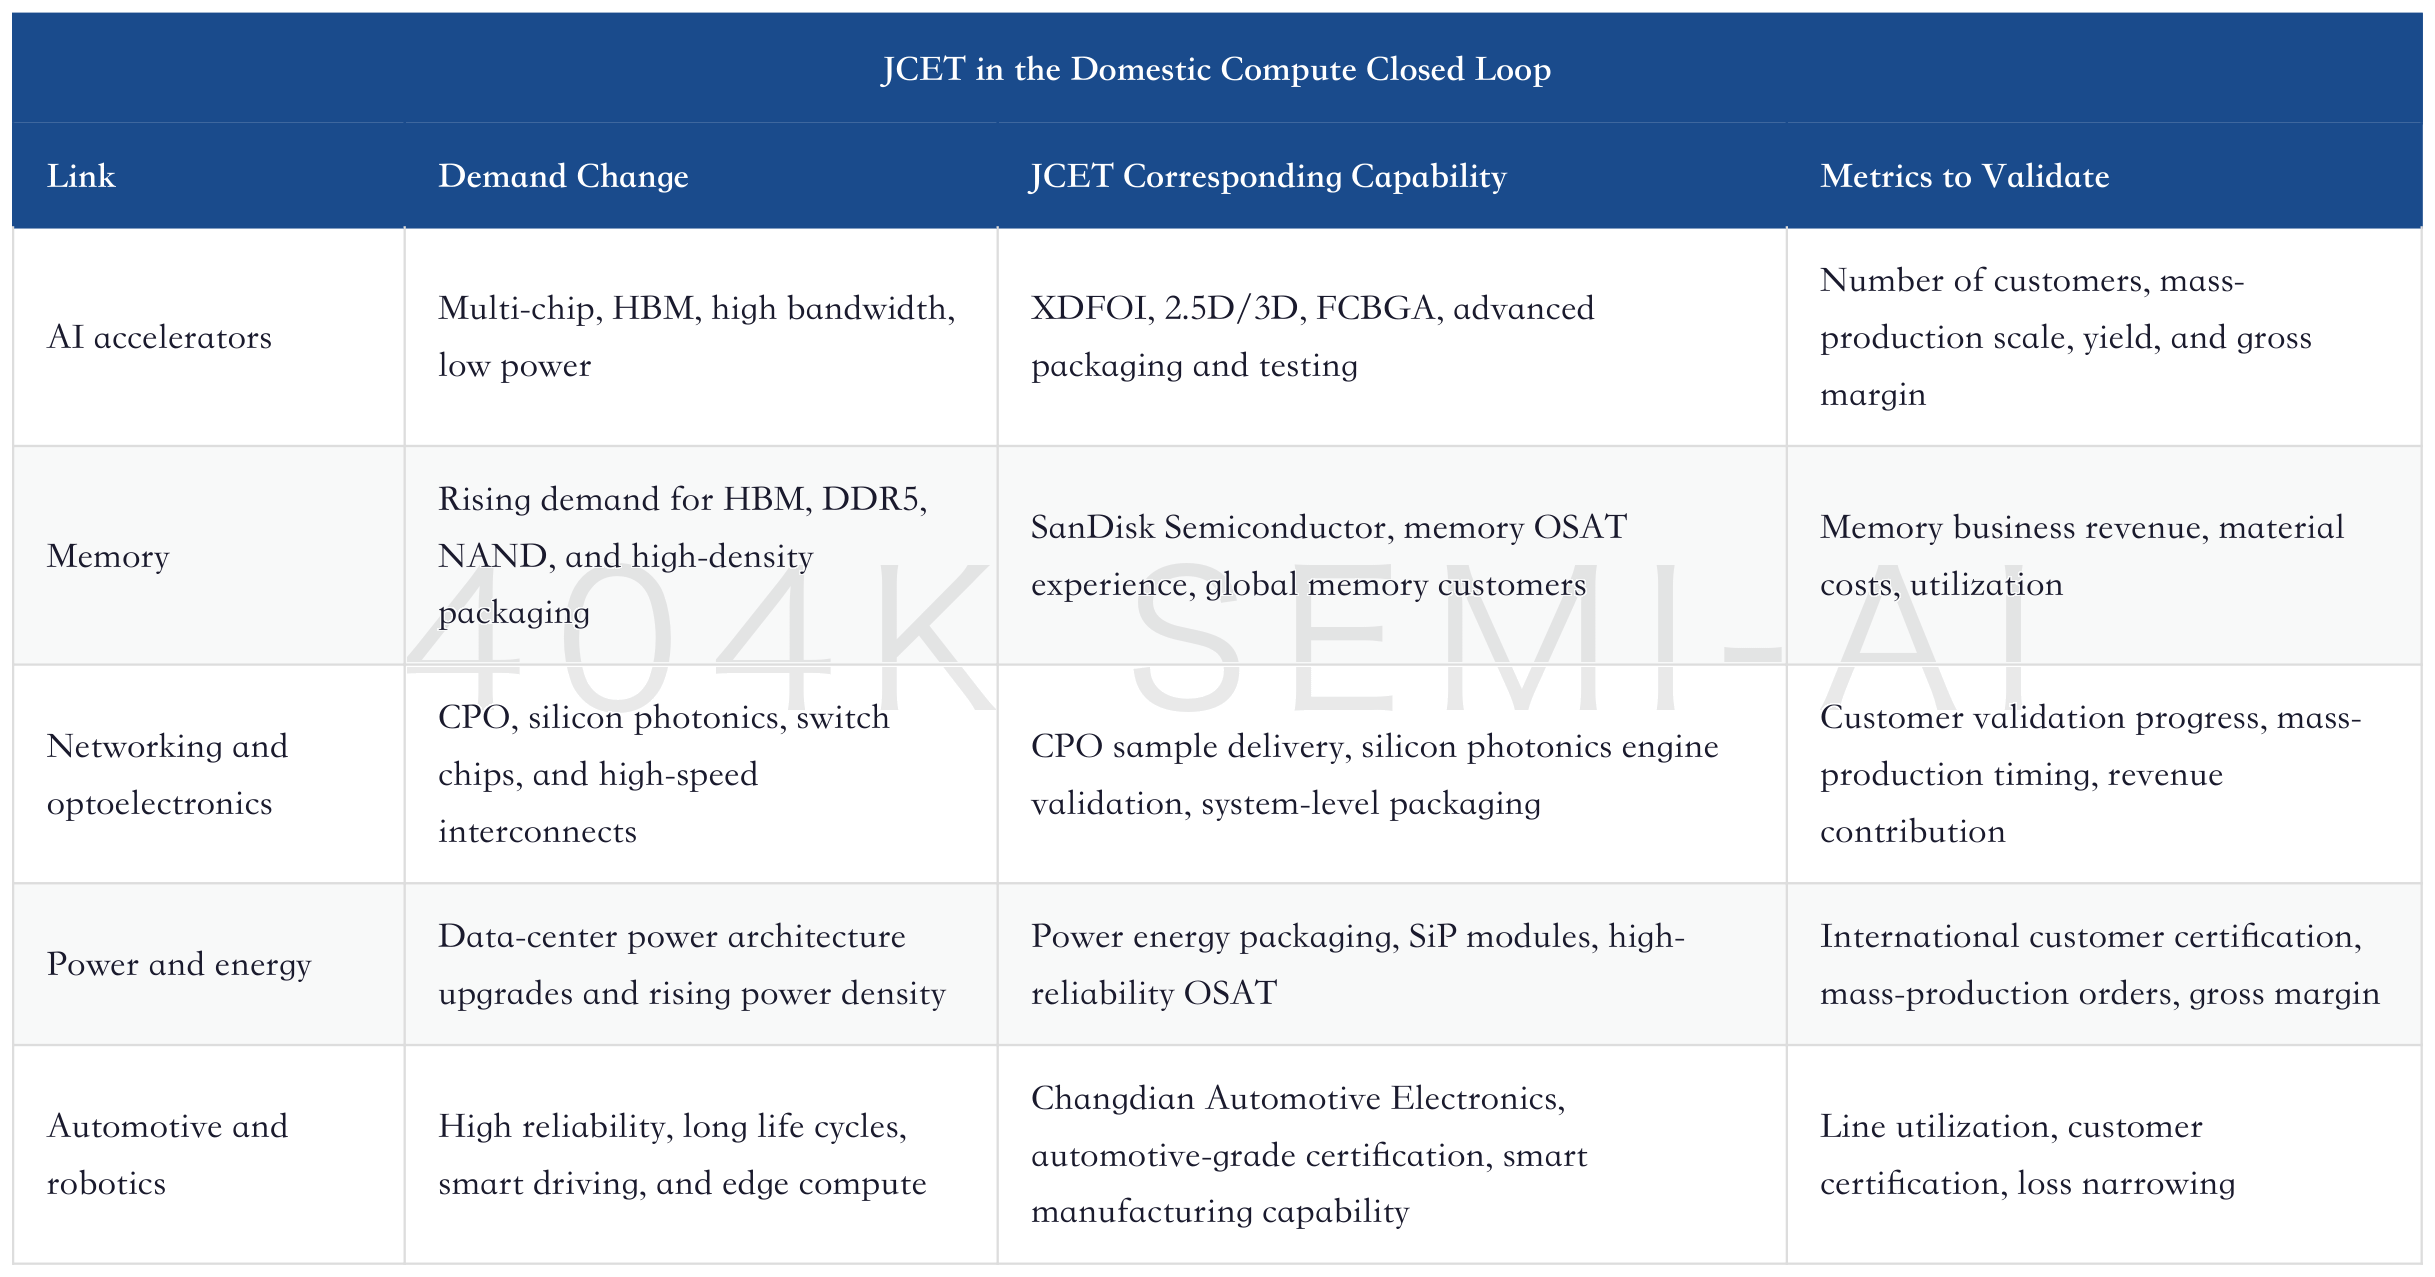
This layer of logic also explains why JCET’s rerating should not be judged only by near-term EPS. The value of the domestic compute closed loop requires the company to invest ahead of time in technology, equipment, processes, customer certification, and capacity. Early-stage profit being suppressed by depreciation, R&D;, and low utilization does not mean the investment is ineffective. But if the ramp-up period is too long, customer orders are discontinuous, or yields are unstable, the advanced-packaging narrative will also become a profit trap.
VI. J.P. Morgan’s Bull-Case Model: The Key Is Not the Target Price, but the Profit Bridge
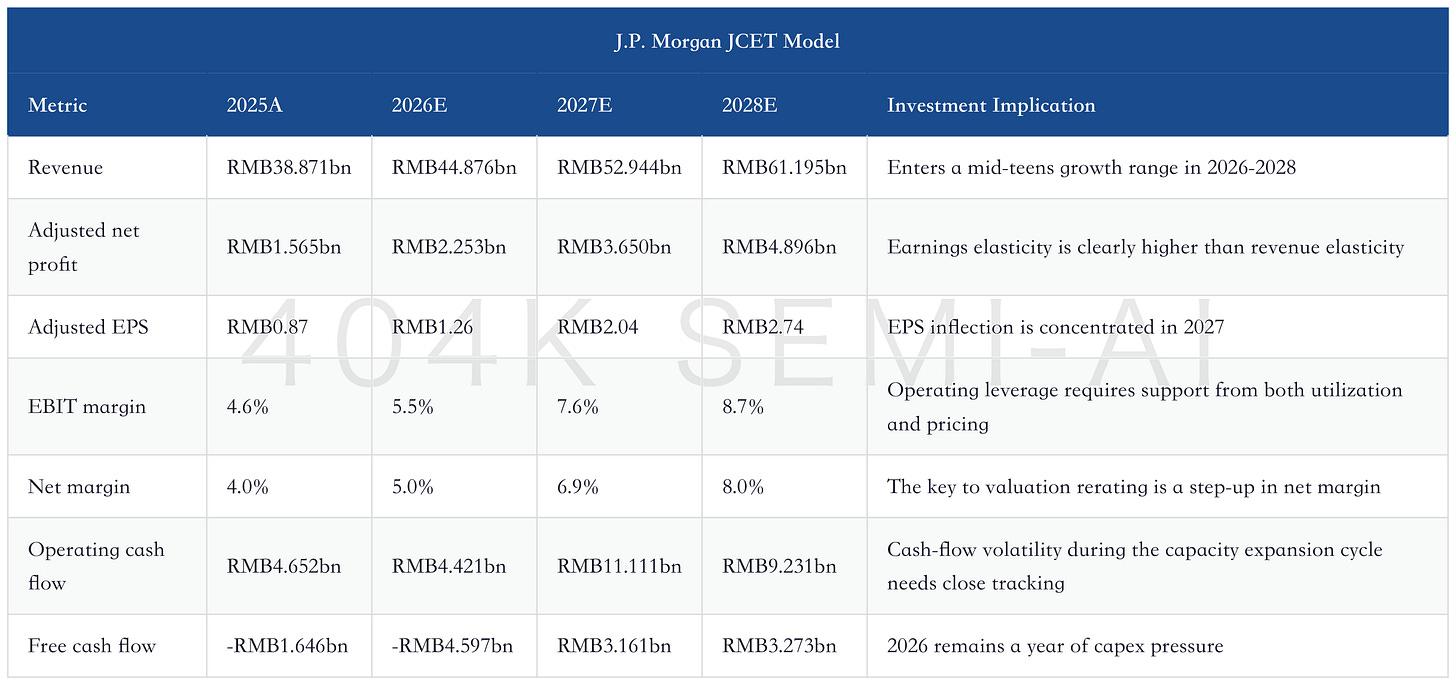
The most valuable part of J.P. Morgan’s June report is not the higher target price, but its clearer decomposition of JCET Group’s 2026-2028 profit bridge.
The model forecasts JCET revenue of RMB44.876bn in 2026, RMB52.944bn in 2027, and RMB61.195bn in 2028; adjusted net profit of RMB2.253bn, RMB3.650bn, and RMB4.896bn, respectively. Under this path, 2026-2028 revenue CAGR is about 16%, while earnings CAGR is about 46%. Earnings growth is materially faster than revenue growth, underpinned by assumptions of mix improvement, higher utilization, material cost pass-through, and a rising share of high-end packaging revenue.
The two most important ratios in the report are: AI-related revenue at about 21% of total revenue in 2025, potentially rising to about 40% in 2028; and gross margin rising from about 14.1% in 2025 to about 16.5% in 2028. If these two ratios are delivered, JCET’s valuation framework will change, because the story will no longer be only revenue scale growth, but margin expansion driven by higher-end revenue.
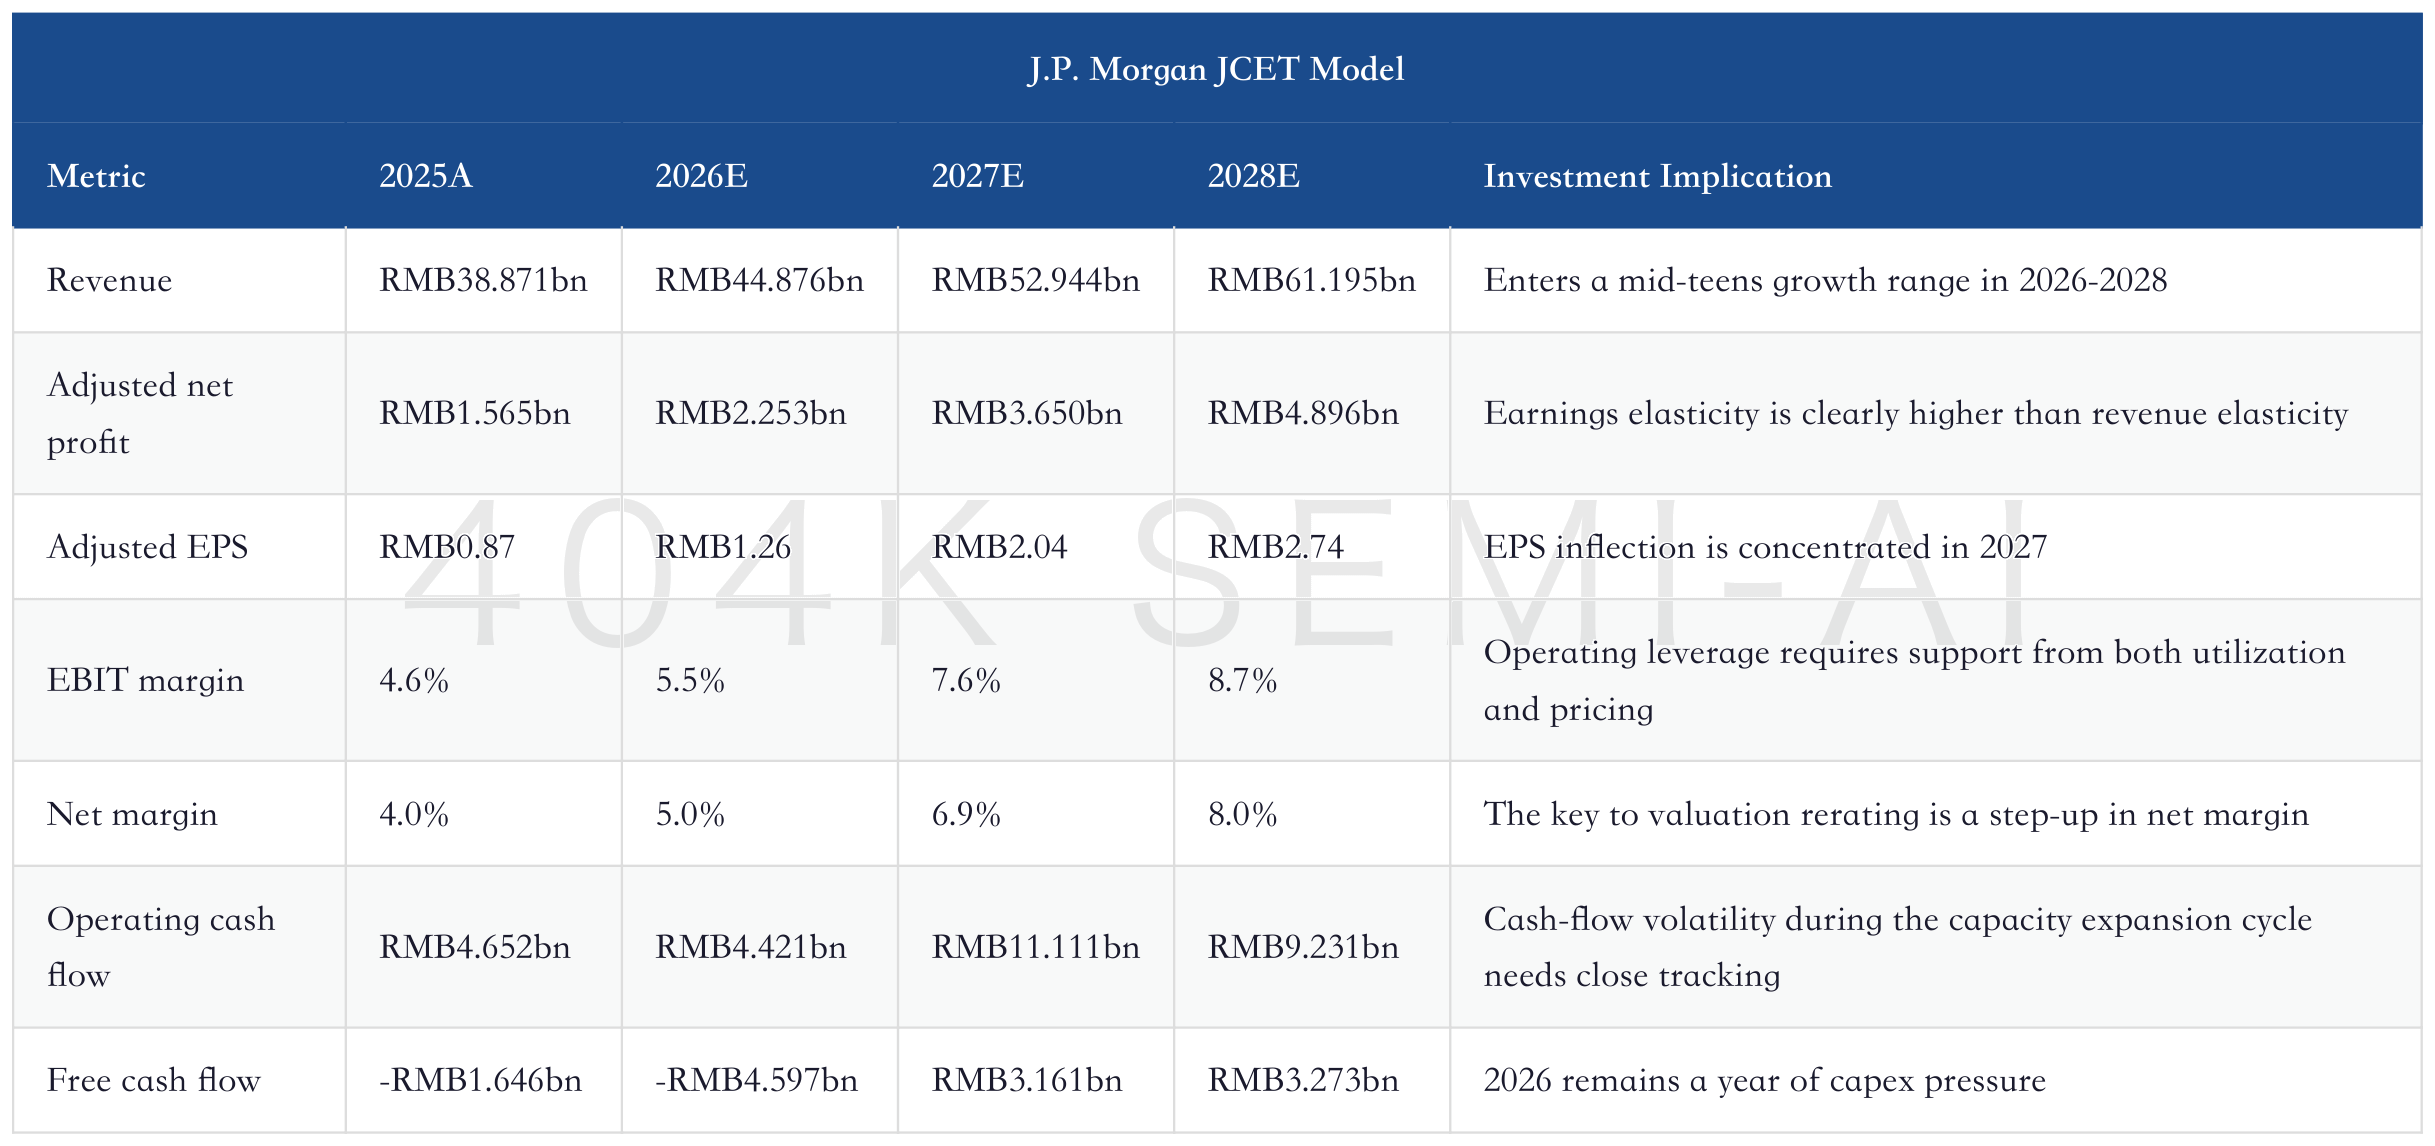
This table should not be treated mechanically as a conclusion, but it can be used as a stress test. For the bull case to hold, at least three linked effects need to be visible: a rising AI-related revenue mix driving higher utilization of high-end capacity; higher utilization and material cost pass-through driving gross margin expansion; and gross margin expansion covering R&D; and depreciation, ultimately improving net margin and cash flow.
Conversely, if capex is delivered in 2026 and revenue also grows, but gross margin does not rise, free cash flow remains negative, and losses at JCET Microelectronics do not narrow, then the market will discount the 2027 earnings elasticity embedded in the model. In other words, J.P. Morgan’s model is not the “answer”; it is the roadmap JCET must deliver against over the next two years.
VII. Technology Ticket: How Advanced Packaging Turns into Profit
JCET’s technology ticket is not a single term, but a set of capabilities. XDFOI, 2.5D/3D, FCBGA, CPO, silicon photonics, memory packaging, power SiP, and complex testing each correspond to different revenue cadences and profit curves. Lumping them all under the label of “advanced packaging” makes the analysis shallow.
Deep Dive on AI Packaging: As HBM4E Moves Toward 2.5TB/s, How Bridge Interconnects, Vertical Power Delivery, and Thermal Paths Rewrite Hardware Competition
The value of XDFOI lies in turning multi-chip heterogeneous integration into a reusable platform. High-performance computing chips are moving from single large dies toward chiplet architectures, with increasingly high connection density among compute, I/O, memory, analog, power delivery, and optoelectronic modules. If a packaging platform can stably support multi-chip interconnect, redistribution, thermal management, and reliability, it is not merely processing capability, but part of system design. JCET’s annual report discloses that its XDFOI chiplet high-density multidimensional heterogeneous integration process series has entered mass production, indicating that it has at least crossed the first threshold from R&D; to commercialization. The next things to track are not whether the platform exists, but how many customers it has, how many products are in mass production, and how many individual products can contribute gross profit.
The value of 2.5D/3D lies in bringing AI accelerators closer to high-bandwidth memory. For AI chips, compute is not the only bottleneck; memory bandwidth, package interconnect, power density, heat dissipation, and yield can all become system constraints. As 2.5D/3D packaging moves higher-end, the difficulty of equipment, process, materials, substrates, and testing rises, and capex also becomes heavier. J.P. Morgan is positive on JCET’s 2.5D/3D capacity ramp, but this is also a source of financial pressure. If customer orders are continuous and product yield is stable, high-end packaging can lift ASP and gross margin; if line changeovers are frequent and customer adoption is slow, depreciation will absorb profit first.
FCBGA is the foundation of high-performance computing packaging. Large package size, more substrate layers, higher I/O density, and more demanding thermal management all increase packaging and testing complexity. JCET’s annual report notes that the company has many years of experience in large FCBGA packaging and testing technology, and continues to advance ultra-large-size devices, high-end panel-level packaging, and high-density system-in-package directions. FCBGA does not create a hot narrative as easily as CPO, but it is closer to current revenue and product upgrades, making it a practical indicator for judging whether JCET can take on AI/HPC customer projects.
CPO and silicon photonics are more like long-dated options. The company disclosed customer sample delivery for CPO products and related validation progress for silicon photonics engine products. AI data-center networks are evolving from 800G and 1.6T toward higher bandwidth, making optoelectronic integration, low-power interconnects, and switch-chip packaging increasingly important. But the current revenue contribution from these areas is limited, so long-term technologies should not be fully capitalized into the profit model too early. A more reasonable treatment is to view CPO and silicon photonics as items to observe for valuation upside, rather than core assumptions for 2026 profit.
Testing capability is often underestimated. Complex packaging does not end with simply testing the finished product; it runs through the whole process, from wafer-level known good die, packaging process control, and post-packaging reliability to system-level validation. AI accelerators, automotive electronics, and power modules carry high value, and any failure at any stage amplifies cost. If JCET can turn packaging and testing into an integrated service, both customer stickiness and value per project will rise. Jiangyin JCET Advanced Packaging recorded sharp revenue and profit growth in 2025, and the annual report cited higher value from integrated wafer-level advanced packaging and testing services. This is a sample case of a technology ticket converting into profit.
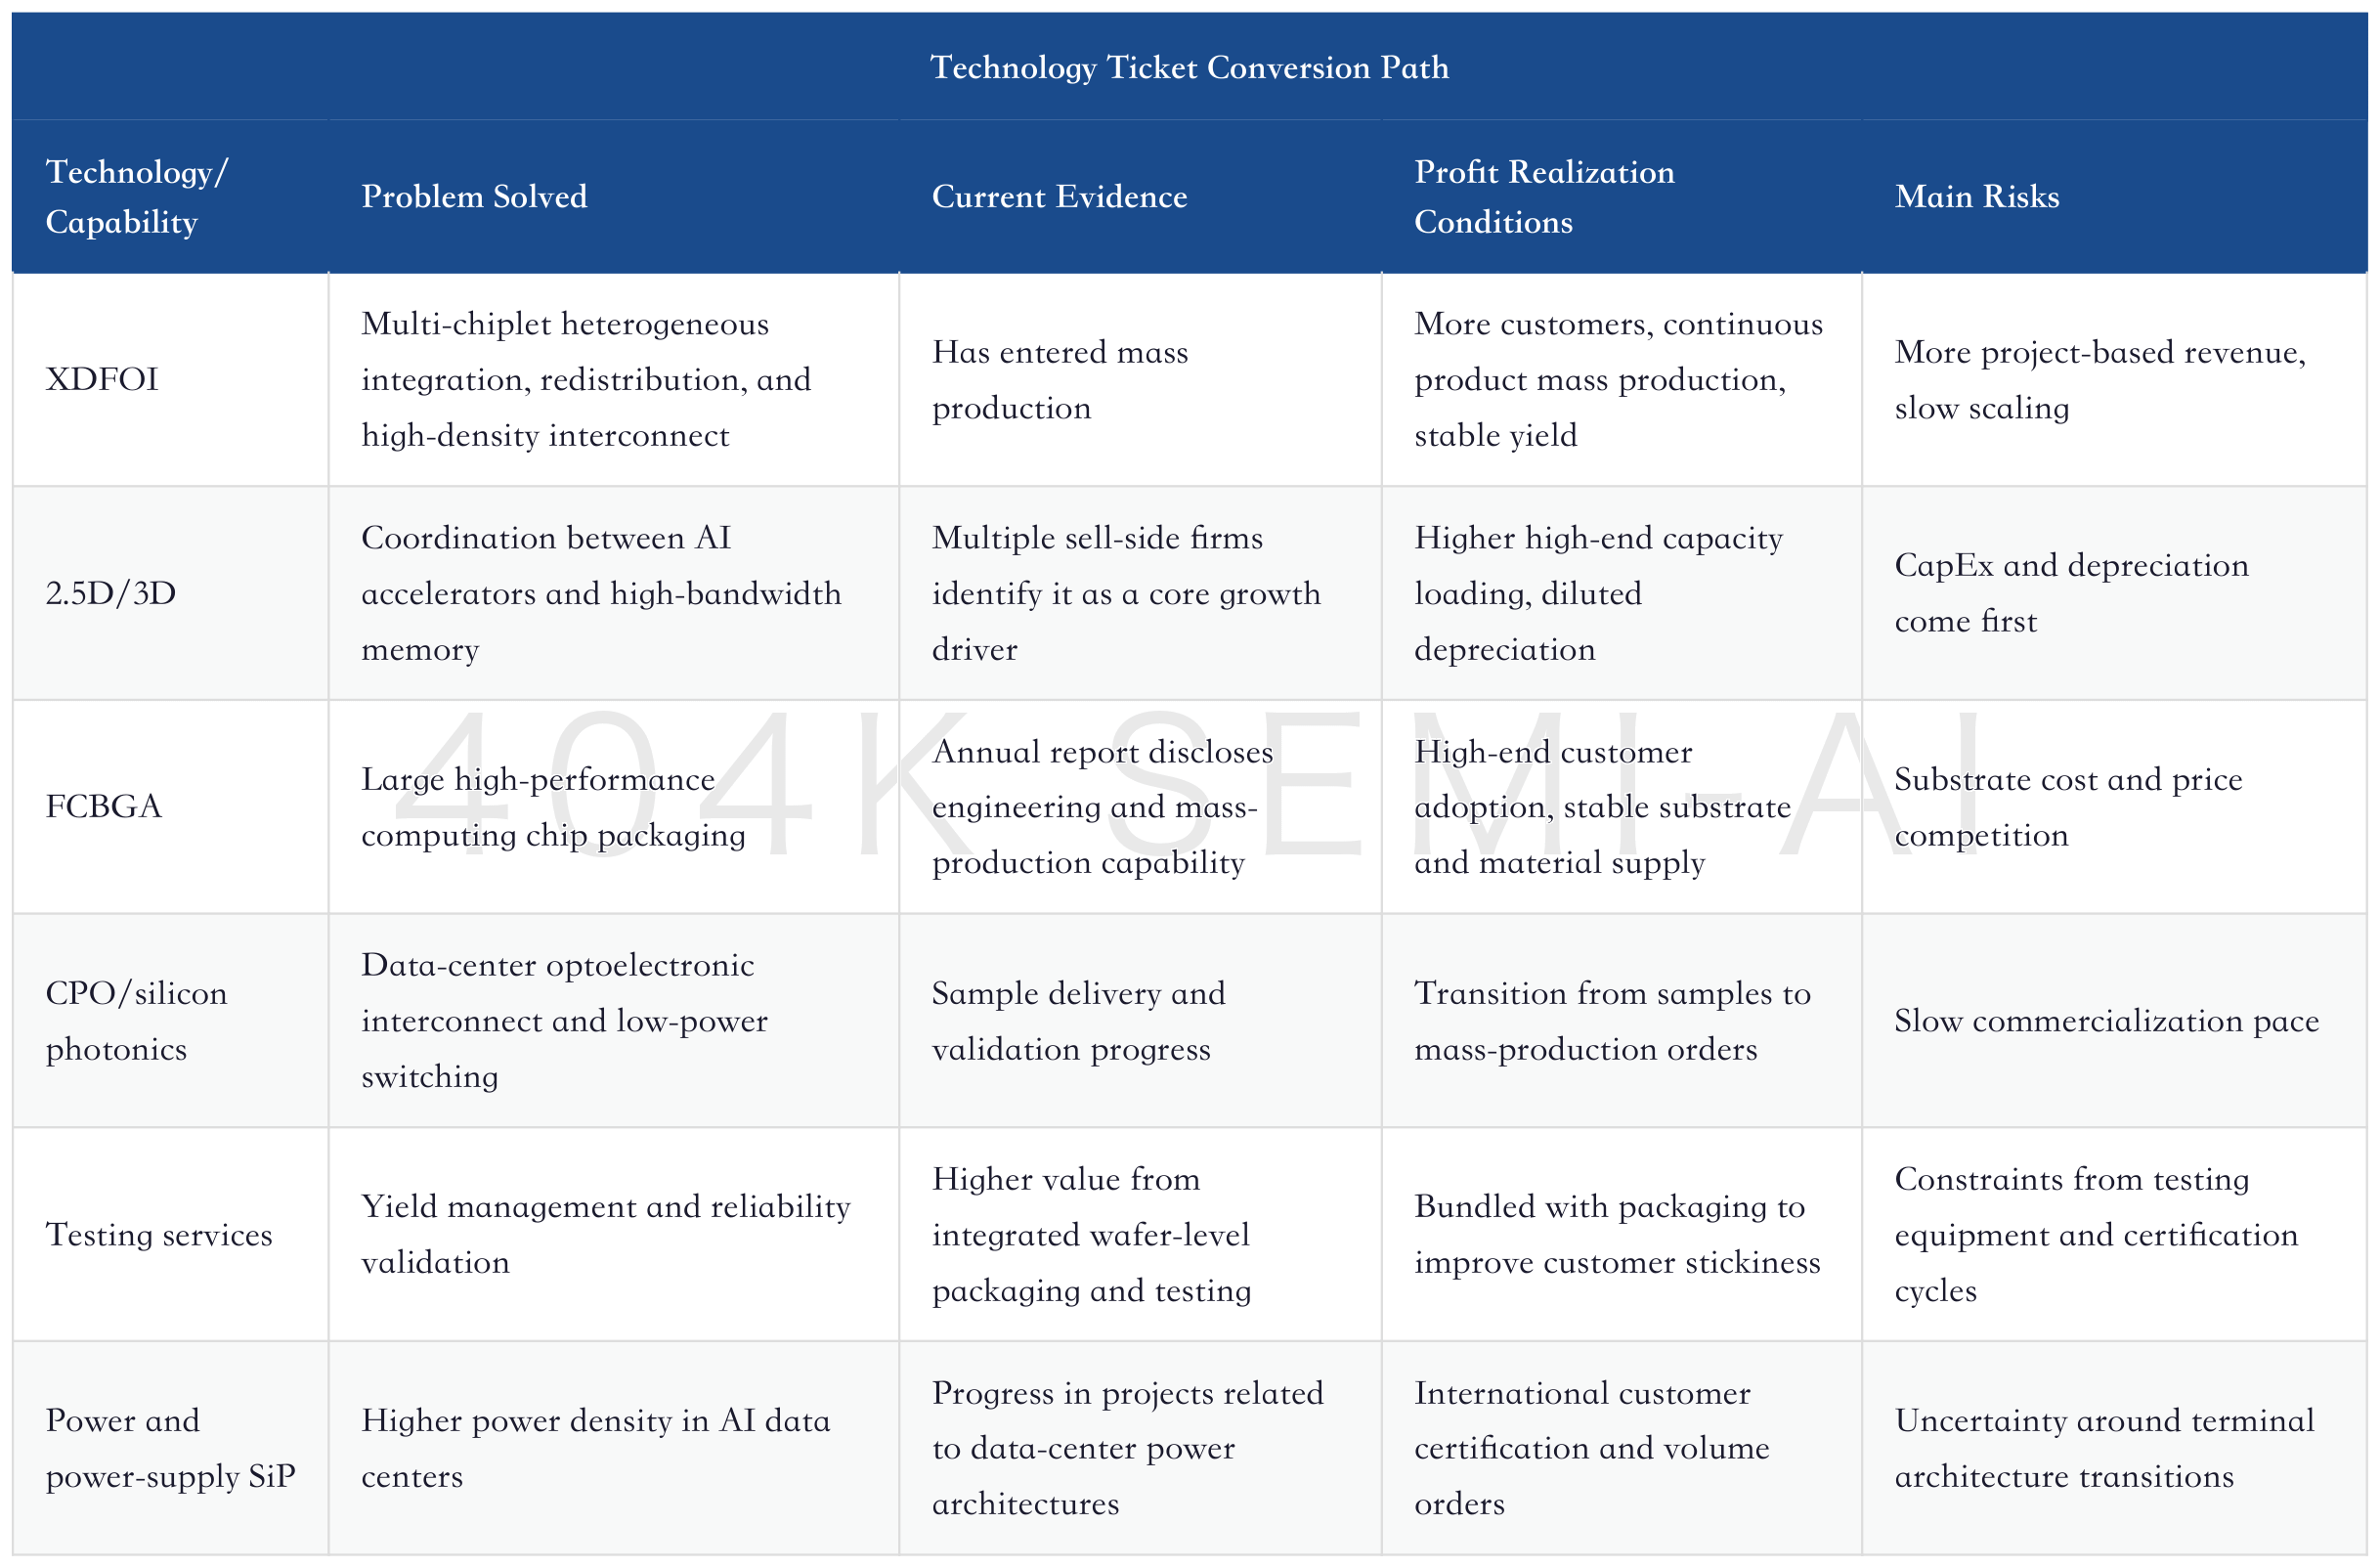
The investment implication of this table is clear: not every technology direction deserves the same valuation. XDFOI, 2.5D/3D, and FCBGA are closer to medium-term profit; CPO, silicon photonics, and glass substrates are closer to long-dated options; testing and power packaging are underlying capabilities that improve customer stickiness and earnings quality. If JCET wants to evolve from an OSAT leader into a platform asset, it must move these capabilities from R&D; and sample stages into customer projects, mass-production revenue, and gross-margin improvement.
Therefore, tracking the technology ticket cannot rely only on news flow. More effective indicators are: the revenue share of advanced packaging, JCET Microelectronics revenue and losses, the gross-profit quality of JCET Advanced, changes in testing revenue, capex tied to customers, quarterly gross margin, and operating cash flow. Only when these indicators improve together does the technology ticket truly become a profit ticket.
VIII. JCET Microelectronics: The Variable with the Greatest Valuation Elasticity
JCET Microelectronics is the most sensitive component in JCET’s rerating. It carries high-end advanced packaging, XDFOI, 2.5D/3D, and capacity related to domestic AI accelerators. It also carries the greatest uncertainty, because 2025 revenue was only RMB204mn, with a net loss of RMB192mn.
The loss itself is not the issue. A new advanced packaging line naturally goes through stages of front-loaded depreciation, R&D; investment, process tuning, material loss, and low utilization from construction to customer introduction, sample validation, small-batch production, and mass-production ramp. The issue is how long this stage lasts, and whether revenue scaling can also bring loss narrowing. If revenue grows while losses widen, it means high-end capacity is still ramping inefficiently. If revenue grows while losses narrow, it means utilization, yield, and customer orders are starting to match.
J.P. Morgan’s assumptions for JCET Microelectronics are quite positive. It believes the company’s 2.5D/3D capacity ramp will benefit from demand for domestic AI chips, and forecasts rapid growth in related sales in 2026-2028. Other prior sell-side materials also identified JCET Microelectronics as the core source of JCET’s advanced packaging elasticity. The disagreement is not whether it has strategic significance, but when it crosses breakeven.
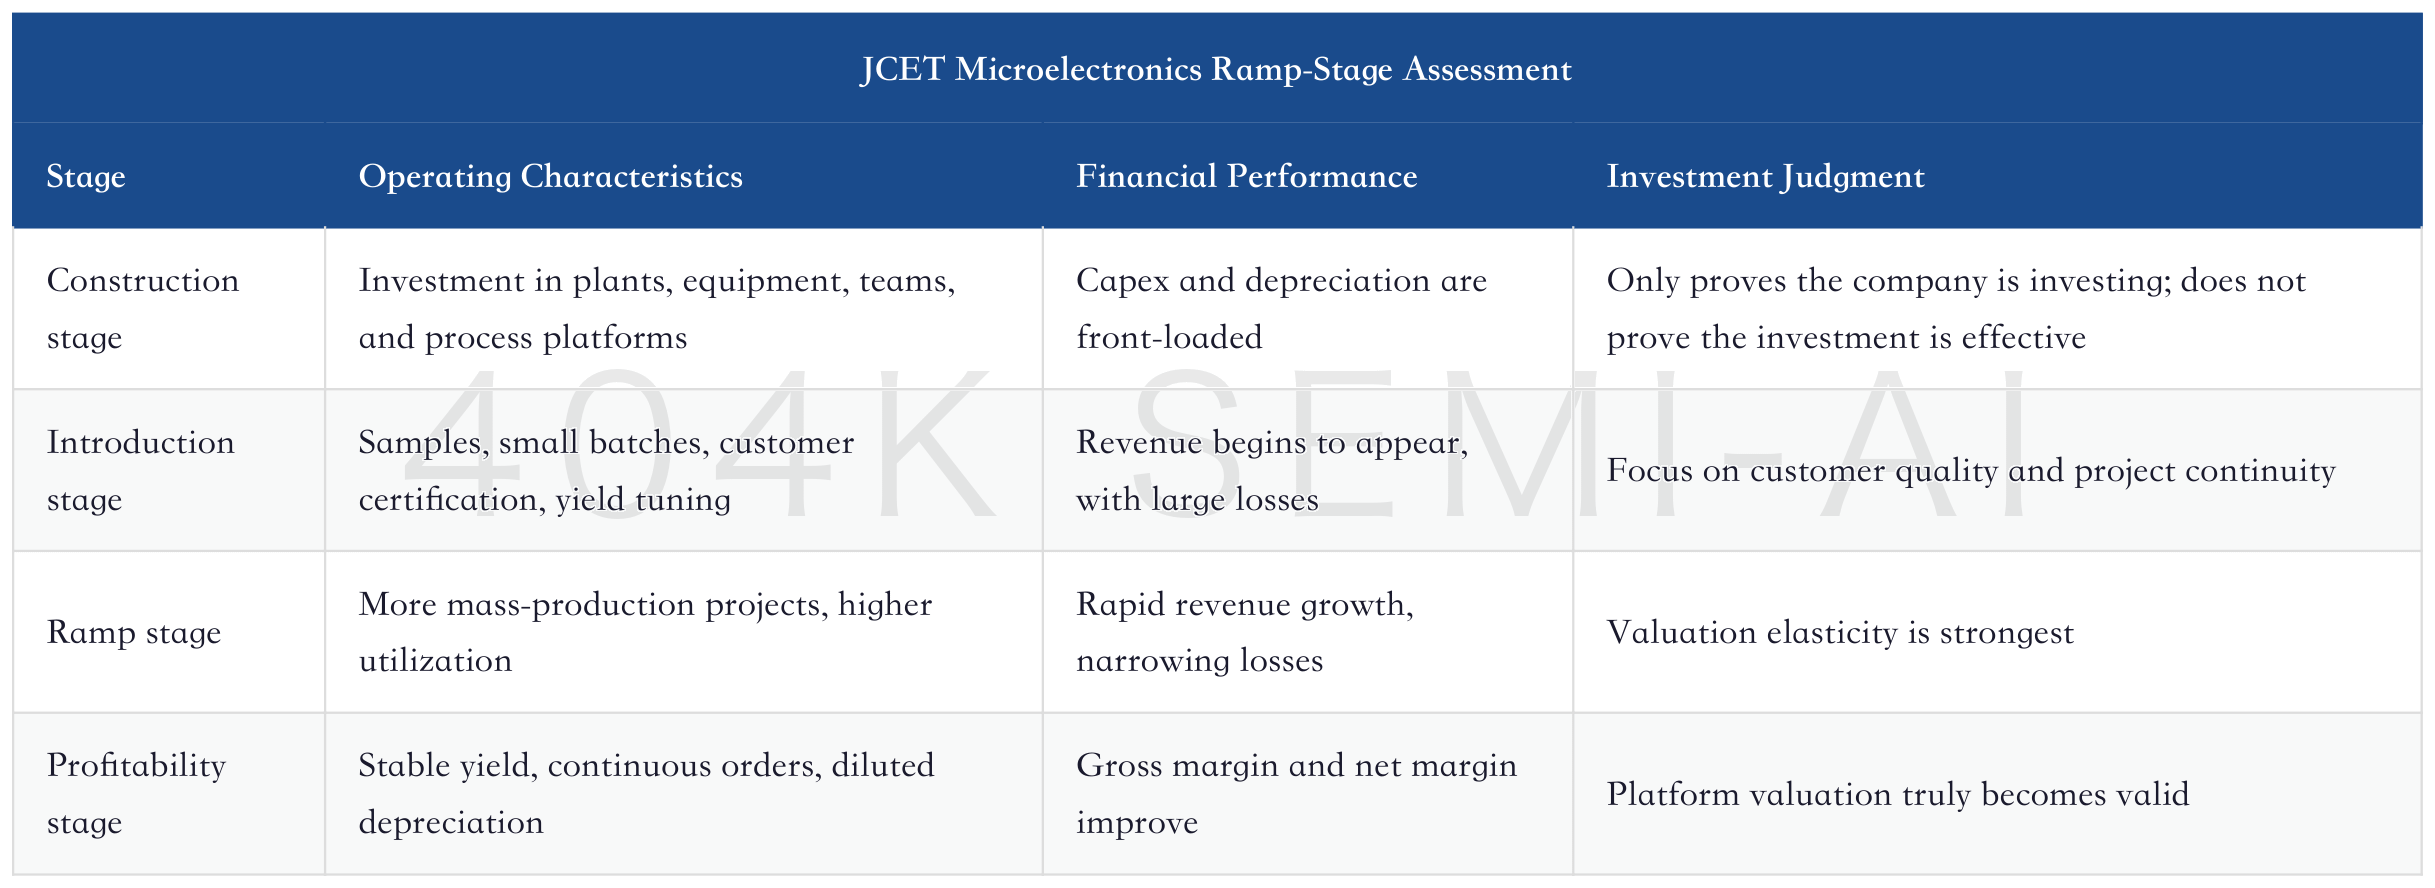
JCET Microelectronics is most likely now in the transition from the introduction stage to the ramp stage. This is the phase where the market is most likely to price in expectations early, because expectations are fullest; it is also where the market is most likely to be disappointed, because the financial statements look worst. The real judgment should return to three indicators: absolute revenue scale, pace of loss narrowing, and linkage with the parent company’s gross margin.
If, from 2H26 to 2027, JCET Microelectronics revenue scales continuously, losses narrow significantly, and the parent company’s gross margin rises at the same time, then JCET’s “AI advanced packaging platform” framework will be materially strengthened. If these three items do not improve simultaneously, advanced packaging can only be considered strategic investment, not something that can be immediately capitalized into a high valuation.
IX. STATS, SanDisk Semiconductor, and Automotive Electronics: Not the Main Narrative, but They Determine Profit Depth
JCET Technology’s Changdian Microelectronics is the asset most likely to attract market attention, but the company’s real asset portfolio is broader.
STATS ChipPAC is one of the biggest differences between JCET and purely domestic OSAT vendors. It brings overseas customers, global operating experience, and high-end application innovation capabilities. In 2025, STATS ChipPAC Management generated revenue of USD 1.723 billion and net profit of USD 127 million. The company’s annual report also noted that it established the STATS ChipPAC global operations center based on SCPM and increased investment in R&D; and application innovation. J.P. Morgan places product optimization at the Korean plant within the AI opportunity, especially connectivity, PMICs, and overseas AI peripheral chips. This shows that JCET’s AI opportunity does not come only from domestic Chinese customers, but also from spillover in global AI demand.
SanDisk Semiconductor is linked to the memory cycle. In 2025, SanDisk Semiconductor generated revenue of RMB 3.621 billion and net profit of RMB 243 million. AI servers are driving demand for HBM, DDR5, LPDDR5, NAND, and enterprise SSDs, making back-end memory packaging and testing experience increasingly important. SanDisk Semiconductor is not directly equivalent to core HBM packaging, but it gives JCET a stronger base in memory customers, packaging experience, and capacity integration.
Automotive electronics improves revenue stability. In 2025, JCET Automotive Electronics was still in the preparation stage, but the line was officially connected by year-end; in 1Q26, automotive electronics revenue increased 28.8% year on year, maintaining double-digit growth. Automotive packaging and testing is characterized by long certification cycles, high reliability requirements, long lifecycles, and slow customer switching. It may not provide the highest valuation elasticity, but it can improve the profit base and customer stickiness.
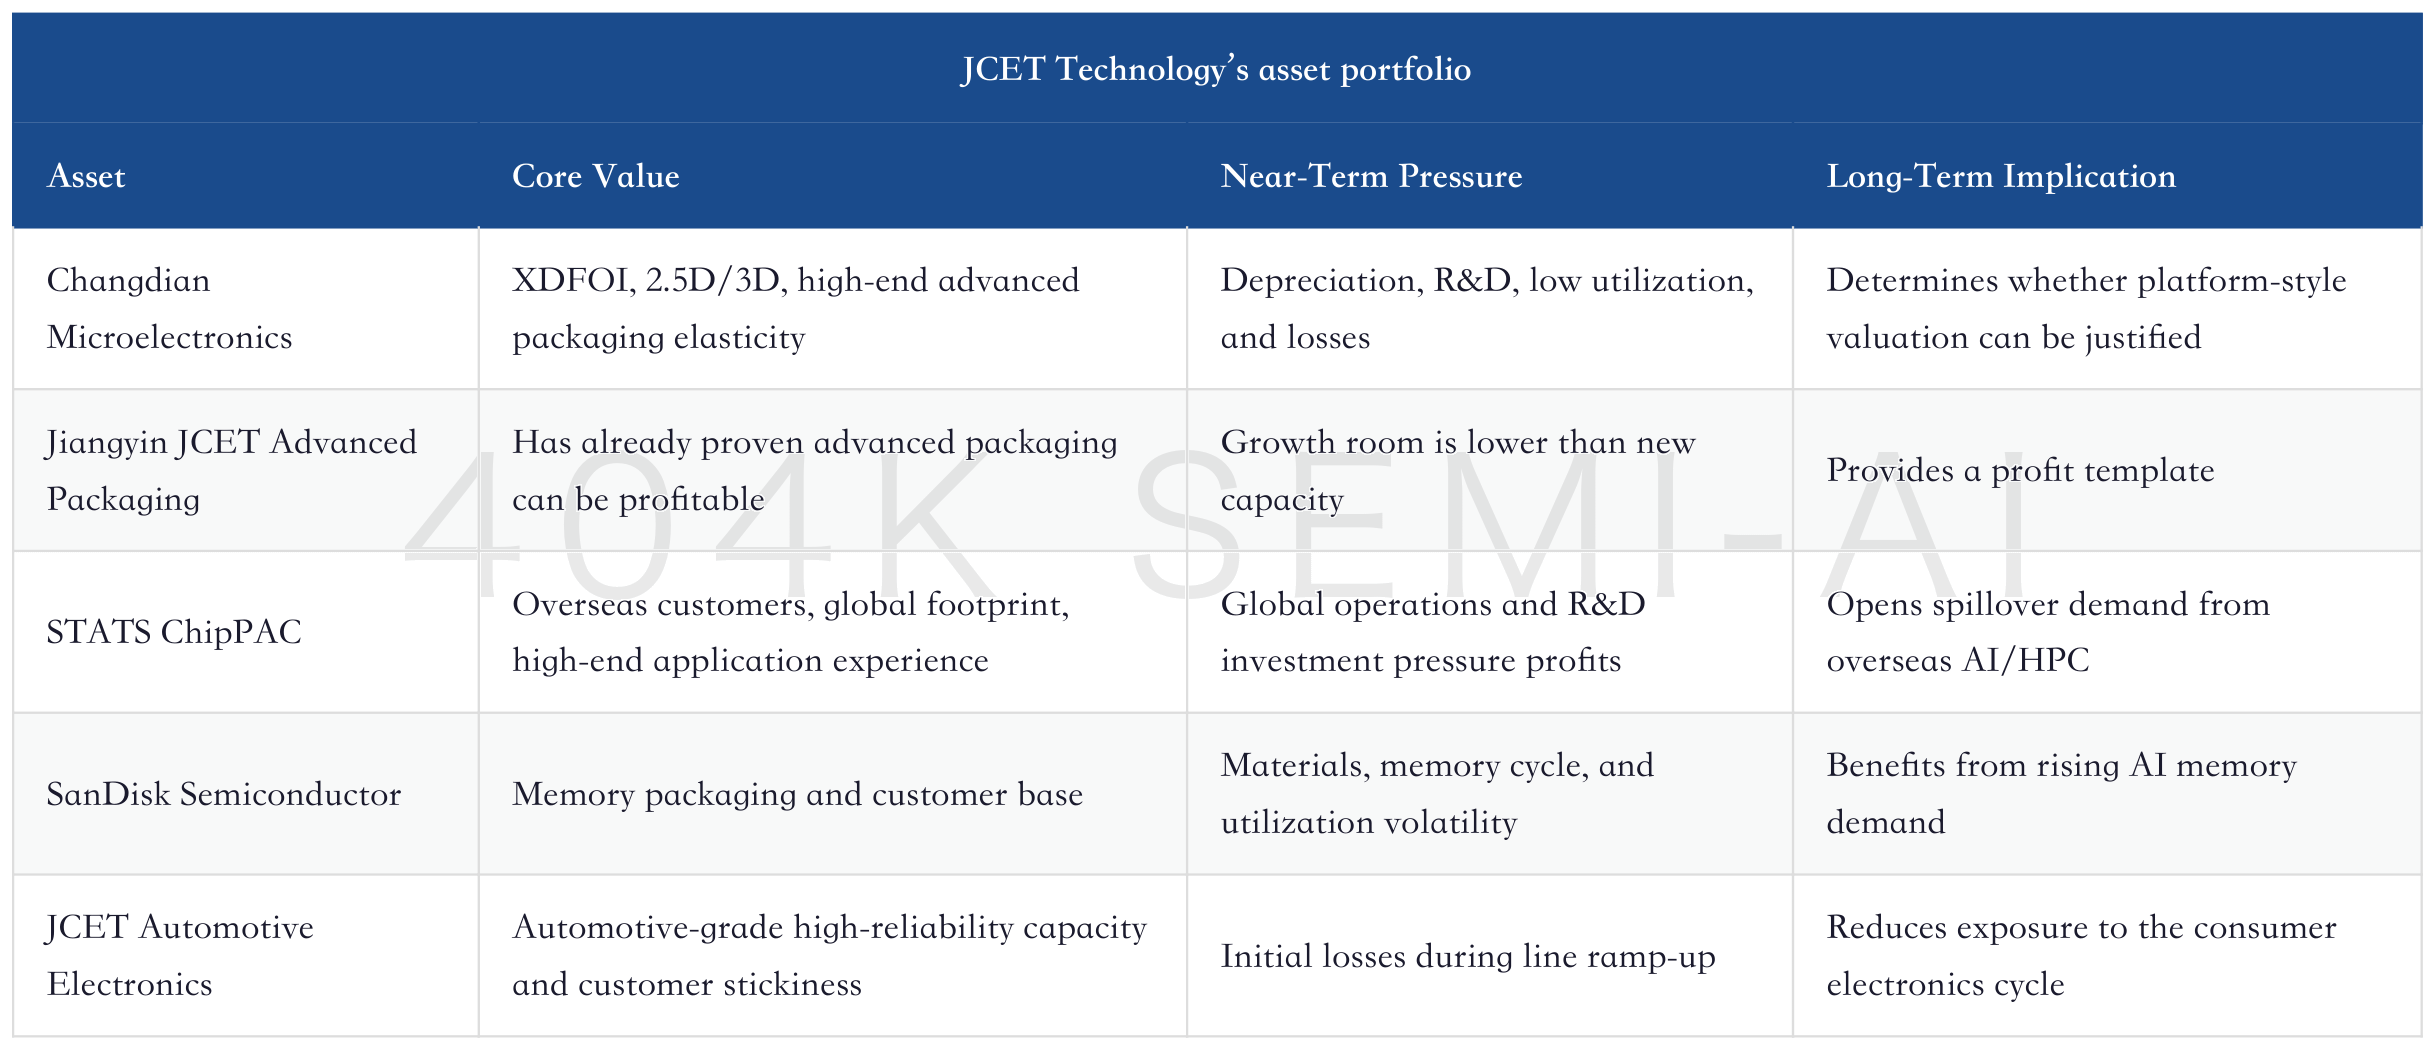
This also explains why JCET Technology cannot be summarized with a single label. It is not a pure AI chip packaging company, nor is it an ordinary consumer electronics OSAT. It is an OSAT platform in an asset restructuring phase: traditional business provides scale, high-growth applications improve the mix, high-end advanced packaging opens the valuation ceiling, and overseas and memory assets provide a second growth curve.
X. Competitive Landscape: Platform Breadth Is an Advantage, Profit Elasticity Is the Constraint
In the global OSAT landscape, ASE, Amkor, JCET Technology, Tongfu Microelectronics, Huatian Technology, and others each have different capabilities. The strongest advanced packaging platforms remain in the hands of foundries and a small number of leading OSATs. TSMC’s advantages are front-end process technology, CoWoS/SoIC, customer roadmaps, and capacity coordination; ASE and Amkor have global customers and high-end packaging experience; JCET’s advantages are advanced packaging and testing supply within China, a global footprint, the XDFOI platform, and its position in the domestic AI chain.
Applied Materials Deep Dive: How the WFE Supercycle, DRAM Expansion, and Advanced Packaging Reprice the Profit Slope
Compared with Tongfu Microelectronics, JCET Technology has a broader platform, a more complete overseas footprint, and more diversified memory and automotive businesses; Tongfu’s elasticity may be more concentrated, with more direct marginal changes from customers and CPU/GPU-related packaging and testing projects. Compared with Huatian Technology, JCET Technology has stronger narratives around global revenue scale, high-end customers, and advanced packaging platforms, but it also faces higher capex pressure and a higher bar for margin validation.
The competitive landscape is not a simple ranking, but a question of who can convert advanced packaging projects into profits. OSAT companies may all benefit from the AI cycle, but only a few can simultaneously meet customer certification, capacity, yield, material supply, testing capability, and cash-flow constraints. JCET Technology’s advantage lies in platform breadth, and so does its risk: the more business lines it has, the more management must properly prioritize capex, customer introduction, and product mix.
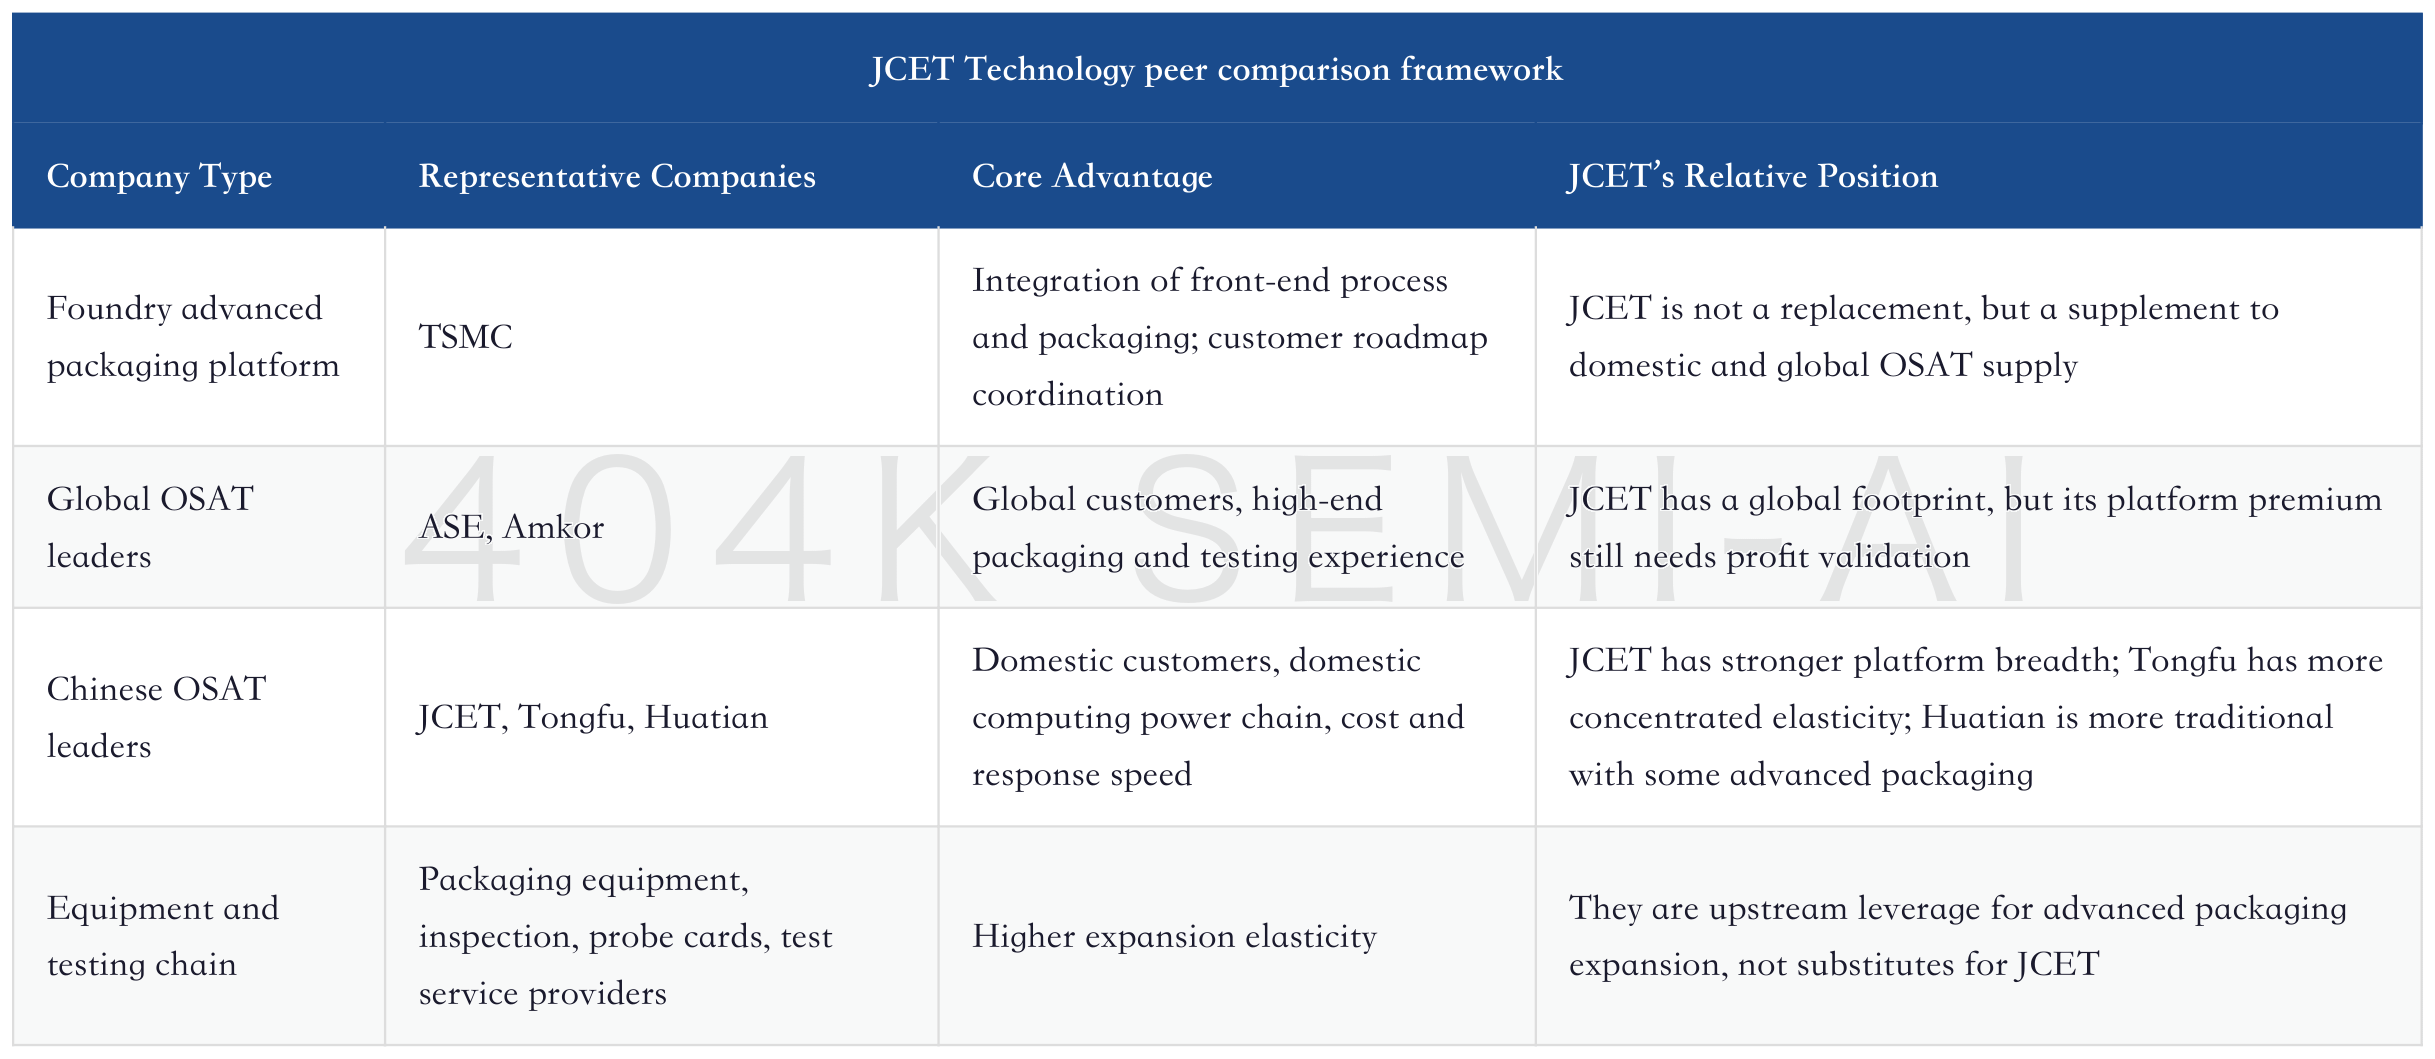
The investment implication of this comparison is that JCET Technology’s valuation cannot be directly benchmarked to TSMC, nor can it be based only on the average for traditional OSATs. A more reasonable approach is to separately assess the traditional packaging and testing base, overseas and memory assets, and high-end advanced packaging platform, then determine the platform premium using gross margin and ROE.
XI. Valuation Divergence: Three Worldviews Determine Three Prices
The most important question for JCET Technology today is not whether it is “expensive,” but which worldview should be used to price it.
The first worldview is that it is a traditional packaging and testing cyclical stock. Under this framework, JCET is mainly evaluated based on the semiconductor cycle, handset and communications demand, capacity utilization, inventory, and gross margin. Advanced packaging is only a structural improvement factor and is insufficient to justify a very high valuation premium. If handsets are weak in 2026, capex rises, and losses at Changdian Microelectronics expand, this worldview will regain dominance.
The second worldview is that it is a leading OSAT in China. This framework acknowledges that the company is not just an ordinary cyclical stock, because domestic AI accelerators, memory, automotive electronics, and industrial and medical applications have improved the quality of the revenue mix; but it also does not directly price the company as a platform-style advanced packaging asset. Valuation mainly depends on ROE recovery, revenue mix, and cash-flow quality.
The third worldview is that it is an AI advanced packaging delivery platform. Under this framework, XDFOI, 2.5D/3D, FCBGA, CPO, memory packaging and testing, testing services, and global customers together constitute platform value. The valuation anchor shifts from cyclical P/E to long-term ROE, platform scarcity, and the share of advanced packaging revenue. This framework has the most imagination, but also the highest requirements, because JCET must prove that high-end revenue can generate high-end profits.
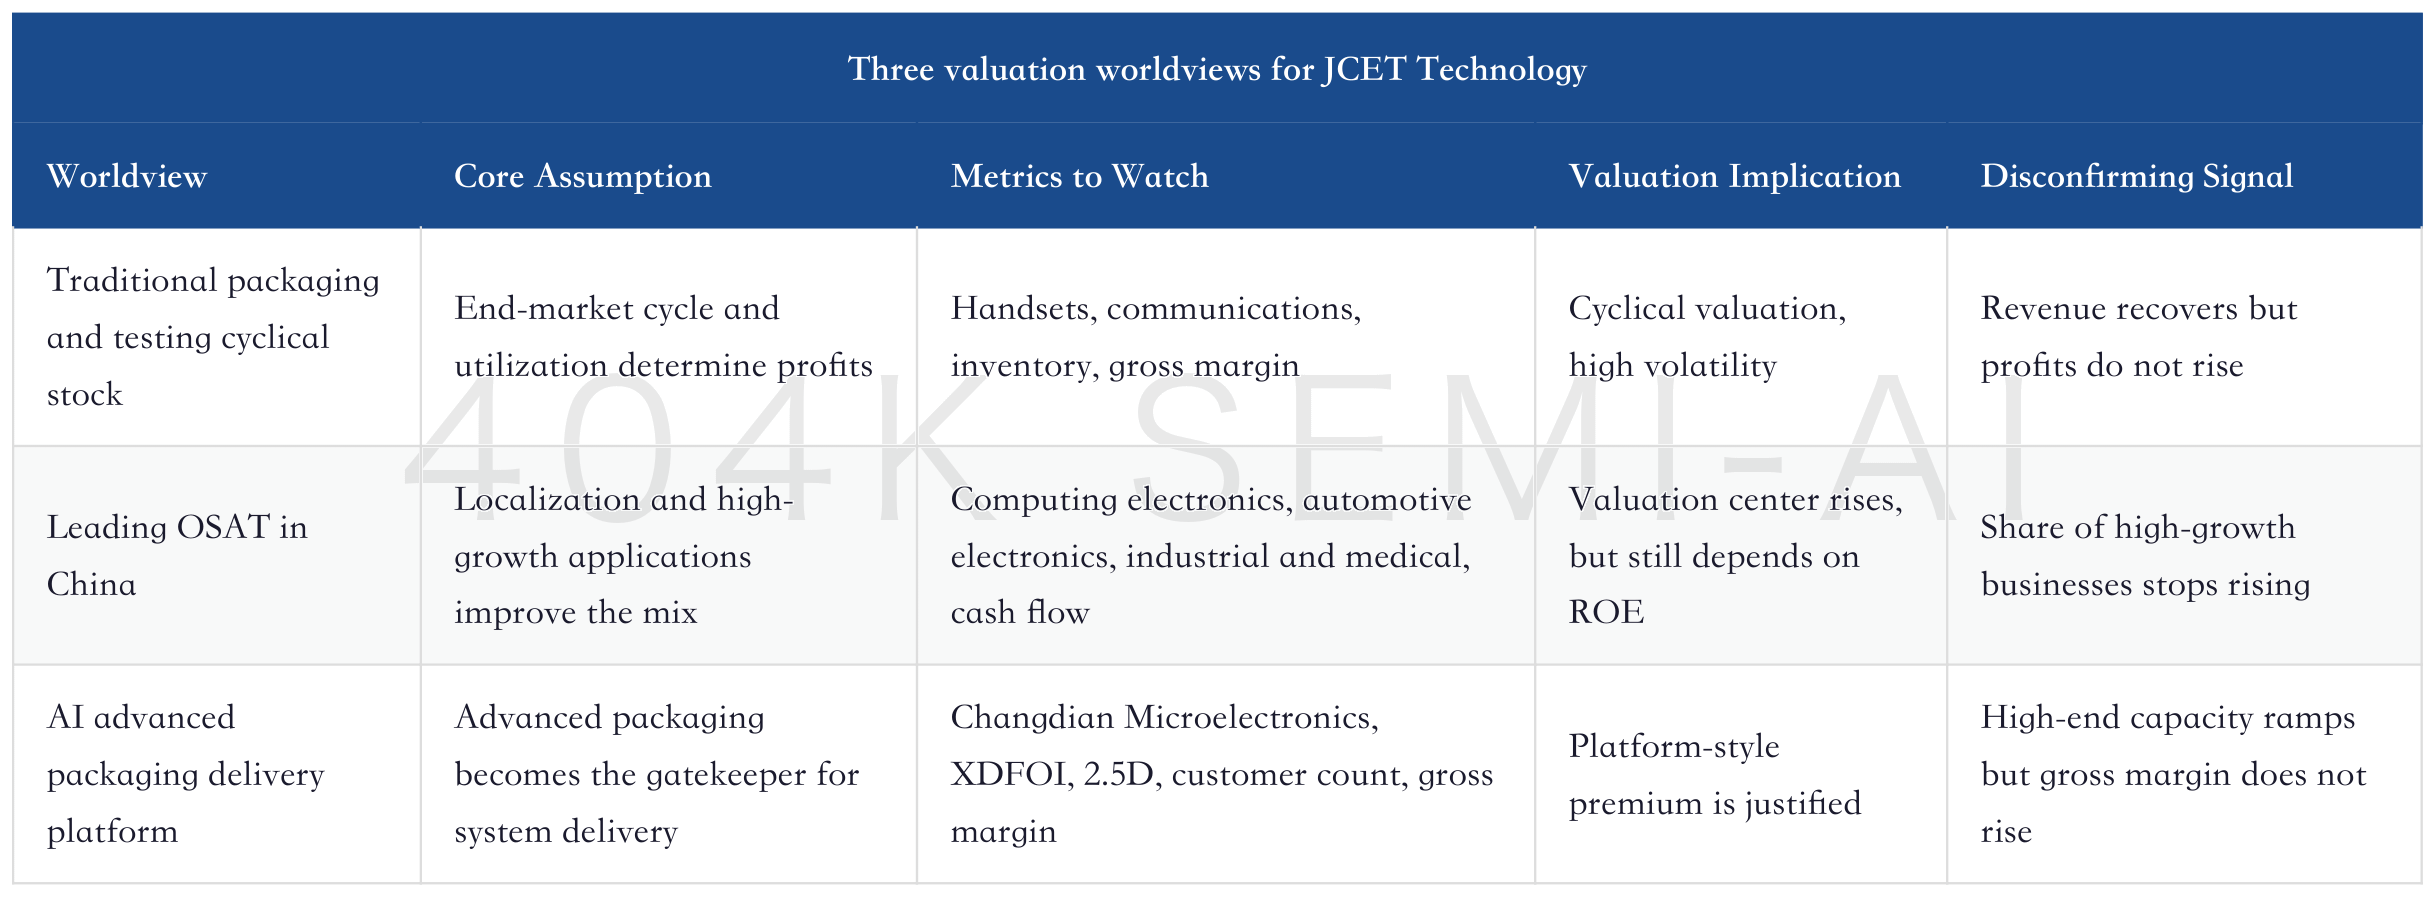
J.P. Morgan’s RMB 110 target price is essentially priced on the third worldview: a 2027 target, 40x forward P/E, rising AI-related revenue share, and earnings CAGR significantly above revenue CAGR. This target price should not be taken simply as a conclusion. It is more like a conditional statement: if JCET’s high-end packaging revenue and gross margin improve as the model suggests, the market can assign a platform premium; if margins do not materialize, valuation will fall back toward the second or even the first worldview.
XII. How to Use Sell-Side Divergence: Do Not Simply Take the Most Optimistic Model
Among this set of materials, J.P. Morgan’s company model is the most aggressive, UBS’s industry materials provide external demand support, and the company’s official financial reports provide more restrained real-world constraints. Only by putting all three together can research on JCET Technology avoid becoming a mere restatement of a single target price.
J.P. Morgan’s strength is that it breaks out the profit bridge. Its 2026-2028 revenue and earnings path puts AI-related revenue share, gross margin, capex, and profit elasticity into the same table. This model is best suited to answering the question: “If everything goes well, where can JCET Technology get to?” But its risks are also obvious: the assumptions include strong improvements in utilization, pricing pass-through, and product mix. If any one of these comes in below expectations, earnings CAGR will be compressed.
UBS’s semiconductor cycle and China semiconductor materials work is strongest in explaining why demand may persist. AI cloud, memory, server CPUs, domestic AI accelerators, networking, and power management together form the upstream sources of packaging and testing demand. It can answer why advanced packaging is not a short-term concept. But UBS’s industry framework does not translate directly into JCET profits, because industry demand must pass through customer introduction, order share, yield, capacity utilization, and pricing pass-through before it appears in JCET Technology’s financial statements.
The company’s official financial reports are the most important because they tell the market where JCET Technology stands now. In 2025, revenue grew and gross margin improved, but net profit declined slightly; in 1Q26, revenue declined slightly while profit improved significantly; JCET Advanced is already profitable, while Changdian Microelectronics is still loss-making; automotive electronics is beginning to shift from construction to customer introduction. The implication of the official reports is that the asset-attribute transition has begun, but the company is still in an investment and ramp-up phase.
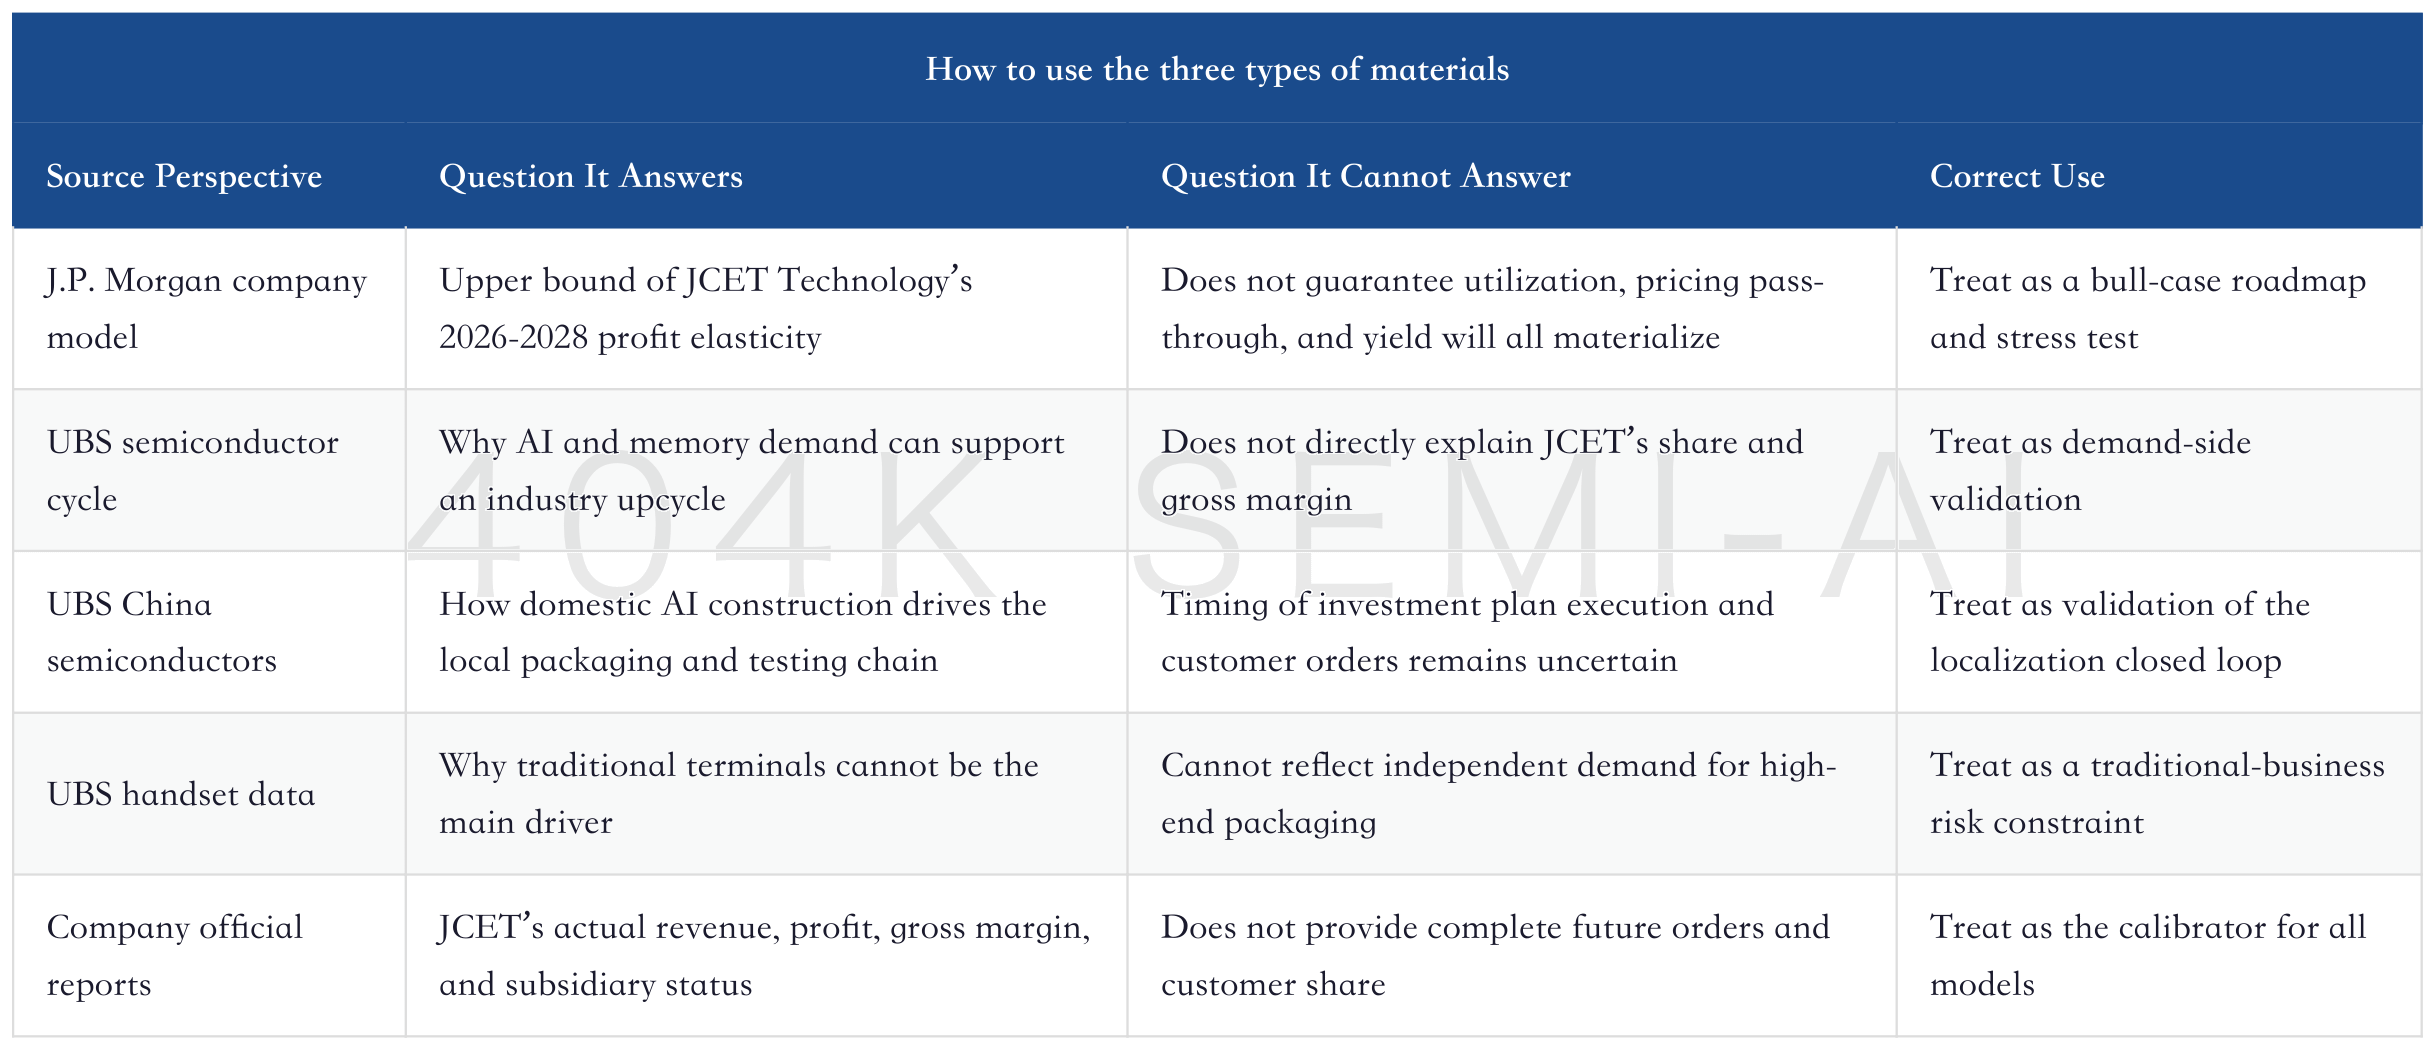
Putting these perspectives together, the investment conclusion for JCET Technology should be “conditional re-rating,” not unconditional linear extrapolation. Industry demand provides direction, sell-side models provide elasticity, and company reports verify reality. As long as all three point to improvement at the same time, the valuation center has a basis to continue moving higher; if the reported numbers fail to cooperate for a long time, even strong industry demand can only support short-term valuation sentiment, not a long-term valuation center.
One detail also needs to be addressed: AI-related revenue is not inherently a high-margin category. Computing, memory, power, connectivity, packaging, and testing can all be classified as AI-related, but different products have different gross margins, capital intensity, customer stickiness, and certification cycles. What really needs to be tracked is not the AI revenue share itself, but whether core gross margin, net margin, ROE, and operating cash flow improve at the same time after the AI revenue share rises. If the share rises but margins do not, the market will view it as low-price expansion; if the share rises and margins also rise, the platform-style valuation will have a firmer foundation.
XIII. Scenario Analysis: 2027 Is the Real Stress-Test Year
For JCET, 2026 will still be a year in which capacity expansion, customer/product ramp-up, and financial-statement validation proceed in parallel. J.P. Morgan expects the company’s capex this year to be around RMB 10.0 billion, above roughly RMB 8.0 billion in the prior year. Capex directed toward high-end applications is not negative in itself, but free cash flow may come under pressure in 2026. What the market really needs to see is whether revenue, gross margin, and cash flow improve simultaneously in 2027.
In the bull case, demand is strong for both domestic AI accelerators and overseas AI peripheral chips; JCET Microelectronics’ 2.5D/3D capacity loads quickly; AI spillover drives memory- and power-related packaging; automotive electronics introduction proceeds smoothly; and material costs can be passed through effectively. In this scenario, revenue grows rapidly, gross margin rises, JCET Microelectronics’ losses narrow quickly, and JCET enters a platform-style re-rating phase.
In the base case, AI demand continues to grow, but the ramp-up of high-end production lines is moderate; depreciation and R&D; investment offset part of the gross-margin improvement; and traditional consumer electronics remain weak. The company delivers revenue growth and some profit recovery, but valuation needs to move with quarterly data.
In the bear case, capex runs ahead of orders; handset and communications businesses weigh on utilization; material and substrate costs are difficult to pass through; and orders slow after inventory rises at domestic AI accelerator customers, expanding losses at JCET Microelectronics. In this scenario, the advanced-packaging narrative remains, but valuation is pulled back toward a cyclical-stock framework.
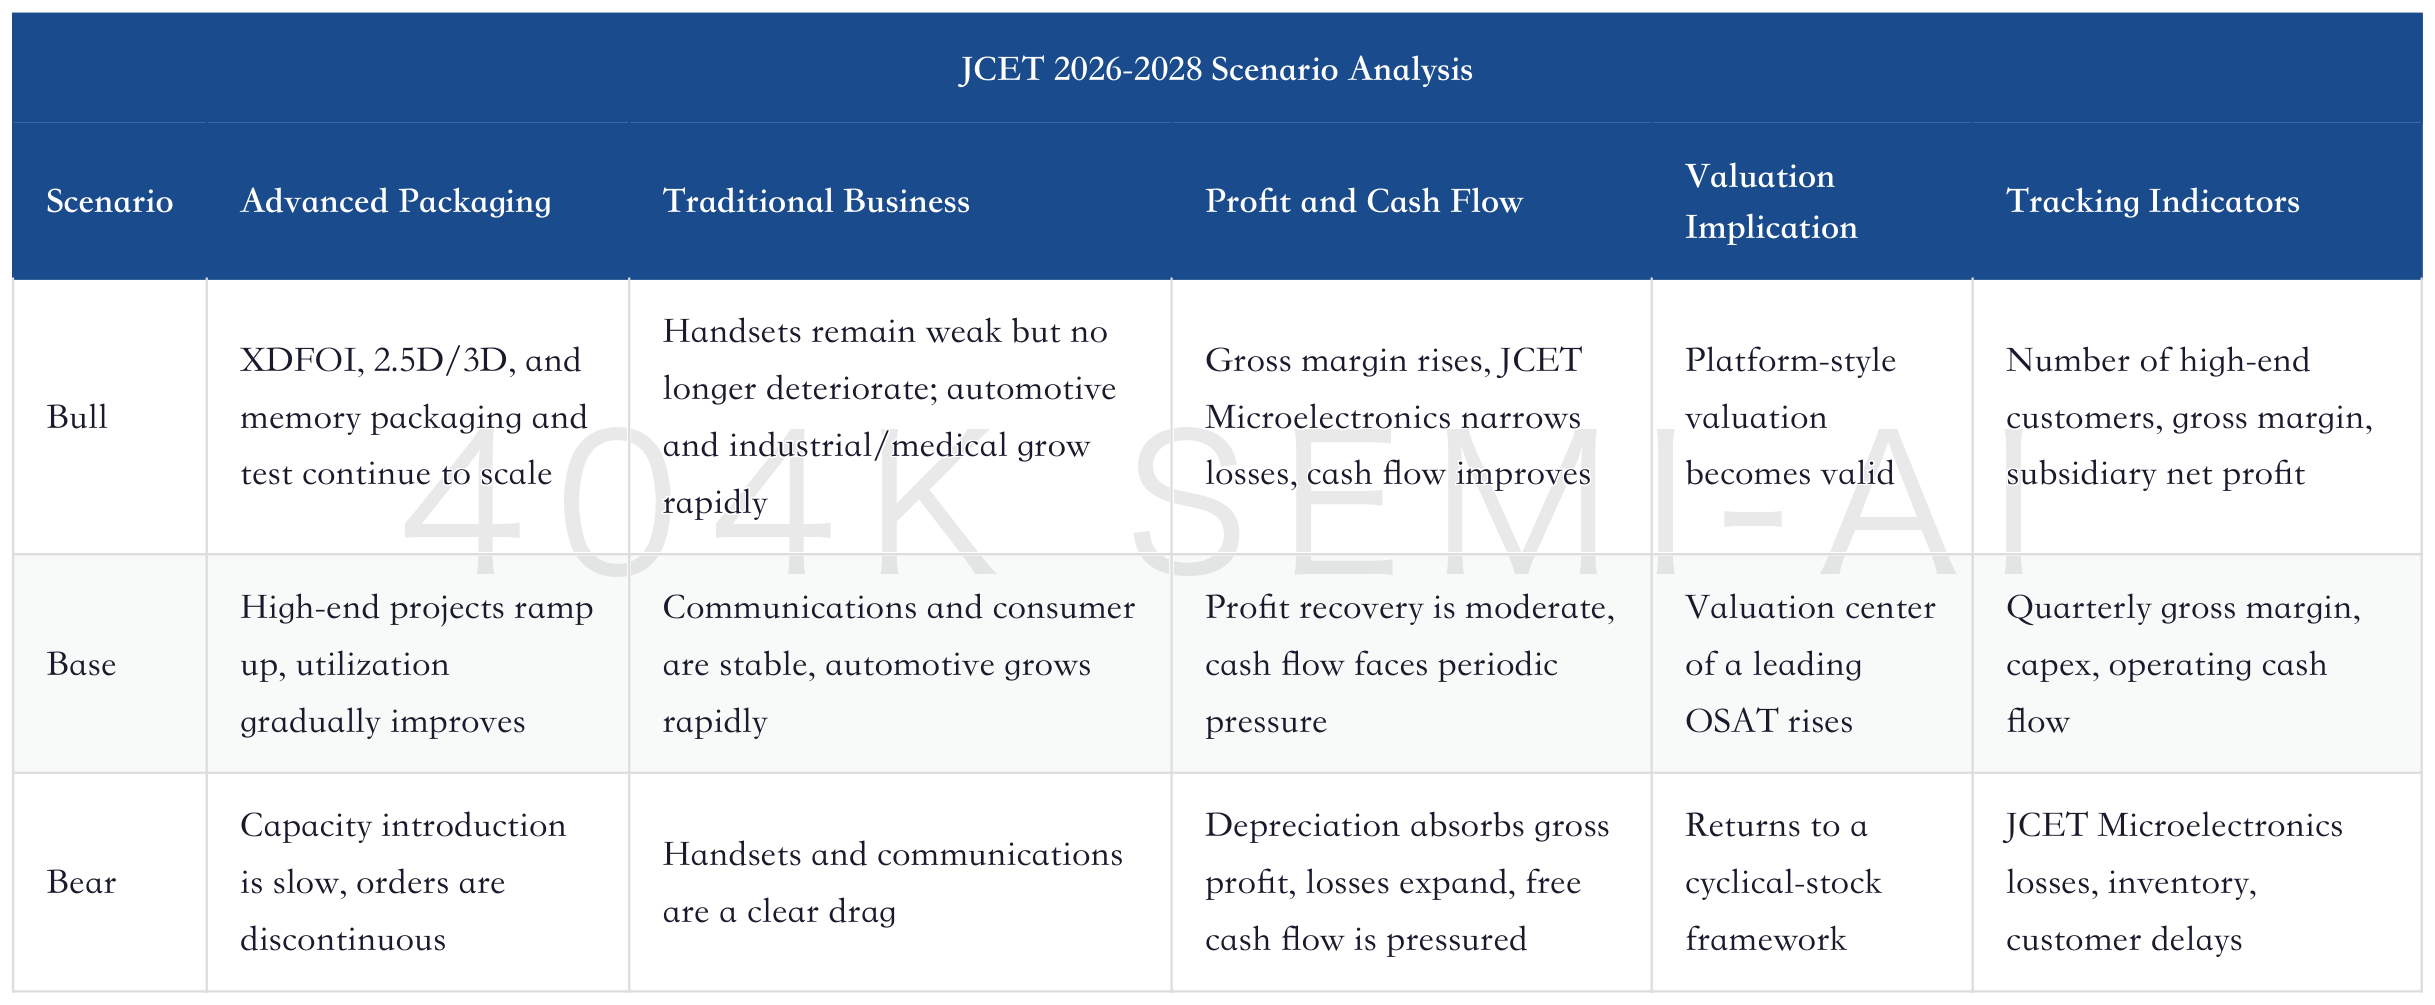
The key point in this scenario table is that JCET’s real inflection point is not revenue, but ROE. Revenue growth can come from consolidation, pricing, the cycle, or new capacity; ROE improvement must come from higher-quality earnings and better asset turnover. If the company can lift its net margin meaningfully from roughly 4% in 2025 while operating cash flow recovers in 2027, the asset re-rating will have a firmer foundation.
XIV. Risks: The Most Dangerous Outcome Is “Revenue Arrives, Profit Does Not”
JCET’s risk is not that the advanced-packaging direction is wrong, but that even the right direction may not generate enough profit.
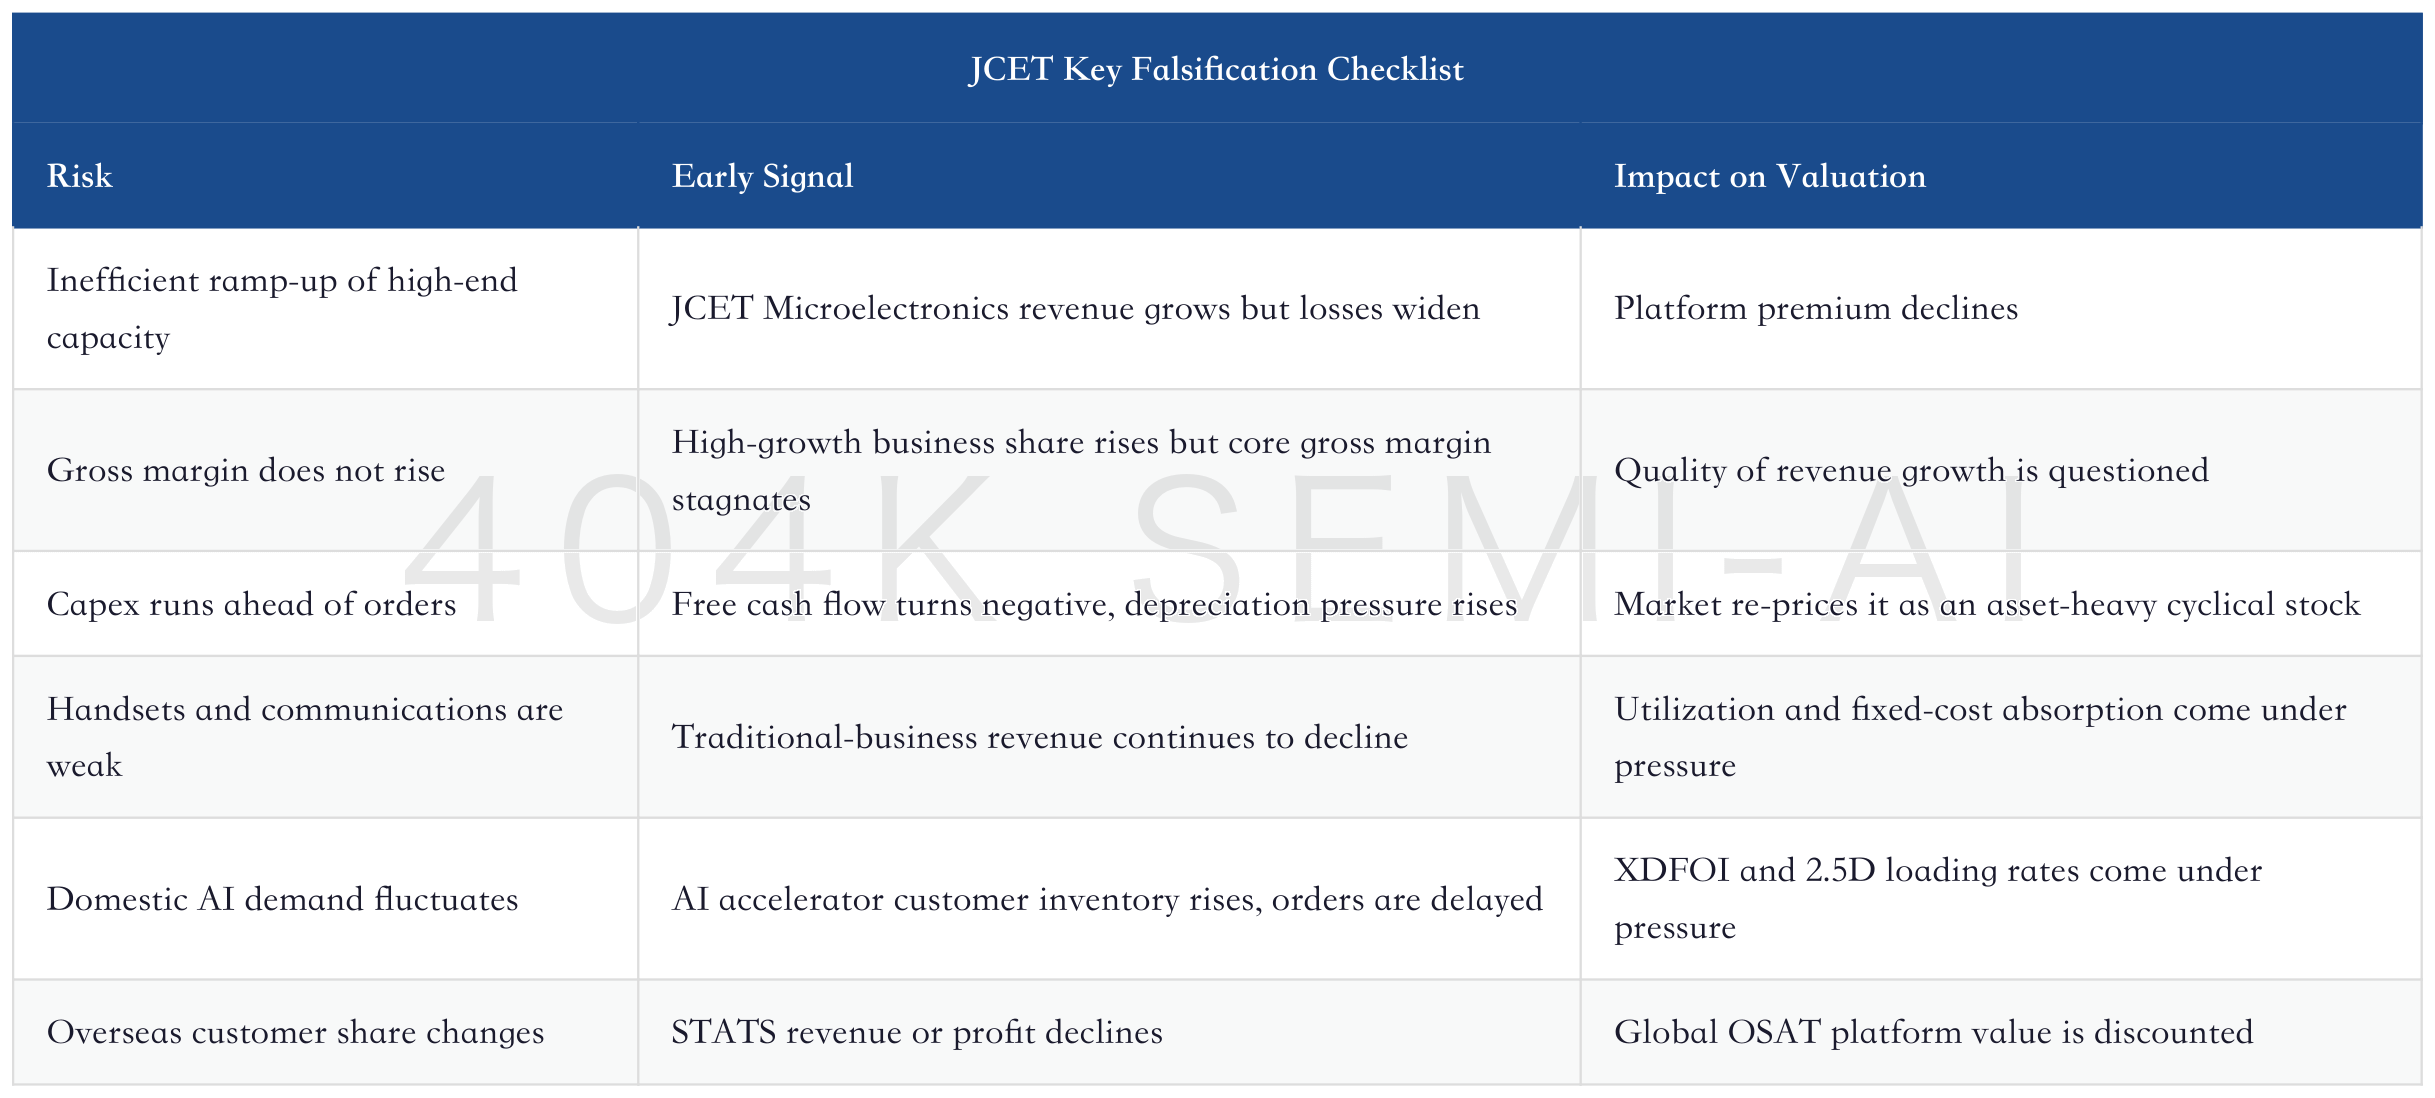
First, advanced packaging may add revenue but not profit. High-end packaging is capital intensive, with heavy initial depreciation and R&D; expenses, slow customer qualification, and slow yield ramp-up. If JCET Microelectronics’ revenue grows but losses widen, it would indicate unsatisfactory capacity loading or yield, and the platform valuation would need to be downgraded.
Second, capex may be too fast. If around RMB 10.0 billion of capex in 2026 runs ahead of customer orders and utilization, it will increase depreciation pressure. Advanced-packaging production lines do not generate profit simply once built; they require customer commitments, product continuity, and stable yield.
Third, handsets and traditional consumer electronics may continue to drag. UBS smartphone data already shows that traditional terminal demand remains weak. JCET still has high exposure to communications and consumer electronics; if traditional businesses continue to weaken, they will offset the incremental contribution from high-growth businesses.
Fourth, domestic AI accelerator demand may fluctuate. Expectations for AI infrastructure investment are strong, but customer inventory, project delays, chip yield, software ecosystems, and server delivery can all affect order timing. Once downstream customers slow down, the impact on packaging and test utilization will be magnified.
Fifth, material, substrate, power, and precious-metal costs. Packaging and test companies have thin gross margins, and material price increases or supply tightness can easily consume the benefits of product-mix improvement. J.P. Morgan believes higher utilization and price pass-through can ease the pressure, but this still requires validation in financial statements.
Sixth, geopolitical and overseas-customer risks. UBS’s dashboard also indicates that the global semiconductor cycle, domestic OSAT competition, and geopolitical factors may affect overseas customer share. JCET’s global footprint is an advantage, but it also means a more complex customer structure.
XV. What to Watch Most Closely Over the Next Four Quarters
JCET’s tracking indicators need to be more rigorous than “the share price went up or down.” Over the next four quarters, seven items deserve priority.
First, watch JCET Microelectronics’ revenue and losses. If revenue scales and losses narrow, that is the strongest positive signal; if revenue scales but losses widen, investors should watch for an inefficient ramp-up of high-end capacity.
Second, watch core gross margin. Core gross margin was 13.95% in 2025, and J.P. Morgan’s model projects gross margin reaching 16.5% in 2028. This improvement path must be validated quarter by quarter, not only when the annual report is released.
Third, watch the share of high-growth businesses. In 2026Q1, automotive electronics, computing electronics, and industrial and medical electronics together exceeded 45%. If this share continues to rise, it means the structural upgrade has not stopped.
Fourth, watch advanced-packaging shipment volume and product disclosure. In 2025, advanced-packaging shipments grew 14.00%, faster than traditional packaging. If the gap continues to widen, it would show that product-mix improvement remains underway.
Fifth, watch capex and operating cash flow. Capacity expansion is necessary, but cash flow cannot remain under pressure for a long period. If free cash flow is negative in 2026, investors must see a path to improvement in 2027.
Sixth, watch STATS and overseas customers. Overseas AI peripheral chips, PMIC, connectivity, and memory demand are important variables that distinguish JCET from purely domestic packaging and test companies.
Seventh, watch dedicated automotive-electronics lines. Automotive-grade lines need to move from line qualification to mass-production introduction, with customer certification, yield, and utilization gradually ramping up. This does not determine peak upside, but it determines long-term earnings quality.
These tracking items can be organized into a simple dashboard. JCET Microelectronics’ P&L; validates the ramp-up of high-end advanced packaging: positive signals are revenue scaling and narrowing losses; negative signals are revenue below expectations or widening losses. Core gross margin validates product mix and price pass-through: a positive signal is sequential quarterly improvement; a negative signal is high-growth business scaling while gross margin stagnates. The share of high-growth businesses validates the migration in asset attributes: a positive signal is a continued increase in the share of computing, automotive, and industrial/medical; a negative signal is a renewed rise in the share of traditional communications and consumer.
Advanced-packaging shipments validate product upgrades: a positive signal is growth that remains faster than traditional packaging; a negative signal is a slowdown in advanced-packaging growth. Operating cash flow and capex validate the quality of capacity expansion: a positive signal is stronger cash-flow coverage; a negative signal is persistently negative free cash flow. STATS and overseas customers validate global platform attributes: a positive signal is an increase in overseas AI peripheral orders; a negative signal is weakening overseas revenue and profit. Automotive-electronics introduction validates the foundation in high-reliability applications: a positive signal is improved customer certification and line utilization; a negative signal is prolonged losses after line qualification.
XVI. Conclusion: JCET Has Secured the Ticket; the Profit Answer Sheet Is Not Yet Complete
JCET’s core change is not the addition of an advanced-packaging concept, but that multiple pieces of evidence are pushing it from a traditional OSAT leader toward an AI advanced-packaging delivery gatekeeper. UBS’s semiconductor-cycle report shows that AI, memory, and server-related chips are forming an industry-level upcycle. Expectations for China AI infrastructure investment show that the domestic compute loop requires local advanced packaging and testing. J.P. Morgan’s company model quantifies this chain into a path for revenue, gross-margin, and profit-margin improvement. The company’s own 2025 annual report and 2026Q1 results show that the share of high-growth businesses is rising and profit growth is starting to outpace revenue growth.
But this is still not an unconditional bullish call. JCET still has around 60% of revenue exposed to communications and consumer electronics, while handset terminals are not strong; advanced packaging requires large capex, with depreciation and R&D; front-loaded; JCET Microelectronics is still loss-making; automotive electronics has only just entered the introduction stage after line qualification; and material costs and overseas-customer risks will still affect profit elasticity.
A more prudent investment judgment is therefore: JCET has moved from a traditional packaging-and-test cyclical stock into a phase of asset-attribute transition, and its valuation center has a basis to move higher, but this must be confirmed jointly by gross margin, ROE, narrowing losses at JCET Microelectronics, and cash flow. If these indicators improve together in 2026-2027, JCET has the opportunity to become one of the most important re-rating examples in China’s advanced-packaging chain. If revenue growth does not translate into earnings quality, the market will again price it as a cyclical packaging-and-test company.
In one sentence: JCET has already secured its ticket to the AI advanced-packaging era; what it needs to prove next is not “whether it can do it,” but “whether it can make money sustainably.”
References
Jiangsu Changjiang Electronics Technology Co., Ltd. 2025 Annual Report.
Jiangsu Changjiang Electronics Technology Co., Ltd. 2026 First Quarterly Report.
Goldman Sachs, AI and China Semis Capacity expansion drives growth ahead; raising TP of JCET, Huafeng Test & Control, and Hwatsing, July 2, 2026.
UBS, China Equity Strategy, Guide to the slow bull, May 19, 2026.
UBS, Going global dashboard, May 20, 2026.
UBS, Global IO Smartphones, April 2026 Sell-Through, June 1, 2026.
UBS, Global IO Semiconductors, Cycle Update, June 9, 2026.
UBS, China Semiconductor First Read, June 10, 2026.
J.P. Morgan, JCET: Strong AI demand and capacity upgrades to drive long-term upside, June 16, 2026.JCET Deep-Dive Update: Goldman Sachs Raises Target Price to RMB125; How AI Chip OSAT Investment Flows Through R&D; Expense and 2030E Discounted Valuation
目录
Too Long; Didn’t Read
I. What Goldman Sachs Actually Changed This Time: Target Price Doubled, Rating Not Upgraded
II. JCET’s New Asset Attribute: From OSAT Leader to AI Packaging and Testing Delivery Gateway
III. The Base Case from Official Financials: Revenue Is Not Perfect, but the Mix Has Already Shifted
IV. The Handset Cycle Is Not the Answer; AI and Memory Are the Main Line
V. The Domestic Compute Closed Loop: JCET Sits at the “Last Mile of Delivery”
VI. J.P. Morgan’s Bull-Case Model: The Key Is Not the Target Price, but the Profit Bridge
VII. Technology Ticket: How Advanced Packaging Turns into Profit
VIII. JCET Microelectronics: The Variable with the Greatest Valuation Elasticity
IX. STATS, SanDisk Semiconductor, and Automotive Electronics: Not the Main Narrative, but They Determine Profit Depth
X. Competitive Landscape: Platform Breadth Is an Advantage, Profit Elasticity Is the Constraint
XI. Valuation Divergence: Three Worldviews Determine Three Prices
XII. How to Use Sell-Side Divergence: Do Not Simply Take the Most Optimistic Model
XIII. Scenario Analysis: 2027 Is the Real Stress-Test Year
XIV. Risks: The Most Dangerous Outcome Is “Revenue Arrives, Profit Does Not”
XV. What to Watch Most Closely Over the Next Four Quarters
XVI. Conclusion: JCET Has Secured the Ticket; the Profit Answer Sheet Is Not Yet Complete
References
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Goldman Sachs raised its target price for JCET to RMB125 while maintaining a Neutral rating. The core change is not a turn bullish, but a shift in valuation anchor from near-term P/E to discounted 2030E P/E. JCET has entered a re-rating phase as an AI chip OSAT, but whether R&D; expense, depreciation, and high-end capacity ramp can convert into gross margin and cash flow is the decisive issue over the next 12-18 months.
Too Long; Didn’t Read
What Goldman really raised is valuation duration. The new model shifts JCET from a near-term earnings trade to long-duration platform pricing, lifting the target price to RMB125. The rating remains Neutral, indicating the market still needs evidence on expense, depreciation, and gross margin delivery; if advanced packaging gross margin does not rise, this duration will be compressed again.
R&D; expense weighing on profit does not mean the investment is ineffective. Goldman attributes profit pressure over the next two years to AI chip OSAT R&D; and yield investment. The key metric is not revenue growth, but whether advanced packaging can lift gross margin; if high-end capacity only brings depreciation, valuation will revert to the traditional OSAT framework.
The financials already show structural upgrading. 2025 revenue was RMB38.871bn, and 2026Q1 attributable net profit rose 42.74% YoY. This shows product mix improvement is beginning to flow into the income statement, but continuity depends on subsequent quarters.
JCET Microelectronics offers the largest upside. This high-end advanced packaging asset is still moving from customer introduction to ramp-up, with revenue just above RMB0.2bn and still loss-making. If revenue scales while losses narrow, the platform re-rating will be more robust; if investment appears without gross-margin improvement, the market will revert to a heavy-asset OSAT discount.
Sell-side divergence reflects three worldviews. Goldman assigns a long-term valuation but maintains Neutral, J.P. Morgan emphasizes earnings acceleration, and UBS emphasizes localization and overseas business. They are not simply more or less optimistic; they are pricing JCET across different time horizons.
Watch four numbers over the next four quarters. JCET Microelectronics P&L;, advanced packaging gross margin, capex-backed orders, and operating cash-flow quality are the hard evidence for whether JCET can upgrade into an AI advanced packaging platform. Looking only at target prices and themes risks missing the real financial verification points.
I. What Goldman Sachs Actually Changed This Time: Target Price Doubled, Rating Not Upgraded
The most interesting part of Goldman’s update is the tension between target price and rating. The target price was raised sharply from RMB50.9 to RMB125, but the rating remains Neutral. This is not simply “bullish but unwilling to say so”; rather, after extending JCET’s valuation duration, Goldman is still restrained on near-term earnings delivery.
JCET Deep Dive: From Cyclical OSAT to AI Advanced Packaging Gateway; How Chiplet, XDFOI, and Domestic Compute Re-rate the OSAT Leader
This is connected to the judgment in the previous deep dive on JCET. JCET should no longer be viewed only as a handset OSAT cycle stock, but it has not yet fully secured the stable valuation of an advanced packaging platform. Goldman’s new model states this intermediate condition more clearly: 2026-2027E profit pressure comes from higher R&D; expense, 2028E profit upgrades come from AI chip advanced packaging revenue and gross-margin improvement, and the valuation method directly shifts to discounted 2030E P/E.
JCET Deep-Dive Update: AI Cycle, Localization, and OSAT Asset Re-rating
The signal from this table is direct: Goldman has not denied the asset re-rating brought by AI advanced packaging, and has even acknowledged longer duration through discounted 2030E P/E. But it also puts near-term profit pressure upfront, reminding the market that advanced packaging is not an asset-light story. It is a heavy-asset platform jointly determined by R&D;, equipment, materials, yield, customer qualification, and capacity utilization.
This is also JCET’s most realistic current contradiction. Looking only at the RMB125 target price can make it seem Goldman has suddenly turned fully bullish; looking only at the Neutral rating can lead to the mistaken view that Goldman lacks confidence in JCET. A more accurate reading is that Goldman recognizes JCET has entered the core beneficiary chain of AI chip OSAT and domestic semiconductor capacity expansion, but believes this chain must pass through expense and depreciation before becoming a stable high-margin asset.
On valuation, Goldman’s 46x discounted 2030E P/E cannot be directly compared with traditional OSAT P/E. It assumes 2031E net profit growth, operating margin approaching 10%, and a higher share of AI advanced packaging revenue, then applies platform pricing to 2030 profit and discounts it back to 2027. The benefit of this method is that it recognizes the long-term value of an advanced packaging platform. The drawback is also clear: the model is highly sensitive to long-term revenue, gross margin, and expense ratio. Any deviation in one variable can materially change the discounted target price.
The previous judgment on JCET had already moved the question from “OSAT industry cycle” to “advanced packaging delivery gateway.” The incremental value of this material is not another repetition of XDFOI, Chiplet, or 2.5D, but the connection of four external pieces of evidence: Goldman’s valuation-method shift, J.P. Morgan’s profit bridge, UBS’s localization and overseas-business framework, and the application-mix improvement already visible in the company’s official financials.
The first piece of evidence comes from aggregate semiconductor demand. In its June semiconductor cycle report, UBS shifted the growth focus of global semiconductor revenue from traditional endpoints to AI cloud, memory, and server CPUs, and emphasized that AI cloud-related chips will continue to rise as a share of total semiconductor revenue. The implication of this framework is that AI is no longer just a GPU line; it is pulling HBM, DRAM, NAND, CPU, packaging, testing, and equipment into a new capacity-expansion cycle together.
The second piece of evidence comes from expectations for China’s AI infrastructure investment. UBS’s June First Read on China semiconductors noted the market’s focus on a roughly RMB2tn five-year AI buildout plan. On an annualized basis of about RMB400bn, GPUs/AI accelerators, networking, and storage would constitute the main hardware spending. In UBS’s estimate, if 50% is allocated to GPUs/AI accelerators and 20% to networking and storage, the revenue elasticity would be substantial for major domestic AI accelerator companies and related semiconductor manufacturing chains. JCET is placed within the advanced packaging and testing beneficiary chain, showing that its re-rating is not only about the company’s own capacity expansion, but also connected to the closed-loop mass production of domestic AI chips.
The third piece of evidence comes from J.P. Morgan’s model for JCET itself. Its June 16 company report upgraded JCET from Neutral to Overweight, with the core rationale that AI-related revenue, capex efficiency, and high-end capacity utilization may improve together. The report quantifies the path for revenue, earnings, AI-related revenue share, and gross margin, with specific figures shown later in the model table. The value of this model is not a static target price, but the way it decomposes JCET’s earnings verification path over the next two years.
The direction from this table is direct: JCET’s investment question is no longer “whether there is an AI packaging story,” but “whether AI packaging can lift margins and ROE.” Looking only at industry space will underestimate the company’s platform value; looking only at target prices and themes will overestimate earnings leverage during the investment phase.
II. JCET’s New Asset Attribute: From OSAT Leader to AI Packaging and Testing Delivery Gateway
OSAT companies have historically been placed at the back end of the semiconductor value chain, and their valuation logic has also been more cyclical. The reason is practical: OSAT revenue follows customer orders, capacity utilization determines gross margin, equipment depreciation and materials costs determine earnings leverage, and once end markets enter destocking, OSAT companies are the most exposed to order cuts and pricing pressure.
What AI changes is the position of OSAT within the system. High-performance computing chips are no longer a contest of single-die performance, but a coordination of multiple compute dies, HBM, I/O, power delivery, thermal management, substrates, testing, and system yield. Advanced packaging is not simply “wrapping the chip”; it determines bandwidth, power consumption, interconnect length, thermal efficiency, reliability, and delivery time. The higher the compute power, the closer packaging moves to the architecture layer; the more multi-chip heterogeneous integration there is, the closer testing becomes to yield insurance.
JCET deserves to be reassessed because it has four entry points at the same time: first, it is one of the largest OSAT leaders by revenue scale in mainland China; second, STATS ChipPAC brings overseas customers and a global manufacturing footprint; third, XDFOI, 2.5D/3D, FCBGA, CPO, silicon photonics, memory packaging and testing, and testing capabilities form a high-end technology portfolio; fourth, automotive electronics, industrial and medical, and high-performance computing applications are improving the quality of its revenue mix.
This does not mean JCET has already become a TSMC-style advanced packaging platform. TSMC’s CoWoS, SoIC, and wafer-manufacturing coordination provide extremely strong customer stickiness and process-synergy advantages. JCET remains an OSAT company, and it must prove platform value through customer introduction, capacity utilization, yield, gross margin, and cash flow. But it also cannot continue to be viewed as ordinary OSAT capacity, because AI/HPC and domestic compute are turning OSAT from a back-end cost item into a system delivery node.
This table also explains why the market is sharply divided on JCET. The conservative camp sees low gross margin, heavy capex, and continued weakness in traditional consumer electronics. The constructive camp sees rising AI-related revenue share, advanced packaging platformization, the domestic compute closed loop, and margin upside. Neither side is entirely wrong. The key is which set of evidence proves stronger over the next few quarters.
III. The Base Case from Official Financials: Revenue Is Not Perfect, but the Mix Has Already Shifted
JCET’s 2025 financial performance was not a perfect report card. The company reported revenue of RMB 38.871 billion, up 8.09% YoY; net profit attributable to the parent of RMB 1.565 billion, down 2.75% YoY; core business gross margin of 13.95%, up 1.07 percentage points YoY; and R&D; spending of RMB 2.086 billion, up 21.37% YoY. This shows revenue recovery and margin improvement, but R&D;, depreciation, materials, and new-business ramp-up are still weighing on profit.
The more valuable signal is the change in mix. Communications and consumer electronics remained JCET’s base in 2025, but the growth slope has shifted to high-performance computing, automotive, and high-reliability applications. The key application-mix figures are better viewed in a table, because they correspond to two very different valuation logics: traditional end markets determine base volatility, while high-growth applications determine the platform premium.
2026Q1 further validated this trajectory. The company reported revenue of RMB 9.171 billion, down 1.76% YoY; net profit attributable to the parent of RMB 290 million, up 42.74% YoY; ex-non-recurring net profit attributable to the parent of RMB 265 million, up 37.03% YoY; and net operating cash flow up 55.44% YoY. More importantly, automotive electronics, computing electronics, and industrial and medical electronics together exceeded 45% of revenue, up 7 percentage points from the same period last year. Slightly lower revenue with materially higher profit indicates that product mix and utilization improvements have started to flow into the income statement.
Production and shipment volumes also support this judgment. In 2025, the company sold 18.019 billion advanced-packaging units, up 14.00% YoY; 39.343 billion traditional-packaging units, up 7.80% YoY; and 9.164 billion test units, up 11.25% YoY. Advanced packaging grew faster than traditional packaging, showing the mix upgrade is not just a narrative.
The subsidiary level reveals JCET’s contradiction more clearly. Jiangyin Changdian Advanced Packaging generated 2025 revenue of RMB 2.158 billion and net profit of RMB 585 million. The annual report attributed this to rising customer demand, full orders, higher capacity utilization, and increased value from integrated wafer-level advanced packaging and testing services. Changdian Microelectronics generated revenue of RMB 204 million and a net loss of RMB 192 million, because high-end advanced-packaging products had entered mass production, capacity utilization had begun to ramp, and the company increased R&D; and resource investment for future scaled mass production. Changdian Automotive Electronics was still in the preparation phase in 2025 and generated losses, but its line was formally commissioned at year-end, and product mass-production introductions will accelerate in 2026.
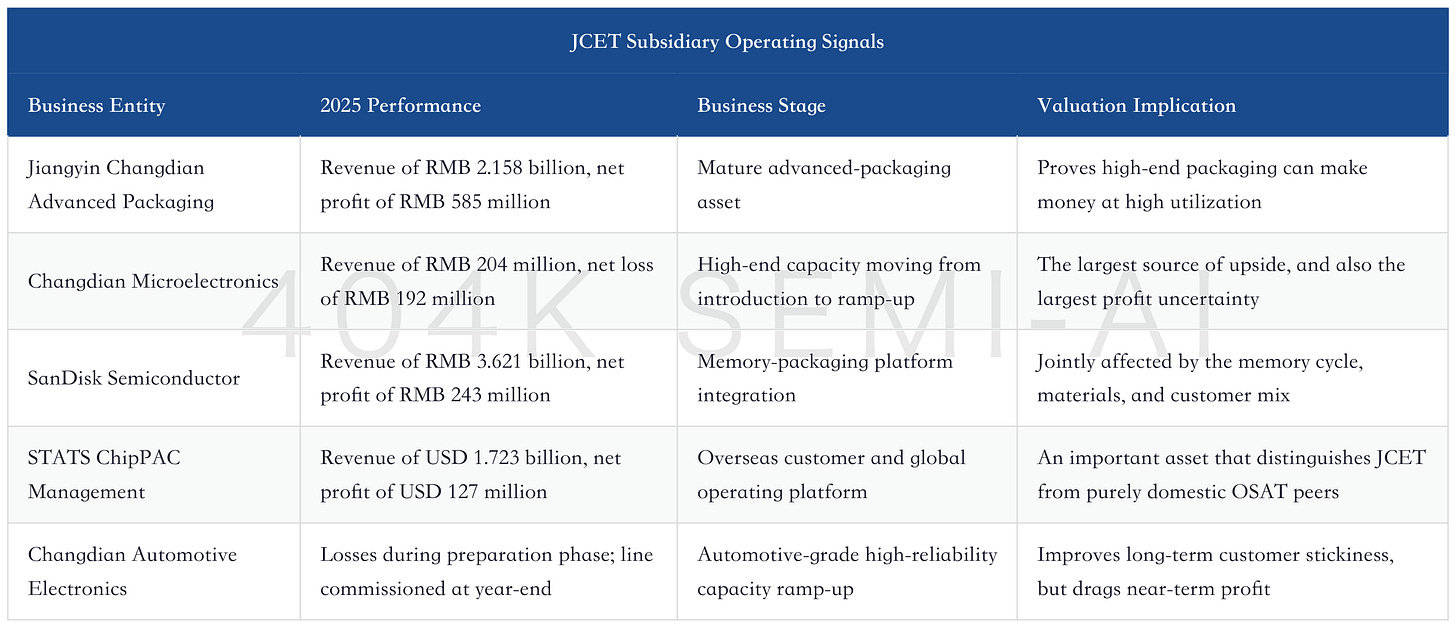
The conclusion from this dataset is: JCET already has profitable advanced-packaging assets, and it also has high-end new capacity that is still burning cash during ramp-up. The market should neither look only at the profit of Changdian Advanced nor focus only on the losses of Changdian Microelectronics. The real question is whether new capacity over the next two years can replicate the profitability curve of mature assets.
IV. The Handset Cycle Is Not the Answer; AI and Memory Are the Main Line
UBS’s smartphone sell-through report provides an important reminder: traditional handset end demand is not strong. In April 2026, global smartphone sell-through was about 87.5 million units, down 8.3% MoM and 9.7% YoY, the lowest level since May 2020 and the fifth consecutive month of YoY decline. China, India, the U.S., Europe, and other regions all declined YoY in April. Apple performed relatively better, but the China Android chain and some emerging-market OEMs were under clear pressure.
This is critical for JCET. Communications and consumer electronics together accounted for about 60% of the company’s 2025 revenue. If handsets and traditional consumer electronics do not recover, the traditional OSAT base will struggle to deliver strong revenue leverage. Precisely because of this, JCET’s current rerating cannot be built on “the handset replacement cycle returning”; it must be built on sustained improvement in higher value-added applications such as AI/HPC, memory, automotive, and industrial/medical.
UBS’s semiconductor cycle report provides evidence from the other side. AI cloud-computing-related chips are expected to rise from about 34% of semiconductor revenue in 2026 to about 48% in 2027; memory revenue has very strong leverage in 2026 and 2027; and non-memory semiconductors will also benefit from AI accelerators, server CPUs, networking, power, and edge computing. For OSAT companies, this is not a simple end-market recovery, but an increase in product complexity and packaging/test content.
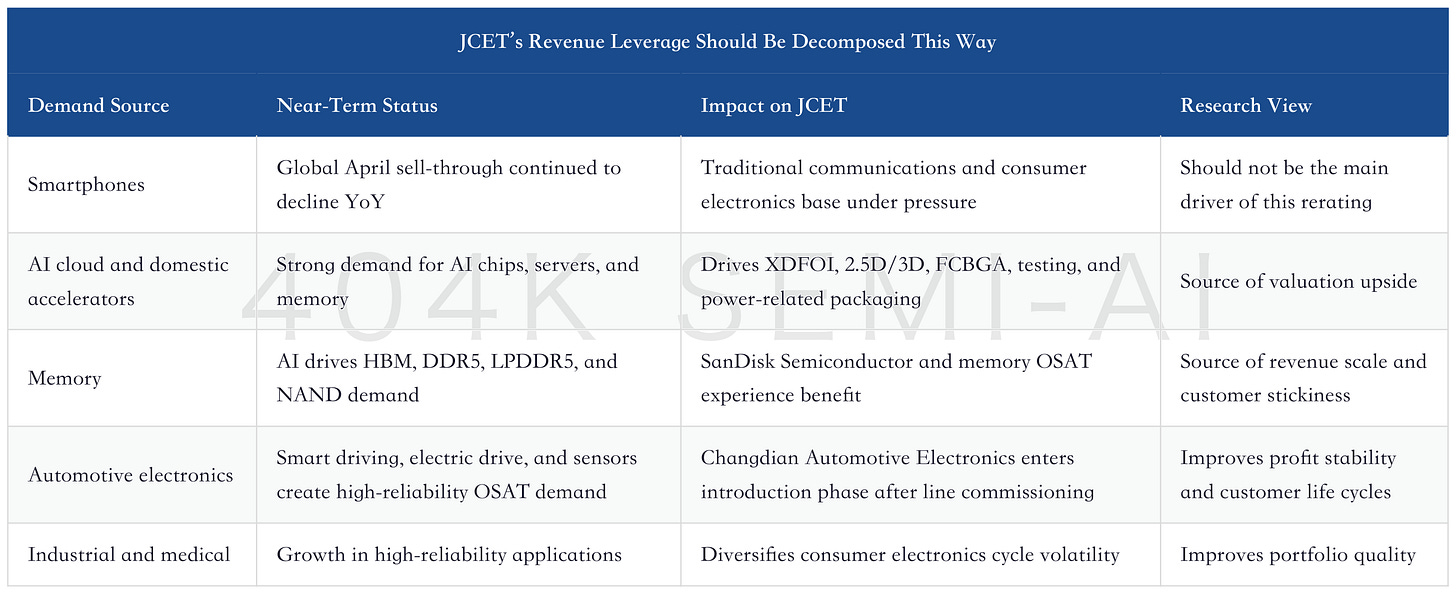
One easily overlooked point is that AI’s pull-through for OSAT does not occur only in GPUs or AI ASICs themselves. It also transmits to memory, PMICs, networking chips, optoelectronic packaging, power modules, test services, and data-center power architectures. JCET’s 2025 R&D; spending referenced directions including high-performance computing, next-generation system-in-package SiP, high-reliability automotive electronics, power energy, CPO, glass substrates, large-size FCBGA, PLP, and 800V HVDC electrical architecture, showing that the company’s technology investment already covers multiple value-migration points around AI systems.
Second Upgrade to the AI Hardware Cycle: The Asian Tech Rerating of Memory, HBM, PCB, and MLCC
From this perspective, JCET is not a single AI accelerator beta, but a composite asset combining “rising AI semiconductor complexity + domestic OSAT supply + spillover from memory and power.” Whether this combination materializes depends on whether the company can integrate multiple lines into profitable capacity, rather than merely running scattered projects.
V. The Domestic Compute Closed Loop: JCET Sits at the “Last Mile of Delivery”
UBS’s China semiconductor report focuses market attention on the industrial implications of China’s AI infrastructure investment plan. Its analytical framework is instructive: if roughly RMB 400 billion in annualized capex allocates half to GPUs/AI accelerators and another 20% to networking and memory, then domestic AI accelerators, wafer manufacturing, packaging and testing, test equipment, memory, networking chips, and power management will all see demand resonance.
For JCET, the key to this chain is not “how large the planned amount is,” but that mass production of domestic AI accelerators requires complete back-end capability. For domestic AI chips to move from design blueprints to deliverable server components, they must pass through wafer fabrication, bumping, redistribution layers, advanced packaging, reliability validation, testing, system-level validation, and supply-chain coordination. Packaging and testing are not auxiliary steps; they are the last mile that determines whether chips can be delivered reliably.
The Frenzied Philadelphia Semiconductor Index: CoWoS, HBM, CPU, Liquid Cooling, Gas Turbines, A
JCET’s position in this chain can be divided into three layers.
The first layer is domestic high-end packaging supply. The XDFOI chiplet high-density multidimensional heterogeneous integration process series has entered mass production, targeting applications such as high-performance computing, artificial intelligence, communications, and automotive electronics. 2.5D/3D packaging, FCBGA, and high-density system-in-package are capabilities that domestic AI accelerators must fill in as they move from single chips to multi-chip systems.
The second layer is testing and yield management. AI chips have high unit value, and packaging failure costs are even higher. The more complex the advanced packaging, the greater the need for known-good die, post-packaging reliability validation, and system-level testing. JCET’s testing business, integrated wafer-level packaging and testing capability, and global customer experience will amplify in value during high-end product ramp-up.
The third layer is global customers and overseas capacity. Domestic compute demand is incremental, but overseas HPC, memory, and power-related demand is also growing. JCET’s STATS ChipPAC, Korea plants, and Singapore footprint mean the company is not merely an asset in China’s domestic supply chain; it also has the opportunity to absorb spillover from global AI demand.
This layer of logic also explains why JCET’s rerating should not be judged only by near-term EPS. The value of the domestic compute closed loop requires the company to invest ahead of time in technology, equipment, processes, customer certification, and capacity. Early-stage profit being suppressed by depreciation, R&D;, and low utilization does not mean the investment is ineffective. But if the ramp-up period is too long, customer orders are discontinuous, or yields are unstable, the advanced-packaging narrative will also become a profit trap.
VI. J.P. Morgan’s Bull-Case Model: The Key Is Not the Target Price, but the Profit Bridge
The most valuable part of J.P. Morgan’s June report is not the higher target price, but its clearer decomposition of JCET Group’s 2026-2028 profit bridge.
The model forecasts JCET revenue of RMB44.876bn in 2026, RMB52.944bn in 2027, and RMB61.195bn in 2028; adjusted net profit of RMB2.253bn, RMB3.650bn, and RMB4.896bn, respectively. Under this path, 2026-2028 revenue CAGR is about 16%, while earnings CAGR is about 46%. Earnings growth is materially faster than revenue growth, underpinned by assumptions of mix improvement, higher utilization, material cost pass-through, and a rising share of high-end packaging revenue.
The two most important ratios in the report are: AI-related revenue at about 21% of total revenue in 2025, potentially rising to about 40% in 2028; and gross margin rising from about 14.1% in 2025 to about 16.5% in 2028. If these two ratios are delivered, JCET’s valuation framework will change, because the story will no longer be only revenue scale growth, but margin expansion driven by higher-end revenue.
This table should not be treated mechanically as a conclusion, but it can be used as a stress test. For the bull case to hold, at least three linked effects need to be visible: a rising AI-related revenue mix driving higher utilization of high-end capacity; higher utilization and material cost pass-through driving gross margin expansion; and gross margin expansion covering R&D; and depreciation, ultimately improving net margin and cash flow.
Conversely, if capex is delivered in 2026 and revenue also grows, but gross margin does not rise, free cash flow remains negative, and losses at JCET Microelectronics do not narrow, then the market will discount the 2027 earnings elasticity embedded in the model. In other words, J.P. Morgan’s model is not the “answer”; it is the roadmap JCET must deliver against over the next two years.
VII. Technology Ticket: How Advanced Packaging Turns into Profit
JCET’s technology ticket is not a single term, but a set of capabilities. XDFOI, 2.5D/3D, FCBGA, CPO, silicon photonics, memory packaging, power SiP, and complex testing each correspond to different revenue cadences and profit curves. Lumping them all under the label of “advanced packaging” makes the analysis shallow.
Deep Dive on AI Packaging: As HBM4E Moves Toward 2.5TB/s, How Bridge Interconnects, Vertical Power Delivery, and Thermal Paths Rewrite Hardware Competition
The value of XDFOI lies in turning multi-chip heterogeneous integration into a reusable platform. High-performance computing chips are moving from single large dies toward chiplet architectures, with increasingly high connection density among compute, I/O, memory, analog, power delivery, and optoelectronic modules. If a packaging platform can stably support multi-chip interconnect, redistribution, thermal management, and reliability, it is not merely processing capability, but part of system design. JCET’s annual report discloses that its XDFOI chiplet high-density multidimensional heterogeneous integration process series has entered mass production, indicating that it has at least crossed the first threshold from R&D; to commercialization. The next things to track are not whether the platform exists, but how many customers it has, how many products are in mass production, and how many individual products can contribute gross profit.
The value of 2.5D/3D lies in bringing AI accelerators closer to high-bandwidth memory. For AI chips, compute is not the only bottleneck; memory bandwidth, package interconnect, power density, heat dissipation, and yield can all become system constraints. As 2.5D/3D packaging moves higher-end, the difficulty of equipment, process, materials, substrates, and testing rises, and capex also becomes heavier. J.P. Morgan is positive on JCET’s 2.5D/3D capacity ramp, but this is also a source of financial pressure. If customer orders are continuous and product yield is stable, high-end packaging can lift ASP and gross margin; if line changeovers are frequent and customer adoption is slow, depreciation will absorb profit first.
FCBGA is the foundation of high-performance computing packaging. Large package size, more substrate layers, higher I/O density, and more demanding thermal management all increase packaging and testing complexity. JCET’s annual report notes that the company has many years of experience in large FCBGA packaging and testing technology, and continues to advance ultra-large-size devices, high-end panel-level packaging, and high-density system-in-package directions. FCBGA does not create a hot narrative as easily as CPO, but it is closer to current revenue and product upgrades, making it a practical indicator for judging whether JCET can take on AI/HPC customer projects.
CPO and silicon photonics are more like long-dated options. The company disclosed customer sample delivery for CPO products and related validation progress for silicon photonics engine products. AI data-center networks are evolving from 800G and 1.6T toward higher bandwidth, making optoelectronic integration, low-power interconnects, and switch-chip packaging increasingly important. But the current revenue contribution from these areas is limited, so long-term technologies should not be fully capitalized into the profit model too early. A more reasonable treatment is to view CPO and silicon photonics as items to observe for valuation upside, rather than core assumptions for 2026 profit.
Testing capability is often underestimated. Complex packaging does not end with simply testing the finished product; it runs through the whole process, from wafer-level known good die, packaging process control, and post-packaging reliability to system-level validation. AI accelerators, automotive electronics, and power modules carry high value, and any failure at any stage amplifies cost. If JCET can turn packaging and testing into an integrated service, both customer stickiness and value per project will rise. Jiangyin JCET Advanced Packaging recorded sharp revenue and profit growth in 2025, and the annual report cited higher value from integrated wafer-level advanced packaging and testing services. This is a sample case of a technology ticket converting into profit.
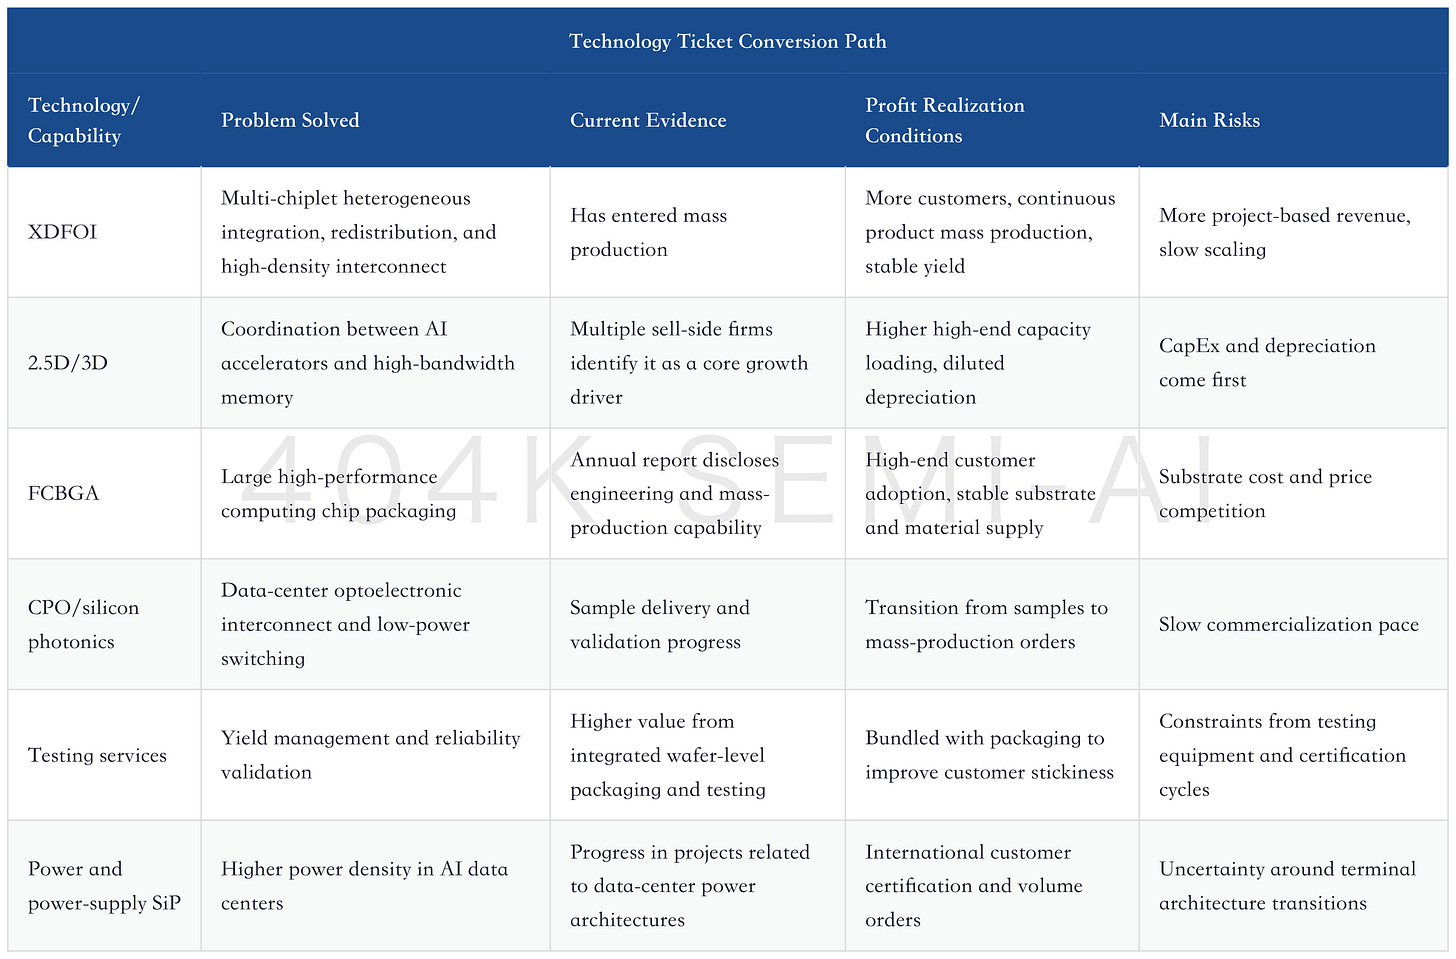
The investment implication of this table is clear: not every technology direction deserves the same valuation. XDFOI, 2.5D/3D, and FCBGA are closer to medium-term profit; CPO, silicon photonics, and glass substrates are closer to long-dated options; testing and power packaging are underlying capabilities that improve customer stickiness and earnings quality. If JCET wants to evolve from an OSAT leader into a platform asset, it must move these capabilities from R&D; and sample stages into customer projects, mass-production revenue, and gross-margin improvement.
Therefore, tracking the technology ticket cannot rely only on news flow. More effective indicators are: the revenue share of advanced packaging, JCET Microelectronics revenue and losses, the gross-profit quality of JCET Advanced, changes in testing revenue, capex tied to customers, quarterly gross margin, and operating cash flow. Only when these indicators improve together does the technology ticket truly become a profit ticket.
VIII. JCET Microelectronics: The Variable with the Greatest Valuation Elasticity
JCET Microelectronics is the most sensitive component in JCET’s rerating. It carries high-end advanced packaging, XDFOI, 2.5D/3D, and capacity related to domestic AI accelerators. It also carries the greatest uncertainty, because 2025 revenue was only RMB204mn, with a net loss of RMB192mn.
The loss itself is not the issue. A new advanced packaging line naturally goes through stages of front-loaded depreciation, R&D; investment, process tuning, material loss, and low utilization from construction to customer introduction, sample validation, small-batch production, and mass-production ramp. The issue is how long this stage lasts, and whether revenue scaling can also bring loss narrowing. If revenue grows while losses widen, it means high-end capacity is still ramping inefficiently. If revenue grows while losses narrow, it means utilization, yield, and customer orders are starting to match.
J.P. Morgan’s assumptions for JCET Microelectronics are quite positive. It believes the company’s 2.5D/3D capacity ramp will benefit from demand for domestic AI chips, and forecasts rapid growth in related sales in 2026-2028. Other prior sell-side materials also identified JCET Microelectronics as the core source of JCET’s advanced packaging elasticity. The disagreement is not whether it has strategic significance, but when it crosses breakeven.
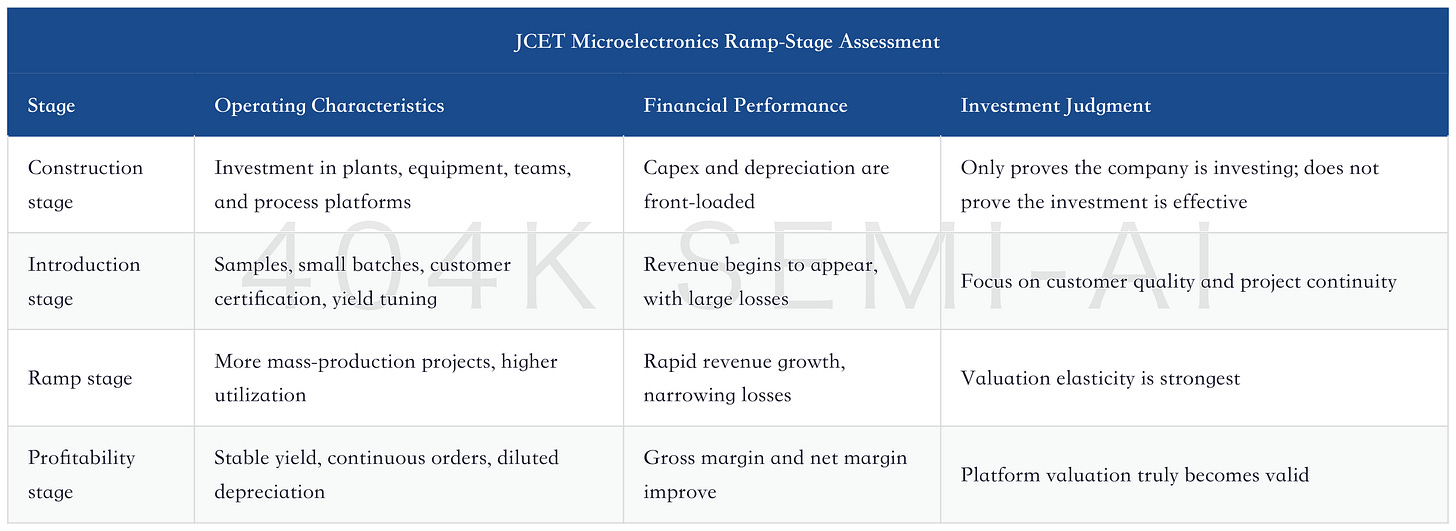
JCET Microelectronics is most likely now in the transition from the introduction stage to the ramp stage. This is the phase where the market is most likely to price in expectations early, because expectations are fullest; it is also where the market is most likely to be disappointed, because the financial statements look worst. The real judgment should return to three indicators: absolute revenue scale, pace of loss narrowing, and linkage with the parent company’s gross margin.
If, from 2H26 to 2027, JCET Microelectronics revenue scales continuously, losses narrow significantly, and the parent company’s gross margin rises at the same time, then JCET’s “AI advanced packaging platform” framework will be materially strengthened. If these three items do not improve simultaneously, advanced packaging can only be considered strategic investment, not something that can be immediately capitalized into a high valuation.
IX. STATS, SanDisk Semiconductor, and Automotive Electronics: Not the Main Narrative, but They Determine Profit Depth
JCET Technology’s Changdian Microelectronics is the asset most likely to attract market attention, but the company’s real asset portfolio is broader.
STATS ChipPAC is one of the biggest differences between JCET and purely domestic OSAT vendors. It brings overseas customers, global operating experience, and high-end application innovation capabilities. In 2025, STATS ChipPAC Management generated revenue of USD 1.723 billion and net profit of USD 127 million. The company’s annual report also noted that it established the STATS ChipPAC global operations center based on SCPM and increased investment in R&D; and application innovation. J.P. Morgan places product optimization at the Korean plant within the AI opportunity, especially connectivity, PMICs, and overseas AI peripheral chips. This shows that JCET’s AI opportunity does not come only from domestic Chinese customers, but also from spillover in global AI demand.
SanDisk Semiconductor is linked to the memory cycle. In 2025, SanDisk Semiconductor generated revenue of RMB 3.621 billion and net profit of RMB 243 million. AI servers are driving demand for HBM, DDR5, LPDDR5, NAND, and enterprise SSDs, making back-end memory packaging and testing experience increasingly important. SanDisk Semiconductor is not directly equivalent to core HBM packaging, but it gives JCET a stronger base in memory customers, packaging experience, and capacity integration.
Automotive electronics improves revenue stability. In 2025, JCET Automotive Electronics was still in the preparation stage, but the line was officially connected by year-end; in 1Q26, automotive electronics revenue increased 28.8% year on year, maintaining double-digit growth. Automotive packaging and testing is characterized by long certification cycles, high reliability requirements, long lifecycles, and slow customer switching. It may not provide the highest valuation elasticity, but it can improve the profit base and customer stickiness.
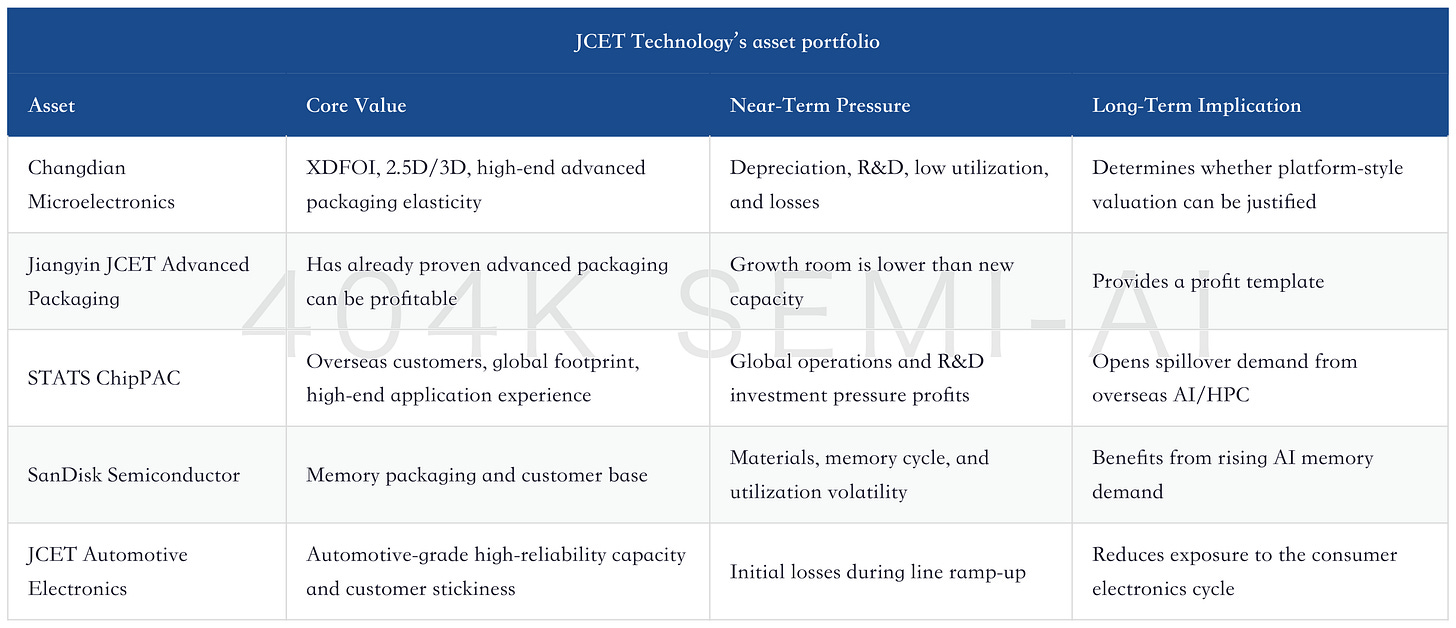
This also explains why JCET Technology cannot be summarized with a single label. It is not a pure AI chip packaging company, nor is it an ordinary consumer electronics OSAT. It is an OSAT platform in an asset restructuring phase: traditional business provides scale, high-growth applications improve the mix, high-end advanced packaging opens the valuation ceiling, and overseas and memory assets provide a second growth curve.
X. Competitive Landscape: Platform Breadth Is an Advantage, Profit Elasticity Is the Constraint
In the global OSAT landscape, ASE, Amkor, JCET Technology, Tongfu Microelectronics, Huatian Technology, and others each have different capabilities. The strongest advanced packaging platforms remain in the hands of foundries and a small number of leading OSATs. TSMC’s advantages are front-end process technology, CoWoS/SoIC, customer roadmaps, and capacity coordination; ASE and Amkor have global customers and high-end packaging experience; JCET’s advantages are advanced packaging and testing supply within China, a global footprint, the XDFOI platform, and its position in the domestic AI chain.
Applied Materials Deep Dive: How the WFE Supercycle, DRAM Expansion, and Advanced Packaging Reprice the Profit Slope
Compared with Tongfu Microelectronics, JCET Technology has a broader platform, a more complete overseas footprint, and more diversified memory and automotive businesses; Tongfu’s elasticity may be more concentrated, with more direct marginal changes from customers and CPU/GPU-related packaging and testing projects. Compared with Huatian Technology, JCET Technology has stronger narratives around global revenue scale, high-end customers, and advanced packaging platforms, but it also faces higher capex pressure and a higher bar for margin validation.
The competitive landscape is not a simple ranking, but a question of who can convert advanced packaging projects into profits. OSAT companies may all benefit from the AI cycle, but only a few can simultaneously meet customer certification, capacity, yield, material supply, testing capability, and cash-flow constraints. JCET Technology’s advantage lies in platform breadth, and so does its risk: the more business lines it has, the more management must properly prioritize capex, customer introduction, and product mix.
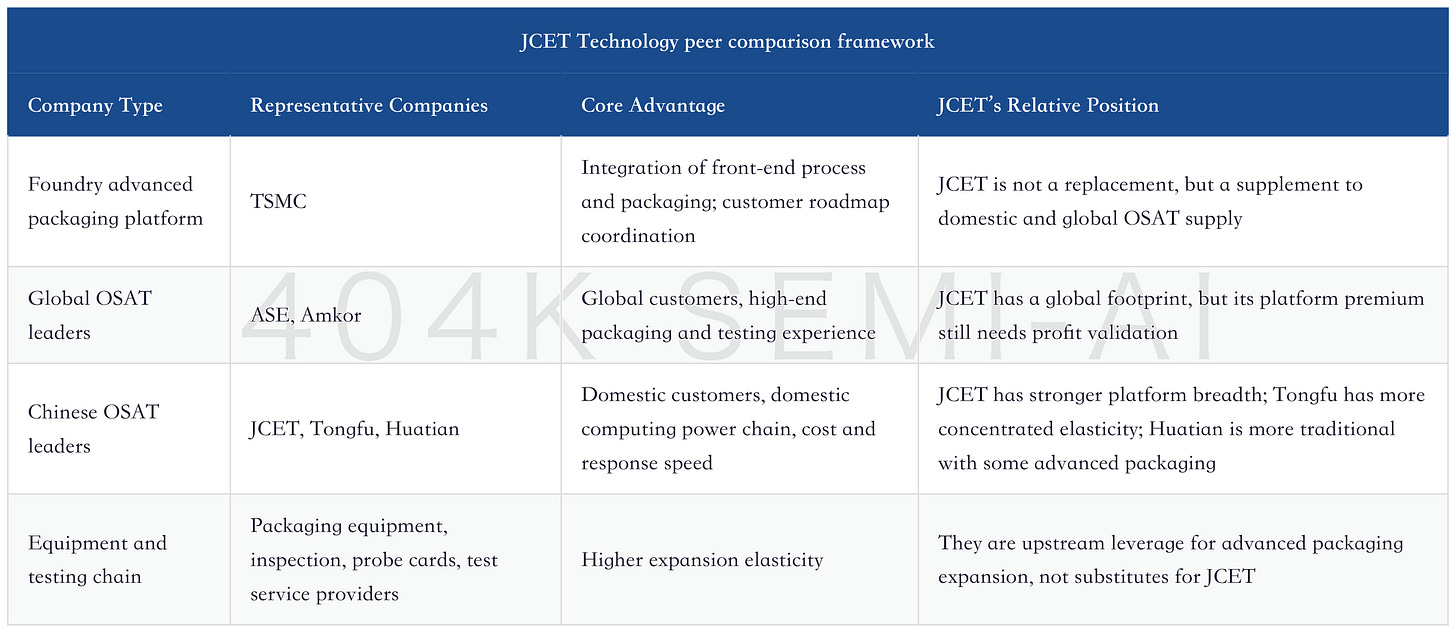
The investment implication of this comparison is that JCET Technology’s valuation cannot be directly benchmarked to TSMC, nor can it be based only on the average for traditional OSATs. A more reasonable approach is to separately assess the traditional packaging and testing base, overseas and memory assets, and high-end advanced packaging platform, then determine the platform premium using gross margin and ROE.
XI. Valuation Divergence: Three Worldviews Determine Three Prices
The most important question for JCET Technology today is not whether it is “expensive,” but which worldview should be used to price it.
The first worldview is that it is a traditional packaging and testing cyclical stock. Under this framework, JCET is mainly evaluated based on the semiconductor cycle, handset and communications demand, capacity utilization, inventory, and gross margin. Advanced packaging is only a structural improvement factor and is insufficient to justify a very high valuation premium. If handsets are weak in 2026, capex rises, and losses at Changdian Microelectronics expand, this worldview will regain dominance.
The second worldview is that it is a leading OSAT in China. This framework acknowledges that the company is not just an ordinary cyclical stock, because domestic AI accelerators, memory, automotive electronics, and industrial and medical applications have improved the quality of the revenue mix; but it also does not directly price the company as a platform-style advanced packaging asset. Valuation mainly depends on ROE recovery, revenue mix, and cash-flow quality.
The third worldview is that it is an AI advanced packaging delivery platform. Under this framework, XDFOI, 2.5D/3D, FCBGA, CPO, memory packaging and testing, testing services, and global customers together constitute platform value. The valuation anchor shifts from cyclical P/E to long-term ROE, platform scarcity, and the share of advanced packaging revenue. This framework has the most imagination, but also the highest requirements, because JCET must prove that high-end revenue can generate high-end profits.

J.P. Morgan’s RMB 110 target price is essentially priced on the third worldview: a 2027 target, 40x forward P/E, rising AI-related revenue share, and earnings CAGR significantly above revenue CAGR. This target price should not be taken simply as a conclusion. It is more like a conditional statement: if JCET’s high-end packaging revenue and gross margin improve as the model suggests, the market can assign a platform premium; if margins do not materialize, valuation will fall back toward the second or even the first worldview.
XII. How to Use Sell-Side Divergence: Do Not Simply Take the Most Optimistic Model
Among this set of materials, J.P. Morgan’s company model is the most aggressive, UBS’s industry materials provide external demand support, and the company’s official financial reports provide more restrained real-world constraints. Only by putting all three together can research on JCET Technology avoid becoming a mere restatement of a single target price.
J.P. Morgan’s strength is that it breaks out the profit bridge. Its 2026-2028 revenue and earnings path puts AI-related revenue share, gross margin, capex, and profit elasticity into the same table. This model is best suited to answering the question: “If everything goes well, where can JCET Technology get to?” But its risks are also obvious: the assumptions include strong improvements in utilization, pricing pass-through, and product mix. If any one of these comes in below expectations, earnings CAGR will be compressed.
UBS’s semiconductor cycle and China semiconductor materials work is strongest in explaining why demand may persist. AI cloud, memory, server CPUs, domestic AI accelerators, networking, and power management together form the upstream sources of packaging and testing demand. It can answer why advanced packaging is not a short-term concept. But UBS’s industry framework does not translate directly into JCET profits, because industry demand must pass through customer introduction, order share, yield, capacity utilization, and pricing pass-through before it appears in JCET Technology’s financial statements.
The company’s official financial reports are the most important because they tell the market where JCET Technology stands now. In 2025, revenue grew and gross margin improved, but net profit declined slightly; in 1Q26, revenue declined slightly while profit improved significantly; JCET Advanced is already profitable, while Changdian Microelectronics is still loss-making; automotive electronics is beginning to shift from construction to customer introduction. The implication of the official reports is that the asset-attribute transition has begun, but the company is still in an investment and ramp-up phase.

Putting these perspectives together, the investment conclusion for JCET Technology should be “conditional re-rating,” not unconditional linear extrapolation. Industry demand provides direction, sell-side models provide elasticity, and company reports verify reality. As long as all three point to improvement at the same time, the valuation center has a basis to continue moving higher; if the reported numbers fail to cooperate for a long time, even strong industry demand can only support short-term valuation sentiment, not a long-term valuation center.
One detail also needs to be addressed: AI-related revenue is not inherently a high-margin category. Computing, memory, power, connectivity, packaging, and testing can all be classified as AI-related, but different products have different gross margins, capital intensity, customer stickiness, and certification cycles. What really needs to be tracked is not the AI revenue share itself, but whether core gross margin, net margin, ROE, and operating cash flow improve at the same time after the AI revenue share rises. If the share rises but margins do not, the market will view it as low-price expansion; if the share rises and margins also rise, the platform-style valuation will have a firmer foundation.
XIII. Scenario Analysis: 2027 Is the Real Stress-Test Year
For JCET, 2026 will still be a year in which capacity expansion, customer/product ramp-up, and financial-statement validation proceed in parallel. J.P. Morgan expects the company’s capex this year to be around RMB 10.0 billion, above roughly RMB 8.0 billion in the prior year. Capex directed toward high-end applications is not negative in itself, but free cash flow may come under pressure in 2026. What the market really needs to see is whether revenue, gross margin, and cash flow improve simultaneously in 2027.
In the bull case, demand is strong for both domestic AI accelerators and overseas AI peripheral chips; JCET Microelectronics’ 2.5D/3D capacity loads quickly; AI spillover drives memory- and power-related packaging; automotive electronics introduction proceeds smoothly; and material costs can be passed through effectively. In this scenario, revenue grows rapidly, gross margin rises, JCET Microelectronics’ losses narrow quickly, and JCET enters a platform-style re-rating phase.
In the base case, AI demand continues to grow, but the ramp-up of high-end production lines is moderate; depreciation and R&D; investment offset part of the gross-margin improvement; and traditional consumer electronics remain weak. The company delivers revenue growth and some profit recovery, but valuation needs to move with quarterly data.
In the bear case, capex runs ahead of orders; handset and communications businesses weigh on utilization; material and substrate costs are difficult to pass through; and orders slow after inventory rises at domestic AI accelerator customers, expanding losses at JCET Microelectronics. In this scenario, the advanced-packaging narrative remains, but valuation is pulled back toward a cyclical-stock framework.

The key point in this scenario table is that JCET’s real inflection point is not revenue, but ROE. Revenue growth can come from consolidation, pricing, the cycle, or new capacity; ROE improvement must come from higher-quality earnings and better asset turnover. If the company can lift its net margin meaningfully from roughly 4% in 2025 while operating cash flow recovers in 2027, the asset re-rating will have a firmer foundation.
XIV. Risks: The Most Dangerous Outcome Is “Revenue Arrives, Profit Does Not”
JCET’s risk is not that the advanced-packaging direction is wrong, but that even the right direction may not generate enough profit.
First, advanced packaging may add revenue but not profit. High-end packaging is capital intensive, with heavy initial depreciation and R&D; expenses, slow customer qualification, and slow yield ramp-up. If JCET Microelectronics’ revenue grows but losses widen, it would indicate unsatisfactory capacity loading or yield, and the platform valuation would need to be downgraded.
Second, capex may be too fast. If around RMB 10.0 billion of capex in 2026 runs ahead of customer orders and utilization, it will increase depreciation pressure. Advanced-packaging production lines do not generate profit simply once built; they require customer commitments, product continuity, and stable yield.
Third, handsets and traditional consumer electronics may continue to drag. UBS smartphone data already shows that traditional terminal demand remains weak. JCET still has high exposure to communications and consumer electronics; if traditional businesses continue to weaken, they will offset the incremental contribution from high-growth businesses.
Fourth, domestic AI accelerator demand may fluctuate. Expectations for AI infrastructure investment are strong, but customer inventory, project delays, chip yield, software ecosystems, and server delivery can all affect order timing. Once downstream customers slow down, the impact on packaging and test utilization will be magnified.
Fifth, material, substrate, power, and precious-metal costs. Packaging and test companies have thin gross margins, and material price increases or supply tightness can easily consume the benefits of product-mix improvement. J.P. Morgan believes higher utilization and price pass-through can ease the pressure, but this still requires validation in financial statements.
Sixth, geopolitical and overseas-customer risks. UBS’s dashboard also indicates that the global semiconductor cycle, domestic OSAT competition, and geopolitical factors may affect overseas customer share. JCET’s global footprint is an advantage, but it also means a more complex customer structure.
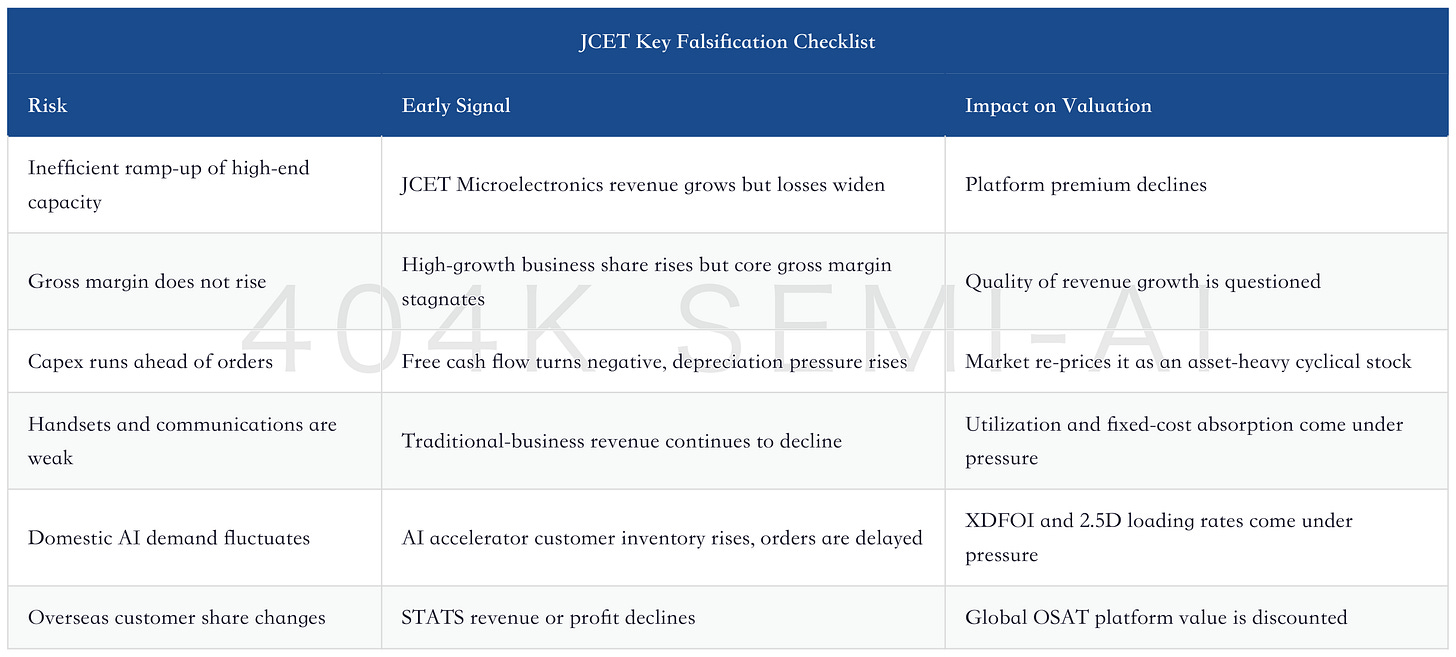
XV. What to Watch Most Closely Over the Next Four Quarters
JCET’s tracking indicators need to be more rigorous than “the share price went up or down.” Over the next four quarters, seven items deserve priority.
First, watch JCET Microelectronics’ revenue and losses. If revenue scales and losses narrow, that is the strongest positive signal; if revenue scales but losses widen, investors should watch for an inefficient ramp-up of high-end capacity.
Second, watch core gross margin. Core gross margin was 13.95% in 2025, and J.P. Morgan’s model projects gross margin reaching 16.5% in 2028. This improvement path must be validated quarter by quarter, not only when the annual report is released.
Third, watch the share of high-growth businesses. In 2026Q1, automotive electronics, computing electronics, and industrial and medical electronics together exceeded 45%. If this share continues to rise, it means the structural upgrade has not stopped.
Fourth, watch advanced-packaging shipment volume and product disclosure. In 2025, advanced-packaging shipments grew 14.00%, faster than traditional packaging. If the gap continues to widen, it would show that product-mix improvement remains underway.
Fifth, watch capex and operating cash flow. Capacity expansion is necessary, but cash flow cannot remain under pressure for a long period. If free cash flow is negative in 2026, investors must see a path to improvement in 2027.
Sixth, watch STATS and overseas customers. Overseas AI peripheral chips, PMIC, connectivity, and memory demand are important variables that distinguish JCET from purely domestic packaging and test companies.
Seventh, watch dedicated automotive-electronics lines. Automotive-grade lines need to move from line qualification to mass-production introduction, with customer certification, yield, and utilization gradually ramping up. This does not determine peak upside, but it determines long-term earnings quality.
These tracking items can be organized into a simple dashboard. JCET Microelectronics’ P&L; validates the ramp-up of high-end advanced packaging: positive signals are revenue scaling and narrowing losses; negative signals are revenue below expectations or widening losses. Core gross margin validates product mix and price pass-through: a positive signal is sequential quarterly improvement; a negative signal is high-growth business scaling while gross margin stagnates. The share of high-growth businesses validates the migration in asset attributes: a positive signal is a continued increase in the share of computing, automotive, and industrial/medical; a negative signal is a renewed rise in the share of traditional communications and consumer.
Advanced-packaging shipments validate product upgrades: a positive signal is growth that remains faster than traditional packaging; a negative signal is a slowdown in advanced-packaging growth. Operating cash flow and capex validate the quality of capacity expansion: a positive signal is stronger cash-flow coverage; a negative signal is persistently negative free cash flow. STATS and overseas customers validate global platform attributes: a positive signal is an increase in overseas AI peripheral orders; a negative signal is weakening overseas revenue and profit. Automotive-electronics introduction validates the foundation in high-reliability applications: a positive signal is improved customer certification and line utilization; a negative signal is prolonged losses after line qualification.
XVI. Conclusion: JCET Has Secured the Ticket; the Profit Answer Sheet Is Not Yet Complete
JCET’s core change is not the addition of an advanced-packaging concept, but that multiple pieces of evidence are pushing it from a traditional OSAT leader toward an AI advanced-packaging delivery gatekeeper. UBS’s semiconductor-cycle report shows that AI, memory, and server-related chips are forming an industry-level upcycle. Expectations for China AI infrastructure investment show that the domestic compute loop requires local advanced packaging and testing. J.P. Morgan’s company model quantifies this chain into a path for revenue, gross-margin, and profit-margin improvement. The company’s own 2025 annual report and 2026Q1 results show that the share of high-growth businesses is rising and profit growth is starting to outpace revenue growth.
But this is still not an unconditional bullish call. JCET still has around 60% of revenue exposed to communications and consumer electronics, while handset terminals are not strong; advanced packaging requires large capex, with depreciation and R&D; front-loaded; JCET Microelectronics is still loss-making; automotive electronics has only just entered the introduction stage after line qualification; and material costs and overseas-customer risks will still affect profit elasticity.
A more prudent investment judgment is therefore: JCET has moved from a traditional packaging-and-test cyclical stock into a phase of asset-attribute transition, and its valuation center has a basis to move higher, but this must be confirmed jointly by gross margin, ROE, narrowing losses at JCET Microelectronics, and cash flow. If these indicators improve together in 2026-2027, JCET has the opportunity to become one of the most important re-rating examples in China’s advanced-packaging chain. If revenue growth does not translate into earnings quality, the market will again price it as a cyclical packaging-and-test company.
In one sentence: JCET has already secured its ticket to the AI advanced-packaging era; what it needs to prove next is not “whether it can do it,” but “whether it can make money sustainably.”
References
Jiangsu Changjiang Electronics Technology Co., Ltd. 2025 Annual Report.
Jiangsu Changjiang Electronics Technology Co., Ltd. 2026 First Quarterly Report.
Goldman Sachs, AI and China Semis Capacity expansion drives growth ahead; raising TP of JCET, Huafeng Test & Control, and Hwatsing, July 2, 2026.
UBS, China Equity Strategy, Guide to the slow bull, May 19, 2026.
UBS, Going global dashboard, May 20, 2026.
UBS, Global IO Smartphones, April 2026 Sell-Through, June 1, 2026.
UBS, Global IO Semiconductors, Cycle Update, June 9, 2026.
UBS, China Semiconductor First Read, June 10, 2026.
J.P. Morgan, JCET: Strong AI demand and capacity upgrades to drive long-term upside, June 16, 2026.