
目录
Executive Summary
The Key 2Q26 Development: Earnings Quality Improved Before Revenue Accelerated
Advanced Packaging Enters the Financials, Raising the Bar for Validation
What the Forecast Upgrades Mean: The Model Begins to Recognize Earnings Leverage
RMB125 Price Target Unchanged as Multiple Compression Offsets Earnings Upside
2H26 Must Demonstrate Consistency
Where JCET Stands Today
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Margins and net profit improved in tandem in 2Q26, but Goldman Sachs maintained its Neutral rating and RMB125 price target. The debate has shifted to whether earnings recovery from advanced packaging can sustainably offset a high valuation multiple and heavy capital requirements.
Executive Summary
Earnings quality outpaced revenue growth. 2Q26 revenue reached RMB10.356bn, up 12% YoY but 8% below Goldman Sachs’ forecast; attributable net profit was RMB554mn, up 107% YoY and 15% above Bloomberg consensus. Higher utilization, tighter cost control, and a richer high-end product mix lifted margins.
Advanced packaging is beginning to show up in earnings. Gross margin rose to 15.7% and operating margin to 6.6%, both improving YoY and QoQ. Management attributed the gains to demand, utilization, and a richer mix of high-end packaging and testing products for AI data centers. For the first time, the technology narrative has clearer quarterly earnings support.
Near-term revenue forecasts fell, while longer-term earnings estimates rose. Goldman Sachs cut its 2026 revenue forecast by 3% but raised 2027–2030 revenue estimates by 4%–5% and net profit estimates by 9%–13%. While 2Q26 did not eliminate ramp-up volatility, it increased confidence in the medium- to long-term margin trajectory.
The RMB125 target is unchanged, while the long-term earnings multiple continues to compress. Goldman Sachs lowered its 2030 reference multiple from 46.0x to 42.8x, exactly offsetting the earnings upgrades. The Neutral rating underscores that valuation has moved beyond whether JCET has AI exposure to whether the pace of earnings delivery justifies the multiple.
2H26 must demonstrate continuity. Goldman Sachs forecasts gross margins of 15.8% and 15.7% for 3Q26 and 4Q26, respectively, and operating margins of 6.9% and 7.6%. If margins hold as revenue expands, the advanced-packaging re-rating will gain a second set of supporting evidence. If utilization or product mix weakens, 2Q26 may prove to have been a one-quarter peak.
The Key 2Q26 Development: Earnings Quality Improved Before Revenue Accelerated
On Goldman Sachs’ figures, JCET Group (600584.SH) reported 2Q26 revenue of RMB10.356bn, up 12% YoY and 13% QoQ. Growth was respectable, but revenue came in 8% below Goldman Sachs’ forecast and 1% below Bloomberg consensus. On revenue alone, the company remains in a phase where capacity ramp-up and order-timing volatility coexist.
Profitability told a different story. Gross profit was RMB1.624bn, up 22% YoY; operating profit reached RMB681mn, up 59%; and attributable net profit was RMB554mn, up 107% YoY and 91% QoQ. Attributable net profit was 4% below Goldman Sachs’ forecast but 15% above consensus. The real upside surprise was the company’s ability to retain more gross and operating profit from every RMB1 of revenue.
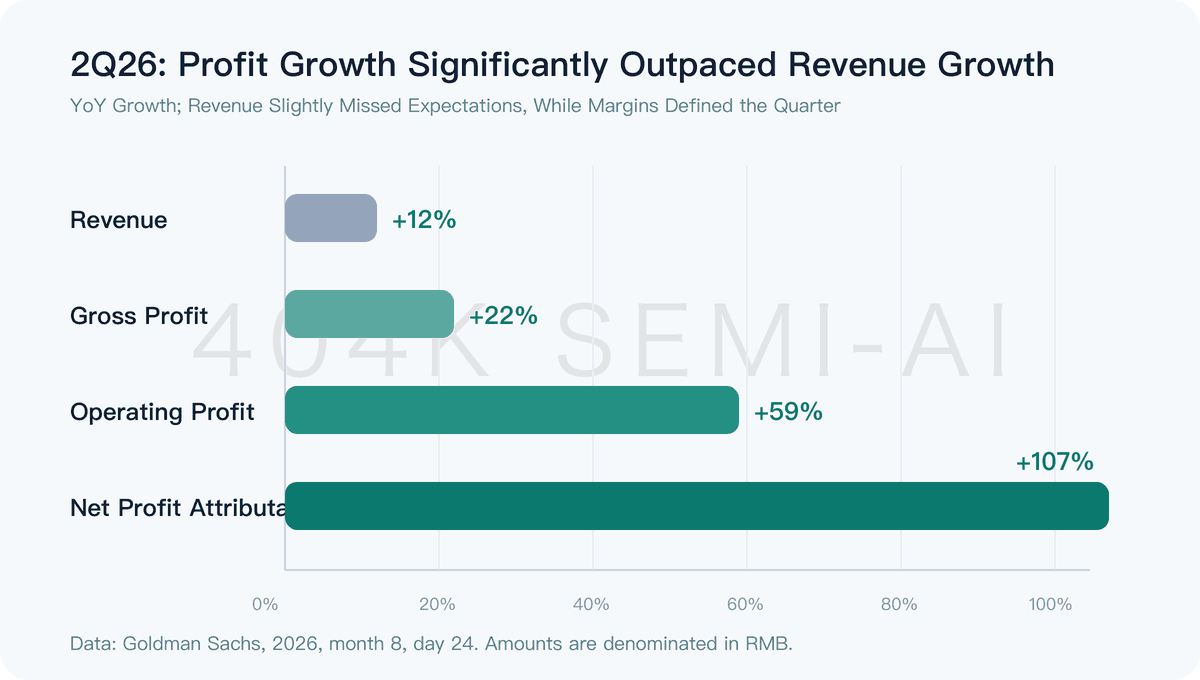
Gross margin was 15.7% in 2Q26, up 1.4 percentage points YoY and 1.1 percentage points QoQ. Operating margin reached 6.6%, up 2.0 percentage points YoY and 2.1 percentage points QoQ. Revenue missed the model while margins beat it, indicating that the improvement was not driven by scale alone. Strong demand, higher capacity utilization, cost control, and a richer high-end product mix, as cited by management, combined to lift the income statement.
Gross margin was 0.6 percentage points above Goldman Sachs’ forecast and 1.5 percentage points above consensus, while operating margin beat the two estimates by 0.8 and 1.2 percentage points, respectively. Net profit still fell short of Goldman Sachs’ own forecast, suggesting that expenses, taxes, or non-operating items absorbed part of the gross-profit improvement. This pattern is more analytically useful than a simultaneous revenue and earnings beat because it focuses attention on manufacturing efficiency and product mix. It also cautions investors against extrapolating net-profit growth mechanically across the full year.
Some restraint remains warranted. Goldman Sachs did not separately disclose revenue, gross margin, or capacity utilization for AI data-center packaging and testing, nor did it provide quarterly earnings for JCET Microelectronics. The positive contribution from the high-end product mix is evident, but the company-wide improvement cannot be attributed entirely to any single advanced-packaging line.
Advanced Packaging Enters the Financials, Raising the Bar for Validation
Our previous report, “JCET Deep-Dive Update: The AI Cycle, Domestic Substitution, and the Re-Rating of Packaging and Testing Assets”, framed the company as transitioning from a conventional semiconductor assembly and testing base into an advanced-packaging platform. The key gap at the time was that R&D;, equipment, depreciation, and customer qualification were already underway, but evidence of sustained high-end revenue and margin contribution remained limited.
