
Japan SPE Turns Positive: How the WFE Upcycle Flows from Billing Data to Test, Packaging, and Front-End Equipment
目录
Too Long; Didn't Read
1. The Point of This Data Is Not "Japan Equipment Is Good"; It Is That the Cycle Has Entered High-Frequency Validation
2. Why Japan Is the Thermometer for Global WFE
3. Test Equipment Breaks Out First, Showing AI Manufacturing Bottlenecks Have Entered the Yield and Validation Stage
4. Tokyo Electron's Near-Term Downgrade Signal Does Not Mean the Front-End Cycle Is Broken
5. Packaging Equipment Is Recovering Steadily, and Disco's Logic Remains the Advanced-Packaging Processing Bottleneck
6. Aggregate WFE Upgrades Are Now Consensus; the Debate Is Structure and Timing
7. Company Differentiation: Buying Japanese Equipment Is Not Buying a Basket, but Buying Different Bottlenecks
8. How the U.S. and Chinese Equipment Chains Map
9. The Key for A-Share Equipment Is Not Following Japan, but Proving Platformization and Customer Validation
10. How to Price Monthly Billings: From SEAJ to Revenue, Profit, and Valuation
11. Three Scenarios for the Next 6-12 Months
12. Beyond Equipment Orders, Watch Components, Service, and Supply-Chain Constraints
13. Over the Next Four Quarters, Watch a Set of Validation Metrics, Not the Phrase "WFE Upgrade"
14. Risks: The Equipment Cycle Fears Order Pull-Forward, Delayed Profits, and Valuation Running Ahead
15. Conclusion: Japan SPE Turning Positive Signals the WFE Supercycle Moving from Models into Billings
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Japan SPE billings have turned positive year over year, showing that the AI-driven equipment cycle is moving out of long-range WFE models and into monthly shipment verification. The real debate is not whether equipment demand is improving, but which segments among test, packaging, front-end, and domestic Chinese equipment will convert orders into profit first. This time, the focus is to use data to reorder the pecking order across equipment stocks.
Too Long; Didn't Read
Japan SPE has turned positive. In May, Japan semiconductor production equipment billings rose 11% YoY in yen terms, while the three-month average rose 18% YoY. The dollar-denominated measure also turned positive. This is not one month of noise, but high-frequency confirmation that Japan's equipment chain continues to recover after bottoming around mid-2023. It shows that the WFE upcycle is moving from sell-side models into monthly billings.
Test is breaking out first. In May, Japan test equipment billings rose 41% YoY, clearly stronger than front-end equipment at 5% and packaging equipment at 12%. This data explains why Advantest's near-term revenue may continue to exceed consensus, and it also shows that AI GPUs, HBM, ASICs, and high-speed interfaces are turning test from a late-cycle step into a manufacturing bottleneck.
Tokyo Electron has near-term noise. This report uses SEAJ front-end data to regress Tokyo Electron's June-quarter revenue, suggesting FQ1 revenue may decline about 15% QoQ, while consensus still expects growth. This signal should not be read simply as cycle weakness. It looks more like disruption in customer delivery and revenue-recognition timing. For the full year, DRAM, advanced logic, and broad product-line leverage remain Tokyo Electron's main themes.
The equipment chain is entering a phase of differentiation. Upward revisions to aggregate WFE are no longer scarce information. The more important message from the May data is which equipment categories are converting first. Test and advanced packaging have the best high-frequency data. DRAM-related front-end equipment still has medium-term leverage. Cleaning and general front-end equipment depend on customer mix. The risk-reward for pure mature-node equipment is beginning to deteriorate.
Japan is a global equipment thermometer. SEAJ members represent roughly 25% of the global WFE market and cover key segments through Tokyo Electron, Disco, Advantest, Kokusai Electric, SCREEN, Lasertec, and others. Japan billings are not only relevant for Japanese equities. They also map to Applied Materials, Lam Research, KLA, ASML, and domestic Chinese platforms such as Naura, AMEC, and Piotech.
Four validation points matter next. First, whether the SEAJ three-month average continues to rise in June and July. Second, whether DRAM and NAND capex moves from orders into equipment move-in. Third, whether high YoY growth in test equipment flows into Advantest and Teradyne margins. Fourth, whether China WFE localization continues to support share gains at Naura, AMEC, and Piotech.
1. The Point of This Data Is Not "Japan Equipment Is Good"; It Is That the Cycle Has Entered High-Frequency Validation
May Japan semiconductor production equipment billings sent a very important signal: the WFE upcycle is no longer just a long-range assumption in 2026-2027 models. It is starting to show up in monthly billings. Under the SEAJ definition, Japan SPE monthly billings rose 11% YoY in yen terms and 1% YoY in dollar terms. The three-month average rose 18% YoY in yen terms and 17% YoY in dollar terms. The absolute growth rate is not spectacular, but the direction matters. Japan's equipment chain bottomed around mid-2023, recovered for several consecutive quarters, and has now finally moved into positive YoY territory.
The real question answered by Japan equipment billings turning positive is whether AI capex, HBM, advanced DRAM, NAND recovery, advanced packaging, and test demand are actually flowing into equipment orders and revenue. Over the past few weeks, the market has repeatedly traded WFE upgrades, with many reports pushing 2026 and 2027 WFE to higher levels. The issue is that long-range models are easily amplified by market sentiment, while monthly billings are harder to fake. Positive billings show that equipment companies are indeed receiving stronger delivery signals, though the pace of conversion differs by segment.
The WFE Supercycle Has Just Begun: How AI Capex Pushes Semiconductor Equipment Toward $250 Billion
This is where this article differs from the prior aggregate WFE discussion. The earlier question was whether AI would push WFE to a higher plateau in 2027-2028. The question this time is which segments have already broken out first in high-frequency data. The former looks at long-range capacity schedules. The latter looks at current-month billings, three-month averages, company revenue regressions, and profit conversion. Once the equipment trade reaches this stage, "industry upcycle" can no longer explain every stock. Test, packaging, front-end, cleaning, deposition, etch, inspection, and domestic substitution need to be separated.
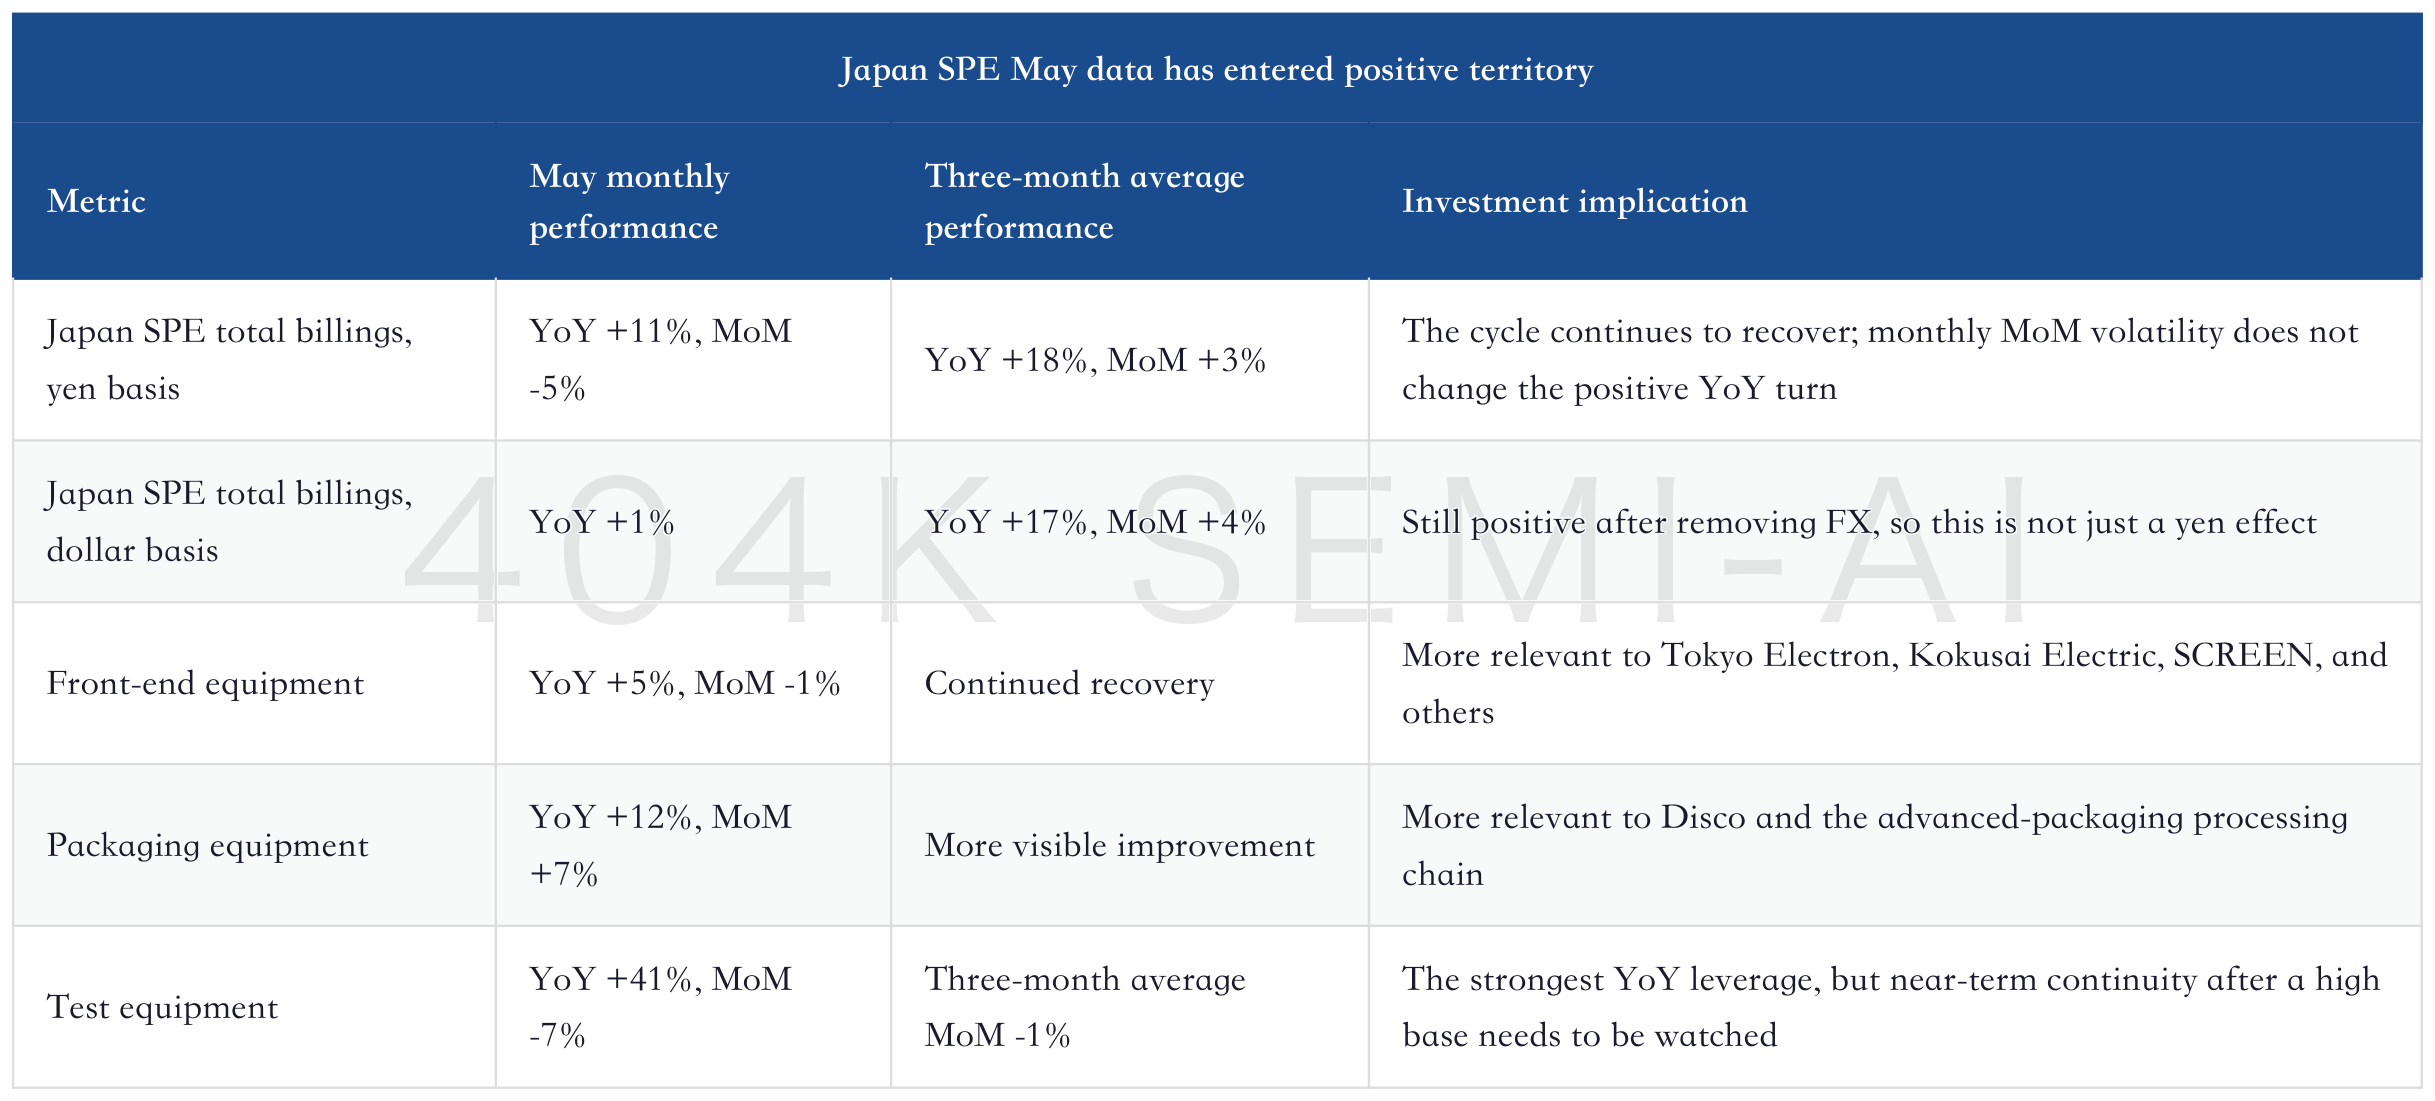
The most important point in this table is divergence, not aggregate volume. Front-end equipment grew 5% YoY, showing that wafer-fab equipment has returned to positive growth but has not yet shown an explosive slope. Packaging equipment grew 12% YoY, showing that advanced packaging and back-end processing continue to convert. Test equipment grew 41% YoY, the strongest high-frequency signal, directly tied to rising test complexity for AI GPUs, HBM, ASICs, and high-speed interfaces.
Yen and dollar measures also need to be separated. Japanese equipment company financials and investor pricing are often affected simultaneously by local-currency billings, dollar revenue, FX translation, and overseas customer procurement timing. In May, monthly billings rose 11% YoY in yen terms and 1% YoY in dollar terms. This means the positive turn is not a pure FX illusion, but it also shows that FX has amplified the visual strength of local-currency billings. Looking only at yen terms can overstate real global demand elasticity. Looking only at dollar terms may understate the improvement in local-currency revenue and P&L; for Japanese equipment companies.
For Japanese equipment stocks, a weak yen has two effects. First, overseas revenue translated back into yen improves revenue and profit performance, especially for companies with high overseas customer exposure such as Tokyo Electron, Disco, and Advantest. Second, a weak yen improves Japanese equipment makers' price flexibility relative to U.S. and European competitors, making it easier to win orders while maintaining margins. The report notes that Tokyo Electron has more room to compete on price and gain share after yen depreciation. That logic is the combined effect of FX and market share.
But FX cannot replace real demand. For equipment stocks to run further, the dollar measure also needs to confirm a positive turn, the three-month average needs to keep improving, and company orders and gross margins need to follow. The May monthly dollar measure was only +1% YoY, showing that global demand has just crossed the positive line and is not yet strong enough to ignore timing. The steadier signal is the three-month average at +17% YoY in dollar terms. This suggests the trend is healthier than a single month and that the recovery in prior months has begun to accumulate into a quarterly measure.
YoY and MoM data should also be read separately. May monthly billings in yen terms rose 11% YoY but fell 5% MoM. Looking only at MoM would suggest the data weakened. Looking only at YoY would suggest the cycle is very strong. The right interpretation is that YoY shows the cycle position is recovering from the trough, while MoM shows the recovery is not linear. Semiconductor equipment is driven by large orders and project recognition. One month's MoM data can easily be affected by customer delivery, acceptance, and working-day noise. The three-month average is closer to the trend.
This matters for investment timing. Chasing after a positive YoY turn may run into MoM volatility the following month. Rejecting the cycle because of a MoM decline may miss the recovery in the YoY trend. A better method is to treat SEAJ data as a trend-confirmation tool: monthly YoY confirms direction, the three-month average confirms persistence, and MoM is used to observe order timing. Only when all three weaken at the same time would it suggest a potential problem in the cycle.
Another detail is that different equipment types require different time scales. Test equipment is closer to chip delivery, so monthly data is more informative for company revenue. Front-end equipment projects are large and have slower delivery, making quarterly and semiannual trends more suitable. Packaging equipment sits between the two. It is affected by near-term AI packaging bottlenecks and by customer expansion timing. Therefore, the same SEAJ monthly billings map more directly to Advantest, more slowly to Tokyo Electron, and for Disco must be assessed alongside advanced-packaging orders and customer capacity ramps.
This is also why this data is more valuable than simply saying "Japan SPE +11%." The real information comes from three layers of disaggregation. First, yen and dollar measures both turned positive, so this is not pure FX. Second, the three-month average is stronger than the single month, so the trend is still improving. Third, test, packaging, and front-end equipment show different levels of strength, meaning AI manufacturing bottlenecks are transmitting in phases. Only by combining these three layers can one reach an investable conclusion.
Transmission across the equipment chain is usually not fully synchronized. Front-end equipment has the largest order value, slower recognition, and is more affected by customer scheduling, cleanrooms, installation and acceptance, and large-project timing. Packaging and test are closer to AI chip delivery bottlenecks, so their data may respond faster. The value of the May data is that it allows investors to see the sequencing inside the aggregate WFE upcycle.
2. Why Japan Is the Thermometer for Global WFE
SEAJ members represent roughly 25% of the global WFE market. This proportion means Japan billings are not a small regional sample, but a high-frequency thermometer for the global equipment chain. Japanese equipment companies cover a wide range of segments: Tokyo Electron is an integrated front-end equipment platform; Disco has a strong position in advanced-packaging processing such as dicing, grinding, and polishing; Advantest is a core AI test company; Kokusai Electric has an important position in batch ALD and thermal processing; SCREEN has a traditional advantage in cleaning equipment; and Lasertec is scarce in mask inspection and EUV-related inspection.
The distinctive feature of Japan's equipment chain is that it is neither purely the U.S. big three nor purely the lithography chain. It is more like a set of manufacturing-process pieces: front-end, back-end, test, inspection, cleaning, and materials engineering all have representative companies. Therefore, SEAJ data can break WFE upgrades into more specific questions: whether wafer-fab equipment has truly started to strengthen, whether AI packaging remains tight, whether test equipment is capturing higher value from GPUs and HBM, and whether NAND and DRAM capex is flowing into batch deposition and cleaning.
Revaluing Japan Semiconductor Equipment and Materials: Physical Bottleneck Assets Behind AI Compute Expansion
Japan's equipment chain also maps strongly to global peers. Tokyo Electron's front-end data affects cycle judgments for Applied Materials, Lam Research, ASML, and KLA. Advantest's test data affects Teradyne and the test consumables chain. Disco's packaging-processing data affects advanced-packaging equipment, dicing/grinding/polishing, probe cards, and back-end equipment. Kokusai Electric's deposition data affects ASM International, Applied Materials, Korean domestic equipment, and Chinese thin-film deposition equipment companies.
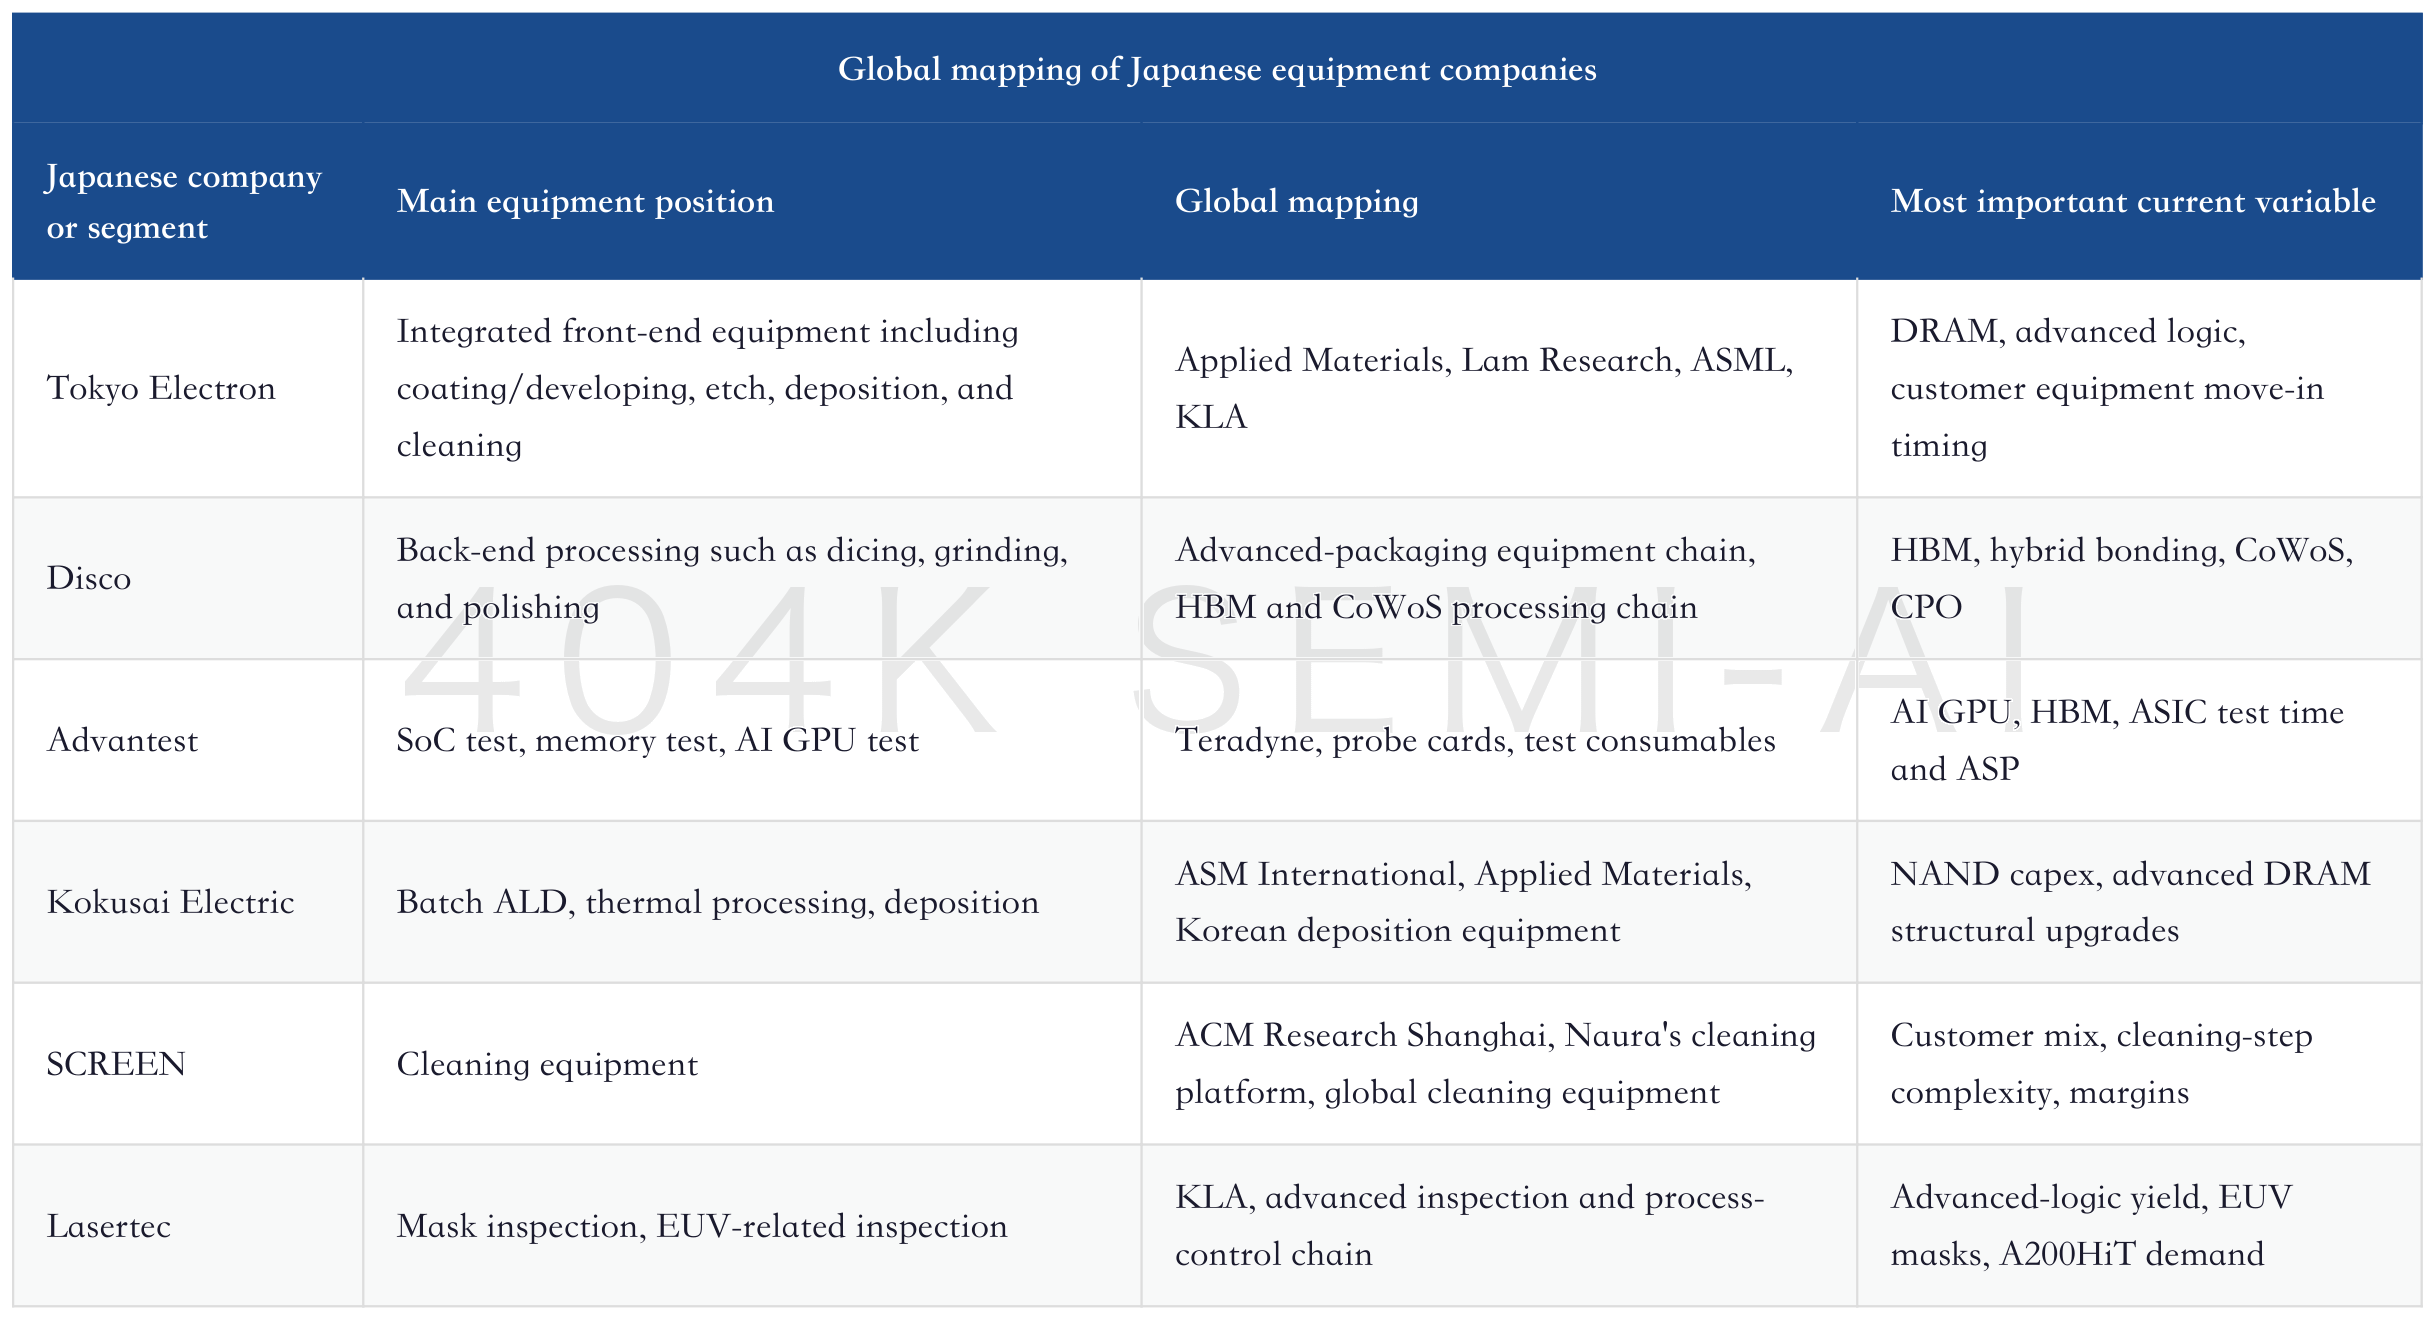
Therefore, May billings are not "small-cap Japanese equity data." They simultaneously tell U.S. equipment stocks, Chinese equipment stocks, and the advanced-packaging and test chain that cycle recovery is happening, but the transmission is uneven. The companies worth owning are those that can turn this high-frequency data into revenue, gross margin, and EPS upgrades.
3. Test Equipment Breaks Out First, Showing AI Manufacturing Bottlenecks Have Entered the Yield and Validation Stage
The strongest May subcategory was test equipment, up 41% YoY. This number was much higher than front-end equipment and packaging equipment. Test strength is not surprising, because AI chip complexity is turning test from "back-end inspection" into a delivery bottleneck. GPUs, ASICs, HBM, high-speed interconnects, CPO, retimers, SerDes, and advanced packaging all increase test time, test coverage, and test-platform value.
AI chips cannot ship simply because they have been manufactured. The more complex the system, the more validation is needed at wafer level, package level, and system level. HBM requires testing of stacks and bandwidth. AI GPUs require testing of logic functions and high-speed interfaces. Custom ASICs require validation against specific customer workloads. Advanced packaging requires confirmation of interconnects and thermal stability across multiple dies. Longer test time, more expensive test platforms, and more concentrated test demand all lift revenue elasticity for companies such as Advantest and Teradyne.
From HBM to WFE: How AI Turns the Memory Cycle into an Equipment Supercycle, and How Much Further Semiconductor Equipment Can Rise
The report regresses Advantest revenue against SEAJ test equipment data and provides an interesting near-term signal: Advantest's June-quarter revenue may be above consensus. The summary indicates revenue growth of roughly 10% QoQ, while the regression chart points to about 14%-15% QoQ growth in test revenue, versus consensus of only about 3%. The exact figures should not be copied mechanically, but the direction is clear: high-frequency test-equipment billings are stronger than market models.
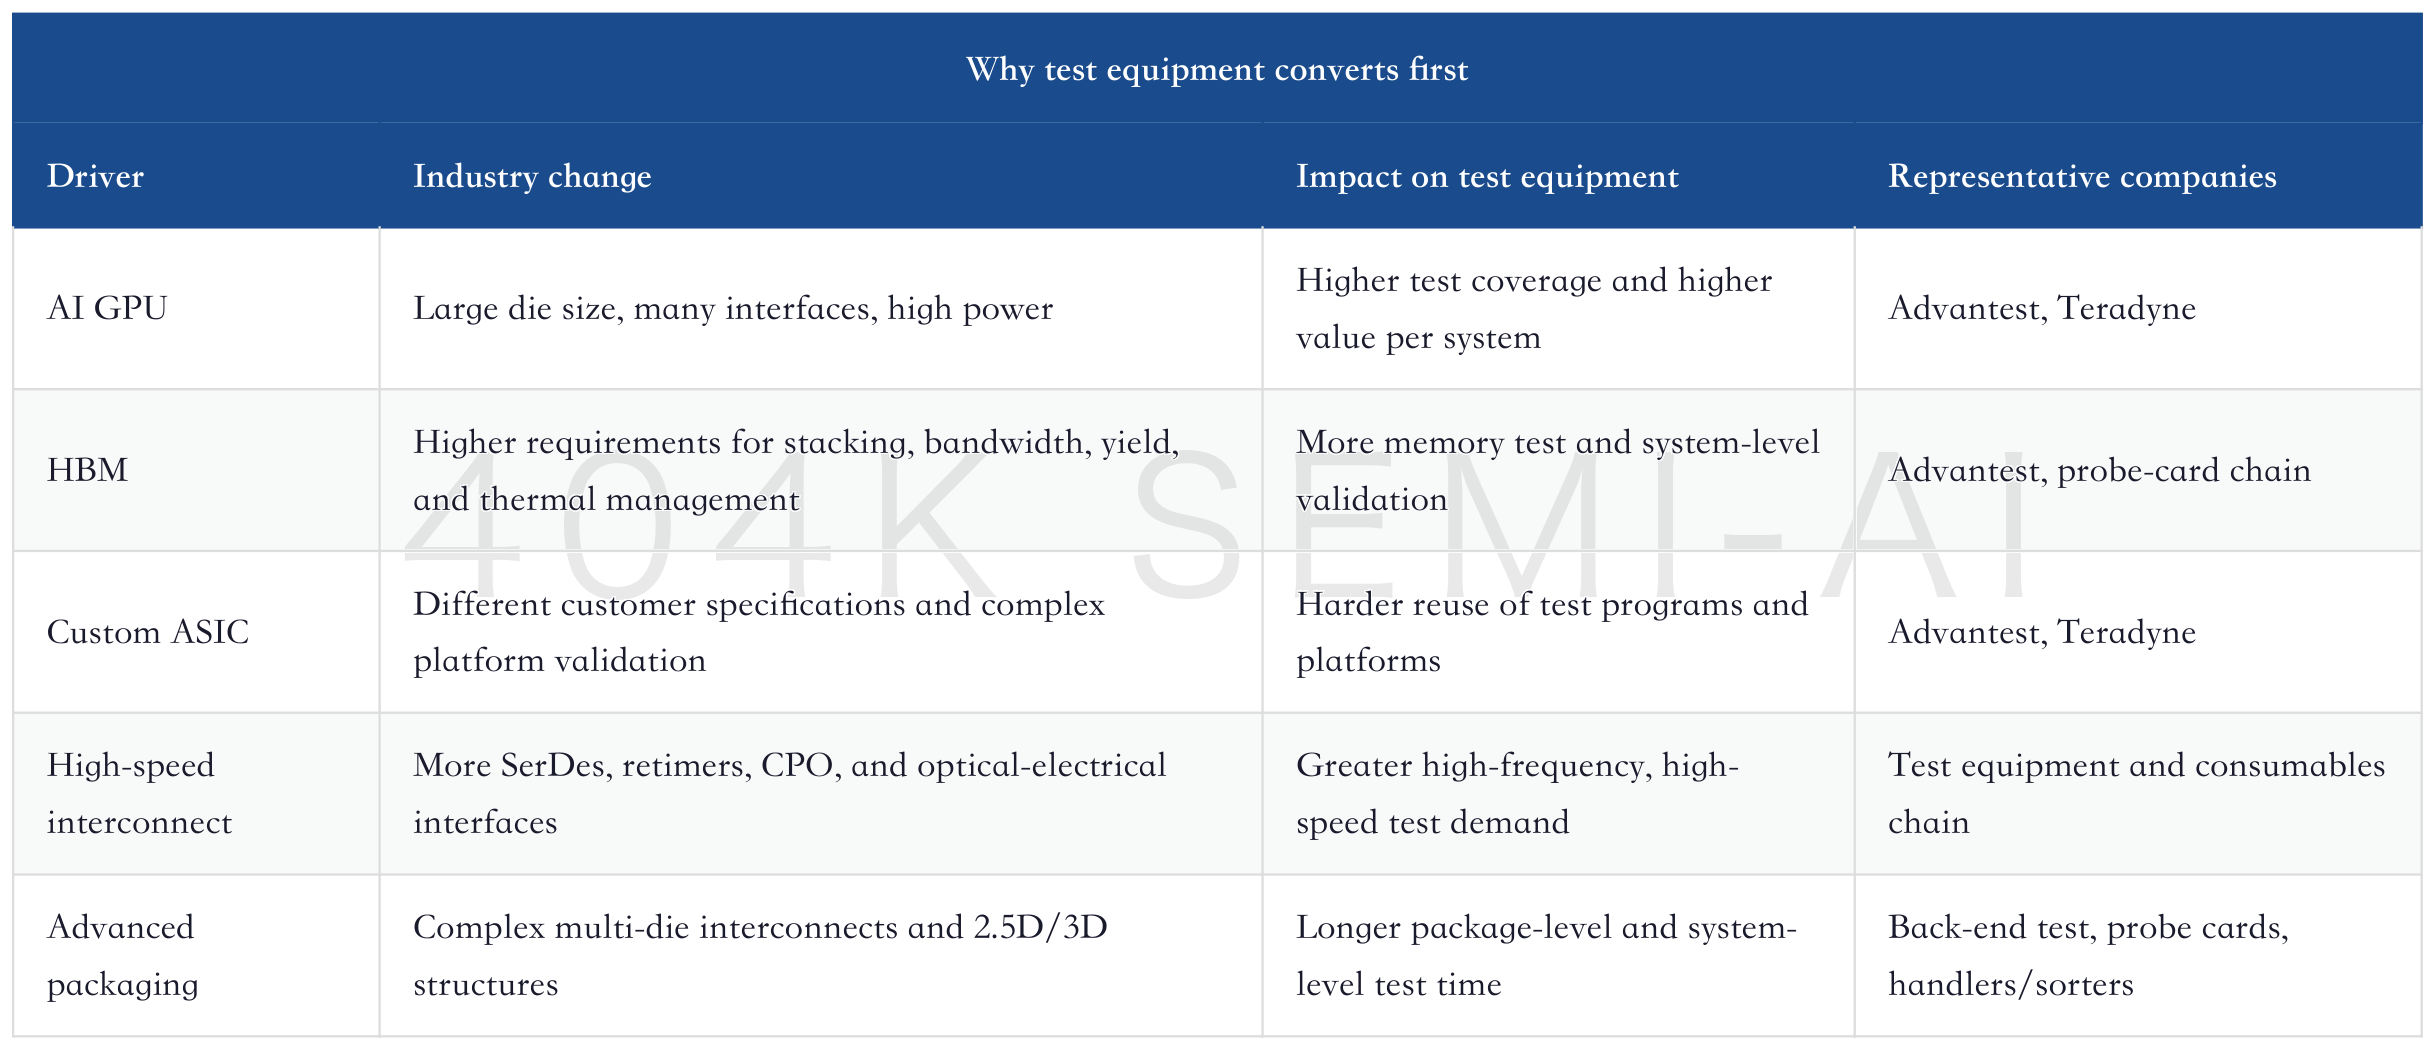
The fact that test equipment is breaking out first has another investment implication: the AI hardware cycle has moved from "buying chips" to "ensuring deliverability." Early on, the market focused only on GPU orders and HBM supply. Later, it will increasingly focus on yield, test, packaging, and system-level reliability. Test is the most direct beneficiary of this stage because it performs the validation work that turns complex chips into shippable products.
However, test equipment is not risk-free. May YoY growth was high, but monthly billings fell 7% MoM and the three-month average also declined slightly MoM. Possible reasons include the base effect, delivery timing, and customer production schedules. Test-equipment investing should avoid extrapolating one month's YoY growth into permanent high growth. A better validation method is to watch Advantest and Teradyne orders, backlog, gross margin, and whether ASPs for AI GPU, ASIC, and HBM test platforms continue to rise.
4. Tokyo Electron's Near-Term Downgrade Signal Does Not Mean the Front-End Cycle Is Broken
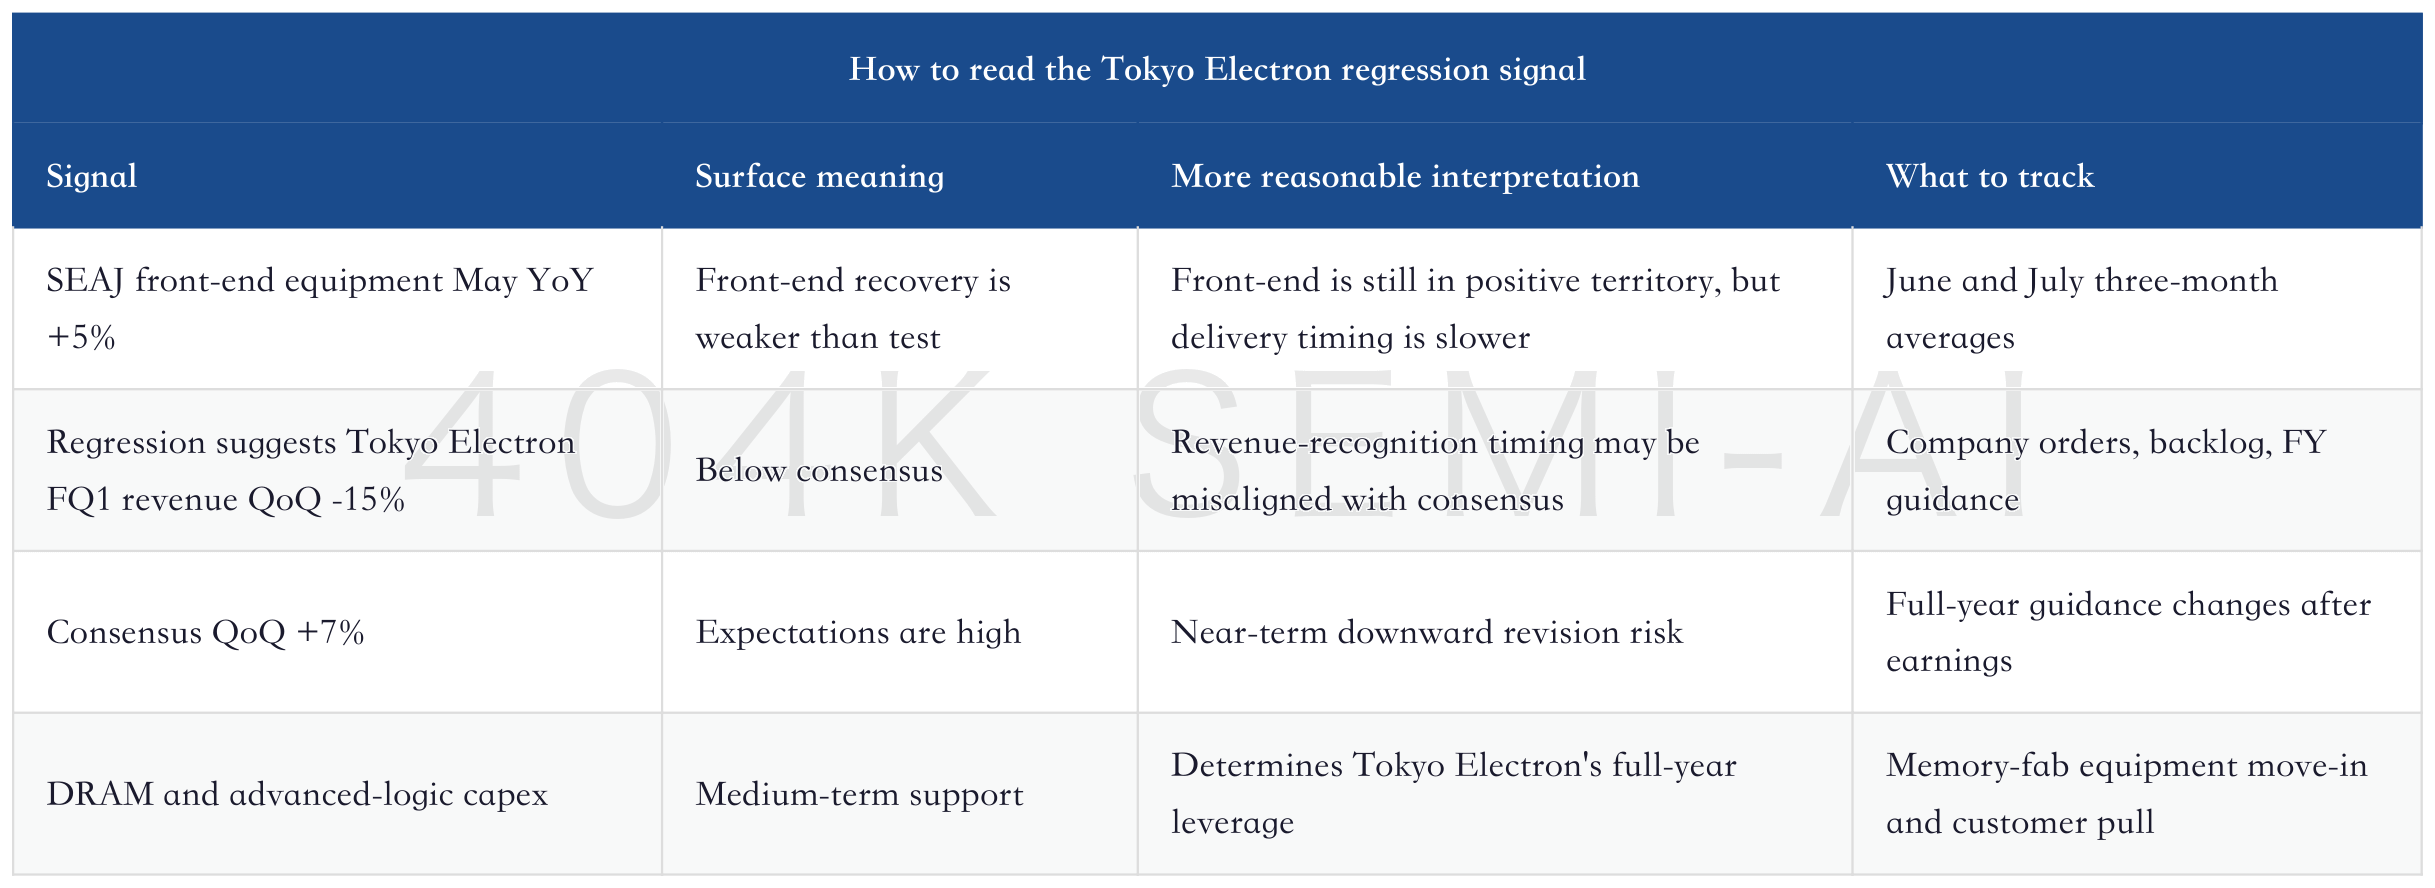
The most controversial point in the report is the regression of Tokyo Electron's June-quarter revenue using SEAJ front-end equipment data, which suggests a QoQ decline of roughly 15%, while consensus still expects about 7% QoQ growth. This looks like a negative signal, but it should not be read simply as front-end cycle weakness.
First, the regression uses only two months of data. The direction is informative, but it is not a full quarterly revenue forecast. Equipment revenue recognition is affected by large-project delivery, installation and acceptance, customer schedules, FX, and product mix. A weak single-quarter regression may mean Tokyo Electron's FQ1 recognition timing is slow, or it may mean consensus is too high. It does not necessarily mean full-year orders are insufficient.
Second, May front-end equipment still grew 5% YoY and did not turn negative. It was simply not as strong as test equipment. Front-end equipment has a larger base and a longer cycle, so billings acceleration often lags test and packaging. The real drivers of Tokyo Electron's full-year profit are whether DRAM expansion, advanced-logic equipment move-in, equipment pricing, product mix, and customer capex continue to be revised upward, not one month of data.
Third, Tokyo Electron is not a single-category front-end equipment asset. It covers coating/developing, etch, deposition, cleaning, and other segments. It benefits from DRAM and NAND as well as advanced logic and higher customer equipment intensity. As long as global WFE continues to rise, Tokyo Electron remains Japan's aggregate equipment asset. A near-term FQ1 miss versus consensus may instead pull the market back from "only looking at aggregate volume" toward delivery timing and margins.
Japan Semiconductor Equipment Deep Dive: Goldman Sachs Raises Target Prices for 10 Companies by 16%, AI WFE Enters the Profit-Conversion Phase
This also explains why Japanese equipment stocks now need to move from an aggregate-volume trade to a company-specific trade. Tokyo Electron may still benefit from WFE for the full year, but quarterly timing will be volatile. Advantest is stronger near term, but high YoY bases need to be watched. Disco benefits from advanced packaging, but order timing is linked to HBM and CoWoS capacity. Kokusai Electric needs clearer NAND and batch-deposition demand. SCREEN depends on cleaning-equipment customer mix and margins.
Investors should not use one month of SEAJ data to buy or sell Tokyo Electron mechanically. A more reasonable approach is this: if FQ1 is below consensus but full-year guidance is not weak, and DRAM/logic customer orders remain strong, a pullback may offer a better medium-term entry point. If FQ1 is below consensus and full-year orders, margins, and pricing all weaken, then actual front-end cycle conversion would be below the model.
5. Packaging Equipment Is Recovering Steadily, and Disco's Logic Remains the Advanced-Packaging Processing Bottleneck
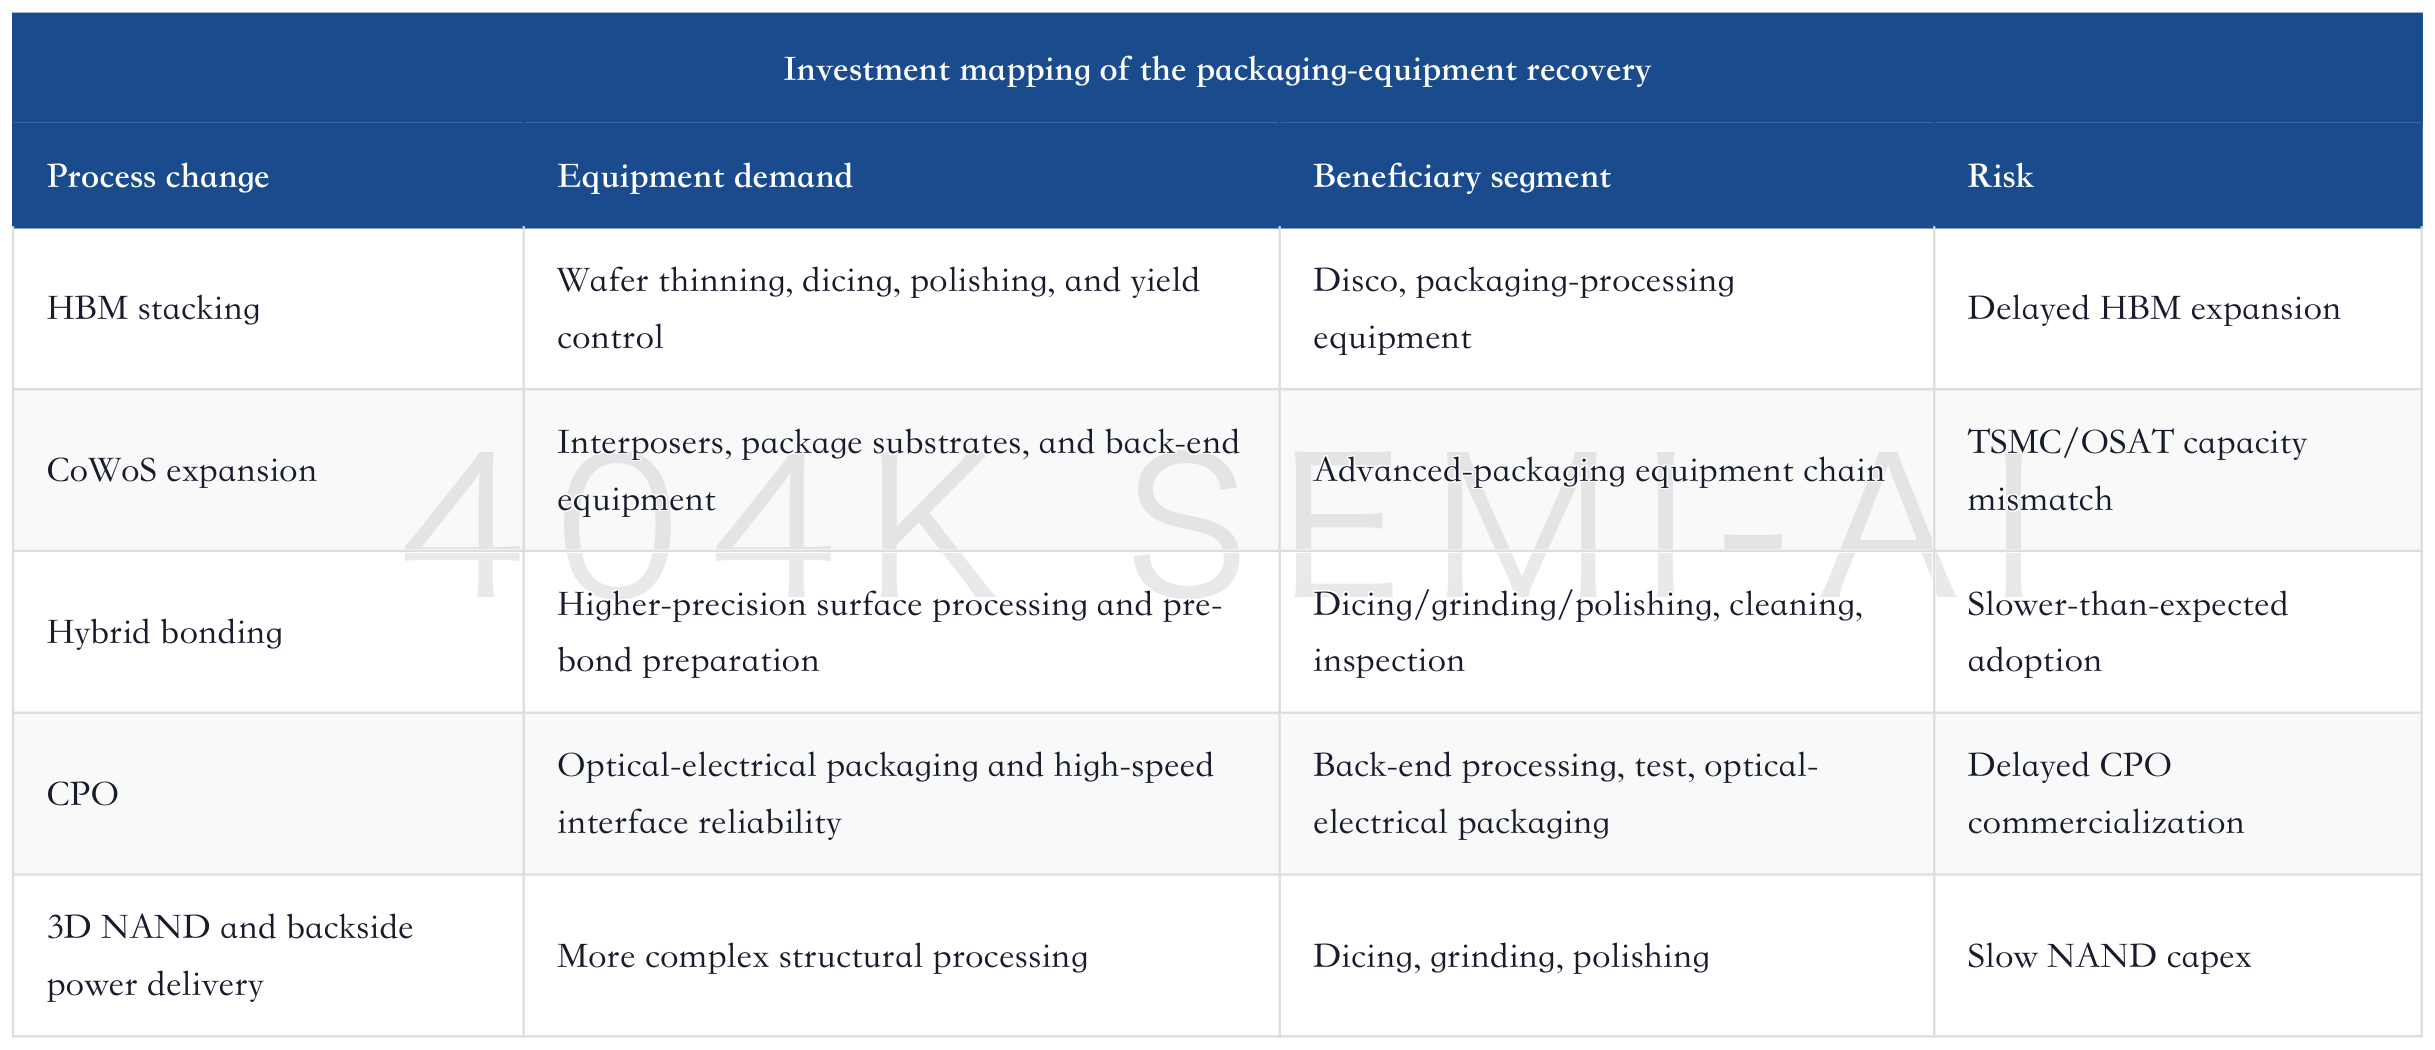
In May, Japan packaging equipment billings rose 12% YoY and 7% MoM. The data is not as dramatic as test equipment, but the direction is good. Advanced packaging has moved from a theme word in the AI chain into real incremental equipment billings. HBM, CoWoS, hybrid bonding, EMIB-T, CPO, and high-density packaging all require more dicing, grinding, polishing, pre- and post-bond processing, and yield control. Disco is the core Japanese company in this line.
Disco's strengths are grinders and dicers. The report notes that it has high market share in these tools and benefits from medium- and long-term process changes including advanced packaging, HBM, CoWoS, hybrid bonding, 3D NAND, and backside power delivery. The market often simplifies Disco as "back-end equipment," but what it really captures is process complexity. The more complex AI packaging becomes, and the more precise wafer and chip handling needs to be, the higher the value of dicing, grinding, and polishing.
The pull from advanced packaging is not only CoWoS. CoWoS is just the first stage. HBM4, hybrid bonding, CPO, panel-level interposers, backside power delivery, and thinner wafers will all bring new process requirements. Companies like Disco benefit from the "front-endization" of packaging: back-end processing precision increasingly resembles front-end manufacturing, raising equipment barriers and customer stickiness.
Japan and Korea AI Semiconductor Supply Chain Deep Dive: Japan Equipment and Materials, Korea HBM, and Industrial Automation as the Next Main Line for Asian Tech Revaluation
The significance of 12% YoY growth in packaging equipment is that it gives the advanced-packaging chain a relatively moderate but solid validation. Compared with test equipment, packaging equipment is more likely to show a sustained ramp rather than one-month high elasticity. As long as AI GPUs and HBM remain in shortage, advanced-packaging capex will not disappear quickly. Disco, selected packaging equipment, probe cards, carriers, substrate materials, and test equipment will together form the second-layer profit pool of the AI hardware cycle.
6. Aggregate WFE Upgrades Are Now Consensus; the Debate Is Structure and Timing
The report expects global WFE to grow 21.4% YoY in 2026 and 18.2% YoY in 2027. This is consistent with the recent direction of upgrades from multiple institutions: equipment demand is strong in 2026 and continues to grow in 2027. Growth mainly comes from the recovery in DRAM and NAND capex, while advanced logic, AI chips, and regional manufacturing policies also support equipment investment.
But the market has already seen the aggregate upgrade. Over the past few weeks, equipment stocks, memory stocks, advanced packaging, and the test chain have already traded the "WFE supercycle." What matters next is not saying again that WFE is good, but breaking down the structure: whether DRAM expands before NAND, whether test converts before front-end, whether TSMC advanced logic follows memory, whether Intel and Samsung Foundry can contribute incremental demand in 2028, and whether China's WFE scale and localization share continue to support A-share equipment companies.
Equipment Capex Ledger Update: AI Financing, $250 Billion WFE, and Semiconductor Equipment Repricing
The structural answer from this SEAJ data is: test is strongest, packaging continues to recover, and front-end has turned positive but remains differentiated in timing. This sequence fits the logic of the AI hardware cycle. AI chips and HBM first bottleneck test and advanced packaging; then memory and logic fabs add front-end capacity for long-term supply. Front-end equipment has the largest dollar value, but recognition is slower. Test and packaging are closer to delivery bottlenecks, so billings reflect the change faster.
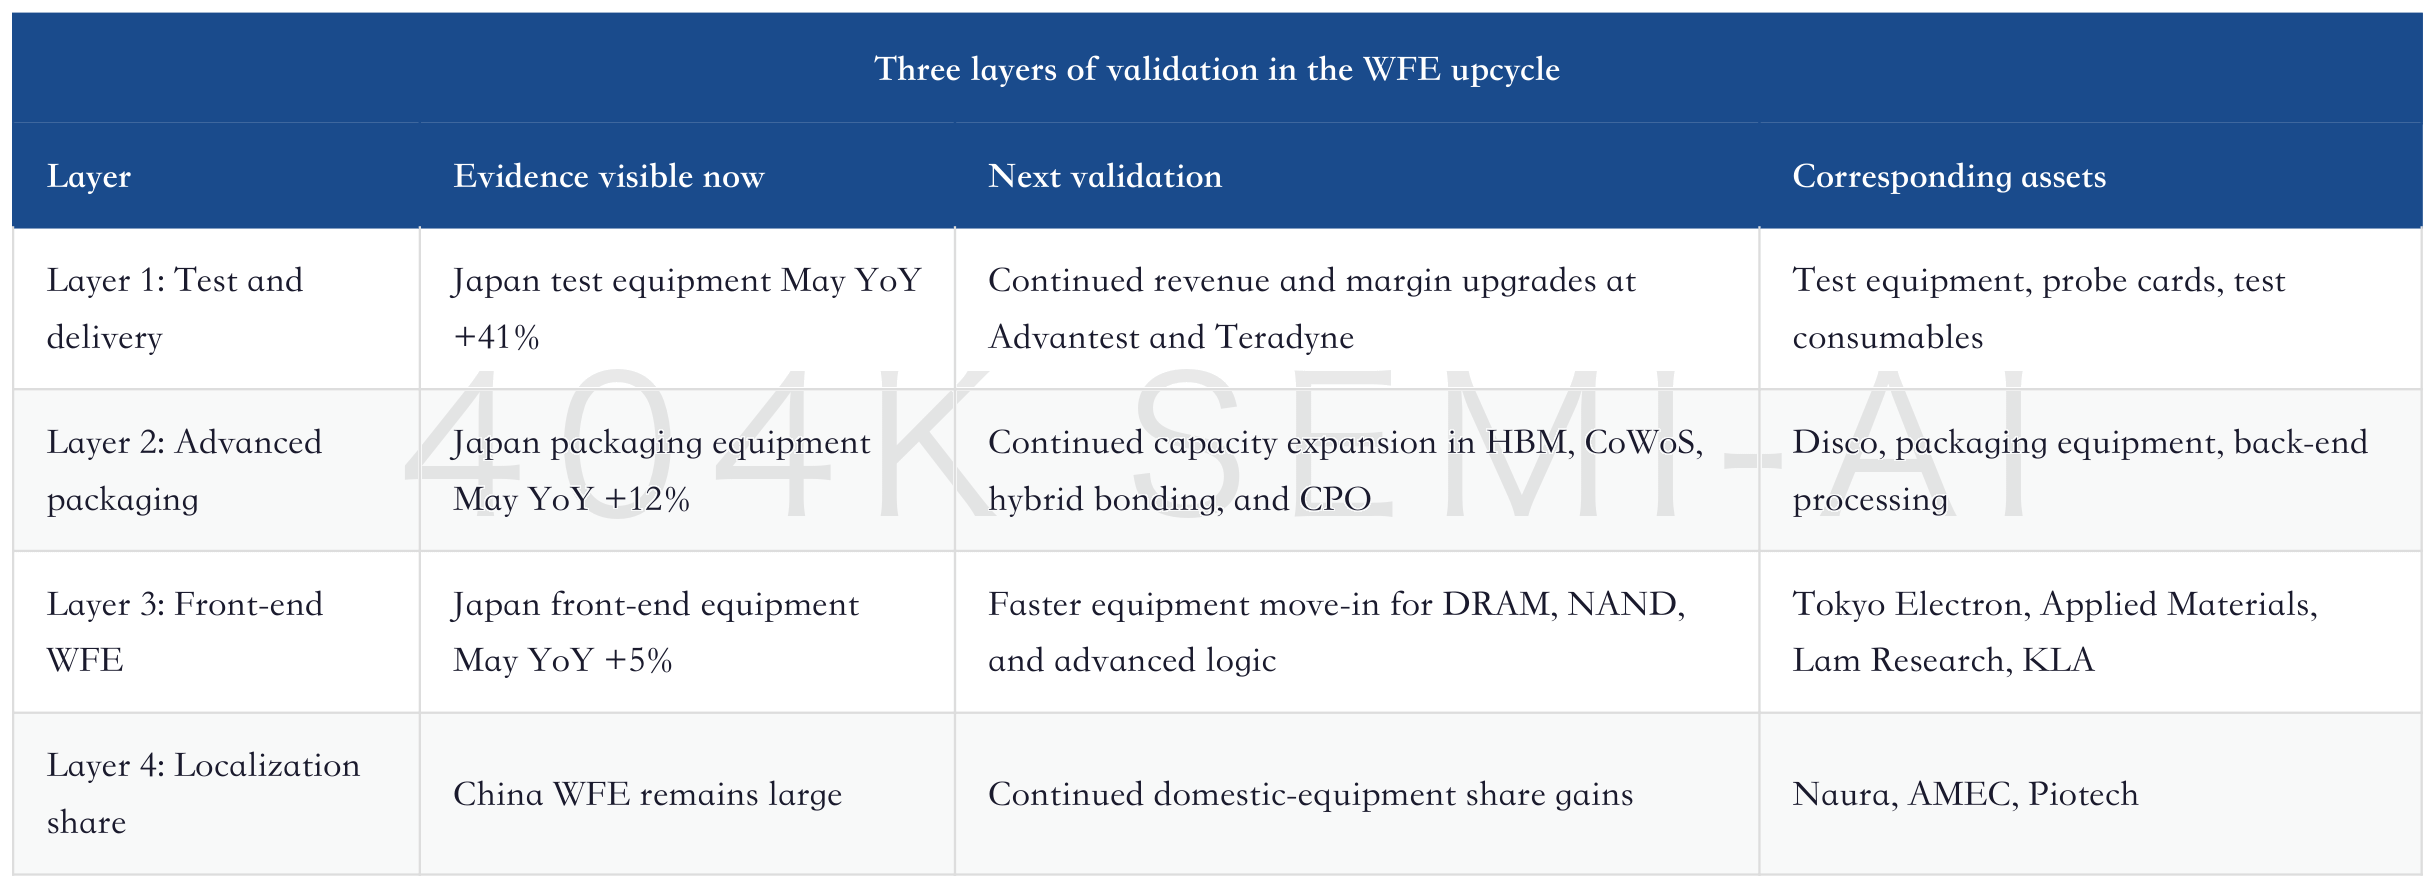
This framework also explains why equipment stocks cannot be analyzed with a single indicator. When aggregate WFE is revised upward, all equipment companies benefit. But in the differentiation phase, the market rewards segments where high-frequency data converts first, margin leverage is clearer, and technical barriers are harder to replace. Test and packaging are near-term, DRAM front-end is mid-phase, advanced logic and NAND are later, and Chinese localization is an independent share-gain logic.
7. Company Differentiation: Buying Japanese Equipment Is Not Buying a Basket, but Buying Different Bottlenecks
The rating mix in this report is interesting: positive on Disco, Advantest, Tokyo Electron, Kokusai Electric, and Lasertec, while relatively cautious on SCREEN. The logic behind this mix is not "all Japan equipment is good," but classifying the equipment chain by bottleneck type.
Advantest corresponds to the AI test bottleneck. The report notes that it has a strong position in HBM test and Nvidia AI GPU test. Rising AI chip complexity should continue to support test-platform ASPs and revenue. Its issue is that valuation and expectations are already high, so orders and margins need to keep proving the case.
Disco corresponds to the advanced-packaging processing bottleneck. It captures HBM, CoWoS, hybrid bonding, and more complex packaging paths. As long as AI chips continue to evolve toward large dies, multi-die systems, high bandwidth, and high reliability, the value of Disco's dicing, grinding, and polishing will not easily disappear.
Tokyo Electron corresponds to integrated front-end WFE. Its near-term quarterly timing may fall below consensus, but it remains the aggregate Japanese equipment asset over the medium term. DRAM, advanced logic, NAND, cleaning, etch, deposition, and coating/developing all affect it.
Kokusai Electric corresponds to batch deposition and NAND/advanced DRAM structures. Its leverage depends more on NAND capex and adoption of batch ALD at advanced nodes. If current capex is still more focused on DRAM and HBM, Kokusai Electric may not move as quickly near term as test and packaging.
Lasertec corresponds to advanced inspection. It is a scarce asset in leading-edge nodes and EUV-related inspection, benefiting from advanced logic and mask inspection. But assets like this usually trade at high valuations and require sustained customer investment in leading-edge nodes.
SCREEN corresponds to cleaning equipment. Cleaning is necessary, but the report is relatively cautious because of margins, customer mix, and competitive pressure from China. Cleaning demand will rise with process complexity, but share-price leverage depends on whether the company can turn demand into high-quality profit.
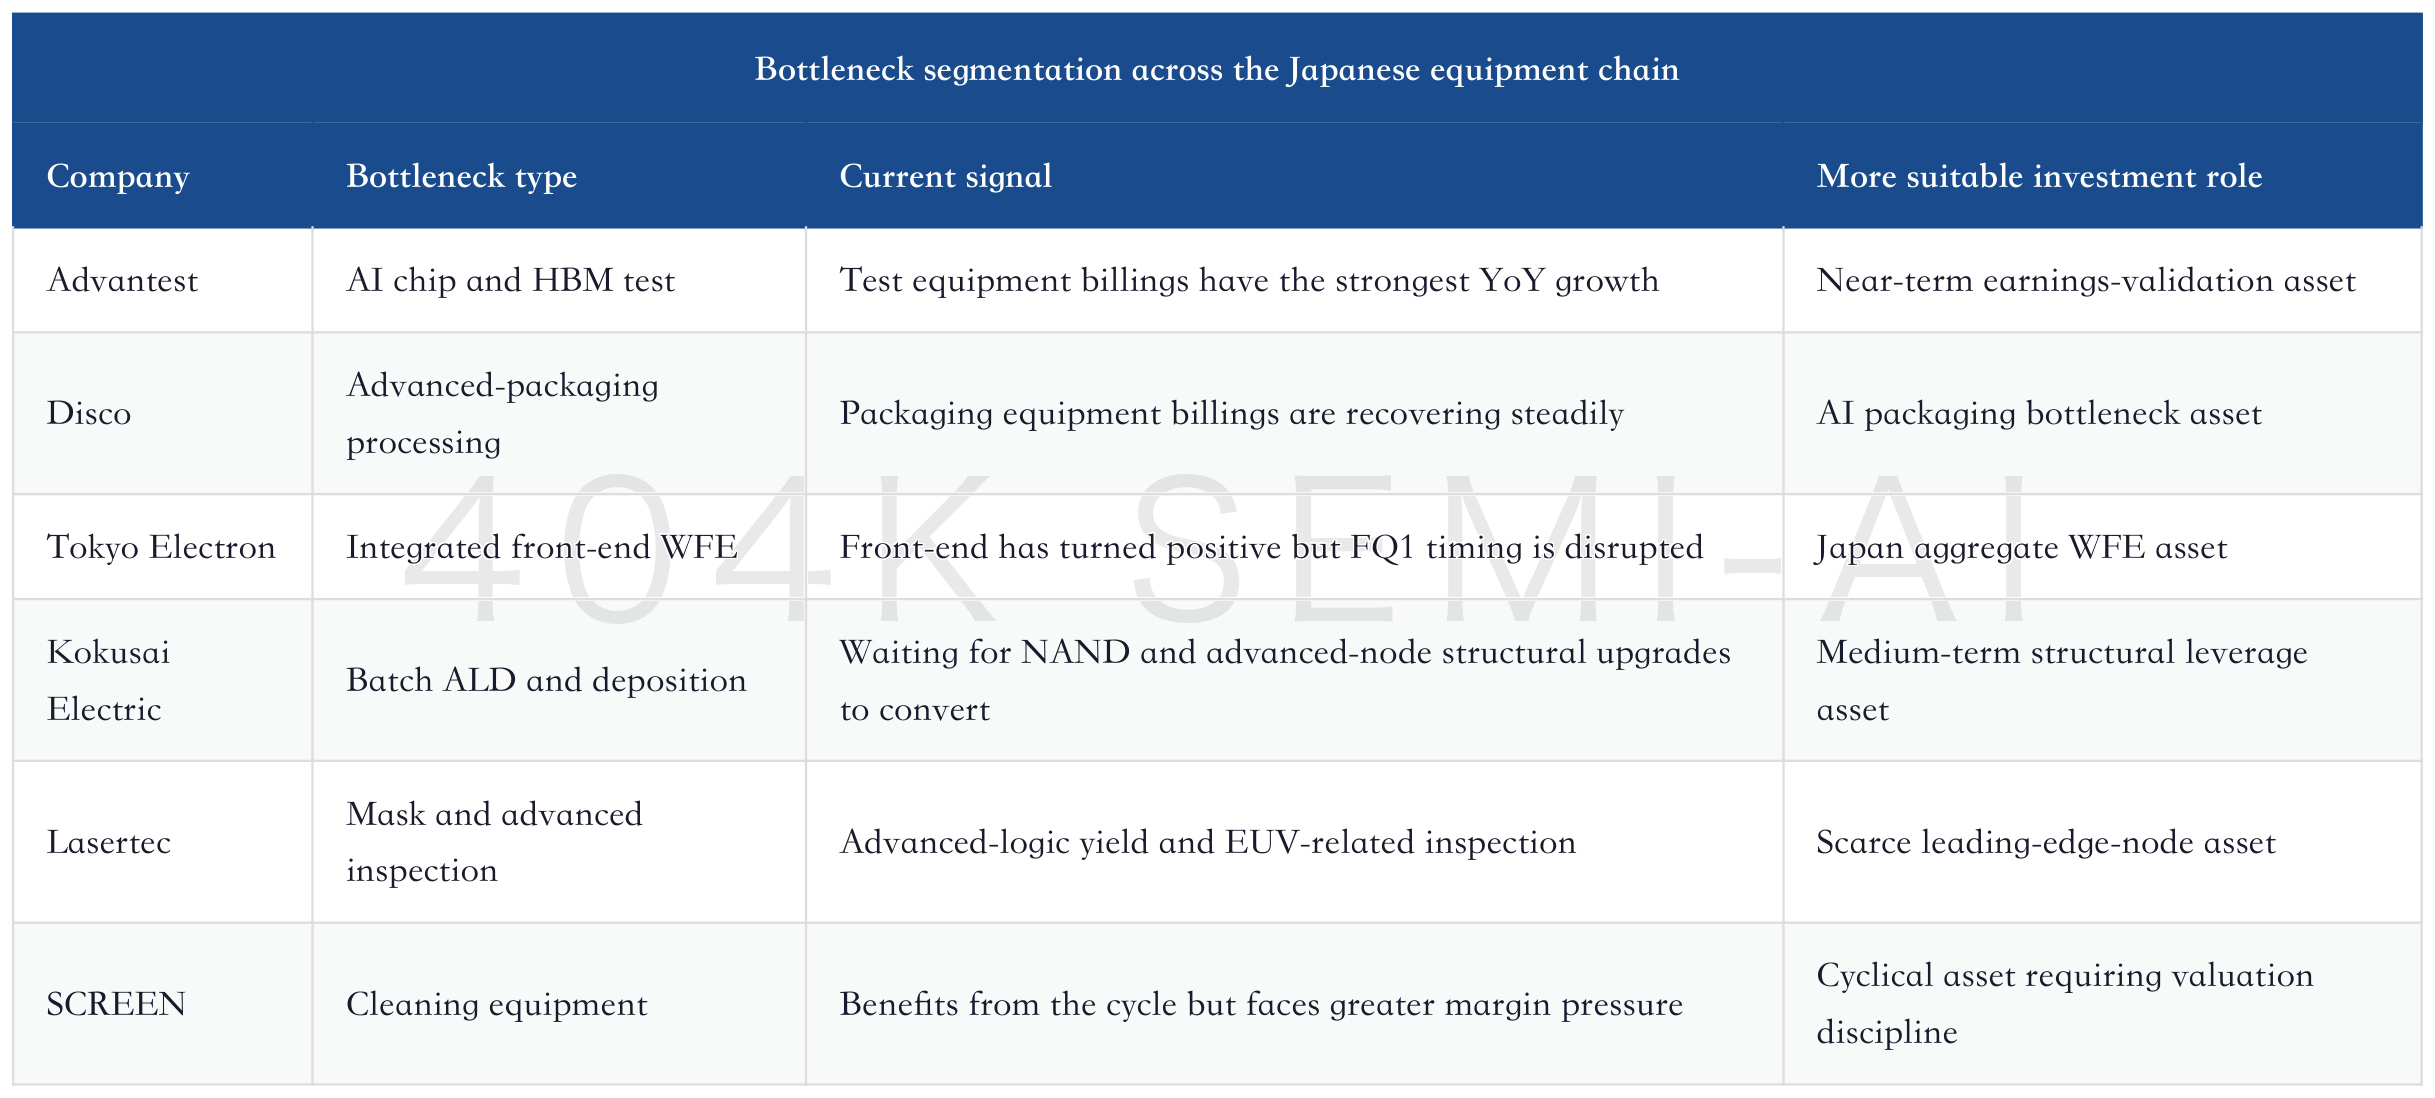
Japanese equipment cannot be treated as "everyone benefits from AI" anymore. Near term, investors should watch whether Advantest and Disco continue to convert; for the integrated cycle, watch Tokyo Electron; for advanced logic, watch Lasertec; for NAND and deposition, watch Kokusai Electric; and for cleaning, require stricter margin validation. This segmentation is more useful than simply buying a Japanese equipment index.
8. How the U.S. and Chinese Equipment Chains Map
Japan SPE data affects the global equipment chain. Among U.S. equipment companies, Applied Materials, Lam Research, and KLA correspond to materials engineering/deposition and etch, NAND and etch, and process control respectively. SEAJ front-end turning positive shows that the WFE cycle direction remains upward, but the early strength in test and packaging suggests the market may increasingly focus on complexity rather than only on front-end tool counts.
Applied Materials benefits most from DRAM, advanced packaging, GAA, and materials-engineering content. Lam Research depends more on NAND and etch intensity. KLA depends more on complex processes, yield, and process control. ASML is the pricing anchor for advanced logic and memory EUV, but this SEAJ data more directly shows strength first in the Japan chain and in back-end test.
Applied Materials Deep Dive: How the WFE Supercycle, DRAM Expansion, and Advanced Packaging Revalue the Profit Slope
The Chinese equipment-chain mapping needs to be viewed separately. The Chinese companies covered in the report include Naura, AMEC, and Piotech. Here, the right framework is China WFE and localization share, not a simple application of Japanese equipment billings. Naura's strength is platform equipment, covering PVD, CVD, etch, thermal processing, cleaning, and other segments. AMEC's core is etch, while it is expanding into more thin-film and epitaxy equipment. Piotech is centered on thin-film deposition, with extensions across PECVD, HDPCVD, SACVD, ALD, and hybrid-bonding-related directions.
Chinese equipment companies benefit from two lines. First, onshore China WFE remains large, with continued equipment demand from mature nodes, memory, specialty processes, and selected advanced nodes. Second, rising localization share allows domestic equipment companies to grow revenue faster than aggregate China WFE. Even if the marginal increase in global WFE comes more from Korea, the United States, Taiwan, and Japan, Chinese domestic equipment companies can still achieve excess growth through share gains.
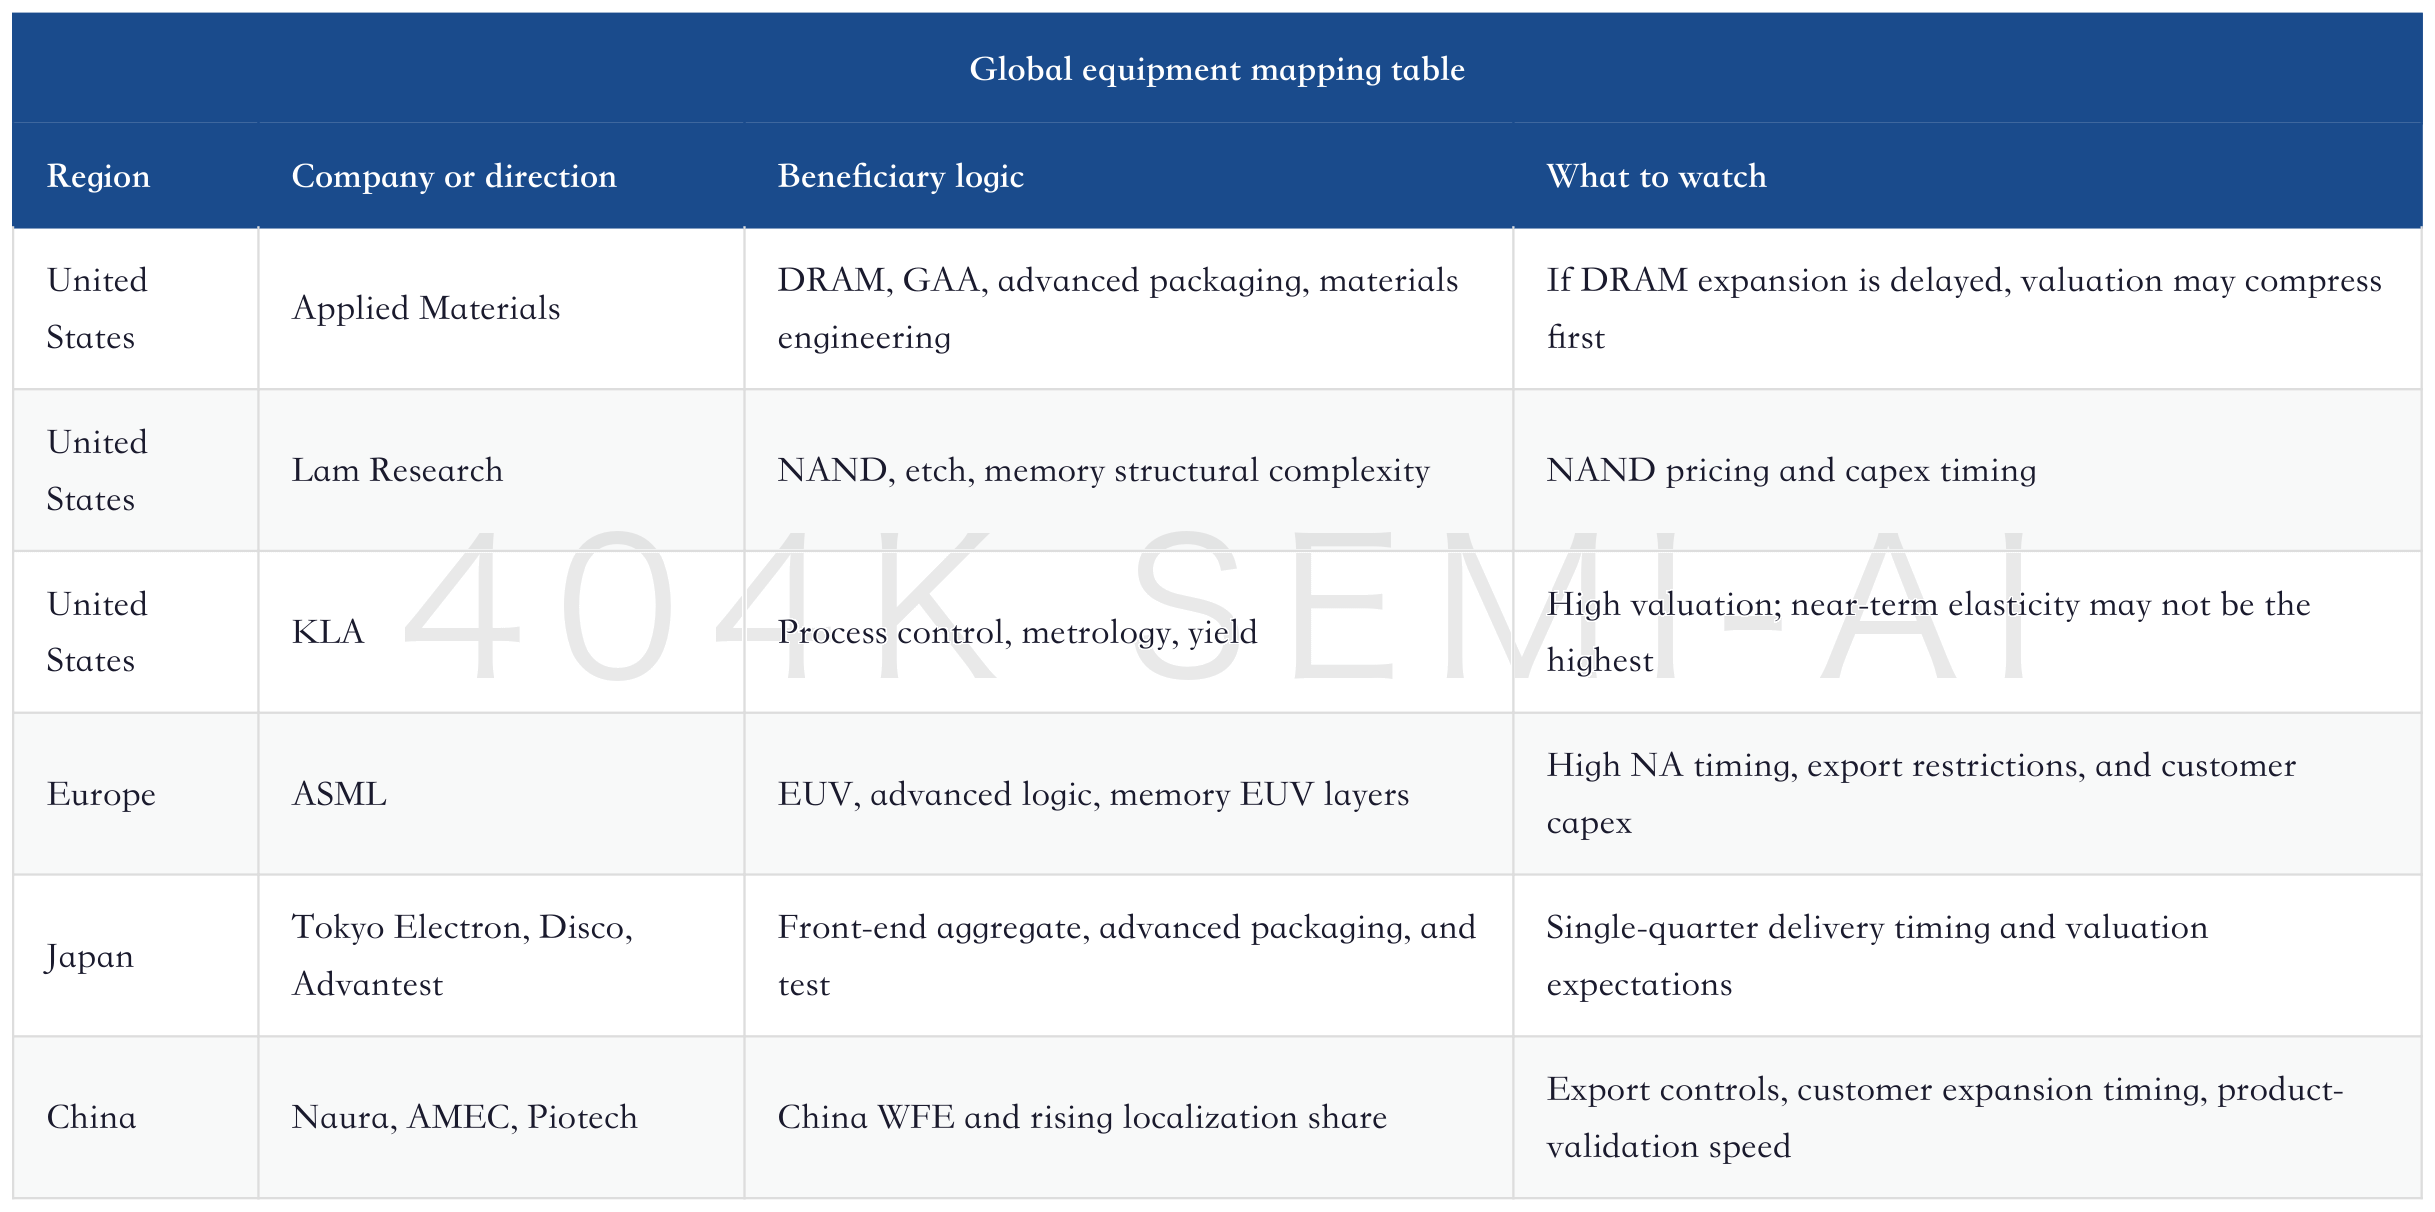
For A-share equipment, the conclusion is not "Japan data is good, so A-share equipment directly follows." A more accurate statement is that the global WFE cycle is continuing to strengthen, raising the strategic value of equipment localization for Chinese customers. The fact that Japanese test and packaging are strengthening first also reminds investors that China's equipment chain should not focus only on mature nodes, but also on product upgrades in advanced memory, advanced packaging, thin-film deposition, etch, cleaning, metrology, and inspection.
9. The Key for A-Share Equipment Is Not Following Japan, but Proving Platformization and Customer Validation
The Chinese equipment chain cannot be traded simply on Japan SPE turning positive YoY. Japan data proves high-frequency improvement in global WFE. What Chinese equipment companies need to deliver is a different logic: against a backdrop of still-large onshore China WFE, can domestic equipment move from point substitution to platform substitution, and from mature nodes to advanced memory, advanced logic, advanced packaging, and key thin-film/etch/cleaning steps? In other words, the core variables for A-share equipment are share and product boundaries, not Japanese billings themselves.
Naura, AMEC, and Piotech are treated in the report as representative Chinese equipment companies for different reasons. Naura is a platform asset, covering PVD, CVD, etch, thermal processing, cleaning, and other areas, with advantages in product breadth and customer stickiness. AMEC's core remains etch, especially CCP and ICP dry-etch platforms, and it continues to expand into adjacent processes such as ALD, LPCVD, and EPI. Piotech's core is thin-film deposition, and its PECVD, HDPCVD, SACVD, ALD, and hybrid-bonding-related directions put it closer to the materials-engineering demand of advanced memory and advanced packaging.
The most important difference among these three companies is how they capture the WFE upcycle. Naura is more of an expression of aggregate China WFE and domestic platformization. AMEC is more of an expression of etch and advanced-process breakthroughs. Piotech is more of an expression of rising thin-film deposition content. If Chinese customers continue to expand DRAM, NAND, logic, specialty processes, and advanced-packaging investment, all three benefit. But if investment is concentrated only in mature nodes and low-margin equipment, profit leverage will diverge sharply.
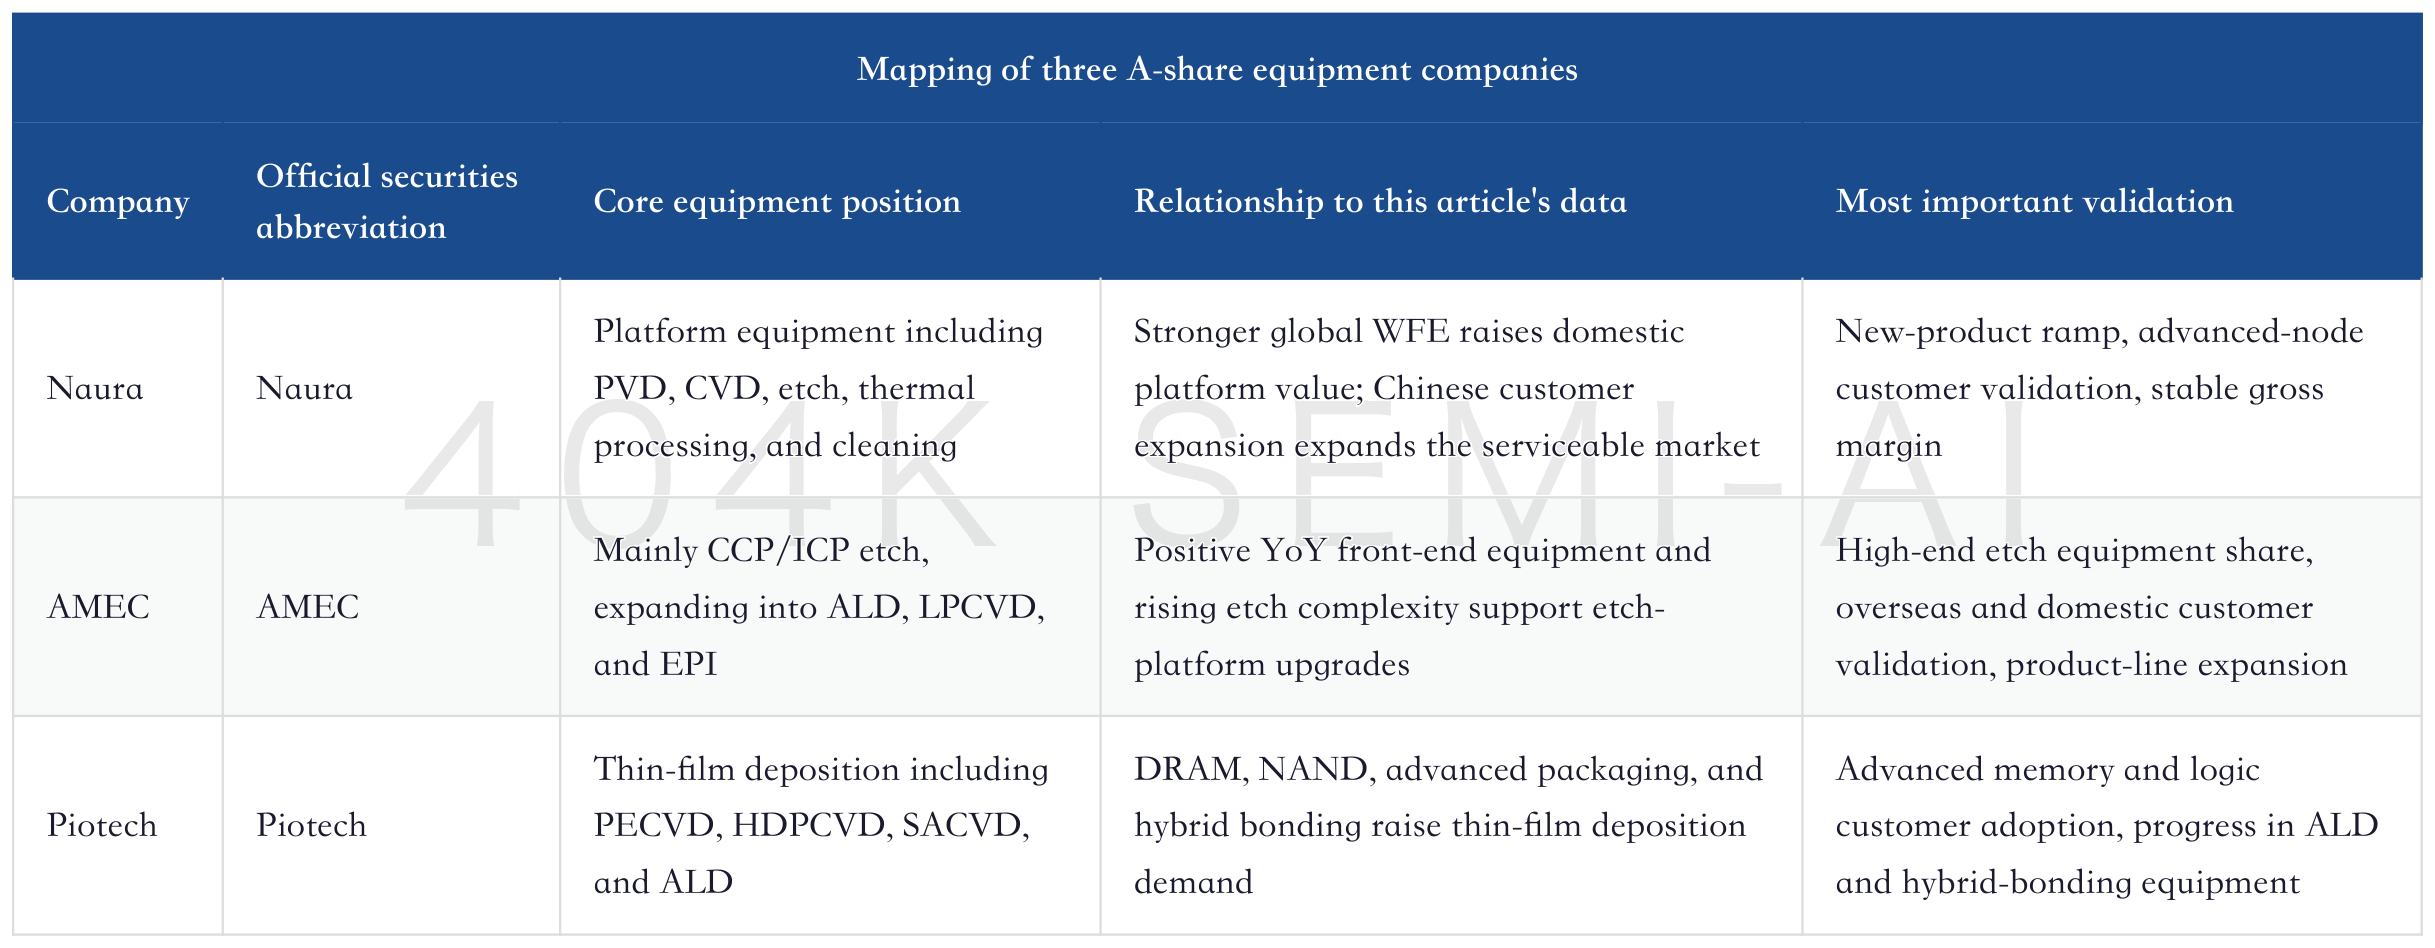
The easiest mistake in Chinese equipment investing is turning "domestic substitution" into an empty phrase. Localization does not happen automatically. It requires customer validation, process stability, yield ramp, spare-parts service, delivery capability, and cost control. Equipment entering the fab is only the first step. Replacement is only successful when tools enter mass-production lines and become a continuing procurement platform for customers. This process is slower than for materials and components, and more dependent on engineering capability than many software-like assets.
The second easy mistake is looking only at revenue growth and not at revenue quality. Equipment companies may ramp volume quickly during an expansion phase, but if orders are concentrated in low-margin mature segments, or if companies sacrifice price to win share, revenue growth may not bring margin improvement. Platform companies like Naura need multiple product lines to enter high-margin customers at the same time. AMEC needs its etch equipment to keep moving into higher-end processes. Piotech needs thin-film deposition to move from a single tool category into part of the customer platform.
The third risk is confusing global WFE growth with China WFE growth. Marginal global WFE growth may come from Korean DRAM, U.S. advanced logic, Taiwan foundry, and Japan's equipment chain, while Chinese domestic equipment companies depend more on customers in mainland China. If China WFE remains high, domestic equipment still has room. If Chinese customer capex slows, A-share equipment will diverge in revenue timing even if global WFE is strong.
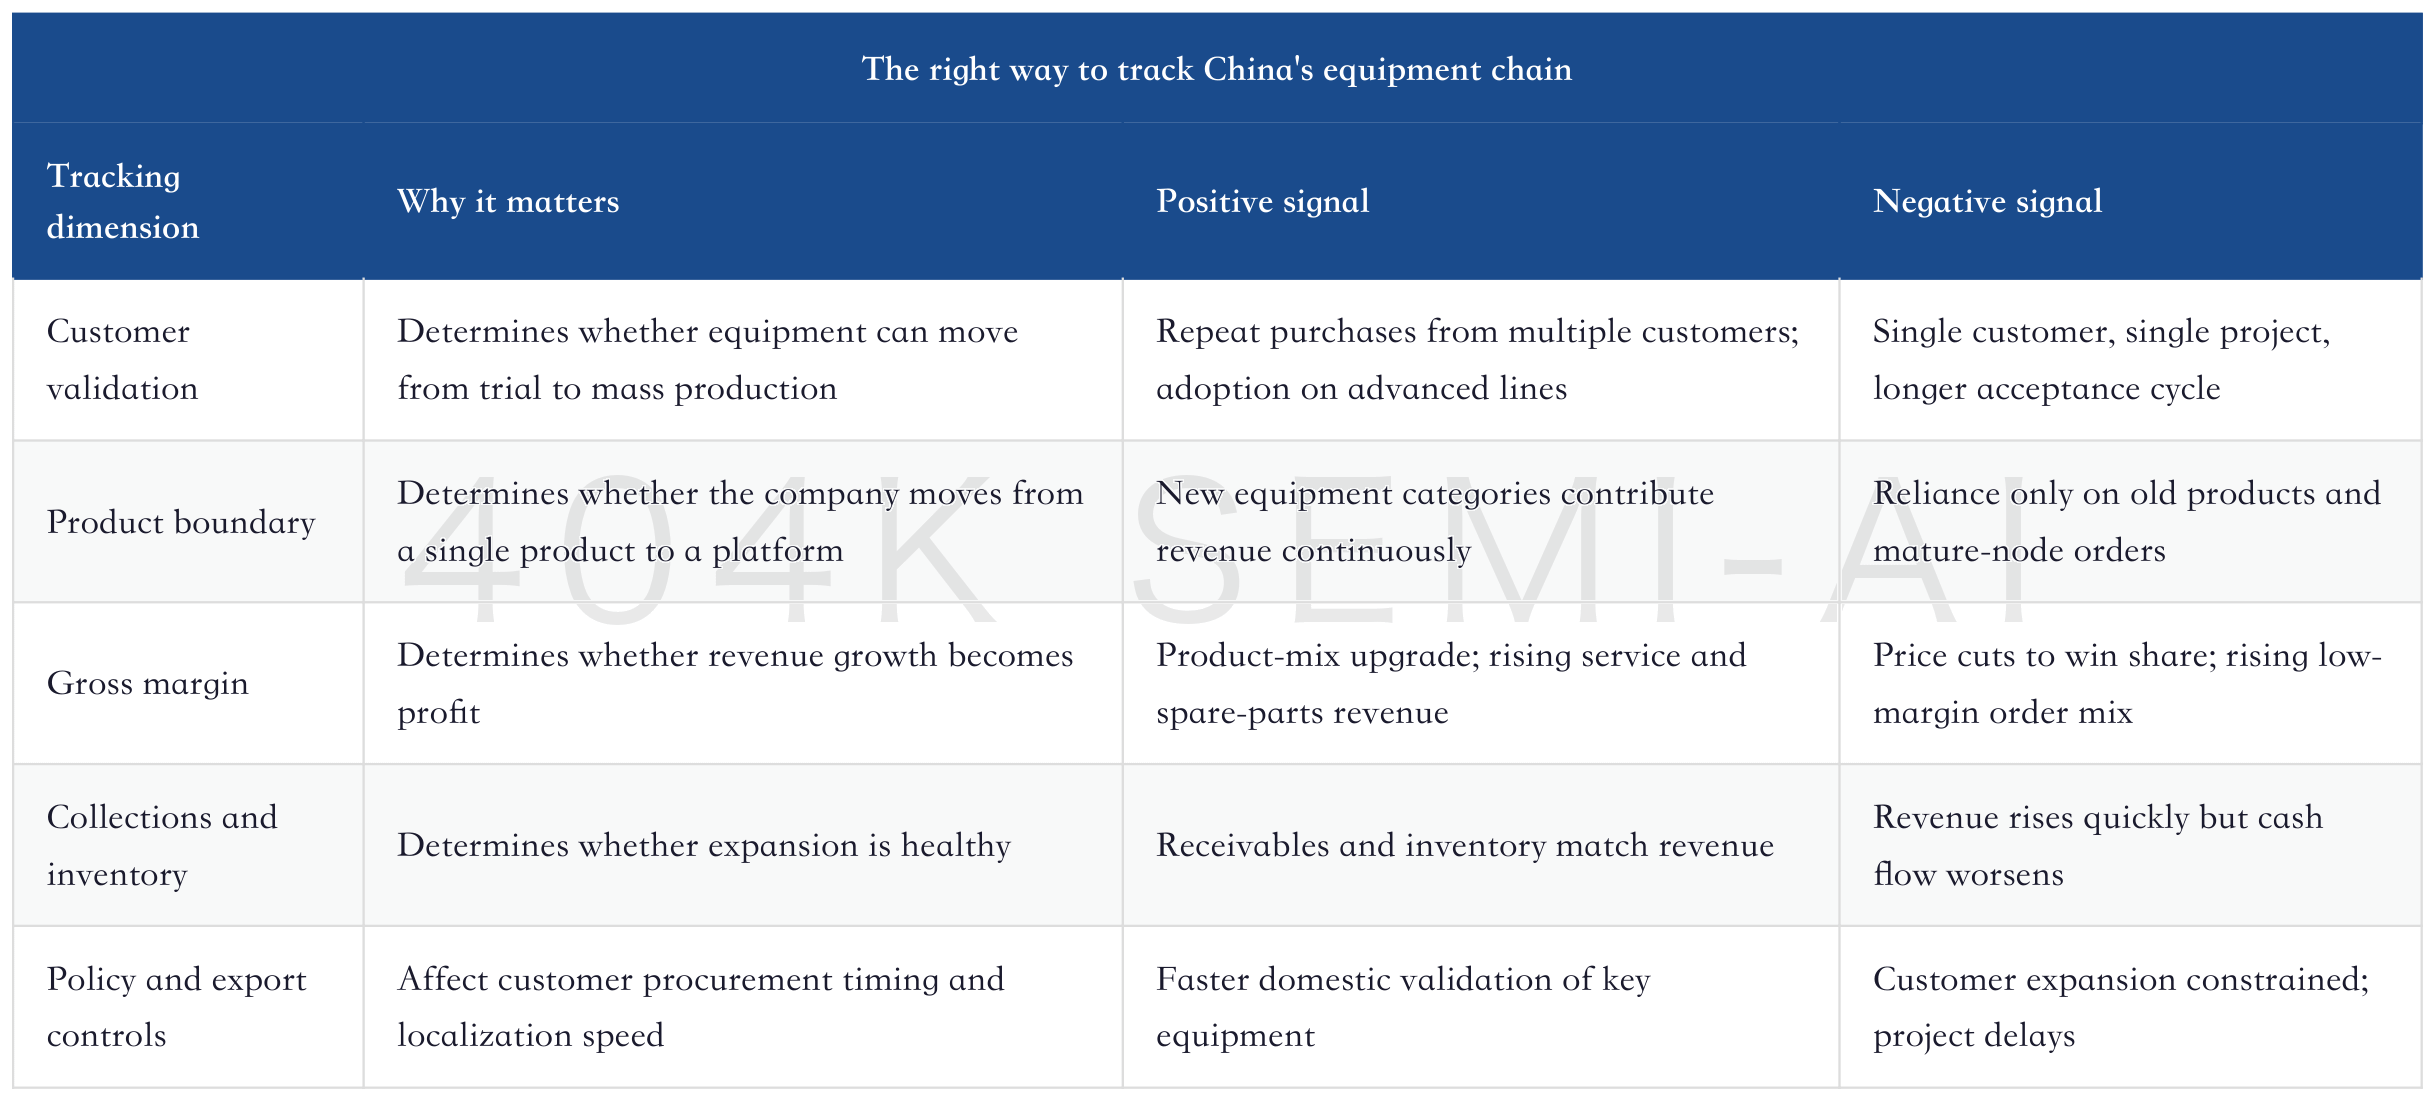
Therefore, the A-share equipment conclusion should be more disciplined. A stronger global equipment cycle is a positive backdrop for Naura, AMEC, and Piotech because it raises the strategic value of customer expansion and supply-chain autonomy. But whether stocks continue to re-rate depends on whether the companies prove three things: first, product boundaries continue to expand; second, high-end customer validation continues to progress; third, revenue growth flows into gross margin and cash flow. Without any one of these, WFE upgrades provide beta, not long-term alpha.
10. How to Price Monthly Billings: From SEAJ to Revenue, Profit, and Valuation
The value of SEAJ data is that it is high frequency, but high-frequency data does not directly equal company profit. Monthly billings must pass through several steps before becoming something equity prices can sustainably discount: billing improvement, order confirmation, equipment delivery, customer acceptance, revenue recognition, gross-margin realization, EPS upgrades, and finally valuation re-rating. Every layer has a time lag and noise.
This is why the same May data can produce two signals: Advantest may be above consensus, while Tokyo Electron may be below consensus near term. Test equipment billings were very strong YoY and have a close regression relationship with Advantest revenue, so they are friendlier for near-term earnings. Front-end billings turned positive but had MoM volatility, and Tokyo Electron is an integrated equipment platform whose revenue recognition is more affected by large-project delivery, so the near-term regression signal is weak. The two signals are not contradictory. They show that revenue-recognition elasticity differs across equipment segments.
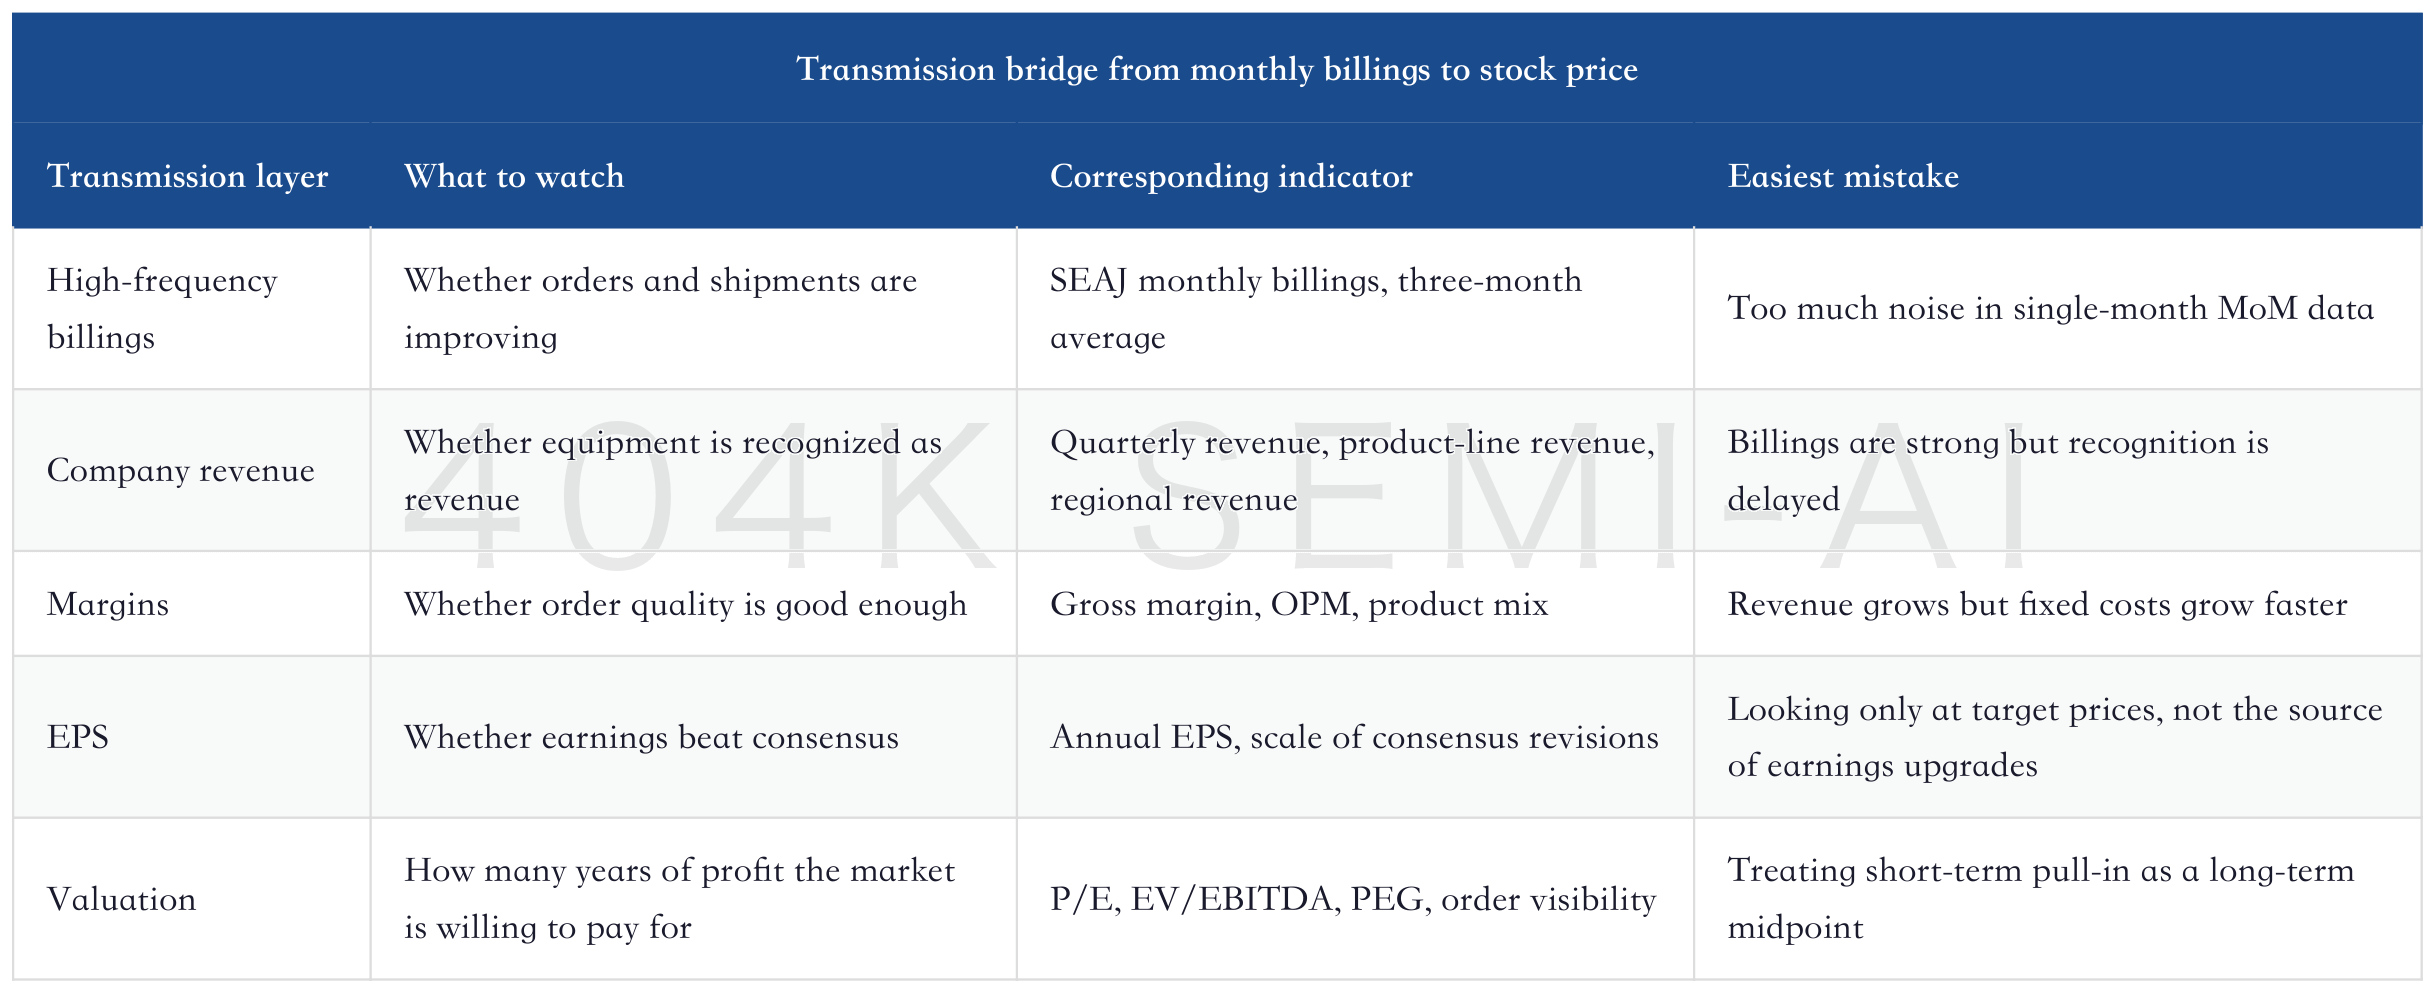
Investors should treat SEAJ data as a validator, not a direct buy/sell signal. If SEAJ strengthens and company earnings also show simultaneous improvement in orders, revenue, and gross margin, the data becomes evidence for earnings upgrades. If SEAJ strengthens but company revenue does not follow, it may be a recognition-timing issue or share loss, requiring further disaggregation. If SEAJ strengthens but gross margin falls, order quality is poor and the stock may come under pressure instead.
Tokyo Electron is a particularly good example. Positive YoY front-end equipment billings prove the industry direction is not bad. A regression suggesting FQ1 may be below consensus indicates near-term revenue recognition may be weaker than market models. What really determines the stock is how the company explains the difference. If the company says orders and full-year guidance are unchanged and only the quarterly timing has shifted, the market will readjust quarterly models. If the company also cuts full-year guidance, then the front-end equipment cycle would be weaker than expected.
Advantest is the opposite. Test equipment billings rose 41% YoY, and the regression suggests revenue may be above consensus. If earnings validate this, the market will begin to re-estimate the growth midpoint of AI test platforms. But if revenue is high while gross margin does not rise, or if orders are concentrated in short-term customer pull-ins, valuation will not expand indefinitely. For test stocks, the next variables are test duration, platform ASP, customer mix, and service revenue.
Equipment-stock valuation needs to move from "revenue elasticity" to "profit elasticity"
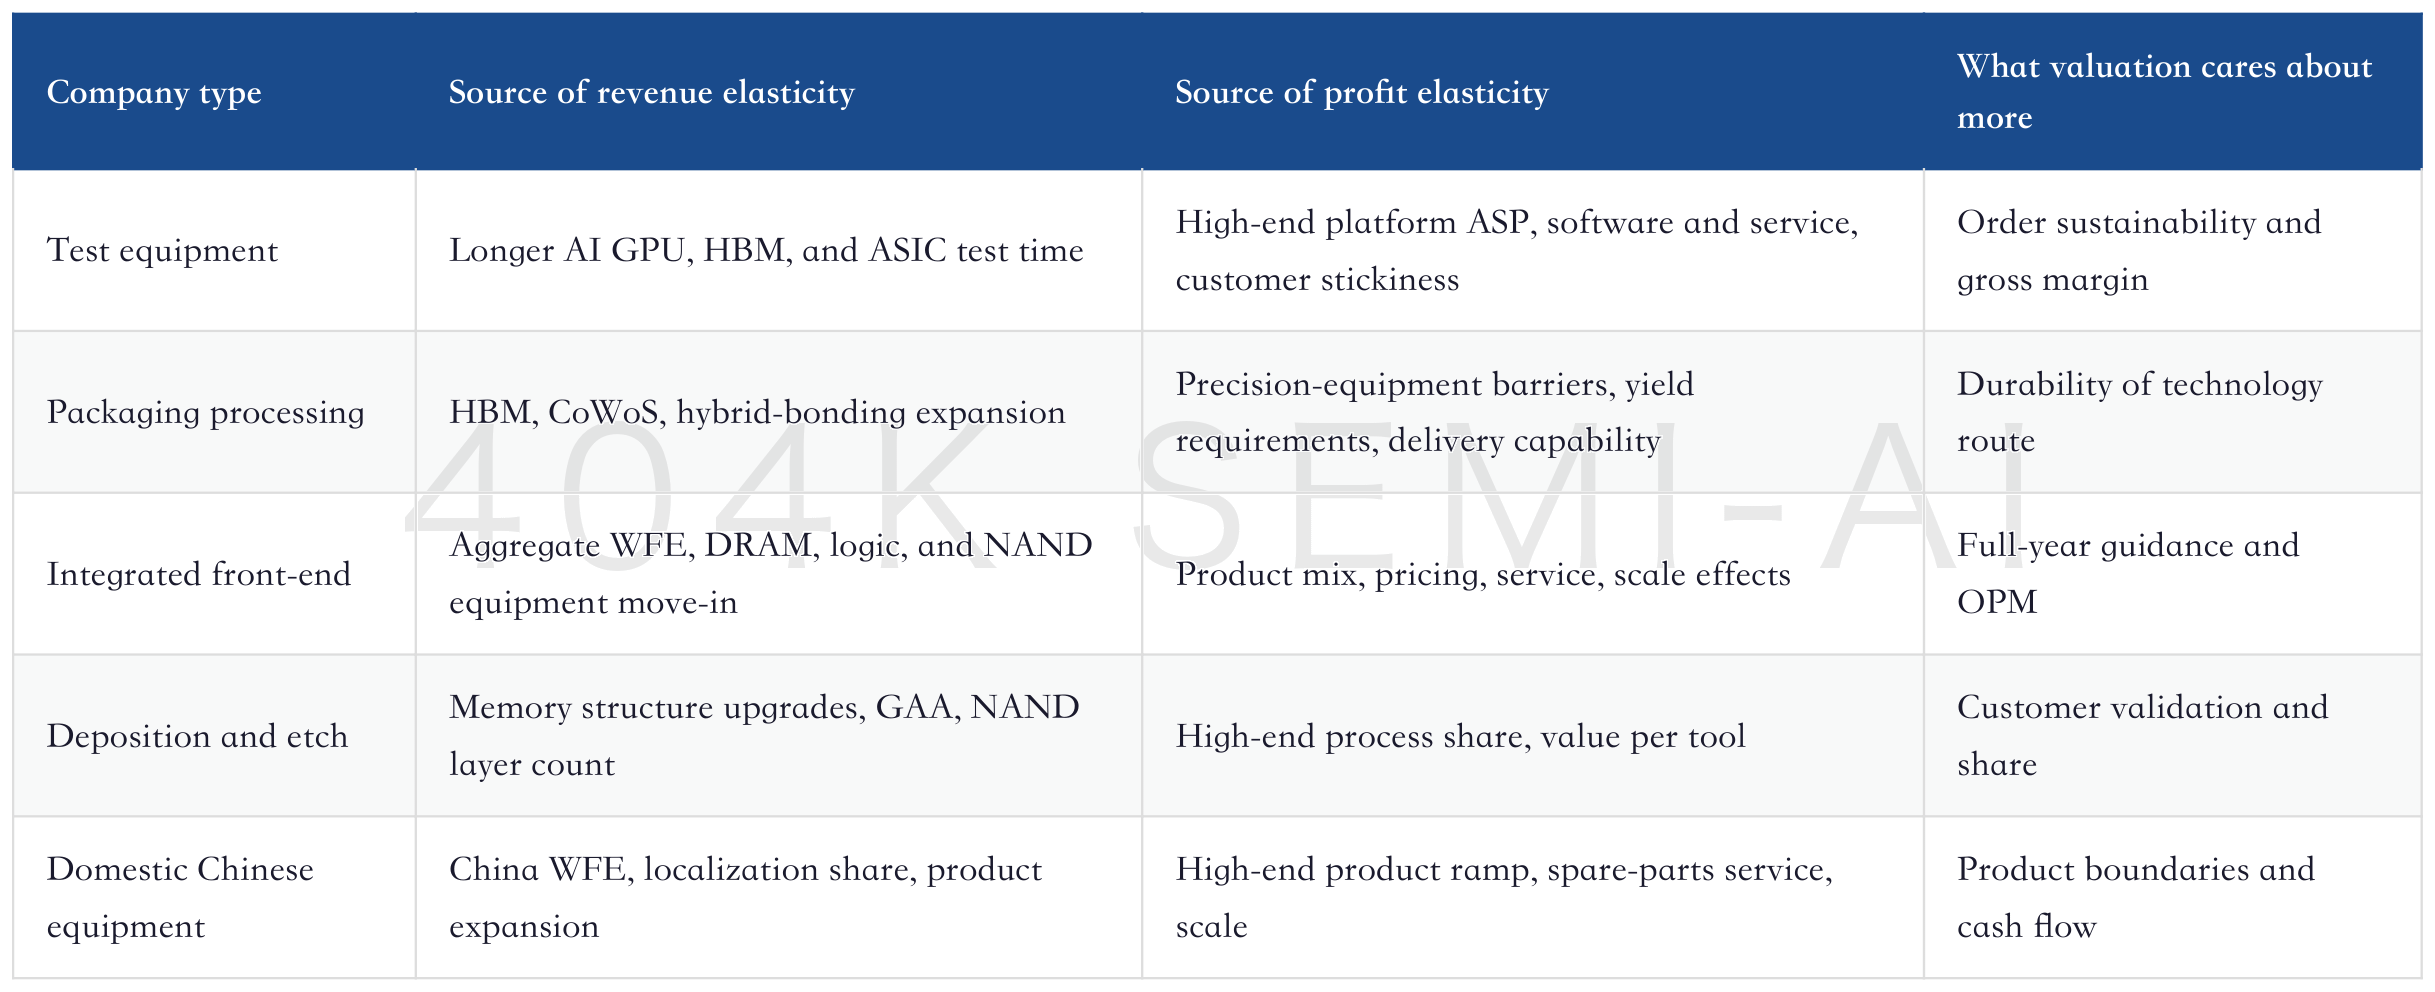
This bridge can also handle valuation disputes. The most dangerous moment for equipment stocks is not necessarily when data weakens, but when share prices have already discounted the next two years of strong demand. If company EPS keeps being revised up, valuation can be absorbed by earnings. If EPS is not revised up and only the industry story remains, the stock may show "good data but no price rise." This is why after the May SEAJ data, investors should watch company consensus revisions more than same-day share-price reactions.
11. Three Scenarios for the Next 6-12 Months
There are roughly three scenarios for the equipment chain over the next 6-12 months.
The optimistic scenario is that test, packaging, DRAM front-end, and NAND equipment all take turns. The SEAJ three-month average continues to rise. Advantest and Teradyne confirm that AI test demand is stronger than expected. Disco and the advanced-packaging chain see orders continue to increase. Tokyo Electron's full-year guidance remains unchanged or is even revised upward after FQ1 timing disruption. DRAM fabs accelerate equipment move-in. NAND recovers from a low base. In this scenario, equipment stocks can maintain high valuations, and the market will continue to move from "WFE beta" to "manufacturing bottleneck assets."
The base scenario is that test and packaging are strong first, while front-end equipment recovers steadily but with quarterly timing volatility. SEAJ YoY growth remains positive, but MoM is not strong every month. Advantest is above consensus, Tokyo Electron is below consensus near term but not weak for the full year, Disco continues to benefit from advanced packaging, and Kokusai Electric and SCREEN need to wait for further validation from NAND and cleaning demand. In this scenario, equipment stocks diverge. Companies with real orders and margins remain strong, while pure industry beta weakens.
The stress scenario is that order pull-forward and valuation overheating appear at the same time. The SEAJ three-month average turns down, high YoY growth in test equipment proves unsustainable, Tokyo Electron and other front-end equipment companies cut full-year guidance, DRAM or NAND customers delay equipment move-in, and cloud capex or AI server deliveries slow. In this scenario, equipment stocks move back from AI manufacturing bottleneck assets to cyclicals. Valuations compress first, followed by earnings downgrades.
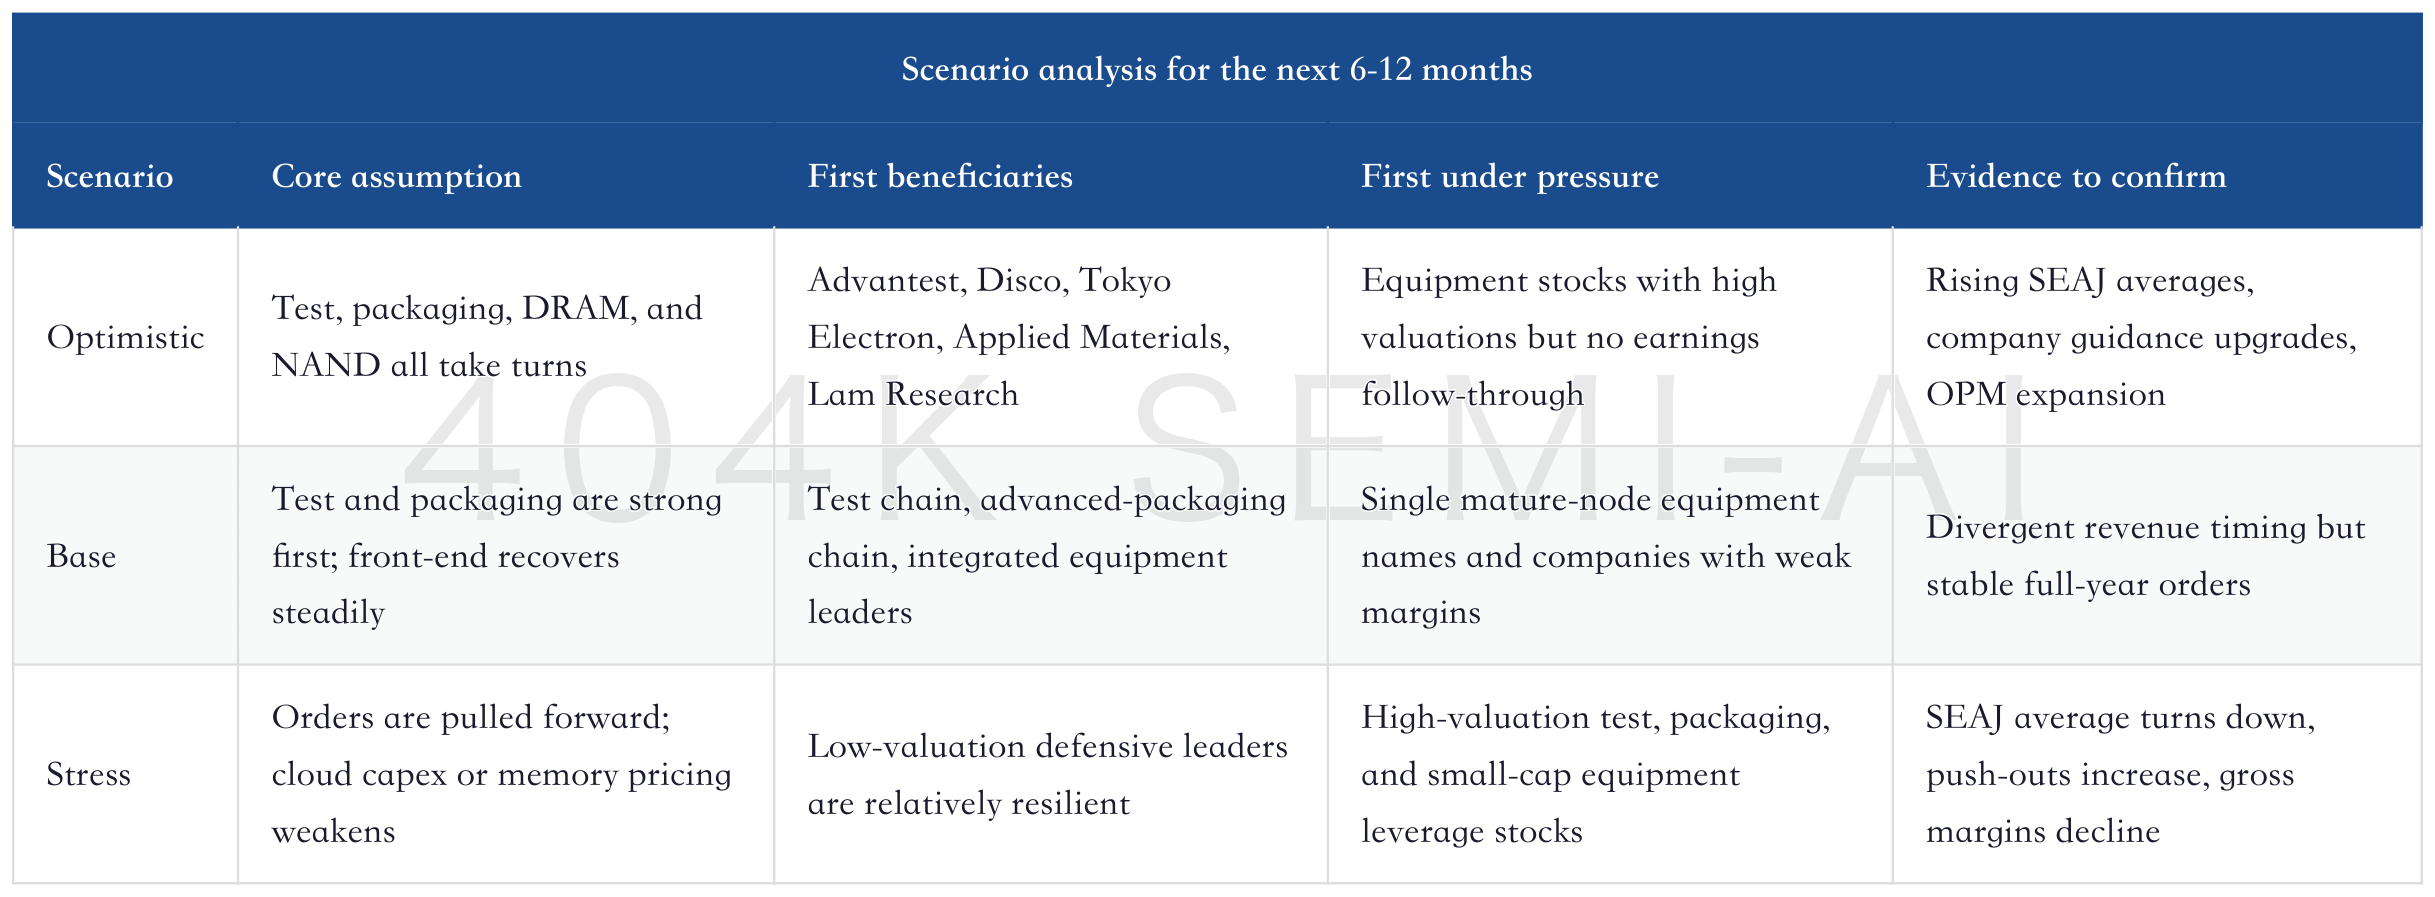
In the optimistic scenario, portfolios should be more offensive. In Japan, watch Advantest, Disco, Tokyo Electron, and Lasertec. In the United States, watch Applied Materials, Lam Research, and KLA. In China, watch high-end equipment validation at Naura, AMEC, and Piotech. In this scenario, test and packaging remain near-term, DRAM front-end is mid-phase, and NAND and advanced logic provide the later phase.
In the base scenario, portfolios should move from beta to selection. In the Japanese equipment chain, Advantest and Disco better explain the near-term data. Tokyo Electron needs earnings to confirm full-year timing. Kokusai Electric needs clearer NAND capex. SCREEN needs margin validation. In the U.S. equipment chain, the relative strength of Applied Materials and Lam Research depends on whether DRAM or NAND becomes the marginal main line. In China's equipment chain, watch high-end product validation rather than just industry sentiment.
In the stress scenario, the first to fall are the segments with the highest valuations and the slowest earnings conversion. If test and packaging have only themes and no profit, they will correct first. If integrated front-end leaders do not see order cancellations, the drawdown may look more like valuation digestion. If domestic Chinese equipment has unstable revenue quality and cash flow, the market will reassess it as well. The stress scenario does not mean AI demand has ended; it means share prices have already bought too much future profit.
The portfolio-level conclusion can be condensed into four points. First, test and advanced packaging remain the strongest near-term validation lines. Second, Tokyo Electron and Applied Materials represent medium-term front-end WFE conversion, but quarterly timing and margins matter. Third, Lam Research, Kokusai Electric, and selected cleaning/etch companies need clearer NAND follow-through. Fourth, excess returns for Naura, AMEC, and Piotech come from localization share and product upgrades, not from simply following overseas equipment higher.
12. Beyond Equipment Orders, Watch Components, Service, and Supply-Chain Constraints
The semiconductor equipment profit pool is not limited to tool makers. The WFE upcycle first enters orders at OEMs such as Tokyo Electron, Applied Materials, Lam Research, KLA, ASML, Advantest, and Disco, then continues to transmit into vacuum valves, pumps, RF power supplies, ceramics, precision machining, motion control, optical components, gas systems, temperature control, probe cards, test interface boards, service parts, and field engineers. The longer the equipment cycle lasts, the more easily these second-tier segments move from "following orders" to becoming delivery bottlenecks.
This is why the SEAJ three-month average matters more than a single month's YoY data. To increase deliveries, tool makers cannot wait until the final quarter to procure key components. Test-equipment volume requires probe cards, interface boards, and customer test programs. Front-end equipment volume requires vacuum, RF, power, ceramics, valves, and precision mechanical supply chains to prepare in advance. Packaging-processing volume requires stable supply of blades, grinding wheels, motion control, and consumables. Sustained improvement in monthly billings implies that supply-chain scheduling may already have started in advance.
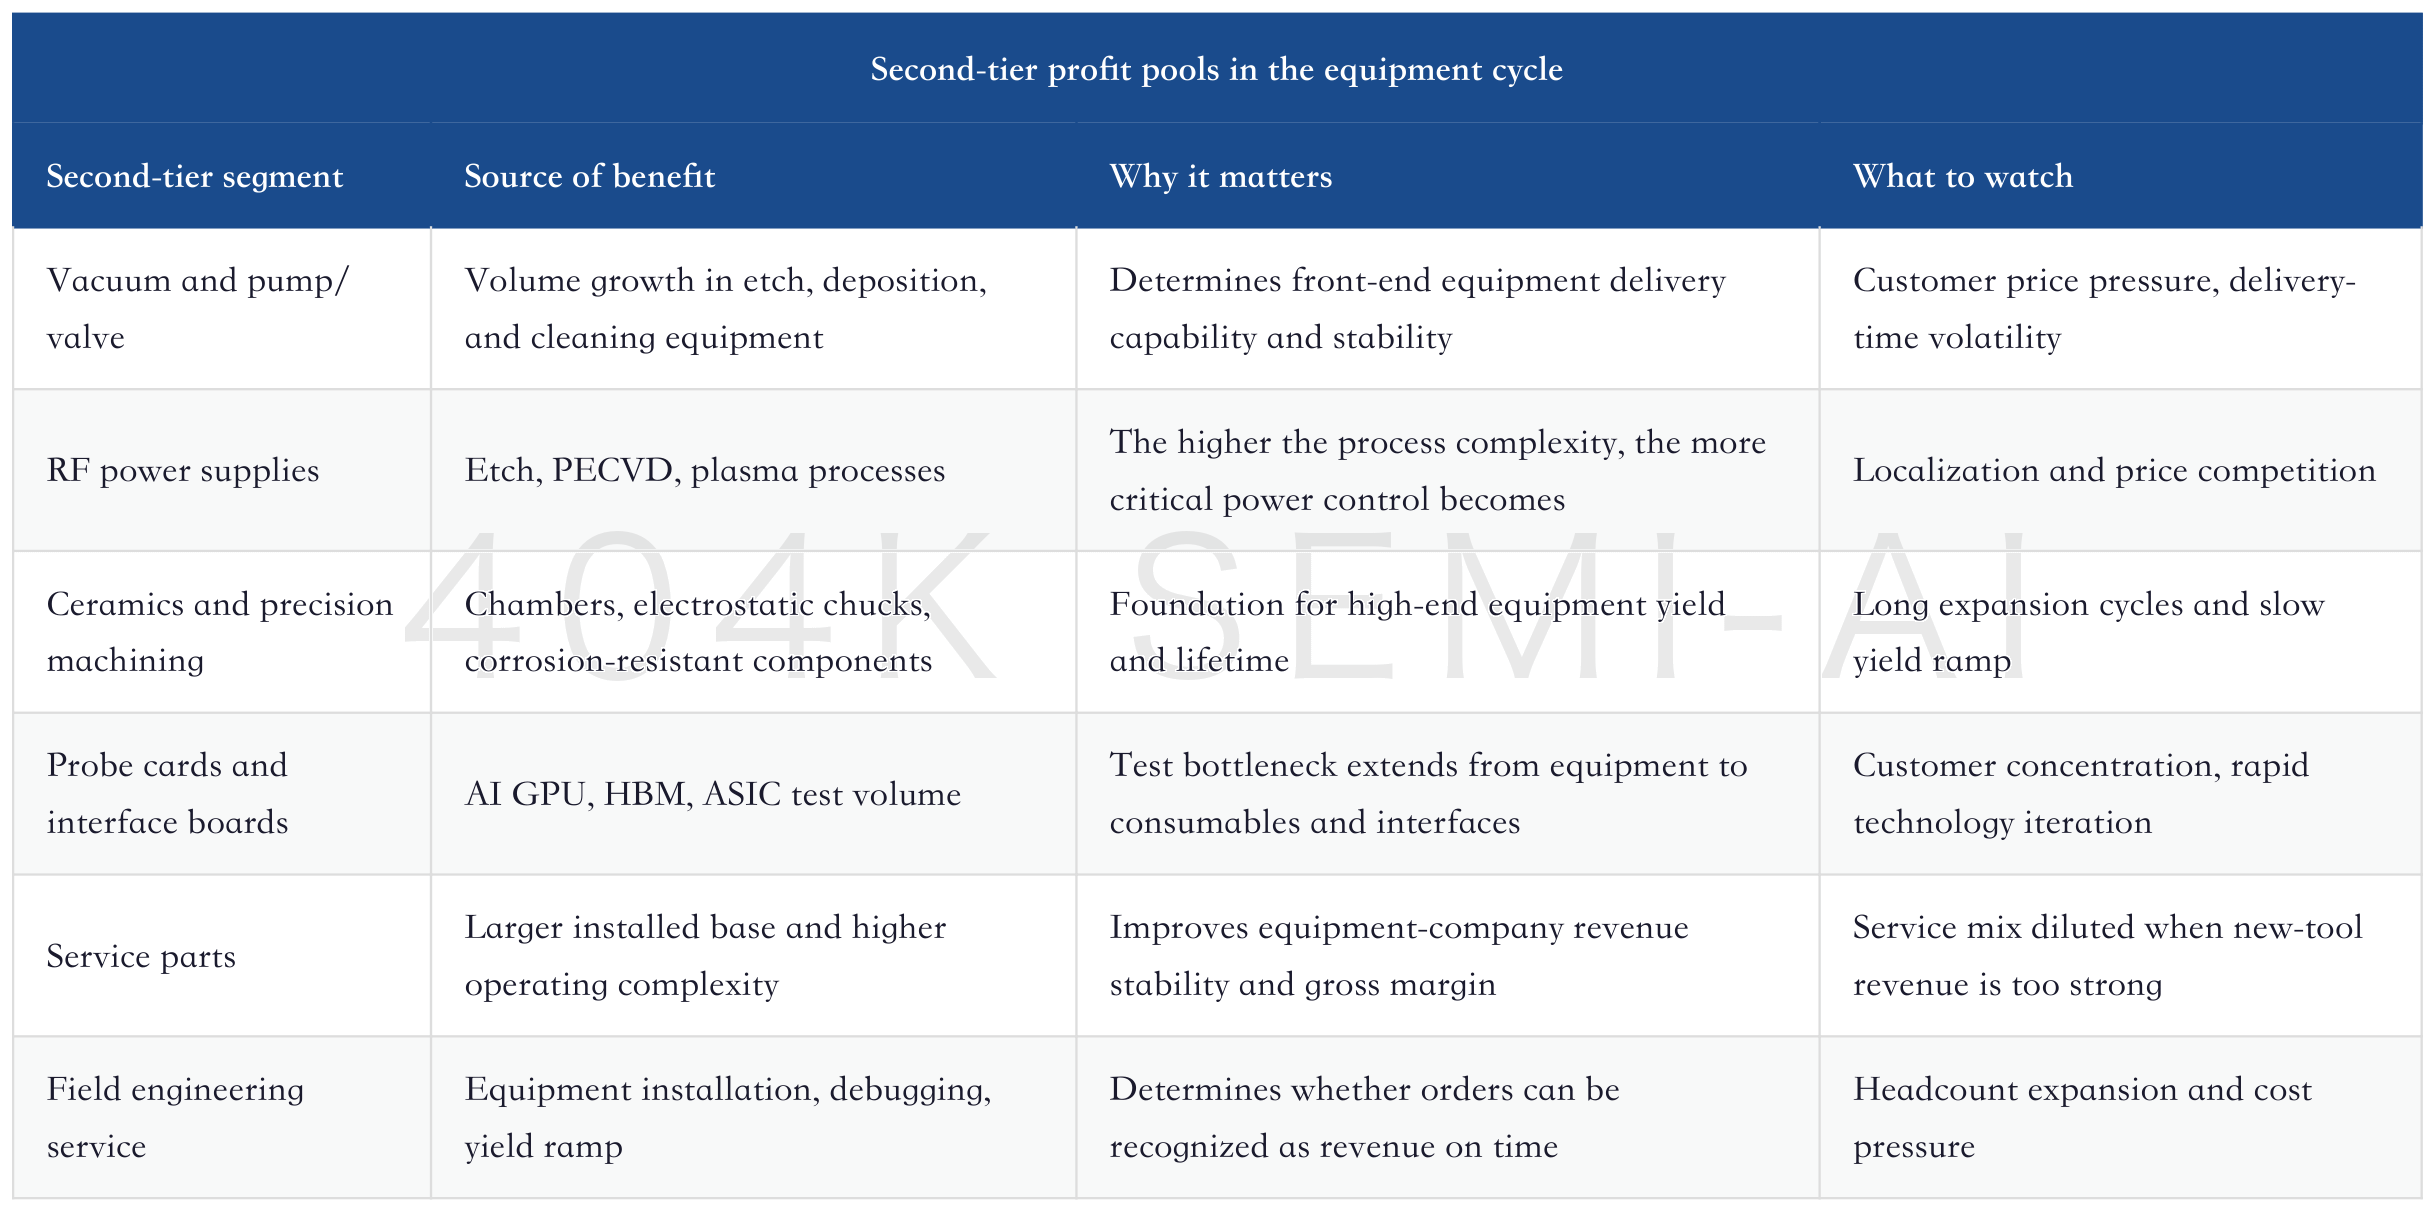
This second-tier chain changes the quality of equipment-company profits. In older cycles, investors focused more on new-tool orders. In the new cycle, service, spare parts, upgrades, and software tuning will become increasingly important. AI chips, advanced DRAM, HBM, GAA, advanced packaging, and high-speed test do not end after equipment is purchased. Customers need continuous tuning, maintenance, yield optimization, and process upgrades. If equipment companies can convert installed base into service revenue, valuation should not be treated entirely like a cyclical stock.
Service-revenue value is especially high for leaders such as Applied Materials, KLA, ASML, and Tokyo Electron. The larger the installed base, the more customers depend on original spare parts and engineering support. Advanced-process equipment cannot be down for long, and downtime cost is often far higher than spare-parts cost. Equipment-company service revenue therefore has stronger stickiness and can make revenue less volatile than new-tool orders. This is not as exciting as a one-month YoY surge in test equipment, but it determines the valuation floor in the later part of the equipment cycle.
The service logic for Advantest and Disco is also different. Test equipment requires continuous updates to test programs, interfaces, platforms, and customer specifications, so service revenue moves with customer chip iterations. Disco's processing equipment and consumables are closer to advanced-packaging mass production; the higher equipment utilization becomes, the more visible the value of spare parts and consumables. This means near-term strength in test and packaging brings not only new-tool orders but also potential follow-on service and consumables revenue.
The second-tier supply chain also provides earlier warning signals. If OEM orders are strong but key-component lead times do not extend, suppliers do not expand, and service staff are not hired, orders may only be short-term volatility. If component suppliers begin expanding capacity, OEMs raise inventory, and customers provide longer demand visibility, the WFE cycle is more likely to continue across quarters. The second leg of equipment-stock performance often requires this kind of supply-chain resonance.
However, the second-tier chain also amplifies risk. OEMs may build inventory early to support delivery. If customers later delay equipment move-in, inventory pressure appears first in the supply chain. Component companies usually have weaker bargaining power than OEMs. Their revenue elasticity is high, but their margins are also more vulnerable to pricing and utilization. For investors, the second-tier chain is useful for judging the direction of demand, but it should not receive the same valuation mechanically. The higher-quality segments are those closest to core processes, hardest to replace, and able to generate repeat purchases through service and consumables.
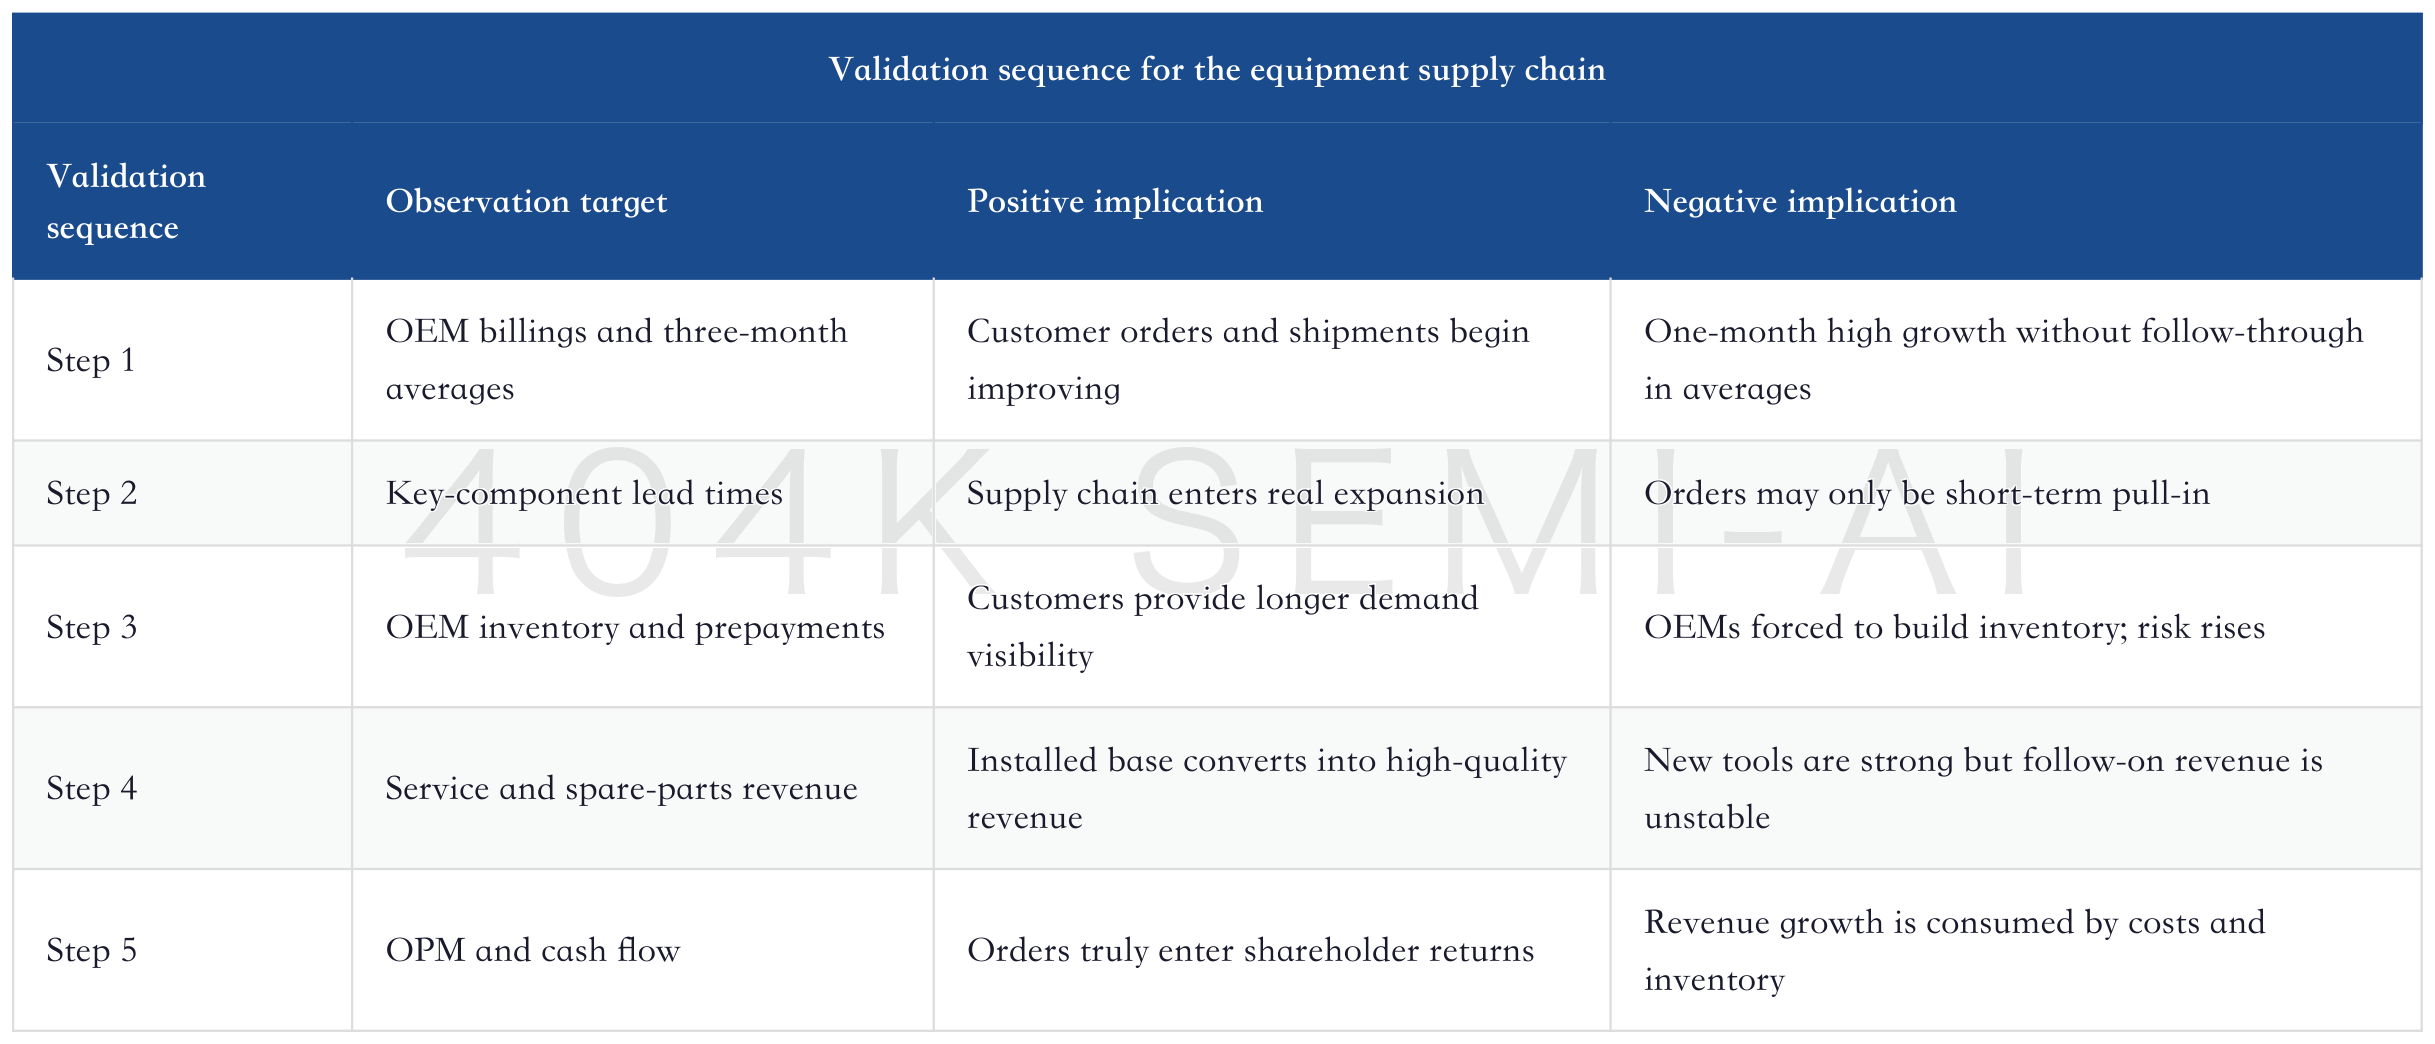
This is why this article does not present Japan SPE +11% YoY in May as a simple positive. It is more like a starting point: billings have turned positive, test is strongest, packaging is following, and front-end is beginning to recover. Next, the question is whether the second-tier supply chain follows. If the supply chain also enters expansion and service-revenue growth, this equipment trade looks more like a multiyear manufacturing bottleneck. If only OEM billings strengthen briefly and the second-tier chain does not resonate, it looks more like order pull-forward.
Equipment stocks suffer most when they are treated like ordinary short-cycle manufacturing stocks. For ordinary manufacturing stocks, when orders improve, the market asks how much revenue can grow next quarter. For semiconductor equipment stocks, when orders improve, the market also asks how long customer cleanrooms, process routes, capex plans, and yield ramps can last. As long as customer capacity construction spans multiple quarters, equipment-company order visibility is clearly longer than in general manufacturing. This is the part of the WFE upcycle most deserving of a valuation premium.
But that valuation premium must be conditional. Long order visibility does not mean every equipment company deserves a high multiple. Only companies tied to leading-edge nodes, advanced memory, advanced packaging, test validation, and key service revenue are more likely to turn long-cycle orders into high-quality cash flow. By contrast, if a company only captures short-term mature-node expansion, or if its orders mainly come from low-margin customers, valuation should still be treated as cyclical. The May SEAJ data provides evidence of demand, but it cannot replace company-quality selection.
This logic also explains why the equipment chain repeatedly experiences phases of "good data, bad stock price." If share prices have already been valued on 2027 or even 2028 profits, and the company only provides stronger current-quarter billings, the market may see that as insufficient. Only if the company also proves order duration, margin expansion, and service-revenue growth will the stock continue upward. The second half of an equipment-stock rally no longer rewards "having orders"; it rewards orders that are high quality, long duration, and margin accretive.
13. Over the Next Four Quarters, Watch a Set of Validation Metrics, Not the Phrase "WFE Upgrade"
Whether the equipment rally can continue depends on four sets of indicators.
First, whether the SEAJ three-month average continues to rise. Single-month data is noisy, and the three-month average matters more. If June and July continue to show double-digit YoY growth, the high-frequency validation of the equipment cycle becomes more solid. If monthly data weakens and the three-month average turns down, investors need to be alert to prior order pull-forward.
Second, whether test-equipment strength flows into company profits. May test equipment growth of 41% YoY is a strong signal, but it needs simultaneous confirmation from Advantest and Teradyne revenue, orders, and gross margin. If revenue is strong but margins are weak, order quality is insufficient. If revenue and margins are both revised up, the test chain still has a second leg.
Third, whether DRAM and NAND capex moves from models into equipment move-in. The biggest risk for WFE upgrades is that they stay in capex plans. Investors need to watch equipment move-in, order confirmation, and supplier guidance from Samsung, SK Hynix, Micron, Kioxia, Western Digital, CXMT, and others. DRAM determines the main slope of 2026-2027, while NAND determines the later-stage leverage in 2027-2028.
Fourth, whether front-end equipment companies can protect margins. If Tokyo Electron's FQ1 is below consensus, that is not a major problem. The real problem would be simultaneous weakness in full-year guidance, orders, equipment pricing, and OPM. The equipment chain does not lack a demand narrative now; it needs to prove that orders can become profit.
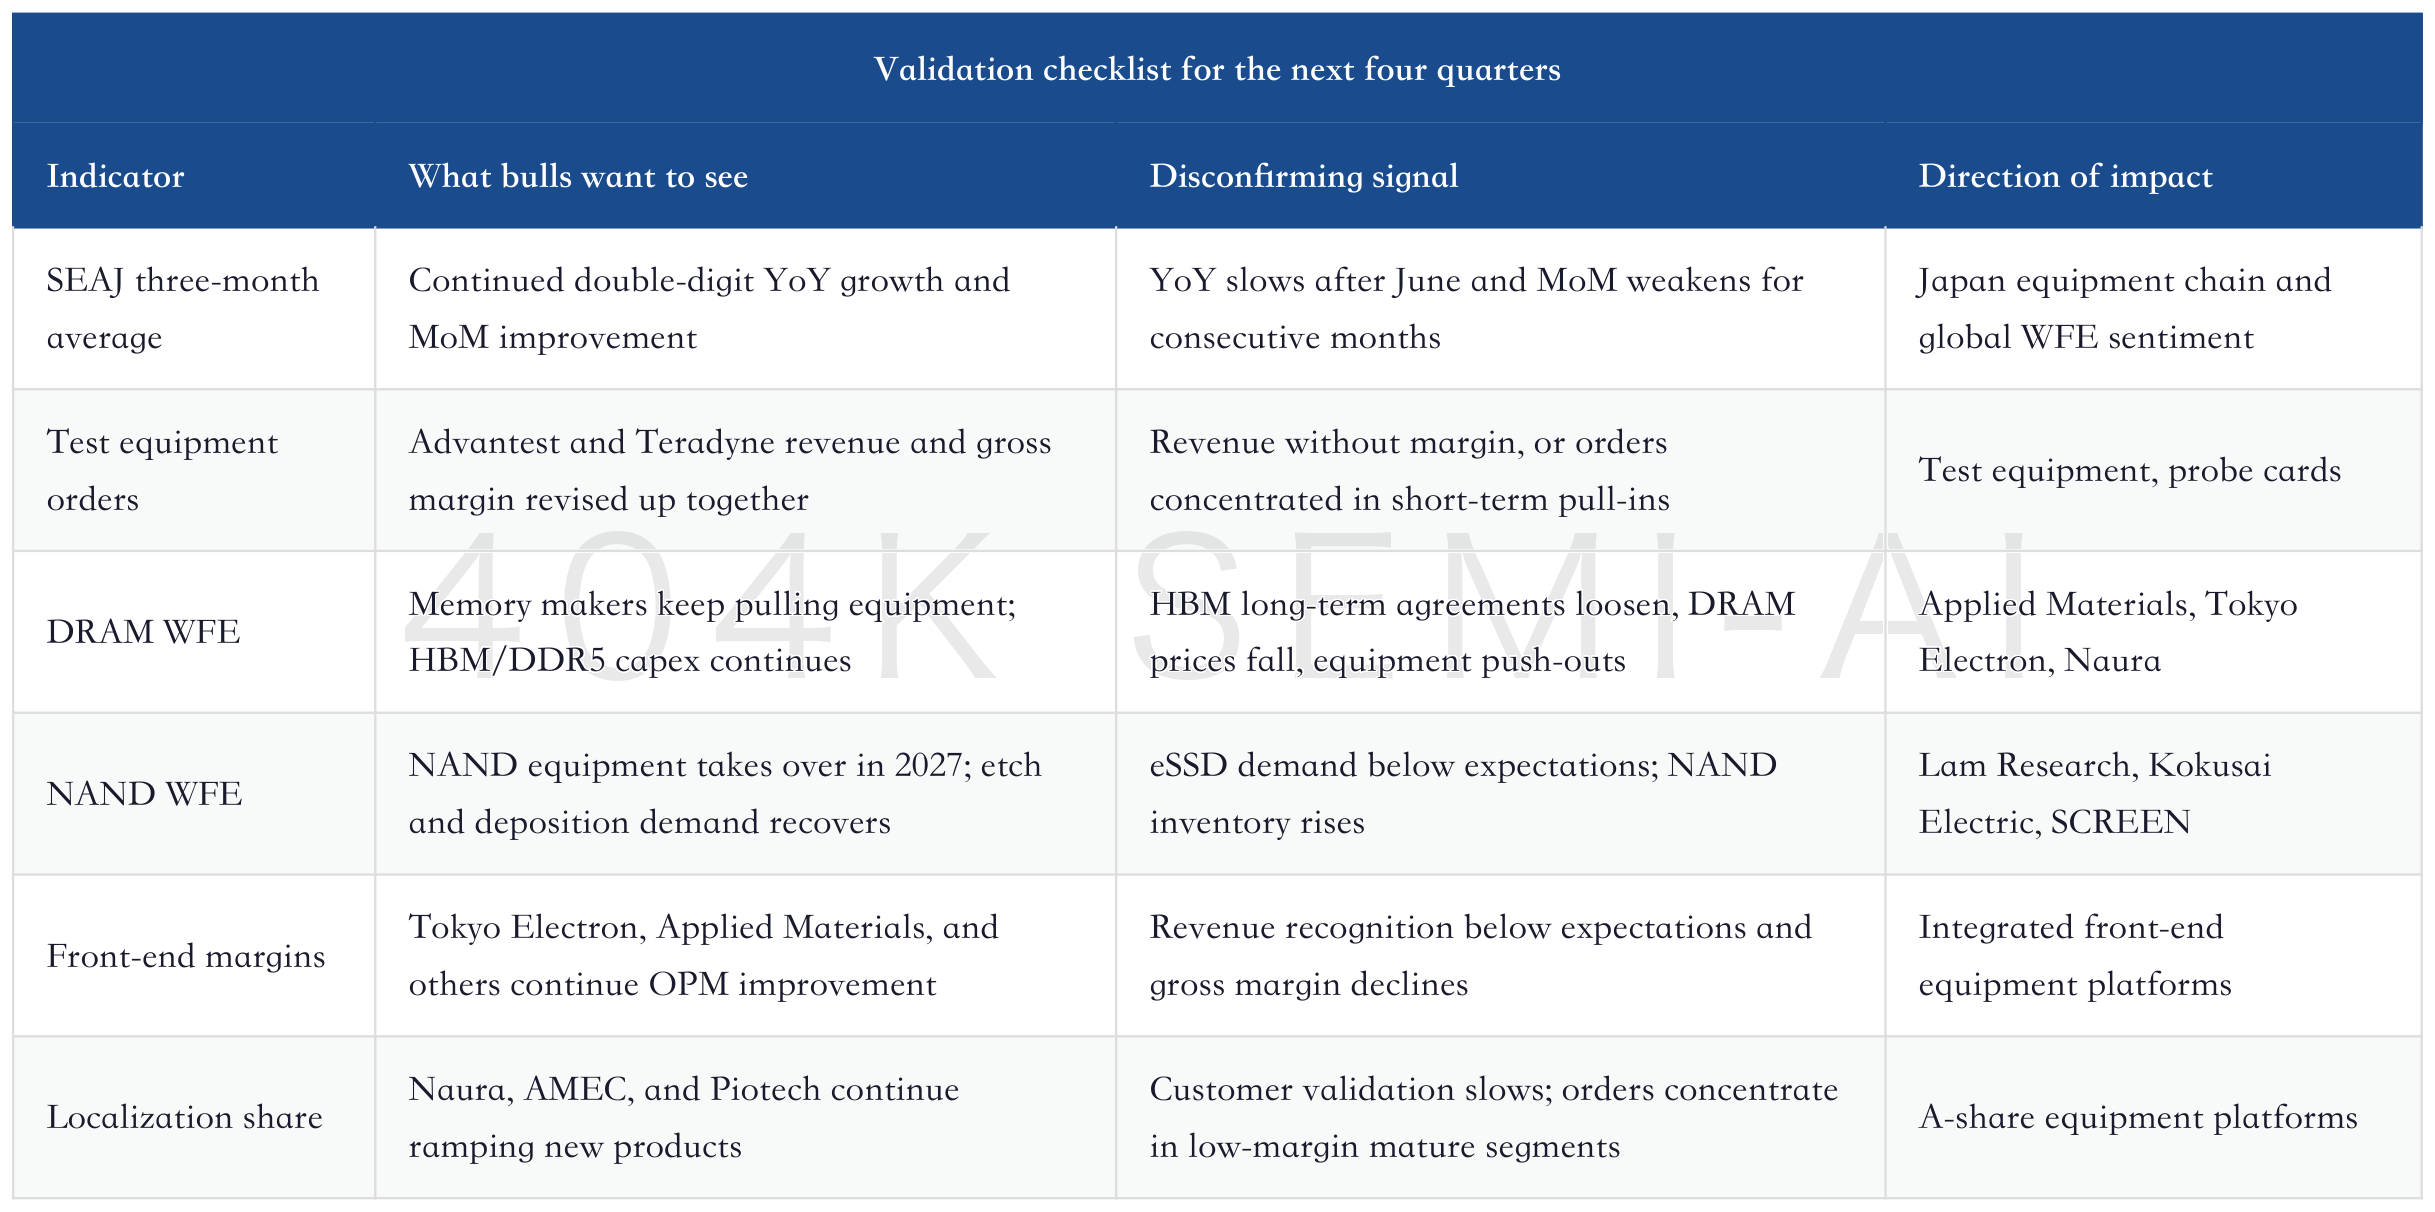
This set of indicators matters more than target prices. Target prices roll with share prices and valuation years, but high-frequency data and company margins do not easily hide problems. As long as these indicators remain positive, the equipment chain cannot be dismissed simply because it has risen a lot. If indicators begin to diverge, investors should move from an aggregate trade to selective stock picking.
14. Risks: The Equipment Cycle Fears Order Pull-Forward, Delayed Profits, and Valuation Running Ahead
The biggest risk in this equipment rally is not that AI demand suddenly disappears, but that orders, profits, and valuation become unsynchronized.
The first risk is order pull-forward. Customers may place orders early to secure tools, lead times, and capacity. Strong billings do not necessarily mean terminal demand is infinitely strong. If cloud capex slows, memory pricing weakens, or advanced-packaging capacity is released later, orders may shift from pull-in to push-out. Equipment stocks would see valuation compression first.
The second risk is delayed profits. Equipment-company revenue growth does not automatically become profit. Faster delivery brings supply-chain costs, installation costs, fixed costs, and service pressure. Customer-mix changes can also pressure gross margin. The relative caution on companies such as SCREEN is essentially about the possibility that revenue and margins do not move together.
The third risk is valuation running ahead. Japanese and U.S. equipment stocks have risen significantly over the past period. The market has already reflected WFE upgrades in advance. If companies only deliver "the industry is good" but not "better than consensus," stocks may still pull back.
The fourth risk is overheated memory expansion. DRAM and HBM tightness are driving equipment higher, but if capacity is released in a concentrated way in 2027-2028, memory pricing and capex discipline will be reassessed. Equipment companies usually peak before memory prices.
The fifth risk is export controls and regional policy. Japanese, U.S., and Chinese equipment companies are all affected by policy. Advanced-equipment export restrictions change customer procurement timing and may accelerate domestic substitution, but they are not linearly positive for all local equipment companies. For Naura, AMEC, and Piotech, share gains require real product validation, not just external restrictions.
Risk response cannot simply be "watch volatility." For order pull-forward, watch the SEAJ three-month average, backlog quality, and whether customer push-outs appear. If billings strengthen first and then weaken, early demand may have only been a scramble for lead times.
For delayed profits, prioritize companies where revenue growth can flow into OPM. If revenue is strong but gross margin and operating margin do not rise, it usually means there are problems in order quality, customer mix, or delivery costs. Such companies should not receive the same AI manufacturing-bottleneck valuation.
For valuation running ahead, separate target-price moves from earnings upgrades. If the share price is already discounting 2027-2028 profits, the company must provide longer order visibility and higher EPS revisions. Otherwise, good-news delivery may become a trigger for a pullback.
For memory overheating, watch DRAM, HBM, NAND pricing and equipment move-in timing. If memory fabs release capacity in a concentrated way, long-term agreement prices loosen, or equipment move-in is delayed, WFE orders will weaken before memory income statements do.
For policy disruption, distinguish global equipment logic from domestic substitution logic. Export restrictions may accelerate domestic validation, but they may also slow customer expansion. For Naura, AMEC, and Piotech, what really matters is product validation and share gains, not treating external restrictions as a linear positive.
The equipment chain is still investable, but it now requires more discipline. Early in the cycle, investors could buy beta. Mid-cycle, they need to buy structure. Later, they need to buy profit conversion. The May Japan SPE data shows beta is still present, but structural differentiation is already very clear.
15. Conclusion: Japan SPE Turning Positive Signals the WFE Supercycle Moving from Models into Billings
The most important significance of Japan SPE turning positive YoY in May is that it pulls the WFE supercycle out of long-range models and back into high-frequency billings. Test equipment rose 41% YoY, packaging equipment rose 12% YoY, and front-end equipment rose 5% YoY. This divergence shows that AI manufacturing bottlenecks are converting in sequence: first test and delivery, then advanced packaging, and finally the larger front-end WFE layer.
From an investment perspective, investors can no longer say broadly that "all semiconductor equipment benefits." Near term, the strongest line is Advantest and the test chain. Packaging processing points to Disco. Integrated front-end points to Tokyo Electron and Applied Materials. NAND and etch point to Lam Research and Kokusai Electric. Process control points to KLA and Lasertec. Chinese domestic equipment points to localization share at Naura, AMEC, and Piotech. Each line has its own validation points and cannot be solved with the same WFE multiple.
The real driver of the second leg in equipment stocks will be whether orders continuously enter the income statement. As long as the SEAJ three-month average continues to rise, test and packaging margins keep converting, and DRAM and NAND equipment move-in is not delayed, the WFE upcycle is not over. Conversely, if billings weaken, orders were pulled forward, and margins fail to follow, the equipment chain will move back from "AI manufacturing bottleneck assets" to cyclical stocks.
Therefore, this data is best used to update investment ranking rather than to draw a static industry conclusion. The first layer of the ranking is test and packaging, where high-frequency data has already converted. The second layer is front-end equipment that is about to enter revenue recognition. The third layer is deposition, etch, and process control, which need NAND and advanced logic to take over. The fourth layer is Chinese equipment platforms that depend on localization share expansion. Entry points, validation indicators, and risks are completely different across these layers.
If SEAJ billings continue to strengthen over the next few months but share-price reactions become dull, it does not necessarily mean the cycle is over. It may simply mean the market is waiting for margin and cash-flow confirmation. Conversely, if share prices keep rising but billings, orders, and margins do not follow, valuation exhaustion needs to be watched. The best phase for equipment stocks is when high-frequency data, company guidance, and margins all move upward together. The most dangerous phase is when only the story moves up while operating validation begins to slow.
That is the value of the May Japan SPE data: it is not the end point, but the first row of the validation table. The market already knows AI will buy more equipment. What now needs to be proven is who can turn those equipment orders into revenue, margins, and cash flow first.Japan SPE Turns Positive: How the WFE Upcycle Flows from Billing Data to Test, Packaging, and Front-End Equipment
目录
Too Long; Didn’t Read
1. The Point of This Data Is Not “Japan Equipment Is Good”; It Is That the Cycle Has Entered High-Frequency Validation
2. Why Japan Is the Thermometer for Global WFE
3. Test Equipment Breaks Out First, Showing AI Manufacturing Bottlenecks Have Entered the Yield and Validation Stage
4. Tokyo Electron’s Near-Term Downgrade Signal Does Not Mean the Front-End Cycle Is Broken
5. Packaging Equipment Is Recovering Steadily, and Disco’s Logic Remains the Advanced-Packaging Processing Bottleneck
6. Aggregate WFE Upgrades Are Now Consensus; the Debate Is Structure and Timing
7. Company Differentiation: Buying Japanese Equipment Is Not Buying a Basket, but Buying Different Bottlenecks
8. How the U.S. and Chinese Equipment Chains Map
9. The Key for A-Share Equipment Is Not Following Japan, but Proving Platformization and Customer Validation
10. How to Price Monthly Billings: From SEAJ to Revenue, Profit, and Valuation
11. Three Scenarios for the Next 6-12 Months
12. Beyond Equipment Orders, Watch Components, Service, and Supply-Chain Constraints
13. Over the Next Four Quarters, Watch a Set of Validation Metrics, Not the Phrase “WFE Upgrade”
14. Risks: The Equipment Cycle Fears Order Pull-Forward, Delayed Profits, and Valuation Running Ahead
15. Conclusion: Japan SPE Turning Positive Signals the WFE Supercycle Moving from Models into Billings
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Japan SPE billings have turned positive year over year, showing that the AI-driven equipment cycle is moving out of long-range WFE models and into monthly shipment verification. The real debate is not whether equipment demand is improving, but which segments among test, packaging, front-end, and domestic Chinese equipment will convert orders into profit first. This time, the focus is to use data to reorder the pecking order across equipment stocks.
Too Long; Didn’t Read
Japan SPE has turned positive. In May, Japan semiconductor production equipment billings rose 11% YoY in yen terms, while the three-month average rose 18% YoY. The dollar-denominated measure also turned positive. This is not one month of noise, but high-frequency confirmation that Japan’s equipment chain continues to recover after bottoming around mid-2023. It shows that the WFE upcycle is moving from sell-side models into monthly billings.
Test is breaking out first. In May, Japan test equipment billings rose 41% YoY, clearly stronger than front-end equipment at 5% and packaging equipment at 12%. This data explains why Advantest’s near-term revenue may continue to exceed consensus, and it also shows that AI GPUs, HBM, ASICs, and high-speed interfaces are turning test from a late-cycle step into a manufacturing bottleneck.
Tokyo Electron has near-term noise. This report uses SEAJ front-end data to regress Tokyo Electron’s June-quarter revenue, suggesting FQ1 revenue may decline about 15% QoQ, while consensus still expects growth. This signal should not be read simply as cycle weakness. It looks more like disruption in customer delivery and revenue-recognition timing. For the full year, DRAM, advanced logic, and broad product-line leverage remain Tokyo Electron’s main themes.
The equipment chain is entering a phase of differentiation. Upward revisions to aggregate WFE are no longer scarce information. The more important message from the May data is which equipment categories are converting first. Test and advanced packaging have the best high-frequency data. DRAM-related front-end equipment still has medium-term leverage. Cleaning and general front-end equipment depend on customer mix. The risk-reward for pure mature-node equipment is beginning to deteriorate.
Japan is a global equipment thermometer. SEAJ members represent roughly 25% of the global WFE market and cover key segments through Tokyo Electron, Disco, Advantest, Kokusai Electric, SCREEN, Lasertec, and others. Japan billings are not only relevant for Japanese equities. They also map to Applied Materials, Lam Research, KLA, ASML, and domestic Chinese platforms such as Naura, AMEC, and Piotech.
Four validation points matter next. First, whether the SEAJ three-month average continues to rise in June and July. Second, whether DRAM and NAND capex moves from orders into equipment move-in. Third, whether high YoY growth in test equipment flows into Advantest and Teradyne margins. Fourth, whether China WFE localization continues to support share gains at Naura, AMEC, and Piotech.
1. The Point of This Data Is Not “Japan Equipment Is Good”; It Is That the Cycle Has Entered High-Frequency Validation
May Japan semiconductor production equipment billings sent a very important signal: the WFE upcycle is no longer just a long-range assumption in 2026-2027 models. It is starting to show up in monthly billings. Under the SEAJ definition, Japan SPE monthly billings rose 11% YoY in yen terms and 1% YoY in dollar terms. The three-month average rose 18% YoY in yen terms and 17% YoY in dollar terms. The absolute growth rate is not spectacular, but the direction matters. Japan’s equipment chain bottomed around mid-2023, recovered for several consecutive quarters, and has now finally moved into positive YoY territory.
The real question answered by Japan equipment billings turning positive is whether AI capex, HBM, advanced DRAM, NAND recovery, advanced packaging, and test demand are actually flowing into equipment orders and revenue. Over the past few weeks, the market has repeatedly traded WFE upgrades, with many reports pushing 2026 and 2027 WFE to higher levels. The issue is that long-range models are easily amplified by market sentiment, while monthly billings are harder to fake. Positive billings show that equipment companies are indeed receiving stronger delivery signals, though the pace of conversion differs by segment.
The WFE Supercycle Has Just Begun: How AI Capex Pushes Semiconductor Equipment Toward $250 Billion
This is where this article differs from the prior aggregate WFE discussion. The earlier question was whether AI would push WFE to a higher plateau in 2027-2028. The question this time is which segments have already broken out first in high-frequency data. The former looks at long-range capacity schedules. The latter looks at current-month billings, three-month averages, company revenue regressions, and profit conversion. Once the equipment trade reaches this stage, “industry upcycle” can no longer explain every stock. Test, packaging, front-end, cleaning, deposition, etch, inspection, and domestic substitution need to be separated.
The most important point in this table is divergence, not aggregate volume. Front-end equipment grew 5% YoY, showing that wafer-fab equipment has returned to positive growth but has not yet shown an explosive slope. Packaging equipment grew 12% YoY, showing that advanced packaging and back-end processing continue to convert. Test equipment grew 41% YoY, the strongest high-frequency signal, directly tied to rising test complexity for AI GPUs, HBM, ASICs, and high-speed interfaces.
Yen and dollar measures also need to be separated. Japanese equipment company financials and investor pricing are often affected simultaneously by local-currency billings, dollar revenue, FX translation, and overseas customer procurement timing. In May, monthly billings rose 11% YoY in yen terms and 1% YoY in dollar terms. This means the positive turn is not a pure FX illusion, but it also shows that FX has amplified the visual strength of local-currency billings. Looking only at yen terms can overstate real global demand elasticity. Looking only at dollar terms may understate the improvement in local-currency revenue and P&L; for Japanese equipment companies.
For Japanese equipment stocks, a weak yen has two effects. First, overseas revenue translated back into yen improves revenue and profit performance, especially for companies with high overseas customer exposure such as Tokyo Electron, Disco, and Advantest. Second, a weak yen improves Japanese equipment makers’ price flexibility relative to U.S. and European competitors, making it easier to win orders while maintaining margins. The report notes that Tokyo Electron has more room to compete on price and gain share after yen depreciation. That logic is the combined effect of FX and market share.
But FX cannot replace real demand. For equipment stocks to run further, the dollar measure also needs to confirm a positive turn, the three-month average needs to keep improving, and company orders and gross margins need to follow. The May monthly dollar measure was only +1% YoY, showing that global demand has just crossed the positive line and is not yet strong enough to ignore timing. The steadier signal is the three-month average at +17% YoY in dollar terms. This suggests the trend is healthier than a single month and that the recovery in prior months has begun to accumulate into a quarterly measure.
YoY and MoM data should also be read separately. May monthly billings in yen terms rose 11% YoY but fell 5% MoM. Looking only at MoM would suggest the data weakened. Looking only at YoY would suggest the cycle is very strong. The right interpretation is that YoY shows the cycle position is recovering from the trough, while MoM shows the recovery is not linear. Semiconductor equipment is driven by large orders and project recognition. One month’s MoM data can easily be affected by customer delivery, acceptance, and working-day noise. The three-month average is closer to the trend.
This matters for investment timing. Chasing after a positive YoY turn may run into MoM volatility the following month. Rejecting the cycle because of a MoM decline may miss the recovery in the YoY trend. A better method is to treat SEAJ data as a trend-confirmation tool: monthly YoY confirms direction, the three-month average confirms persistence, and MoM is used to observe order timing. Only when all three weaken at the same time would it suggest a potential problem in the cycle.
Another detail is that different equipment types require different time scales. Test equipment is closer to chip delivery, so monthly data is more informative for company revenue. Front-end equipment projects are large and have slower delivery, making quarterly and semiannual trends more suitable. Packaging equipment sits between the two. It is affected by near-term AI packaging bottlenecks and by customer expansion timing. Therefore, the same SEAJ monthly billings map more directly to Advantest, more slowly to Tokyo Electron, and for Disco must be assessed alongside advanced-packaging orders and customer capacity ramps.
This is also why this data is more valuable than simply saying “Japan SPE +11%.” The real information comes from three layers of disaggregation. First, yen and dollar measures both turned positive, so this is not pure FX. Second, the three-month average is stronger than the single month, so the trend is still improving. Third, test, packaging, and front-end equipment show different levels of strength, meaning AI manufacturing bottlenecks are transmitting in phases. Only by combining these three layers can one reach an investable conclusion.
Transmission across the equipment chain is usually not fully synchronized. Front-end equipment has the largest order value, slower recognition, and is more affected by customer scheduling, cleanrooms, installation and acceptance, and large-project timing. Packaging and test are closer to AI chip delivery bottlenecks, so their data may respond faster. The value of the May data is that it allows investors to see the sequencing inside the aggregate WFE upcycle.
2. Why Japan Is the Thermometer for Global WFE
SEAJ members represent roughly 25% of the global WFE market. This proportion means Japan billings are not a small regional sample, but a high-frequency thermometer for the global equipment chain. Japanese equipment companies cover a wide range of segments: Tokyo Electron is an integrated front-end equipment platform; Disco has a strong position in advanced-packaging processing such as dicing, grinding, and polishing; Advantest is a core AI test company; Kokusai Electric has an important position in batch ALD and thermal processing; SCREEN has a traditional advantage in cleaning equipment; and Lasertec is scarce in mask inspection and EUV-related inspection.
The distinctive feature of Japan’s equipment chain is that it is neither purely the U.S. big three nor purely the lithography chain. It is more like a set of manufacturing-process pieces: front-end, back-end, test, inspection, cleaning, and materials engineering all have representative companies. Therefore, SEAJ data can break WFE upgrades into more specific questions: whether wafer-fab equipment has truly started to strengthen, whether AI packaging remains tight, whether test equipment is capturing higher value from GPUs and HBM, and whether NAND and DRAM capex is flowing into batch deposition and cleaning.
Revaluing Japan Semiconductor Equipment and Materials: Physical Bottleneck Assets Behind AI Compute Expansion
Japan’s equipment chain also maps strongly to global peers. Tokyo Electron’s front-end data affects cycle judgments for Applied Materials, Lam Research, ASML, and KLA. Advantest’s test data affects Teradyne and the test consumables chain. Disco’s packaging-processing data affects advanced-packaging equipment, dicing/grinding/polishing, probe cards, and back-end equipment. Kokusai Electric’s deposition data affects ASM International, Applied Materials, Korean domestic equipment, and Chinese thin-film deposition equipment companies.
Therefore, May billings are not “small-cap Japanese equity data.” They simultaneously tell U.S. equipment stocks, Chinese equipment stocks, and the advanced-packaging and test chain that cycle recovery is happening, but the transmission is uneven. The companies worth owning are those that can turn this high-frequency data into revenue, gross margin, and EPS upgrades.
3. Test Equipment Breaks Out First, Showing AI Manufacturing Bottlenecks Have Entered the Yield and Validation Stage
The strongest May subcategory was test equipment, up 41% YoY. This number was much higher than front-end equipment and packaging equipment. Test strength is not surprising, because AI chip complexity is turning test from “back-end inspection” into a delivery bottleneck. GPUs, ASICs, HBM, high-speed interconnects, CPO, retimers, SerDes, and advanced packaging all increase test time, test coverage, and test-platform value.
AI chips cannot ship simply because they have been manufactured. The more complex the system, the more validation is needed at wafer level, package level, and system level. HBM requires testing of stacks and bandwidth. AI GPUs require testing of logic functions and high-speed interfaces. Custom ASICs require validation against specific customer workloads. Advanced packaging requires confirmation of interconnects and thermal stability across multiple dies. Longer test time, more expensive test platforms, and more concentrated test demand all lift revenue elasticity for companies such as Advantest and Teradyne.
From HBM to WFE: How AI Turns the Memory Cycle into an Equipment Supercycle, and How Much Further Semiconductor Equipment Can Rise
The report regresses Advantest revenue against SEAJ test equipment data and provides an interesting near-term signal: Advantest’s June-quarter revenue may be above consensus. The summary indicates revenue growth of roughly 10% QoQ, while the regression chart points to about 14%-15% QoQ growth in test revenue, versus consensus of only about 3%. The exact figures should not be copied mechanically, but the direction is clear: high-frequency test-equipment billings are stronger than market models.
The fact that test equipment is breaking out first has another investment implication: the AI hardware cycle has moved from “buying chips” to “ensuring deliverability.” Early on, the market focused only on GPU orders and HBM supply. Later, it will increasingly focus on yield, test, packaging, and system-level reliability. Test is the most direct beneficiary of this stage because it performs the validation work that turns complex chips into shippable products.
However, test equipment is not risk-free. May YoY growth was high, but monthly billings fell 7% MoM and the three-month average also declined slightly MoM. Possible reasons include the base effect, delivery timing, and customer production schedules. Test-equipment investing should avoid extrapolating one month’s YoY growth into permanent high growth. A better validation method is to watch Advantest and Teradyne orders, backlog, gross margin, and whether ASPs for AI GPU, ASIC, and HBM test platforms continue to rise.
4. Tokyo Electron’s Near-Term Downgrade Signal Does Not Mean the Front-End Cycle Is Broken
The most controversial point in the report is the regression of Tokyo Electron’s June-quarter revenue using SEAJ front-end equipment data, which suggests a QoQ decline of roughly 15%, while consensus still expects about 7% QoQ growth. This looks like a negative signal, but it should not be read simply as front-end cycle weakness.
First, the regression uses only two months of data. The direction is informative, but it is not a full quarterly revenue forecast. Equipment revenue recognition is affected by large-project delivery, installation and acceptance, customer schedules, FX, and product mix. A weak single-quarter regression may mean Tokyo Electron’s FQ1 recognition timing is slow, or it may mean consensus is too high. It does not necessarily mean full-year orders are insufficient.
Second, May front-end equipment still grew 5% YoY and did not turn negative. It was simply not as strong as test equipment. Front-end equipment has a larger base and a longer cycle, so billings acceleration often lags test and packaging. The real drivers of Tokyo Electron’s full-year profit are whether DRAM expansion, advanced-logic equipment move-in, equipment pricing, product mix, and customer capex continue to be revised upward, not one month of data.
Third, Tokyo Electron is not a single-category front-end equipment asset. It covers coating/developing, etch, deposition, cleaning, and other segments. It benefits from DRAM and NAND as well as advanced logic and higher customer equipment intensity. As long as global WFE continues to rise, Tokyo Electron remains Japan’s aggregate equipment asset. A near-term FQ1 miss versus consensus may instead pull the market back from “only looking at aggregate volume” toward delivery timing and margins.
Japan Semiconductor Equipment Deep Dive: Goldman Sachs Raises Target Prices for 10 Companies by 16%, AI WFE Enters the Profit-Conversion Phase
This also explains why Japanese equipment stocks now need to move from an aggregate-volume trade to a company-specific trade. Tokyo Electron may still benefit from WFE for the full year, but quarterly timing will be volatile. Advantest is stronger near term, but high YoY bases need to be watched. Disco benefits from advanced packaging, but order timing is linked to HBM and CoWoS capacity. Kokusai Electric needs clearer NAND and batch-deposition demand. SCREEN depends on cleaning-equipment customer mix and margins.
Investors should not use one month of SEAJ data to buy or sell Tokyo Electron mechanically. A more reasonable approach is this: if FQ1 is below consensus but full-year guidance is not weak, and DRAM/logic customer orders remain strong, a pullback may offer a better medium-term entry point. If FQ1 is below consensus and full-year orders, margins, and pricing all weaken, then actual front-end cycle conversion would be below the model.
5. Packaging Equipment Is Recovering Steadily, and Disco’s Logic Remains the Advanced-Packaging Processing Bottleneck
In May, Japan packaging equipment billings rose 12% YoY and 7% MoM. The data is not as dramatic as test equipment, but the direction is good. Advanced packaging has moved from a theme word in the AI chain into real incremental equipment billings. HBM, CoWoS, hybrid bonding, EMIB-T, CPO, and high-density packaging all require more dicing, grinding, polishing, pre- and post-bond processing, and yield control. Disco is the core Japanese company in this line.
Disco’s strengths are grinders and dicers. The report notes that it has high market share in these tools and benefits from medium- and long-term process changes including advanced packaging, HBM, CoWoS, hybrid bonding, 3D NAND, and backside power delivery. The market often simplifies Disco as “back-end equipment,” but what it really captures is process complexity. The more complex AI packaging becomes, and the more precise wafer and chip handling needs to be, the higher the value of dicing, grinding, and polishing.
The pull from advanced packaging is not only CoWoS. CoWoS is just the first stage. HBM4, hybrid bonding, CPO, panel-level interposers, backside power delivery, and thinner wafers will all bring new process requirements. Companies like Disco benefit from the “front-endization” of packaging: back-end processing precision increasingly resembles front-end manufacturing, raising equipment barriers and customer stickiness.
Japan and Korea AI Semiconductor Supply Chain Deep Dive: Japan Equipment and Materials, Korea HBM, and Industrial Automation as the Next Main Line for Asian Tech Revaluation
The significance of 12% YoY growth in packaging equipment is that it gives the advanced-packaging chain a relatively moderate but solid validation. Compared with test equipment, packaging equipment is more likely to show a sustained ramp rather than one-month high elasticity. As long as AI GPUs and HBM remain in shortage, advanced-packaging capex will not disappear quickly. Disco, selected packaging equipment, probe cards, carriers, substrate materials, and test equipment will together form the second-layer profit pool of the AI hardware cycle.
6. Aggregate WFE Upgrades Are Now Consensus; the Debate Is Structure and Timing
The report expects global WFE to grow 21.4% YoY in 2026 and 18.2% YoY in 2027. This is consistent with the recent direction of upgrades from multiple institutions: equipment demand is strong in 2026 and continues to grow in 2027. Growth mainly comes from the recovery in DRAM and NAND capex, while advanced logic, AI chips, and regional manufacturing policies also support equipment investment.
But the market has already seen the aggregate upgrade. Over the past few weeks, equipment stocks, memory stocks, advanced packaging, and the test chain have already traded the “WFE supercycle.” What matters next is not saying again that WFE is good, but breaking down the structure: whether DRAM expands before NAND, whether test converts before front-end, whether TSMC advanced logic follows memory, whether Intel and Samsung Foundry can contribute incremental demand in 2028, and whether China’s WFE scale and localization share continue to support A-share equipment companies.
Equipment Capex Ledger Update: AI Financing, $250 Billion WFE, and Semiconductor Equipment Repricing
The structural answer from this SEAJ data is: test is strongest, packaging continues to recover, and front-end has turned positive but remains differentiated in timing. This sequence fits the logic of the AI hardware cycle. AI chips and HBM first bottleneck test and advanced packaging; then memory and logic fabs add front-end capacity for long-term supply. Front-end equipment has the largest dollar value, but recognition is slower. Test and packaging are closer to delivery bottlenecks, so billings reflect the change faster.
This framework also explains why equipment stocks cannot be analyzed with a single indicator. When aggregate WFE is revised upward, all equipment companies benefit. But in the differentiation phase, the market rewards segments where high-frequency data converts first, margin leverage is clearer, and technical barriers are harder to replace. Test and packaging are near-term, DRAM front-end is mid-phase, advanced logic and NAND are later, and Chinese localization is an independent share-gain logic.
7. Company Differentiation: Buying Japanese Equipment Is Not Buying a Basket, but Buying Different Bottlenecks
The rating mix in this report is interesting: positive on Disco, Advantest, Tokyo Electron, Kokusai Electric, and Lasertec, while relatively cautious on SCREEN. The logic behind this mix is not “all Japan equipment is good,” but classifying the equipment chain by bottleneck type.
Advantest corresponds to the AI test bottleneck. The report notes that it has a strong position in HBM test and Nvidia AI GPU test. Rising AI chip complexity should continue to support test-platform ASPs and revenue. Its issue is that valuation and expectations are already high, so orders and margins need to keep proving the case.
Disco corresponds to the advanced-packaging processing bottleneck. It captures HBM, CoWoS, hybrid bonding, and more complex packaging paths. As long as AI chips continue to evolve toward large dies, multi-die systems, high bandwidth, and high reliability, the value of Disco’s dicing, grinding, and polishing will not easily disappear.
Tokyo Electron corresponds to integrated front-end WFE. Its near-term quarterly timing may fall below consensus, but it remains the aggregate Japanese equipment asset over the medium term. DRAM, advanced logic, NAND, cleaning, etch, deposition, and coating/developing all affect it.
Kokusai Electric corresponds to batch deposition and NAND/advanced DRAM structures. Its leverage depends more on NAND capex and adoption of batch ALD at advanced nodes. If current capex is still more focused on DRAM and HBM, Kokusai Electric may not move as quickly near term as test and packaging.
Lasertec corresponds to advanced inspection. It is a scarce asset in leading-edge nodes and EUV-related inspection, benefiting from advanced logic and mask inspection. But assets like this usually trade at high valuations and require sustained customer investment in leading-edge nodes.
SCREEN corresponds to cleaning equipment. Cleaning is necessary, but the report is relatively cautious because of margins, customer mix, and competitive pressure from China. Cleaning demand will rise with process complexity, but share-price leverage depends on whether the company can turn demand into high-quality profit.
Japanese equipment cannot be treated as “everyone benefits from AI” anymore. Near term, investors should watch whether Advantest and Disco continue to convert; for the integrated cycle, watch Tokyo Electron; for advanced logic, watch Lasertec; for NAND and deposition, watch Kokusai Electric; and for cleaning, require stricter margin validation. This segmentation is more useful than simply buying a Japanese equipment index.
8. How the U.S. and Chinese Equipment Chains Map
Japan SPE data affects the global equipment chain. Among U.S. equipment companies, Applied Materials, Lam Research, and KLA correspond to materials engineering/deposition and etch, NAND and etch, and process control respectively. SEAJ front-end turning positive shows that the WFE cycle direction remains upward, but the early strength in test and packaging suggests the market may increasingly focus on complexity rather than only on front-end tool counts.
Applied Materials benefits most from DRAM, advanced packaging, GAA, and materials-engineering content. Lam Research depends more on NAND and etch intensity. KLA depends more on complex processes, yield, and process control. ASML is the pricing anchor for advanced logic and memory EUV, but this SEAJ data more directly shows strength first in the Japan chain and in back-end test.
Applied Materials Deep Dive: How the WFE Supercycle, DRAM Expansion, and Advanced Packaging Revalue the Profit Slope
The Chinese equipment-chain mapping needs to be viewed separately. The Chinese companies covered in the report include Naura, AMEC, and Piotech. Here, the right framework is China WFE and localization share, not a simple application of Japanese equipment billings. Naura’s strength is platform equipment, covering PVD, CVD, etch, thermal processing, cleaning, and other segments. AMEC’s core is etch, while it is expanding into more thin-film and epitaxy equipment. Piotech is centered on thin-film deposition, with extensions across PECVD, HDPCVD, SACVD, ALD, and hybrid-bonding-related directions.
Chinese equipment companies benefit from two lines. First, onshore China WFE remains large, with continued equipment demand from mature nodes, memory, specialty processes, and selected advanced nodes. Second, rising localization share allows domestic equipment companies to grow revenue faster than aggregate China WFE. Even if the marginal increase in global WFE comes more from Korea, the United States, Taiwan, and Japan, Chinese domestic equipment companies can still achieve excess growth through share gains.
For A-share equipment, the conclusion is not “Japan data is good, so A-share equipment directly follows.” A more accurate statement is that the global WFE cycle is continuing to strengthen, raising the strategic value of equipment localization for Chinese customers. The fact that Japanese test and packaging are strengthening first also reminds investors that China’s equipment chain should not focus only on mature nodes, but also on product upgrades in advanced memory, advanced packaging, thin-film deposition, etch, cleaning, metrology, and inspection.
9. The Key for A-Share Equipment Is Not Following Japan, but Proving Platformization and Customer Validation
The Chinese equipment chain cannot be traded simply on Japan SPE turning positive YoY. Japan data proves high-frequency improvement in global WFE. What Chinese equipment companies need to deliver is a different logic: against a backdrop of still-large onshore China WFE, can domestic equipment move from point substitution to platform substitution, and from mature nodes to advanced memory, advanced logic, advanced packaging, and key thin-film/etch/cleaning steps? In other words, the core variables for A-share equipment are share and product boundaries, not Japanese billings themselves.
Naura, AMEC, and Piotech are treated in the report as representative Chinese equipment companies for different reasons. Naura is a platform asset, covering PVD, CVD, etch, thermal processing, cleaning, and other areas, with advantages in product breadth and customer stickiness. AMEC’s core remains etch, especially CCP and ICP dry-etch platforms, and it continues to expand into adjacent processes such as ALD, LPCVD, and EPI. Piotech’s core is thin-film deposition, and its PECVD, HDPCVD, SACVD, ALD, and hybrid-bonding-related directions put it closer to the materials-engineering demand of advanced memory and advanced packaging.
The most important difference among these three companies is how they capture the WFE upcycle. Naura is more of an expression of aggregate China WFE and domestic platformization. AMEC is more of an expression of etch and advanced-process breakthroughs. Piotech is more of an expression of rising thin-film deposition content. If Chinese customers continue to expand DRAM, NAND, logic, specialty processes, and advanced-packaging investment, all three benefit. But if investment is concentrated only in mature nodes and low-margin equipment, profit leverage will diverge sharply.
The easiest mistake in Chinese equipment investing is turning “domestic substitution” into an empty phrase. Localization does not happen automatically. It requires customer validation, process stability, yield ramp, spare-parts service, delivery capability, and cost control. Equipment entering the fab is only the first step. Replacement is only successful when tools enter mass-production lines and become a continuing procurement platform for customers. This process is slower than for materials and components, and more dependent on engineering capability than many software-like assets.
The second easy mistake is looking only at revenue growth and not at revenue quality. Equipment companies may ramp volume quickly during an expansion phase, but if orders are concentrated in low-margin mature segments, or if companies sacrifice price to win share, revenue growth may not bring margin improvement. Platform companies like Naura need multiple product lines to enter high-margin customers at the same time. AMEC needs its etch equipment to keep moving into higher-end processes. Piotech needs thin-film deposition to move from a single tool category into part of the customer platform.
The third risk is confusing global WFE growth with China WFE growth. Marginal global WFE growth may come from Korean DRAM, U.S. advanced logic, Taiwan foundry, and Japan’s equipment chain, while Chinese domestic equipment companies depend more on customers in mainland China. If China WFE remains high, domestic equipment still has room. If Chinese customer capex slows, A-share equipment will diverge in revenue timing even if global WFE is strong.
Therefore, the A-share equipment conclusion should be more disciplined. A stronger global equipment cycle is a positive backdrop for Naura, AMEC, and Piotech because it raises the strategic value of customer expansion and supply-chain autonomy. But whether stocks continue to re-rate depends on whether the companies prove three things: first, product boundaries continue to expand; second, high-end customer validation continues to progress; third, revenue growth flows into gross margin and cash flow. Without any one of these, WFE upgrades provide beta, not long-term alpha.
10. How to Price Monthly Billings: From SEAJ to Revenue, Profit, and Valuation
The value of SEAJ data is that it is high frequency, but high-frequency data does not directly equal company profit. Monthly billings must pass through several steps before becoming something equity prices can sustainably discount: billing improvement, order confirmation, equipment delivery, customer acceptance, revenue recognition, gross-margin realization, EPS upgrades, and finally valuation re-rating. Every layer has a time lag and noise.
This is why the same May data can produce two signals: Advantest may be above consensus, while Tokyo Electron may be below consensus near term. Test equipment billings were very strong YoY and have a close regression relationship with Advantest revenue, so they are friendlier for near-term earnings. Front-end billings turned positive but had MoM volatility, and Tokyo Electron is an integrated equipment platform whose revenue recognition is more affected by large-project delivery, so the near-term regression signal is weak. The two signals are not contradictory. They show that revenue-recognition elasticity differs across equipment segments.
Investors should treat SEAJ data as a validator, not a direct buy/sell signal. If SEAJ strengthens and company earnings also show simultaneous improvement in orders, revenue, and gross margin, the data becomes evidence for earnings upgrades. If SEAJ strengthens but company revenue does not follow, it may be a recognition-timing issue or share loss, requiring further disaggregation. If SEAJ strengthens but gross margin falls, order quality is poor and the stock may come under pressure instead.
Tokyo Electron is a particularly good example. Positive YoY front-end equipment billings prove the industry direction is not bad. A regression suggesting FQ1 may be below consensus indicates near-term revenue recognition may be weaker than market models. What really determines the stock is how the company explains the difference. If the company says orders and full-year guidance are unchanged and only the quarterly timing has shifted, the market will readjust quarterly models. If the company also cuts full-year guidance, then the front-end equipment cycle would be weaker than expected.
Advantest is the opposite. Test equipment billings rose 41% YoY, and the regression suggests revenue may be above consensus. If earnings validate this, the market will begin to re-estimate the growth midpoint of AI test platforms. But if revenue is high while gross margin does not rise, or if orders are concentrated in short-term customer pull-ins, valuation will not expand indefinitely. For test stocks, the next variables are test duration, platform ASP, customer mix, and service revenue.
Equipment-stock valuation needs to move from “revenue elasticity” to “profit elasticity”
This bridge can also handle valuation disputes. The most dangerous moment for equipment stocks is not necessarily when data weakens, but when share prices have already discounted the next two years of strong demand. If company EPS keeps being revised up, valuation can be absorbed by earnings. If EPS is not revised up and only the industry story remains, the stock may show “good data but no price rise.” This is why after the May SEAJ data, investors should watch company consensus revisions more than same-day share-price reactions.
11. Three Scenarios for the Next 6-12 Months
There are roughly three scenarios for the equipment chain over the next 6-12 months.
The optimistic scenario is that test, packaging, DRAM front-end, and NAND equipment all take turns. The SEAJ three-month average continues to rise. Advantest and Teradyne confirm that AI test demand is stronger than expected. Disco and the advanced-packaging chain see orders continue to increase. Tokyo Electron’s full-year guidance remains unchanged or is even revised upward after FQ1 timing disruption. DRAM fabs accelerate equipment move-in. NAND recovers from a low base. In this scenario, equipment stocks can maintain high valuations, and the market will continue to move from “WFE beta” to “manufacturing bottleneck assets.”
The base scenario is that test and packaging are strong first, while front-end equipment recovers steadily but with quarterly timing volatility. SEAJ YoY growth remains positive, but MoM is not strong every month. Advantest is above consensus, Tokyo Electron is below consensus near term but not weak for the full year, Disco continues to benefit from advanced packaging, and Kokusai Electric and SCREEN need to wait for further validation from NAND and cleaning demand. In this scenario, equipment stocks diverge. Companies with real orders and margins remain strong, while pure industry beta weakens.
The stress scenario is that order pull-forward and valuation overheating appear at the same time. The SEAJ three-month average turns down, high YoY growth in test equipment proves unsustainable, Tokyo Electron and other front-end equipment companies cut full-year guidance, DRAM or NAND customers delay equipment move-in, and cloud capex or AI server deliveries slow. In this scenario, equipment stocks move back from AI manufacturing bottleneck assets to cyclicals. Valuations compress first, followed by earnings downgrades.
In the optimistic scenario, portfolios should be more offensive. In Japan, watch Advantest, Disco, Tokyo Electron, and Lasertec. In the United States, watch Applied Materials, Lam Research, and KLA. In China, watch high-end equipment validation at Naura, AMEC, and Piotech. In this scenario, test and packaging remain near-term, DRAM front-end is mid-phase, and NAND and advanced logic provide the later phase.
In the base scenario, portfolios should move from beta to selection. In the Japanese equipment chain, Advantest and Disco better explain the near-term data. Tokyo Electron needs earnings to confirm full-year timing. Kokusai Electric needs clearer NAND capex. SCREEN needs margin validation. In the U.S. equipment chain, the relative strength of Applied Materials and Lam Research depends on whether DRAM or NAND becomes the marginal main line. In China’s equipment chain, watch high-end product validation rather than just industry sentiment.
In the stress scenario, the first to fall are the segments with the highest valuations and the slowest earnings conversion. If test and packaging have only themes and no profit, they will correct first. If integrated front-end leaders do not see order cancellations, the drawdown may look more like valuation digestion. If domestic Chinese equipment has unstable revenue quality and cash flow, the market will reassess it as well. The stress scenario does not mean AI demand has ended; it means share prices have already bought too much future profit.
The portfolio-level conclusion can be condensed into four points. First, test and advanced packaging remain the strongest near-term validation lines. Second, Tokyo Electron and Applied Materials represent medium-term front-end WFE conversion, but quarterly timing and margins matter. Third, Lam Research, Kokusai Electric, and selected cleaning/etch companies need clearer NAND follow-through. Fourth, excess returns for Naura, AMEC, and Piotech come from localization share and product upgrades, not from simply following overseas equipment higher.
12. Beyond Equipment Orders, Watch Components, Service, and Supply-Chain Constraints
The semiconductor equipment profit pool is not limited to tool makers. The WFE upcycle first enters orders at OEMs such as Tokyo Electron, Applied Materials, Lam Research, KLA, ASML, Advantest, and Disco, then continues to transmit into vacuum valves, pumps, RF power supplies, ceramics, precision machining, motion control, optical components, gas systems, temperature control, probe cards, test interface boards, service parts, and field engineers. The longer the equipment cycle lasts, the more easily these second-tier segments move from “following orders” to becoming delivery bottlenecks.
This is why the SEAJ three-month average matters more than a single month’s YoY data. To increase deliveries, tool makers cannot wait until the final quarter to procure key components. Test-equipment volume requires probe cards, interface boards, and customer test programs. Front-end equipment volume requires vacuum, RF, power, ceramics, valves, and precision mechanical supply chains to prepare in advance. Packaging-processing volume requires stable supply of blades, grinding wheels, motion control, and consumables. Sustained improvement in monthly billings implies that supply-chain scheduling may already have started in advance.
This second-tier chain changes the quality of equipment-company profits. In older cycles, investors focused more on new-tool orders. In the new cycle, service, spare parts, upgrades, and software tuning will become increasingly important. AI chips, advanced DRAM, HBM, GAA, advanced packaging, and high-speed test do not end after equipment is purchased. Customers need continuous tuning, maintenance, yield optimization, and process upgrades. If equipment companies can convert installed base into service revenue, valuation should not be treated entirely like a cyclical stock.
Service-revenue value is especially high for leaders such as Applied Materials, KLA, ASML, and Tokyo Electron. The larger the installed base, the more customers depend on original spare parts and engineering support. Advanced-process equipment cannot be down for long, and downtime cost is often far higher than spare-parts cost. Equipment-company service revenue therefore has stronger stickiness and can make revenue less volatile than new-tool orders. This is not as exciting as a one-month YoY surge in test equipment, but it determines the valuation floor in the later part of the equipment cycle.
The service logic for Advantest and Disco is also different. Test equipment requires continuous updates to test programs, interfaces, platforms, and customer specifications, so service revenue moves with customer chip iterations. Disco’s processing equipment and consumables are closer to advanced-packaging mass production; the higher equipment utilization becomes, the more visible the value of spare parts and consumables. This means near-term strength in test and packaging brings not only new-tool orders but also potential follow-on service and consumables revenue.
The second-tier supply chain also provides earlier warning signals. If OEM orders are strong but key-component lead times do not extend, suppliers do not expand, and service staff are not hired, orders may only be short-term volatility. If component suppliers begin expanding capacity, OEMs raise inventory, and customers provide longer demand visibility, the WFE cycle is more likely to continue across quarters. The second leg of equipment-stock performance often requires this kind of supply-chain resonance.
However, the second-tier chain also amplifies risk. OEMs may build inventory early to support delivery. If customers later delay equipment move-in, inventory pressure appears first in the supply chain. Component companies usually have weaker bargaining power than OEMs. Their revenue elasticity is high, but their margins are also more vulnerable to pricing and utilization. For investors, the second-tier chain is useful for judging the direction of demand, but it should not receive the same valuation mechanically. The higher-quality segments are those closest to core processes, hardest to replace, and able to generate repeat purchases through service and consumables.
This is why this article does not present Japan SPE +11% YoY in May as a simple positive. It is more like a starting point: billings have turned positive, test is strongest, packaging is following, and front-end is beginning to recover. Next, the question is whether the second-tier supply chain follows. If the supply chain also enters expansion and service-revenue growth, this equipment trade looks more like a multiyear manufacturing bottleneck. If only OEM billings strengthen briefly and the second-tier chain does not resonate, it looks more like order pull-forward.
Equipment stocks suffer most when they are treated like ordinary short-cycle manufacturing stocks. For ordinary manufacturing stocks, when orders improve, the market asks how much revenue can grow next quarter. For semiconductor equipment stocks, when orders improve, the market also asks how long customer cleanrooms, process routes, capex plans, and yield ramps can last. As long as customer capacity construction spans multiple quarters, equipment-company order visibility is clearly longer than in general manufacturing. This is the part of the WFE upcycle most deserving of a valuation premium.
But that valuation premium must be conditional. Long order visibility does not mean every equipment company deserves a high multiple. Only companies tied to leading-edge nodes, advanced memory, advanced packaging, test validation, and key service revenue are more likely to turn long-cycle orders into high-quality cash flow. By contrast, if a company only captures short-term mature-node expansion, or if its orders mainly come from low-margin customers, valuation should still be treated as cyclical. The May SEAJ data provides evidence of demand, but it cannot replace company-quality selection.
This logic also explains why the equipment chain repeatedly experiences phases of “good data, bad stock price.” If share prices have already been valued on 2027 or even 2028 profits, and the company only provides stronger current-quarter billings, the market may see that as insufficient. Only if the company also proves order duration, margin expansion, and service-revenue growth will the stock continue upward. The second half of an equipment-stock rally no longer rewards “having orders”; it rewards orders that are high quality, long duration, and margin accretive.
13. Over the Next Four Quarters, Watch a Set of Validation Metrics, Not the Phrase “WFE Upgrade”
Whether the equipment rally can continue depends on four sets of indicators.
First, whether the SEAJ three-month average continues to rise. Single-month data is noisy, and the three-month average matters more. If June and July continue to show double-digit YoY growth, the high-frequency validation of the equipment cycle becomes more solid. If monthly data weakens and the three-month average turns down, investors need to be alert to prior order pull-forward.
Second, whether test-equipment strength flows into company profits. May test equipment growth of 41% YoY is a strong signal, but it needs simultaneous confirmation from Advantest and Teradyne revenue, orders, and gross margin. If revenue is strong but margins are weak, order quality is insufficient. If revenue and margins are both revised up, the test chain still has a second leg.
Third, whether DRAM and NAND capex moves from models into equipment move-in. The biggest risk for WFE upgrades is that they stay in capex plans. Investors need to watch equipment move-in, order confirmation, and supplier guidance from Samsung, SK Hynix, Micron, Kioxia, Western Digital, CXMT, and others. DRAM determines the main slope of 2026-2027, while NAND determines the later-stage leverage in 2027-2028.
Fourth, whether front-end equipment companies can protect margins. If Tokyo Electron’s FQ1 is below consensus, that is not a major problem. The real problem would be simultaneous weakness in full-year guidance, orders, equipment pricing, and OPM. The equipment chain does not lack a demand narrative now; it needs to prove that orders can become profit.
This set of indicators matters more than target prices. Target prices roll with share prices and valuation years, but high-frequency data and company margins do not easily hide problems. As long as these indicators remain positive, the equipment chain cannot be dismissed simply because it has risen a lot. If indicators begin to diverge, investors should move from an aggregate trade to selective stock picking.
14. Risks: The Equipment Cycle Fears Order Pull-Forward, Delayed Profits, and Valuation Running Ahead
The biggest risk in this equipment rally is not that AI demand suddenly disappears, but that orders, profits, and valuation become unsynchronized.
The first risk is order pull-forward. Customers may place orders early to secure tools, lead times, and capacity. Strong billings do not necessarily mean terminal demand is infinitely strong. If cloud capex slows, memory pricing weakens, or advanced-packaging capacity is released later, orders may shift from pull-in to push-out. Equipment stocks would see valuation compression first.
The second risk is delayed profits. Equipment-company revenue growth does not automatically become profit. Faster delivery brings supply-chain costs, installation costs, fixed costs, and service pressure. Customer-mix changes can also pressure gross margin. The relative caution on companies such as SCREEN is essentially about the possibility that revenue and margins do not move together.
The third risk is valuation running ahead. Japanese and U.S. equipment stocks have risen significantly over the past period. The market has already reflected WFE upgrades in advance. If companies only deliver “the industry is good” but not “better than consensus,” stocks may still pull back.
The fourth risk is overheated memory expansion. DRAM and HBM tightness are driving equipment higher, but if capacity is released in a concentrated way in 2027-2028, memory pricing and capex discipline will be reassessed. Equipment companies usually peak before memory prices.
The fifth risk is export controls and regional policy. Japanese, U.S., and Chinese equipment companies are all affected by policy. Advanced-equipment export restrictions change customer procurement timing and may accelerate domestic substitution, but they are not linearly positive for all local equipment companies. For Naura, AMEC, and Piotech, share gains require real product validation, not just external restrictions.
Risk response cannot simply be “watch volatility.” For order pull-forward, watch the SEAJ three-month average, backlog quality, and whether customer push-outs appear. If billings strengthen first and then weaken, early demand may have only been a scramble for lead times.
For delayed profits, prioritize companies where revenue growth can flow into OPM. If revenue is strong but gross margin and operating margin do not rise, it usually means there are problems in order quality, customer mix, or delivery costs. Such companies should not receive the same AI manufacturing-bottleneck valuation.
For valuation running ahead, separate target-price moves from earnings upgrades. If the share price is already discounting 2027-2028 profits, the company must provide longer order visibility and higher EPS revisions. Otherwise, good-news delivery may become a trigger for a pullback.
For memory overheating, watch DRAM, HBM, NAND pricing and equipment move-in timing. If memory fabs release capacity in a concentrated way, long-term agreement prices loosen, or equipment move-in is delayed, WFE orders will weaken before memory income statements do.
For policy disruption, distinguish global equipment logic from domestic substitution logic. Export restrictions may accelerate domestic validation, but they may also slow customer expansion. For Naura, AMEC, and Piotech, what really matters is product validation and share gains, not treating external restrictions as a linear positive.
The equipment chain is still investable, but it now requires more discipline. Early in the cycle, investors could buy beta. Mid-cycle, they need to buy structure. Later, they need to buy profit conversion. The May Japan SPE data shows beta is still present, but structural differentiation is already very clear.
15. Conclusion: Japan SPE Turning Positive Signals the WFE Supercycle Moving from Models into Billings
The most important significance of Japan SPE turning positive YoY in May is that it pulls the WFE supercycle out of long-range models and back into high-frequency billings. Test equipment rose 41% YoY, packaging equipment rose 12% YoY, and front-end equipment rose 5% YoY. This divergence shows that AI manufacturing bottlenecks are converting in sequence: first test and delivery, then advanced packaging, and finally the larger front-end WFE layer.
From an investment perspective, investors can no longer say broadly that “all semiconductor equipment benefits.” Near term, the strongest line is Advantest and the test chain. Packaging processing points to Disco. Integrated front-end points to Tokyo Electron and Applied Materials. NAND and etch point to Lam Research and Kokusai Electric. Process control points to KLA and Lasertec. Chinese domestic equipment points to localization share at Naura, AMEC, and Piotech. Each line has its own validation points and cannot be solved with the same WFE multiple.
The real driver of the second leg in equipment stocks will be whether orders continuously enter the income statement. As long as the SEAJ three-month average continues to rise, test and packaging margins keep converting, and DRAM and NAND equipment move-in is not delayed, the WFE upcycle is not over. Conversely, if billings weaken, orders were pulled forward, and margins fail to follow, the equipment chain will move back from “AI manufacturing bottleneck assets” to cyclical stocks.
Therefore, this data is best used to update investment ranking rather than to draw a static industry conclusion. The first layer of the ranking is test and packaging, where high-frequency data has already converted. The second layer is front-end equipment that is about to enter revenue recognition. The third layer is deposition, etch, and process control, which need NAND and advanced logic to take over. The fourth layer is Chinese equipment platforms that depend on localization share expansion. Entry points, validation indicators, and risks are completely different across these layers.
If SEAJ billings continue to strengthen over the next few months but share-price reactions become dull, it does not necessarily mean the cycle is over. It may simply mean the market is waiting for margin and cash-flow confirmation. Conversely, if share prices keep rising but billings, orders, and margins do not follow, valuation exhaustion needs to be watched. The best phase for equipment stocks is when high-frequency data, company guidance, and margins all move upward together. The most dangerous phase is when only the story moves up while operating validation begins to slow.
That is the value of the May Japan SPE data: it is not the end point, but the first row of the validation table. The market already knows AI will buy more equipment. What now needs to be proven is who can turn those equipment orders into revenue, margins, and cash flow first.