
Japan Semiconductor Equipment Deep Dive: Strong Orders Do Not Guarantee Strong Profits—How Capacity Bottlenecks and ULVAC’s Downgrade to Sell Reshape Equipment Stock Rankings
目录
TL;DR
I. Demand Has Not Weakened, but the Scoring Rules for Equipment Stocks Have Changed
II. Cross-Company Comparison of 10 Companies: ULVAC Sits in the Most Unfavorable Combination
III. Why the Four Buy-Rated Companies Are Better Positioned to Convert Demand into Profit
IV. The Real Reason for ULVAC’s Downgrade: Strong Orders Are Bottlenecked at Delivery
V. The Most Striking Discrepancy in the Financial Model: Revenue Above Plan, but Profit Below Plan
VI. How Margins Reshape Valuation: From Operating Quality to Valuation Multiples
VII. Ratings Matrix: A Strong Industry Does Not Make Every Company Investable
VIII. Conditions That Would Disprove the ULVAC Thesis: What Could Invalidate the Sell Case
IX. How to Monitor the Next Phase: From Order Tables to a Margin Dashboard
Conclusion
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Demand for Japanese semiconductor equipment has not weakened; the change is in profit conversion. Goldman Sachs’ latest report puts capacity, lead times, and pricing power into a single framework, while also explaining why ULVAC was downgraded to Sell despite strong orders.
TL;DR
This cycle is no longer just about orders, but whether orders can translate into profits. Semiconductor manufacturers’ capital expenditure remains elevated, equipment components and materials are becoming more expensive, and customers are still requesting earlier deliveries, particularly for front-end equipment. Strong demand is already the consensus; what truly differentiates companies is whether capacity can keep pace, costs can be passed through, lead times remain under control, and revenue growth ultimately flows through to operating margin.
Goldman Sachs remains positive on Lasertec, EBARA, DISCO, and Tokyo Electron. These 4 companies are expected to deliver above-peer sales growth from FY25 to FY27 while continuing to expand margins. Overall, they have relatively ample capacity, stable lead times, and moderate-to-strong cost pass-through capabilities. Goldman Sachs’ selection criteria are clear: preserve delivery execution and pricing power amid strong demand.
ULVAC was downgraded not because orders disappeared. Orders in the company’s Semiconductor & Electronics segment are still growing, but the relevant equipment lines are already close to full utilization, with lead times extending from the usual approximately 6 months to 7–8 months. Apart from its high-share power-semiconductor equipment, ULVAC has relatively weak pricing power across other products. The stronger the orders, the more readily the bottlenecks are exposed.
ULVAC’s core issue is that it may achieve its revenue target but not necessarily its margin target. Goldman Sachs forecasts FY6/28 revenue of ¥287.6bn, above the company’s medium-term plan of ¥260.0bn; however, it forecasts operating profit of only ¥33.9bn and an operating margin of 11.8%, below the company’s targets of ¥39.0bn and 15%. The real point of disagreement is the quality of the incremental scale.
The price target was cut from ¥10,300 to ¥8,200, reflecting a dual hit from earnings and valuation. Goldman Sachs lowered its ULVAC operating-profit forecasts for FY6/27–FY6/29 by 18%, 15%, and 12%, respectively, while widening the EV/EBITDA discount to the global equipment sector from 50% to 55%. The new price target implies 17x forecast FY6/28 P/E, while the current share price still represents approximately 19x on the new forecasts; the upside case cannot be explained simply by “low valuation.”
Future validation should focus on 5 operating metrics. Watch whether ULVAC’s lead times decline, whether equipment modularization rises significantly above approximately 30%, whether the new management team changes its pricing strategy, whether the FY6/28 operating margin can move toward 15%, and whether operating cash flow can leave more free cash flow after capital expenditure. Unless all 5 improve concurrently, strong orders will remain only an indicator of revenue and will not yet be sufficient to demonstrate margin delivery.
I. Demand Has Not Weakened, but the Scoring Rules for Equipment Stocks Have Changed
Goldman Sachs’ June 30 Japan semiconductor-equipment strategy already made the industry thesis clear: AI and memory capital expenditure are continuing to drive wafer-fab equipment (WFE) demand higher, shifting Japanese equipment stocks from a total-demand trade into an earnings-delivery phase. The new July 27 report does not overturn that foundation; instead, it applies a more rigorous company-level stress test.
Demand remains strong in the report’s assessment. Major semiconductor manufacturers continue to pursue aggressive capital expenditure, while upstream supply chains are beginning to tighten. TSMC noted rising production-equipment prices during its earnings communication, and Goldman Sachs’ channel checks also indicate that equipment-component and material prices have begun to increase. At the same time, customers are still asking equipment vendors to bring deliveries forward, particularly for front-end equipment.
The issue is that the same set of signals can represent either an opportunity or a source of pressure.
For companies with ample capacity and competitive products, customer requests for faster deliveries mean earlier revenue recognition, while higher component costs can be passed through more readily via equipment price increases. For companies already operating at full capacity, facing longer lead times, and lacking enough market share to support aggressive price increases, customer requests for faster deliveries may simply expose capacity bottlenecks more fully: orders are in hand but cannot be converted into shipments at the original pace; procurement costs rise first while equipment prices cannot be adjusted simultaneously; revenue is deferred, placing both gross margin and operating margin under pressure.
The real update in this report, therefore, is the allocation framework under strong demand:
The first test is capacity flexibility: when new orders arrive, is there still room at the main production sites?
The second test is delivery stability: do lead times remain within the normal range, or will revenue recognition be deferred?
The third test is cost pass-through: when component costs rise, can equipment vendors pass those costs on to customers?
The fourth test is margin delivery: can revenue growth ultimately produce improvements in operating margin and cash flow?
The previous equipment Capex aggregate update addressed the total-demand question; this update addresses how profits from the same capital-expenditure cycle will be redistributed among equipment companies.
II. Cross-Company Comparison of 10 Companies: ULVAC Sits in the Most Unfavorable Combination
Goldman Sachs places the companies it covers into a “capacity–lead times–pricing power” framework and compares this with FY25–FY27 sales growth and changes in operating margin. This table explains the current company-level divergence better than orders alone.
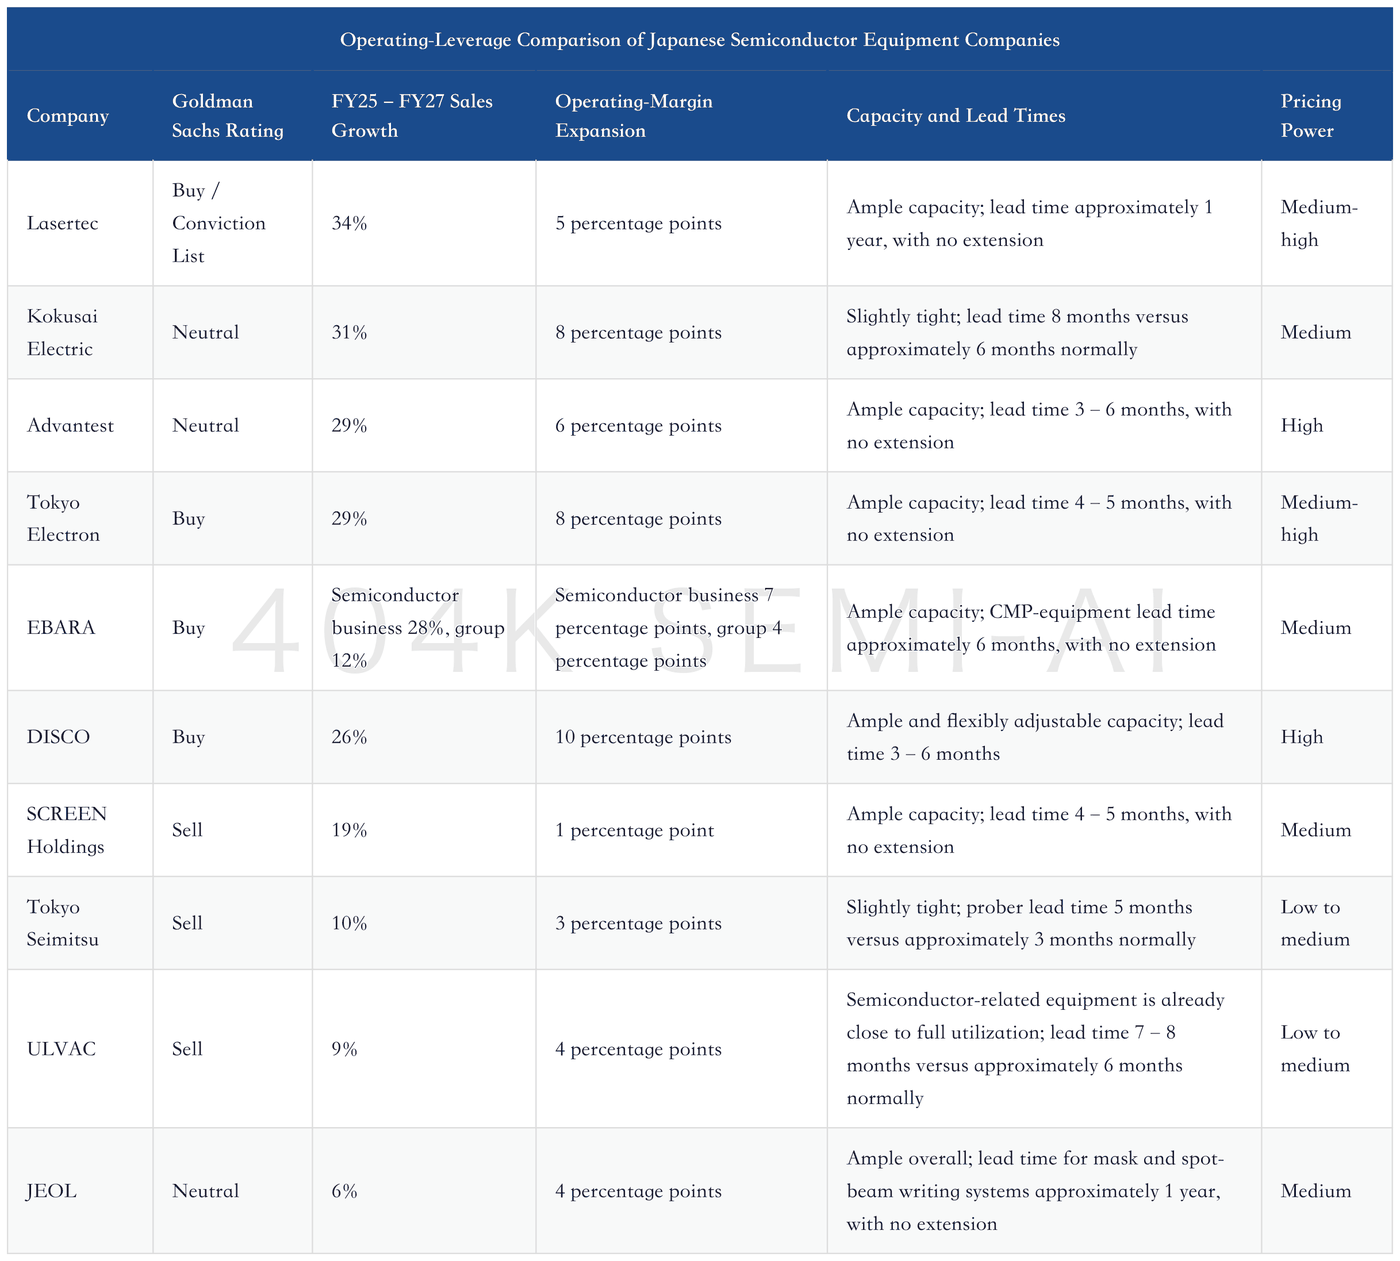
Average FY25–FY27 sales growth for the coverage group is approximately 19%. Even using the business-adjusted figure of 9%, ULVAC remains near the bottom. Its operating margin is expected to improve by 4 percentage points, which does represent progress, but it clearly trails DISCO’s 10 percentage points, Tokyo Electron’s and Kokusai Electric’s 8 percentage points, and EBARA’s semiconductor business at 7 percentage points.
More importantly, ULVAC simultaneously falls into all 3 unfavorable categories: “full utilization, extended lead times, and relatively weak pricing power.” Kokusai Electric and Tokyo Seimitsu also face capacity or lead-time pressure, but Kokusai Electric has stronger sales and margin growth, while Tokyo Seimitsu is already rated Sell. What distinguishes ULVAC is the particularly pronounced mismatch between order strength and operating flexibility.
The table also shows that long lead times are not inherently negative. Lasertec’s lead time is approximately 1 year, but it has not lengthened further, while the company has ample capacity and medium-high pricing power. ULVAC’s problem is that lead times continue to extend beyond normal levels while it lacks sufficient capacity and pricing power to absorb the change. Investors should distinguish between “products that inherently require long delivery cycles” and “delivery deterioration caused by supply bottlenecks.”
III. Why the Four Buy-Rated Companies Are Better Positioned to Convert Demand into Profit
Goldman Sachs maintains Buy ratings on Lasertec, Ebara, DISCO, and Tokyo Electron. The four companies are not inexpensive, and their businesses differ, but their shared advantage is a more complete operating chain.
Lasertec’s advantages are rapid growth, sufficient capacity, and relatively strong pricing power. Sales are expected to grow 34% from FY25 to FY27, the highest in the coverage group; operating margin is expected to rise by 5 percentage points. The roughly 1-year lead time appears long but has not deteriorated further. As long as leading-edge nodes and critical inspection demand remain resilient, the company has a better chance of converting orders into high-quality revenue.
DISCO has the greatest margin upside. Sales are expected to grow 26%, with operating margin rising by 10 percentage points; capacity can be adjusted flexibly in line with demand, and pricing power is rated high. The most important factor here is not any single order, but the company’s ability both to meet demand and defend pricing, making it more likely that economies of scale will flow through to the income statement.
Tokyo Electron combines industry breadth with pricing pass-through. Sales are expected to grow 29%, with operating margin rising by 8 percentage points; capacity is sufficient, lead times are stable, and pricing power is medium-high. When component costs rise, Tokyo Electron is better able than companies with weaker market shares to adjust equipment prices on new orders.
Ebara’s key attraction is the operating leverage of its semiconductor business. Semiconductor-business sales are expected to grow 28%, with operating margin rising by 7 percentage points; both capacity and CMP-equipment lead times are relatively stable. Group revenue growth is only 12%, cautioning investors against directly extrapolating the strength of the semiconductor segment to the entire company, but also indicating that this high-operating-leverage business is improving the group’s profit mix.
These four companies respectively represent technological barriers, flexible capacity, broad product portfolios, and operating leverage in semiconductor operations. Goldman Sachs assigns them more positive ratings because they retain supply capability when demand is strong and pricing power when costs rise.
IV. The Real Reason for ULVAC’s Downgrade: Strong Orders Are Bottlenecked at Delivery
Interpreting ULVAC’s downgrade simply as weak demand would miss its most important message. Goldman Sachs explicitly acknowledges that major semiconductor manufacturers are increasing capital expenditure and that orders for ULVAC’s semiconductor products are expanding. Orders in the Semiconductor & Electronics business are expected to rise from JPY 70.4bn in FY6/25 to JPY 115.3bn in FY6/26, JPY 124.5bn in FY6/27, JPY 138.3bn in FY6/28, and JPY 149.9bn in FY6/29.
The order curve is rising, but the production system has not gained sufficient flexibility in tandem.
First, the main production base is already close to its capacity ceiling. New orders do not automatically translate into higher shipments, and further order-backlog growth could instead delay revenue recognition. Goldman Sachs also reviewed ULVAC’s execution record in FY6/23, when the company lowered guidance due to delays in component deliveries. This does not mean history will necessarily repeat itself, but it does show that delivery control still needs to be validated when both orders and supply-chain demands are increasing simultaneously.
Second, component cost inflation cannot be fully passed through. The company can reflect part of the higher costs in quotes when accepting orders, but its market position varies by product. ULVAC has a relatively high share in power-semiconductor equipment, particularly ion implanters, giving it comparatively greater room to raise prices; its competitive position is weaker in other equipment, where aggressive price increases could affect order intake and market share. Cost pressures are therefore more likely to remain embedded in gross margin.
Third, production reforms have begun but are not yet sufficiently mature. The company is promoting equipment modularization, securing components in advance, and conducting planned production before receiving formal orders, with the aim of shortening cycle times and raising productivity. However, the equipment modularization rate is only about 30% in FY6/26, while lead times have lengthened from 6 months to 7–8 months. The direction of reform is correct, but that does not mean the current pace is sufficient to support management’s margin target.
Fourth, the pricing strategy has historically been passive. Gross margin reached a record high of 31.8% in FY6/25 but remained below the 35% target set in the previous medium-term plan. This indicates that structural reforms and cost controls have delivered results, but profitability has not yet sustainably cleared the threshold. Junya Kiyota became the new president on July 1, 2026, and the market will now assess whether new-order pricing, lead times, and the modularization rate can improve simultaneously.
Accordingly, Goldman Sachs downgraded ULVAC from Neutral to Sell and lowered its 12-month price target from JPY 10,300 to JPY 8,200. The order trajectory remains upward, but the current capacity and pricing structure make it difficult to achieve a sufficiently rapid margin improvement.
V. The Most Striking Discrepancy in the Financial Model: Revenue Above Plan, but Profit Below Plan
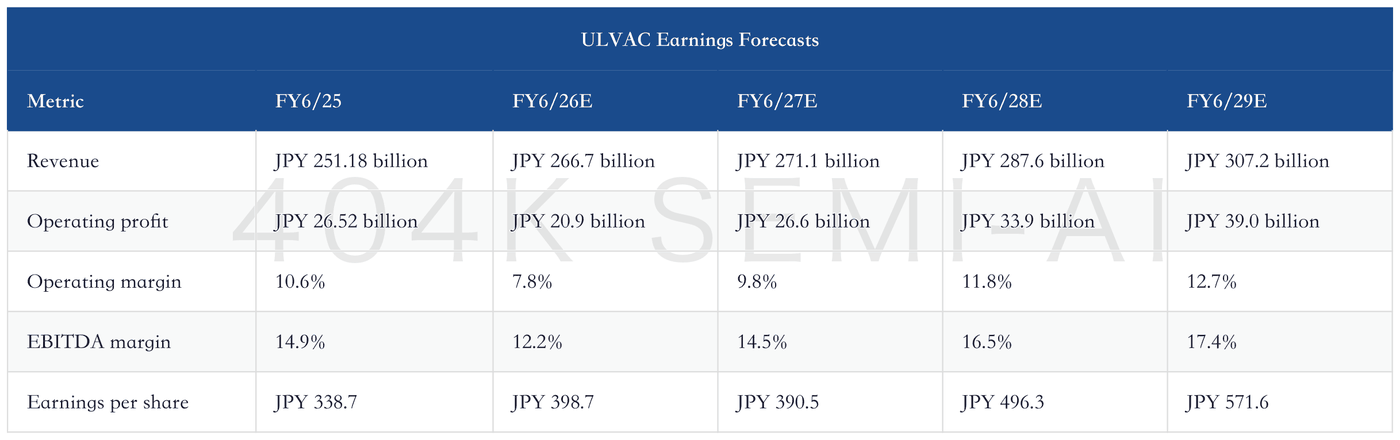
This model should not be assessed solely on the profit recovery after FY6/27. FY6/26 revenue is expected to grow 6.2%, while operating profit declines 21.2%, indicating that cost, mix, and delivery issues initially depress operating leverage. In FY6/27, revenue grows only 1.6%, while operating profit is expected to rebound 27.3%, reflecting a clear low-base effect. By FY6/28, operating margin recovers to 11.8%, but this is still insufficient to demonstrate that the company has achieved a structural step-change.
The most important comparison is in FY6/28. The company’s medium-term plan targets revenue of JPY 260.0bn, operating profit of JPY 39.0bn, and an operating margin of 15%; Goldman Sachs forecasts revenue of JPY 287.6bn, JPY 27.6bn above the company’s target, but operating profit of only JPY 33.9bn, JPY 5.1bn below the company’s target. In other words, Goldman Sachs does not doubt ULVAC’s ability to achieve scale, but questions the margin on that incremental scale.
The divergence persists further out. The company targets FY6/31 revenue of JPY 360.0bn, operating profit of JPY 79.0bn, and an operating margin of 22%; Goldman Sachs forecasts only 12.7% by FY6/29. The fiscal years differ, so the terminal values cannot be compared mechanically, but the directional contrast is clear: management believes capacity, modularization, and product mix will drive a step-change in margin, while Goldman Sachs expects only gradual recovery.
Goldman Sachs therefore cut its FY6/27, FY6/28, and FY6/29 operating-profit forecasts by 18%, 15%, and 12%, respectively, with its FY6/28 forecast more than 20% below Bloomberg consensus. EPS was also cut substantially: FY6/27 from JPY 488.2 to JPY 390.5, and FY6/28 from JPY 600 to JPY 496.3.
There is some contrary near-term evidence. Goldman Sachs’s FY6/26 fourth-quarter revenue and operating-profit forecasts remain above the company’s implied figures, while the balance sheet remains in a net-cash position. The issue is that free-cash-flow yields from FY6/26 through FY6/29 are expected to be only 1.2%, 2.2%, 2.4%, and 2.9%, respectively. After capital expenditure and working-capital absorption, incremental total cash flow remains limited. If margin recovery does not translate into cash flow more quickly, the valuation downside protection will be weakened.
VI. How Margins Reshape Valuation: From Operating Quality to Valuation Multiples
Goldman Sachs plots forecast FY27 EBITDA margins against the EV/EBITDA multiples implied by current share prices, with a linear-fit R²=0.6548. Within this sample of equipment companies, margins explain about 65% of the cross-sectional valuation differences. DISCO and Advantest occupy the high-margin, high-multiple region, while ULVAC falls into the low-margin, low-multiple region.
This result should not be misread as meaning that every 1-percentage-point margin increase necessarily produces a specific valuation increase. The sample contains a limited number of companies, which also differ in products, customers, growth rates, and capital structures; correlation does not equal causation. However, it captures the economic reality of the equipment industry: high margins generally indicate stronger technological barriers, pricing power, product mix, and capacity efficiency, and these capabilities also improve earnings visibility.
ULVAC’s problem is that the market has already priced in part of the expected cyclical recovery. The current share price implies a P/E of about 19x based on Goldman Sachs’s new FY6/28 forecast, placing it toward the high end of its range from slightly below 10x to slightly above 20x over the past 5 years. If margins can recover only gradually, 19x does not represent clear undervaluation.
Goldman Sachs’s new price target is based on forecast FY6/28 EBITDA, applying the global semiconductor production equipment (SPE) industry’s 18x EV/EBITDA multiple and then assigning ULVAC a 55% discount, wider than the previous 50% discount. The JPY 8,200 price target corresponds to a forecast FY6/28 P/E of 17x, P/B of 1.5x, and EV/EBITDA of 8x. The price target was cut by about 20%, partly due to downward earnings revisions and partly because the multiple the market is willing to assign to low-margin assets has declined further.
The report body indicates potential downside of about 18% using a different price reference, while the summary table calculates 14.7% based on the July 24, 2026 closing price of JPY 9,610. These are not the same valuation dates and cannot be combined into a more “precise” conclusion; only the direction can be confirmed: the new price target is below the share price around the report date and lacks appeal relative to the coverage group.
VII. Ratings Matrix: A Strong Industry Does Not Make Every Company Investable
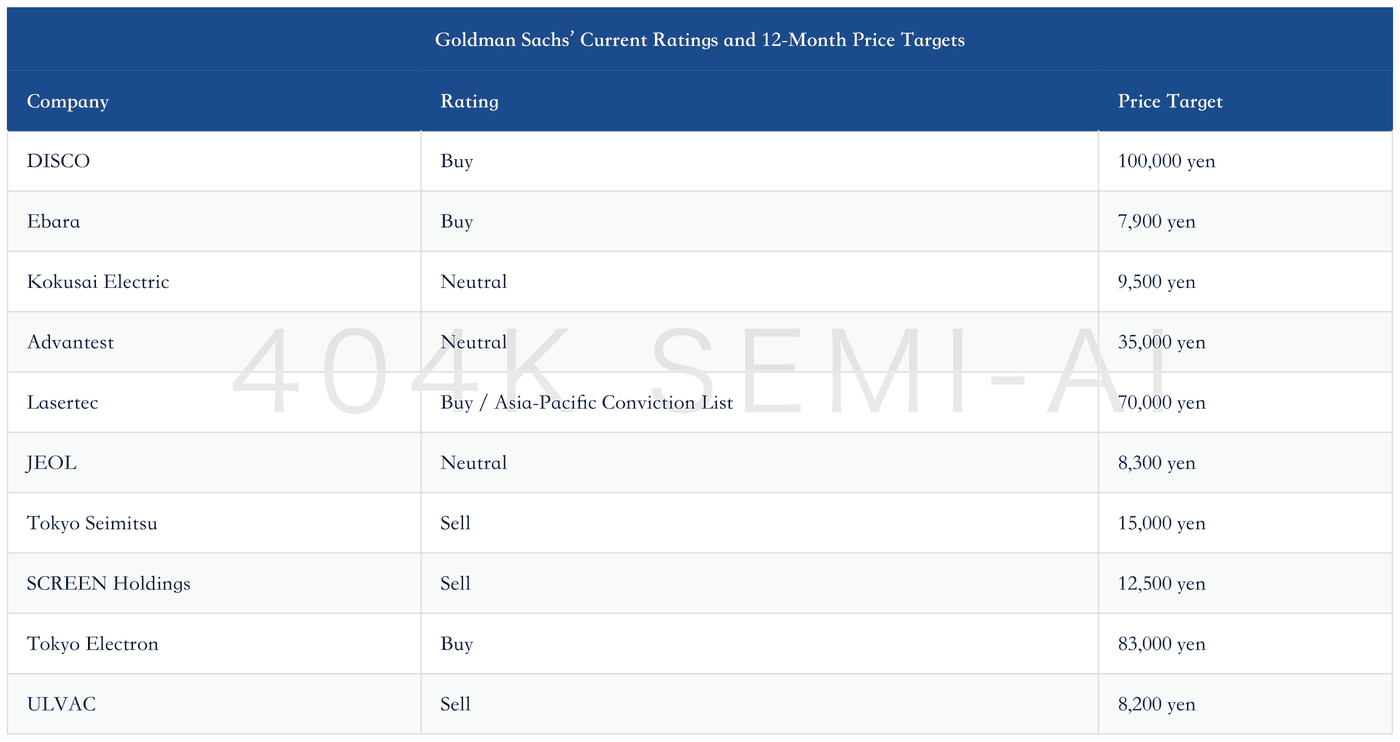
The absolute price targets in this table are not comparable across companies because their share counts and per-share prices differ. What matters is the combination of rating and valuation methodology: DISCO and Lasertec receive 50% EV/EBITDA premiums to the sector due to their high margins and technological advantages, while Tokyo Electron receives a 30% premium; Kokusai Electric is valued at the sector average of 18x; Tokyo Seimitsu and SCREEN Holdings are assigned 40% discounts; and ULVAC is assigned a 55% discount, one of the most pronounced valuation penalties in the coverage group.
Advantest is a useful counterexample. Its FY25–FY27 sales growth of 29%, 6 percentage-point increase in operating margin, ample capacity, and strong pricing power give it a respectable operating score, yet it remains rated Neutral. This shows that operating leverage is only a necessary condition; how much is already priced into the shares, the current multiple, and the scope for incremental expectation upside are equally important. Kokusai Electric also has 31% sales growth and an 8 percentage-point margin increase, but with longer lead times and slightly tight capacity, it remains rated Neutral.
It is also important to note that Goldman Sachs’ Buy, Neutral, and Sell ratings rank total returns relative to the relevant coverage group and do not constitute promises of absolute returns. The disclosure appendix also states that, as of the end of the month preceding the report’s publication, Goldman Sachs beneficially owned 1% or more of the common shares of Ebara, Lasertec, and ULVAC, and had or was seeking investment-banking relationships with multiple covered companies. These disclosures do not automatically invalidate the research conclusions, but they remind readers to independently verify them against operating data rather than treat ratings as trading instructions.
VIII. Conditions That Would Disprove the ULVAC Thesis: What Could Invalidate the Sell Case
Goldman Sachs identifies several upside risks for ULVAC, all of which can be translated into explicit monitoring indicators.
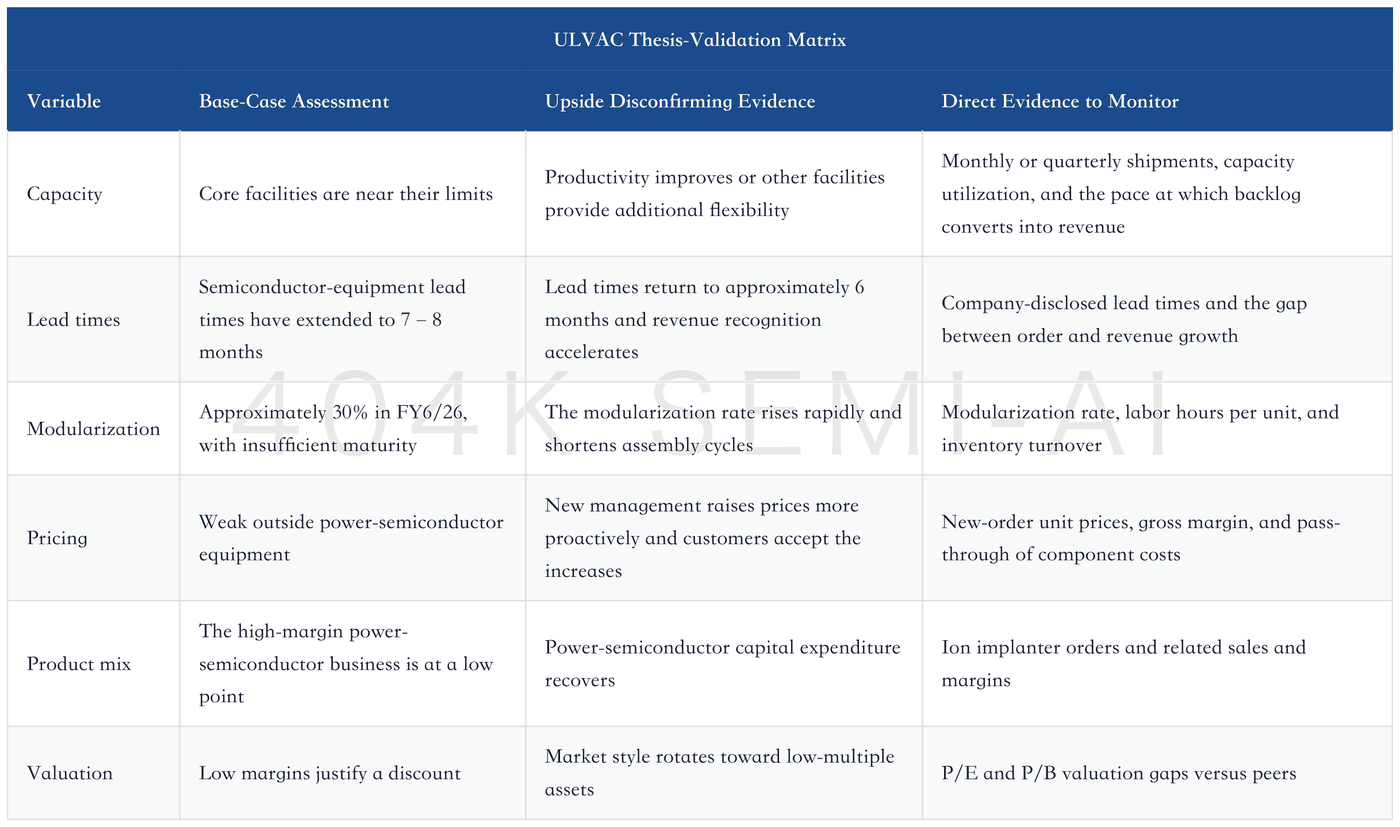
The strongest upside disconfirming scenario would be for new management to resolve both pricing and capacity constraints. If ULVAC can increase its modularization rate, mobilize other facilities, and pass component-cost inflation through in new orders, lead times could decline while revenue recognition and gross margin improve together. In that case, with the FY6/28 operating margin approaching 15%, the 55% discount to the sector valuation could prove excessive.
A second disconfirming scenario comes from power semiconductors. Related sales have now fallen to less than one-third of their recent peak, while ULVAC has a high share and strong margins in ion implanters. If this investment cycle recovers, the company would not only generate additional revenue but could also improve its product mix. Until order and earnings data emerge, however, this remains an option rather than the base case.
The base case remains strong demand and a gradual margin recovery. ULVAC’s revenue and operating profit continue to grow after FY6/27, indicating that the Sell thesis is not based on the company entering a downturn, but on its slower growth and lower margins relative to other equipment companies, while its valuation is not cheap enough to compensate for execution risk.
In the bear case, component costs continue to rise, lead times extend further, and customers’ requests for earlier delivery cannot be met. This would create a self-reinforcing loop of “high backlog—slow revenue recognition—pressure on gross margin—weak free cash flow.” The more orders the company receives, the greater the near-term pressure on working capital and supply-chain management.
IX. How to Monitor the Next Phase: From Order Tables to a Margin Dashboard
The industry-wide volume thesis for Japanese equipment stocks remains intact. Capital expenditure on AI, DRAM, and HBM continues to drive demand for front-end, testing, inspection, and advanced-packaging equipment, while the memory-capacity expansion described in Goldman Sachs’ in-depth DRAM update remains an important source of demand. After the equipment sector’s earlier rerating, however, a strong industry alone is no longer sufficient.
The monitoring sequence should now be:
Start with lead times. Stable lead times indicate that supply chains and capacity remain manageable; if lead times continue to extend, investors must determine whether this reflects pricing power from product scarcity or production bottlenecks that are delaying revenue.
Then assess pricing. Equipment components and materials have already become more expensive. Whether new-order prices and gross margins improve in tandem will directly distinguish strong suppliers from weak ones.
Third, examine the divergence between revenue and orders. Orders growing materially faster than revenue alongside extending lead times generally indicate accumulating bottlenecks; only when revenue keeps pace with orders is capacity actually converting demand into deliveries.
Fourth, monitor operating margins. Expected margin improvements are greater for DISCO, Tokyo Electron, Kokusai Electric, and Ebara’s semiconductor business, and weaker for ULVAC and SCREEN Holdings. If reported results do not conform to this ranking, the ratings framework will need to be reassessed.
Finally, examine cash flow. Equipment companies can use raw-material inventories and work in progress to accelerate deliveries, but this consumes working capital. Earnings are fully realized only when margins and free cash flow improve together.
This dashboard also applies across the entire Japanese equipment supply chain. During periods of strong industry demand, the easiest mistake is to treat all backlog as equal in quality. Truly high-quality orders must be validated jointly by deliverable capacity, sustainable pricing, and cash-flow generation.
Conclusion
Goldman Sachs’ July 27 report did not change its view that demand for Japanese semiconductor equipment is rising, but it advanced the investment focus from “who has orders” to “who can convert orders into profit.” Lasertec, Ebara, DISCO, and Tokyo Electron are better positioned not merely because they are growing rapidly, but because capacity, lead times, and pricing power form a more complete operating loop.
ULVAC’s downgrade provides the clearest counterexample: semiconductor orders continue to grow and revenue can still expand, but full capacity utilization, extending lead times, a low modularization rate, and insufficient pricing power lead Goldman Sachs to forecast an FY6/28 operating margin of only 11.8%, below the company’s 15% target. Whether this conclusion can reverse depends on lead times, the modularization rate, equipment pricing, margins, and free cash flow all improving together; another large order alone would not be enough.