
Japan Semiconductor Equipment Deep Dive: Goldman Raises Target Prices for 10 Companies by 16%; AI WFE Enters the Earnings-Delivery Stage
目录
TL;DR
I. The Key Point of This Goldman Report Is Not "Bullish on Equipment," but "A New Stock-Selection Framework"
II. Target-Price Table: Goldman Raises Targets by 16% on Average, but Upside Varies Widely
III. Industry Aggregate: CY27 WFE +32%, but Aggregate Upgrades Are No Longer Scarce Information
IV. Core Model: Valuing the Japanese Equipment Chain Requires the Revenue Slope and Margin Slope
V. Lasertec: Leading-Edge Inspection Is the Most Direct Bottleneck Asset
VI. Disco: Advanced Packaging Pushes Cutting, Grinding, and Polishing from Cyclical Equipment to AI Process Bottleneck
VII. Ebara: Precision Machinery Is the More Visible Margin Elasticity That Can Beat Guidance
VIII. Tokyo Electron: Broad Product Line and Equipment Price Hikes Make It Japan's WFE Ledger Stock
IX. Kokusai Electric: High Probability of Guidance Upgrade, but Risk-Reward Is Already Balanced
X. Advantest, Ulvac, and JEOL: Neutral Does Not Mean No Cycle; It Means Not Enough Expectations Gap
XI. SCREEN and Tokyo Seimitsu: Also Benefiting from WFE, but Profit and Order Quality Are Not Enough
XII. Ranking the 10 Companies: Buy Technology Bottlenecks, Buy Earnings Delivery, Avoid Fully Priced Expectations
XIII. The AI WFE Transmission Chain: From Memory-Maker Capex to Japanese Equipment Profits
XIV. Margins Are the Deciding Factor in Stage Two: Good Revenue Is Not Enough; OPM Must Follow
XV. Quality of Target-Price Increases: Some Are Earnings Upgrades, Others Are Valuation-Year Roll-Forwards
XVI. Three Scenarios: Can Equipment Stocks Keep Rising?
XVII. Disconfirmation Checklist: What Would Invalidate the Report's Logic
XVIII. Connection with Existing WFE Views: From Industry Ledger to Company Delivery
XIX. What to Track Over the Next Four Quarters
XX. Valuation in Practice: From WFE Elasticity to Earnings Quality
XXI. Investment Conclusion: Japanese Equipment Stocks Still Work, but They Can No Longer Be Bought with an Everything-Rises Mindset
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The trade in Japanese semiconductor equipment stocks has moved from "AI capex upgrades" to "who can turn orders into profit." Goldman Sachs raised its target prices for 10 equipment companies by an average of 16%, but also notes that valuation expansion is no longer cheap. The next stage will be decided by earnings beats, margin improvement, and pricing power around technology bottlenecks.
TL;DR
Japanese equipment stocks have entered the earnings-delivery stage. Goldman Sachs raised its target prices for 10 Japanese semiconductor equipment companies by an average of 16%, driven by upward revisions to capex expectations at memory makers such as Samsung and Micron Technology, with WFE still potentially growing 32% YoY by CY27. The issue is that share prices have already moved: the 10 companies are up 65% on average year to date, far above TOPIX at 17%, so the next leg cannot rely only on industry beta.
Stock selection is shifting from multiple expansion to earnings surprise. Goldman explicitly says equipment-company valuations are already above historical ranges, leaving limited room for further multiple expansion. The real drivers of share prices from here are two things: whether a company's revenue can outgrow the industry average, and whether that revenue growth can translate into visible margin improvement. This screen divides the Japanese equipment chain into two types of assets: those that can turn AI WFE into earnings upgrades, and those that are simply rising with the industry cycle.
Goldman is most positive on Lasertec, Ebara, Disco, and Tokyo Electron. After target-price increases, these four still offer double-digit or near-double-digit upside. Their common trait is not cheapness, but the possibility that orders, technology changes, or margins can continue to exceed market expectations. The target-price details are in the table below; more importantly, the four companies represent four different ways for the Japanese equipment chain to deliver earnings.
Kokusai Electric has been reinstated at Neutral. Goldman forecasts Kokusai FY3/27 operating profit of JPY70.1bn, well above company guidance of JPY54.5bn, and sees a meaningful probability of guidance being raised after 1Q. But the share price has already reflected this in advance. The company also has high exposure to NAND equipment and high-margin mini-batch deposition systems, while current capex is still more skewed toward DRAM and HBM. Because the NAND recovery is not strong enough, the risk-reward has been pulled back to balance.
This equipment rally is not about all equipment rising together. AI servers, HBM, CoWoS, EMIB-T, hybrid bonding, CPO, DRAM expansion, and leading-edge processes are all pulling WFE higher, but different equipment companies capture different profit pools. Disco benefits from cutting, grinding, and polishing for advanced packaging; Lasertec from leading-edge inspection; Ebara from CMP and precision machinery; Tokyo Electron from a broad product line and equipment price hikes; while SCREEN and Tokyo Seimitsu face constraints around margins and order quality.
Four numbers matter for validation. First, whether CY27 WFE growth approaches Goldman's 32% forecast; second, whether memory-maker capex continues to spread from HBM into DRAM/NAND; third, whether Japanese equipment-company FY27-FY28 earnings continue to exceed consensus; and fourth, whether order growth flows into OPM rather than being absorbed by fixed costs, lead times, competition, or changes in the Chinese customer mix. Only if all four hold can the Japanese equipment chain move from a cycle trade into an earnings-delivery trade.
I. The Key Point of This Goldman Report Is Not "Bullish on Equipment," but "A New Stock-Selection Framework"
Japanese semiconductor equipment stocks have already completed the first phase of rerating over the past six months. The market first traded AI capex upgrades, memory-maker capacity expansion, equipment intensity driven by HBM, and demand for advanced packaging and inspection. In that phase, many stocks could rise as long as they were on the WFE chain. The value of this Goldman 2H CY26 strategy report is that it pushes the question one step forward: after the market has already recognized the industry cycle, who can keep rising?
The answer is not to simply buy every equipment stock. Goldman's framework is clear: valuations have risen, it is harder to rely on further multiple expansion, and the next question is whether earnings expectations can still be revised up. The trade in Japanese equipment stocks is shifting from "WFE upgrades driving industry beta" to "can company profits beat consensus." That is the most important inflection point in this report.
The 10 Japanese SPE companies covered by Goldman are up 65% on average year to date, while TOPIX is up only 17% over the same period. That gap shows the market has already priced in AI capex, memory-maker expansion, and CY26-CY27 WFE growth expectations. If investors continue to explain upside simply by saying "the industry is strong," they risk chasing the second half of the move. The more useful questions are: which equipment segment still has order upside, which company still has margin elasticity, which target-price increase is merely a valuation-year roll-forward, and which target-price increase reflects a true earnings rerating?
Rerating Japanese Semiconductor Equipment and Materials: Physical Bottleneck Assets Behind AI Compute Expansion
This report continues the main line of the Japanese equipment-and-materials rerating, but with a finer focus. The previous logic was that Japanese equipment and materials are the physical bottlenecks behind AI compute expansion. The question now is: once the market has already priced those bottlenecks, how do we distinguish "bottlenecks that can still surprise" from "bottlenecks that are already fully reflected"? Goldman's answer is to screen by revenue growth and margin improvement.
This screening method suits the current stage. When aggregate WFE is rising, equipment-company orders generally improve; but good orders do not necessarily mean continued share-price elasticity. For stocks to keep moving higher, new earnings expectations must exceed old earnings expectations, exceed market consensus, and not be fully offset by higher valuations. Put differently, the equipment chain has moved from "who has orders" to "who can turn orders into higher margins."
Goldman states this directly in the report: first, can the company deliver revenue growth above the industry average through technology changes, proprietary technology, or share gains; second, can revenue intensity drive visible margin improvement. These two items correspond to the slope of revenue and the slope of margins. Only when both are present do equipment stocks have the foundation for a second leg higher.
II. Target-Price Table: Goldman Raises Targets by 16% on Average, but Upside Varies Widely
The most striking number in this update is that target prices for the 10 companies were raised by an average of 16%. But an average target-price increase does not mean all 10 companies deserve the same view. Goldman's rating distribution is clear: Lasertec, Ebara, Disco, and Tokyo Electron are Buy; Advantest, JEOL, Ulvac, and Kokusai Electric are Neutral; Tokyo Seimitsu and SCREEN Holdings are Sell.
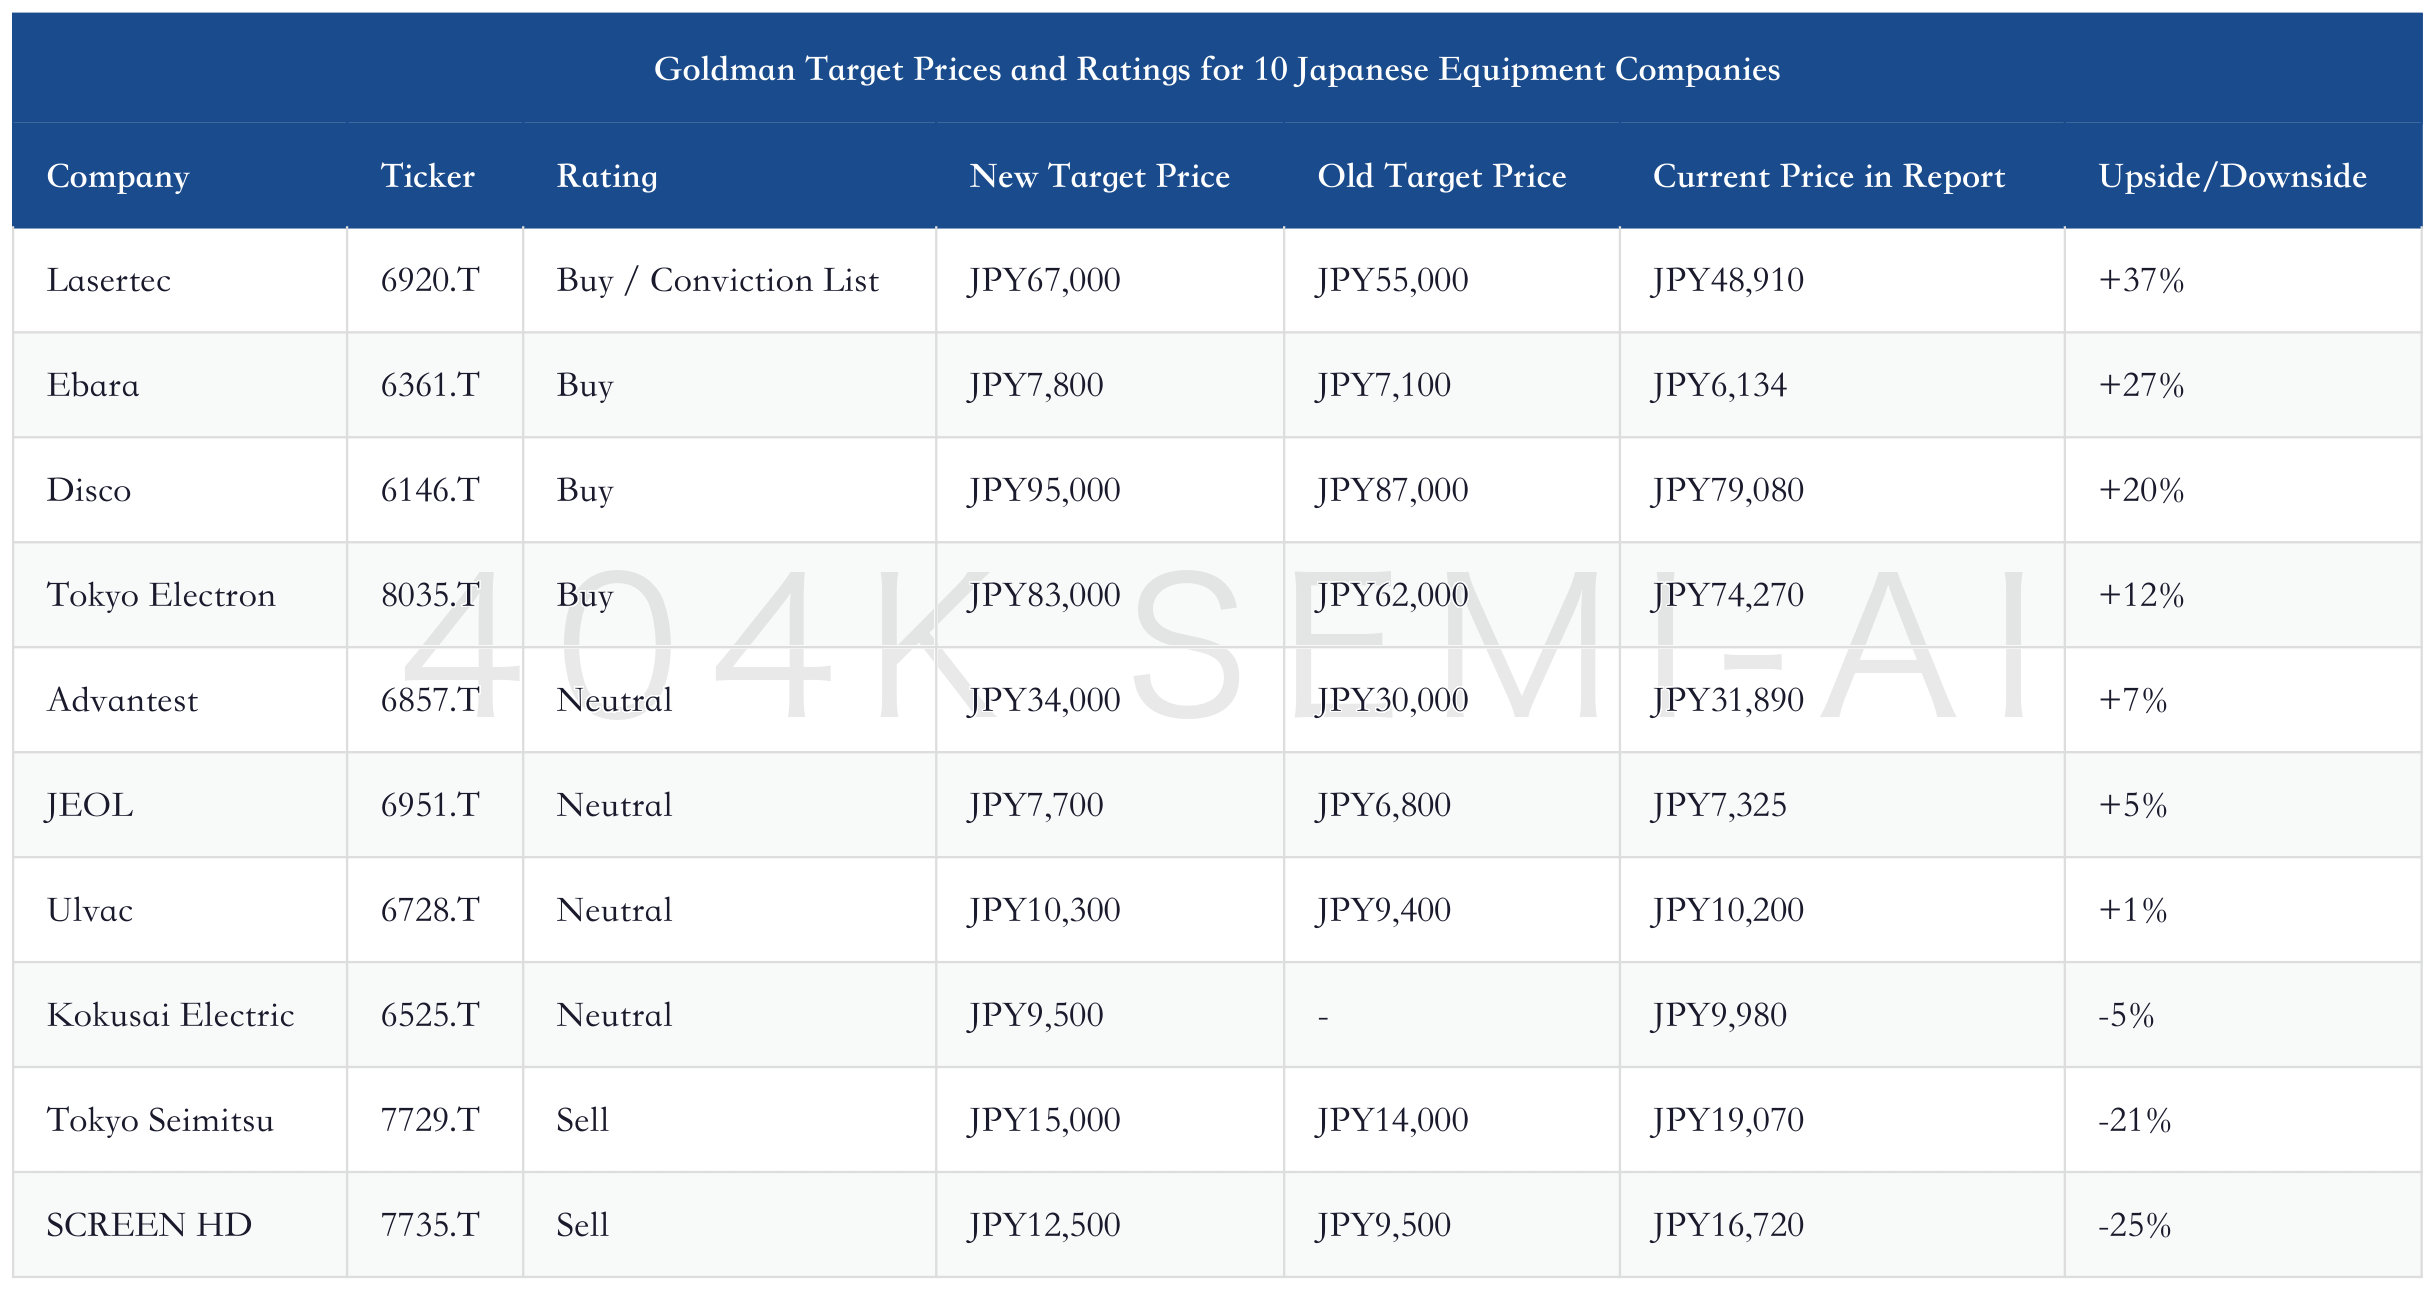
This table should be read in three layers.
The first layer is the four companies where Goldman is clearly willing to assign upside. Lasertec, Ebara, Disco, and Tokyo Electron all have double-digit upside and Buy ratings. They are not the same type of asset. Lasertec is closer to leading-edge inspection and key-customer capex; Ebara is closer to CMP and precision-machinery guidance upgrades; Disco is closer to advanced-packaging processing; Tokyo Electron is closer to a broad product line and equipment price hikes.
The second layer is Neutral-rated companies. Advantest, JEOL, Ulvac, and Kokusai are not weak fundamentally; rather, expectations, margins, or valuations have already absorbed most of the good news. Advantest benefits from AI test demand, but the market already has high expectations for GPU/ASIC testing; Kokusai has a probability of guidance upgrades, but the share price has already reflected that; Ulvac has order expansion, but lead times and margin ramp limit near-term elasticity; JEOL has an opportunity in spot-beam mask writers, but multi-beam mask writers and scientific metrology instruments have not fully recovered.
The third layer is Tokyo Seimitsu and SCREEN, where Goldman remains bearish. Both also benefit from the industry cycle, but Goldman believes it is harder for earnings to materially beat market expectations. Tokyo Seimitsu has high customer concentration in HBM probers, while logic probers face competition from OSATs. SCREEN may have guidance upside in 2H, but margin improvement is constrained by customer mix and fixed costs for future growth.
This is why the report deserves to be written as a deep dive. Goldman is not simply bullish on Japanese equipment; it is stratifying companies within the same WFE upcycle: even within equipment, technology bottlenecks, customer mix, margin elasticity, and valuation frameworks differ completely.
III. Industry Aggregate: CY27 WFE +32%, but Aggregate Upgrades Are No Longer Scarce Information
Goldman expects the WFE market to grow 32% YoY by CY27, with CY27 growth faster than CY26. This is a critical view. It means the semiconductor equipment cycle is not relying only on an order recovery in 2026; it may still accelerate into 2027. AI semiconductor demand is lifting capex at major players, memory makers are raising DRAM/HBM-related investment again, and advanced packaging and front-end equipment are being pulled higher together, naturally benefiting the Japanese equipment chain.
The WFE Supercycle Has Just Begun: How AI Capex Can Push Semiconductor Equipment Toward USD250bn
This is consistent with the view of a global WFE supercycle. AI capex does not only mean buying more GPUs; it also rewrites wafer-fab equipment demand. Memory needs to expand for HBM and DDR5; logic foundries need to expand for advanced nodes and ASICs; advanced packaging needs to expand for CoWoS, hybrid bonding, EMIB-T, and CPO. What the equipment chain captures is the second-layer elasticity from "AI server demand transmitting from chip orders to capacity orders."
But aggregate upgrades themselves are no longer scarce. Over the past period, the market has repeatedly traded WFE upgrades, memory price increases, HBM expansion, and equipment order visibility. The gains in Japanese equipment stocks year to date already show that investors are not short of an industry-cycle story. What is truly scarce is the earnings divergence at the company level.
This divergence can be broken into four questions.
First, can an equipment company's revenue growth outpace WFE? Tokyo Electron has a broad product line and equipment price hikes; Disco has advanced-packaging processing; Lasertec has leading-edge inspection and A200HiT; Ebara has CMP and precision-machinery orders. These companies may not simply track WFE; technology changes may give them a higher value share.
Second, can order growth flow into margins? Strong orders but no gross-margin improvement leave limited share-price elasticity. The equipment industry's biggest problem is good revenue combined with rising costs, with margins ultimately absorbed by capacity, people, fixed costs, and customer mix. Goldman emphasizes OPM improvement in its stock selection precisely to guard against this issue.
Third, can earnings expectations exceed consensus? Goldman's outer-year profit forecasts for Disco, Ebara, Lasertec, and Tokyo Electron are meaningfully above consensus, suggesting there is still room that "the market has not fully priced." By contrast, even though Goldman raised target prices for SCREEN and Tokyo Seimitsu, it is not constructive on their earnings relative to consensus.
Fourth, is there room for further valuation expansion? Goldman says equipment-company valuations have already risen toward the upper end of historical ranges, making further multiple expansion difficult. This sentence matters. It means the next leg higher will not come from "the whole industry valuation moving up another notch," but from EPS and OP upgrades.
The WFE supercycle is never a straight line. Every equipment rally goes through three stages: first trade the aggregate, then trade orders, and finally trade profits. Japanese equipment stocks have clearly entered the third stage. The aggregate logic remains, but share prices now require more concrete earnings delivery.
IV. Core Model: Valuing the Japanese Equipment Chain Requires the Revenue Slope and Margin Slope
The most useful model in Goldman's report is to compress company selection into two variables: whether revenue growth is above the industry and whether margins improve visibly. This model is simple, but it suits equipment stocks well.
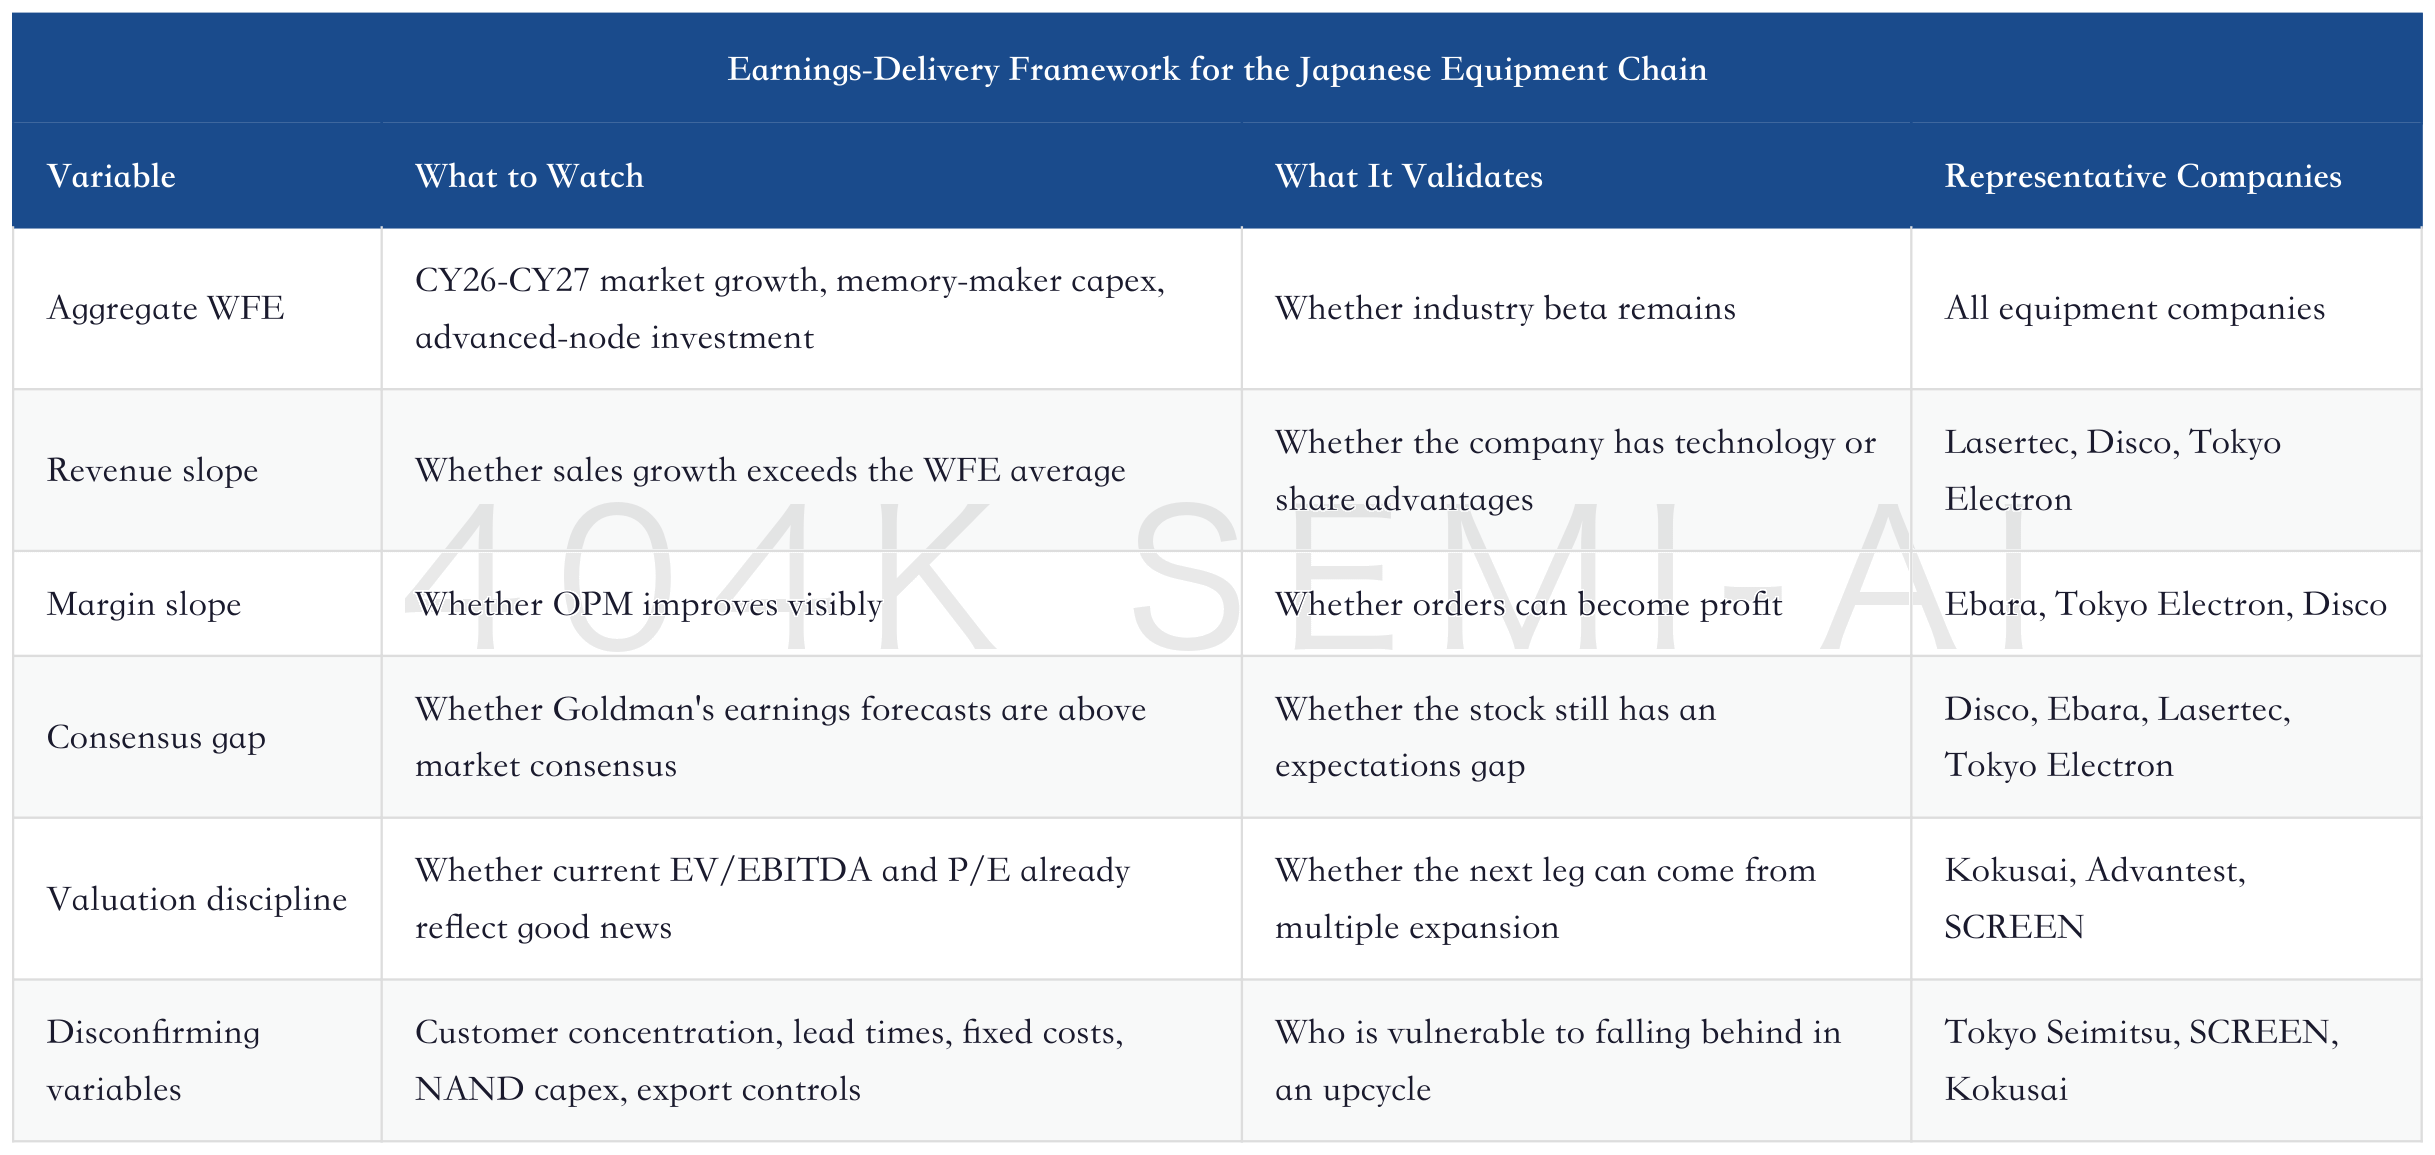
This framework explains why Goldman raised many target prices while assigning only a small number of Buy ratings. A target-price increase can come from earnings upgrades, a valuation-year roll-forward, or a broader increase in industry valuations. A Buy rating requires more: earnings must be better than the market expects, margins must be more elastic, and risk-reward cannot have been fully consumed by the share price.
Lasertec and Disco share a revenue slope created by technology change. Lasertec benefits from leading-edge customer investment and new products, while Disco benefits from advanced-packaging process changes. AI servers raise requirements for packaging and inspection, turning technology barriers into order elasticity.
Ebara and Tokyo Electron share guidance-upgrade and margin-improvement logic. Ebara has relatively high visibility for precision-machinery guidance upgrades, while Tokyo Electron may continue to beat consensus through sales growth above WFE, equipment price increases, and margin improvement. They are not the purest single-technology assets, but their operating leverage is clearer.
The divergence around Kokusai, Advantest, SCREEN, and Tokyo Seimitsu can also be explained with this model. Kokusai's earnings may be upgraded, but valuation is already not low and NAND exposure affects margin targets; Advantest benefits from AI testing, but test duration and CPU market size are insufficient to support more aggressive upgrades; SCREEN and Tokyo Seimitsu face margin, customer concentration, or order-quality issues. They are not lacking cycle exposure; rather, the cycle has difficulty becoming a sufficiently new expectations gap.
V. Lasertec: Leading-Edge Inspection Is the Most Direct Bottleneck Asset
Lasertec remains one of the Japanese equipment stocks Goldman emphasizes most. The target price was raised from JPY55,000 to JPY67,000, with Buy and Conviction List retained. Goldman's indicated upside is 37%, the highest among the 10 companies.
Lasertec's core is not "equipment-stock cyclicality," but leading-edge inspection. AI chips, advanced nodes, EUV-related inspection, leading-edge customer investment, and new-product ramp determine whether it can continue to outgrow the equipment industry. Goldman continues to expect order growth above market consensus, mainly from capex by key customers such as TSMC, Intel, and Samsung Electronics, as well as full A200HiT contribution from FY6/27 onward.
Lasertec's asset profile is closer to a "scarce leading-edge inspection platform." This type of company has elasticity when aggregate WFE is revised up, and additional elasticity when advanced-node complexity rises. As AI training and inference platforms continue to advance, GPUs, ASICs, and advanced packaging require higher standards for process yield, defect inspection, and mask-related steps. As long as customers keep pursuing leading-edge nodes, inspection equipment is not just cyclical; it is yield infrastructure.
Japan and Korea AI Semiconductor Chain Deep Dive: Japanese Equipment and Materials, Korean HBM, Industrial Automation, and the Next Rerating Theme in Asian Tech
Lasertec's risks are also clear. The first is new entrants and share risk. Goldman's risk table notes that target-price logic would be damaged if new entrants caused share loss. The second is the progress of ACTIS adoption; if fabs adopt it more slowly than expected, the revenue slope would be pressured. The third is leading-edge customer investment appetite. Strong AI demand can support investment, but if customer capex is constrained by yield, costs, or macro financing conditions, orders will be affected first. The fourth is rapid yen appreciation, which pressures both exports and valuation.
Lasertec belongs at the front of the Japanese equipment chain because it represents the question of "can technology bottlenecks continue to be capitalized?" If Lasertec orders keep beating expectations, the market is still willing to pay a premium for leading-edge bottlenecks; if Lasertec starts to slow, the Japanese equipment chain will first lose its strongest benchmark for technology premia.
VI. Disco: Advanced Packaging Pushes Cutting, Grinding, and Polishing from Cyclical Equipment to AI Process Bottleneck
Disco's target price was raised from JPY87,000 to JPY95,000, with a Buy rating and 20% upside indicated by Goldman. Disco's logic differs from Lasertec's. Lasertec is closer to inspection, while Disco is closer to advanced-packaging processing.
Goldman expects Disco's shipment momentum to recover from 2Q, benefiting from multiple advanced-packaging technology changes, including not only HBM and CoWoS, but also EMIB-T, hybrid bonding, and CPO. This point is important. The market often understands advanced packaging only as CoWoS expansion, but Disco's benefit is broader. As long as AI packaging continues to evolve toward higher density, higher bandwidth, and higher reliability, cutting, grinding, polishing, and related processing steps all become more important.
Disco's advantage is that it is not betting on only one customer or one packaging route. HBM requires more precise thinning and stacking; CoWoS requires advanced-packaging capacity expansion; hybrid bonding requires higher-precision wafer handling; CPO pushes optoelectronic packaging into more complex structures. The higher the process complexity, the easier it is for processing-equipment value in companies such as Disco to rise.
This matches the second stage of the AI hardware cycle. In the first stage, the market bought GPUs and HBM; in the second, it buys the process bottlenecks that allow AI chips to actually be delivered. Disco sits in that second stage. It does not directly sell AI chips, but it sells processing capability that cannot be bypassed in AI chip packaging and manufacturing.
Goldman is also relatively positive on Disco's earnings versus consensus. In the report table, Disco's operating-profit forecasts for later years are above Bloomberg consensus, indicating that although the market has already recognized advanced packaging, it may not yet fully reflect earnings durability. The investment point for Disco is not simply how much the target price was raised; it is whether advanced-packaging technology changes can keep shipments and margins above market models.
The risks should not be ignored. Once advanced packaging enters a period of concentrated capacity release, equipment orders may become volatile in timing. China demand, export controls, and yen appreciation will also affect the share price. More importantly, if AI packaging moves from shortage to balance, Disco's valuation will move from "bottleneck asset" back to "high-quality cyclical equipment." That would not mean the fundamentals have broken, but it would lower share-price elasticity.
VII. Ebara: Precision Machinery Is the More Visible Margin Elasticity That Can Beat Guidance
Ebara's core is not just the target-price increase; it is Goldman's view that the precision-machinery business has relatively high visibility for guidance upgrades. Within the Japanese equipment chain, Ebara is more of an "orders into margins" asset.
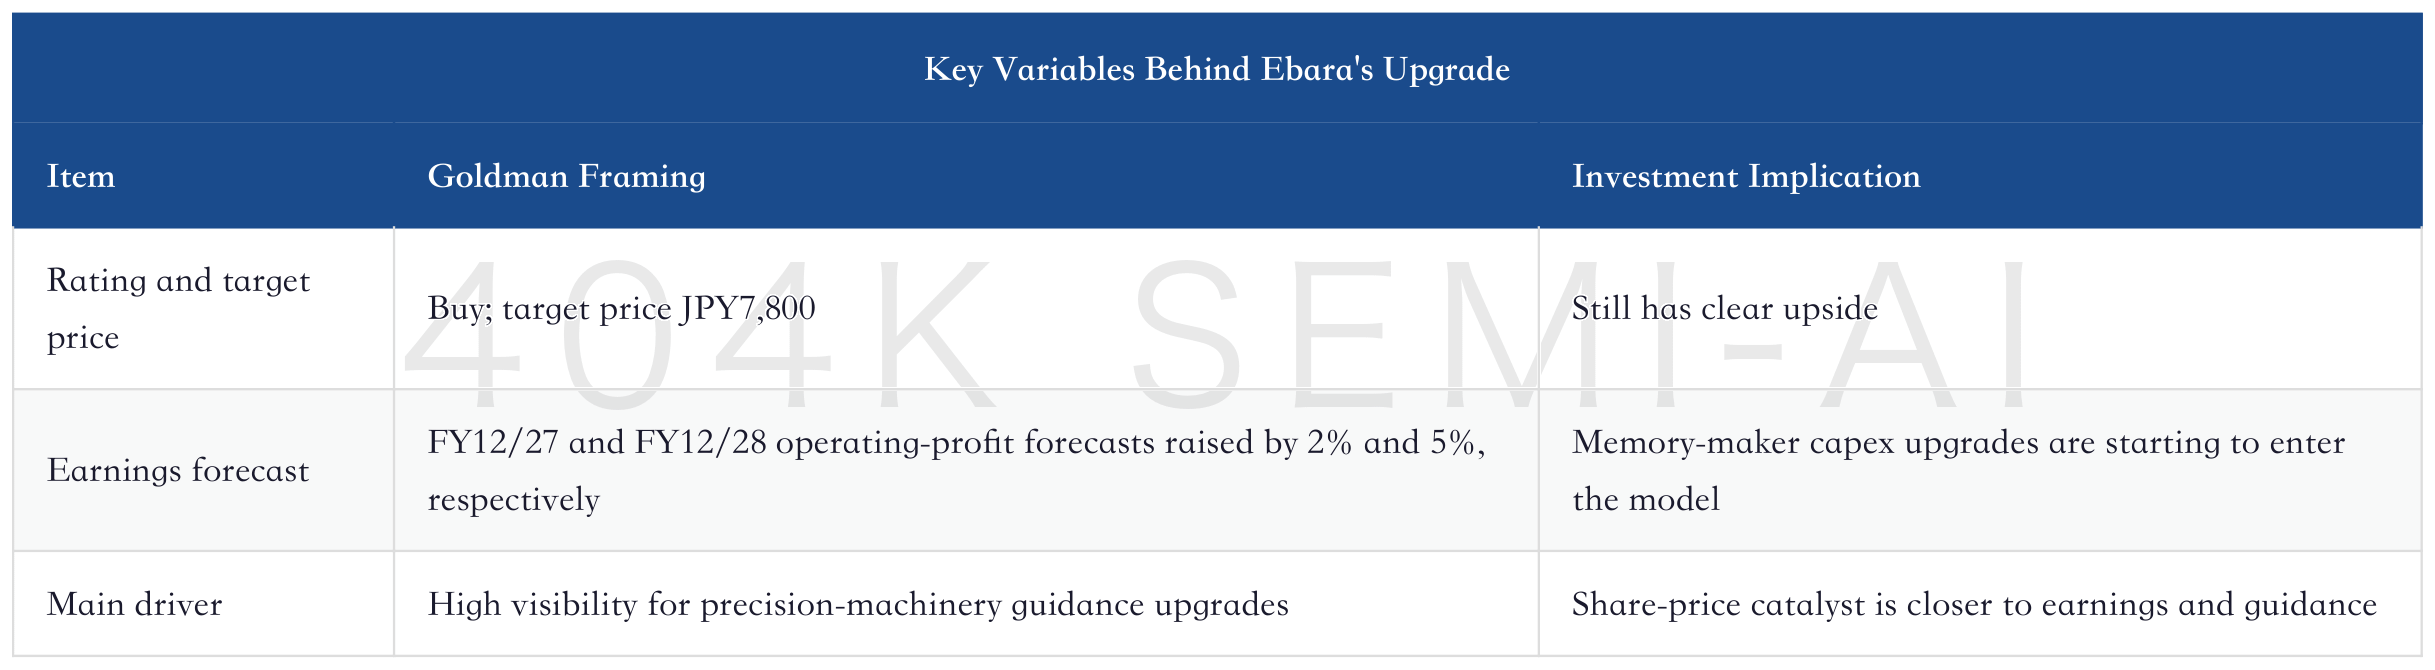
Ebara's attraction lies in its precision-machinery business. Goldman believes FY12/26 guidance has high visibility to beat expectations, mainly from precision machinery, and confirmation at the next results release could become a share-price catalyst. This logic differs from Lasertec and Disco. Lasertec and Disco are more technology-change driven; Ebara is more order-and-profit-delivery driven.
Ebara's equipment exposure is related to CMP, precision machinery, and semiconductor capex. Memory-maker expansion in DRAM/HBM and advanced-node investment will generate demand for CMP and related precision machinery. When aggregate WFE rises, Ebara naturally benefits; but what Goldman emphasizes is guidance-upgrade visibility. In other words, the market is not only buying its industry position; it is buying the possibility that company guidance has underestimated current order strength.
Ebara also has a valuation angle. Goldman's target-price method is based on the relationship between P/B and ROE, and it lowers the FY12/27E cost of equity from 4.3% to 4.0%, citing share-price increases among peers. This shows Goldman's valuation of Ebara is not simply EPS multiplied by a multiple; it also considers the support that improved profitability gives to P/B. After the equipment rally enters the earnings-delivery stage, ROE and margins matter more than revenue growth.
Ebara's risks come from three directions. First, if semiconductor capex enters a downcycle, orders will be directly pressured. Second, improving competitiveness among Chinese CMP equipment suppliers could affect share and margins. Third, slower-than-expected adoption of new technologies in semiconductor devices would reduce equipment demand. In addition, Ebara has non-semiconductor business exposure, so changes in oil prices, LNG, and petrochemical profits also affect group-level valuation.
Ebara fits in the "earnings-delivery group." It does not have Lasertec's most visible leading-edge narrative, nor does it capture the advanced-packaging concept like Disco. But if guidance is indeed upgraded and precision-machinery margins continue to improve, Ebara becomes a more practical earnings-delivery asset in the equipment chain.
VIII. Tokyo Electron: Broad Product Line and Equipment Price Hikes Make It Japan's WFE Ledger Stock
Tokyo Electron's target price was raised sharply from JPY62,000 to JPY83,000, with a Buy rating and 12% upside. On the surface, the upside is lower than Lasertec, Ebara, and Disco. But Tokyo Electron's significance is that it is more like the ledger stock for the Japanese equipment chain.
Goldman raised its Tokyo Electron FY3/27-FY3/29 operating-profit forecasts by 2%, 7%, and 8%. That is a meaningful increase. The reasons include upward revisions to memory-maker capex forecasts, the possibility that sales growth can exceed the WFE market, and margin improvement. Goldman also increased the valuation premium from +20% to +30%, citing improved profitability.
Tokyo Electron's investment logic has two layers.
The first layer is product breadth. A WFE upcycle does not happen in only one equipment segment. Advanced logic, DRAM, HBM, NAND, deposition, coater/developer, etch, cleaning, and other segments all benefit. Tokyo Electron has broad coverage and is naturally closer to the WFE ledger. If WFE continues to accelerate into CY27, Tokyo Electron will not only capture single-point orders, but the combined expansion of the entire front-end equipment chain.
The second layer is equipment price hikes and margins. Goldman notes that the market already has high expectations for the equipment price increases the company is pursuing. Whether equipment price hikes can translate into margins is the key for Tokyo Electron from here. The equipment industry has pricing power when supply and demand are tight, but price hikes are not free. Customer acceptance of price increases usually means the equipment is genuinely constraining yield, capacity, or delivery. If Tokyo Electron can continue to raise system prices and maintain delivery, its valuation premium has support.
Equipment Capex Ledger Update: AI Financing, USD250bn WFE, and Semiconductor Equipment Repricing
Tokyo Electron's risk is that it is also one of the companies most exposed to aggregate WFE volatility. If the semiconductor industry re-enters inventory adjustment, or if export restrictions tighten further, a broad product line would turn from an advantage into a risk exposure. Higher interest rates compressing valuation multiples would also affect a large-cap equipment leader such as Tokyo Electron.
Tokyo Electron is better viewed as "Japan's WFE ledger." If investors believe CY27 WFE will continue to accelerate, Tokyo Electron is the most direct integrated expression. If investors want to bet on a specific technology bottleneck, Lasertec or Disco is purer. The two types of assets can coexist, but their drivers are different.
IX. Kokusai Electric: High Probability of Guidance Upgrade, but Risk-Reward Is Already Balanced
Kokusai Electric is the most controversial part of this report. Goldman reinstated coverage with Neutral and a 12-month target price of JPY9,500. The report current price is about JPY9,980, implying 5% downside. This is not because the fundamentals are poor, but because good news has already been reflected in the share price.
Goldman's earnings forecast for Kokusai is actually strong. Company FY3/27 guidance is for operating profit of JPY54.5bn, while Goldman forecasts JPY70.1bn, well above guidance. Goldman believes the company has a meaningful probability of raising full-year guidance after 1Q results, mainly driven by DRAM demand.
The problem is that the share price has already strengthened in advance. Kokusai has risen significantly since its previous results release, and the market already has high expectations for FY3/27 upside. The biggest risk in investing is not that there is no good news, but that the good news is already in the price. Goldman's Neutral rating is essentially saying: a guidance raise may be real, but it may not necessarily create new share-price elasticity.
Kokusai's second issue is product mix. The company has high exposure to NAND, especially high-margin mini-batch deposition equipment related to NAND. Goldman notes that large memory makers are still prioritizing investment in DRAM and HBM. Although NAND capex is gradually rising, its momentum remains weaker than other applications. DRAM and logic/foundry mainly use large-batch deposition systems, while Kokusai's high-margin advantage in NAND mini-batch cannot be fully transferred to the strongest current capex direction.
This affects medium-term margins. Kokusai's medium-term plan targets adjusted OPM of 30%, but Goldman believes the hurdle is high. At Goldman's target price, the company's FY3/28 valuation implies roughly 30x P/E and about 7.1x P/B, with EV/EBITDA using the global SPE average of 18x. If margins are lower than Tokyo Electron's but valuation is close to Tokyo Electron's, it is hard to argue the stock is cheap.
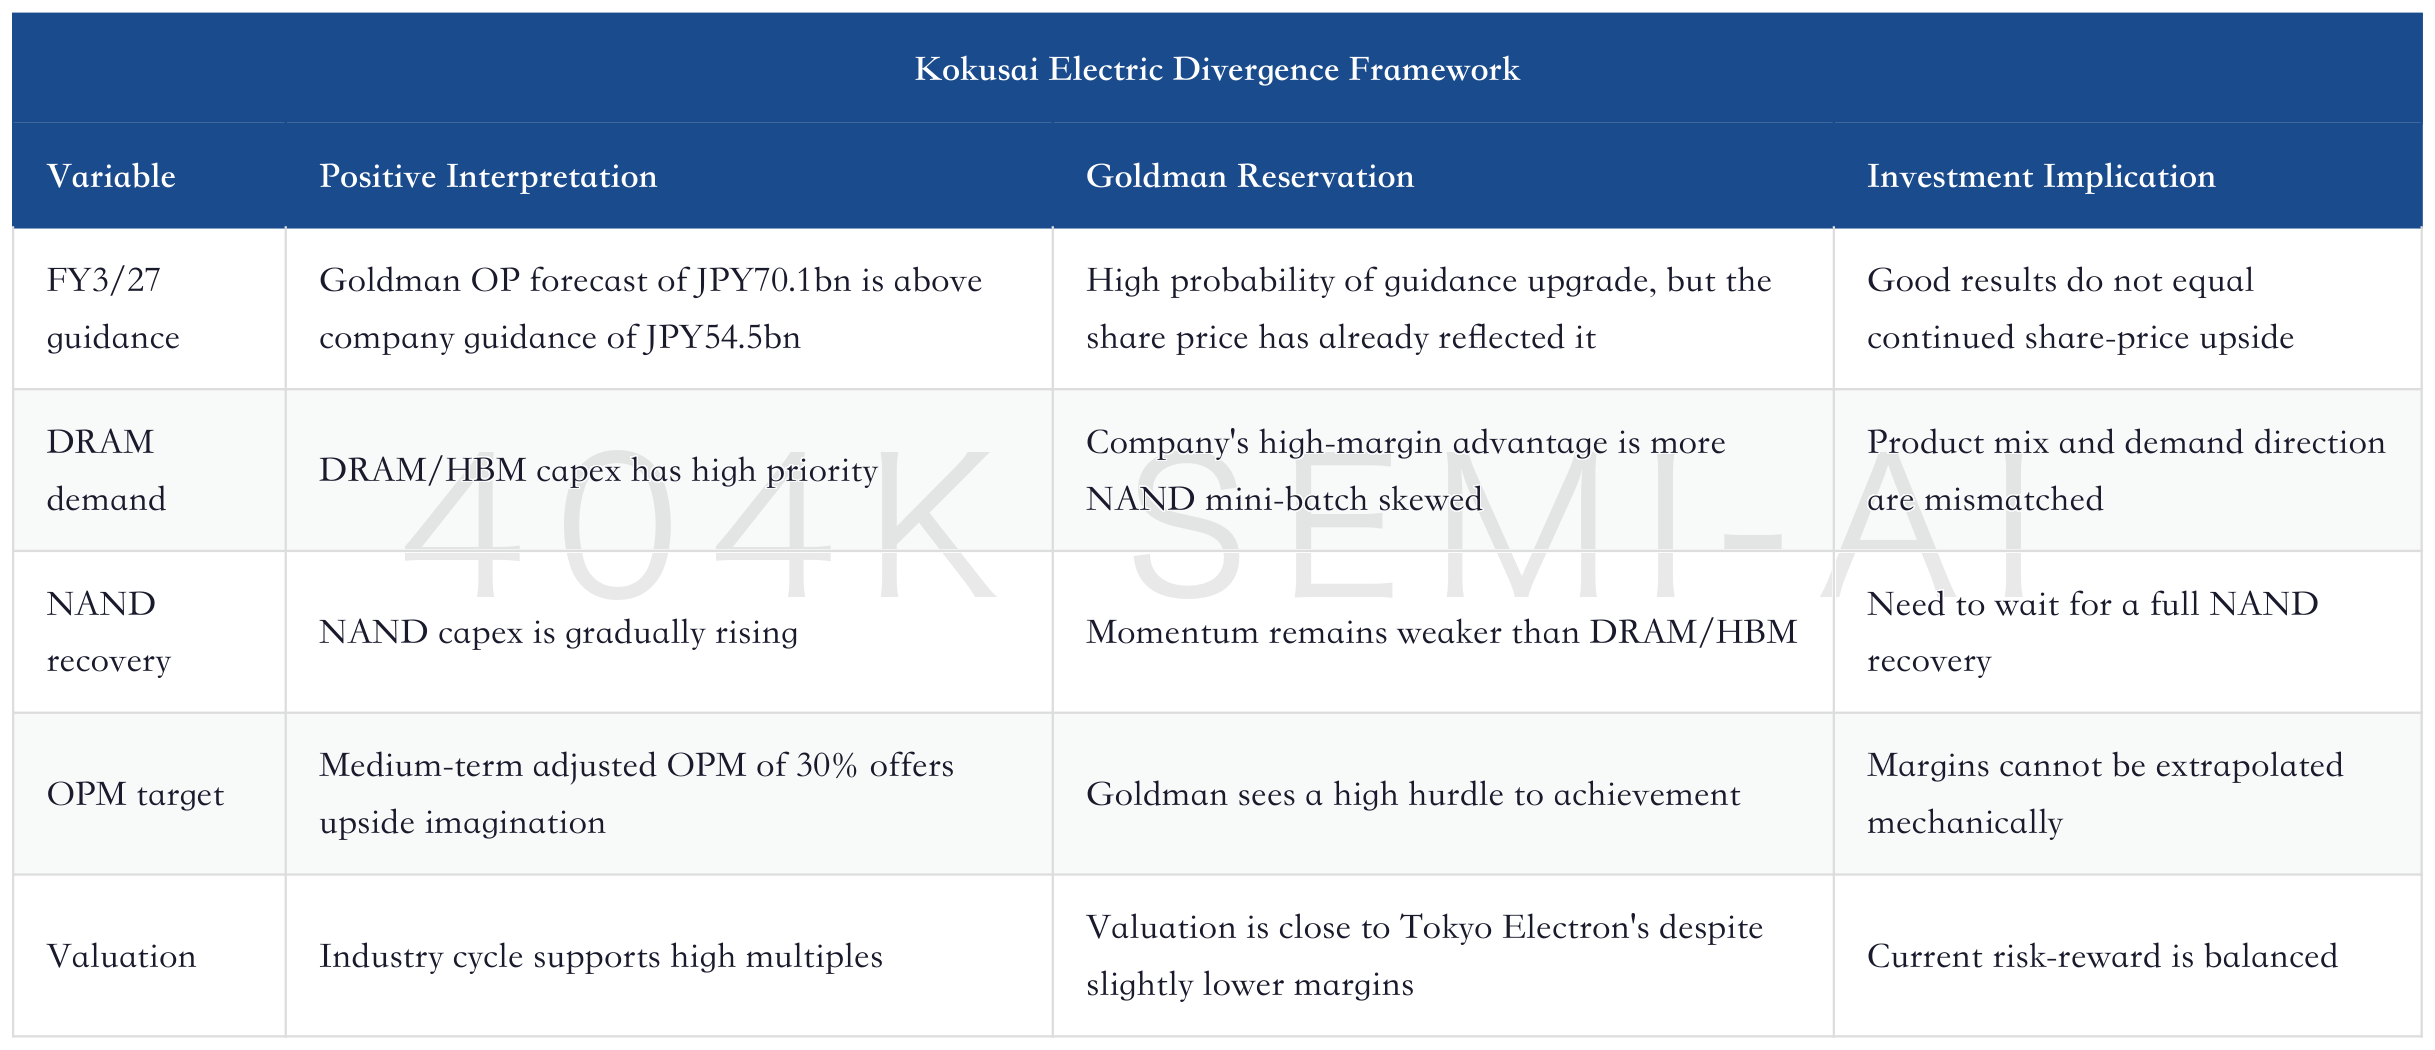
Kokusai is a typical case: industry strength, company earnings upgrades, and a rising share price can all be true at the same time, while the rating is still not Buy. The reason is that stock pricing depends on the incremental expectations gap, not the absolute quality of fundamentals. Kokusai's next leg requires a true recovery in NAND capex, or proof that DRAM/logic/foundry can also deliver sufficiently high margins. Otherwise, it looks more like an upgrade trade that has already been delivered in advance.
X. Advantest, Ulvac, and JEOL: Neutral Does Not Mean No Cycle; It Means Not Enough Expectations Gap
Advantest, Ulvac, and JEOL are all rated Neutral by Goldman. Their common trait is that fundamentals are improving, but market expectations, margins, or business mix make share-price elasticity less clear.
Advantest's target price was raised from JPY30,000 to JPY34,000. AI semiconductor test demand is strong, and the company's early capacity expansion has also led the market to revise earnings expectations up. But Goldman believes there are insufficient catalysts to drive further material upgrades. There is no new evidence that GPU/ASIC test time can continue to lengthen significantly; the CPU market is also unlikely to reach the scale of GPU/ASIC. This is important. Growth in test equipment depends not only on chip volumes, but also on test complexity and test time. If test time cannot continue to be revised up, earnings expectations can easily peak.
Ulvac's target price was raised from JPY9,400 to JPY10,300. Goldman believes orders will continue to expand as the business environment improves, but lead times are lengthening due to the recent high level of activity, potentially limiting the speed of FY6/27 margin improvement. Ulvac's problem is not the absence of orders, but whether orders can be recognized in time and flow smoothly into margins.
JEOL's target price was raised from JPY6,800 to JPY7,700. Spot-beam mask writers have order and sales expansion opportunities due to increased production of optical devices and DFB lasers. But Goldman still believes that without a full recovery in demand for multi-beam mask writers and scientific metrology instruments, it will be hard for the company to achieve earnings growth above market consensus. JEOL has valuable technology points, but they are not yet enough to move the whole company into a high-elasticity stage.
Neutral companies are the easiest to misread. Neutral does not mean bearish; it means there is not a sufficiently large mismatch between the share price and fundamentals. For investors, Neutral companies can serve as validation indicators: if Advantest test time is revised up again, Ulvac lead-time pressure eases, and JEOL multi-beam mask writers recover, they can move from the Neutral group back into the offensive group. But based on current evidence, Goldman does not assign them sufficient risk-reward.
XI. SCREEN and Tokyo Seimitsu: Also Benefiting from WFE, but Profit and Order Quality Are Not Enough
Goldman still rates SCREEN HD and Tokyo Seimitsu Sell, even though their target prices were also raised. This shows industry strength does not automatically protect all equipment stocks.
Tokyo Seimitsu's target price was raised from JPY14,000 to JPY15,000, but the rating remains Sell, with 21% downside implied by the report current price. Goldman's concerns focus on two points. First, HBM probers have high dependence on specific customers, and near-term order momentum may be weak. Second, logic probers face intensifying competition from OSATs. In other words, the company operates in markets with cycle exposure, but order quality and the competitive environment are not stable enough.
SCREEN's target price was raised from JPY9,500 to JPY12,500, but the rating remains Sell, with 25% downside implied by the report current price. Goldman acknowledges that FY3/27 guidance may have upside in 2H, but believes the company will struggle to generate earnings above market expectations. Reasons include a declining sales mix from emerging Chinese customers, accelerated fixed-cost investment for future growth, and difficulty improving margins.
These two cases matter for the entire equipment chain. When WFE is rising, the market tends to buy all equipment segments higher. But share prices ultimately depend on order quality, customer mix, and margins. If orders come from low-margin customers, customer concentration is high, competition intensifies, or fixed costs rise, revenue growth may not become shareholder returns.
This is also why Goldman emphasizes OPM improvement. Equipment stocks are not software stocks; revenue growth comes with production, lead times, inventory, labor, service, and fixed costs. If a company invests in fixed costs ahead of future growth, near-term margins may be pressured. If the customer mix shifts from high-margin emerging customers to a lower-margin mix, revenue growth quality will also deteriorate.
SCREEN and Tokyo Seimitsu are not a negation of the WFE supercycle; they are the counterexample to "everything goes up." A strong industry can support revenue, but it cannot guarantee every company will beat earnings expectations.
XII. Ranking the 10 Companies: Buy Technology Bottlenecks, Buy Earnings Delivery, Avoid Fully Priced Expectations
Putting the 10 companies together, the Japanese equipment chain can be divided into four groups.
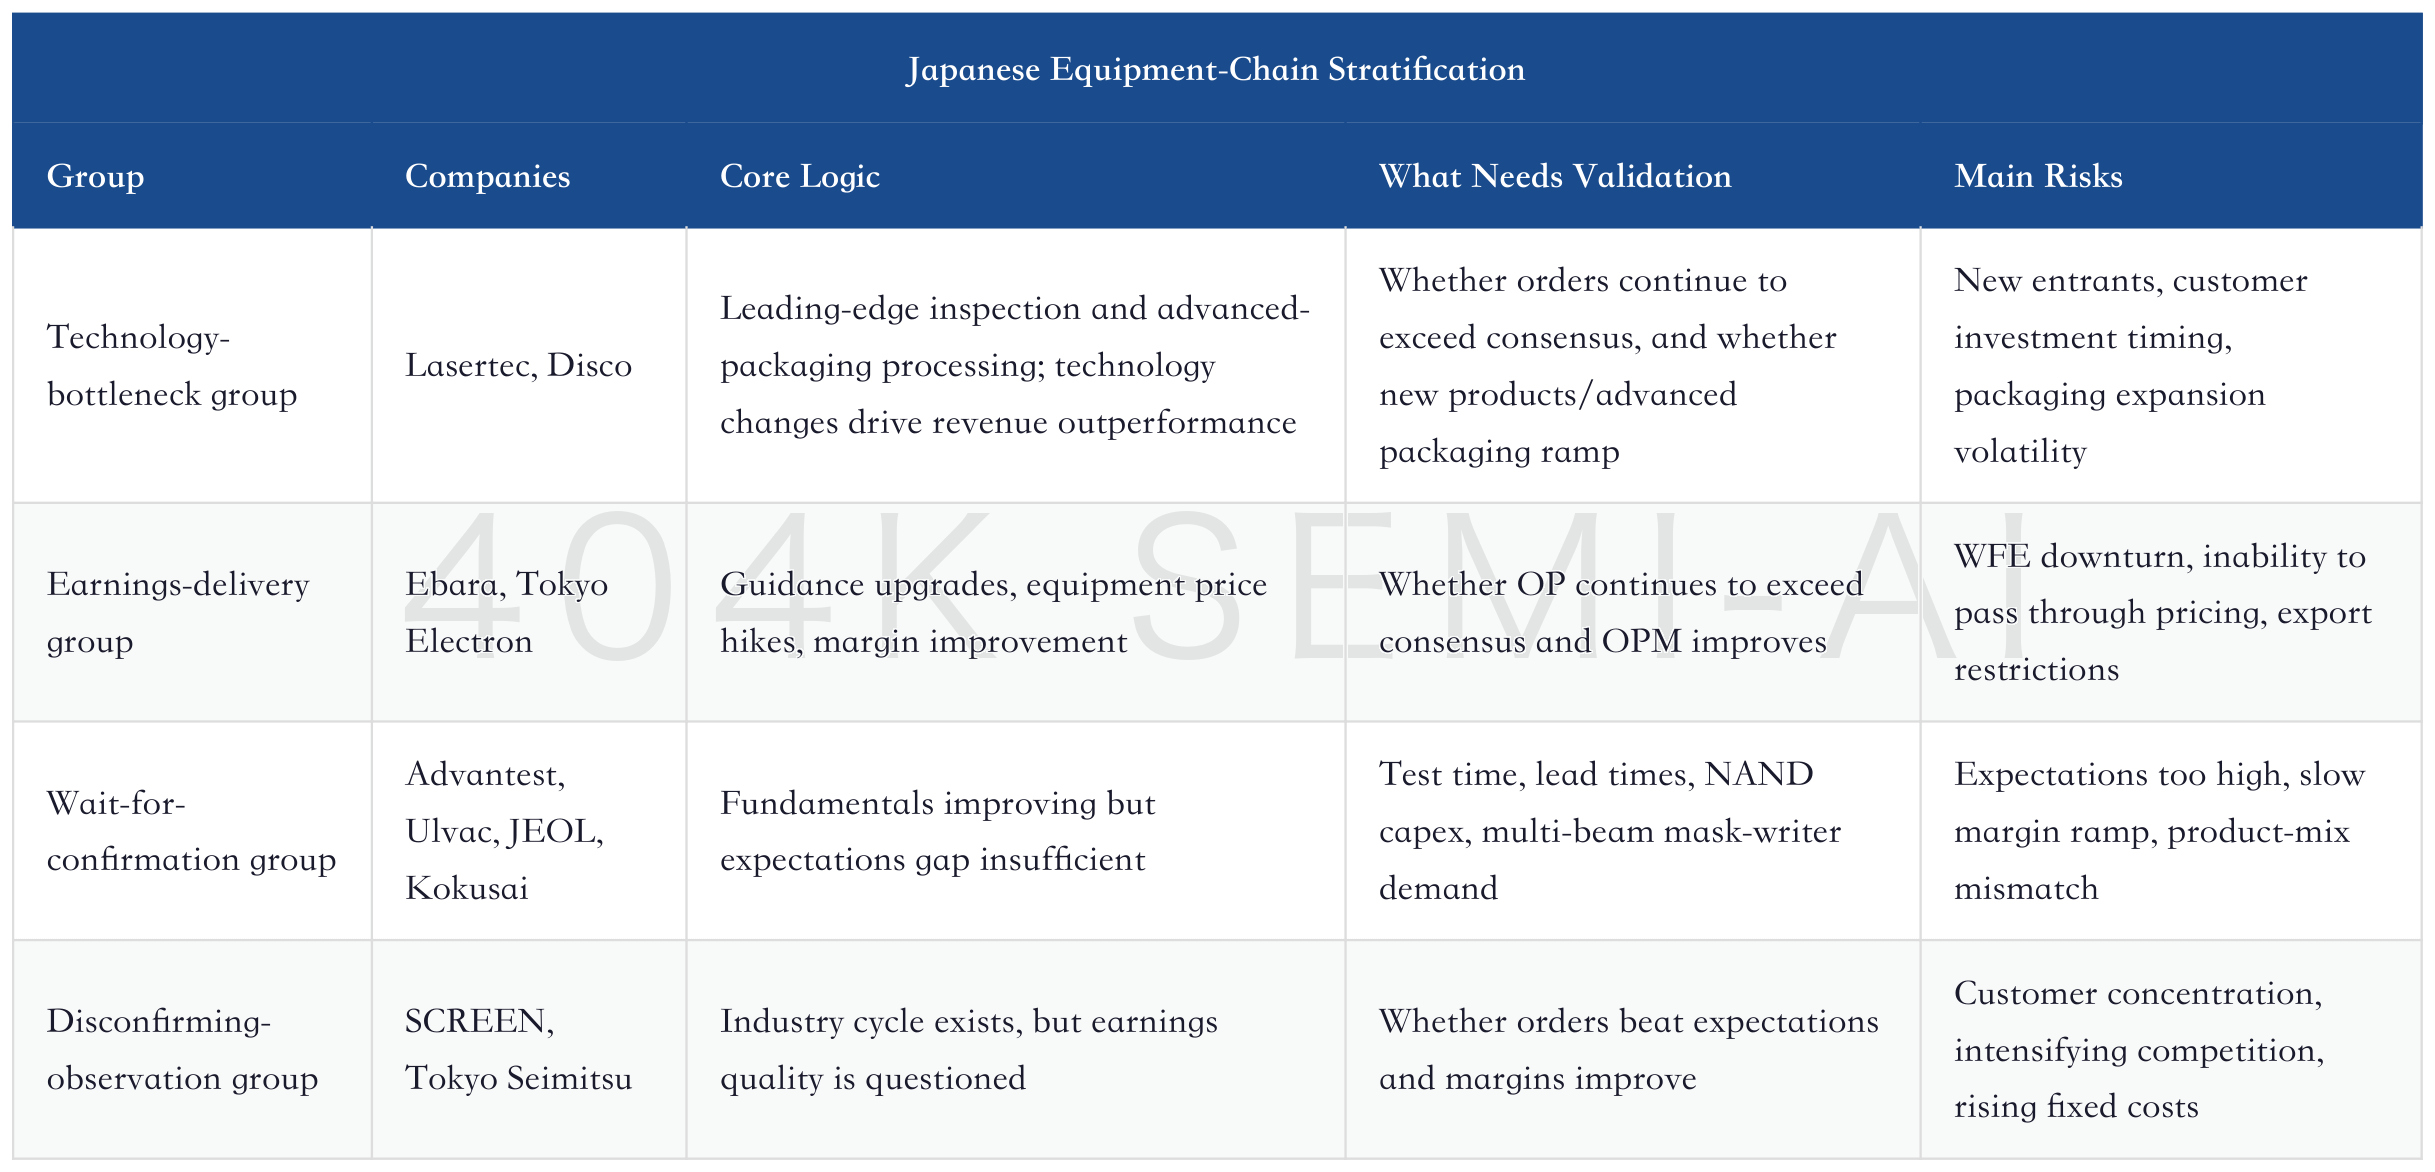
This ranking is more useful than looking only at ratings. Ratings tell you Goldman's current risk-reward view; the groups tell you which metrics to watch. For Lasertec and Disco, watch whether technology bottlenecks continue to expand; for Ebara and Tokyo Electron, watch earnings delivery; for Advantest and Kokusai, watch whether the expectations gap reopens; for SCREEN and Tokyo Seimitsu, watch whether the counterevidence can be fixed.
From HBM to WFE: How AI Turns the Memory Cycle into an Equipment Supercycle, and How Much Further Semiconductor Equipment Can Rise
The advantage of the Japanese equipment chain is that it controls multiple physical links between AI hardware design and delivery. Inspection, dicing, polishing, deposition, CMP, coater/developer, cleaning, testing, and metrology cannot be copied overnight. AI servers make chips larger, packaging more complex, memory bandwidth higher, and yield requirements stricter, lifting equipment value.
But an advantage does not mean every company benefits equally. The closer a company is to new technology bottlenecks, the easier it is to earn a valuation premium; the closer it is to mature competitive segments, the more it must rely on costs, share, and customer mix to deliver profits. Goldman's report is effectively breaking "the Japanese equipment chain benefits from AI" into "which Japanese equipment companies can still beat expectations."
XIII. The AI WFE Transmission Chain: From Memory-Maker Capex to Japanese Equipment Profits
The starting point of this Japanese equipment rally is that AI semiconductor demand has led memory makers and foundries to revise capex higher again. Upward revisions to capex expectations at memory makers such as Samsung and Micron Technology are an important reason Goldman raised earnings forecasts. Why are memory makers expanding? Because HBM, DDR5, enterprise SSDs, advanced packaging, and AI server system memory jointly drive demand.
