
目录
TL;DR
I. What the May Data Add Is a Clear Ranking of Relative Strength
II. Capacitors Accounted for Nearly Half of Shipments, Leaving Industry Growth Highly Concentrated
III. MLCC Materials Remain at Decade-High Levels, but Elevated Levels Alone Do Not Prove Pricing Power
IV. Connectors Are Recovering, but the Data Does Not Yet Prove a Shortage in AI Connectors
V. Asia Is Stronger Year on Year, but Every Region Declined Month on Month
VI. The Market Has Already Priced “Modest Shipment Growth” as a “Surge in Long-Term Earnings”
VII. From Monthly Shipments to the Income Statement, Four Gates Remain
VIII. Over the Next 3 Months, Six Data Sets Will Determine Whether This Update Remains Valid
Conclusion: The Industry Direction Remains Upward, but Trading Has Become More Difficult Than Interpreting the Data
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
May did not mark a broad-based recovery: capacitors remained on an uptrend, connectors were merely recovering, and the real debate has shifted to whether longer-term earnings can justify elevated valuations.
TL;DR
Industry demand did not weaken overall, but yen-denominated figures materially amplified the apparent strength. In May 2026, global shipments by 60 Japanese electronic-component companies totaled ¥353.3bn, up 15% YoY and down 6% MoM; in US-dollar terms, shipments were US$2.233bn, up 5% YoY and likewise down 6% MoM. The roughly 10-percentage-point gap between yen- and dollar-denominated YoY growth indicates that currency translation made a non-negligible contribution. The more prudent conclusion is that the industry is experiencing moderate growth, rather than 15% YoY demand growth.
Capacitors are the only category large enough to define the industry’s core trend. Capacitor shipments totaled ¥158.8bn, up 21% YoY and down 5% MoM; in US-dollar terms, shipments were US$1.004bn, up 11% YoY. Capacitors represented approximately 45% of total industry shipments and approximately 73% of passive-component shipments. Resistor growth was high but came from a small base; in US-dollar terms, inductor shipments fell 3% YoY and high-frequency component shipments fell 15%. Industry strength is highly concentrated and should not be characterized as a simultaneous recovery across all components.
Connectors continued their moderate recovery but have not yet entered an acceleration phase. Connector shipments totaled ¥58.7bn, up 15% YoY and down 8% MoM; in US-dollar terms, shipments rose 5% YoY and fell 7% MoM. The return to positive YoY growth confirms that the recovery from depressed levels remains intact, while the weaker MoM performance relative to the overall industry indicates a modest trajectory. These data support a “recovery” thesis, but do not yet support an “inflection” or “supply shortage” thesis.
Upstream MLCC materials are “cooling from elevated levels.” May production of dielectric ceramic electrode materials used in capacitors fell 10% YoY and 13% MoM, but absolute output remained near the high end of the past 10 years. This confirms that production intensity remains high, while also cautioning that orders, inventory builds, and output are not continuously accelerating. The next questions are whether elevated production can stabilize and whether high-end specifications can translate full utilization into pricing and profits.
Regional data did not identify a new, one-way growth engine. China and the rest of Asia grew 19% and 20% YoY, respectively, in yen terms, but only 9% and 10% in US-dollar terms; the US and Europe declined 1% and 5% YoY, respectively, in US-dollar terms. Every region declined MoM, and JPMorgan also believes that regional trend lines are broadly flat. Asia is stronger, but not yet strong enough to demonstrate that global demand is accelerating again.
Stocks are already pricing in the 2027–2028 earnings environment. JPMorgan continues to rank Murata Manufacturing as its top pick in electronic components and sees substantial upside to its price targets for Murata Manufacturing, Taiyo Yuden, TDK, ROHM, Ibiden, and others; however, Murata Manufacturing, Taiyo Yuden, and Ibiden trade at FY26E P/E multiples of 36.23x, 49.61x, and 50.24x, respectively. These price targets require rapid EPS growth over the next 2 years. The data direction may be correct, yet share prices could still come under pressure if earnings materialize too slowly.
I. What the May Data Add Is a Clear Ranking of Relative Strength
This JPMorgan report uses global shipment data from 60 Japanese electronic-component companies compiled by the Japan Electronics and Information Technology Industries Association (JEITA). Although the data are reported with a two-month lag, they offer one clear advantage: they span companies, products, and regions, making them useful for assessing the common direction of Japan’s electronic-component supply chain. Total May shipments increased YoY but declined MoM. The first-order conclusion is that the industry has not reversed course; the second-order conclusion is that growth is uneven.
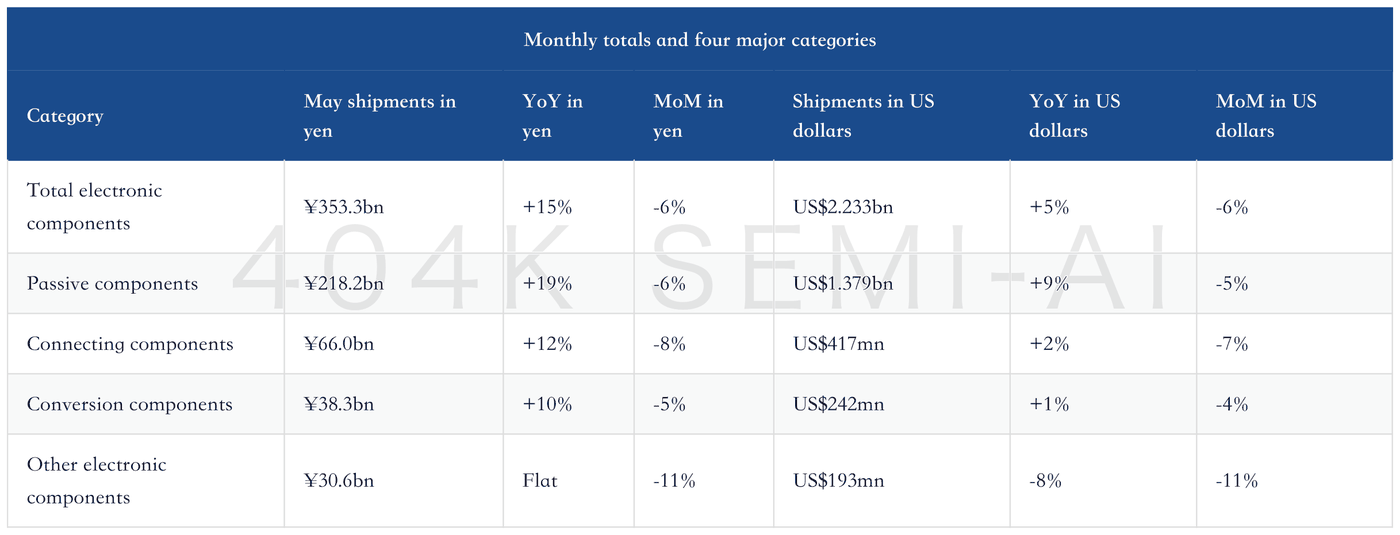
All major categories declined MoM, broadly in line with or slightly below their seasonal averages. The most likely misinterpretation is to treat the MoM decline as direct evidence of deteriorating demand. May includes Japan’s Golden Week holidays, and shipments normally retreat from April’s elevated levels even in typical years; if the YoY trend remains positive and the three-month trend line has not turned downward, a single month of negative MoM growth provides limited disconfirming evidence.
Another potential misreading is to focus only on YoY growth in yen. Total industry shipments grew 15% YoY in yen but only 5% in US dollars; passive components grew 19% and 9%, respectively, while connectors grew 15% and 5%, respectively. The almost uniform 10-percentage-point gap indicates that yen-denominated figures include a meaningful currency-translation benefit. For corporate financial statements, yen depreciation can increase the translated value of overseas revenue; for assessing underlying demand, US-dollar figures provide a more conservative gauge. Taken together, the two measures suggest that May reflected approximately 5% global demand growth plus currency effects, rather than a 15% surge in physical demand.
JEITA data are also subject to retrospective revisions: the latest YoY figures may not be fully reproducible from historical absolute values, so JPMorgan explicitly notes that priority should be given to the YoY figures published each month, which already incorporate retrospective revisions. This is not merely a methodological issue. Simply dividing old absolute values from the database may produce conclusions that differ from the officially reported YoY figures. For investment analysis, the trend matters more than decimal-level precision, and official YoY figures are more reliable than independently spliced historical values.
II. Capacitors Accounted for Nearly Half of Shipments, Leaving Industry Growth Highly Concentrated
May capacitor shipments totaled ¥158.8bn, representing approximately 45% of total electronic-component shipments and approximately 73% of passive-component shipments. Shipments grew 21% YoY in yen terms and 11% YoY in US-dollar terms, while declining 5% MoM in both currencies. Capacitors combine the largest absolute scale, double-digit US-dollar growth, and a relatively modest MoM decline, directly explaining why the report identifies them as the industry’s sustained growth driver.
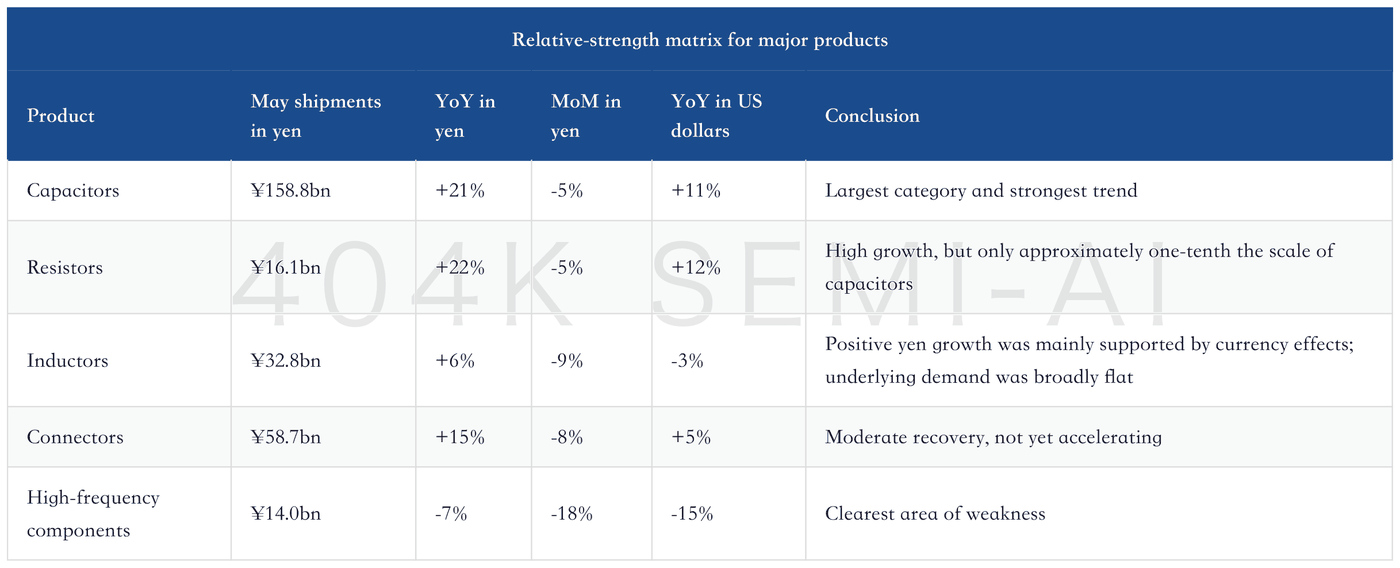
This table separates the “electronic-component recovery” into 3 distinct worlds. The 1st consists of capacitors and resistors, which are still delivering double-digit growth in US-dollar terms; the 2nd consists of connectors, which have emerged from depressed levels but are following a moderate growth trajectory; the 3rd consists of inductors and high-frequency components, where US-dollar-denominated shipments are declining YoY and have not yet caught up.
Resistor shipments grew 22% YoY, apparently faster than capacitors, but their absolute scale was only ¥16.1bn and therefore insufficient to change the industry total. Positive YoY growth for inductors in yen terms alongside negative growth in US-dollar terms illustrates precisely how currency effects can create “nominal growth.” High-frequency components fell 7% YoY in yen terms, 15% YoY in US-dollar terms, and another 18% MoM, providing the clearest counterevidence: if the consumer-electronics, communications, and RF supply chains had already recovered broadly, high-frequency components should not continue to lag.
