
Japan Electronic Components In-Depth Update: AI Orders Shift to Profit Conversion as Ibiden Expands Capacity, MLCC Pricing Evolves, and Power Semiconductors Recover
目录
TL;DR
I. What This Preview Adds
II. Profit Forecasts Are Strong, but Companies Are Not Moving in Sync
III. Ibiden: The Strongest Demand, the Highest Execution Threshold
IV. MLCCs: Product Mix at Murata, Yield at Taiyo Yuden
V. Renesas Electronics and Rohm: The Semiconductor Recovery Must Pass Through Capacity and Integration
VI. Do Not Overlook Verification Signals from the Second Tier
VII. Valuations Correspond to a Set of Conditions Yet to Be Met
VIII. Post-Earnings Market Reactions Should Be Separated into Three Layers
Conclusion: The Next Stage Is a Competition in Profit Conversion
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The central test this earnings season is whether orders can pass through capacity, yield, pricing, and costs to ultimately become sustainable profits.
TL;DR
The industry thesis is moving from “demand confirmation” to “profit conversion.” Goldman Sachs forecasts aggregate FY3/27 operating profit of ¥2.7031 trillion for the companies under its coverage, up 36% year on year and 9% above Bloomberg consensus; it forecasts ¥3.3604 trillion for FY3/28, up 24% year on year and 13% above consensus. Apr–Jun results are unlikely to disappoint materially. What will truly determine share-price direction is whether management teams can provide evidence on orders, capacity, and pricing that supports earnings in 2H 2026, FY3/28, and beyond.
Ibiden still offers the steepest profit trajectory—and faces the highest verification threshold. Utilization of the new Ono production line, mass production of Rubin substrates, and demand for CPUs and switch chips could lift FY3/27 operating profit to ¥102.5 billion. However, the market still needs to establish whether the company will expand capacity beyond its committed ¥500 billion capex program and whether its FY3/31 operating-profit target of ¥300 billion has room for an upgrade.
For MLCCs, the key question is who can convert tighter supply-demand conditions into high margins; there is still no evidence of broad-based price increases. Murata and Taiyo Yuden must both address book-to-bill ratios, lead times, long-term agreements extending through 2027, and AI data-center sales growth. Non-Japanese suppliers have already initiated price increases, but neither company had previously planned to raise prices. Product mix, yield, and utilization are therefore more important this cycle, and investors should not assume a broad-based round of price increases.
The recovery in analog and power semiconductors is beginning to flow through to earnings. Renesas Electronics must demonstrate that bottlenecks in test equipment, foundry supply, and internal capacity can be removed on schedule. Rohm must demonstrate improving pricing for analog and power products, narrowing SiC losses, and whether transaction costs and goodwill amortization will dilute the benefits from integrating Toshiba-related operations.
Valuations already require companies to provide forward evidence. Based on share prices as of July 23, 2026, Goldman Sachs’ price targets imply upside of 74%, 48%, 41%, 34%, and 29% for Taiyo Yuden, Murata, Ibiden, Rohm, and Renesas Electronics, respectively. These figures should be viewed as a verification checklist rather than a margin of safety: any failure in order quality, yield, capacity ramp-up, or pricing power could cause forward valuations to decline before near-term earnings do.
I. What This Preview Adds
The previous preview of Japan’s electronic-components earnings season established that AI servers are moving multilayer ceramic capacitors (MLCCs), ABF package substrates, HDD heads, and high-end connectors into a period of profit expansion. That discussion focused on whether Apr–Jun profits could exceed companies’ initial guidance. This Goldman Sachs report dated July 24, 2026 takes the analysis one step further: strong near-term earnings are gradually becoming consensus; the new point of contention is whether these earnings can persist beyond 2027.
Japan Electronic Components In-Depth Update: Apr–Jun Earnings Preview—How Long Can Strong MLCC and ABF Profits Last?
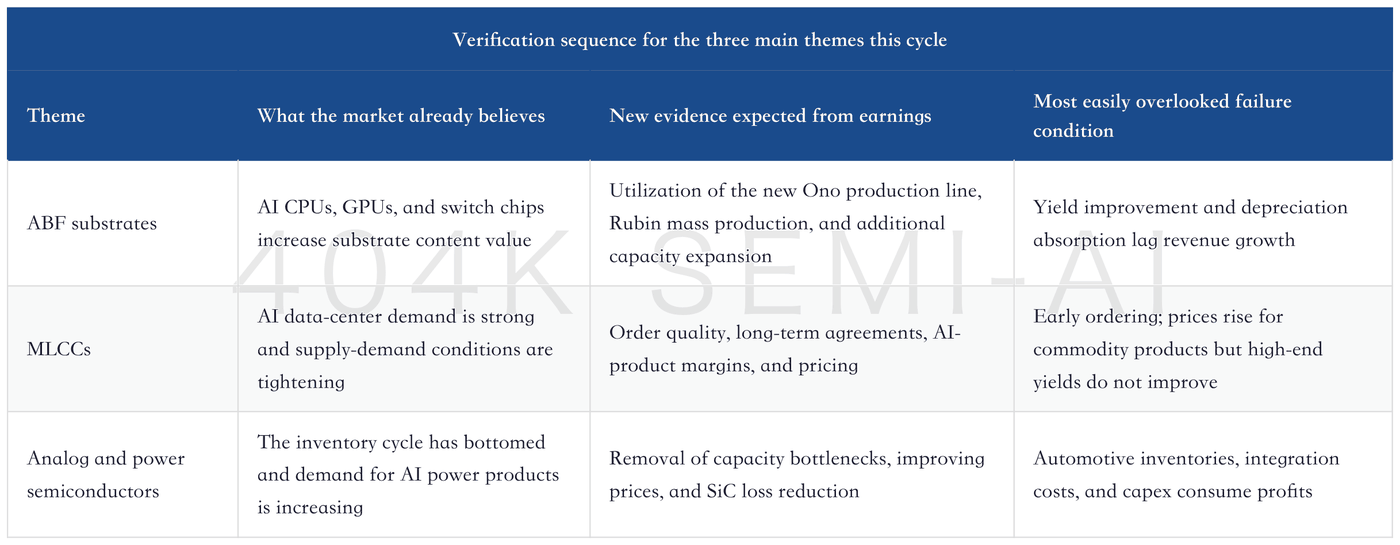
Goldman Sachs concentrates the incremental signals across three value chains. The first is ABF substrates, where the focus is capacity utilization and additional capex. The second is MLCCs, where the focus is order quality, long-term agreements, and pricing. The third is analog and power semiconductors, where the focus is the removal of production bottlenecks, improving prices, and business integration. All three point to the same question: AI demand is already visible, but how much profit companies retain depends on internal execution.
This also explains why investors cannot focus solely on “earnings beats” this cycle. If customers are placing orders early to secure capacity, shipments will be strong but may subsequently decline. If revenue growth comes from lower-margin products, higher utilization may not generate an equivalent increase in profit. If price increases merely offset precious-metals, energy, or outsourcing costs, margins will not expand materially. Conversely, if book-to-bill ratios remain above 1, lead times lengthen while cancellation rates remain stable, the share of high-end products rises, yields improve, and new capacity ramps as planned, profits may extend beyond the near-term cycle into a longer earnings upcycle.
II. Profit Forecasts Are Strong, but Companies Are Not Moving in Sync
Goldman Sachs forecasts aggregate FY3/27 operating profit of ¥2.7031 trillion for the companies under its coverage, up 36% year on year and 9% above Bloomberg consensus; it expects this to rise further to ¥3.3604 trillion in FY3/28, up 24% year on year and 13% above consensus. This indicates that sell-side models no longer treat the industry’s recovery as a one-quarter rebound, but are incorporating a longer AI data-center cycle, tightening supply-demand conditions, and improving product mix.
However, once the aggregate is disaggregated, profit sensitivity differs significantly. Murata’s advantage lies in its scale and mix in high-end MLCCs; Taiyo Yuden’s lies in its cyclical operating leverage; Ibiden’s lies in the content value of AI package substrates; Renesas Electronics’ key variable is the removal of capacity bottlenecks; and Rohm is exposed to both an industry recovery and business restructuring.
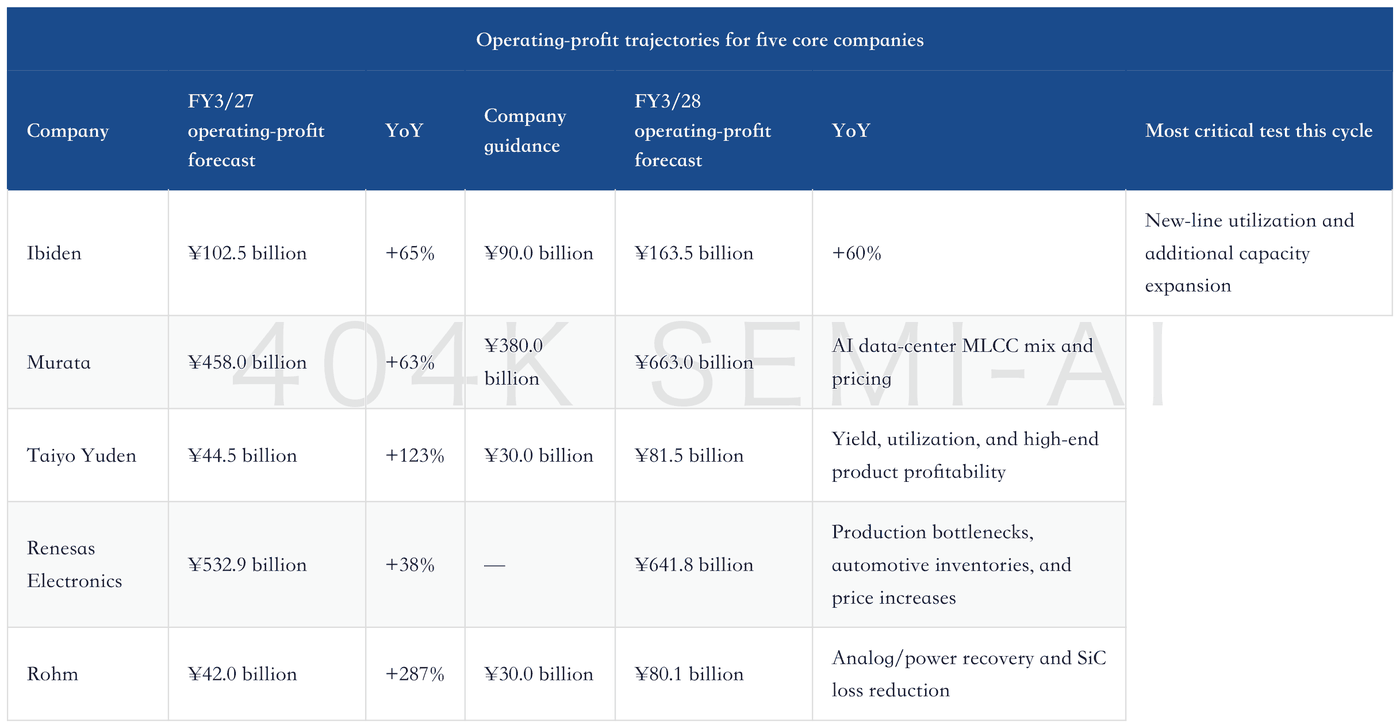
Renesas Electronics has a December fiscal year, so the figures in the table correspond to FY12/26 and FY12/27. Goldman Sachs uses non-GAAP operating profit, while Bloomberg consensus is primarily based on GAAP figures; percentage differences therefore cannot be used directly to assess an “earnings beat.” Such differences in accounting definitions are particularly important: some of the apparently substantial gap between models may reflect definitions rather than changes in operations.
The quarterly cadence is also worth monitoring. Goldman Sachs forecasts Ibiden operating profit of ¥20.7 billion for Apr–Jun, followed by sequential increases to ¥24.3 billion, ¥26.8 billion, and ¥30.7 billion. For Murata, it forecasts ¥99.5 billion, ¥117.5 billion, ¥126.0 billion, and ¥115.0 billion; for Taiyo Yuden, ¥6.6 billion, ¥12.4 billion, ¥13.4 billion, and ¥12.1 billion. The market is pricing in continued profit growth during Jul–Dec, not merely a strong Apr–Jun result. If a company delivers one strong quarter but cannot explain its subsequent order and capacity outlook, the share-price reaction may be weaker than the headline earnings suggest.
