
Japan Electronic Components Deep Update: April-June Earnings Preview, and How Long Can Strong MLCC and ABF Profits Last?
目录
Too Long; Didn’t Read
1. April-June Earnings Preview: Strong Profits Are No Longer the Debate; the Debate Is Where They Come From
II. MLCC: From a “Price-Hike Cycle” to “Product-Power Pricing”
III. ABF Substrates: Ibiden’s Earnings Are Strong; Its Valuation Is Stronger
IV. TDK: Multiple Profit Engines Are More Stable Than a Pure MLCC Story
V. Connectors, Spark Plugs, and Photonic Devices: Not All High Profits Come From AI Servers
VI. Raw Materials and FX: Two Headwinds Behind Strong Profits
VII. Valuation Discipline: A Big Rally Does Not Mean the Thesis Is Wrong, but Earnings Must Still Take Over
VIII. Company Ranking: From “AI Purity” to “Quality of Earnings Delivery”
IX. Four Sets of Validation Metrics for the April-June Earnings Season
X. Investment View: Strong Profit Is Not the Conclusion, but the Filter
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The core issue for Japan’s April-June electronic components earnings season is not whether profits are high, but whether AI data-center demand has truly flowed through to operating profit in MLCCs, ABF substrates, HDD heads, and connectors, and whether that profit can endure through raw materials, depreciation, and yen volatility. This determines whether the market is buying a short-cycle upturn or a reassessment of product competitiveness.
Too Long; Didn’t Read
Strong profits are already showing up in the numbers. Morgan Stanley MUFG expects aggregate April-June operating profit for its 19 covered companies to reach JPY319.2bn, up 33.6% YoY. FY26 operating profit is forecast at JPY1.5419tn, up 31.1% YoY; the real test is whether these profits can withstand depreciation, materials, and FX volatility.
AI data-center-driven profit divergence is increasingly becoming a test of product strength. MLCCs, ABF package substrates, HDD heads, connectors, and high-end passive components all benefit, but the real sustained differentiation will come from small-form-factor high-capacitance MLCCs, Rubin-platform ABF substrates, and high-reliability connectors. Not every “electronic component” will benefit in sync.
Murata remains the cleanest profit-slope story in this theme. The report forecasts Murata FY26 operating profit at JPY431.9bn, above company guidance of JPY380.0bn; April-June operating profit is expected at JPY90.4bn, above FactSet consensus of JPY85.6bn, driven by AI data-center MLCCs, mix improvement, and rising capacity utilization.
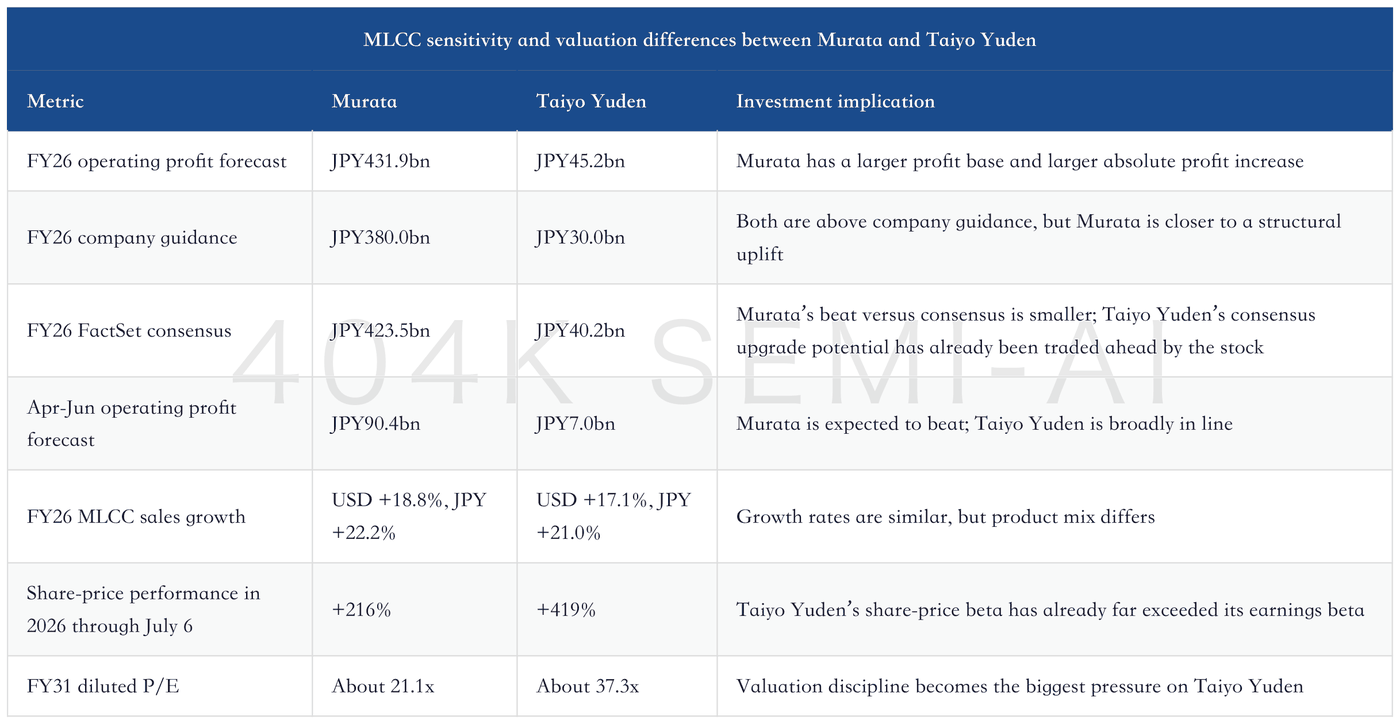
Taiyo Yuden’s issue is not the absence of recovery, but that the share price has already run too far. The report forecasts Taiyo Yuden FY26 operating profit at JPY45.2bn, above company guidance of JPY30.0bn, but the stock was already up 419% in 2026 as of July 6, and FY31 diluted P/E remains around 37.3x, materially above Murata’s 21.1x.
Ibiden’s value lies in expectations. The report expects Rubin-platform ABF substrate ASPs to be roughly 2x Blackwell levels, leaving room for near-term earnings upside. But even if the company reaches its FY31 operating profit target of JPY300.0bn, the implied P/E is still around 24x; the market therefore needs to see ABF ASPs, yields, and depreciation all come through together.
The tracking points should come down to four data sets. Going forward, the focus should be Murata AI/DC MLCC sales and utilization, Ibiden ABF ASPs and depreciation, TDK HDD heads and passive-component profits, and the ability of connector and aluminum electrolytic capacitor makers to pass through metal prices. If all four data sets strengthen together, the sector enters a structural re-rating; if only pricing and FX contribute, the trade will revert to an earnings-season game.
1. April-June Earnings Preview: Strong Profits Are No Longer the Debate; the Debate Is Where They Come From
The first signal from this April-June earnings preview is straightforward: profit growth in Japan’s electronic components industry has not stopped at cyclical repair. Morgan Stanley MUFG expects aggregate April-June operating profit for its 19 covered companies to reach JPY319.2bn, up 33.6% from JPY238.9bn in the same period of 2025 and up 8.3% from JPY294.8bn in January-March 2026. In an electronic components industry that typically peaks in July-September, declines in October-December, and weakens further in January-March, continued sequential growth in April-June itself shows that the demand structure has already been reshaped by AI data centers.
The annual slope is more important. The report pushes covered-company operating profit to a new cycle high in FY26, above FactSet consensus. After consecutive declines, industry profit has returned to growth. The point now is not a low-base rebound, but AI data centers and high-value-added components starting to drive profit back above the previous cyclical peak.
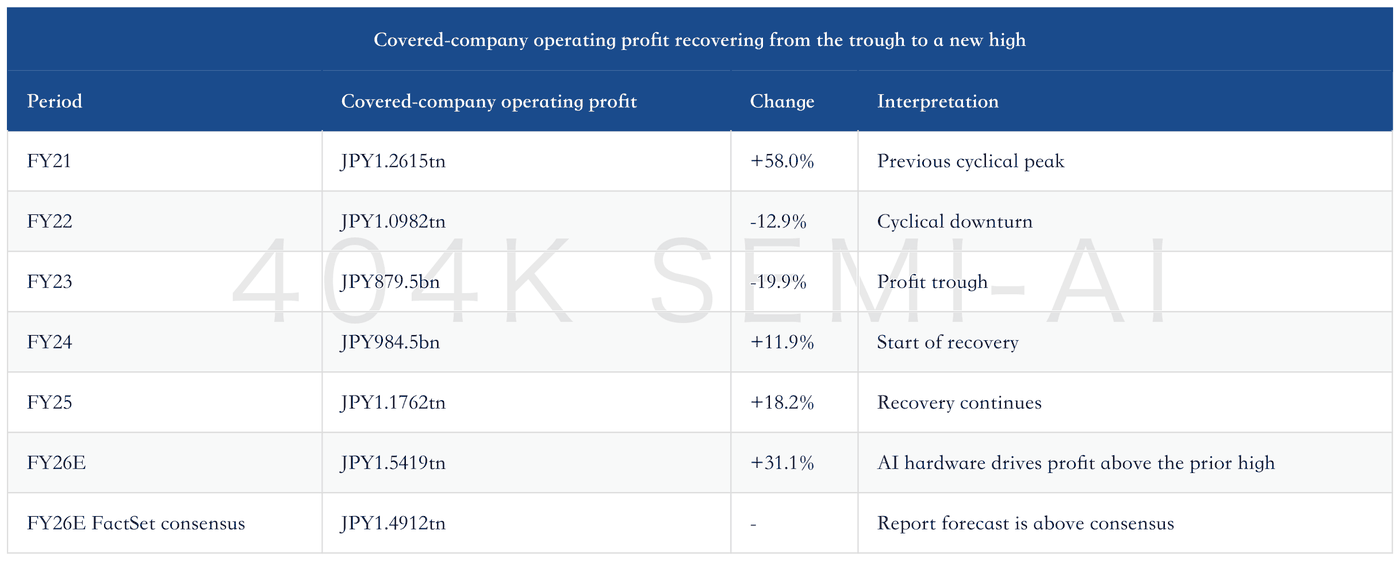
This is also the real meaning of whether “strong earnings can continue.” A 33.6% YoY increase is not hard to explain: low base effects, the yen, cost absorption, and fading one-off expenses can all contribute to the number. The harder task is distinguishing which profits come from high-value-added products driven by AI servers and data centers, which come from one-off factors that may reverse, which come from pricing and FX, and which merely reflect raw material costs not yet fully passing through. The most valuable part of earnings season is not companies reporting operating profit above expectations, but whether management can clearly explain orders, pricing, capacity, yield, and depreciation.
The most important change in this report is that Morgan Stanley MUFG divides Japanese electronic components into three asset categories. The first category comprises clear beneficiaries of high-value-added products, such as Murata Manufacturing, TDK, Hirose Electric, NGK Spark Plug, and Alps Alpine. The second comprises companies where earnings are genuinely improving but valuation or the delivery path still needs validation, such as Meiko Electronics, MinebeaMitsumi, Kyocera, Nichicon, Nihon Dempa Kogyo, Hamamatsu Photonics, and KOA. The third comprises companies whose near-term earnings look solid, but where there is a gap between share prices and earnings delivery, such as Taiyo Yuden, Ibiden, Nippon Chemi-Con, and Daishinku.
Morgan Stanley MUFG covered-company ratings, target prices, and April-June earnings signals
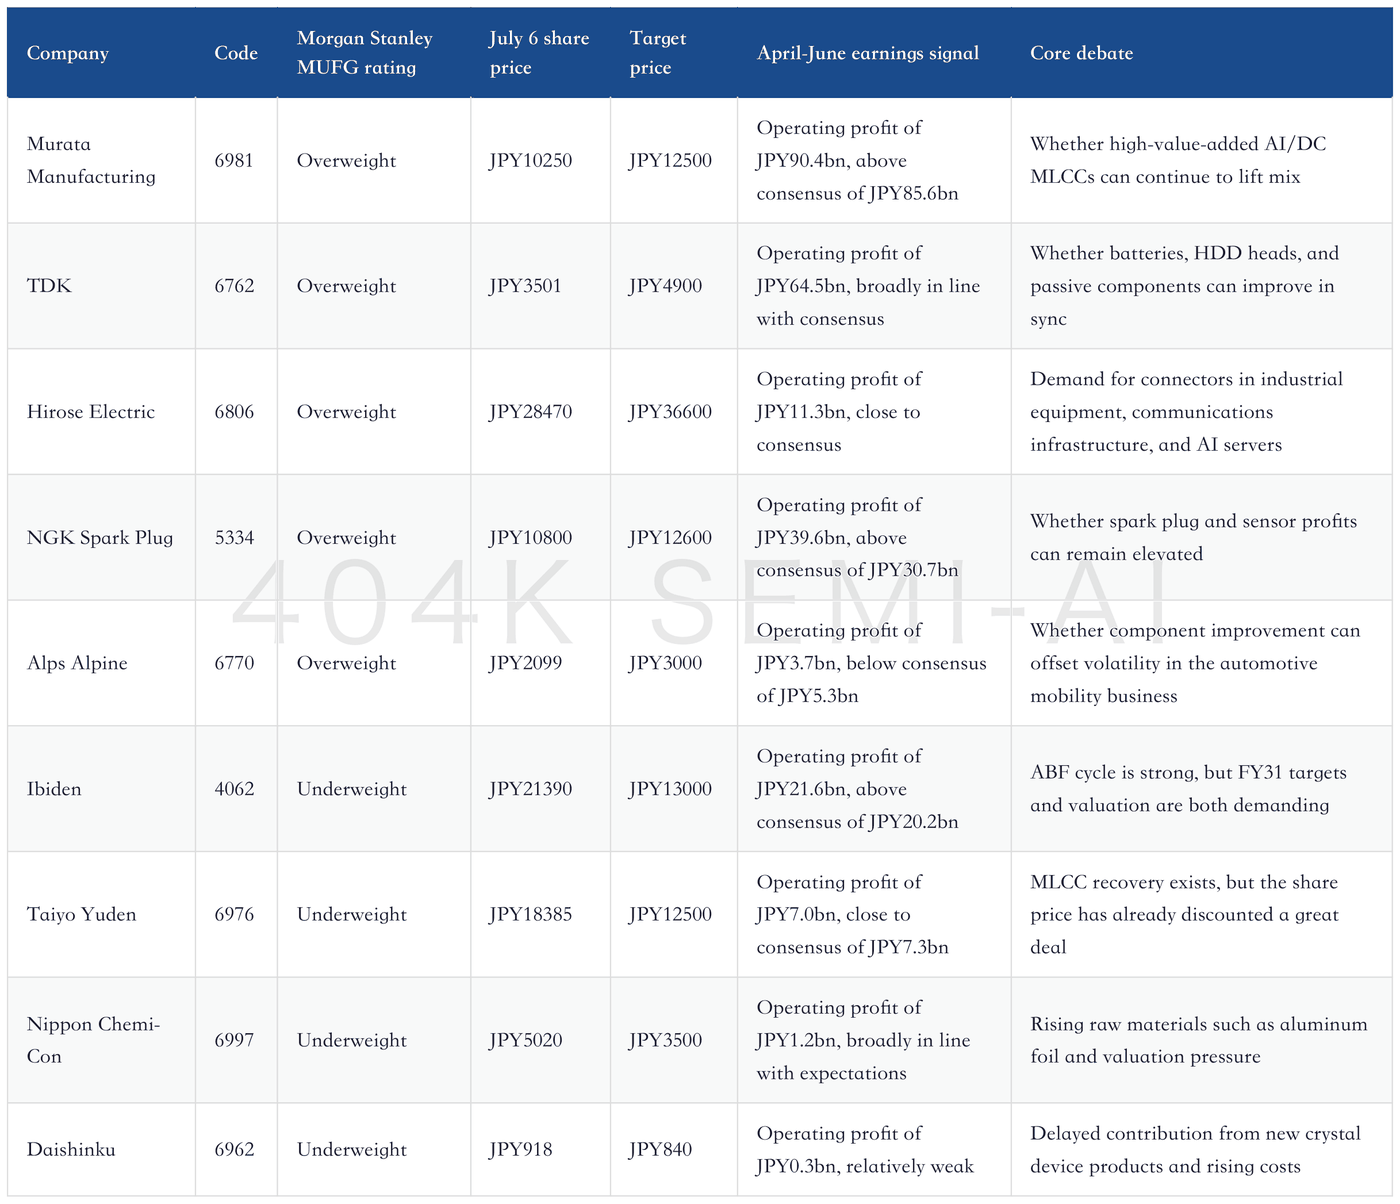
This segmentation matters more than simply looking at April-June operating profit. Once the industry enters an AI hardware re-rating phase, share prices no longer move only with “this-quarter beats,” but with “who can retain AI hardware value in their own income statement over the next three years.” Murata and Taiyo Yuden both sell MLCCs, but their valuation logic differs. Ibiden and Meiko Electronics both sit in the AI packaging/PCB materials chain, but the market has already discounted Ibiden’s future profits very aggressively. TDK also has MLCCs, but the report places greater weight on the multi-engine profit contribution from HDD heads and rechargeable batteries.
Japan Electronic Components Deep Dive: AI Servers Push MLCCs, HDD Heads, and ABF Substrates Toward a 2027 Supply Anchor
The prior Japan electronic components framework had already broken AI servers into three supply anchors: MLCCs, HDD heads, and ABF substrates. The incremental point in this April-June earnings preview is that these supply anchors are now entering the earnings-verification window: Murata needs to validate the product mix of AI/DC MLCCs, TDK needs to validate the profit contribution from HDD heads and passive components, and Ibiden needs to validate Rubin-platform ABF substrate pricing and depreciation absorption.
II. MLCC: From a “Price-Hike Cycle” to “Product-Power Pricing”
MLCC is the core thread of this report. Murata Manufacturing and Taiyo Yuden both benefit from AI data centers and rising MLCC utilization, but the report’s relative conclusion is entirely different: Murata remains the top pick, while Taiyo Yuden stays Underweight. The difference is not demand direction, but product mix, technical barriers, and the extent to which future profits are already reflected in the share price.
The reason is not that Taiyo Yuden lacks growth, but that its growth quality and valuation position are different. The report notes that in FY26, MLCC accounts for 51% of Murata’s sales and 71% of Taiyo Yuden’s sales. Taiyo Yuden has higher cycle beta to MLCC, and its share price is more easily driven by “price hikes” and “tight supply-demand.” But Murata is stronger in technology and cost advantages for small, high-capacitance, high-value-added MLCCs. What AI servers and data centers really lift is the value content of high-end products, not the average price of all general-purpose MLCCs.
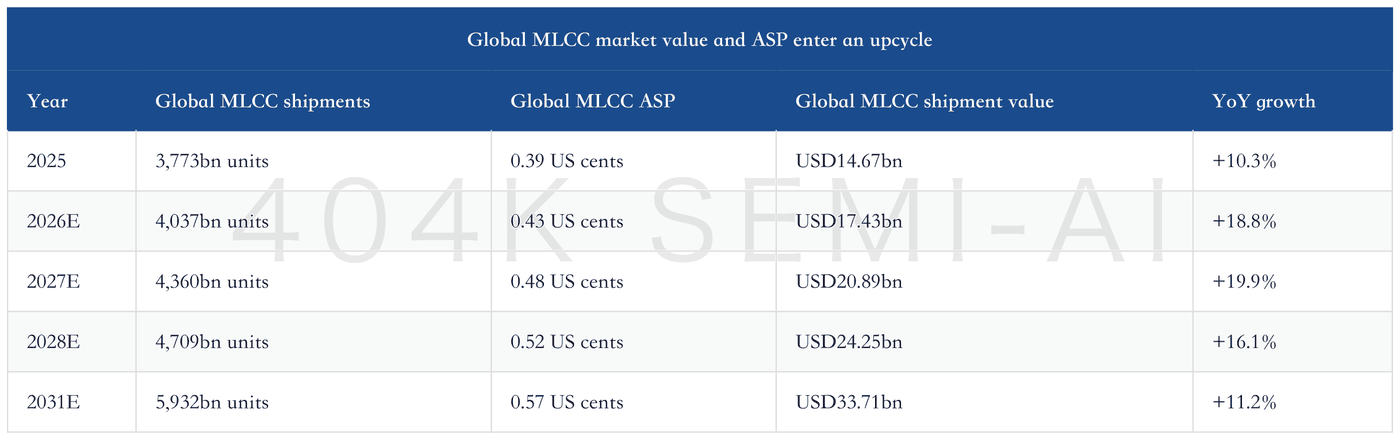
The MLCC market itself is also undergoing a structural shift. The report expects global MLCC shipment value to rise from USD14.67bn in 2025 to USD24.25bn in 2028, implying a three-year CAGR of about 18.2%; it further reaches USD33.71bn in 2031. The key here is not unit shipments, but ASP and product mix. Global MLCC unit shipments are expected to be 3,773bn units in 2025 and 4,709bn units in 2028; but ASP rises from 0.39 US cents in 2025 to 0.52 US cents in 2028. In other words, the industry is not growing on “more cheap capacitors,” but on “more expensive, harder-to-make capacitors.”
Global MLCC share explains why AI server-driven MLCC revaluation lands first on Murata. AI servers are seeing rapid demand growth for small, high-capacitance products such as 1608-size 100μF, 1005-size 47μF, and 0603-size 10μF MLCCs. The report believes Murata appears to be the only vendor able to stably mass-produce these specifications at scale while maintaining yield. The constraint for high-end MLCCs is not ordinary capacity, but the combined capability across materials, layering, sintering, yield, size, and cost.
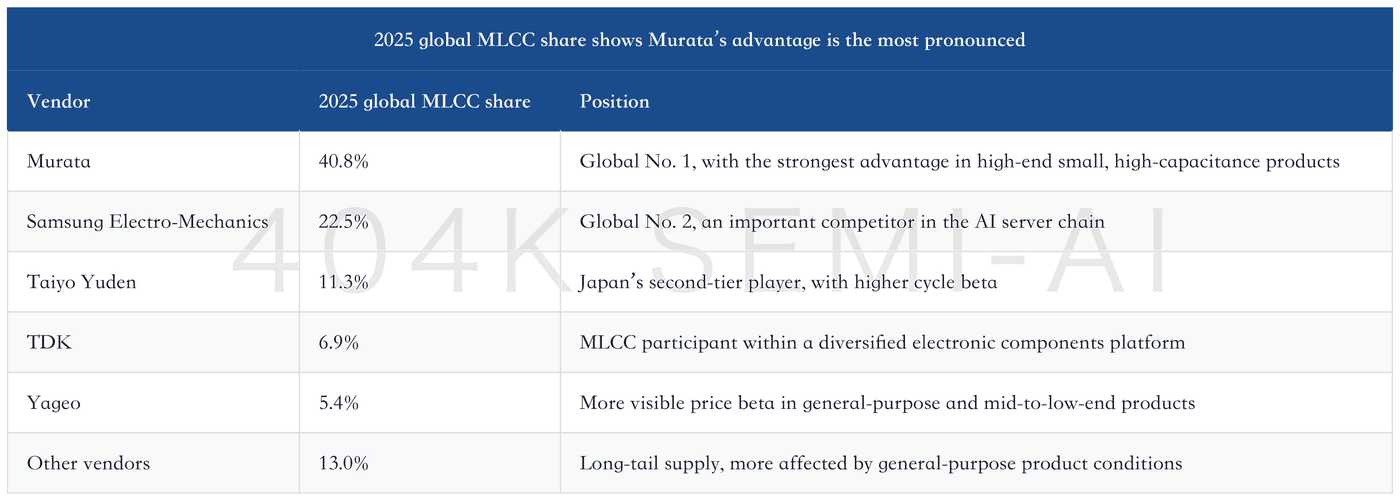
Therefore, the MLCC rally cannot be simply understood as “shortages driving price hikes.” General-purpose MLCCs will of course be affected by supply-demand conditions, and distributors may also push customers to place orders earlier and accept price increases. But if price increases mainly come from general-purpose products, that may actually lower entry barriers over the long term, giving manufacturers in China, South Korea, and Taiwan more profit and R&D; cash flow. What truly enhances corporate value is ASP and gross-margin improvement from AI/DC high-value-added products, and companies that can expand share in high-capacitance, small-size products with stable yields.
This is also why the report is cautious on Taiyo Yuden. Taiyo Yuden’s core MLCC business will still grow, and utilization is expected to rise from slightly below 85% in 4Q to about 90% in 1Q, with operating profit increasing from JPY3.5bn in 4Q to JPY7.0bn in Apr-Jun. But this kind of improvement looks more like cyclical recovery plus fixed-cost absorption, rather than a clear widening of product barriers. If the market buys Taiyo Yuden at a higher multiple than Murata, Taiyo Yuden needs to prove it can also achieve a profit slope close to Murata’s in AI/DC high-value-added MLCCs. At least this report does not provide such evidence.
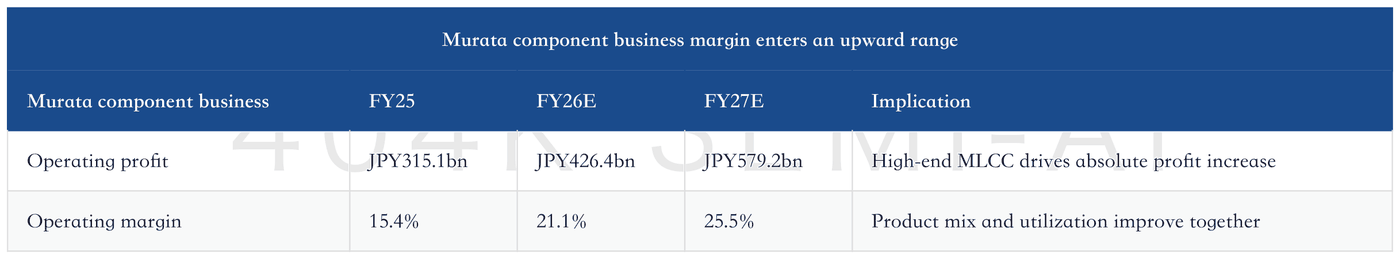
Murata’s profit curve is shifting from “cyclical product recovery” to “capturing AI hardware value content.” Component business profit and margin are rising at the same time, showing that the market is not buying simple price hikes, but AI server power integrity and high-end passive component supply capability.
III. ABF Substrates: Ibiden’s Earnings Are Strong; Its Valuation Is Stronger
ABF substrates are the report’s second major strong thread. Ibiden’s Apr-Jun earnings may surprise positively, driven by factors including electronics business sales growth and a QoQ decline in depreciation. The controversy is that although the FY26 forecast is above company guidance, it is below FactSet consensus, indicating that the market has already priced more distant Rubin and Rubin Ultra profits into the stock.
But the market’s real expectation for Ibiden is not Apr-Jun, but the Rubin platform. The report expects Nvidia’s flagship product transition from Blackwell to Rubin to drive sales growth in high-value-added ABF package substrates, with Rubin-platform ABF substrate unit price at roughly 2x Blackwell. By FY27, as Rubin Ultra advances, ABF substrate ASP is expected to continue rising. Against the backdrop of increased T-Glass and CCL procurement and higher output at the Ono plant, the report expects Ibiden’s FY27 ABF substrate sales to grow +31% YoY, increasing by JPY100.8bn.
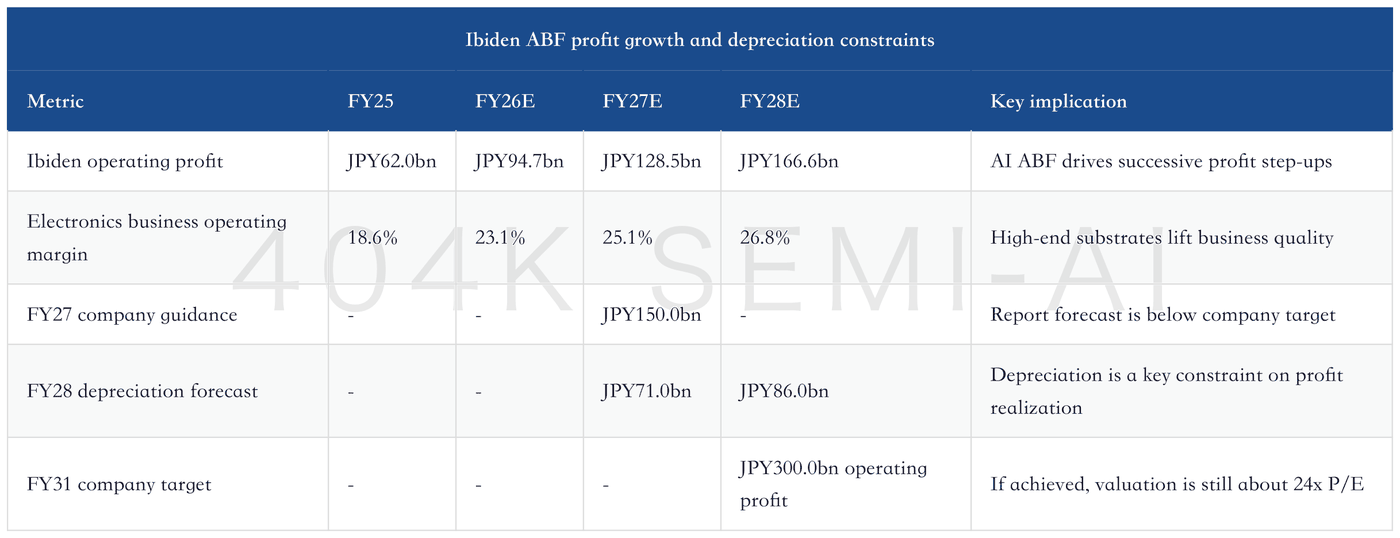
These numbers show that Ibiden’s business trend is very strong, but the share price has already discounted that strength in advance. The report rates Ibiden Underweight with a target price of JPY13,000, while the July 6 share price was JPY21,390, implying about 39% downside to the target price. This is not a bearish view on ABF fundamentals, but a view that the market has over-discounted Ibiden’s FY31 operating profit target of JPY300.0bn. Even if the company achieves that target, the implied P/E would still be about 24x, which is not cheap under high depreciation, high capex, customer platform transitions, and material supply constraints.
The easiest mistake in ABF investing is to directly equate “Rubin value-content uplift” with “valuation upgrades for all suppliers.” The Rubin platform may indeed make package substrate unit prices materially higher than Blackwell, but this chain also faces three constraints: first, whether high-end T-Glass/CCL is sufficient; second, whether capacity ramp and yield proceed smoothly; third, whether depreciation and capex will absorb part of the price beta. Ibiden’s short-term operating profit can look good because depreciation declines QoQ, but medium- to long-term profit must withstand the test of rising depreciation from new capacity.
From a cross-sectional perspective, Ibiden looks more like a combination of “high-certainty orders + high valuation expectations.” The difference between Ibiden and Murata is that Murata’s growth is driven by a large number of product mix, customer mix, and technical-specification factors, making single-platform transition risk relatively diversified; Ibiden’s profit slope is highly tied to Nvidia GPU platform timing, ABF unit price, and new-plant depreciation. The more the market believes in Rubin, the more it needs to check whether Ibiden can keep the unit-price advantage in operating profit, rather than see it diluted by depreciation, materials, and yield.
IV. TDK: Multiple Profit Engines Are More Stable Than a Pure MLCC Story
TDK is an easily underestimated name in this report. Market discussion of Japanese electronic components often focuses on Murata, Taiyo Yuden, and Ibiden, but TDK’s profit sources are more diversified: rechargeable batteries, HDD heads, passive components, and sensors together drive FY26 profit growth. The report forecasts TDK FY26 operating profit at JPY335.8bn, above company guidance of JPY295.0bn and FactSet consensus of JPY307.7bn; it further rises to JPY369.1bn in FY27 and JPY414.7bn in FY28.
For April-June, the report forecasts TDK operating profit of JPY64.5bn, almost in line with FactSet consensus of JPY64.6bn, but up JPY22.8bn quarter on quarter. Key reasons include the absence of the JPY9.8bn restructuring expense booked in 4Q, and clear growth from the recovery in HDD head sales to Seagate and Western Digital. In other words, TDK’s April-June quarter is not necessarily an “earnings beat” story, but rather a story of more balanced profit recovery quality.
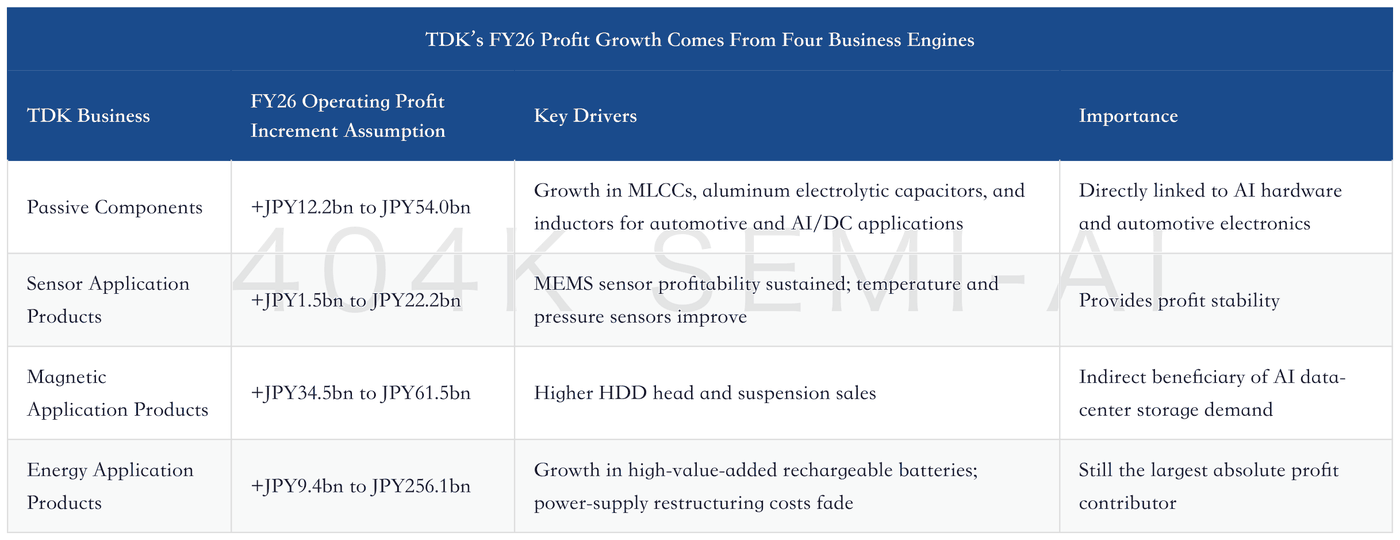
The investment implication for TDK is not that it is “purer than Murata,” but that it is more diversified than a single MLCC cycle. If AI data centers continue to drive nearline HDD storage demand, TDK’s head and suspension businesses will gain incremental growth outside the normal cycle. If AI server power supplies and high-reliability passive component usage rise, TDK’s passive components business will benefit. If consumer-electronics battery demand remains stable and the mix improves, the energy application business provides a profit base. This combination may not deliver the strongest single-quarter elasticity, but it can reduce the impact of single-category price volatility on earnings.
TDK’s risk is that part of the profit recovery comes from fading expenses and resumed HDD head production, which is not fully equivalent to a long-term structural upgrade. After FY26, the market will focus on two questions: whether HDD heads are merely benefiting from inventory replenishment and shipment recovery, or from sustained AI data-center nearline storage capex expansion; and whether the passive components business can enjoy mix improvement like Murata, rather than relying only on a recovery in general-purpose MLCC and inductor demand. If both materialize, TDK’s valuation should look more like a diversified AI hardware component platform. If not, it will still be viewed as a collection of cyclical businesses.
V. Connectors, Spark Plugs, and Photonic Devices: Not All High Profits Come From AI Servers
Another easily overlooked detail in this report is that Morgan Stanley MUFG maintains Overweight not only on Murata and TDK, but also on Hirose Electric, NGK Spark Plug, and Alps Alpine. The logic here is not entirely the same.
Hirose Electric’s April-June operating profit is forecast at JPY11.3bn, close to FactSet consensus of JPY11.5bn; FY26 operating profit is forecast at JPY47.3bn, slightly below consensus of JPY49.8bn. The report still rates it Overweight because connector demand from industrial equipment, communications infrastructure, and AI servers supports sales growth, while the company is expected over the long term to improve ROE through shareholder returns and strategic investment. Hirose Electric’s AI exposure is not as concentrated as Murata’s, but it is close to a combination of “high-reliability connectors + industrial/communications infrastructure recovery.”
NGK Spark Plug’s April-June operating profit is forecast at JPY39.6bn, well above FactSet consensus of JPY30.7bn; FY26 operating profit is forecast at JPY158.2bn, above company guidance of JPY150.0bn and consensus of JPY154.0bn. Its profits do not mainly come from AI servers, but from price increases for replacement-market spark plugs, growth in motorcycle oxygen sensors, and the fading of one-off pressures such as prior inventory valuation losses, restructuring costs, and PPA expenses. NGK Spark Plug shows that the Japanese electronic-components coverage universe still includes traditional high-margin assets; not every allocation has to revolve around AI hardware.
Alps Alpine is more complex. The report forecasts April-June operating profit of JPY3.7bn, below consensus of JPY5.3bn. The components business benefits from high-value-added smartphone camera actuators, but the automotive mobility business is dragged down by lower customer development fees. Morgan Stanley MUFG still rates it Overweight, more because of subsequent component upgrades and valuation positioning than near-term earnings surprise.
Earnings Validation Points for Hirose Electric, NGK Spark Plug, and Other Electronic Component Companies
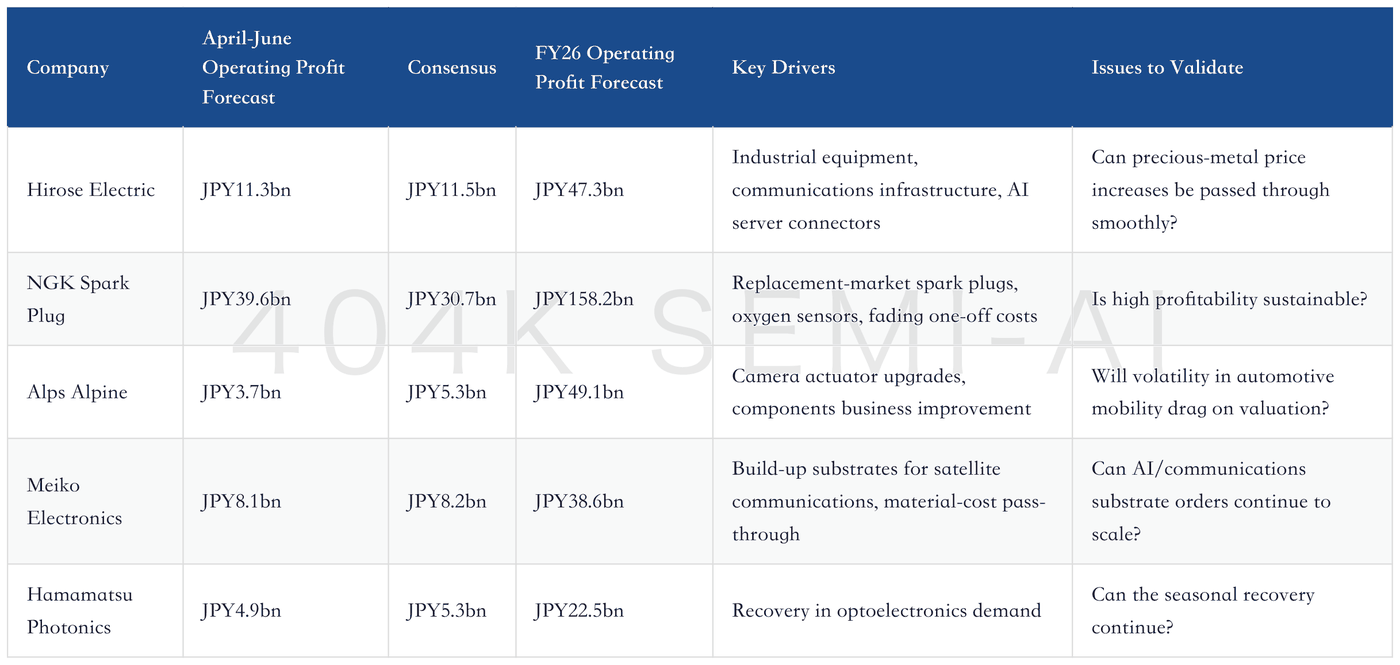
The lesson from this group of companies is that Japanese electronic components should not be ranked only by “AI server purity.” High-purity assets can more easily receive valuation premiums, but they are also more prone to expectation overshoot. Companies with slightly lower purity but stable earnings quality and clear ROE improvement may instead offer better risk-reward during earnings season. The report’s positive stance on Hirose Electric and NGK Spark Plug reminds the market not to reduce all electronic components to the two lines of MLCC and ABF.
VI. Raw Materials and FX: Two Headwinds Behind Strong Profits
Whether strong profits can be sustained ultimately depends on passing through the two tests of costs and FX. The report’s earnings forecasts are based on a weak-yen assumption, and the covered companies in aggregate still have clear sensitivity to USD/JPY. For companies with higher earnings elasticity such as Murata, Taiyo Yuden, and Alps Alpine, FX moves will directly affect the market’s judgment on full-year profit upgrades.
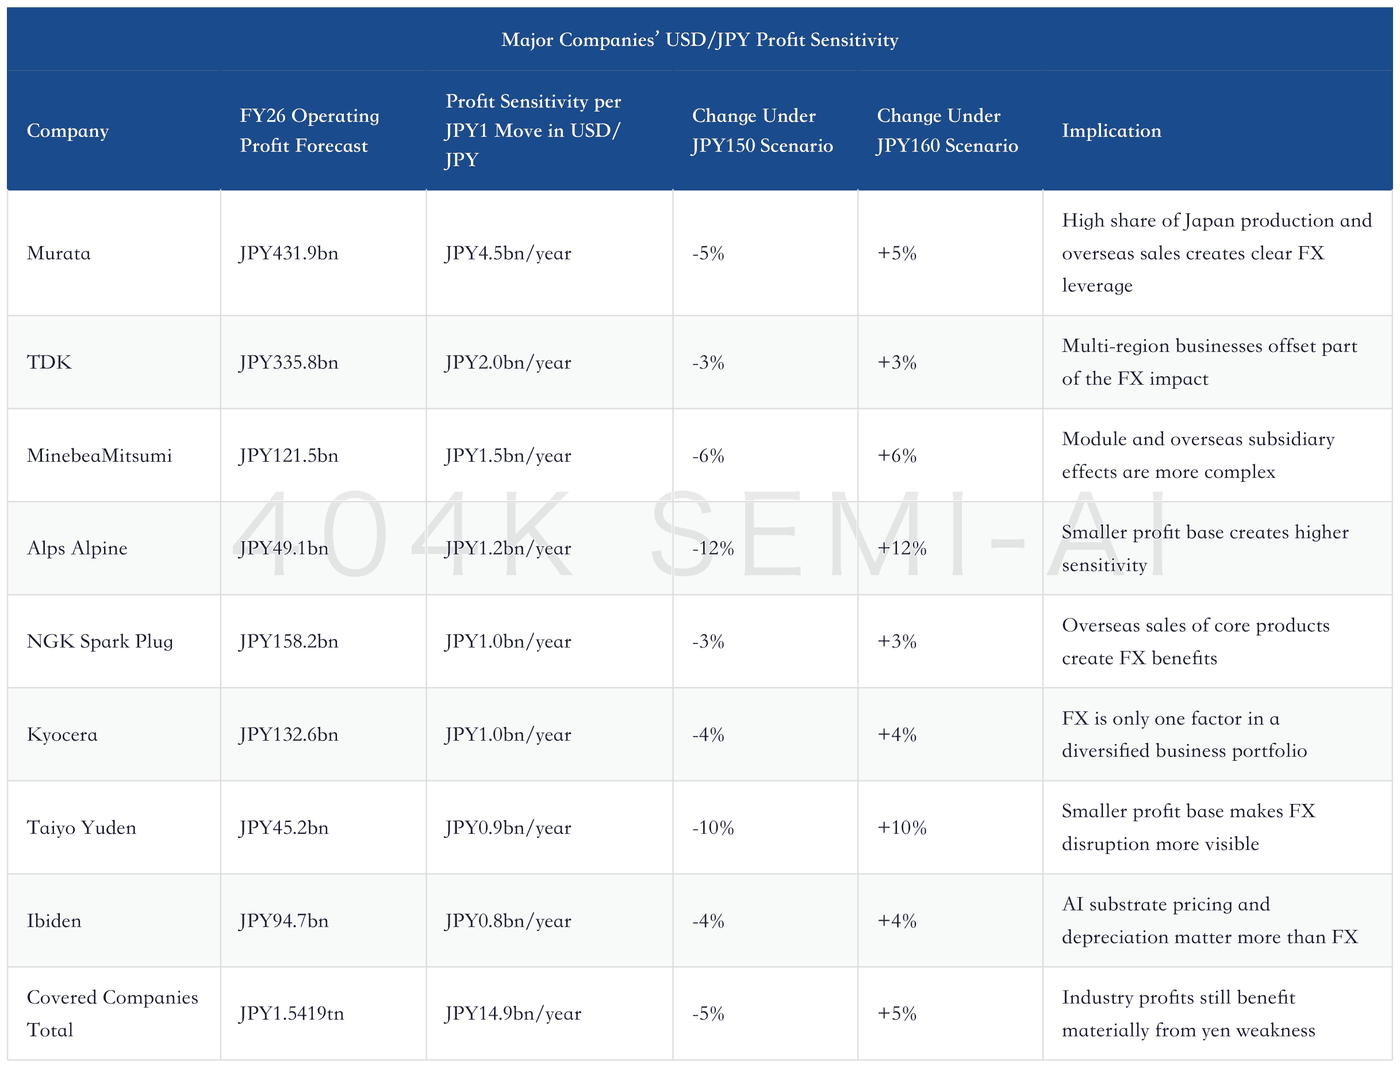
FX is not the only cost variable. Raw-material price increases recur throughout the report, especially gold prices, aluminum foil, CCL, T-Glass, and precious metals. Hirose Electric and Japan Aviation Electronics are affected by precious-metal prices; Daishinku faces pressure from gold prices, depreciation, and fixed costs; Nippon Chemi-Con is affected by higher raw-material costs such as aluminum foil; Meiko Electronics benefits from material-cost pass-through for CCL and other inputs in the previous quarter.
This means the April-June earnings season should not be judged only by the absolute level of operating profit; the pace of price pass-through also matters. If companies can pass material price increases on to customers, margin pressure will be delayed or offset. If they can only absorb it temporarily, gross margins may fall in subsequent quarters. Suppliers with stronger bargaining power in the AI hardware chain can usually transmit material costs more easily; general-purpose products or highly competitive products are more likely to be squeezed by costs.
