
Japan Electronic Components Deep Dive Update: Morgan Stanley Asia Investor Checks, and How AI Servers Are Widening the Valuation Gap Between MLCC and ABF
目录
Too Long; Didn’t Read
1. Conclusion First: This Investor Check Re-Tiers Electronic Components
2. Investors Ask About Commodity Price Hikes; Morgan Stanley Answers With Product Mix
3. Murata’s Core Variable: High-End MLCCs Shift from Tiny Components to Power-Supply Gatekeepers
4. Taiyo Yuden’s Contradiction: AI Upside, but an Execution Discount
5. Commodity MLCC Price Increases: The Choice Between Short-Term Profit and Long-Term Share
6. The Ibiden Debate: Rubin Ramp Is Strong, Consensus Is Stronger
7. Company Ranking: Murata Has the Highest Win Rate, Taiyo Yuden Offers Higher Upside, Ibiden Must Deliver the Data
8. Why the 2018 Playbook Is a Reference, Not a Template for 2026
9. Earnings Bridge: Five Gates Between AI Server Demand and Company Value
10. How to Use Sell-Side Divergence: Goldman Talks Demand, Morgan Stanley Talks Discipline, JPMorgan Talks Supply and Demand
11. Data Framework: Target Price, PE, and ROE Should Be Read Together
12. Three Worldviews: High-End MLCC Wins, Commodity Price Increases Spread, ABF Is Re-Validated
13. Asia and A-Share Read-Through: Look First at Specification Tickets, Then at Price Spillover
14. Tracking Checklist for the Next Four Quarters
15. Risk Breakdown: The Biggest Concern Is Right Demand, Wrong Company, Expensive Valuation
16. Conclusion: AI Electronic Components Enter the “Product Capability Realization Period”
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Morgan Stanley’s Asia investor checks have brought the divergence in Japanese electronic components to the forefront: AI servers continue to drive high-value-added MLCC demand, but valuation has shifted from demand elasticity to mass-production capability, product mix, ROE, and ABF profit delivery. This note breaks down the different paths of Murata, Taiyo Yuden, and Ibiden, and the validation signals to watch over the next four quarters.
Too Long; Didn’t Read
Divergence has shifted from demand to delivery. Morgan Stanley’s meeting feedback shows MLCC and ABF remain the main threads, but valuation is starting to screen for high-end mass production, product mix, and earnings quality. Generic price hikes can only provide temporary elasticity. Going forward, watch whether quarterly gross margin, inventory, and cash flow improve in tandem.
Murata’s swing factor is structural ASP. Morgan Stanley expects Murata’s AI data-center MLCC sales to grow 85-90% in F3/27, with ASP up roughly 50%, driven by a higher mix of high-priced products. The core lies in materials, layering, external electrodes, and stable mass production.
Taiyo Yuden’s upside is constrained by execution. The company also benefits from AI server MLCC demand, but the timing of high-end miniaturized mass production, roughly 5% MLCC capacity growth in F3/26, and its technology catch-up versus Murata will weigh on income-statement quality.
Commodity MLCC price hikes have limits. Rising distribution prices for commoditized MLCC can lift near-term earnings, but if companies only chase price hikes while neglecting R&D; and process capabilities, they will lose medium- to long-term share to vendors that keep improving product competitiveness. Price news must be validated against contract prices, customer orders, and inventory turnover.
Ibiden’s risk is elevated consensus. Rubin ABF substrate ramp-up will continue to drive earnings higher, but Morgan Stanley’s F3/28 and F3/31 operating profit forecasts are below the company’s targets, suggesting the market has already priced in substantial long-dated profit. EMIB-T contribution comes later, while gross margin from non-Nvidia customers and depreciation absorption still need validation.
Watch six indicators next. Focus on Murata’s AI/DC MLCC mix, mass production of key specifications, Taiyo Yuden capex, quality of commodity MLCC price hikes, Ibiden’s Rubin and EMIB-T gross margin, and the yen exchange rate. Also assess revenue growth together with inventory and cash flow to avoid relying only on price headlines. These indicators will determine whether valuation spreads widen or converge.
1. Conclusion First: This Investor Check Re-Tiers Electronic Components
This Morgan Stanley update on Japanese electronic components is short, but the signals are firm. It comes from institutional investor checks in Singapore and Hong Kong from June 22 to 26, including 31 one-on-one meetings and two luncheon sessions, with discussion focused on MLCC and ABF package substrates. The truly valuable point is that Morgan Stanley puts investors’ focus and its own judgment on the same map: investors care most about commoditized MLCC price hikes, AI server MLCC demand, and Ibiden’s valuation; Morgan Stanley cares more about product mix, stable mass production, and profit delivery.
This marks the second stage of the Japanese electronic components trade. In the first stage, the market confirmed that AI servers would push MLCC, ABF substrates, connectors, batteries, HDD heads, and other high-value-added components toward higher content value. In the second stage, the market starts to distinguish who can translate demand into the income statement and who merely has an AI exposure that sounds similar. Demand remains strong and prices are changing, but valuation must now be justified by earnings quality.
The ranking from this investor check is clear. Murata Manufacturing remains the strongest asset in high-end MLCC because AI servers require smaller, higher-capacitance, higher-reliability MLCC, and Murata leads in materials, layering, external electrodes, and mass-production stability. Taiyo Yuden also sits within the MLCC demand upcycle, but lags in high-end specification mass production and capacity expansion cadence, making its upside more dependent on execution. Ibiden remains a scarce ABF supplier, but Rubin ramp-up and EMIB-T contribution have already been priced in by the market in advance, and consensus beyond F3/28 appears more aggressive.
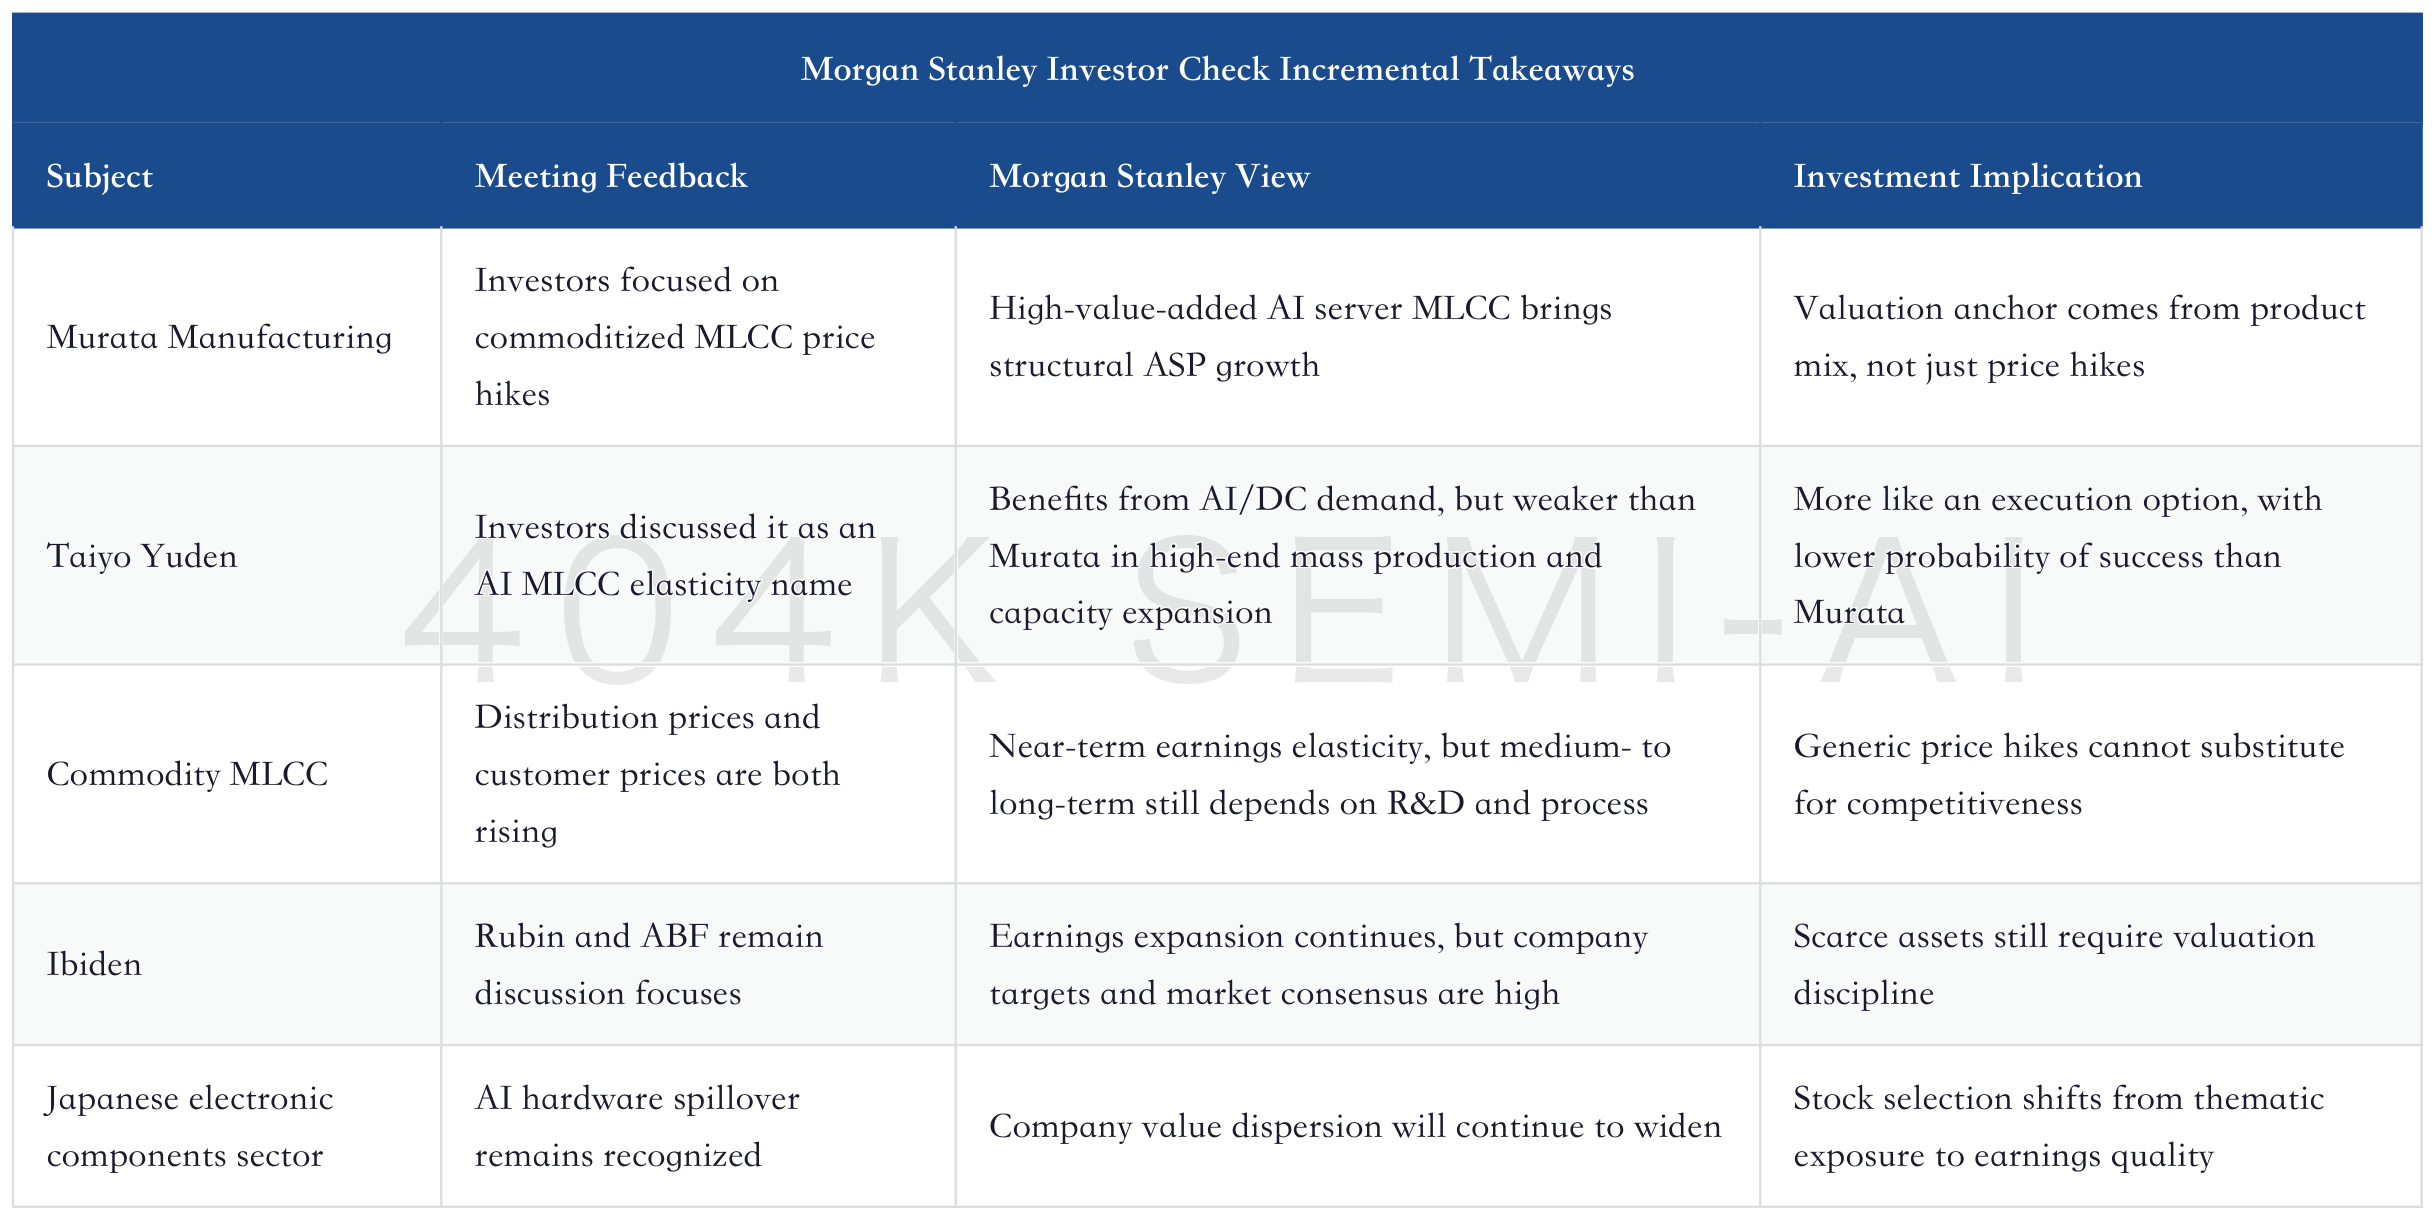
This table directly explains the “valuation gap” in the title. Japanese electronic components have not lost their AI logic; instead, they have entered a more selective phase. While all benefit from AI servers, Murata’s valuation can be supported by high-end product mix, Taiyo Yuden must catch up through execution, and Ibiden must deliver on high consensus through Rubin and EMIB-T. The market will next use quarterly data to test these differences, rather than indiscriminately assigning higher multiples to all AI component companies.
2. Investors Ask About Commodity Price Hikes; Morgan Stanley Answers With Product Mix
The most interesting contrast in this report is that the focus of the meetings and Morgan Stanley’s final conclusion do not fully overlap. Morgan Stanley states this directly: investors in the meetings were almost all asking about the magnitude of commoditized MLCC price hikes, while paying less attention to earnings expansion from growth in high-value-added products. This difference shows that the market still tends to understand the current cycle through the framework of the previous MLCC cycle.
In the last MLCC upcycle, the most visible signals were spot prices, lead times, distribution inventory, and price hikes for general-purpose products. That framework of course still has value, because distribution prices for commoditized MLCC have already started to rise, and there are also signs of adjustments in customer prices. But the new variable brought by AI servers is that high-end miniaturized, high-capacitance, high-reliability products are changing the revenue mix. Mix shifts are usually slower than pure price hikes, but they are also harder for competitors to replicate.
Murata is the representative case of this difference. Morgan Stanley notes that Murata’s AI data-center MLCC is expected to grow 85-90% in F3/27, assuming volume growth of roughly 40% and ASP growth of roughly 50%. The key is the latter half: ASP growth does not assume a simple unit-price increase for the same product, but mainly comes from a rising mix of high-priced, high-value-added products. In other words, Murata’s pricing is closer to product-mix repricing from specification upgrades, reducing the relevance of the traditional general-purpose price-hike lens.
"does not assume unit price hikes"
This short quote is the key to understanding Murata. Many electronic component companies derive earnings elasticity from list-price increases; Murata’s line comes more from customers needing to use higher-specification products. Space on AI server accelerator boards is limited, while each generation of GPU and ASIC platforms has higher power consumption, more severe transient current, and harder-to-control power-supply noise. Systems need small-size, high-capacitance MLCC to maintain power integrity. Product specification upgrades naturally increase unit value and also raise the barriers for yield, qualification, and delivery.
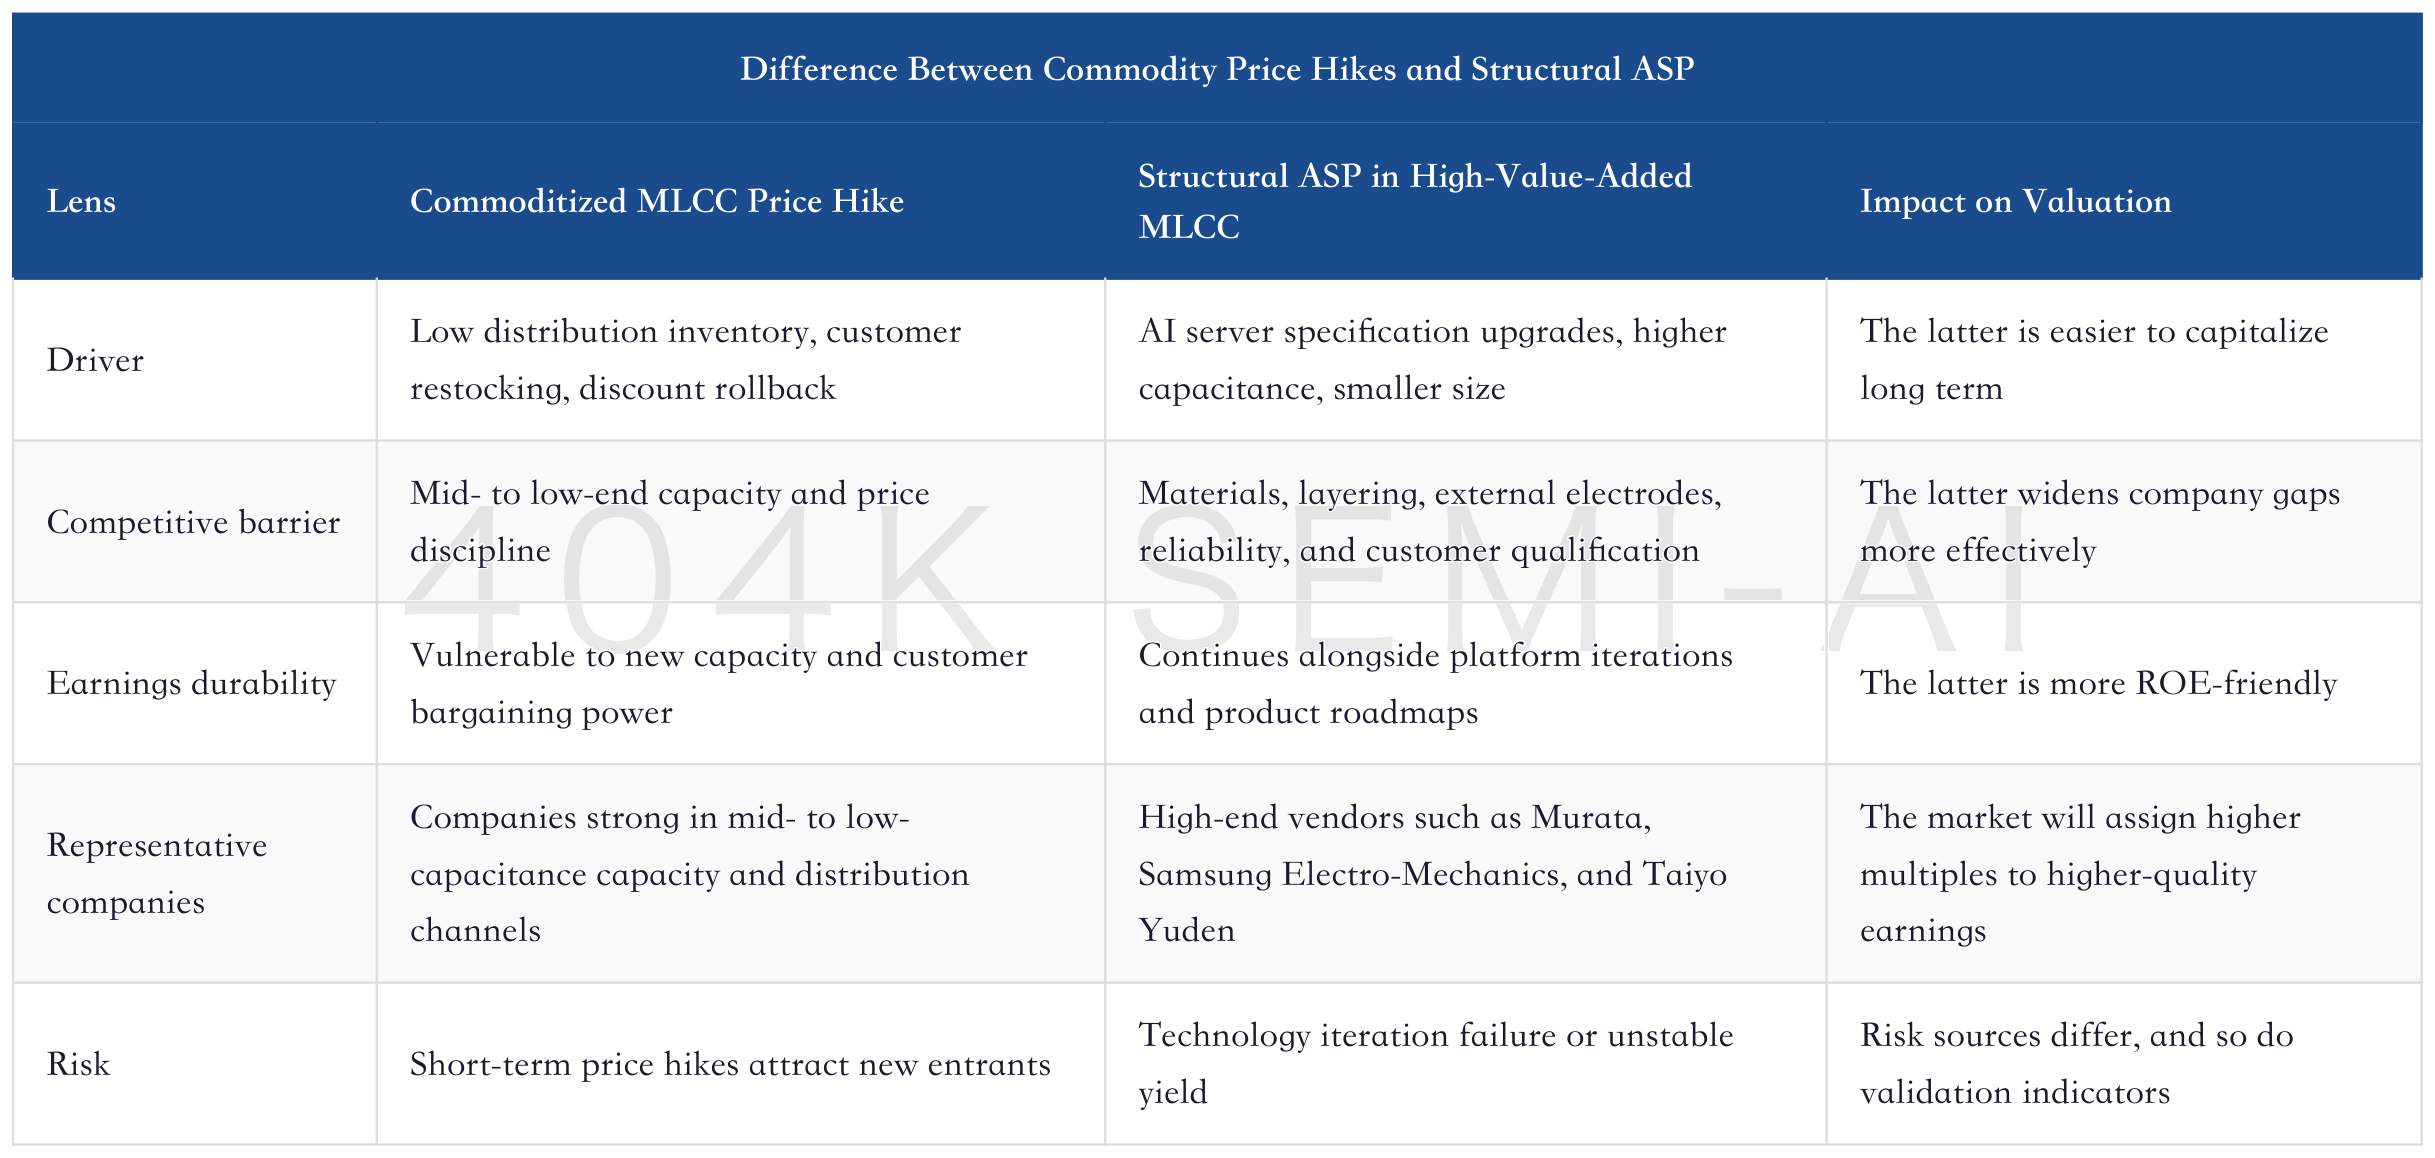
This is also why Morgan Stanley says company value gaps will continue to widen. Near-term price hikes can improve financials, but medium- to long-term corporate value comes from product competitiveness. If companies mainly allocate resources to capturing the price-hike window while falling behind in R&D;, materials, processes, and customer qualification, they may make money in one price cycle but struggle to qualify for the next generation of AI server platforms. Murata’s strategy is more focused on keeping general-purpose pricing flexible while allocating resources to high-end product competitiveness.
This view is also instructive for supply chains in mainland China, South Korea, and Taiwan. Price hikes in mid- to low-capacitance MLCC will benefit many vendors, but the ticket to high-end AI server MLCC comes from long-term investment. For A-share and Taiwan equity mappings, investors should not only look at who has MLCC capacity, but also who can approach high-end specifications in powder, thin-layering, stacking, sintering, screening, customer qualification, and stable mass production. Supply shortages provide beta for mid- to low-end companies; high-end specifications determine alpha.
3. Murata’s Core Variable: High-End MLCCs Shift from Tiny Components to Power-Supply Gatekeepers
The core driver of AI server demand for MLCCs is power density. GPUs, ASICs, CPUs, HBM, and high-speed switching chips continue to raise power consumption, requiring stronger board-level transient response, decoupling capability, and noise control. Traditional servers also need MLCCs, but new-generation AI acceleration platforms push MLCCs into tighter space, higher capacitance, and stricter reliability constraints.
Morgan Stanley provides a critical engineering judgment: on AI server accelerator cards, the total capacitance required from MLCCs rises by roughly 2x with each GPU generation, while mounting space remains limited. This means AI server MLCC demand has become a problem of capacitance per unit volume. High capacitance, small size, and high reliability have become the same problem.
"total capacitance required of MLCC increases"
Murata’s leading position rests on a full set of process capabilities. Morgan Stanley notes that the company improves dielectric-layer volume by refining and homogenizing barium titanate particles, increasing the number of layers, and narrowing external electrode width, thereby driving miniaturization and higher capacitance. Broken down, these three actions correspond to materials, manufacturing, and structural design: materials determine whether dielectric layers can be made thinner; layering determines how much effective capacitance can fit into the same volume; external electrode design determines how much internal space can be used for dielectric layers.
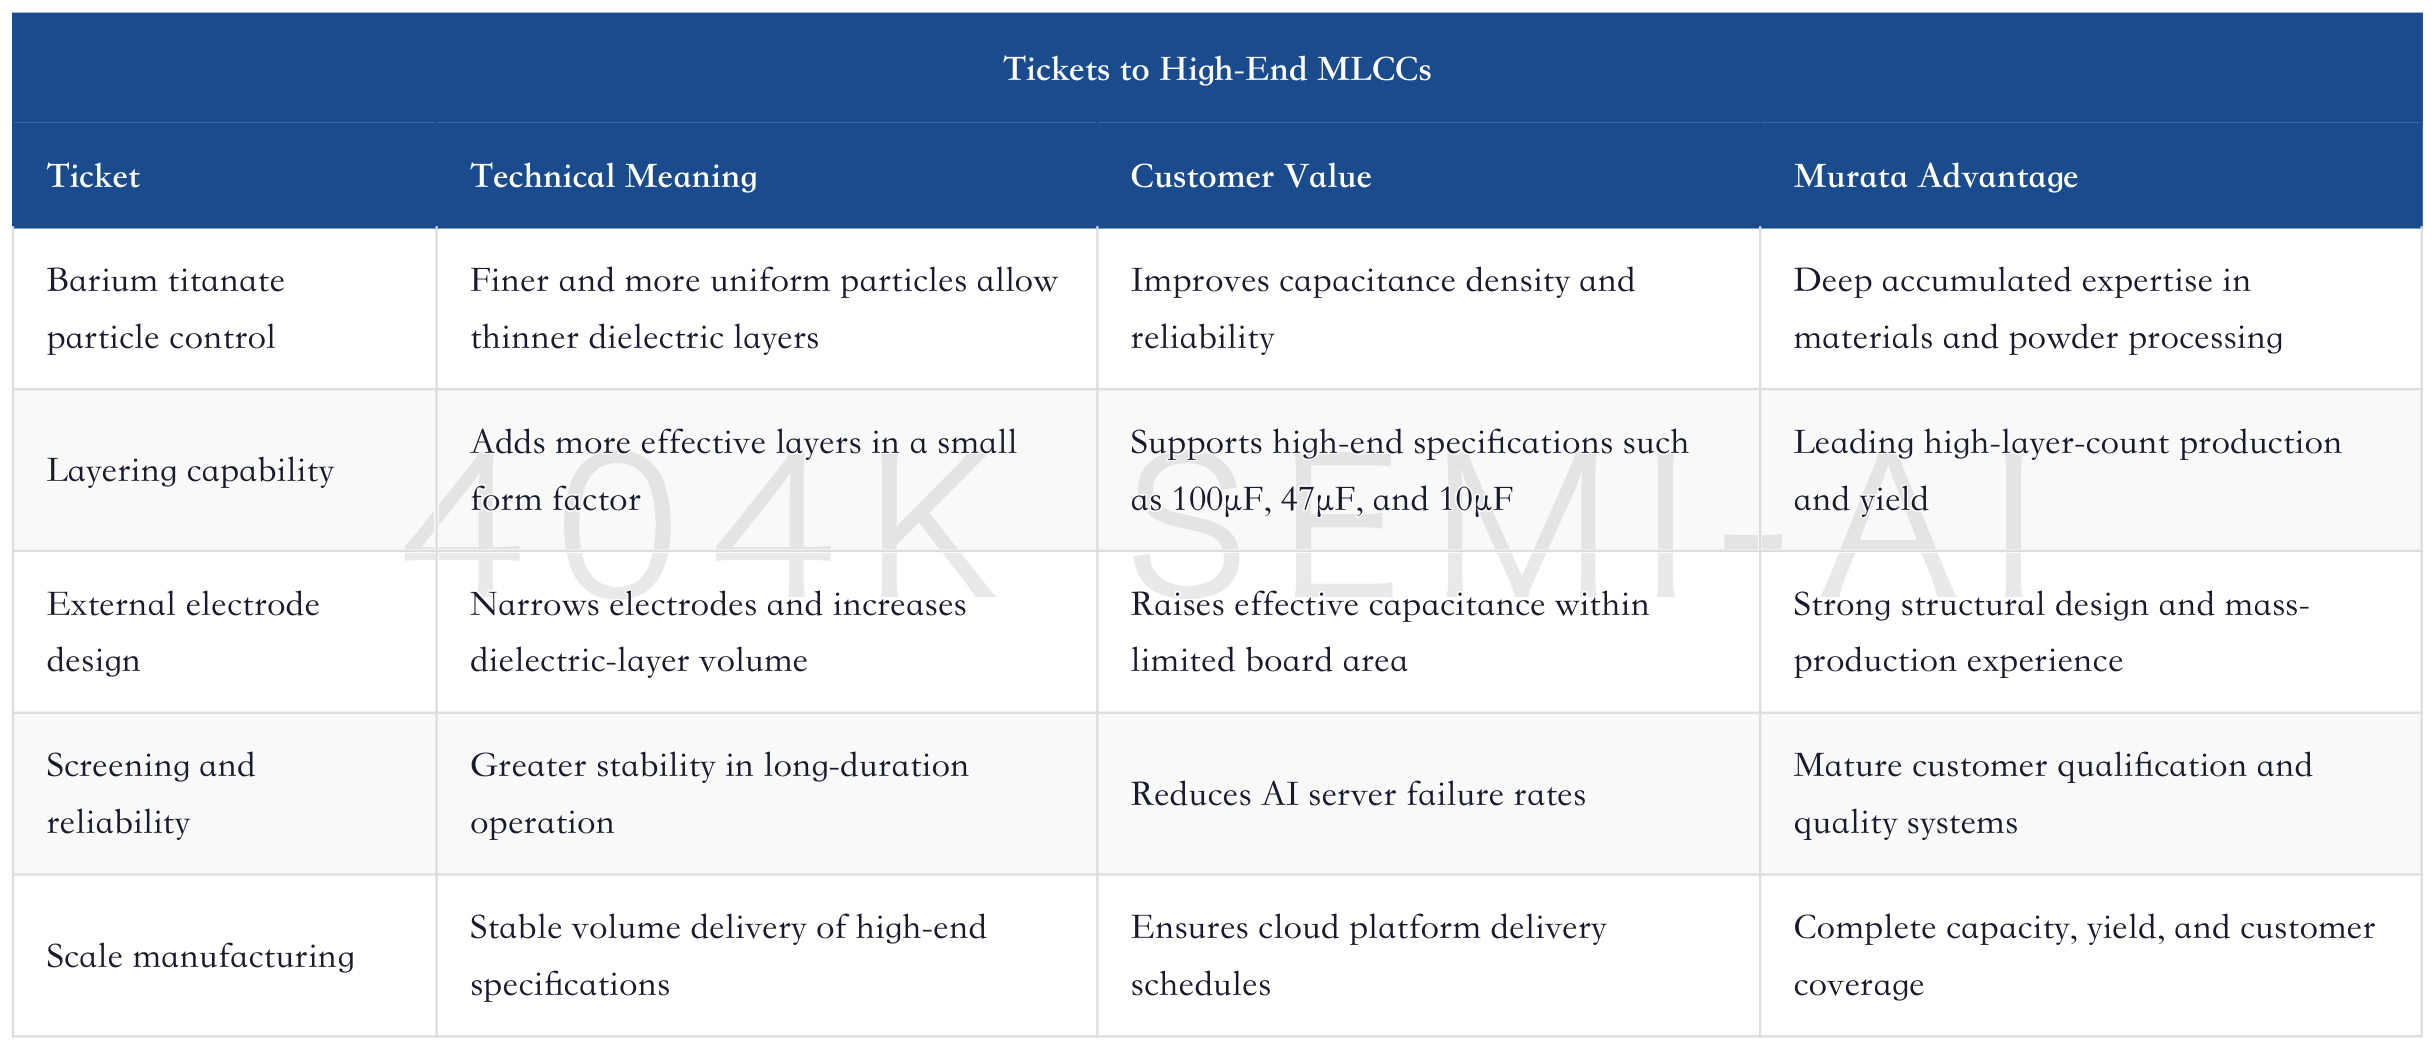
This capability set determines Murata’s valuation foundation. Looking only at AI server revenue as a share of MLCC revenue, the 10-15% level in F3/26 does not appear especially high; Morgan Stanley expects it to rise to 20-25% in F3/27 and continue growing at a similar pace after F3/28. The real meaning behind the change in mix is that high-end products are moving from marginal contribution to the center of the profit pool. As long as high-end products have meaningfully higher ASPs, margins, and customer stickiness than standard products, rising revenue contribution will drive simultaneous improvement in margins and ROE.
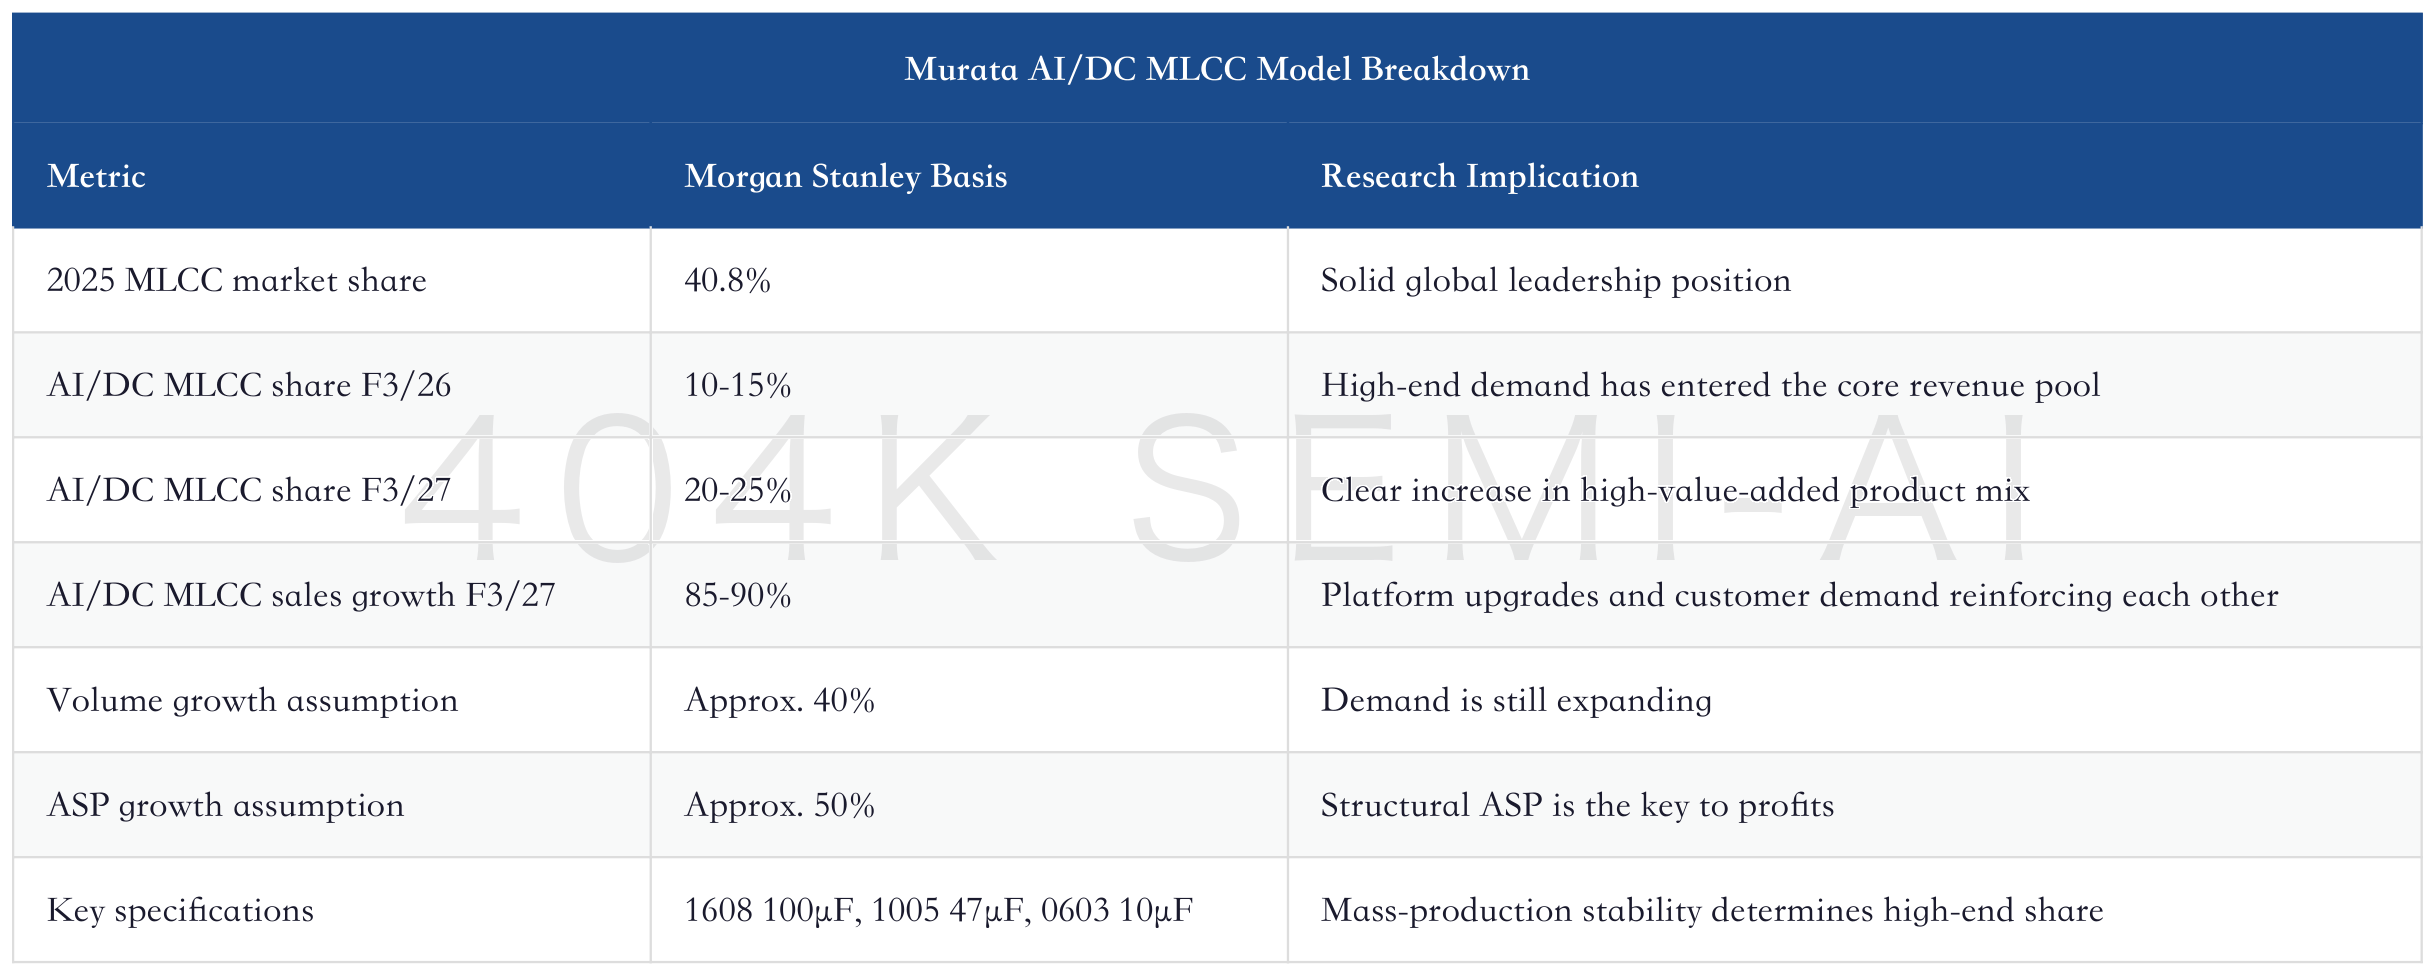
From an investment research perspective, Murata’s re-rating does not rely on a single quarter of price-hike news. It requires continuous validation of three points. First, the AI/DC MLCC share must continue rising, showing that high-end demand has entered the main line of the income statement. Second, key specifications must reach stable mass production, showing that share and customer qualification are not being eroded by challengers. Third, ASP growth must come from mix, not price hikes for commodity products, showing that ROE improvement is sustainable.
The risks are also clear. If the rollout of customers’ next-generation platforms slows, or if yields on high-end specifications improve too quickly and allow competitors to catch up, Murata’s structural ASP will be compressed. If the yen appreciates sharply, Morgan Stanley’s model also implies mid-single-digit pressure on Murata’s operating profit from FX. High-end MLCC is a good business, but the valuation has already recognized this line in advance. Going forward, it will not be enough to look only at strong orders; margins, ROE, and free cash flow also need to be watched.
4. Taiyo Yuden’s Contradiction: AI Upside, but an Execution Discount
Taiyo Yuden provides the best negative control in this report. Morgan Stanley acknowledges that Taiyo Yuden will benefit from growth in AI server and data-center MLCC sales, as well as higher utilization rates. At the same time, Morgan Stanley believes the contribution from high-value-added products to Taiyo Yuden’s earnings will be limited. This judgment sounds restrained, but it captures Taiyo Yuden’s core contradiction.
Taiyo Yuden’s problem is not demand. Morgan Stanley estimates that Taiyo Yuden’s AI data-center MLCCs will account for 5-10% of total MLCC sales in F3/26, then grow 82-83% in F3/27 to reach about 15% of sales, and continue expanding after F3/28. This growth rate is not weak; it is even close to Murata’s. The divergence comes from win rate: whether the company can stably mass-produce high-end specifications, catch up with the next-generation small-form-factor, high-capacitance roadmap, and secure enough new business in the critical window.
The key specifications Morgan Stanley lists are 1608-size 100µF, 1005-size 47µF, and 0603-size 10µF. It believes that, for now, only Murata appears able to stably mass-produce all of these products. When Taiyo Yuden can do so remains unclear. By the time it catches up with Murata’s current comparable products, Murata may already have started mass production of the next generation of smaller and higher-capacitance MLCCs. This is the harshest part of high-end electronic components: catching up is a moving exam, and the leader keeps moving too.
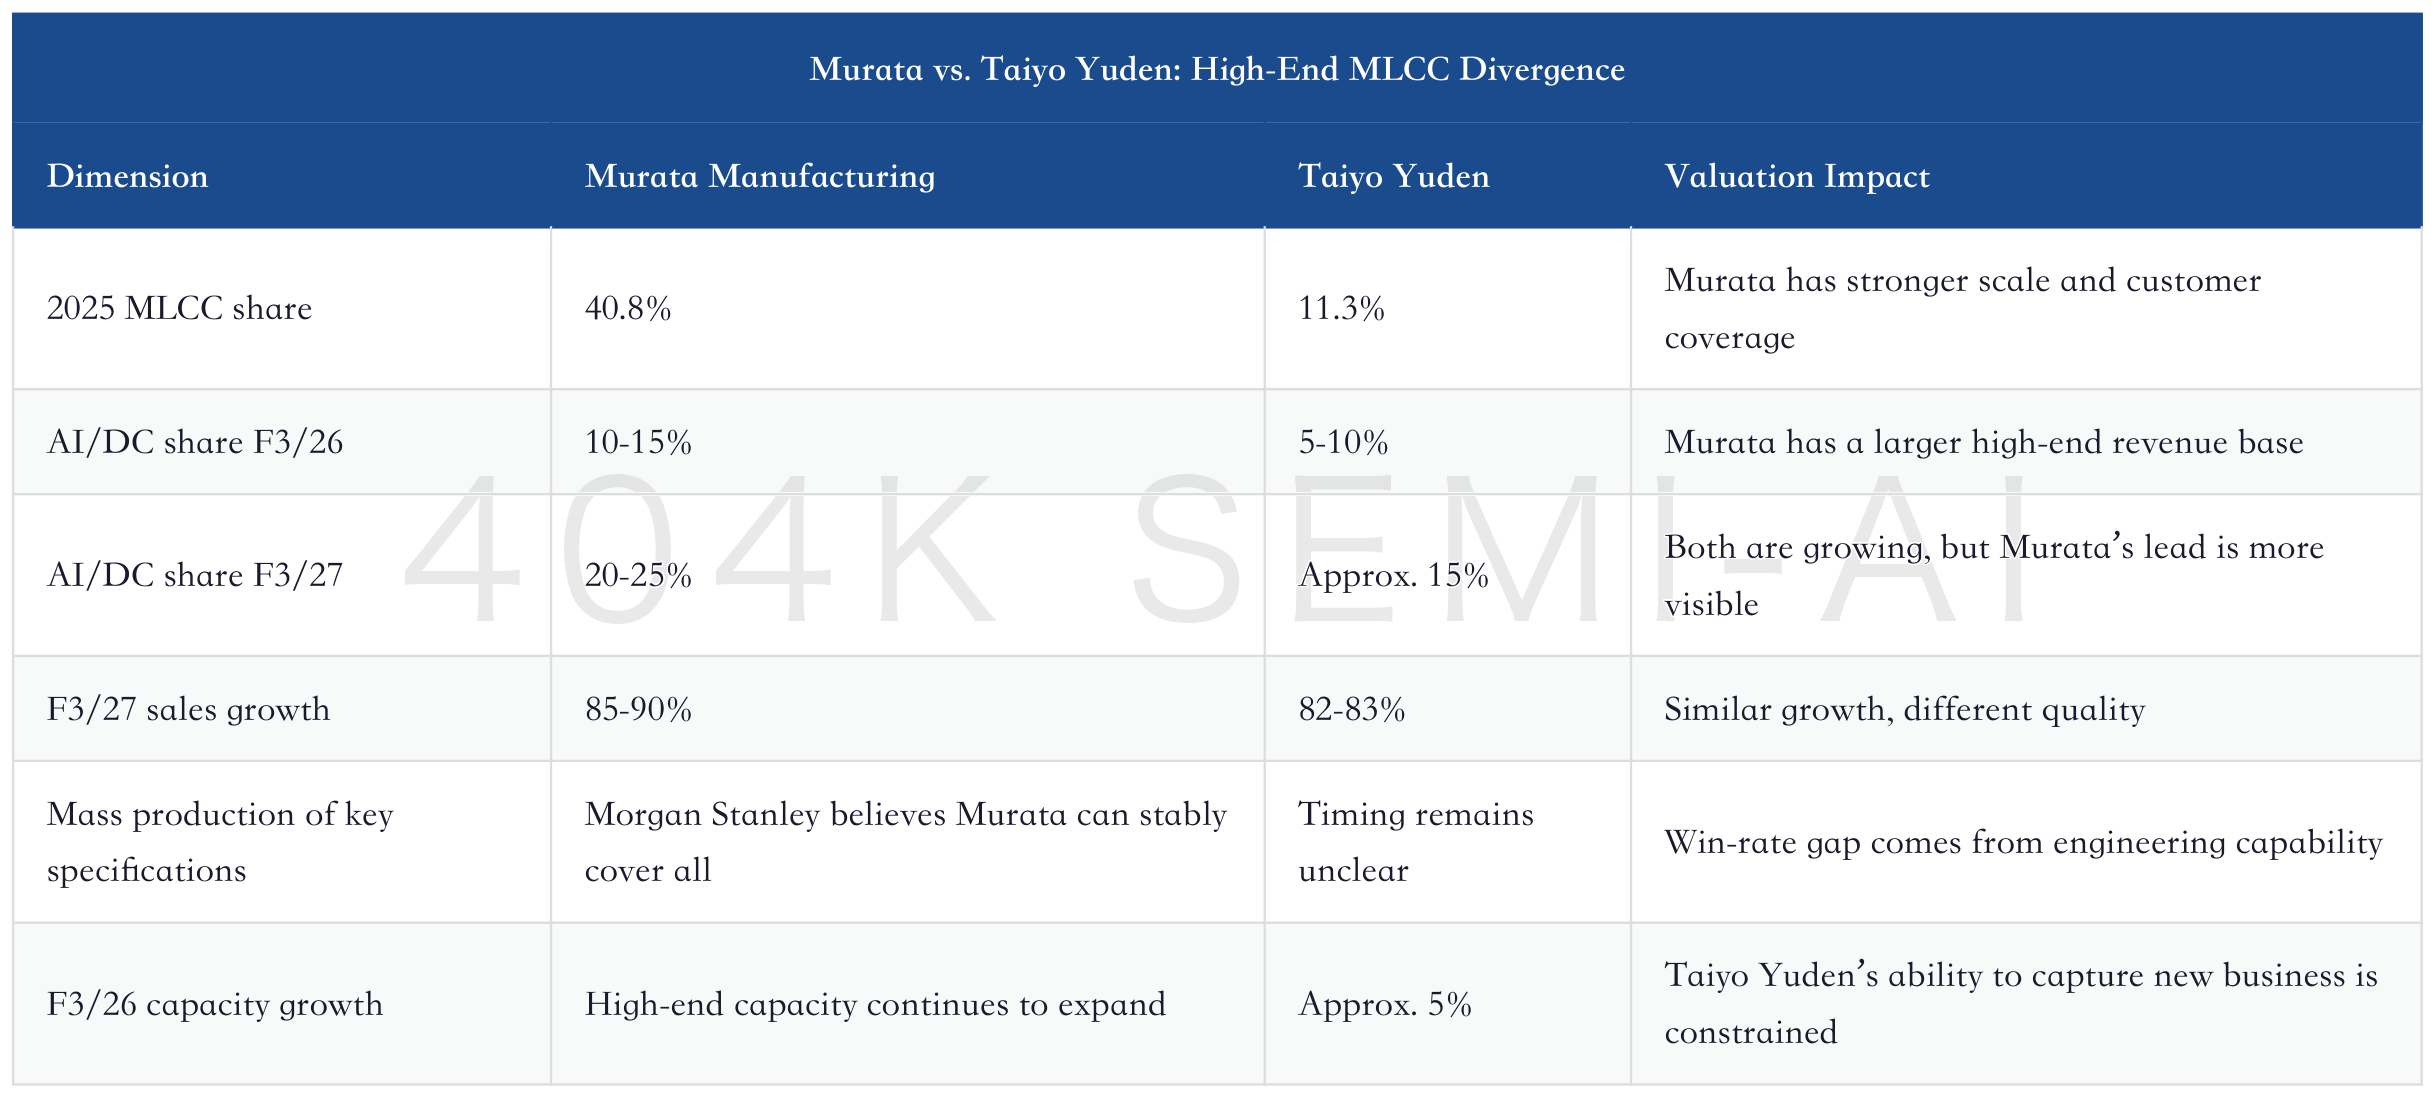
Capacity timing is the second constraint. Morgan Stanley notes that Taiyo Yuden froze capex in 2H24, limiting F3/26 MLCC capacity growth to about 5% and affecting its ability to capture new business. For a traditional cycle, this capital discipline may be a strength; during the AI server high-end MLCC window, excessive conservatism can cause the company to miss customer qualification and share gains. Taiyo Yuden needs to balance two risks: expanding too slowly means losing orders, while expanding too quickly risks repeating depreciation and inventory pressure.
Taiyo Yuden’s investment value therefore looks more like an execution option. Its revenue concentration is high, so the earnings sensitivity from AI MLCC volume ramp could be greater than Murata’s. But it needs to prove that its roadmap, mass production, capex, and customer adoption can keep pace. If the next few quarters show synchronized improvement in AI server orders, BB ratio, capacity utilization, and gross margin, Taiyo Yuden’s valuation discount will narrow. If investors see only revenue growth without improvement in high-end mix and margins, the market will still treat it as a high-volatility MLCC beta.
5. Commodity MLCC Price Increases: The Choice Between Short-Term Profit and Long-Term Share
Morgan Stanley’s stance on commodity MLCC price increases is worth unpacking. The report acknowledges that distributor selling prices for commodity MLCCs appear to be rising, and that Murata will also adjust prices flexibly based on market conditions. The issue is that Murata is not proactively pushing price increases for commodity products, because excessive pursuit of short-term profit would lower entry barriers, attract accelerated entry by manufacturers in mainland China, South Korea, and Taiwan, and ultimately lead to medium- to long-term share erosion.
This may sound like a management philosophy, but it is essentially the competitive logic of the electronic components industry. Price elasticity in standard MLCCs is the easiest for the market to observe and the easiest to attract new capacity. Short-term price increases lift industry profit, but if product specifications lack barriers, customers will look for second suppliers, competitors will allocate more resources, channels will build inventory, and the benefit from price increases will ultimately be absorbed by competition and the inventory cycle.
High-end MLCCs are priced differently. Customers are willing to pay premiums for smaller size, higher capacitance, higher reliability, and more stable delivery, because these products directly affect AI server platform delivery. Customers care more about failure rates, qualification cycles, and platform compatibility; unit price is only one constraint. Suppliers can therefore achieve ASP growth through new specifications, new products, and mix improvement, without having to center the competition on commodity product quotations.
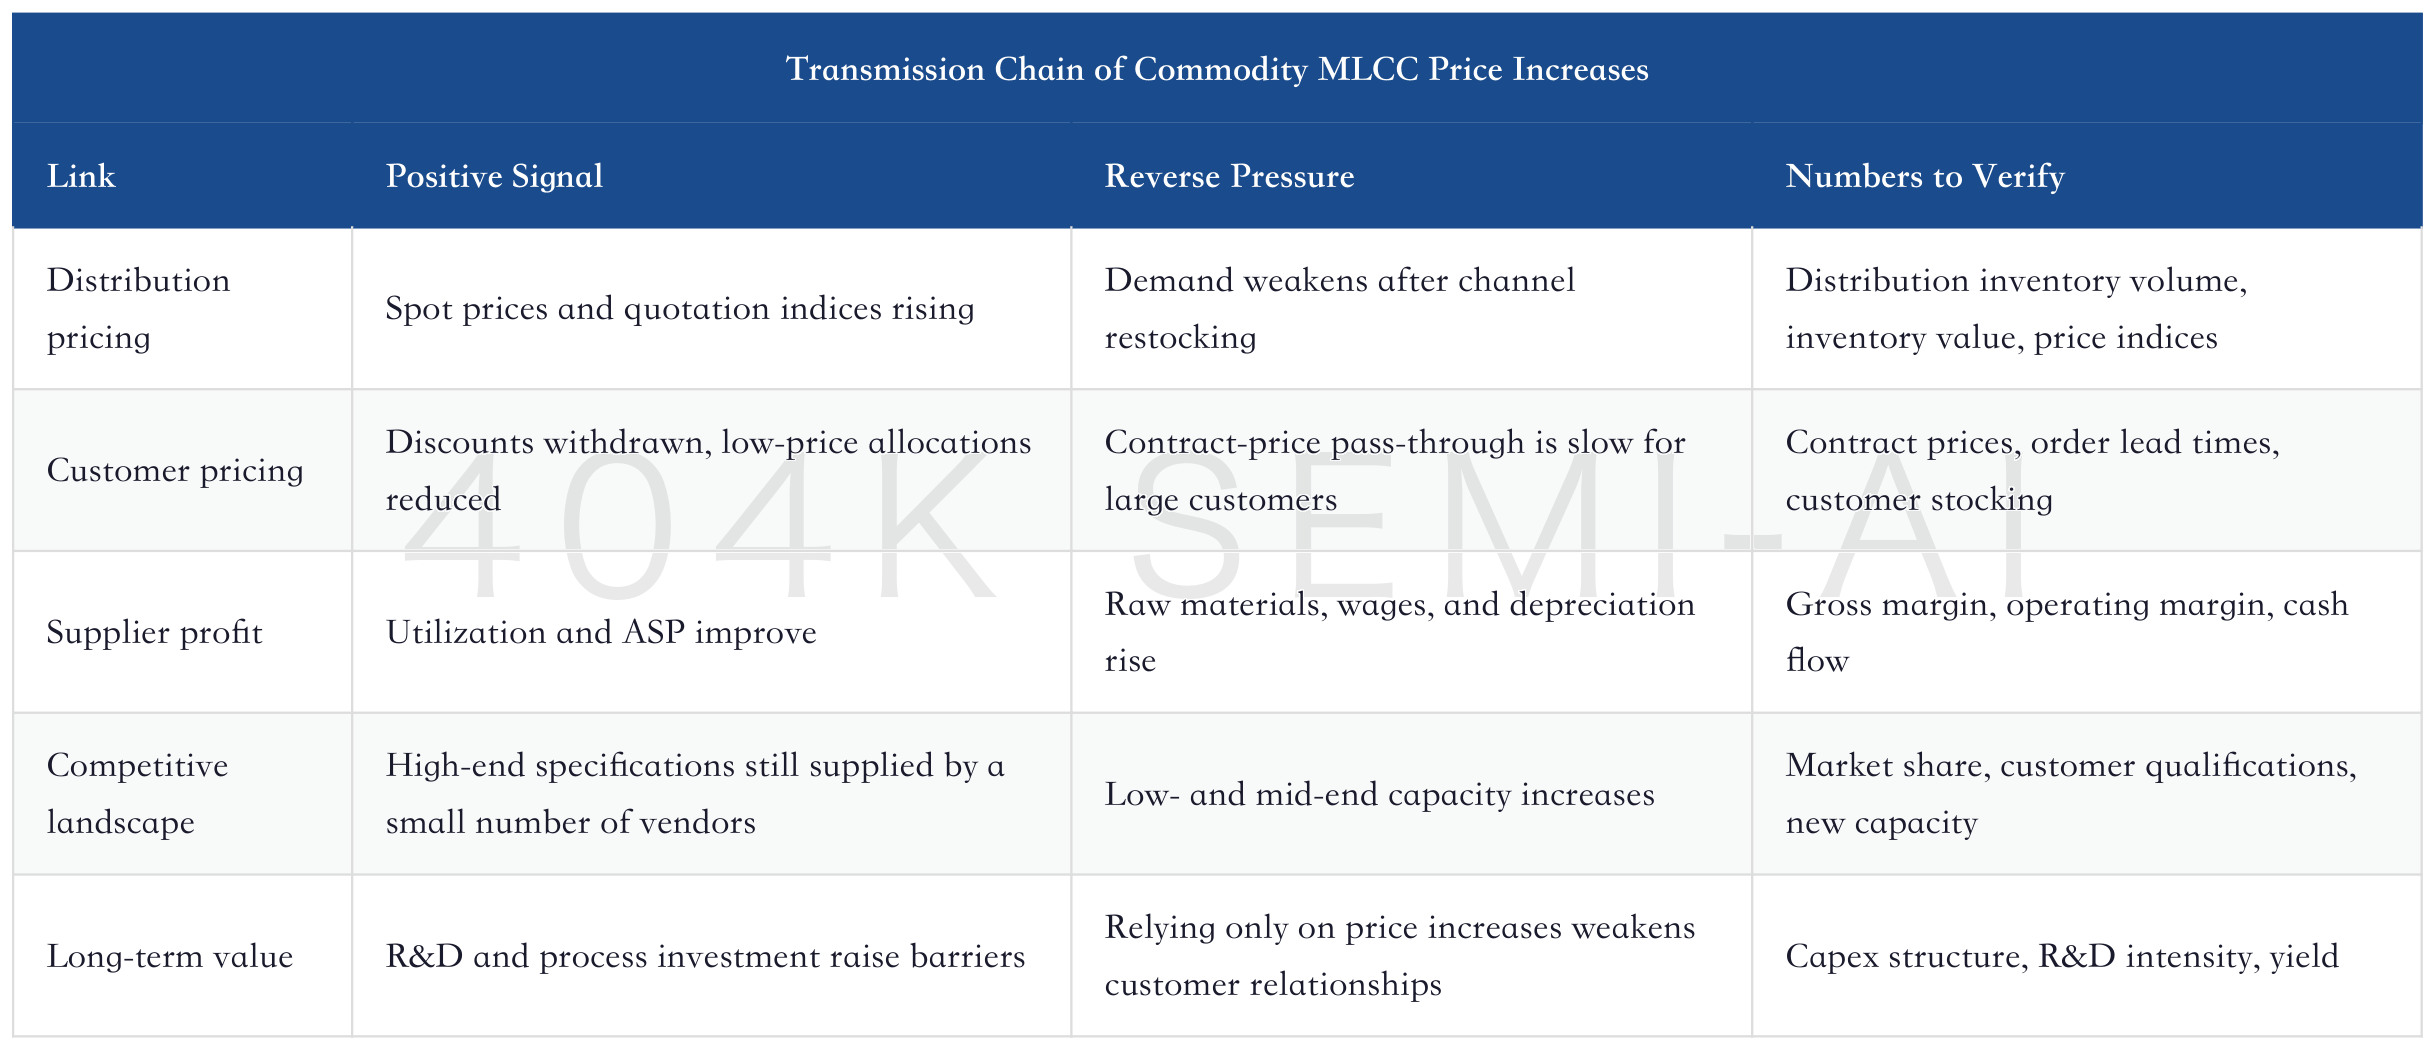
This framework is especially important for mapping to domestic passive components. Price increases in low- and mid-capacitance MLCCs will lift revenue and gross margin for related companies, and materials suppliers will also benefit from higher utilization. But the valuation ceiling depends on progress in high-end specifications. If a company can only earn cyclical profit from commodity price increases, valuation will be constrained by the cycle peak. If it can enter AI servers, high-reliability automotive, and high-end industrial specifications, and improve customer qualification through powder, end electrodes, thinning, and screening capabilities, it has a chance to shift from a cyclical stock into a platform-type component asset.
This time, Morgan Stanley separates “price-increase companies” from “product-competitiveness companies,” offering a very clear research signal. Ordinary price increases can serve as an early signal for the income statement, but not as the final valuation anchor. The real variables to track are whether price increases are accompanied by a higher share of high-end products, whether margin improvement is accompanied by healthy inventory, and whether customer qualifications can move from short-term shortages to next-generation platform status.
6. The Ibiden Debate: Rubin Ramp Is Strong, Consensus Is Stronger
The Ibiden section is the most valuation-disciplined part of the report. Morgan Stanley does not deny the company’s fundamentals. On the contrary, the report expects Ibiden to have started volume shipments of NVIDIA Rubin ABF package substrates in Q4 F3/26, and expects Rubin-related ABF sales to exceed Blackwell in Q1 F3/27, driving continued profit expansion from high-value-added ABF package substrates.
The disagreement comes from the height of expectations. Morgan Stanley believes market expectations for Ibiden are too high. The report’s operating profit forecasts show F3/27 slightly below FactSet consensus, F3/28 meaningfully below the company’s target and FactSet consensus, and F3/31 also below the company’s long-term target. In other words, the Rubin ramp is a positive variable with relatively high visibility, but the market has already priced in a lot of future profit.
"market consensus appears too high"
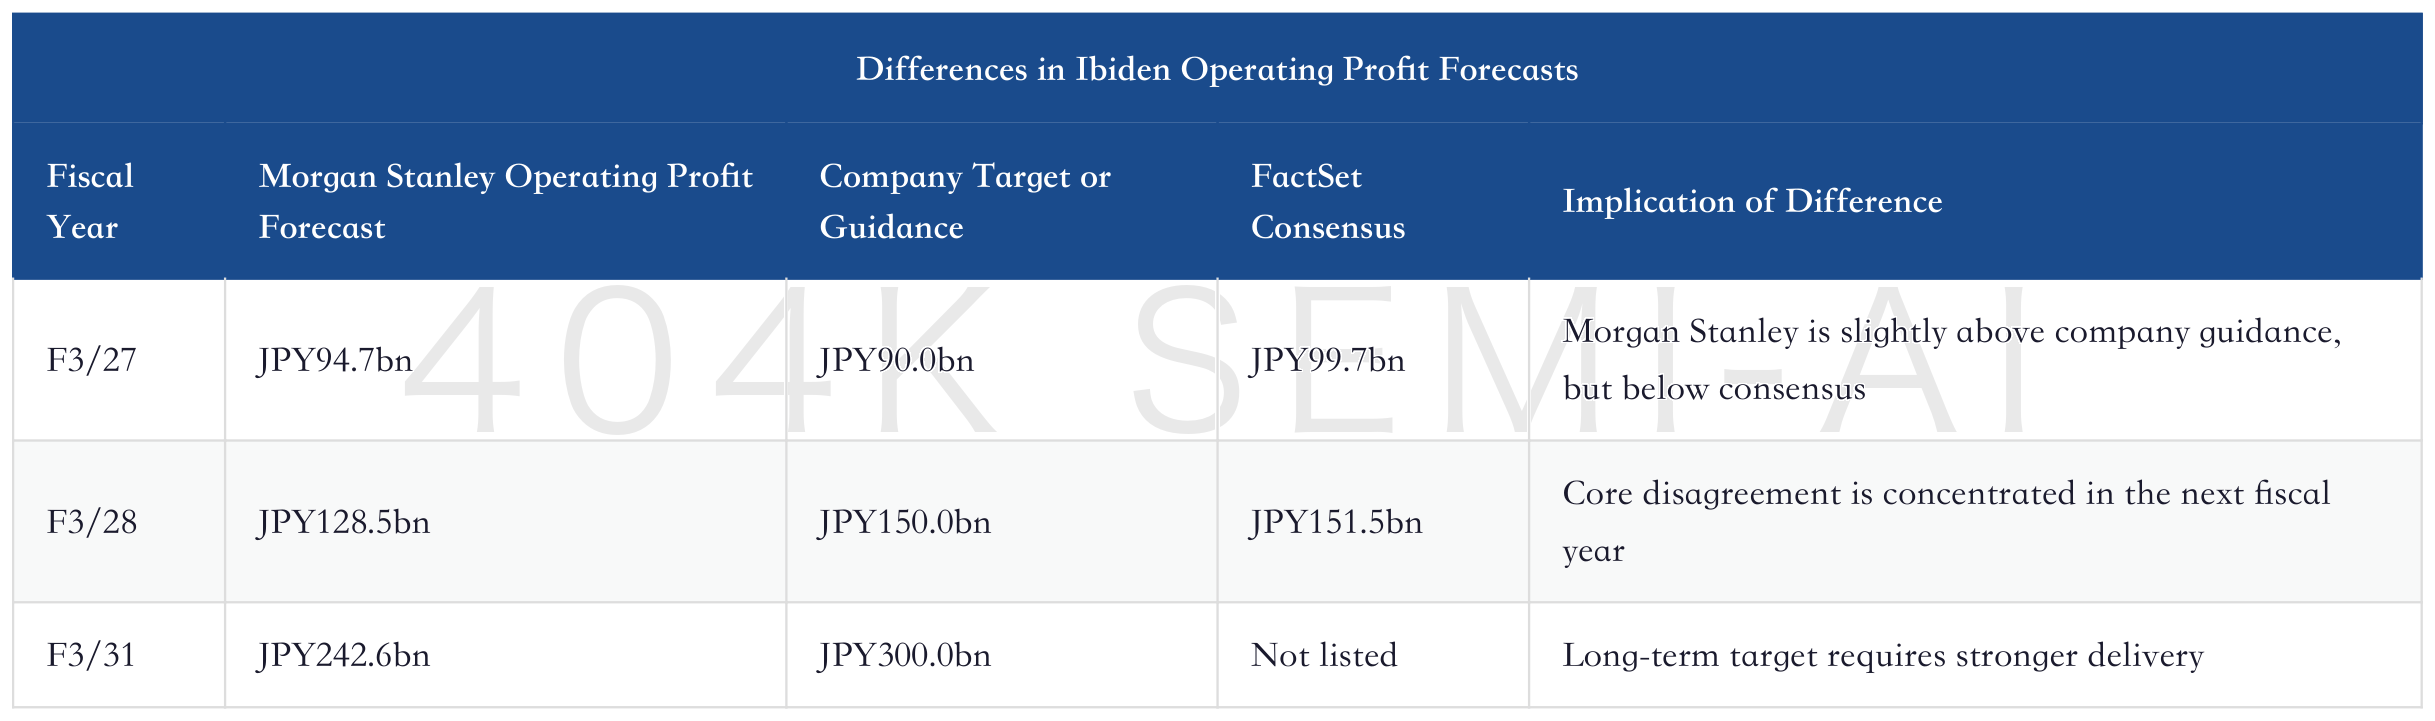
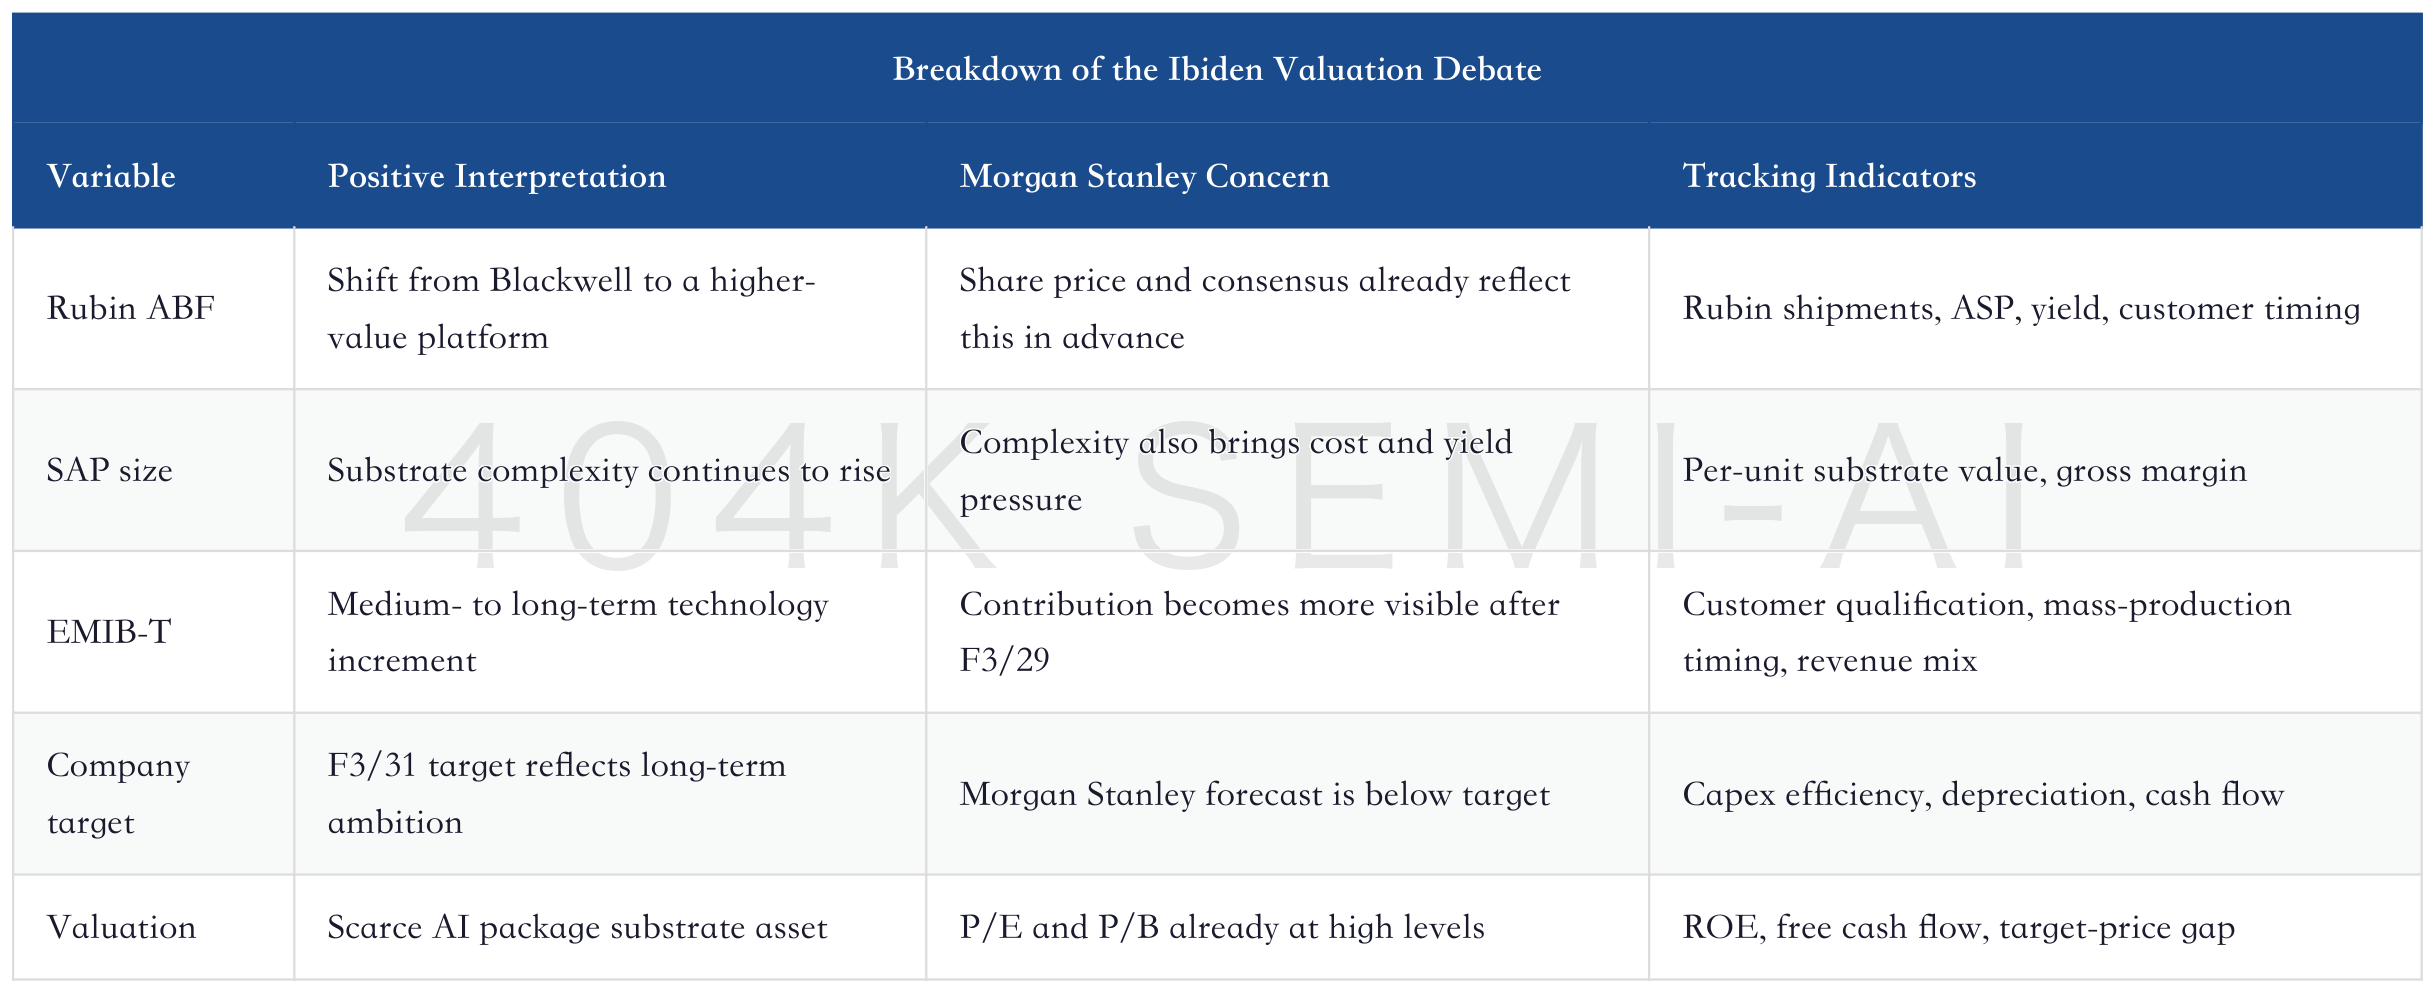
Why is Morgan Stanley cautious? First, the value uplift in ABF is real, and larger SAP size will continue to make substrates more value-added; but higher value-added does not mean unlimited gross margin upside. Second, EMIB-T will bring profit expansion, but Morgan Stanley believes meaningful contribution will not appear until after F3/29. Third, EMIB-T pricing will be significantly higher than existing ABF, but Morgan Stanley believes it will be difficult for its margin to reach the level of existing NVIDIA products.
Ibiden can be broken down into three lines. The Rubin line is the short- to medium-term growth anchor, showing that NVIDIA platforms continue to lift ABF value content. The EMIB-T line is the medium- to long-term technology anchor, showing that high-end package substrates still have more complex forms ahead. The valuation line is the risk anchor, showing that the market has already traded these variables in advance at high multiples. As long as the Rubin or EMIB-T timetable slips slightly, or non-NVIDIA customer margins fall short of expectations, valuation will adjust first.
This section also has implications for the broader AI hardware chain. Packaging, substrates, MLCCs, CCL, glass fiber cloth, and high-end PCBs will all benefit from rising system complexity, but every link faces the same valuation question: strong demand is one thing; margins, depreciation, customer structure, and long-term ROE delivery are another. Ibiden shows that even scarce assets enter a verification period when prices are too high.
7. Company Ranking: Murata Has the Highest Win Rate, Taiyo Yuden Offers Higher Upside, Ibiden Must Deliver the Data
Morgan Stanley covers 20 Japanese electronic components companies, but this research is best divided into three types of assets. The first is product-structure driven, represented by Murata, where the core question is whether high-end MLCCs can continue to lift ASP and ROE. The second is execution-option driven, represented by Taiyo Yuden, where the core question is whether it can catch up in high-end specifications and convert AI demand into margins. The third is high-consensus verification, represented by Ibiden, where the core question is whether Rubin, EMIB-T, and margins can support already elevated expectations.
TDK, Hirose, NGK Spark Plug, Alps Alpine, and others are also among Morgan Stanley’s relatively positive ratings. Their common feature is not extreme single-point elasticity, but steadier ROE and profit growth through HDD heads, BBU batteries, connectors, existing automotive businesses, or operational improvement. Once the market enters a valuation-discipline phase, these assets may instead gain more relative value.
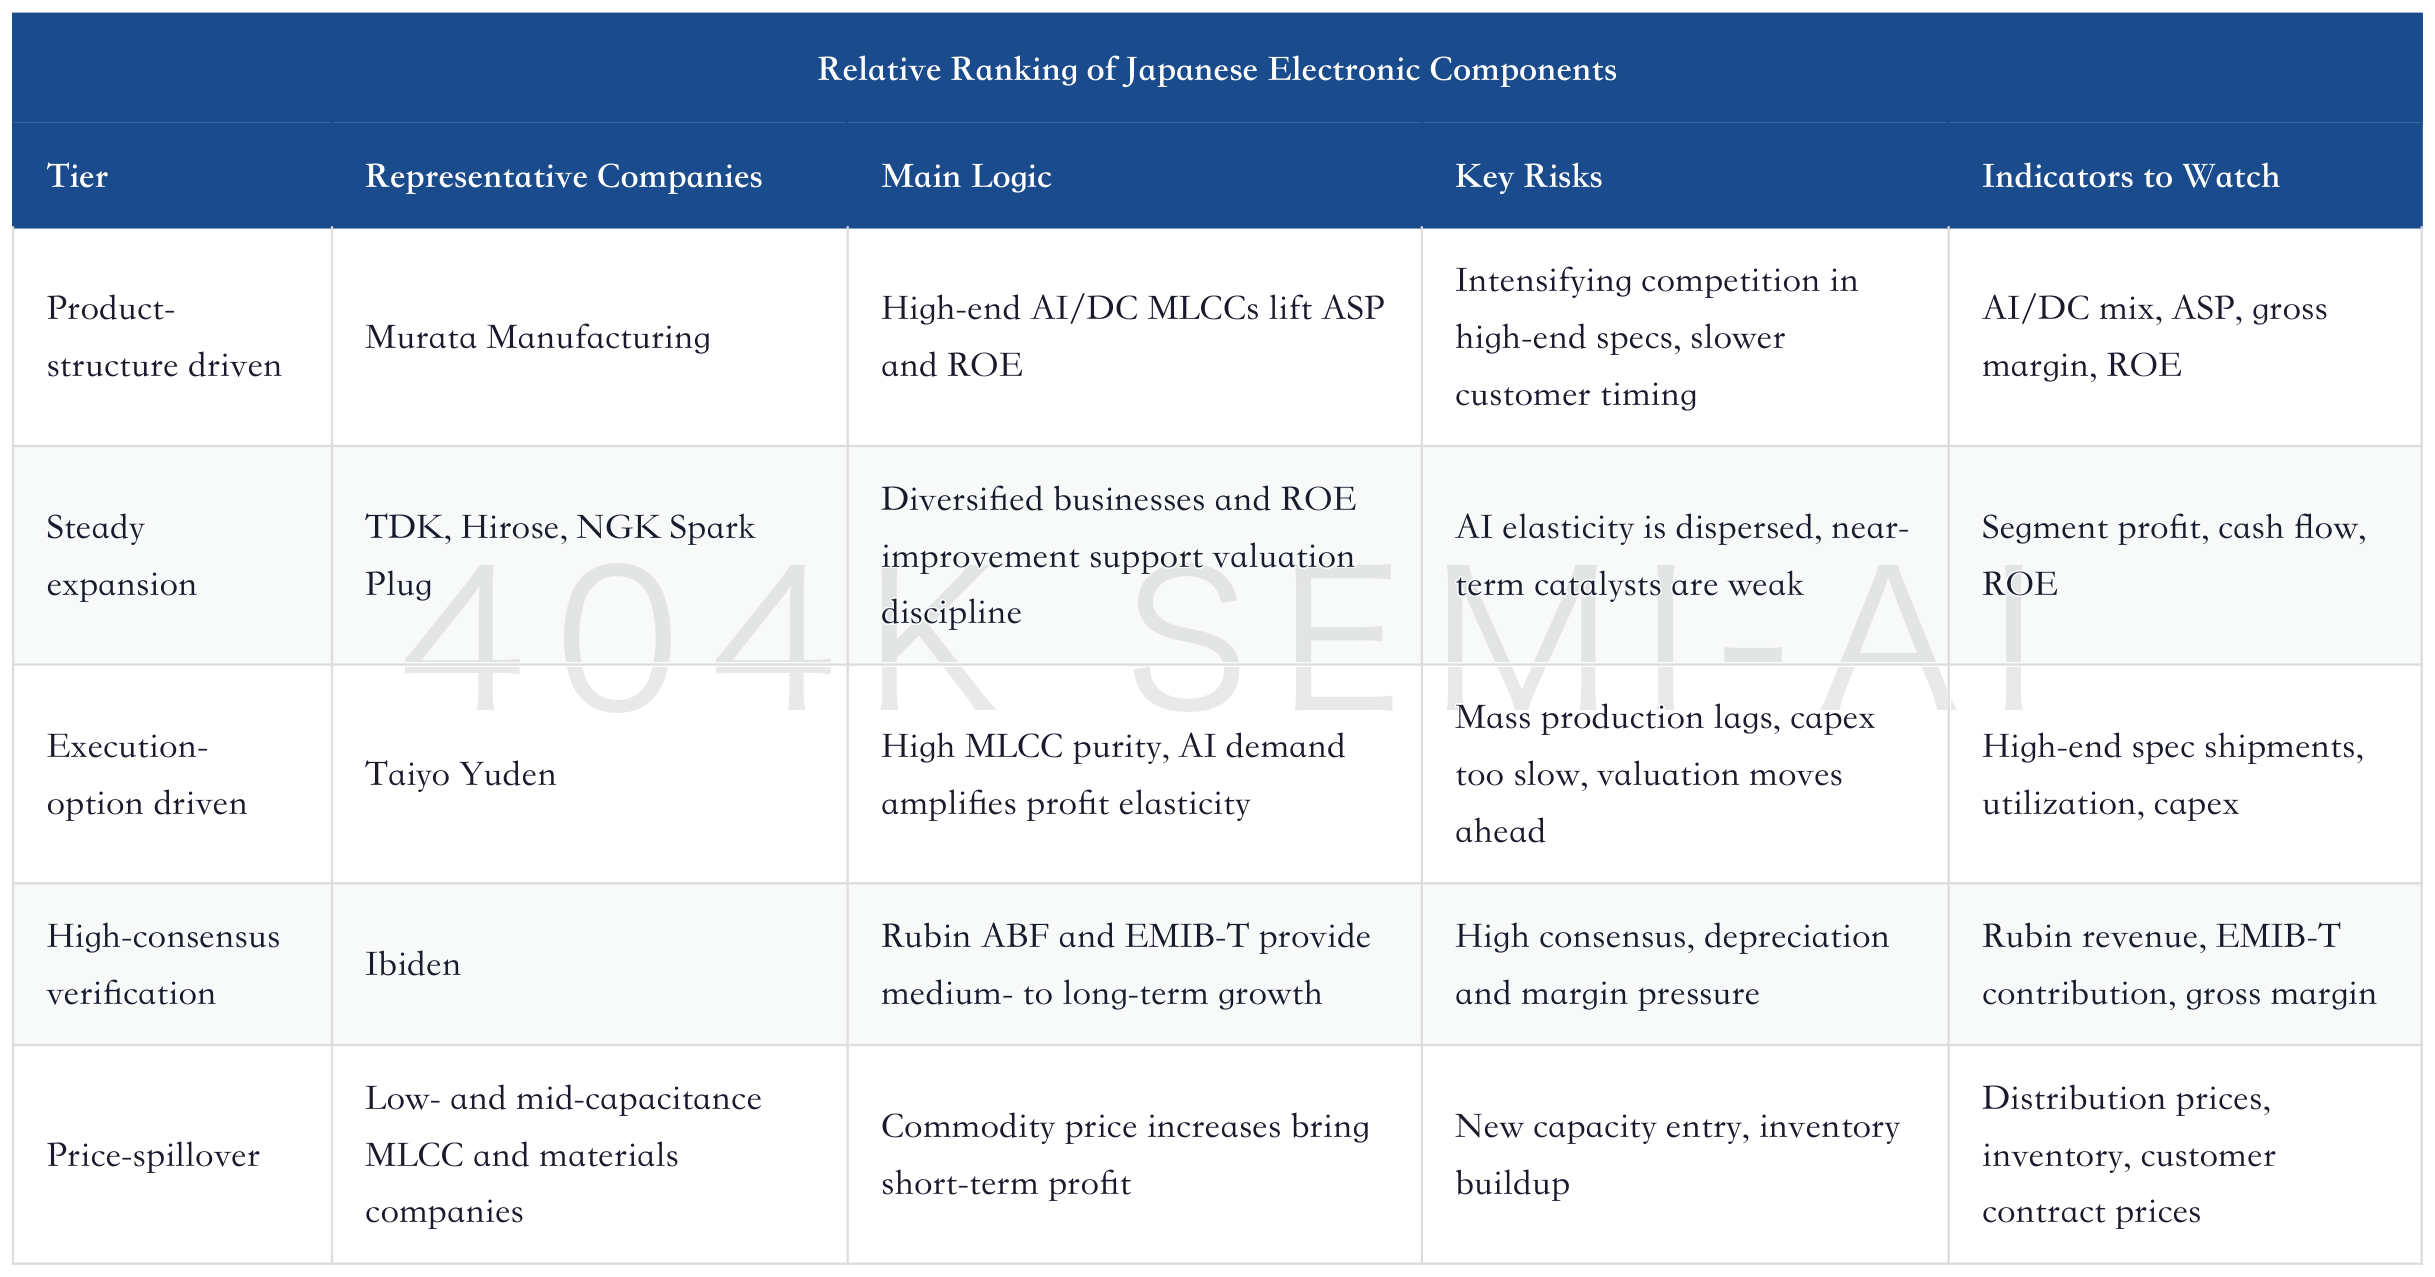
This ranking is not a permanent judgment on company quality, but the current risk-reward structure based on available data. Murata looks most like a high-probability asset, Taiyo Yuden more like a high-upside asset, and Ibiden like a scarce asset that the market has already recognized in advance. All three assets benefit from AI servers, but the market is asking each of them a completely different verification question.
For Murata, the question is whether the share of high-end MLCCs can continue to rise, and whether ASP growth can mainly come from product structure. For Taiyo Yuden, the question is whether it can use customer qualifications and capex to prove that it is not only a beneficiary, but also a stable supplier to high-end platforms. For Ibiden, the question is whether Rubin and EMIB-T can support company targets in gross margin and cash flow. If all three questions are answered positively, the sector can continue to be strong. If demand is strong but profit quality is weak, valuation dispersion will continue to widen.
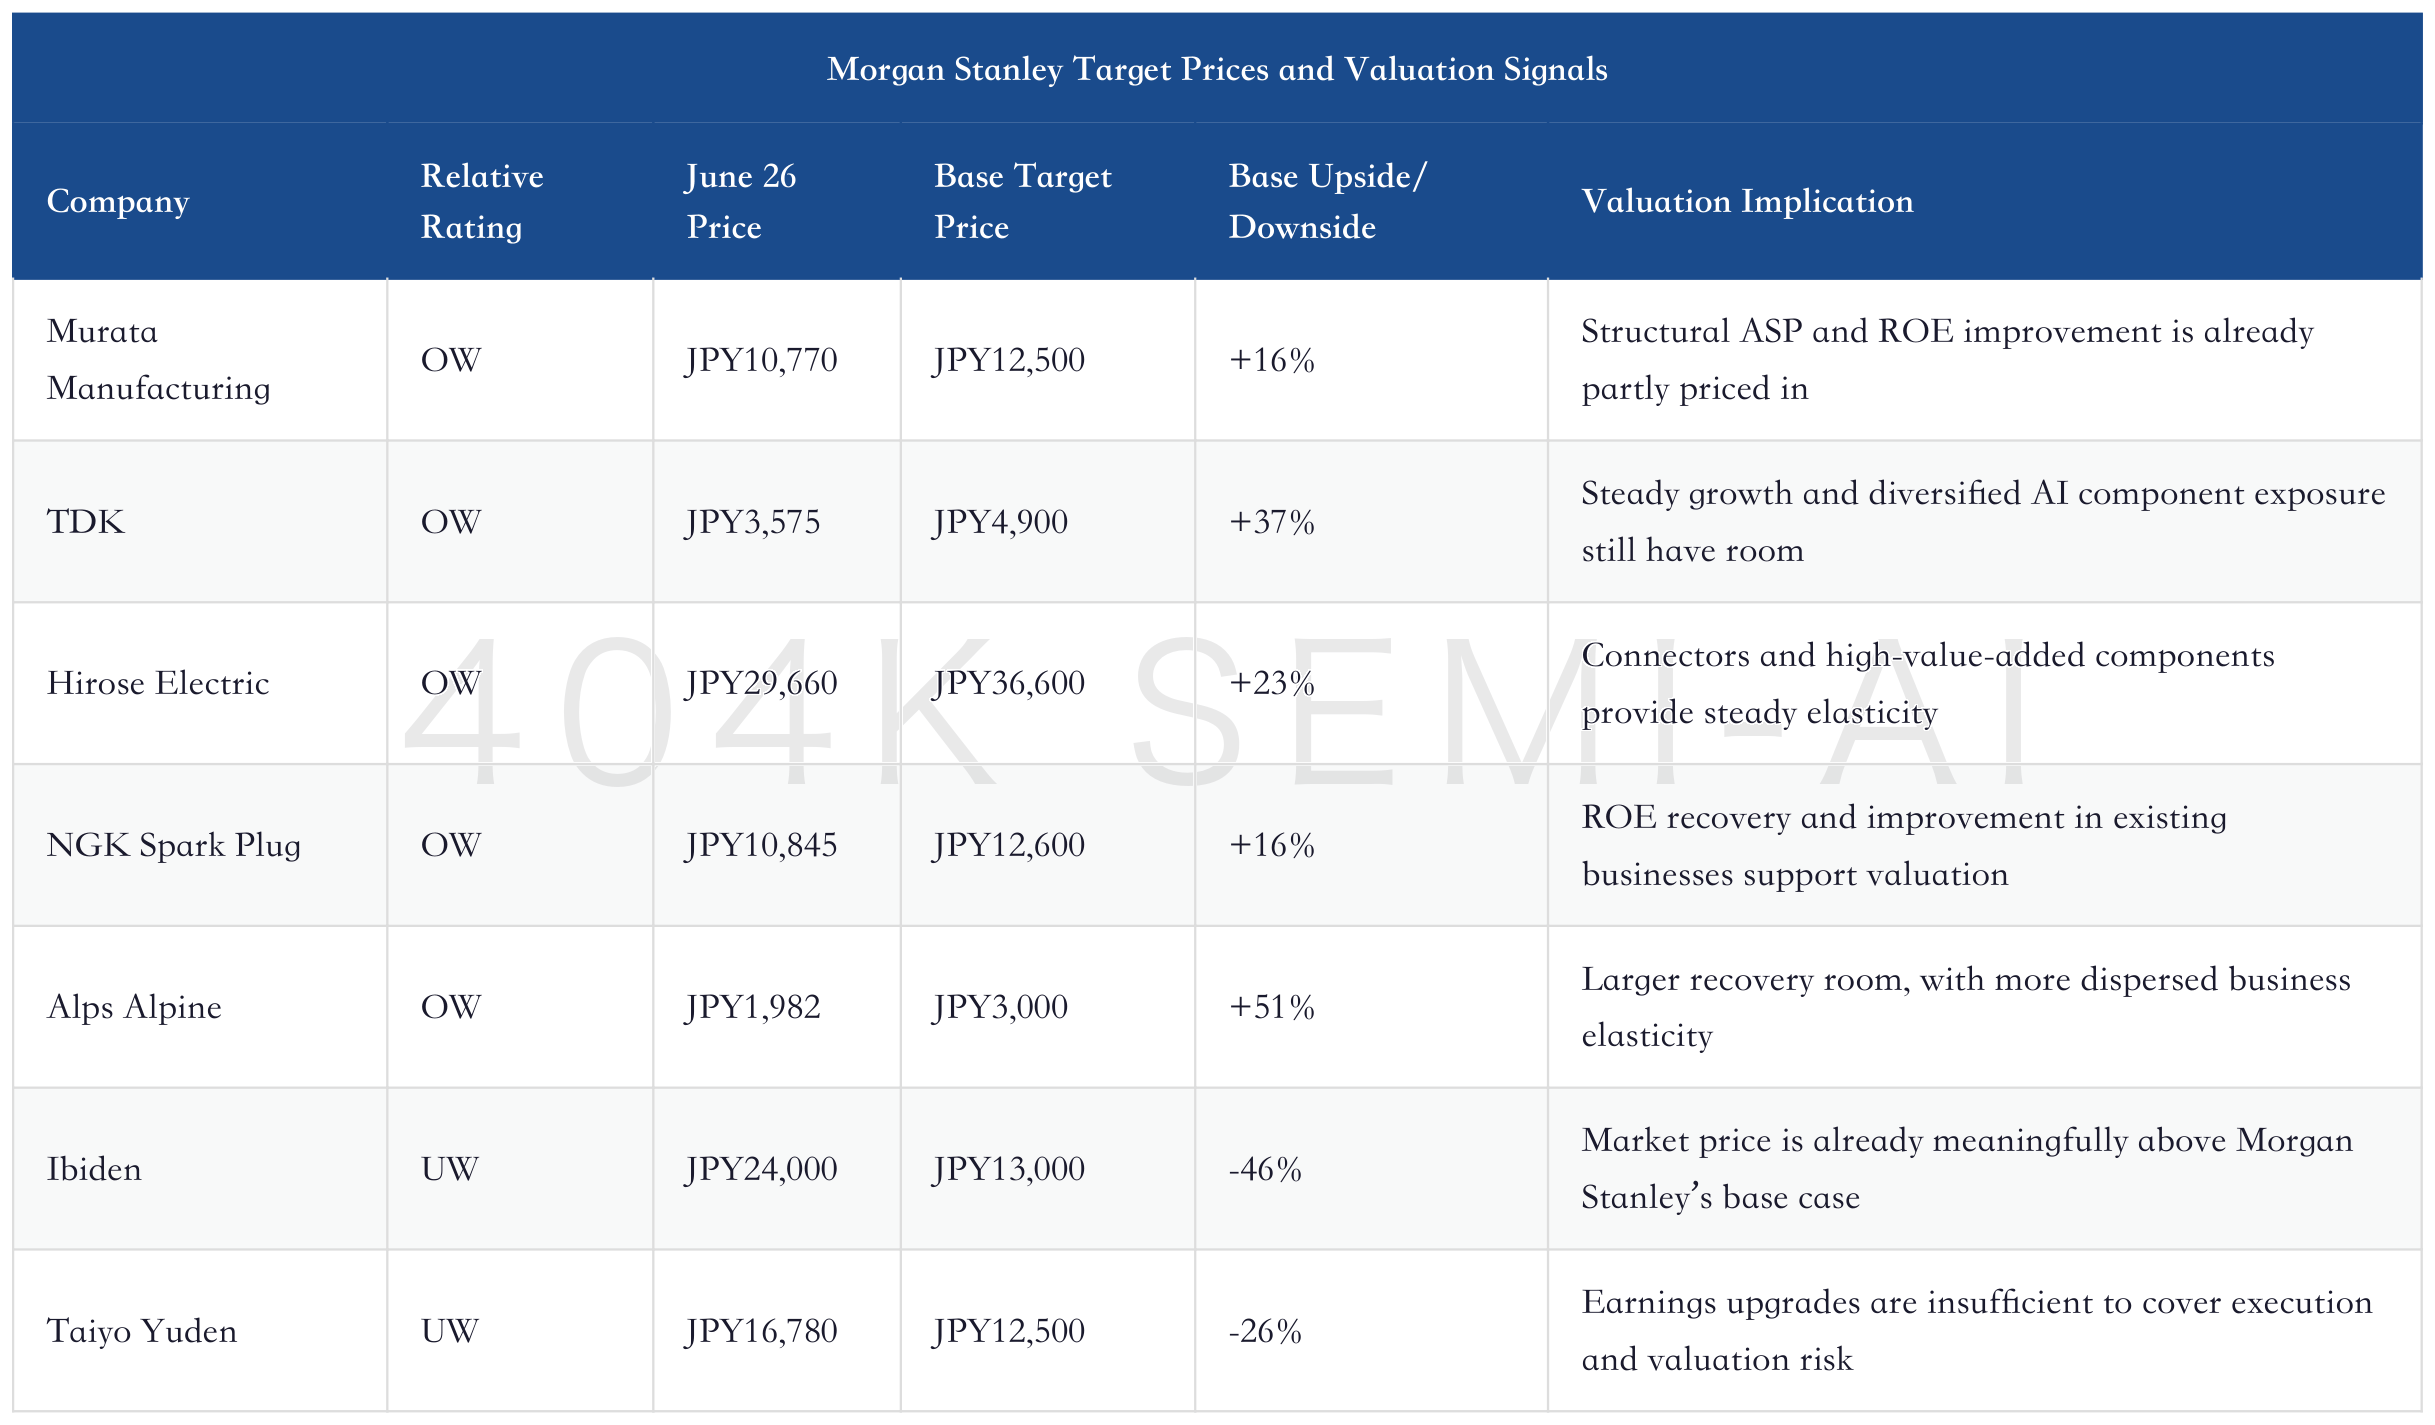
It is important to note that target prices are only model expressions and cannot replace operating verification. For chains such as high-end MLCC and ABF, share prices will react before financial reports, but financial reports will determine whether valuations can remain elevated. Over the next few quarters, the market will care more about gross margin, ROE, cash flow, and inventory, not just revenue.
8. Why the 2018 Playbook Is a Reference, Not a Template for 2026
Morgan Stanley explicitly raised the “differences between the 2018 and 2026 MLCC markets” in its meeting agenda. This is a critical point. The 2017-2018 MLCC upcycle left a strong market memory: smartphones, automotive electronics, industrial control, and restocking resonated at the same time; supply could not expand fast enough; prices rose rapidly; and Japanese and Taiwanese vendors saw margins improve sharply. Many investors naturally use that experience to frame 2026.
The similarity in 2026 is that both supply and demand are tightening. Distribution prices for commodity MLCCs are rising, customers are beginning to accept tighter supply, and delivery pressure is increasing for high-end MLCCs. The difference is that both the demand source and supply constraint are more engineering-driven. 2018 was closer to broad-based demand plus restocking; 2026 is closer to AI servers pushing high-capacitance, small-form-factor, high-reliability products into bottleneck territory. Nominal capacity still exists, but effective capacity is being consumed by more difficult specifications.
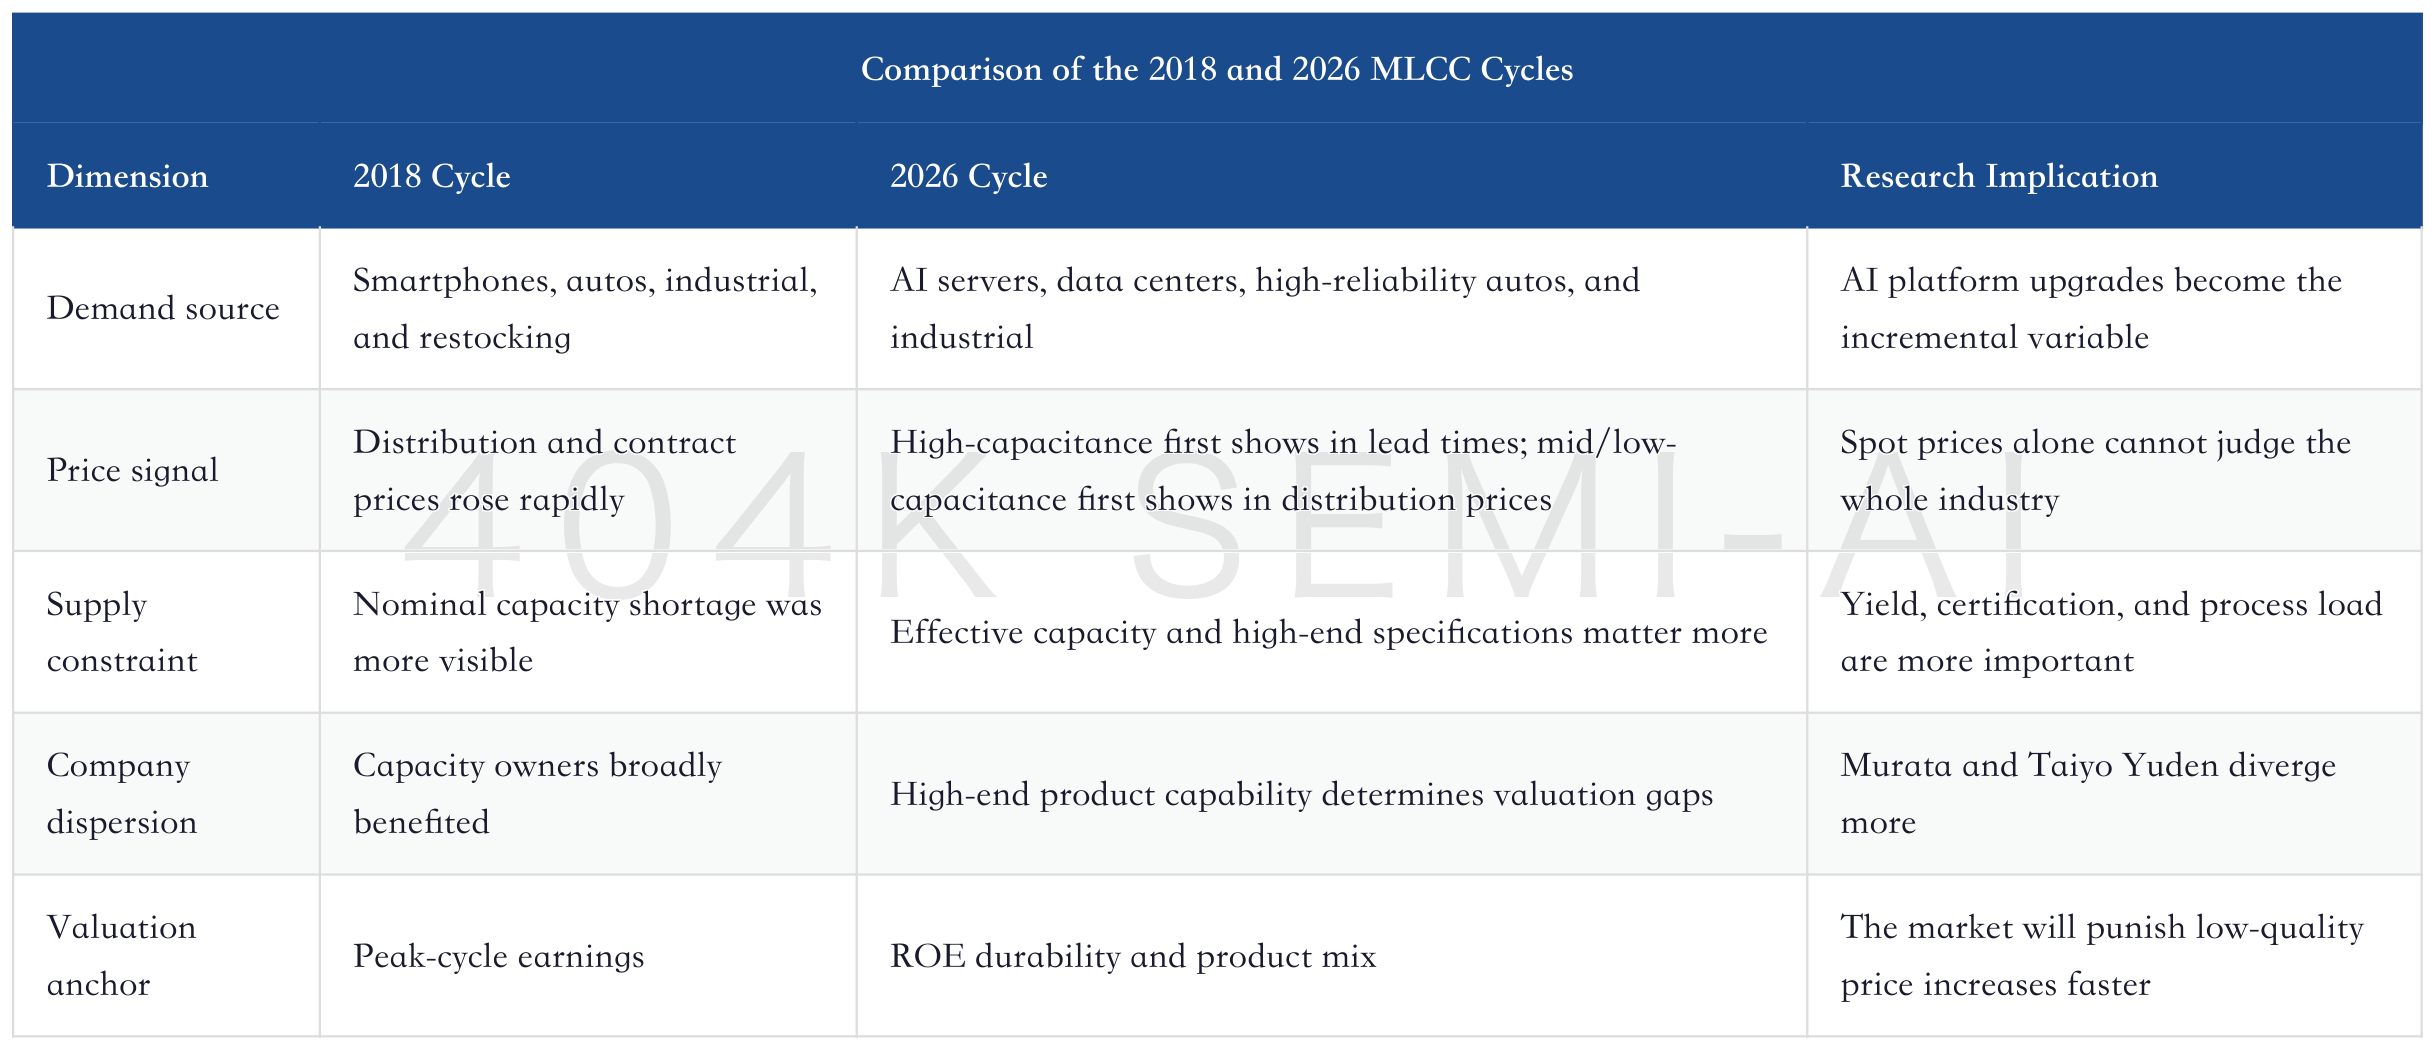
This comparison explains why Morgan Stanley is more positive on Murata. Murata has cost competitiveness in general-purpose products and a high-end product roadmap. It benefits in a price-increase phase and benefits even more in a specification-upgrade phase. Taiyo Yuden and other challengers also have elasticity, but they need to prove effective capacity, yield, and customer qualification. Mid/low-capacitance MLCC vendors will benefit from price pass-through, but their valuations cannot simply be benchmarked against high-end leaders.
For China’s domestic supply chain, the 2018 experience can also only serve as a base case. The last round of domestic substitution mainly focused on cost, supply stability, and mid/low-end capacity expansion. If high-end MLCCs for AI servers become a long-term variable in this round, domestic companies need to prove deeper materials and process capabilities. Materials such as powders, pastes, terminal electrodes, nickel powder, carrier tape, and release film may see utilization and earnings elasticity first, but customer certification for high-end MLCC systems will be slower. Share prices can trade expectations first, but the income statement still needs quarterly verification.
9. Earnings Bridge: Five Gates Between AI Server Demand and Company Value
Strong AI server demand is only the first gate. The real reminder from Morgan Stanley’s research is that the re-rating of electronic components must pass through five gates: demand, specification, mass production, pricing, and financial quality. Each gate can turn what looks like a strong industry story into very different company outcomes.
The first gate is demand. As GPUs, ASICs, AI CPUs, and networking chips continue to upgrade, board-level power delivery and packaging complexity increase, lifting demand for both MLCCs and ABF. The second gate is specification. Customers are not asking for more general-purpose products, but for smaller, higher-capacitance, higher-reliability MLCCs, as well as larger, more complex SAP and higher-yield ABF substrates. The third gate is mass production. Making samples and steadily supplying cloud platform customers are entirely different capabilities.
The fourth gate is pricing. Murata’s pricing comes from a high-unit-price product mix; commodity MLCC pricing comes from spot prices and discount clawbacks; ABF pricing comes from platform complexity and customer delivery pressure. The fifth gate is financial quality. Revenue growth must translate into improvements in gross margin, operating margin, ROE, and cash flow, or valuation will return to a cyclical framework.
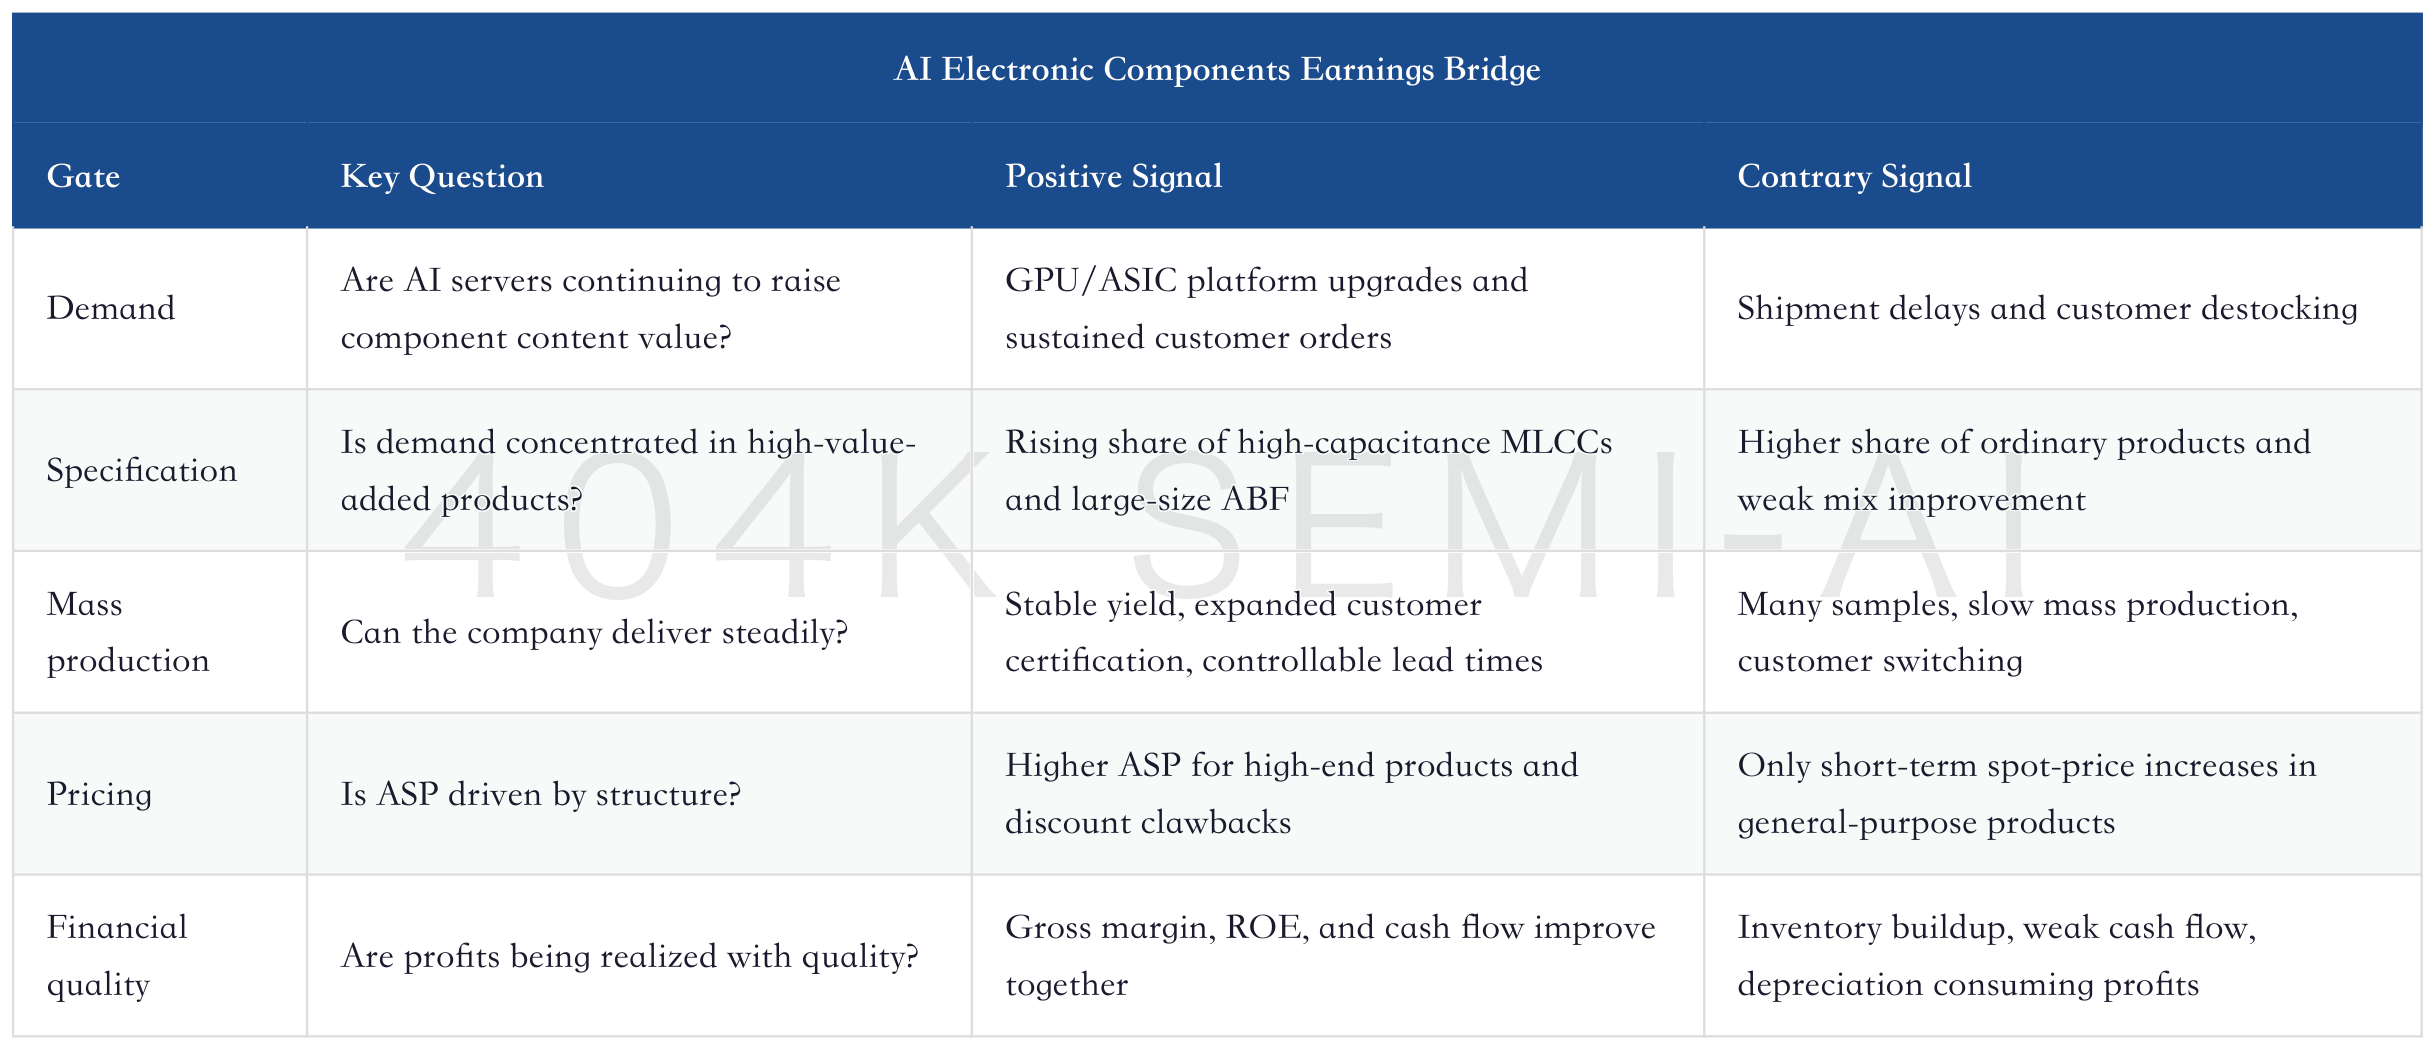
This earnings bridge explains the differences among the three companies. Murata has already passed the demand, specification, and mass-production gates, and is now validating pricing and financial quality. Taiyo Yuden has clear demand, but still needs to prove mass production and capex. Ibiden has clear demand and specifications, and mass production is also advancing; the difficulty has shifted to pricing, depreciation, margins, and valuation.
Therefore, tracking Japanese electronic components cannot focus only on news flow. Strong AI server shipments will bring beta to the entire chain, but what truly determines relative share-price performance is which company can pass the five gates more smoothly. If all companies have only opened the demand gate, the rally will shift from broad-based gains to dispersion. If Murata can continue to open the structural ASP and ROE gates, the valuation gap will keep widening. If Taiyo Yuden and Ibiden also prove financial quality with data, the divergence will narrow.
10. How to Use Sell-Side Divergence: Goldman Talks Demand, Morgan Stanley Talks Discipline, JPMorgan Talks Supply and Demand
There have already been many recent reports on MLCCs, ABF, and Japanese electronic components. Simply lining them up can easily become a stack of institutional views. A better reading is to treat them as a complete puzzle: Goldman Sachs is better at explaining how AI server demand spreads into components and materials; JPMorgan is better at building MLCC supply-demand and pricing models; and Morgan Stanley’s latest work translates survey feedback into valuation discipline and company segmentation.
Goldman Sachs’ earlier Asia investor conference and electronic components reports emphasized the demand opportunity from rising AI server power consumption for MLCCs, PMICs, ABF, and other high-value-added components, and argued that many investors had not fully reflected these profit contributions. JPMorgan’s MLCC report laid out the supply-demand gap, price pass-through, industry TAM, and margin upside more systematically. Morgan Stanley’s latest update does not rebuild the industry model. Instead, it narrows the market discussion to more granular questions: who can capture ASP through product mix, who is merely following price increases, and whose consensus expectations are already too high.
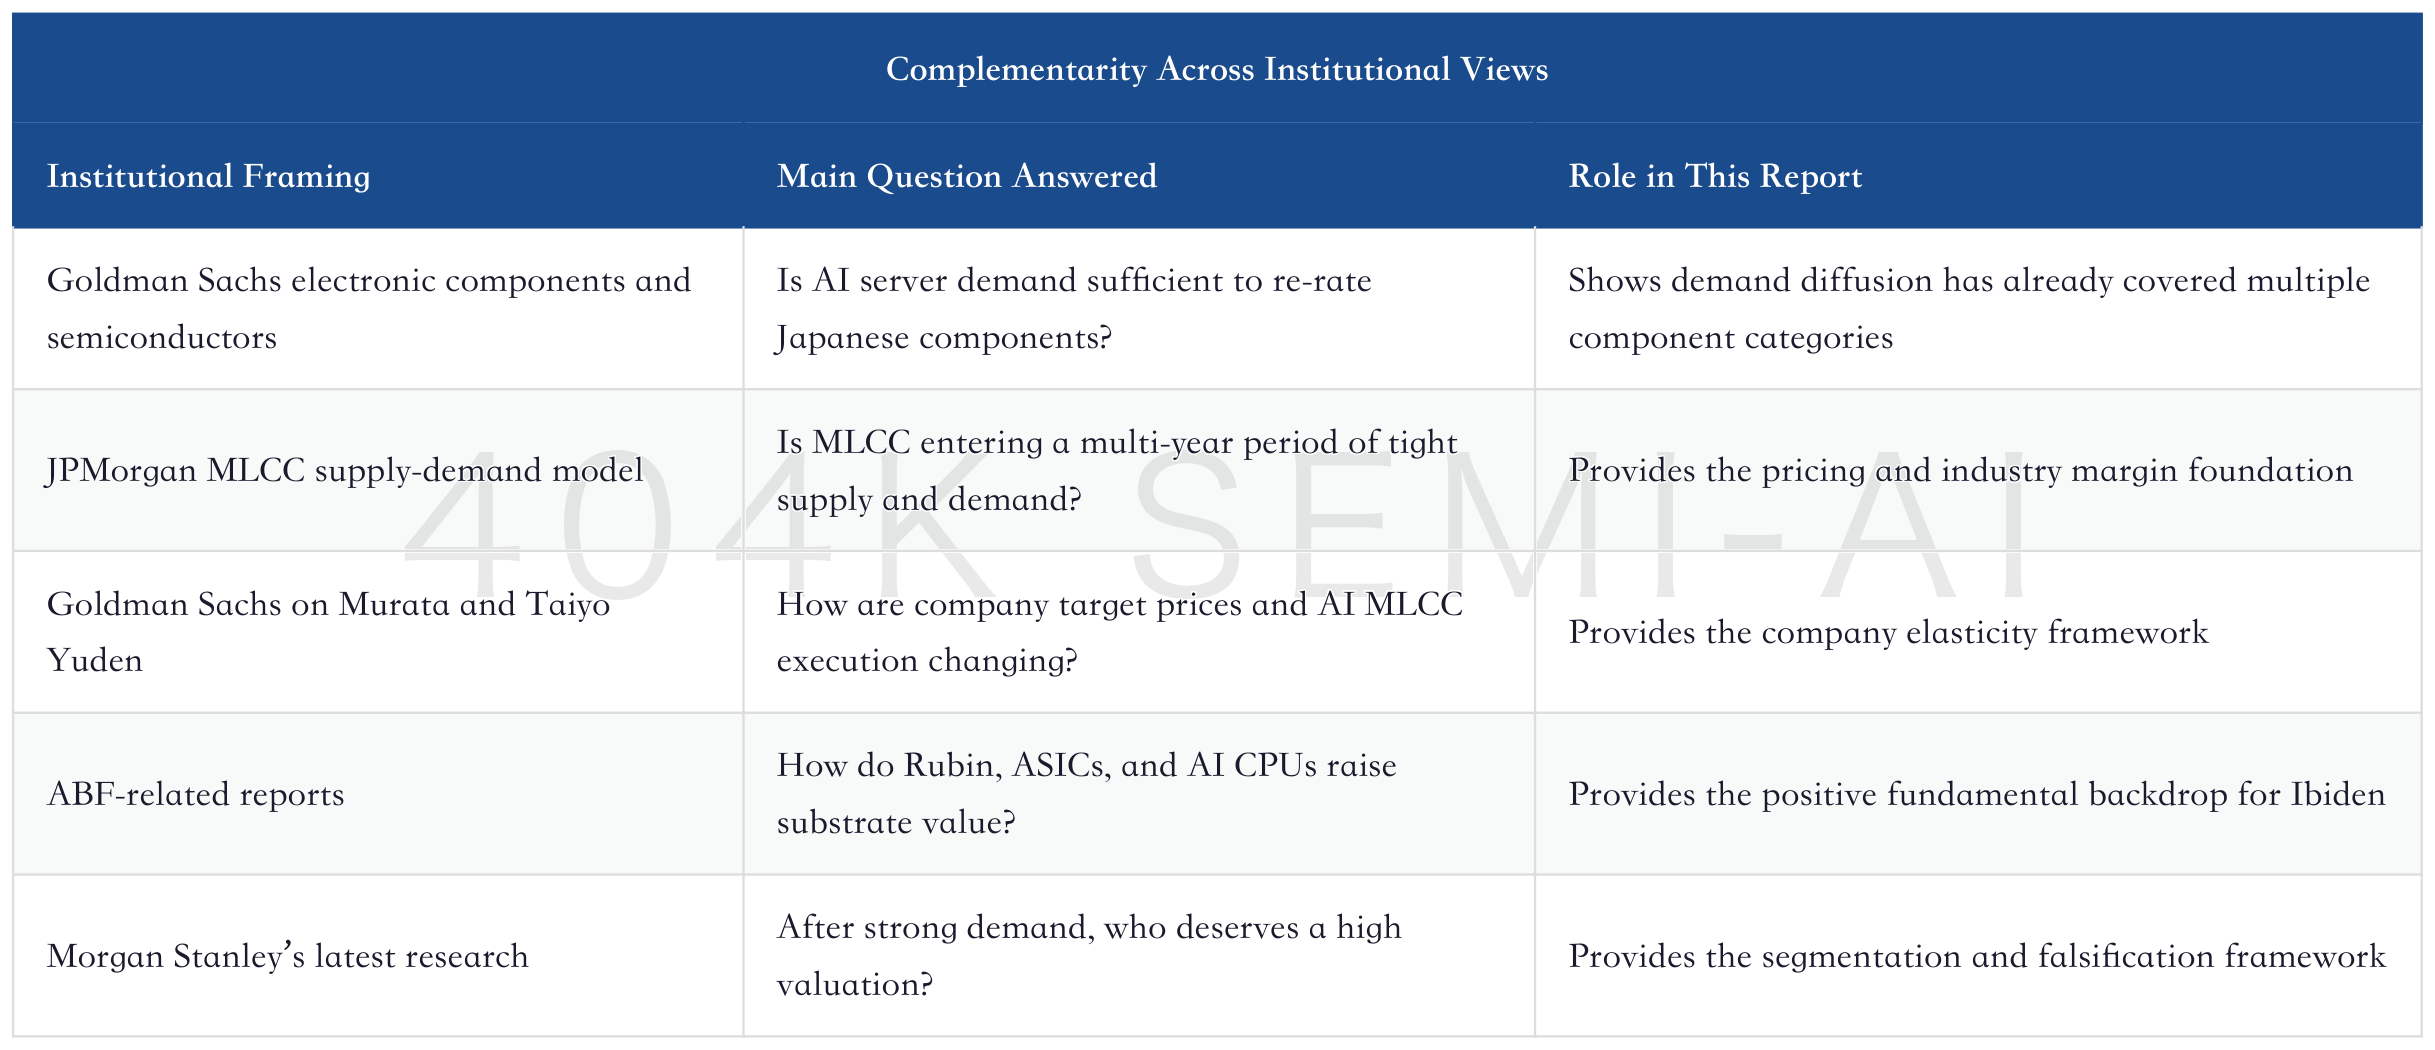
Viewed through this puzzle, the conclusion is more stable. Goldman Sachs and JPMorgan help confirm that MLCC and ABF have indeed entered an AI hardware diffusion cycle. Morgan Stanley reminds us that this diffusion cycle has already been traded once in share prices, and the next phase depends on company execution. The former answers “why there is room”; the latter answers “why we cannot buy every company on the same story.”
This also explains why this report deserves to be written separately. It is not long, but its incremental value is concentrated: investors remain focused on price, while Morgan Stanley’s conclusion focuses on product capability; Murata and Taiyo Yuden are both on the MLCC theme, yet their probability of success has widened; Ibiden sits in a strong ABF cycle, but its valuation is subject to stricter constraints. For future writing and tracking, this is the inflection point from industry momentum to company quality.
11. Data Framework: Target Price, PE, and ROE Should Be Read Together
Morgan Stanley’s target price table can easily be read as a simple upside/downside screen. A more robust reading is to assess target price, PE, P/B, and ROE together. Murata’s base-case target price still implies upside versus the June 26 closing price, but its F26e PE is already very high. What the market is paying for is ROE improvement after F27 and a higher-end product mix. Taiyo Yuden and Ibiden have target prices below their current share prices because Morgan Stanley believes too much future delivery is already embedded in prices, not because they lack fundamentals entirely.
Valuation comparison cannot rely only on PE levels. Murata’s F26e PE is high, but it falls quickly in F27 and F28 as earnings grow, while ROE improvement becomes clearer. Taiyo Yuden’s PE is also high, but its pace of ROE improvement and certainty in high-end products are weaker than Murata’s. Ibiden has a high PE and high P/B, while its ROE improvement also needs a longer cycle to prove out. The market has already assigned substantial weight to Rubin and EMIB-T.
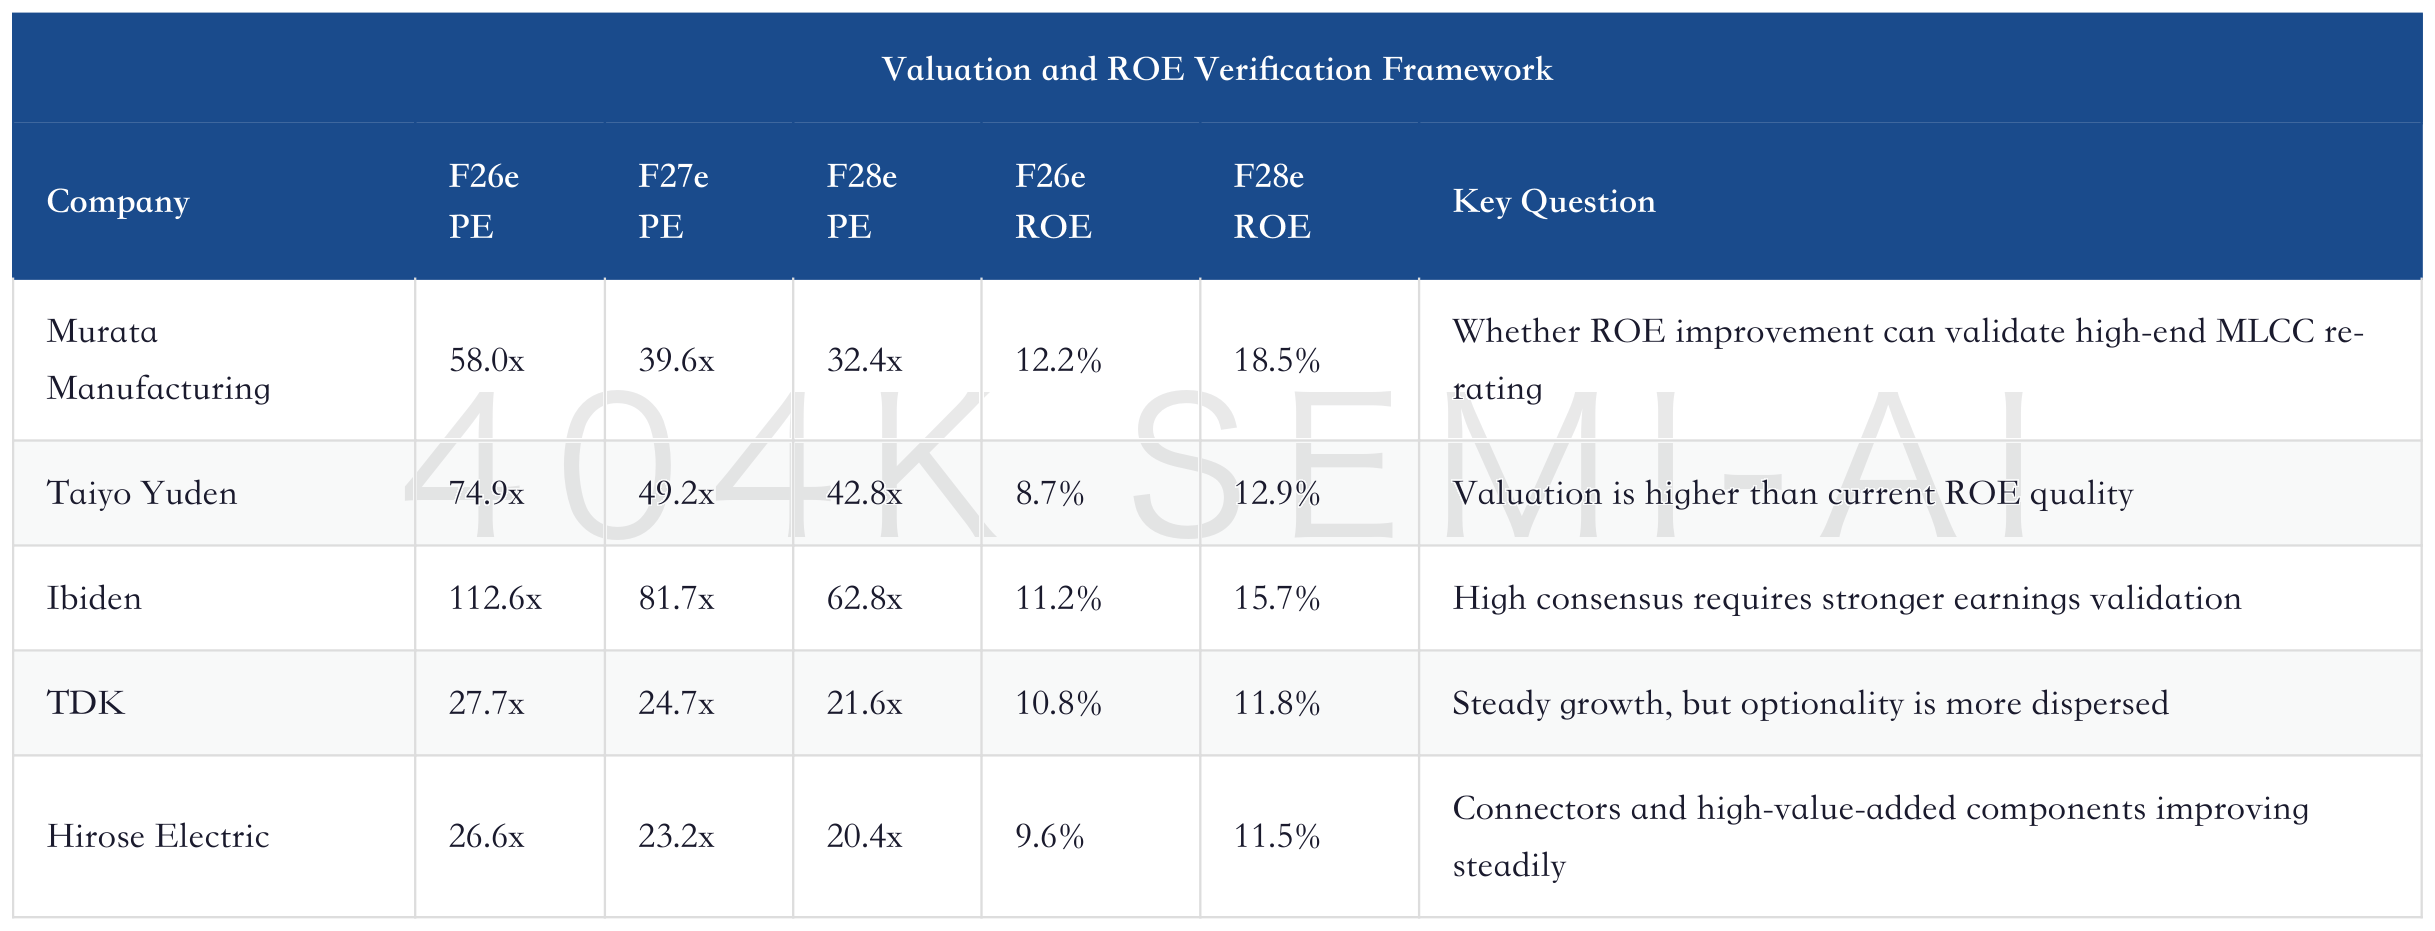
The table is straightforward to read. Murata is expensive, but it has a relatively clear upward ROE trajectory. Taiyo Yuden and Ibiden are also expensive, with higher execution difficulty. TDK and Hirose do not have the same extreme AI leverage, but their valuations and ROE profiles are more balanced. If the market enters a stricter risk appetite environment, assets with stable ROE will be more resilient. If AI server supply and demand continue to exceed expectations, high-beta assets will rise first, but they are also more vulnerable to pullbacks if financial results fail to validate the story.
FX assumptions should also be incorporated into the model. Morgan Stanley uses a relatively weak yen as its F26e average assumption. For the industry overall, operating profit has mid-single-digit sensitivity to USD/JPY movements. Murata, Taiyo Yuden, and Ibiden have different FX sensitivities, as shown below. The conclusion is that yen movement is a second-order variable, but it affects quarterly profits and market sentiment, especially for companies such as Taiyo Yuden with higher margin sensitivity.
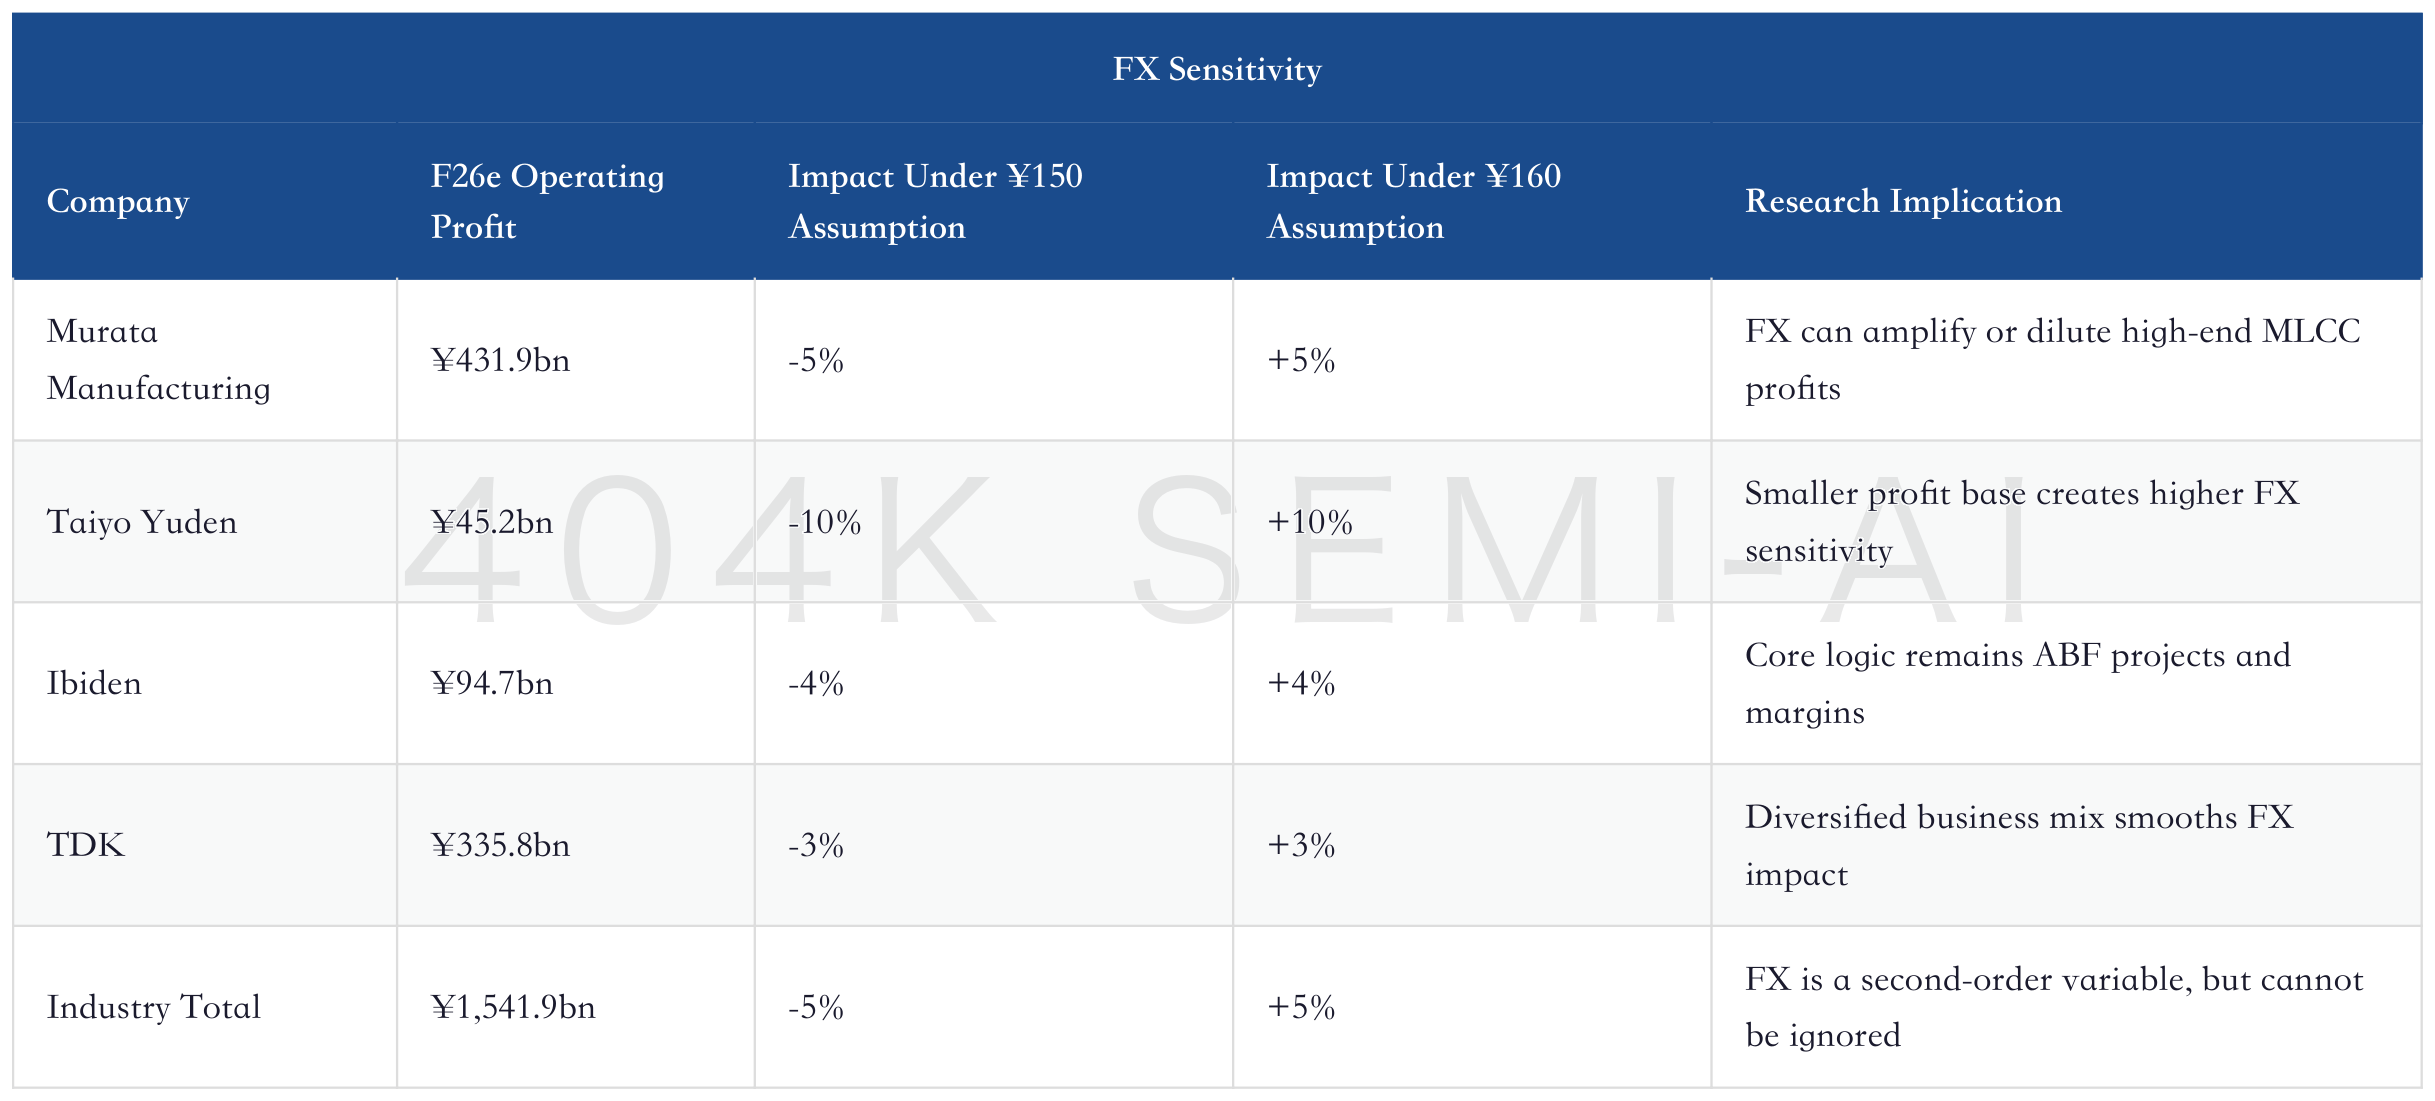
For readers, target price is only the model output. The real answer lies in the operating profit, ROE, FX assumptions, and product mix behind that target price. Murata’s target price requires the AI/DC MLCC share to keep rising. Taiyo Yuden needs to prove high-end mass production and capex decisions. Ibiden needs to prove that Rubin and EMIB-T can generate high-quality profits.
12. Three Worldviews: High-End MLCC Wins, Commodity Price Increases Spread, ABF Is Re-Validated
Japanese electronic components can be tracked through three worldviews.
The first worldview is that high-end MLCC wins. AI servers continue to raise power density, and customers are willing to pay for small size, high capacitance, high reliability, and stable delivery. Murata maintains its lead, while Samsung Electro-Mechanics and Taiyo Yuden catch up but struggle to close the gap quickly. In this scenario, Murata remains the strongest main line. Materials and domestic high-end MLCC have long-term read-through, but the valuation ceiling for companies benefiting only from low- to mid-end price increases is limited.
The second worldview is that commodity price increases spread. Spot and contract prices for low- to mid-capacitance MLCC continue to rise, inventories remain healthy, and standard specifications also begin flowing into the income statement. This scenario benefits more companies, including Taiwanese, Korean, domestic MLCC, and materials companies. The risk is that broad-based price increases are more likely to attract new capacity, so valuation durability requires support from inventory and cash flow.
The third worldview is that ABF is re-validated. Rubin, ASIC, and AI CPU continue to increase ABF content value, benefiting Ibiden, Taiwanese ABF producers, and the Korean FC-BGA supply chain. But the market is already trading high-end substrate assets at very high prices. From here, investors must see gross margin, depreciation absorption, and customer project delivery. In this scenario, the ABF trade will not disappear, but stock-level volatility will be greater.
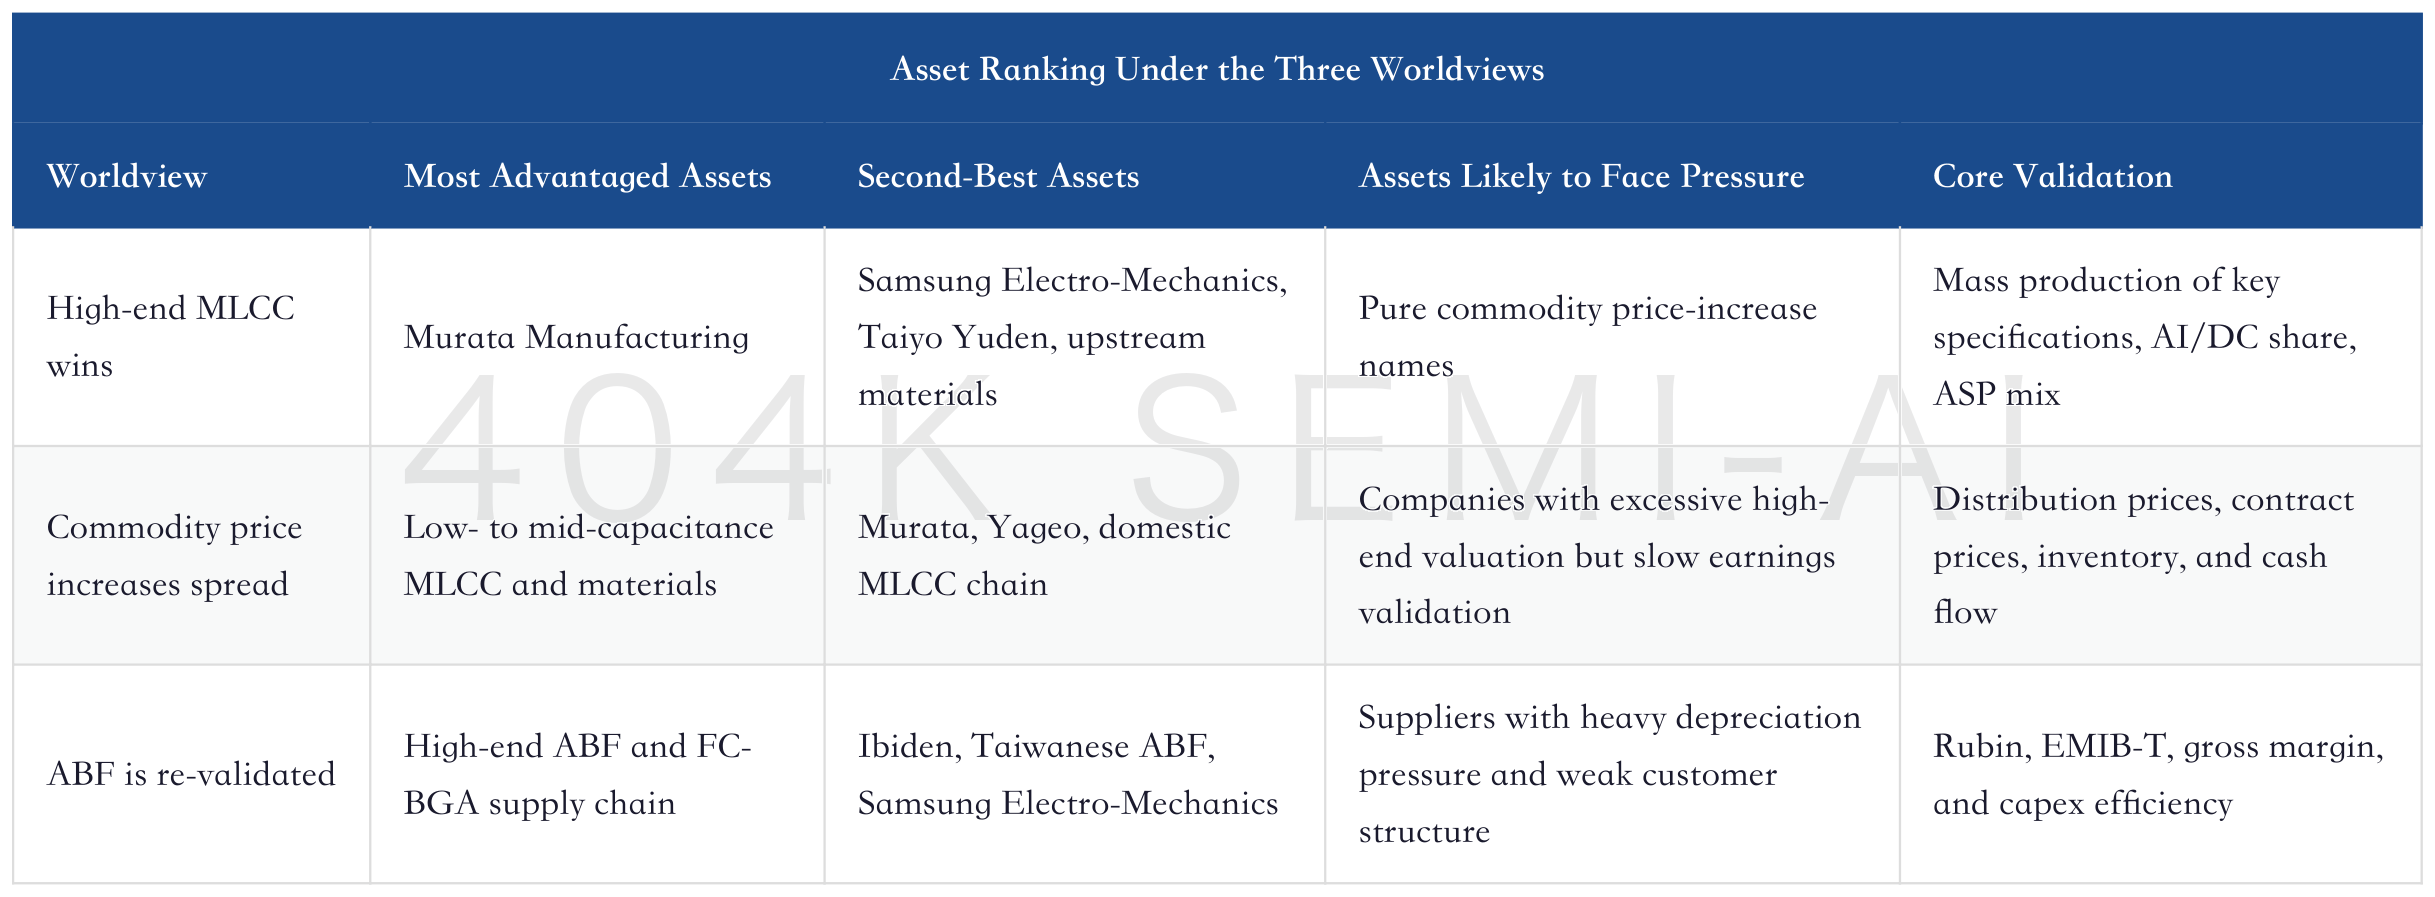
These three worldviews are not mutually exclusive. The best industry state is one in which high-end MLCC, commodity price increases, and ABF all materialize at the same time. The worst state is one in which demand remains strong but profit quality diverges, with only a few companies capturing truly high-quality profits. The current state is closer to the middle: the high-end MLCC logic is clearest, commoditized price increases are emerging, and ABF remains strong but faces the greatest valuation validation pressure.
This is also why the title puts MLCC and ABF together. Both lines come from AI servers, but they are at different pricing stages. The focus for MLCC is shifting from the spread of price increases to product mix. The focus for ABF is shifting from strong demand to whether consensus is too high. Together, they form the next round of differentiation in Japanese electronic components.
13. Asia and A-Share Read-Through: Look First at Specification Tickets, Then at Price Spillover
Although this Morgan Stanley report focuses on Japanese companies, it has substantial value for Asia and A-share read-through. It reframes the research sequence for MLCC and ABF from “who is in the supply chain” to “who has the specification ticket.” This will affect the valuation approach for domestic passive components, ceramic materials, electronic paste, carrier tape, release film, nickel powder, PCB materials, and package substrates.
For the A-share MLCC and materials chain, the first read-through is price spillover. Rising distribution prices for commoditized MLCC, recovery of customer discounts, and utilization improvement will first transmit to domestic MLCC platforms such as Fenghua Advanced Technology, and also to materials names such as Sinocera, Jiemi Technology, and Boqian New Materials. Their short-term earnings leverage mainly comes from demand recovery, price increases, and utilization. This leverage is important, but quality needs to be verified through inventory and cash flow.
The second read-through is the high-end specification ticket. If companies such as Chaozhou Three-Circle and Sinocera are to move from cyclical recovery to AI server re-rating, they need to prove capabilities in high-reliability ceramic materials, high-end powders, electronic paste, and customer qualification. What is truly scarce in AI server MLCC is small size, high capacitance, high reliability, and stable mass production. Simply expanding low- to mid-end capacity cannot substitute for this. If domestic companies can enter high-end specification validation, their valuation ceiling will rise. If they remain limited to ordinary price increases, their valuation will look more like cyclical products.
The third read-through is ABF and PCB materials. Ibiden’s example reminds us that even scarce AI packaging and substrate assets are still constrained by margins, depreciation, and customer structure. A-share and Taiwan-share companies in ABF, BT, CCL, fiberglass cloth, copper foil, and high-end PCB need a similar framework: strong demand is only the starting point. Ultimately, the key variables are yield, customer qualification, price pass-through, material lock-in, and cash flow.
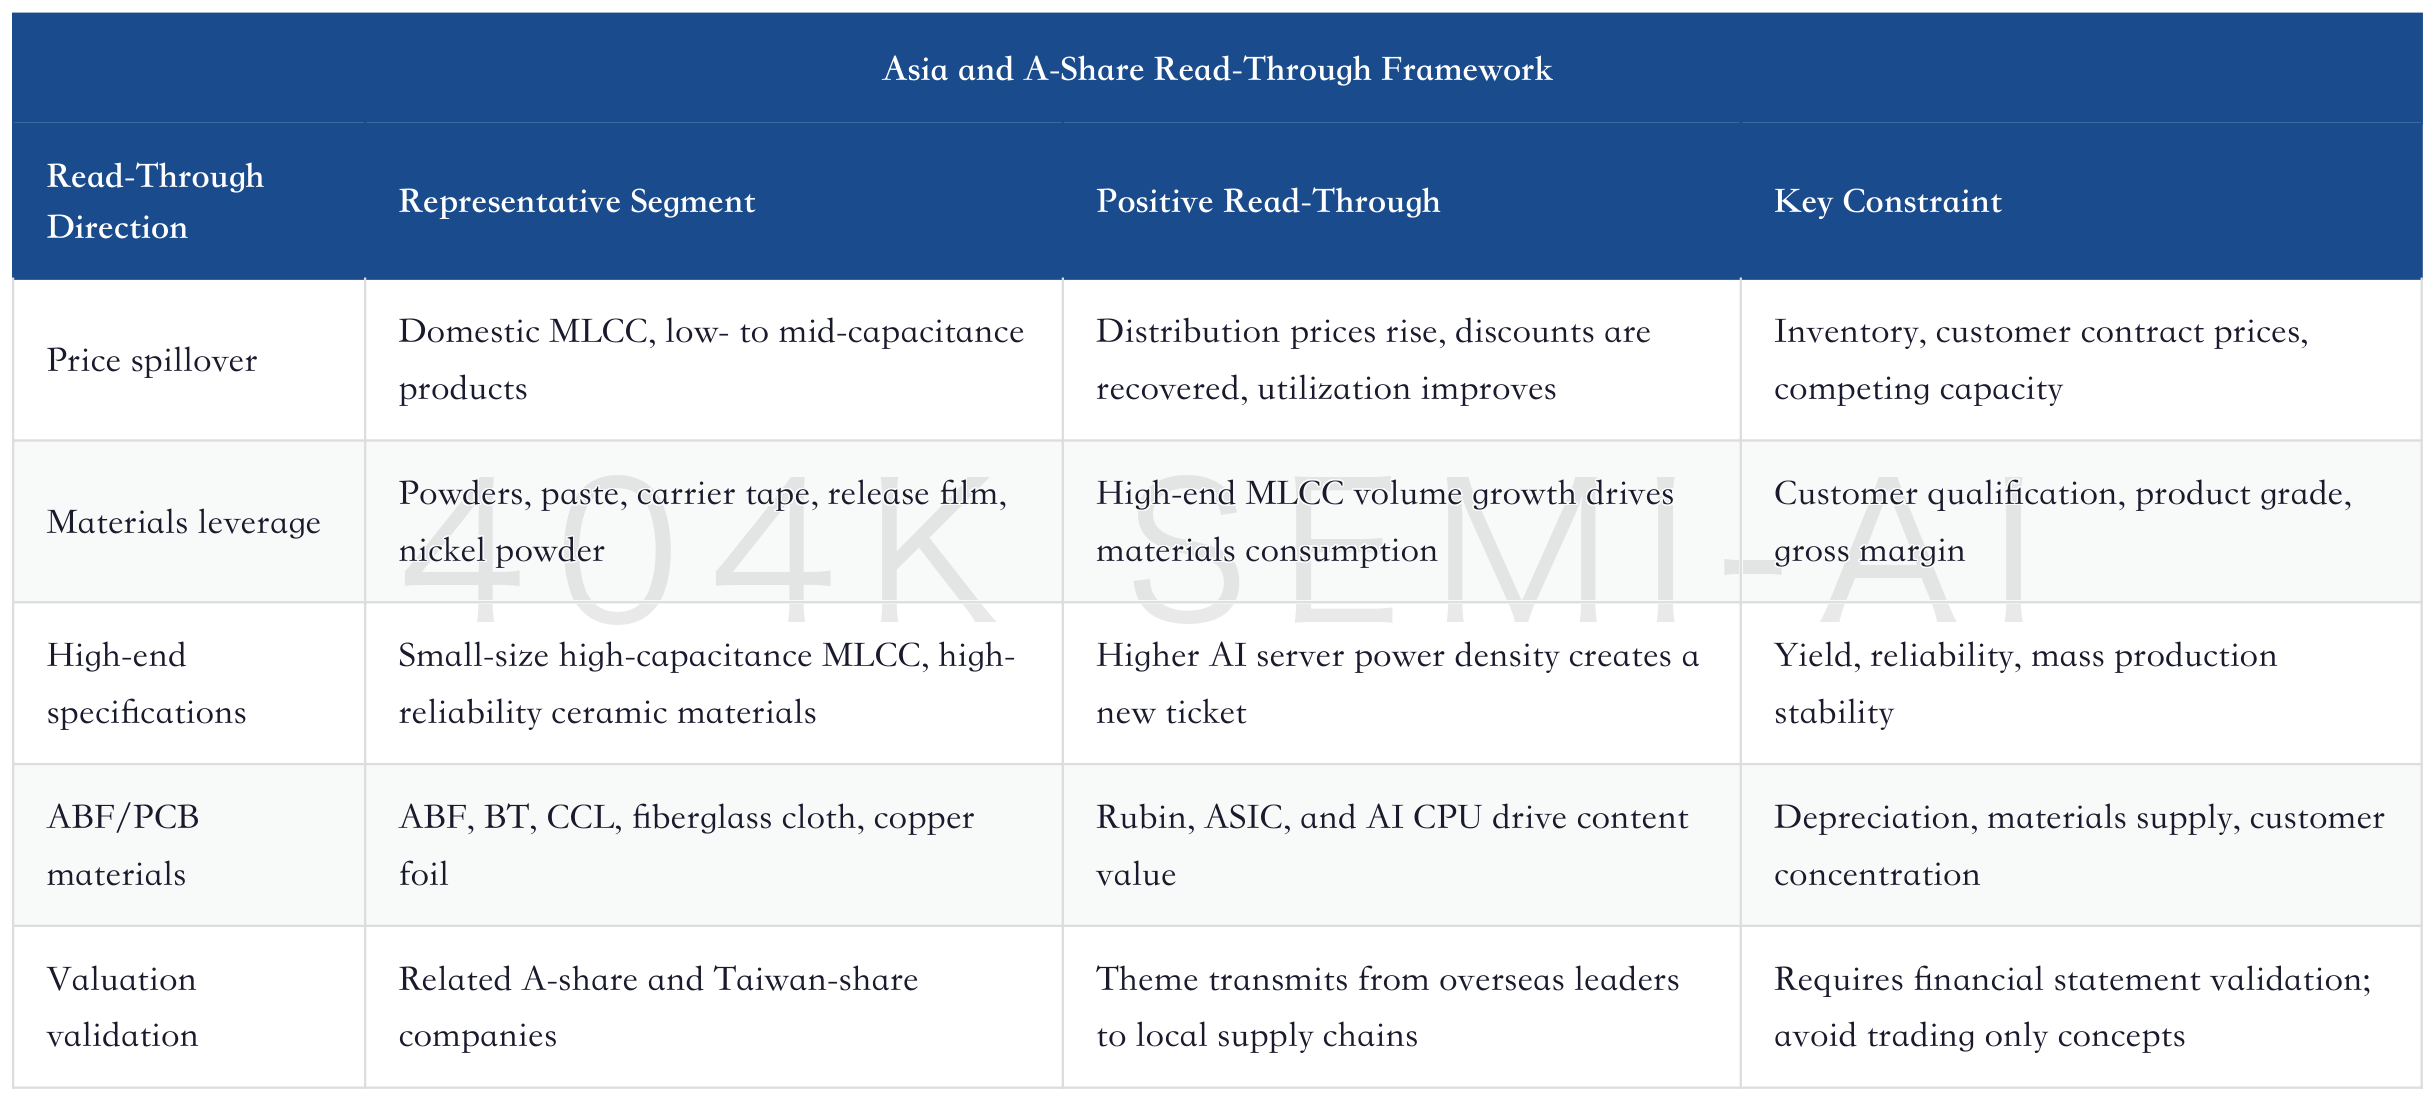
This mapping also helps avoid placing all companies in the same basket. Fenghua Advanced Technology is more of a domestic MLCC platform and cyclical recovery story. Chaozhou Three-Circle is more about electronic ceramics and high-end MLCC capability. Sinocera is more exposed to powders and electronic paste. Jiemi Technology is more geared to consumables and carrier tape. Boqian New Materials is more exposed to nickel powder materials. They may all benefit, but the valuation question differs: companies that can move from price increases into high-end specifications are closer to the Murata-style logic; companies that can only benefit from ordinary price spillover are closer to the cyclical recovery logic.
14. Tracking Checklist for the Next Four Quarters
The most important task over the next four quarters is to translate the news flow back into verifiable metrics. Themes such as strong AI server demand, MLCC price increases, and Rubin volume ramp will recur, but what ultimately determines valuation is continuous evidence from company financials and customer programs.
First, monitor Murata’s AI/DC MLCC revenue mix. Whether F3/27 can move toward the 20-25% range is central to whether structural ASP uplift can be realized. Second, monitor mass production of key specifications. If Murata continues to lead stably in products such as 1608 100µF, 1005 47µF, and 0603 10µF, the valuation gap will widen; if Taiyo Yuden and other manufacturers catch up faster, the profit pool will be redistributed. Third, monitor Taiyo Yuden capex. It needs to strike a balance between avoiding overinvestment and capturing the high-end window.
Fourth, monitor pass-through of price increases in commodity MLCCs. Rising distribution prices are only an early signal; contract prices, discount recapture, inventory value, and cash flow are more important. Fifth, monitor Ibiden’s Rubin and EMIB-T. Rubin sales exceeding Blackwell is only the beginning; gross margin, depreciation absorption, and the timing of EMIB-T contribution matter more. Sixth, monitor FX. Yen movements will affect quarterly profits, especially amplifying earnings volatility for smaller-base companies such as Taiyo Yuden.
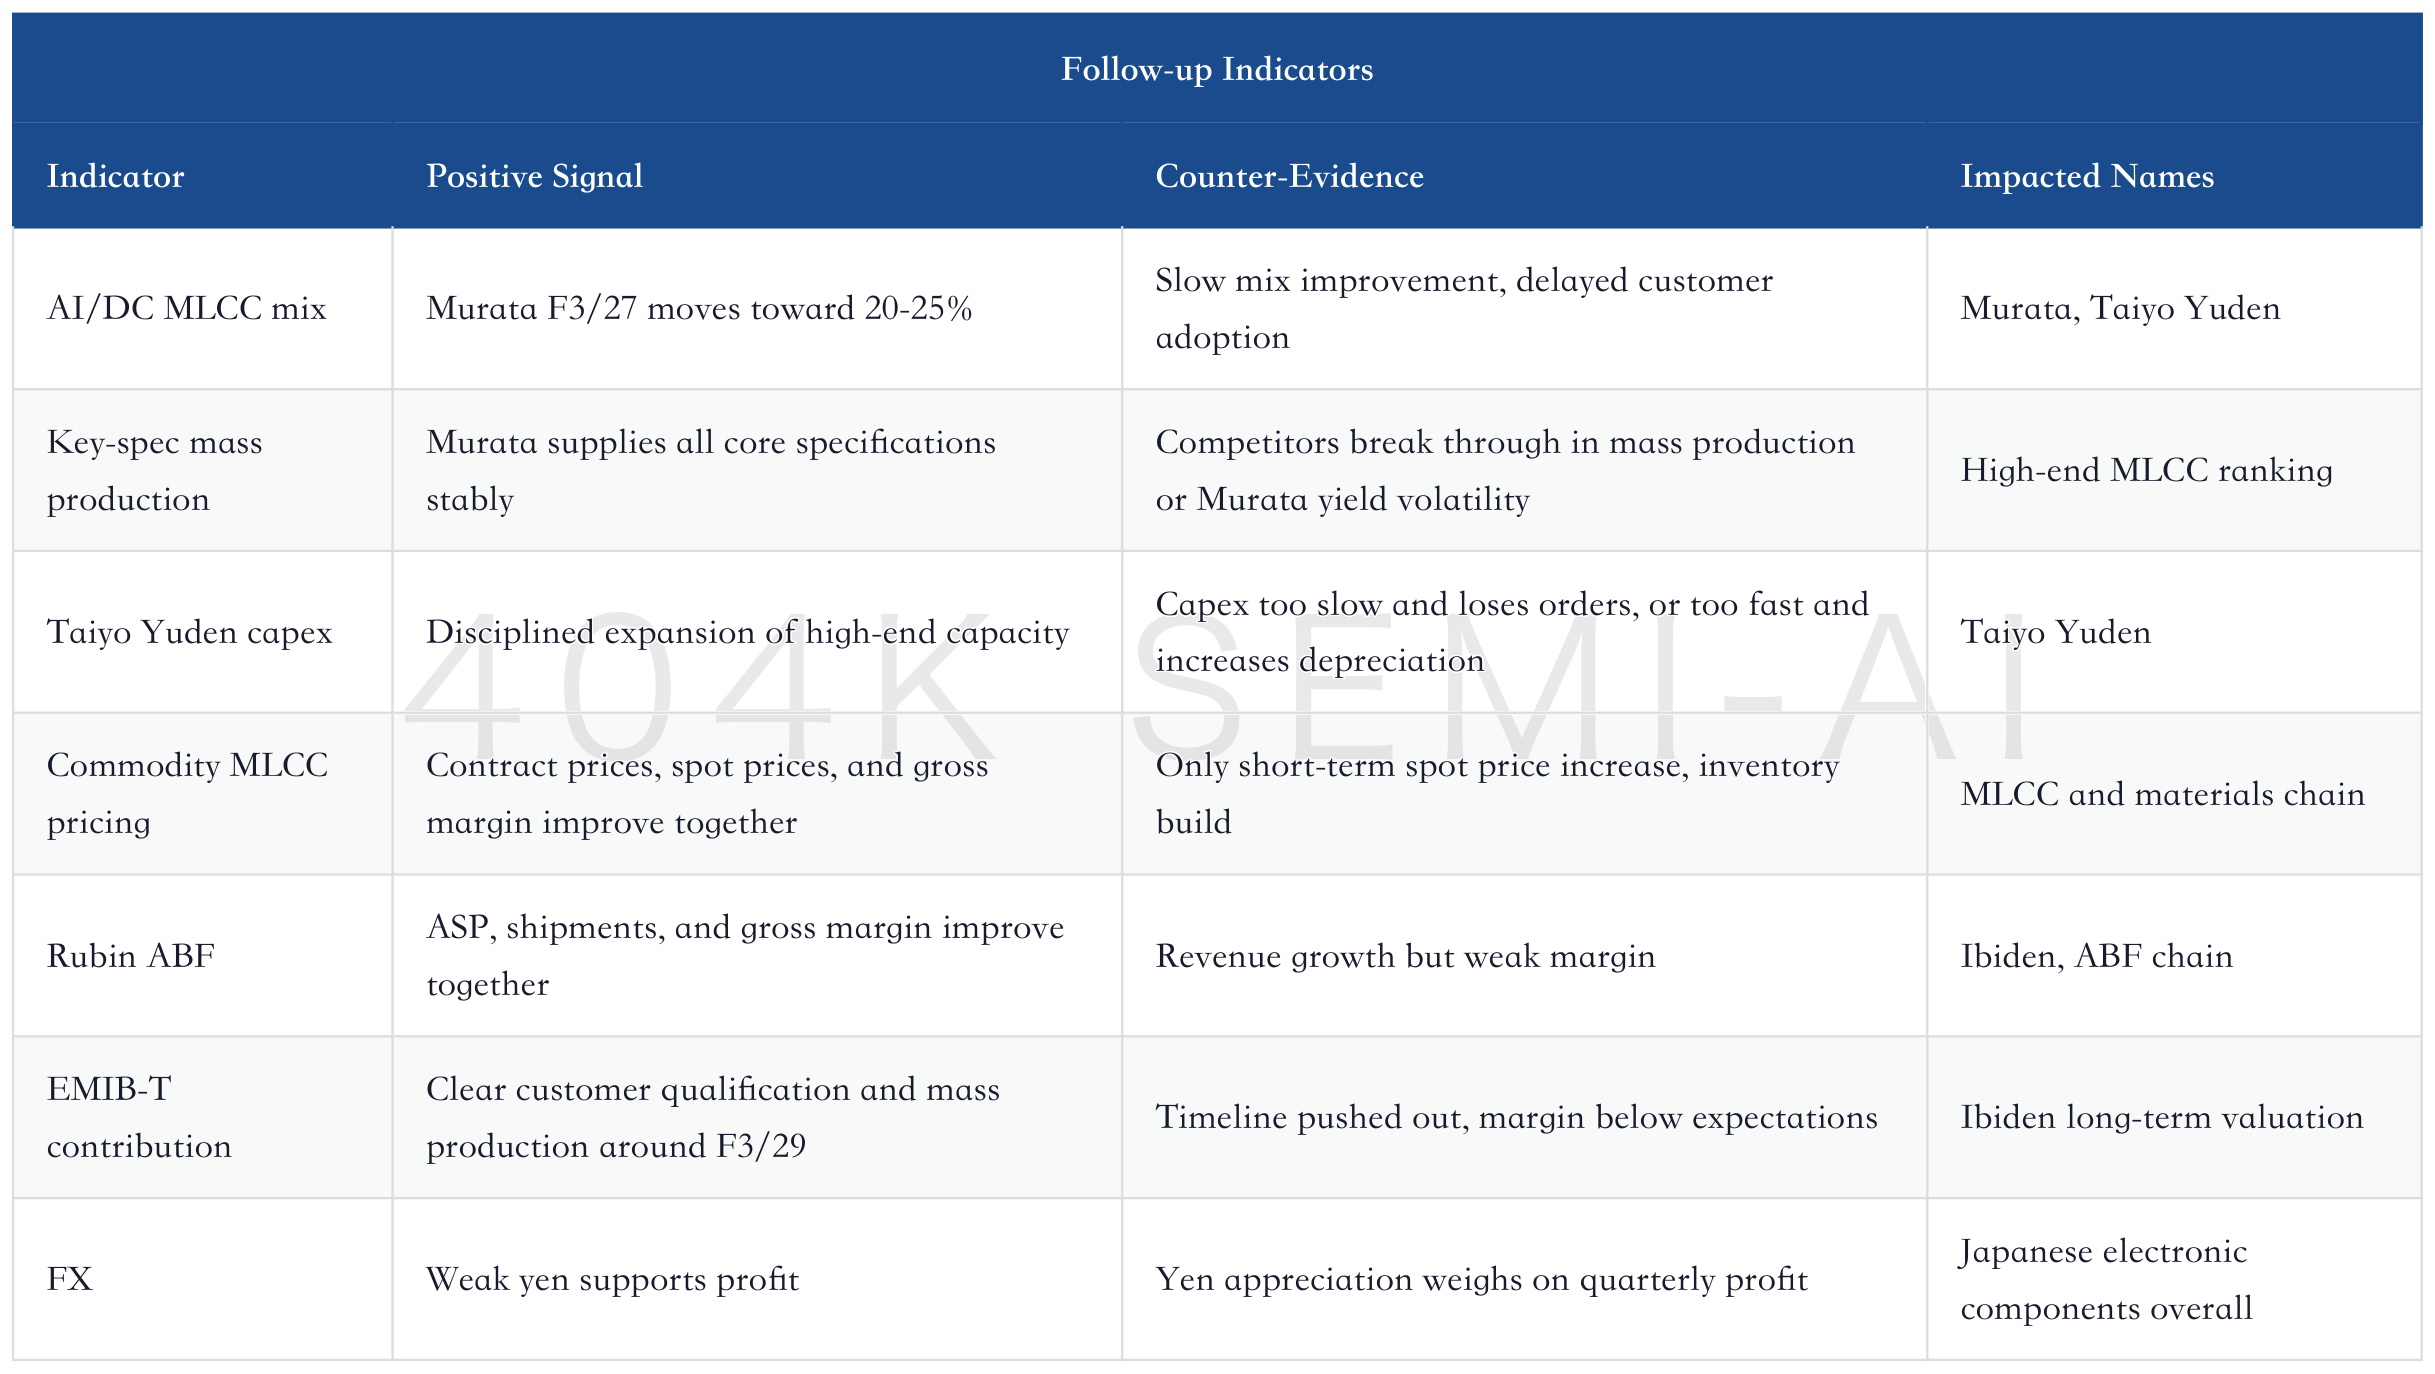
The sequence also matters. Prices and orders change first, gross margin validates later, inventory and cash flow move more slowly, while customer qualification and capex efficiency are slower still. If all indicators improve in the same direction, electronic components will continue to be re-rated from cyclical products into AI hardware infrastructure. If prices rise first, inventories build later, and cash flow fails to keep up, the trade will revert from structural re-rating to cyclical trading.
15. Risk Breakdown: The Biggest Concern Is Right Demand, Wrong Company, Expensive Valuation
The biggest risk in this theme is “right demand, wrong company, expensive valuation.” Strong industry demand does not mean every company can secure high-end qualification. Winning orders does not mean margins can be realized. Rising gross margin does not mean cash flow is healthy. Japanese electronic components have already rallied, and the market will punish companies with insufficient validation more quickly.
The first category of risk is technology catch-up. If Taiyo Yuden, Samsung Electro-Mechanics, or mainland Chinese manufacturers accelerate catch-up in key high-end MLCC specifications, Murata’s structural ASP and high-end share will be compressed. This risk does not carry a high near-term weight, but it needs continuous monitoring.
The second category is inventory and pricing mismatch. If commodity MLCC price increases come only from channel expectations, subsequent inventory build will quickly compress gross margin. A genuinely healthy price increase should come with simultaneous improvement in customer demand, lead times, contract prices, and cash flow.
The third category is high consensus in ABF. Ibiden’s Rubin and EMIB-T are both real variables, but market expectations are already high. If F3/28 operating profit moves closer to Morgan Stanley’s forecast, deviating from company targets and FactSet consensus, the stock will first see valuation de-rating.
The fourth category is FX and costs. Yen appreciation, rising material costs, and energy and wage pressure could all affect quarterly profit. High-end products can partially offset cost pressure, while commodity products are more easily squeezed.
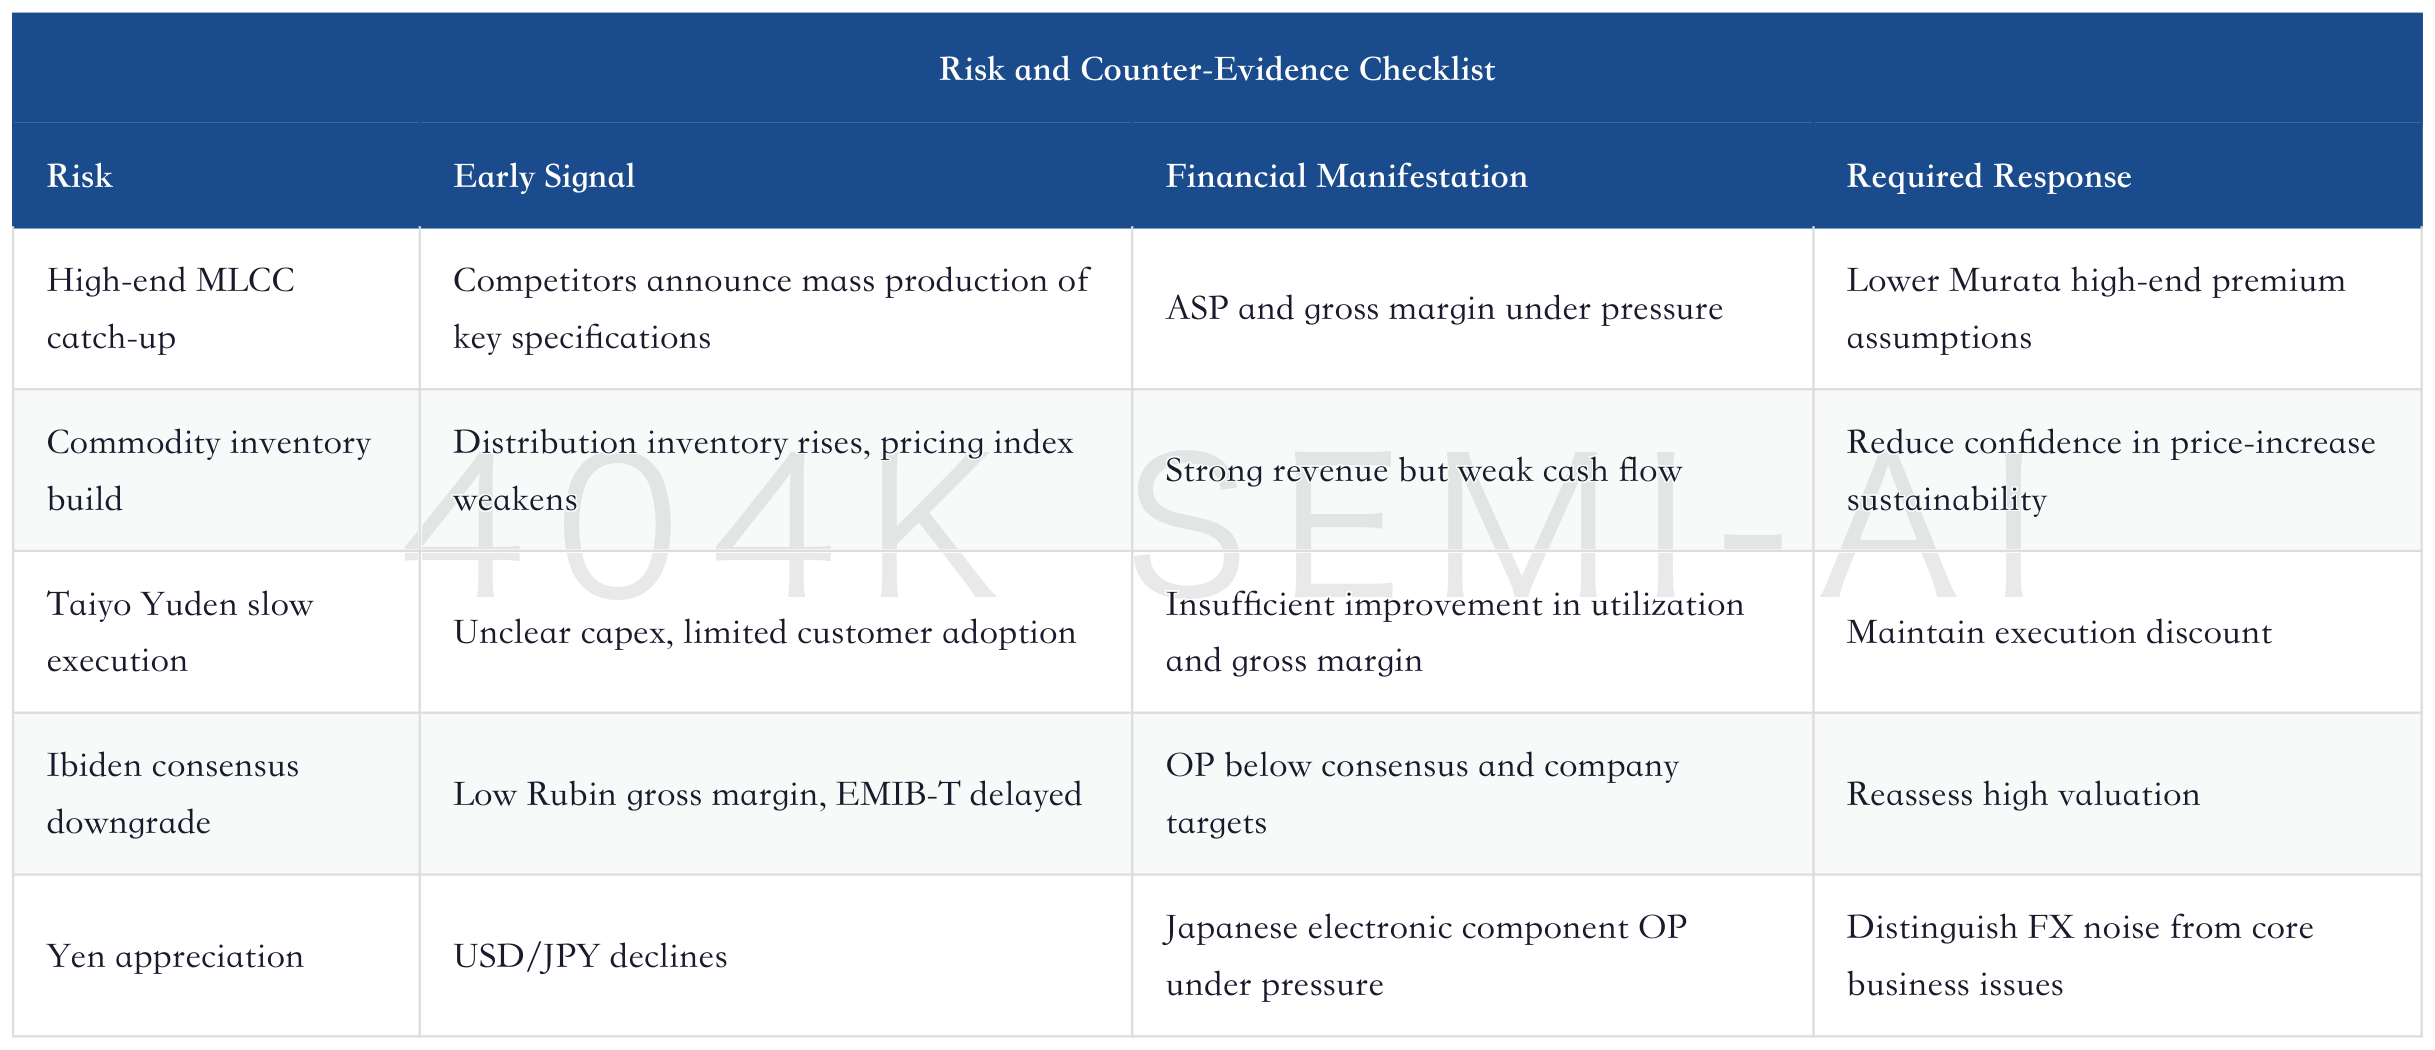
These risks do not change the main line that AI servers are driving electronic components, but they will change relative company performance. Good industries can still produce bad trades, and strong demand can still generate low-quality profits. The most important value of Morgan Stanley’s research is that it reminds the market to break “AI beneficiary” into five questions: product, mass production, price, profit, and valuation.
16. Conclusion: AI Electronic Components Enter the “Product Capability Realization Period”
Japanese electronic components have moved from the AI hardware diffusion phase into the product capability realization period. Morgan Stanley’s Asia investor survey shows that investors remain highly focused on MLCC and ABF, but the market most easily overlooks that price increases and demand do not automatically translate into long-term corporate value. What truly widens valuation gaps is high-end specifications, stable mass production, customer qualification, ROE, and cash flow.
Murata has the highest probability of winning in this theme. Its high-end MLCC growth comes from AI server product mix, not simple price increases for the same specifications. Its capabilities in materials, layering, external electrodes, and mass production make it easier to convert AI demand into structural ASP uplift. Taiyo Yuden also has upside, but it needs to use capex, mass production, and customer adoption to prove it can keep up with high-end platforms. Ibiden remains in the ABF upcycle, and Rubin and EMIB-T will continue to bring incremental growth, but market consensus and the company’s long-term targets have placed heavier validation pressure on it.
The final judgment can be reduced to one sentence: AI servers are still re-rating Japanese electronic components, but the next stage will no longer reward similar stories; it will reward verifiable product capability. If Murata continues to prove high-end MLCC mix and ROE improvement, the valuation gap will widen. If Taiyo Yuden catches up in key specifications, its discount will narrow. If Ibiden turns Rubin and EMIB-T into high-quality profit, the market will reassess Morgan Stanley’s cautious assumptions. Over the next four quarters, every judgment should return to six numbers: AI/DC MLCC mix, mass production of key specifications, Taiyo Yuden capex, quality of commodity MLCC pricing, Ibiden gross margin, and the yen exchange rate.Japan Electronic Components Deep Dive Update: Morgan Stanley Asia Investor Checks, and How AI Servers Are Widening the Valuation Gap Between MLCC and ABF
目录
Too Long; Didn’t Read
1. Conclusion First: This Investor Check Re-Tiers Electronic Components
2. Investors Ask About Commodity Price Hikes; Morgan Stanley Answers With Product Mix
3. Murata’s Core Variable: High-End MLCCs Shift from Tiny Components to Power-Supply Gatekeepers
4. Taiyo Yuden’s Contradiction: AI Upside, but an Execution Discount
5. Commodity MLCC Price Increases: The Choice Between Short-Term Profit and Long-Term Share
6. The Ibiden Debate: Rubin Ramp Is Strong, Consensus Is Stronger
7. Company Ranking: Murata Has the Highest Win Rate, Taiyo Yuden Offers Higher Upside, Ibiden Must Deliver the Data
8. Why the 2018 Playbook Is a Reference, Not a Template for 2026
9. Earnings Bridge: Five Gates Between AI Server Demand and Company Value
10. How to Use Sell-Side Divergence: Goldman Talks Demand, Morgan Stanley Talks Discipline, JPMorgan Talks Supply and Demand
11. Data Framework: Target Price, PE, and ROE Should Be Read Together
12. Three Worldviews: High-End MLCC Wins, Commodity Price Increases Spread, ABF Is Re-Validated
13. Asia and A-Share Read-Through: Look First at Specification Tickets, Then at Price Spillover
14. Tracking Checklist for the Next Four Quarters
15. Risk Breakdown: The Biggest Concern Is Right Demand, Wrong Company, Expensive Valuation
16. Conclusion: AI Electronic Components Enter the “Product Capability Realization Period”
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Morgan Stanley’s Asia investor checks have brought the divergence in Japanese electronic components to the forefront: AI servers continue to drive high-value-added MLCC demand, but valuation has shifted from demand elasticity to mass-production capability, product mix, ROE, and ABF profit delivery. This note breaks down the different paths of Murata, Taiyo Yuden, and Ibiden, and the validation signals to watch over the next four quarters.
Too Long; Didn’t Read
Divergence has shifted from demand to delivery. Morgan Stanley’s meeting feedback shows MLCC and ABF remain the main threads, but valuation is starting to screen for high-end mass production, product mix, and earnings quality. Generic price hikes can only provide temporary elasticity. Going forward, watch whether quarterly gross margin, inventory, and cash flow improve in tandem.
Murata’s swing factor is structural ASP. Morgan Stanley expects Murata’s AI data-center MLCC sales to grow 85-90% in F3/27, with ASP up roughly 50%, driven by a higher mix of high-priced products. The core lies in materials, layering, external electrodes, and stable mass production.
Taiyo Yuden’s upside is constrained by execution. The company also benefits from AI server MLCC demand, but the timing of high-end miniaturized mass production, roughly 5% MLCC capacity growth in F3/26, and its technology catch-up versus Murata will weigh on income-statement quality.
Commodity MLCC price hikes have limits. Rising distribution prices for commoditized MLCC can lift near-term earnings, but if companies only chase price hikes while neglecting R&D; and process capabilities, they will lose medium- to long-term share to vendors that keep improving product competitiveness. Price news must be validated against contract prices, customer orders, and inventory turnover.
Ibiden’s risk is elevated consensus. Rubin ABF substrate ramp-up will continue to drive earnings higher, but Morgan Stanley’s F3/28 and F3/31 operating profit forecasts are below the company’s targets, suggesting the market has already priced in substantial long-dated profit. EMIB-T contribution comes later, while gross margin from non-Nvidia customers and depreciation absorption still need validation.
Watch six indicators next. Focus on Murata’s AI/DC MLCC mix, mass production of key specifications, Taiyo Yuden capex, quality of commodity MLCC price hikes, Ibiden’s Rubin and EMIB-T gross margin, and the yen exchange rate. Also assess revenue growth together with inventory and cash flow to avoid relying only on price headlines. These indicators will determine whether valuation spreads widen or converge.
1. Conclusion First: This Investor Check Re-Tiers Electronic Components
This Morgan Stanley update on Japanese electronic components is short, but the signals are firm. It comes from institutional investor checks in Singapore and Hong Kong from June 22 to 26, including 31 one-on-one meetings and two luncheon sessions, with discussion focused on MLCC and ABF package substrates. The truly valuable point is that Morgan Stanley puts investors’ focus and its own judgment on the same map: investors care most about commoditized MLCC price hikes, AI server MLCC demand, and Ibiden’s valuation; Morgan Stanley cares more about product mix, stable mass production, and profit delivery.
This marks the second stage of the Japanese electronic components trade. In the first stage, the market confirmed that AI servers would push MLCC, ABF substrates, connectors, batteries, HDD heads, and other high-value-added components toward higher content value. In the second stage, the market starts to distinguish who can translate demand into the income statement and who merely has an AI exposure that sounds similar. Demand remains strong and prices are changing, but valuation must now be justified by earnings quality.
The ranking from this investor check is clear. Murata Manufacturing remains the strongest asset in high-end MLCC because AI servers require smaller, higher-capacitance, higher-reliability MLCC, and Murata leads in materials, layering, external electrodes, and mass-production stability. Taiyo Yuden also sits within the MLCC demand upcycle, but lags in high-end specification mass production and capacity expansion cadence, making its upside more dependent on execution. Ibiden remains a scarce ABF supplier, but Rubin ramp-up and EMIB-T contribution have already been priced in by the market in advance, and consensus beyond F3/28 appears more aggressive.
This table directly explains the “valuation gap” in the title. Japanese electronic components have not lost their AI logic; instead, they have entered a more selective phase. While all benefit from AI servers, Murata’s valuation can be supported by high-end product mix, Taiyo Yuden must catch up through execution, and Ibiden must deliver on high consensus through Rubin and EMIB-T. The market will next use quarterly data to test these differences, rather than indiscriminately assigning higher multiples to all AI component companies.
2. Investors Ask About Commodity Price Hikes; Morgan Stanley Answers With Product Mix
The most interesting contrast in this report is that the focus of the meetings and Morgan Stanley’s final conclusion do not fully overlap. Morgan Stanley states this directly: investors in the meetings were almost all asking about the magnitude of commoditized MLCC price hikes, while paying less attention to earnings expansion from growth in high-value-added products. This difference shows that the market still tends to understand the current cycle through the framework of the previous MLCC cycle.
In the last MLCC upcycle, the most visible signals were spot prices, lead times, distribution inventory, and price hikes for general-purpose products. That framework of course still has value, because distribution prices for commoditized MLCC have already started to rise, and there are also signs of adjustments in customer prices. But the new variable brought by AI servers is that high-end miniaturized, high-capacitance, high-reliability products are changing the revenue mix. Mix shifts are usually slower than pure price hikes, but they are also harder for competitors to replicate.
Murata is the representative case of this difference. Morgan Stanley notes that Murata’s AI data-center MLCC is expected to grow 85-90% in F3/27, assuming volume growth of roughly 40% and ASP growth of roughly 50%. The key is the latter half: ASP growth does not assume a simple unit-price increase for the same product, but mainly comes from a rising mix of high-priced, high-value-added products. In other words, Murata’s pricing is closer to product-mix repricing from specification upgrades, reducing the relevance of the traditional general-purpose price-hike lens.
“does not assume unit price hikes”
This short quote is the key to understanding Murata. Many electronic component companies derive earnings elasticity from list-price increases; Murata’s line comes more from customers needing to use higher-specification products. Space on AI server accelerator boards is limited, while each generation of GPU and ASIC platforms has higher power consumption, more severe transient current, and harder-to-control power-supply noise. Systems need small-size, high-capacitance MLCC to maintain power integrity. Product specification upgrades naturally increase unit value and also raise the barriers for yield, qualification, and delivery.
This is also why Morgan Stanley says company value gaps will continue to widen. Near-term price hikes can improve financials, but medium- to long-term corporate value comes from product competitiveness. If companies mainly allocate resources to capturing the price-hike window while falling behind in R&D;, materials, processes, and customer qualification, they may make money in one price cycle but struggle to qualify for the next generation of AI server platforms. Murata’s strategy is more focused on keeping general-purpose pricing flexible while allocating resources to high-end product competitiveness.
This view is also instructive for supply chains in mainland China, South Korea, and Taiwan. Price hikes in mid- to low-capacitance MLCC will benefit many vendors, but the ticket to high-end AI server MLCC comes from long-term investment. For A-share and Taiwan equity mappings, investors should not only look at who has MLCC capacity, but also who can approach high-end specifications in powder, thin-layering, stacking, sintering, screening, customer qualification, and stable mass production. Supply shortages provide beta for mid- to low-end companies; high-end specifications determine alpha.
3. Murata’s Core Variable: High-End MLCCs Shift from Tiny Components to Power-Supply Gatekeepers
The core driver of AI server demand for MLCCs is power density. GPUs, ASICs, CPUs, HBM, and high-speed switching chips continue to raise power consumption, requiring stronger board-level transient response, decoupling capability, and noise control. Traditional servers also need MLCCs, but new-generation AI acceleration platforms push MLCCs into tighter space, higher capacitance, and stricter reliability constraints.
Morgan Stanley provides a critical engineering judgment: on AI server accelerator cards, the total capacitance required from MLCCs rises by roughly 2x with each GPU generation, while mounting space remains limited. This means AI server MLCC demand has become a problem of capacitance per unit volume. High capacitance, small size, and high reliability have become the same problem.
“total capacitance required of MLCC increases”
Murata’s leading position rests on a full set of process capabilities. Morgan Stanley notes that the company improves dielectric-layer volume by refining and homogenizing barium titanate particles, increasing the number of layers, and narrowing external electrode width, thereby driving miniaturization and higher capacitance. Broken down, these three actions correspond to materials, manufacturing, and structural design: materials determine whether dielectric layers can be made thinner; layering determines how much effective capacitance can fit into the same volume; external electrode design determines how much internal space can be used for dielectric layers.
This capability set determines Murata’s valuation foundation. Looking only at AI server revenue as a share of MLCC revenue, the 10-15% level in F3/26 does not appear especially high; Morgan Stanley expects it to rise to 20-25% in F3/27 and continue growing at a similar pace after F3/28. The real meaning behind the change in mix is that high-end products are moving from marginal contribution to the center of the profit pool. As long as high-end products have meaningfully higher ASPs, margins, and customer stickiness than standard products, rising revenue contribution will drive simultaneous improvement in margins and ROE.
From an investment research perspective, Murata’s re-rating does not rely on a single quarter of price-hike news. It requires continuous validation of three points. First, the AI/DC MLCC share must continue rising, showing that high-end demand has entered the main line of the income statement. Second, key specifications must reach stable mass production, showing that share and customer qualification are not being eroded by challengers. Third, ASP growth must come from mix, not price hikes for commodity products, showing that ROE improvement is sustainable.
The risks are also clear. If the rollout of customers’ next-generation platforms slows, or if yields on high-end specifications improve too quickly and allow competitors to catch up, Murata’s structural ASP will be compressed. If the yen appreciates sharply, Morgan Stanley’s model also implies mid-single-digit pressure on Murata’s operating profit from FX. High-end MLCC is a good business, but the valuation has already recognized this line in advance. Going forward, it will not be enough to look only at strong orders; margins, ROE, and free cash flow also need to be watched.
4. Taiyo Yuden’s Contradiction: AI Upside, but an Execution Discount
Taiyo Yuden provides the best negative control in this report. Morgan Stanley acknowledges that Taiyo Yuden will benefit from growth in AI server and data-center MLCC sales, as well as higher utilization rates. At the same time, Morgan Stanley believes the contribution from high-value-added products to Taiyo Yuden’s earnings will be limited. This judgment sounds restrained, but it captures Taiyo Yuden’s core contradiction.
Taiyo Yuden’s problem is not demand. Morgan Stanley estimates that Taiyo Yuden’s AI data-center MLCCs will account for 5-10% of total MLCC sales in F3/26, then grow 82-83% in F3/27 to reach about 15% of sales, and continue expanding after F3/28. This growth rate is not weak; it is even close to Murata’s. The divergence comes from win rate: whether the company can stably mass-produce high-end specifications, catch up with the next-generation small-form-factor, high-capacitance roadmap, and secure enough new business in the critical window.
The key specifications Morgan Stanley lists are 1608-size 100µF, 1005-size 47µF, and 0603-size 10µF. It believes that, for now, only Murata appears able to stably mass-produce all of these products. When Taiyo Yuden can do so remains unclear. By the time it catches up with Murata’s current comparable products, Murata may already have started mass production of the next generation of smaller and higher-capacitance MLCCs. This is the harshest part of high-end electronic components: catching up is a moving exam, and the leader keeps moving too.
Capacity timing is the second constraint. Morgan Stanley notes that Taiyo Yuden froze capex in 2H24, limiting F3/26 MLCC capacity growth to about 5% and affecting its ability to capture new business. For a traditional cycle, this capital discipline may be a strength; during the AI server high-end MLCC window, excessive conservatism can cause the company to miss customer qualification and share gains. Taiyo Yuden needs to balance two risks: expanding too slowly means losing orders, while expanding too quickly risks repeating depreciation and inventory pressure.
Taiyo Yuden’s investment value therefore looks more like an execution option. Its revenue concentration is high, so the earnings sensitivity from AI MLCC volume ramp could be greater than Murata’s. But it needs to prove that its roadmap, mass production, capex, and customer adoption can keep pace. If the next few quarters show synchronized improvement in AI server orders, BB ratio, capacity utilization, and gross margin, Taiyo Yuden’s valuation discount will narrow. If investors see only revenue growth without improvement in high-end mix and margins, the market will still treat it as a high-volatility MLCC beta.
5. Commodity MLCC Price Increases: The Choice Between Short-Term Profit and Long-Term Share
Morgan Stanley’s stance on commodity MLCC price increases is worth unpacking. The report acknowledges that distributor selling prices for commodity MLCCs appear to be rising, and that Murata will also adjust prices flexibly based on market conditions. The issue is that Murata is not proactively pushing price increases for commodity products, because excessive pursuit of short-term profit would lower entry barriers, attract accelerated entry by manufacturers in mainland China, South Korea, and Taiwan, and ultimately lead to medium- to long-term share erosion.
This may sound like a management philosophy, but it is essentially the competitive logic of the electronic components industry. Price elasticity in standard MLCCs is the easiest for the market to observe and the easiest to attract new capacity. Short-term price increases lift industry profit, but if product specifications lack barriers, customers will look for second suppliers, competitors will allocate more resources, channels will build inventory, and the benefit from price increases will ultimately be absorbed by competition and the inventory cycle.
High-end MLCCs are priced differently. Customers are willing to pay premiums for smaller size, higher capacitance, higher reliability, and more stable delivery, because these products directly affect AI server platform delivery. Customers care more about failure rates, qualification cycles, and platform compatibility; unit price is only one constraint. Suppliers can therefore achieve ASP growth through new specifications, new products, and mix improvement, without having to center the competition on commodity product quotations.
This framework is especially important for mapping to domestic passive components. Price increases in low- and mid-capacitance MLCCs will lift revenue and gross margin for related companies, and materials suppliers will also benefit from higher utilization. But the valuation ceiling depends on progress in high-end specifications. If a company can only earn cyclical profit from commodity price increases, valuation will be constrained by the cycle peak. If it can enter AI servers, high-reliability automotive, and high-end industrial specifications, and improve customer qualification through powder, end electrodes, thinning, and screening capabilities, it has a chance to shift from a cyclical stock into a platform-type component asset.
This time, Morgan Stanley separates “price-increase companies” from “product-competitiveness companies,” offering a very clear research signal. Ordinary price increases can serve as an early signal for the income statement, but not as the final valuation anchor. The real variables to track are whether price increases are accompanied by a higher share of high-end products, whether margin improvement is accompanied by healthy inventory, and whether customer qualifications can move from short-term shortages to next-generation platform status.
6. The Ibiden Debate: Rubin Ramp Is Strong, Consensus Is Stronger
The Ibiden section is the most valuation-disciplined part of the report. Morgan Stanley does not deny the company’s fundamentals. On the contrary, the report expects Ibiden to have started volume shipments of NVIDIA Rubin ABF package substrates in Q4 F3/26, and expects Rubin-related ABF sales to exceed Blackwell in Q1 F3/27, driving continued profit expansion from high-value-added ABF package substrates.
The disagreement comes from the height of expectations. Morgan Stanley believes market expectations for Ibiden are too high. The report’s operating profit forecasts show F3/27 slightly below FactSet consensus, F3/28 meaningfully below the company’s target and FactSet consensus, and F3/31 also below the company’s long-term target. In other words, the Rubin ramp is a positive variable with relatively high visibility, but the market has already priced in a lot of future profit.
“market consensus appears too high”
Why is Morgan Stanley cautious? First, the value uplift in ABF is real, and larger SAP size will continue to make substrates more value-added; but higher value-added does not mean unlimited gross margin upside. Second, EMIB-T will bring profit expansion, but Morgan Stanley believes meaningful contribution will not appear until after F3/29. Third, EMIB-T pricing will be significantly higher than existing ABF, but Morgan Stanley believes it will be difficult for its margin to reach the level of existing NVIDIA products.
Ibiden can be broken down into three lines. The Rubin line is the short- to medium-term growth anchor, showing that NVIDIA platforms continue to lift ABF value content. The EMIB-T line is the medium- to long-term technology anchor, showing that high-end package substrates still have more complex forms ahead. The valuation line is the risk anchor, showing that the market has already traded these variables in advance at high multiples. As long as the Rubin or EMIB-T timetable slips slightly, or non-NVIDIA customer margins fall short of expectations, valuation will adjust first.
This section also has implications for the broader AI hardware chain. Packaging, substrates, MLCCs, CCL, glass fiber cloth, and high-end PCBs will all benefit from rising system complexity, but every link faces the same valuation question: strong demand is one thing; margins, depreciation, customer structure, and long-term ROE delivery are another. Ibiden shows that even scarce assets enter a verification period when prices are too high.
7. Company Ranking: Murata Has the Highest Win Rate, Taiyo Yuden Offers Higher Upside, Ibiden Must Deliver the Data
Morgan Stanley covers 20 Japanese electronic components companies, but this research is best divided into three types of assets. The first is product-structure driven, represented by Murata, where the core question is whether high-end MLCCs can continue to lift ASP and ROE. The second is execution-option driven, represented by Taiyo Yuden, where the core question is whether it can catch up in high-end specifications and convert AI demand into margins. The third is high-consensus verification, represented by Ibiden, where the core question is whether Rubin, EMIB-T, and margins can support already elevated expectations.
TDK, Hirose, NGK Spark Plug, Alps Alpine, and others are also among Morgan Stanley’s relatively positive ratings. Their common feature is not extreme single-point elasticity, but steadier ROE and profit growth through HDD heads, BBU batteries, connectors, existing automotive businesses, or operational improvement. Once the market enters a valuation-discipline phase, these assets may instead gain more relative value.
This ranking is not a permanent judgment on company quality, but the current risk-reward structure based on available data. Murata looks most like a high-probability asset, Taiyo Yuden more like a high-upside asset, and Ibiden like a scarce asset that the market has already recognized in advance. All three assets benefit from AI servers, but the market is asking each of them a completely different verification question.
For Murata, the question is whether the share of high-end MLCCs can continue to rise, and whether ASP growth can mainly come from product structure. For Taiyo Yuden, the question is whether it can use customer qualifications and capex to prove that it is not only a beneficiary, but also a stable supplier to high-end platforms. For Ibiden, the question is whether Rubin and EMIB-T can support company targets in gross margin and cash flow. If all three questions are answered positively, the sector can continue to be strong. If demand is strong but profit quality is weak, valuation dispersion will continue to widen.
It is important to note that target prices are only model expressions and cannot replace operating verification. For chains such as high-end MLCC and ABF, share prices will react before financial reports, but financial reports will determine whether valuations can remain elevated. Over the next few quarters, the market will care more about gross margin, ROE, cash flow, and inventory, not just revenue.
8. Why the 2018 Playbook Is a Reference, Not a Template for 2026
Morgan Stanley explicitly raised the “differences between the 2018 and 2026 MLCC markets” in its meeting agenda. This is a critical point. The 2017-2018 MLCC upcycle left a strong market memory: smartphones, automotive electronics, industrial control, and restocking resonated at the same time; supply could not expand fast enough; prices rose rapidly; and Japanese and Taiwanese vendors saw margins improve sharply. Many investors naturally use that experience to frame 2026.
The similarity in 2026 is that both supply and demand are tightening. Distribution prices for commodity MLCCs are rising, customers are beginning to accept tighter supply, and delivery pressure is increasing for high-end MLCCs. The difference is that both the demand source and supply constraint are more engineering-driven. 2018 was closer to broad-based demand plus restocking; 2026 is closer to AI servers pushing high-capacitance, small-form-factor, high-reliability products into bottleneck territory. Nominal capacity still exists, but effective capacity is being consumed by more difficult specifications.
This comparison explains why Morgan Stanley is more positive on Murata. Murata has cost competitiveness in general-purpose products and a high-end product roadmap. It benefits in a price-increase phase and benefits even more in a specification-upgrade phase. Taiyo Yuden and other challengers also have elasticity, but they need to prove effective capacity, yield, and customer qualification. Mid/low-capacitance MLCC vendors will benefit from price pass-through, but their valuations cannot simply be benchmarked against high-end leaders.
For China’s domestic supply chain, the 2018 experience can also only serve as a base case. The last round of domestic substitution mainly focused on cost, supply stability, and mid/low-end capacity expansion. If high-end MLCCs for AI servers become a long-term variable in this round, domestic companies need to prove deeper materials and process capabilities. Materials such as powders, pastes, terminal electrodes, nickel powder, carrier tape, and release film may see utilization and earnings elasticity first, but customer certification for high-end MLCC systems will be slower. Share prices can trade expectations first, but the income statement still needs quarterly verification.
9. Earnings Bridge: Five Gates Between AI Server Demand and Company Value
Strong AI server demand is only the first gate. The real reminder from Morgan Stanley’s research is that the re-rating of electronic components must pass through five gates: demand, specification, mass production, pricing, and financial quality. Each gate can turn what looks like a strong industry story into very different company outcomes.
The first gate is demand. As GPUs, ASICs, AI CPUs, and networking chips continue to upgrade, board-level power delivery and packaging complexity increase, lifting demand for both MLCCs and ABF. The second gate is specification. Customers are not asking for more general-purpose products, but for smaller, higher-capacitance, higher-reliability MLCCs, as well as larger, more complex SAP and higher-yield ABF substrates. The third gate is mass production. Making samples and steadily supplying cloud platform customers are entirely different capabilities.
The fourth gate is pricing. Murata’s pricing comes from a high-unit-price product mix; commodity MLCC pricing comes from spot prices and discount clawbacks; ABF pricing comes from platform complexity and customer delivery pressure. The fifth gate is financial quality. Revenue growth must translate into improvements in gross margin, operating margin, ROE, and cash flow, or valuation will return to a cyclical framework.
This earnings bridge explains the differences among the three companies. Murata has already passed the demand, specification, and mass-production gates, and is now validating pricing and financial quality. Taiyo Yuden has clear demand, but still needs to prove mass production and capex. Ibiden has clear demand and specifications, and mass production is also advancing; the difficulty has shifted to pricing, depreciation, margins, and valuation.
Therefore, tracking Japanese electronic components cannot focus only on news flow. Strong AI server shipments will bring beta to the entire chain, but what truly determines relative share-price performance is which company can pass the five gates more smoothly. If all companies have only opened the demand gate, the rally will shift from broad-based gains to dispersion. If Murata can continue to open the structural ASP and ROE gates, the valuation gap will keep widening. If Taiyo Yuden and Ibiden also prove financial quality with data, the divergence will narrow.
10. How to Use Sell-Side Divergence: Goldman Talks Demand, Morgan Stanley Talks Discipline, JPMorgan Talks Supply and Demand
There have already been many recent reports on MLCCs, ABF, and Japanese electronic components. Simply lining them up can easily become a stack of institutional views. A better reading is to treat them as a complete puzzle: Goldman Sachs is better at explaining how AI server demand spreads into components and materials; JPMorgan is better at building MLCC supply-demand and pricing models; and Morgan Stanley’s latest work translates survey feedback into valuation discipline and company segmentation.
Goldman Sachs’ earlier Asia investor conference and electronic components reports emphasized the demand opportunity from rising AI server power consumption for MLCCs, PMICs, ABF, and other high-value-added components, and argued that many investors had not fully reflected these profit contributions. JPMorgan’s MLCC report laid out the supply-demand gap, price pass-through, industry TAM, and margin upside more systematically. Morgan Stanley’s latest update does not rebuild the industry model. Instead, it narrows the market discussion to more granular questions: who can capture ASP through product mix, who is merely following price increases, and whose consensus expectations are already too high.
Viewed through this puzzle, the conclusion is more stable. Goldman Sachs and JPMorgan help confirm that MLCC and ABF have indeed entered an AI hardware diffusion cycle. Morgan Stanley reminds us that this diffusion cycle has already been traded once in share prices, and the next phase depends on company execution. The former answers “why there is room”; the latter answers “why we cannot buy every company on the same story.”
This also explains why this report deserves to be written separately. It is not long, but its incremental value is concentrated: investors remain focused on price, while Morgan Stanley’s conclusion focuses on product capability; Murata and Taiyo Yuden are both on the MLCC theme, yet their probability of success has widened; Ibiden sits in a strong ABF cycle, but its valuation is subject to stricter constraints. For future writing and tracking, this is the inflection point from industry momentum to company quality.
11. Data Framework: Target Price, PE, and ROE Should Be Read Together
Morgan Stanley’s target price table can easily be read as a simple upside/downside screen. A more robust reading is to assess target price, PE, P/B, and ROE together. Murata’s base-case target price still implies upside versus the June 26 closing price, but its F26e PE is already very high. What the market is paying for is ROE improvement after F27 and a higher-end product mix. Taiyo Yuden and Ibiden have target prices below their current share prices because Morgan Stanley believes too much future delivery is already embedded in prices, not because they lack fundamentals entirely.
Valuation comparison cannot rely only on PE levels. Murata’s F26e PE is high, but it falls quickly in F27 and F28 as earnings grow, while ROE improvement becomes clearer. Taiyo Yuden’s PE is also high, but its pace of ROE improvement and certainty in high-end products are weaker than Murata’s. Ibiden has a high PE and high P/B, while its ROE improvement also needs a longer cycle to prove out. The market has already assigned substantial weight to Rubin and EMIB-T.
The table is straightforward to read. Murata is expensive, but it has a relatively clear upward ROE trajectory. Taiyo Yuden and Ibiden are also expensive, with higher execution difficulty. TDK and Hirose do not have the same extreme AI leverage, but their valuations and ROE profiles are more balanced. If the market enters a stricter risk appetite environment, assets with stable ROE will be more resilient. If AI server supply and demand continue to exceed expectations, high-beta assets will rise first, but they are also more vulnerable to pullbacks if financial results fail to validate the story.
FX assumptions should also be incorporated into the model. Morgan Stanley uses a relatively weak yen as its F26e average assumption. For the industry overall, operating profit has mid-single-digit sensitivity to USD/JPY movements. Murata, Taiyo Yuden, and Ibiden have different FX sensitivities, as shown below. The conclusion is that yen movement is a second-order variable, but it affects quarterly profits and market sentiment, especially for companies such as Taiyo Yuden with higher margin sensitivity.
For readers, target price is only the model output. The real answer lies in the operating profit, ROE, FX assumptions, and product mix behind that target price. Murata’s target price requires the AI/DC MLCC share to keep rising. Taiyo Yuden needs to prove high-end mass production and capex decisions. Ibiden needs to prove that Rubin and EMIB-T can generate high-quality profits.
12. Three Worldviews: High-End MLCC Wins, Commodity Price Increases Spread, ABF Is Re-Validated
Japanese electronic components can be tracked through three worldviews.
The first worldview is that high-end MLCC wins. AI servers continue to raise power density, and customers are willing to pay for small size, high capacitance, high reliability, and stable delivery. Murata maintains its lead, while Samsung Electro-Mechanics and Taiyo Yuden catch up but struggle to close the gap quickly. In this scenario, Murata remains the strongest main line. Materials and domestic high-end MLCC have long-term read-through, but the valuation ceiling for companies benefiting only from low- to mid-end price increases is limited.
The second worldview is that commodity price increases spread. Spot and contract prices for low- to mid-capacitance MLCC continue to rise, inventories remain healthy, and standard specifications also begin flowing into the income statement. This scenario benefits more companies, including Taiwanese, Korean, domestic MLCC, and materials companies. The risk is that broad-based price increases are more likely to attract new capacity, so valuation durability requires support from inventory and cash flow.
The third worldview is that ABF is re-validated. Rubin, ASIC, and AI CPU continue to increase ABF content value, benefiting Ibiden, Taiwanese ABF producers, and the Korean FC-BGA supply chain. But the market is already trading high-end substrate assets at very high prices. From here, investors must see gross margin, depreciation absorption, and customer project delivery. In this scenario, the ABF trade will not disappear, but stock-level volatility will be greater.
These three worldviews are not mutually exclusive. The best industry state is one in which high-end MLCC, commodity price increases, and ABF all materialize at the same time. The worst state is one in which demand remains strong but profit quality diverges, with only a few companies capturing truly high-quality profits. The current state is closer to the middle: the high-end MLCC logic is clearest, commoditized price increases are emerging, and ABF remains strong but faces the greatest valuation validation pressure.
This is also why the title puts MLCC and ABF together. Both lines come from AI servers, but they are at different pricing stages. The focus for MLCC is shifting from the spread of price increases to product mix. The focus for ABF is shifting from strong demand to whether consensus is too high. Together, they form the next round of differentiation in Japanese electronic components.
13. Asia and A-Share Read-Through: Look First at Specification Tickets, Then at Price Spillover
Although this Morgan Stanley report focuses on Japanese companies, it has substantial value for Asia and A-share read-through. It reframes the research sequence for MLCC and ABF from “who is in the supply chain” to “who has the specification ticket.” This will affect the valuation approach for domestic passive components, ceramic materials, electronic paste, carrier tape, release film, nickel powder, PCB materials, and package substrates.
For the A-share MLCC and materials chain, the first read-through is price spillover. Rising distribution prices for commoditized MLCC, recovery of customer discounts, and utilization improvement will first transmit to domestic MLCC platforms such as Fenghua Advanced Technology, and also to materials names such as Sinocera, Jiemi Technology, and Boqian New Materials. Their short-term earnings leverage mainly comes from demand recovery, price increases, and utilization. This leverage is important, but quality needs to be verified through inventory and cash flow.
The second read-through is the high-end specification ticket. If companies such as Chaozhou Three-Circle and Sinocera are to move from cyclical recovery to AI server re-rating, they need to prove capabilities in high-reliability ceramic materials, high-end powders, electronic paste, and customer qualification. What is truly scarce in AI server MLCC is small size, high capacitance, high reliability, and stable mass production. Simply expanding low- to mid-end capacity cannot substitute for this. If domestic companies can enter high-end specification validation, their valuation ceiling will rise. If they remain limited to ordinary price increases, their valuation will look more like cyclical products.
The third read-through is ABF and PCB materials. Ibiden’s example reminds us that even scarce AI packaging and substrate assets are still constrained by margins, depreciation, and customer structure. A-share and Taiwan-share companies in ABF, BT, CCL, fiberglass cloth, copper foil, and high-end PCB need a similar framework: strong demand is only the starting point. Ultimately, the key variables are yield, customer qualification, price pass-through, material lock-in, and cash flow.
This mapping also helps avoid placing all companies in the same basket. Fenghua Advanced Technology is more of a domestic MLCC platform and cyclical recovery story. Chaozhou Three-Circle is more about electronic ceramics and high-end MLCC capability. Sinocera is more exposed to powders and electronic paste. Jiemi Technology is more geared to consumables and carrier tape. Boqian New Materials is more exposed to nickel powder materials. They may all benefit, but the valuation question differs: companies that can move from price increases into high-end specifications are closer to the Murata-style logic; companies that can only benefit from ordinary price spillover are closer to the cyclical recovery logic.
14. Tracking Checklist for the Next Four Quarters
The most important task over the next four quarters is to translate the news flow back into verifiable metrics. Themes such as strong AI server demand, MLCC price increases, and Rubin volume ramp will recur, but what ultimately determines valuation is continuous evidence from company financials and customer programs.
First, monitor Murata’s AI/DC MLCC revenue mix. Whether F3/27 can move toward the 20-25% range is central to whether structural ASP uplift can be realized. Second, monitor mass production of key specifications. If Murata continues to lead stably in products such as 1608 100µF, 1005 47µF, and 0603 10µF, the valuation gap will widen; if Taiyo Yuden and other manufacturers catch up faster, the profit pool will be redistributed. Third, monitor Taiyo Yuden capex. It needs to strike a balance between avoiding overinvestment and capturing the high-end window.
Fourth, monitor pass-through of price increases in commodity MLCCs. Rising distribution prices are only an early signal; contract prices, discount recapture, inventory value, and cash flow are more important. Fifth, monitor Ibiden’s Rubin and EMIB-T. Rubin sales exceeding Blackwell is only the beginning; gross margin, depreciation absorption, and the timing of EMIB-T contribution matter more. Sixth, monitor FX. Yen movements will affect quarterly profits, especially amplifying earnings volatility for smaller-base companies such as Taiyo Yuden.
The sequence also matters. Prices and orders change first, gross margin validates later, inventory and cash flow move more slowly, while customer qualification and capex efficiency are slower still. If all indicators improve in the same direction, electronic components will continue to be re-rated from cyclical products into AI hardware infrastructure. If prices rise first, inventories build later, and cash flow fails to keep up, the trade will revert from structural re-rating to cyclical trading.
15. Risk Breakdown: The Biggest Concern Is Right Demand, Wrong Company, Expensive Valuation
The biggest risk in this theme is “right demand, wrong company, expensive valuation.” Strong industry demand does not mean every company can secure high-end qualification. Winning orders does not mean margins can be realized. Rising gross margin does not mean cash flow is healthy. Japanese electronic components have already rallied, and the market will punish companies with insufficient validation more quickly.
The first category of risk is technology catch-up. If Taiyo Yuden, Samsung Electro-Mechanics, or mainland Chinese manufacturers accelerate catch-up in key high-end MLCC specifications, Murata’s structural ASP and high-end share will be compressed. This risk does not carry a high near-term weight, but it needs continuous monitoring.
The second category is inventory and pricing mismatch. If commodity MLCC price increases come only from channel expectations, subsequent inventory build will quickly compress gross margin. A genuinely healthy price increase should come with simultaneous improvement in customer demand, lead times, contract prices, and cash flow.
The third category is high consensus in ABF. Ibiden’s Rubin and EMIB-T are both real variables, but market expectations are already high. If F3/28 operating profit moves closer to Morgan Stanley’s forecast, deviating from company targets and FactSet consensus, the stock will first see valuation de-rating.
The fourth category is FX and costs. Yen appreciation, rising material costs, and energy and wage pressure could all affect quarterly profit. High-end products can partially offset cost pressure, while commodity products are more easily squeezed.
These risks do not change the main line that AI servers are driving electronic components, but they will change relative company performance. Good industries can still produce bad trades, and strong demand can still generate low-quality profits. The most important value of Morgan Stanley’s research is that it reminds the market to break “AI beneficiary” into five questions: product, mass production, price, profit, and valuation.
16. Conclusion: AI Electronic Components Enter the “Product Capability Realization Period”
Japanese electronic components have moved from the AI hardware diffusion phase into the product capability realization period. Morgan Stanley’s Asia investor survey shows that investors remain highly focused on MLCC and ABF, but the market most easily overlooks that price increases and demand do not automatically translate into long-term corporate value. What truly widens valuation gaps is high-end specifications, stable mass production, customer qualification, ROE, and cash flow.
Murata has the highest probability of winning in this theme. Its high-end MLCC growth comes from AI server product mix, not simple price increases for the same specifications. Its capabilities in materials, layering, external electrodes, and mass production make it easier to convert AI demand into structural ASP uplift. Taiyo Yuden also has upside, but it needs to use capex, mass production, and customer adoption to prove it can keep up with high-end platforms. Ibiden remains in the ABF upcycle, and Rubin and EMIB-T will continue to bring incremental growth, but market consensus and the company’s long-term targets have placed heavier validation pressure on it.
The final judgment can be reduced to one sentence: AI servers are still re-rating Japanese electronic components, but the next stage will no longer reward similar stories; it will reward verifiable product capability. If Murata continues to prove high-end MLCC mix and ROE improvement, the valuation gap will widen. If Taiyo Yuden catches up in key specifications, its discount will narrow. If Ibiden turns Rubin and EMIB-T into high-quality profit, the market will reassess Morgan Stanley’s cautious assumptions. Over the next four quarters, every judgment should return to six numbers: AI/DC MLCC mix, mass production of key specifications, Taiyo Yuden capex, quality of commodity MLCC pricing, Ibiden gross margin, and the yen exchange rate.