
Intel Q2 In-Depth Update: Margin Beat, Accelerating 14A Expansion, External Foundry Demand Still Unproven
目录
Executive Summary
1. From Last Quarter to This Quarter: Intel Moves from a “Recovery Narrative” to Profit Delivery
2. Why Data Center Has Become the Largest Profit Pool: Strong Demand, Even Scarcer Supply
3. Client Revenue Was Strong, but Higher ASPs Should Not Be Mistaken for a Recovery in Unit Demand
4. 18A Has Provided Internal Validation and 14A Investment Has Begun, but External Customers Remain the Missing Link
5. Why Capital Expenditure Is Suddenly Accelerating: Both a Vote on Demand and a Financing Test
6. $150 Versus $85: Why Target Prices Differ by Nearly 2x When Revenue Forecasts Differ by Only 2%
7. What Actually Matters Over the Next Four Quarters Is More Than a Single Revenue Figure
8. Final Assessment: The Technology and Operating Inflection Points Are Confirmed; the Commercial and Cash Flow Inflection Points Are Not
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Intel has demonstrated that server demand and manufacturing execution can translate into profits. Its next task is to prove that capacity expansion can also translate into external orders, free cash flow, and per-share value retained by shareholders.
Executive Summary
The operating baseline has moved materially higher. Intel reported Q2 2026 revenue of $16.128 billion, adjusted gross margin of 41.8%, and adjusted EPS of $0.42, approximately 11.7%, 2.6 percentage points, and 91% above pre-earnings consensus, respectively. The midpoint of Q3 revenue guidance is $16.3 billion, with adjusted gross margin guided to 42%, indicating that Q2 was not driven by one-off shipment concentration.
Data Center and AI has evolved from a growth engine into Intel’s largest profit pool. Revenue reached $6.262 billion, up 59% year over year, while operating profit was $2.474 billion at a 39.5% margin, exceeding Client Computing’s $2.343 billion of operating profit for the first time. Server demand remains supply-constrained, making the release of incremental capacity in Q4 the next key growth test.
The 41.8% gross margin beat was high quality, but margins are unlikely to rise in a straight line near term. Yield, cycle time, average selling prices, and product mix all contributed to the upside. At the same time, Panther Lake and Granite Rapids remain below the corporate average gross margin during their early ramps. The client inventory write-down will not recur, but memory and other input costs will create pressure in the second half.
Intel 14A has cleared the internal threshold for investment, but not the commercial threshold for external foundry adoption. The 0.9 process design kit is scheduled for release in October 2026, followed by risk production in the second half of 2027 and high-volume manufacturing in 2028. However, external foundry revenue remains small, no anchor customer has been publicly disclosed, and the foundry segment recorded a quarterly loss of $2.089 billion.
The gap between Goldman Sachs’ $150 target and JPMorgan’s $85 target appears to be about valuation, but is fundamentally about margins, multiples, and financing assumptions. The firms’ 2028 revenue forecasts differ by only approximately 2.2%, while their adjusted EPS forecasts differ by roughly 28%, compounded by valuation multiples of 30x versus 24x. Whether Intel can convert capital expenditure into high-margin external revenue will determine which model is closer to reality.
The operating inflection point has arrived; the cash flow inflection point has not. Q2 operating cash flow was $7.006 billion, but company-defined adjusted free cash flow was negative $8.419 billion. Intel raised its 2026 capital expenditure outlook to more than $20 billion, with another significant increase expected in 2027. The ceiling for the share price will depend not only on revenue, but also on foundry loss reduction, returns on capital, and the fully diluted share count.
1. From Last Quarter to This Quarter: Intel Moves from a “Recovery Narrative” to Profit Delivery
Intel had already provided signs of recovery in Q1: revenue of approximately $13.6 billion, adjusted gross margin of 41.0%, and adjusted EPS of $0.29. Intel 18A entered mainstream products, Data Center and AI revenue reached approximately $5.1 billion at a 30.5% operating margin, and the foundry loss was approximately $2.4 billion. The key conclusion at the time was that internal products could validate the process technology, but server share, external foundry customers, and cash returns would still require confirmation from subsequent results.
Q2 moved two of those indicators from signals into reported financials. Revenue increased by approximately $2.5 billion sequentially to $16.128 billion, while adjusted operating profit reached $2.77 billion. Data Center and AI revenue increased by approximately $1.2 billion sequentially, and its operating margin rose another 9 percentage points to 39.5%. The foundry loss narrowed by approximately another $350 million quarter over quarter. Intel has now met or exceeded its financial expectations for seven consecutive quarters, indicating that internal forecasting, capacity allocation, and cost discipline have all become more stable than during the early stages of the transformation.
The earnings beat was also broad-based.
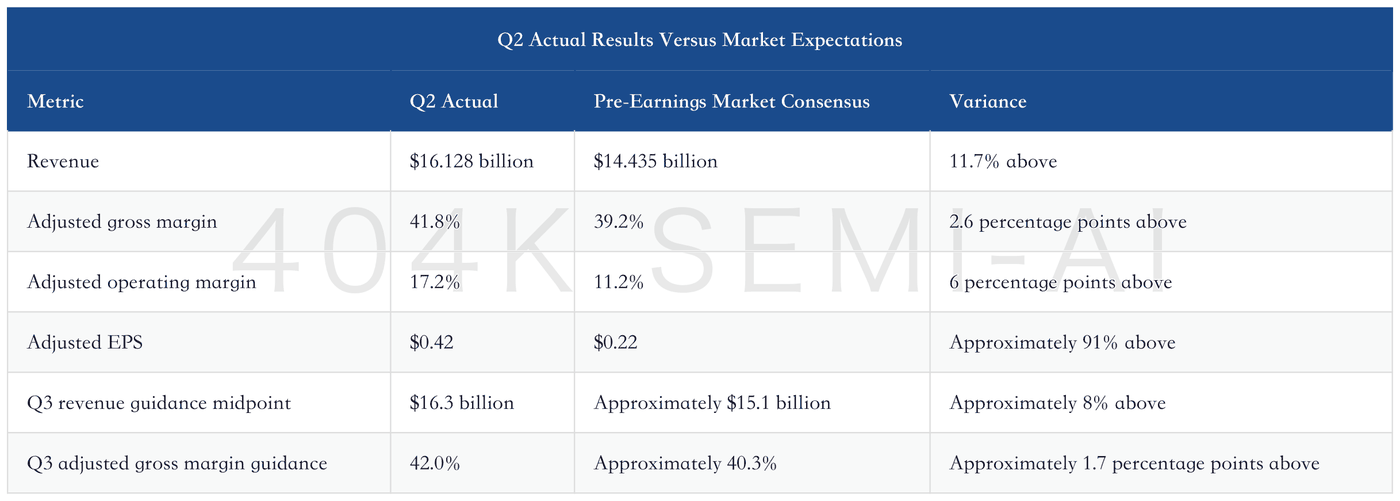
Goldman Sachs attributed the combination to Data Center and Client revenue, materially higher gross margin, and constructive commentary on process technology and supply. JPMorgan went further, noting that the upside came from higher wafer output, better average selling prices, and improved product mix rather than simply stronger end-market unit demand. The firms agree on one point: the old revenue model is no longer valid. They differ on whether this improvement in execution can support the long-term profitability implied by the current share price.
2. Why Data Center Has Become the Largest Profit Pool: Strong Demand, Even Scarcer Supply
The most valuable change in Intel’s Q2 results was not Client revenue returning to nearly $9 billion, but Data Center and AI becoming the company’s largest source of segment operating profit for the first time. The business generated $6.262 billion in revenue, up 59% year over year and 24% sequentially, with operating profit of $2.474 billion, exceeding Client Computing’s $2.343 billion. Its 39.5% operating margin indicates that incremental server revenue is now delivering not only scale, but also high-quality earnings.
Management divided demand into three layers. The first is general-purpose server CPUs. Agentic AI increases inference, orchestration, data preparation, storage, and networking workloads. GPU clusters do not eliminate CPUs; instead, they increase the number of CPUs, core counts, and average selling prices within the system. Management expects server revenue to grow at a compound annual rate materially above 10% over the next several years, while Goldman Sachs expects industry unit demand to maintain strong double-digit growth through at least 2028.
The second layer is long-term agreements. Granite Rapids supply is extremely tight, and Intel has signed long-term agreements with customers including Google. These agreements do not represent unconditional revenue guarantees, but they improve visibility for capacity investment and are an important reason Intel is willing to increase spending on Intel 3, substrates, and advanced packaging.
The third layer is custom silicon and design services. JPMorgan estimates that the related business is approaching a $2 billion annualized revenue run rate, nearly triple the prior-year level. Management stated on the earnings call that the design services business is approaching a $1 billion annualized run rate and could reach approximately $4 billion over the next several years. These figures use different definitions and cannot be added directly, but together they show that Intel’s Data Center growth is no longer dependent solely on traditional Xeon processors.
Supply remains the near-term ceiling. Front-end wafers, advanced packaging, substrates, T-Glass, and memory could all become bottlenecks, with most incremental capacity expected to come online in late Q3 and Q4. The midpoint of Q3 revenue guidance is only 1.1% above Q2—not because orders have suddenly disappeared, but because supply improvements are not linear. The real next test is whether Data Center revenue can continue growing after Q4 capacity comes online while sustaining an operating margin near 40%. If revenue grows but margins fall materially, the current benefits from mix or pricing will prove shorter-lived than the market expects.
3. Client Revenue Was Strong, but Higher ASPs Should Not Be Mistaken for a Recovery in Unit Demand
Client Computing revenue was $8.877 billion, up 13% year over year and 15% sequentially, materially ahead of expectations. However, operating profit was $2.343 billion, representing a 26.4% margin, down 6.2 percentage points from 32.6% in Q1. Management explicitly stated that the revenue beat was driven primarily by higher average selling prices, including premium product mix and proactive price increases, rather than stronger PC unit demand.
AI PC revenue increased 26% sequentially and now represents approximately two-thirds of Client revenue. Edge deployments account for approximately 10% of Client revenue, providing additional resilience. However, JPMorgan expects higher memory prices could reduce PC consumption by low double digits in 2026. Channel CPU inventories are expected to remain low in Q3, while traditional Client revenue may temporarily remain flat before end-market weakness becomes more visible in Q4.
The margin decline also reflected a temporary factor. After reallocating manufacturing resources from Client to Server, Intel recorded an inventory write-down on certain work-in-process products that were no longer economical to complete and test. This charge will not recur in Q3, creating a gross margin tailwind. However, Panther Lake and Granite Rapids remain in the early stages of their cost curves, with gross margins below the corporate average over the next several quarters, while input costs are expected to rise in the second half. Management continues to use a 40%–60% incremental revenue conversion framework over the medium term and aims to keep corporate gross margin “comfortably above 40%.”
The best-case scenario for Client is therefore not a return to high single-digit unit growth. It is for premium products and the edge business to stabilize revenue, cost-optimized products to ramp gradually, and pricing to offset inflation in memory and other components. If Q3 gross margin reaches 42% and Client margins stabilize, the ASP improvement seen this quarter will appear sustainable. If Client revenue holds but margins continue to decline, the quality of growth will need to be reassessed.
4. 18A Has Provided Internal Validation and 14A Investment Has Begun, but External Customers Remain the Missing Link
Intel’s manufacturing recovery can be divided into five levels of evidence: roadmap, yield, internal volume, external customer production, and external cash returns. Q1 largely completed the first two levels, while Q2 advanced further into the third.
Intel 18A output was approximately 25% above internal targets and grew more than 50% sequentially. 18A-P entered risk production in Q2, and some Panther Lake products are already in high-volume manufacturing. Foundry revenue was $5.765 billion, up 31% year over year, while the operating loss narrowed from $3.168 billion a year earlier to $2.089 billion. Improvements in yield and cycle time are no longer confined to management commentary; they have translated into more wafers, higher revenue, and smaller losses.
The change in Intel 14A is even more significant. Management stated that its transistor performance, yields, and internal metrics are ahead of 18A at the same stage of development. The 0.9 process design kit is scheduled to become available in October 2026, followed by risk production in the second half of 2027 and high-volume manufacturing in 2028. Compared with Q1, when management continued to emphasize that investment depended on sufficient customer commitments, Intel began deploying equipment capital in Q2, indicating that management believes the technology and level of customer engagement have cleared its internal investment threshold.
However, a willingness to invest does not mean customers have already committed to sufficient wafer volumes. JPMorgan estimates external foundry revenue at $293 million, up from $174 million previously, while the EMIB-T advanced-packaging order backlog points to customer ramps in 2027. Yet external revenue remains small relative to the foundry segment’s $5.765 billion of revenue and $2.089 billion quarterly loss, and Intel has not publicly disclosed an anchor customer for 14A. Internal products can prove that a process works. External customers must also assess the design ecosystem, yield stability, delivery credibility, intellectual-property isolation, and long-term capacity commitments—a fundamentally different commercial threshold.
The next strong evidence will not be more statements about “positive customer feedback,” but tape-out decisions following the release of the 0.9 process design kit, customer prepayments, long-term wafer agreements, external revenue, and capacity utilization. Until those indicators emerge, Intel 14A remains primarily a valuable option rather than a cash-generating asset that can be valued like a mature foundry business.
5. Why Capital Expenditure Is Suddenly Accelerating: Both a Vote on Demand and a Financing Test
Intel raised its 2026 capital expenditure forecast from approximately $17 billion to more than $20 billion, with equipment investment increasing approximately 40% year over year. Spending in 2027 will be “significantly higher” than in 2026, with JPMorgan estimating approximately $26 billion. The capital will primarily fund front-end wafer capacity, Intel 3 and 14A equipment, advanced packaging, substrates, and Intel’s US manufacturing network.
The constructive interpretation is that this investment cycle is more tightly constrained by demand than prior cycles. Management says incremental capital will be deployed only after yields, customer commitments, and returns meet established thresholds, supported by long-term agreements, customer prepayments, and an advanced-packaging order backlog. Whereas substantial historical spending funded factory shells and cleanrooms, more capital is now being directed toward equipment that can directly increase output, theoretically shortening the conversion cycle from investment to revenue. US investment tax credits could ultimately cover approximately 35% of qualifying investments, also reducing lifecycle project costs.
The more cautious interpretation is that cash outflows precede both revenue and tax credits. Intel generated $7.006 billion of operating cash flow in Q2 and invested $2.652 billion in property, plant, and equipment, but net partner contributions were negative $12.216 billion. After finance lease payments, company-defined adjusted free cash flow was negative $8.419 billion. This figure includes event-driven settlements of partner funding and should not be annualized directly, but it demonstrates that “partner co-investment” has not eliminated Intel’s ultimate capital obligations.
The company ended the quarter with approximately $29.7 billion in cash and short-term investments, an additional $10 billion revolving credit facility, and approximately $10 billion of monetizable non-core assets. There is no near-term liquidity crisis. The issue is 2027: management acknowledges that achieving positive free cash flow will become more challenging as capital expenditure and back-end supply investment increase, and it has not ruled out raising capital.
This is precisely the per-share value issue that concerns JPMorgan most. Q2 diluted weighted-average shares were approximately 5.104 billion, versus approximately 4.369 billion a year earlier, an increase of roughly 17%. Historical financing and escrow share arrangements have already expanded the denominator. If the next capacity expansion is again financed primarily with equity, higher corporate profits will not fully accrue to common shareholders on a per-share basis. Intel must prove not only that project-level internal rates of return are positive, but also that they exceed the cost of debt and equity capital.
6. $150 Versus $85: Why Target Prices Differ by Nearly 2x When Revenue Forecasts Differ by Only 2%
The conclusions from Goldman Sachs and JPMorgan appear opposed: Goldman maintained a Neutral rating and a 12-month price target of $150, while JPMorgan maintained an Underweight rating and a December 2027 price target of $85. In reality, the firms do not fundamentally disagree on the scale of the business.
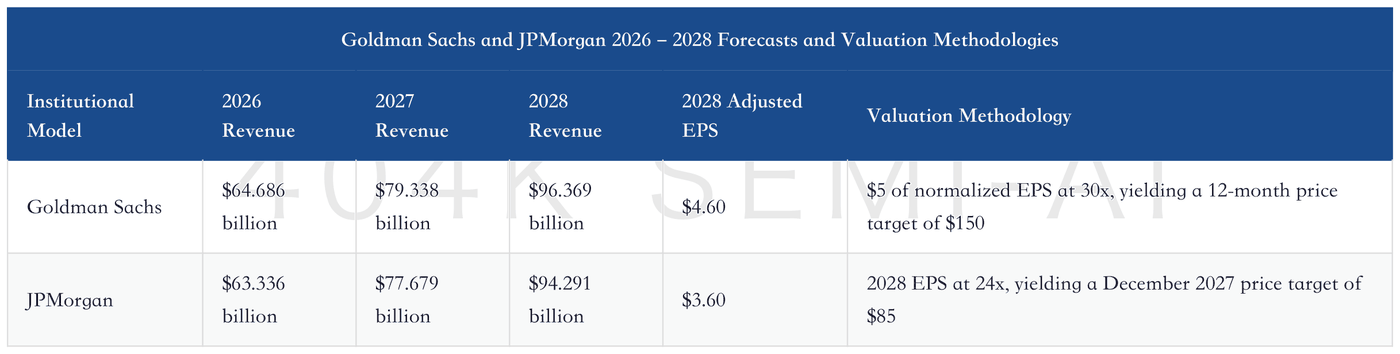
By 2028, the firms’ revenue forecasts differ by only $2.078 billion, or approximately 2.2%, while their adjusted EPS forecasts differ by $1.00, or roughly 28%. The disagreement is therefore not about whether server demand will remain strong, but how much profit will remain after incremental revenue passes through manufacturing costs, foundry losses, depreciation, financing expenses, and share dilution. Goldman Sachs also applies a 30x P/E multiple, compared with JPMorgan’s 24x, amplifying the price-target gap through both earnings and valuation.
Goldman Sachs’ $5 figure represents “normalized” EPS and is not equivalent to a specific-year US GAAP forecast. JPMorgan’s $85 target also corresponds to the more distant date of December 2027. The two targets use different time horizons and definitions and should not be treated as a simple bullish-versus-bearish vote measured on the same basis. A more useful interpretation is that they represent two potential paths for Intel:
The Goldman Sachs path requires sustained double-digit Data Center growth, gross margin approaching 50%, orderly foundry loss reduction, capital expenditure ultimately producing high utilization, and no further material increase in the share count.
The JPMorgan path allows for similar revenue growth but assumes that 2027 free cash flow remains negative $3.476 billion, external foundry conversion proceeds more slowly, and financing-related dilution risk remains higher, warranting a more conservative multiple within the peer range.
The October 2026 release of the 14A process design kit, the expansion of server supply in Q4, the 2027 capital expenditure budget, and external foundry contracts will determine which path prevails.
7. What Actually Matters Over the Next Four Quarters Is More Than a Single Revenue Figure
First, monitor the volume, pricing, and share components of Data Center growth. Revenue should continue to increase as supply comes online. If average selling prices and the 39.5% operating margin are both sustained, the economic value created by long-term agreements and higher-core-count products will be validated. If revenue growth comes only from volume while margins decline rapidly, current profitability includes a substantial scarcity premium.
Second, monitor external foundry revenue and losses. Quarterly losses should remain below $2.1 billion, while external revenue needs to progress from several hundred million dollars toward a visible annualized run rate of approximately $1 billion. Intel Foundry will truly transition from a cost center into a standalone business only when external customer growth outpaces internal eliminations.
Third, monitor evidence of 14A customer adoption. An on-schedule release of the 0.9 process design kit would be a technical milestone; customer tape-outs, prepayments, long-term agreements, and publicly disclosed production plans would be commercial milestones. Without this evidence, estimated capital expenditure of approximately $26 billion will initially increase risk rather than value.
Fourth, monitor free cash flow and the share count. Operating cash flow, capital expenditure, partner contributions, investment tax credits, and finance leases must be assessed together. If capital expenditure rises in 2027 while the fully diluted share count continues to grow at a double-digit rate, improvements in the income statement will be absorbed by the capital structure. If customer prepayments and tax credits fund a greater portion of investment while net debt and the share count remain stable, the market will be more willing to assign a higher valuation multiple.
8. Final Assessment: The Technology and Operating Inflection Points Are Confirmed; the Commercial and Cash Flow Inflection Points Are Not
The most important result from Intel’s Q2 was that its recovery progressed from “cost cutting and easy comparisons” to “high-profit server growth and increased manufacturing output.” Revenue of $16.128 billion, adjusted gross margin of 41.8%, 59% Data Center growth, a narrower foundry loss, and a Q3 revenue guidance midpoint of $16.3 billion collectively confirm the operating inflection point. Intel 18A is also no longer merely a roadmap item, but a production node capable of influencing volume, revenue, and gross margin.
However, the market is no longer pricing Intel merely for survival. Based on the report-date share price of $100.23 used by both research reports, investors are effectively paying in advance for 14A success, sustained server scarcity, lower foundry losses, and normalized earnings. To support a higher valuation, Intel must convert internal manufacturing validation into external customer contracts, operating profit into free cash flow, and capacity-expansion returns into value faster than equity dilution erodes it.
This earnings report therefore does not provide final confirmation; instead, it changes the sequence of validation. The earlier question was whether Intel could manufacture the wafers. The question now is whether it can sell incremental wafers to external customers, deliver them at sufficiently high gross margins, and retain the resulting cash for common shareholders. The answer to the first question has improved materially. The second question accounts for the $65 gap between Goldman Sachs’ $150 target and JPMorgan’s $85 target.