
Intel Q2 2026 Earnings Deep Dive: $16.1 Billion in Revenue, 59% Data Center Growth, and Why Adjusted Free Cash Flow Was Negative $8.4 Billion
目录
TL;DR
1. Quantifying the “Beat”: Actual Results Have Rendered the Previous Model Obsolete
2. Quality of Revenue Growth: Data Center Was Strongest, Client Was Most Complex, and Foundry Remained Loss-Making
Data Center: From “Industry Recovery” to “Earnings Delivery”
Client: Revenue Resilience Beat the Model, but Margins Issued a Warning
Intel Foundry: Yield Recovery Is Finally Visible in the Numbers, but External Customers Remain Unquantified
3. Loss Per Share of $2.16: Core Operations Were Profitable, So Why Was the Net Loss Still $11 Billion?
Cost Discipline: Operating Leverage Came From More Than Revenue Growth
4. Where Did the Negative $8.4 Billion of Free Cash Flow Come From?
Two Cash-Flow Definitions Are Needed to Avoid an Extreme Conclusion
5. Intel 18A Evidence Improves: From “Roadmap” to “Production,” but Not Yet to External Revenue
AI Revenue Is No Longer Dependent Solely on Traditional CPUs
6. Revisiting Bernstein’s Preview: Five Calls—Two Disproved, Two Confirmed, and One Still Unresolved
7. Recalculating Valuation: Revenue Estimates, Net Debt, and the Share Count All Need Updating
8. Q3 Outlook: Strong Revenue Midpoint, but Sequential Growth Has Plateaued
9. Final Assessment: The Operating Inflection Is Established; the Cash-Flow Inflection Is Not
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
This was a strong earnings report—and an expensive one. Intel drove revenue to $16.1 billion through data center growth, yield improvements, and foundry recovery, but cash flow offered a sobering reminder: the turnaround is far from complete.
TL;DR
Intel’s actual results comprehensively beat Bernstein’s model published two days before earnings. Bernstein forecast Q2 revenue of $14.311 billion, an adjusted gross margin of 39.0%, and adjusted EPS of $0.20; Intel reported $16.128 billion, 41.8%, and $0.42, respectively. Revenue was $1.817 billion higher, gross margin was 2.8 percentage points higher, and EPS was $0.22 higher. More importantly, the midpoint of Intel’s Q3 revenue guidance was $16.3 billion, $1.435 billion above Bernstein’s forecast, indicating that this was not simply a case of orders being recognized early.
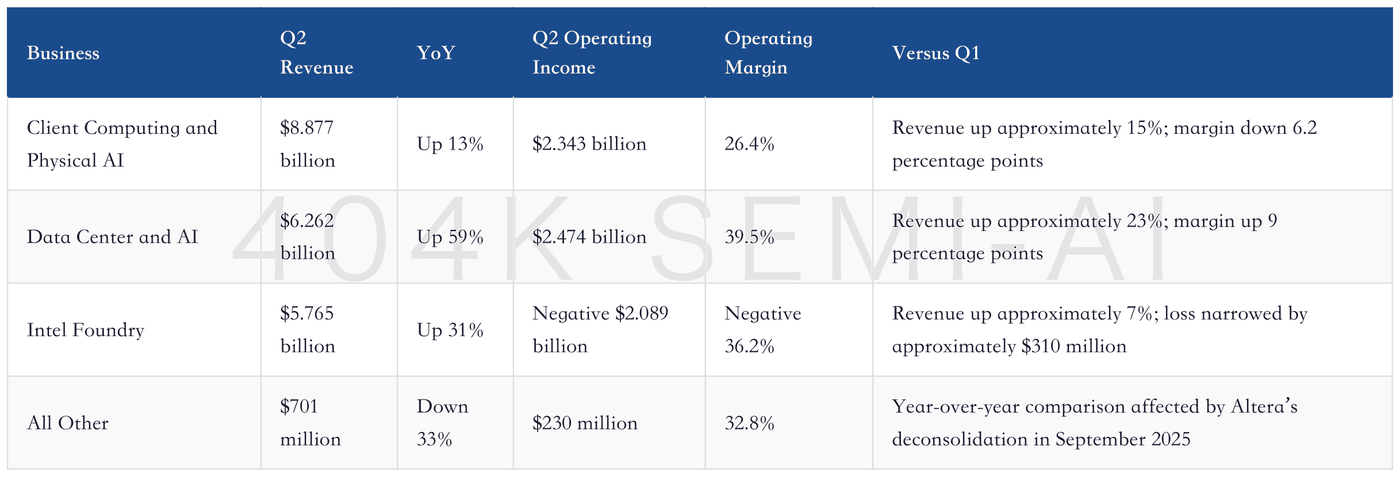
Data Center and AI was the highest-quality component of the quarter. Revenue reached $6.262 billion, up 59% year over year and approximately 23% sequentially; operating income was $2.474 billion, with operating margin rising from 30.5% in Q1 to 39.5%. AI is driving higher CPU density and more long-term agreements, while custom silicon revenue nearly tripled year over year. Intel has finally translated the thesis that “AI also needs CPUs” into reported earnings.
Client revenue was strong, but did not deliver comparable operating leverage. Client Computing and Physical AI revenue was $8.877 billion, up 13% year over year and approximately 15% sequentially; however, operating margin fell from 32.6% in Q1 to 26.4%. Intel attributed the pressure to component inflation. This validated Bernstein’s concerns about PC costs and demand, although revenue resilience was far better than its model assumed.
Intel Foundry is recovering, but is not yet self-funding. Foundry revenue was $5.765 billion, up 31% year over year; the operating loss narrowed from $3.168 billion a year earlier to $2.089 billion, with the loss margin improving from negative 71.7% to negative 36.2%. Better yields and shorter cycle times created incremental supply, Intel 18A-P entered risk production, and some Panther Lake products are already in high-volume manufacturing. Even so, a quarterly loss of approximately $2.1 billion still consumes nearly half of the product businesses’ operating income.
The $2.16 GAAP loss per share does not directly imply a collapse in the core business, but it cannot be ignored entirely. Intel generated $1.796 billion in GAAP operating income this quarter. The substantial net loss primarily reflected a $12.529 billion non-operating loss from marking escrowed shares to market. Excluding this item, stock-based compensation, and other adjustments, adjusted net income was $2.197 billion, or $0.42 per share. This was not an operating loss, but it represents potential value transfer and dilution and therefore cannot simply be dismissed as immaterial.
Negative adjusted free cash flow of $8.419 billion is the strongest counterpoint to the earnings beat. Q2 operating cash flow was $7.006 billion, leaving substantial headroom after $2.652 billion of capital expenditures. However, net partner contributions were negative $12.216 billion; together with finance lease payments, this resulted in negative adjusted free cash flow of $8.419 billion. The growth is real, but so is the cash consumption associated with capital deployment and partner funding settlements.
1. Quantifying the “Beat”: Actual Results Have Rendered the Previous Model Obsolete
On July 21, 2026, Bernstein published Intel, AMD: Is Dawn Breaking? Q2 2026 Preview. Its base case was that Intel would struggle to create a major positive surprise merely by beating Q2 guidance; the real tests would be Q3, server CPU share, Intel 18A yields, and free cash flow. Two days later, Intel delivered an answer far more aggressive than that model anticipated.
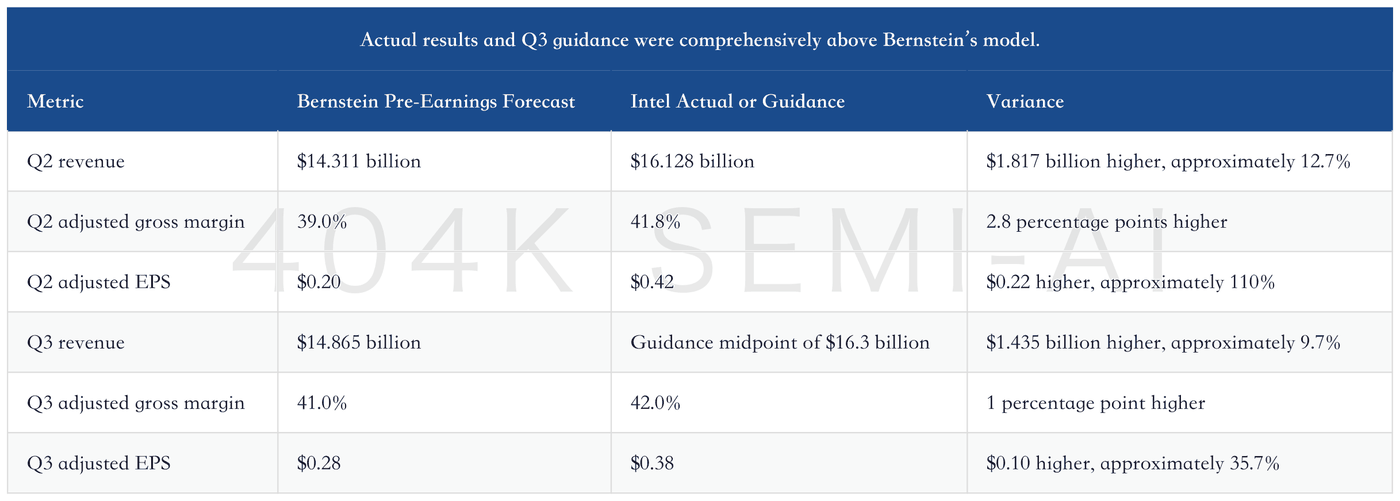
Page 10 of Bernstein’s preview provided its quarterly model, while pages 1 and 3 of Intel’s earnings release and pages 5 and 11 of its presentation provided actual results and Q3 guidance. Q2 revenue was not only $1.817 billion above Bernstein’s forecast, but also approximately $1.8 billion above the midpoint of Intel’s April guidance. Adjusted gross margin and EPS exceeded the April outlook by 2.8 percentage points and $0.22, respectively. The simultaneous upside in revenue, gross margin, and EPS indicates that the variance was not merely due to early shipment of a product batch; it also reflected higher output, a better product mix, and meaningful operating leverage.
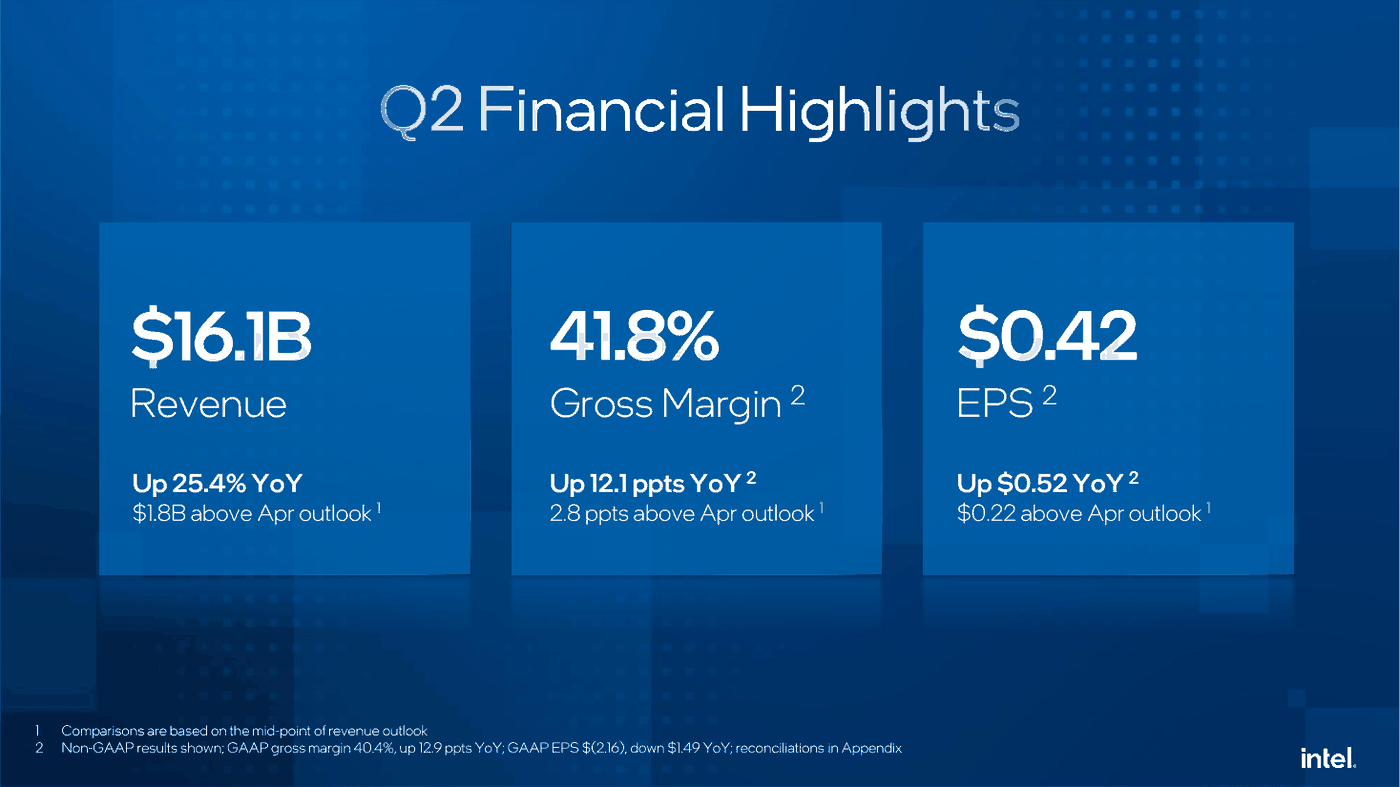
Management offered a two-part explanation. On the demand side, AI computing drove demand for CPUs, custom silicon, advanced packaging, and wafer foundry services. On the supply side, higher fab yields and shorter production cycle times enabled output above the company’s original plan. Demand determines the revenue ceiling, while supply determines whether that demand can be converted into revenue and gross profit within the quarter. Both must occur simultaneously to produce the combination of $16.1 billion in revenue and a 41.8% adjusted gross margin.
There was another, more easily overlooked signal. Intel generated approximately $13.6 billion in Q1 revenue, which jumped to $16.128 billion in Q2, while the midpoint of Q3 guidance was another $16.3 billion. Q2 represented a step-up, and Q3 is not expected to revert to the previous baseline. Even if sequential revenue growth slows significantly from Q2’s elevated rate, the $16.3 billion midpoint still implies that most of the current supply-and-demand improvement is sustainable rather than a one-off Q2 release followed by an immediate reversal.
2. Quality of Revenue Growth: Data Center Was Strongest, Client Was Most Complex, and Foundry Remained Loss-Making
Looking only at consolidated revenue understates the structural changes in this earnings report. Intel Products generated $15.139 billion in revenue, up 28% year over year, and $4.817 billion in operating income, up approximately 79%. Intel Foundry, meanwhile, remained primarily an internal manufacturing operation, generating $5.765 billion in revenue, of which $5.477 billion was eliminated internally. The real drivers of operating leverage were the sharp increase in Data Center margins and the narrowing of Foundry losses.
Data Center delivered the strongest operating leverage, while Foundry remained loss-making.
Data Center: From “Industry Recovery” to “Earnings Delivery”
Data Center and AI represented the clearest upside surprise. Revenue of $6.262 billion increased by nearly $1.2 billion from approximately $5.1 billion in Q1; operating income rose from approximately $1.5 billion to $2.474 billion, with incremental revenue translating almost directly into profit. Operating margin reached 39.5%, 23.4 percentage points above the 16.1% recorded a year earlier and 9 percentage points above Q1.
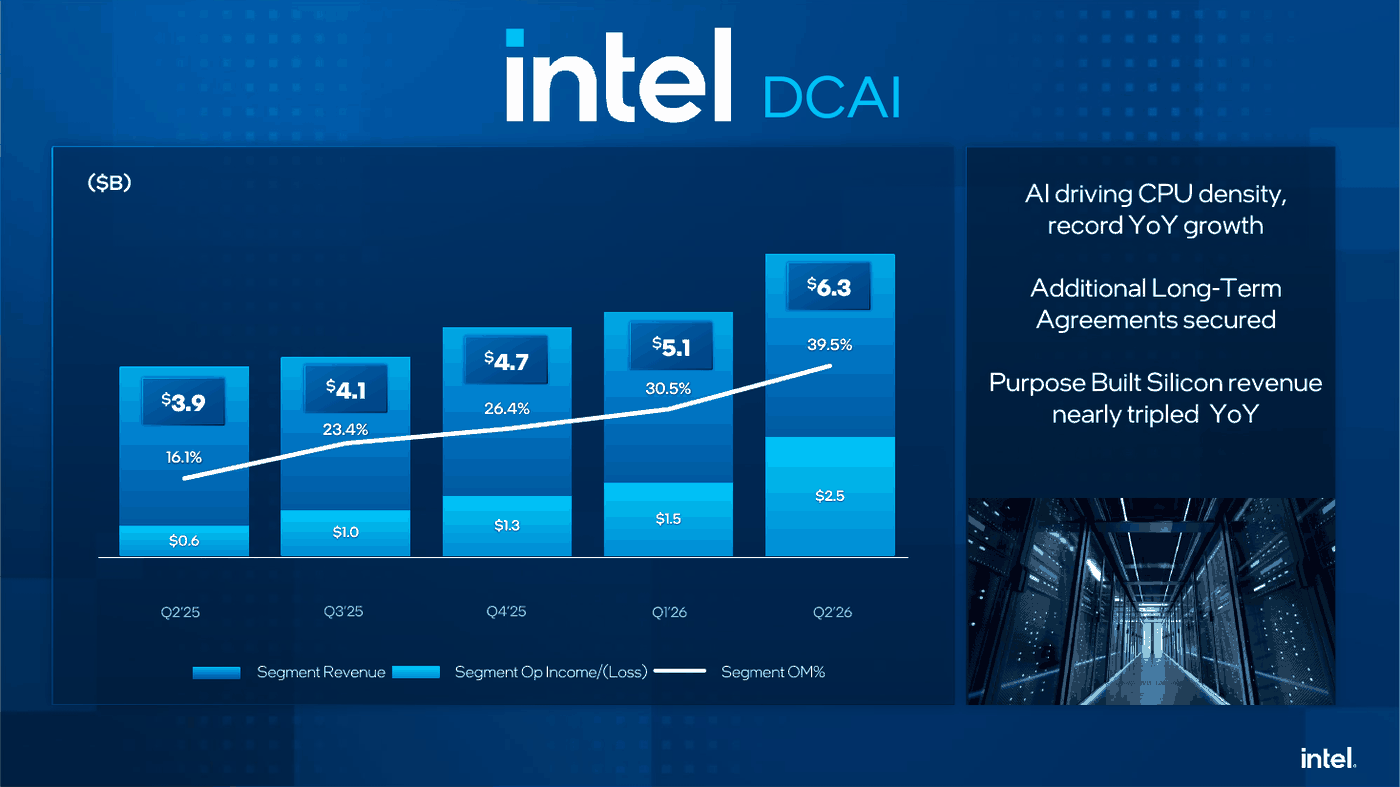
On page 8 of the presentation, management provided three explanations: AI is driving higher CPU density, Intel is securing more long-term agreements, and custom silicon revenue nearly tripled year over year. These correspond to three types of growth:
Higher CPU density means each accelerated computing cluster adds not only GPUs, but also general-purpose compute capacity for hosts, orchestration, storage, and inference.
More long-term agreements suggest that current demand is not entirely driven by short-term inventory grabs; some customers are willing to secure supply through longer-duration contracts.
Nearly threefold growth in custom silicon indicates that Intel is no longer relying solely on conventional x86 CPUs and is beginning to generate incremental revenue from specialized computing and related manufacturing.
This also confirms the most important bullish thesis in Bernstein’s preview: AI infrastructure is indeed expanding the addressable market for server CPUs. However, Intel did not disclose server CPU unit share, revenue share, or average selling prices, so the results do not yet prove that the company has reversed its market-share losses. An expanding market can allow Intel to deliver strong growth even while losing share. Only subsequent share stabilization would upgrade this from an “industry tailwind” to a “recovery in product competitiveness.”
Client: Revenue Resilience Beat the Model, but Margins Issued a Warning
Client Computing and Physical AI generated $8.877 billion in revenue, up 13% year over year and significantly higher than approximately $7.7 billion in Q1. The result was far stronger than Bernstein’s cautious assumption of a 4%–5% year-over-year decline in global PC shipments. It also suggests that PC unit shipments are not the only variable explaining Intel’s client revenue. Product mix, channel restocking, AI PCs, edge computing, and physical AI may all have contributed incremental revenue.
However, margins did not expand alongside revenue. The segment generated $2.343 billion in operating income, below approximately $2.5 billion in Q1, while operating margin fell from 32.6% to 26.4%. On page 7 of the presentation, management explicitly cited component inflation. Strong revenue combined with weak margins may indicate higher bill-of-materials costs, product-mix changes, or a lag in passing through higher prices. Intel did not quantify the precise contribution of each factor, so the margin decline cannot be attributed entirely to a single cause.
