
Intel Deep Update: Goldman Sees $150; How Server CPU Tailwinds and the Foundry Option Reprice the Stock
目录
TL;DR
1. Start With One Sentence: Intel Has Rallied From a “Turnaround” Into “Option Pricing”
2. Server CPU Is the Real Inflection: AI Inference Does Not Only Buy GPUs; It Also Buys the “Scheduling Layer”
3. But the CPU Dividend Is Not Intel’s Alone: AMD Competes on Performance, Arm on Architecture, and Intel on the Delivery Window
4. The Right Way to Read Foundry: Advanced Packaging Monetizes First, Wafer Foundry Enters the Model Later
5. How the $150 Price Target Is Derived: Goldman Is Buying Long-Term EPS, Not 2026 EPS
6. The Core of the Financial Model Is Not Revenue, but Whether Gross Margin Can Recover Above 50%
7. How to Use Sell-Side Disagreement: Do Not Pick the Most Bullish Target Price, Decompose Who Is Betting on What
8. Investment View: Intel Can Still Be Followed, but the Framework Must Shift from “Believing the Story” to “Checking the Deliverables”
9. Risks and Disproof: The Biggest Risk Is Not Weak CPU Demand, but Options That Fail to Enter the Financials
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Intel’s rerating has moved from whether it can survive to how much the market is willing to pay for a server CPU recovery and the Foundry option. Goldman assigns a $150 price target but only a Neutral rating. The key is not whether the story is real, but the pace of delivery, gross-margin repair, external customer wins, and whether the stock still has enough margin of safety after already pulling forward upside.
TL;DR
Goldman’s Neutral rating is not bearish on Intel. The $150 target price alongside a Neutral rating means the sell side acknowledges the server CPU and Foundry options have improved, while also believing the stock has already priced in a lot of the future.
The hardest near-term fundamental evidence is in DCAI. Intel’s 2026 Q1 results show server CPU demand is entering the financials; the next test is whether revenue growth can continue driving operating-margin repair.
Server CPU is the profit-validation point. Agentic AI is making CPUs foundational again for inference, orchestration, and enterprise workflows, but AMD and Arm are still taking share. Intel cannot rely only on a higher TAM.
For Foundry, watch packaging before wafers. Advanced packaging is closer to orders and revenue; external wafer customers are still more of a long-dated item, and meaningful P&L; impact is more likely after 2028.
Valuation is no longer a low-base recovery. Goldman applies a high multiple to normalized EPS to reach its target price. The market is buying the long-term profit curve, not a single-quarter earnings beat.
The biggest upside comes from dual delivery. If server CPUs, advanced packaging, and external wafer customers all break through, Intel can move from a turnaround asset to a platform asset; otherwise, it remains a cyclical recovery.
The more rational action is to track validation rather than chase blindly. Key markers are DCAI revenue, 18A yield, 14A design commitments, EMIB-T customers, narrowing Foundry losses, and free cash flow.
1. Start With One Sentence: Intel Has Rallied From a “Turnaround” Into “Option Pricing”
The interesting part of Goldman’s initiation is not that it assigns a $150 target price, but that it gives only a Neutral rating despite a seemingly high target. In other words, Goldman acknowledges Intel’s fundamentals have indeed improved, and that both server CPUs and foundry offer upside, but it believes the market has already paid a sizable option premium upfront.
This is a very different trade from Intel in 2025 and early 2026. Back then, the market was asking whether Intel 18A could work, whether client and server CPUs would continue losing share to AMD, and whether Foundry losses would overwhelm the balance sheet. Now the question is: if server CPUs truly enter an AI inference cycle, if advanced packaging starts taking external customers, and if Intel Foundry wins major wafer foundry orders after 2028, how much of that is already reflected in the current share price?
“stock largely reflects it.”
Goldman’s answer is restrained: server CPU tailwinds are clear, Foundry provides an upside option, but the stock has largely reflected both. The $150 target price corresponds to 30x normalized EPS. Goldman is using $5 of long-term earnings power, not short-term 2026 or 2027 EPS. In other words, it is repricing Intel away from a “low-valuation manufacturing asset” and back into the lane of whether it can deliver a long-term profit curve.
That is the key point in this update. Intel is no longer just a mix of book-value discount, U.S. manufacturing premium, policy protection, and cyclical recovery. It is beginning to be priced as one of the few companies in AI infrastructure that can sell CPUs, advanced packaging, and wafer capacity at the same time. The issue is that the certainty of these three items differs: server CPUs are entering the financials, advanced packaging is entering orders, and external wafer foundry is still mostly in the model.
Intel Q1’26 Earnings Beat Across the Board: Deep Collaboration With Musk, CPU Enters NVIDIA Rubin, AI ASIC Doubles, and Intel 18A’s First Volume-Production Run
2. Server CPU Is the Real Inflection: AI Inference Does Not Only Buy GPUs; It Also Buys the “Scheduling Layer”
The hardest change in Intel’s 2026 Q1 was in DCAI. Revenue, gross margin, and EPS all exceeded the high end of guidance. The data-center business was clearly stronger than client seasonality, and management’s Q2 guide also kept DCAI on a sequential-growth trajectory. This aligns with updates from multiple sell-side firms: near-term momentum is not only from client inventory replenishment; server CPUs are genuinely tightening.
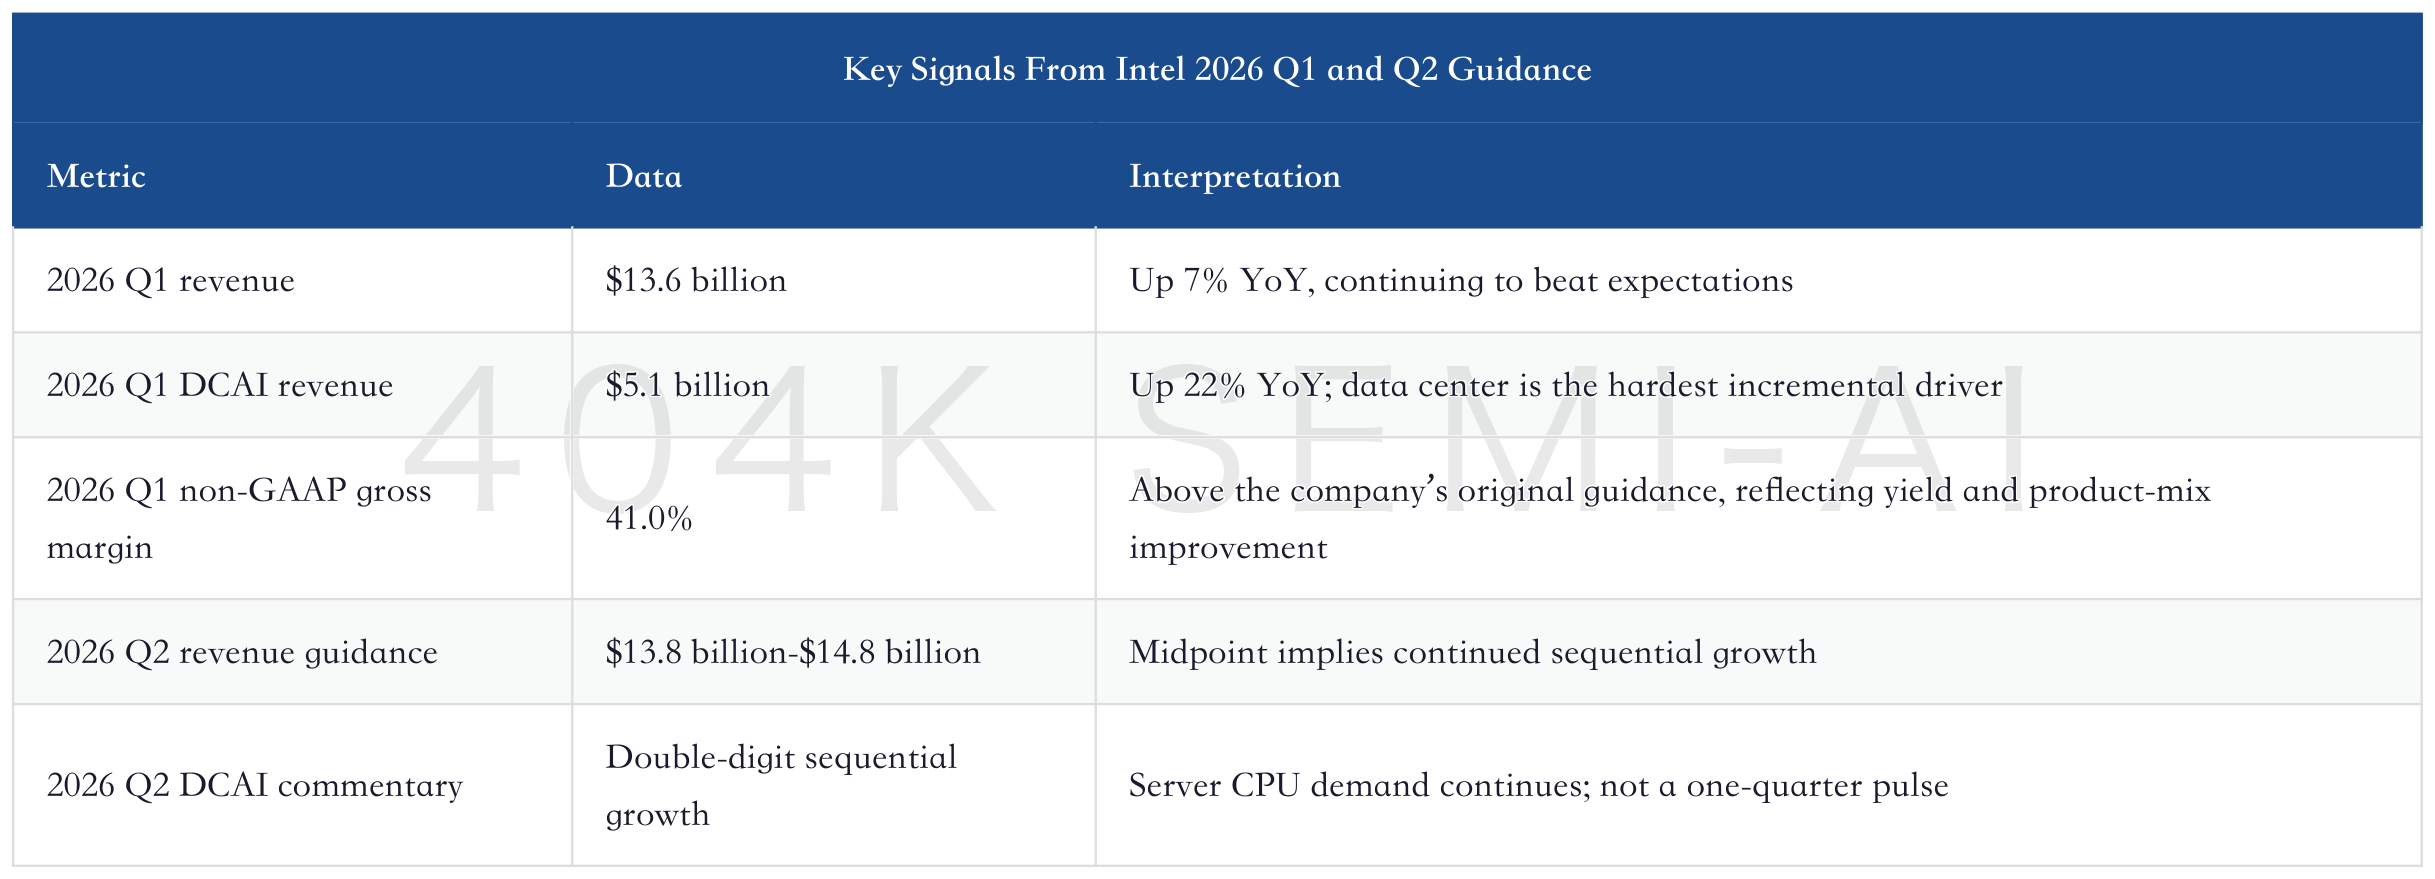
The role of CPUs in AI infrastructure needs to be reframed from “compute chip” to “control plane.” In the training era, the market cared most about GPUs. In the inference and Agentic AI era, enterprise workflows, data access, model routing, security isolation, network orchestration, databases, storage, and action execution all require CPUs. GPUs remain the most expensive component, but CPUs determine whether those GPUs can be scheduled, reused, and run reliably in real business environments.
“the CPU is reasserting itself as the indispensable foundation of the AI era.”
This line comes from Intel’s 2026 Q1 earnings-call messaging. The key is not the slogan, but that there is already financial evidence behind it. DCAI grew 22% YoY. The company also said Xeon 6 is being used as the host CPU for NVIDIA DGX Rubin NVL8, Google continues to deploy Xeon, and SambaNova is working with Intel on heterogeneous inference architecture. Server CPU is not a distant PowerPoint story; it is already moving from customer selection into revenue growth.
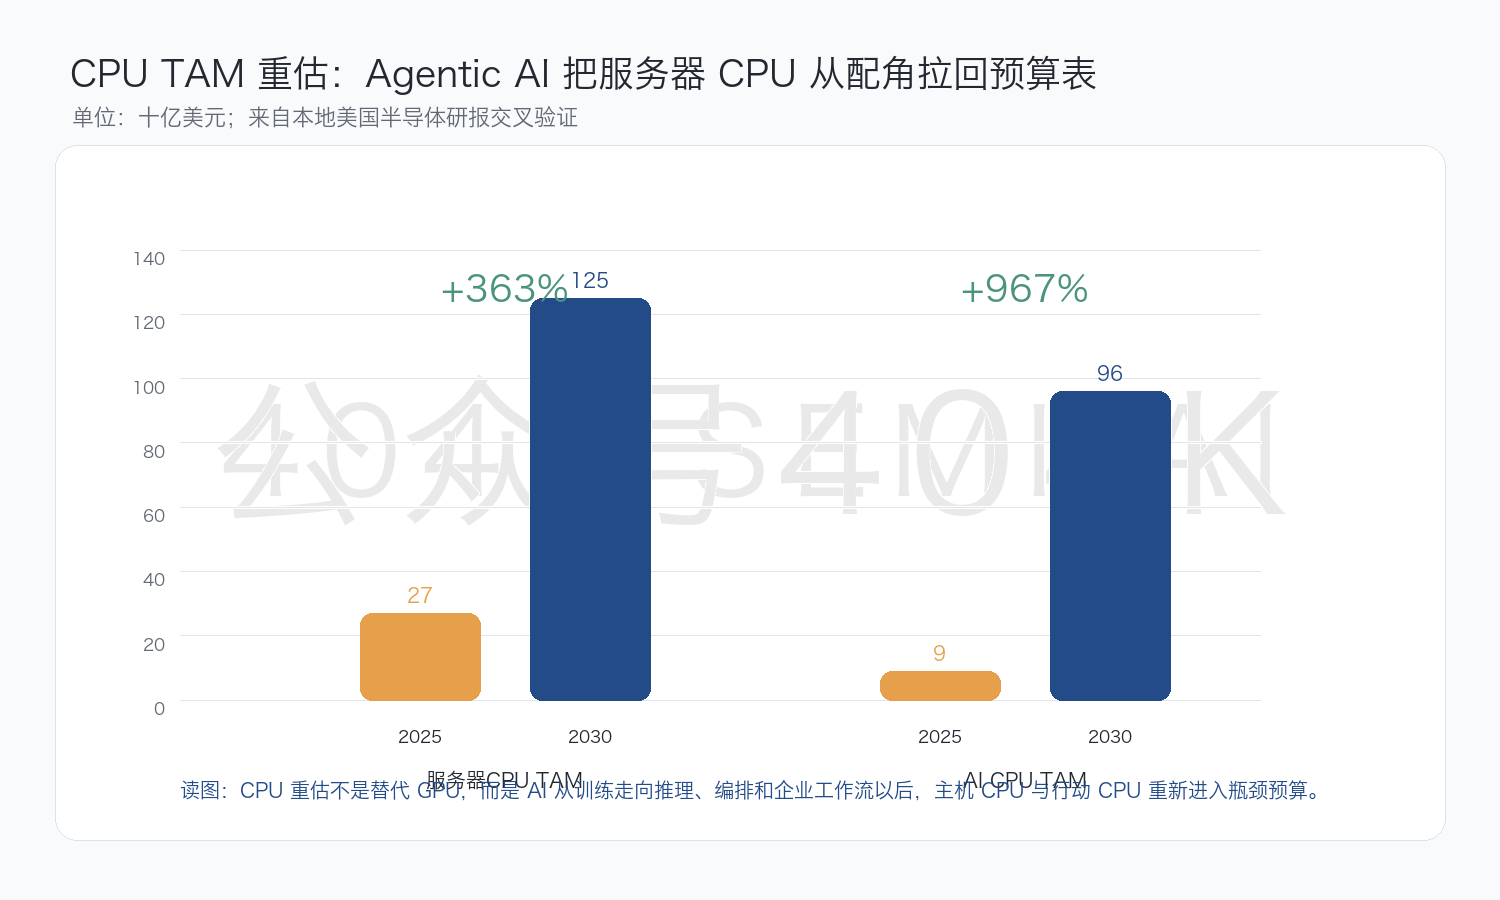
Multiple research reports are more aggressive in raising CPU TAM. U.S. semiconductor research puts the total server CPU TAM at $125 billion in 2030, with AI CPU rising from $9 billion in 2025 to $96 billion in 2030, implying about a 61% CAGR. That number is not the same as Intel revenue, but it explains why the market is willing to revisit Intel: if CPUs move from a “supporting role” in server budgets back to a must-have layer in AI inference infrastructure, Intel is at least back in the discussion.
AI CPU TAM Revaluation: $132 Billion in 2030 and the Repricing of AMD and Intel
CPU Returns to the Center of AI Inference Infrastructure
3. But the CPU Dividend Is Not Intel’s Alone: AMD Competes on Performance, Arm on Architecture, and Intel on the Delivery Window
The upward revision to the server CPU TAM only answers whether the industry has incremental growth; it does not answer how much Intel can capture. Goldman Sachs’ view is relatively balanced: Intel benefits from the enterprise x86 installed base, software compatibility, the host CPU position, and improving internal manufacturing, but AMD still has a stronger medium-term product roadmap, while Arm will continue taking share in cloud providers’ self-developed CPUs and specific workloads.
Intel’s most immediate advantage is the delivery window. In 2026, industry supply is tight: GPUs, HBM, ABF, advanced packaging, full server systems, and power are all queued up, and CPUs have been pulled back into the bottleneck chain. If Intel can allocate more Intel 3, Intel 7, and 18A-related capacity to server CPUs, it can turn tight supply into near-term upside for ASPs, gross margin, and DCAI profit elasticity. HSBC is more optimistic, arguing that server CPUs are a bigger near-term catalyst than Foundry, even raising its price target from $50 to $95 and upgrading the stock to Buy.
“server CPU bigger catalyst than foundry”
This divergence matters. Both Goldman Sachs and HSBC see server CPU tailwinds, but HSBC believes the market is underestimating DCAI revenue and gross-margin elasticity in 2026-2027, while Goldman Sachs believes the share price has already priced in a good amount of long-term improvement. This is not about who is right or wrong; it is about different time frames: one is looking for near-term earnings surprises, while the other is looking at the odds after discounting long-term optionality.
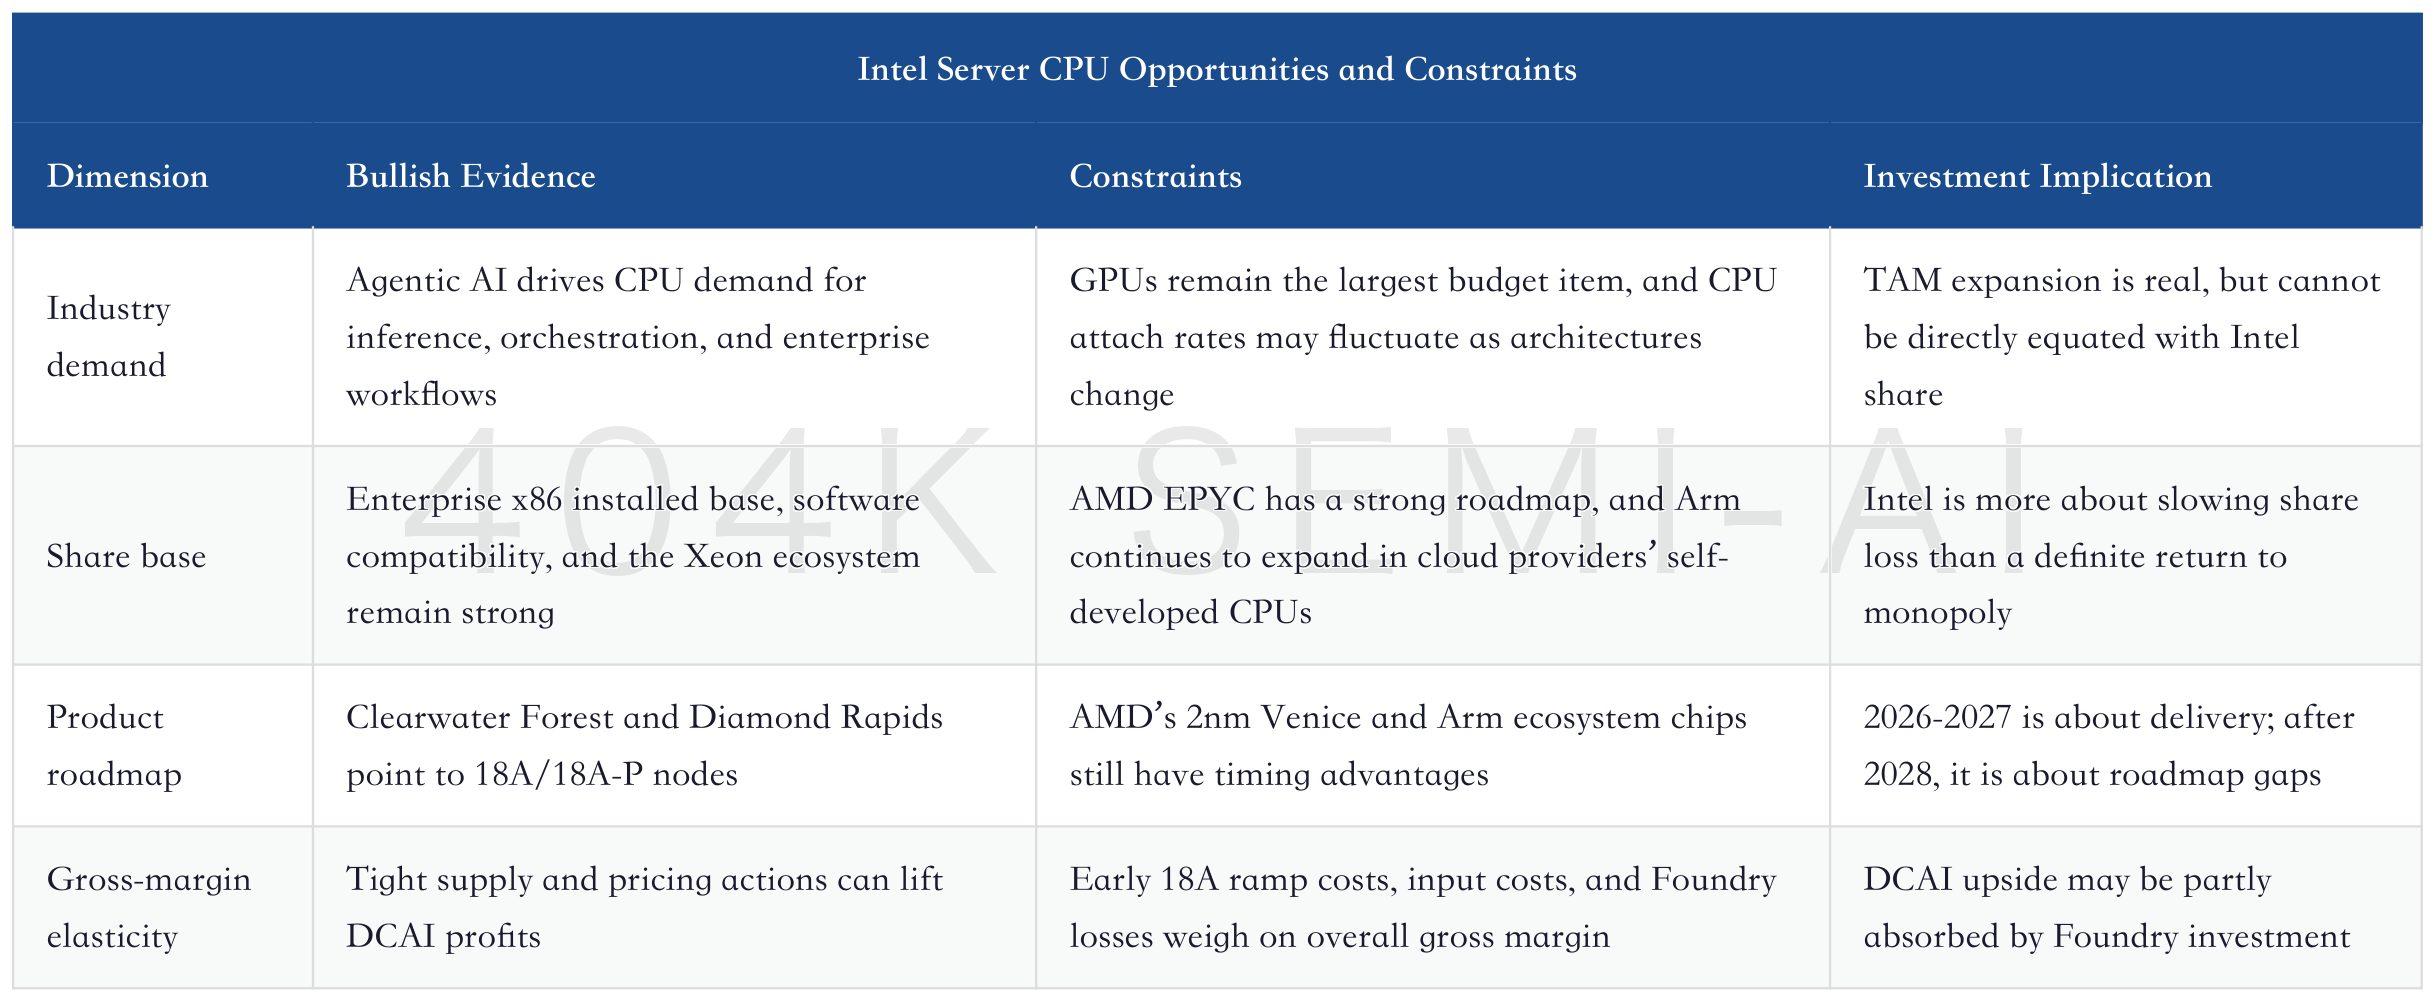
Therefore, Intel’s best medium-term scenario is not “re-monopolizing CPUs,” but “using tighter supply, higher ASPs, and a better product cadence in the AI inference cycle to first restore DCAI margins.” This path is more realistic and better suited to earnings tracking: DCAI revenue, server CPU shipments, ASPs, order visibility, and operating margin are more informative than simply saying “CPU is back.”
Arm Deep Dive: The Arm Tax Every CSP Self-Developed CPU Must Pay, and the Biggest Direct Beneficiary of Nvidia’s CPU Surge
4. The Right Way to Read Foundry: Advanced Packaging Monetizes First, Wafer Foundry Enters the Model Later
Foundry is Intel’s largest option, and also the part most easily over-linearly extrapolated by the market. Goldman Sachs splits Foundry into two layers: advanced packaging in the short term, and external wafer foundry in the long term. This distinction matters because the two have completely different levels of execution difficulty.
Advanced packaging is closer to orders and revenue. Intel has technology reserves including EMIB, Foveros, EMIB-T, and HBI. Against the backdrop of tight CoWoS capacity, larger AI accelerator die sizes, and rising integration complexity between HBM and logic die, customers are more willing to seek a second source. In June, Intel announced the appointment of Lee Seok-hee to lead Foundry advanced packaging, system integration, and back-end manufacturing, turning advanced packaging into a more focused business unit. This is consistent with Goldman Sachs’ view that advanced packaging comes first.
External wafer foundry is more like a profit option after 2028. Goldman Sachs expects Intel’s external advanced packaging revenue to rise from about $500 million in 2026 to about $10.1 billion in 2030, while external wafer revenue starts at about $2.7 billion in 2028 and reaches about $11.0 billion by 2030. In other words, what can truly change Foundry’s P&L; is not external wafer revenue in 2026, but whether customers are willing after 2028 to entrust Intel with key tiles, HPC, mobile, and consumer electronics chips.
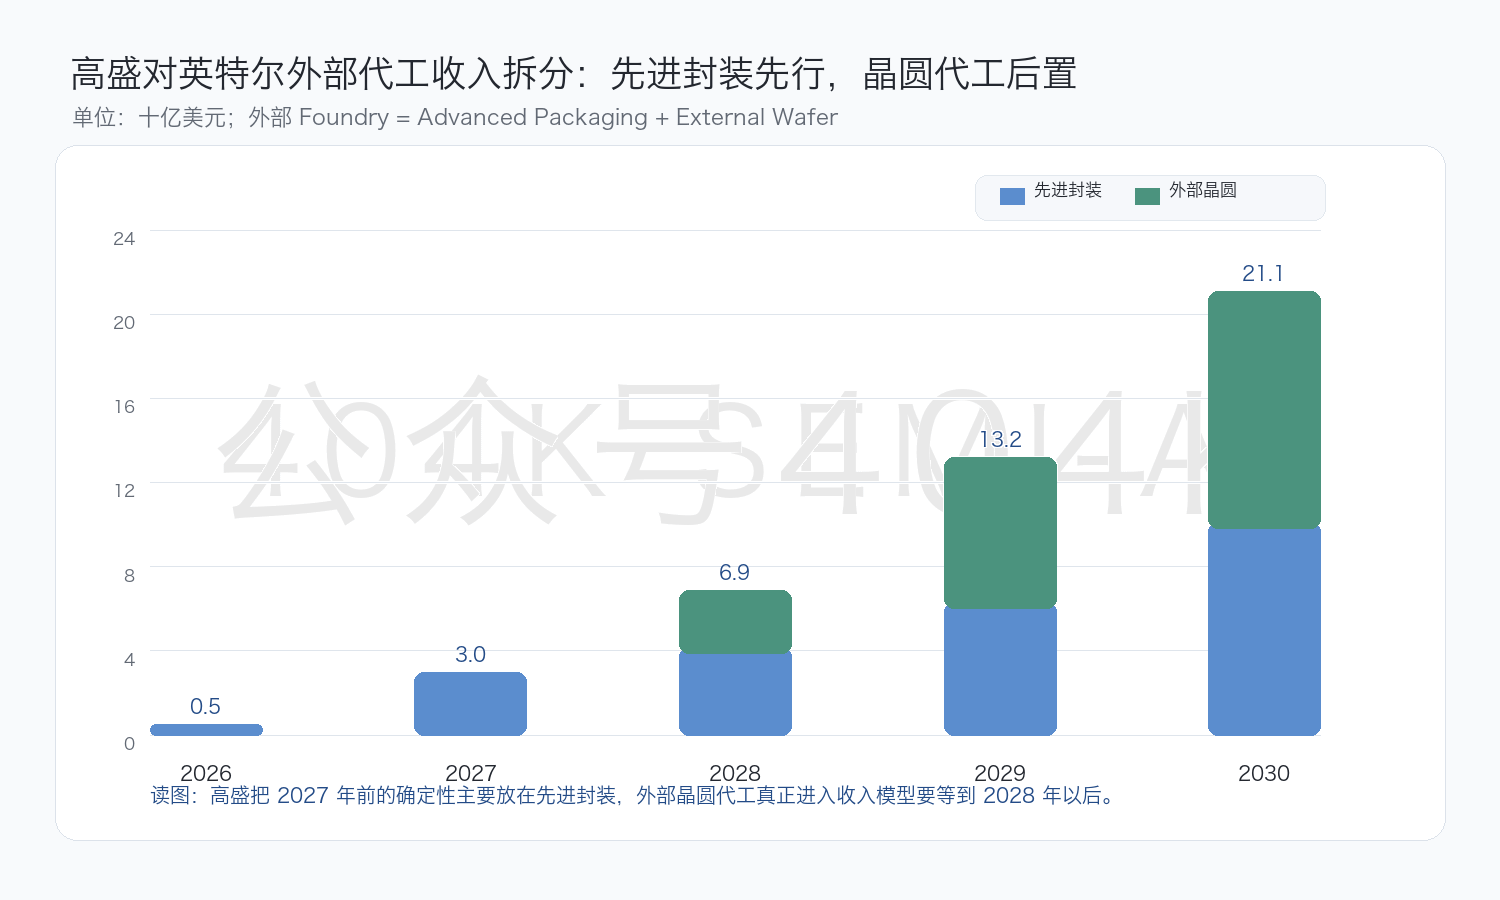
Two questions need to be separated here. The first is whether Intel has the capability to win packaging orders; the answer is becoming more positive. The second is whether Intel can secure genuinely high-volume external wafer customers on 18A, 18A-P, and 14A; that has not yet been proven. Intel itself also warned in its 10-Q risk disclosures that if 14A cannot secure sufficient customer demand and internal product design wins, the advancement of next-generation nodes may face adjustment risk. This risk does not affect the near-term recovery in server CPUs, but it does affect the valuation ceiling for the Foundry option.
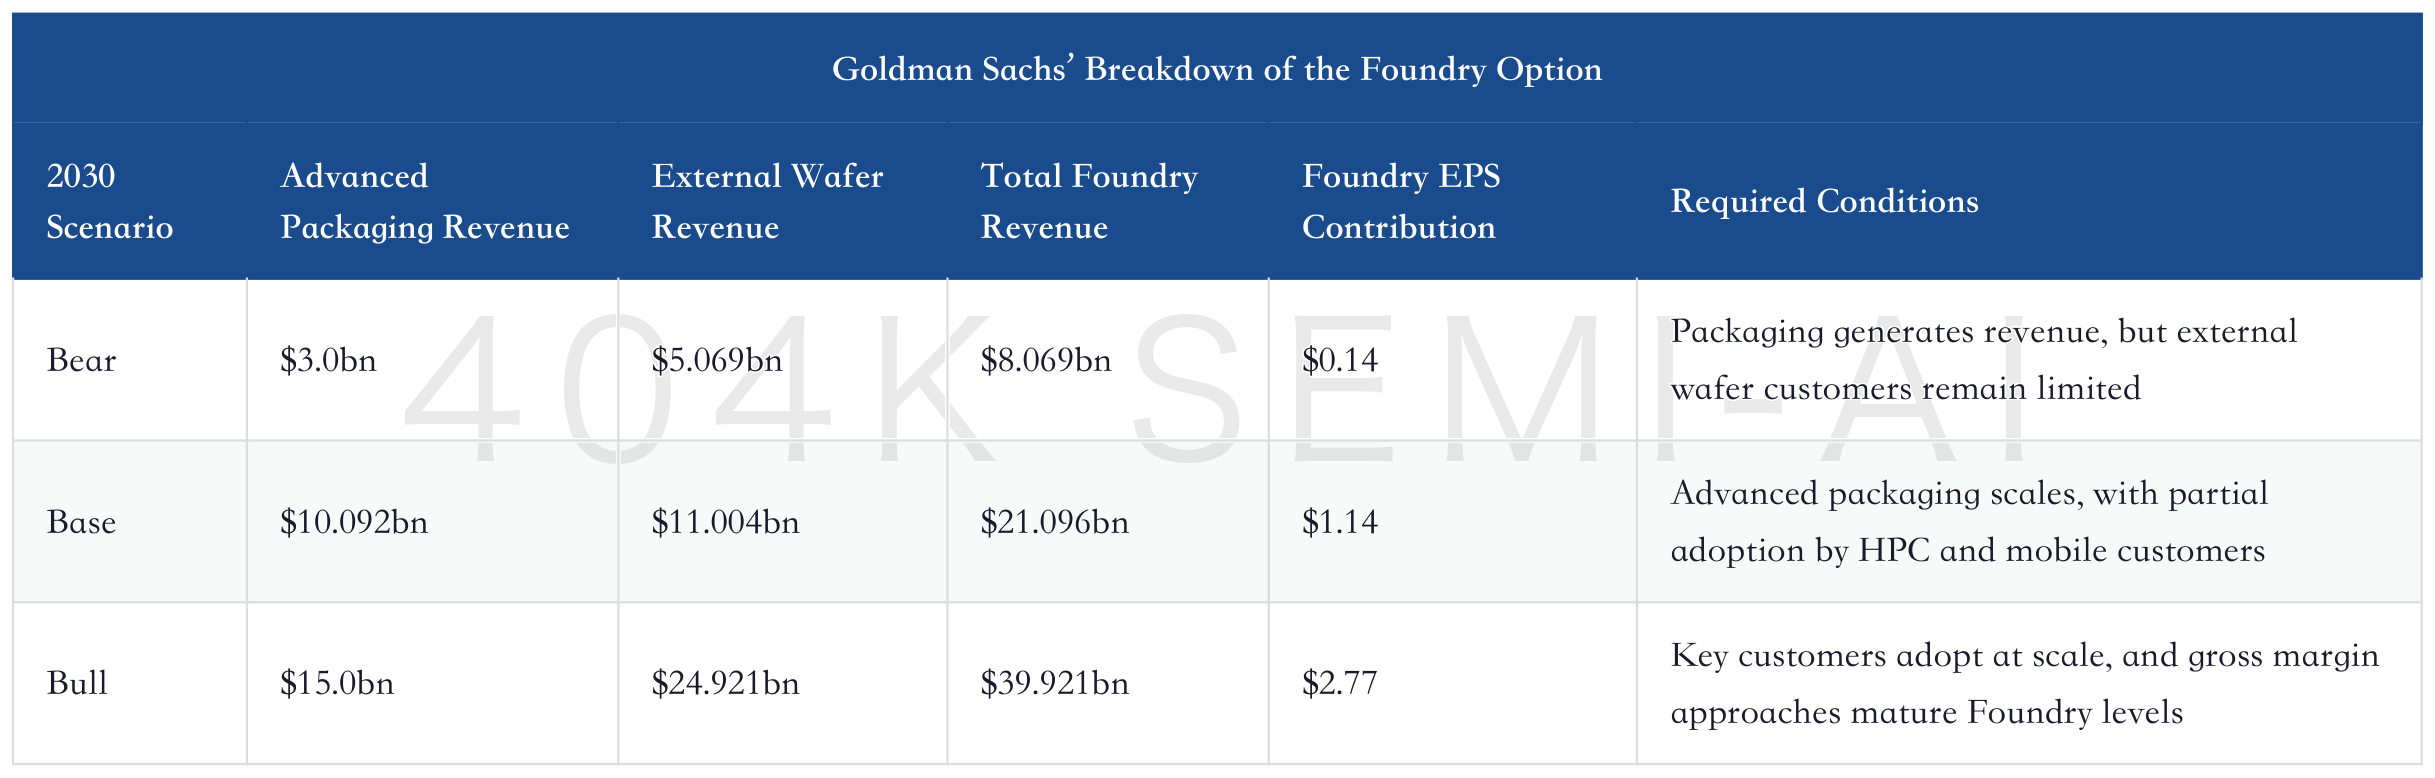
A European semiconductor research report quantifies the Apple foundry option more specifically: if Intel wins foundry work for iPad and Mac processors, it could imply about €1.8 billion of lithography equipment revenue opportunity for ASML; if the optimistic scenario extends to iPhone processors and modems, EUV demand would be larger, and demand for hybrid bonding equipment would also expand significantly. This scenario analysis does not mean Apple orders have already been secured, but it explains why the market is willing to pay an option premium for Intel Foundry: once external customers materialize, the benefits would spread from Intel across the entire chain of EUV, deposition, bonding, packaging, and substrates.
Intel CEO Lip-Bu Tan: Reshaping the Semiconductor Supply Chain
JCET Deep Dive: From Cyclical OSAT to the AI Advanced Packaging Gatekeeper, and How Chiplets, XDFOI, and Domestic Compute Revalue the OSAT Leader
5. How the $150 Price Target Is Derived: Goldman Is Buying Long-Term EPS, Not 2026 EPS
Goldman’s valuation approach is straightforward: apply a 30x multiple to $5 of normalized non-GAAP EPS to arrive at a $150 price target. That multiple is not low, because Intel is no longer being valued purely as a traditional CPU cyclical stock. Its valuation now embeds a server CPU recovery, a Foundry option, gross margin repair, and a re-rating of U.S. advanced manufacturing assets.
But this also explains why Goldman does not rate the stock Buy. Under Goldman’s model, Intel’s non-GAAP EPS is about $1.05 in 2026, $1.75 in 2027, and $3.35 in 2028. The $150 target is not based on 2026 earnings. It discounts further-out gross margin improvement, DCAI growth, and Foundry contribution into today’s price. If investors are buying 2026 earnings upside, the stock can continue to be driven by results. If they are buying a successful 2030 Foundry outcome, the current price is no longer a “free option.”
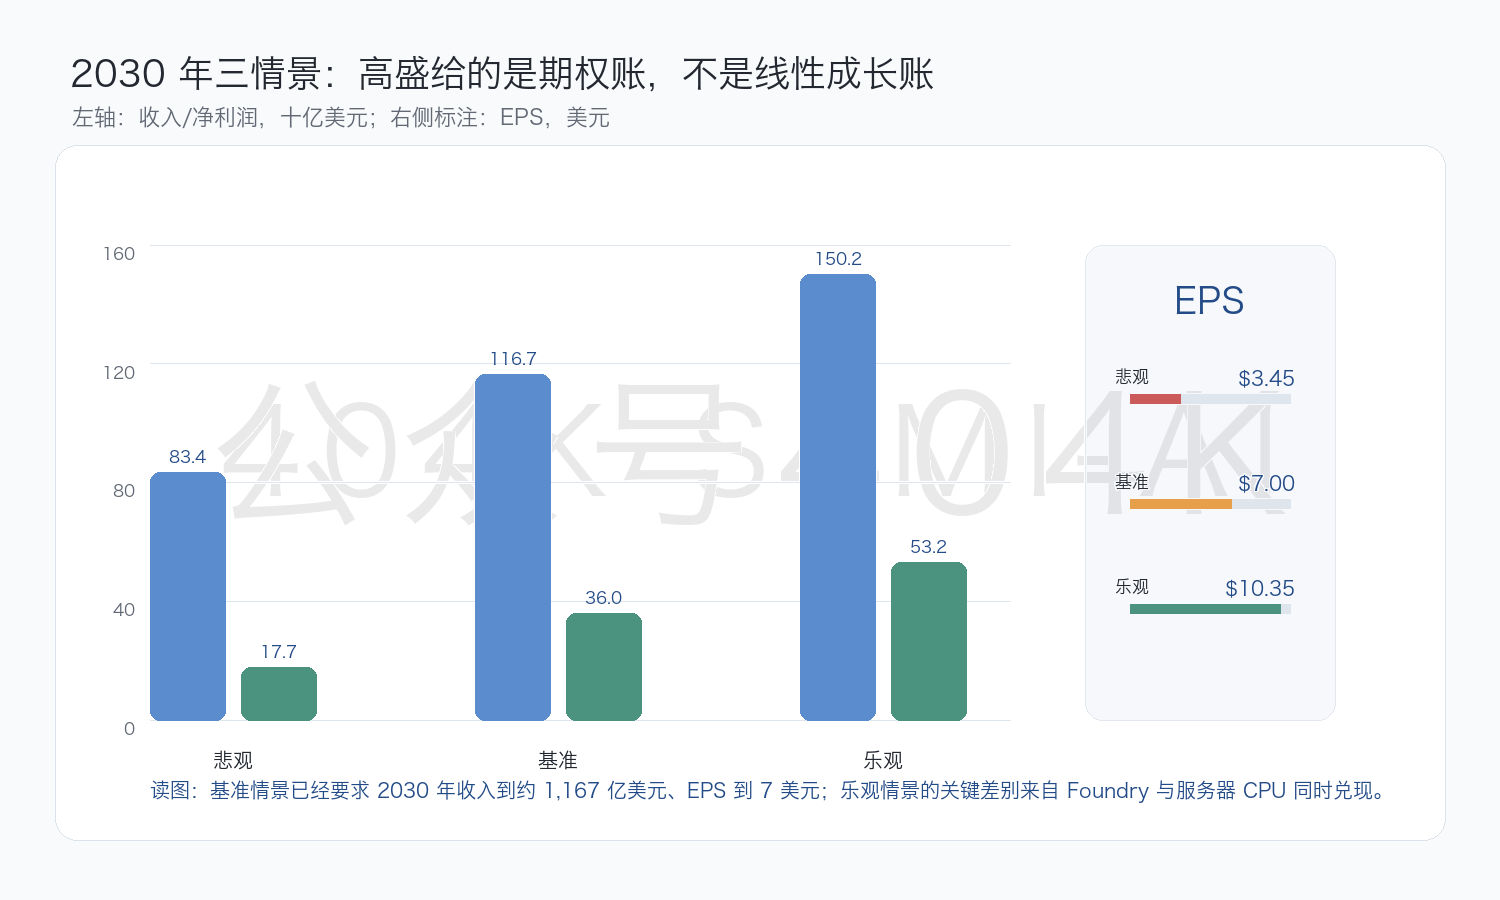
Goldman’s 2030 scenario framework shows that Intel’s valuation elasticity today does not come only from revenue growth, but also from whether gross margin can continue to recover. The base case already requires the company to return to a high-quality earnings profile. The bull case requires both Foundry and server CPU to deliver. In the bear case, revenue still has scale, but both the multiple and earnings would be compressed again.
