
Innoscience Deep Dive: 800VDC, 8-Inch GaN, and 68k wpm Capacity, the Ticket to AI Data Center Power Restructuring
目录
Too Long; Didn’t Read
I. Company Profile: An Industrialization Player in 8-Inch GaN-on-Si
II. What Goldman Sachs’ Initiation Changes
III. 800VDC: Why Data Centers Are Starting to Need GaN
IV. Capacity: Heavy-Asset Validation from 20k wpm to 68k wpm
V. Product Matrix: How 15V-1200V Becomes a Customer Ticket
VI. Financial Model: From Positive Gross Profit to Positive Cash Flow
VII. Compared with Peers: Where Innoscience Is Expensive, and Where It Is Strong
VIII. Three Scenarios: What Multiple Is the Market Really Paying?
IX. Disconfirmation Checklist: What Would Show the Story Is Going Off Track
X. The Next Four Quarters: Translating Tracking Indicators Into Financial Statements
XI. Investment Conclusion: The Ticket Has Been Secured; Delivery Still Depends on Four Numbers
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Innoscience’s re-rating anchors are 800VDC data center power delivery, mass production of 8-inch GaN-on-Si, a full 15V-1200V voltage spectrum, and a capacity ramp to 68k wpm. These four variables determine whether the company can move from a fast-charging GaN supplier into the AI power tree, and whether the HK$114 target price can be validated by revenue, gross margin, and cash flow.
Too Long; Didn’t Read
The valuation is betting on two migrations. Innoscience’s verifiable historical base came from fast charging, consumer electronics, BMS, LiDAR, and industrial power supplies. Since 2025, the incremental variable has been the AI data center shift from 48V board-level conversion toward 800VDC rack-level architecture. If the company can extend from server power supplies and board-level DC conversion into the GPU/ASIC power chain, its revenue mix will migrate from “consumer electronics GaN supplier” to “data center power semiconductor platform.”
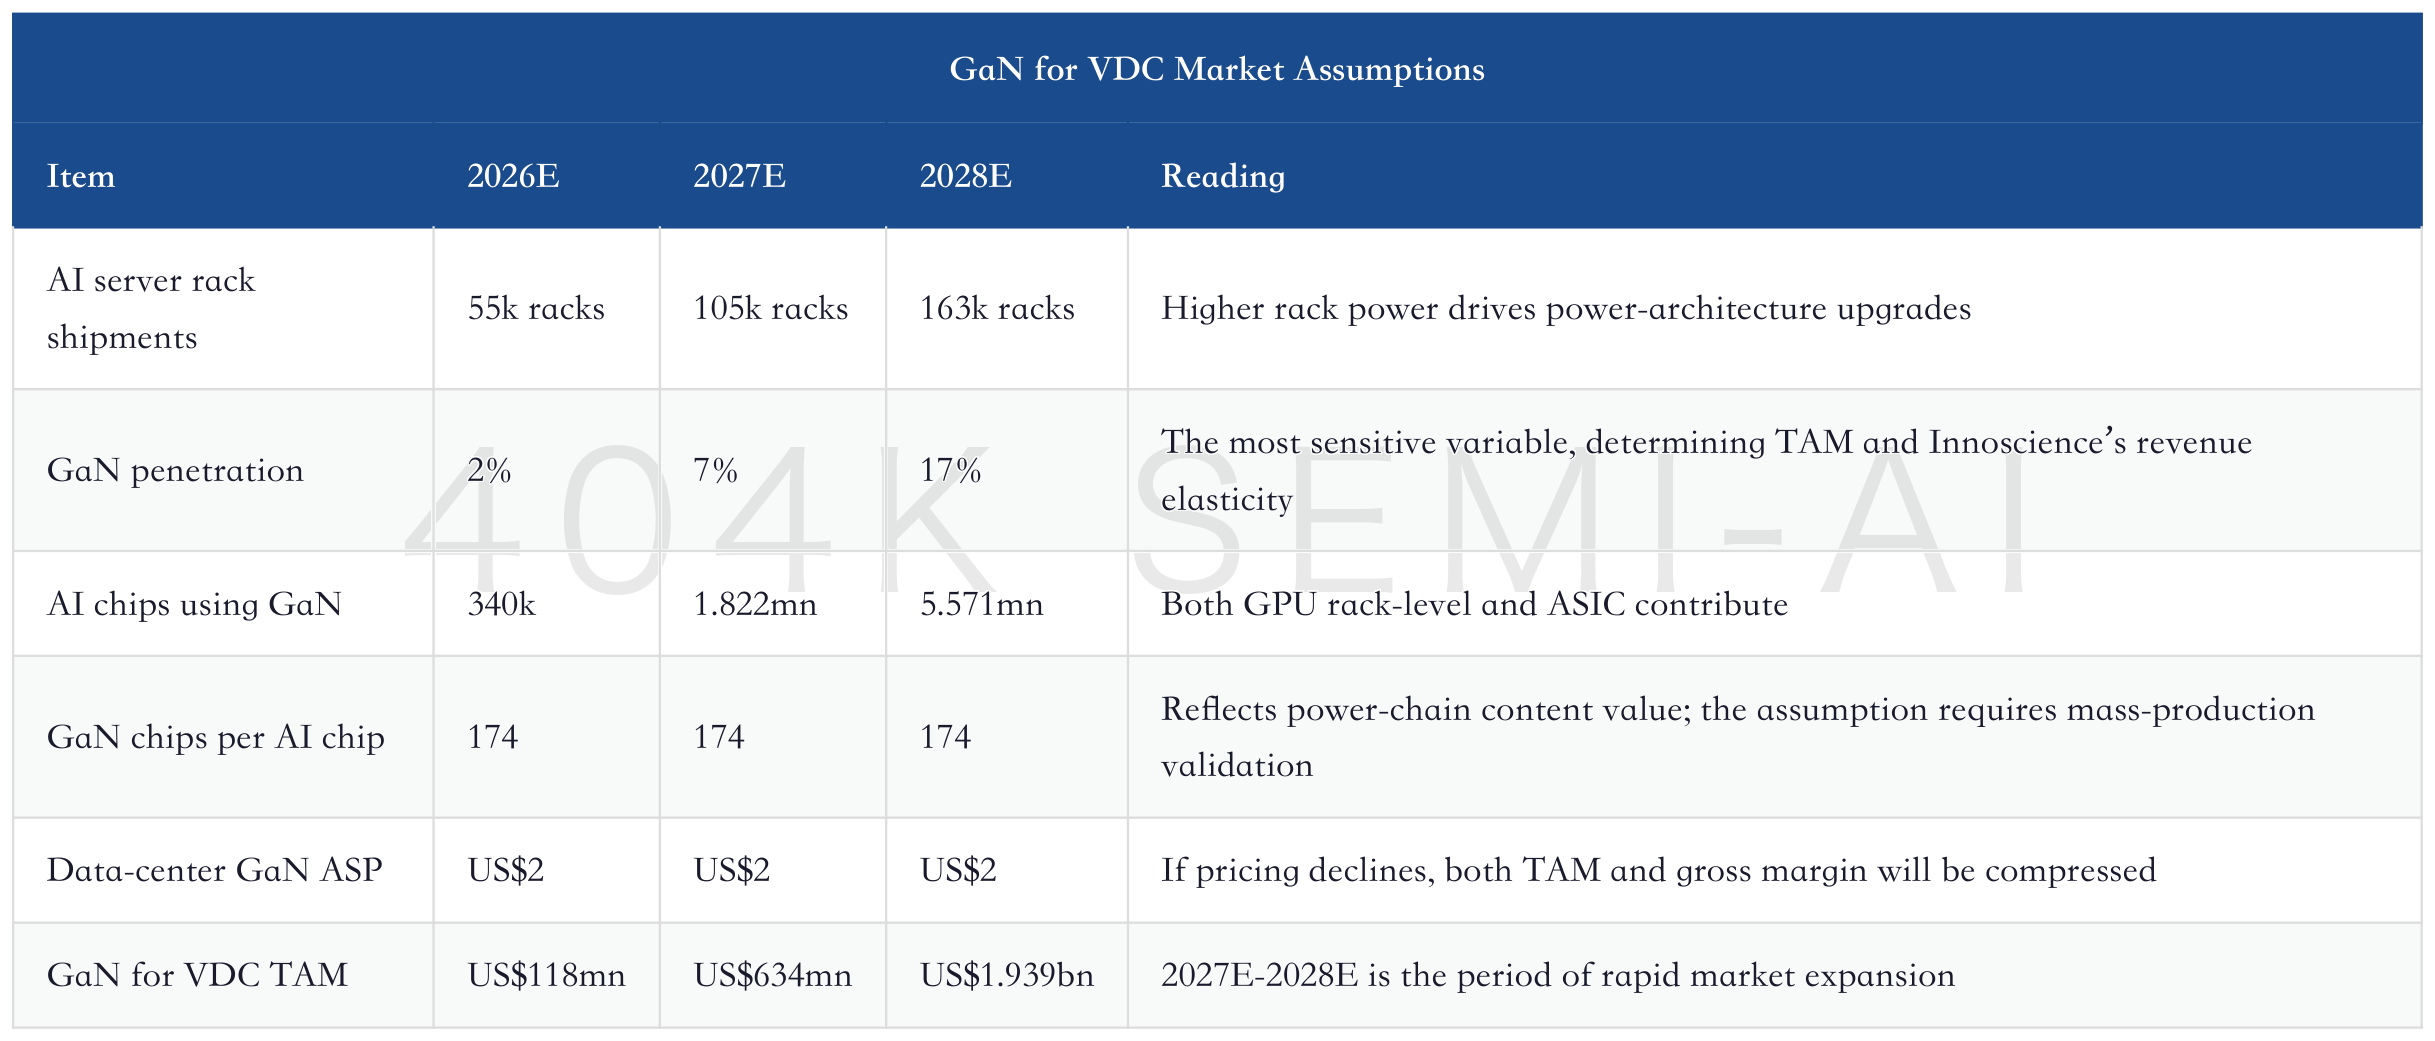
800VDC opens the second growth curve. Goldman Sachs’ initiation pushes the 2026E-2028E GaN for VDC TAM from US$118 million to US$1.939 billion. Core assumptions include GaN penetration rising from 2% to 17%, 174 GaN chips per AI chip, and ASP staying at US$2, making the model more sensitive than a simple linear increase in AI server volumes. This model is highly sensitive to penetration, and it gives Innoscience a clear validation point: customer adoption cadence matters more than the concept.
Capacity is both the ticket and the leverage. The company’s official interim report disclosed 2025H1 capacity of 13k wpm and overall yield above 95%. Goldman Sachs expects roughly 20k wpm by end-2025 and more than 68k wpm by end-2029. GaN is a capital-intensive manufacturing story. Capacity expansion will first consume depreciation and cash flow, but once high-end applications scale, fixed-cost dilution and product-mix upgrade can push gross margin from single digits to above 30%.
The gross-margin inflection has already appeared. The company’s 2025H1 revenue grew 43.4% YoY, and gross margin turned positive to 6.8%. Goldman Sachs’ model further assumes 2027E gross margin rising to 31.1%. This means investors need to track the quality of revenue growth: whether incremental revenue comes from higher-value discrete chips, ICs, modules, and data center/automotive applications.
HK$114 requires earnings delivery. Goldman Sachs assigns a Buy rating and a HK$114 target price, equivalent to roughly 22x 2027E P/S and implying 107.5% upside versus the HK$54.95 closing price. For this valuation to hold, 2027E revenue must reach RMB4.026 billion, EBITDA margin must reach 22.8%, and net margin must turn positive to 9.1%. If 800VDC remains only a handful of pilot projects, valuation will compress first and wait for earnings repair.
Risks concentrate in three areas. First, GaN penetration in data centers may fall short of expectations. Second, new entrants and price cuts from silicon-based solutions may pressure ASP. Third, the 8-inch GaN-on-Si capacity ramp may lag the revenue curve. In addition, overseas patent disputes, customer qualification cycles, and major-customer concentration will affect foreign investors’ willingness to assign a high multiple. Investors cannot look only at target-price upside.
I. Company Profile: An Industrialization Player in 8-Inch GaN-on-Si
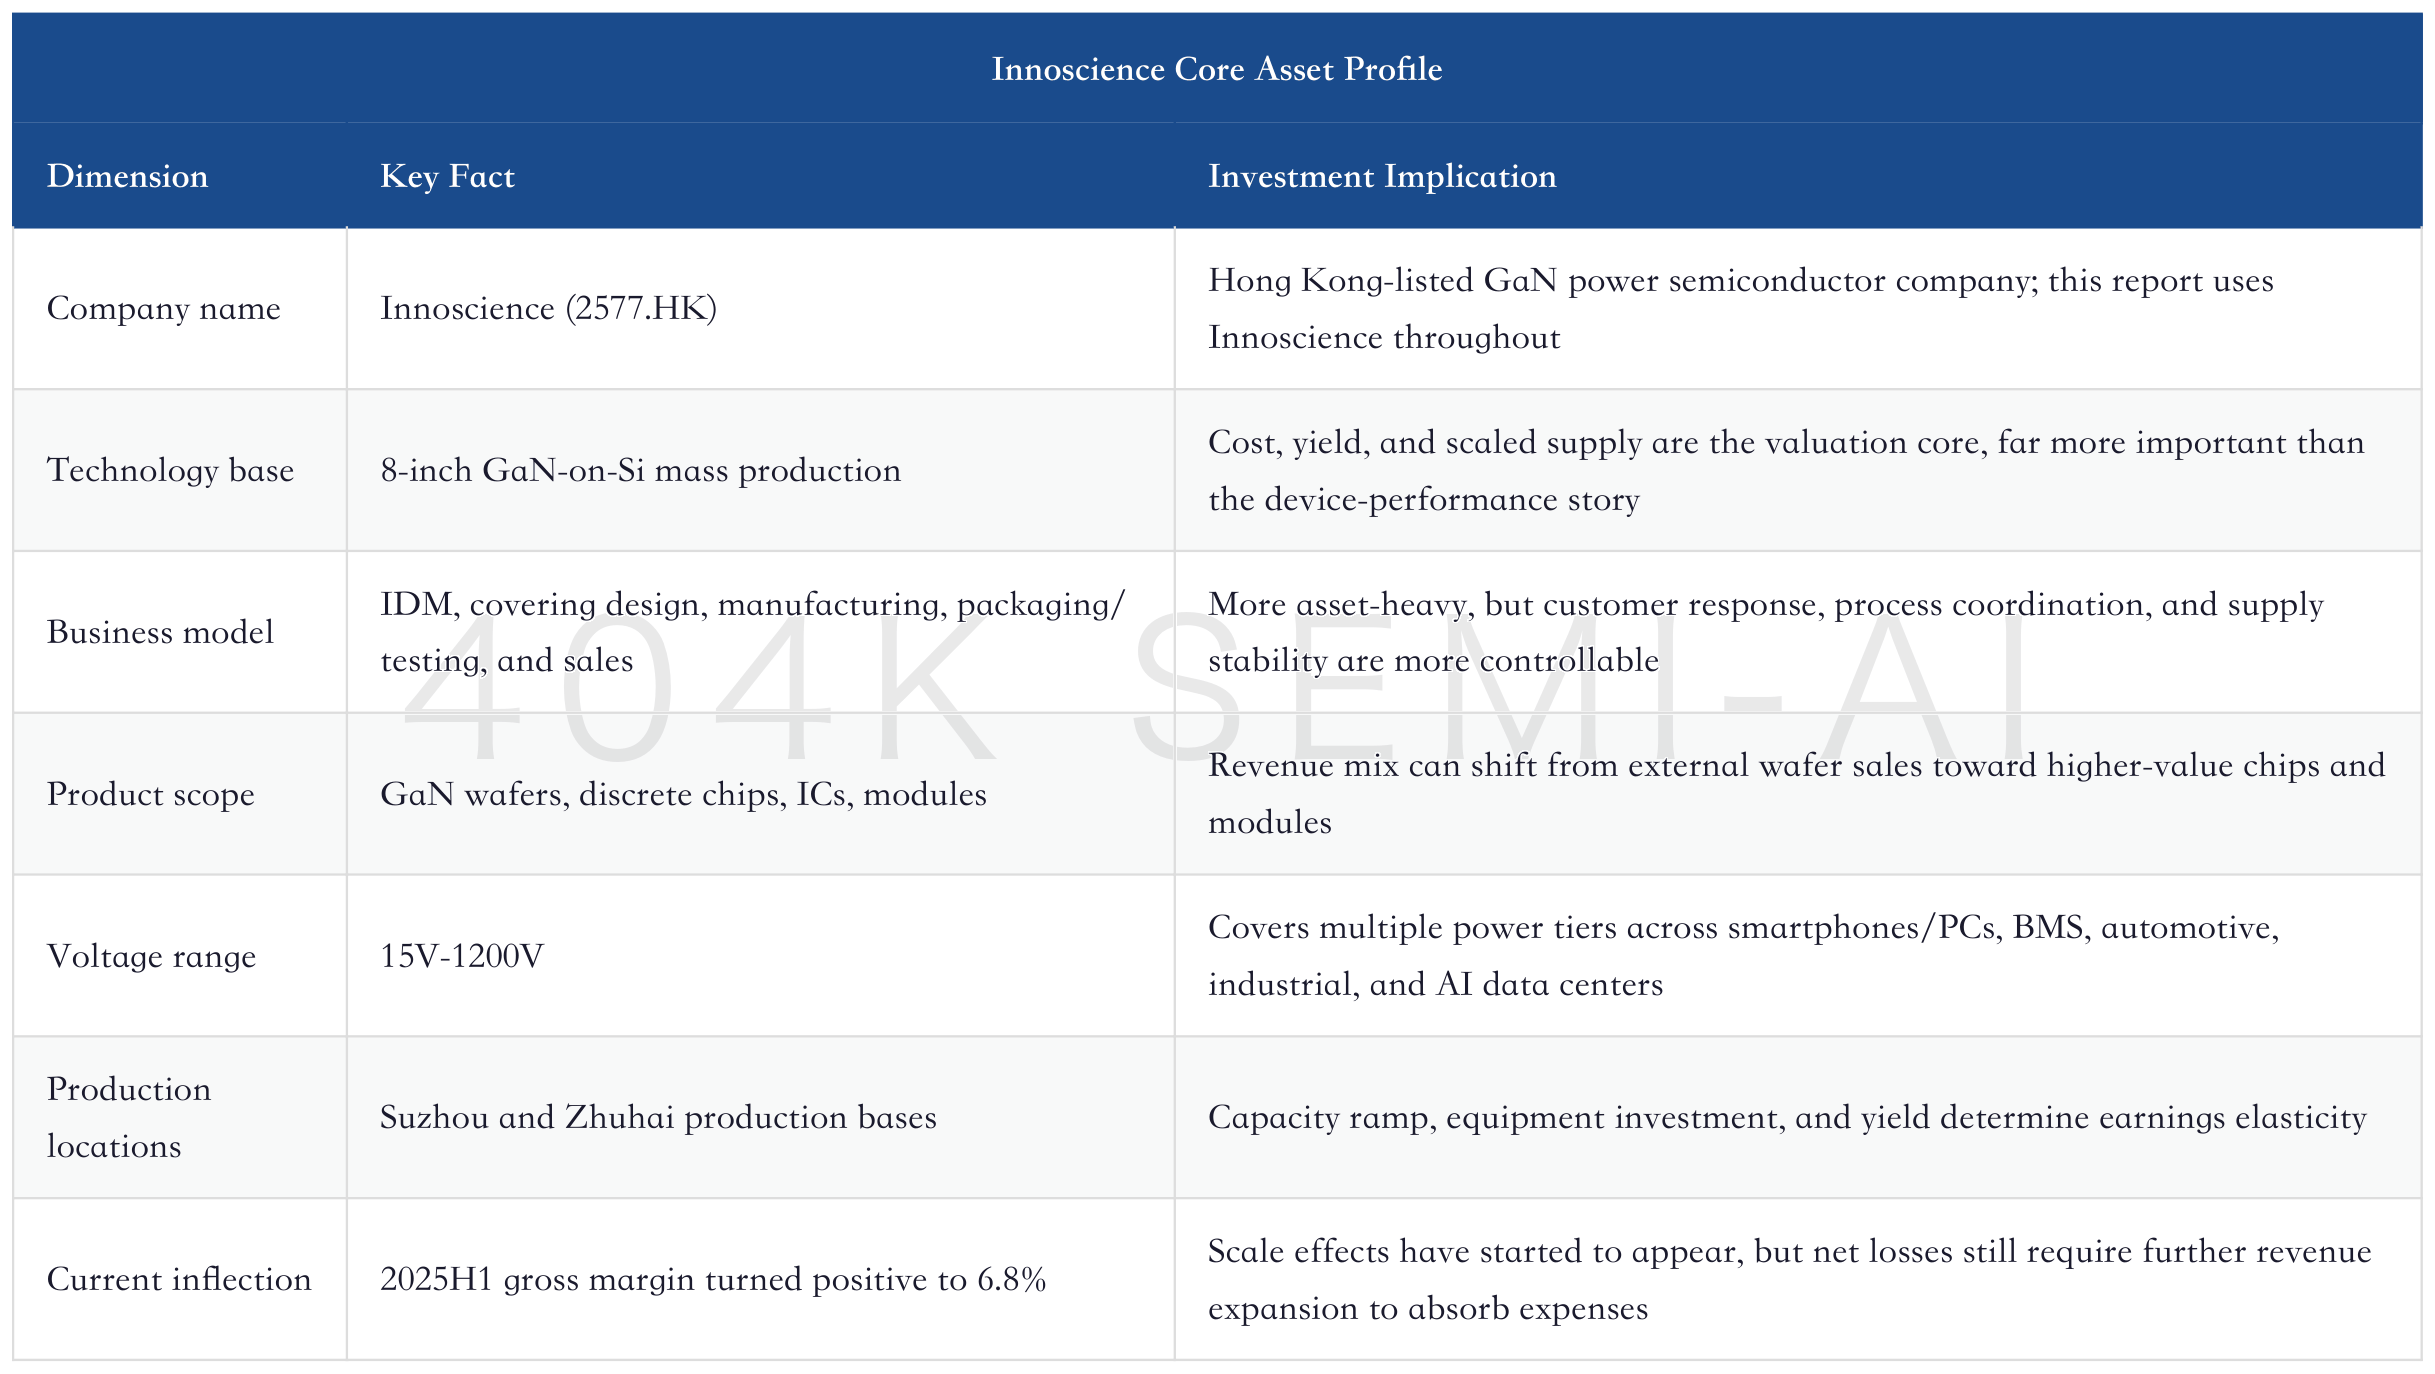
The first thing worth clarifying about Innoscience is what it actually sells. The company has expanded from single power devices used in smartphone fast chargers to a portfolio built around GaN-on-Si wafers, discrete chips, ICs, and modules. Its voltage coverage spans 15V to 1200V, and its applications have expanded from consumer electronics to industrial, new energy vehicles, AI data centers, and robotics.
The company’s prospectus states its official positioning directly: Innoscience is the world’s first company to achieve mass production of 8-inch GaN-on-Si wafers, and one of the few companies able to provide a full-voltage-spectrum GaN-on-Si power semiconductor product portfolio at industrial scale. This matters because GaN investment discussions often stop at the industry truism that “performance is better than silicon,” but what truly determines corporate value is mass-production cost, yield, customer qualification, and supply stability.
The significance of 8-inch GaN-on-Si goes far beyond “larger wafers.” The prospectus discloses that, compared with traditional 6-inch GaN-on-Si wafers, the company’s 8-inch platform can increase the number of chips per wafer by 80% and reduce per-chip cost by 30%. This explains why Innoscience insists on the IDM model: integrating design, manufacturing, packaging and testing, and sales allows customer requirements, device architecture, process iteration, and yield ramp to sit within the same feedback loop.
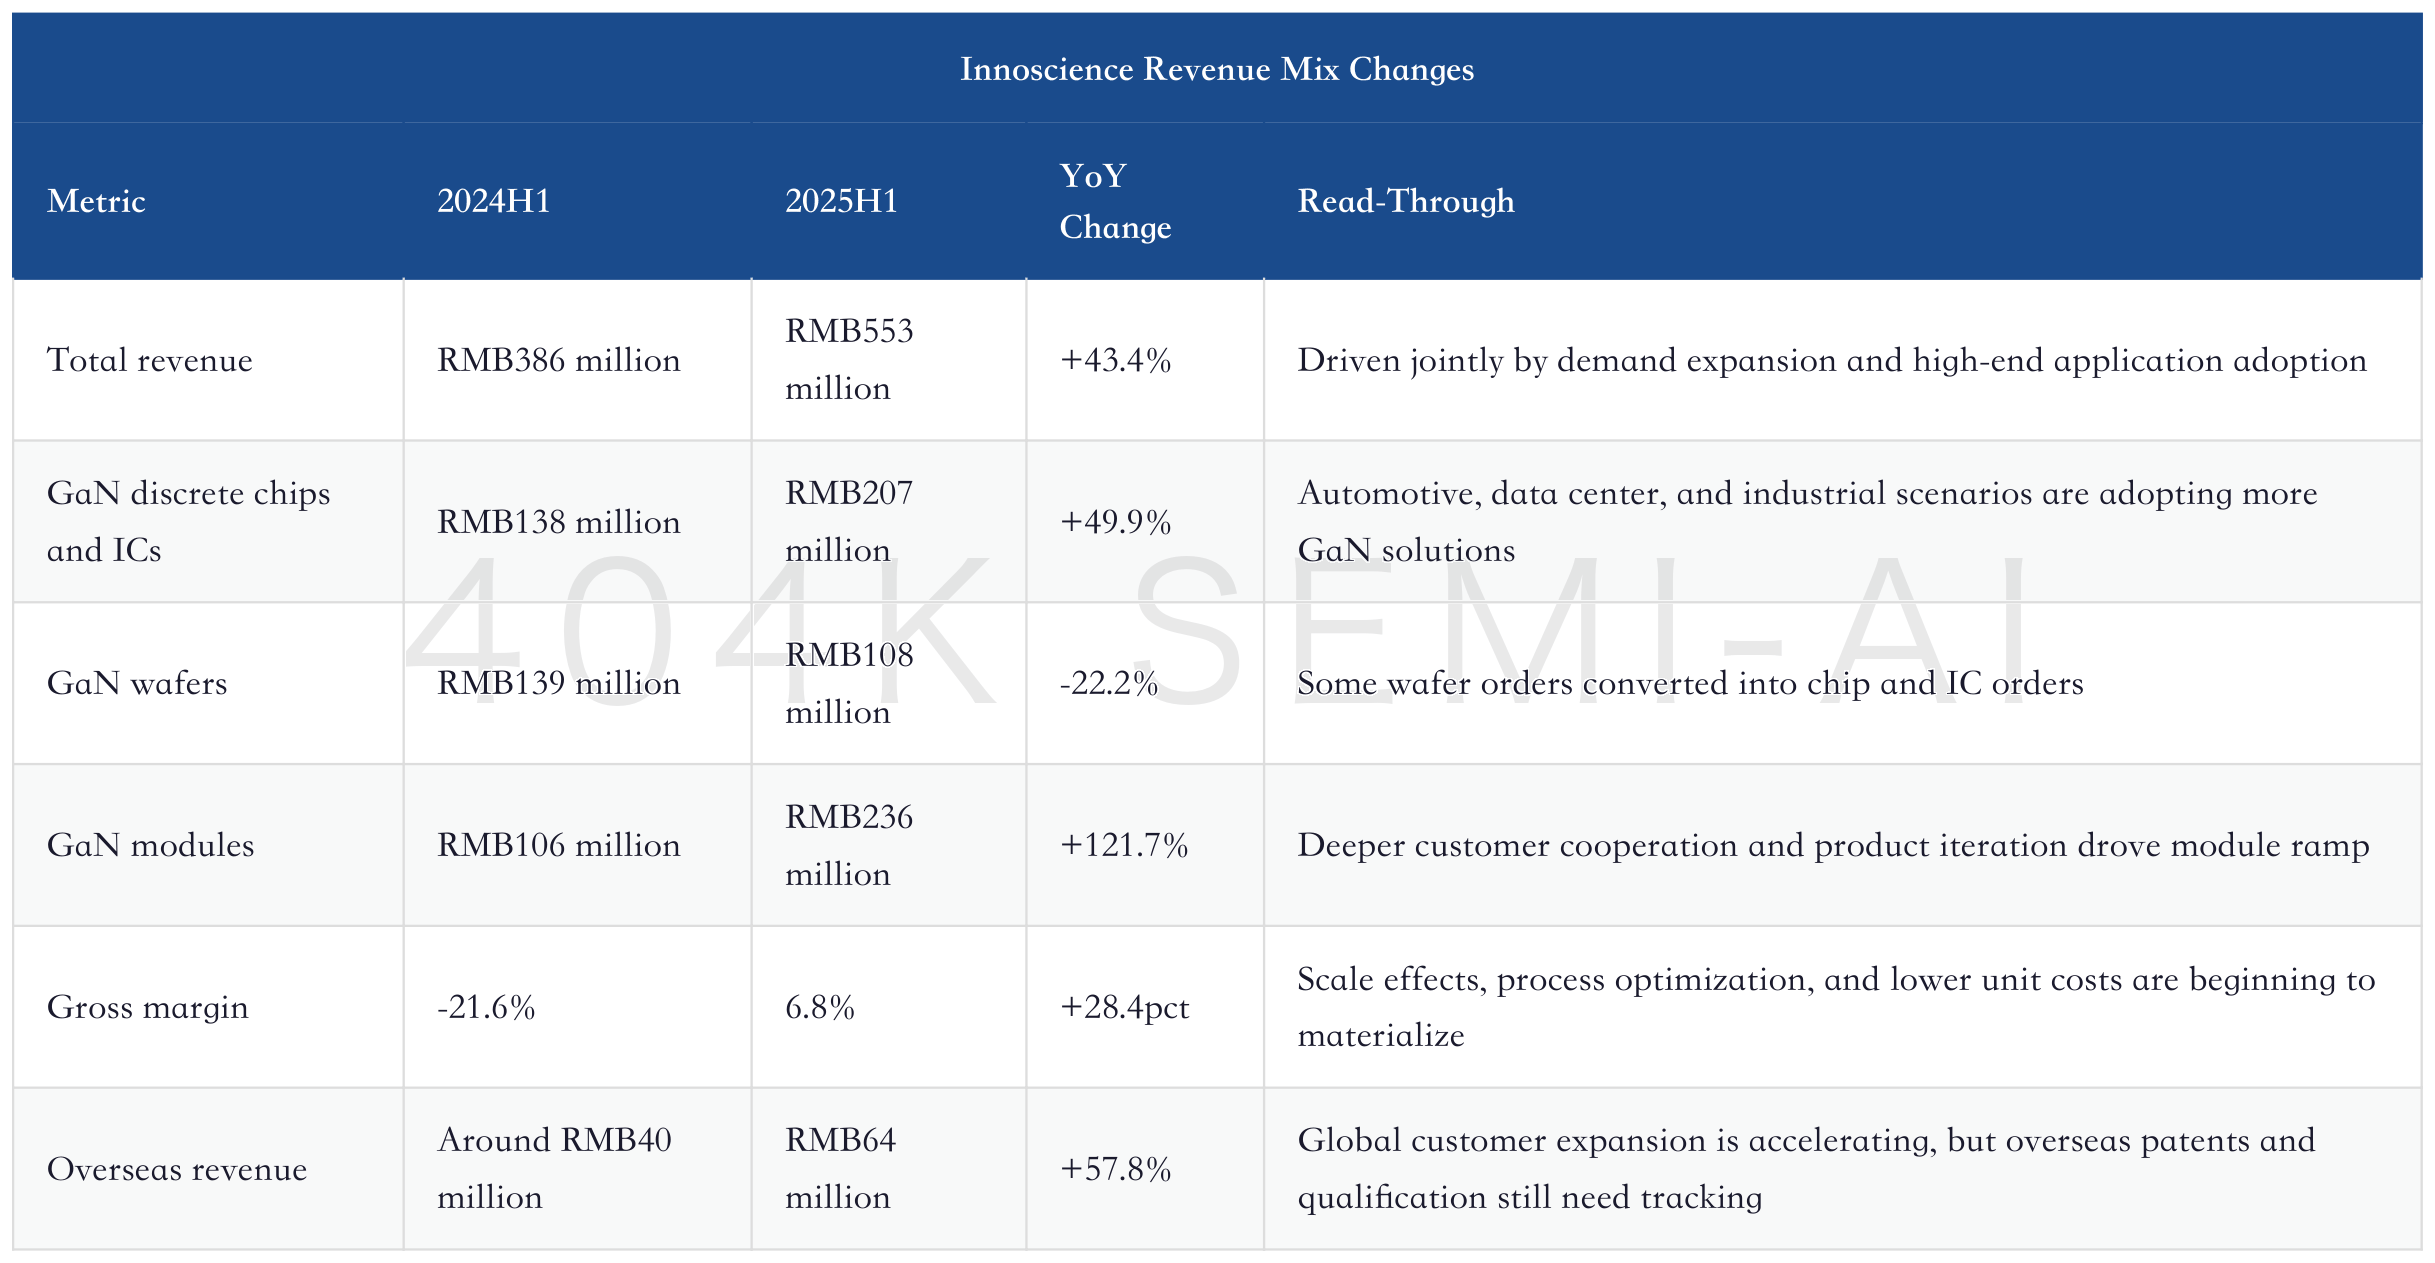
The company’s own business evolution also illustrates this point. Around the time of listing, Innoscience’s revenue scaled rapidly. Early growth relied more on GaN wafers and consumer electronics applications; later, GaN modules, discrete chips, and ICs ramped faster, while the share of external wafer sales declined. This change matters more than revenue growth alone because it means the company is moving closer to system design and toward areas where process and packaging capabilities are more visible.
The implication is that the company is reducing its dependence on pure external wafer sales and pushing wafer capability up the device and module value chain. A decline in wafer revenue is not necessarily negative. The 2025 interim report explained that some wafer orders were converted into discrete chip and IC orders to meet customer demand for system-integrated products. In other words, the revenue mix is shifting from “giving customers a piece of raw material” to “giving customers a power device that can go directly into system design.”
From an investment perspective, Innoscience’s first-principles question is not “whether the GaN industry has growth,” but whether the company can convert 8-inch manufacturing capability into system capability that customers must use. Power semiconductor customers rarely change designs simply because device parameters look attractive. This is especially true in data center, automotive, and industrial applications, where customers care more about device reliability, volume supply, application engineering support, long-term consistency, and fault-liability boundaries. If Innoscience remains only ahead on device specifications, its valuation will be pulled back into the ordinary hardware-company framework. Only if it enters customers’ power architectures and reference designs can its valuation move into a platform-type power semiconductor framework.
The significance of the IDM model for this company also needs to be made clear. IDM makes the balance sheet heavier and increases pressure from depreciation and capacity utilization. But in a GaN-on-Si track where materials, devices, processes, packaging, and applications are tightly coupled, pure outsourced manufacturing makes it difficult to quickly feed customer feedback back into epitaxy and process flows. Innoscience puts wafers, devices, ICs, and modules within the same system. In the short term, this weighs on the expense ratio; over the long term, it creates the opportunity to turn customer requirements into faster process and product iteration.
The company’s most valuable asset today is not any single product, but “transferable capability.” Consumer electronics trained shipment and cost control; industrial and home appliances trained reliability; automotive trained qualification and long-term supply; data centers train system-level efficiency and customer co-creation. As long as these capabilities can be reused on the same 8-inch GaN-on-Si platform, Innoscience is not merely rising and falling with a single application cycle. It has the opportunity to translate different end-market demands into utilization of the same manufacturing platform.
Conversely, this also explains why the market still applies a discount to the company. GaN has not yet built the same long and stable profit history as silicon power devices. The company is still expanding capacity, and its expense ratio and cash flow have not entered a mature state. High-end customer adoption often requires a long qualification cycle, and revenue recognition can lag design wins. What investors are buying today is the “platform validation period,” not mature profits that have already been fully delivered.
II. What Goldman Sachs’ Initiation Changes
The incremental point in Goldman Sachs’ July 2026 initiation is that it moves Innoscience from the frame of “GaN application expansion” into the model of “AI data-center 800VDC power architecture,” rather than staying with the industry common sense that GaN offers higher frequency and lower losses than silicon. The report gives a 12-month target price of HK$114, implying 107.5% upside from the HK$54.95 closing price, corresponding to roughly 22x 2027E P/S.
This is a high-growth, high-validation-pressure call. Goldman expects the company’s GaN revenue to grow at a 73% CAGR over 2025E-2028E, with total revenue increasing from RMB1.213bn in 2025 to RMB6.233bn in 2028, EBITDA turning positive in 2026, net profit turning positive in 2027, and free cash flow turning positive in 2028.
The core of Goldman’s model lies in three assumptions behind the revenue curve. First, AI data-center power delivery requires higher power density and efficiency, and 800VDC rack-level architecture increases GaN content value. Second, applications expand from fast charging to automotive, industrial, data centers, and robotics, with the product mix migrating toward higher value-added categories. Third, Suzhou capacity continues to ramp, with total capacity exceeding 68k wpm by the end of 2029.
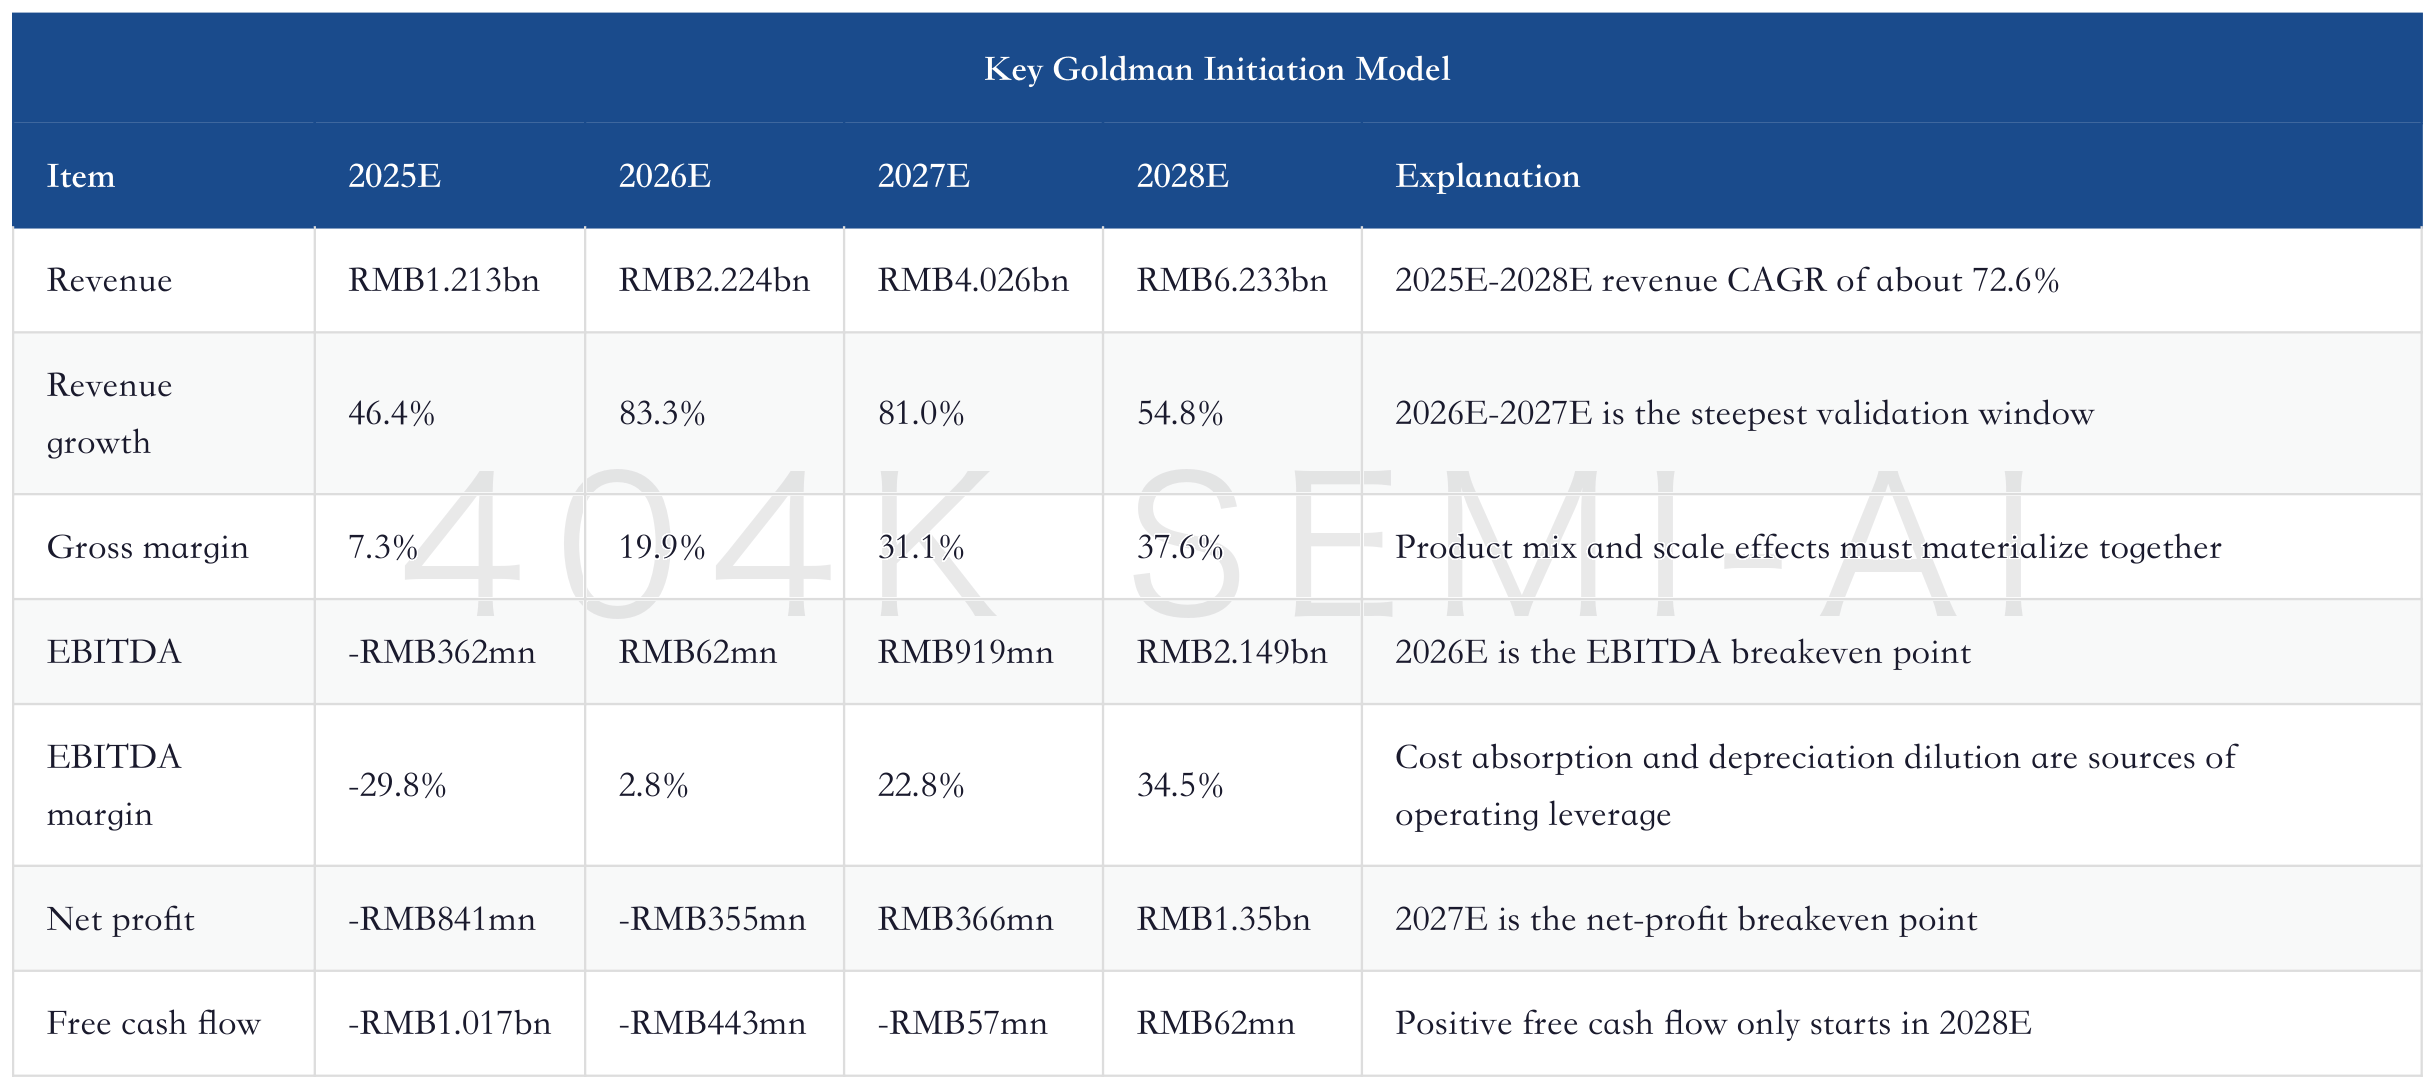
There is one uncomfortable but necessary point in this model: the current valuation has already priced in growth expectations in advance, and it must be digested through revenue and gross-margin ramp over the next two to three years. 22x 2027E P/S is high for a hardware company still transitioning at the edge of net losses. But if 2027E revenue really reaches RMB4bn and EBITDA margin reaches 22.8%, the market will re-rate the company from a “loss-making manufacturing asset” into a “high-end power semiconductor platform.”
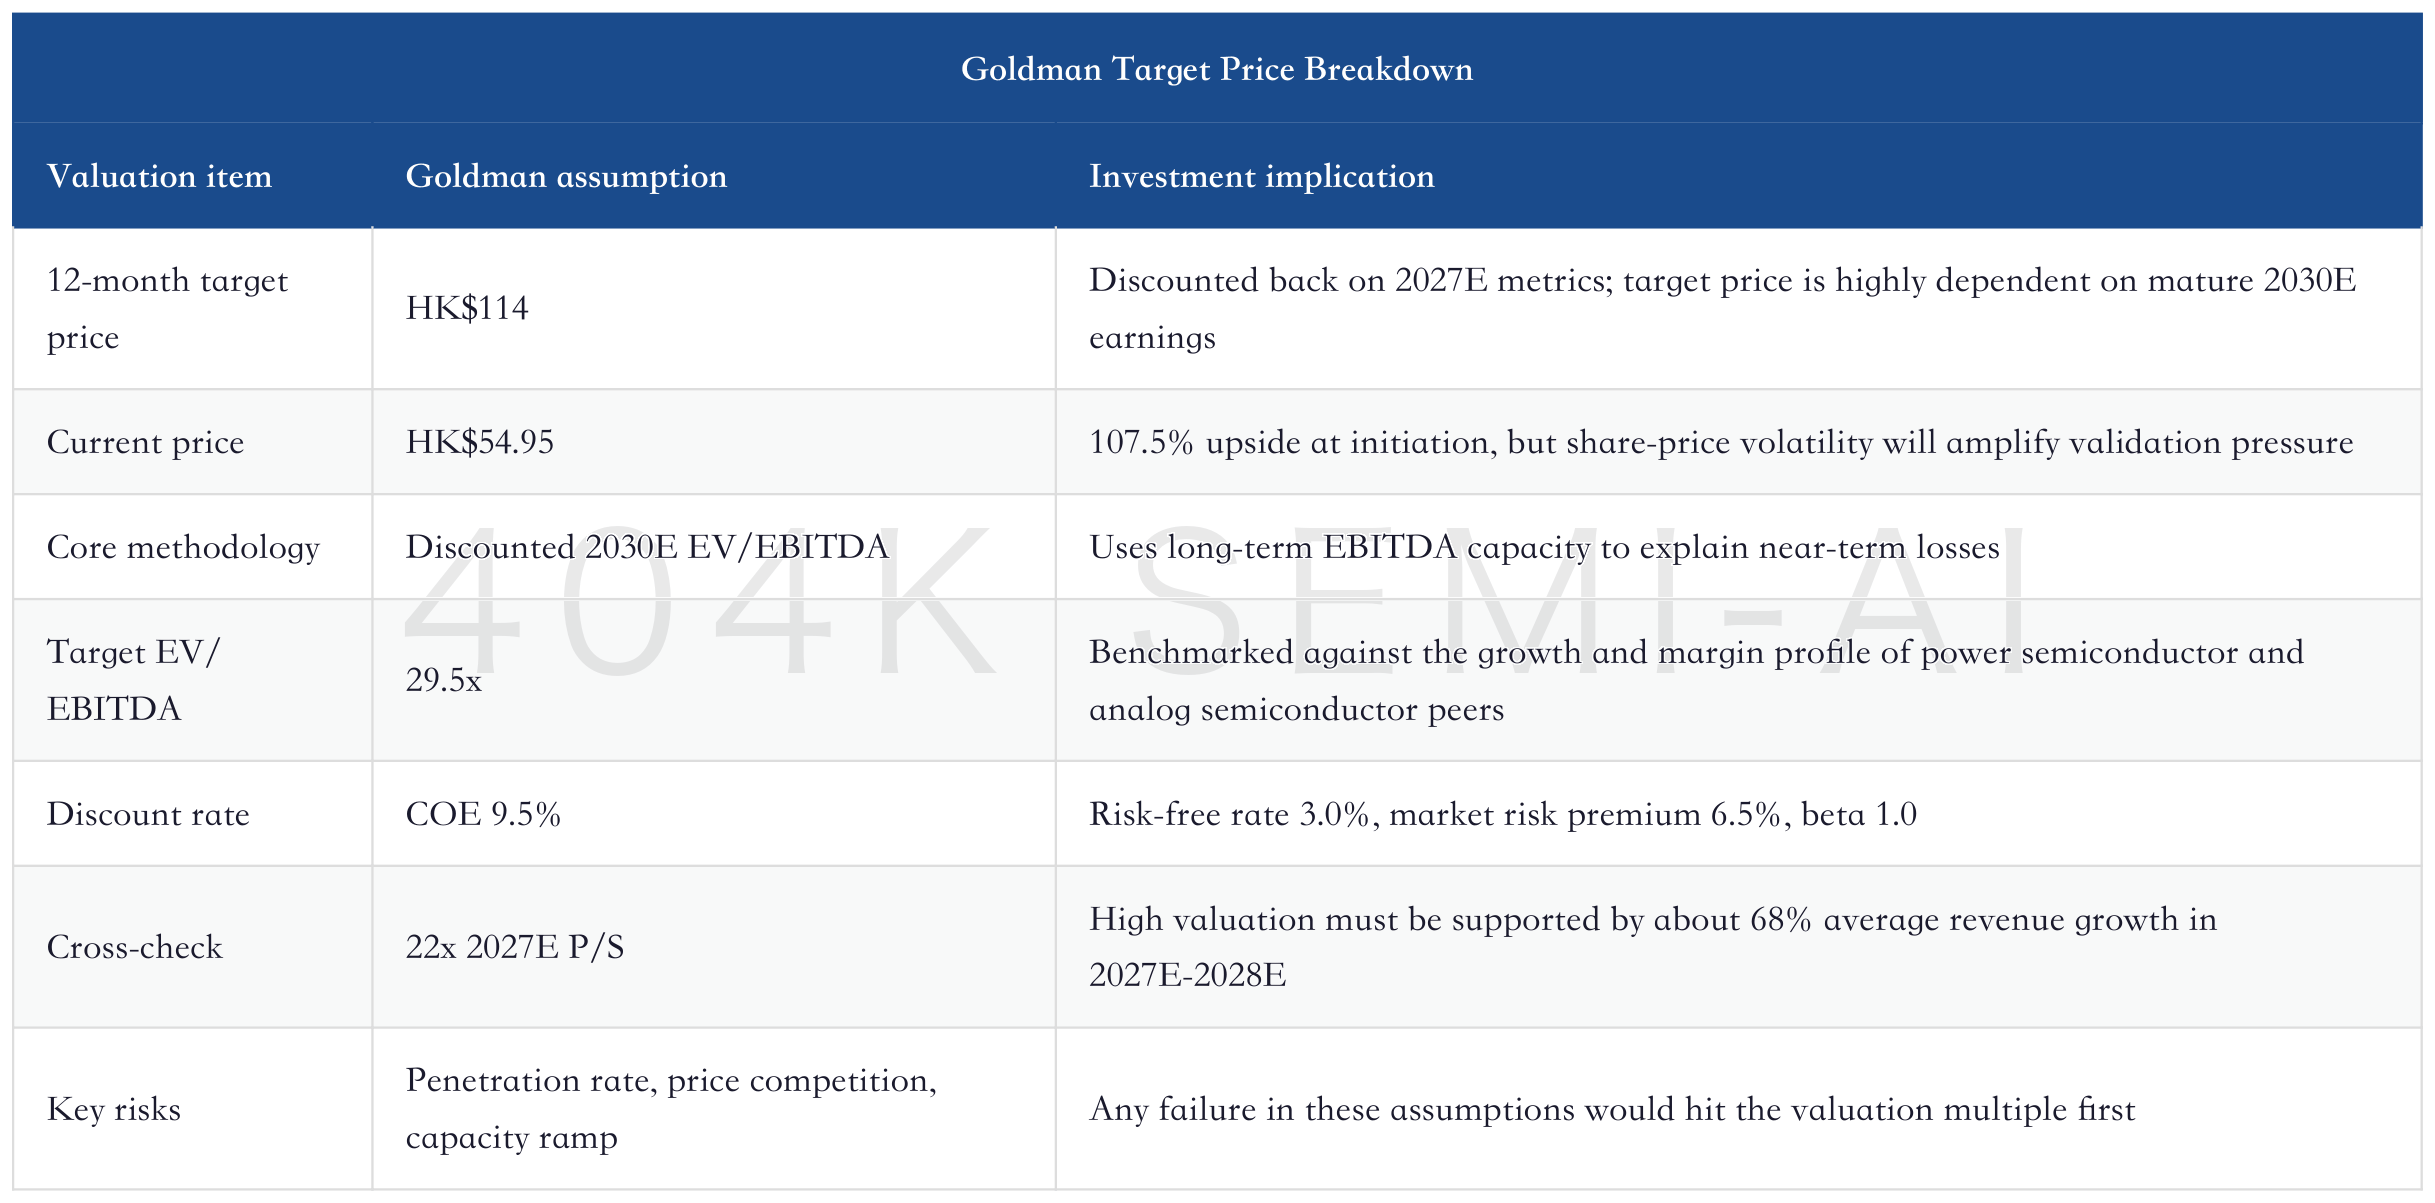
The most important part of Goldman’s valuation method to unpack is that it uses forward EBITDA to explain current losses. This method suits companies in the middle of capacity build-out and product-mix migration, because near-term net profit is weighed down by depreciation, R&D;, and customer qualification costs. But it also has a natural risk: if forward revenue, gross margin, or expense ratio falls short of the model at any point, the discounted value can decline quickly. Innoscience has high valuation elasticity, but also high valuation fragility.
More specifically, HK$114 does not imply that “today’s financials are already cheap.” It implies that the market is willing to pay in advance for platformized profit. This platformized profit comes from three layers: first, lower unit cost after 8-inch capacity is released; second, higher gross margin as the share of discrete chips, ICs, and modules increases; third, data-center and automotive customers putting the company’s products into systems with higher content value and longer lifecycles. Only if all three layers occur together can forward EBITDA be supported.
Therefore, the target price itself cannot be treated as the conclusion; it can only be treated as a reverse-engineered model. After reverse engineering it, the key question is not how far the target price is from the current price, but how much operating evidence is needed to close that gap. For Innoscience, investors need to see at least identifiable revenue contribution from data-center customers, stable improvement in 20k wpm capacity utilization, continued gross-margin expansion, and expense ratio decline with scale. Without this financial-statement evidence, the target price is the “price of a good story,” not the “price of realized profit.”
This valuation framework also affects trading rhythm. Each time the company discloses a new customer, new application, or new capacity, the share price may first react based on forward upside. But if each earnings report fails to show coordination between revenue mix and gross margin, the market will also quickly compress the multiple. Innoscience is not a low-volatility defensive asset. It is more like a validation-driven growth stock, and the research focus needs to shift from “is there positive news” to “can the positive news flow into the financials.”
Follow the Power: AI Data Centers Move from GPU Shortages to Grid, 800V, and Power Semiconductor Re-Rating
III. 800VDC: Why Data Centers Are Starting to Need GaN
The power-delivery problem in AI data centers is essentially that “power is increasingly concentrated, and losses are increasingly expensive.” As GPU and ASIC rack power rises, traditional low-voltage, high-current paths bring higher line losses, thicker copper busbars, more complex thermal management, and larger space requirements. 800VDC rack-level architecture attempts to raise voltage, reduce current and transmission losses on the higher-voltage side, and then convert power step by step near the rack, board, and chip.
Innoscience’s opportunity is that GaN’s high frequency, low on-resistance, and high power density directly address three pain points in data-center power: efficiency, size, and heat. Goldman’s report emphasizes that the company’s products can participate in multi-stage power conversion from 800V to 54V, 54V to 12V, and 12V to 0.8V. Management says its solution can reduce driver losses by 80% and switching losses by 50%. This claim needs to be validated by future customer mass production, but the direction is clear: GaN’s value is no longer limited to making chargers smaller; it is entering AI rack energy efficiency and space budgets.
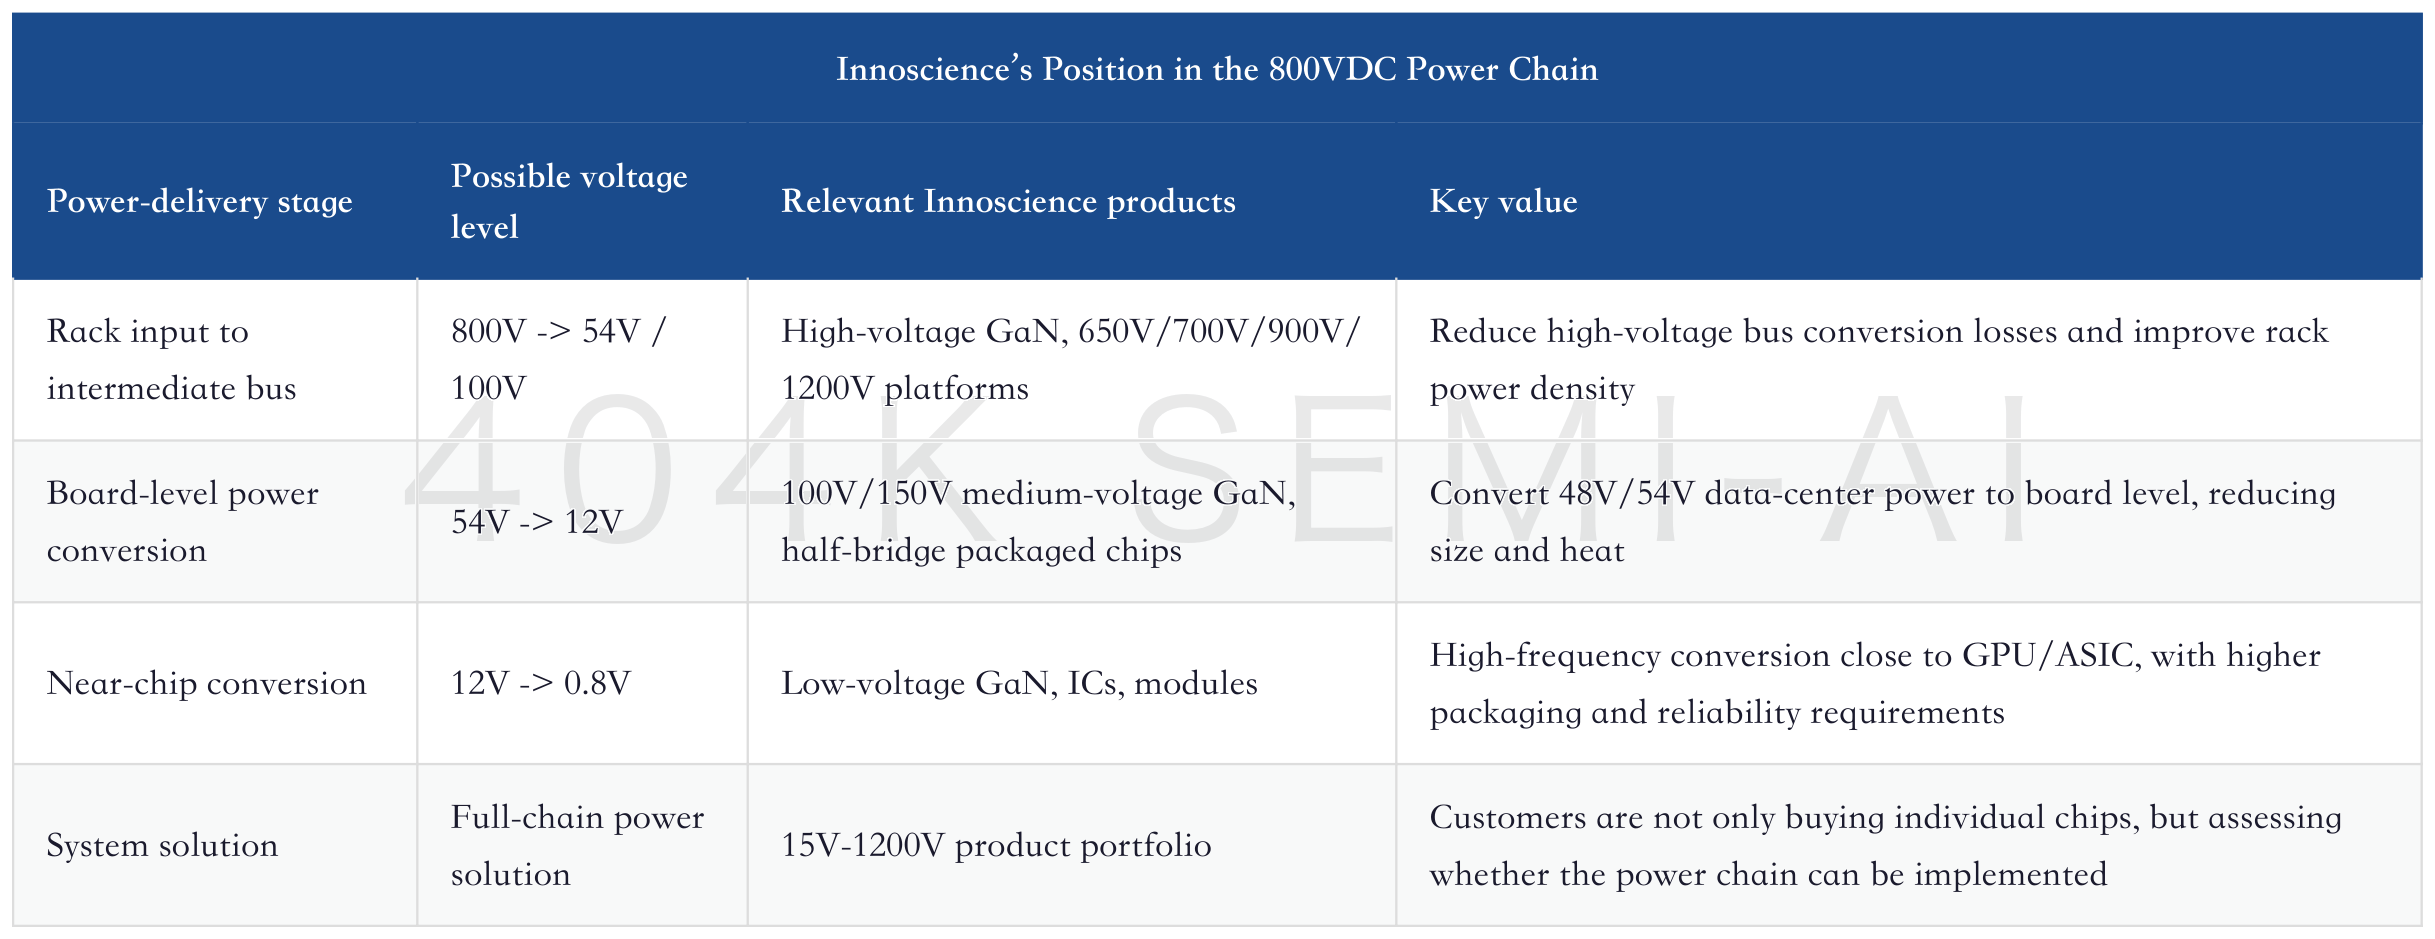
This is also the biggest distinction between Innoscience and traditional fast-charging GaN suppliers. Fast charging is a consumer-electronics trade-off among cost, size, and efficiency. 800VDC is an engineering problem jointly determined by reliability, supply capability, customer qualification, system efficiency, and AI rack architecture choices. The former can scale through single-product iteration; the latter needs to enter reference designs and supply chains of leading customers.
The company’s 2025 interim report has already provided some early validation. It stated that AI and data-center sales increased 180% YoY; 100V GaN-based 48V-to-12V applications had entered mass production; and the company had entered Nvidia’s 800V high-voltage DC solution chip supplier list, providing a full-chain GaN power solution from 800V input to the GPU end, covering 15V to 1200V. This cannot be directly equated with large-scale revenue realization, but it at least shows that the company has reached the stage of customer collaboration and product qualification.
Goldman’s TAM model quantifies this opportunity more aggressively. What it is really trying to express is that AI rack power consumption, the number of GPU/ASIC chips, GaN penetration, and per-system content value are all rising at the same time. If these assumptions hold, GaN for VDC will quickly grow from a small market into a new application large enough to affect Innoscience’s revenue mix.
Data-center customers will also raise requirements for suppliers. Fast-charging customers focus more on cost, size, and supply speed. AI rack customers will also examine long-duration reliability, thermal design margin, failure rate, system-level reference designs, and cross-region delivery capability. If Innoscience can establish itself in this market, revenue elasticity will come from new applications, valuation elasticity will come from customer thresholds and validation cycles, and the cost of failure will also be higher.
The importance of 800VDC for Innoscience also lies in pushing GaN competition from “single-device replacement” toward “system energy-efficiency reconstruction.” Single-device replacement is usually easily constrained by customers’ cost-reduction logic, because customers compare the cost of GaN, silicon MOS, SiC, packaging solutions, and magnetic components together. System energy-efficiency reconstruction is different: customers calculate rack space, thermal management, copper losses, conversion stages, maintenance cost, and usable power. If GaN helps customers fit more compute into the same cabinet space, the pricing logic will be better than for consumer-electronics standalone products.
Restraint is still required here. 800VDC is not a straight line that will automatically become universal. Data-center architecture changes require cloud providers, server OEMs, power-supply vendors, chip vendors, and safety standards to move together. If any link has concerns about reliability or cost, mass-production timing will be delayed. Innoscience has already obtained customer-collaboration signals, but between collaboration signals and sustainable revenue still lie design finalization, reliability testing, mass-production ramp, and inventory management. Goldman’s model provides direction and elasticity; financial reports need to provide the pace of realization.
ASIC is even more worth watching. GPU rack power delivery is already sufficiently complex, and ASIC further amplifies customization and system coordination. Goldman’s model assumes ASIC share gradually rises, which means different customers may require different power paths, package forms, and module solutions. If Innoscience can secure design positions in both GPU and ASIC platforms, data-center revenue will become more diversified and more sustainable. If it only remains in a few demonstration projects, the penetration curve in the model will look too optimistic.
Therefore, validation of 800VDC should not be judged only by headlines. Harder evidence includes server power supplies or board-level conversion products entering mass-production BOMs, customers continuing to use GaN in next-generation racks, orders moving from samples and small batches to stable quarterly delivery, and the product mix expanding from single devices to half-bridges, ICs, modules, and system solutions. Only when this evidence appears can Innoscience truly shift from a “GaN concept stock” to an “AI power-architecture supplier.”
From 800V High-Voltage DC and Chroma’s Test Platform to Delta’s High-Voltage Infrastructure
IV. Capacity: Heavy-Asset Validation from 20k wpm to 68k wpm
Innoscience’s valuation elasticity ultimately comes down to capacity and yield. Scaling GaN requires design, manufacturing, and mass-production capabilities to all clear the bar. This is especially true for 8-inch GaN-on-Si, where epitaxial uniformity, wafer bow control, process stability, packaging reliability, and customer validation cycles can all slow revenue recognition. In its 2025 interim report, the company said its overall production yield exceeded 95%, a leading industry level. In earlier research reports, management also noted that GaN device processes involve more than 400 steps, with epitaxial wafer challenges including uniformity and bow.
Goldman Sachs models the capacity curve rising from about 20k wpm at end-2025 to more than 68k wpm by end-2029. This has two implications. First, the company must prepare capacity before demand is fully realized, or it cannot enter large-scale supply chains for leading customers. Second, capacity expansion brings pressure from depreciation, cash flow, and utilization. If customer adoption is slow, capacity can instead become a valuation discount.
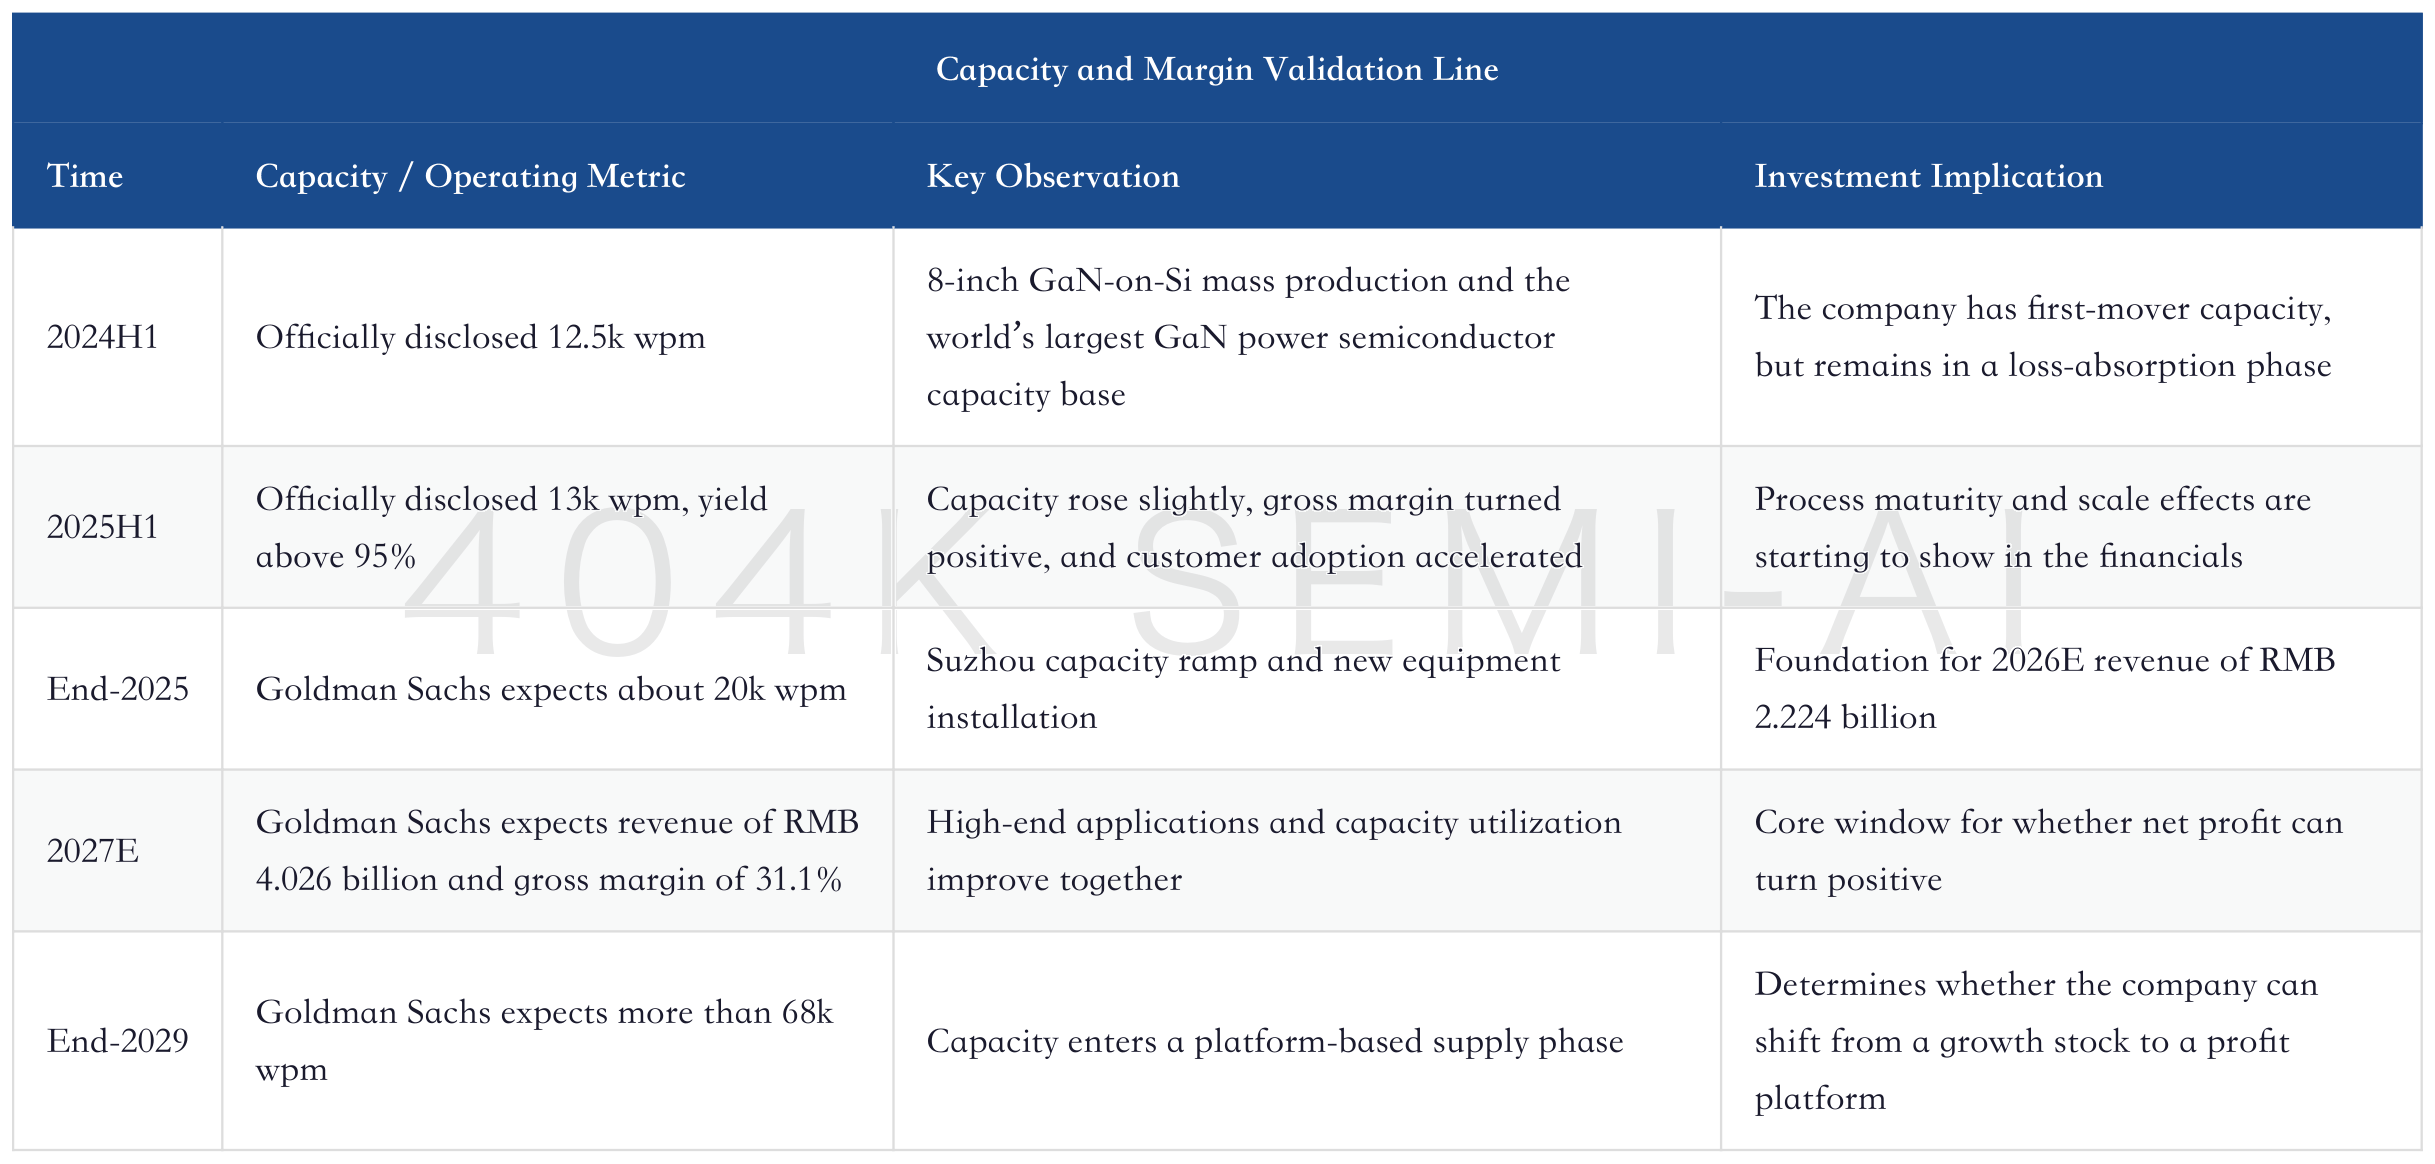
Capacity expansion does not naturally equal profit expansion. One of the main reasons for Innoscience’s prior losses was that equipment depreciation and R&D; spending hit the income statement before revenue scale was sufficient. The positive gross margin in 2025H1 shows scale effects have begun to emerge, but the company still recorded a net loss of RMB 429 million, R&D; expenses of RMB 162 million, and administrative expenses of RMB 246 million. To make the market accept a HK$114 target price, the company must prove that high-end application ramp-up can cover the expense ratio, rather than merely making revenue larger while losses grow in parallel.
This is also why product mix matters more than total revenue. If incremental revenue mainly comes from external wafer sales, gross margin improvement will be limited. If it comes from more complex discrete chips, ICs, and modules in data centers, automotive, industrial, and robotics applications, then fixed-cost absorption and product value-add can occur at the same time. Goldman Sachs pushing long-term gross margin toward about 40% is essentially a bet on “scale + high-end mix,” not just a capacity story of “selling more wafers.”
8-inch capacity also has an easily underestimated role: it changes how customers assess supply stability. Many new-material device companies can produce strong samples, but what customers truly worry about is mass-production consistency and long-term delivery. If Innoscience can prove that its 8-inch platform remains stable in yield, reliability, and cost, customers will be more willing to commit their next-generation power architectures to it. For large customers, a supplier’s ability to expand capacity sustainably is itself part of product competitiveness.
But capacity is also the most realistic source of pressure. Expansion requires buying equipment, building production lines, validating processes, and reserving personnel and materials upfront, while revenue has to wait for customer certification and mass-production schedules. This mismatch can leave the company in a “revenue looks good, cash flow does not” state during high-growth phases. Investors must distinguish between two types of cash-flow pressure: one is upfront inventory preparation driven by high-end orders, which is acceptable; the other is inventory buildup caused by weaker-than-expected demand, which requires caution. In the short term, both may appear in the income statement as expense and inventory pressure, but their investment implications are completely different.
Innoscience’s yield disclosure also should not be viewed in isolation. A yield above 95% is an important positive signal, but from an investment perspective, the product structure behind that yield matters. If high yield mainly comes from mature low-voltage products, the valuation implication is limited. If high-voltage, medium-voltage, module, and automotive/data-center products can also maintain stable yields, gross-margin upside becomes more credible. If future reports disclose more gross margin by product, revenue by application, or capacity utilization, market confidence in the company’s model would improve meaningfully.
The capacity ramp also affects bargaining power between the company and its customers. When capacity is insufficient, customers will not hand critical architectures to a supplier with high supply risk. When capacity is excessive, large customers will push back on pricing. The ideal state is for Innoscience’s capacity to stay slightly ahead of demand, while customer adoption is fast enough to keep utilization in a healthy range. That balance is difficult and is the part of the Goldman Sachs model that most needs continuous validation.
V. Product Matrix: How 15V-1200V Becomes a Customer Ticket
Innoscience’s full voltage spectrum is one of the most easily underestimated parts of the company. Market discussions of GaN often divide it by application, with fast charging, automotive, data centers, and robotics discussed separately. But from the company’s perspective, what matters more is whether voltage platforms can be reused and whether customers can extend from one scenario to another. 15V, 30V, 40V, 100V, 150V, 200V, 650V, 700V, 900V, and 1200V correspond to tickets into different levels of power conversion.
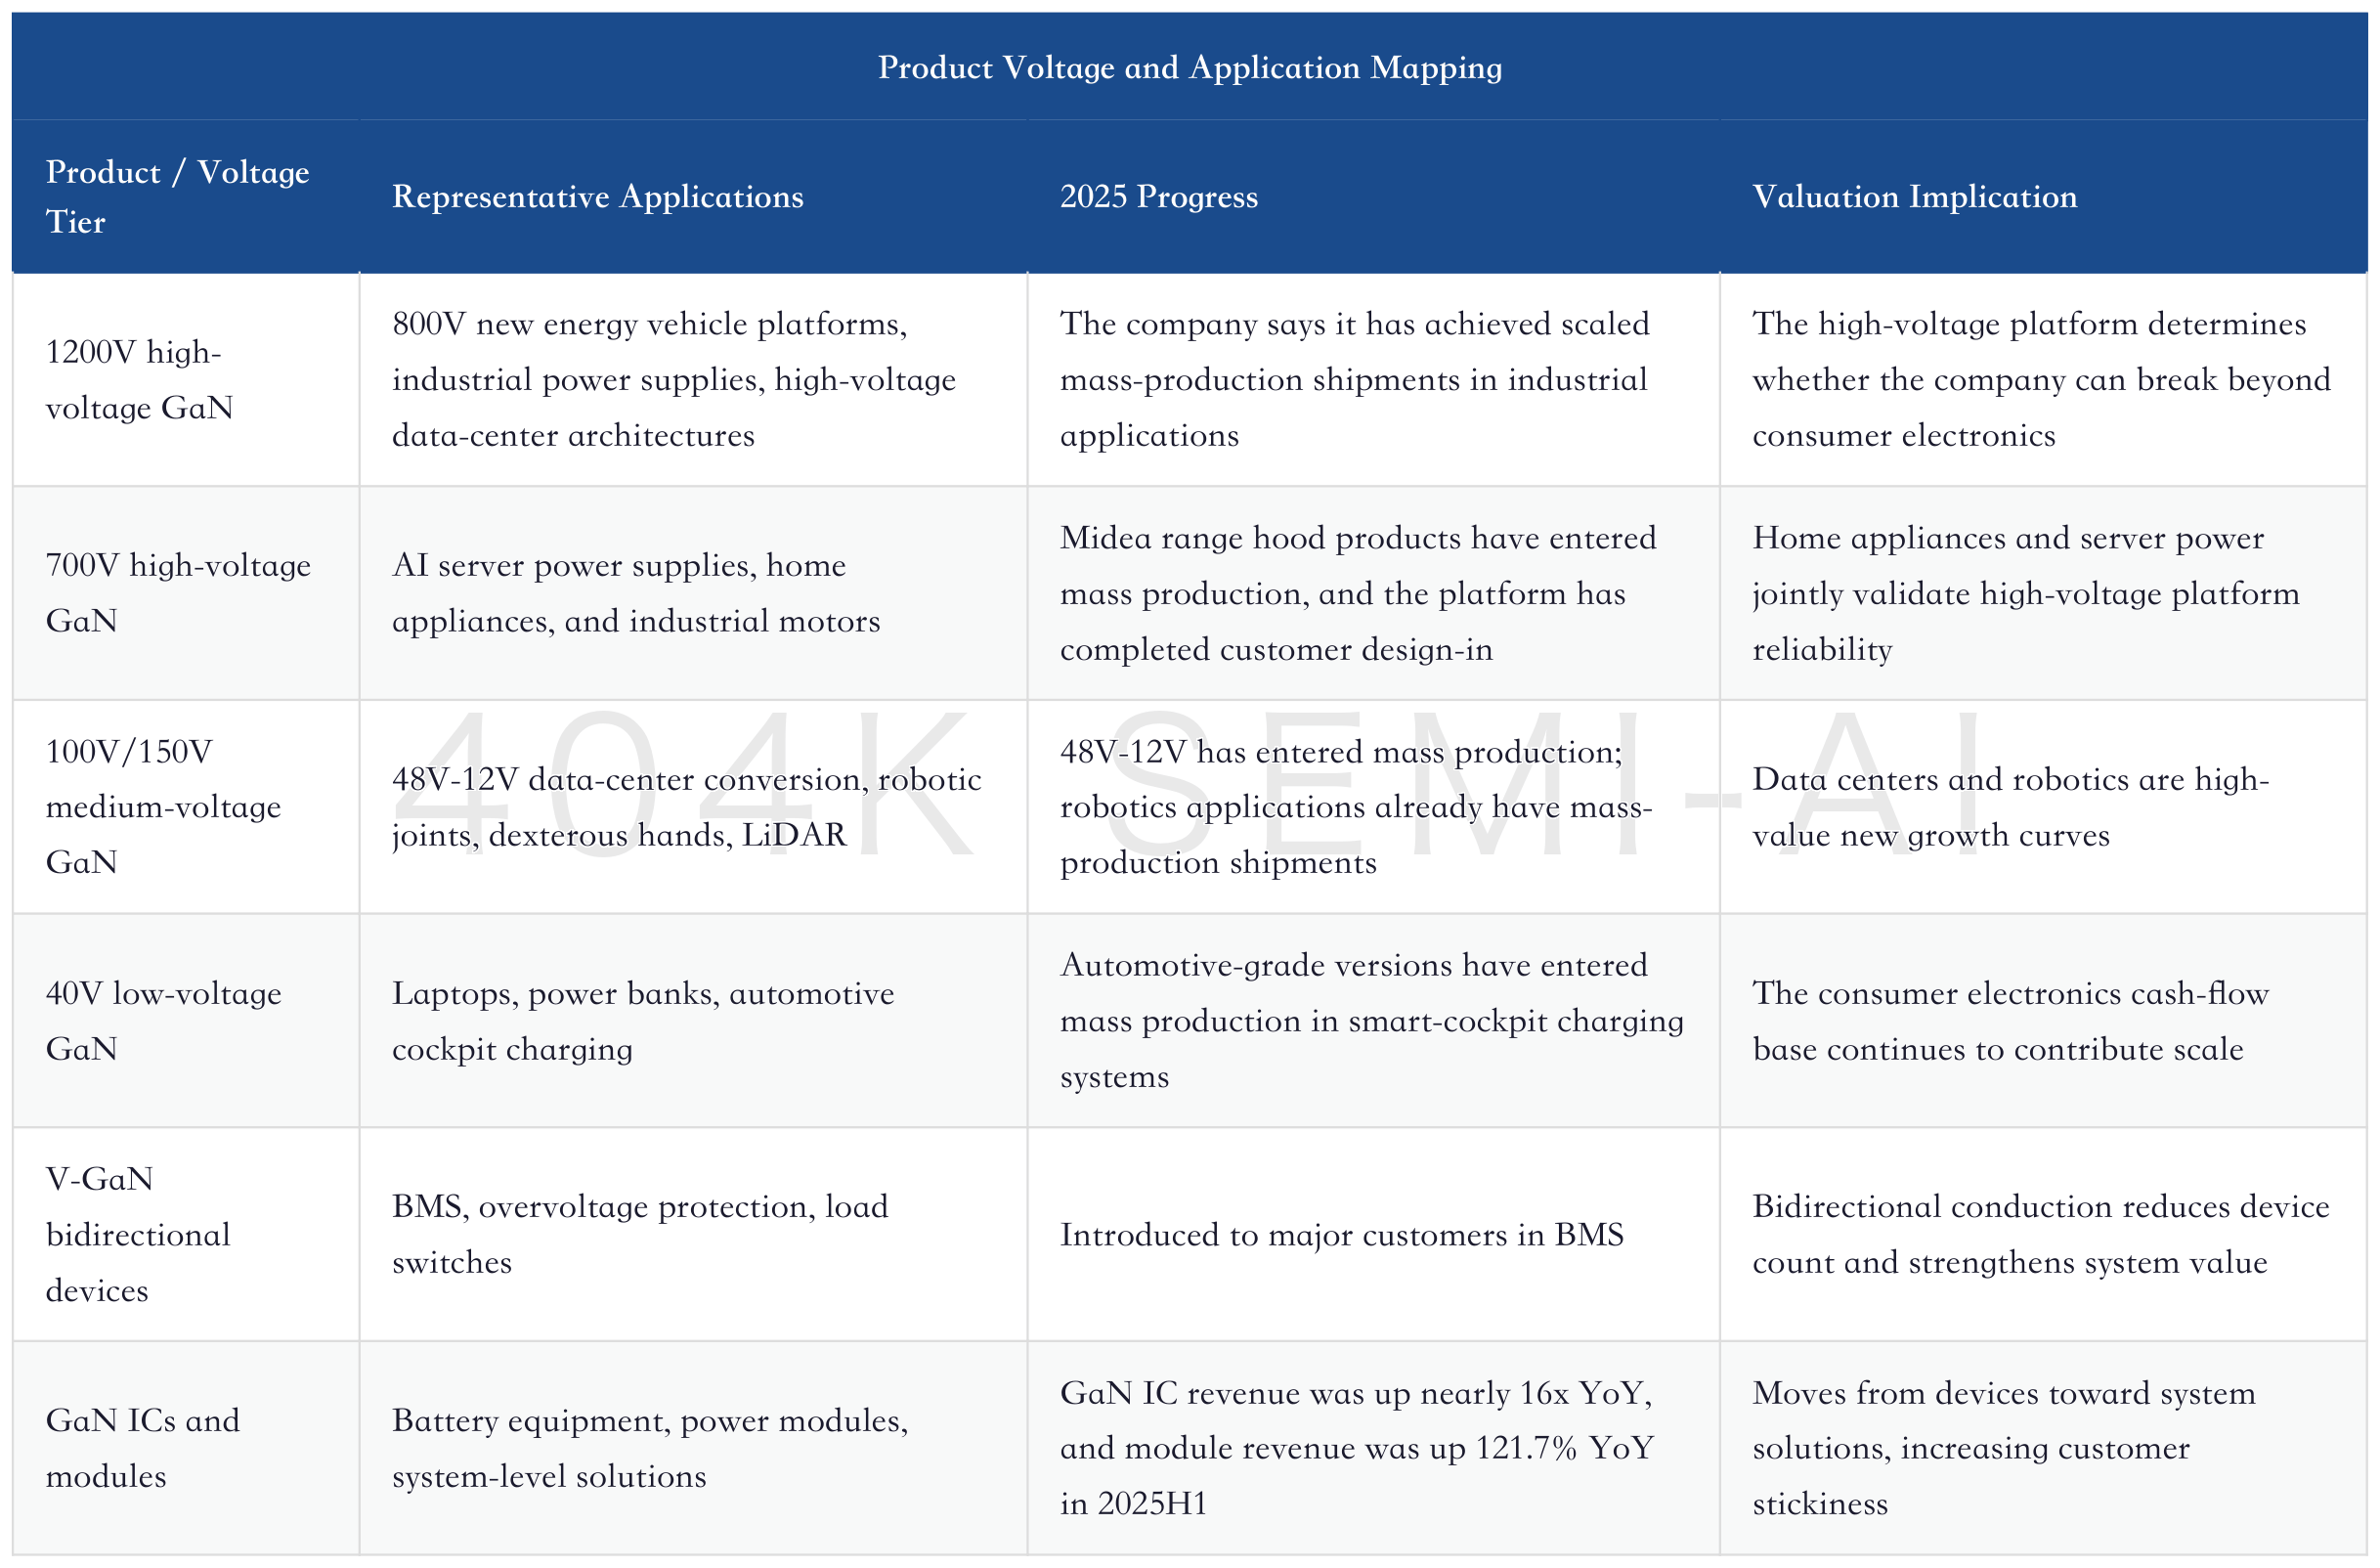
The 2025 interim report explains the product tiers relatively clearly. High-voltage products include 650V/700V/900V/1200V, used in new energy vehicle 800V battery platforms, AI data-center high-voltage buses, and industrial power supplies. Medium-voltage 100V/150V/200V products are used in data-center DC conversion, robotic dexterous hands and servo motors, and automotive LiDAR. Low-voltage 15V/30V/40V products are used in phones, PCs, power banks, load switches, overvoltage protection, and automotive smart-cockpit charging systems.
The value of a full voltage spectrum lies in reuse of customer certification. AI data-center customers will not look at only one high-voltage device, but rather the entire chain from input to the GPU end. Robotics customers will not buy only one medium-voltage device, but will look at the reliability of joint motors, internal power conversion, and power management. Automotive customers will care even more about IATF16949, long-term supply, and migration across multiple vehicle platforms. If Innoscience can turn 8-inch capacity and full-voltage-spectrum products into supply-chain stability, it will have an easier path to a premium valuation than single-device companies.
Another clue from 2025H1 is the partner base. The interim report disclosed that STMicroelectronics entered into a joint development agreement with the company, Midea established a strategic partnership with the company around GaN applications in home appliances, United Automotive Electronic Systems set up a joint laboratory with the company, and Nvidia is working with the company to promote large-scale application of 800VDC architecture in AI data centers. These partnerships do not automatically equal long-term orders, but together they point to one fact: customers are moving GaN from an “optional substitute” to a “candidate component for next-generation system architectures.”
The change in customer mix determines Innoscience’s revenue quality. Consumer electronics customers bring scale and cost learning, but product lifecycles are short and pricing pressure is high. Home appliance and industrial customers place more emphasis on reliability and can help the company validate its high-voltage platform. Automotive customers have long certification cycles, but once the company enters a platform, revenue stability and brand endorsement both become stronger. Data-center customer demand is the steepest, but reliability and supply pressure are also the highest. What Innoscience truly needs to do is transfer validation results across these customers, rather than fight a new battle in every application.
Automotive is an intermediate variable that the market can easily underestimate. It is not as attractive as AI data centers, but it is critical for a power semiconductor company. Automotive customers require long-term reliability, quality systems, batch consistency, and multi-model adaptability. Once these capabilities are established, they also help in industrial, robotics, and data-center applications. Innoscience’s high growth in automotive-grade chip shipments in 2025H1 and progress in cooperation with United Automotive Electronic Systems also show the company is not relying only on consumer electronics to prove itself.
Robotics is more like an extension scenario for medium-voltage GaN. Humanoid robot joints, dexterous hands, and servo motors require small size, high efficiency, and relatively high power density. Medium-voltage GaN can add value in drive and power-management stages. This market may not generate as much near-term revenue as data centers, but it can validate the company’s medium-voltage platform and modular design capabilities. If robotics applications move from samples to volume, Innoscience’s product matrix will look more like a multi-scenario platform rather than a single data-center bet.
Home appliance and industrial scenarios provide another type of value: scale, reliability, and cost discipline. The Midea partnership, industrial 1200V GaN shipments, and high-voltage home appliance platform adoption show the company has the opportunity to prove GaN durability in more conservative scenarios. These scenarios have less valuation elasticity than AI, but they can provide a more solid revenue base and reduce volatility from dependence on a single large customer or a single architectural shift.
This is also why Goldman Sachs is willing to assign a high multiple. Power semiconductors generally struggle to enjoy software-like valuations, because customer certification is slow, large customers push down pricing, and cycles are affected by inventory. But if GaN enters AI data-center power architectures, unit value, customer stickiness, and system importance will all rise. What Innoscience needs to prove is whether it can move from being a “high-performance substitute” to a “necessary component in an architectural upgrade.”
VI. Financial Model: From Positive Gross Profit to Positive Cash Flow
Innoscience’s most important financial inflection point has already appeared, but it is not complete. In 2025H1, total revenue was RMB553 million, up 43.4% YoY; gross profit was RMB37.848 million, with a gross margin of 6.8%, a clear improvement from -21.6% in 2024H1. This change shows the company has begun to move beyond the constraints of depreciation and its cost structure, and scale effects are starting to show up in the financials.
The issue is that turning gross margin positive is still some distance from turning net profit positive. In 2025H1, the company remained in both operating loss and net loss, with heavy expense pressure on the income statement; Goldman Sachs expects net profit and free cash flow to turn positive only in subsequent years. This means investors should not treat 2025H1 positive gross profit as the full victory. They still need to assess whether revenue quality can cover R&D;, administrative expenses, depreciation, and capacity expansion inventory build.
The financial model is really worth tracking across three lines. First, whether revenue can continue climbing from RMB1.213 billion in 2025E to RMB4.026 billion in 2027E; second, whether gross margin can rise from 7.3% to 31.1% under Goldman Sachs’ model; third, whether inventory turnover, accounts receivable, and capex allow free cash flow to turn positive in 2028E. If any one of these breaks, the high valuation will be repriced.
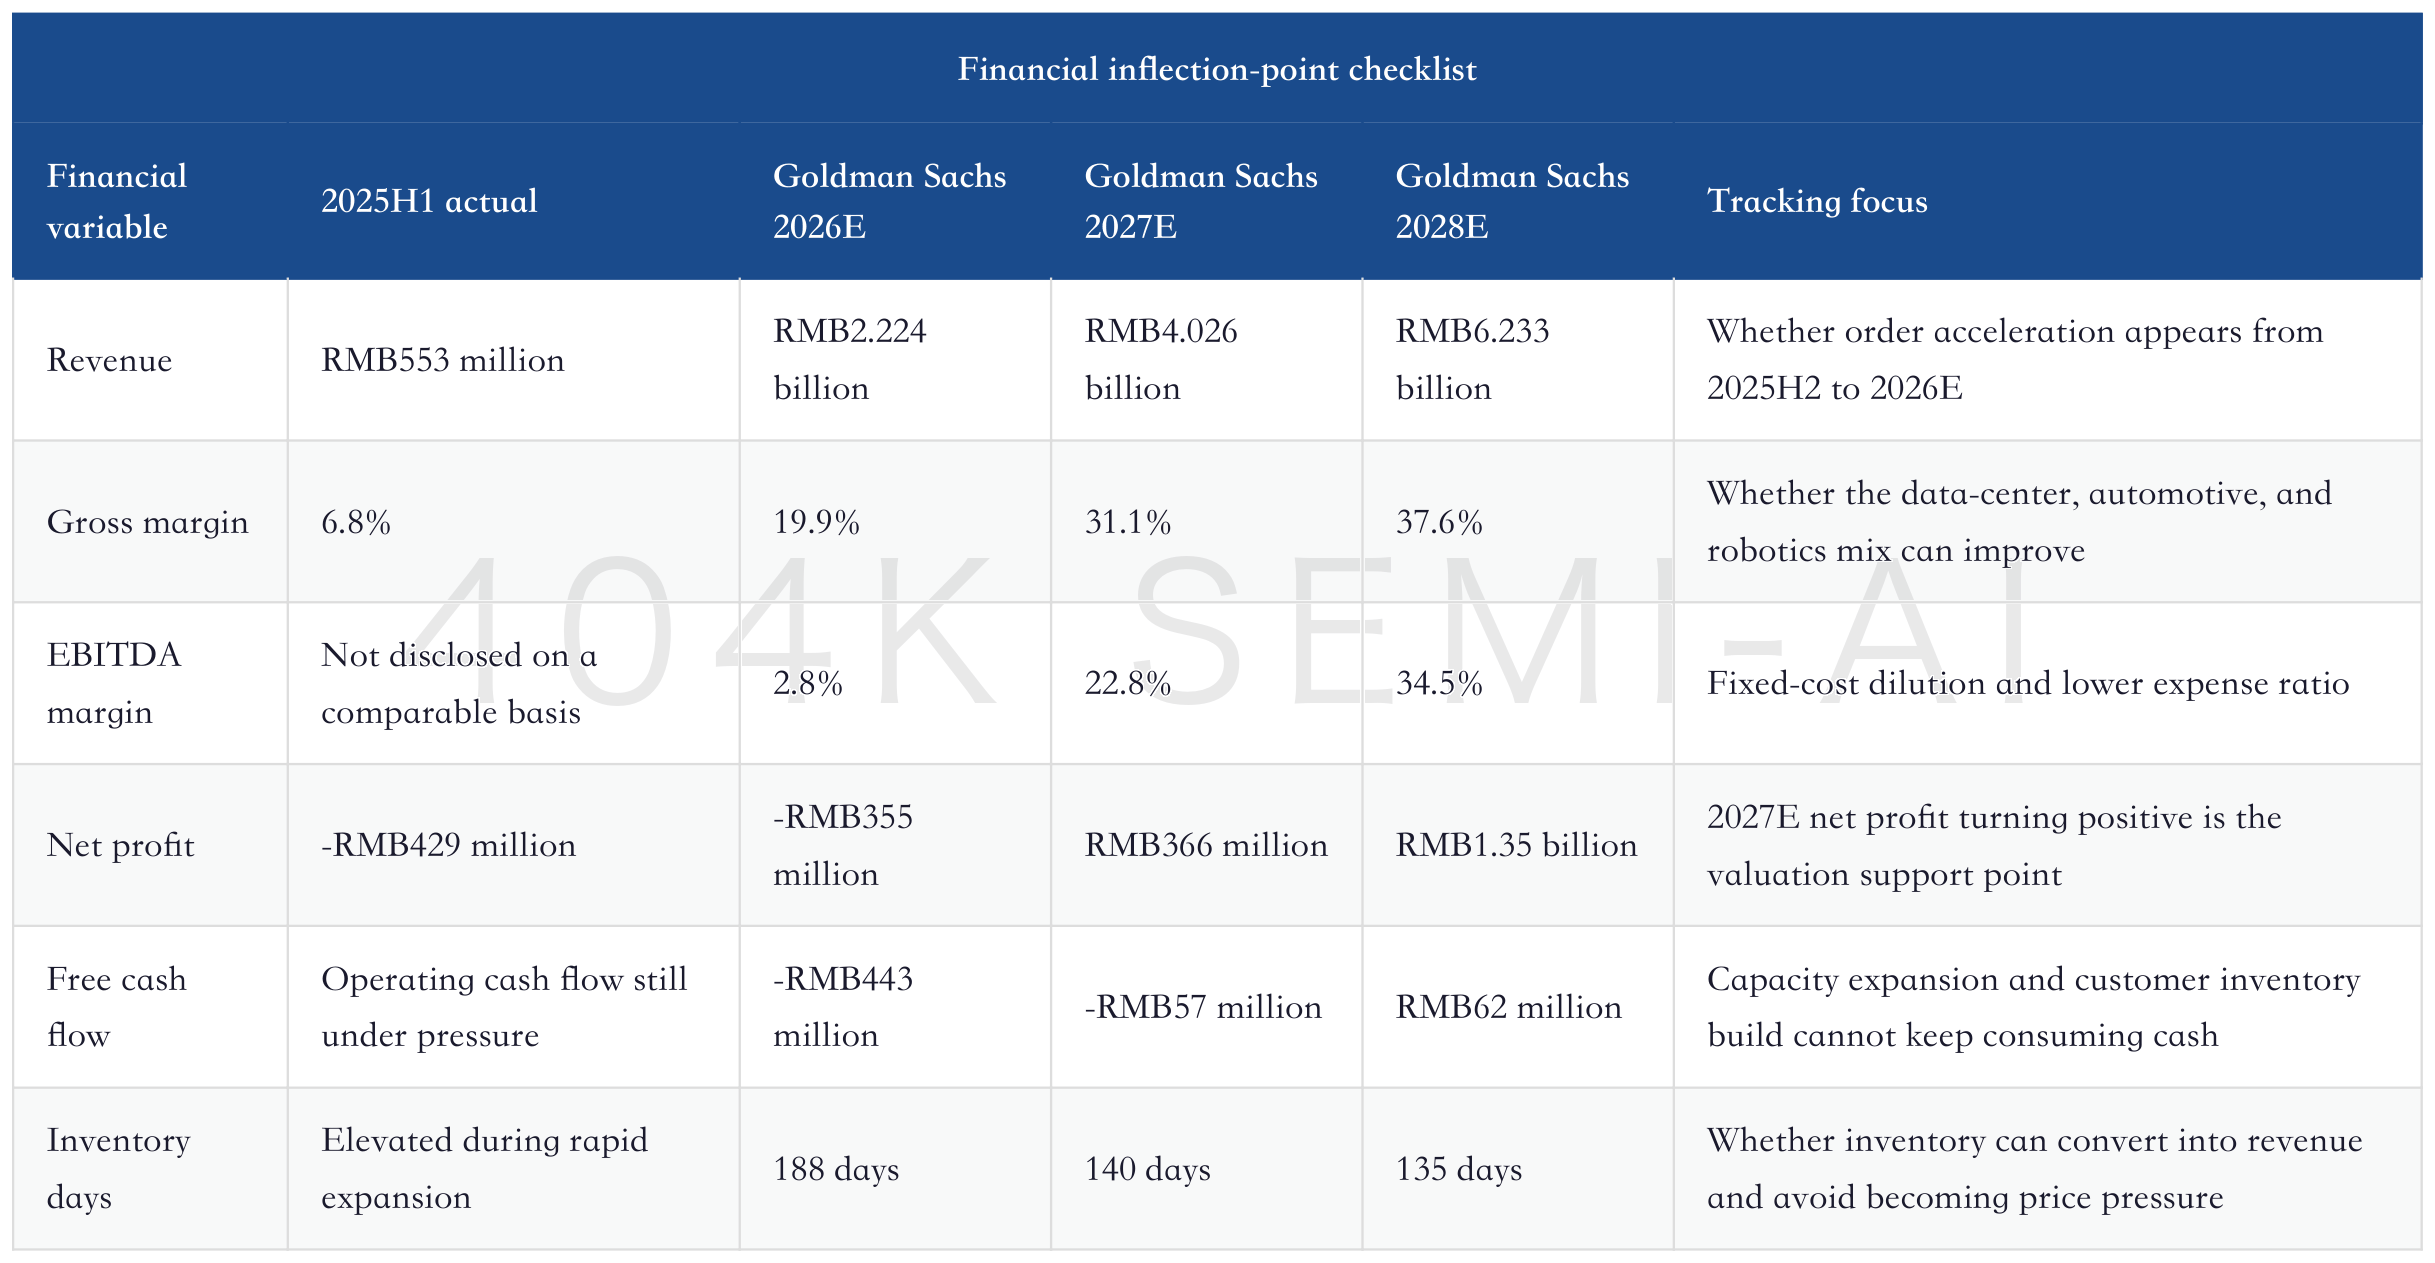
Goldman Sachs is not materially aggressive versus market consensus on revenue. Its 2026E, 2027E, and 2028E revenue forecasts are only 0%, 1%, and 2% above Bloomberg consensus, respectively. The real difference is on profitability: 2027E and 2028E net profit are 8% and 11% higher, respectively, mainly from product mix and operating-expense-ratio improvement driven by scale advantages. This shows the investment debate on Innoscience is not “whether there is growth,” but “whether the growth has profit quality.”
Therefore, the next earnings report should be judged by specific numbers, not a sentence like “AI customer progress is smooth”: data-center and automotive revenue mix, module and IC mix, gross-margin breakdown, inventory days, accounts-reivable days, capex, and utilization of 20k wpm capacity. If these metrics improve together, HK$114 will have financial-statement support; if only revenue grows while gross margin and cash flow fail to follow, valuation will come under pressure first.
The most easily overlooked part of financial quality is working capital. Innoscience is in a phase of rapid capacity expansion and customer introduction, so inventory and receivables can easily show up before profit does. The healthy state is inventory build following increased orders from high-end customers, with inventory turnover improving afterward; the dangerous state is inventory growth coming from overly optimistic demand assumptions, eventually turning into price cuts and impairment pressure. For a company still crossing the profitability threshold, changes in working capital can sometimes flag risks earlier than single-quarter revenue.
Expense ratios also need to be unpacked. High R&D; expense is not necessarily bad, as a GaN platform needs continuous work on epitaxy, devices, packaging, applications, and reliability validation; administrative expenses and post-listing compliance costs may also be elevated in the short term. The key is whether expenses can be absorbed by a higher revenue base. If revenue scales but expenses scale in tandem, platform-level profit will not appear; if revenue scales, gross margin rises, and expense ratios fall at the same time, the net-profit inflection point will have more leverage than the market originally expected.
The timing Goldman Sachs models for positive net profit and positive free cash flow is actually two different thresholds. Positive net profit means scale effects and gross margin are beginning to cover expenses; positive free cash flow means capacity expansion, inventory build, and customer payment terms are no longer continuing to consume profit. The former can support a transition from P/S toward earnings-based valuation, while the latter is needed to support a longer-cycle EV/EBITDA or discounted-cash-flow framework. If Innoscience only turns net profit positive while free cash flow remains under pressure for a long time, valuation will still be discounted.
