
Innolight Technology Deep-Dive Update: NPO Upgrades and 90 Million-Unit Capacity Behind the RMB1,375 Price Target
目录
TL;DR
Deconstructing RMB1,375: The Price Target Was Raised Even as EPS Declined Slightly
Financial Revisions: 2028 Matters More Than 2026
Product Curves: 1.6T Is the Core Driver, While 2.4T and NPO Provide Incremental Growth
CPO Has Substantial Upside, but It Cannot Be Directly Mapped to Company Revenue
90 Million Units of Capacity: Funding Has Been Secured, but Delivery Constraints Remain
Beyond Earnings, Cash Conversion Is a Hidden Optimistic Assumption
Three-Tier Scenario Framework: Revise EPS First, Then Discuss the Multiple
Investment View: RMB1,375 Is a Long-Term Validation Framework
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The price target was raised by only approximately 3.8%, yet long-term earnings continue to move higher. What Nomura has fundamentally rewritten is the timeline for NPO, 2.4T, and capacity-expansion delivery.
TL;DR
Nomura maintains its “Buy” rating on Innolight Technology (300308.SZ) and raised its price target from RMB1,325 to RMB1,375, implying 52.4% upside from the RMB902.01 share price on the report date. However, the price-target increase is only 3.8%; this is not a report built on a substantial near-term EPS upgrade.
The valuation bridge presents the most notable contrast: 2027 diluted EPS was trimmed from RMB66.06 to RMB65.47, while the P/E multiple was raised from 20x to 21x. The new price target is driven almost entirely by multiple expansion, also indicating that dilution from the H-share issuance has already been incorporated into the model.
Earnings upgrades are concentrated in the outer years. Nomura raised its 2026—2028 revenue forecasts by 2%, 2%, and 5%, net profit forecasts by 7%, 4%, and 10%, and gross-margin forecasts by 1.5, 2.1, and 3.1 percentage points. Its 2028 revenue and net profit forecasts are 75% and 50% above Wind consensus, respectively, showing that the debate has shifted from near-term orders to product generations and market share.
NPO is the most tangible incremental industry opportunity in this update. Nomura raised its 2027—2028 global shipment forecasts from 5 million and 20 million units to 8 million and 25 million units. It expects Innolight to capture a 40%—50% share, contributing 5%—6% of revenue. By comparison, CPO is more appropriately viewed as a long-term scenario ceiling.
The H-share financing has provided the necessary funding for R&D; and capacity. Citing company plans, Nomura states that approximately 35% of net proceeds will fund R&D; for 1.6T, 3.2T, NPO, and CPO, while 30% will support global capacity expansion, increasing annual capacity from approximately 40 million units to 90 million units by 2029. The funding is now in place; the next question is whether equipment deployment, yields, and customer share can ramp in tandem.
The report’s optimism extends beyond revenue and gross margin to cash conversion. Nomura expects the cash conversion cycle to decline from 95.6 days in 2025 to 28.5 days in 2026 and 8.6 days in 2027, with operating cash flow broadly keeping pace with net profit. If revenue grows rapidly but inventories, receivables, and cash flow do not improve concurrently, the earnings anchor will need to be recalibrated.
Deconstructing RMB1,375: The Price Target Was Raised Even as EPS Declined Slightly
Nomura’s previous valuation was straightforward: 20x 2027 diluted EPS of RMB66.06 produced RMB1,321.2, rounded to a price target of RMB1,325. The new report raises the multiple to 21x but adjusts diluted EPS for the same year to RMB65.47, yielding RMB1,374.87—exactly consistent with the new price target.
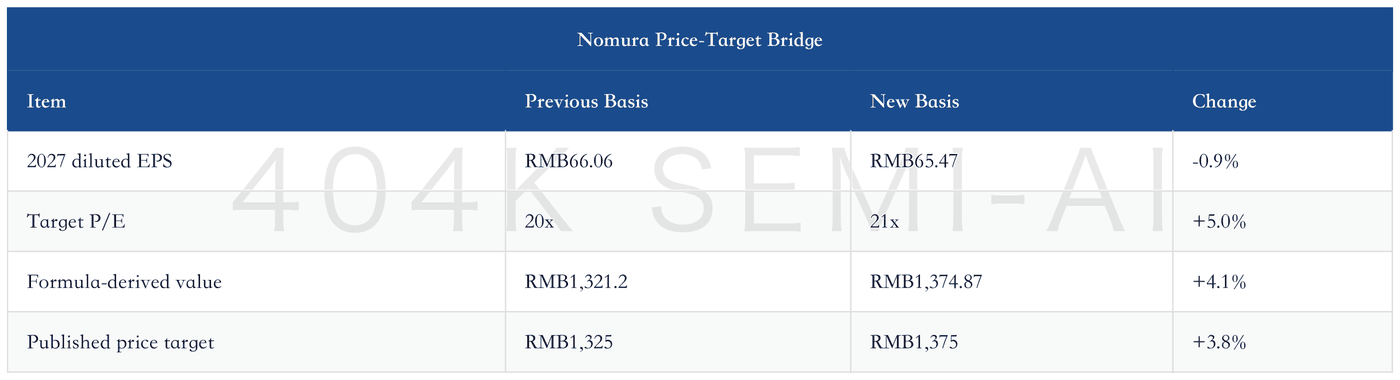
This result has two implications. First, the price-target increase does not mean 2027 per-share earnings were upgraded. Nomura did raise its 2027 net profit forecast by 4%, but diluted EPS is slightly below the previous model after the H-share issuance increased the share count. Second, Nomura is willing to assign an additional 1x P/E because it believes the company no longer has only a single growth trajectory built around 800G and 1.6T; it now has multiple verifiable growth engines spanning 2.4T, NPO, 3.2T, and CPO.
Basic EPS and diluted EPS should also not be conflated. The revision table on page 8 of the report shows 2027 basic EPS of RMB68.71, whereas the cover page, page 2, and the valuation formula use diluted EPS of RMB65.47, a difference of approximately 5%. In addition, page 3 states the price target as HKD1,375 and uses the Hang Seng Index as the benchmark; this is inconsistent with the cover page, page 7, and the A-share valuation context. The internally consistent and correct basis should be RMB1,375, benchmarked against the median valuation of A-share technology/electronic-component peers.
Innolight Technology Deep Dive: Behind Nomura’s RMB1,325 Target, How 2.4T, 3.2T, NPO, and CPO Push the Earnings Anchor Beyond 2028
Financial Revisions: 2028 Matters More Than 2026
Under Nomura’s new forecasts, revenue for 2026—2028 is RMB124.24 billion, RMB266.386 billion, and RMB388.945 billion, respectively, while net profit is RMB35.844 billion, RMB76.341 billion, and RMB114.172 billion. Revenue forecasts were raised by 2%, 2%, and 5% versus the previous model, while net profit forecasts were raised by 7%, 4%, and 10%. The progressively larger revisions in the outer years demonstrate that this is not an adjustment to the delivery cadence of a particular quarter, but a repricing of when next-generation products enter the revenue base.
