
目录
Executive Summary
1. The Most Important Change: Order Cycles Have Lengthened
2. Q2 Demonstrates Both Strong Demand and Emerging Delivery Constraints
3. With Orders Now Clear, 3nm and 5nm DSPs Become the Critical Bottleneck
IV. Base-Case Gross Margin Is Stable; New Products Are Needed to Drive Further Upside
V. The NPO and CPO Timelines Are Clearer, but Pluggable Products Will Still Drive 2026
VI. Overseas Capacity and Cash Flow Will Determine Whether Orders Become Free Cash Flow
VII. The Six Numbers That Matter Over the Next Several Quarters
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Orders are already in hand, but the supply chain remains the key determinant of the delivery ramp. Demand visibility into 2027 has improved, while DSPs, optical chips, overseas capacity, and working-capital requirements still need to be monitored quarter by quarter.
Executive Summary
Demand visibility for 2027 has strengthened further. Innolight management said key customers have converted their 2027 demand guidance into full-year orders. The customary order cycle of approximately 3 months has lengthened materially, and some customers are discussing longer-term supply agreements. As visibility improves, the market debate will shift from whether demand exists to whether suppliers can deliver on time.
The Q2 revenue ramp was constrained by capacity expansion, while earnings continued to outpace revenue. Based on the official financial statements, Q2 revenue was RMB22.281bn, up 14.3% sequentially, while net profit attributable to shareholders was RMB7.917bn, up 38.1%. Management attributed the gap partly to capacity ramp-up and delivery constraints across the supply chain; underlying orders remained strong.
Critical components will remain the principal constraint from 2026 through 1H27. Supply remains tight for the 3nm DSPs used in 1.6T products, the 5nm DSPs used in 800G products, and certain optical chips and PICs. Upstream capacity additions should improve supply each quarter, but management does not expect the tightness to dissipate quickly.
Gross margin is more likely to remain stable near current highs than rise continuously in the near term. A higher 1.6T mix and greater silicon-photonics penetration provide upside support, while upstream price increases, higher R&D; spending, and FX volatility create pressure. Official data imply a Q2 gross margin of approximately 45.6%, slightly below approximately 46.1% in Q1. The earnings acceleration reflected a combination of product mix, operating leverage, and other operating items.
The commercialization timelines for NPO, CPO, and 2.4T are becoming clearer. Two leading customers have already provided explicit demand indications, guidance, or orders for NPO. Mass production of the new products is expected to begin in 2H27 and scale in 2028. However, 800G and 1.6T pluggable products will remain the primary profit contributors in 2026; longer-term technology leadership should not be conflated with current-period earnings.
Longer order coverage also increases working-capital intensity. Innolight must use long-term agreements, prepayments, advance inventory purchases, and overseas capacity to secure delivery. Operating cash flow was only RMB1.787bn in 1H26, while inventories, receivables, and prepayments increased materially. Approximately HK$52.9bn in net proceeds from the H-share offering eases funding pressure, but also raises the bar for returns on capital and EPS delivery.
1. The Most Important Change: Order Cycles Have Lengthened
Innolight (300308.SZ; 03308.HK) is seeing demand visibility extend from quarterly production schedules to full-year deliveries. Management said the industry’s typical order cycle had historically been approximately 3 months. Many customers have now placed orders covering all of 2027, while some are discussing longer-term supply arrangements. In August 2026, a group of key customers converted their 2027 demand guidance into firm orders.
This is a significant development. The optical-module industry has historically been exposed to fluctuations in customer capex, product-generation transitions, and inventory adjustments. When orders cover only one quarter, suppliers cannot readily commit a year in advance to expensive chips, equipment, and facilities. Full-year orders provide a stronger basis for inventory procurement and capacity expansion, while improving suppliers’ ability to negotiate long-term agreements with upstream vendors.
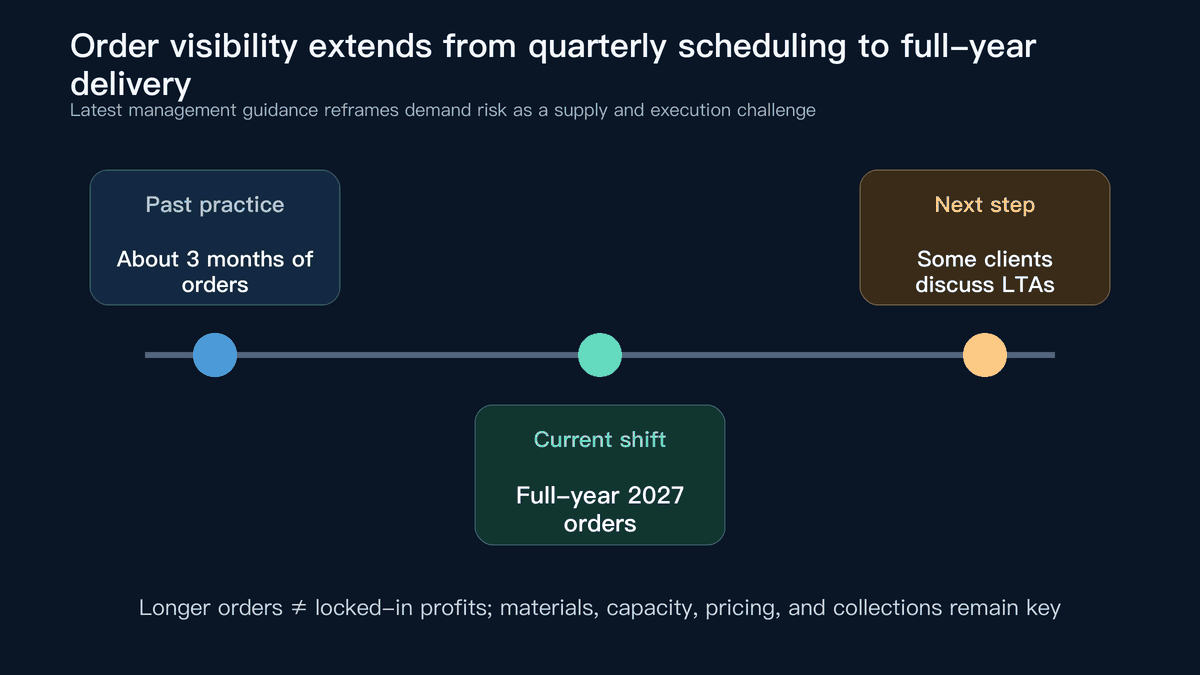
Longer order cycles do not mean profits are already locked in. Even after customers provide full-year demand, Innolight must still address four issues: whether critical components arrive on schedule, whether new capacity reaches target yields, whether product pricing offsets higher material costs, and whether customers pay under existing terms. Delays at any stage could initially convert orders into inventories, prepayments, and construction in progress, with revenue and cash collection lagging behind.
Demand-side evidence is currently strong. Management expects 800G and 1.6T to maintain rapid growth in 2027, with Innolight’s 1.6T share among established cloud customers remaining stable. New entrants are serving more emerging cloud customers and foundation-model companies, while incumbent hyperscalers continue to favor suppliers with completed qualifications and established delivery records. As the addressable market expands, new competitors can gain business even as leading suppliers maintain their shares.
Customer capex is also supporting orders. Several major cloud providers have raised their infrastructure spending plans for 2026 and 2027, with continued growth in GPU and custom-accelerator clusters. Higher compute density requires more high-speed interconnects and increases the required deployment intensity of switching chips and optical modules. Innolight’s near-term challenge therefore appears to be supply constraints rather than insufficient demand.
There are clear limits to this conclusion. Cloud-customer concentration remains high, and even annual orders may be revised because of changes in data-center construction, chip deliveries, or network architecture. Investors should view full-year orders as stronger production-planning support, rather than treating the entire order book as non-cancellable revenue.
2. Q2 Demonstrates Both Strong Demand and Emerging Delivery Constraints
The official interim report showed 1H26 revenue of RMB41.778bn, up 182.5% year over year, and net profit attributable to shareholders of RMB13.651bn, up 241.7%. Subtracting Q1 results from the first-half totals yields Q2 revenue of RMB22.281bn and attributable net profit of RMB7.917bn. Revenue rose 14.3% sequentially, while profit increased 38.1%.
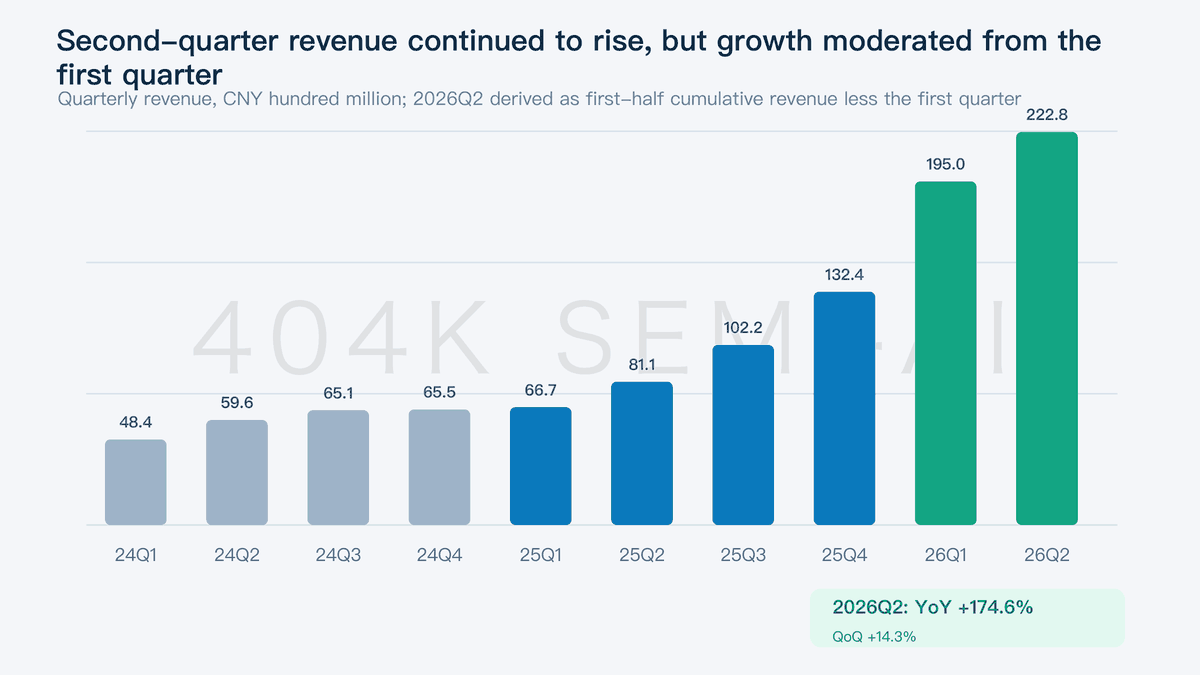
Management attributed the slower increase in Q2 revenue relative to profit partly to capacity ramp-up and delivery issues across the production chain. This adds important context to the reported figures. Q2 revenue still reached a record high, but its 14.3% sequential growth was materially below Q1’s 47.3%. Viewed in isolation, the financial statements could suggest weakening demand momentum. Management’s earnings-call commentary indicates that part of the gap instead reflected supply and manufacturing constraints that prevented all orders from converting into shipments during the quarter.
Several factors drove profit growth ahead of revenue. The 1.6T shipment mix increased, silicon-photonics penetration rose, and the overall product mix continued to improve. Revenue growth also reduced administrative, R&D;, and selling expenses as a percentage of sales. Q1 additionally included a subsidiary’s one-off expenses and settlement of service fees from prior years, with no comparable items of the same scale recurring in Q2.
