
In-Depth Review of Google, Meta, Microsoft, and Amazon’s Latest Earnings: Divergence in Capex Efficiency, Cloud Revenue, and Free Cash Flow
目录
TL;DR
1. The Same AI Buildout Cycle, 4 Completely Different Financial Statements
2. First, Separate the 4 Definitions of “Capex”
3. Cross-Sectional Cloud Comparison: 3 Different Rankings for Growth, Scale, and Margins
4. Sequential Changes: Q2 Widened the Divergence Further
5. Microsoft: Currently the Closest to a “Build First, Then Fill Capacity Rapidly” Model
6. Amazon: AWS Delivers the Most Direct Returns, While Group Cash Flow Faces the Most Visible Pressure
7. Google: Cloud Business Quality Is Improving, but Cash Flow Has Already Crossed a Critical Threshold
8. Meta: Not a Cloud Provider, but the Most Aggressive Buyer of Computing Capacity
9. The Depreciation Wall: Today’s Capital Expenditures Become Costs Over the Coming Years
10. Supply-Chain Implications: Order Strength Remains High, but Revenue Recognition Timelines Will Diverge
11. Whose Capital Expenditures Are Most Efficient: Only a Preliminary Answer Is Possible for Now
12. Five Pairs of Metrics to Watch Over the Next Four Quarters
Conclusion: The Capital-Expenditure Race Has Entered the Profit and Cash-Flow Validation Phase
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
All 4 companies are accelerating AI infrastructure buildouts, but cloud revenue, profit realization, and cash recovery have already diverged along 4 distinct paths.
TL;DR
This quarter’s returns on investment have already become clearly stratified. Google, Meta, Microsoft, and Amazon invested $44.924 billion, $30.116 billion, $35.802 billion, and $54.208 billion in property and equipment on a cash basis, up 100%, 82%, 110%, and 68% year over year, respectively. Microsoft can still cover capex with $55.441 billion of operating cash flow; at Google and Amazon, quarterly cash investment exceeded operating cash flow, while Meta’s company-defined free cash flow after finance lease principal payments was only $784 million.
There are 3 leading dimensions on the public-cloud revenue front. Google Cloud revenue grew 82% year over year, the fastest rate, but included the first-time recognition of sales from delivering TPU systems to customers’ own data centers; Azure revenue is not disclosed separately, but grew 43% year over year, while Intelligent Cloud revenue increased 32%; AWS revenue grew 37%, its fastest pace in 18 quarters. Looking simultaneously at cloud-segment operating income, AWS generated $16.621 billion, Intelligent Cloud $15.955 billion, and Google Cloud $8.814 billion. All 3 demonstrate that AI demand has entered the income statement and moved beyond order-book evidence.
Microsoft currently has the strongest cash-flow defense. Quarterly operating cash flow was equivalent to 1.55x cash capex, and free cash flow remained $19.639 billion. AWS revenue and operating income accelerated more visibly, but Amazon’s quarterly cash purchases of property and equipment reached $54.208 billion, exceeding operating cash flow of $45.387 billion; after deducting proceeds from asset disposals and incentives, quarterly free cash flow remained negative at $7.689 billion. Microsoft leads in cash coverage, while Amazon leads in cloud-business acceleration and profit scale.
Meta has the highest capex intensity and the least direct evidence of returns among the 4 companies. Its cash investment in property and equipment was equivalent to 49.5% of revenue, rising to 51.1% after including finance lease principal payments; however, Meta has no standalone public-cloud revenue, so investment returns can only materialize gradually through ad ranking, recommendation efficiency, engagement, and future new products. This quarter, Family of Apps revenue grew 28%, while operating income declined 6%. Although the $2.4 billion legal matter and $1.18 billion of severance costs were significant disruptions, evidence of returns on capital remains more indirect than at the 3 cloud providers.
Google occupies the position of “fastest growth, tightest cash flow, but still ample financing.” Google Cloud generated $24.768 billion of revenue and $8.814 billion of operating income, with segment margin rising to 35.6%; however, group capex of $44.924 billion exceeded operating cash flow of $39.069 billion, turning free cash flow negative at $5.855 billion. Google also expanded its funding through equity and debt financing, indicating that the company has chosen to capture the compute-capacity window rather than wait for operating cash flow to naturally cover the pace of construction.
The real test ahead is whether 3 clocks can resynchronize. The first clock is capex, initially created by servers, GPUs, networking, and data centers; the second is monetization through cloud and advertising revenue; the third is depreciation, energy, leasing, and maintenance costs entering the income statement. The second clock has now clearly started for Microsoft, AWS, and Google Cloud, but cash recovery at Google, Meta, and Amazon continues to lag; if cloud growth slows in the next phase while depreciation continues to rise, the divergence in capital efficiency will widen further.
1. The Same AI Buildout Cycle, 4 Completely Different Financial Statements
All 4 companies appear to be buying GPUs, servers, networking equipment, power, and data centers, but the financial implications cannot simply be reduced to “the greater the capex, the stronger the AI leadership.” Microsoft, Amazon, and Google operate public clouds that charge external customers, allowing new infrastructure to generate revenue directly through Azure, AWS, and Google Cloud; Meta primarily uses compute capacity for ad recommendations, content ranking, generative-AI products, and long-term research, with returns first appearing in ad conversion rates, user engagement, and product experience, making them difficult to discern from a standalone cloud segment.
Accordingly, this report evaluates capital efficiency through 3 layers of metrics. The first is group-level cash capacity: whether operating cash flow can cover cash investment in property and equipment. The second is business monetization: whether incremental revenue and operating income from cloud or core businesses are accelerating. The third is future costs: whether depreciation and amortization, leasing, energy, and networking costs are beginning to erode gross margin. Looking only at the first layer would underestimate demand intensity; looking only at the second would overlook cash pressure; and looking only at the third would misclassify new capacity that is still ramping as permanently inefficient.
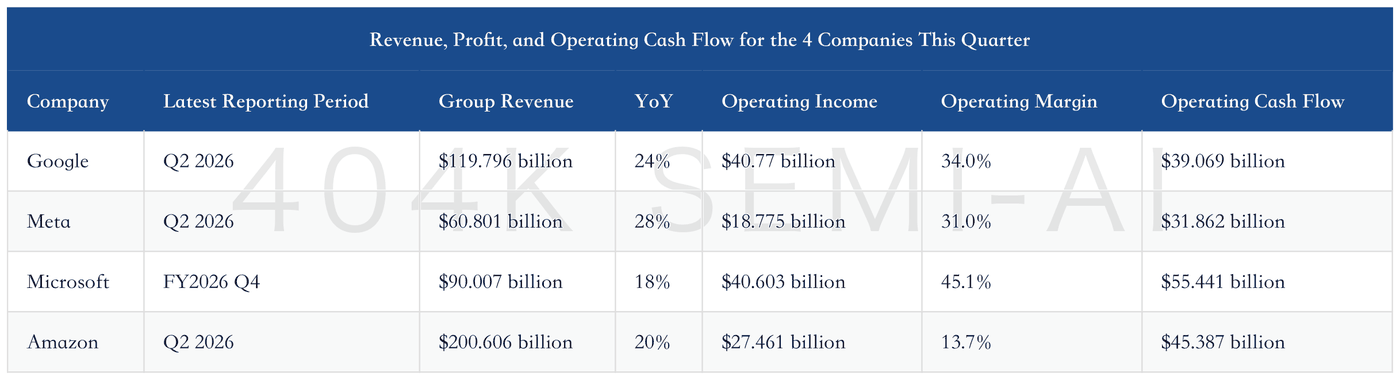
Microsoft’s group operating margin remains the highest because enterprise software, subscriptions, and its cloud platform collectively provide high-margin revenue; Google ranks second, with the search-ad cash cow continuing to support cloud buildouts; Meta’s operating margin declined to 31%, reflecting both one-time expenses and expanding infrastructure and R&D; Amazon has the lowest operating margin, but its retail and logistics businesses structurally depress the group margin, so this cannot be used to dismiss AWS’s returns on capital.
Net income is particularly easy to misread this quarter. Google recorded substantial gains on equity securities, while Amazon also recognized a $53.415 billion non-operating pre-tax gain from its Anthropic investment, significantly boosting net income at both companies. To assess whether capex is effective, investors should prioritize operating income, operating cash flow, and segment profit rather than treating changes in investment valuations as returns from cloud operations.
2. First, Separate the 4 Definitions of “Capex”
The most common error in comparing capex is to simply rank the headline figures reported by the 4 companies. Google’s capex refers to purchases of property and equipment in the cash-flow statement; the capex figure Meta emphasizes externally also includes finance lease principal payments; Microsoft’s financial statements report cash additions to property and equipment, while the broader measure that includes differences related to leases and the timing of receipts cannot be mixed with the cash figure; when calculating free cash flow, Amazon deducts proceeds from asset disposals and incentives from purchases of property and equipment.
To produce the closest possible like-for-like comparison, the main table first presents “quarterly cash purchases of property and equipment.” Amazon’s company-defined net cash investment is also shown, while finance lease principal payments are listed separately for Meta. Operating cash flow less cash purchases is only a standardized analytical metric and does not necessarily equal the free cash flow formally disclosed by each company.
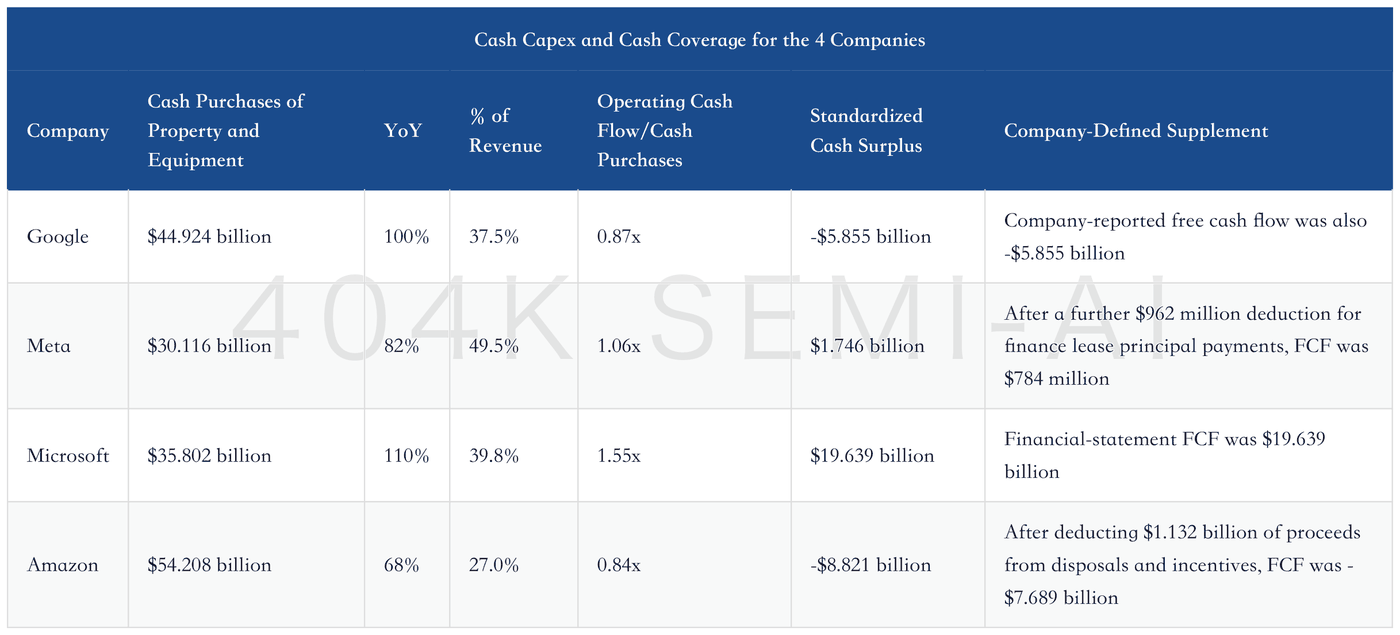
This table shows 3 things.
First, Amazon has the largest absolute investment, Meta has the highest investment intensity, and Microsoft has the best cash coverage. Amazon’s quarterly cash purchases of property and equipment totaled $54.208 billion, the highest of the group; Meta’s cash purchases were equivalent to 49.5% of revenue and exceeded half of revenue if finance lease principal payments are included; although Microsoft’s cash capex doubled year over year, operating cash flow still exceeded cash investment by $19.639 billion.
Second, capex growth exceeded group revenue growth at all 4 companies. Revenue at the 4 companies grew 18%—28%, while cash capex increased 68%—110%. This means current revenue is not the primary constraint on the pace of construction; management teams are deploying supply in advance based on future demand. As long as future revenue materializes smoothly, operating leverage may continue to improve; if demand falls below expectations, depreciation and cash-flow pressure will emerge before assets can be retired.
Third, negative cash flow does not mean business momentum is stalling, but it raises the required return threshold. Cloud revenue and segment profit accelerated at both Google and Amazon, while the groups’ quarterly cash surpluses were negative, showing that “real demand” and “delayed cash recovery” can coexist. Meta retained a modest positive surplus, but it nearly disappeared after including finance lease principal payments. Only Microsoft maintained both high cloud growth and a substantial free-cash-flow cushion.
3. Cross-Sectional Cloud Comparison: 3 Different Rankings for Growth, Scale, and Margins
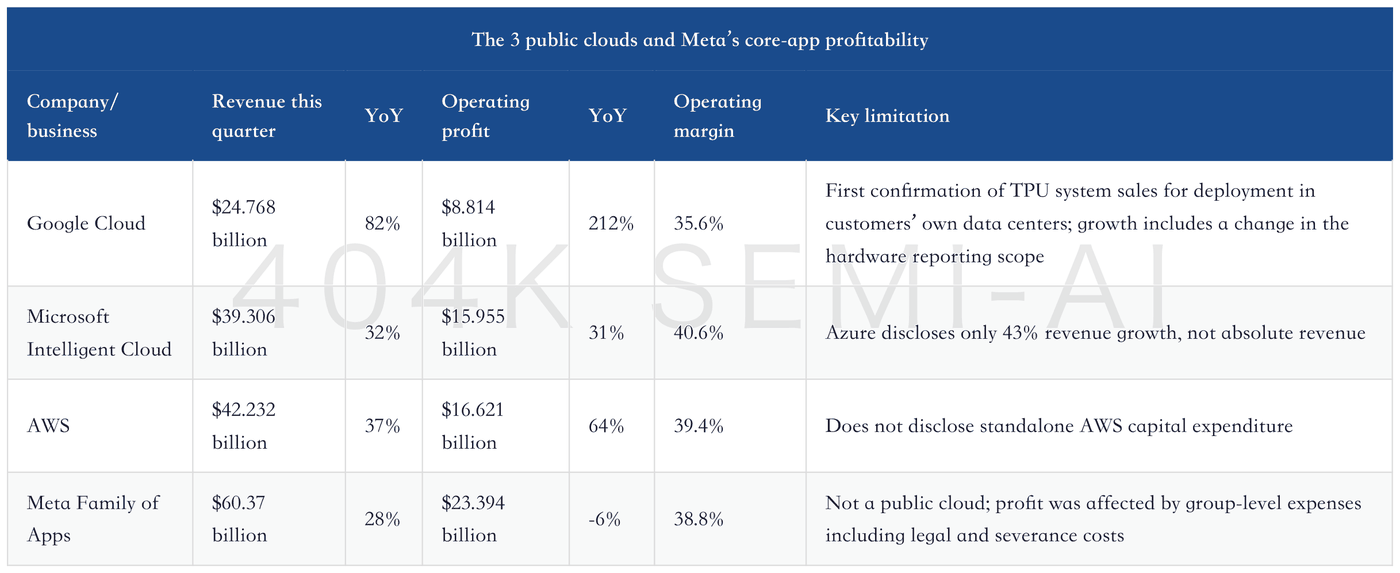
By revenue growth, Google Cloud ranks 1st; by absolute cloud profit, AWS ranks 1st; by group-level cash coverage, Microsoft ranks 1st. This is also why no single metric can determine the winner this quarter.
Google Cloud revenue increased 82% YoY, accelerating significantly again from the previous quarter, while operating profit rose to $8.814 billion and segment margin increased from 20.7% to 35.6%. Growth did not rely solely on price reductions: incremental cloud operating profit was approximately $5.988 billion, against incremental revenue of approximately $11.143 billion, implying an incremental margin of approximately 54%. However, this quarter marked the first confirmation of sales involving TPU systems delivered for deployment in customers’ own data centers, which simultaneously boosted revenue and changed the business mix. The official financial results explicitly stated that cloud growth still accelerated significantly even excluding these sales. The accurate conclusion is therefore that TPU sales amplified growth but did not account for all of it.
