
In-Depth on CXMT: DDR5 Ramp, RMB50 Billion 1H Attributable Profit, and the Cycle Test for China’s DRAM Leader
目录
Too Long; Didn’t Read
I. What CXMT Actually Sells: Memory Chips, Not a Concept Stock
II. The Real Highlight of This Prospectus: The Income Statement Suddenly Looks Intimidating
III. Where the Profit Comes From: Pricing, DDR5, and Scale Effects Working Together
IV. Revenue Mix Has Changed: From a Mobile Memory Base to Server DDR5 Upside
V. Why 2023 Losses Were So Large: DRAM Fabs Have Heavy Fixed Costs
VI. Customer Mix: High Concentration, But Not Single-Customer Dependence
VII. RMB34.5 Billion Fundraising Projects: The Money Is Mainly for Upgrades, Not Storytelling
VIII. Offering Arrangement: Pricing Is Not Set Yet; For Now, Focus on the Mechanism
IX. Three Scenarios: Profit Delivery Cannot Be Viewed Only From the Optimistic Side
X. Compared with Global Peers, CXMT’s Strengths and Weaknesses Are Both Clear
XI. The Easiest Misread: First-Half Profit Is Very High, but Full-Year Results Cannot Be Linearly Extrapolated
XII. Risk List: This Company Is Strong, but the Risks Are Not Soft
XIII. How to Define CXMT Before the Offer Price Is Announced
XIV. After the Offer Price Is Set, First Clarify the Profit Basis
XV. Post-Listing Monitoring Checklist for ChangXin
XVI. Conclusion: The Key Question for ChangXin Technology Is How Much of Its High Profit Can Stay
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The core of CXMT’s prospectus is how a DRAM manufacturer whose profits have long been suppressed by depreciation, R&D;, and the memory downcycle can unlock earnings in 2026 through DDR5 volume growth, price increases, and scale effects. The offer price has not been set, so valuation must wait for the bookbuilding result, but the sources of profit, cycle risks, and use of proceeds are already clear.
Too Long; Didn’t Read
CXMT is entering the profit realization phase. Revenue reached RMB61.799 billion in 2025, and 2026Q1 revenue had already reached RMB50.8 billion. The prospectus gives an even stronger 1H 2026 estimate: revenue of RMB110-120 billion, net profit attributable to shareholders of RMB50-57 billion, and recurring net profit attributable to shareholders of RMB52-58 billion. These figures show that CXMT’s earnings leverage has now reached the scale of mainstream DRAM makers, but the company has not provided an official full-year profit forecast, so investors should not simply double the first-half number.
The profit surge comes from three variables. DRAM price increases, DDR5 volume growth, and capacity scale diluting fixed costs are together pushing the income statement higher. In 2025, DDR-series revenue was already close to RMB20 billion, while server application revenue also expanded significantly. This shows CXMT is shifting from a business dominated by smartphone LPDDR toward higher-priced, higher-margin DDR5 and server memory.
Net profit metrics need to be unpacked. CXMT’s 2025 net profit was RMB7.144 billion, but net profit attributable to shareholders was only RMB1.875 billion, while recurring net profit attributable to shareholders was RMB5.316 billion. The reason is the company has complex reporting items such as structured entities, minority interests, and fair value changes. When assessing earning power, investors should not focus on a single net profit number, but should look at recurring attributable profit, gross margin, operating cash flow, and the pricing cycle together. In 2026Q1, recurring attributable profit reached RMB26.341 billion, nearly five times the full-year 2025 level. This is the strongest financial signal in the prospectus.
CXMT’s risks are also clear: DRAM is a highly cyclical industry. Prices rise quickly, and can fall sharply as well. The prospectus itself warns that the sharp growth in 1H 2026 results may not be sustainable. In 2023, the company posted an attributable net loss of RMB16.34 billion, mainly because the industry downturn, price declines, depreciation, and inventory impairment all hit at the same time. CXMT’s current profit should not be viewed like that of a stable consumer electronics company. It is more like a capital-intensive cyclical manufacturer moving from capacity ramp-up into a pricing upcycle.
Valuation must wait for the offer price. Before the offer price is announced, CXMT’s valuation should be assessed through three questions: how high the offer price implies for annualized 1H 2026 recurring attributable PE; whether the market is willing to assign a higher multiple to peak-cycle profits for China’s domestic DRAM leader; and whether the RMB29.5 billion in proceeds can turn technology platform and capacity upgrades into cost advantages in the next cycle. If priced on 2025 profit, the stock will look expensive. If priced on annualized 1H 2026 profit, it will look cheap. The real question is how much of this cycle’s profit can be retained.
I. What CXMT Actually Sells: Memory Chips, Not a Concept Stock
CXMT makes DRAM. In plain language, DRAM is the memory used when smartphones, PCs, and servers are running. No matter how fast a CPU, GPU, or smartphone processor calculates, it needs DRAM to feed in the data currently being processed. If memory is insufficient, the system lags; if memory bandwidth is insufficient, the performance of AI servers and high-end devices is held back.
CXMT’s products mainly fall into two lines. The first is DDR, mainly used in servers, desktops, laptops, and workstations. The second is LPDDR, mainly used in smartphones, tablets, thin-and-light notebooks, and wearables. DDR is more oriented toward performance and capacity, while LPDDR is more oriented toward low power consumption and mobile devices. CXMT currently covers DDR4, DDR5, LPDDR4X, and LPDDR5/5X, and can also produce DRAM wafers, chips, and modules.
This matters for investment analysis. CXMT’s revenue does not come from a single product, nor is it only betting on smartphone memory. It already serves applications including mobile devices, servers, PCs, and intelligent vehicles. Before 2025, LPDDR was the largest revenue contributor because smartphone customers were onboarded earlier. After 2025, DDR5 and server revenue rose quickly, truly opening up the company’s earnings leverage.
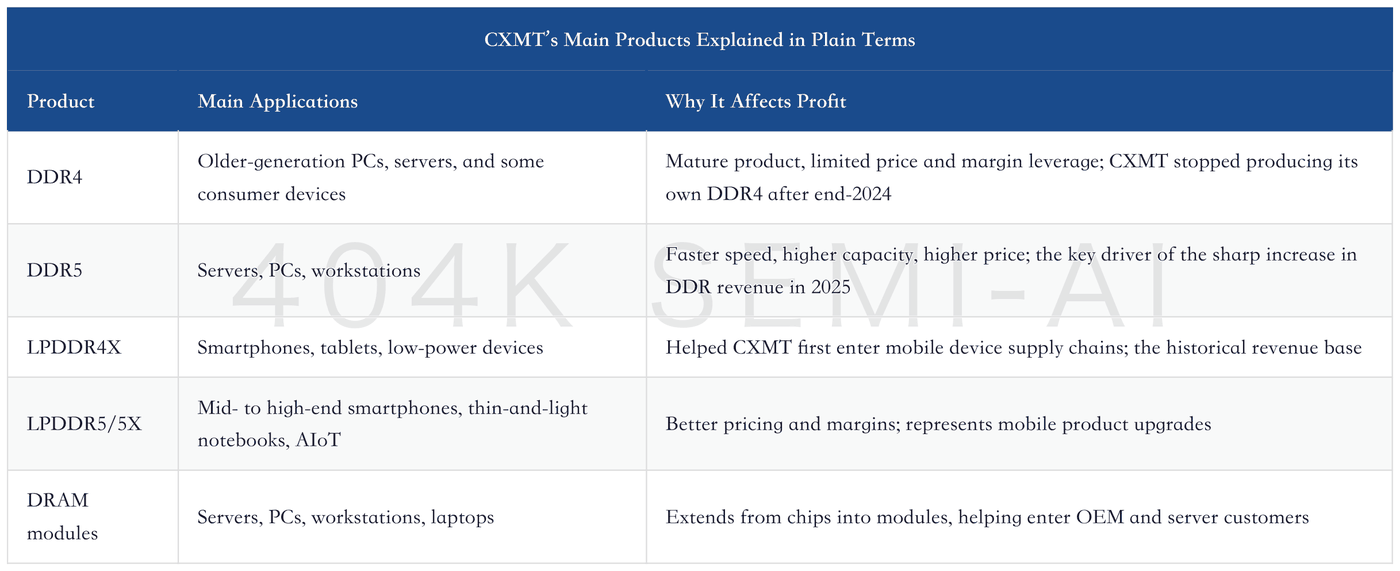
CXMT is no longer at the stage of “whether China can make domestic DRAM.” The prospectus says the company has completed mass production of first- through fourth-generation process technology platforms and has iterated from DDR4 and LPDDR4X to DDR5 and LPDDR5/5X. According to Omdia data, based on DRAM sales in 2025Q4, CXMT’s global market share reached 7.67%. This is not top three globally, but it is already enough to place the company inside the global DRAM supply structure.
China’s No. 1 and the world’s No. 4 DRAM manufacturer.
The investment implication is direct: CXMT is not a niche chip company. It has entered one of the most concentrated, capital-intensive, and price-cyclical categories in semiconductors globally. The top three players, Samsung Electronics, SK hynix, and Micron Technology, have long held more than 90% of global share. CXMT’s opportunity comes from the China market, domestic supply security, DDR5/LPDDR5 product upgrades, and tight global supply-demand conditions. Its pressure comes from the same place: in this industry, scale, technology, capital, and customer qualification cannot fall behind.
AI Drives a Full-Sector Re-Rating in Memory: Who Has the Most Pricing Power Across DRAM, NAND, SSD, and HDD, with Samsung, SK hynix, SanDisk, Western Digital, and Seagate Earnings Cross-Checking One Another
II. The Real Highlight of This Prospectus: The Income Statement Suddenly Looks Intimidating
CXMT was still posting large losses in 2023, narrowed losses in 2024, turned profitable in 2025, and saw profits suddenly expand in 2026Q1. This is not financial magic. The core reason is that the DRAM industry shifted from a downcycle into an upcycle, while CXMT’s own capacity, yield, product mix, and customer onboarding all moved into a better position.
The core financial changes show this most clearly.
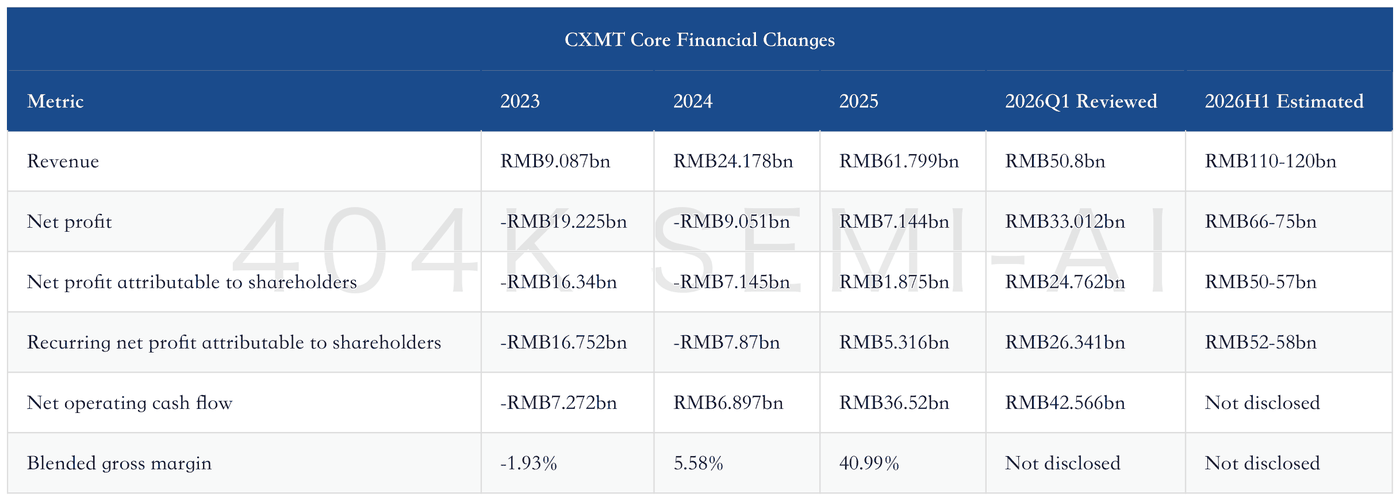
This set of data supports four conclusions.
First, CXMT’s revenue increased from RMB9.087 billion in 2023 to RMB61.799 billion in 2025, nearly 5.8 times in two years. 2026Q1 revenue was RMB50.8 billion, already close to 82% of full-year 2025 revenue. This shows the company is in a phase where both pricing and volume are moving upward.
Second, 2026Q1 net profit attributable to shareholders was RMB24.762 billion, while recurring attributable profit was RMB26.341 billion. Recurring attributable profit being higher than attributable profit indicates that non-recurring items dragged on the attributable metric in the first quarter. For investors, recurring attributable profit better reflects the earning power of the core business.
Third, 1H 2026 net profit attributable to shareholders is expected at RMB50-57 billion, and recurring attributable profit at RMB52-58 billion. This is the most important profit anchor in the prospectus. It proves that CXMT already has very strong earnings leverage under the current DRAM pricing environment.
Fourth, the prospectus does not provide a full-year profit forecast. The company explicitly discloses:
The company has not prepared a profit forecast report.
Full-year 2026 profit will still depend on DRAM prices in the third and fourth quarters, customer pull-ins, capacity ramp-up, and product mix. The first-half profit range is already impressive, but it is not a full-year performance commitment.
III. Where the Profit Comes From: Pricing, DDR5, and Scale Effects Working Together
CXMT’s profit did not appear out of nowhere. In 2023, it was weighed down by three factors: low DRAM prices, capacity still ramping, and heavy fixed-asset depreciation. Starting in 2H25, all three moved in the opposite direction: prices rose, utilization improved, and DDR5 and LPDDR5/5X scaled up.
DRAM is a highly standardized product. When prices rise, profit expands quickly because fixed costs such as production lines, fabs, and equipment depreciation do not increase in proportion to revenue. When prices fall, profit can also be hit quickly because those fixed costs remain.
CXMT’s 2025 gross margin changes already illustrate this logic.
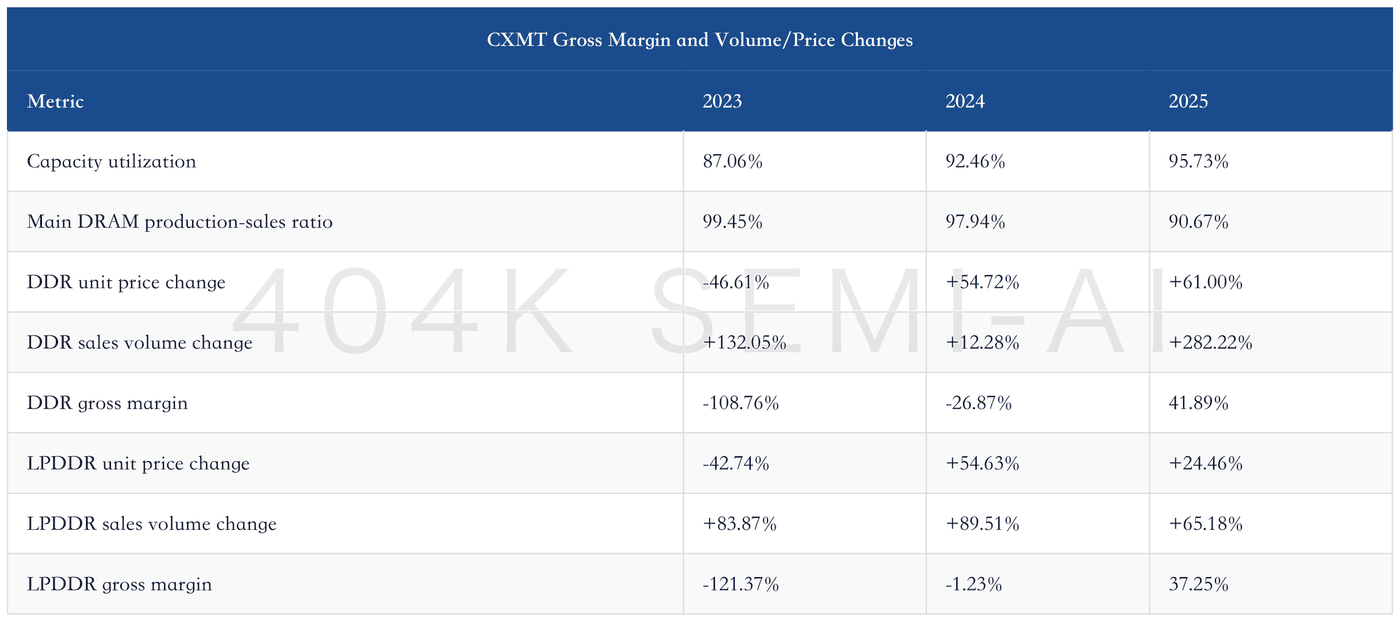
The direction is what matters most in this table.
The DDR series saw a classic “volume and price up together” pattern in 2025. Unit price rose 61.00%, sales volume increased 282.22% on a capacity basis, and gross margin recovered from -26.87% in 2024 to 41.89%. This means DDR5 volume growth brought not only revenue, but also better gross-profit quality.
LPDDR also recovered meaningfully. In 2025, LPDDR unit price rose 24.46%, sales volume increased 65.18%, and gross margin returned to 37.25%. Mobile-device demand remains CXMT’s revenue base, but servers and DDR5 are the areas with the larger change in profit slope.
CXMT’s own explanation is also straightforward: in 2025, high-priced, high-margin DDR5 products ramped quickly, lifting the revenue share of the DDR series. Product mix changes are often more important than total revenue growth. Selling RMB10bn of low-margin mature products and selling RMB10bn of high-margin DDR5 have completely different implications for the income statement.
IV. Revenue Mix Has Changed: From a Mobile Memory Base to Server DDR5 Upside
CXMT used to look more like a mobile DRAM vendor, with LPDDR accounting for the bulk of revenue. In 2025, the DDR series began to rise materially.
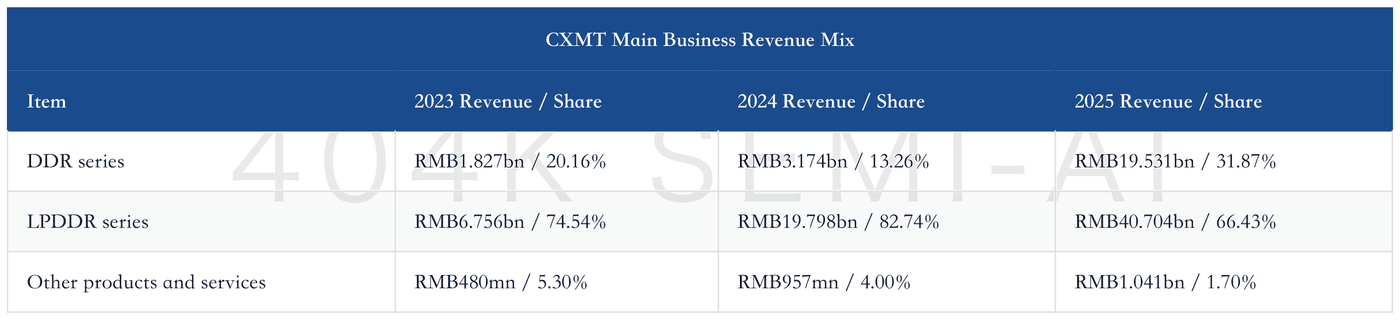
In 2025, DDR-series revenue reached RMB19.531bn, up more than fivefold year over year. This change is critical. After DDR5 entered servers and PCs, CXMT was no longer only exposed to mobile-memory demand. Server DRAM is more sensitive to AI infrastructure, cloud capex, and data-center expansion; once prices rise, its profit elasticity is stronger than that of mobile LPDDR.
The application mix also shows this change.
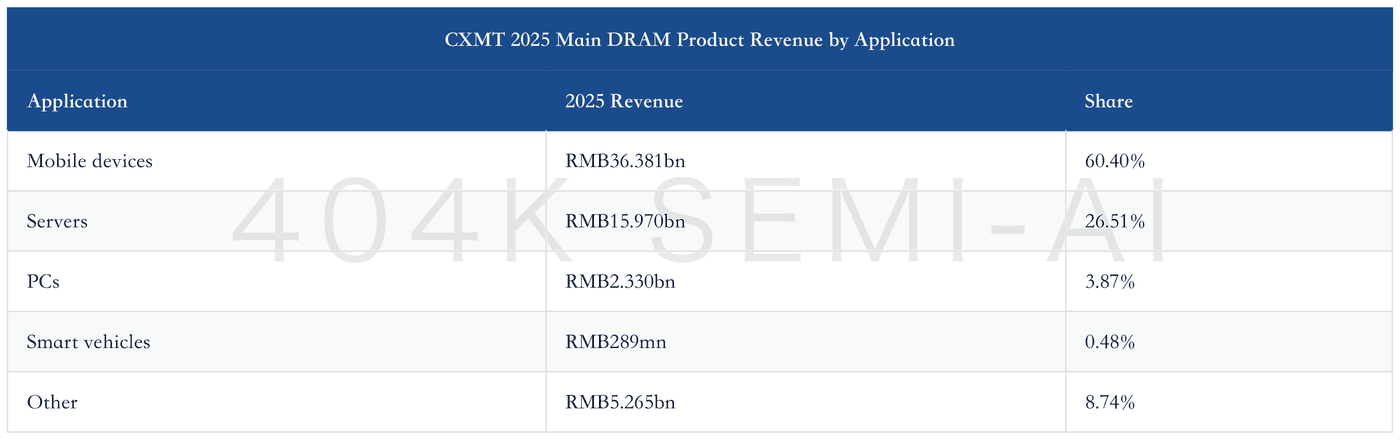
Mobile devices are still the largest revenue source, accounting for 60.40%. This provides CXMT with a stable shipment base. Server revenue has become the second-largest application source, accounting for 26.51%, and its growth rate is far higher than that of mobile devices. The prospectus discloses a CAGR of 536.24% for server-application revenue.
These figures show that CXMT’s second growth line has already emerged. It does not need to immediately capture the global HBM leadership narrative to enter the commodity-memory layer of AI infrastructure through server DDR5, RDIMM, MRDIMM, and higher-capacity modules. Commodity DRAM does not have the same technology premium as HBM, but it is essential for server operation, and price increases will still lift profit.
The Memory Tax Has Arrived: How AI Is Turning HBM, DRAM, and NAND into a Global Macro Bottleneck
V. Why 2023 Losses Were So Large: DRAM Fabs Have Heavy Fixed Costs
CXMT’s 2023 net loss attributable to the parent was RMB16.340bn, and its ex-exceptional net loss attributable to the parent was RMB16.752bn. This loss should not be simplistically interpreted as evidence that the company’s products lack value. During the capacity ramp-up phase, DRAM manufacturers bear very heavy depreciation, R&D;, and inventory write-down pressure.
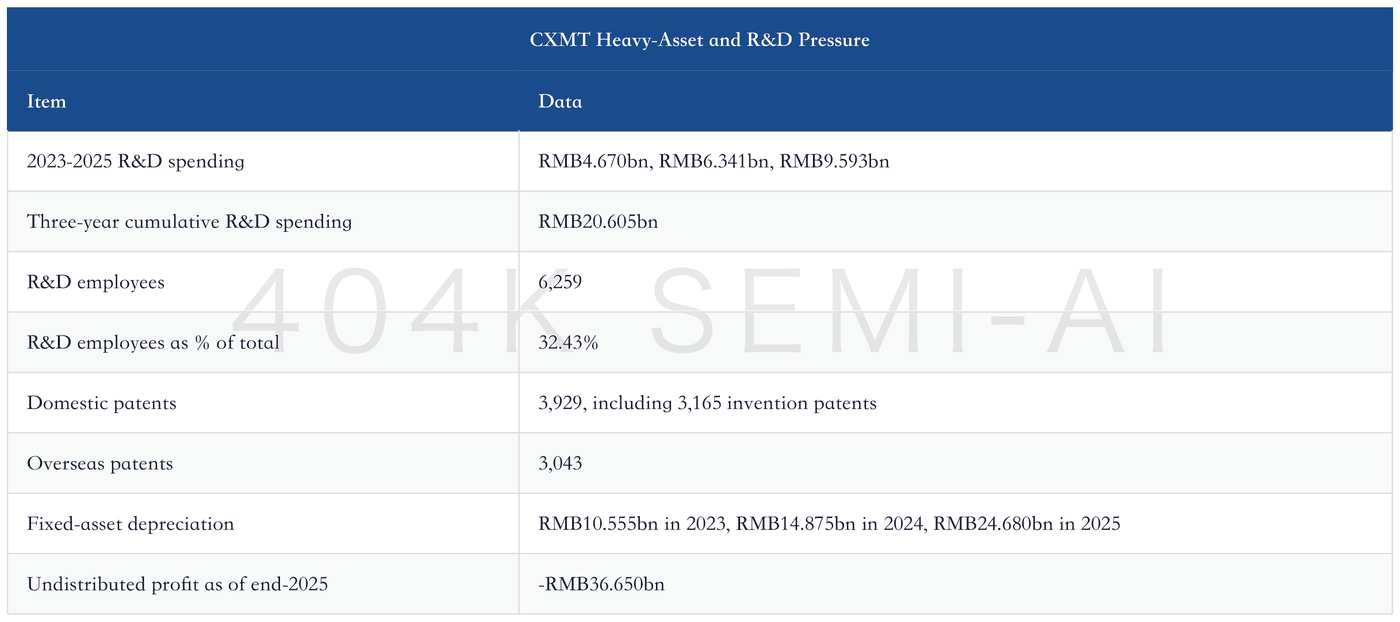
DRAM production lines are expensive. Fabs, equipment, cleanrooms, and process platforms all require upfront investment. Before capacity and yield have fully ramped, depreciation has already started flowing through costs. CXMT’s fixed-asset depreciation was RMB10.555bn in 2023, RMB14.875bn in 2024, and RMB24.680bn in 2025. Depreciation suppresses profit, but it also shows that the company has already invested in heavy-asset production lines.
R&D; is also heavy. From 2023 to 2025, CXMT’s R&D; spending was RMB4.670bn, RMB6.341bn, and RMB9.593bn, respectively, totaling RMB20.605bn over three years. In 2025, it had 6,259 R&D; employees, accounting for 32.43% of total headcount. This is not an asset-light design company, nor a chip brand that relies only on outsourced manufacturing. It follows the DRAM IDM model.
Uncovered losses do not mean the company has poor cash flow. In 2025, CXMT’s net operating cash flow was RMB36.520bn; in 1Q26, net operating cash flow was RMB42.566bn. The historical losses on the income statement mainly came from earlier heavy-asset investment, depreciation, R&D;, and the cyclical downturn. Now that prices are rising, cash flow is already very strong.
What really needs to be tracked is whether depreciation and R&D; can be diluted by a larger revenue base. This already happened in 2025, when gross margin rose from 5.58% in 2024 to 40.99%. Forecasts for 1Q26 and 1H26 show that scale effects are continuing to expand.
VI. Customer Mix: High Concentration, But Not Single-Customer Dependence
ChangXin’s customer concentration is not low. In 2025, its top five customers accounted for 68.08% of core operating revenue, versus 67.30% in 2024 and 74.12% in 2023. For a DRAM manufacturer, this is not surprising. Memory customers are mainly large accounts in smartphones, servers, PCs, modules, and distribution channels, and the industry is inherently concentrated.
The prospectus discloses that the company has entered the customer systems of Alibaba Cloud, ByteDance, Tencent, Lenovo, Xiaomi, Transsion, Honor, OPPO, vivo, and others. These include two types of demand: mobile devices, which require power efficiency, stability, and supply assurance; and servers and cloud vendors, which require capacity, bandwidth, reliability, and long-term supply.
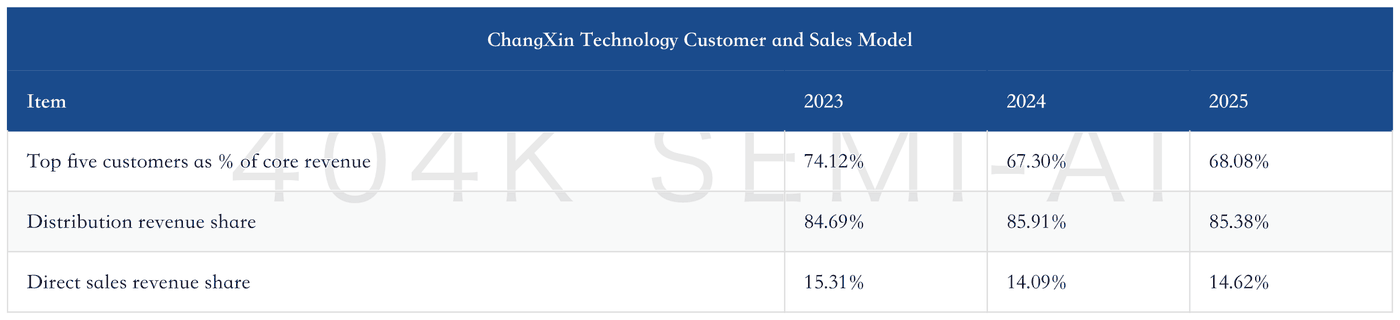
The high distribution share is one point investors should note in this prospectus. In 2025, distribution revenue accounted for 85.38% of core operating revenue. Selling semiconductor products through distributors is common, especially for standardized products such as memory, where distributors can help companies reach downstream customers quickly and accelerate turnover. But a high distribution share also means end demand, inventory, and the actual pace of customer pull-ins need continuous cross-checking.
ChangXin has not currently disclosed any single customer accounting for more than 50% of revenue, and says it does not have severe dependence on a small number of customers. Investors should monitor whether the share of direct sales customers can gradually rise, whether server customers and leading cloud vendors can continue to be introduced, and whether AI server-related revenue can move from “still relatively low” to a truly material profit source.
VII. RMB34.5 Billion Fundraising Projects: The Money Is Mainly for Upgrades, Not Storytelling
This IPO involves total project investment of RMB34.5 billion, with RMB29.5 billion planned to be raised. The project directions are highly focused, all around DRAM technology upgrades, production-line renovation, and forward-looking R&D.;
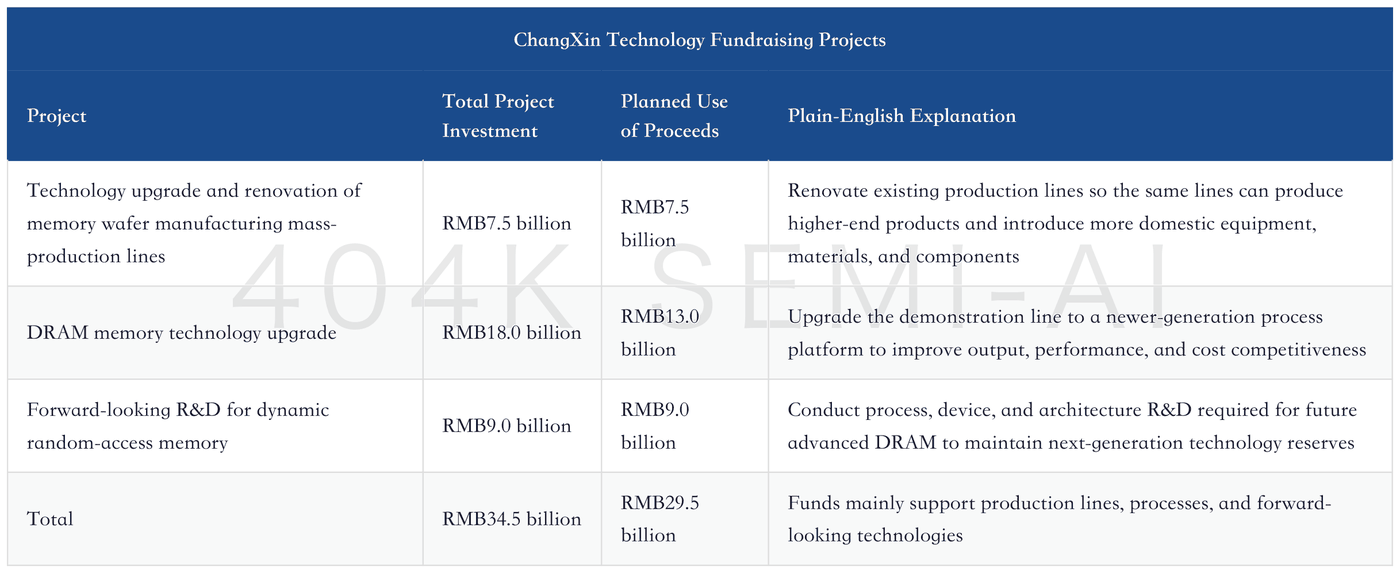
These three fundraising projects correspond to ChangXin’s next three core questions.
First, can unit costs continue to decline? DRAM is a scale- and process-driven industry. If more qualified chips can be produced from the same wafer, costs fall. If ChangXin can improve wafer output, yield, and equipment efficiency through process upgrades, gross margin will not depend only on price increases.
Second, can high-end products continue to scale? DDR5 and LPDDR5/5X have already shown that product-mix upgrades can improve gross margin. The next question is whether server DDR5, high-capacity modules, low-power high-end mobile memory, and future products can continue to be introduced at customers.
Third, can supply-chain security become stronger? The prospectus mentions the introduction of domestic and new types of equipment, materials, and components. For domestic DRAM, the ecosystem for equipment, materials, EDA, components, and packaging and testing directly determines capacity expansion and long-term stable supply.
This money will not immediately turn into profit. The fundraising projects will bring more depreciation, R&D;, and upfront expenses. The real investment judgment is whether they can deliver higher output, lower costs, a higher share of newer-generation products, and stronger customer certification.
VIII. Offering Arrangement: Pricing Is Not Set Yet; For Now, Focus on the Mechanism
ChangXin’s offering combines strategic placement, offline price inquiry, and online subscription. The issuance ratio is 10.00%, with an over-allotment option also arranged. Share capital, the greenshoe, and the timetable will determine the subsequent valuation basis.
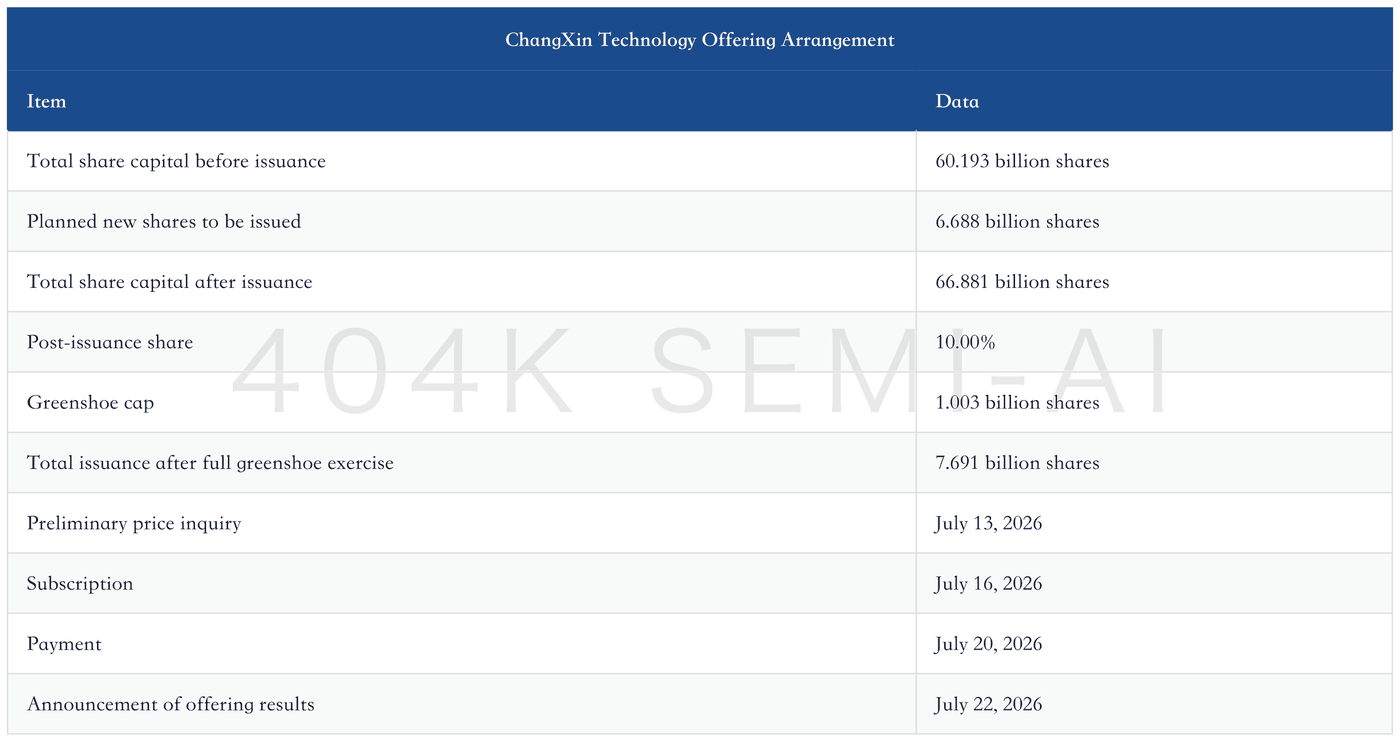
The most important variable has not yet been released: the issue price. Without the issue price, there is no definitive market capitalization, issuance P/E, or issuance P/B. EPS in the prospectus is also temporarily calculated by dividing the lower of 2025 net profit attributable to the parent before and after non-recurring items by pre-issuance total share capital. Post-issuance valuation must wait until the price is determined.
Before the issue price is released, valuation judgment should first distinguish between 2025 profit, annualized 1H26 profit, P/B, peer-cycle positioning, and A-share scarcity.
