
In-Depth Analysis of the Fed’s July Decision: No Rate Hike Does Not Mean a Dovish Pivot; Policy Is Shifting from “Guiding the Market” to “Reading the Market”
目录
TL;DR
I. The Same Rate Decision, but a Completely Different Internal Structure
II. The June Dot Plot Had Already Foreshadowed the July Split
III. The Real New Policy Tool Is Reducing the Fed’s Own Voice
IV. Reflexivity Is the Greatest Risk in This Framework
V. Tough Rhetoric on the 2% Target Is an Effort to Restore Credibility, Not a Substitute for Action
VI. AI Capital Expenditure Is Reshaping Both Supply and Inflation
VII. The Balance Sheet Is the Next Hidden Theme
VIII. Three Future Scenarios and Their Market Implications
Conclusion: The Policy Rate Has Paused, Not the Tightening Process
Full Chinese Translation of the English Press Conference Content
Opening Statement
Q&A 1: What Signal Is the Market Sending Without Forward Guidance?
Q&A 2: How to Interpret the 3 Dissenting Votes for a Rate Hike
Q&A 3: How Much Did the Softer June CPI Affect This Decision?
Q&A 4: Why Is the Current Interest Rate Not Higher?
Q&A 5: Are Interest Rates the Primary Tool for Reducing Inflation?
Q&A 6: Was Today’s Decision a “Pause,” and What Will Be Said at Jackson Hole?
Q&A 7: Does Monetary Policy Reduce Inflation by Damaging Employment?
Q&A 8: Is the Disagreement About Forecasts, Risks, or the Timing of Action?
Q&A 9: Does Reducing Guidance Mean Deliberately Creating Surprises?
Q&A 10: Which Specific Inflation Measure Does the 2% Target Refer To?
Q&A 11: If Inflation Remains High, What Exactly Is the Federal Reserve Still Waiting For?
Q&A 12: Could External Working Groups Be Influenced by Industry Interests?
Q&A 13: Why Has “Zero Tolerance for High Inflation” Not Yet Translated into a Rate Increase?
Q&A 14: Will Market Pricing for the September Meeting Constrain the Federal Reserve?
Q&A 15: With Rates Unchanged and No Guidance, Why Hold a Press Conference?
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
On July 29, the Federal Reserve maintained the 3.5%—3.75% target range, but the vote fractured from 12–0 in June to 9–3, with 3 dissenters calling for a 25-basis-point rate hike. The real change lies not in the policy rate but in the policy mechanism: the Fed is reducing forward guidance, allowing market rates to tighten first, and then reading price signals unfiltered by its own communications.
TL;DR
An unchanged policy rate does not mean an unchanged policy stance. The vote was still 12–0 in June but shifted to 9–3 in July, formally revealing a public rate-hike camp.
July brought no new SEP or dot plot. The latest dot plot remains the one from June: of the 18 participants, 9 projected the year-end 2026 rate above the current midpoint, 8 projected no change, and only 1 projected a lower rate.
The Chair deliberately reduced forward guidance, arguing that the sharp rise in nominal and real Treasury yields over the past 42 days showed that markets were beginning to “watch the data, not the Fed.” In effect, this allows the market to deliver part of the tightening first.
The advantage of this mechanism is that it reduces central-bank distortion of price signals; its weakness is the risk of a reflexive loop: the market guesses what the Fed will do, while the Fed reads the market, potentially making the policy threshold even less clear.
AI-related capital expenditure may raise long-term supply through productivity gains, but it may also push up memory, logic-chip, and infrastructure prices in the near term. It has moved from an industry variable into monetary-policy assessment.
The forward baseline is not rapid rate cuts, but the maintenance of restrictive rates while monitoring developments. If underlying inflation rises again or price pressures broaden, a 25-basis-point rate hike will become a realistic option.
I. The Same Rate Decision, but a Completely Different Internal Structure
Both the June and July meetings maintained the target range at 3.5%—3.75%, but the voting structure shifted from 12–0 to 9–3. The 3 dissenters did not call for a rate cut; they called for a 25-basis-point rate hike. This is critical: the Committee’s disagreement is not about “when to begin easing,” but about “whether further tightening is already necessary.”
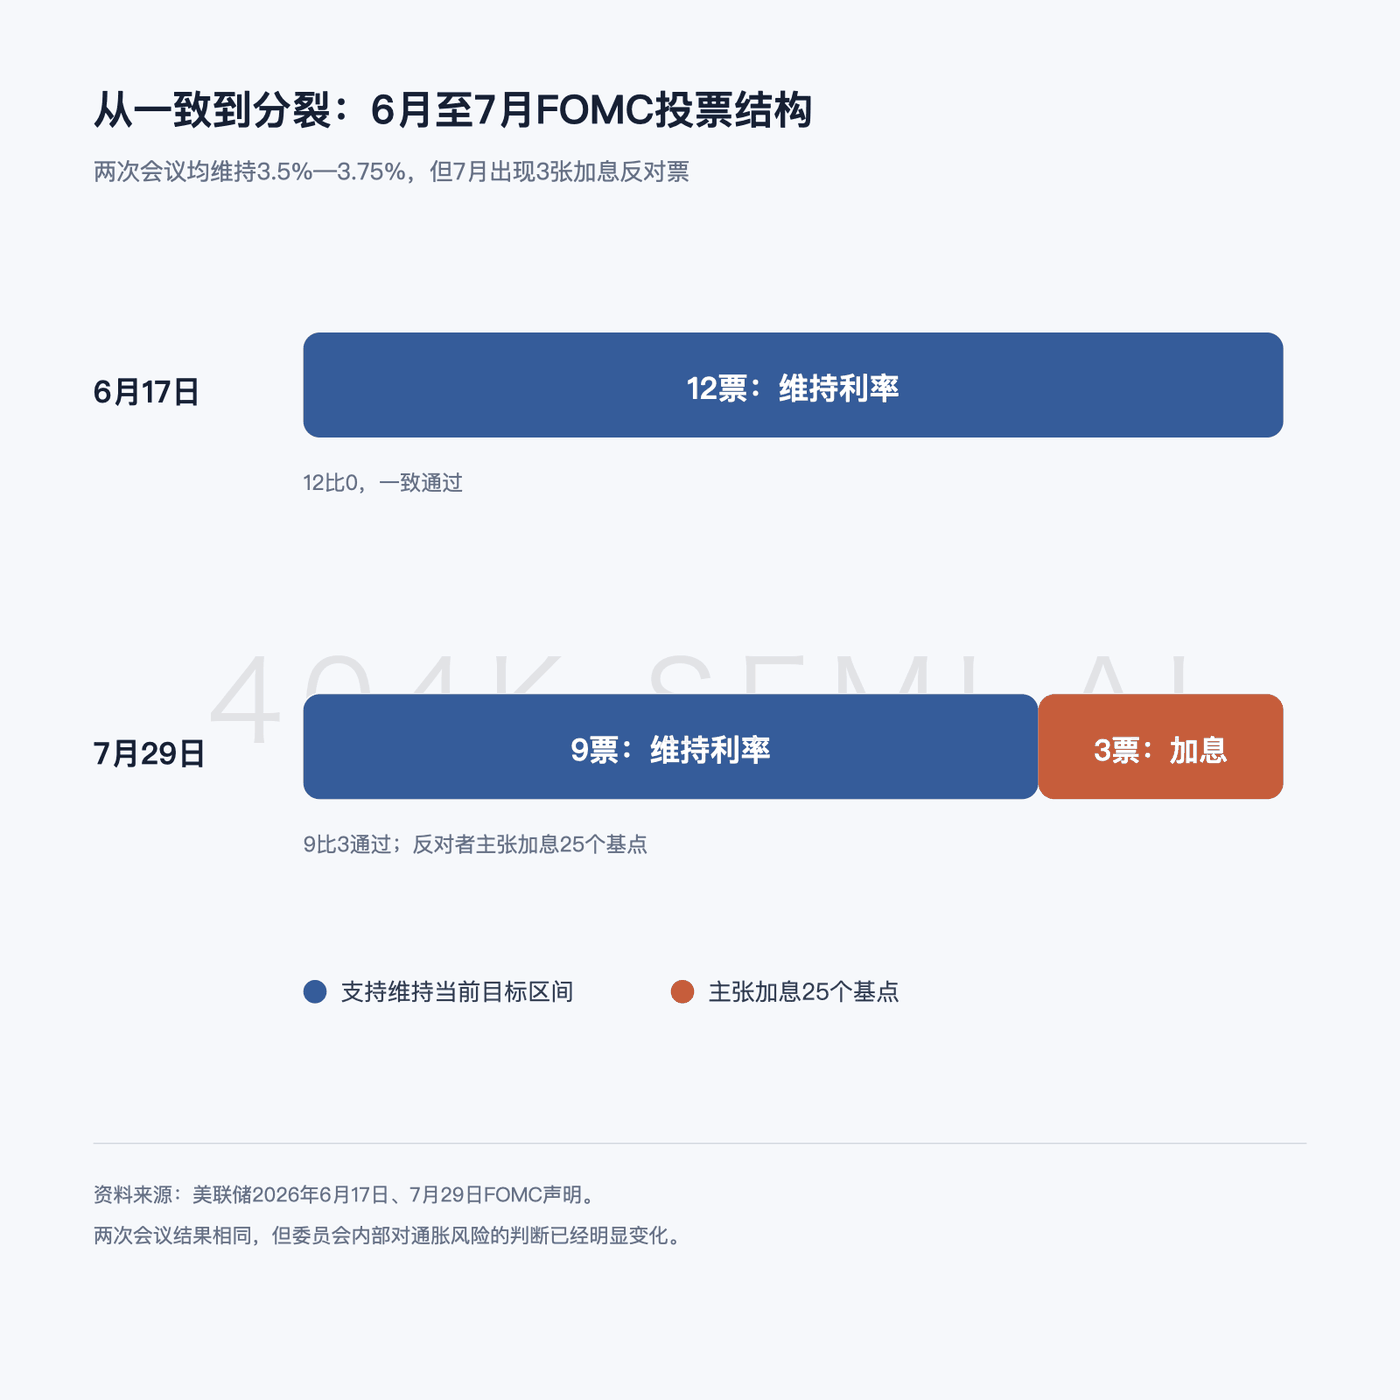
The June meeting marked the new Chair’s debut. At the time, the Committee shortened its statement, removed forward guidance, and used a unanimous vote to provide institutional cover for the new framework. By July, the statement’s basic descriptions of growth, employment, and inflation were almost unchanged, but unanimity had disappeared. This indicates that the disagreement stems from different policy weights assigned to the same set of facts: the majority prefers to first observe the transmission of supply shocks, market rates, and the real economy, while the minority worries that inflation remaining above 2% for an extended period has already damaged credibility and that further delay would raise the cost of future tightening.
The Chair described the meeting’s discussion as a necessary “family argument,” emphasizing that disagreement did not mean the Committee had lost its shared objective. This has two implications: first, the 2% target remains the consensus; second, there is no longer agreement on the path, tools, or timing for reaching 2%. For markets, the latter matters more than verbal unity because it means the next rate hike is no longer merely an abstract tail scenario in the dot plot.
II. The June Dot Plot Had Already Foreshadowed the July Split
The July meeting did not publish a new Summary of Economic Projections (SEP), and therefore provided no new dot plot. The latest available projections remain those from June 17. The June SEP raised the median 2026 PCE inflation projection from 2.7% in March to 3.6%, and the core PCE projection from 2.7% to 3.3%. Over the same period, projected real GDP growth was lowered from 2.4% to 2.2%, while the unemployment-rate projection was lowered from 4.4% to 4.3%. This is a classic combination of “higher inflation, slightly weaker growth, and still-stable employment,” leaving the Fed room to continue prioritizing inflation control.
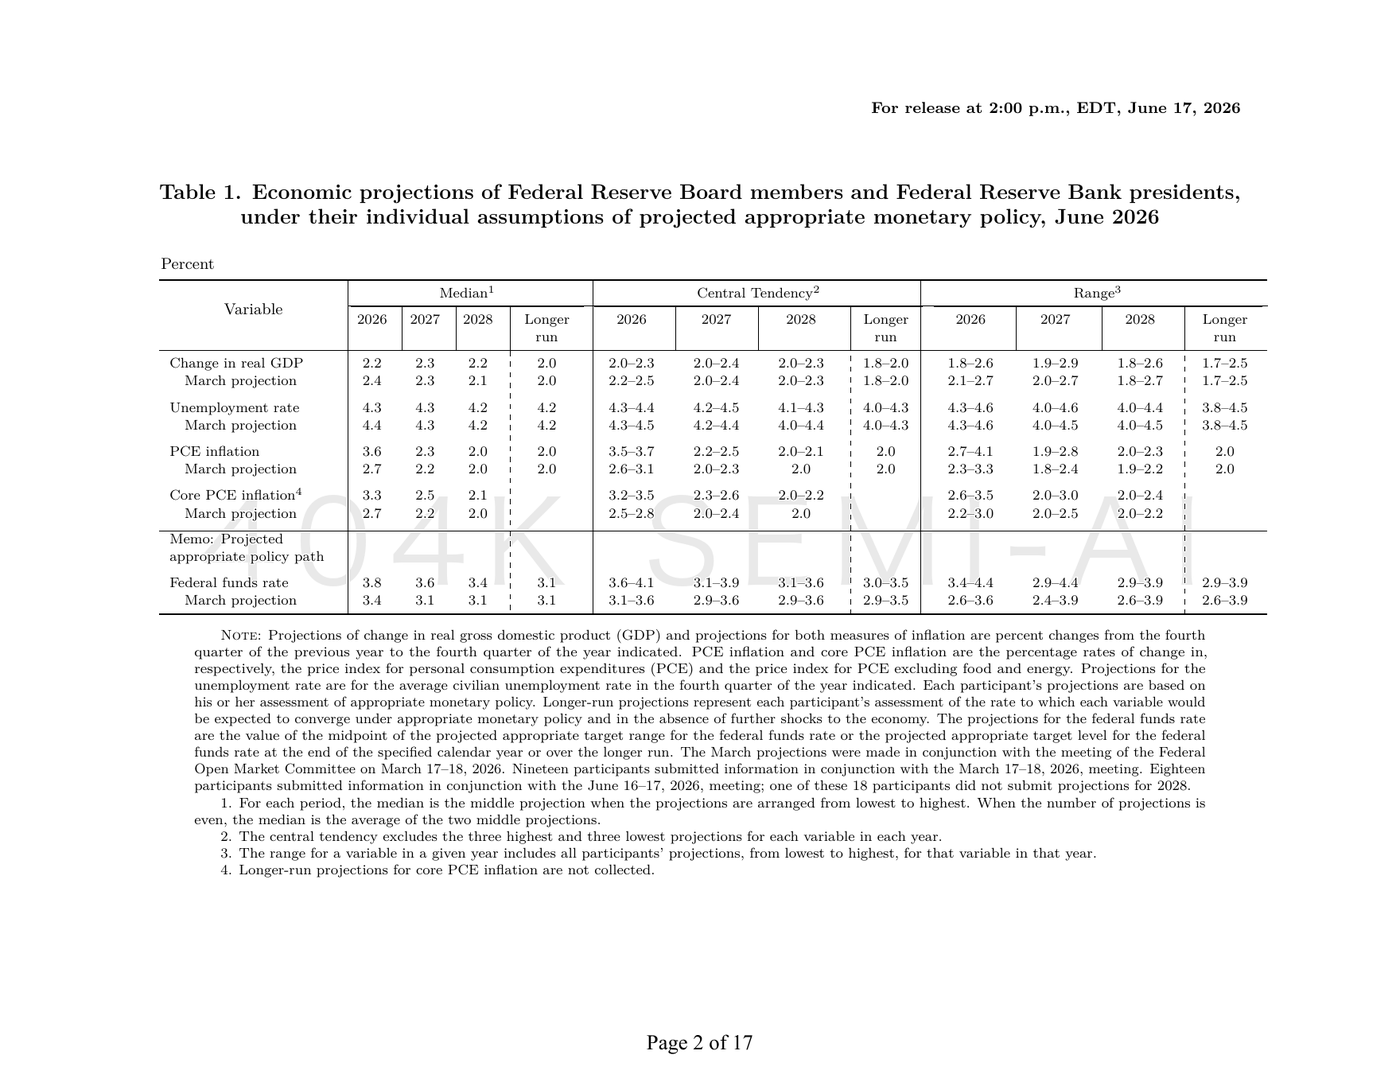
The distribution of policy-rate dots warrants closer attention. Of the 18 participants, 1 projected a year-end 2026 midpoint of 3.375%, 8 projected 3.625%, 3 projected 3.875%, 5 projected 4.125%, and 1 projected 4.375%. In other words, 1 favored a rate cut, 8 favored holding rates unchanged, and 9 favored rate hikes. The 3.8% median shown in the table is the 3.75% average of the two middle dots in the even-numbered sample—3.625% and 3.875%—displayed to one decimal place; it is not a directly actionable policy setting.
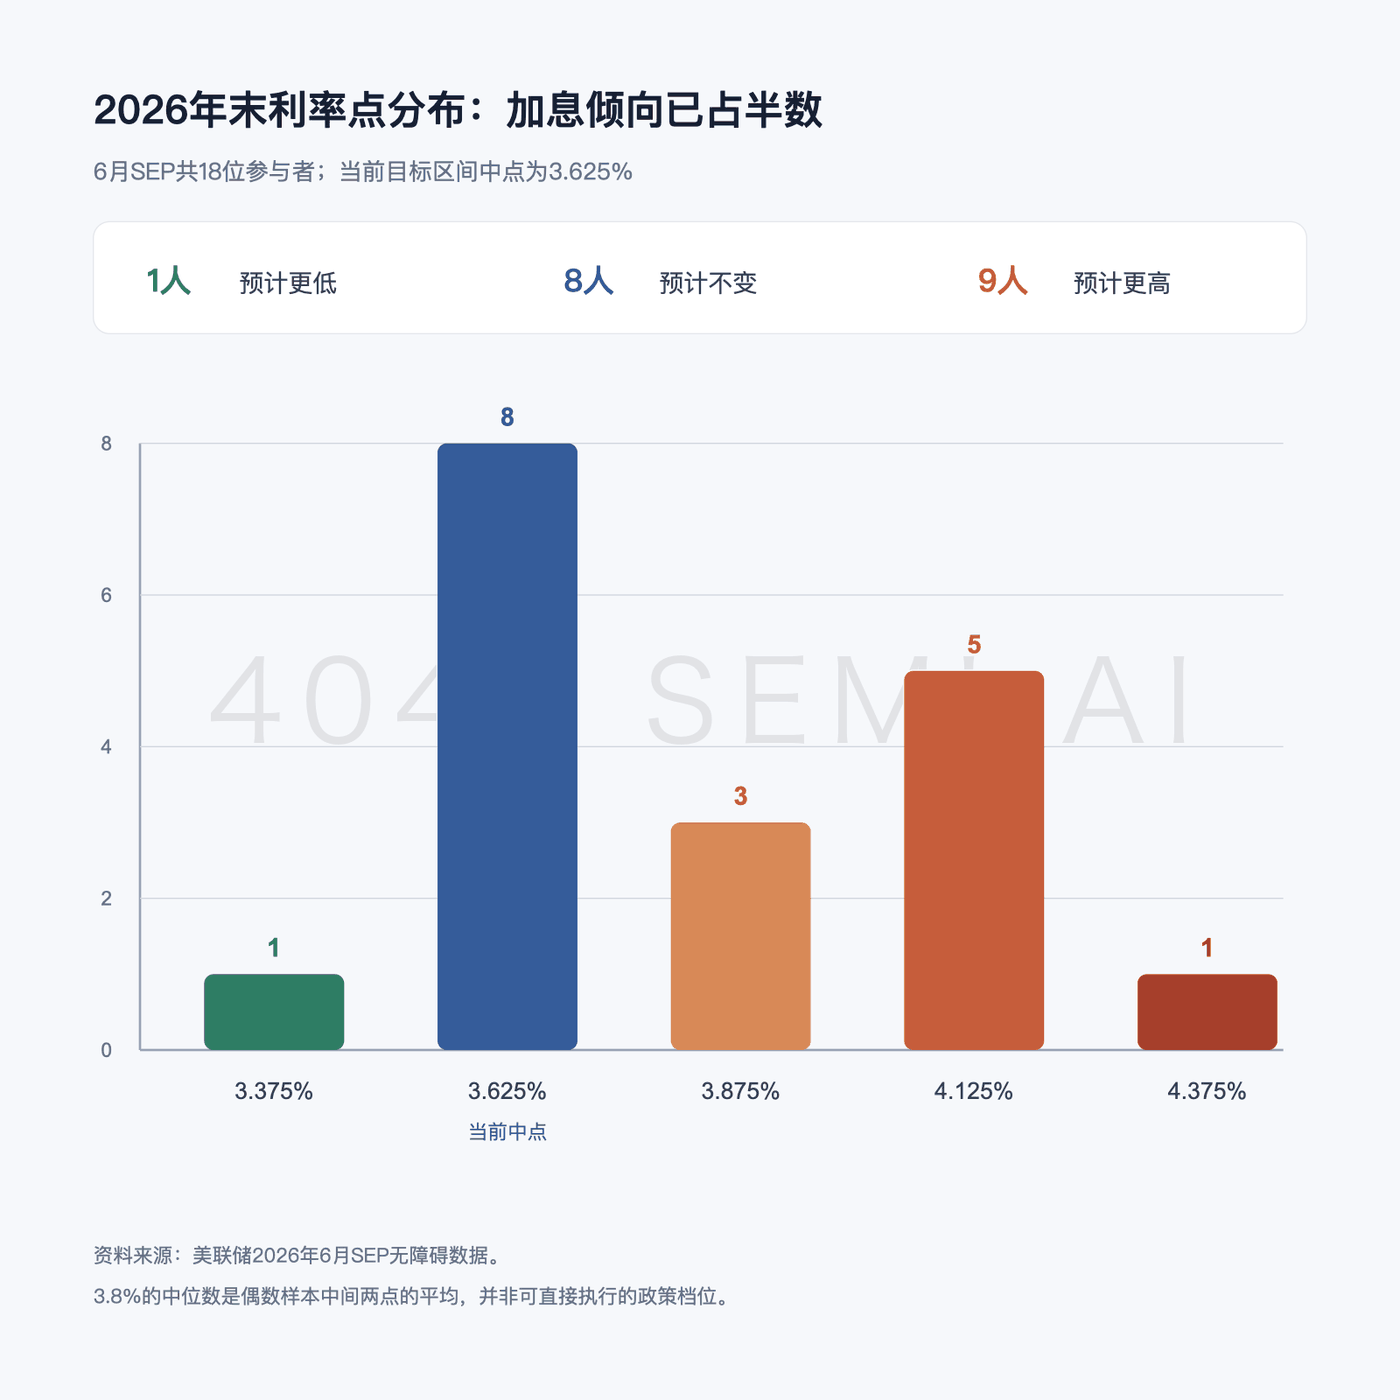
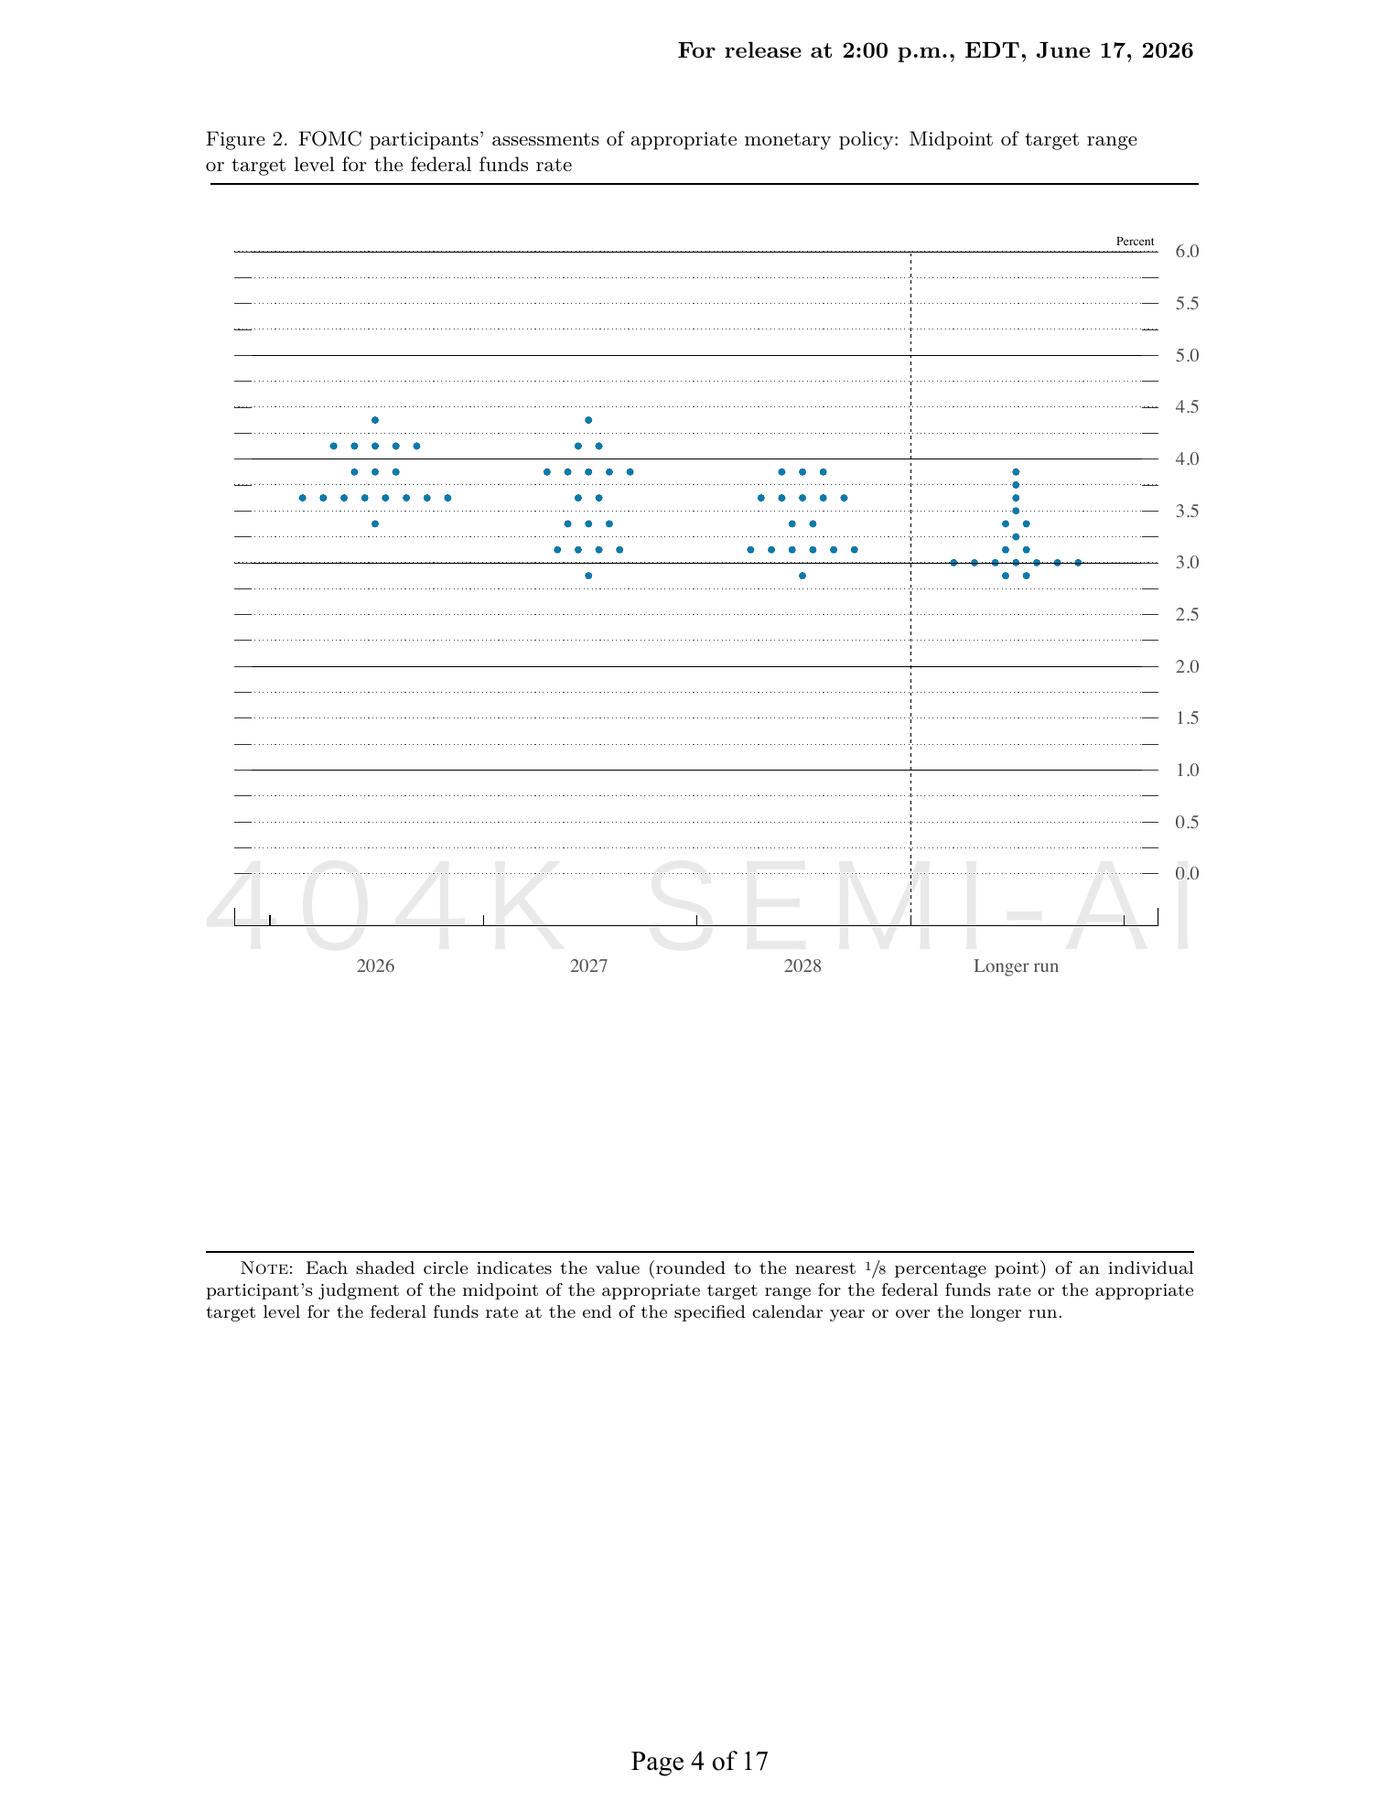
It is important to emphasize that dot-plot participants and voting members at a given meeting are not the same group, so the 3 dissenting votes in July cannot be mechanically mapped to 3 dots in the chart. The direction, however, is consistent: in June, half of the participants already believed at least one rate hike would be needed before year-end; in July, 3 voters converted that inclination into formal dissents.
III. The Real New Policy Tool Is Reducing the Fed’s Own Voice
The most informative part of this press conference was not the phrase “data dependent,” but the Chair’s redefinition of the market-pricing mechanism. He noted that both nominal and real yields across the Treasury curve had risen significantly over the past 42 days, with some moves ranking around the top 10% of intermeeting changes over the past 20 years. The policy rate did not move, but market rates already had.
His explanation was that after forward guidance was withdrawn in June, markets reduced their mechanical reliance on Fed speeches and the dot plot and began responding more directly to inflation, growth, and other real-time information. In the press conference’s vivid formulation, markets began “watching the ball, not the referee.” For the Fed, these prices both affect the real economy and serve as a source of policy information. Allowing markets to raise yields on their own may therefore have already delivered part of the tightening that otherwise would have required a rate hike.
This is also an implicit reason why the majority chose to hold rates steady in July: if real rates and financing costs have already risen, the Fed can first assess their transmission without immediately layering on a policy-rate adjustment. In other words, this is not “doing nothing”; it is delegating part of the action to the market.
IV. Reflexivity Is the Greatest Risk in This Framework
Reducing forward guidance has genuine value. During crises, central banks need to stabilize expectations through commitments; during normal periods, excessive guidance encourages markets to focus solely on interpreting central-bank language, so prices no longer reflect economic fundamentals. The Chair aims to remove this “central-bank filter,” a direction that has merit.
But the difficulty is also clear. Market prices are not pure signals of fundamentals; they inherently incorporate expectations about the Fed’s reaction function. If markets believe inflation will force the Fed to raise rates, yields rise; the Fed may then view the higher yields as tightening that has already occurred and therefore temporarily refrain from hiking; markets may subsequently mark down rate-hike expectations, easing financial conditions again. Conversely, if markets tighten excessively, the Fed may also be misled by a price signal that contains its own reflection.
The Chair stressed that markets are merely a “useful but not determinative” source of information and will not constrain decision-making. This qualification is crucial, but it does not fully resolve the predictability problem. Previously, markets debated whether a particular data release would change the dot plot; going forward, they will increasingly need to guess the extent to which the Fed will treat market rates themselves as part of policy transmission. The result may not be less informational noise, but higher term premiums and volatility.
V. Tough Rhetoric on the 2% Target Is an Effort to Restore Credibility, Not a Substitute for Action
The Chair repeatedly denied the existence of a “soft target” or “implicit target” above 2% and emphasized that the Committee recognizes only 2%. This is consistent with the June meeting, but the tone was stronger in July because the official report showed that headline PCE rose 4.1% over the 12 months through May, while core PCE rose 3.4%, and the June SEP still projected full-year 2026 PCE inflation of 3.6%.
This rhetoric is first and foremost an exercise in expectations management. After inflation remained above target for more than 5 years, households and businesses may infer a revealed preference that “the Fed says 2% but in practice tolerates something higher.” The Chair is attempting to sever that inference so that high inflation does not become self-reinforcing through wages, pricing, and long-term expectations.
But the press conference also acknowledged that credibility ultimately depends on outcomes, not language. A single moderate decline in prices cannot resolve a deviation lasting more than 5 years, and the Committee has no “magic wand.” This is precisely the tension in the July decision: the verbal commitment is exceptionally strong, yet the actual rate decision is to wait. If underlying inflation rises again over the next two or three months and the Committee still does not act, its “zero tolerance” rhetoric will instead become the benchmark by which markets test its credibility.
VI. AI Capital Expenditure Is Reshaping Both Supply and Inflation
The Chair described high-tech capital expenditure as one of the most striking features of the current economy and said that 4-quarter growth in AI-related high-tech equipment and software was approaching 20%. This has supported U.S. manufacturing output and future productivity, and also helps explain why the economy has remained resilient despite high interest rates and external shocks.
But AI investment is not a one-way disinflationary story. In the near term, demand for data centers, memory, logic chips, electricity, and related infrastructure will push up specific prices. The press conference directly raised the question: are price increases in memory and logic chips merely the result of localized supply-demand tightness, or are they part of a broader inflationary process? This means the Federal Reserve will not simply view AI capital expenditure as a positive that raises potential growth; it will also monitor its effects on the diffusion of price pressures and on financial conditions.
For asset pricing, this creates a “double-edged sword”: higher productivity can lift long-term growth and corporate earnings, but stronger investment demand may also keep real interest rates elevated and raise discount rates for long-duration assets. Improving fundamentals and valuation pressure may coexist across the AI value chain.
VII. The Balance Sheet Is the Next Hidden Theme
The decision maintained the ample-reserves framework. The implementation note kept the interest rate on reserve balances at 3.65%, the standing overnight repo rate at 3.75%, and the overnight reverse repo rate at 3.5%; it also allowed purchases of short-term Treasury securities as needed to maintain ample reserves and provided for reinvesting principal payments from agency securities into Treasury bills.
These arrangements do not amount to restarting large-scale quantitative easing, but they show that the policy rate is not the only tool affecting financial conditions. In his opening remarks, the Chair directly asked: if interest rates are the primary tool, how much accommodation does the balance sheet still provide? This continues the thinking behind the balance-sheet working group established in June and also suggests that future framework adjustments may involve the reserve regime, asset composition, and maturity structure—not merely whether to raise or cut rates by 25 basis points.
VIII. Three Future Scenarios and Their Market Implications
Inflation and employment trajectories determine three Federal Reserve policy scenarios
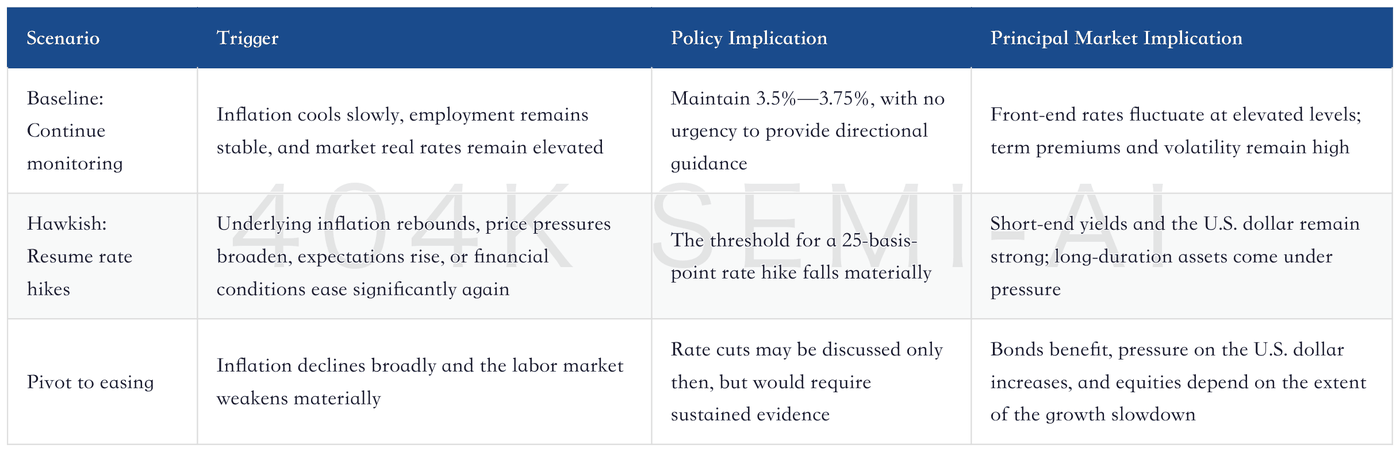
What matters most now is not any single month’s data, but 5 sets of sustained signals: core PCE and the breadth of its components; market real rates and credit conditions; short- and long-term inflation expectations; whether employment and wages cool in tandem; and whether the price pressures generated by AI investment can translate into incremental productivity.
