
目录
TL;DR
How Far Are Current Rules from a “Comprehensive Ban”?
What Could Actually Break Is “Qualified Supply”
Why Coherent and Lumentum Cannot Immediately Fill the Gap
The Global Landscape Will Fragment, Rather Than Simply Become “US Vendors Take All”
The Real Cost to US Data Centers Is Delivery Risk
Impact on China’s Supply Chain Will Hit Orders First, Then Upstream Suppliers
Which Signals Would Escalate “Localized Order Switching” into a “Supply Discontinuity”
Key References
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The real risk for the US during the transition from 800G to 1.6T is that it may be unable to find sufficient qualified replacement capacity within a short period.
TL;DR
As of July 2026, the US has not yet implemented rules “comprehensively banning Chinese optical modules.” The FCC did seek comment in 2025 on broad restrictions involving optical transceivers, but its final order in July 2026 addressed only data-carrying hardware components produced by entities on the FCC Covered List and explicitly did not yet extend the rules to all suppliers controlled by foreign adversaries.
If the policy escalates from restrictions on named entities to broad restrictions on Chinese-controlled optical-module vendors, US cloud service providers would first face a qualified-supply shortage; global physical capacity would not disappear. Innolight and Eoptolink are already deeply embedded in the supply chains of leading US cloud customers. Replacement suppliers would need not only factories, but also renewed certification for interoperability, firmware, thermal performance, reliability, and complete systems.
Coherent and Lumentum would benefit, but could not immediately fill the gap. Both companies have indium phosphide, laser, and some module capabilities, and Nvidia has committed $2 billion to each to support capacity expansion. However, Coherent’s additional indium phosphide output will come online across 2026—2027, while Lumentum’s US 6-inch indium phosphide fab is not expected to ramp until mid-2028.
The supply chain is more likely to split than permanently break. The US will accelerate the formation of a “domestic or trusted-source” supply chain for optical sources, modules, and systems. Chinese vendors will redirect more capacity toward China and other markets while advancing the localization of digital signal processors, indium phosphide lasers, continuous-wave lasers, silicon photonics, and testing.
The main cost for US data centers would be cluster delays, not the incremental price of an individual module. The reference architecture for a 127-node DGX B200 SuperPOD lists more than 2,000 400G high-speed transceivers for the compute network alone. If any single module category has not yet been certified, switches, GPUs, and racks may be unable to form an operational cluster on schedule.
Where the final rules draw the line is the most important variable to monitor: named entities versus Chinese-controlled suppliers, manufacturing location versus ownership, new models versus all imports, finished modules versus upstream components, and whether a sufficiently long transition period is provided. These 5 factors will determine whether the impact is limited to localized order reallocation or becomes a multi-quarter delivery disruption.
How Far Are Current Rules from a “Comprehensive Ban”?
Market commentary surrounding Chinese optical modules has conflated 3 distinct levels of facts.
The first is the notice of proposed rulemaking issued by the FCC in October 2025. The document did ask whether restrictions should apply to equipment containing semiconductors, positioning and timing modules, and “optical transceivers,” if those components were produced by entities owned, controlled, or subject to the jurisdiction of foreign adversaries. This confirms that optical transceivers were included in policy discussions, but does not mean the proposal had already become an effective rule. FCC’s 2025 notice of proposed rulemaking
The second is the final order adopted by the FCC in July 2026. The new rule closed a component loophole: if equipment contains data-carrying hardware components produced by entities on the FCC Covered List, that equipment may be ineligible for authorization. However, the FCC also explicitly stated that it was not adopting at that time a broad prohibition covering components produced by all entities controlled by foreign adversaries, while reserving the right to take further action. More importantly, when discussing market costs, the document noted that major optical-transceiver vendors including Coherent and Innolight were not on the FCC Covered List. FCC’s 2026 final order
The third is Innolight’s addition to the US Department of Defense Section 1260H list in June 2026. This development will increase compliance sensitivity among US customers and may signal future policy escalation, but the Department of Defense list, the FCC Covered List, and a civilian import ban do not have the same legal consequences. The evidence does not support directly equating “designation under Section 1260H” with “the US has already banned imports of Innolight optical modules.” US Department of Defense’s 2026 Section 1260H list
Reuters’ actual July 22, 2026 report also needs to be read in its original context. It stated that the FCC had barred equipment containing critical data-carrying hardware produced by Covered List entities such as Huawei from entering the US market; it did not announce a ban on all Chinese optical transceivers. Recasting it as “the US is about to ban new Chinese data-center optical modules” appears to combine the 2025 proposal, the 2026 component rule, and Innolight’s Section 1260H designation. Mirror of Reuters report
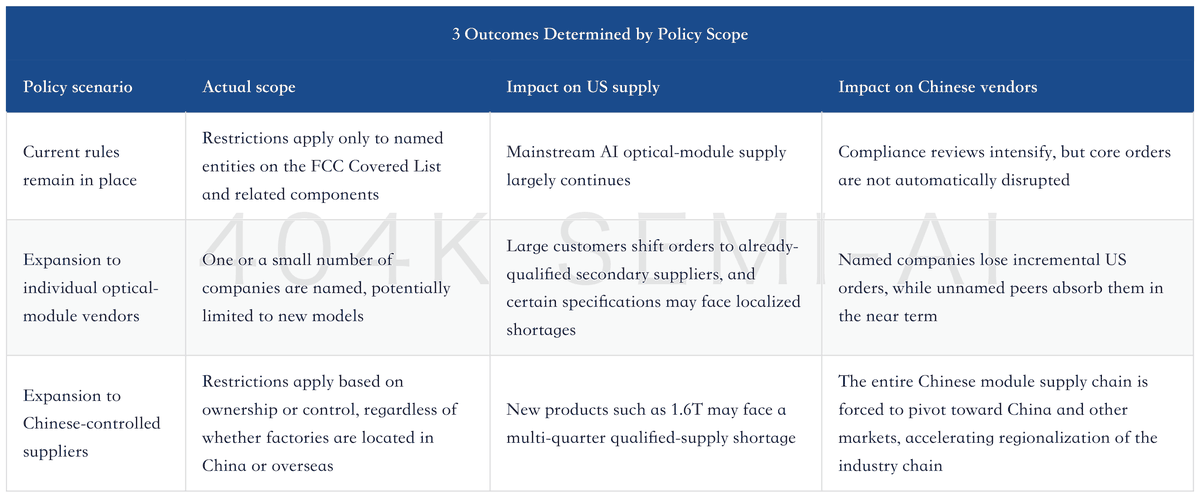
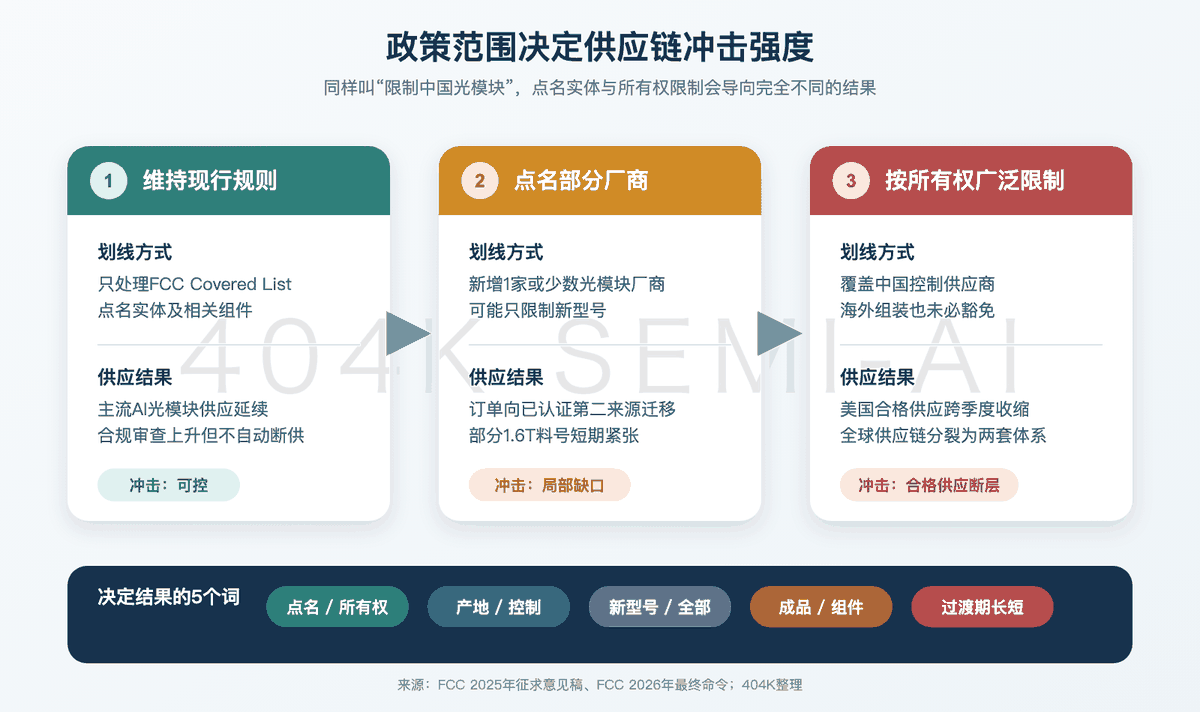
Therefore, the most rigorous characterization at this stage is that comprehensive restrictions remain a policy-escalation scenario, not an event that has already occurred. However, this is no longer a tail risk that can be ignored, because regulatory discussions, entity listings, and US domestic capacity expansion are accumulating in the same direction.
What Could Actually Break Is “Qualified Supply”
If the US broadly excludes Chinese optical modules, the market may initially perform a simple static calculation: transfer Innolight’s and Eoptolink’s market shares to Coherent, Lumentum, Fabrinet, Molex, or other vendors. Global capacity has not disappeared; the orders have merely changed hands. This calculation overlooks the most important asset in AI optical interconnects—customer qualification.
LightCounting data show that sales of optical transceivers and related products totaled approximately $23.8 billion in 2025, including nearly $18 billion of Ethernet optical transceivers. Innolight generated approximately $5.3 billion in 2025 revenue, ranking first in the industry; Eoptolink generated approximately $3.5 billion, rising to second place for the first time. These positions reflect the companies’ long-term service to the largest US cloud providers and their established product, delivery, and qualification track records across 400G, 800G, and 1.6T. LightCounting’s May 2026 vendor landscape
Before high-speed modules enter cloud customers’ data centers, they must clear at least 5 hurdles: electro-optical performance must meet specifications; digital signal processors, lasers, and driver chips must operate together reliably; firmware must be compatible with switches and network interface cards; reliability under high temperatures, vibration, and long-duration operation must pass validation; and mass-produced units must maintain consistent yields. Switching suppliers requires revalidating a substantial portion of these areas. Moving to an entirely new supply system also requires rebuilding supply traceability, quality accountability, and spare-parts systems.
This is the distinction between “having capacity” and “having qualified capacity.” Production lines for conventional modules can be expanded rapidly at the factory level, but high-speed 1.6T modules are jointly constrained by lasers, indium phosphide epitaxy, silicon-photonics coupling, packaging, testing, and yields. LightCounting estimated in April 2026 that demand for indium phosphide electro-absorption modulated lasers and laser chips still exceeded supply by approximately 30%. If the largest-scale suppliers are suddenly excluded from an already tight system, replacement vendors may win the orders but still cannot immediately convert nominal capacity into qualified shipments. LightCounting’s April 2026 market forecast
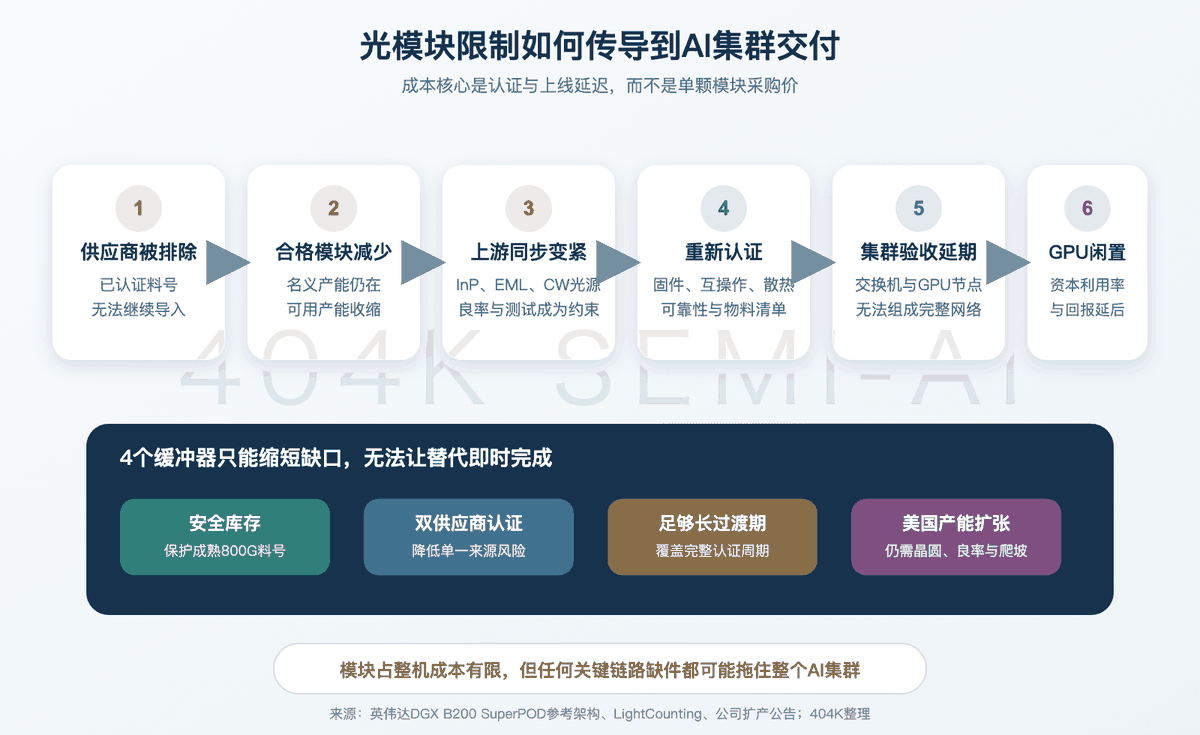
The supply-chain disruption would therefore unfold sequentially: first, shortages of specific already-qualified part numbers; next, shortages of upstream optical sources capable of stable mass production; and finally, customers being forced to adjust switch bills of materials and deployment schedules. Modules would still exist globally, but they could not be installed in these AI clusters according to the original schedule.
AI Optical-Module Demand Revised Higher Again: How Morgan Stanley’s May Report Extends the 1.6T, InP, and CPO Bottlenecks to 2028
Why Coherent and Lumentum Cannot Immediately Fill the Gap
Coherent and Lumentum are the most direct beneficiaries of substitution, but “benefiting” and “immediately replacing Chinese module capacity” are two different things.
Coherent’s strength lies in vertical integration. The company produces materials and indium phosphide lasers, as well as optical transceivers, passive components, and systems, giving it control from the light source through to the module. In March 2026, NVIDIA announced a $2 billion investment in Coherent and provided multi-year, multi-billion-dollar purchase commitments. Coherent subsequently disclosed plans to double internal indium phosphide output by the end of 2026 and more than double it again in 2027. This roadmap shows that substitution capacity genuinely exists, while also demonstrating that it will take several production cycles to deliver—not just a few weeks after the release of regulatory documents. NVIDIA and Coherent Partnership Announcement
Lumentum is more concentrated in electro-absorption modulated lasers, continuous-wave lasers, ultra-high-power lasers, and optical subsystems. NVIDIA likewise invested $2 billion in Lumentum and secured future capacity. Lumentum’s acquired facility in North Carolina, US, will use 6-inch indium phosphide wafers to produce continuous-wave and ultra-high-power lasers, but the company’s stated ramp-up timeline extends to mid-2028. It is better viewed as building the light-source foundation for next-generation CPO, NPO, and silicon-photonics systems, rather than providing module replacement volumes that will become immediately available in 2026. Lumentum US Indium Phosphide Facility Announcement
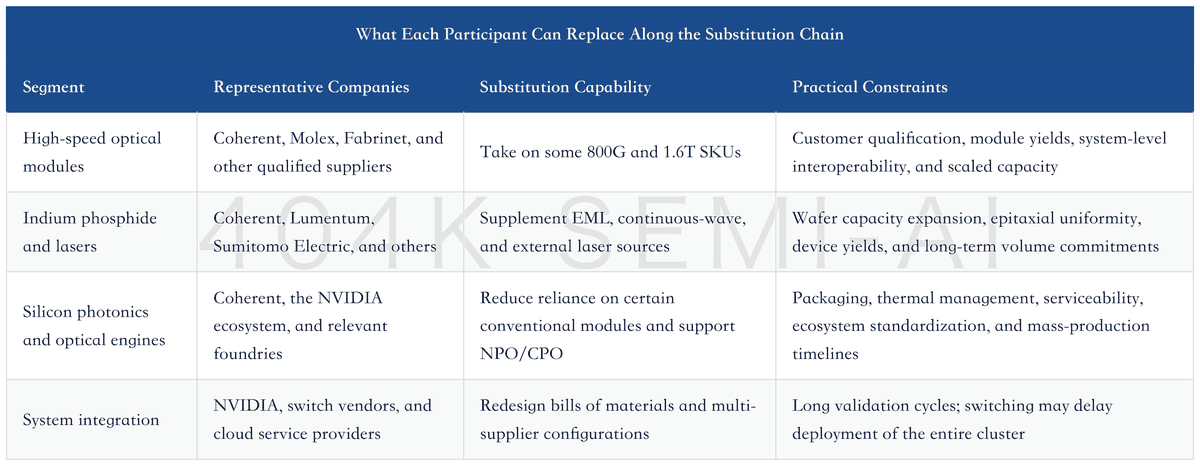
There is also an easily overlooked two-way relationship: Coherent and Lumentum are not only competitors to Chinese module manufacturers, but may also supply lasers and other components to the global module ecosystem. If restrictions cover finished products based on corporate ownership while upstream components can still move across borders, both companies will secure more upstream orders; if restrictions expand further to cover component origins, the globally interconnected optical supply chain will also be fragmented, partially offsetting the benefits of capacity expansion through duplicated qualification and supply-chain restructuring costs.
The Global Landscape Will Fragment, Rather Than Simply Become “US Vendors Take All”
Once broad restrictions take effect, the first stage will see US cloud customers competing for qualified supply. Vendors that already possess US manufacturing capacity, US customer relationships, and upstream light-source capabilities will secure longer-duration orders, stronger capacity commitments, and greater capital support. NVIDIA’s investments in both Coherent and Lumentum already demonstrate that customers are unwilling to place next-generation optics with a single supplier. The objective of the US supply chain is not merely to find one replacement for Innolight, but to prepare at least two sources each for light sources, modules, silicon photonics, packaging, and systems.
The second stage will involve Chinese vendors reallocating capacity. China’s cloud market is accelerating 800G deployment and will introduce 1.6T and 3.2T during 2027—2029. LightCounting estimates that China’s relevant market will grow at a CAGR of approximately 29% during 2025—2031, versus approximately 18% in the US, and that the difference in market size between the two countries may narrow to approximately 2.5x by 2031. This gives Chinese module manufacturers a new pool of demand, but it cannot fully replace, in the short term, the order volumes, product mix, and profit quality provided by leading US cloud customers. LightCounting China Market Forecast
The third stage will be the gradual formation of two technology ecosystems. The US supply chain will emphasize traceable light sources, domestic or trusted manufacturing, hardware bills of materials, and customer control; the Chinese supply chain will accelerate efforts to fill gaps in digital signal processors, indium phosphide epitaxy, electro-absorption modulated lasers, continuous-wave lasers, silicon photonics, coupling and packaging, and high-speed testing. Chinese module companies have traditionally been strongest in systems engineering, manufacturing efficiency, and delivery to major customers. If upstream localization fills the remaining gaps, their end-to-end capabilities in China and other markets may instead strengthen; the cost will be the fragmentation of global unified scale, with both duplicated investment and intraregional competition increasing.
Whether overseas factories can avoid the impact depends on how the rules define “Chinese optical modules.” If the determination is based on the location of final assembly or country of origin, overseas facilities in Thailand, Malaysia, and elsewhere may retain US orders; if it is based on corporate ownership, control relationships, the location of design and development, or the origin of key components, relocating the final assembly step will not change the product’s identity. FCC documents issued in 2026 are considering two frameworks—“determination by place of production” and “determination by producer”—and this difference in wording matters more than how many new overseas factories vendors announce.
AI Network Interconnect Hardware, Part I: The Value Migration Behind 1.6T/3.2T—Who Benefits Most Across Switching, Copper Interconnects, Optical Interconnects, and the Physical Layer?
The Real Cost to US Data Centers Is Delivery Risk
Reducing the impact to “how much module prices will rise” understates the problem. Modules account for a limited share of total AI cluster investment, but they determine whether expensive GPUs, switches, and racks can form an operational network.
NVIDIA’s reference architecture for a 127-node DGX B200 SuperPOD lists, for the compute network alone, 1536 switch-side 400G OSFP transceivers, 508 system-side 400G OSFP transceivers, and 4 management-side transceivers, totaling more than 2000; the management and storage networks require additional optical connections. If a system like this is missing dozens of critical SKUs, the issue is not simply that dozens of components remain uninstalled, but that certain links, switching tiers, or entire groups of nodes cannot pass acceptance testing on schedule. NVIDIA DGX B200 SuperPOD Component List
US cloud service providers will face 4 categories of costs. The first is the personnel and laboratory time required to requalify suppliers; the second is the engineering cost of changing switch bills of materials, firmware, and inventory; the third is idle capital when GPUs arrive before the network is ready; and the fourth is the operating complexity created by multiple suppliers, small batches, and safety stock. Even if per-module prices change little, a one-quarter delay in cluster deployment may create losses far exceeding the procurement price difference.
Customers can mitigate the impact through advance inventory purchases, dual-supplier qualification, and longer transition periods, but they cannot eliminate it completely. Advance inventory purchases apply only to finalized 800G SKUs and offer limited help for new 1.6T models still being introduced; dual-supplier qualification takes time; if the transition period is too short, inventory will shift from a buffer into an amplifier of panic buying and duplicate ordering. Policy design that can genuinely reduce risk would restrict only new models, provide explicit exemptions for signed contracts and orders in transit, and give customers sufficient time to complete second-source qualification.
Impact on China’s Supply Chain Will Hit Orders First, Then Upstream Suppliers
For companies such as Zhongji Innolight, Eoptolink, and Accelink, the first-round impact will be on high-end U.S. orders and customer share, rather than an immediate loss of all global revenue. Leading U.S. cloud customers have long generated the strongest demand for high-speed products and provided a critical entry point for validating 1.6T, silicon photonics, and next-generation architectures. Once these orders are restricted, overseas capacity utilization, product mix, R&D; returns, and valuations will come under pressure first.
The second-round impact depends on whether the Chinese market can absorb the displaced capacity. Chinese cloud customers’ demand for 800G and subsequently 1.6T products could absorb some capacity, but their customer mix, pricing, payment terms, and technology roadmaps may not fully match those of U.S. orders. If domestic demand grows more slowly than export orders decline, capacity competition will emerge first at the module level; if domestic demand scales rapidly, the impact will shift from a revenue issue to an upstream component-supply issue.
The third-round impact will be investment in localization. High-speed digital signal processors, indium phosphide lasers, continuous-wave light sources, silicon photonics processes, and testing equipment all require more comprehensive alternatives. These investments will improve supply security, but may also result in duplicated capacity if multiple vendors expand simultaneously. Whether China’s supply chain can convert policy pressure into stronger industrial capabilities will ultimately depend on the yield, power consumption, reliability, and customer mass production of locally produced components—not on the number of projects announced.
The implications for U.S. suppliers should not be characterized as purely positive either. Coherent and Lumentum will receive orders and capital support, but they must convert nominal wafer capacity into qualified lasers and modules; if capacity expansion, yields, or customer qualification fall behind schedule, orders will merely become backlogs and capital expenditure. U.S. cloud providers will also face greater supply concentration: after excluding a group of established suppliers, any manufacturing incident among the remaining vendors will reverberate across the entire AI infrastructure buildout cycle.
Which Signals Would Escalate “Localized Order Switching” into a “Supply Discontinuity”
Five terms in policy documents warrant close attention. First, whether the rules cover “new models” or “all imports”; second, whether they target named entities or all China-controlled entities; third, whether they are based on the location of final assembly or on ownership and design control; fourth, whether they restrict only finished modules or also cover lasers, digital signal processors, and other components; and fifth, whether the transition period spans a full customer-qualification cycle.
On the industry side, four sets of data should be monitored: whether U.S. cloud customers withdraw already allocated 1.6T share from Chinese suppliers; whether Coherent and Lumentum ramp qualified indium phosphide output on schedule; whether alternative module vendors enter leading customers’ formal bills of materials; and whether 800G and 1.6T orders in China’s cloud market can absorb export capacity. Vendor capacity-expansion announcements alone cannot determine whether the discontinuity has been repaired.
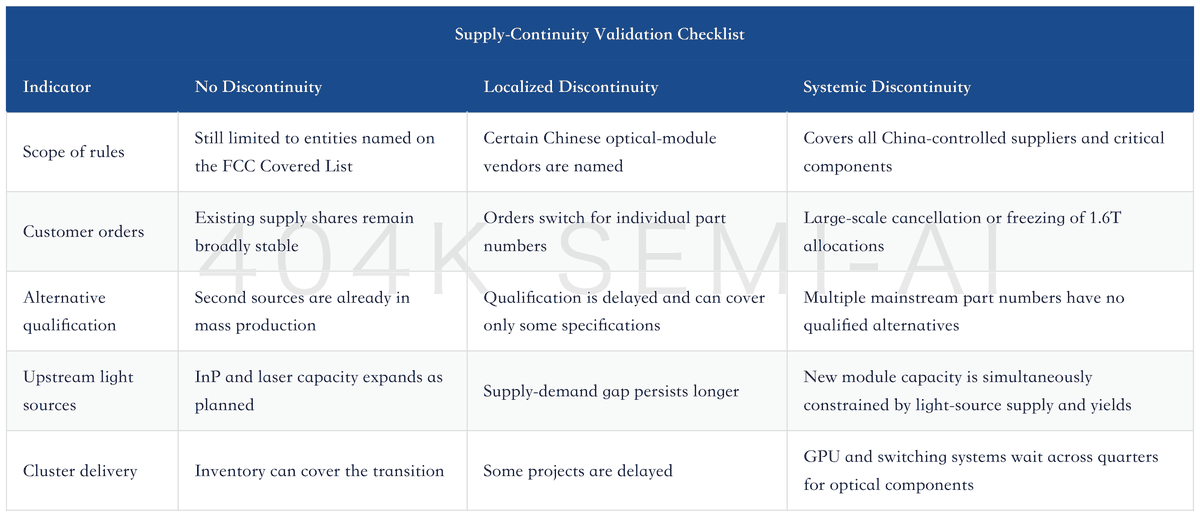
The ultimate answer is not a simple “yes” or “no.” If the U.S. maintains its current rules targeting named entities, this round of policy changes will not create a discontinuity in the global AI interconnect supply chain; if the rules expand to all China-controlled optical-module suppliers, the U.S. market will likely experience a qualified-supply shortfall lasting several quarters. Global capacity will subsequently find new customers, but at the cost of splitting a unified supply chain into two regional systems: the U.S. will bear the risks to cluster delivery and capital utilization, while China will face the loss of high-end customers and pressure to localize upstream supply.
The greatest risk is not that modules become unavailable on a particular day, but that the largest group of established suppliers is removed from qualified-vendor lists all at once during the fastest phase of AI network upgrades, before alternatives have secured sufficient wafers, yields, and customer qualifications. That would constitute a true supply-chain “discontinuity.”
Key References
U.S. Federal Communications Commission: 2025 Second Further Notice of Proposed Rulemaking; 2026 Third Report and Order.
U.S. Department of Defense: 2026 Section 1260H entity list.
LightCounting: Optical-module market and vendor updates from January, March, April, and May 2026.
NVIDIA: DGX B200 SuperPOD reference architecture; announcements of strategic optical partnerships with Coherent and Lumentum.
Coherent: FY2025 10-K; FY2026 third-quarter presentation materials.
Lumentum: Announcement of its U.S. 6-inch indium phosphide facility.
Related Reading
Rubin Ultra HBM Capacity Cut to 192GB: Supply and Power Constraints Drive Roadmap Downgrade