
Ibiden Deep Dive: Citi Sees ¥30,000; How AI CPU Package Substrates Re-rate the ABF Leader
目录
Too Long; Didn’t Read
1. First, Define the Company Clearly: Ibiden Sells Effective Capacity for Advanced Packaging
2. Sell-Side Divergence: What Is the ¥30,000 Target Price Actually Buying?
3. Business Essence: Not Ordinary ABF Price Hikes, but Scarce Delivery Capability in High-End Package Substrates
4. Supply-Demand Math: Demand Is Running Ahead of Capacity, and the Gap Is the Hard Constraint for Re-Rating
5. Profit Model: FY3/27 Is About CPU Recovery, FY3/28 About Gama, and FY3/31 About the Profit Ceiling
6. Company Ranking: Why Ibiden Should Not Be Equated Simply with Unimicron, Nan Ya PCB, Kinsus, or Samsung Electro-Mechanics
7. Valuation Framework: ¥30,000 Is Neither the Endpoint Nor a Cheap Price
8. Technology Roadmap: EMIB-T, Silicon Bridges, and Large Packages Determine How Far the Valuation Premium Can Go
9. Management Targets: Conservative Company Guidance, or Overly Optimistic Sell-Side Models?
10. Risks and Disconfirming Evidence: When This Re-Rating Would Be Invalidated
11. How to Track the Next Four Quarters: Do Not Track the Story, Track the Numbers That Change the Model
12. Financial Quality: Customer Funding Turns Expansion Risk from a Debt Issue into a Delivery Issue
13. Trading Framework: Use Sharp Pullbacks for Verification; Do Not Treat Target Prices as a Trading Plan
14. Investment Conclusion: Buying the AI Packaging Gatekeeper, but Paying the Valuation Through Earnings Delivery
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Ibiden’s current re-rating is not primarily about ABF shortages themselves. The core is that AI GPUs, ASICs, and server CPUs are turning high-end package substrates from cyclical materials into tickets to advanced packaging. The stock has already moved ahead; what must be validated next is whether capacity, pricing, customer funding, and silicon-bridge mass production can all translate into a profit step-up by FY3/31.
Too Long; Didn’t Read
The asset attributes have changed. Ibiden is no longer just an ABF supplier in the PC cycle; it is selling effective high-end package-substrate capacity as AI GPUs, ASICs, server CPUs, and switch chips ramp.
The highest target price is ¥30,000. Citi sees ¥30,000, while BofA is at ¥29,800. The debate is not direction, but whether FY3/29 to FY3/31 earnings can keep being revised up.
The gap is a hard constraint. The company’s FY3/29 capacity is around 2.8x, but demand from AI servers and ASICs could approach 5x. Morgan Stanley also sees a 22% ABF shortage in 2030.
Profit depends on three assets. Ono maps to GPU substrates, Gama maps to AI ASICs and silicon bridges, and utilization of existing CPU substrates recovering from 60-70% to 80-90% should first contribute to the FY3/27 slope.
Sell-side entry points differ. UBS is buying supply-demand, BofA is buying CPU recovery and silicon bridges, Macquarie is buying the EMIB-T position, and Citi is buying nearly 30% annual AI server growth and a higher valuation center.
The stock has entered the delivery zone. ¥30,000 is not a cheap undervaluation call; it prices in FY3/29 earnings, upward revisions to FY3/31 targets, and expectations for additional capacity expansion ahead of time.
The sell-down signals are specific. Whichever breaks first among AI ASIC demand, T-Glass supply, customer prepayments, and CPU utilization will be the signal that the re-rating is cooling. Sharp pullbacks without fundamental deterioration are more worth watching.
1. First, Define the Company Clearly: Ibiden Sells Effective Capacity for Advanced Packaging
The easiest way to describe Ibiden’s current rally is “ABF is short again,” but that understates why it has become more expensive. ABF substrates are of course important, and the shortage is a real issue. But the market’s willingness to lift BofA’s target price from ¥17,700 to ¥29,800 and push Citi’s target to ¥30,000 is not about a normal price-upcycle. It is buying the fact that a Japanese company has become a scarcer capacity gate in the AI advanced-packaging chain.
The company used to look more like a cyclical materials and electronic components company. PCs, general-purpose servers, CPU platform refreshes, customer inventory, and capital-expenditure timing determined the up and down cycles in ABF orders. In the last cycle, substrate makers expanded capacity, consumer electronics cooled, and PC demand fell back, making it easy for investors to treat ABF as a typical high-beta cyclical asset: strong earnings elasticity when the cycle rises, then pricing and utilization return to earth after capacity comes online.
What is different this time is that downstream demand is no longer just PC CPUs, or even just general-purpose server CPUs. AI GPUs, cloud in-house ASICs, server CPUs, and data-center switch chips are all pushing package substrates toward larger sizes, higher layer counts, higher yields, and more difficult materials management. Ibiden’s product is not an abstract “board”; it is the underlying carrier that determines whether compute chips can enter advanced packaging, whether systems can be delivered on schedule, and whether production can ramp stably.
In the past, the core ABF question was “is there demand?” Now the more important question is “who can turn demand into qualified capacity?” AI accelerator packages are getting larger, layer counts are rising, SAP process requirements are becoming tougher, and the materials side is constrained by bottlenecks such as T-Glass. Customers cannot simply switch to any supplier, and suppliers cannot simply buy equipment and expand. For Ibiden, customer qualification, yield experience, materials coordination, cleanrooms, labor, and investment cadence together form the ticket of entry.
This is also why the company’s FY3/31 medium-term target and sell-side models have changed so sharply. In its latest medium-term target, the company points to electronics business sales of around ¥800 billion in FY3/31, group operating profit above ¥300 billion, and a long-term FY2030 framework of ¥1 trillion in net sales, ¥300 billion in operating profit, and a 30% operating margin. This target is not simply “industry conditions are good, so revenue rises.” It reflects a change in margin structure as the product mix shifts from ordinary substrates to GPUs, ASICs, server CPUs, and switch chips.
Understanding Ibiden requires placing it in the middle of the AI hardware value chain. Upstream are ABF film, T-Glass, copper foil, resins, equipment, and precision-processing capability. Midstream are package-substrate manufacturers. Downstream are Nvidia GPUs, cloud ASICs, server CPUs, switch chips, and advanced-packaging houses. Chip design determines the performance ceiling, wafer manufacturing determines transistor density, advanced packaging determines how chips interconnect, and ABF substrates determine whether large packages can be stably supported, powered, and routed. At the high end, substrates are not accessories; they are part of system-level capacity.
So the investment judgment can be put up front: Ibiden’s re-rating works not because of the phrase “ABF price increases,” but because AI servers are repricing high-end ABF from cyclical materials into advanced-packaging infrastructure. If this premise holds, the ¥30,000 target price is not arbitrary; it discounts the FY3/29 to FY3/31 profit step-up in advance. If this premise is wrong, the valuation drawdown will also be rapid, because the current share price is no longer cheap.
2. Sell-Side Divergence: What Is the ¥30,000 Target Price Actually Buying?
The common ground among several investment banks this time is very clear: all acknowledge that Ibiden has entered an upward revision cycle for AI package substrates. The divergence is equally clear: some are buying the short-term recovery in CPU-substrate utilization, some are buying the contribution from the new Gama plant after FY3/28, some are buying AI ASIC silicon-bridge substrates, and some are buying a higher valuation center driven by industry supply shortages. The higher the target price, the more it implies not “a bit more profit next year,” but a simultaneous upward move in the profit step and valuation multiple after FY3/29.
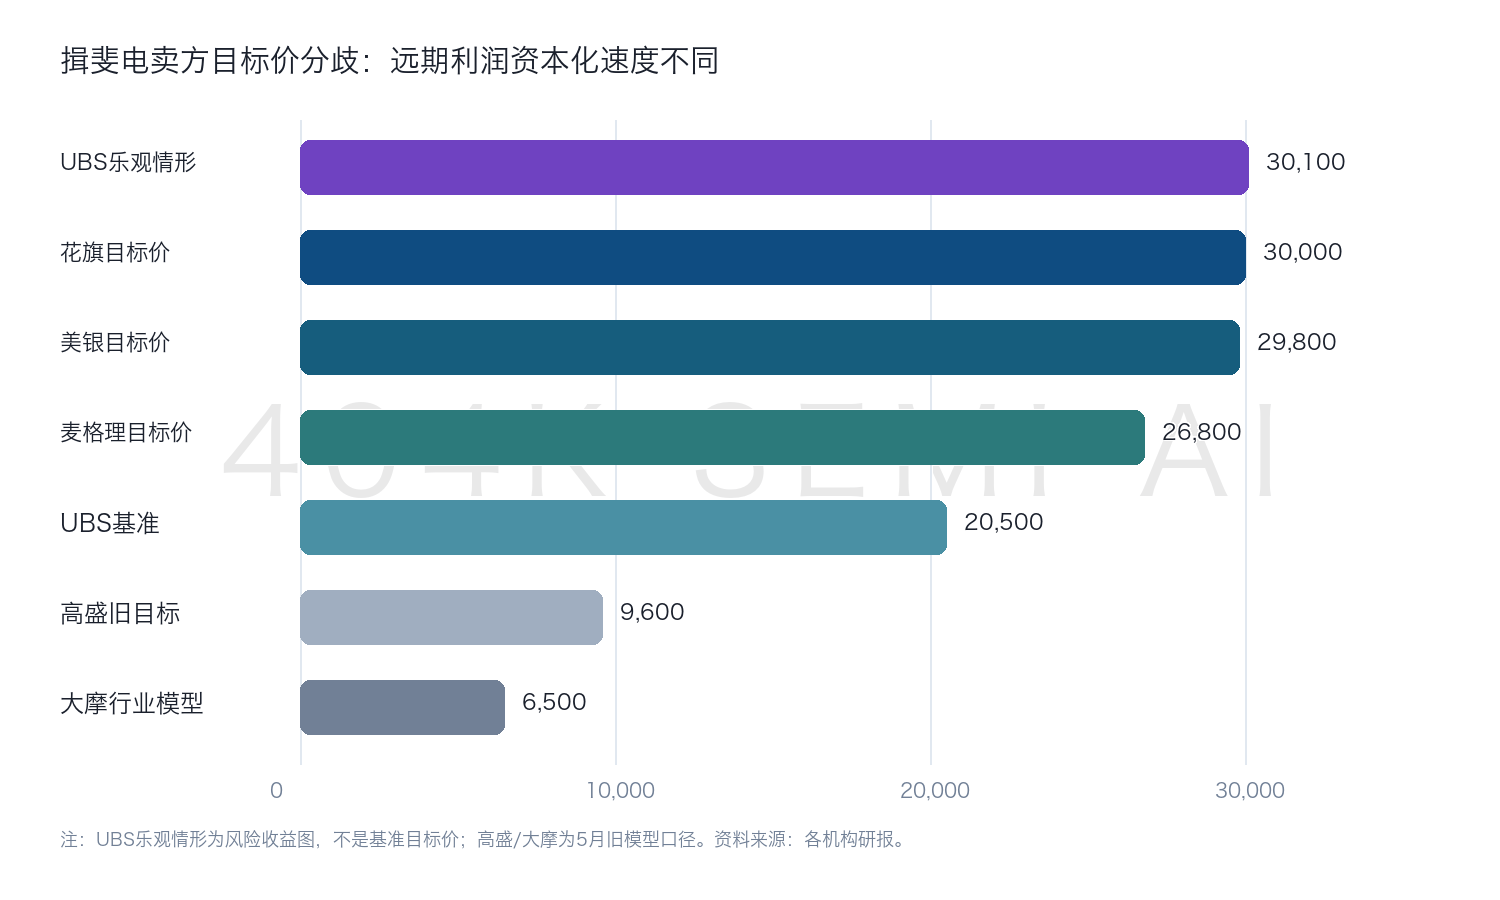
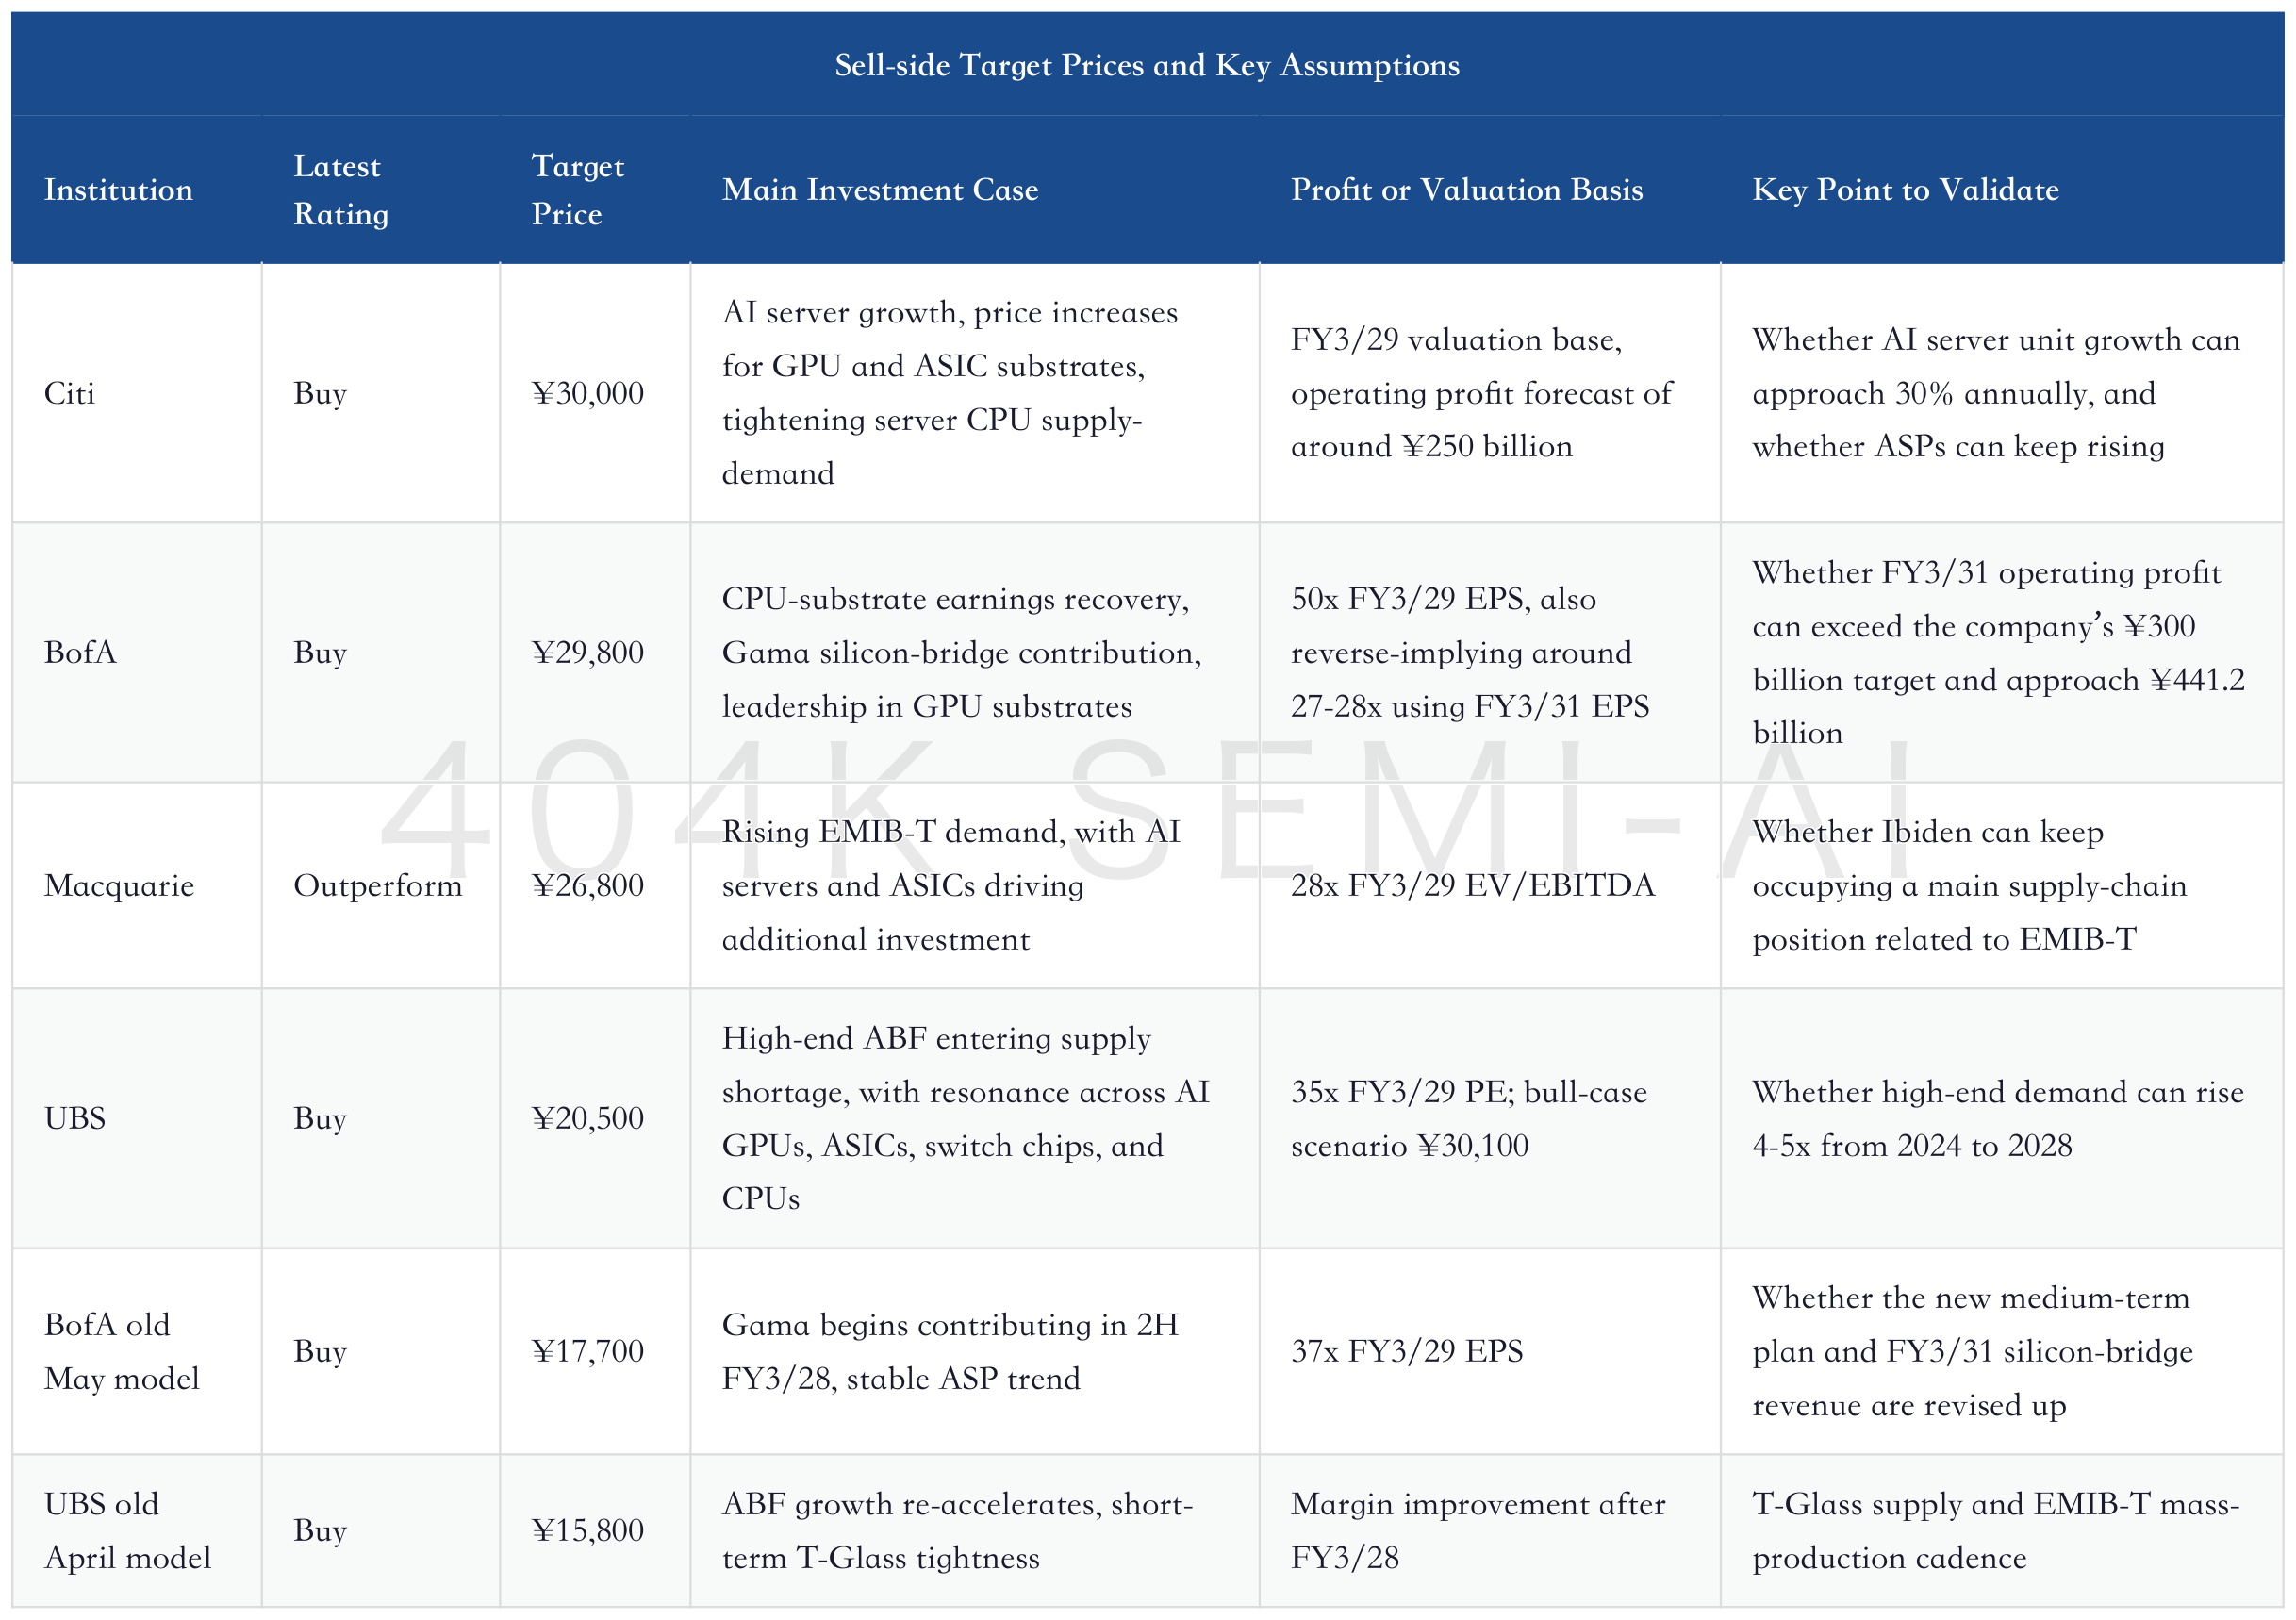
Looking at these target prices together, the useful question is not “who is highest,” but where each institution locates the profit. Citi leans toward industry and valuation, with the core being upward revisions to AI server demand assumptions and the view that GPU, ASIC, and CPU substrates will all gradually tighten.
BofA is more company-model-driven, focusing on recovery in CPU-substrate utilization, the start of Gama’s contribution, and silicon-bridge business potentially coming in materially above company guidance. Macquarie emphasizes EMIB-T, effectively treating Ibiden as a key substrate supplier for a specific advanced-packaging route. UBS is more restrained, but its bull-case scenario is also close to the highest target price, showing that it does not disbelieve the supply-demand story; it is simply more disciplined on the valuation landing point.
This divergence affects investment action. Looking only at Citi’s ¥30,000 target can easily lead to the simplistic conclusion that “there is still upside.” Putting the models together yields a more nuanced conclusion: the current share price has already absorbed much of the FY3/27 profit recovery and FY3/28 expansion visibility. To earn greater upside from here, silicon bridges, AI ASICs, CPUs, and additional capacity expansion all need to provide evidence after FY3/29. In other words, the buy thesis has shifted from “cycle is improving” to “the profit step keeps being revised up.”
This also explains why Morgan Stanley’s industry report was bullish on ABF supply-demand but had previously been more cautious on Ibiden’s valuation. Industry supply shortages can benefit all leading players, but different stocks have reflected this to different degrees. Unimicron, Nan Ya PCB, Kinsus, Samsung Electro-Mechanics, and Ibiden are all in the ABF re-rating chain, but each company differs in starting point, customer mix, expansion position, and valuation expectations. Ibiden’s advantage is stronger high-end customers and a stronger advanced-packaging position; the issue is that its stock has also risen first.
Therefore, the right way to read the headline ¥30,000 figure is not “Citi is calling the trade,” but that it draws a test line for the market: if FY3/29 operating profit can indeed exceed ¥250 billion, and if the company’s FY3/31 target of ¥300 billion can still be revised further upward, then ¥30,000 has an earnings foundation. If capacity ramp-up, customer demand, or ASPs begin to come in below expectations after FY3/28, then ¥30,000 will become a resistance level for high-level volatility.
3. Business Essence: Not Ordinary ABF Price Hikes, but Scarce Delivery Capability in High-End Package Substrates
ABF substrates themselves are not new. They have long been used in high-end chip packaging for CPUs, GPUs, ASICs, FPGAs, and other products, serving as high-performance substrates that connect the die, package, and motherboard. In the past, investors focused on PC CPU shipments, server platform refreshes, inventory cycles, and yield ramp-ups. What has truly changed now is the packaging format and chip application: AI GPUs and ASICs are becoming larger, I/O and power delivery are becoming more complex, server CPUs are also being pulled by AI inference demand, and switch chips likewise require larger, higher-layer-count package substrates.
Based on company disclosures and sell-side models, Ibiden needs to serve four types of high-end demand over the next several years. The first is AI GPUs, mainly supported by Ono-related capacity, corresponding to large-size, high-layer-count substrates and SAP processes. The second is AI ASICs and inference chips, with Gama Cell 6 viewed by the market as a key source of incremental growth; the sell side is especially focused on silicon bridge and EMIB-T-related opportunities. The third is server CPUs: utilization of high-end CPU substrates remained low in the latter part of FY3/26, but is expected to recover in FY3/27. The fourth is data center switch chips. Official Q&A; mentioned that the company has begun supporting switch-chip substrates, and orders from a major GPU customer have already emerged.
What these demand sources have in common is that higher value per unit matters more than shipment volume. AI servers do not need to ship in the hundreds of millions like PCs. What truly drives substrate value is larger package area, higher layer count, greater manufacturing difficulty, and higher yield thresholds. The value content of high-end GPU and ASIC substrates may be far higher than that of ordinary PC CPU substrates. If silicon bridges, advanced interconnects, and high-density routing are added, the ASP elasticity per unit can exceed the traditional cyclical logic of “a few percentage points of price increases.”
In the company’s official medium-term plan, the direction of substrate specification changes is very explicit: package sizes are moving from the 80x80 mm class toward 90x90, 110x110, and even larger formats, while SAP layer counts are advancing from 9-X-9 and 10-X-10 toward 12-X-12 and 14-X-14. This may sound like engineering parameters, but the investment implication is direct: as size and layer count increase, unit capacity does not expand linearly. Yield, materials, equipment, cleanrooms, labor, and customer qualification all become amplified constraints.
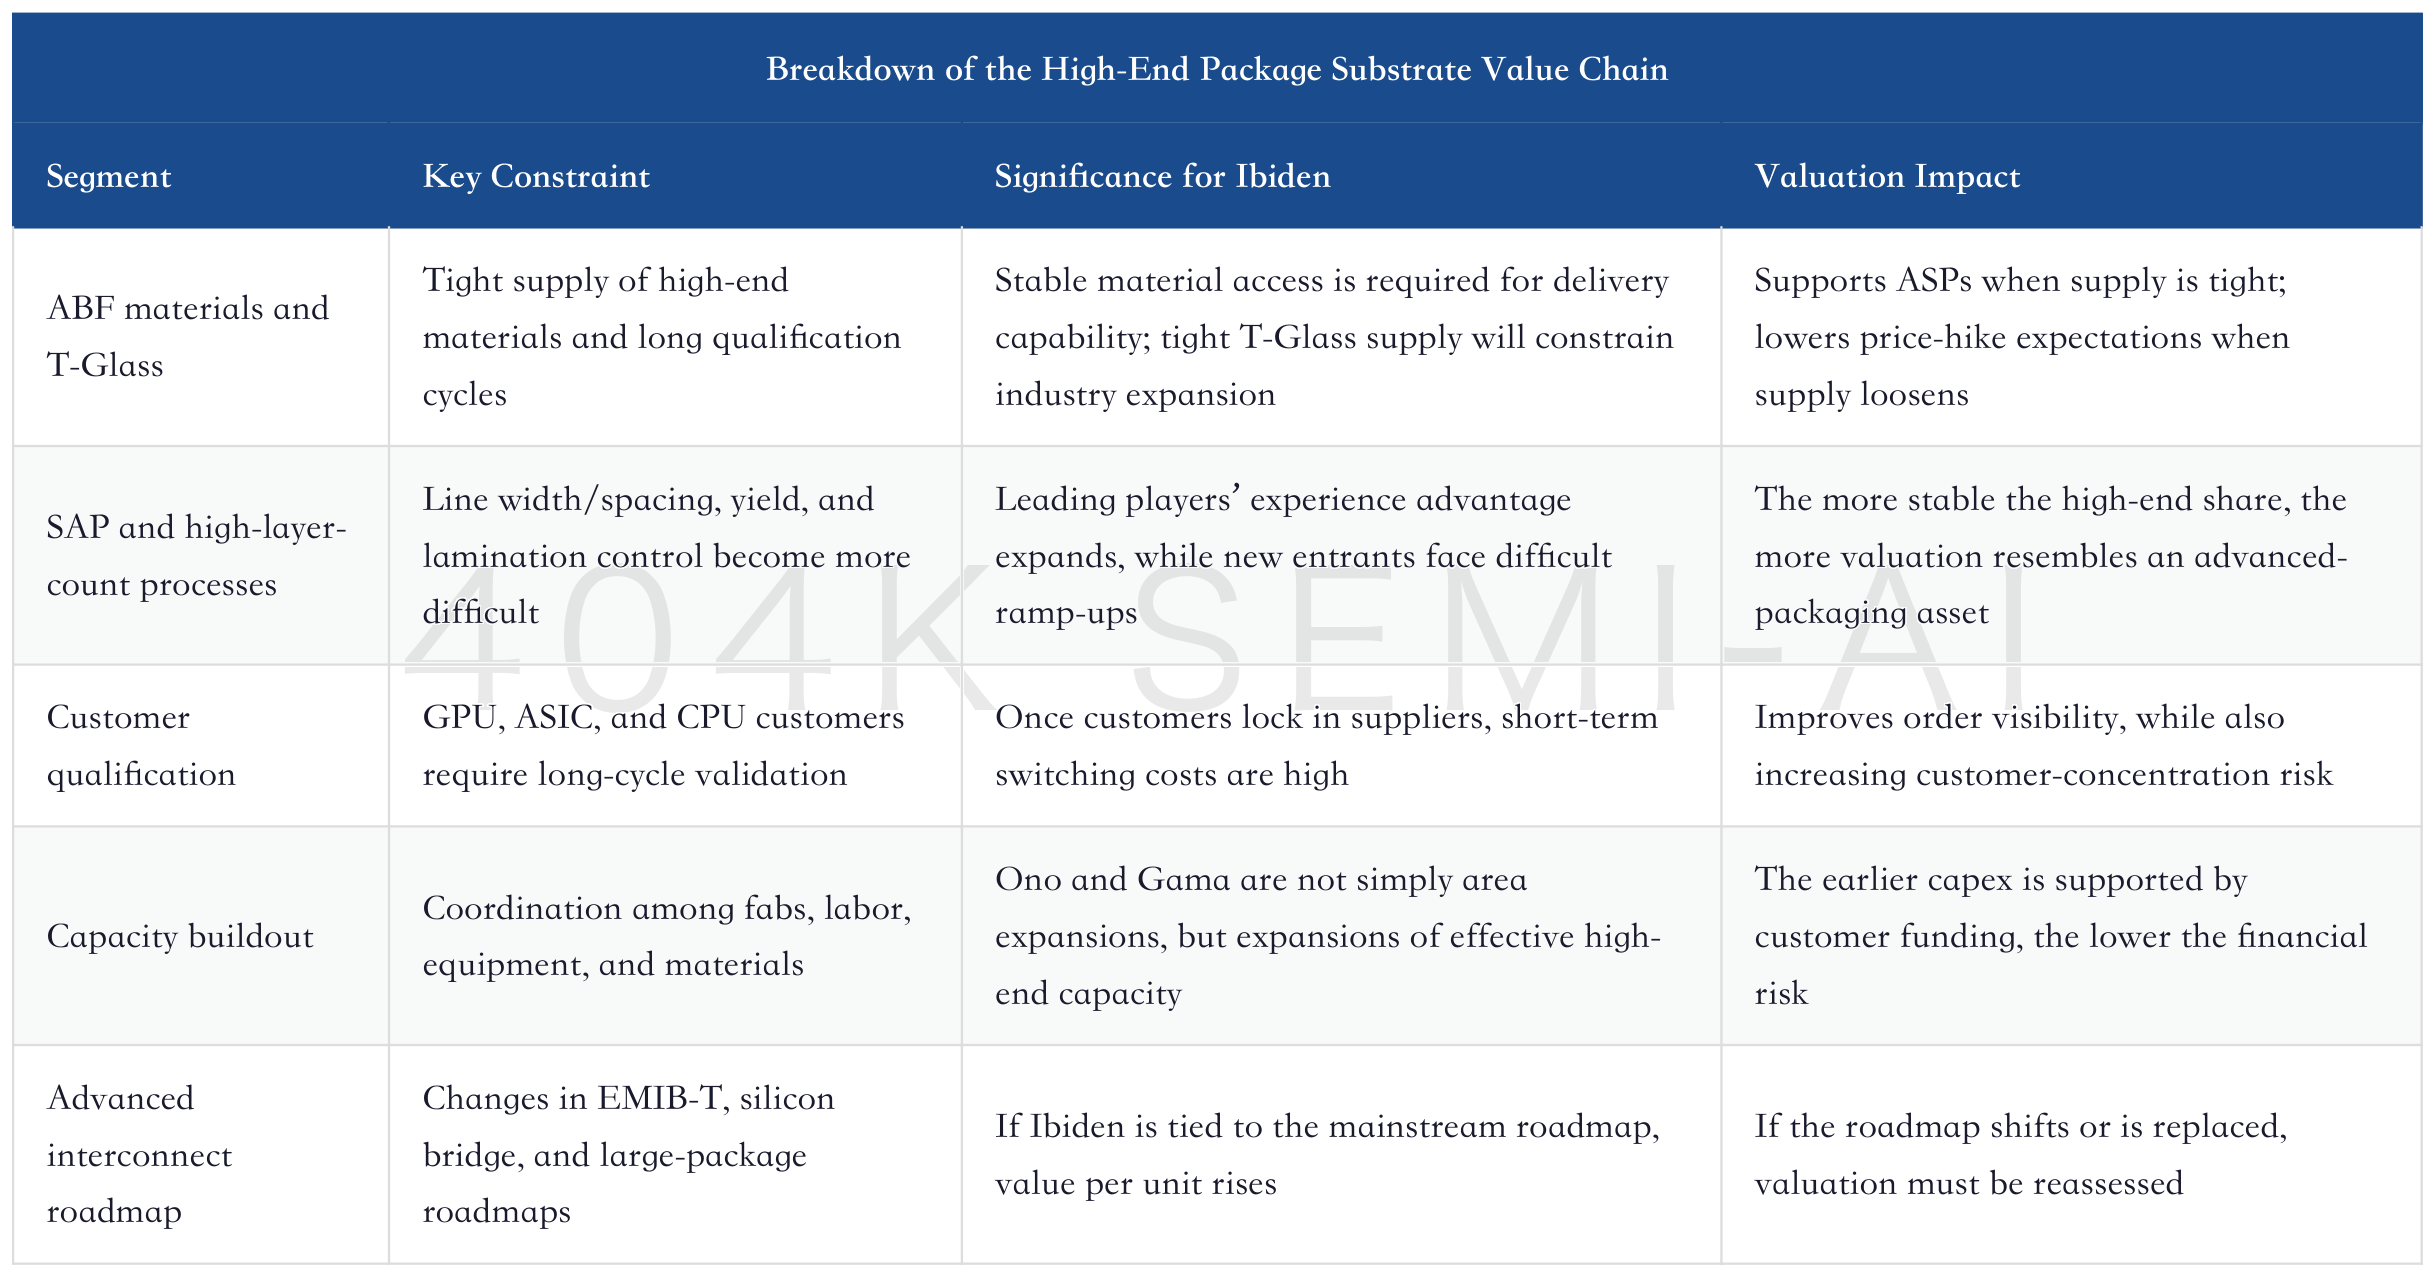
One judgment sits behind this table: Ibiden’s high-end capacity increasingly resembles “advanced-packaging infrastructure pre-booked by customers,” rather than materials capacity in a fully open market. Official Q&A; mentioned that customer agreements and prepayments can support investment, and that there are currently no additional financing plans. This is highly important for valuation. What the market fears most is not large capex itself, but capacity expansion funded solely by the company, uncertain demand, and depreciation consuming profits once prices fall. If customer funding and order visibility are sufficiently strong, the JPY500 billion investment shifts from a risk item into an entry-barrier item.
Of course, an entry barrier does not mean zero risk. The higher the customer concentration, the more complex the bargaining power. Ibiden needs to balance reasonable pricing, long-term cooperation, and capacity lock-in. Official Q&A; also mentioned that the company will not over-extract from customers simply because of short-term tightness, but will maintain reasonable negotiations within long-term relationships. This means ASP elasticity may be more moderate than in some aggressive models, but order stability and the quality of investment recovery should be better.
4. Supply-Demand Math: Demand Is Running Ahead of Capacity, and the Gap Is the Hard Constraint for Re-Rating
The ABF industry has experienced shortages before, but this time the supply-demand constraint is harder. The reason is not strength in a single end market, but the simultaneous increase in high-end substrate demand from GPUs, ASICs, server CPUs, and switch chips. Ordinary ABF capacity cannot be fully equated with high-end ABF capacity, and ordinary substrate manufacturers cannot immediately enter high-end AI orders simply by expanding capacity. What is truly scarce is effective capacity capable of producing large-size, high-layer-count, high-yield substrates that have passed leading-customer qualification.
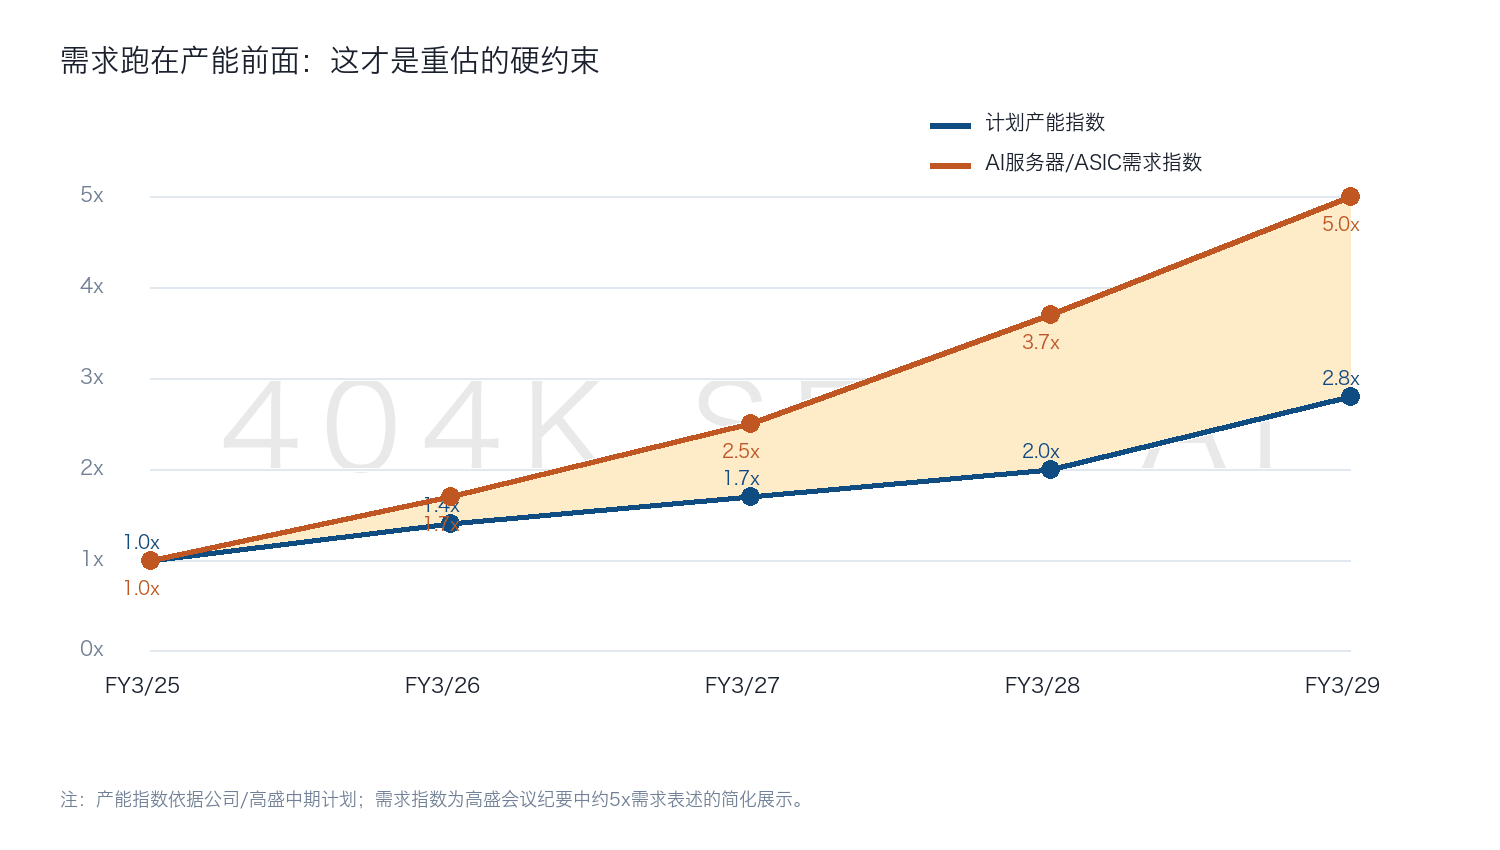
Goldman Sachs provided a highly important directional data point in its notes from Ibiden’s medium-term plan meeting: the company’s AI server and ASIC-related capacity is planned to reach about 2.8x by the end of FY3/29, while GPU and ASIC-related SAP demand could approach 5x by the same stage. Capacity is expanding quickly, but demand is running even faster. This is the hardest part of the re-rating.
Morgan Stanley’s industry model extends this gap further. It expects ABF market value demand to grow at a 22.2% CAGR from 2025 to 2030, with the supply gap potentially widening to 22% by 2030. More importantly, the demand structure is shifting: PC ABF’s value share could fall from about 70% in 2015 to below 15% by 2030, while servers, AI GPUs, AI ASICs, and networking chips combined could rise to more than 75%. The industry is not seeing only modest volume growth; the profit pool is migrating toward high-end compute packaging.
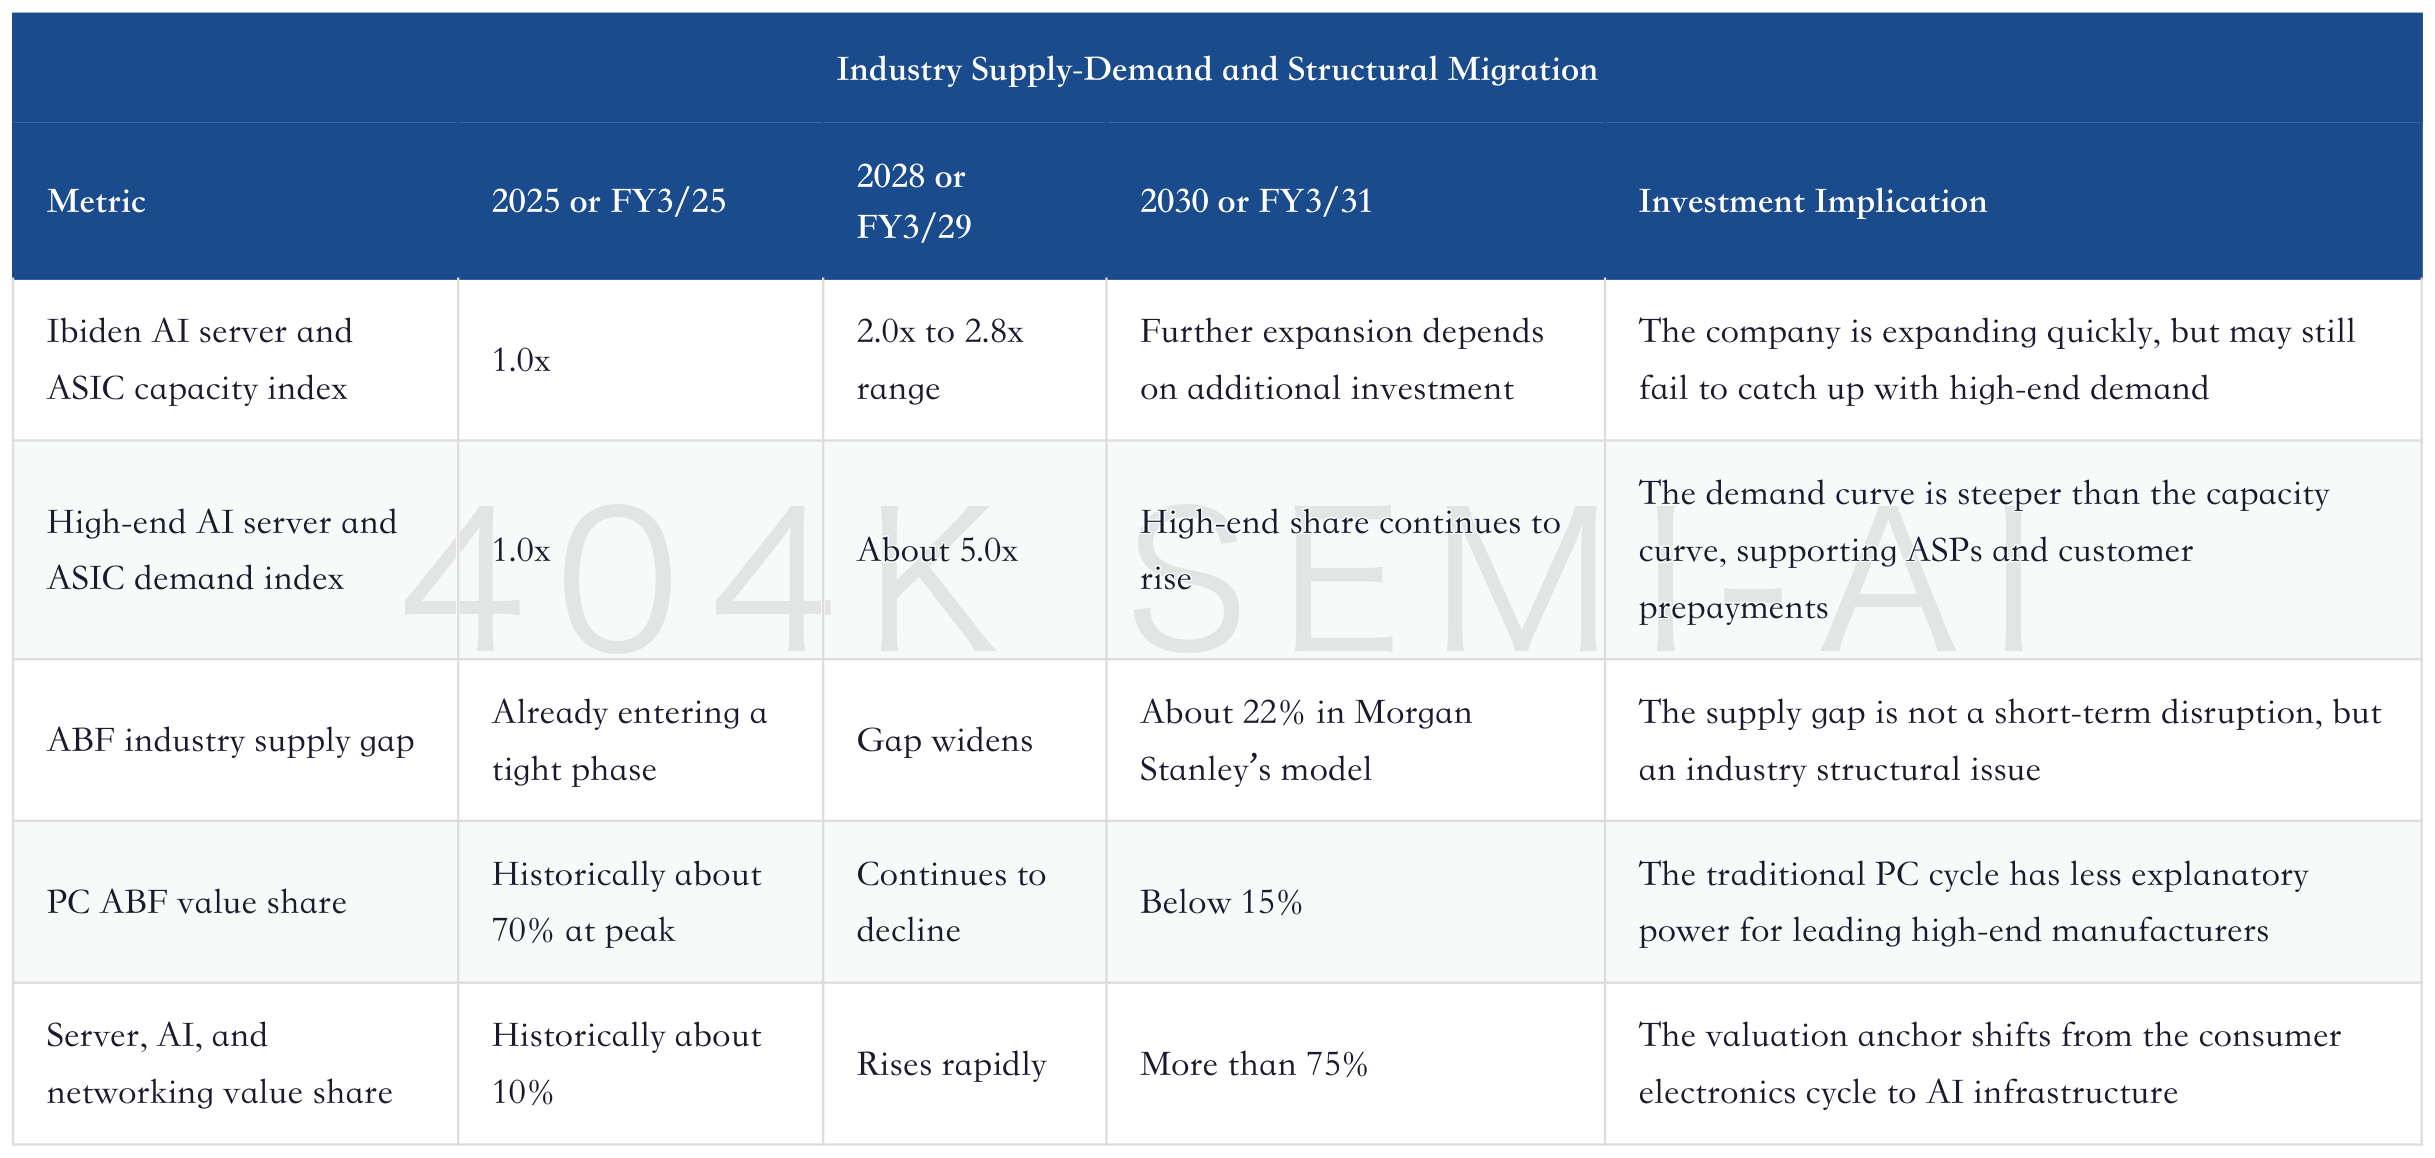
The implication of this data set for Ibiden is direct. If high-end demand really approaches 5x, while the company’s visible capacity reaches only about 2.8x by the end of FY3/29, then high-end customers must accept stronger long-term agreements, prepayments, reasonable price increases, and product-mix upgrades in order to secure stable capacity. Suppliers do not need to push prices to the limit every year. As long as the order mix continues shifting toward GPUs, ASICs, server CPUs, and switch chips, revenue and margins should naturally move upward.
The key supply-side variable to monitor is T-Glass. UBS has repeatedly flagged tight near-term T-Glass supply, with FY3/28 capacity potentially doubling versus FY3/25 and supply volume increasing by about 1.7x. This sounds like supply is improving, but if high-end demand grows 4-5x from 2024 to 2028, material improvement does not mean the shortage disappears. As long as T-Glass remains a bottleneck, it will amplify leading customers’ competition for certain capacity and allow leading substrate manufacturers to retain initiative in price negotiations.
Another easily overlooked variable is delivery lead time. New capacity, from investment, construction, equipment installation, material qualification, and customer validation to stable mass production, usually cannot be completed in just a few months. Morgan Stanley and multiple institutions have noted that meaningful new capacity generally takes more than two years. In other words, even if the industry sees the gap, the supply response is slow. For a company like Ibiden, which already has customers, processes, and fab planning in place, early positioning is even more valuable.
The supply-demand conclusion can be compressed into one sentence: ordinary ABF shortages are cyclical, while high-end ABF shortages are a capacity mismatch in AI advanced packaging. The former can be absorbed through capacity expansion; the latter requires customer qualification, materials, process technology, yield, capital, and labor to all be in place at the same time. Ibiden’s current re-rating reflects the market beginning to view it less as an “ABF company in an expansion cycle” and more as a “high-end gatekeeper in an AI packaging capacity mismatch.”
5. Profit Model: FY3/27 Is About CPU Recovery, FY3/28 About Gama, and FY3/31 About the Profit Ceiling
If we only discuss supply and demand, Ibiden is easily reduced to an industry story. What really determines whether the stock can support a JPY 30,000 target price is whether the profit model can be delivered year by year. The timeline needs to be separated: FY3/27 is mainly about utilization recovery in existing CPU substrates and GPU substrates; FY3/28 is mainly about incremental ramp-up from Gama and Ono; FY3/29 is about high-end capacity release and ASP; and FY3/31 is about whether the company’s medium-term targets still have room for further upward revision.
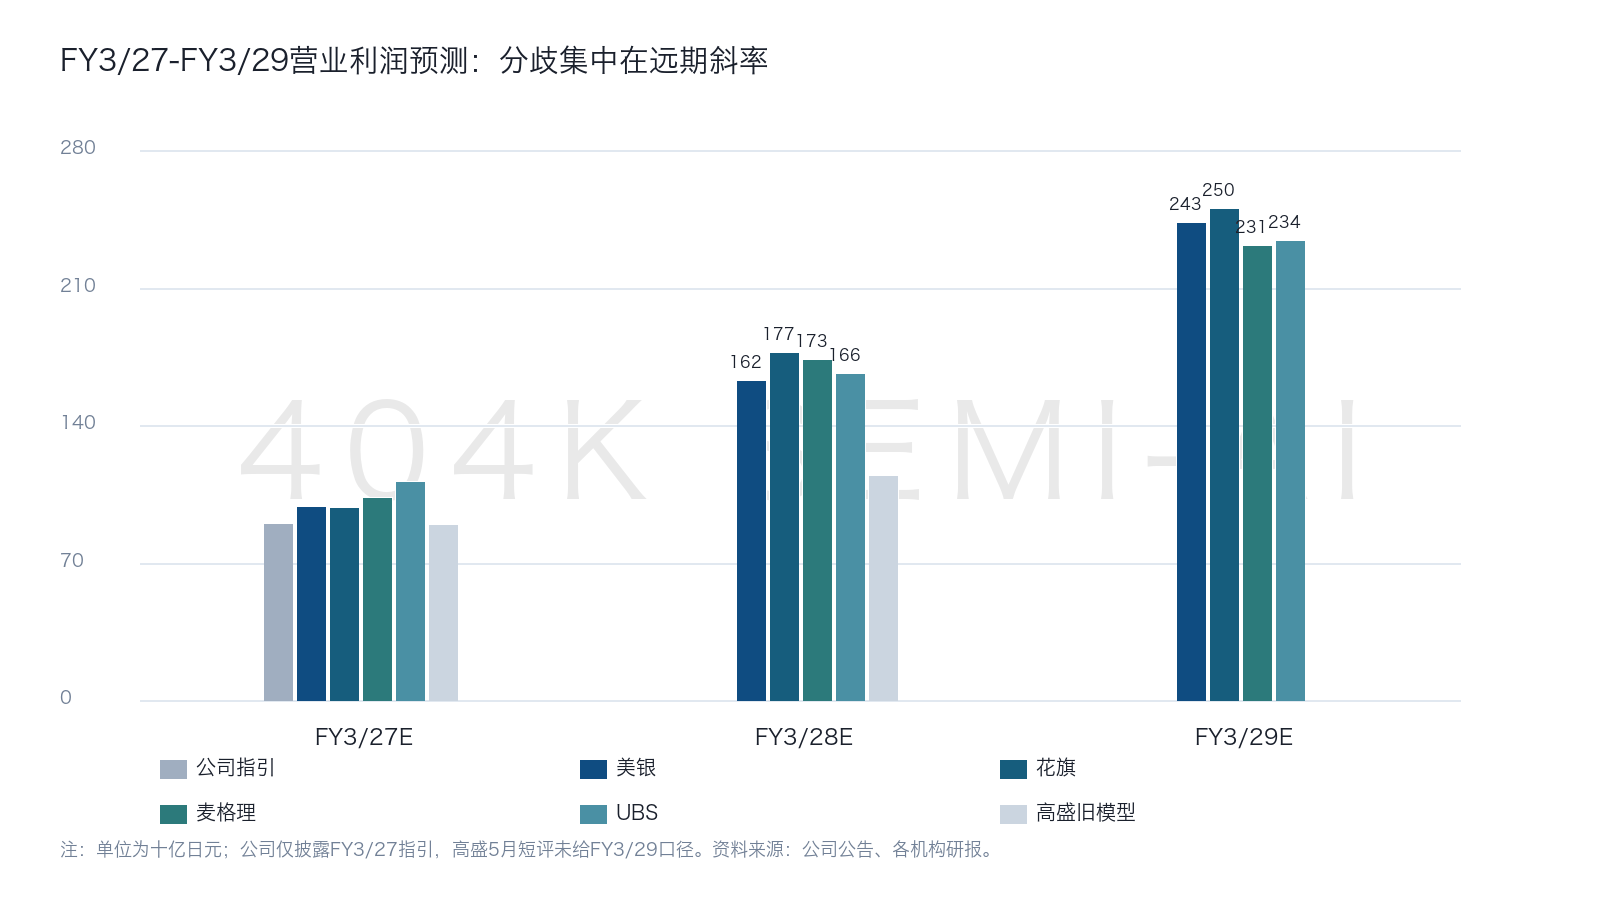
The key in FY3/27 is not full release from new plants, but the existing business returning from low utilization to a healthy level. In its latest model, BofA noted that utilization at the Ogaki Chuo plant, where CPU substrates are produced, was still in the 60-70% range in FY3/26 Q4 and is expected to rise to 80-90% in FY3/27. This type of recovery is highly sensitive for operating profit because depreciation, labor, and fixed costs are already in place; a rebound in utilization from low levels directly improves marginal profit.
After FY3/28, the contribution from Gama Cell 6 and Ono becomes more important. The company plans to execute roughly JPY 500 billion of investment from FY3/27 to FY3/29, including around JPY 220 billion for Gama, mainly tied to demand from AI ASICs and silicon bridges, and around JPY 280 billion for Ono, mainly tied to AI GPU substrates. Official materials indicate that Gama-related production lines are expected to begin sequential launch and mass production from FY3/28, which is also why multiple institutions have shifted their valuation benchmark to FY3/29.
FY3/31 is the most debated year in the market. The company’s group operating profit target is more than JPY 300 billion, while BofA’s latest model estimates FY3/31 operating profit at JPY 441.2 billion, materially above the company target. This gap is not a minor adjustment; it is the key variable determining the valuation ceiling. If the company target is merely conservative, and there is still additional capacity expansion and product-mix upside ahead, JPY 30,000 can be supported by earnings. If the company target is already close to the true ceiling, the stock will require a higher risk premium.
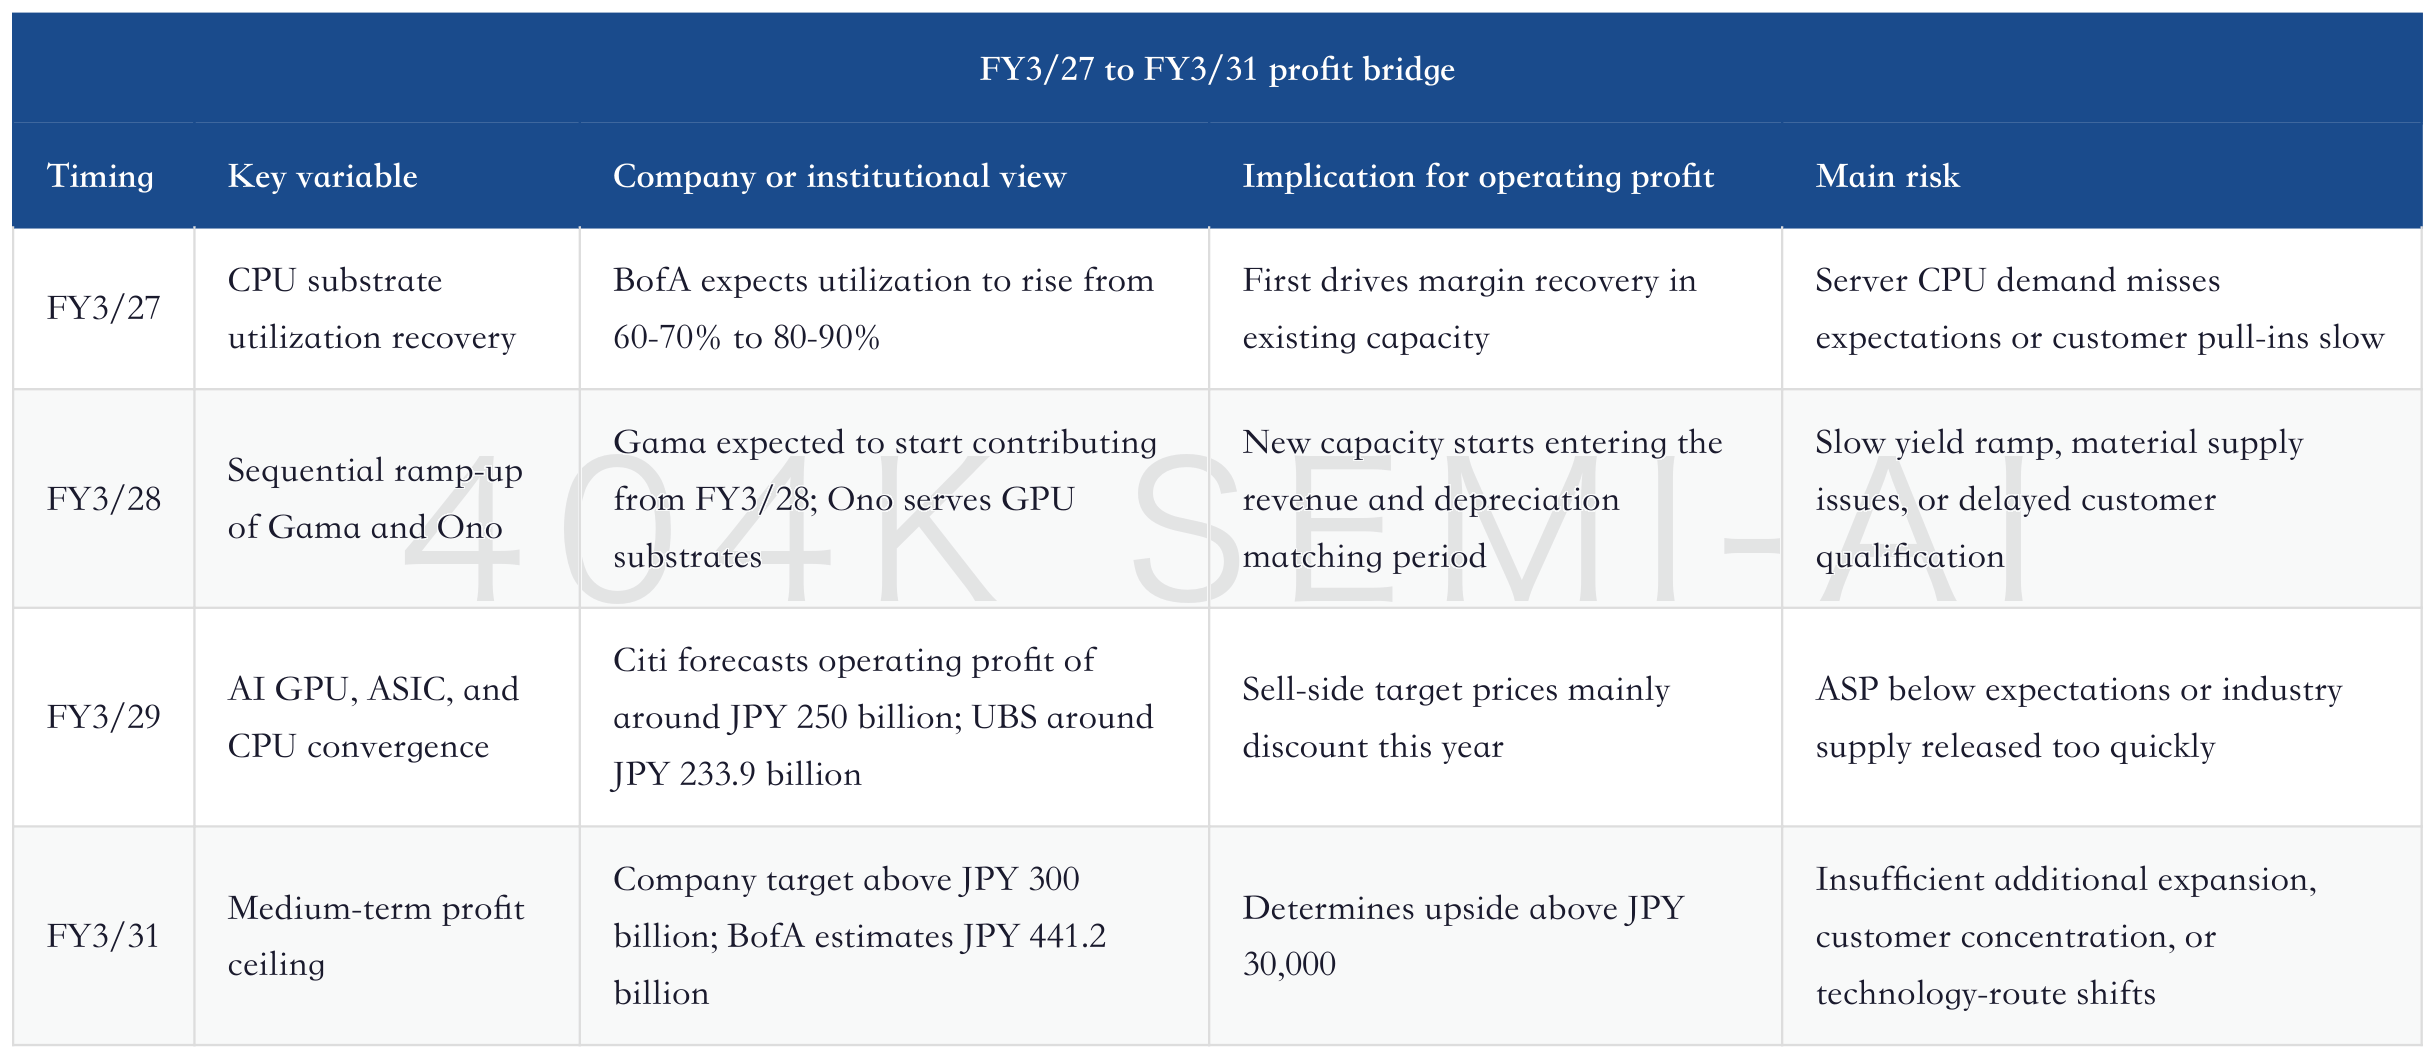
This profit bridge explains why sell-side numbers differ so much despite the same bullish direction. Citi’s FY3/29 operating profit estimate is around JPY 250 billion, BofA already sees FY3/28 at JPY 162.5 billion, UBS sees FY3/29 at JPY 233.9 billion, and Macquarie estimates FY3/29 EBIT at around JPY 231.2 billion. All appear to be revising upward, but the differences lie in who assigns more revenue to silicon bridges, who assumes ASP increases last longer, and who views CPU recovery as more stable. The more aggressive the assumptions on these variables, the higher the target price.
The most aggressive part of BofA’s model is that it pushes FY3/31 operating profit to JPY 441.2 billion and derives valuation from FY3/31 EPS of around JPY 1,076. In its logic, silicon bridges alone could bring substantial revenue, while the company’s medium-term target language on CPU customer revenue share may be conservative.
If silicon bridge revenue materializes and traditional CPU substrates do not shrink materially, the company’s JPY 800 billion electronics sales target may not be the ceiling. This is the core reason BofA is more optimistic than the company target.
Citi’s logic is more industry- and pricing-oriented. It believes AI server unit growth can approach a 30% CAGR from CY2026 to CY2028, above its previous assumption of around 20%. At the same time, GPU, ASIC, server CPU, and PC-related substrates all have greater potential for price increases. Citi has also shifted its target price benchmark to FY3/29, showing that it is not only focused on near-term FY3/27 earnings, but is pricing the current share price based on the future high-end mix and industry valuation expansion.
Macquarie’s focus is EMIB-T. It believes Intel-related EMIB-T demand is increasing and that Ibiden may be the main supplier of integrated EMIB-T board components. If this view proves correct, Ibiden would not merely be a GPU substrate supplier in the Nvidia chain; it would also gain broader opportunities in AI ASICs, CPUs, and advanced interconnect routes. The risk is that route judgment is inherently uncertain: if advanced packaging routes shift, other suppliers catch up, or customer allocations change internally, the valuation premium from EMIB-T needs to be discounted.
The profit model ultimately has to return to cash flow. A JPY 500 billion investment program is large, and if borne solely by the company, the market would worry about the balance sheet and depreciation pressure. But the official Q&A; mentioned that customer agreements and prepayments can support investment, and that there is currently no additional financing plan. This detail is critical: customer capital involvement means higher order visibility, and also means expansion is not a blind attempt to grab share, but construction around confirmed high-end demand. As long as this point remains intact, capex should not simply be viewed as a burden.
6. Company Ranking: Why Ibiden Should Not Be Equated Simply with Unimicron, Nan Ya PCB, Kinsus, or Samsung Electro-Mechanics
The ABF industry re-rating is not a story about Ibiden alone. Unimicron, Nan Ya PCB, Kinsus, Samsung Electro-Mechanics, and Ibiden are all benefiting, and tight supply and demand for high-end substrates will also lift valuation across the sector. But from an investment perspective, the company ranking must be made clear; otherwise, “the industry is good” can easily be misread as “all companies are equally good.” The real comparison is customer position, product difficulty, expansion certainty, pricing mechanism, and the degree to which valuation can be delivered.
Ibiden’s relative advantage lies in high-end customers and technical positioning. It has a stronger position in high-end substrates for AI GPUs, AI ASICs, server CPUs, and switch chips, and official materials also emphasize that it maintains a top-tier share in SAP demand. Compared with some Taiwanese companies, Ibiden looks more like a scarce capacity supplier in the high-end AI packaging chain. Compared with Samsung Electro-Mechanics, it is more focused on package substrates themselves and is less affected by MLCC and other business cycles.
But these advantages also bring constraints. First, Ibiden has higher customer concentration, and the order cadence of its largest GPU, CPU, and ASIC customers will strongly affect profit. Second, capacity expansion in Japan is affected by labor, construction cycles, and material coordination. The official Q&A; also mentioned that further expansion beyond existing plans before FY2028 would be constrained by labor and delivery cycles. Third, the share price has already undergone a major re-rating, leaving a smaller valuation margin of safety than some companies that have not yet fully reflected the AI cycle.
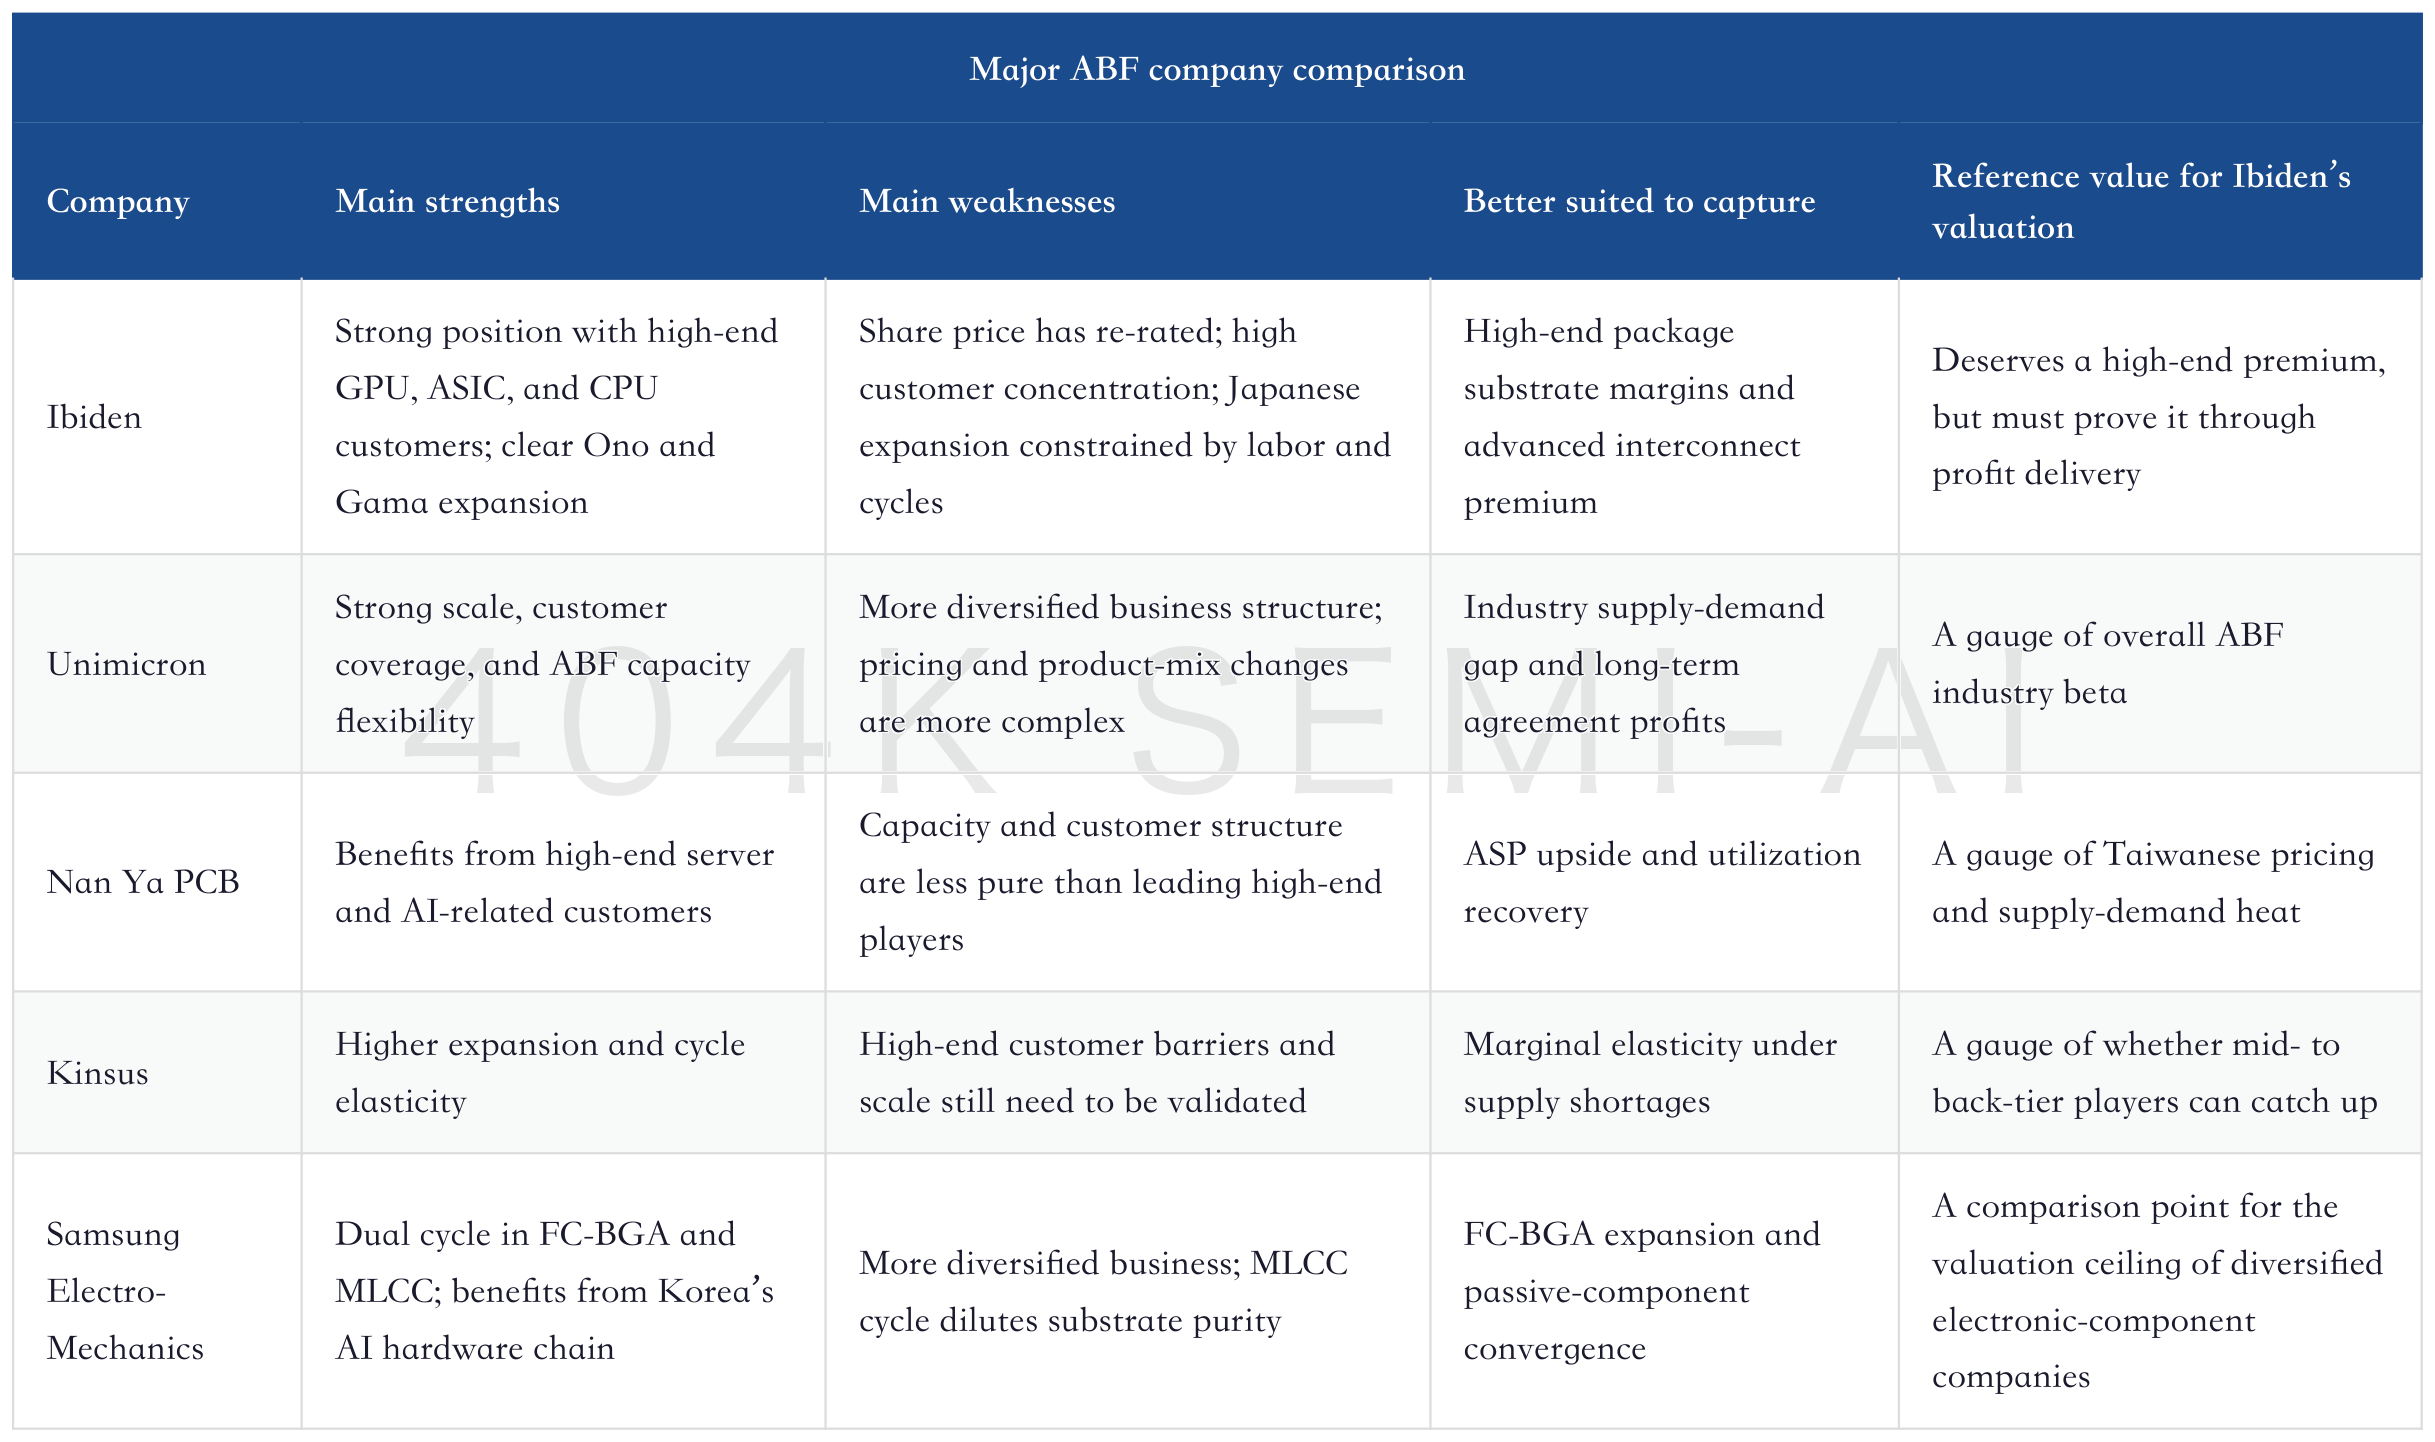
This comparison gives a clearer ranking: if investors want the purest exposure to the high-end AI ABF bottleneck, Ibiden ranks first; if they want industry diffusion and valuation repair, Unimicron, Nan Ya PCB, and Kinsus may have higher beta; if they want diversified exposure to Korea’s AI hardware chain, Samsung Electro-Mechanics is more like an FC-BGA and MLCC convergence asset. Ibiden is not the best on every dimension, but it is the company most likely to receive a valuation premium across the three dimensions of high-end customers, advanced interconnects, and customer funding.
Peer comparison has another important use: helping determine whether Ibiden’s valuation is overheated. If Taiwanese supplier pricing continues to rise, industry long-term agreements strengthen, and T-Glass remains tight, Ibiden’s high valuation becomes easier to accept. If Taiwanese capacity expansion and pricing begin to loosen, or if customers allocate more orders to second and third suppliers, Ibiden’s premium will be reassessed. It is not a stock rising independently of the industry; it is the most front-end, most expensive asset in the industry supply-demand cycle, and also the one that most needs to prove itself.
7. Valuation Framework: ¥30,000 Is Neither the Endpoint Nor a Cheap Price
The hardest part of Ibiden today is not judging whether the company is good, but judging what price is reasonable for that quality. Citi’s ¥30,000, BofA’s ¥29,800, and UBS’s bull-case ¥30,100 are not directionally inconsistent. Together, they point to one fact: if operating profit continues to be revised up after FY3/29, the market is willing to assign a higher valuation to the leader in high-end ABF substrates. But they also point to another fact: this is no longer a cheap phase, and every further move up will require more evidence.
Valuation can be split into three scenarios. In the conservative scenario, FY3/31 operating profit is only slightly above ¥300 billion; the Gama and Ono ramps proceed in line with the medium-term plan but without additional upward revisions; and industry ASPs stabilize after FY3/28. In the neutral scenario, FY3/29 operating profit approaches ¥230-250 billion, FY3/31 reaches the upper end of the company’s target range or slightly above it, and valuation lands near the Citi and BofA target prices. In the optimistic scenario, silicon-bridge revenue, AI ASIC demand, and additional capacity expansion jointly push FY3/31 operating profit close to BofA’s ¥441.2 billion model, giving the share price a chance to move beyond ¥30,000 and seek a new anchor.
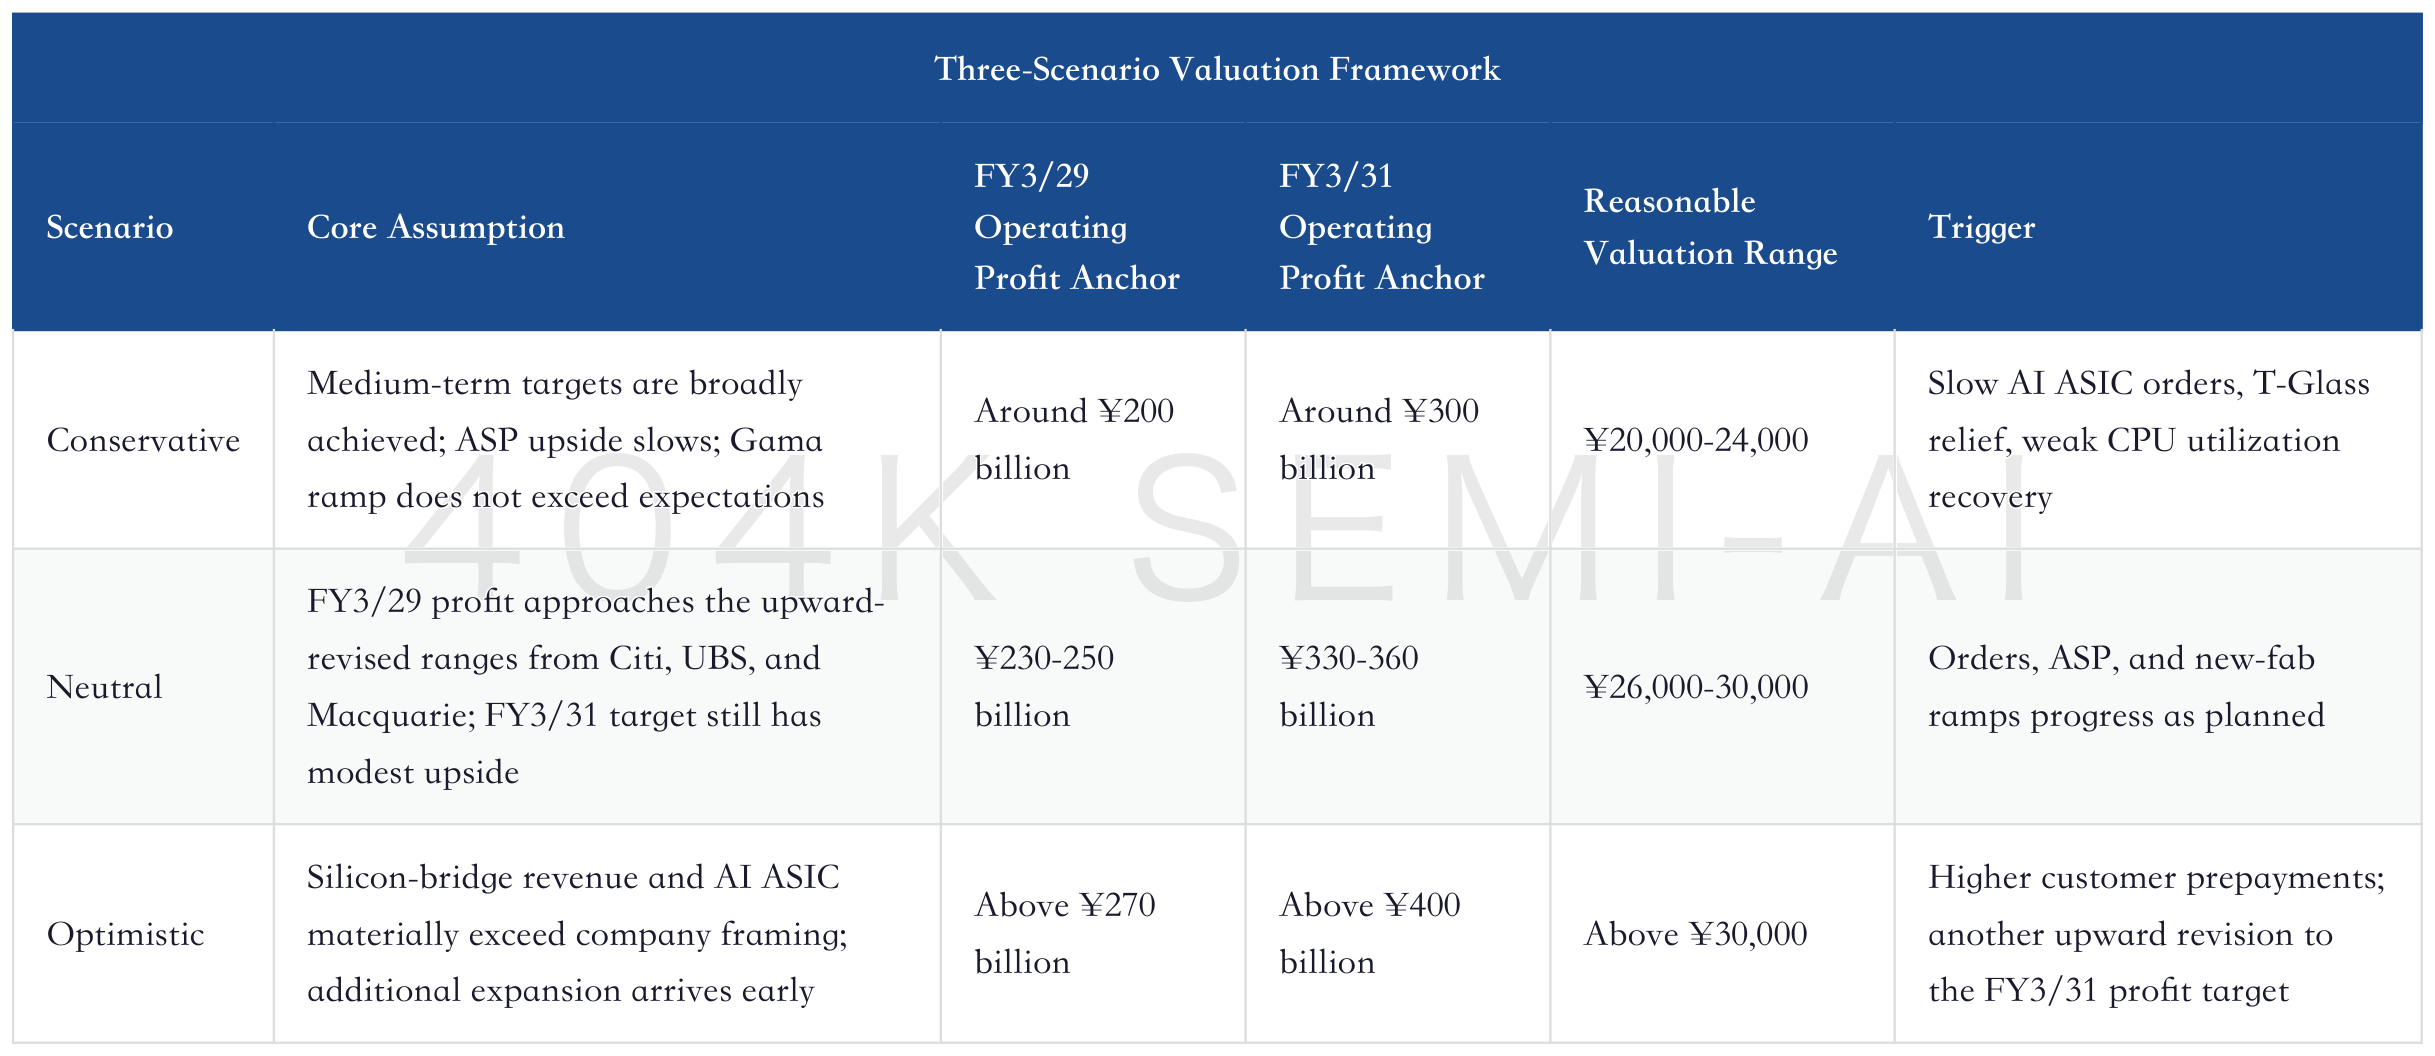
Among these three scenarios, the neutral scenario deserves the most attention. Current market pricing is already roughly in neutral-to-optimistic territory, not in the conservative scenario. In other words, investors buying here are not buying “the company is undervalued”; they are buying “continued evidence of upward revisions over the next few quarters.” The trading rhythm for this type of stock is usually not indiscriminate chasing, but checking whether the evidence has truly deteriorated when the market questions orders, ASP, capacity, or profit.
Valuation multiples also need to be viewed in the context of the cycle. Citi lowered its risk premium from 5% to 3%, effectively acknowledging that the risk profile of AI high-end substrate assets has declined. BofA’s use of 50x FY3/29 EPS also assigns greater certainty to forward earnings. But if the profit is merely cyclical upside, 50x forward EPS would look aggressive. Only if Ibiden is viewed as a bottleneck asset in advanced packaging do high forward multiples make sense. The key to the valuation logic is not the multiple itself, but whether the asset profile can shift from cyclical material to infrastructure access.
There is one further detail: the company’s current market cap has already discounted a lot of good news. Citi’s target price implied about 16.7% upside when its report was published, while BofA’s target implied about 22.2% upside. That is not small, but compared with the previous rally, it is no longer an “extremely thick odds” setup.
Therefore, the position strategy should look more like a high-quality growth cyclical: do not miss it entirely just because it is expensive, but do not ignore drawdown risk just because the highest target price looks attractive.
8. Technology Roadmap: EMIB-T, Silicon Bridges, and Large Packages Determine How Far the Valuation Premium Can Go
If Ibiden is viewed only as an ABF supplier, ¥30,000 looks aggressive. If it is viewed as a supplier of advanced interconnect and silicon-bridge-related packaging substrates, the valuation premium becomes easier to understand. One core reason Macquarie raised its target price sharply to ¥26,800 was increased EMIB-T demand and its view that Ibiden occupies an important position in the relevant substrate supply chain. BofA places more emphasis on the upside potential of future silicon-bridge substrate revenue from Gama.
The commonality between EMIB-T and silicon bridges is that both serve more complex advanced packaging. AI chips are no longer just a single large die mounted on a substrate. They require compute dies, HBM, I/O, bridge structures, and packaging substrates to work together. Silicon bridges or embedded bridge solutions can improve interconnect efficiency, but they also raise the difficulty of substrate design and manufacturing. If Ibiden can maintain a primary supply-chain position in these roadmaps, per-unit value and customer stickiness will be significantly higher than in ordinary ABF.
One statement in the official Q&A; is worth noting: competition in interconnect technology is relatively stable; launch share is close to 100%, then may decline by 20-30% over the following 3-6 months; but in high-difficulty backside interconnect for silicon bridges, the company believes it will still have an advantage through FY2030. This should not be interpreted simply as “share never falls.” A more accurate reading is that Ibiden may take an extremely high share during the launch phase, and subsequent multi-supplier qualification will dilute that share, but the technical difficulty should allow it to maintain an advantage in high-end roadmaps.
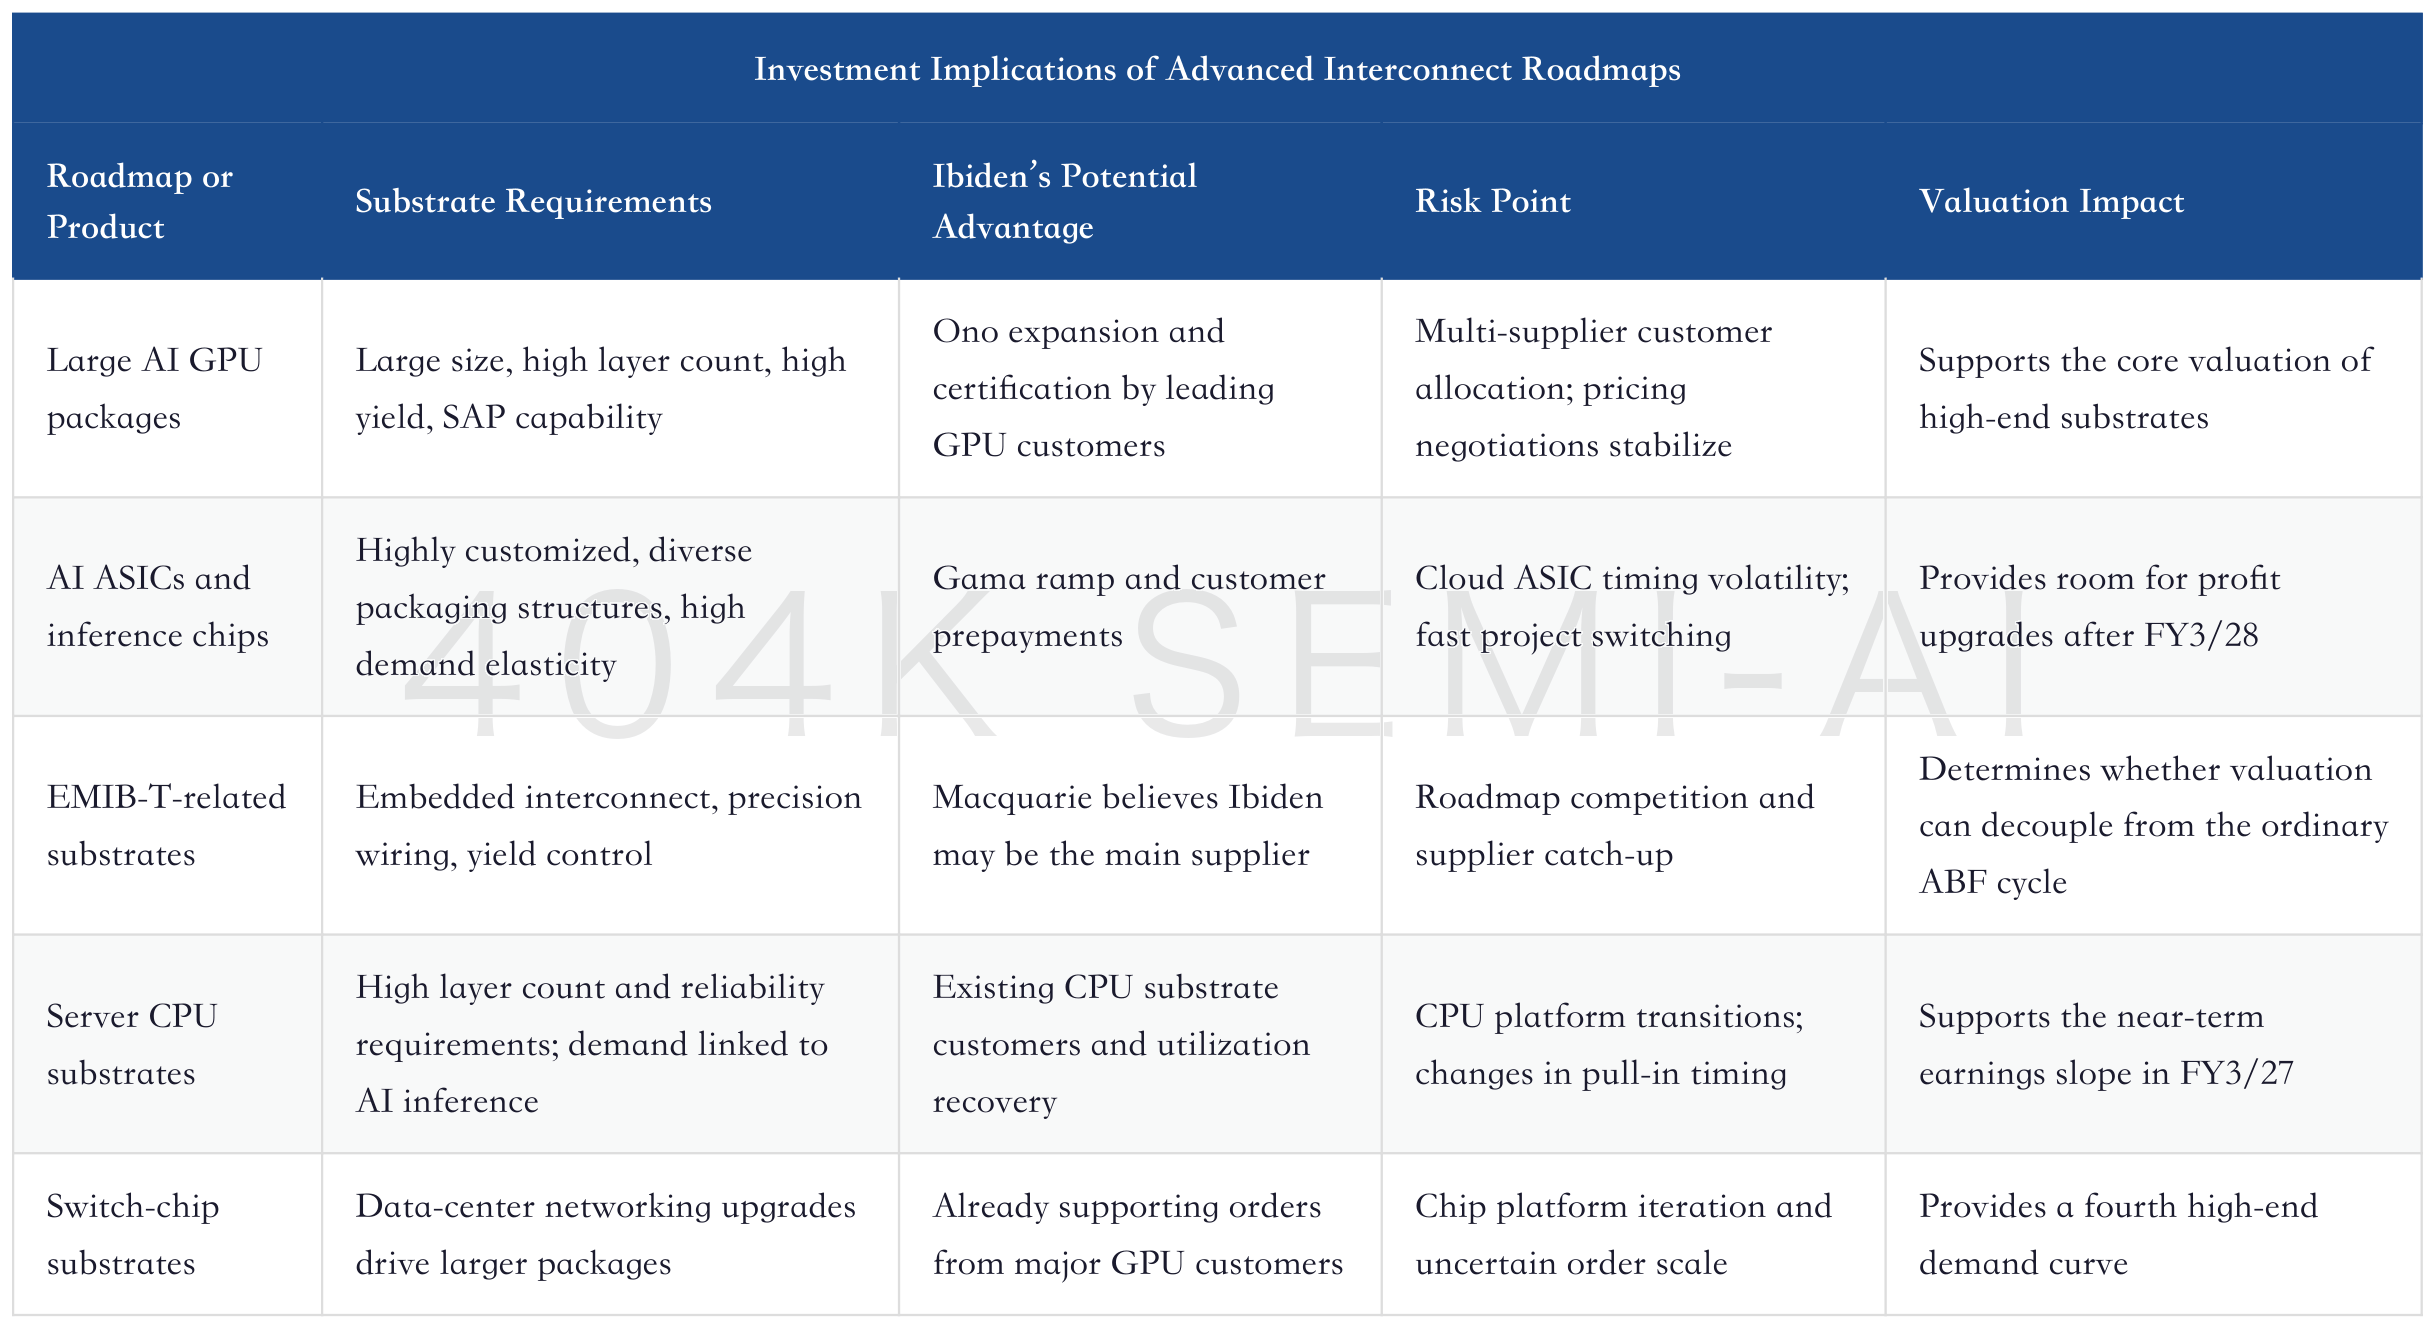
This table shows that Ibiden’s investment value is not confined to a single product line. GPUs are the main line the market understands most easily. ASICs and EMIB-T provide valuation upside elasticity. CPU recovery is a near-term profit bridge. Switch chips are an incremental driver that is easy to underestimate. As long as these four lines operate at the same time, Ibiden is no longer a single-customer, single-product, single-cycle stock.
The risk also comes from here. Advanced packaging roadmaps are not static. If glass substrates, CoWoP, alternative bridge structures, or customers’ in-house packaging roadmaps mature faster, part of ABF demand may be reallocated. Morgan Stanley’s industry report lists CoWoP replacing ABF as a potential risk. For now, this is not the main short-term risk, because high-end customers care more about mass production, validation, and on-time delivery. But if the technology roadmap changes after FY2028, the long-term valuation will need to be recalculated.
