
Hygon Information Deep Dive: Bernstein TP Rmb450, Morgan Stanley Sees Rmb480. Can the DCU/GPU Business Push Hygon from a CPU Company into a Domestic Compute Platform Company?
目录
Too Long; Didn’t Read
I. What Exactly Does Hygon Sell: Not a Single CPU, but an x86 Migration Path
II. From Old Asset to New Asset: From IT Application Innovation CPU Supplier to Domestic Compute Platform
III. Why Revisit CPUs Now: Agentic AI Brings CPUs Back to the Foreground
IV. C86-G5: The Key Product Validation Point for Hygon’s Valuation
V. The DCU Second Curve: Can Hygon Move from a CPU Company to a Platform Company?
VI. Financial Model: Revenue Elasticity Has Emerged; Profit Elasticity Is Still Being Tested
VII. Customers and Ecosystem: Sugon Is the Entry Point, and Also a Concentration Risk
VIII. Horizontal Ranking: Hygon Is Not the Strongest AI Chip, but May Be the Scarcest CPU+DCU Combination
IX. Supply Chain and Software Ecosystem: The Real Moat Is Not One Chip Specification
10. Valuation: The Real Disagreement Behind RMB 450, RMB 480, RMB 680, and RMB 200
11. Core Model: Four Variables Decide Whether Hygon Can Move from “High Valuation” to “High Quality”
12. Risks: Hygon’s Biggest Risk Is Not Demand, but the Delivery Path
13. Tracking Checklist for the Next Four Quarters
14. Conclusion: Hygon Is Not a Cheap Stock, but It Is One of the Few Domestic Compute Companies That Can Address Both CPU and GPU
XV. What Really Needs to Be Verified Is Not Domestic Substitution, but Platform Repurchasing
XVI. Data Scope and Sources
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Bernstein assigns Hygon Information a Rmb450 target price, while Morgan Stanley assigns Rmb480. Both institutions frame Hygon as a CPU + DCU/GPU compute platform. The key is not just domestic CPU substitution, but whether C86-G5 can expand into CSP/AIDC customers, and whether DCU/GPU can move the company from a CPU asset into a domestic compute platform.
Too Long; Didn’t Read
Both institutions are re-rating Hygon’s platform attributes. Bernstein gives Hygon Information a Rmb450 target price; Morgan Stanley gives Rmb480. The core argument is not simply domestic substitution. Bernstein focuses more on expansion of China’s x86 server CPU market and Hygon’s share gains, while Morgan Stanley emphasizes the revenue mix shift after DCU/GPU volume ramps. This raises the market’s requirement for validation of C86-G5 and recurring DCU orders.
C86-G5 is the key product variable that determines whether Hygon moves from “able to substitute” to “able to expand.” G4 has already brought core count, DDR5, and PCIe 5.0 to a usable stage. The key for G5 is 128 cores, 512 threads, 16-channel DDR5, and CXL 2.0. If mass production timing and software adaptation are delivered, it can cover more inference, database, virtualization, and cloud-native scenarios. If G5 is delayed, Hygon can still benefit from IT application innovation, but valuation will fall back to a policy substitution framework.
DCU determines whether Hygon has a second growth curve. Morgan Stanley expects Hygon’s total revenue CAGR to be 47% from 2025 to 2028, with CPU revenue CAGR at 31% and DCU/GPU revenue CAGR at 69%. By 2027, CPU and GPU revenue are expected to be close to 50:50; by 2028, GPU scale is expected to exceed CPU. If this assumption holds, Hygon will no longer be just a CPU company, but a domestic CPU + GPU compute platform company.
The core income statement tension is whether gross margin decline or operating leverage improvement is stronger. In Morgan Stanley’s model, Hygon’s revenue rises from Rmb14.377bn in 2025 to Rmb45.342bn in 2028, while ModelWare net profit rises from Rmb2.545bn to Rmb12.308bn. But gross margin falls from 57.8% to 53.3%, due to a higher DCU mix and intensifying domestic AI chip competition. The real question is whether the R&D; expense ratio can decline from 28.8% to 20.7%, leaving scale benefits for shareholders.
Valuation divergence comes from three worldviews. The base case is continued CPU substitution and DCU volume ramp in commercial AI projects, with Bernstein at a Rmb450 target price and Morgan Stanley at Rmb480. The bull case requires 2025-2028 revenue CAGR above 60%, upward revision to GPU share, and gross margin sustained above 60%. The bear case is slower domestic AI capex, discontinuous large DCU orders, and gross margin falling below 40%. Whether Hygon is expensive depends on which world the market believes in.
Over the next four quarters, watch five numbers. First, whether C86-G5 enters customer sampling and small-batch introduction. Second, whether large DCU customer orders expand from government projects to internet companies and carriers. Third, whether the top-five customer revenue share can decline from 90%. Fourth, whether quarterly gross margin can stabilize near 55%. Fifth, whether 2026 revenue can approach Rmb22.420bn. Unless these five numbers are delivered together, Hygon is not yet “China’s Nvidia,” but a domestic compute platform still moving through product validation.
I. What Exactly Does Hygon Sell: Not a Single CPU, but an x86 Migration Path
Hygon Information (688041.SH) is most easily misread as a “domestic substitution CPU company.” That description is not wrong, but it is too narrow. What Hygon really sells is a server compute path with low migration cost, policy compatibility, and the ability to bind with domestic accelerator cards.
A more accurate one-sentence profile: Hygon is a platform chip company that enters the domestic server ecosystem with x86-compatible CPUs, then uses DCUs to move customers from general-purpose computing toward AI computing. It does not sell consumer electronics chips, nor a single AI accelerator card. It sells the hardest-to-replace foundation in government, enterprise, and cloud data centers: the compatibility relationship among CPU sockets, server motherboards, operating systems, and accelerator cards.
The company’s strongest points are threefold. First, it has an x86 migration advantage. When customers switch from Intel/AMD systems to Hygon, the software reconstruction burden is lower than moving to a completely new instruction set. Second, it has IT application innovation certifications and a government-enterprise customer base, providing the foundation for CPU revenue. Third, it has DCU and full-system ecosystems, allowing it to convert the CPU entry point into accelerator card orders when domestic AI compute is in shortage.
Its weakest points are also threefold. First, advanced process nodes, EDA, and high-end IP remain externally constrained, so technology iteration cannot be extrapolated linearly. Second, the DCU software ecosystem still needs repeated refinement through customer projects and cannot directly match the maturity of Nvidia CUDA. Third, customer concentration is too high. Revenue growth is strong, but the company has not fully proven a replicable, broad customer base.
Therefore, what matters most for Hygon is not the short-cycle logic of “domestic CPU price increases,” but three more specific questions: whether C86-G5 can move x86 CPUs from IT application innovation into commercial cloud; whether DCU can shift the revenue structure from a single engine to dual engines; and whether more CSP, carrier, and industry cloud customers can emerge beyond the Sugon ecosystem. As long as these three questions remain unanswered, Hygon is still in the middle of a re-rating process.
The most important thing to watch in the next earnings report is not a single quarterly revenue figure, but revenue quality. If high revenue growth comes with stable gross margin, the R&D; expense ratio starts to be diluted, and inventories and receivables do not build abnormally, it means high growth is entering the income statement. If revenue is driven by a few projects, gross margin declines, and cash flow lags, the market will first treat it as order delivery, not platform capability delivery.
A truly good Hygon earnings report should show four signals at the same time: a more diversified customer base, higher-end products, a lower expense ratio, and smoother cash flow. Seeing only one means the story is still in progress; seeing three or more means the asset attribute will truly change. Every quarterly report should be reviewed against these four signals, rather than only whether revenue growth looks impressive. This is the core issue, highly important, and must be watched closely.
The key difference between server CPUs and consumer CPUs is not brand awareness, but software ecosystem. In cloud providers, banks, telecom, energy, and government systems, operating systems, databases, middleware, virtualization, containers, application software, and operations tools are all built around instruction sets and platform validation. CPU replacement is not changing a hardware SKU, but migrating the entire software stack. If the performance gap is not unacceptably large, x86 compatibility itself is a commercial barrier.
This is also where Hygon differs from domestic CPU players such as Loongson, Phytium, and Kunpeng. Hygon’s foundation comes from earlier AMD Zen 1 licensing, after which it iterated the C86 series in the Chinese market. It does not have Intel’s or AMD’s global supply capability, nor the absolute performance of the most advanced process nodes. But it has a combination rarely seen in China’s server market: x86 compatibility, domestic certification, a government-enterprise customer base, the Sugon ecosystem, DCU accelerator cards, and a self-developed roadmap that is gradually moving beyond the original licensed architecture.
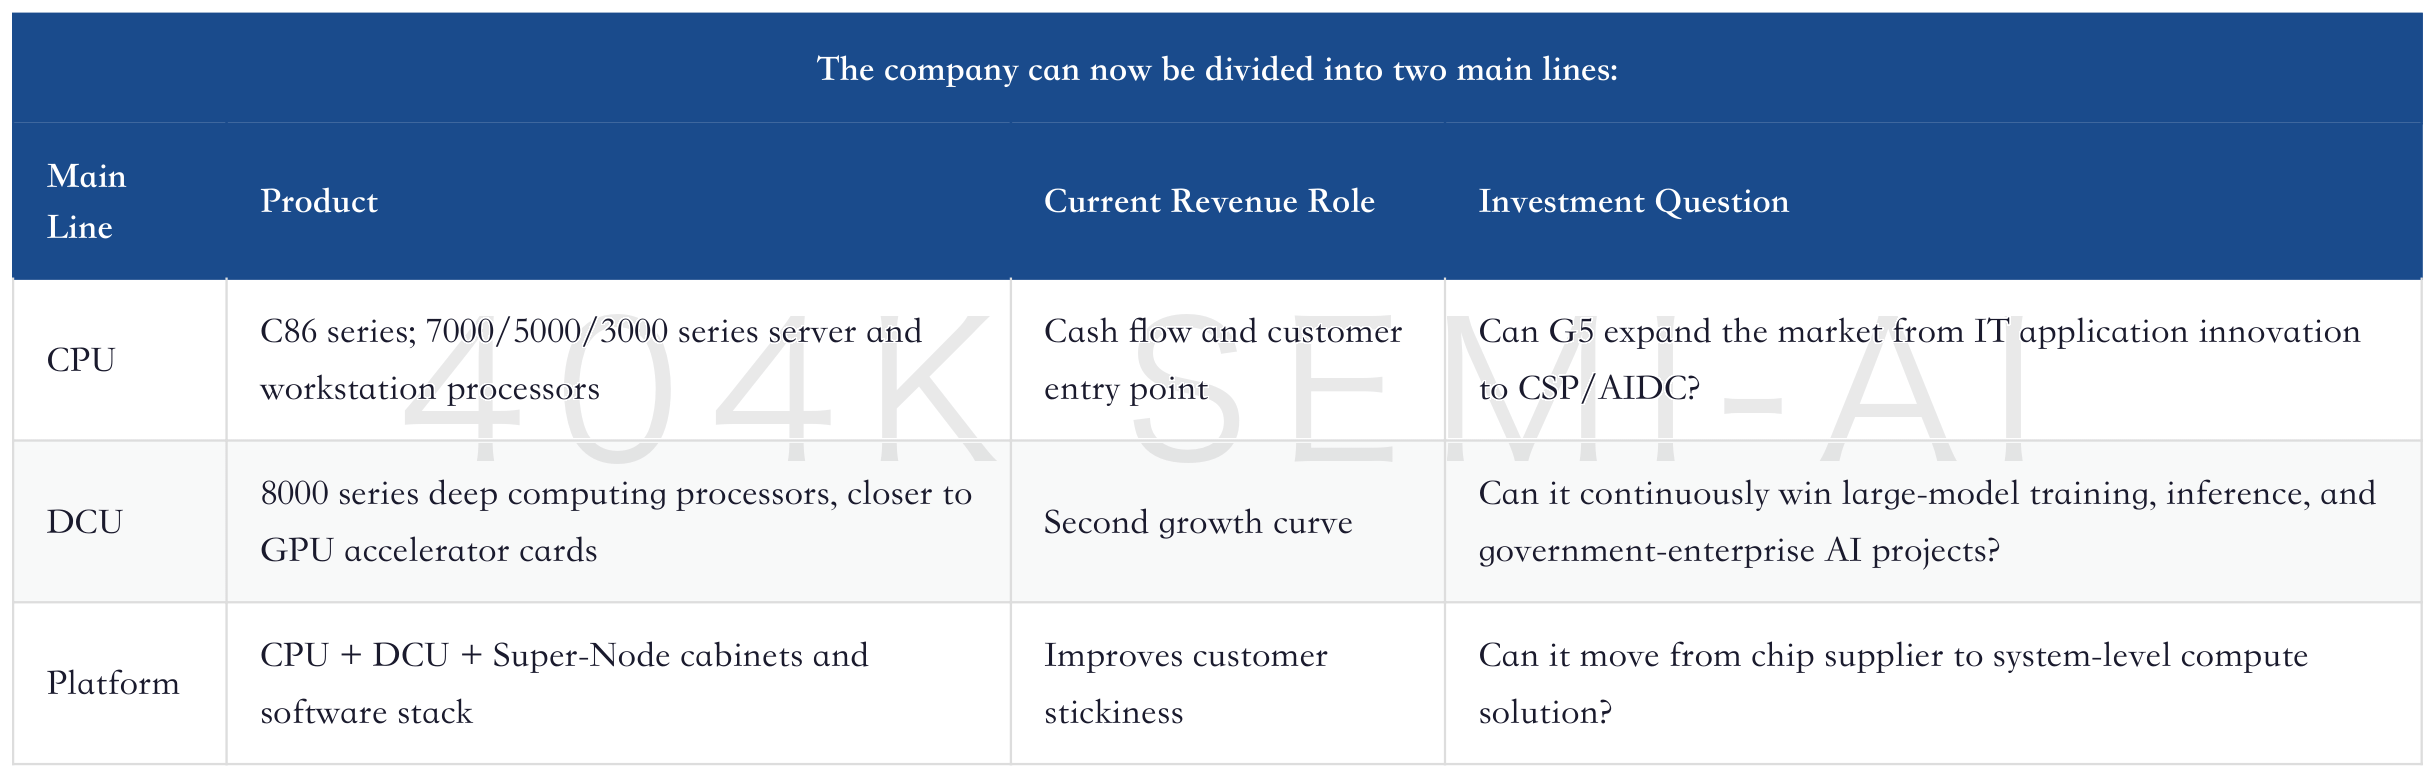
Hygon CPU’s revenue base comes from IT application innovation and key-industry servers. Morgan Stanley estimates that in the 2025 product revenue mix, the 7000 series CPU accounts for about 59%, the DCU 8000 series about 35%, and the 5000 and 3000 series about 3% each. This structure shows that Hygon is no longer a CPU-only company, but CPU remains the customer entry point and profit anchor.
The strategic significance of DCU lies in bundling. Viewed alone, Hygon’s DCU is not necessarily an absolute technology leader versus domestic AI chips such as Huawei Ascend, Cambricon, and Biren. But if a customer lacks both CPUs and AI accelerator cards, Hygon can package “CPU + DCU” to meet domestic compute requirements. This combination gives it stronger pricing power when AI chip supply is tight, and can bring CPU share from government procurement into cloud providers and AIDC projects.
The urgency for China to localize CPU and GPU supply is rising. CPUs and GPUs are at the heart of AI infrastructure, yet global supply is still dominated by companies such as Nvidia, AMD, and Intel. China’s AI deployment is driving strong demand for compute, but export restrictions on advanced chips are tightening supply.
The key point in this judgment is not that “more restrictions are better,” but that supply constraints change the procurement function. In the past, domestic CPU procurement was mostly driven by compliance and budgets. In the future, cloud provider and AIDC procurement will place more weight on delivery, performance, total cost of ownership, and software adaptation. If Hygon is only a compliance substitute, it is hard for valuation to support the current high multiple. If it becomes a “deliverable domestic x86 + DCU platform” in AI data centers, the valuation anchor will change.
The CPU Frenzy | From Supporting Role Back to Center Stage — A 40,000-Word Panoramic View of the New Compute Bottleneck in the AI Agent Era
II. From Old Asset to New Asset: From IT Application Innovation CPU Supplier to Domestic Compute Platform
Hygon’s first-layer asset attribute is that of an IT application innovation CPU supplier. The “2+8+N” substitution path in IT application innovation drives government, SOEs, and key industries to gradually replace software and hardware. CPU is the underlying compute entry point. Hygon’s special feature is that it is one of the few current domestic server CPU suppliers that can support migration within the x86 ecosystem, so customers do not need to reconstruct all applications onto a completely new instruction set at once.
The advantage of this asset layer is that demand has a floor; the disadvantage is that growth cadence is easily affected by budget cycles and project-based procurement. Historical tracking reports in 2024 and 2025 repeatedly showed one phenomenon: revenue grew rapidly, but margins did not improve linearly. Full-year 2024 revenue guidance implied about 52% YoY growth, and 4Q24 quarterly revenue rose about 44% YoY, but quarterly net margin declined significantly. In 4Q25, revenue was Rmb4.886bn, up 61.5% YoY; the midpoint of 1Q26 revenue guidance was about Rmb4.065bn, up 69% YoY, while margins remained pressured by R&D;, equity incentives, and project expenses.
This is not simply a bad thing. If Hygon only made mature IT application innovation CPUs, margins should be more stable. Margin pressure indicates the company is allocating resources to next-generation CPUs, DCUs, software stacks, and system-level solutions. The question is whether these investments can push the company’s asset attribute from “policy-driven CPU substitution” to “commercial compute platform.”
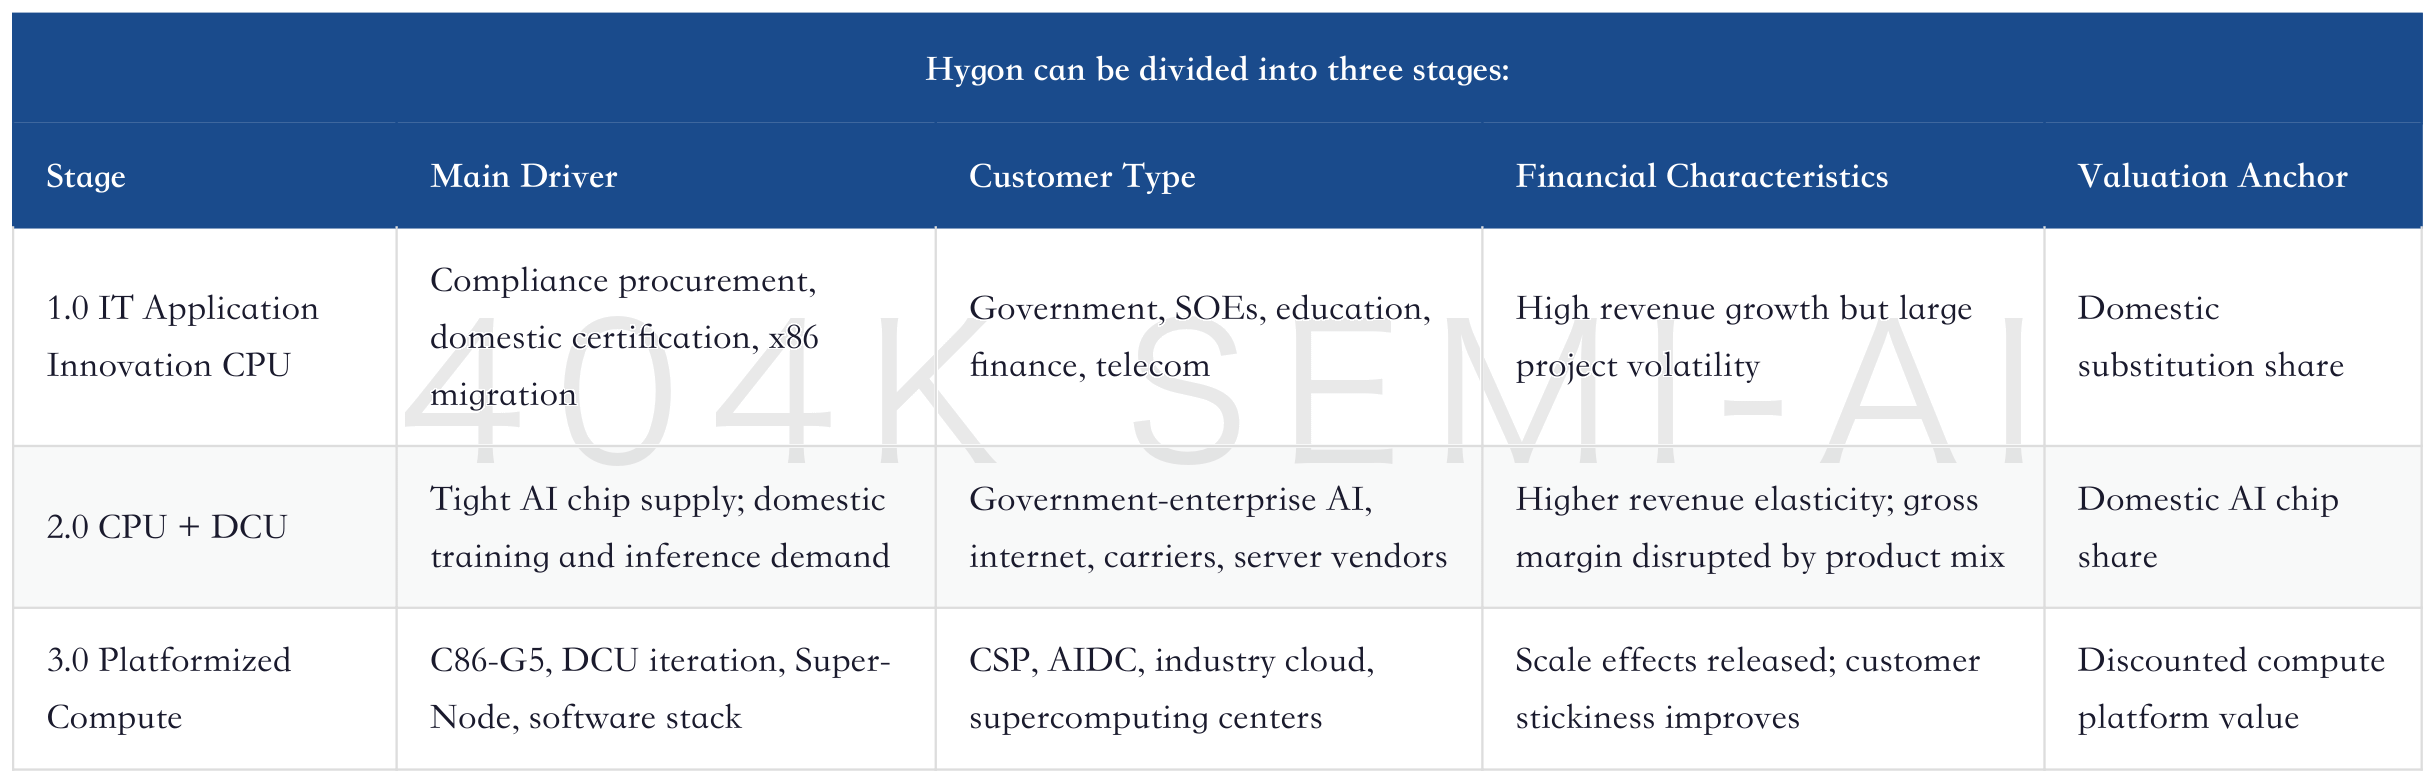
Hygon is now in a position where 1.0 has been delivered, 2.0 is ramping, and 3.0 still needs validation. The market is willing to assign a high valuation because it wants to buy 3.0 in advance. The market worries the valuation is too high because the financial statements are still mainly determined by 1.0 and the early stage of 2.0.
This state differs from many domestic semiconductor companies. Equipment, materials, PCB, or memory companies usually first see overseas supply chain cycles, then map them to domestic substitution. Hygon’s cycle is directly tied to the supply-demand gap in China’s compute infrastructure. The tighter overseas CPU and GPU supply becomes, the more the Chinese market needs local compute. But local advanced process nodes, EDA, software ecosystems, and major-customer validation will then become new bottlenecks.
CPU Returns to the Center of AI Inference Infrastructure
III. Why Revisit CPUs Now: Agentic AI Brings CPUs Back to the Foreground
Over the past two years, when the market discussed AI hardware, the focus was almost entirely on GPUs, HBM, advanced packaging, and optical modules. CPUs looked like a supporting role: every server needed them, but they lacked an exciting incremental story. Agentic AI changes that.
In multi-agent and complex reasoning workflows, GPUs handle matrix computation, while CPUs handle scheduling, retrieval, tool calling, data preprocessing, network I/O, task orchestration, container management, and system control. An AI agent is not just one model forward pass; it continuously calls models, databases, code interpreters, external tools, caches, and memory systems. The more complex the workflow, the heavier the CPU orchestration load.
Bernstein’s framework is more aggressive: global x86 server CPU TAM could rise from around USD 39 billion in 2025 to around USD 223 billion in 2030. The core assumption is that the CPU:GPU ratio gradually moves from roughly 1:8 today toward 1:1. Morgan Stanley’s framework is relatively more conservative, but it also expects China’s Agentic AI CPU TAM to reach USD 17 billion by 2030, representing about 21% of global demand.
There is no need to mechanically take the midpoint of these two figures. What matters is the direction: AI servers are no longer priced only by GPU count. CPU sockets, memory bandwidth, I/O, CXL, system orchestration, and host-side throughput are beginning to be repriced.
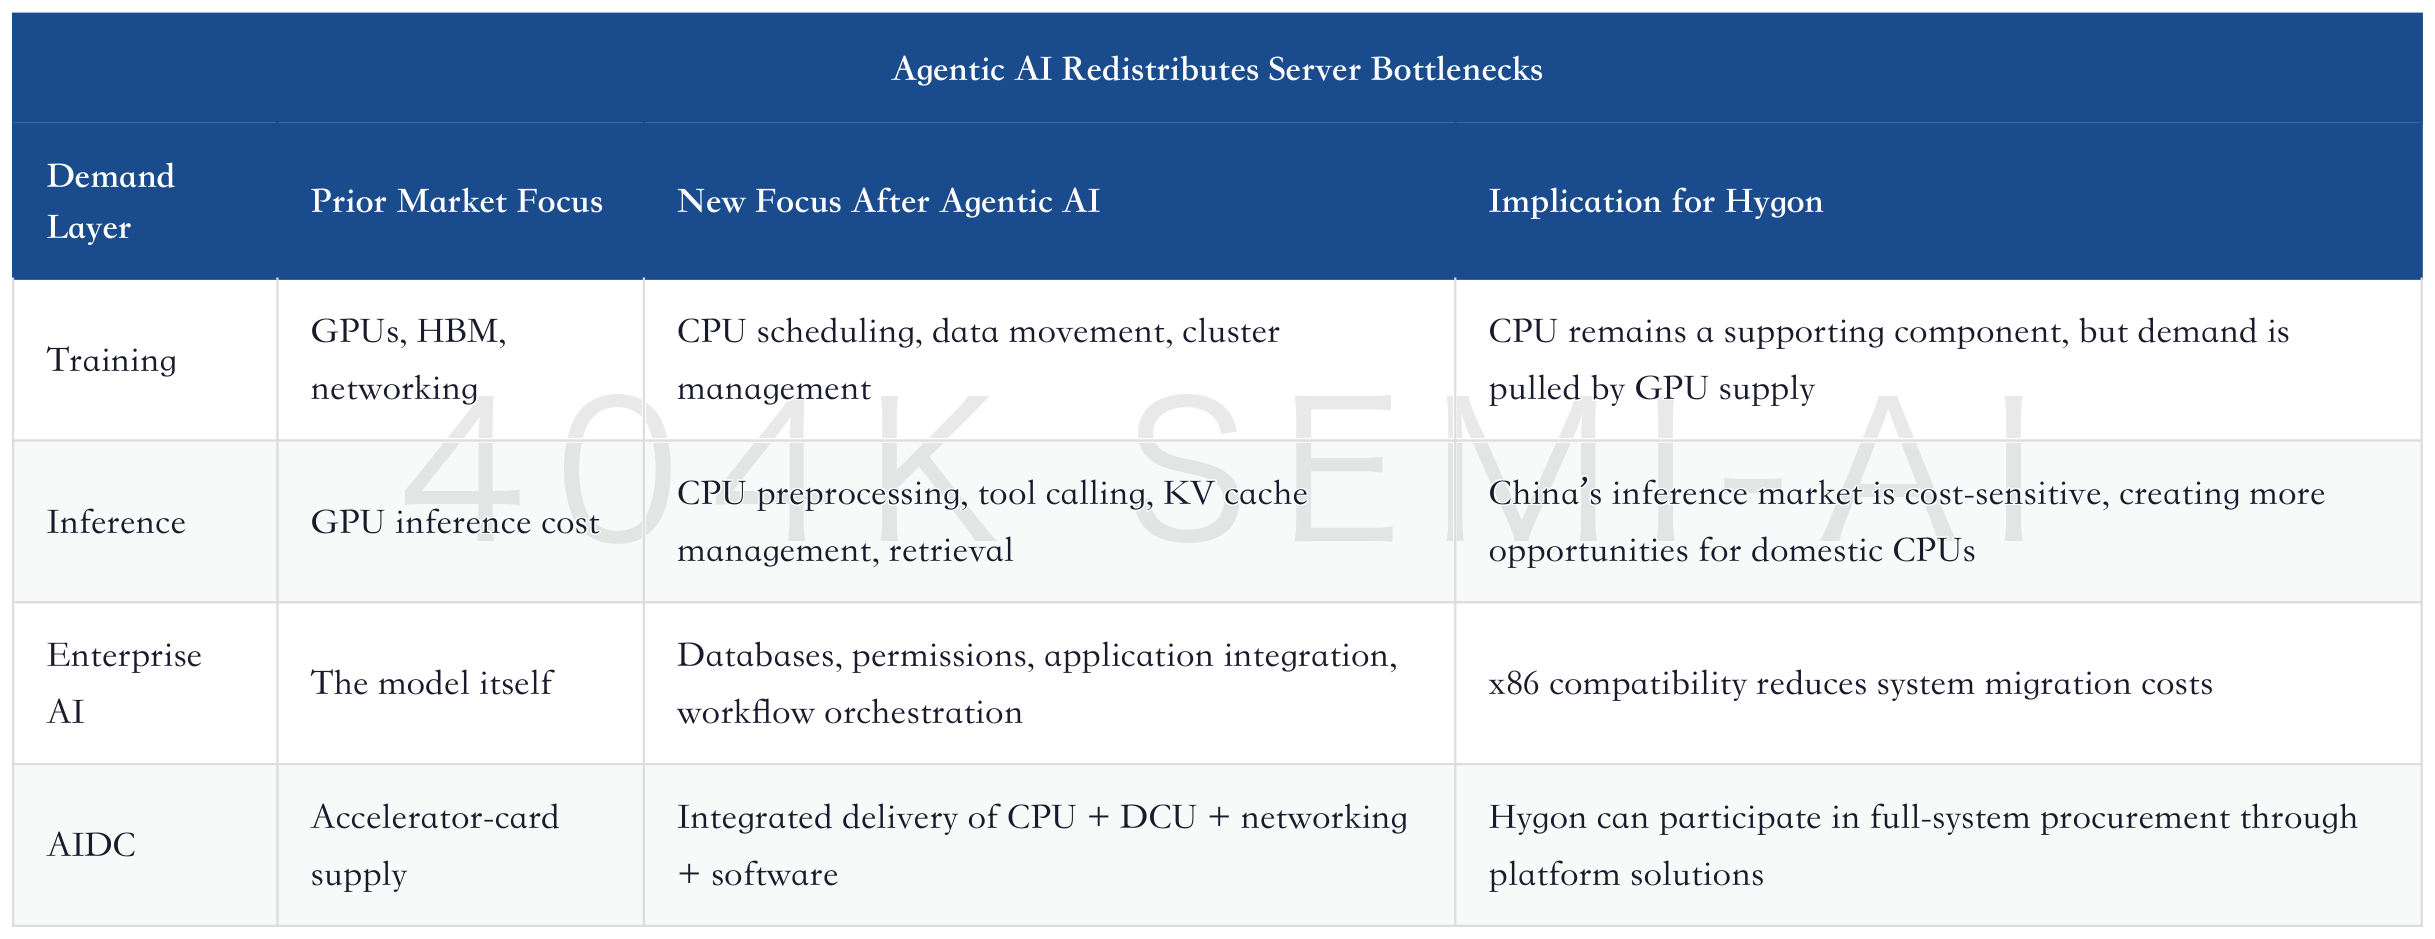
China has one additional variable: inference may commercialize faster than training. Training prioritizes peak performance and is more easily constrained by advanced GPUs and high-bandwidth interconnects; inference places more emphasis on cost, deployment scale, application adaptation, and data security. If Chinese enterprises allocate more AI budgets to vertical-scenario inference, CPU demand elasticity may be higher than in pure training scenarios.
China’s x86 server CPU total addressable market (TAM) is projected to grow significantly from USD 7 billion in 2025 to USD 27 billion by 2030. Despite the rapid expansion of the global market, China is expected to maintain a relatively stable share of approximately 25% to 27%. In terms of shipment volume, China’s server CPU demand is forecast to triple over the next five years.
Hygon’s opportunity is not only that China’s CPU TAM expands, but that it gains share within that TAM. Bernstein expects Hygon’s value share in China’s x86 server CPU market to rise from 19% in 2025 to 36% in 2030, and the self-sufficiency rate to increase from 23% in 2025 to 48% in 2030. If those assumptions hold, Hygon benefits from both market expansion and share gains.
AI CPU TAM Reassessment: USD 132 Billion in 2030 and Repricing AMD and Intel
IV. C86-G5: The Key Product Validation Point for Hygon’s Valuation
C86-G5 is the most important product variable in this report. It determines whether Hygon’s CPU can move from “permitted to procure” to “actively selected for procurement.”
Hygon’s earlier product generations had a clear evolution path. The first-generation Dhyana was the commercialization of AMD Zen1 licensing in 2018, using GlobalFoundries 14nm and establishing the foundation for x86 compatibility. The second and third generations were originally planned to use overseas 7nm capacity, but after the 2019 Entity List designation, Hygon was forced to iterate within China’s manufacturing capabilities. Through architecture, memory, and I/O improvements, the company achieved 30%-50% performance gains per generation. C86-G4 entered sales in 2024, with up to 64 cores and support for DDR5 and PCIe 5.0; Bernstein estimates its process is close to SMIC N+1.
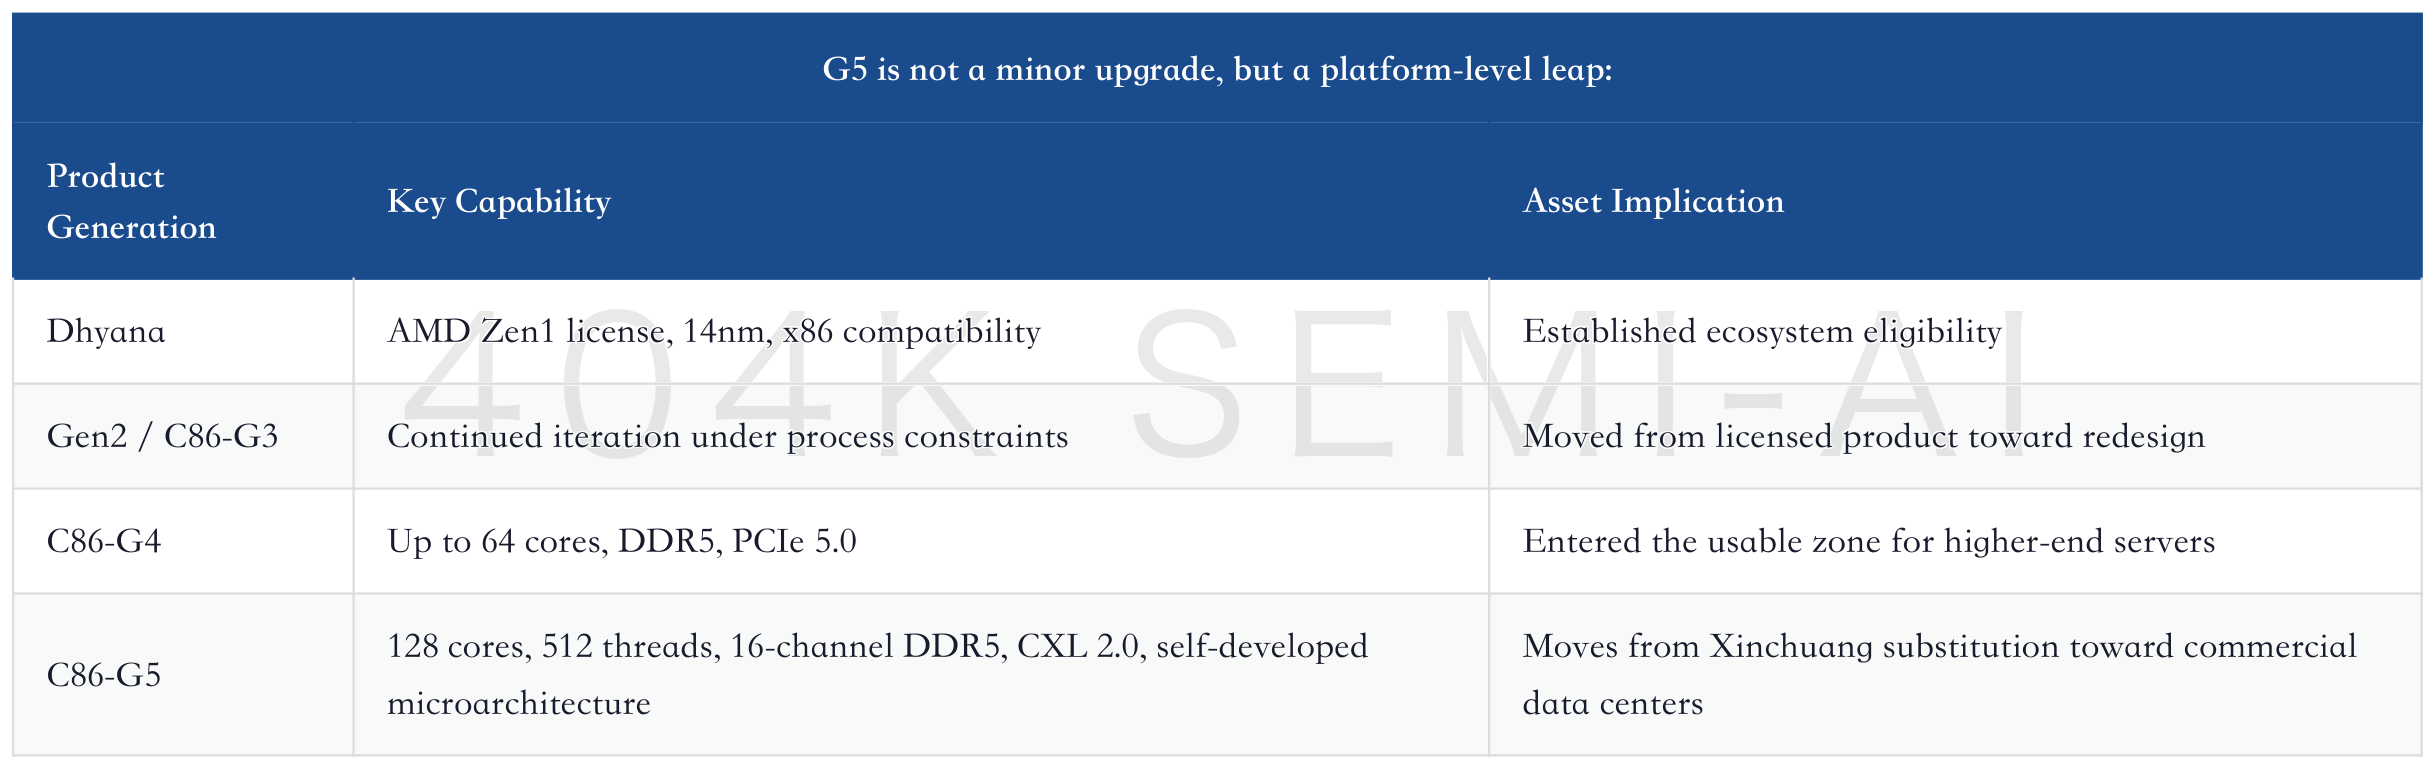
Why is G5 so important? Because cloud vendors and AIDC procurement follow a different logic from Xinchuang procurement. Xinchuang procurement focuses more on domestic compliance and ecosystem usability; commercial data centers focus on performance per watt, compute per rack, memory bandwidth, virtualization density, operations tools, deliverability, and total cost of ownership. Only after the performance gap narrows to a certain level will customers move Hygon from a “compliance backup” into a “cost and supply backup.”
G5’s feasibility mainly comes from three variables.
The first is chiplets. If 128 cores are built as one large die, yield and die-area pressure are too high. If multiple smaller compute dies are combined through packaging interconnects, core-count expansion is no longer completely constrained by advanced process nodes. AMD has already proven that chiplets are an effective path for scaling server CPU cores. Whether Hygon can replicate this engineering path is the first validation point for G5.
The second is self-developed microarchitecture. Hygon cannot rely on Zen1 licensing indefinitely. Bernstein emphasizes that G5 uses a fully self-developed microarchitecture, with targets including IPC improvement, SMT4 thread throughput, and stronger security features. If this view proves correct, Hygon’s technological independence will be stronger; if the specifications look good but real workload performance is insufficient, the market will again question its ability to iterate after moving beyond AMD’s legacy.
The third is memory and I/O. 16-channel DDR5 and CXL 2.0 are not marketing parameters; they are core to AI inference and database workloads. Agentic AI amplifies demand for memory, cache, retrieval, and multi-service orchestration. The CPU does not only run compute; it is also responsible for extensive memory access and device coordination. If G5 delivers on memory bandwidth and the CXL ecosystem, Hygon can move from single-CPU competition to full-platform competition.
The C86-G5 is Hygon’s most ambitious product and the centerpiece of its medium-term growth thesis. It represents a fundamental architectural inflection. Together, these specifications position C86-G5 to be broadly competitive with current available offerings from AMD and Intel nowadays.
Some discipline is needed here: “broadly competitive” in the report does not mean fully catching up with AMD EPYC and Intel Xeon. It is closer to “good enough in supply available to China, domestic certification, and specific workloads.” Hygon does not need to win every benchmark. As long as it can become substitutable in government and enterprise cloud, industry inference, databases, virtualization, and data-center host-side scenarios, it can unlock SAM.
The validation sequence for G5 is also clear: sample testing, customer adaptation, ecosystem certification, small-batch orders, quarterly revenue recognition, and gross-margin stability. If any link breaks, the market will cut the valuation multiple first, rather than wait for full confirmation in financial statements.
V. The DCU Second Curve: Can Hygon Move from a CPU Company to a Platform Company?
If we look only at CPUs, Hygon is a scarce domestic substitution company. If DCU scales, it may become a domestic compute-platform company.
DCU is Hygon’s term for GPU-like accelerator cards, mainly targeting AI training, inference, big-data processing, and scientific computing. Its ecosystem is not equivalent to CUDA, but Hygon has built a software stack including hipBLAS, hipRand, hipFFT, MIOpen, RCCL, OpenCL, the LLVM compiler, and the HIP interface. For customers, whether the hardware can be purchased is only the first step. Whether models, operators, frameworks, debugging tools, and cluster management can run determines whether orders are sustainable.
Morgan Stanley describes Hygon as a “CPU + GPU Compute Platform,” precisely because DCU is no longer just an ancillary business. Morgan Stanley expects:
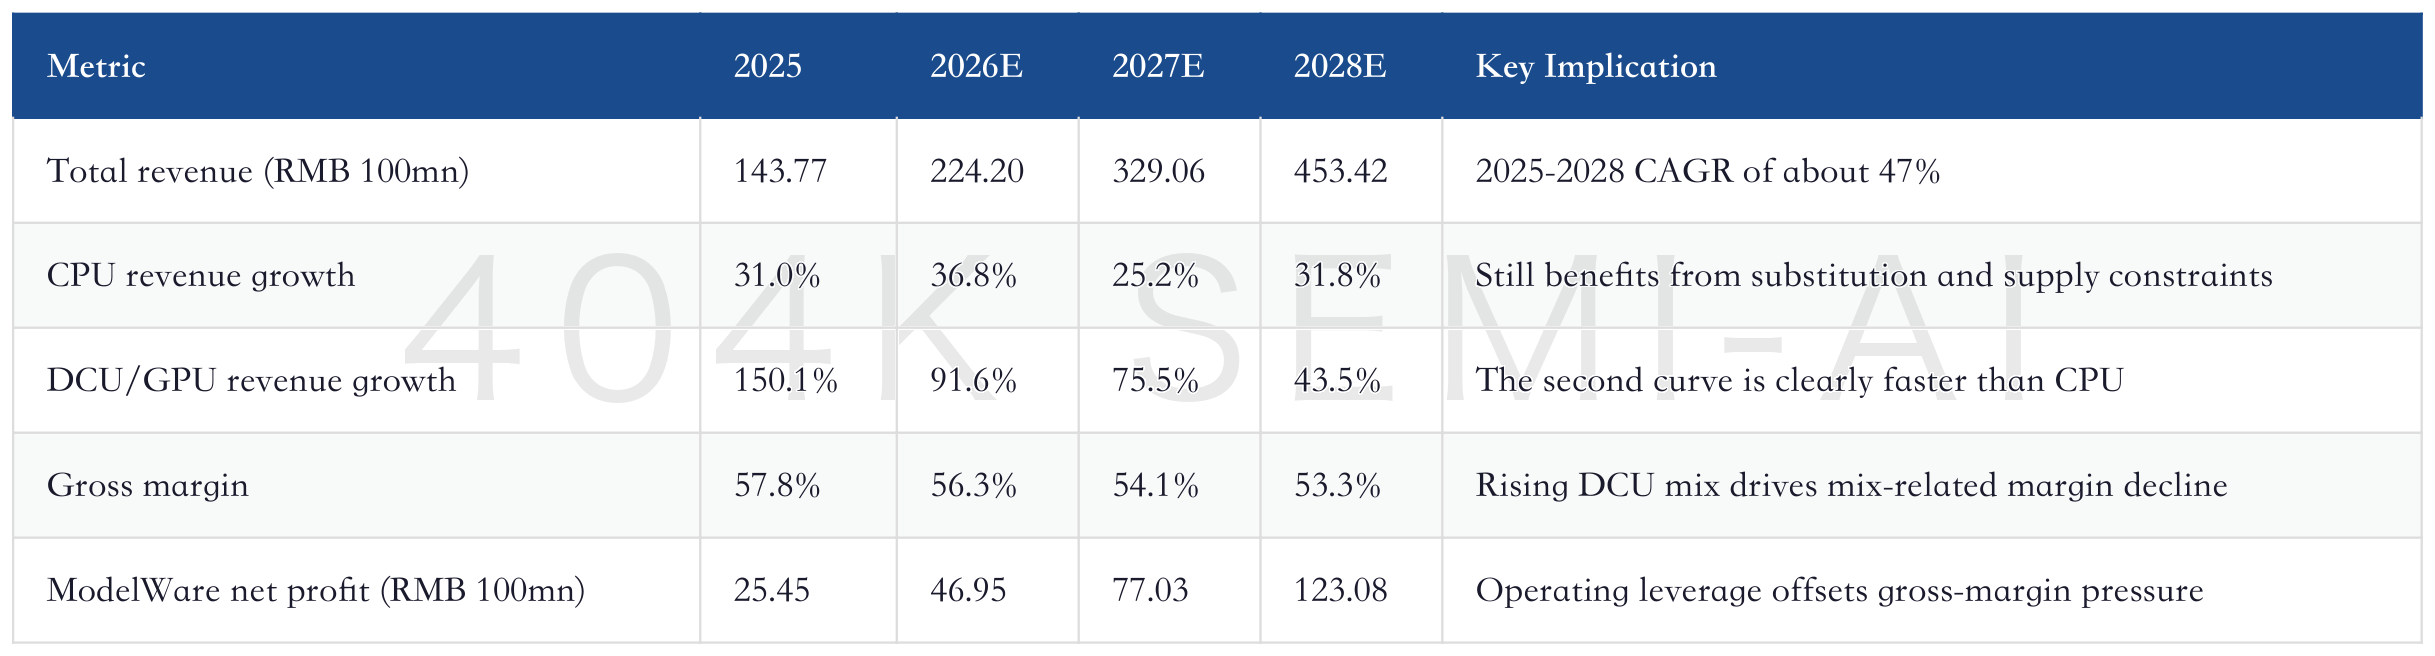
The most important part of this model is not 2028 revenue of RMB 45.3 billion, but the change in revenue mix between CPU and DCU. Morgan Stanley expects CPU and GPU revenue to be close to 50:50 in 2027, with GPU revenue exceeding CPU revenue in 2028. If this structure materializes, Hygon’s valuation cannot be viewed only through a CPU-company lens; if it does not, Hygon’s valuation will return to the framework of a high-growth domestic CPU company.
DCU has three layers of opportunity.
The first layer is domestic AI chip substitution. With overseas advanced GPU supply constrained, Chinese customers will continue looking for local training and inference chips. Huawei Ascend has the strongest ecosystem, and companies such as Cambricon are also competing for share. Hygon is not the leading single-card player. But Hygon can use its CPU entry point and full-system solutions to win orders, especially in integrated projects that require domestic server platforms.
The second layer is inference-side cost. As Chinese large models and vertical applications enter commercialization, inference cost becomes more important than peak training performance. If DCU can become “usable, deliverable, and maintainable” across mainstream models, industry models, and private deployments, it does not need to become the world’s strongest GPU to capture a sufficiently large local market.
The third layer is Super-Node. Prior tracking reports mentioned rack-level solutions such as ScaleX640, which integrate Hygon CPUs and DCUs into large-scale parallel computing in a single rack, attempting to address interconnect bandwidth bottlenecks in large-model training. If this system-level capability proves stable, it will push Hygon from “selling chips” toward “selling compute units,” with higher customer stickiness and larger project sizes.
Server Industry Reassessment: From CPU Platforms to AI Acceleration Systems
But DCU is also a major source of risk. First, domestic GPU competition is more intense than domestic CPU competition, and price wars will emerge earlier. Second, DCU gross margin is likely lower than CPU gross margin, so a higher revenue mix will drag down blended gross margin. Third, software ecosystems are difficult to form organically through single-customer projects; Hygon needs to keep investing in compilers, operator libraries, framework adaptation, and developer support. Fourth, concentration among top customers is high. Once large-order timing fluctuates, quarterly revenue and gross margin volatility will be amplified.
Therefore, DCU is not “one more story”; it widens Hygon’s risk-reward profile. If it succeeds, Hygon moves from CPU substitution to a domestic compute platform. If it fails, investors need to accept higher R&D; investment, lower gross margin, and stronger quarterly volatility.
VI. Financial Model: Revenue Elasticity Has Emerged; Profit Elasticity Is Still Being Tested
Hygon’s financial performance in 2024-2026 shows a typical high-growth semiconductor pattern: revenue moves first, margins are confirmed later.
The midpoint of 2024 revenue guidance was about RMB 9.125 billion, up 52% YoY, mainly driven by higher adoption of Xinchuang CPUs and ramp-up of DCU/AI chips. But the 4Q24 net margin midpoint was only 12.9%, below 3Q24’s 28.3%. Growth continued to accelerate in 2025, with 4Q25 revenue of RMB 4.886 billion, up 61.5% YoY, and full-year revenue of RMB 14.377 billion. The midpoint of 1Q26 revenue guidance was about RMB 4.065 billion, up 69% YoY. The revenue curve has already proven that demand exists.
The issue is that the income statement has not yet fully proven operating leverage. In 4Q25, revenue grew strongly YoY, but operating margin and net margin declined QoQ, mainly due to year-end expense recognition, R&D; intensity, share-based compensation, and project investment. In 2026, what the market really needs to see is whether the expense ratio can fall as revenue scales.
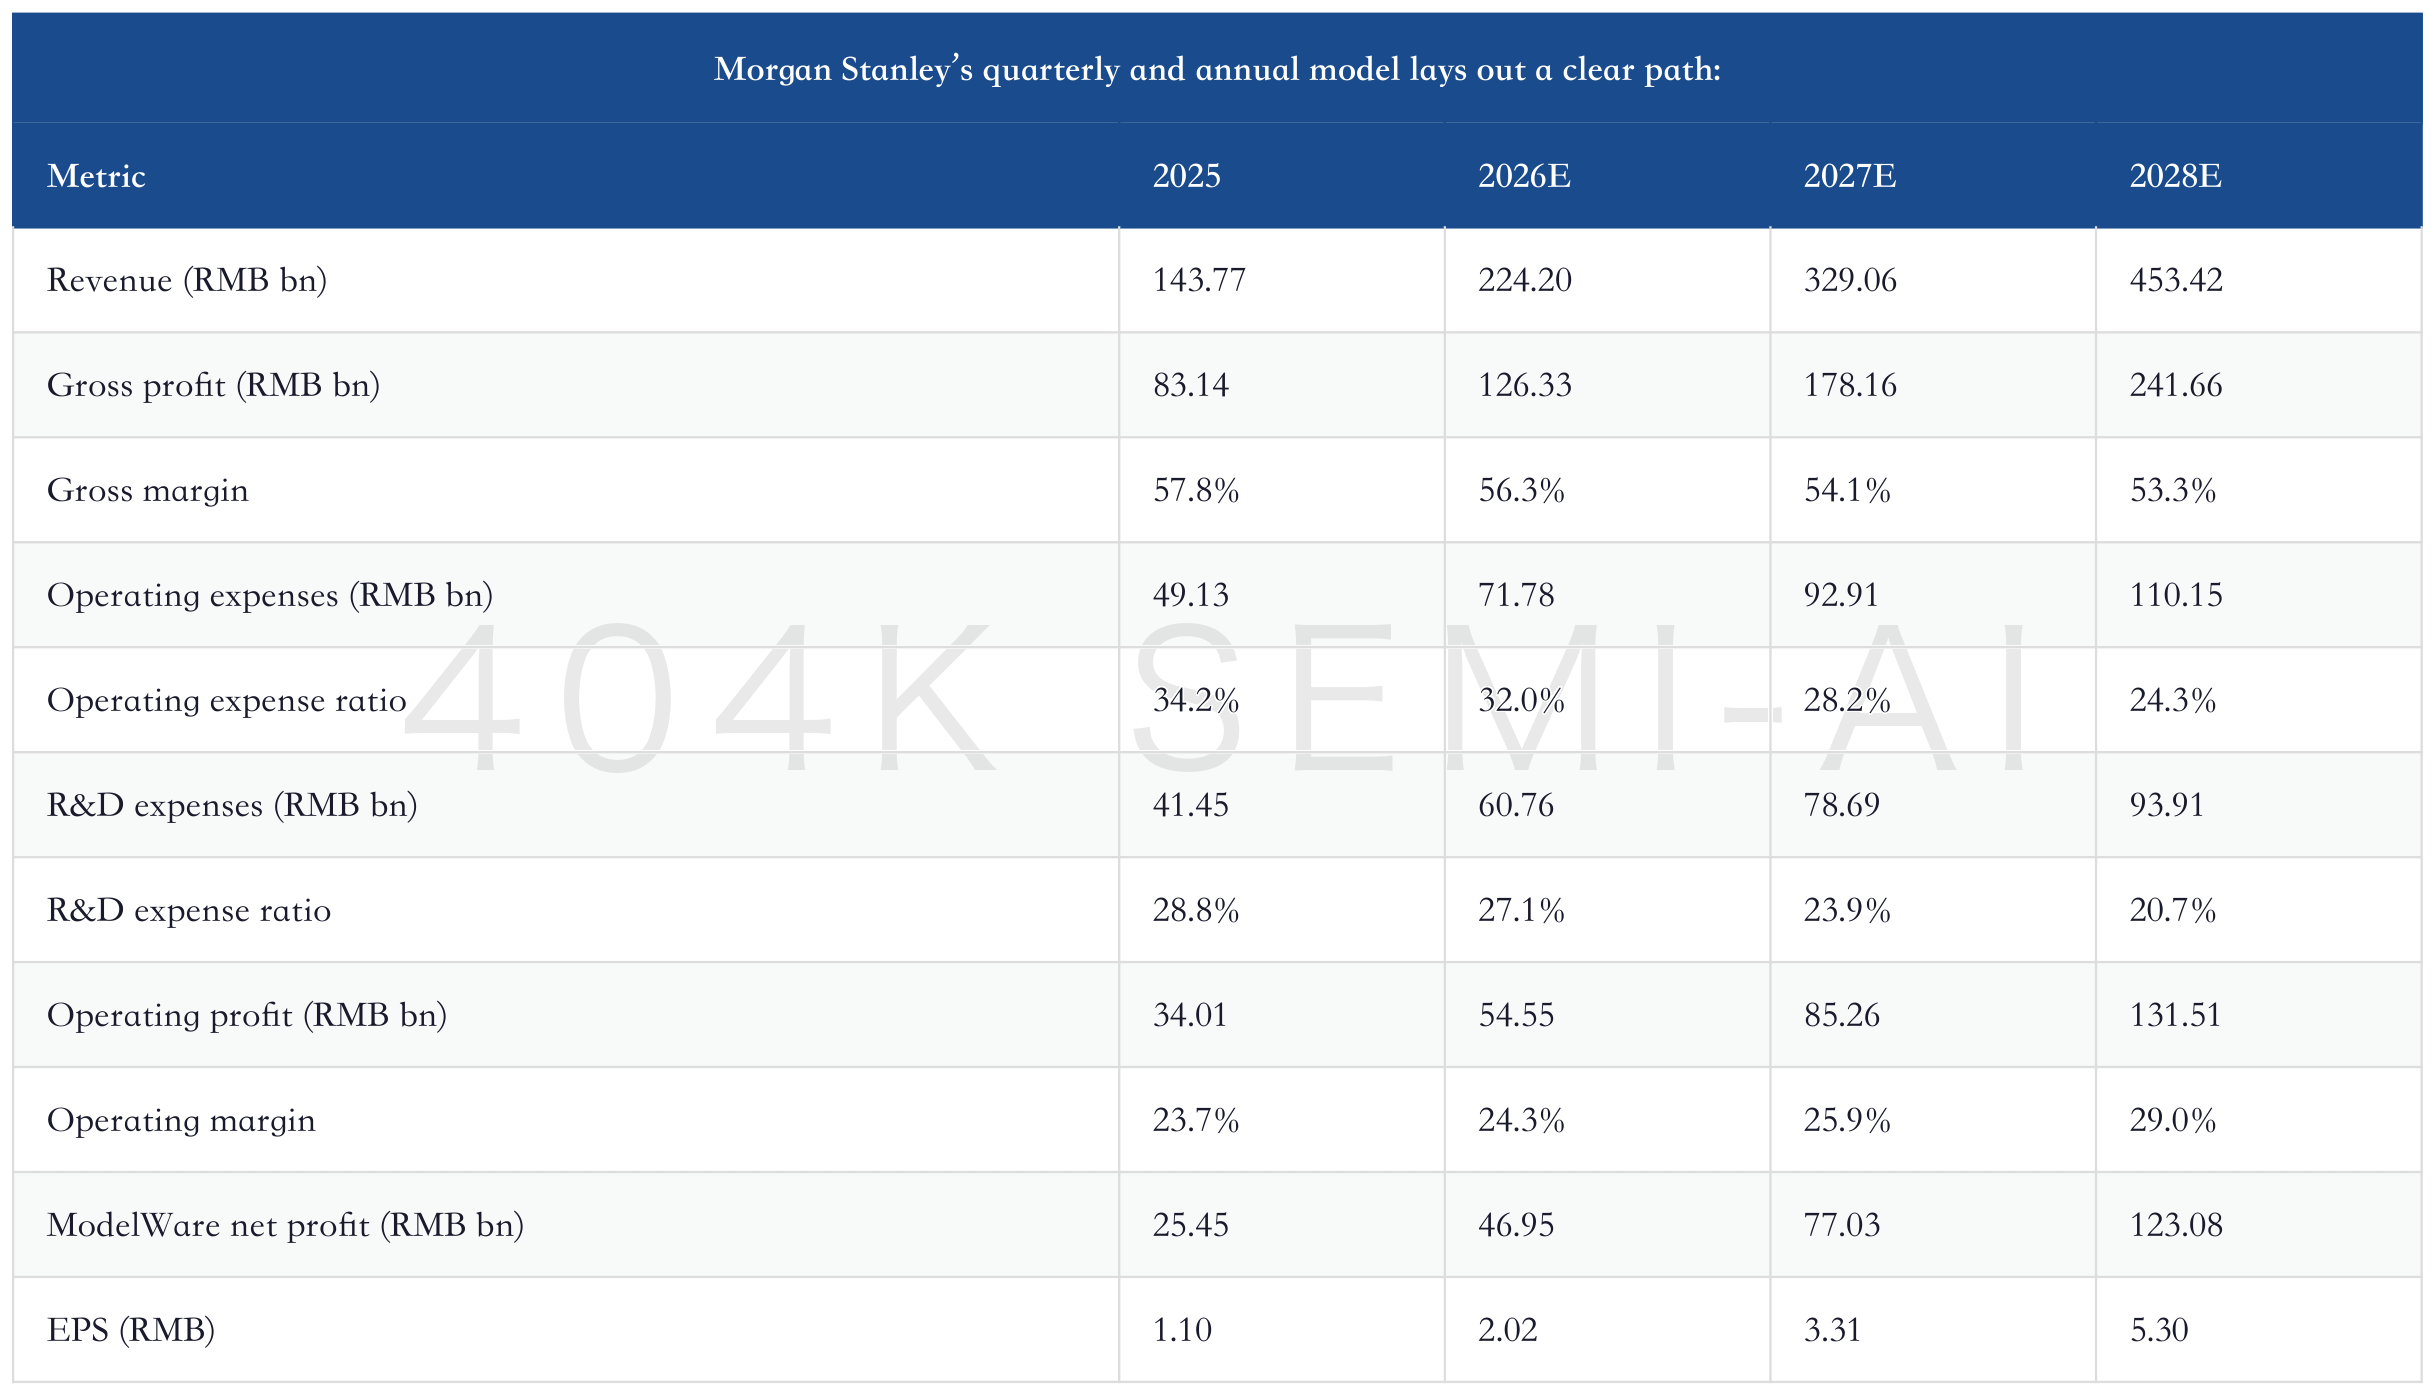
There are two key points in this table.
First, gross-margin decline does not mean the model is breaking; it reflects product-mix change. The CPU business has higher gross margin, while the DCU business has lower gross margin in the early ramp phase. A blended gross margin decline from 57.8% to 53.3% is acceptable. The real danger would be gross margin falling below 50%, especially toward 40% as DCU competition intensifies. That would no longer be mix; it would indicate pricing and yield pressure.
Second, the decline in the operating expense ratio is the core of profit elasticity. Hygon must sustain heavy R&D; investment in next-generation CPUs, DCUs, and the software stack, and it cannot cut R&D; for short-term earnings. But if revenue can rise from RMB 14.4 billion to RMB 45.3 billion, the R&D; expense ratio should fall from nearly 29% to around 21%, while sales and administrative expense ratios also need to be diluted by scale. Otherwise, high revenue growth will remain a capitalization narrative rather than becoming EPS.
Hygon’s cash flow also warrants caution. AI chips and server-platform businesses consume inventory, receivables, and supply-chain credit; when customer concentration is high, collection timing has a greater impact on operating cash flow. In Morgan Stanley’s model, CFO is about RMB 2.097 billion in 2025, RMB 3.065 billion in 2026, RMB 3.316 billion in 2027, and only rises sharply to RMB 7.285 billion in 2028. This means 2026-2027 is the validation period for revenue and profit, while cash flow may not break out at the same time.
If one only looks at high revenue growth, Hygon can easily be written up as a linear growth stock. If one looks at margins and cash flow, it is more like a company converting R&D; investment into platform assets. The key question for 2026 is not “will revenue keep growing,” but “can revenue growth flow through to operating margin and cash flow.”
VII. Customers and Ecosystem: Sugon Is the Entry Point, and Also a Concentration Risk
Hygon cannot be analyzed without Sugon. Sugon is Hygon’s largest shareholder; Morgan Stanley shows a 27.96% stake as of 1Q26. At the same time, Morgan Stanley estimates that Hygon’s top five customers accounted for about 90% of revenue in 2025, and that the largest customer may be Sugon, accounting for about 57% of revenue. These numbers explain Hygon’s industrial synergy, but also the market’s concerns.
Sugon’s value lies in access to servers, storage, cloud computing, and high-performance computing systems. Hygon makes CPUs and DCUs; Sugon makes complete machines and systems. If the two integrate smoothly, they can form a closed loop across “chips, machines, systems, and services.” In domestic compute projects, customers usually do not buy a single chip; they procure a deliverable server cluster or compute platform. Sugon’s ecosystem can reduce Hygon’s go-to-market cost.
But customer concentration also amplifies risk. A 90% revenue share from the top five customers means quarterly volatility, project acceptance, payment collection, and related ecosystems can all affect financials. To earn a higher valuation, Hygon must prove it is not merely following Sugon-led projects, but can enter more server OEMs, internet customers, carriers, financial institutions, and industry-cloud procurement systems.
Hygon and Sugon previously planned a share-swap absorption merger, with a transaction value of about RMB 115.967 billion, which was later terminated. The termination itself does not change Hygon’s production and operations, but it leaves a more important question: should Hygon become part of the Sugon system, or maintain the independence and openness of a chip-platform company?
From an investment perspective, the termination is not necessarily negative. If the merger had succeeded, Hygon would have gained more complete system capabilities, but its asset purity could also have been diluted by the complete-machine business. After the termination, Hygon can still cooperate with Sugon while retaining room to supply the broader server ecosystem, including Inspur, Lenovo, H3C, Tongfang, Ruijie Networks, and PowerLeader. For Hygon, the best outcome is not to be tied only to Sugon, but to use Sugon as a benchmark customer and system-validation site, then replicate that model across a broader customer base.
There is a clear metric to monitor: the revenue share of the top five customers. From 2019 to 2025, Hygon’s top-five customer share stayed at or above roughly 90% for a long period. If revenue continues to grow in 2026-2028 but the top-five share does not decline, the market will view Hygon as a project-based company. If the share gradually declines and the revenue contribution from internet companies and carriers rises, the valuation will move closer to that of a platform-type chip company.
VIII. Horizontal Ranking: Hygon Is Not the Strongest AI Chip, but May Be the Scarcest CPU+DCU Combination
In the domestic compute value chain, Hygon’s position needs to be evaluated separately. Ranked by the performance of a single AI accelerator card, it may not be first. Ranked by server CPU ecosystem migration and the CPU+DCU combination, it is near the front.
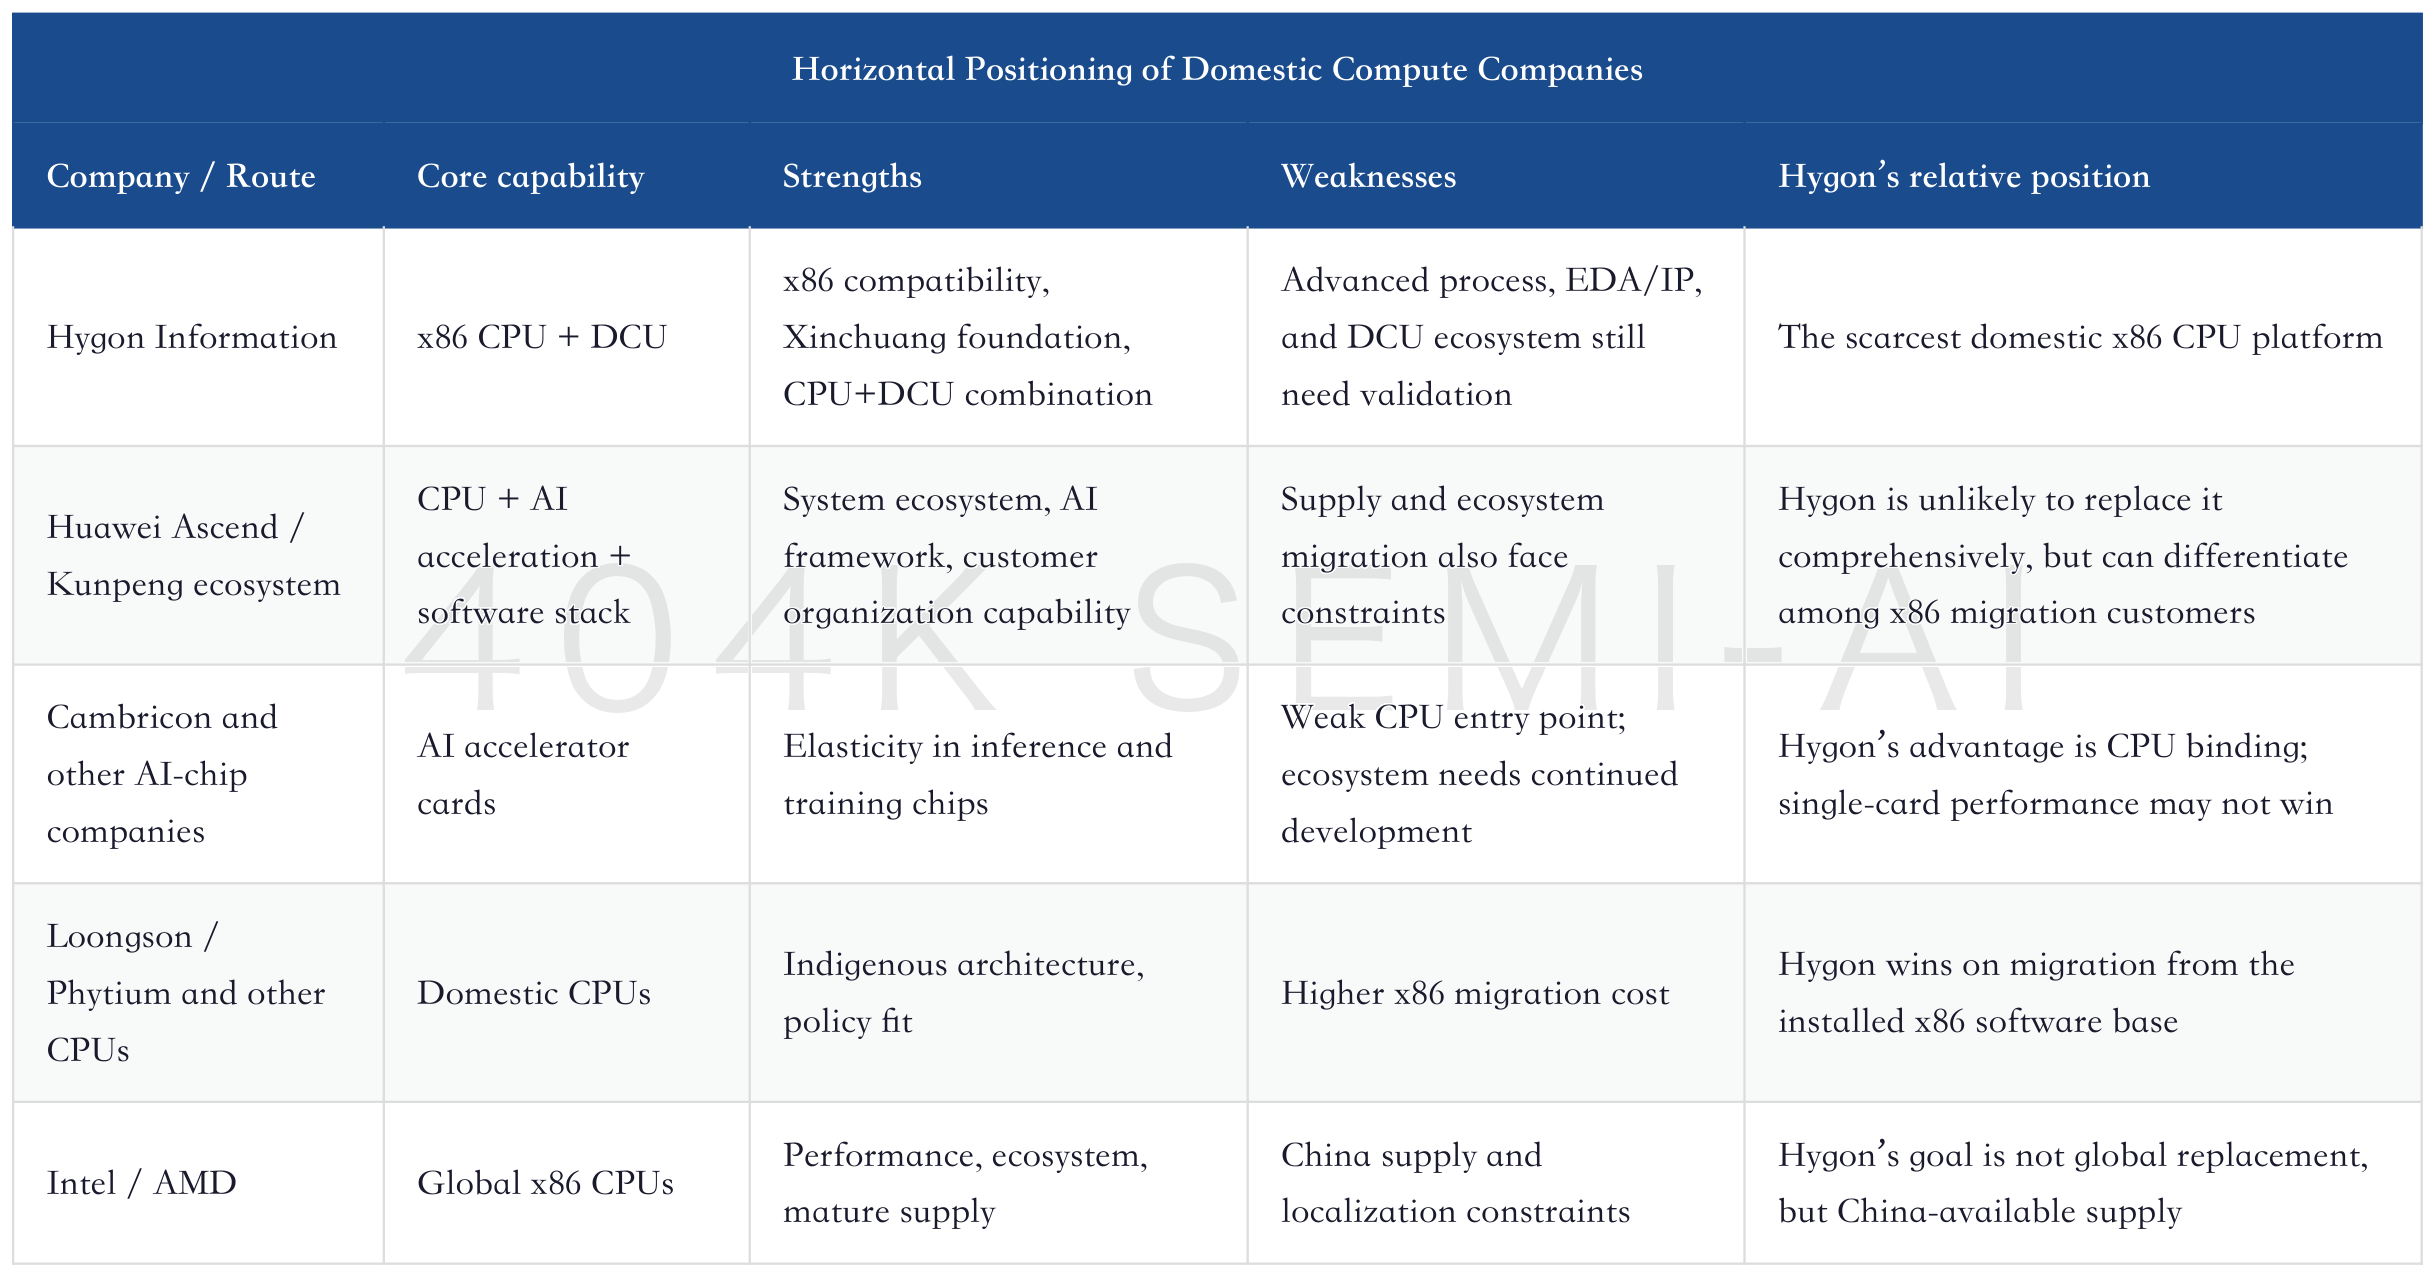
This table explains why Hygon’s valuation should not be compared only with one domestic AI-chip company, nor only with Intel/AMD P/E multiples. Hygon is a “position asset”: it sits between China’s server x86 migration, domestic compute buildout, and AI inference infrastructure.
If Chinese customers only buy the highest-performance GPUs, Hygon is not the most direct beneficiary. If Chinese customers need a server platform that is available, deployable, able to pass domestic approval, able to run the existing x86 ecosystem, and able to pair with local AI acceleration, Hygon’s value rises.
IX. Supply Chain and Software Ecosystem: The Real Moat Is Not One Chip Specification
The easiest way for semiconductor companies to be misled by stock-price narratives is to treat a single chip’s specifications as the moat. Hygon is the opposite: the specifications of a single CPU or DCU are of course important, but whether it can move through cycles depends on whether four layers of ecosystem are simultaneously established.
The first layer is manufacturing and packaging. Hygon is a fabless design company. Advanced process supply for CPUs and DCUs depends on external foundries, and back-end packaging and testing also require partners. For a Chinese high-end chip company affected by export controls, capacity is not something that appears just by placing an order. If G5 uses a local advanced node close to 7nm equivalent, yield, cost, scheduling priority, and competition for capacity across multiple projects will all affect the mass-production pace. DCU ramp-up will also consume advanced logic capacity, and CPUs and DCUs will compete for resources within the company.
This means Hygon’s capacity model cannot simply be extrapolated from demand. Customers’ willingness to buy is one thing; whether the company can deliver steadily, and whether gross margin after delivery is acceptable, is another. If China’s advanced logic capacity expansion proceeds smoothly in 2026-2027, Hygon will benefit from improved CPU and DCU supply at the same time. If capacity expansion falls short of expectations, Hygon may have enough orders but slow revenue recognition and pressure on gross margin.
The second layer is memory, interconnect, and server support. C86-G5’s 16-channel DDR5 and CXL2.0 only have full value when domestic memory, controllers, motherboards, BIOS, firmware, and system software are mature. A CPU is not a standalone benchmark tool; it is the center of a server platform. DDR5 supply, memory controllers, CXL expansion, PCIe devices, NICs, storage, virtualization, and cloud-native scheduling all need to pass customer validation together.
This is also why the synergy between Hygon and Sugon’s ecosystem is valuable. Complete-machine vendors can jointly tune the CPU, motherboard, memory, DCU, NIC, thermals, power supply, rack, and software, shortening customers’ deployment cycles. If a single chip is strong but the complete-machine solution is unstable, customers will not deploy it at scale. If a single chip is not world-class, but the complete-machine platform is usable, delivery is stable, and software migration costs are low, customers will procure it.
The third layer is the software stack. CPU x86 compatibility is Hygon’s first advantage, but DCU does not have the same ready-made ecosystem dividend. For DCU to be accepted by large-model and industry AI customers, it must solve operator libraries, framework adaptation, compilers, communication libraries, debugging tools, and cluster management. The hipBLAS, hipRand, hipFFT, MIOpen, RCCL, OpenCL, LLVM, and HIP interfaces listed in the report sound like technical terms, but in substance they determine the cost for customers to migrate models from other ecosystems.
The hardest part of the software stack is negative feedback. When there are few customers, the ecosystem develops slowly; when the ecosystem develops slowly, there are few customers. To break this loop, Hygon usually needs benchmark projects, engineering support for major customers, and binding with complete-machine solutions. Government, enterprise, and industry customers may accept higher adaptation costs because localization and data security carry high weight. Commercial CSPs are more sensitive to cost, stability, and development efficiency. Hygon must prove that DCU can not only run, but run at scale in a maintainable way.
The fourth layer is customer validation. For a chip company entering the core systems of cloud vendors, financial institutions, telecom operators, and government and enterprise customers, the most time-consuming part is not signing contracts, but validation. CPUs need to be tested for stability, virtualization, databases, operating systems, power consumption, failure rates, and compatibility. DCUs need to be tested for model accuracy, throughput, operator coverage, cluster communication, failure recovery, and developer experience. Many orders start with pilots, small clusters, and non-core workloads before expanding to large-scale deployment.
Hygon’s investment logic therefore cannot only focus on “what product was released”; it must also look at “whose production system the product entered.” If G5 remains only on the spec sheet, valuation realization will be limited. If G5 enters the actual procurement catalogs of CSPs, carriers, and financial customers, the valuation anchor will change materially. The same applies to DCU: one large order is not enough; consecutive orders and repeat purchases are what matter.
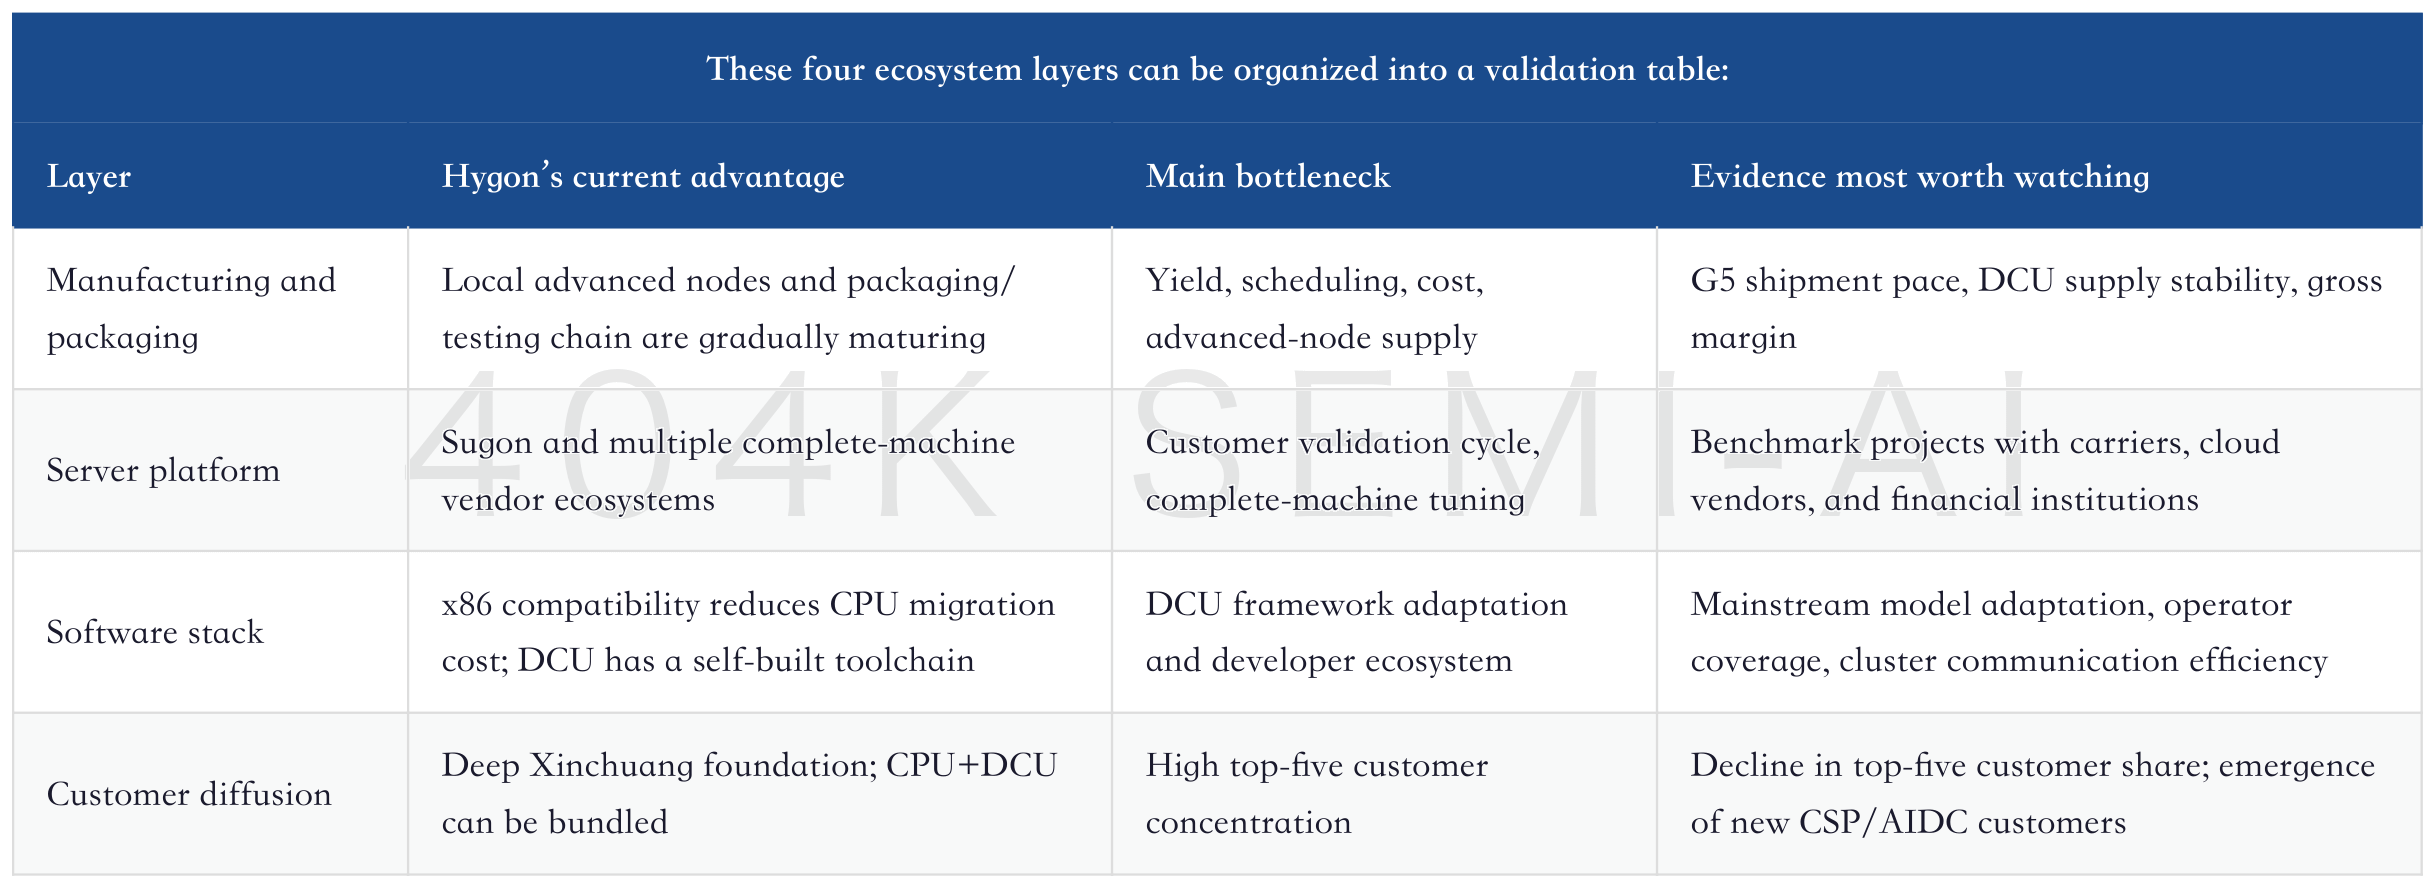
This table also shows the difference between Hygon and ordinary domestic-substitution companies. In an ordinary substitution logic, as long as the localization ratio rises, the company can grow. To receive a higher valuation, Hygon must move from substitution logic to platform logic. Platform logic requires the supply chain, complete machines, software, and customers to all become stronger together.
Therefore, Hygon’s moat is not “we also have 128 cores,” but “a 128-core CPU can be delivered together with DCU, servers, a software stack, and a customer migration path.” If this closed loop holds, Hygon’s business model will increasingly resemble a platform. If one layer is missing, Hygon will revert to being a chip company with high R&D;, project-based revenue, customer concentration, and margin volatility.
10. Valuation: The Real Disagreement Behind RMB 450, RMB 480, RMB 680, and RMB 200
Hygon’s valuation dispersion is large, but the disagreement is not as simple as “expensive” or “cheap.” Bernstein has a RMB 450 target price; Morgan Stanley has a RMB 480 target price. Morgan Stanley’s bull case is RMB 680, while its bear case is RMB 200. When the same research framework produces such a wide range for one stock, it means the core variable is not static earnings, but a commercial worldview.
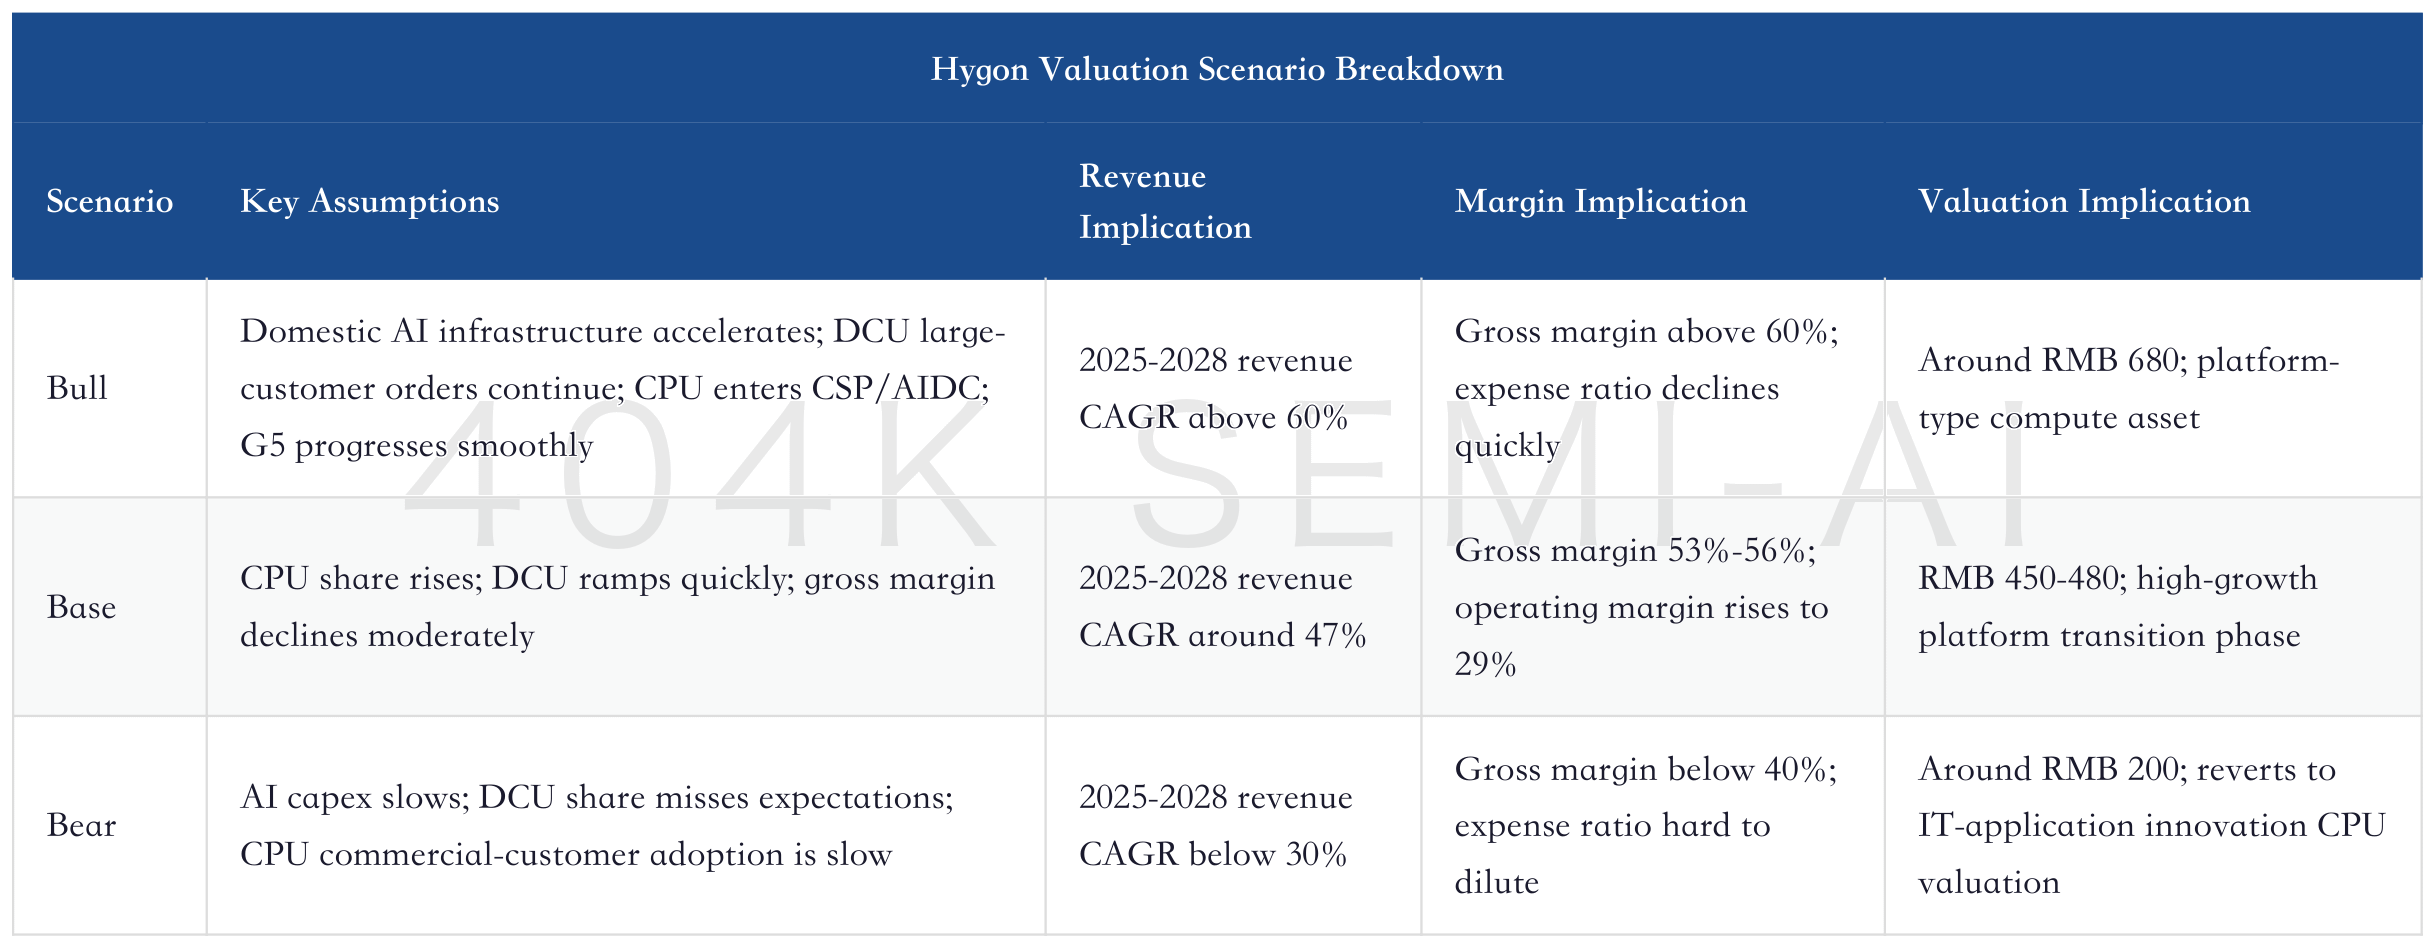
Morgan Stanley’s RMB 480 target price comes from a residual income model. The key parameters include an 8.0% cost of equity, 50% payout ratio, 25% medium-term growth rate, and 5% terminal growth rate. This valuation implies 34x 2027 sales, roughly 1 standard deviation above the average NTM P/S over the past four years. In other words, the market must believe Hygon is not an ordinary hardware company, but a domestic AI compute platform.
Bernstein’s RMB 450 target price is more tilted toward CPU re-rating. It believes Agentic AI will pull server CPUs back to the center of infrastructure, with China’s x86 server CPU TAM reaching USD 27 billion by 2030 and Hygon’s share continuing to rise. This line of reasoning emphasizes C86-G5 and China’s CPU localization rate more than a pure DCU boom.
The overlap between these two frameworks is Hygon’s real core thesis: CPU is the entry point, DCU is the upside, G5 is the product validation, and customer expansion is the condition for valuation transition.
If investors are only buying CPU substitution, the RMB 450-480 valuation is not cheap. If they are buying a CPU+DCU platform, the market will be willing to tolerate a high P/S. If they are buying a “domestic Nvidia,” that is too aggressive, because Hygon has not yet proven its software ecosystem, single-card competitiveness, or recurring large-customer orders. The most prudent judgment is that Hygon is the scarcest CPU+DCU platform option in China’s compute supply chain, but it is still in the early stage of earnings delivery and should not be statically priced on mature earnings multiples.
Intel Deep Update: Goldman Sachs Sees USD 150; How Server CPU Tailwinds and Foundry Optionality Could Drive a Re-rating
11. Core Model: Four Variables Decide Whether Hygon Can Move from “High Valuation” to “High Quality”
Hygon’s model over the next two years can be compressed into four variables: CPU share, DCU ramp, gross margin, and expense ratio.
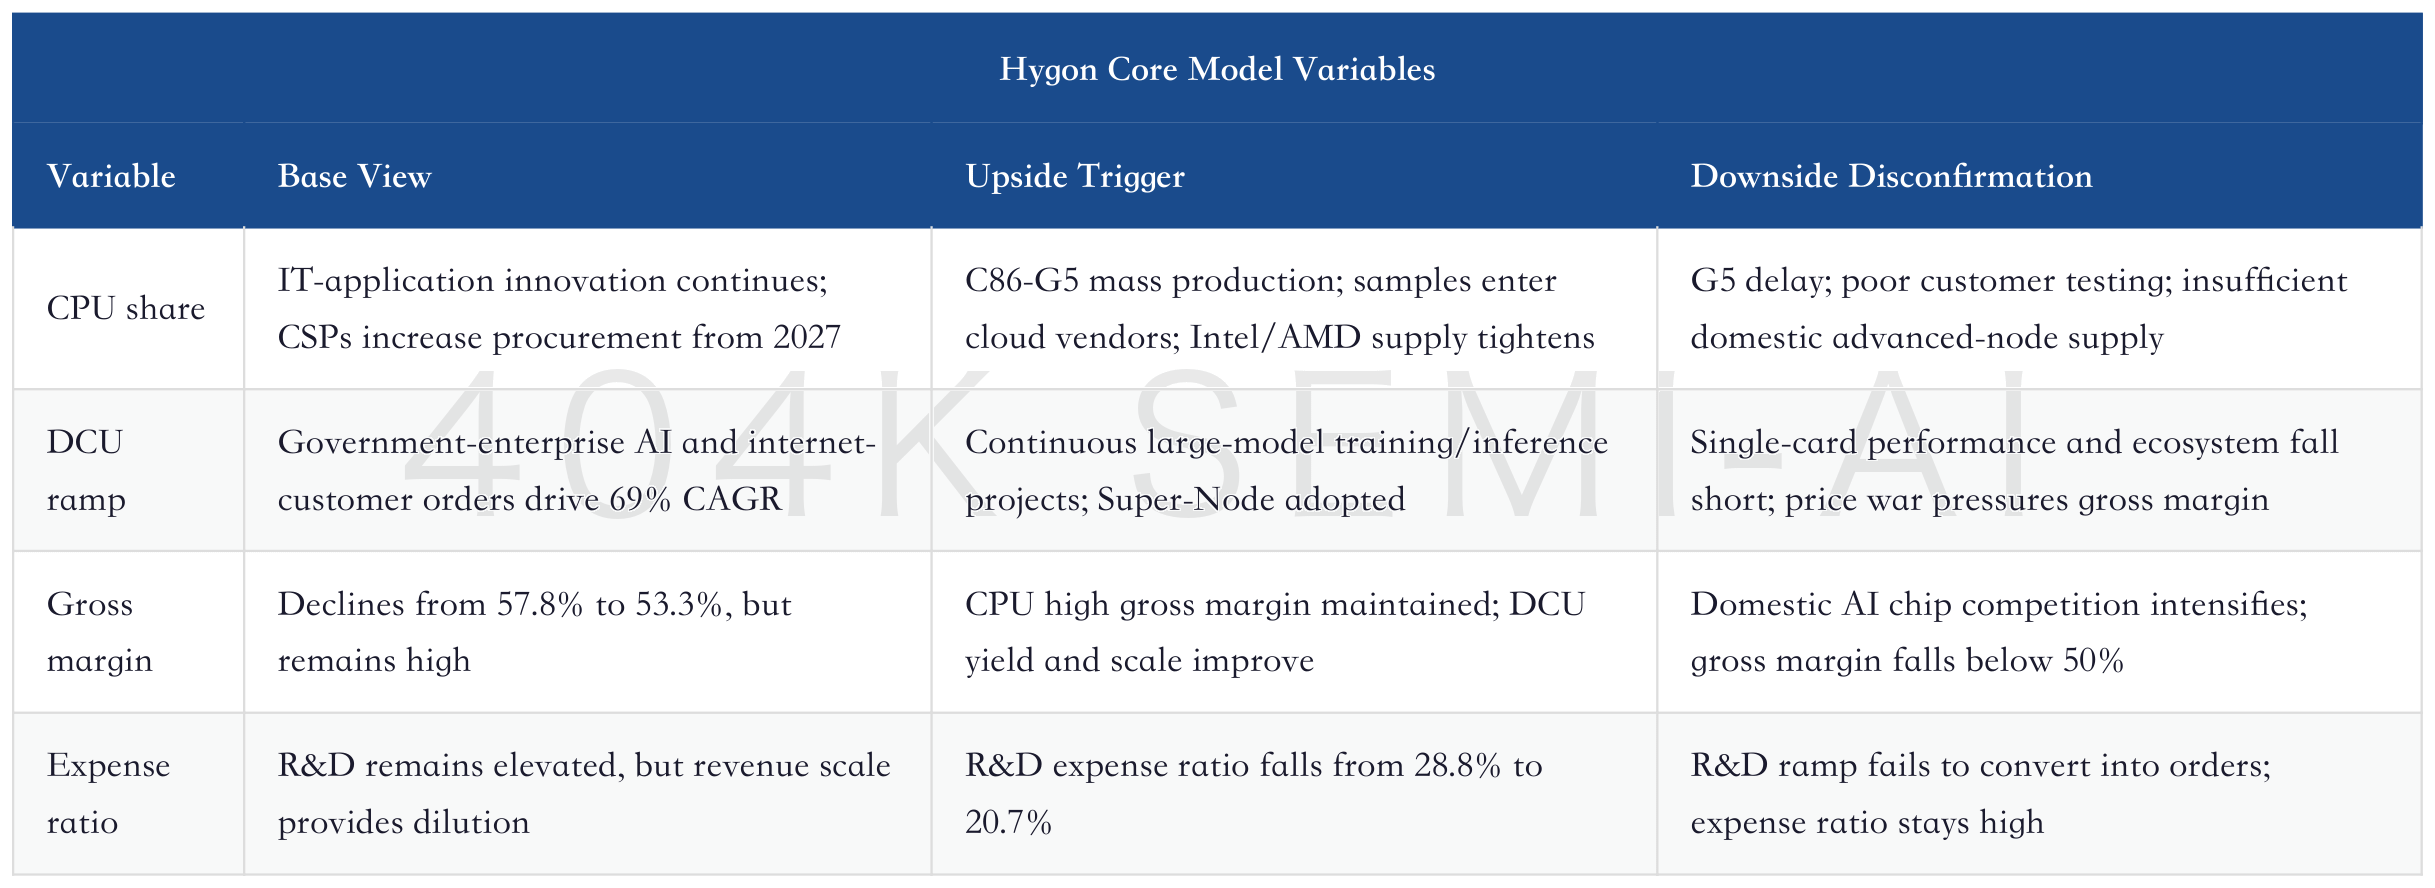
Linking these four variables together, Hygon’s earnings leverage is not mysterious.
On revenue, CPU provides steady incremental growth, while DCU provides high elasticity. As long as DCU growth remains meaningfully higher than CPU growth, overall revenue has a chance to sustain high compound growth. On gross margin, a higher DCU mix will weigh on blended gross margin, but as long as CPU gross margin is stable and DCU does not fall into a price war, blended gross margin will still be excellent. On expenses, high R&D; spending is a necessary cost, but once scale is large enough, expense-ratio decline will lift operating margin.
This is why Morgan Stanley’s model shows “gross margin down, but operating margin up.” From 2025 to 2028, gross margin falls from 57.8% to 53.3%, while operating margin rises from 23.7% to 29.0%. Investors who look only at gross margin will underestimate scale effects; investors who look only at revenue will underestimate product-mix risk. The two must be assessed together.
Hygon’s ideal state is to become a platform fee on a “domestic CPU socket + local AI acceleration + server ecosystem.” Each round of domestic compute buildout brings cross-selling of CPUs, DCUs, and whole-server solutions; each round of software adaptation raises customer switching costs. In this state, Hygon’s valuation can remain elevated.
The worst state is that DCU becomes one-off project orders, CPU remains confined to IT-application innovation budgets, expenses stay high, and customer concentration does not decline. Hygon would still have revenue growth, but the market would view it as a project-based hardware company, making a high P/S difficult to sustain.
12. Risks: Hygon’s Biggest Risk Is Not Demand, but the Delivery Path
Hygon’s demand narrative is strong. China AI infrastructure, localized procurement, CPU resurgence, x86 migration, and DCU substitution are all real variables. But strong demand does not equal strong returns, especially for chip companies, where the execution path is usually harder than demand.
First, EDA and IP dependence is a long-term risk. Advanced CPU design cannot do without EDA tools, IP libraries, and technical support. After Hygon was placed on the Entity List, access to overseas tool updates, IP libraries, and technical support became uncertain. Domestic EDA is improving, but there is still a gap in the full digital IC workflow. Whether iterations after G5 can maintain cadence is the long-term valuation ceiling.
Second, advanced-node supply is a capacity risk. Hygon’s CPU and DCU products both need to compete for limited domestic advanced logic capacity. Even if demand is sufficient, wafer allocation, yield, packaging, and testing can all constrain shipments. China’s AI chip shortage will improve Hygon’s bargaining power, but it will also force Hygon to compete with other priority projects for capacity.
Third, DCU competition will erode gross margin faster. CPUs have a relatively clear competitive landscape due to x86 compatibility and IT-application innovation certification. AI accelerator cards have more local players, and customers can switch more easily among performance, price, and ecosystem. If DCU gross margin falls too quickly, revenue growth will be consumed by margin pressure.
Fourth, customer concentration amplifies financial volatility. The top five customers contributing roughly 90% of revenue in 2025 is not a small issue. Large-customer project timing, acceptance cycles, collections, and inventory strategies will all affect Hygon’s quarterly financials. Before customer concentration declines, Hygon will find it hard to be viewed as a fully mature platform company.
Fifth, valuation already reflects a lot of good news in advance. At the time of Morgan Stanley’s report, Hygon’s market cap was about RMB 813.3 billion, and 2027 P/S was still high. A high valuation can exist, but it requires positive feedback every quarter. If any one of C86-G5, DCU, gross margin, expense ratio, or customer expansion stays below expectations for consecutive periods, valuation correction will be swift.
Sixth, politics and export controls are not a one-way positive. External restrictions stimulate local substitution, but they also restrict tools, IP, advanced equipment, and supply-chain cooperation. They are positive for demand in the short term, but raise the difficulty of technology iteration over the long term. Hygon’s investment logic should not be written simply as “the more restrictions, the more upside,” but rather as “supply constraints create local demand, but local supply capability must keep up.”
13. Tracking Checklist for the Next Four Quarters
Hygon is not a static asset that can be understood at a glance; it requires quarterly tracking. The most useful work in the next stage is not to repeat the grand narrative, but to monitor specific indicators.
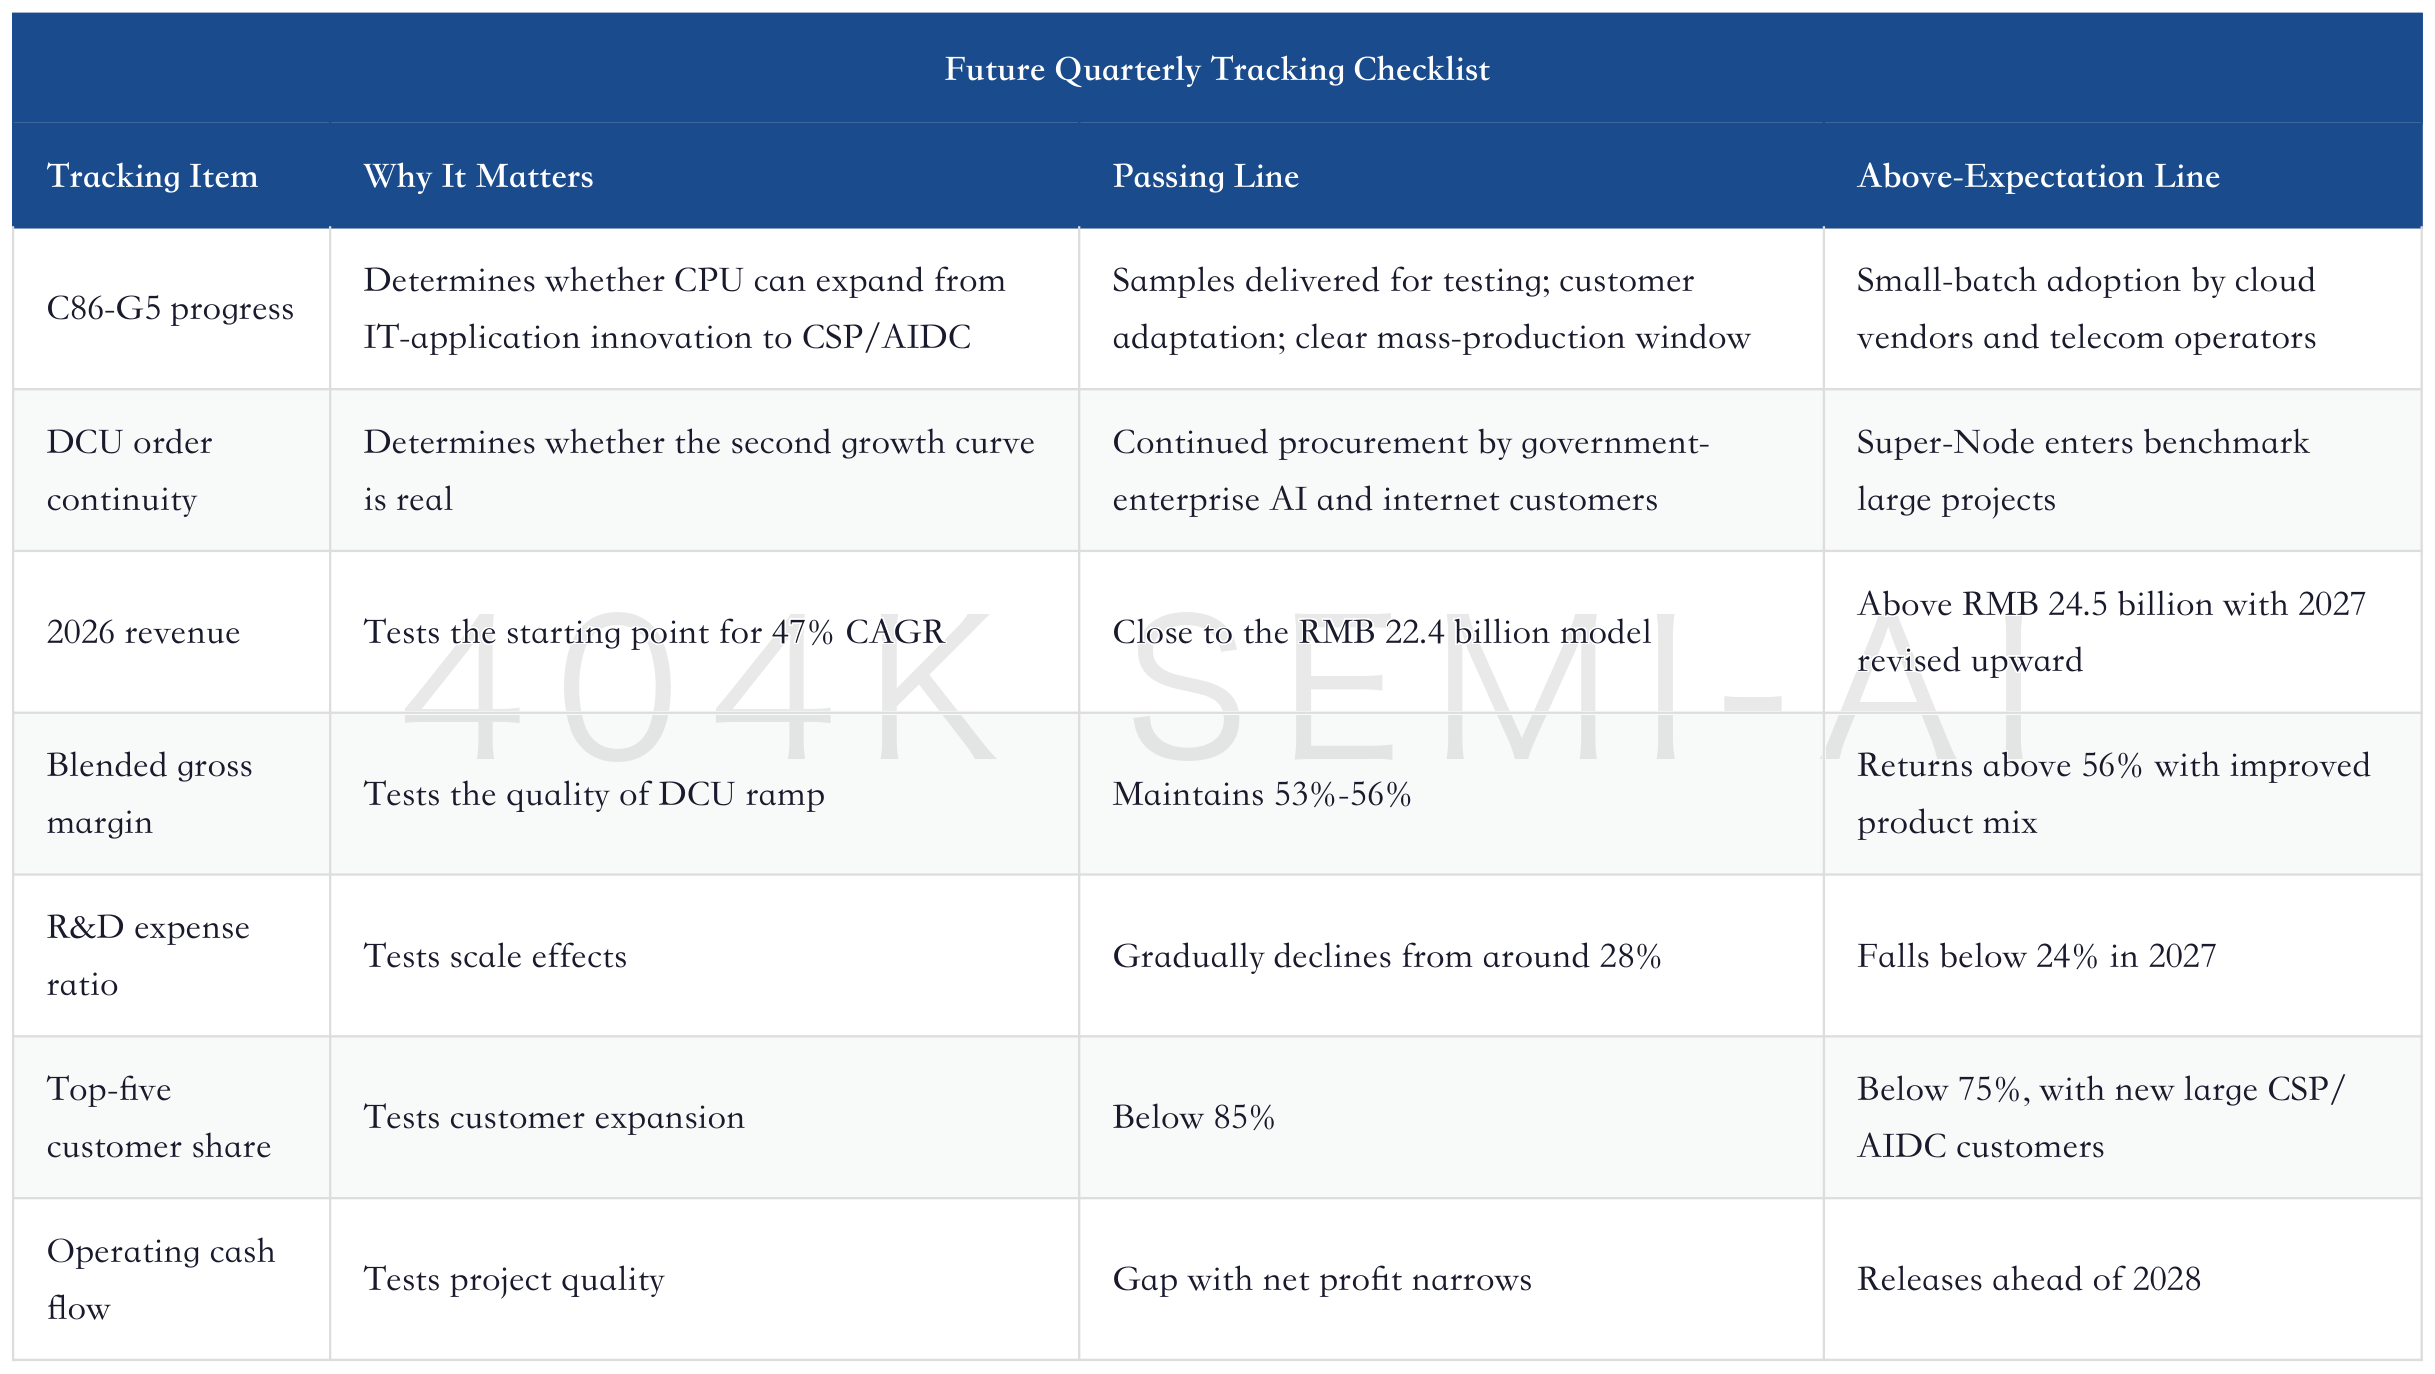
Among these seven items, the first three are the most important. G5 determines CPU TAM expansion, DCU orders determine the second growth curve, and 2026 revenue determines the model’s starting point. Gross margin, expense ratio, and cash flow determine earnings quality.
If 2026 brings a combination of “smooth G5 progress, continuous large DCU orders, revenue near or above RMB 22.4 billion, and gross margin stable around 55%,” Hygon’s high valuation will have further room to digest. If the combination is “revenue growth but rapid gross-margin decline, no reduction in customer concentration, and vague G5 progress,” the market will reclassify it from a platform asset back into project-based hardware.
14. Conclusion: Hygon Is Not a Cheap Stock, but It Is One of the Few Domestic Compute Companies That Can Address Both CPU and GPU
The most attractive part of Hygon Information today is that it stands at the intersection of several real inflection points. CPUs are becoming important again in AI infrastructure; China’s market needs controllable server CPUs; x86 migration lowers customer friction; DCU provides the company with a second growth curve; and Sugon plus the server ecosystem give it a system-level entry point.
But this company is not a risk-free, one-way growth story. Its valuation has already paid upfront for a lot of the future: C86-G5 must progress smoothly, DCU must ramp, customers must expand, expense ratio must decline, gross margin cannot collapse, and cash flow must keep up. Failure to deliver on any one of these conditions is enough for the market to reprice the stock.
The most appropriate description is this: Hygon is the most worth-tracking “CPU+DCU platform option” in China’s compute infrastructure. It is not yet a high-performance chip giant in the global sense, nor is it simply an IT-application innovation CPU company. Its value comes from a narrower but scarcer path: under China’s available-supply and localization constraints, using x86-compatible CPUs to capture the existing server ecosystem, using DCUs to capture local AI acceleration demand, and then using system-level solutions to lock customers into the platform.
Hygon’s next stage is not about proving whether domestic substitution has demand, but about proving whether it can turn demand into sustainable profit. C86-G5 is the first answer sheet, recurring DCU orders are the second, and expense ratio plus cash flow are the third. If it gets all three right, it has a chance to move from high valuation to high quality. If it gets only one right, it will still grow, but valuation will find it hard to remain this forgiving.
This is also what makes Hygon different from most theme trades. Theme trades only need catalysts; platform re-rating requires continuous delivery. Hygon already has catalysts. What it needs to deliver next is execution capability. A real re-rating will not come only from one new-product release, but from customer repeat purchases, ecosystem migration, and margin stability appearing together. Future reviews should continue to revolve around this line.
The Second Engine of the Storage Supercycle: CPU Return, HBM Spillover, and the Re-rating of a USD 1.7 Trillion TAM
Nvidia GTC Deep Dive | From GPU Racks to Token Factories, Nvidia Brings CPU, Storage, Networking, and Power into the Token Economy, Repricing Full-Stack AI Infrastructure
XV. What Really Needs to Be Verified Is Not Domestic Substitution, but Platform Repurchasing
The easiest catalysts for trading Hygon are domestic CPUs, domestic AI chips, and external supply restrictions. These catalysts are real. But if the analysis stops at the catalyst level, Hygon will repeatedly be priced as a thematic stock: valuation rises when news flow strengthens and falls back when project pacing slows. What can truly move Hygon from a theme trade to a platform re-rating is not “whether there is demand for domestic substitution,” but “whether customers are willing to repurchase the same platform.”
Repurchasing matters more than the first order. A first order may come from policy, budget, pilots, supply tightness, or project windows; repurchasing means the product has entered the customer’s production system, and migration costs, operations experience, and software adaptation have begun to accumulate. CPU and DCU repurchases also mean different things. CPU repurchasing indicates Hygon is stable enough across operating systems, databases, middleware, virtualization, and business applications; DCU repurchasing indicates customers can accept its model adaptation, operator coverage, cluster communication, and training/inference efficiency. Only when both forms of repurchasing occur at the same time does this become a platform story.
Platform repurchasing will also change Hygon’s earnings quality. Project-based chip companies are prone to revenue jumps, gross-margin volatility, and longer receivables, because every order is like fighting a new battle. Platform-based chip companies are different. Once customers pass validation, subsequent procurement expands around the same architecture; software adaptation costs are amortized, after-sales and developer-support efficiency improves, and R&D; investment becomes easier to reuse. If Hygon can replicate the validation experience inside the Sugon ecosystem across more server OEMs, cloud providers, and industry customers, its declining expense ratio will not be a financial-model assumption, but the natural result of the business model.
This is also why the share of the top five customers must decline. Customer concentration is not inherently bad; in the early stage, relying on major customers to refine products is necessary. But if the company remains highly dependent on a small number of customers after revenue scales, the market will worry that revenue is merely project transfer rather than ecosystem expansion. Hygon’s best path is to retain Sugon as a highly synergistic customer while gradually adding incremental contribution from Inspur, Lenovo, H3C, telecom operators, financial clouds, local AIDCs, and industry clouds. The more diversified the customer base, the stronger the platform attributes; the more concentrated the customer base, the more order volatility deserves a discount.
Software migration is the underlying reason for repurchasing. For cloud providers and financial customers, the CPU has never been a standalone procurement item. Every migration must validate the operating system, database, virtualization, containers, monitoring, backup, permissions, application performance, and disaster recovery. Hygon’s x86 compatibility advantage is that it reduces this set of migration frictions. The first customer adoption may come from localization requirements, but the second purchase often depends on whether the operations team believes the platform is “controllable, maintainable, and less prone to problems.” Once this reputation forms, it is more valuable than a single benchmark.
DCU migration is harder, and therefore even more worth watching. Large-model customers do not only look at peak chip compute. They look at whether models can run stably, whether operator gaps can be filled, whether training interruptions can recover, whether inference costs can decline, and whether engineering teams can receive continuous support. If Hygon only sells accelerator cards, customers will keep comparing prices against other domestic GPUs. If it sells CPU, DCU, communication libraries, compilers, servers, and rack-level coordination, customer switching costs will be much higher. The essence of platform repurchasing is to shift customers from buying hardware to expanding along an ecosystem.
Margin verification should also be viewed through the repurchasing framework. A rising DCU mix will pressure blended gross margin in the short term, but if repurchasing is stable, yield improvement, software reuse, and after-sales efficiency will gradually offset mix pressure. Conversely, if every DCU order requires extensive customization, delivery, and adaptation, the faster revenue grows, the greater the expense pressure and the harder it is to defend gross margin. The best future financial signal for Hygon is not a sudden high gross margin in a given quarter, but stable gross margin despite product-mix changes, alongside a slowly declining expense ratio.
Cash flow is likewise a shadow indicator of repurchasing. Platform-type orders usually make it easier to form rolling procurement and predictable collections, while project-type orders tend to create volatility in inventory, receivables, and acceptance timing. If Hygon can improve operating cash flow while revenue is growing rapidly, that indicates relatively high-quality customer demand. If revenue grows rapidly but cash flow continues to lag, investors need to revisit whether orders are overly concentrated, delivery is complex, or customer acceptance is being extended.
Therefore, follow-up research on Hygon should not only track new products and target prices. More useful questions are: Which customers have moved from pilot to expansion? Which workloads have moved from non-core to core? Which software stacks have moved from runnable to usable? Which projects have formed continuous repurchasing? Which revenue comes from customers outside Sugon? These questions may not offer the excitement of target prices, but they determine whether Hygon is a high-beta theme or a platform company capable of long-term re-rating.
Another easily overlooked variable is that shareholders and the industry ecosystem will affect Hygon’s boundaries. Sugon is both a major shareholder and an important customer and system entry point. This relationship makes it easier for Hygon to complete full-system validation and land benchmark projects in the early stage. But for a chip platform to scale, it ultimately cannot rely on a single system partner. Hygon needs to maintain Sugon synergies while continuing to bring more server OEMs and industry customers into validation; otherwise, the market will interpret its growth as intra-system orders rather than an open ecosystem.
This is also what remains worth watching after the termination of the merger by absorption. If the merger had proceeded, Hygon could have gained a more complete system chain; with the merger terminated, it retains the independence of a chip company and an open customer boundary. Neither path is absolutely better or worse. The key is whether the company can retain its synergy advantage while avoiding a narrowing of its customer base. If Sugon continues to contribute benchmark projects in the future while other server vendors, telecom operators, and financial customers keep growing, termination of the merger may instead help Hygon preserve its platform purity.
Capex and R&D; cadence should also be placed within the repurchasing framework. Hygon does not need to bear large-scale manufacturing capex like a foundry, but it must continue investing in front-end design, validation, software stack, customer engineering, and ecosystem adaptation. R&D; investment pressures profit in the short term and determines product generations in the long term. Investors cannot simply demand cost cuts, nor can they unconditionally accept persistently high expenses. The most reasonable requirement is that R&D; investment must translate into higher-end products, a broader customer base, and more stable repurchasing.
If R&D; expenses remain high while customer diffusion stalls, it means investment has not yet become platform capability. If the R&D; expense ratio falls too quickly while the product roadmap slows, the company may be sacrificing long-term competitiveness. Only when revenue expansion, customer repurchasing, and product iteration occur together is a declining R&D; expense ratio a good signal. Hygon’s future profit elasticity should ideally not come from “spending less,” but from “using the same R&D; system to serve a larger revenue base.”
Cash flow will ultimately judge the investment thesis. Hygon can deliver very high revenue in a given quarter, and it can also show attractive orders because of major-customer concentration. But if those orders require longer payment terms, higher inventory, and more customized support, the free cash flow shareholders actually receive will not improve in sync. Conversely, if orders come from more customers, product configurations are more standardized, and software migration is smoother, revenue growth will convert into cash collection more quickly. For a chip platform company, the income statement answers “how much was sold,” while cash flow answers “whether it was worth selling.”
Therefore, Hygon’s ideal path is not to press all resources into a single product to chase short-term revenue, but to form a replicable combination of CPU, DCU, server partners, and software ecosystem. The first round of customer procurement solves localization and supply issues; the second round solves expansion and stability issues; the third round is where platform stickiness truly forms. When customers no longer revalidate every purchase, but naturally expand along the same architecture, Hygon’s valuation can shift from high beta to high certainty.
This path is slow, but it is more reliable than a single order. The value of a chip platform is not selling goods once, but making customers default to continuing with the same architecture in the next budget cycle. If Hygon can achieve this, what investors see will no longer be just domestic-substitution orders, but a gradually deepening customer-relationship curve.
The longer this customer-relationship curve, the lower Hygon’s dependence on any single project or customer, and the stronger the predictability of its income statement. At that point, the market will be more willing to view it through the lens of a platform company rather than a project company. This is where all judgments converge, and it is the main axis for future reviews. It needs continuous verification, no relaxation, and follow-through to the end.
XVI. Data Scope and Sources
This report uses Hygon Information company announcements, exchange disclosure portals, Bernstein and Morgan Stanley research models, and locally archived CPU, AI infrastructure, and domestic-chip framework materials for cross-validation. Revenue, profit, gross margin, target prices, and scenario assumptions use verifiable table-based scopes from institutional reports; information on company products, customers, shareholders, and roadmap is primarily based on company disclosures and institutional compilation.
Key uncertainties include: institutional-model assumptions for 2026-2028 DCU ramp-up, C86-G5 mass production, domestic advanced-process supply, and customer diffusion still require validation through subsequent quarterly financial reports; target prices and valuation multiples are used only to decompose market expectations and do not constitute trading advice.Hygon Information Deep Dive: Bernstein TP Rmb450, Morgan Stanley Sees Rmb480. Can the DCU/GPU Business Push Hygon from a CPU Company into a Domestic Compute Platform Company?
目录
Too Long; Didn’t Read
I. What Exactly Does Hygon Sell: Not a Single CPU, but an x86 Migration Path
II. From Old Asset to New Asset: From IT Application Innovation CPU Supplier to Domestic Compute Platform
III. Why Revisit CPUs Now: Agentic AI Brings CPUs Back to the Foreground
IV. C86-G5: The Key Product Validation Point for Hygon’s Valuation
V. The DCU Second Curve: Can Hygon Move from a CPU Company to a Platform Company?
VI. Financial Model: Revenue Elasticity Has Emerged; Profit Elasticity Is Still Being Tested
VII. Customers and Ecosystem: Sugon Is the Entry Point, and Also a Concentration Risk
VIII. Horizontal Ranking: Hygon Is Not the Strongest AI Chip, but May Be the Scarcest CPU+DCU Combination
IX. Supply Chain and Software Ecosystem: The Real Moat Is Not One Chip Specification
10. Valuation: The Real Disagreement Behind RMB 450, RMB 480, RMB 680, and RMB 200
11. Core Model: Four Variables Decide Whether Hygon Can Move from “High Valuation” to “High Quality”
12. Risks: Hygon’s Biggest Risk Is Not Demand, but the Delivery Path
13. Tracking Checklist for the Next Four Quarters
14. Conclusion: Hygon Is Not a Cheap Stock, but It Is One of the Few Domestic Compute Companies That Can Address Both CPU and GPU
XV. What Really Needs to Be Verified Is Not Domestic Substitution, but Platform Repurchasing
XVI. Data Scope and Sources
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Bernstein assigns Hygon Information a Rmb450 target price, while Morgan Stanley assigns Rmb480. Both institutions frame Hygon as a CPU + DCU/GPU compute platform. The key is not just domestic CPU substitution, but whether C86-G5 can expand into CSP/AIDC customers, and whether DCU/GPU can move the company from a CPU asset into a domestic compute platform.
Too Long; Didn’t Read
Both institutions are re-rating Hygon’s platform attributes. Bernstein gives Hygon Information a Rmb450 target price; Morgan Stanley gives Rmb480. The core argument is not simply domestic substitution. Bernstein focuses more on expansion of China’s x86 server CPU market and Hygon’s share gains, while Morgan Stanley emphasizes the revenue mix shift after DCU/GPU volume ramps. This raises the market’s requirement for validation of C86-G5 and recurring DCU orders.
C86-G5 is the key product variable that determines whether Hygon moves from “able to substitute” to “able to expand.” G4 has already brought core count, DDR5, and PCIe 5.0 to a usable stage. The key for G5 is 128 cores, 512 threads, 16-channel DDR5, and CXL 2.0. If mass production timing and software adaptation are delivered, it can cover more inference, database, virtualization, and cloud-native scenarios. If G5 is delayed, Hygon can still benefit from IT application innovation, but valuation will fall back to a policy substitution framework.
DCU determines whether Hygon has a second growth curve. Morgan Stanley expects Hygon’s total revenue CAGR to be 47% from 2025 to 2028, with CPU revenue CAGR at 31% and DCU/GPU revenue CAGR at 69%. By 2027, CPU and GPU revenue are expected to be close to 50:50; by 2028, GPU scale is expected to exceed CPU. If this assumption holds, Hygon will no longer be just a CPU company, but a domestic CPU + GPU compute platform company.
The core income statement tension is whether gross margin decline or operating leverage improvement is stronger. In Morgan Stanley’s model, Hygon’s revenue rises from Rmb14.377bn in 2025 to Rmb45.342bn in 2028, while ModelWare net profit rises from Rmb2.545bn to Rmb12.308bn. But gross margin falls from 57.8% to 53.3%, due to a higher DCU mix and intensifying domestic AI chip competition. The real question is whether the R&D; expense ratio can decline from 28.8% to 20.7%, leaving scale benefits for shareholders.
Valuation divergence comes from three worldviews. The base case is continued CPU substitution and DCU volume ramp in commercial AI projects, with Bernstein at a Rmb450 target price and Morgan Stanley at Rmb480. The bull case requires 2025-2028 revenue CAGR above 60%, upward revision to GPU share, and gross margin sustained above 60%. The bear case is slower domestic AI capex, discontinuous large DCU orders, and gross margin falling below 40%. Whether Hygon is expensive depends on which world the market believes in.
Over the next four quarters, watch five numbers. First, whether C86-G5 enters customer sampling and small-batch introduction. Second, whether large DCU customer orders expand from government projects to internet companies and carriers. Third, whether the top-five customer revenue share can decline from 90%. Fourth, whether quarterly gross margin can stabilize near 55%. Fifth, whether 2026 revenue can approach Rmb22.420bn. Unless these five numbers are delivered together, Hygon is not yet “China’s Nvidia,” but a domestic compute platform still moving through product validation.
I. What Exactly Does Hygon Sell: Not a Single CPU, but an x86 Migration Path
Hygon Information (688041.SH) is most easily misread as a “domestic substitution CPU company.” That description is not wrong, but it is too narrow. What Hygon really sells is a server compute path with low migration cost, policy compatibility, and the ability to bind with domestic accelerator cards.
A more accurate one-sentence profile: Hygon is a platform chip company that enters the domestic server ecosystem with x86-compatible CPUs, then uses DCUs to move customers from general-purpose computing toward AI computing. It does not sell consumer electronics chips, nor a single AI accelerator card. It sells the hardest-to-replace foundation in government, enterprise, and cloud data centers: the compatibility relationship among CPU sockets, server motherboards, operating systems, and accelerator cards.
The company’s strongest points are threefold. First, it has an x86 migration advantage. When customers switch from Intel/AMD systems to Hygon, the software reconstruction burden is lower than moving to a completely new instruction set. Second, it has IT application innovation certifications and a government-enterprise customer base, providing the foundation for CPU revenue. Third, it has DCU and full-system ecosystems, allowing it to convert the CPU entry point into accelerator card orders when domestic AI compute is in shortage.
Its weakest points are also threefold. First, advanced process nodes, EDA, and high-end IP remain externally constrained, so technology iteration cannot be extrapolated linearly. Second, the DCU software ecosystem still needs repeated refinement through customer projects and cannot directly match the maturity of Nvidia CUDA. Third, customer concentration is too high. Revenue growth is strong, but the company has not fully proven a replicable, broad customer base.
Therefore, what matters most for Hygon is not the short-cycle logic of “domestic CPU price increases,” but three more specific questions: whether C86-G5 can move x86 CPUs from IT application innovation into commercial cloud; whether DCU can shift the revenue structure from a single engine to dual engines; and whether more CSP, carrier, and industry cloud customers can emerge beyond the Sugon ecosystem. As long as these three questions remain unanswered, Hygon is still in the middle of a re-rating process.
The most important thing to watch in the next earnings report is not a single quarterly revenue figure, but revenue quality. If high revenue growth comes with stable gross margin, the R&D; expense ratio starts to be diluted, and inventories and receivables do not build abnormally, it means high growth is entering the income statement. If revenue is driven by a few projects, gross margin declines, and cash flow lags, the market will first treat it as order delivery, not platform capability delivery.
A truly good Hygon earnings report should show four signals at the same time: a more diversified customer base, higher-end products, a lower expense ratio, and smoother cash flow. Seeing only one means the story is still in progress; seeing three or more means the asset attribute will truly change. Every quarterly report should be reviewed against these four signals, rather than only whether revenue growth looks impressive. This is the core issue, highly important, and must be watched closely.
The key difference between server CPUs and consumer CPUs is not brand awareness, but software ecosystem. In cloud providers, banks, telecom, energy, and government systems, operating systems, databases, middleware, virtualization, containers, application software, and operations tools are all built around instruction sets and platform validation. CPU replacement is not changing a hardware SKU, but migrating the entire software stack. If the performance gap is not unacceptably large, x86 compatibility itself is a commercial barrier.
This is also where Hygon differs from domestic CPU players such as Loongson, Phytium, and Kunpeng. Hygon’s foundation comes from earlier AMD Zen 1 licensing, after which it iterated the C86 series in the Chinese market. It does not have Intel’s or AMD’s global supply capability, nor the absolute performance of the most advanced process nodes. But it has a combination rarely seen in China’s server market: x86 compatibility, domestic certification, a government-enterprise customer base, the Sugon ecosystem, DCU accelerator cards, and a self-developed roadmap that is gradually moving beyond the original licensed architecture.
Hygon CPU’s revenue base comes from IT application innovation and key-industry servers. Morgan Stanley estimates that in the 2025 product revenue mix, the 7000 series CPU accounts for about 59%, the DCU 8000 series about 35%, and the 5000 and 3000 series about 3% each. This structure shows that Hygon is no longer a CPU-only company, but CPU remains the customer entry point and profit anchor.
The strategic significance of DCU lies in bundling. Viewed alone, Hygon’s DCU is not necessarily an absolute technology leader versus domestic AI chips such as Huawei Ascend, Cambricon, and Biren. But if a customer lacks both CPUs and AI accelerator cards, Hygon can package “CPU + DCU” to meet domestic compute requirements. This combination gives it stronger pricing power when AI chip supply is tight, and can bring CPU share from government procurement into cloud providers and AIDC projects.
The urgency for China to localize CPU and GPU supply is rising. CPUs and GPUs are at the heart of AI infrastructure, yet global supply is still dominated by companies such as Nvidia, AMD, and Intel. China’s AI deployment is driving strong demand for compute, but export restrictions on advanced chips are tightening supply.
The key point in this judgment is not that “more restrictions are better,” but that supply constraints change the procurement function. In the past, domestic CPU procurement was mostly driven by compliance and budgets. In the future, cloud provider and AIDC procurement will place more weight on delivery, performance, total cost of ownership, and software adaptation. If Hygon is only a compliance substitute, it is hard for valuation to support the current high multiple. If it becomes a “deliverable domestic x86 + DCU platform” in AI data centers, the valuation anchor will change.
The CPU Frenzy | From Supporting Role Back to Center Stage — A 40,000-Word Panoramic View of the New Compute Bottleneck in the AI Agent Era
II. From Old Asset to New Asset: From IT Application Innovation CPU Supplier to Domestic Compute Platform
Hygon’s first-layer asset attribute is that of an IT application innovation CPU supplier. The “2+8+N” substitution path in IT application innovation drives government, SOEs, and key industries to gradually replace software and hardware. CPU is the underlying compute entry point. Hygon’s special feature is that it is one of the few current domestic server CPU suppliers that can support migration within the x86 ecosystem, so customers do not need to reconstruct all applications onto a completely new instruction set at once.
The advantage of this asset layer is that demand has a floor; the disadvantage is that growth cadence is easily affected by budget cycles and project-based procurement. Historical tracking reports in 2024 and 2025 repeatedly showed one phenomenon: revenue grew rapidly, but margins did not improve linearly. Full-year 2024 revenue guidance implied about 52% YoY growth, and 4Q24 quarterly revenue rose about 44% YoY, but quarterly net margin declined significantly. In 4Q25, revenue was Rmb4.886bn, up 61.5% YoY; the midpoint of 1Q26 revenue guidance was about Rmb4.065bn, up 69% YoY, while margins remained pressured by R&D;, equity incentives, and project expenses.
This is not simply a bad thing. If Hygon only made mature IT application innovation CPUs, margins should be more stable. Margin pressure indicates the company is allocating resources to next-generation CPUs, DCUs, software stacks, and system-level solutions. The question is whether these investments can push the company’s asset attribute from “policy-driven CPU substitution” to “commercial compute platform.”
Hygon is now in a position where 1.0 has been delivered, 2.0 is ramping, and 3.0 still needs validation. The market is willing to assign a high valuation because it wants to buy 3.0 in advance. The market worries the valuation is too high because the financial statements are still mainly determined by 1.0 and the early stage of 2.0.
This state differs from many domestic semiconductor companies. Equipment, materials, PCB, or memory companies usually first see overseas supply chain cycles, then map them to domestic substitution. Hygon’s cycle is directly tied to the supply-demand gap in China’s compute infrastructure. The tighter overseas CPU and GPU supply becomes, the more the Chinese market needs local compute. But local advanced process nodes, EDA, software ecosystems, and major-customer validation will then become new bottlenecks.
CPU Returns to the Center of AI Inference Infrastructure
III. Why Revisit CPUs Now: Agentic AI Brings CPUs Back to the Foreground
Over the past two years, when the market discussed AI hardware, the focus was almost entirely on GPUs, HBM, advanced packaging, and optical modules. CPUs looked like a supporting role: every server needed them, but they lacked an exciting incremental story. Agentic AI changes that.
In multi-agent and complex reasoning workflows, GPUs handle matrix computation, while CPUs handle scheduling, retrieval, tool calling, data preprocessing, network I/O, task orchestration, container management, and system control. An AI agent is not just one model forward pass; it continuously calls models, databases, code interpreters, external tools, caches, and memory systems. The more complex the workflow, the heavier the CPU orchestration load.
Bernstein’s framework is more aggressive: global x86 server CPU TAM could rise from around USD 39 billion in 2025 to around USD 223 billion in 2030. The core assumption is that the CPU:GPU ratio gradually moves from roughly 1:8 today toward 1:1. Morgan Stanley’s framework is relatively more conservative, but it also expects China’s Agentic AI CPU TAM to reach USD 17 billion by 2030, representing about 21% of global demand.
There is no need to mechanically take the midpoint of these two figures. What matters is the direction: AI servers are no longer priced only by GPU count. CPU sockets, memory bandwidth, I/O, CXL, system orchestration, and host-side throughput are beginning to be repriced.
China has one additional variable: inference may commercialize faster than training. Training prioritizes peak performance and is more easily constrained by advanced GPUs and high-bandwidth interconnects; inference places more emphasis on cost, deployment scale, application adaptation, and data security. If Chinese enterprises allocate more AI budgets to vertical-scenario inference, CPU demand elasticity may be higher than in pure training scenarios.
China’s x86 server CPU total addressable market (TAM) is projected to grow significantly from USD 7 billion in 2025 to USD 27 billion by 2030. Despite the rapid expansion of the global market, China is expected to maintain a relatively stable share of approximately 25% to 27%. In terms of shipment volume, China’s server CPU demand is forecast to triple over the next five years.
Hygon’s opportunity is not only that China’s CPU TAM expands, but that it gains share within that TAM. Bernstein expects Hygon’s value share in China’s x86 server CPU market to rise from 19% in 2025 to 36% in 2030, and the self-sufficiency rate to increase from 23% in 2025 to 48% in 2030. If those assumptions hold, Hygon benefits from both market expansion and share gains.
AI CPU TAM Reassessment: USD 132 Billion in 2030 and Repricing AMD and Intel
IV. C86-G5: The Key Product Validation Point for Hygon’s Valuation
C86-G5 is the most important product variable in this report. It determines whether Hygon’s CPU can move from “permitted to procure” to “actively selected for procurement.”
Hygon’s earlier product generations had a clear evolution path. The first-generation Dhyana was the commercialization of AMD Zen1 licensing in 2018, using GlobalFoundries 14nm and establishing the foundation for x86 compatibility. The second and third generations were originally planned to use overseas 7nm capacity, but after the 2019 Entity List designation, Hygon was forced to iterate within China’s manufacturing capabilities. Through architecture, memory, and I/O improvements, the company achieved 30%-50% performance gains per generation. C86-G4 entered sales in 2024, with up to 64 cores and support for DDR5 and PCIe 5.0; Bernstein estimates its process is close to SMIC N+1.
Why is G5 so important? Because cloud vendors and AIDC procurement follow a different logic from Xinchuang procurement. Xinchuang procurement focuses more on domestic compliance and ecosystem usability; commercial data centers focus on performance per watt, compute per rack, memory bandwidth, virtualization density, operations tools, deliverability, and total cost of ownership. Only after the performance gap narrows to a certain level will customers move Hygon from a “compliance backup” into a “cost and supply backup.”
G5’s feasibility mainly comes from three variables.
The first is chiplets. If 128 cores are built as one large die, yield and die-area pressure are too high. If multiple smaller compute dies are combined through packaging interconnects, core-count expansion is no longer completely constrained by advanced process nodes. AMD has already proven that chiplets are an effective path for scaling server CPU cores. Whether Hygon can replicate this engineering path is the first validation point for G5.
The second is self-developed microarchitecture. Hygon cannot rely on Zen1 licensing indefinitely. Bernstein emphasizes that G5 uses a fully self-developed microarchitecture, with targets including IPC improvement, SMT4 thread throughput, and stronger security features. If this view proves correct, Hygon’s technological independence will be stronger; if the specifications look good but real workload performance is insufficient, the market will again question its ability to iterate after moving beyond AMD’s legacy.
The third is memory and I/O. 16-channel DDR5 and CXL 2.0 are not marketing parameters; they are core to AI inference and database workloads. Agentic AI amplifies demand for memory, cache, retrieval, and multi-service orchestration. The CPU does not only run compute; it is also responsible for extensive memory access and device coordination. If G5 delivers on memory bandwidth and the CXL ecosystem, Hygon can move from single-CPU competition to full-platform competition.
The C86-G5 is Hygon’s most ambitious product and the centerpiece of its medium-term growth thesis. It represents a fundamental architectural inflection. Together, these specifications position C86-G5 to be broadly competitive with current available offerings from AMD and Intel nowadays.
Some discipline is needed here: “broadly competitive” in the report does not mean fully catching up with AMD EPYC and Intel Xeon. It is closer to “good enough in supply available to China, domestic certification, and specific workloads.” Hygon does not need to win every benchmark. As long as it can become substitutable in government and enterprise cloud, industry inference, databases, virtualization, and data-center host-side scenarios, it can unlock SAM.
The validation sequence for G5 is also clear: sample testing, customer adaptation, ecosystem certification, small-batch orders, quarterly revenue recognition, and gross-margin stability. If any link breaks, the market will cut the valuation multiple first, rather than wait for full confirmation in financial statements.
V. The DCU Second Curve: Can Hygon Move from a CPU Company to a Platform Company?
If we look only at CPUs, Hygon is a scarce domestic substitution company. If DCU scales, it may become a domestic compute-platform company.
DCU is Hygon’s term for GPU-like accelerator cards, mainly targeting AI training, inference, big-data processing, and scientific computing. Its ecosystem is not equivalent to CUDA, but Hygon has built a software stack including hipBLAS, hipRand, hipFFT, MIOpen, RCCL, OpenCL, the LLVM compiler, and the HIP interface. For customers, whether the hardware can be purchased is only the first step. Whether models, operators, frameworks, debugging tools, and cluster management can run determines whether orders are sustainable.
Morgan Stanley describes Hygon as a “CPU + GPU Compute Platform,” precisely because DCU is no longer just an ancillary business. Morgan Stanley expects:
The most important part of this model is not 2028 revenue of RMB 45.3 billion, but the change in revenue mix between CPU and DCU. Morgan Stanley expects CPU and GPU revenue to be close to 50:50 in 2027, with GPU revenue exceeding CPU revenue in 2028. If this structure materializes, Hygon’s valuation cannot be viewed only through a CPU-company lens; if it does not, Hygon’s valuation will return to the framework of a high-growth domestic CPU company.
DCU has three layers of opportunity.
The first layer is domestic AI chip substitution. With overseas advanced GPU supply constrained, Chinese customers will continue looking for local training and inference chips. Huawei Ascend has the strongest ecosystem, and companies such as Cambricon are also competing for share. Hygon is not the leading single-card player. But Hygon can use its CPU entry point and full-system solutions to win orders, especially in integrated projects that require domestic server platforms.
The second layer is inference-side cost. As Chinese large models and vertical applications enter commercialization, inference cost becomes more important than peak training performance. If DCU can become “usable, deliverable, and maintainable” across mainstream models, industry models, and private deployments, it does not need to become the world’s strongest GPU to capture a sufficiently large local market.
The third layer is Super-Node. Prior tracking reports mentioned rack-level solutions such as ScaleX640, which integrate Hygon CPUs and DCUs into large-scale parallel computing in a single rack, attempting to address interconnect bandwidth bottlenecks in large-model training. If this system-level capability proves stable, it will push Hygon from “selling chips” toward “selling compute units,” with higher customer stickiness and larger project sizes.
Server Industry Reassessment: From CPU Platforms to AI Acceleration Systems
But DCU is also a major source of risk. First, domestic GPU competition is more intense than domestic CPU competition, and price wars will emerge earlier. Second, DCU gross margin is likely lower than CPU gross margin, so a higher revenue mix will drag down blended gross margin. Third, software ecosystems are difficult to form organically through single-customer projects; Hygon needs to keep investing in compilers, operator libraries, framework adaptation, and developer support. Fourth, concentration among top customers is high. Once large-order timing fluctuates, quarterly revenue and gross margin volatility will be amplified.
Therefore, DCU is not “one more story”; it widens Hygon’s risk-reward profile. If it succeeds, Hygon moves from CPU substitution to a domestic compute platform. If it fails, investors need to accept higher R&D; investment, lower gross margin, and stronger quarterly volatility.
VI. Financial Model: Revenue Elasticity Has Emerged; Profit Elasticity Is Still Being Tested
Hygon’s financial performance in 2024-2026 shows a typical high-growth semiconductor pattern: revenue moves first, margins are confirmed later.
The midpoint of 2024 revenue guidance was about RMB 9.125 billion, up 52% YoY, mainly driven by higher adoption of Xinchuang CPUs and ramp-up of DCU/AI chips. But the 4Q24 net margin midpoint was only 12.9%, below 3Q24’s 28.3%. Growth continued to accelerate in 2025, with 4Q25 revenue of RMB 4.886 billion, up 61.5% YoY, and full-year revenue of RMB 14.377 billion. The midpoint of 1Q26 revenue guidance was about RMB 4.065 billion, up 69% YoY. The revenue curve has already proven that demand exists.
The issue is that the income statement has not yet fully proven operating leverage. In 4Q25, revenue grew strongly YoY, but operating margin and net margin declined QoQ, mainly due to year-end expense recognition, R&D; intensity, share-based compensation, and project investment. In 2026, what the market really needs to see is whether the expense ratio can fall as revenue scales.
There are two key points in this table.
First, gross-margin decline does not mean the model is breaking; it reflects product-mix change. The CPU business has higher gross margin, while the DCU business has lower gross margin in the early ramp phase. A blended gross margin decline from 57.8% to 53.3% is acceptable. The real danger would be gross margin falling below 50%, especially toward 40% as DCU competition intensifies. That would no longer be mix; it would indicate pricing and yield pressure.
Second, the decline in the operating expense ratio is the core of profit elasticity. Hygon must sustain heavy R&D; investment in next-generation CPUs, DCUs, and the software stack, and it cannot cut R&D; for short-term earnings. But if revenue can rise from RMB 14.4 billion to RMB 45.3 billion, the R&D; expense ratio should fall from nearly 29% to around 21%, while sales and administrative expense ratios also need to be diluted by scale. Otherwise, high revenue growth will remain a capitalization narrative rather than becoming EPS.
Hygon’s cash flow also warrants caution. AI chips and server-platform businesses consume inventory, receivables, and supply-chain credit; when customer concentration is high, collection timing has a greater impact on operating cash flow. In Morgan Stanley’s model, CFO is about RMB 2.097 billion in 2025, RMB 3.065 billion in 2026, RMB 3.316 billion in 2027, and only rises sharply to RMB 7.285 billion in 2028. This means 2026-2027 is the validation period for revenue and profit, while cash flow may not break out at the same time.
If one only looks at high revenue growth, Hygon can easily be written up as a linear growth stock. If one looks at margins and cash flow, it is more like a company converting R&D; investment into platform assets. The key question for 2026 is not “will revenue keep growing,” but “can revenue growth flow through to operating margin and cash flow.”
VII. Customers and Ecosystem: Sugon Is the Entry Point, and Also a Concentration Risk
Hygon cannot be analyzed without Sugon. Sugon is Hygon’s largest shareholder; Morgan Stanley shows a 27.96% stake as of 1Q26. At the same time, Morgan Stanley estimates that Hygon’s top five customers accounted for about 90% of revenue in 2025, and that the largest customer may be Sugon, accounting for about 57% of revenue. These numbers explain Hygon’s industrial synergy, but also the market’s concerns.
Sugon’s value lies in access to servers, storage, cloud computing, and high-performance computing systems. Hygon makes CPUs and DCUs; Sugon makes complete machines and systems. If the two integrate smoothly, they can form a closed loop across “chips, machines, systems, and services.” In domestic compute projects, customers usually do not buy a single chip; they procure a deliverable server cluster or compute platform. Sugon’s ecosystem can reduce Hygon’s go-to-market cost.
But customer concentration also amplifies risk. A 90% revenue share from the top five customers means quarterly volatility, project acceptance, payment collection, and related ecosystems can all affect financials. To earn a higher valuation, Hygon must prove it is not merely following Sugon-led projects, but can enter more server OEMs, internet customers, carriers, financial institutions, and industry-cloud procurement systems.
Hygon and Sugon previously planned a share-swap absorption merger, with a transaction value of about RMB 115.967 billion, which was later terminated. The termination itself does not change Hygon’s production and operations, but it leaves a more important question: should Hygon become part of the Sugon system, or maintain the independence and openness of a chip-platform company?
From an investment perspective, the termination is not necessarily negative. If the merger had succeeded, Hygon would have gained more complete system capabilities, but its asset purity could also have been diluted by the complete-machine business. After the termination, Hygon can still cooperate with Sugon while retaining room to supply the broader server ecosystem, including Inspur, Lenovo, H3C, Tongfang, Ruijie Networks, and PowerLeader. For Hygon, the best outcome is not to be tied only to Sugon, but to use Sugon as a benchmark customer and system-validation site, then replicate that model across a broader customer base.
There is a clear metric to monitor: the revenue share of the top five customers. From 2019 to 2025, Hygon’s top-five customer share stayed at or above roughly 90% for a long period. If revenue continues to grow in 2026-2028 but the top-five share does not decline, the market will view Hygon as a project-based company. If the share gradually declines and the revenue contribution from internet companies and carriers rises, the valuation will move closer to that of a platform-type chip company.
VIII. Horizontal Ranking: Hygon Is Not the Strongest AI Chip, but May Be the Scarcest CPU+DCU Combination
In the domestic compute value chain, Hygon’s position needs to be evaluated separately. Ranked by the performance of a single AI accelerator card, it may not be first. Ranked by server CPU ecosystem migration and the CPU+DCU combination, it is near the front.
This table explains why Hygon’s valuation should not be compared only with one domestic AI-chip company, nor only with Intel/AMD P/E multiples. Hygon is a “position asset”: it sits between China’s server x86 migration, domestic compute buildout, and AI inference infrastructure.
If Chinese customers only buy the highest-performance GPUs, Hygon is not the most direct beneficiary. If Chinese customers need a server platform that is available, deployable, able to pass domestic approval, able to run the existing x86 ecosystem, and able to pair with local AI acceleration, Hygon’s value rises.
IX. Supply Chain and Software Ecosystem: The Real Moat Is Not One Chip Specification
The easiest way for semiconductor companies to be misled by stock-price narratives is to treat a single chip’s specifications as the moat. Hygon is the opposite: the specifications of a single CPU or DCU are of course important, but whether it can move through cycles depends on whether four layers of ecosystem are simultaneously established.
The first layer is manufacturing and packaging. Hygon is a fabless design company. Advanced process supply for CPUs and DCUs depends on external foundries, and back-end packaging and testing also require partners. For a Chinese high-end chip company affected by export controls, capacity is not something that appears just by placing an order. If G5 uses a local advanced node close to 7nm equivalent, yield, cost, scheduling priority, and competition for capacity across multiple projects will all affect the mass-production pace. DCU ramp-up will also consume advanced logic capacity, and CPUs and DCUs will compete for resources within the company.
This means Hygon’s capacity model cannot simply be extrapolated from demand. Customers’ willingness to buy is one thing; whether the company can deliver steadily, and whether gross margin after delivery is acceptable, is another. If China’s advanced logic capacity expansion proceeds smoothly in 2026-2027, Hygon will benefit from improved CPU and DCU supply at the same time. If capacity expansion falls short of expectations, Hygon may have enough orders but slow revenue recognition and pressure on gross margin.
The second layer is memory, interconnect, and server support. C86-G5’s 16-channel DDR5 and CXL2.0 only have full value when domestic memory, controllers, motherboards, BIOS, firmware, and system software are mature. A CPU is not a standalone benchmark tool; it is the center of a server platform. DDR5 supply, memory controllers, CXL expansion, PCIe devices, NICs, storage, virtualization, and cloud-native scheduling all need to pass customer validation together.
This is also why the synergy between Hygon and Sugon’s ecosystem is valuable. Complete-machine vendors can jointly tune the CPU, motherboard, memory, DCU, NIC, thermals, power supply, rack, and software, shortening customers’ deployment cycles. If a single chip is strong but the complete-machine solution is unstable, customers will not deploy it at scale. If a single chip is not world-class, but the complete-machine platform is usable, delivery is stable, and software migration costs are low, customers will procure it.
The third layer is the software stack. CPU x86 compatibility is Hygon’s first advantage, but DCU does not have the same ready-made ecosystem dividend. For DCU to be accepted by large-model and industry AI customers, it must solve operator libraries, framework adaptation, compilers, communication libraries, debugging tools, and cluster management. The hipBLAS, hipRand, hipFFT, MIOpen, RCCL, OpenCL, LLVM, and HIP interfaces listed in the report sound like technical terms, but in substance they determine the cost for customers to migrate models from other ecosystems.
The hardest part of the software stack is negative feedback. When there are few customers, the ecosystem develops slowly; when the ecosystem develops slowly, there are few customers. To break this loop, Hygon usually needs benchmark projects, engineering support for major customers, and binding with complete-machine solutions. Government, enterprise, and industry customers may accept higher adaptation costs because localization and data security carry high weight. Commercial CSPs are more sensitive to cost, stability, and development efficiency. Hygon must prove that DCU can not only run, but run at scale in a maintainable way.
The fourth layer is customer validation. For a chip company entering the core systems of cloud vendors, financial institutions, telecom operators, and government and enterprise customers, the most time-consuming part is not signing contracts, but validation. CPUs need to be tested for stability, virtualization, databases, operating systems, power consumption, failure rates, and compatibility. DCUs need to be tested for model accuracy, throughput, operator coverage, cluster communication, failure recovery, and developer experience. Many orders start with pilots, small clusters, and non-core workloads before expanding to large-scale deployment.
Hygon’s investment logic therefore cannot only focus on “what product was released”; it must also look at “whose production system the product entered.” If G5 remains only on the spec sheet, valuation realization will be limited. If G5 enters the actual procurement catalogs of CSPs, carriers, and financial customers, the valuation anchor will change materially. The same applies to DCU: one large order is not enough; consecutive orders and repeat purchases are what matter.
This table also shows the difference between Hygon and ordinary domestic-substitution companies. In an ordinary substitution logic, as long as the localization ratio rises, the company can grow. To receive a higher valuation, Hygon must move from substitution logic to platform logic. Platform logic requires the supply chain, complete machines, software, and customers to all become stronger together.
Therefore, Hygon’s moat is not “we also have 128 cores,” but “a 128-core CPU can be delivered together with DCU, servers, a software stack, and a customer migration path.” If this closed loop holds, Hygon’s business model will increasingly resemble a platform. If one layer is missing, Hygon will revert to being a chip company with high R&D;, project-based revenue, customer concentration, and margin volatility.
10. Valuation: The Real Disagreement Behind RMB 450, RMB 480, RMB 680, and RMB 200
Hygon’s valuation dispersion is large, but the disagreement is not as simple as “expensive” or “cheap.” Bernstein has a RMB 450 target price; Morgan Stanley has a RMB 480 target price. Morgan Stanley’s bull case is RMB 680, while its bear case is RMB 200. When the same research framework produces such a wide range for one stock, it means the core variable is not static earnings, but a commercial worldview.
Morgan Stanley’s RMB 480 target price comes from a residual income model. The key parameters include an 8.0% cost of equity, 50% payout ratio, 25% medium-term growth rate, and 5% terminal growth rate. This valuation implies 34x 2027 sales, roughly 1 standard deviation above the average NTM P/S over the past four years. In other words, the market must believe Hygon is not an ordinary hardware company, but a domestic AI compute platform.
Bernstein’s RMB 450 target price is more tilted toward CPU re-rating. It believes Agentic AI will pull server CPUs back to the center of infrastructure, with China’s x86 server CPU TAM reaching USD 27 billion by 2030 and Hygon’s share continuing to rise. This line of reasoning emphasizes C86-G5 and China’s CPU localization rate more than a pure DCU boom.
The overlap between these two frameworks is Hygon’s real core thesis: CPU is the entry point, DCU is the upside, G5 is the product validation, and customer expansion is the condition for valuation transition.
If investors are only buying CPU substitution, the RMB 450-480 valuation is not cheap. If they are buying a CPU+DCU platform, the market will be willing to tolerate a high P/S. If they are buying a “domestic Nvidia,” that is too aggressive, because Hygon has not yet proven its software ecosystem, single-card competitiveness, or recurring large-customer orders. The most prudent judgment is that Hygon is the scarcest CPU+DCU platform option in China’s compute supply chain, but it is still in the early stage of earnings delivery and should not be statically priced on mature earnings multiples.
Intel Deep Update: Goldman Sachs Sees USD 150; How Server CPU Tailwinds and Foundry Optionality Could Drive a Re-rating
11. Core Model: Four Variables Decide Whether Hygon Can Move from “High Valuation” to “High Quality”
Hygon’s model over the next two years can be compressed into four variables: CPU share, DCU ramp, gross margin, and expense ratio.
Linking these four variables together, Hygon’s earnings leverage is not mysterious.
On revenue, CPU provides steady incremental growth, while DCU provides high elasticity. As long as DCU growth remains meaningfully higher than CPU growth, overall revenue has a chance to sustain high compound growth. On gross margin, a higher DCU mix will weigh on blended gross margin, but as long as CPU gross margin is stable and DCU does not fall into a price war, blended gross margin will still be excellent. On expenses, high R&D; spending is a necessary cost, but once scale is large enough, expense-ratio decline will lift operating margin.
This is why Morgan Stanley’s model shows “gross margin down, but operating margin up.” From 2025 to 2028, gross margin falls from 57.8% to 53.3%, while operating margin rises from 23.7% to 29.0%. Investors who look only at gross margin will underestimate scale effects; investors who look only at revenue will underestimate product-mix risk. The two must be assessed together.
Hygon’s ideal state is to become a platform fee on a “domestic CPU socket + local AI acceleration + server ecosystem.” Each round of domestic compute buildout brings cross-selling of CPUs, DCUs, and whole-server solutions; each round of software adaptation raises customer switching costs. In this state, Hygon’s valuation can remain elevated.
The worst state is that DCU becomes one-off project orders, CPU remains confined to IT-application innovation budgets, expenses stay high, and customer concentration does not decline. Hygon would still have revenue growth, but the market would view it as a project-based hardware company, making a high P/S difficult to sustain.
12. Risks: Hygon’s Biggest Risk Is Not Demand, but the Delivery Path
Hygon’s demand narrative is strong. China AI infrastructure, localized procurement, CPU resurgence, x86 migration, and DCU substitution are all real variables. But strong demand does not equal strong returns, especially for chip companies, where the execution path is usually harder than demand.
First, EDA and IP dependence is a long-term risk. Advanced CPU design cannot do without EDA tools, IP libraries, and technical support. After Hygon was placed on the Entity List, access to overseas tool updates, IP libraries, and technical support became uncertain. Domestic EDA is improving, but there is still a gap in the full digital IC workflow. Whether iterations after G5 can maintain cadence is the long-term valuation ceiling.
Second, advanced-node supply is a capacity risk. Hygon’s CPU and DCU products both need to compete for limited domestic advanced logic capacity. Even if demand is sufficient, wafer allocation, yield, packaging, and testing can all constrain shipments. China’s AI chip shortage will improve Hygon’s bargaining power, but it will also force Hygon to compete with other priority projects for capacity.
Third, DCU competition will erode gross margin faster. CPUs have a relatively clear competitive landscape due to x86 compatibility and IT-application innovation certification. AI accelerator cards have more local players, and customers can switch more easily among performance, price, and ecosystem. If DCU gross margin falls too quickly, revenue growth will be consumed by margin pressure.
Fourth, customer concentration amplifies financial volatility. The top five customers contributing roughly 90% of revenue in 2025 is not a small issue. Large-customer project timing, acceptance cycles, collections, and inventory strategies will all affect Hygon’s quarterly financials. Before customer concentration declines, Hygon will find it hard to be viewed as a fully mature platform company.
Fifth, valuation already reflects a lot of good news in advance. At the time of Morgan Stanley’s report, Hygon’s market cap was about RMB 813.3 billion, and 2027 P/S was still high. A high valuation can exist, but it requires positive feedback every quarter. If any one of C86-G5, DCU, gross margin, expense ratio, or customer expansion stays below expectations for consecutive periods, valuation correction will be swift.
Sixth, politics and export controls are not a one-way positive. External restrictions stimulate local substitution, but they also restrict tools, IP, advanced equipment, and supply-chain cooperation. They are positive for demand in the short term, but raise the difficulty of technology iteration over the long term. Hygon’s investment logic should not be written simply as “the more restrictions, the more upside,” but rather as “supply constraints create local demand, but local supply capability must keep up.”
13. Tracking Checklist for the Next Four Quarters
Hygon is not a static asset that can be understood at a glance; it requires quarterly tracking. The most useful work in the next stage is not to repeat the grand narrative, but to monitor specific indicators.
Among these seven items, the first three are the most important. G5 determines CPU TAM expansion, DCU orders determine the second growth curve, and 2026 revenue determines the model’s starting point. Gross margin, expense ratio, and cash flow determine earnings quality.
If 2026 brings a combination of “smooth G5 progress, continuous large DCU orders, revenue near or above RMB 22.4 billion, and gross margin stable around 55%,” Hygon’s high valuation will have further room to digest. If the combination is “revenue growth but rapid gross-margin decline, no reduction in customer concentration, and vague G5 progress,” the market will reclassify it from a platform asset back into project-based hardware.
14. Conclusion: Hygon Is Not a Cheap Stock, but It Is One of the Few Domestic Compute Companies That Can Address Both CPU and GPU
The most attractive part of Hygon Information today is that it stands at the intersection of several real inflection points. CPUs are becoming important again in AI infrastructure; China’s market needs controllable server CPUs; x86 migration lowers customer friction; DCU provides the company with a second growth curve; and Sugon plus the server ecosystem give it a system-level entry point.
But this company is not a risk-free, one-way growth story. Its valuation has already paid upfront for a lot of the future: C86-G5 must progress smoothly, DCU must ramp, customers must expand, expense ratio must decline, gross margin cannot collapse, and cash flow must keep up. Failure to deliver on any one of these conditions is enough for the market to reprice the stock.
The most appropriate description is this: Hygon is the most worth-tracking “CPU+DCU platform option” in China’s compute infrastructure. It is not yet a high-performance chip giant in the global sense, nor is it simply an IT-application innovation CPU company. Its value comes from a narrower but scarcer path: under China’s available-supply and localization constraints, using x86-compatible CPUs to capture the existing server ecosystem, using DCUs to capture local AI acceleration demand, and then using system-level solutions to lock customers into the platform.
Hygon’s next stage is not about proving whether domestic substitution has demand, but about proving whether it can turn demand into sustainable profit. C86-G5 is the first answer sheet, recurring DCU orders are the second, and expense ratio plus cash flow are the third. If it gets all three right, it has a chance to move from high valuation to high quality. If it gets only one right, it will still grow, but valuation will find it hard to remain this forgiving.
This is also what makes Hygon different from most theme trades. Theme trades only need catalysts; platform re-rating requires continuous delivery. Hygon already has catalysts. What it needs to deliver next is execution capability. A real re-rating will not come only from one new-product release, but from customer repeat purchases, ecosystem migration, and margin stability appearing together. Future reviews should continue to revolve around this line.
The Second Engine of the Storage Supercycle: CPU Return, HBM Spillover, and the Re-rating of a USD 1.7 Trillion TAM
Nvidia GTC Deep Dive | From GPU Racks to Token Factories, Nvidia Brings CPU, Storage, Networking, and Power into the Token Economy, Repricing Full-Stack AI Infrastructure
XV. What Really Needs to Be Verified Is Not Domestic Substitution, but Platform Repurchasing
The easiest catalysts for trading Hygon are domestic CPUs, domestic AI chips, and external supply restrictions. These catalysts are real. But if the analysis stops at the catalyst level, Hygon will repeatedly be priced as a thematic stock: valuation rises when news flow strengthens and falls back when project pacing slows. What can truly move Hygon from a theme trade to a platform re-rating is not “whether there is demand for domestic substitution,” but “whether customers are willing to repurchase the same platform.”
Repurchasing matters more than the first order. A first order may come from policy, budget, pilots, supply tightness, or project windows; repurchasing means the product has entered the customer’s production system, and migration costs, operations experience, and software adaptation have begun to accumulate. CPU and DCU repurchases also mean different things. CPU repurchasing indicates Hygon is stable enough across operating systems, databases, middleware, virtualization, and business applications; DCU repurchasing indicates customers can accept its model adaptation, operator coverage, cluster communication, and training/inference efficiency. Only when both forms of repurchasing occur at the same time does this become a platform story.
Platform repurchasing will also change Hygon’s earnings quality. Project-based chip companies are prone to revenue jumps, gross-margin volatility, and longer receivables, because every order is like fighting a new battle. Platform-based chip companies are different. Once customers pass validation, subsequent procurement expands around the same architecture; software adaptation costs are amortized, after-sales and developer-support efficiency improves, and R&D; investment becomes easier to reuse. If Hygon can replicate the validation experience inside the Sugon ecosystem across more server OEMs, cloud providers, and industry customers, its declining expense ratio will not be a financial-model assumption, but the natural result of the business model.
This is also why the share of the top five customers must decline. Customer concentration is not inherently bad; in the early stage, relying on major customers to refine products is necessary. But if the company remains highly dependent on a small number of customers after revenue scales, the market will worry that revenue is merely project transfer rather than ecosystem expansion. Hygon’s best path is to retain Sugon as a highly synergistic customer while gradually adding incremental contribution from Inspur, Lenovo, H3C, telecom operators, financial clouds, local AIDCs, and industry clouds. The more diversified the customer base, the stronger the platform attributes; the more concentrated the customer base, the more order volatility deserves a discount.
Software migration is the underlying reason for repurchasing. For cloud providers and financial customers, the CPU has never been a standalone procurement item. Every migration must validate the operating system, database, virtualization, containers, monitoring, backup, permissions, application performance, and disaster recovery. Hygon’s x86 compatibility advantage is that it reduces this set of migration frictions. The first customer adoption may come from localization requirements, but the second purchase often depends on whether the operations team believes the platform is “controllable, maintainable, and less prone to problems.” Once this reputation forms, it is more valuable than a single benchmark.
DCU migration is harder, and therefore even more worth watching. Large-model customers do not only look at peak chip compute. They look at whether models can run stably, whether operator gaps can be filled, whether training interruptions can recover, whether inference costs can decline, and whether engineering teams can receive continuous support. If Hygon only sells accelerator cards, customers will keep comparing prices against other domestic GPUs. If it sells CPU, DCU, communication libraries, compilers, servers, and rack-level coordination, customer switching costs will be much higher. The essence of platform repurchasing is to shift customers from buying hardware to expanding along an ecosystem.
Margin verification should also be viewed through the repurchasing framework. A rising DCU mix will pressure blended gross margin in the short term, but if repurchasing is stable, yield improvement, software reuse, and after-sales efficiency will gradually offset mix pressure. Conversely, if every DCU order requires extensive customization, delivery, and adaptation, the faster revenue grows, the greater the expense pressure and the harder it is to defend gross margin. The best future financial signal for Hygon is not a sudden high gross margin in a given quarter, but stable gross margin despite product-mix changes, alongside a slowly declining expense ratio.
Cash flow is likewise a shadow indicator of repurchasing. Platform-type orders usually make it easier to form rolling procurement and predictable collections, while project-type orders tend to create volatility in inventory, receivables, and acceptance timing. If Hygon can improve operating cash flow while revenue is growing rapidly, that indicates relatively high-quality customer demand. If revenue grows rapidly but cash flow continues to lag, investors need to revisit whether orders are overly concentrated, delivery is complex, or customer acceptance is being extended.
Therefore, follow-up research on Hygon should not only track new products and target prices. More useful questions are: Which customers have moved from pilot to expansion? Which workloads have moved from non-core to core? Which software stacks have moved from runnable to usable? Which projects have formed continuous repurchasing? Which revenue comes from customers outside Sugon? These questions may not offer the excitement of target prices, but they determine whether Hygon is a high-beta theme or a platform company capable of long-term re-rating.
Another easily overlooked variable is that shareholders and the industry ecosystem will affect Hygon’s boundaries. Sugon is both a major shareholder and an important customer and system entry point. This relationship makes it easier for Hygon to complete full-system validation and land benchmark projects in the early stage. But for a chip platform to scale, it ultimately cannot rely on a single system partner. Hygon needs to maintain Sugon synergies while continuing to bring more server OEMs and industry customers into validation; otherwise, the market will interpret its growth as intra-system orders rather than an open ecosystem.
This is also what remains worth watching after the termination of the merger by absorption. If the merger had proceeded, Hygon could have gained a more complete system chain; with the merger terminated, it retains the independence of a chip company and an open customer boundary. Neither path is absolutely better or worse. The key is whether the company can retain its synergy advantage while avoiding a narrowing of its customer base. If Sugon continues to contribute benchmark projects in the future while other server vendors, telecom operators, and financial customers keep growing, termination of the merger may instead help Hygon preserve its platform purity.
Capex and R&D; cadence should also be placed within the repurchasing framework. Hygon does not need to bear large-scale manufacturing capex like a foundry, but it must continue investing in front-end design, validation, software stack, customer engineering, and ecosystem adaptation. R&D; investment pressures profit in the short term and determines product generations in the long term. Investors cannot simply demand cost cuts, nor can they unconditionally accept persistently high expenses. The most reasonable requirement is that R&D; investment must translate into higher-end products, a broader customer base, and more stable repurchasing.
If R&D; expenses remain high while customer diffusion stalls, it means investment has not yet become platform capability. If the R&D; expense ratio falls too quickly while the product roadmap slows, the company may be sacrificing long-term competitiveness. Only when revenue expansion, customer repurchasing, and product iteration occur together is a declining R&D; expense ratio a good signal. Hygon’s future profit elasticity should ideally not come from “spending less,” but from “using the same R&D; system to serve a larger revenue base.”
Cash flow will ultimately judge the investment thesis. Hygon can deliver very high revenue in a given quarter, and it can also show attractive orders because of major-customer concentration. But if those orders require longer payment terms, higher inventory, and more customized support, the free cash flow shareholders actually receive will not improve in sync. Conversely, if orders come from more customers, product configurations are more standardized, and software migration is smoother, revenue growth will convert into cash collection more quickly. For a chip platform company, the income statement answers “how much was sold,” while cash flow answers “whether it was worth selling.”
Therefore, Hygon’s ideal path is not to press all resources into a single product to chase short-term revenue, but to form a replicable combination of CPU, DCU, server partners, and software ecosystem. The first round of customer procurement solves localization and supply issues; the second round solves expansion and stability issues; the third round is where platform stickiness truly forms. When customers no longer revalidate every purchase, but naturally expand along the same architecture, Hygon’s valuation can shift from high beta to high certainty.
This path is slow, but it is more reliable than a single order. The value of a chip platform is not selling goods once, but making customers default to continuing with the same architecture in the next budget cycle. If Hygon can achieve this, what investors see will no longer be just domestic-substitution orders, but a gradually deepening customer-relationship curve.
The longer this customer-relationship curve, the lower Hygon’s dependence on any single project or customer, and the stronger the predictability of its income statement. At that point, the market will be more willing to view it through the lens of a platform company rather than a project company. This is where all judgments converge, and it is the main axis for future reviews. It needs continuous verification, no relaxation, and follow-through to the end.
XVI. Data Scope and Sources
This report uses Hygon Information company announcements, exchange disclosure portals, Bernstein and Morgan Stanley research models, and locally archived CPU, AI infrastructure, and domestic-chip framework materials for cross-validation. Revenue, profit, gross margin, target prices, and scenario assumptions use verifiable table-based scopes from institutional reports; information on company products, customers, shareholders, and roadmap is primarily based on company disclosures and institutional compilation.
Key uncertainties include: institutional-model assumptions for 2026-2028 DCU ramp-up, C86-G5 mass production, domestic advanced-process supply, and customer diffusion still require validation through subsequent quarterly financial reports; target prices and valuation multiples are used only to decompose market expectations and do not constitute trading advice.