
Hua Hong Grace Deep Dive: Goldman Raises Target to HK$333. From 8-Inch Power Devices to 12-Inch 28nm AI Power Chips, Can the HLMC Acquisition and New Fabs Support the Valuation?
目录
Too Long; Didn’t Read
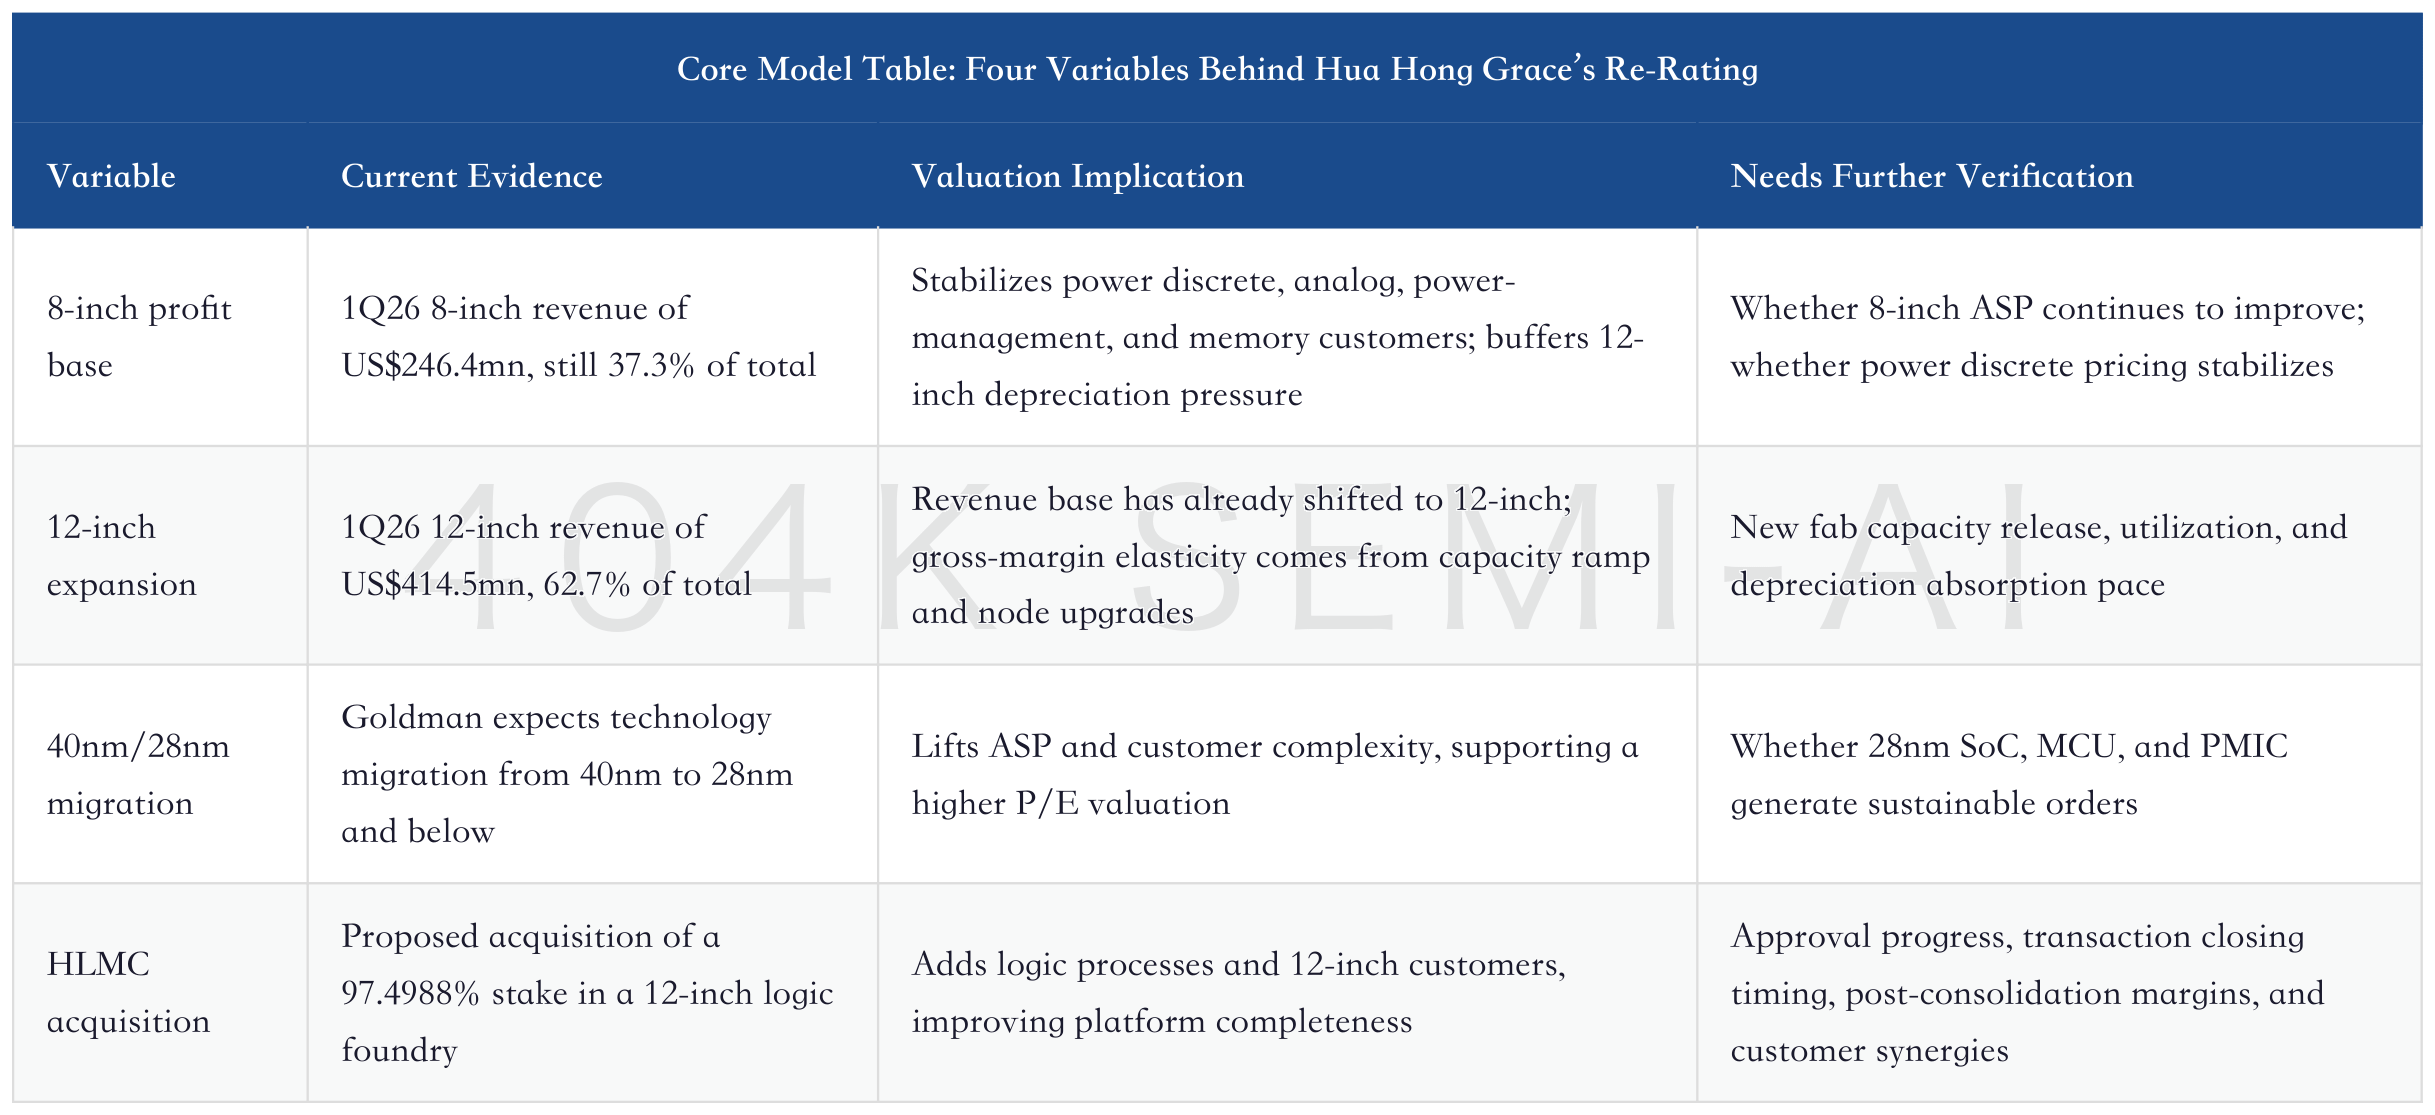
1. What Hua Hong Grace Actually Sells: 8-Inch Protects Profit, 12-Inch Drives Growth
2. Why Goldman Raised the Target Price to HK$333: It Is Buying the 2030E Profit Slope
3. How AI Enters the Hua Hong Model: PMIC, BCD, MCU, and Silicon Photonics Are Closer Than GPUs
IV. 12-Inch and 28nm Migration: From Capacity Expansion to Depreciation Absorption
V. The Real Meaning of the Huali Micro Acquisition: Filling the Logic-Process Gap, Not Simply Buying Revenue
VI. Financial Model: 2026 for Turning Positive, 2027 for Slope, 2028 for Gross Margin
VII. Operating Quality and Balance Sheet: During Expansion, the Biggest Risk Is High Revenue but Weak Cash Flow
VIII. Peer Ranking and Valuation Disagreement: Hua Hong Grace Is Not SMIC, Nor Is It UMC
IX. What to Watch Over the Next Four Quarters: Six Numbers Decide Whether HK$333 Can Hold
X. Risk Checklist: These Four Issues Would Push Hua Hong Grace Back to Mature-Node Valuation
XI. How to Use the Valuation: Do Not Treat HK$333 as a Static Anchor
XII. Scenario Framework: What It Takes to Move from Foundry Cycle to Platform Revaluation
XIII. Investment Conclusion: HK$333 Is Not “Cheap”; It Is a Growth Valuation That Must Be Proven
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Hua Hong Grace’s valuation anchor is shifting from 8-inch power devices and full utilization to four variables: 12-inch 28nm, AI power chips, the HLMC acquisition, and cash flow from new fabs. The key to the HK$333 target price is whether incremental capacity and gross margin can both deliver the profit slope over the next few years.
Too Long; Didn’t Read
New production lines have become the main thread. The core signal in the latest results is that revenue from new production lines has become the main contributor. Goldman raised its target price to pre-price node migration, AI power chips, and the profit slope after new fabs ramp. If gross margin rises in parallel, valuation will continue to look through to long-term profit. If revenue scales but profit does not move, the target price needs to be discounted.
Mature lines remain the profit base. Power discretes, analog and power management, and embedded memory provide cash-flow stability. This part of the business is not responsible for telling the new story, but it absorbs depreciation and stabilizes cash flow. If pricing rolls over, pressure from new capacity expansion will surface faster.
AI demand lands in PMIC and BCD. Hua Hong Grace does not directly benefit from the main GPU compute die. It benefits from AI server power architecture, edge AI devices, MCU, BCD processes, and silicon-photonics support chips, converting AI capex into specialty-process wafer demand.
The HLMC acquisition fills the logic-process gap. After the proposed acquisition of a 97.4988% stake in Shanghai Huali Microelectronics, the company has an opportunity to connect 12-inch logic processes, the customer mix, and its existing specialty-process platform. But the deal still requires approval, so valuation cannot treat it as already consolidated.
HK$333 depends on extrapolating 2030E profit. Goldman uses 92.0x 2030E P/E and discounts it back to 2027E at a 9.3% cost of equity to derive the HK$333 target price. This requires revenue to rise from US$2.40bn in 2025 to US$5.85bn in 2029E, and gross margin to rise from 11.8% to 22.5%.
The disconfirmation points are clear. Over the next four quarters, focus on Q2 revenue guidance of US$690mn-700mn, gross margin of 14%-16%, 12-inch revenue share, growth in 65nm-and-below nodes, capex intensity, and HLMC approval progress. If any one of these falls behind, valuation will compress first.
1. What Hua Hong Grace Actually Sells: 8-Inch Protects Profit, 12-Inch Drives Growth
The company first needs to be understood through its name and assets. HKEX announcements show that from June 2026, 01347.HK changed its Chinese stock short name from “Hua Hong Semiconductor” to “Hua Hong Grace,” and its English stock short name from “HUA HONG SEMI” to “HUA HONG GRACE.” The market will still use “Hua Hong Semiconductor” to understand its historical assets, but the formal name has become “Hua Hong Grace.” This is not a pure renaming event. Behind it are asset integration within the Hua Hong system, 12-inch capacity expansion, and platform restructuring from the HLMC acquisition.
Hua Hong Grace’s underlying business is specialty-process wafer foundry. The company does not manufacture the most advanced logic processes, does not compete with TSMC and Samsung on the 3nm and 2nm main track, and does not mainly compete with SMIC for the same advanced-logic narrative. Its core assets are specialty-process portfolios on 8-inch and 12-inch lines: embedded non-volatile memory, standalone non-volatile memory, power discretes, analog and power management, and logic and RF. These processes usually do not pursue the smallest linewidth. They pursue reliability, automotive- or industrial-grade certification, voltage tolerance, low leakage, analog performance, cost structure, and long-term supply.
This gives Hua Hong Grace a very different cycle profile. In the previous downturn, consumer-electronics destocking, pricing pressure in power devices, and new capacity releases jointly pushed down margins. After 2025, revenue, utilization, and gross margin began to recover, with 1Q26 and Q2 guidance further confirming improvement. This cadence suggests the cycle trough has passed, but the company has not yet entered the most comfortable phase of profit release.
The real change comes from 12-inch share and node structure. In 1Q26, revenue from the company’s new production lines had already become the main contributor, while mature lines still provided the cash-flow base. Revenue from finer nodes grew significantly faster than group revenue. This means the company’s growth is not just about “selling more wafers,” but about gradually migrating toward finer nodes, higher ASP, and more complex processes.
Investors need to split Hua Hong Grace into two layers. The first layer is 8-inch mature specialty processes, responsible for utilization, cash flow, and customer stickiness. The second layer is 12-inch 40nm, 28nm, and future more advanced specialty processes, responsible for revenue growth, gross-margin improvement, and valuation optionality. 8-inch determines the floor; 12-inch determines the ceiling. If Hua Hong Grace is viewed only as a “mature-node foundry,” the slope of 12-inch migration will be underestimated. If investors look only at AI and 28nm, they will miss the impact of 8-inch pricing, depreciation, and cyclical rollback on the profit base.
2. Why Goldman Raised the Target Price to HK$333: It Is Buying the 2030E Profit Slope
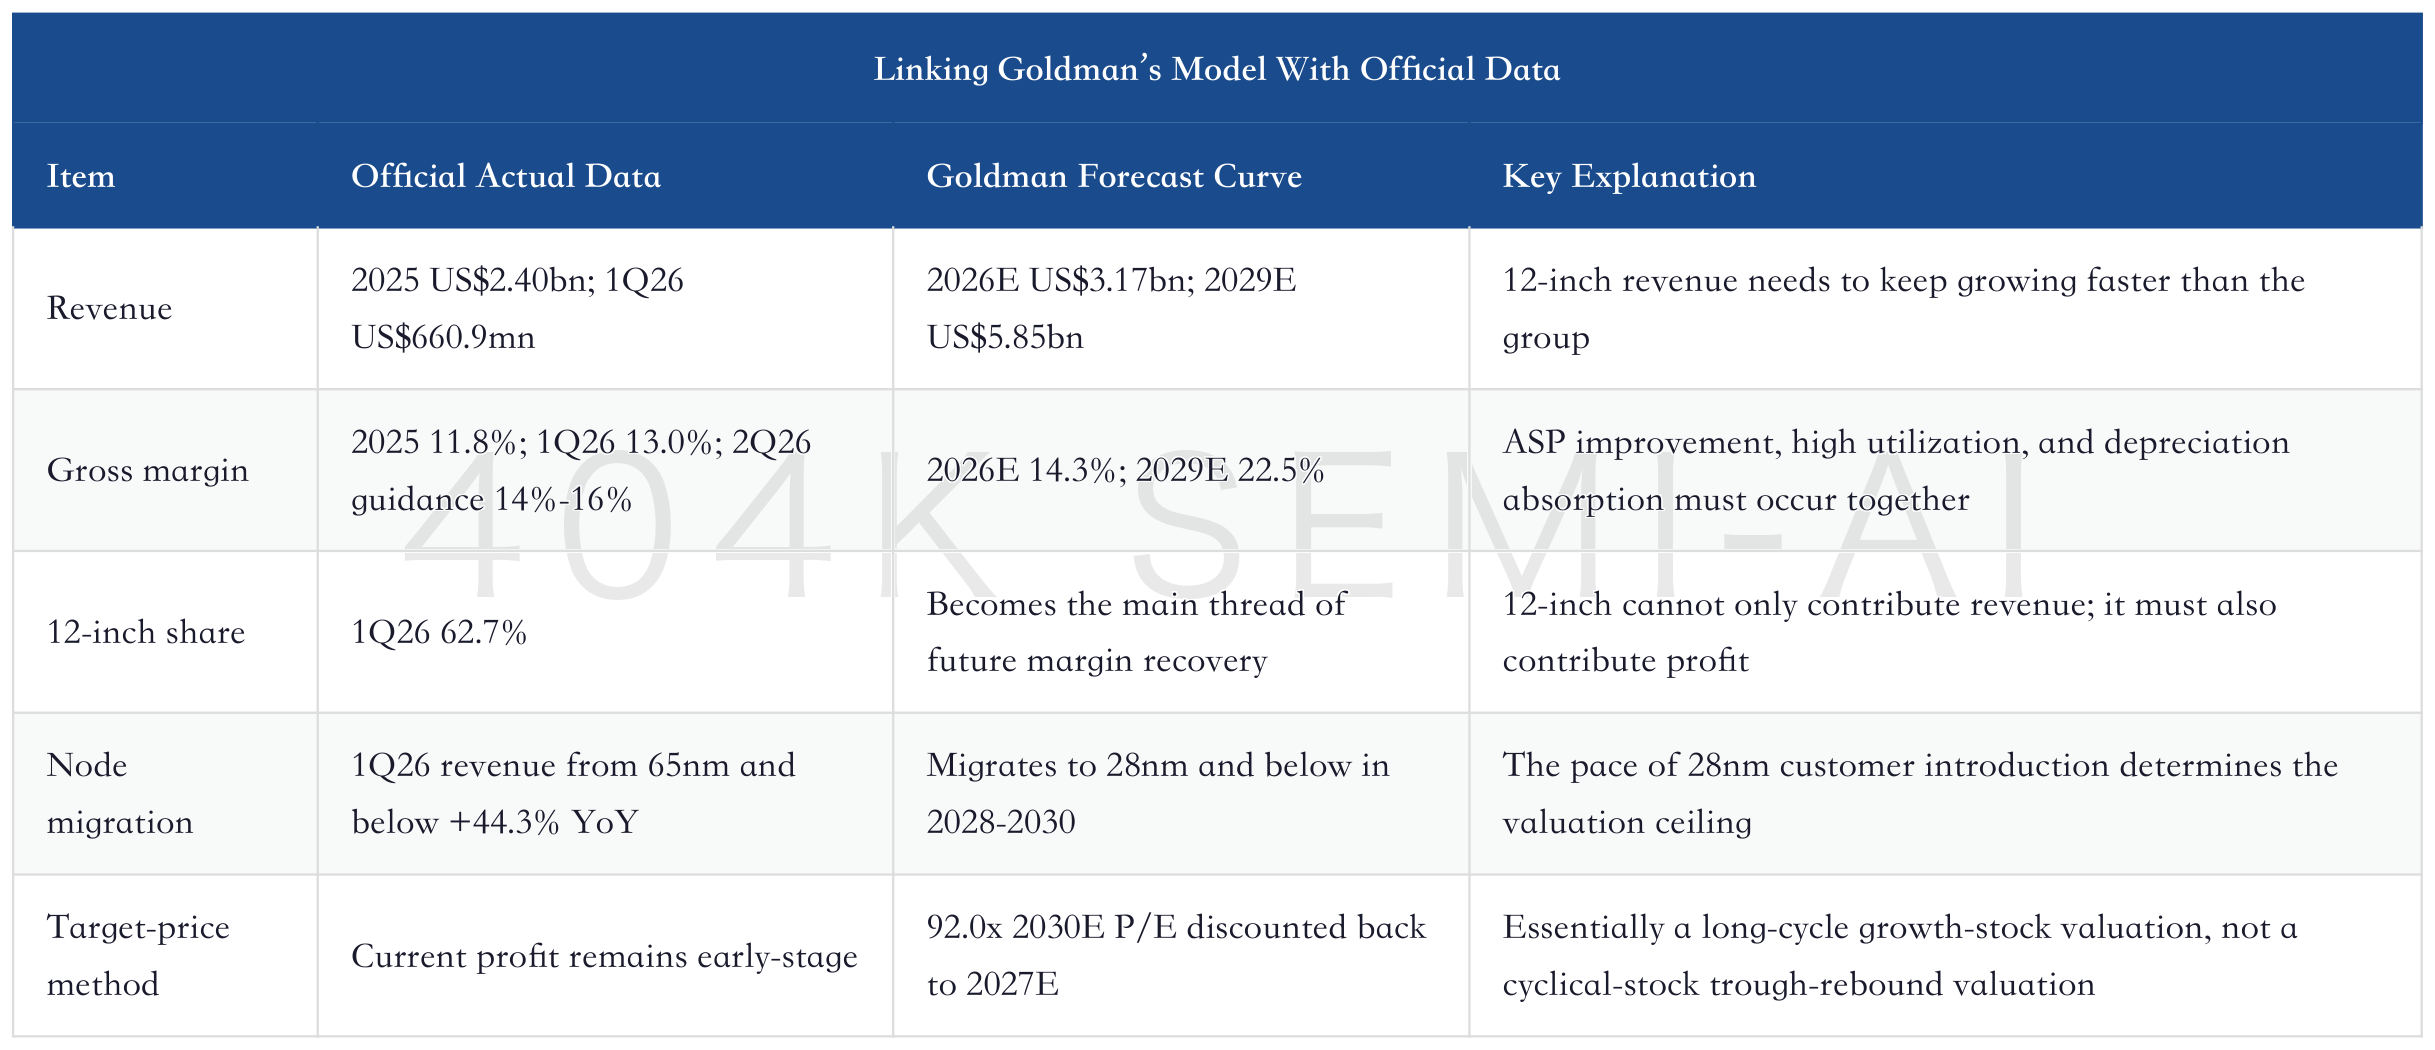
The HK$333 target price looks aggressive, but unpacked, it is a long-cycle profit extrapolation. Goldman raised Hua Hong Grace’s 12-month target price from HK$174 to HK$333 and maintained a Buy rating. This target price is not based directly on short-term 2026E or 2027E earnings. It uses a 2030E target P/E and discounts it back to 2027E. Key assumptions include a 2030E target P/E of 92.0x, 2029E-2030E average EPS growth of 38%, and a 9.3% cost of equity. So the report is not buying the current 13%-16% gross margin. It is buying the asset re-rating after the company enters a higher-margin state around 2030.
Goldman’s model has three core steps. First, revenue expands year by year. Second, gross margin climbs steadily from the low teens. Third, operating margin moves from just turning positive toward the mid-teens. The specific forecasts are in the model table below. The real point is that three things must happen simultaneously: new capacity ramps, nodes upgrade, and the expense ratio is diluted.
The real debate is the P/E, not the target-price number itself. If a mature foundry has a long-term gross margin only in the low teens, it is very hard to justify a forward P/E above 100x. But if it moves from trough margins into a phase of 12-inch, 28nm, AI power chips, and domestic customer expansion, the market will be willing to look at the profit slope first and current valuation second. Goldman lowering the cost of equity to 9.3% from a previously higher framework both reduces the discounting penalty and recognizes a falling asset risk premium for Hua Hong Grace.
This also explains why the share price is sensitive to “AI” and “28nm.” Hua Hong Grace’s 2026E valuation looks very expensive on the surface. Goldman estimates the current market cap still implies a 2027E P/E above 100x. Short-term profit cannot explain this pricing. Only two things can: first, the market is willing to treat it as a China specialty-process platform rather than an ordinary mature-node foundry; second, the market believes margin repair will continue through 2027-2029. If either belief is shaken, valuation will compress first and then wait for financial data to verify it.
The direction of Goldman’s earnings revisions is also instructive. The latest report raises 2027E, 2028E, and 2029E net profit by 1%, 2%, and 8%, respectively. The main reasons are higher 28nm revenue from AI power supply and AI terminal devices, while the 2028E and 2029E operating expense ratios fall with scale expansion. Note that the largest upward revision is to 2029E, not 2026E. This shows short-term performance is only the entry ticket for valuation. The real pricing comes from medium-term node migration and scale effects.
3. How AI Enters the Hua Hong Model: PMIC, BCD, MCU, and Silicon Photonics Are Closer Than GPUs
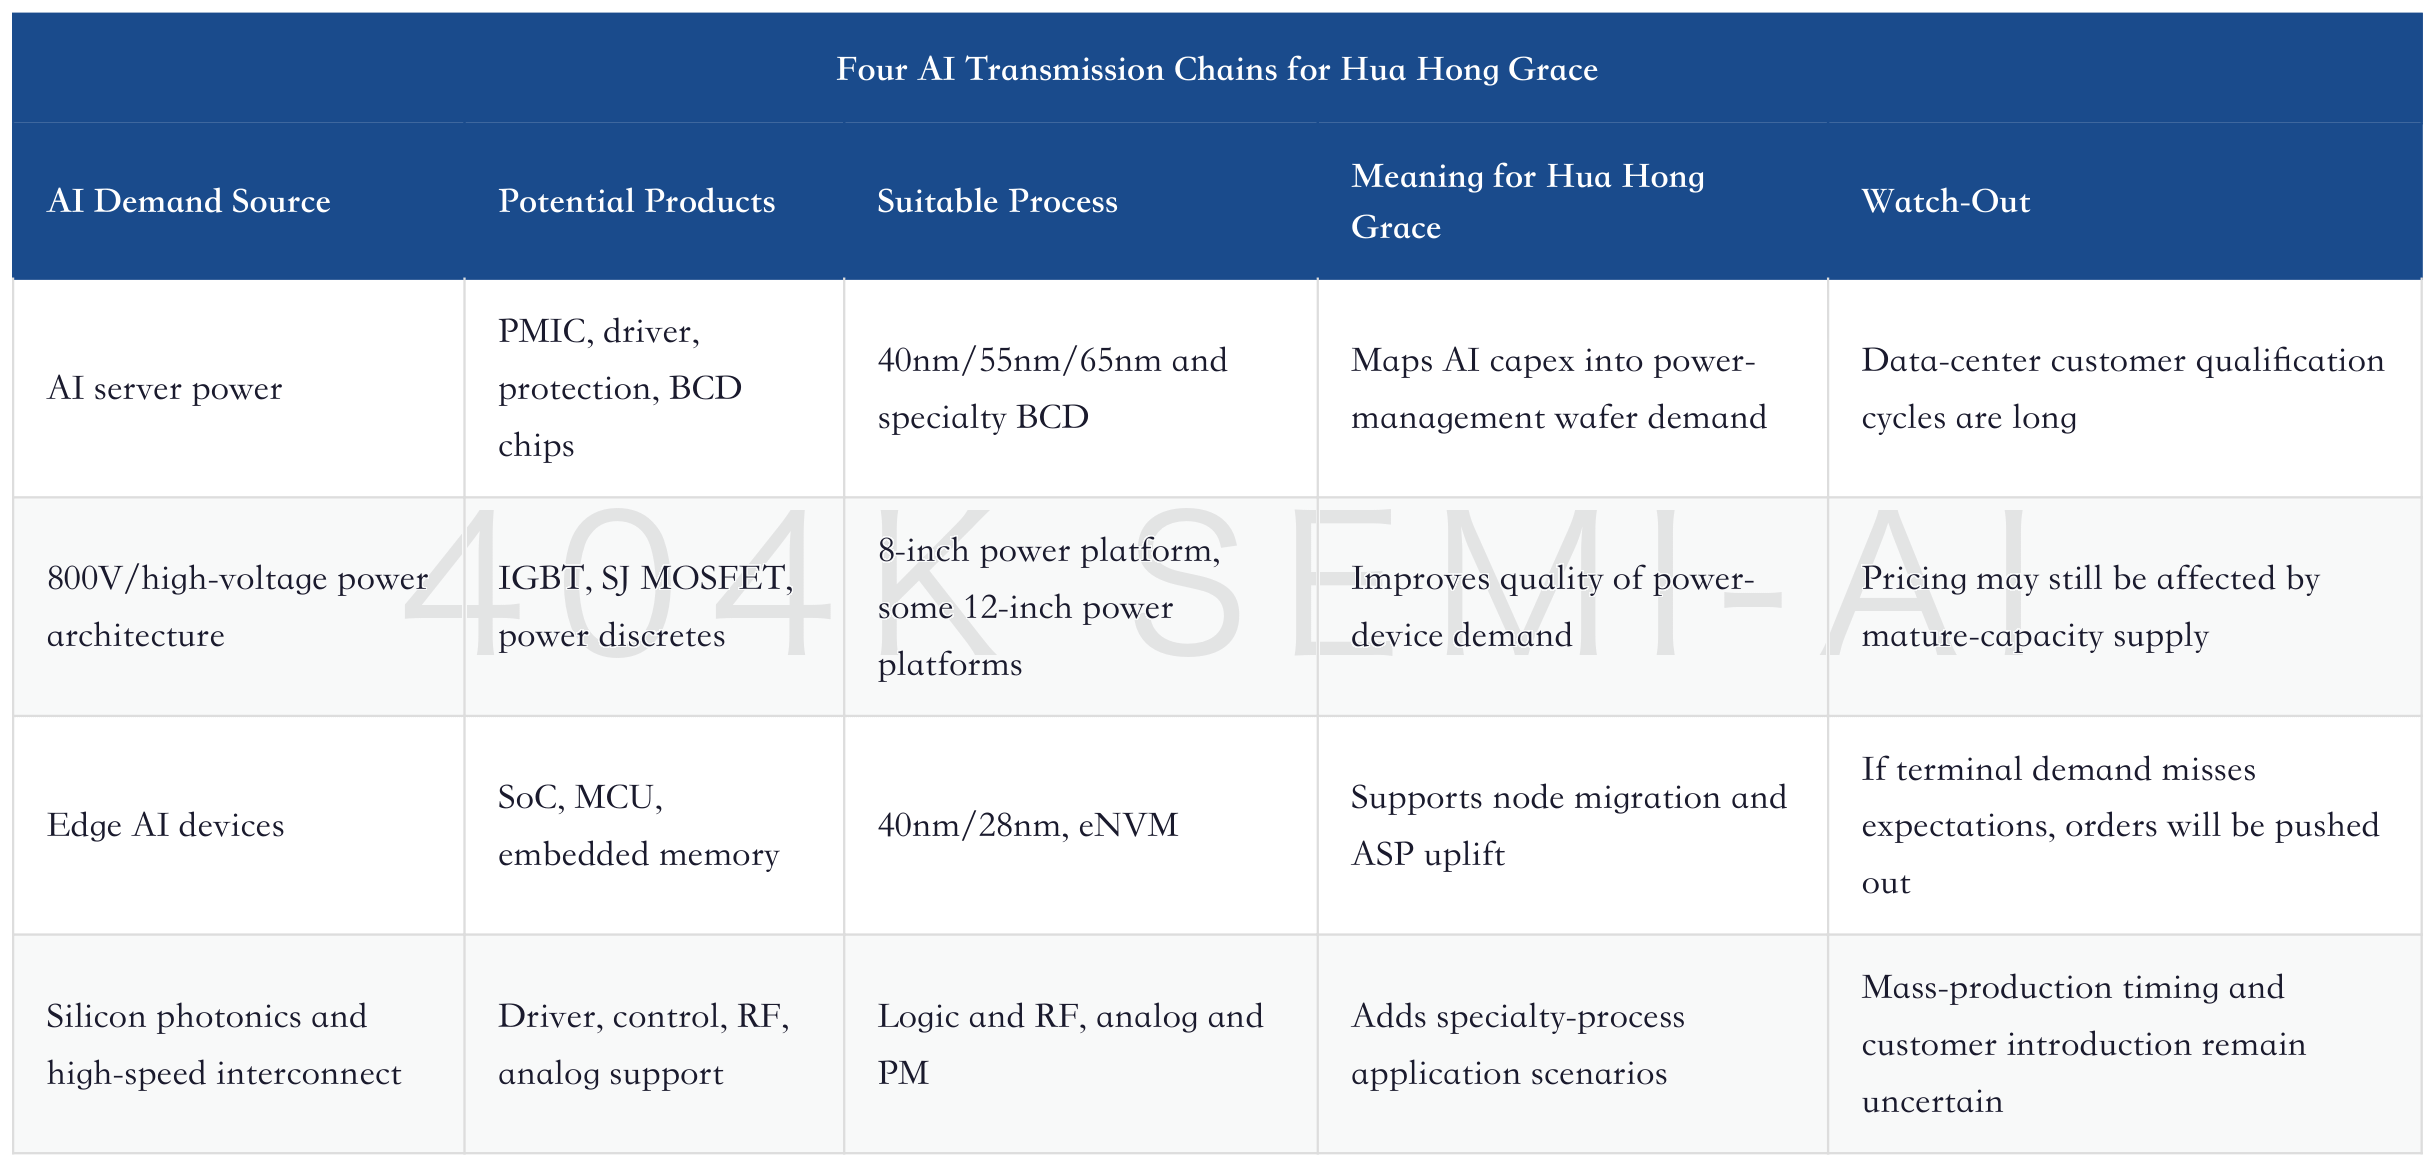
Hua Hong Grace’s AI benefit is not in the main GPU chip, but in power and support chips. AI servers need more power conversion, more complex power management, higher-reliability power devices, and greater analog chip content. Training and inference clusters increasingly resemble a combination of “power equipment + semiconductor systems,” with the power chain upgrading from cabinets and server motherboards to areas around chip packages. Within Hua Hong Grace’s advantaged processes, analog and power management, power discretes, BCD, MCU, embedded memory, and some RF/silicon-photonics support chips can all find positions in this diffusion chain.
The advantage of this transmission path is that it is closer to specialty-process foundries than GPUs are. GPU, ASIC, and HBM main chips require advanced logic, advanced packaging, and high-bandwidth memory. Hua Hong Grace is not the core supplier in that segment. But every AI server needs power-management chips, protection devices, drivers, control MCUs, communications, and sensing support chips. The further the chain moves toward power and analog, the more process differentiation shifts from “the most advanced linewidth” to “voltage tolerance, yield, reliability, cost, long-term supply, and customer validation.” This is exactly the value zone of specialty-process wafer foundry.
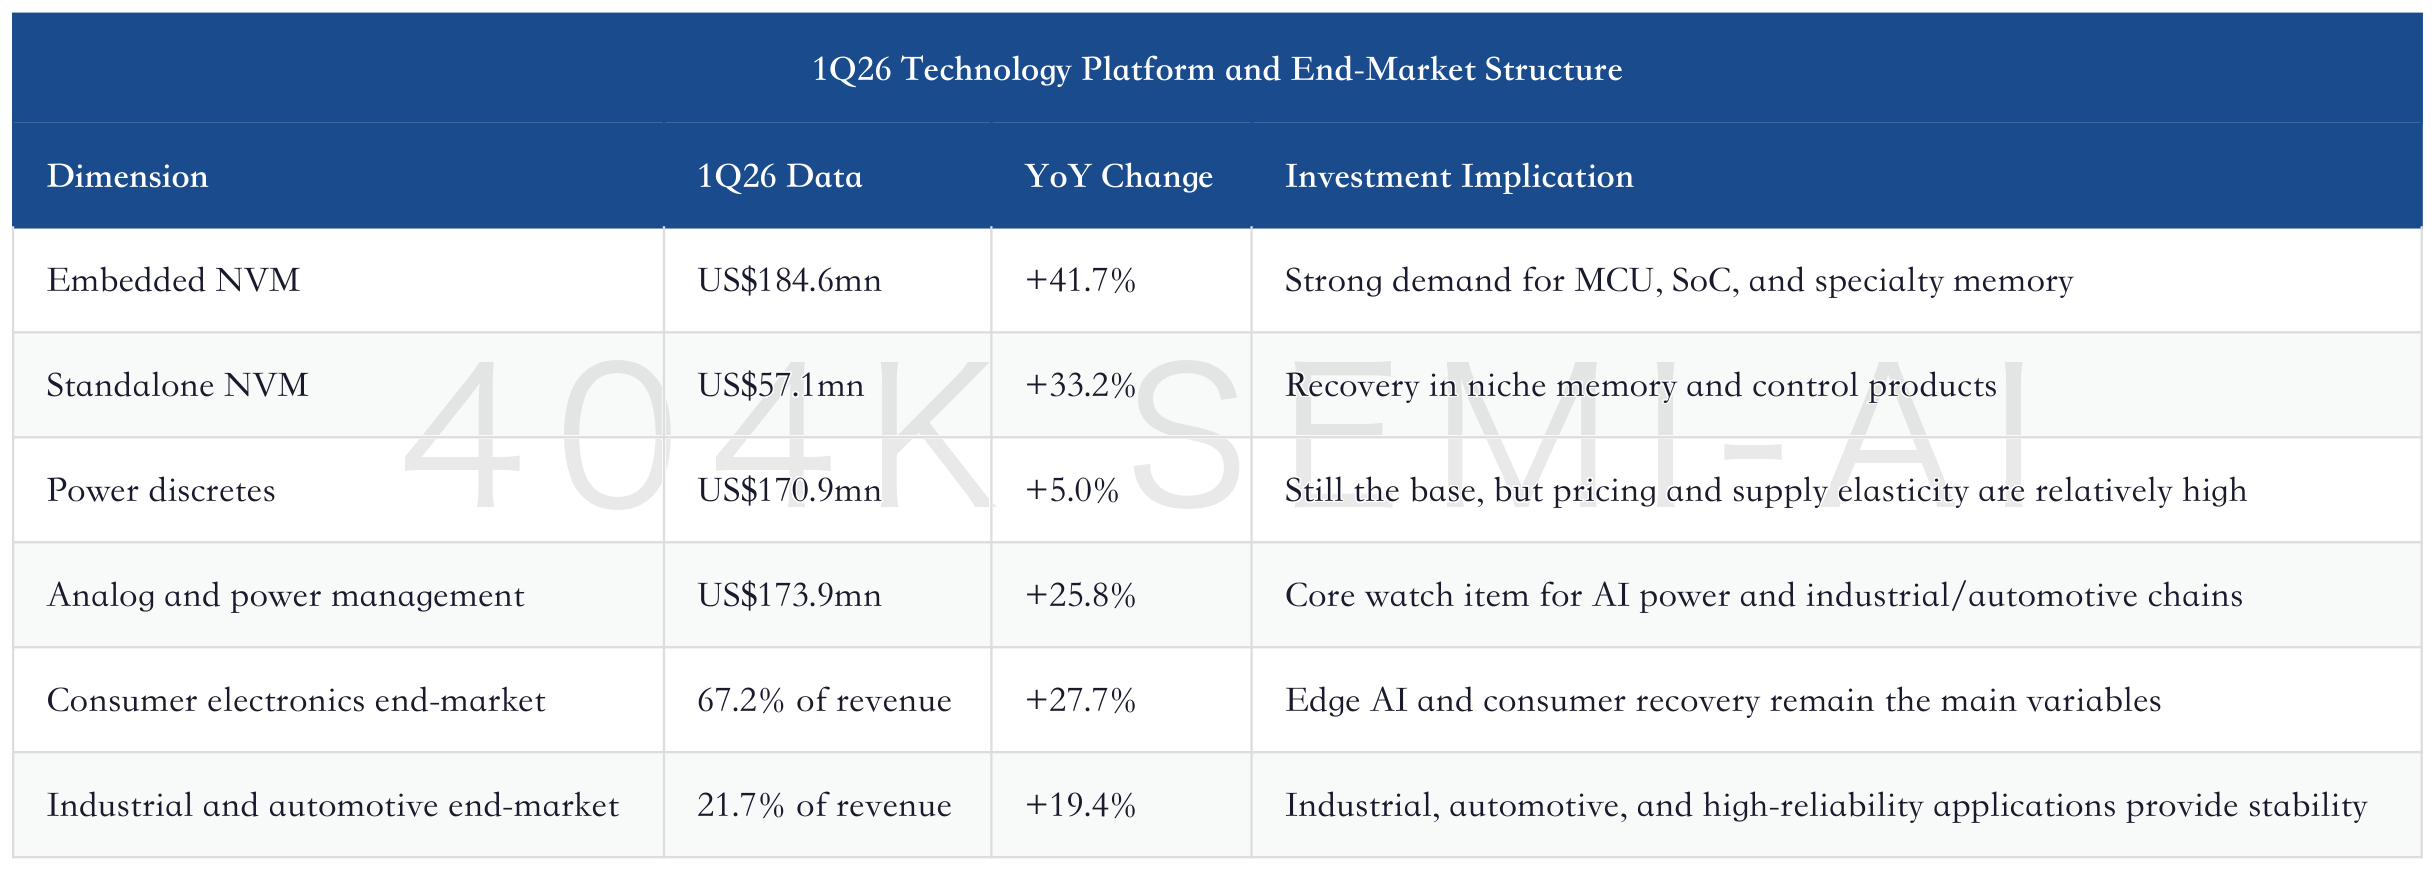
The 1Q26 revenue structure already provides some evidence. Analog and power management, embedded memory, and standalone memory all grew significantly, while power discretes grew more slowly. By end-market structure, consumer electronics remained the largest segment, industrial and automotive formed the second-largest block, and compute revenue share was still small. This shows AI has not directly turned compute-end revenue into the main contributor, but it may already be influencing the process platform through power management, MCU, memory, and industrial applications.
AI devices in consumer electronics and home appliances cannot be ignored either. Goldman attributes part of its upward revision to 28nm revenue to AI devices, including 28nm SoC/MCU in home appliances and consumer electronics. This assumption does not look as exciting as GPUs, but it is more realistic for Hua Hong Grace. AI terminals do not all need the most advanced process. A large volume of edge control, sensing, power, connectivity, and local-inference coprocessors can land on mature or specialty nodes. As long as terminal manufacturers begin embedding AI functions into more devices, 28nm and 40nm specialty processes will have better order visibility than before.
Silicon photonics is another potential incremental driver, but it should not be fully priced in too early. Data-center optical interconnects are moving from 800G to 1.6T, then toward CPO and silicon photonics. Related driver, modulation, control, and power chips will increase specialty-process demand. Hua Hong Grace’s participation in these opportunities is more likely through logic and RF, analog, and power-management platforms, rather than replacing the most core optical-device or advanced-packaging assets. It can add narrative optionality, but it is not enough on its own to support HK$333.
IV. 12-Inch and 28nm Migration: From Capacity Expansion to Depreciation Absorption
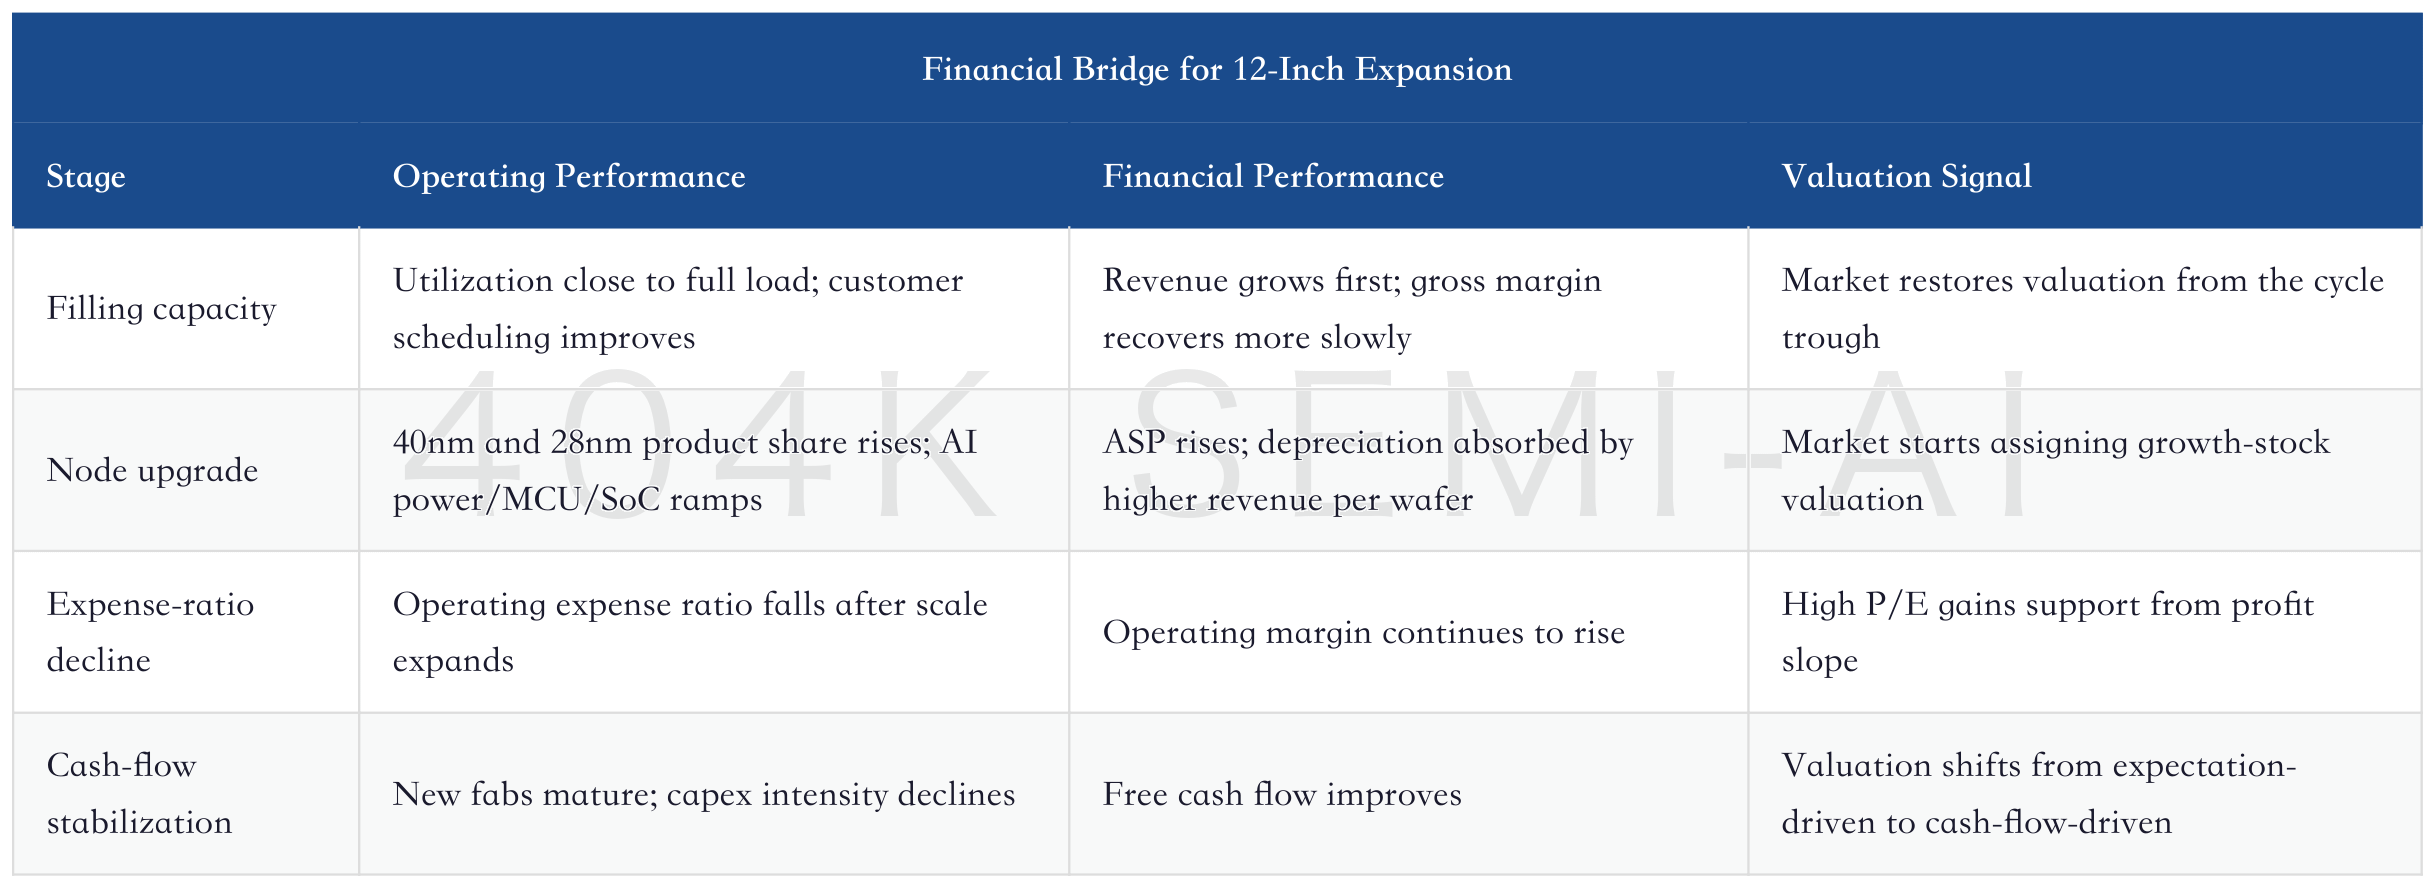
The core tension for Hua Hong Semiconductor is how quickly 12-inch capacity expansion moves from “revenue contribution” to “profit contribution.” In 1Q26, the company’s monthly capacity reached 489,000 8-inch-equivalent wafers, with overall utilization at 99.7%. High utilization makes it easy for investors to turn optimistic, but the economics of 12-inch lines are not determined by utilization alone. They also depend on product mix, node structure, depreciation burden, and customer pricing. When a new line is still ramping, revenue can scale quickly while gross margin lags. The 2024-2025 financials have already shown this tension: revenue recovered earlier than profit.
After 12-inch revenue exceeded 60% of the total, Hua Hong Semiconductor entered the second stage. The first stage is filling 12-inch capacity and proving the line’s value through high utilization and customer demand. The second stage is migrating 12-inch capacity from more mature 55/65nm toward 40nm, 28nm, and higher-ASP products. Only in the third stage, after depreciation is more fully absorbed, product mix becomes higher-end, and the operating expense ratio declines, can margins be magnified. Goldman Sachs’ model has essentially moved into the second and third stages, but actual operations are still in the early part of the second stage.
28nm is not about showing off advanced-process capability; it is the pricing anchor for specialty-process upgrades. For TSMC, Samsung, and Intel, 28nm has long ceased to be a leading node. For specialty foundries, however, 28nm still matters. Many MCU, SoC, display, RF, embedded-memory, and power-management products need a 28nm platform that is mature, reliable, cost-controlled, and supply-secure. If Hua Hong Semiconductor can build customer stickiness on its 28nm platform, what it receives is not an “advanced logic premium,” but a combined premium from “specialty-node scarcity + domestic supply-chain security + AI edge-device diffusion.”
Capex is the cost of this path. In 1Q26, the company’s capex was approximately US$924.9mn, of which US$886.1mn went to 12-inch lines and US$38.7mn to 8-inch lines. This is a very heavy number. It means growth is not asset-light expansion, but ongoing capital-intensive fab expansion. If revenue and gross margin ramp smoothly, capex will become future capacity and cash flow. If orders, ASP, or utilization weaken, depreciation will instead weigh on margins.
Valuation therefore cannot look only at revenue growth. Hua Hong Semiconductor’s 2026-2029 revenue growth curve looks strong, but what really determines the share price is whether gross margin and operating margin can rise in tandem. In Goldman Sachs’ model, gross margin rises from 14.3% in 2026E to 22.5% in 2029E, while operating margin rises from about 1% to about 12%. This is harder than revenue growth and also more valuable. Revenue expansion is only the entry ticket; margin ramp is the main course.
V. The Real Meaning of the Huali Micro Acquisition: Filling the Logic-Process Gap, Not Simply Buying Revenue
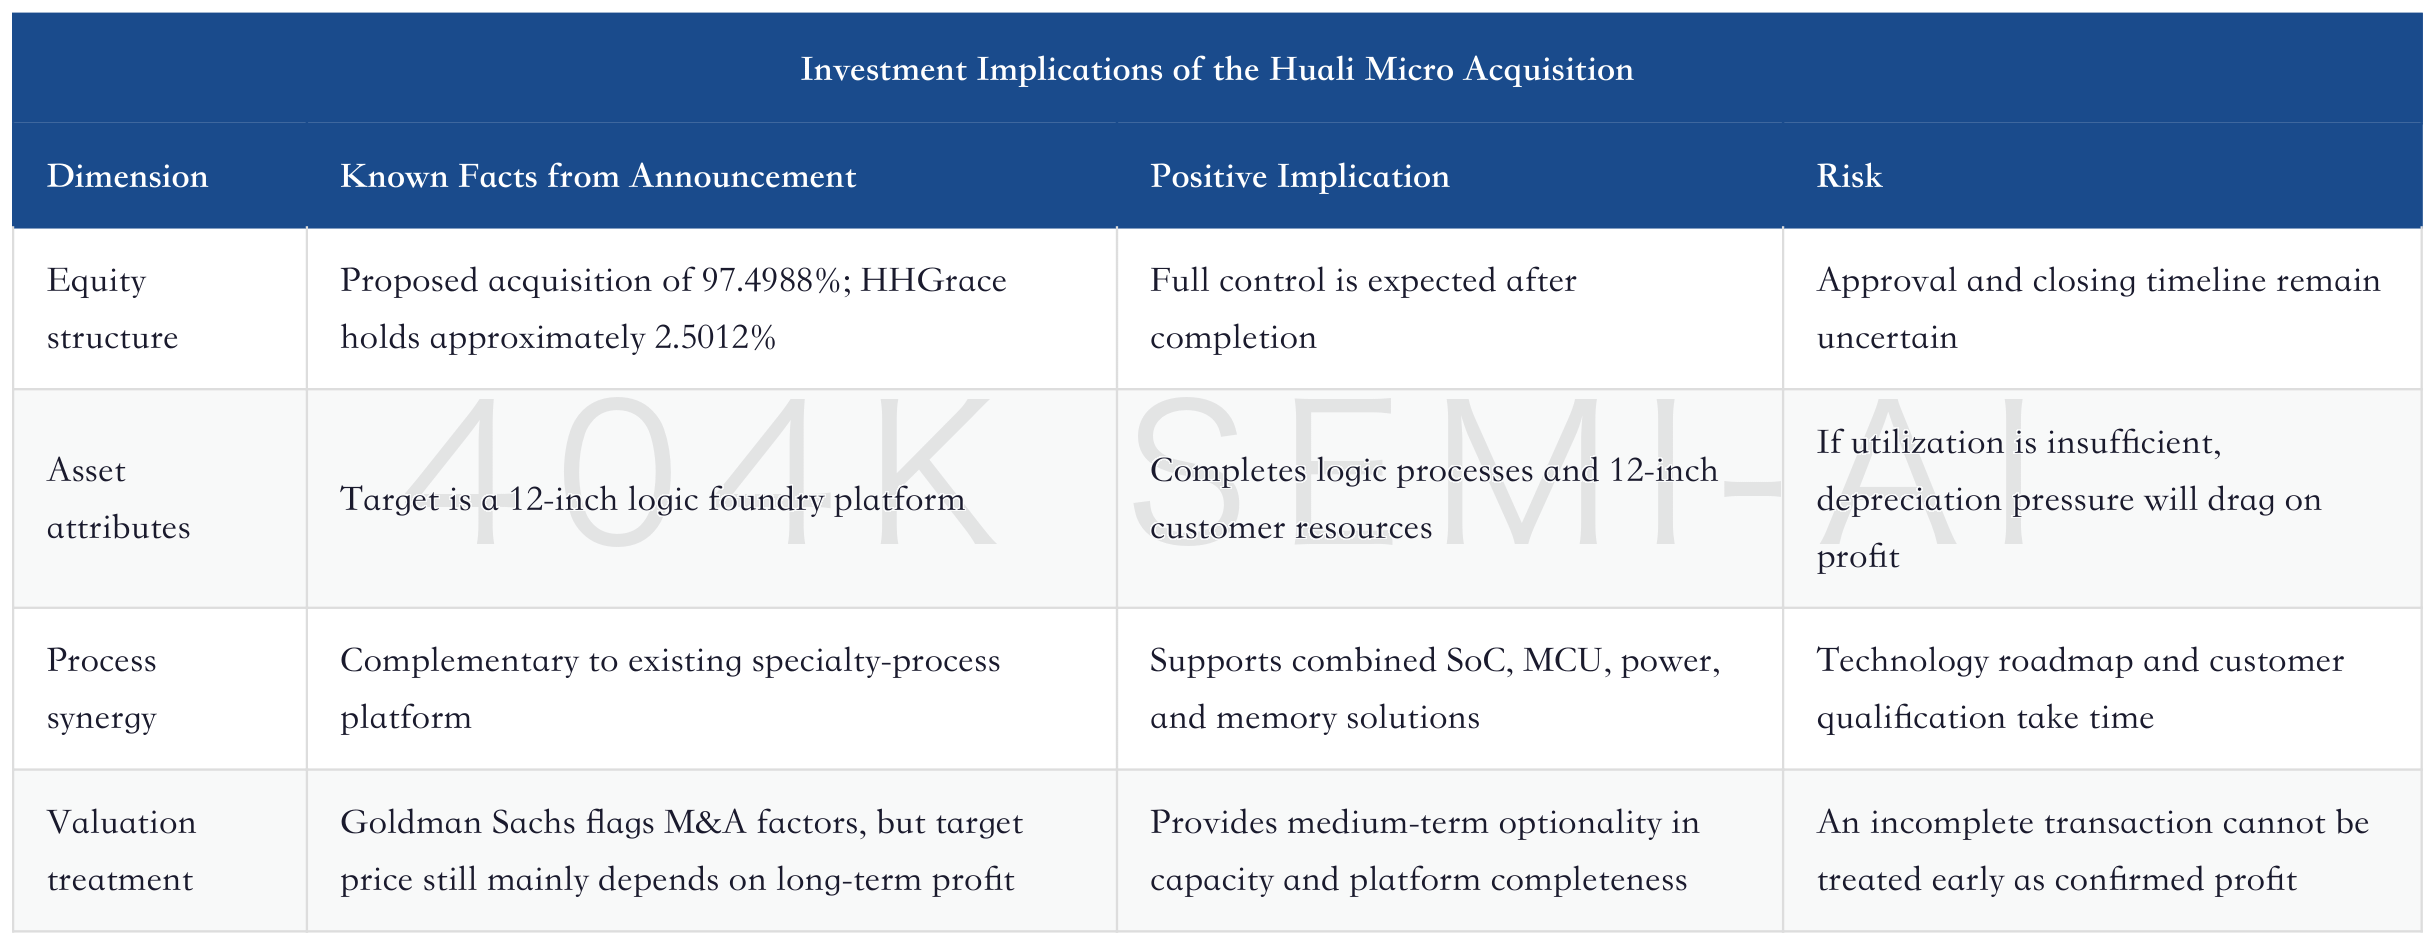
The Huali Micro acquisition should be understood as “process-chain completion.” The transaction announcement shows that Hua Hong Semiconductor plans to acquire a 97.4988% stake in Shanghai Huali Microelectronics, while its subsidiary HHGrace already holds the remaining approximately 2.5012%; if the transaction is completed, the company expects to hold 100% of the target. Huali Micro mainly provides 12-inch integrated-circuit wafer foundry services in China, with a focus on developing logic processes. For Hua Hong Semiconductor, this is not simply buying another fab, but connecting a 12-inch logic platform with its existing specialty-process platform.
Filling the logic-process gap will improve platform completeness. Hua Hong Semiconductor’s historical strengths are in power, analog, power management, memory, and specialty processes. Huali Micro’s 12-inch logic capacity can supplement customer demand in SoCs, MCUs, and some logic products. AI edge devices and power systems increasingly require combined “logic + analog + memory + power” solutions. A single-process platform can easily see customers split orders. If Huali Micro is integrated smoothly, Hua Hong Semiconductor can capture more product combinations on the same group platform.
The approval process should not be written as if consolidation has already happened. The June 11, 2026 announcement shows that the company received an implementation letter from the Shanghai Stock Exchange review center regarding the transaction application documents and submitted the meeting-version restructuring report as required. Completion of the transaction still depends on approval by the competent authorities and satisfaction of relevant conditions. In other words, the Huali Micro acquisition has advanced to substantive review, but it cannot yet be treated as confirmed consolidated profit. Valuation can assign option value, but the financial model needs to retain timing and approval discounts.
The short-term risk of the transaction is integration cost; the long-term value is customer synergy. A 12-inch fab is asset-heavy, carries high depreciation, and requires long customer qualification cycles. The acquisition may not immediately lift margins. If Huali Micro is still in a ramp, technical-upgrade, or customer-mix optimization phase, it may increase depreciation, expenses, and capital needs in the short term. Over the long term, however, logic-process assets can move Hua Hong Semiconductor from a “specialty-process foundry” closer to a “specialty-process + logic-chain-completion platform,” improving customer stickiness and process coverage.
The three numbers most worth tracking after deal completion are clear. First, total 12-inch capacity and utilization after Huali Micro is consolidated. Second, customer cross-selling between Huali Micro’s logic platform and Hua Hong Semiconductor’s existing analog, power, and memory platforms. Third, changes in depreciation, gross margin, and operating expense ratio after consolidation. If these three numbers improve, the Huali Micro acquisition will become an important support for the HK$333 target price. If it merely expands the balance sheet, valuation will instead worry about dilution and cash flow.
VI. Financial Model: 2026 for Turning Positive, 2027 for Slope, 2028 for Gross Margin
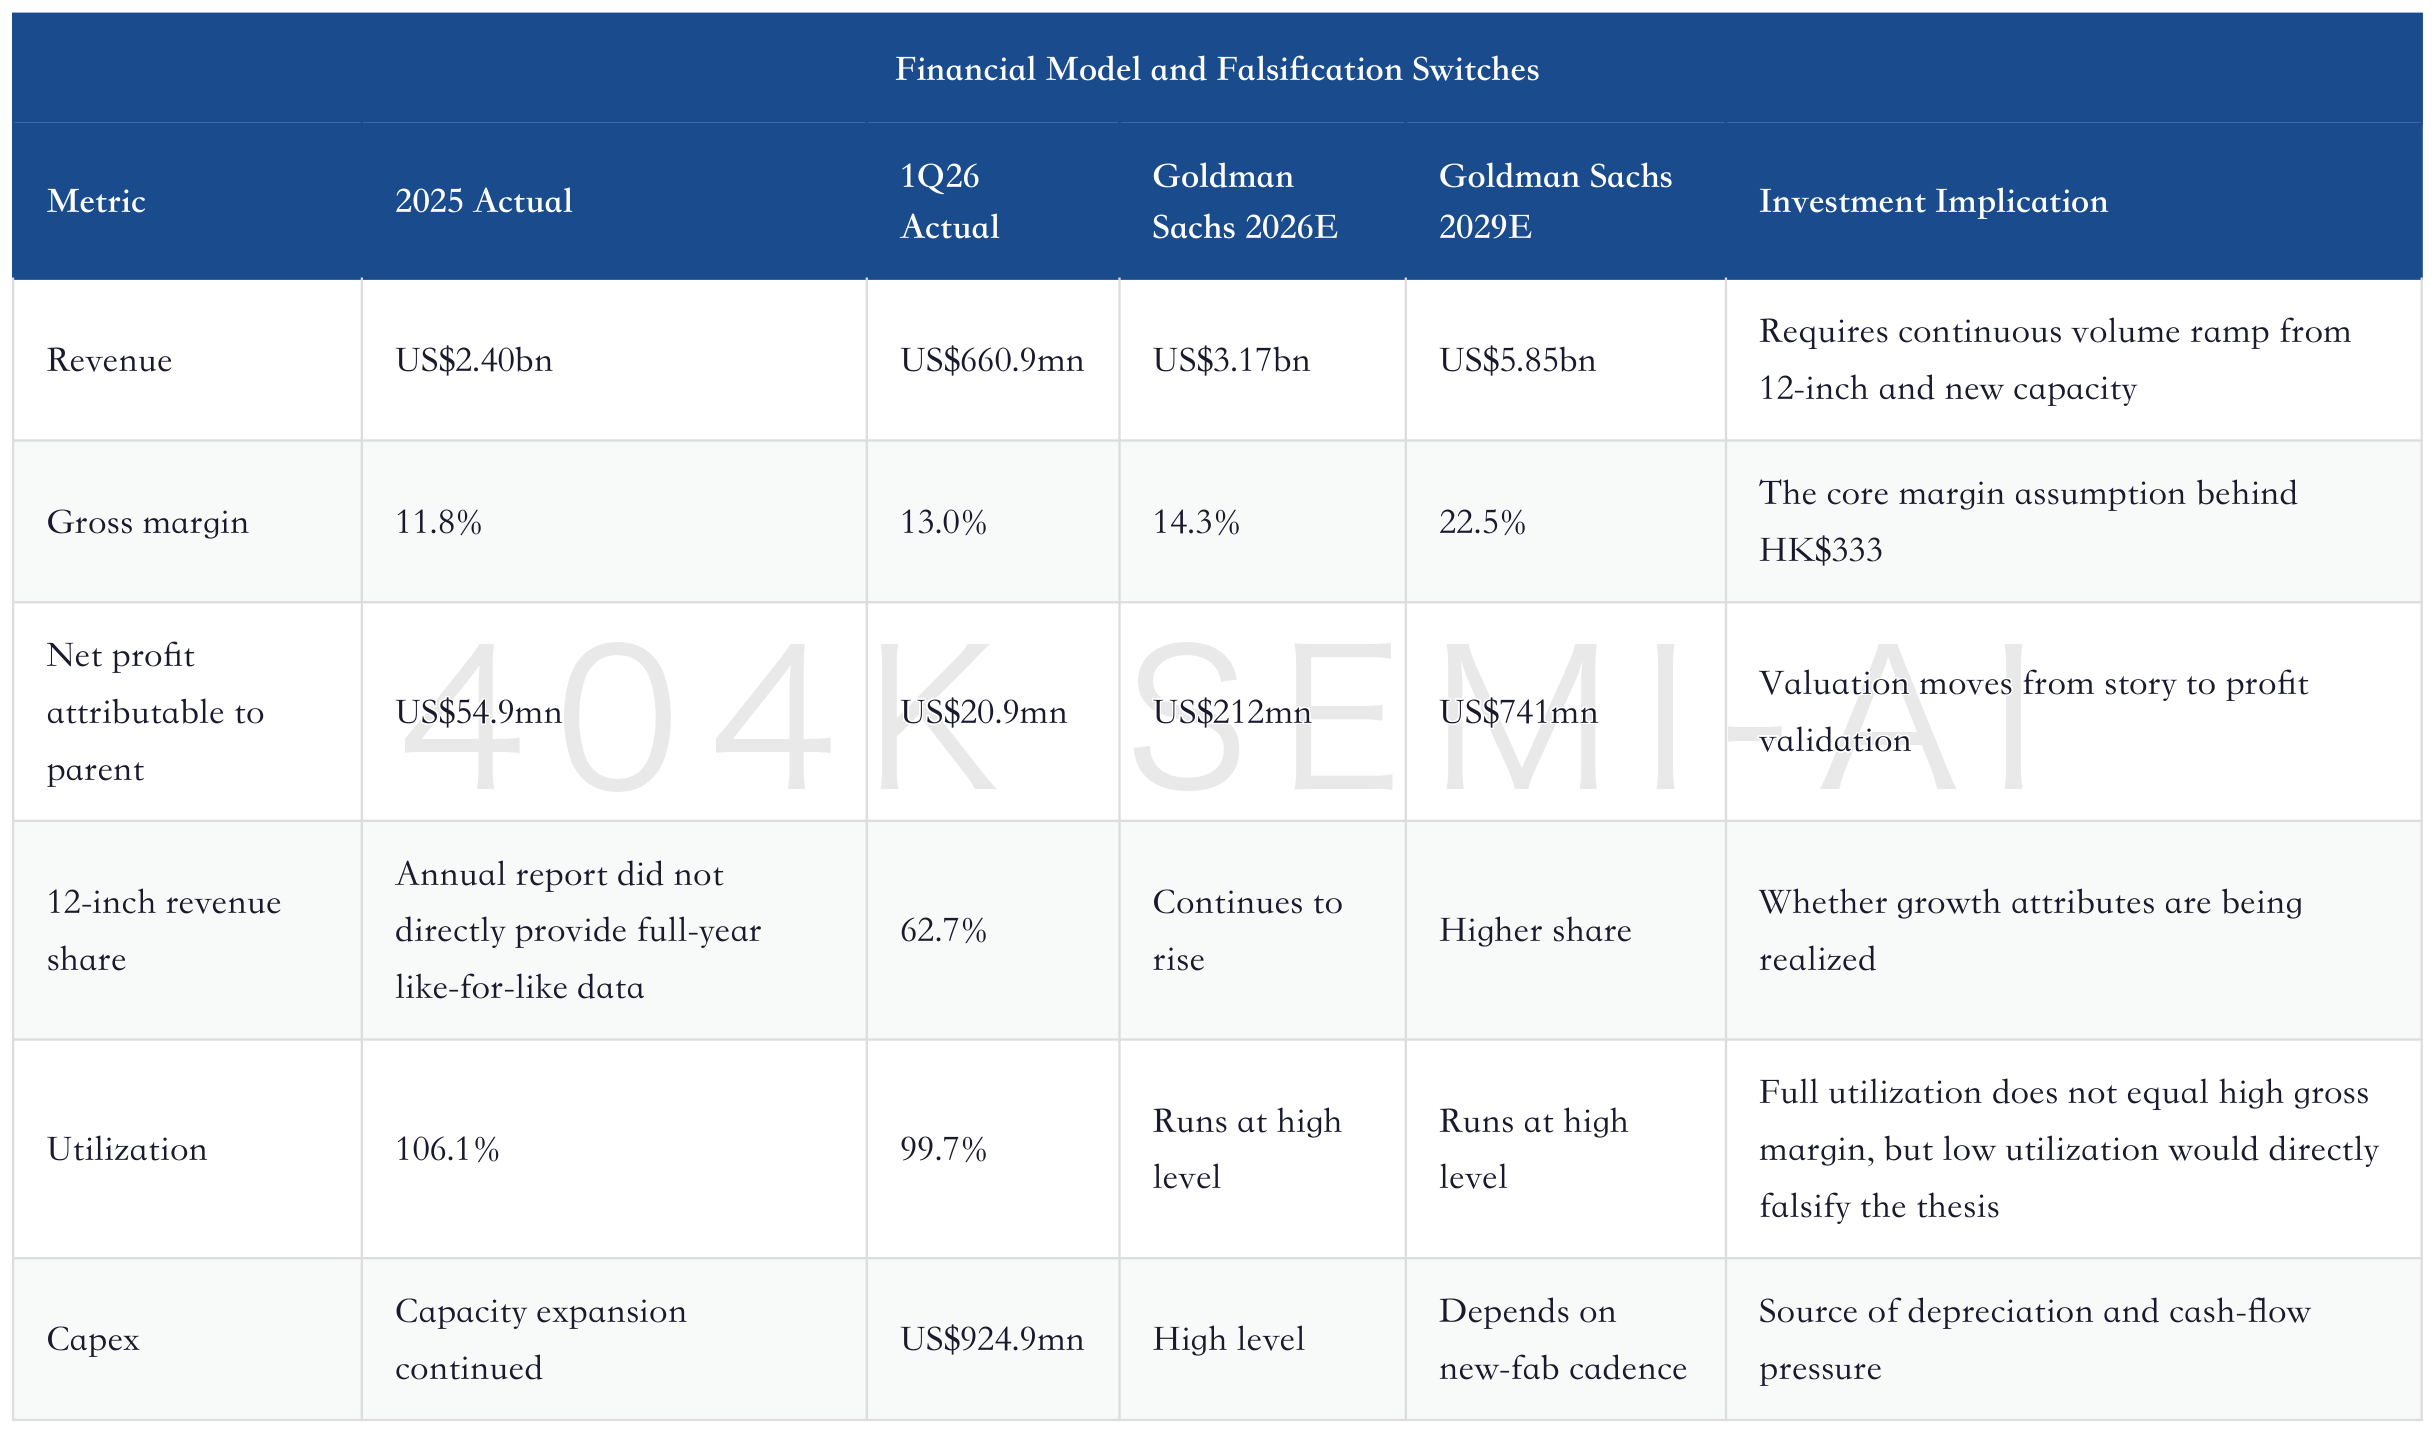
Hua Hong Semiconductor is now in the early stage of profit recovery. In 2025, revenue was US$2.40bn, up 19.9% YoY, gross margin was 11.8%, and net profit attributable to the parent was US$54.9mn, but the group level still had minority-interest effects and loss-related disruptions. In 1Q26, net profit attributable to the parent was US$20.9mn, a sharp YoY improvement, and Q2 guidance further raised revenue and gross margin. This means 2026 is more like a confirmation year for profit recovery than the endpoint of profit release.
Goldman Sachs’ forecast curve gives a clear cadence. 2026E revenue is US$3.17bn, net profit is US$212mn, and gross margin is 14.3%; 2027E revenue is US$4.11bn, net profit is US$356mn, and gross margin is 16.8%; 2028E revenue is US$4.92bn, net profit is US$526mn, and gross margin is 20.2%; 2029E revenue is US$5.85bn, net profit is US$741mn, and gross margin is 22.5%. The implication behind this curve is that 2026 proves earnings recovery, 2027 proves revenue slope, 2028 proves the gross-margin inflection, and 2029 proves operating leverage.
The path from 13% gross margin to 22.5% will not be easy. Four things need to happen at the same time: high 12-inch utilization cannot fall, the share of 40nm/28nm products must continue rising, ASPs for power and analog products must hold steady, and incremental depreciation cannot exceed the improvement in revenue and value per wafer. If any link weakens, gross margin will remain stuck in the teens. Foundry earnings leverage is usually powerful, but only when capacity, pricing, and product mix move in the same direction.
Capex and cash flow are the other side of valuation. Hua Hong Semiconductor’s 1Q26 capex was close to US$925mn, with the vast majority going to 12-inch. This scale of capex can easily make revenue growth look reliable, but it also increases depreciation, debt, and cash-flow pressure. At end-2025, the company had total assets of approximately US$14.95bn and liabilities of approximately US$5.66bn, with a liability-to-asset ratio of 37.9%. This level is not dangerous yet, but if capacity expansion and acquisitions proceed simultaneously, capital discipline will become the key to whether valuation can hold.
The most valuable way to track the financial model is to break it into five switches. The first switch is 12-inch revenue share, representing growth quality. The second is revenue growth from 65nm and below, representing node migration. The third is revenue growth from analog and power management, representing delivery from AI and the power chain. The fourth is gross margin, representing depreciation absorption. The fifth is operating expense ratio, representing scale effect. Looking only at revenue would miss the real issues in margins and cash flow.
VII. Operating Quality and Balance Sheet: During Expansion, the Biggest Risk Is High Revenue but Weak Cash Flow
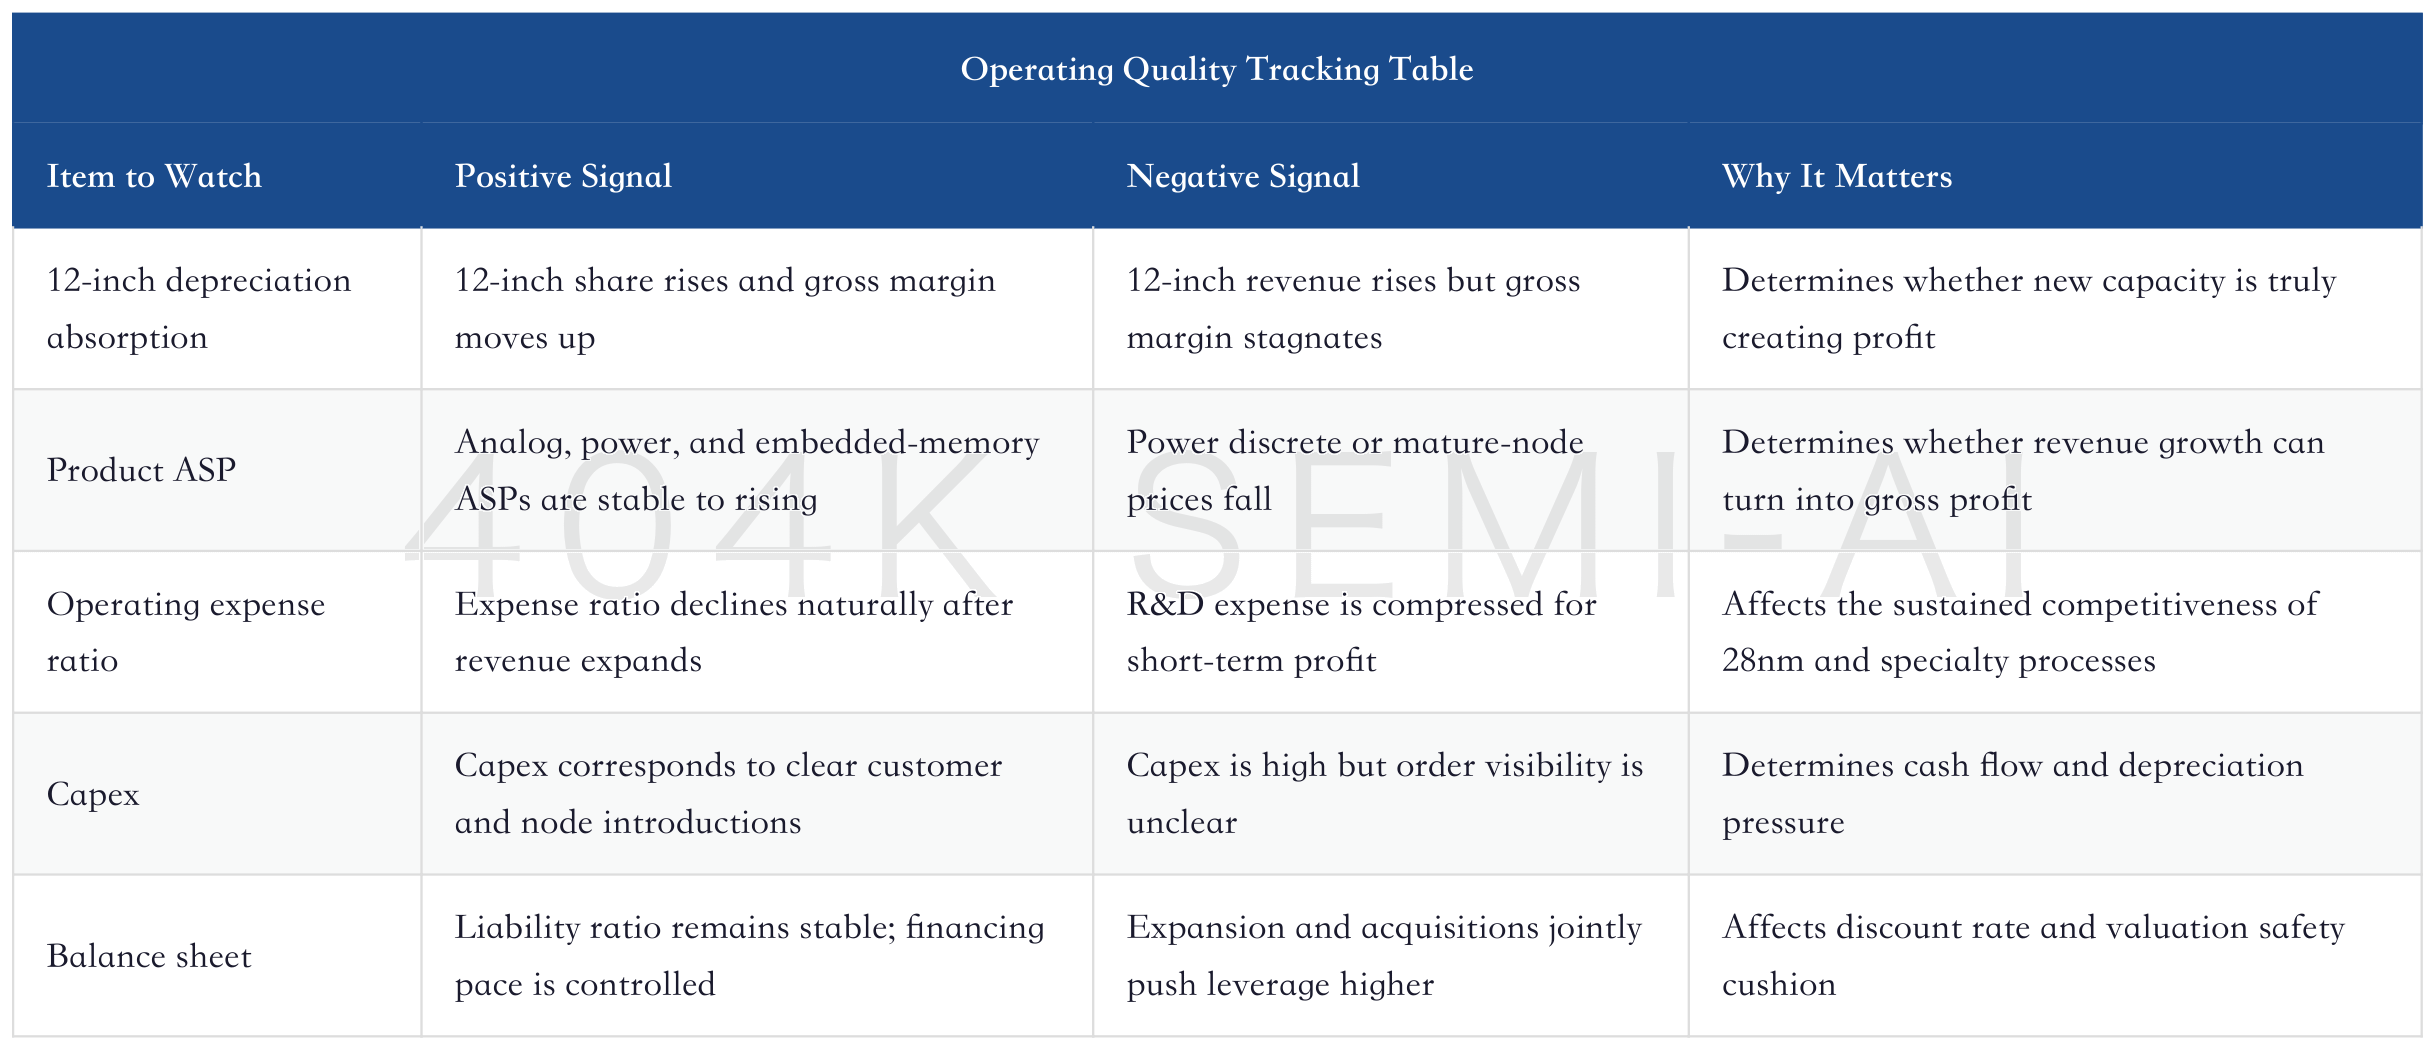
The second layer of validation for Hua Hong Semiconductor is the balance sheet. Foundry expansion is completely different from software-company expansion. More orders do not automatically translate into easy profit leverage. A new fab must first buy equipment, build cleanrooms, bring in customers, ramp yield, and then gradually spread depreciation across more wafers and higher-ASP products. The easiest illusion in financial statements is that revenue has already accelerated, while operating cash flow and free cash flow have not caught up. For a capex-intensive company like Hua Hong Semiconductor, high revenue growth only gets it to the next gate; cash-flow quality determines whether valuation can be sustained.
From 2025 to 1Q26, pressure and improvement are already visible at the same time. The cycle recovery and cost improvement have started to show, and Q2 guidance further confirms that gross-margin repair is not purely one-off. At the same time, however, the company is still directing substantial capex toward new production lines. This combination means investors must accept one reality: margin improvement takes time, while cash flow may continue to be consumed by expansion.
Depreciation is Hua Hong Semiconductor’s largest hidden variable over the next few years. Once new production lines are transferred to fixed assets, depreciation enters the cost side. If 12-inch utilization is high, the customer mix is good, and the share of 40/28nm products rises, depreciation can be absorbed by higher revenue per wafer and gross margin will rise. If capacity release runs ahead of customer onboarding, depreciation will consume revenue growth and gross-margin improvement will stall in the teens. Therefore, when analyzing Hua Hong Semiconductor, one cannot only ask “how much capacity is there”; one must also ask “who is this capacity sold to, what node is being sold, and how much gross profit can each wafer contribute?”
Minority interests also affect how net profit attributable to the parent appears. Hua Hong Semiconductor’s group structure includes different production lines and equity arrangements. Net profit attributable to the parent was still positive in 2025, but group-level losses and fluctuations in non-controlling interests made the income statement less intuitive. Investors looking only at quarterly net profit attributable to the parent can easily be distorted by non-controlling interests and one-off items. A steadier approach is to look at group revenue, gross margin, operating margin, net profit attributable to the parent, and operating cash flow together, and then separate out profit quality.
R&D; and operating expense ratios cannot simply be cut. In Goldman Sachs’ model, lower operating expense ratios in 2028E and 2029E are an important source of margin upside. But a specialty-process platform cannot exchange lower R&D; for short-term profit, because 28nm, BCD, eNVM, analog and power management, automotive, and industrial customer qualifications all require continued R&D; and engineering investment. Reasonable improvement should come from expense-ratio dilution after revenue scale expands, not from weakened R&D; capability. If the expense-ratio decline comes from scale effect, that is positive. If it comes from insufficient R&D; investment, it will weaken future node migration.
The liability-to-asset ratio is not yet a red flag, but it will become a boundary condition. At end-2025, the company’s liability-to-asset ratio was approximately 37.9%, which is not excessive for heavy-asset manufacturing. The issue is that capital needs will continue to rise when new 12-inch lines, the Huali Micro transaction, and subsequent equipment purchases occur at the same time. If the share price is at a high level, the company can reduce debt pressure through financing. If the market becomes volatile, financing costs rise, or approvals take longer, the cash-flow safety cushion will become more important. The higher the valuation, the more sensitive the market becomes to capital discipline.
The view on operating quality can be compressed into one sentence. For Hua Hong Semiconductor to move from “revenue recovery” to “asset re-rating,” 12-inch expansion, node upgrades, and expense-ratio dilution must all hold at the same time. If any one of them falls behind, the market will put it back into the mature-node cyclical-stock framework. What growth-stock valuation fears most is not slower growth, but growth that requires higher capex to sustain, which lowers the value of each dollar of revenue.
VIII. Peer Ranking and Valuation Disagreement: Hua Hong Grace Is Not SMIC, Nor Is It UMC
Hua Hong Grace cannot simply be placed in the same foundry bucket. SMIC’s core issues are advanced logic, domestic compute, and capacity utilization; UMC is more like a global mature-node cycle and cash-flow asset; GlobalFoundries focuses on long-term agreements, automotive and industrial customers, and scarcity value in U.S. manufacturing; Tower is more exposed to specialty processes such as analog, RF, power, and silicon photonics. Hua Hong Grace sits between mature nodes and specialty processes, while also carrying growth attributes from China supply-chain security, 12-inch expansion, and 28nm migration.
It has more upside torque than UMC, but also needs to prove margins more than SMIC. UMC’s strengths are capital discipline and mature cash flow, so valuation tends to focus on dividends, utilization, and the mature-node cycle. SMIC has a stronger domestic advanced-logic narrative, but also faces higher capex, geopolitical constraints, and advanced-node limits. Hua Hong Grace’s advantage lies in specialty processes and 12-inch migration; its risks are a low margin base, heavy depreciation from expansion, and a valuation that already reflects too much future growth.
The most important peer-comparison question is “who can turn AI diffusion into revenue.” As the AI theme spreads from GPUs and HBM to power, analog, MCUs, power devices, silicon photonics, and industrial automation, the status of specialty-process foundries should rise. Tower and GlobalFoundries can tell this story, and Hua Hong Grace can as well. The difference is that Hua Hong Grace also has demand from Chinese customers for domestic substitution and an integration option with Huali Micro. If Chinese AI servers, power supplies, edge AI, and industrial customers begin systematically increasing the domestic foundry share, Hua Hong Grace’s revenue elasticity should be higher than that of overseas mature-node foundries.
Valuation disagreement comes from the time horizon. On 2026E, Hua Hong Grace looks expensive because profit has only just started to recover and capex remains high. On 2029E, if Goldman’s US$741mn net profit and 22.5% gross margin can be delivered, the current valuation would move from extremely expensive to explainable. On 2030E, if operating margin further normalizes to 14%-17%, HK$333 has model support. The issue is that the market will price first and financial results will prove later. Investors are getting a forward-priced asset, not a cheap, low-valuation cyclical stock.
A more prudent framing is to give Hua Hong Grace three worldviews. In the bullish worldview, 12-inch 28nm ramps quickly, AI power, PMICs, MCUs, and Huali Micro synergies drive both revenue and gross margin higher, and HK$333 becomes a reasonable medium-term target. In the neutral worldview, revenue growth is solid, but depreciation and pricing pressure make gross-margin improvement slower than the model, so the share price needs time to digest valuation. In the bearish worldview, AI orders and end demand fall short of expectations, Huali Micro integration slows margin recovery, and the market revalues the company as a mature-node cyclical stock.
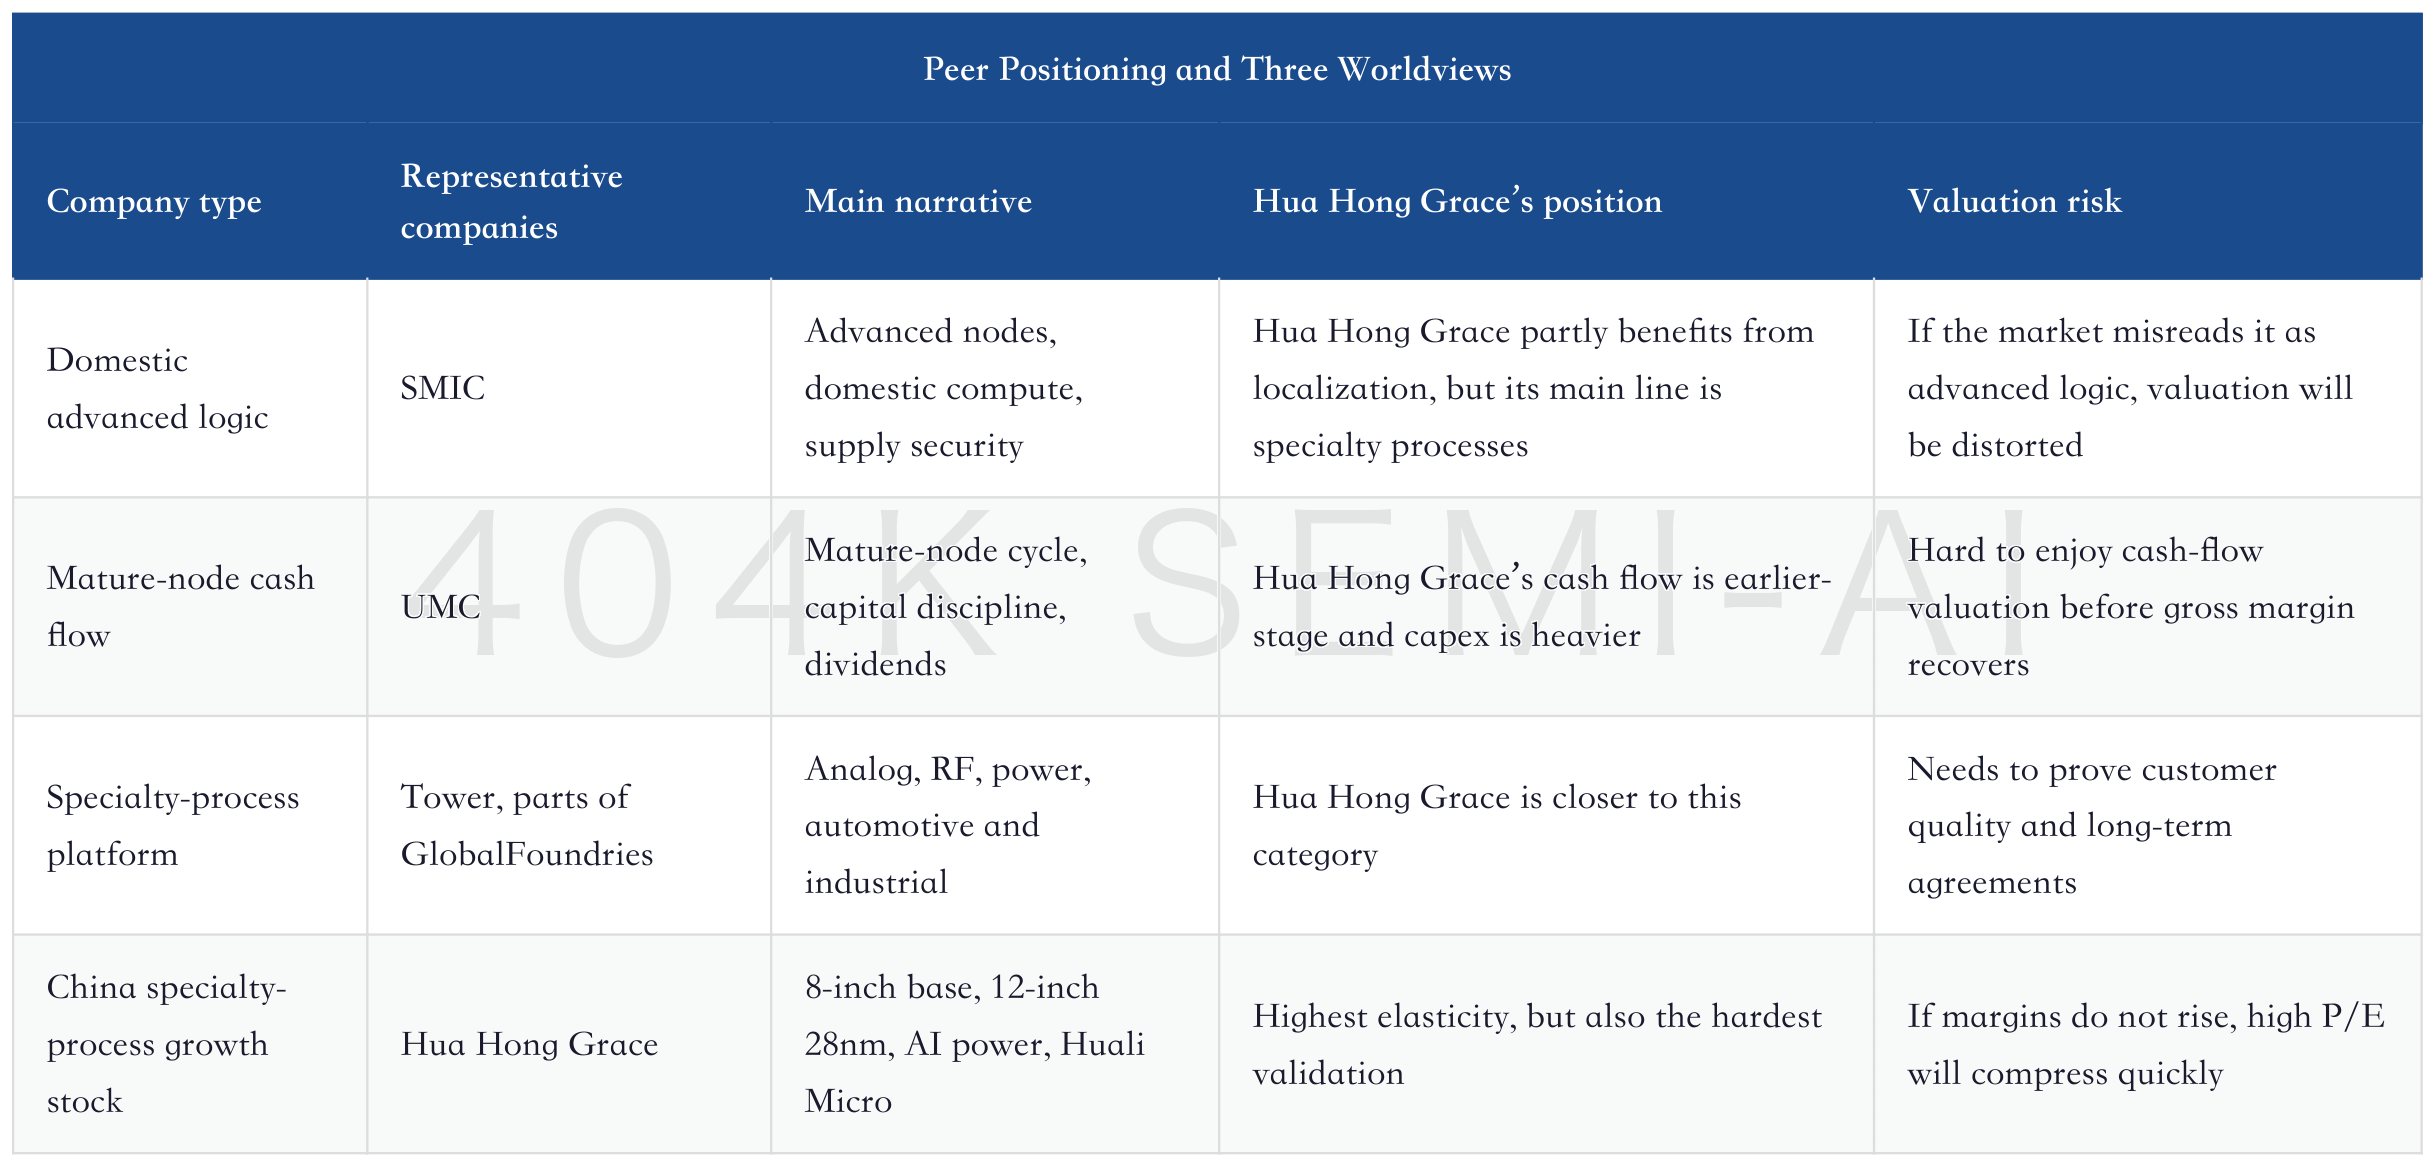
Viewed alongside peers, what Hua Hong Grace lacks most is evidence of long-term margins. UMC and GlobalFoundries benefit from the fact that investors can already value them using mature margins, cash flow, and capital discipline. SMIC’s advantage is that the advanced-logic and domestic-compute narrative is strong enough for the market to grant a strategic-asset premium even when margins are under pressure. Hua Hong Grace now stands between the two: it has a story around domestic specialty processes and the AI power chain, but still needs several consecutive quarters of results to lift gross margin to a more comfortable level. That position gives it high elasticity, but also means drawdowns can be faster.
More specifically, Hua Hong Grace’s customer structure means it cannot simply copy UMC. UMC is more like a cash-flow asset tied to the global mature-node supply-demand cycle, with diversified customers and more mature pricing and capex discipline. Hua Hong Grace has a high China revenue mix: China accounted for 82.2% of revenue in 2025 and 79.5% in 1Q26. This makes it more likely to benefit from domestic supply-chain security and local AI hardware diffusion, but also leaves it more exposed to China’s consumer electronics, industrial, and domestic foundry supply cycles. When Chinese customer pull is strong, it has more elasticity than UMC; when pricing competition among Chinese customers intensifies, it is also more vulnerable.
Hua Hong Grace also cannot simply copy SMIC. SMIC’s valuation is often tied to advanced logic, domestic GPUs/AI chips, equipment restrictions, and capacity scarcity. Hua Hong Grace’s strengths are specialty-process depth and its mix across power, analog, memory, and power devices. The right question is not “can it catch up in the most advanced logic,” but “can it form sufficiently high customer stickiness and margins on 28nm, 40nm, BCD, eNVM, PMIC, and power platforms.” This is also why the Huali Micro acquisition matters: only after filling out logic processes can the platform become more complete and move closer to customers’ system-level solutions.
Valuation comparison should therefore avoid two traps. The first trap is treating Hua Hong Grace as an ordinary mature-node foundry, valuing it only on trough P/B or low-single-digit EV/EBITDA, and ignoring the profit elasticity from AI power and 12-inch migration. The second trap is treating it as an advanced-logic leader, giving it too much strategic premium upfront while ignoring depreciation, gross margin, customer qualification, and capex. A more reasonable approach is to view it as a “specialty-process growth stock,” priced jointly by its medium-term profit slope and near-term earnings validation.
IX. What to Watch Over the Next Four Quarters: Six Numbers Decide Whether HK$333 Can Hold
Tracking Hua Hong Grace from here needs to be highly quantitative. The question for the company is no longer “does it have an AI story,” but “can the AI story enter revenue, gross margin, and cash flow.” The market has already priced in part of the future. The next step requires the company to prove over several consecutive quarters that the 12-inch revenue share continues to rise, that 65nm and below and 40/28nm migration are truly happening, that analog and power management revenue continues to grow faster than the group, that capex is not consuming margin, and that the Huali Micro transaction proceeds smoothly.
First, watch delivery against 2Q26 guidance. The company’s 2Q26 guidance is US$690mn-700mn in revenue and 14%-16% gross margin. If both revenue and gross margin land in the upper half of the range, the market will believe 1Q26 was not a one-off rebound. If revenue is sufficient but gross margin is weak, the issue will return to depreciation, pricing, and product mix. If both are low, the medium-term validation path for HK$333 becomes much steeper.
Second, watch the 12-inch revenue share. In 1Q26, 12-inch already accounted for 62.7%. If it continues to rise while group gross margin also moves higher, it would indicate that 12-inch is shifting from revenue contribution to profit contribution. If the 12-inch share rises but gross margin does not, it suggests new capacity is still “selling volume to absorb depreciation,” and valuation will become more cautious.
Third, watch 65nm and below and 28nm progress. In 1Q26, revenue from 65nm and below grew 44.3% YoY, early evidence of node migration. If future results show clearer 40nm and 28nm applications, especially customer traction in AI power, MCUs, SoCs, and embedded memory, that would support higher ASP and a higher P/E.
