
目录
Contents
Scale Moves Prices Before Challenging Technology Leadership
Why AI Delays the Pricing Impact
How Four-Way Competition Changes the Downcycle
Why Scale Matters in Shifts in Industry Leadership
Separate Battles for Mainstream Capacity and High-End Profits
The Technology Gap Lies in Cost, Packaging, and Qualification
How Margins and Valuation Benchmarks May Change
Why NAND Is the Biggest Variable in 2028
Winners, Losers, and What to Watch Next
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
ChangXin Memory Technologies (CXMT) and Yangtze Memory Technologies (YMTC) have yet to fully catch the global leaders, but their capacity is already changing the marginal supply of mainstream memory. AI should keep supply and demand tight through 2026—2027; after 2028, industry supply discipline, margins, and valuation floors will face a much tougher test.
Contents
Scale Moves Prices Before Challenging Technology Leadership
Why AI Delays the Pricing Impact
How Four-Way Competition Changes the Downcycle
Leadership Shifts Show Why Scale Matters
Mainstream Capacity and High-End Profit Pools Will Compete Separately
The Technology Gap Lies in Cost, Packaging, and Qualification
How Margin and Valuation Midpoints Will Change
Why NAND Is the Biggest Variable in 2028
Who Benefits, Who Faces Pressure, and What to Watch Next
Scale Moves Prices Before Challenging Technology Leadership
The most common mistake in assessing the influence of China’s memory industry is to reduce the question to whether its process technology has caught up. Memory chips are highly standardized commodities with transparent pricing and pronounced inventory cycles. Once incremental supply qualifies for mainstream applications, even output from less advanced processes can move marginal prices. Technology determines how much profit a wafer can generate; capacity determines how deep the industry’s next downturn may be.
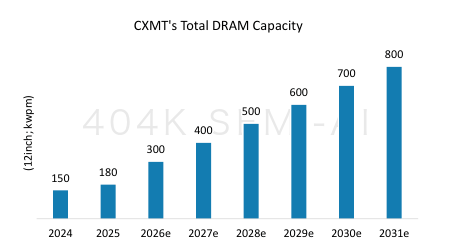
Morgan Stanley estimates that CXMT’s monthly DRAM capacity will rise from 180,000 wafers in 2025 to 300,000 wafers in 2026, reach 500,000 wafers in 2028, and increase further to 800,000 wafers in 2031. On its estimates, CXMT will account for approximately 13% of global DRAM wafer capacity in 2026 but around 11% of bit shipments. The gap between wafer share and bit share reflects its continuing disadvantage in process technology and output per unit area. Even so, an 11% bit share would make CXMT a meaningful part of the global supply curve.
Monthly capacity is not the same as effective supply. Wafers must move through yield ramp-up, product qualification, customer adoption, and inventory digestion before becoming actual bit shipments. CXMT’s GEN4B process is approximately 16nm, and the report states that yields have already exceeded 90%, indicating that its expansion is moving from nominal fab capacity to saleable output. Its current DDR5 roadmap supports 5600MHz and is expected to advance toward 6400MHz. At these performance levels, its products can address a broader range of server, PC, and consumer-electronics demand.
This expansion changes the identity of the global DRAM industry’s marginal producer. Historically, Samsung, SK hynix, and Micron could collectively slow capital expenditure as demand changed because virtually all incremental supply came from within the three vendors. As CXMT expands, global effective capacity may continue rising even if the traditional Big Three reduce investment. During a price decline, whether the last tranche of incremental supply exits the market often matters more than average cost.
CXMT still trails the most advanced products, but its near-term strategy does not require full market coverage. Establishing a foothold in DDR5, LPDDR, and selected server DRAM would be enough to draw the leaders’ commodity products into more intense price competition. High-end segments such as high-bandwidth memory may retain superior margins, while the price floor for mainstream products is redefined first.
Why AI Delays the Pricing Impact
CXMT’s expansion has not immediately created a global DRAM surplus because AI is simultaneously tightening the supply side. HBM appears to be a source of high-growth demand, but its production also consumes more advanced DRAM wafers. Morgan Stanley estimates that, for an equivalent volume of effective bit shipments, HBM’s wafer-consumption penalty will increase from approximately 2.5x today to approximately 3x in 2028. Additional stack layers, redundant dies, and yield losses all widen this gap.
The report expects HBM’s share of advanced DRAM wafers to rise from 6% in 2023 to 34% in 2028. Thus, even as the Big Three increase wafer input, a growing proportion of capacity will be absorbed by high-value HBM rather than converted directly into standard DRAM for PCs, smartphones, and conventional servers. AI is simultaneously boosting demand and constraining commodity-product supply, creating an unusual buffer period.
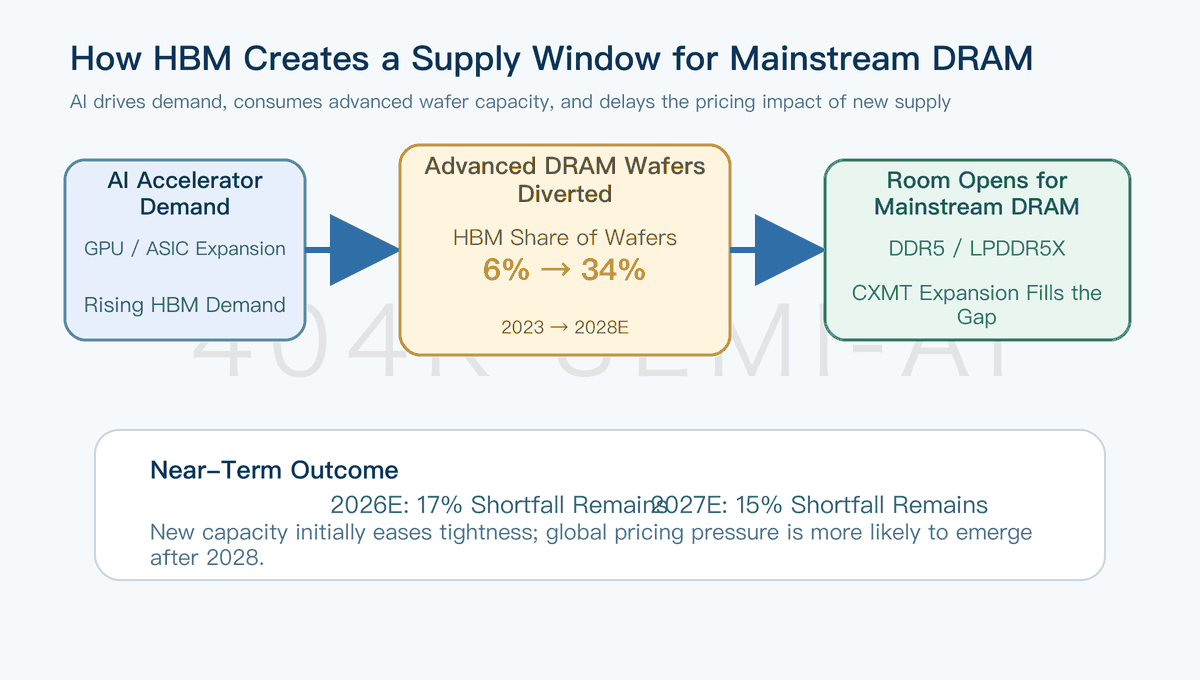
Even after incorporating CXMT’s incremental capacity, Morgan Stanley still forecasts a global DRAM supply-demand deficit of approximately 17% in 2026 and approximately 15% in 2027. Estimates of this magnitude are better viewed as directional stress tests, as actual outcomes will depend on inventories, demand elasticity, and vendor capacity allocation. At minimum, they indicate that inadequate advanced supply will remain the dominant issue over the next two years, with CXMT’s expansion doing more to alleviate shortages than create oversupply.
Strong industry conditions in 2026—2027 can therefore coexist with the rise of Chinese supply. The former is driven by HBM, AI servers, and tight advanced-node capacity; the latter reflects China’s gradual share gains through mainstream DRAM expansion. Focusing only on shortages risks overstating the duration of elevated margins, while focusing only on expansion understates HBM’s absorption of supply.
CXMT’s HBM roadmap reinforces this two-stage outlook. The report estimates that the company may launch 12-layer HBM3E in the first half of 2027 and progress toward HBM4 in 2028. Its 2027 HBM3E shipments could reach 3 million to 4 million stacks, supporting approximately 800,000 to 1 million AI GPUs in the Chinese market. This volume is not yet sufficient to disrupt the global HBM landscape, but it would improve supply-chain resilience for China’s AI industry.
The critical inflection point is around 2028. If AI-accelerator demand continues growing rapidly, HBM will keep absorbing substantial advanced-wafer capacity, further postponing the pricing pressure from new Chinese supply. If HBM growth slows while CXMT’s new fabs ramp as planned, mainstream DRAM could face the combined impact of decelerating demand and expanding supply.
How Four-Way Competition Changes the Downcycle
The global DRAM industry’s strong returns over the past decade reflected not only technological complexity but also market structure. After competition consolidated around three vendors, decisions on capital expenditure, inventories, and production cuts increasingly shifted from survival-driven competition toward return preservation. As listed companies accountable for profits, free cash flow, and shareholder returns, the three incumbents have stronger incentives to reduce wafer starts and delay new fabs when demand weakens.
With CXMT emerging as a fourth scaled player, market participants no longer share the same objective function. For China’s memory industry, supply security, learning-curve gains, customer adoption, and import substitution all carry strategic value. Continued expansion may therefore deliver technological progress and market-share gains even when near-term prices are weak. CXMT may not cut production in step with the traditional Big Three during a downturn.
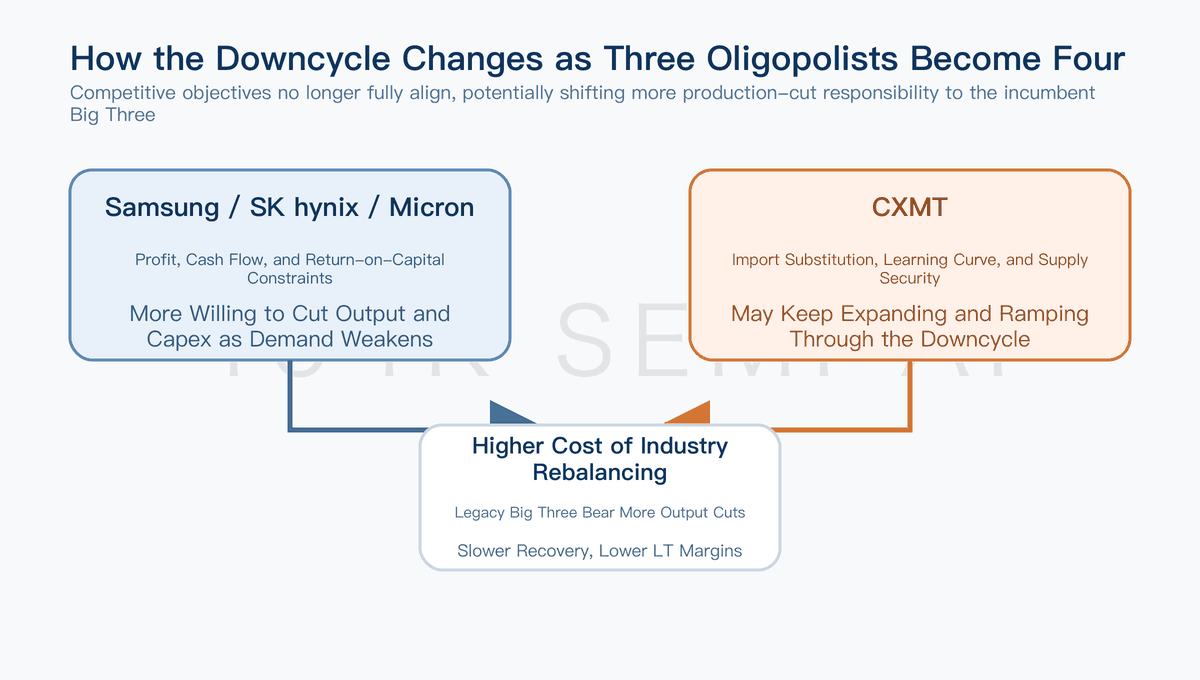
CXMT does not need to become the lowest-cost producer for this shift to matter. As long as incremental bits continue entering the market, more of the burden of restoring supply-demand balance will fall on Samsung, SK hynix, and Micron. The three may cut production to defend prices, but at the cost of lower utilization, higher fixed cost per unit, and surrendered market share. Alternatively, they may defend share while accepting lower prices and margins. Either way, the cost of balancing the industry will be higher than under the previous three-player oligopoly.
