HBM Export Tracker Update: Samsung’s 2Q26 Revenue Estimated at $6.7 Billion—Is Its HBM4 Catch-Up Really Accelerating?
目录
TL;DR
What the June Data Actually Changed
Why $6.7 Billion Is Useful—and Why It Is Not a Reported Figure
Value per Unit Weight: An HBM4 Signal or a Statistical Illusion?
Malaysia: Is a Second Packaging Channel Emerging?
What Else Does the Model Miss?
The Implications Differ Across the Four Companies
Five Validation Points to Watch
Conclusion: Samsung Electronics’ Catch-Up Is Now Visible, but an Overtake Remains Unproven
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
June export data move Samsung Electronics’ HBM catch-up story toward quantitative validation, but the $6.7 billion figure remains a regression estimate. The key variables are the HBM4 product mix, customer channels, and whether the momentum continues into the third quarter.
TL;DR
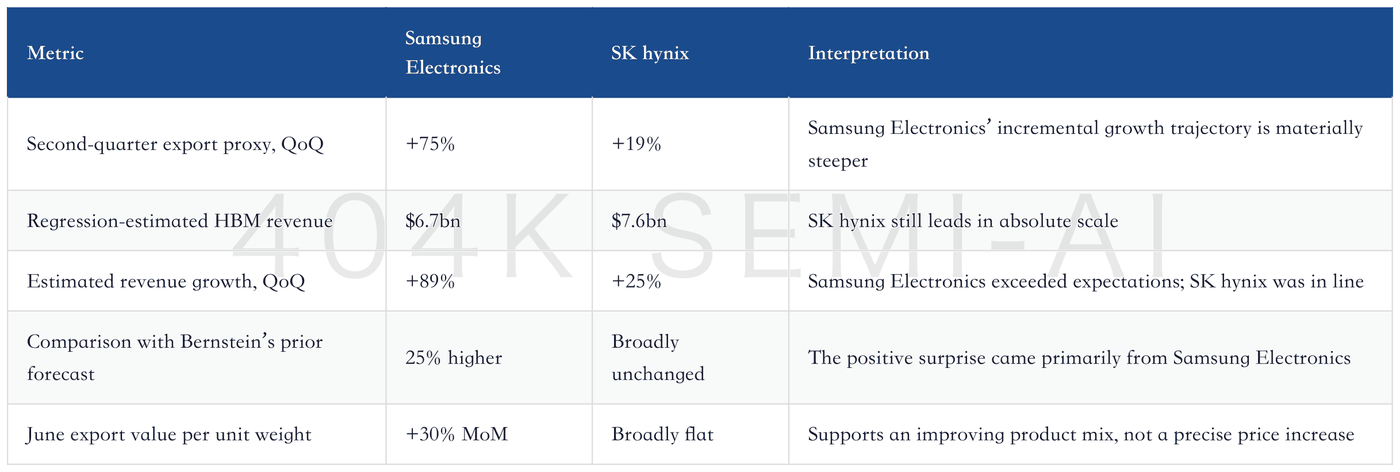
Samsung Electronics’ incremental improvement is strong enough to warrant a reassessment. In June 2026, South Korea’s multi-chip memory exports to Taiwan and Malaysia totaled approximately $6.2 billion, up 45% MoM and 46% from March; second-quarter exports rose 39% QoQ. Using South Chungcheong Province as a proxy for Samsung Electronics’ back-end packaging activity, its second-quarter exports increased 75% QoQ. Bernstein’s regression therefore estimates Samsung Electronics’ quarterly HBM revenue at approximately $6.7 billion, up 89% QoQ and 25% above its previous model estimate of $5.4 billion.
However, an “accelerating catch-up” does not mean Samsung has already overtaken SK hynix. The same methodology estimates SK hynix’s second-quarter HBM revenue at approximately $7.6 billion, up 25% QoQ and still above Samsung Electronics’ $6.7 billion. Samsung leads in growth and positive surprise, while SK hynix retains the advantage in absolute scale and visibility. Samsung’s monthly exports exceeded SK hynix’s for the first time in June, demonstrating a change in incremental momentum but not a reversal of the quarterly competitive landscape.
The best—and most easily misinterpreted—indicator of HBM4 ramp-up is export value per unit weight. Samsung Electronics’ proxy increased 30% MoM in June and approximately 70% from April, while SK hynix’s was broadly flat. This supports the view that higher-value products are gaining share, but it cannot prove that the entire increase came from HBM4, much less directly determine average selling prices or shipment volumes.
Malaysia is evolving from a peripheral destination into a second monitoring channel. June exports reached approximately $1.1 billion, up 231% MoM, driven primarily by Samsung Electronics’ proxy regions. This could reflect the expansion of advanced-packaging and customer channels, but it may also include inventory build, batch effects, and quarter-end shipment concentration. Without supporting customer, capacity, and subsequent monthly data, a one-month surge cannot be interpreted as a durable share gain.
For investors, the greatest value lies in separating the earnings drivers of the four companies. Samsung Electronics offers dual upside from HBM share recovery and rising conventional DRAM/NAND prices; SK hynix remains the name with the greatest HBM scale and execution visibility; Micron benefits from industry supply-demand conditions but cannot be directly validated through Korean export data; and Kioxia is primarily exposed to the NAND cycle, so the HBM framework cannot simply be applied to it.
What the June Data Actually Changed
This report provides an observation window that is earlier than financial results and more consistent than industry rumors, making it more valuable than another confirmation that “HBM demand is strong.” South Korean customs data are updated monthly. Bernstein treats multi-chip memory exports to Taiwan and Malaysia as an HBM proxy, then breaks them down by region of origin: South Chungcheong Province maps to Samsung Electronics, while North Chungcheong Province and Icheon map to SK hynix.
The most striking June figure was Samsung Electronics’ proxy exports of approximately $3.4 billion, nearly double the May level; second-quarter exports rose 75% QoQ. More importantly, June accounted for 55% of Samsung’s quarterly proxy exports and marked the first month in which its exports exceeded SK hynix’s since HBM shipments began ramping in early 2024. The market had debated whether Samsung Electronics’ HBM4 progress remained at the sampling stage or had begun translating into revenue. These data show at minimum that Samsung’s high-value memory shipments accelerated materially toward the end of the second quarter.
2Q26 HBM Export Proxy Comparison: Samsung Electronics Growing Faster, While SK hynix Retains the Scale Lead