
目录
Executive Summary
I. Citi Raised Earnings Forecasts—Why Did It Still Cut Its A-Share and H-Share Price Targets?
II. 2Q26 Was Genuinely Strong, with Simultaneous Improvements in Revenue, Margins, and Expense Ratios
III. AI-Related Revenue Has Reached Approximately 50%, but Established Equipment Still Generates Most of the Profit
IV. Ultrafast Laser Contributes Just 2% of Revenue—Evidence of a Slower Commercialization Pace, Not Vanishing Demand
V. Why Earnings Forecasts Rose: Revenue Upgrades More Than Offset Lower Gross-Margin Assumptions
VI. Why the A-Share and H-Share Targets Fell by Different Amounts: Same Earnings, Different Valuation Anchors
VII. Cash Flow Is the Next Hurdle: Rapid Earnings Growth Still Requires Substantial Working Capital
VIII. The September—October Order Window Will Shape 2027; Ultrafast-Laser Reorders Will Determine the Longer-Term Valuation
IX. Han’s Laser Remains the Relative Preference Because Its Risk-Reward Profile Is More Balanced
X. Conclusion: Earnings in 2026, Orders in 2027, and Technology Reorders Thereafter
Han’s CNC’s profit growth continues to accelerate, but ultrafast laser drilling remains in customer validation. Citi raised its earnings forecasts while cutting its A-share and H-share price targets, reflecting a divergence between the earnings mix and the pace of technology commercialization.
Executive Summary
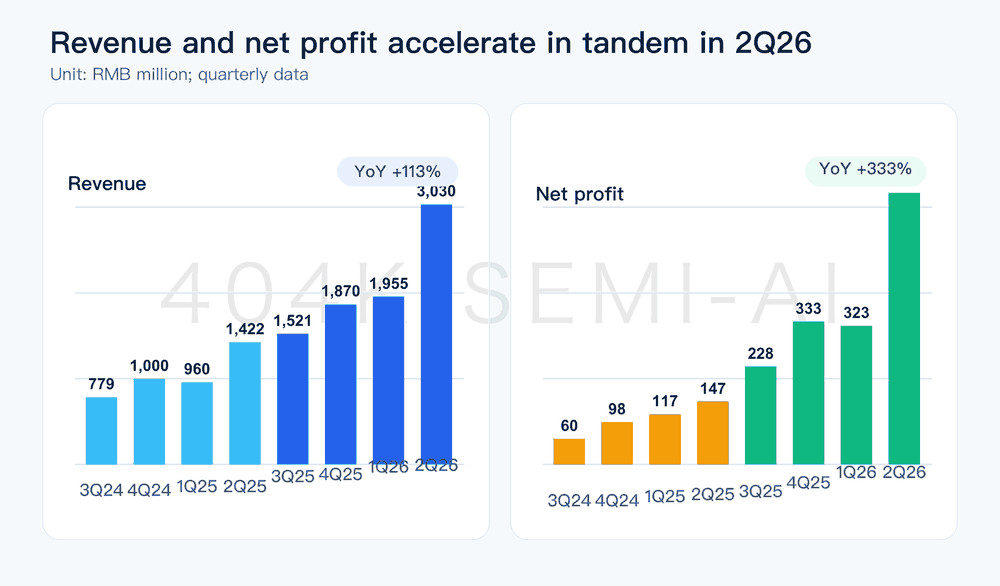
Han’s CNC reported 2Q26 revenue of RMB3.03bn, up 113% YoY, and net profit of RMB634mn, up 333%. Profit significantly outpaced revenue, driven by operating leverage from an improved product mix and lower operating-expense ratios.
Approximately 50% of 1H26 revenue was AI-related, but current volume growth still comes primarily from established products such as mechanical drilling, testing, routing, and exposure equipment. Only 20 ultrafast laser drilling machines were delivered, contributing approximately RMB100mn, or around 2% of total revenue—below Citi’s previous estimate of approximately 5%.
Citi raised its 2026—2028 revenue forecasts by 6%, 8%, and 8%, respectively, and its net-profit forecasts by 11%, 13%, and 11%. At the same time, it cut its gross-margin forecasts by 1.7, 2.3, and 2.8 percentage points. Scale and cost efficiency can drive higher earnings, but the technological content and margin profile of incremental revenue have yet to meet previous bullish assumptions.
Citi cut its A-share price target from RMB377 to RMB322, primarily because it reduced the 2027 earnings multiple from approximately 68x to approximately 51x. It cut its H-share price target from HKD325 to HKD189 and widened the discount to the A shares from approximately 25% to approximately 50%.
The two most important upcoming catalysts are: first, management expects a new round of AI PCB equipment procurement in September—October 2026; second, ultrafast laser equipment must transition from validation units to volume orders. The former will determine 2027 earnings visibility, while the latter will determine whether the valuation multiple can rerate.
I. Citi Raised Earnings Forecasts—Why Did It Still Cut Its A-Share and H-Share Price Targets?
The most counterintuitive aspect of Citi’s update is that its earnings forecasts and price targets moved in opposite directions. Its 2026 and 2027 net-profit forecasts rose by 11% and 13%, respectively, yet its A-share and H-share price targets fell by 15% and 42%. Earnings growth remains strong and industry demand has not reversed; the key change is how much investors are willing to pay for those earnings.
What has changed is the composition of earnings and the valuation anchor. Han’s CNC is benefiting from a strong AI PCB equipment cycle, with mechanical drilling, routing, testing, and exposure equipment all ramping simultaneously. The larger revenue base is absorbing fixed costs, allowing profit to grow faster than revenue. A major reason investors previously assigned a higher multiple was the prospect of volume commercialization for ultrafast laser drilling equipment. Progress has fallen short of expectations, however, and near-term incremental profit still comes primarily from established-product volume growth and operating efficiencies, with limited contribution from the technology option.
Citi’s valuation can be reduced to a simple equation: earnings per share multiplied by the 2027 earnings multiple. Han’s CNC’s EPS increased, but its multiple declined—and the multiple compression was larger. Citi raised its 2027 A-share EPS forecast from RMB5.576 to RMB6.292, an increase of approximately 13%, while cutting the corresponding multiple from approximately 68x to approximately 51x, a decline of approximately 25%. The resulting price target fell from RMB377 to RMB322. A wider H-share discount compounded the impact, producing a much larger reduction.
The earnings cycle remains strong, but the technology premium now requires more evidence. Earnings delivery and technology validation must therefore be assessed separately, as they are no longer driven by the same dataset.
II. 2Q26 Was Genuinely Strong, with Simultaneous Improvements in Revenue, Margins, and Expense Ratios
Han’s CNC reported 2Q26 revenue of RMB3.03bn, up 113% YoY and 55% QoQ; gross profit of RMB1.104bn, up 153% YoY; operating profit of RMB745mn, up 359%; and net profit of RMB634mn, up 333%. Net margin reached 20.9%, improving by 10.6 percentage points YoY and 4.4 percentage points from 1Q26.
The significance lies not only in the pace of growth, but also in its quality. Over the past eight quarters, revenue increased from RMB779mn in 3Q24 to RMB3.03bn in 2Q26, while net profit rose from RMB60mn to RMB634mn. Revenue grew by approximately 2.9x, while net profit expanded by approximately 9.6x. Equipment companies have substantial operating leverage across capacity utilization, supply-chain procurement, and the absorption of R&D; and selling expenses. Once order density exceeds the breakeven threshold, earnings can scale rapidly.
Gross margin rose from 30.7% in 2Q25 to 36.5% in 2Q26, an increase of 5.7 percentage points YoY; operating margin increased from 11.4% to 24.6%, while net margin rose from 10.3% to 20.9%. The operating-expense ratio declined by 4.3 percentage points, from 16.4% to 12.1%. The 13.2-percentage-point improvement in operating margin was substantially greater than the 5.7-percentage-point increase in gross margin, indicating that close to half of the quarterly earnings surge came from gross-margin expansion, with much of the remainder driven by operating-expense leverage.
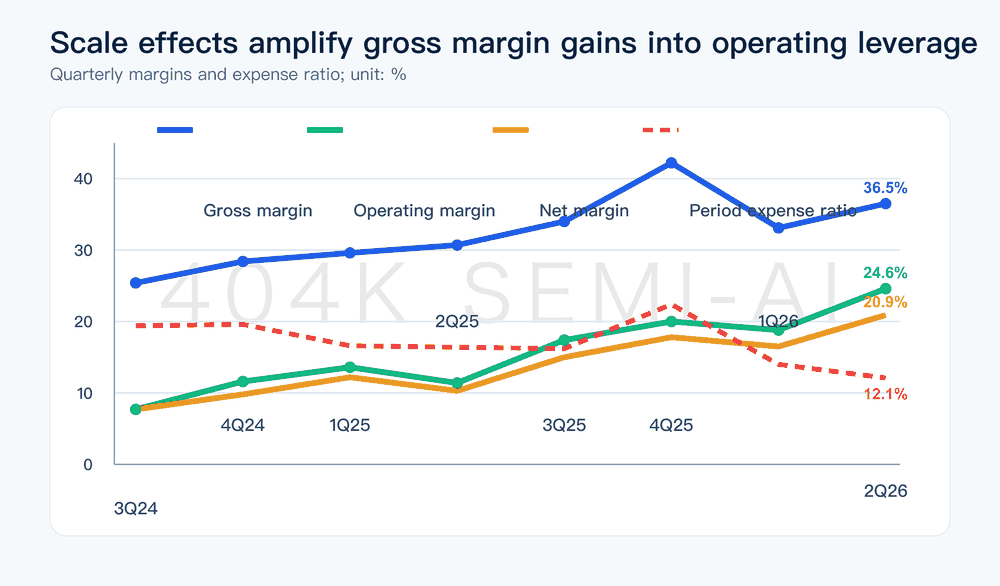
This earnings profile also explains how Citi could lower its medium-term gross-margin forecasts while raising its net-profit estimates. Provided the revenue upgrade is sufficiently large and R&D;, selling, and administrative expenses grow more slowly than revenue, operating and net margins can continue to expand. Citi’s new model forecasts 2026—2028 gross margins of 37.6%, 37.9%, and 38.2%, respectively, all below its previous estimates. Yet its operating-margin forecasts rise to 20.8%, 21.7%, and 22.4%, respectively, all above its previous estimates.
That said, the quarterly gross margin of 36.5% remained below the 42.2% recorded in 4Q25. Equipment deliveries are subject to substantial variation in product mix and acceptance timing, and quarterly margins can fluctuate when high-margin equipment is recognized in clusters. Product-level margins, expense ratios, and cash collection should therefore be assessed together rather than extrapolating directly from a single quarter’s peak.
III. AI-Related Revenue Has Reached Approximately 50%, but Established Equipment Still Generates Most of the Profit
Management stated that approximately 50% of 1H26 revenue was AI-related, versus less than 30% in 1H25. AI PCB capacity expansion has therefore progressed from the thematic and order stages to equipment-revenue recognition. However, “AI-related revenue” spans a broad range of equipment and should not be equated solely with ultrafast laser drilling. Mechanical drilling, testing, routing, exposure, lamination, and pressing equipment may all serve production lines for AI server boards, switch boards, optical modules, and advanced packaging.
By product, drilling equipment remained the dominant revenue contributor, generating approximately RMB3.6bn in 1H26, up 114% YoY. Testing and routing equipment each generated approximately RMB400mn, up 101% and 180%, respectively, while exposure equipment contributed approximately RMB300mn, up 140%. Routing equipment has entered the optical-module market, and its gross margin increased by 10.8 percentage points, from 24.4% in 1H25 to 35.1% in 1H26. As optical modules transition to 800G and 1.6T, more demanding requirements for housings, structural components, and precision machining are creating new applications for routing equipment.
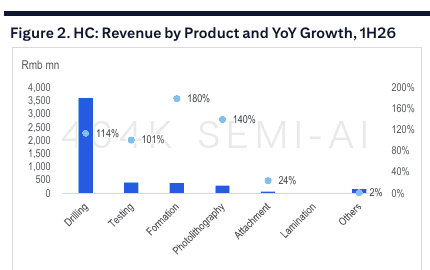
The broad-based improvement in product margins shows that earnings growth is not dependent on a single equipment category. Gross margin on drilling equipment rose from 26.1% to 32.8%, testing equipment from 41.0% to 42.3%, and exposure equipment from 38.3% to 45.2%. Lamination-equipment gross margin edged down to 43.4%, while other businesses declined to 48.0%, with limited impact on the overall trend. Pressing equipment, disclosed as a new category, recorded a gross margin of 17.2%, indicating that newly scaling businesses can still dilute the consolidated gross margin during their early ramp-up.
