
目录
Executive Summary
UBS Defines the Architecture; Nomura Adds the Orders
Agentic AI Raises Both CPU and GPU Workloads
PCB, Substrate, and HDI Suppliers Make the First Capacity Commitments
Liquid Cooling Has Evolved from an Add-On into a Platform-Level Value Pool
Optical Interconnect and Advanced Packaging Still Face Meaningful Timing Gaps
800V Power Must First Clear the Sidecar and Certification Stages
Full-Rack Delivery Monetizes Engineering Capabilities
Who Is Best Positioned to Retain Profits
What Could Delay Orders
A Time-Based Validation Framework
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
UBS explains why cloud providers are expanding AI infrastructure across the full stack, while Nomura sees capacity expansion and production milestones emerging in equipment, substrates, liquid cooling, connectors, and complete racks. The key question is whether these orders can clear qualification, yield, and fixed-cost hurdles to generate sustainable profits.
Executive Summary
AI capital spending has spread across the full stack, with utilization serving as the common return function. At the OCP Summit, UBS found that CPUs, memory, networking, packaging, power delivery, liquid cooling, and operations collectively determine whether GPUs can operate continuously. Nomura subsequently identified capacity-expansion plans and project timelines among Asian hardware suppliers, indicating that parts of demand have moved beyond technical discussion.
PCB equipment, ABF substrates, and optical-module HDI have made the earliest capital commitments. Ta Liang Technology currently has monthly drilling and routing equipment capacity of approximately 300–400 units and plans to increase outsourced capacity from 50 units/month in 2026 to 100 units/month in 2027. Kinsus Interconnect Technology plans to expand monthly ABF capacity from 40 million units in 2026 to 50 million in 2027 and 80 million in 2029. Compeq Manufacturing expects 2026 capital expenditure of NT$20 billion, up from NT$7 billion in 2025.
Liquid cooling offers earnings leverage through comprehensive deployment and ASIC customization. Asia Vital Components estimates that once Vera Rubin adopts full liquid cooling, cooling content per tray will rise by approximately 50% versus Grace Blackwell. Auras Technology estimates that liquid-cooling content per tray for one ASIC project will be approximately 3 times that of GB300, and expects CDU revenue contribution to increase from approximately 5% in 1H26 to approximately 10% in 2027.
Connector and complete-rack revenue will arrive later and remain more dependent on platform schedules. LOTES expects 2H26 revenue from SOCAMM and quick-disconnect couplings to exceed its initial plan, while removable CPO/NPO sockets could enter mass production as early as 2H27. Hon Hai Precision’s new cloud-provider projects should begin contributing in late 2026, with a more meaningful impact in 2027; system testing of at least 1 week before rack shipment will constrain delivery speed.
Technology roadmaps and earnings realization must be assessed separately. Near-term indicators include equipment shipments, HDI utilization, Vera Rubin and ASIC liquid-cooling revenue, connector qualification, and ODM operating cash flow. Beyond 2027, focus should shift to repeat orders from multiple customers, CPO/NPO mass production, 400V/800V sidecar deployment, and solid-state transformer qualification. Platform delays will defer revenue, while insufficient utilization of expanded capacity will pressure margins first.
UBS Defines the Architecture; Nomura Adds the Orders
UBS’s review of the 2026 OCP Asia Summit frames AI infrastructure as a system-wide competition. Compute chips remain the center of value, but data movement, power conversion, cooling, packaging, management, and maintenance determine how long those chips can remain productive. Customer procurement has expanded from individual GPUs to CPUs, memory, networking, power delivery, liquid cooling, and complete racks.
This framework explains why capital expenditure is broadening. When accelerators wait for data, the installed GPU count remains unchanged, but usable compute declines. Unstable power, excessive temperatures, link instability, and rack failures likewise reduce Token output. Cloud providers are willing to invest in these areas because they improve utilization of expensive accelerators and lower cost per Token.
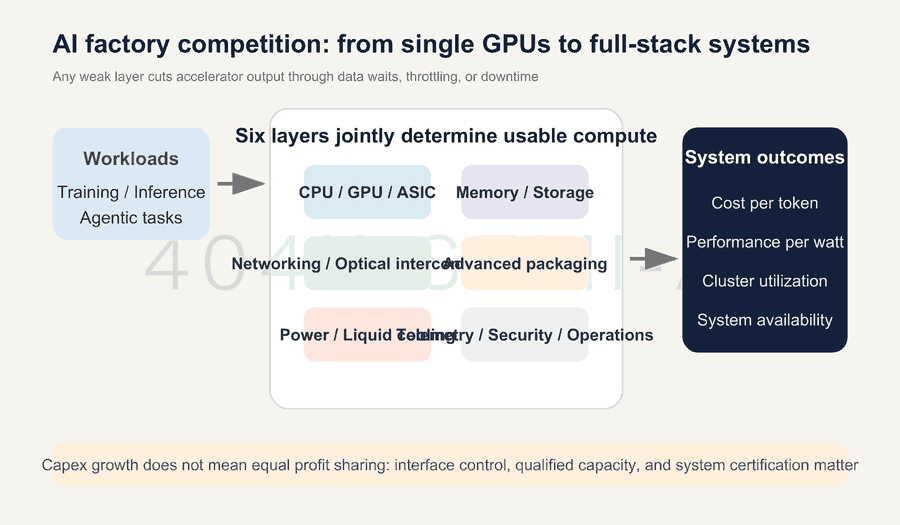
Nomura’s Asia technology fieldwork takes this architectural logic one step further. Company meetings now include monthly capacity, capital expenditure, customer-backed expansion, content per tray, gross margins, and mass-production quarters. The evidence still relies primarily on management guidance, but it is sufficient to distinguish segments approaching revenue realization from technologies still awaiting qualification.
The two reports are therefore complementary. UBS answers why customers are buying; Nomura addresses what suppliers are preparing to sell, when they expect to sell it, and where costs will be incurred first. Architectural demand becomes sustainable profit only after clearing customer qualification, capacity utilization, yield, and system-testing hurdles.
Agentic AI Raises Both CPU and GPU Workloads
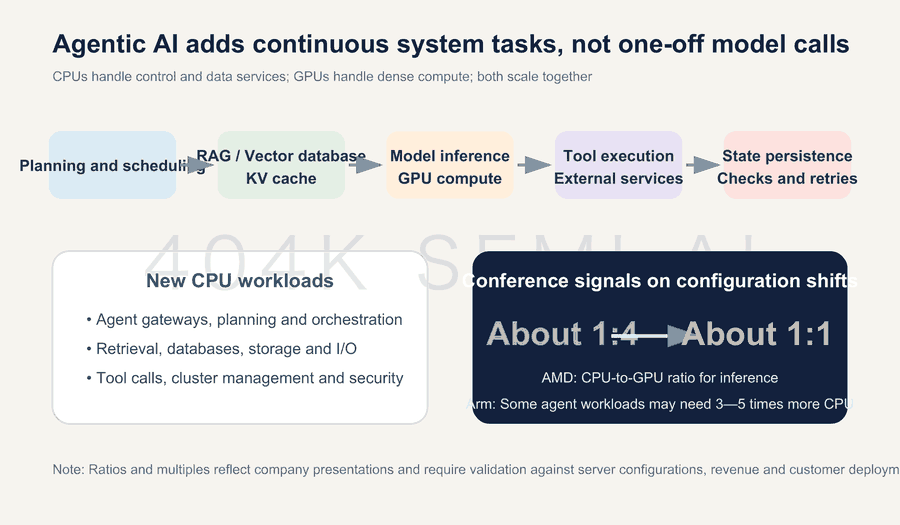
Agentic AI extends a single model call into a continuous workflow. The system must plan tasks, retrieve data, invoke tools, preserve state, validate results, and generate responses. GPUs handle highly parallel computation, while CPUs support gateways, scheduling, retrieval-augmented generation, vector databases, KV caches, tool execution, and system management.
At the OCP Summit, AMD observed that some traditional inference architectures deploy approximately 1 CPU for every 4 GPUs, while new agentic infrastructure is moving toward approximately 1:1. Arm’s upside scenario is more aggressive, suggesting that some workloads may require 3–5 times more CPUs to balance agentic traffic. These figures reflect vendor assessments and should not be treated as standardized bill-of-materials ratios.
Nomura’s research highlights practical platform frictions. LOTES said AMD Venice penetration could slow in late 2026, while Intel Oak Stream will not enter mass production until Q1 2027. Server-board output is also being constrained by memory and PCB shortages. The direction of CPU demand is positive, but platform delays and component shortages will push revenue further out.
LOTES is participating in a cloud service provider’s Arm server CPU socket project, with production scheduled for 2H27. Its 2H26 revenue from SOCAMM connectors and quick-disconnect couplings is tracking ahead of initial expectations. These products connect the expansion of CPUs, memory, and liquid cooling, illustrating how incremental agentic-AI hardware demand will be distributed across multiple interfaces.
CPU expansion should be assessed alongside server-platform mass production, the number of CPU racks, system memory and storage capacity, and revenue from networking and management chips. If a higher CPU count does not improve end-to-end throughput, the additional hardware may become underutilized redundancy.
PCB, Substrate, and HDI Suppliers Make the First Capacity Commitments
Ta Liang Technology’s equipment plan provides a relatively near-term revenue anchor. The company currently has monthly drilling and routing equipment capacity of approximately 300–400 units and plans to add 50 units/month of outsourced standard-equipment capacity through partners in 2026, rising to 100 units/month in 2027. High-end equipment accounted for more than 60% of revenue in 1H26.
Optical-module PCBs are driving demand for routing equipment, while drilling-equipment demand should begin improving in 2H26. The approximately 3-month lag between equipment shipment and revenue recognition creates a natural mismatch among orders, shipments, and reported earnings. Ta Liang Technology has also separated its semiconductor-equipment business into a subsidiary covering advanced-packaging metrology, inspection, and automation, targeting SoIC, CoPoS, fan-out panel-level packaging, and CPO.
Kinsus Interconnect Technology’s ABF expansion is more tightly linked to customer funding. The company plans to increase monthly capacity from 40 million units in 2026 to 50 million in 2027 and 80 million in 2029. It expects part of its 2028–2029 equipment capital expenditure to be supported through customer investment or equipment consignment, under contracts totaling approximately NT$60–80 billion.
