
目录
Too Long; Didn't Read
1. Capital Spending Is Rising Again, So Architecture Competition Is Taking Place Inside a Larger Budget Pool
2. Why ASIC Units Could Exceed GPUs in 2027
3. “Share” Must Be Split Into Four Layers Before Declaring a Winner
4. Nvidia: Defending System Value Share, Not GPU Unit Share
5. Broadcom: Not a GPU Substitute, but the Industrialization Platform for Cloud Custom Silicon
6. AMD: The Second Platform Has Appeared; Now Scale and Profit Must Work Together
7. The Three Companies Are Not Competing for the Same Layer of Profit
8. Three 2027–2028 Scenarios: Where Wins and Losses Reach the Income Statement First
9. What to Track During the Next Four Quarters
10. Conclusion: Budget Bifurcation Changes Growth Rankings, but Not Yet the Value Ranking
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
AI capital spending is still expanding, but the same budget is now being allocated between GPUs and ASICs according to workload.
Too Long; Didn't Read
Microsoft, Meta, Google, and Amazon now point to roughly US$720 billion–US$745 billion of 2026 capital spending. All 4 companies are adding compute. The difference is how much they spend on general-purpose GPUs versus internal ASICs, not whether they continue building.
JPMorgan estimates that global AI accelerator unit mix will shift from 58% GPU and 42% ASIC in 2026 to 47% GPU and 53% ASIC in 2027. This is unit share, not revenue or profit share; high-end GPUs still carry much higher chip prices, networking content, and software value.
Nvidia's strongest moat has expanded from individual GPUs to full racks, interconnect, networking, and software. SpaceX management targets more than 5GW of compute capacity by the end of 2027, closer to 10GW, and says it intends to use Nvidia GPUs exclusively. That creates 1 new source of nontraditional hyperscale GPU demand, but it remains a buildout target rather than a firm order.
Broadcom is the most direct beneficiary of the ASIC trend, but it is not another merchant GPU vendor. It helps cloud providers turn internal chip designs into manufacturable systems while supplying high-speed networking. Fiscal 2026 second-quarter AI semiconductor revenue reached US$10.8 billion, up 143% year over year, and third-quarter revenue is expected to reach US$16 billion. The theme is already visible in the income statement.
AMD has the highest upside and the lowest certainty among the 3 companies. Meta's commitment of up to 6GW, Anthropic's commitment of up to 2GW, and Microsoft's Helios deployment show that a No. 2 GPU platform is forming. The remaining questions are whether frameworks convert into revenue, software and racks deliver reliably, and gross margin and free cash flow improve together.
The base case is a 3-layer division of profit pools: Nvidia preserves value share in general-purpose compute, Broadcom captures custom ASIC and networking growth, and AMD contests the No. 2 merchant GPU platform. The thesis is falsified if Nvidia's system revenue and cash flow weaken together, or if AMD and Broadcom customer deployments fail to become recognized revenue for an extended period.
1. Capital Spending Is Rising Again, So Architecture Competition Is Taking Place Inside a Larger Budget Pool
During the past 2 years, the GPU-versus-ASIC debate often began in the wrong order: assume a fixed AI budget, then ask how much ASICs would take from GPUs. After the second quarter of 2026, the new fact is that the budget pool itself is still expanding. The latest figures from Microsoft, Meta, Google, and Amazon add up to roughly US$720 billion–US$745 billion, while several companies are already discussing even greater build intensity in 2027.
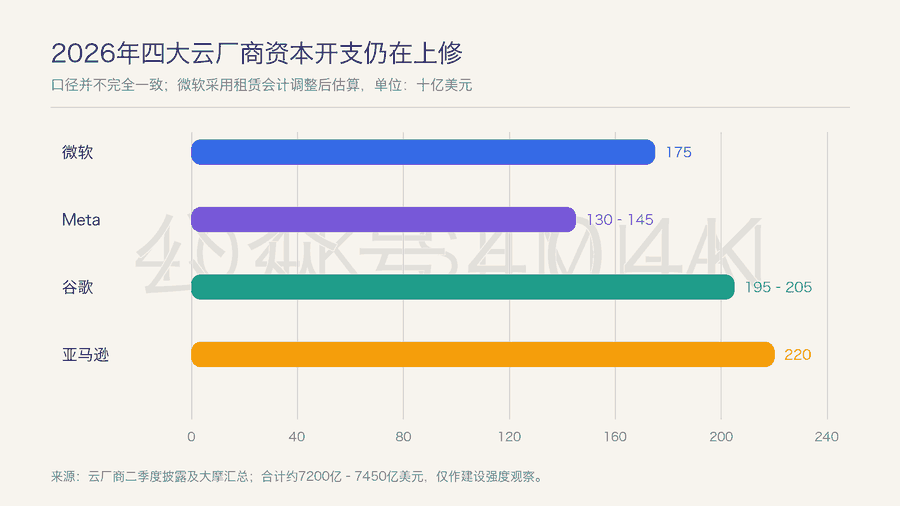
Microsoft's 2026 capital spending is about US$190 billion, or roughly US$175 billion after adjusting for the new lease-accounting treatment. Its fiscal 2027 first-quarter capital spending, corresponding to the third calendar quarter of 2026, is expected to exceed US$50 billion, up from US$41 billion in the prior quarter. Microsoft is deploying its own Maia silicon alongside Nvidia and AMD platforms. This matters: leading cloud providers have not designed internal chips and merchant GPUs as mutually exclusive choices. They use different platforms for different workloads.
Meta narrowed its 2026 capital-spending range to US$130 billion–US$145 billion. Google raised its full-year range by US$15 billion to US$195 billion–US$205 billion and said 2027 would be significantly higher. Amazon raised 2026 capital spending by about US$20 billion to US$220 billion, citing compute construction and higher memory costs, among other factors. Morgan Stanley's compilation also indicates that most of Amazon's 2027 compute capacity has already been reserved, while management continues to describe 2028 demand as strong.
2026 Capital Spending and Architecture Implications at the Four Largest Cloud Providers
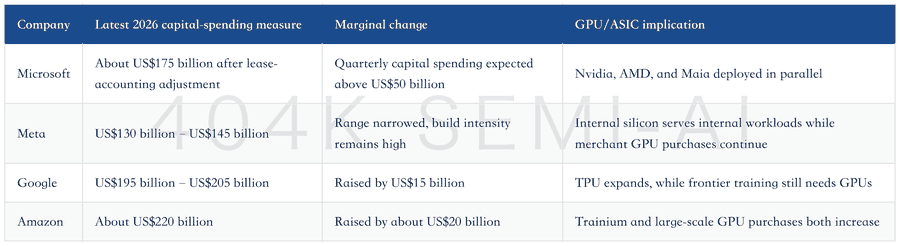
These figures cannot be treated as perfectly comparable accounting data because leases, server purchases, data-center construction, and networking equipment are classified differently. They nevertheless establish the direction: while demand still exceeds available compute, ASIC growth first appears as a division of incremental budgets rather than an absolute decline in GPU orders.
That is why cloud providers can promote internal silicon while signing large Nvidia and AMD deployments. Internal ASICs lower the unit cost of stable workloads; merchant GPUs shorten the launch time for new models, algorithms, and customers. As long as total AI workloads grow faster than the pace of architecture substitution, both tracks can expand at once.
The more important warning signal is a different combination: capital spending rises, but powered racks, cloud revenue, order absorption, and free cash flow do not. At that point, the question is no longer which architecture took share. The entire buildout cycle would be producing a lower return on investment. Second-quarter evidence still looks more like insufficient supply than comprehensive compute overcapacity.
2. Why ASIC Units Could Exceed GPUs in 2027
ASICs improve task-specific efficiency by removing general-purpose capability that a defined workload does not need. When model architecture, operators, data flows, and deployment scale become stable enough, cloud providers can use custom chips to reduce inference power, chip cost, and system cost while retaining part of the supply-chain economics inside their own cloud platforms.
JPMorgan estimates that GPUs will represent 58% and ASICs 42% of global AI accelerator shipments in 2026. By 2027, GPU share falls to 47% and ASIC share rises to 53%. Component forecasts show that the combined growth of Google's TPU, Amazon's Trainium and Inferentia, Meta's MTIA, and Microsoft's Maia is enough for ASIC units to exceed GPU units for the first time.
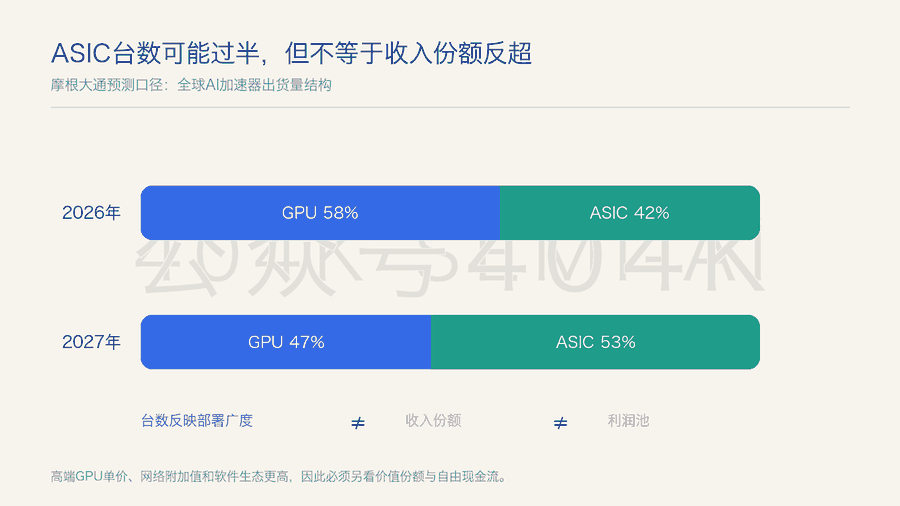
The key is not the 53% figure by itself. ASICs are moving from single-customer experiments to million-unit production. Morgan Stanley estimates that major ASIC shipments could rise from about 5.8 million units in 2026 to roughly 12 million in 2027. Within that total, TPU shipments rise from about 3.7 million to about 7.35 million, while Trainium rises from about 1.7 million to about 2.53 million. Once volume crosses a threshold, custom silicon improves its software tools, supply-chain bargaining power, and system reliability, creating positive feedback.
ASICs also have clear boundaries. First, upfront design costs are high and require a large stable workload for amortization. Second, workload changes can make a specialized design obsolete faster. Third, a chip is not the same as usable compute: cloud providers still need compilers, frameworks, interconnect, memory, fault recovery, and developer tools. Fourth, external customers care more about migration cost and vendor neutrality, so successful internal use does not guarantee broad adoption by outside cloud customers.
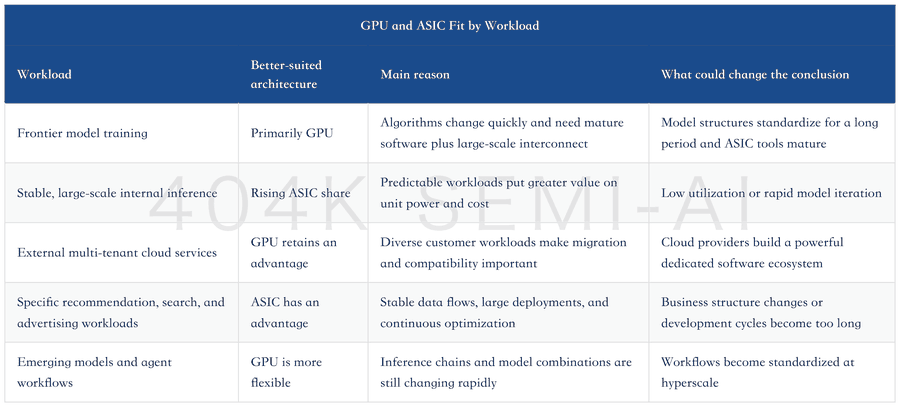
The most likely 2027 outcome is therefore a 2-tier procurement structure. Cloud providers move the largest, most predictable internal workloads to ASICs while retaining GPUs for fast-changing, high-value, or externally compatible workloads. ASICs win more units, while GPUs can still generate more system revenue and profit.
3. “Share” Must Be Split Into Four Layers Before Declaring a Winner
AI-chip competition has at least 4 different share measures: units, advanced-packaging demand, revenue, and profit. Each can describe a real change, but none can substitute for the next layer.
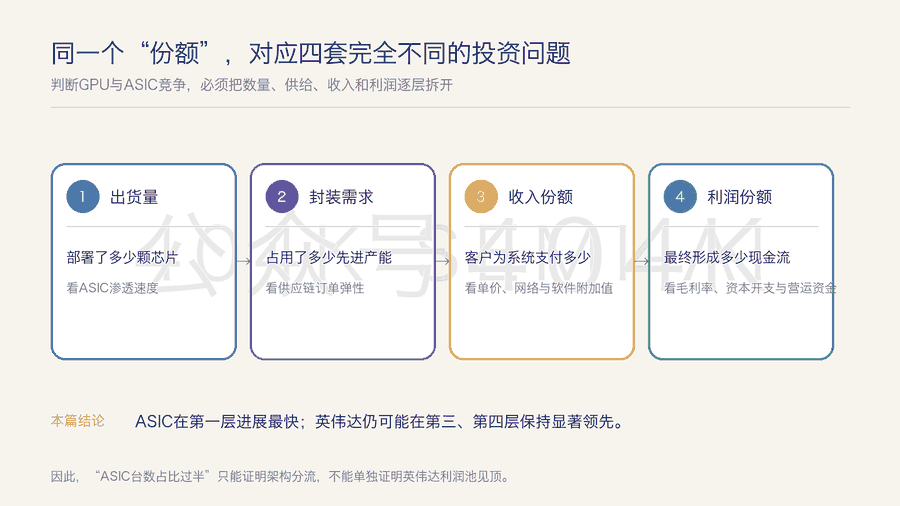
Unit share answers how broadly a chip is deployed. ASICs usually sell below the price of the most advanced GPU systems, so units can grow quickly. Advanced-packaging demand answers how supply-chain orders are redistributed. Morgan Stanley expects Nvidia, Broadcom, and AMD to move from 56%, 22%, and 9% of CoWoS demand in 2026 to 45%, 18%, and 20% in 2027. AMD gets the largest marginal increase, Nvidia still controls the largest packaging pool, and Broadcom can grow in absolute terms even as its percentage declines.
