
目录
Executive Summary
Breaking Down the “$200 Billion”
How the $27 Billion per GW Estimate Is Derived
TPUs Will Make Google Cloud a Much Larger Revenue Pillar
Revenue Surges, but Margins Edge Lower
Three Catalysts Will Determine the Valuation Multiple
The Strongest Counterargument Is Capex and Cash Flow
The $400 Price Target Requires Two Wins
Eight Validation Metrics to Monitor
Conclusion: $200 Billion Is Quantifiable; $400 Requires Execution
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Morgan Stanley now models nearly $200 billion in Google TPU system sales over two years. The revenue path is quantifiable, but a valuation rerating must still clear three hurdles: models, products, and cash flow.
Executive Summary
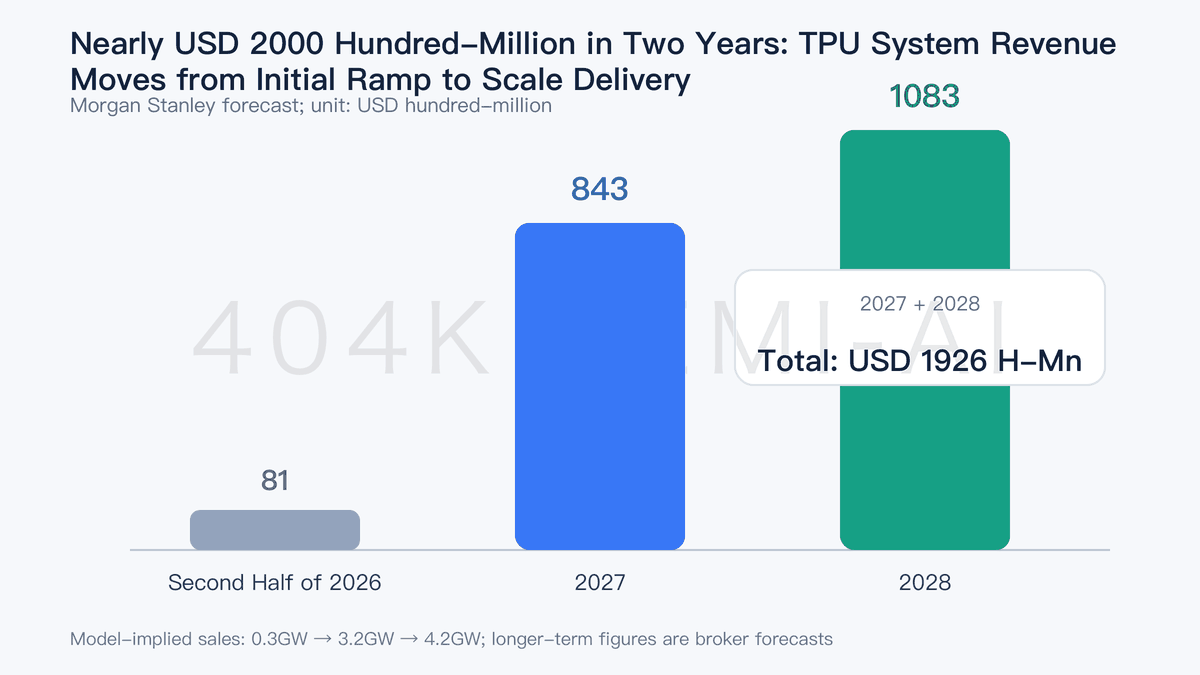
Morgan Stanley raised its first-party Google TPU system revenue assumption from approximately $20 billion to $27 billion per GW and its gross-margin assumption from 20% to 30%. The model projects 3.2 GW of sales and $84.3 billion of revenue in 2027, followed by 4.2 GW and $108.3 billion in 2028. The combined $192.6 billion for 2027–2028 underpins the headline “$200 billion.”
This revenue forecast depends on a multi-stage chain of assumptions. Media reports of a supply arrangement involving approximately 1 million TPUs, 1.3 GW of capacity, and $35 billion in value imply roughly $27 billion per GW. Morgan Stanley then extrapolates using v8 and v9 rack volumes, power consumption, costs, and a 30% gross margin. Google has not issued corporate guidance for these long-term assumptions.
TPU sales would rapidly reshape Google Cloud’s business mix. Morgan Stanley expects Google Cloud revenue to reach $235.7 billion in 2027 and $343.2 billion in 2028, with TPUs contributing 36% and 32%, respectively. Cloud EBIT is projected at $86.5 billion and $136.6 billion, accounting for 48% of Google’s company-wide EBIT in 2028.
Scale will not translate proportionally into earnings per share. The TPU sales assumptions lift Google’s projected revenue by approximately 2% in 2027 and 3% in 2028, but EPS by only about 1% and 2%. Equipment costs, depreciation, working capital, and capital expenditure absorb most of the incremental revenue, while the assumed 30% TPU gross margin remains below that of the core cloud business.
Morgan Stanley identifies three valuation catalysts: Gemini 4 returning to or approaching the frontier; highly efficient models such as Gemini Flash gaining adoption as enterprise budgets tighten; and generative AI features scaling fully across Search, YouTube, and other products. TPUs raise earnings, but these three product catalysts determine the valuation multiple.
The $400 price target requires both earnings and valuation assumptions to materialize. Morgan Stanley applies an approximately 24x P/E multiple to average 2027–2028 EPS of $16.84. Its bear, base, and bull cases are $225, $400, and $460. Capital expenditure and free cash flow will determine whether the market accepts this premium.
Breaking Down the “$200 Billion”
The $200 billion in Morgan Stanley’s headline refers to approximately $192.6 billion of first-party TPU system sales revenue across 2027 and 2028: $84.3 billion in 2027 and $108.3 billion in 2028. It excludes both the GPU procurement savings generated by Google’s internal TPU use and Google Cloud service revenue unrelated to TPUs.
The report classifies these transactions as first-party sales. Revenue is recognized on complete racks and systems rather than individual chips. TPU system sales are already included in Google Cloud product revenue, but the company has not disclosed unit volumes, customer concentration, contract duration, or generation-specific pricing. Investors are therefore looking at a new business with a visible financial contribution but limited underlying disclosure.
The model begins in the second half of 2026. Morgan Stanley expects sales of 0.3 GW, generating approximately $8.1 billion in TPU revenue. Volume then rises to 3.2 GW in 2027 and 4.2 GW in 2028. GW capacity sold increases approximately 14-fold over two and a half years, driving a corresponding surge in revenue. Most of the growth comes from higher delivery volumes, while pricing assumptions remain broadly stable.
It is important to distinguish the “revenue headline” from economic value. The $27 billion per GW represents system revenue recognized by Google from customers. At a 30% gross margin, every $27 billion of revenue generates approximately $8.1 billion in gross profit, while roughly $18.9 billion is absorbed by racks, chips, networking, power systems, and other costs. The revenue figure is large, but profit does not scale at the same rate.
How the $27 Billion per GW Estimate Is Derived
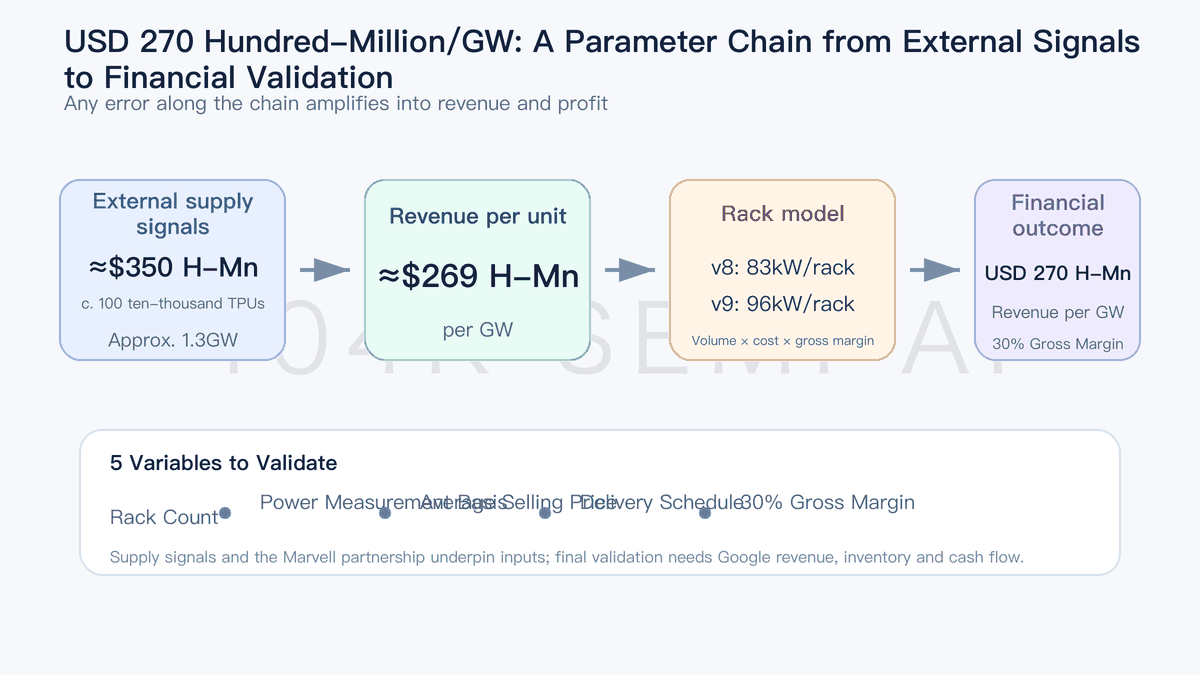
Morgan Stanley’s previous model assumed approximately $20 billion in revenue per GW and a 20% gross margin. The first piece of evidence supporting the new model comes from external reports that Google could supply approximately 1 million TPUs, representing roughly 1.3 GW of compute capacity and a contract value of about $35 billion. Dividing $35 billion by 1.3 GW yields approximately $26.9 billion per GW, close to the new $27 billion assumption.
The second piece of evidence is Google’s expanded custom-chip partnership with Marvell Technology. Morgan Stanley views this as supporting evidence that TPU pricing and average selling prices are higher than previously estimated. The partnership itself demonstrates only an expansion in the supply chain and product roadmap; it cannot independently substantiate end-market pricing or gross margins. Actual contracts, inventory, and revenue recognition must still validate the new assumptions.
The bottom-up 2027 model is more specific. Morgan Stanley projects sales of 31,154 v8 racks, each consuming approximately 83 kW, for a total of roughly 2.6 GW. It also expects sales of 6,114 v9 racks, each consuming approximately 96 kW, totaling about 0.6 GW. v8 and v9 revenue is estimated at approximately $69.3 billion and $15.0 billion, respectively, for total revenue of $84.3 billion.
The model further assumes that each v8 rack costs Google approximately $1.71 million and each v9 rack approximately $1.88 million, with a 30% gross margin added above cost. The report estimates TPU revenue at approximately $26.5 billion per GW, 18% below the estimated cost per GW of Nvidia Vera Rubin racks. This comparison juxtaposes Google’s sales revenue with a competing system’s cost, so the metrics are not fully comparable. It is useful for assessing price competitiveness but cannot directly determine customers’ total cost of ownership.
