
Goldman Sachs Sharply Raises Yageo Target Price: Commodity MLCC at Full Utilization, 93% Price Hike, and Inventory Payback Risk
目录
Too Long; Didn’t Read
I. What Really Changed in This Goldman Sachs Update
II. Commodity MLCC Is Not a Lagging Asset, But Second-Order Leverage After AI Capacity Migration
III. Yageo’s Company Profile: Not the Highest-End Anchor, but a Commodity MLCC and Multi-Product Platform
IV. Asset-Attribute Migration: From Inventory-Cycle Stock to High-ROE Pricing Platform
V. Goldman Sachs Model: ASP, Gross Margin, and EPS All Revised Up
VI. Raising the Target Price from NT$346 to NT$1,490: Is It Expensive?
VII. Difference Versus Morgan Stanley’s Earlier Model: From High-Capacitance Crowding-Out to Commodity Full Utilization
VIII. Peer Comparison: Yageo Has Strong Leverage, but the Technical Anchor Is Not There
IX. Supply-Chain Mapping: Upstream Powders and Consumables Will Become Validation Windows
X. Disconfirmation Checklist: What Would Push Yageo Back to Cyclical-Stock Valuation
XI. How to Track the Next Four Quarters
XII. Three Worldviews: Price Cycle, Profit Platform, Inventory Backlash
XIII. How to Use Sell-Side Divergence: Do Not Look Only at Target Prices; Look at the Assumption Chain
XIV. Investment Judgment: Yageo’s Risk-Reward Has Shifted from “Cheap” to “Execution”
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Goldman Sachs sharply raised its Yageo target price from NT$346 to NT$1,490. The core is not a price increase for a single AI component, but rather that after Japanese and Korean capacity shifts toward AI, commodity MLCC supply has been squeezed to full utilization. With a 25% capacity share, Yageo can turn price hikes into profit and valuation upside in 2027-2028.
Too Long; Didn’t Read
What investors are buying in Yageo this time is commodity MLCC price inflation. Goldman Sachs raised its commodity MLCC ASP assumptions to 93%/84%, arguing that after AI-grade MLCC absorbs Japanese and Korean high-end capacity, non-AI commodity MLCC supply will tighten. This is not simply chasing an AI theme, but translating the second-order impact of AI demand into commodity MLCC, where Yageo has the strongest share and the greatest ability to manage channels and pricing cadence.
The target price was raised from NT$346 to NT$1,490. That move itself is the report’s key signal, backed by simultaneous upgrades to EPS, gross margin, and ROE. If price increases stop at the distribution channel, valuation could easily give back gains; if direct-customer pricing, utilization, and inventory discipline all materialize, the market will re-rate Yageo as a high-ROE cyclical platform.
Yageo is not the leading player in the most advanced AI MLCC segment. Murata, Samsung Electro-Mechanics, and Taiyo Yuden have more direct exposure to 47uF+ high-capacitance MLCC and AI server qualification. Yageo’s strengths are commodity MLCC, chip resistors, tantalum capacitors, and its distribution system. The more high-end capacity shifts toward AI, the harder it becomes for low- and mid-capacitance and non-AI customers to secure low-cost supply. That is exactly where Yageo’s profit leverage comes from.
Valuation is no longer cheap, but it also cannot be judged only on static multiples. Yageo’s current valuation needs to be explained through forward EPS, ROE, and gross margin together. Looking only at current-year PE can easily lead to the conclusion that it is too expensive. This valuation only holds if commodity MLCC price increases persist, gross margin moves onto a new platform, and ROE is materially above the historical cycle average.
The biggest risk is that price hikes are pulled forward by inventory. Goldman Sachs’ downside risks include OEM inventories falling short of expectations, weakening IT end-market demand, and slower-than-expected integration of Kemet/Chilisin/Telemecanique/Shibaura. More practical falsification indicators are price increases failing to land consecutively, non-AI MLCC utilization declining, distribution inventory building, and monthly EPS failing to follow ASP upgrades.
Over the next four quarters, watch four data sets. First, whether commodity MLCC ASP continues to rise; second, whether MLCC revenue mix continues to increase; third, whether operating margin rises with pricing; and fourth, whether consensus catches up with Goldman Sachs’ new assumptions. As long as these four data sets improve in the same direction, Yageo’s high valuation still has room to be explained.
I. What Really Changed in This Goldman Sachs Update
The importance of this Yageo update lies in Goldman Sachs moving the company from “a beneficiary of spillover from AI high-capacitance MLCC” to “the company with the strongest operating lever in a commodity MLCC price-up cycle.” Yageo’s prior investment case was already familiar: AI servers lift demand for high-capacitance MLCC; Japanese and Korean suppliers allocate high-end capacity to AI customers; low- and mid-capacitance and standard specifications are squeezed out; and Yageo regains pricing power through commodity MLCC, chip resistors, and tantalum capacitors.
Yageo Deep-Dive Update: Pricing Power Arrives Faster and Stronger; How AI Crowding-Out Rewrites the Income Statement
The new information this time is not the broad statement that “AI demand remains very strong,” but that Goldman Sachs has provided a more aggressive and more testable commodity MLCC model. The key numbers should not be scattered through the text; they are clearer in the table below.
These figures must be read together. The 93% and 84% price-increase assumptions show that Goldman Sachs is not only looking at high-capacitance MLCC for AI servers themselves, but judging that the migration of high-end capacity will push non-AI commodity MLCC close to full utilization. The 46% and 51% gross margins show that this is not merely a revenue upgrade, but a direct flow-through of price increases into margins. NT$57.32 EPS shows that the valuation anchor has already been pushed out to 2028.
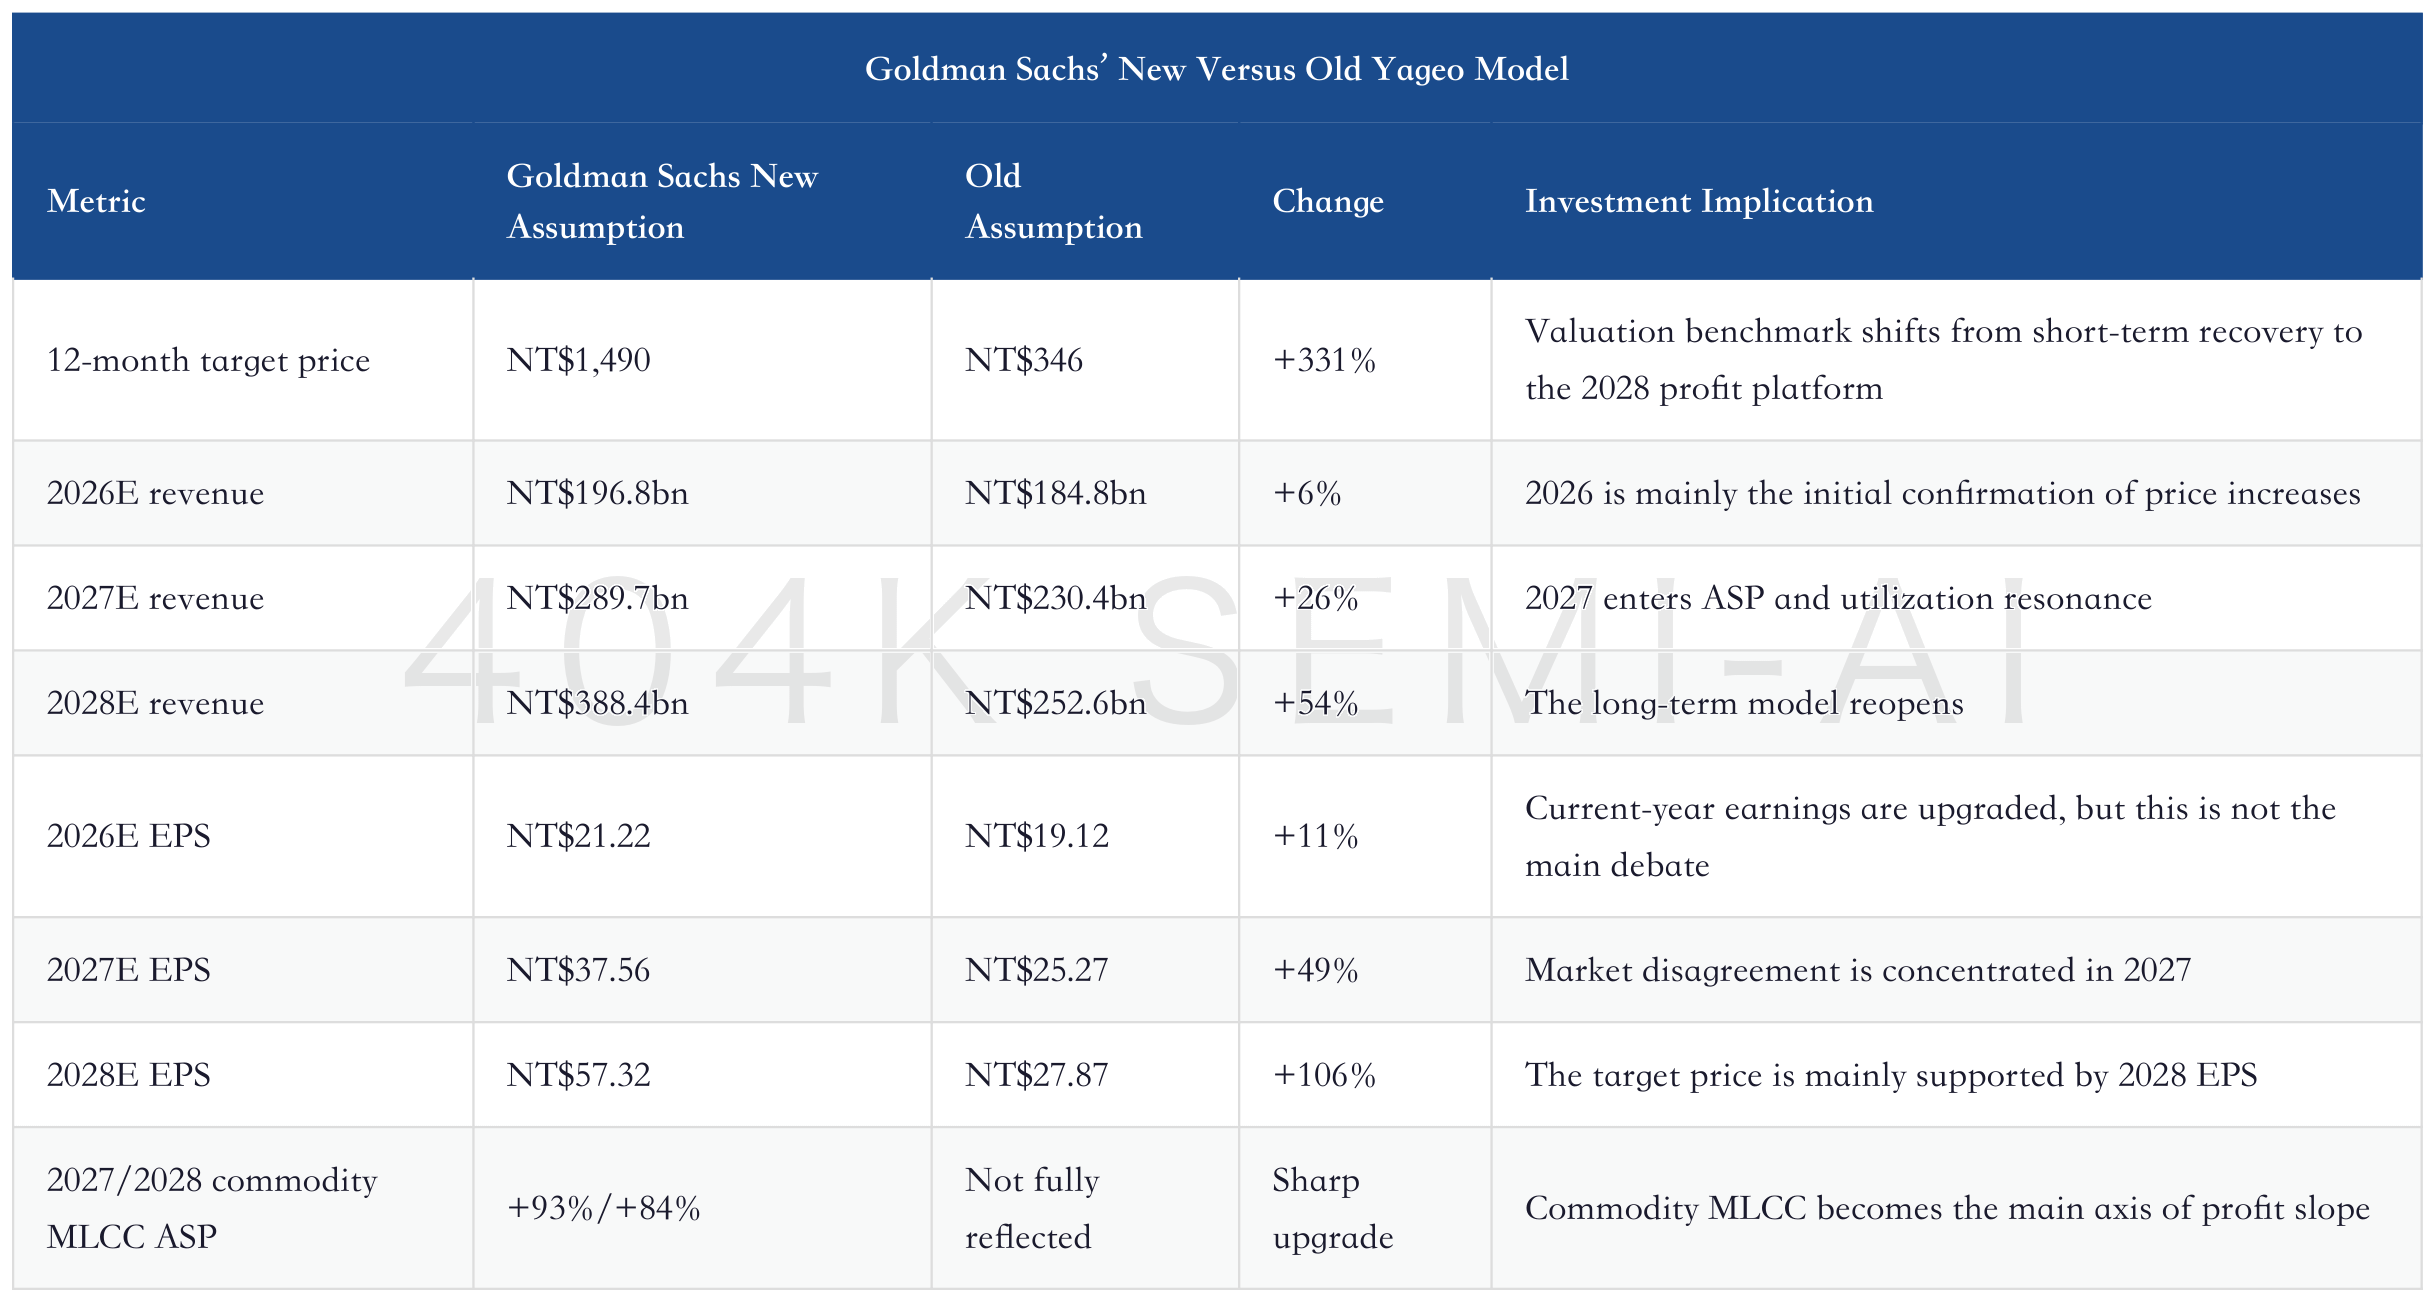
The key point in this table is not how much the target price increased, but that the upgrades are concentrated in 2027-2028. If one only looks at 2026, Yageo has already risen substantially and static valuation is no longer cheap. If one looks at 2028, the market is starting to trade a completely different income statement. That income statement requires three conditions to hold at the same time: commodity MLCC capacity utilization approaches full load, Yageo can continue raising prices through channel and customer relationships, and costs do not rise sharply in parallel.
Goldman Sachs’ framework clearly links with Morgan Stanley’s Yageo update in late June. Morgan Stanley earlier provided evidence of direct-customer price increases and monthly earnings, while Goldman Sachs frames commodity MLCC price increases as the main long-term profit engine. The two firms’ target prices are close, but Goldman Sachs raises the 2028 earnings model more aggressively.
This is not a simple report saying “Yageo can still rise.” What it really answers is: after Yageo’s share price has already rallied sharply, can the market still use a framework of higher ROE, higher gross margin, and a longer price-up cycle to reprice the stock? The answer depends on commodity MLCC, not a single word: AI.
II. Commodity MLCC Is Not a Lagging Asset, But Second-Order Leverage After AI Capacity Migration
The easiest way to misread Yageo is to ask: if what AI servers truly need is high-capacitance, high-reliability, miniaturized MLCC, why buy a company like Yageo, which has a higher commodity MLCC mix? The question is fair, but the answer is not “Yageo is also an AI MLCC leader.” It is that “the more high-end capacity is taken by AI, the tighter commodity MLCC supply becomes.”
Goldman Sachs’ industry assumptions are clear: AI MLCC grows faster, per-rack content in servers is materially higher than in standard servers, and AI-grade products will absorb effective capacity first. The specific assumptions are better shown in the table below, which explains why commodity MLCC is being squeezed.
MLCC Deep-Dive Update: Agentic AI, Rubin Racks, and the High-End Capacitor Supply Gap
These numbers directly explain why Japanese and Korean manufacturers will migrate capacity toward AI-grade MLCC. High-end products have higher gross margins, more concentrated customers, and longer order visibility, so suppliers naturally prioritize AI servers, high-end computing, automotive, and other applications. The issue is that MLCC capacity is not infinitely elastic. Advanced part numbers require more stacking, sintering, screening, reliability testing, and customer qualification. Nominal capacity can grow by about 10% per year, but effective capacity will be consumed by product transitions and yield requirements.
Commodity MLCC therefore becomes second-order leverage. It is not the main battlefield for AI servers, but it is the pressured zone after AI crowds out the main battlefield. As high-end capacity is absorbed by AI, non-AI customers return to normal demand growth, and inventory remains below historical highs, commodity MLCC will move from loose supply back to high utilization.
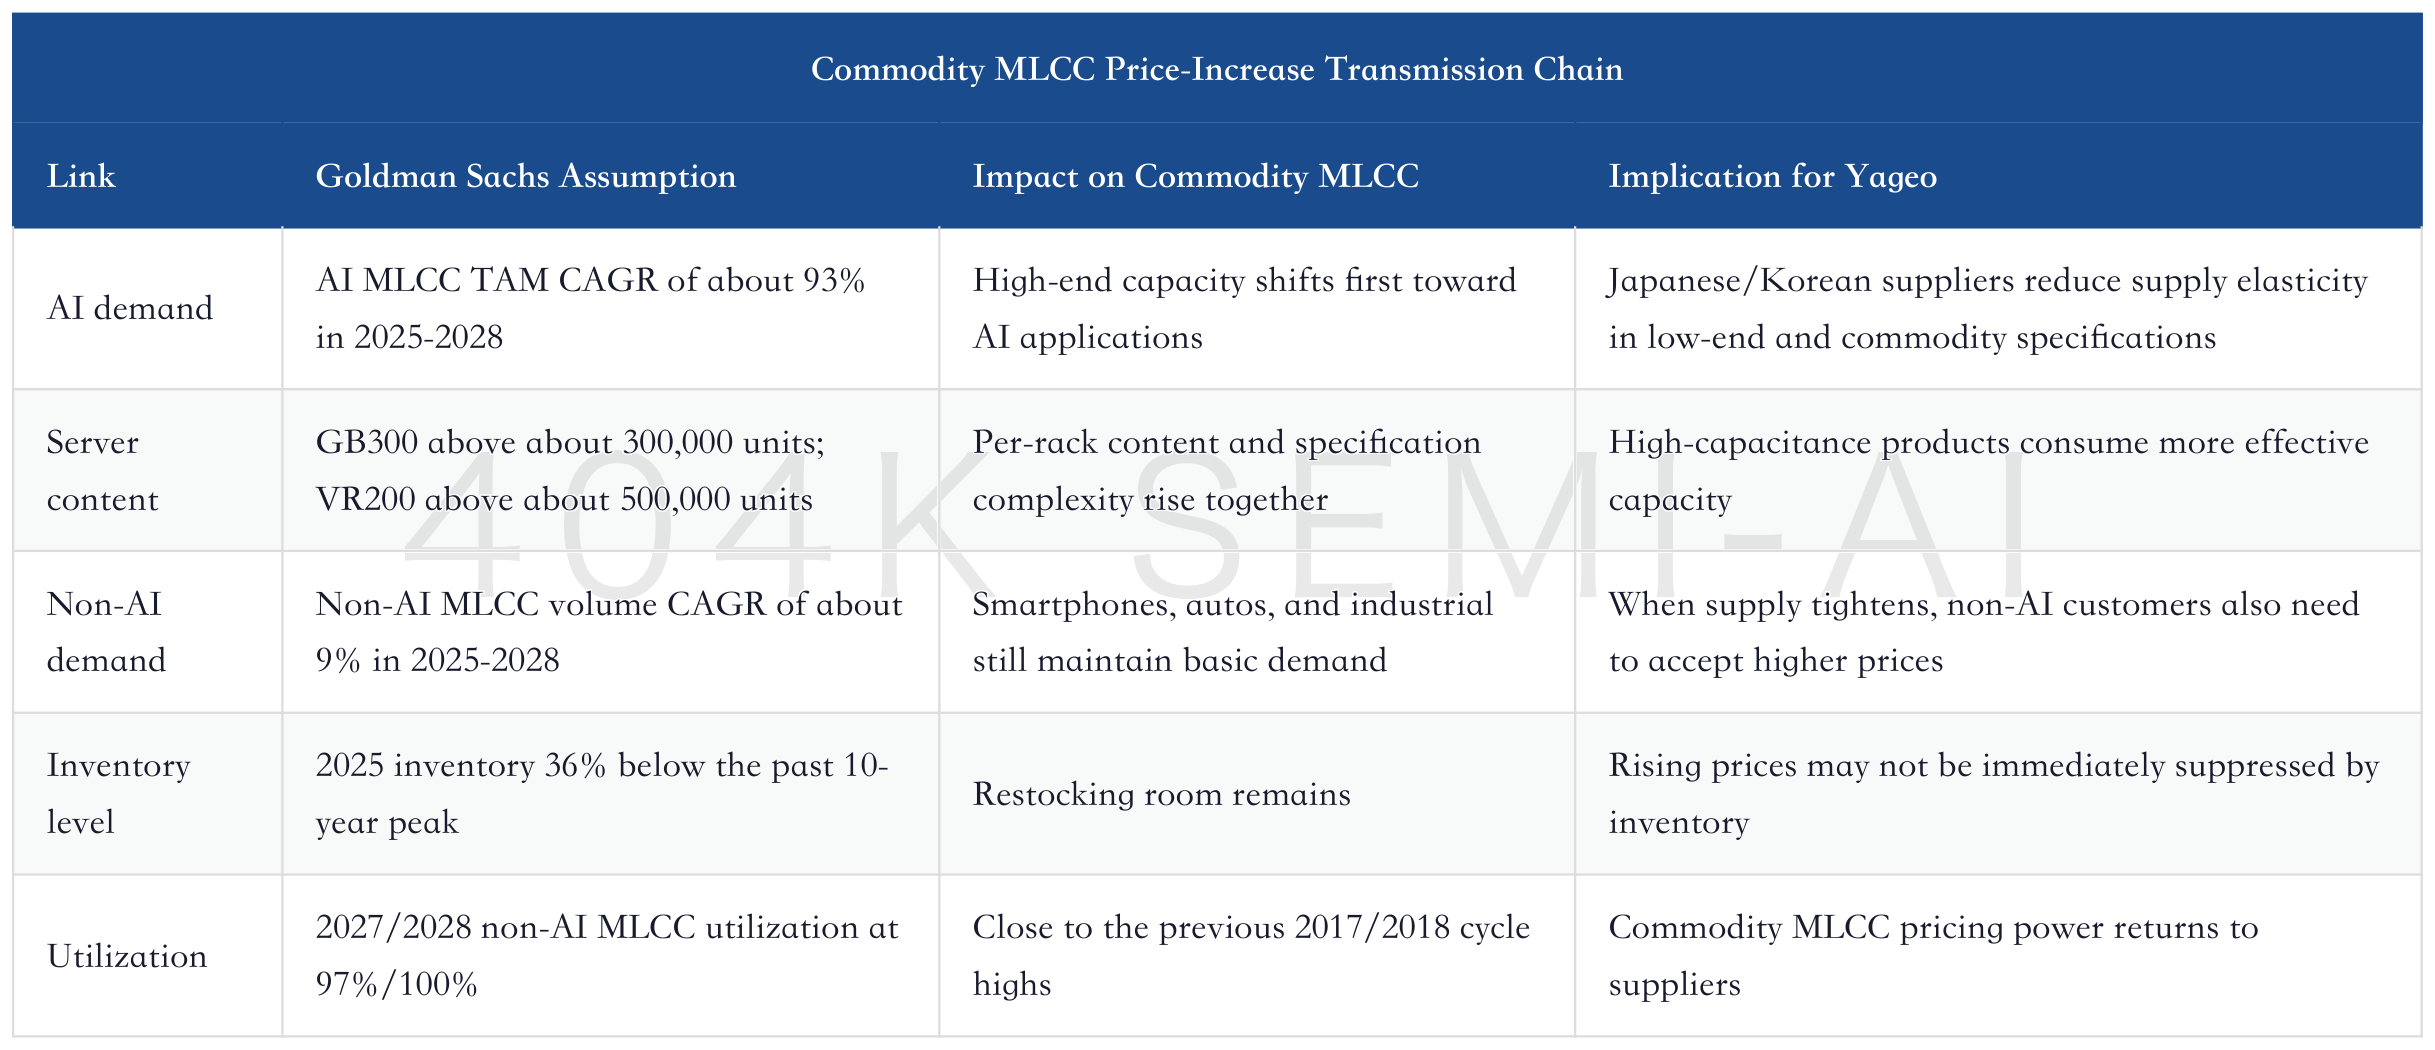
This round of commodity MLCC price increases differs from the previous 2017-2018 cycle. The last cycle was driven by smartphones, automotive electronics, and passive-component restocking all at once. Prices were quickly amplified through distribution and the spot market, which also led to channel hoarding. The new cycle is more about a change in capacity structure: AI locks up high-end capacity, non-AI demand is not booming but is still growing, and low inventory leaves customers with limited buffer.
This is why Goldman Sachs believes the magnitude of commodity MLCC price increases may exceed that of high-end MLCC. High-end AI part numbers already have relatively high gross margins, customers are mostly large accounts, and price adjustments require long-term agreements and qualification cadence. Commodity MLCC has a low base, fragmented customers, and heavy historical discounts. Once supply tightens, the percentage price increase can actually be larger. This view looks counterintuitive, but it is very important for Yageo.
Yageo is not the purest technology anchor in high-end AI MLCC. Murata, Samsung Electro-Mechanics, and Taiyo Yuden have more direct exposure to high-capacitance, high-reliability, miniaturized part numbers. But Yageo is one of the largest holders of commodity MLCC capacity. Goldman Sachs estimates Yageo’s commodity MLCC capacity share at about 23% in 2026, and the report’s opening section puts its global commodity MLCC capacity share at about 25% in 2026-2028. The second-largest supplier has only about 15% share. In a market where pricing shifts from loose to tight, share, channel control, and inventory discipline matter more than having the most advanced specifications.
Murata Manufacturing Deep-Dive Update: The Profit Gate and Valuation Discipline of AI Server MLCC
III. Yageo’s Company Profile: Not the Highest-End Anchor, but a Commodity MLCC and Multi-Product Platform
Yageo’s investment framework should not be written as “it will replace Murata.” What is truly distinctive about the company is its high share in commodity MLCCs, deep distribution system, meaningful profit contribution from chip resistors and tantalum capacitors, and the broader passive-component portfolio it has built through acquisitions such as Kemet, Chilisin, Telemecanique, and Shibaura.
Goldman Sachs describes Yageo in its investment thesis as the world’s third-largest MLCC supplier and one of the world’s largest suppliers of resistors and tantalum capacitors. This positioning is critical. MLCCs give it an entry point into AI hardware price increases; resistors and tantalum capacitors provide platform-level profit leverage; and acquired assets give it a customer base across automotive, industrial, high-reliability, and power-supply chains. Yageo’s asset profile is not a single specification or part number, but a group of passive components that may all be repriced as AI power density rises.
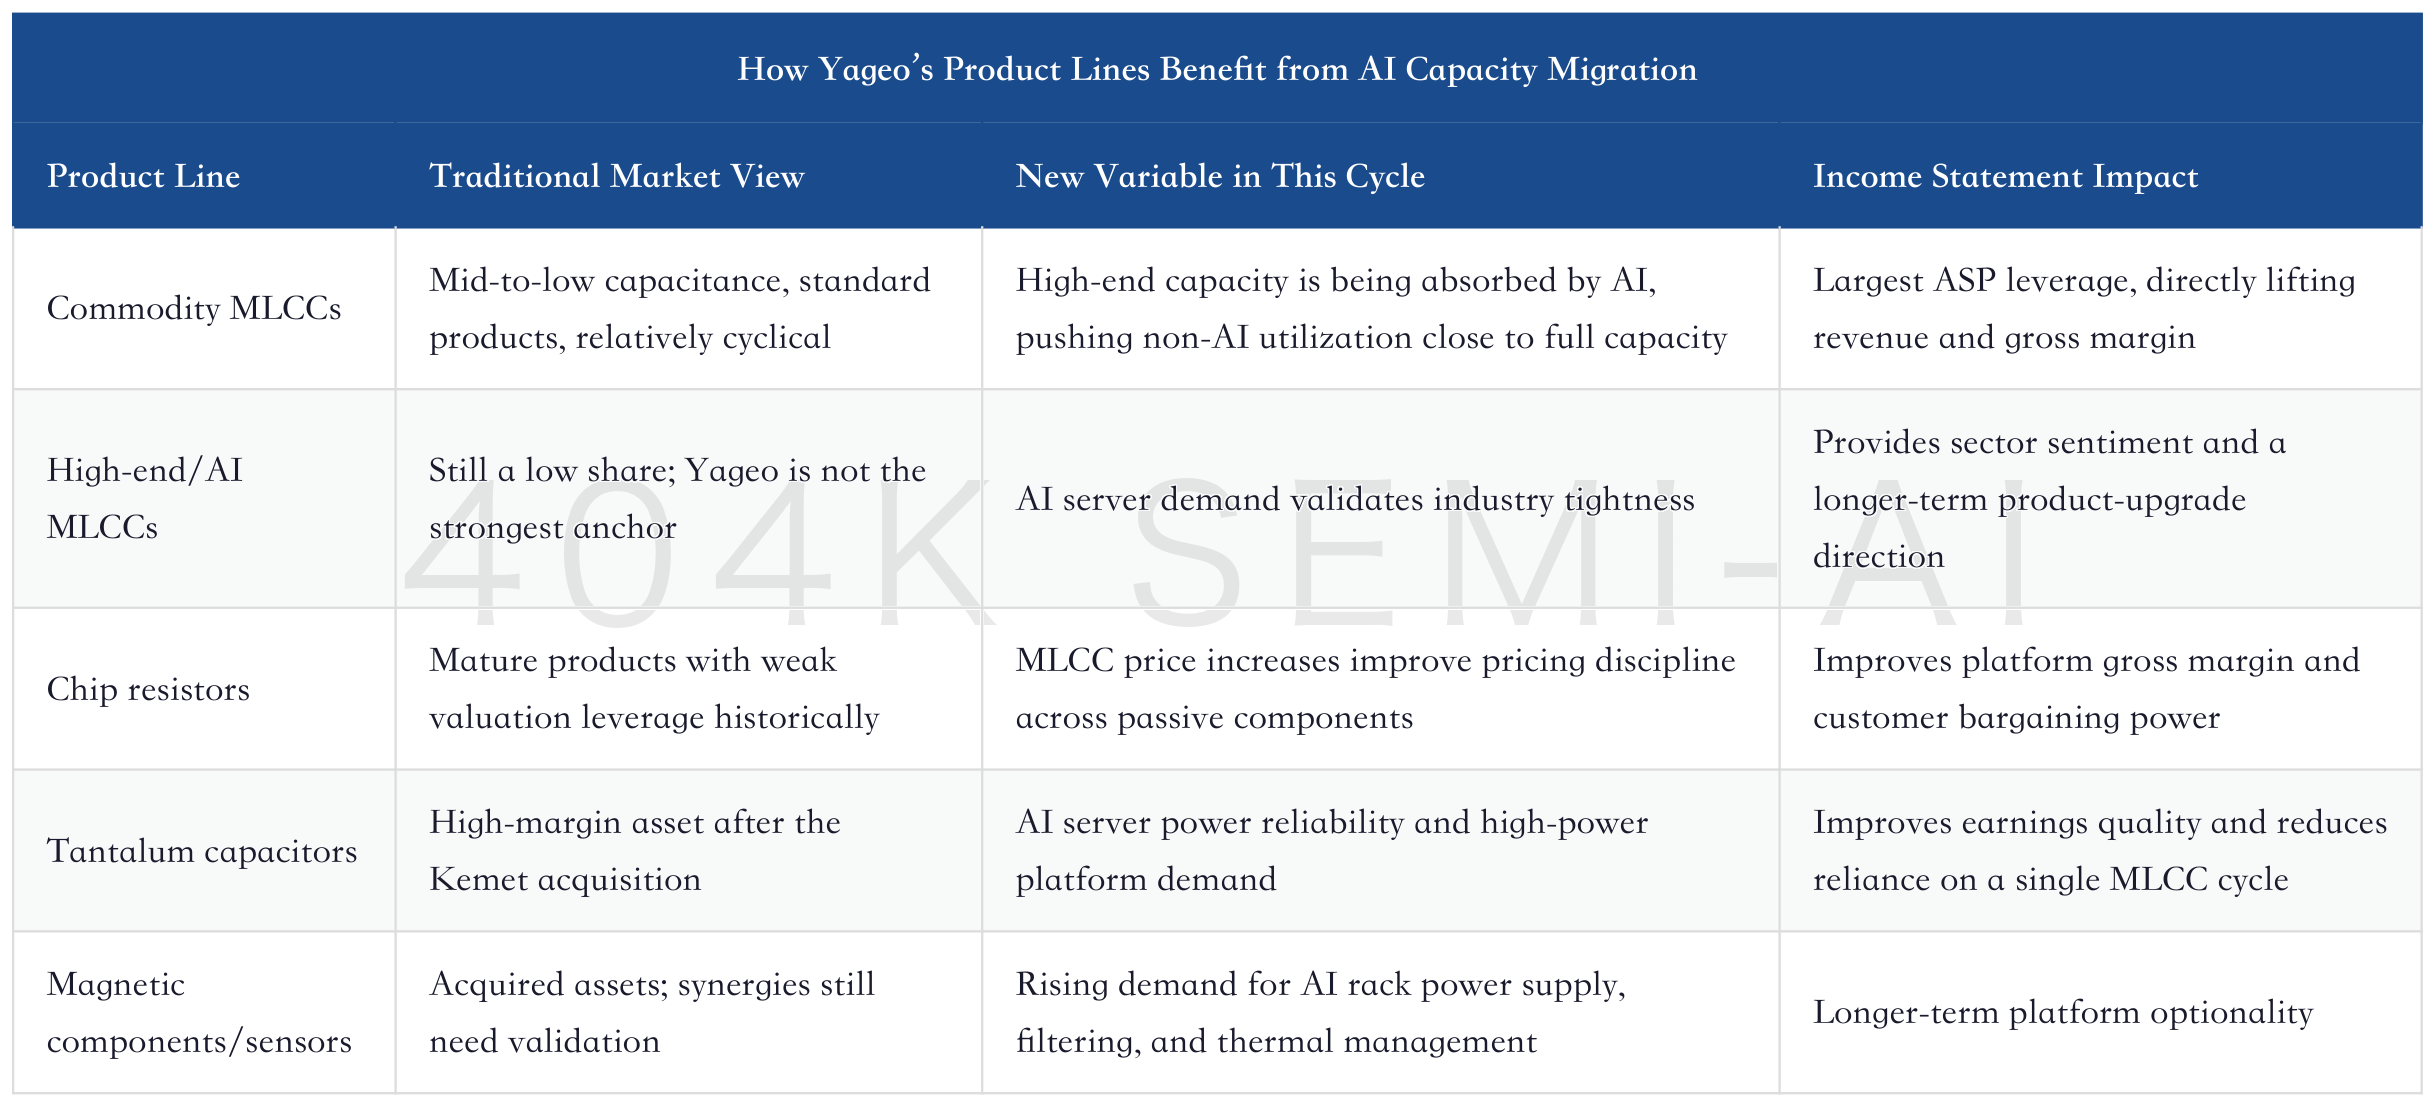
This also explains why Yageo shows large earnings leverage across different institutional models. Morgan Stanley emphasizes high-capacitance crowding-out and direct-customer price increases, while Goldman Sachs emphasizes commodity MLCC price increases and capacity share. The two are not contradictory: high-capacitance MLCCs are the starting point of supply reallocation, while commodity MLCCs are the main lever through which Yageo monetizes profit.
Another variable in Yageo’s business model is easily underestimated: distributor relationships. Goldman Sachs specifically notes that Yageo’s leadership in the commodity MLCC market, high capacity share, and strong distributor relationships enable the company to control utilization and industry inventory levels, thereby pushing through price increases. In the passive-component market, pricing is not a single unified list price. Distribution inventory, customer allocation, direct-customer discounts, and the mix of long- and short-term orders all affect realized ASP. Yageo’s channel capability makes it easier than many pure manufacturers for the company to manage the pace of pricing.
Of course, this is also a source of risk. A distribution system can amplify profits, but it can also amplify inventory volatility. If price increases drive customers and distributors to stockpile ahead of demand, near-term EPS will look strong; but if end demand does not follow, the inventory backlash can also arrive quickly. That was the lesson of the 2018 cycle. Whether Yageo can break away from the old script of a post-price-bubble decline depends on whether price increases are being driven more by genuine effective capacity shortages than by channel hoarding.
A more balanced judgment is that Yageo still has cyclical attributes, but the cycle anchor is changing. In the past, the cycle anchor was consumer electronics and channel inventory. Now it is AI-driven migration of high-end capacity, non-AI utilization, direct-customer pricing, and commodity MLCC pricing discipline. It is not yet a pure structural growth stock, but it is no longer just a restocking stock.
IV. Asset-Attribute Migration: From Inventory-Cycle Stock to High-ROE Pricing Platform
The real change for Yageo this time is not only that Goldman Sachs has raised its model, but that the market is redefining what kind of asset it is. In the past, Yageo’s trading framework was simple: consumer electronics restocking, recovery in MLCC and chip-resistor prices, channel inventory drawdown, gross-margin repair, and then a decline during the next capacity expansion and inventory reversal. This is the typical framework for an inventory-cycle stock: strong earnings leverage, but a clear valuation ceiling.
The question has changed. AI servers have not instantly turned Yageo into a non-cyclical growth stock, but they have changed the cycle’s starting point, duration, and margin ceiling. In the past, price increases mostly came from sudden demand improvement and restocking. Now, price increases are more driven by high-end effective capacity being locked up by AI applications. In the past, Yageo’s advantages were standard-product scale and channels. Now, these advantages can be converted into pricing discipline. In the past, the market worried that standard products were vulnerable to competitive price pressure. Now, standard products are instead gaining room for price increases because supply is being crowded out by the migration of capacity to high-end products.
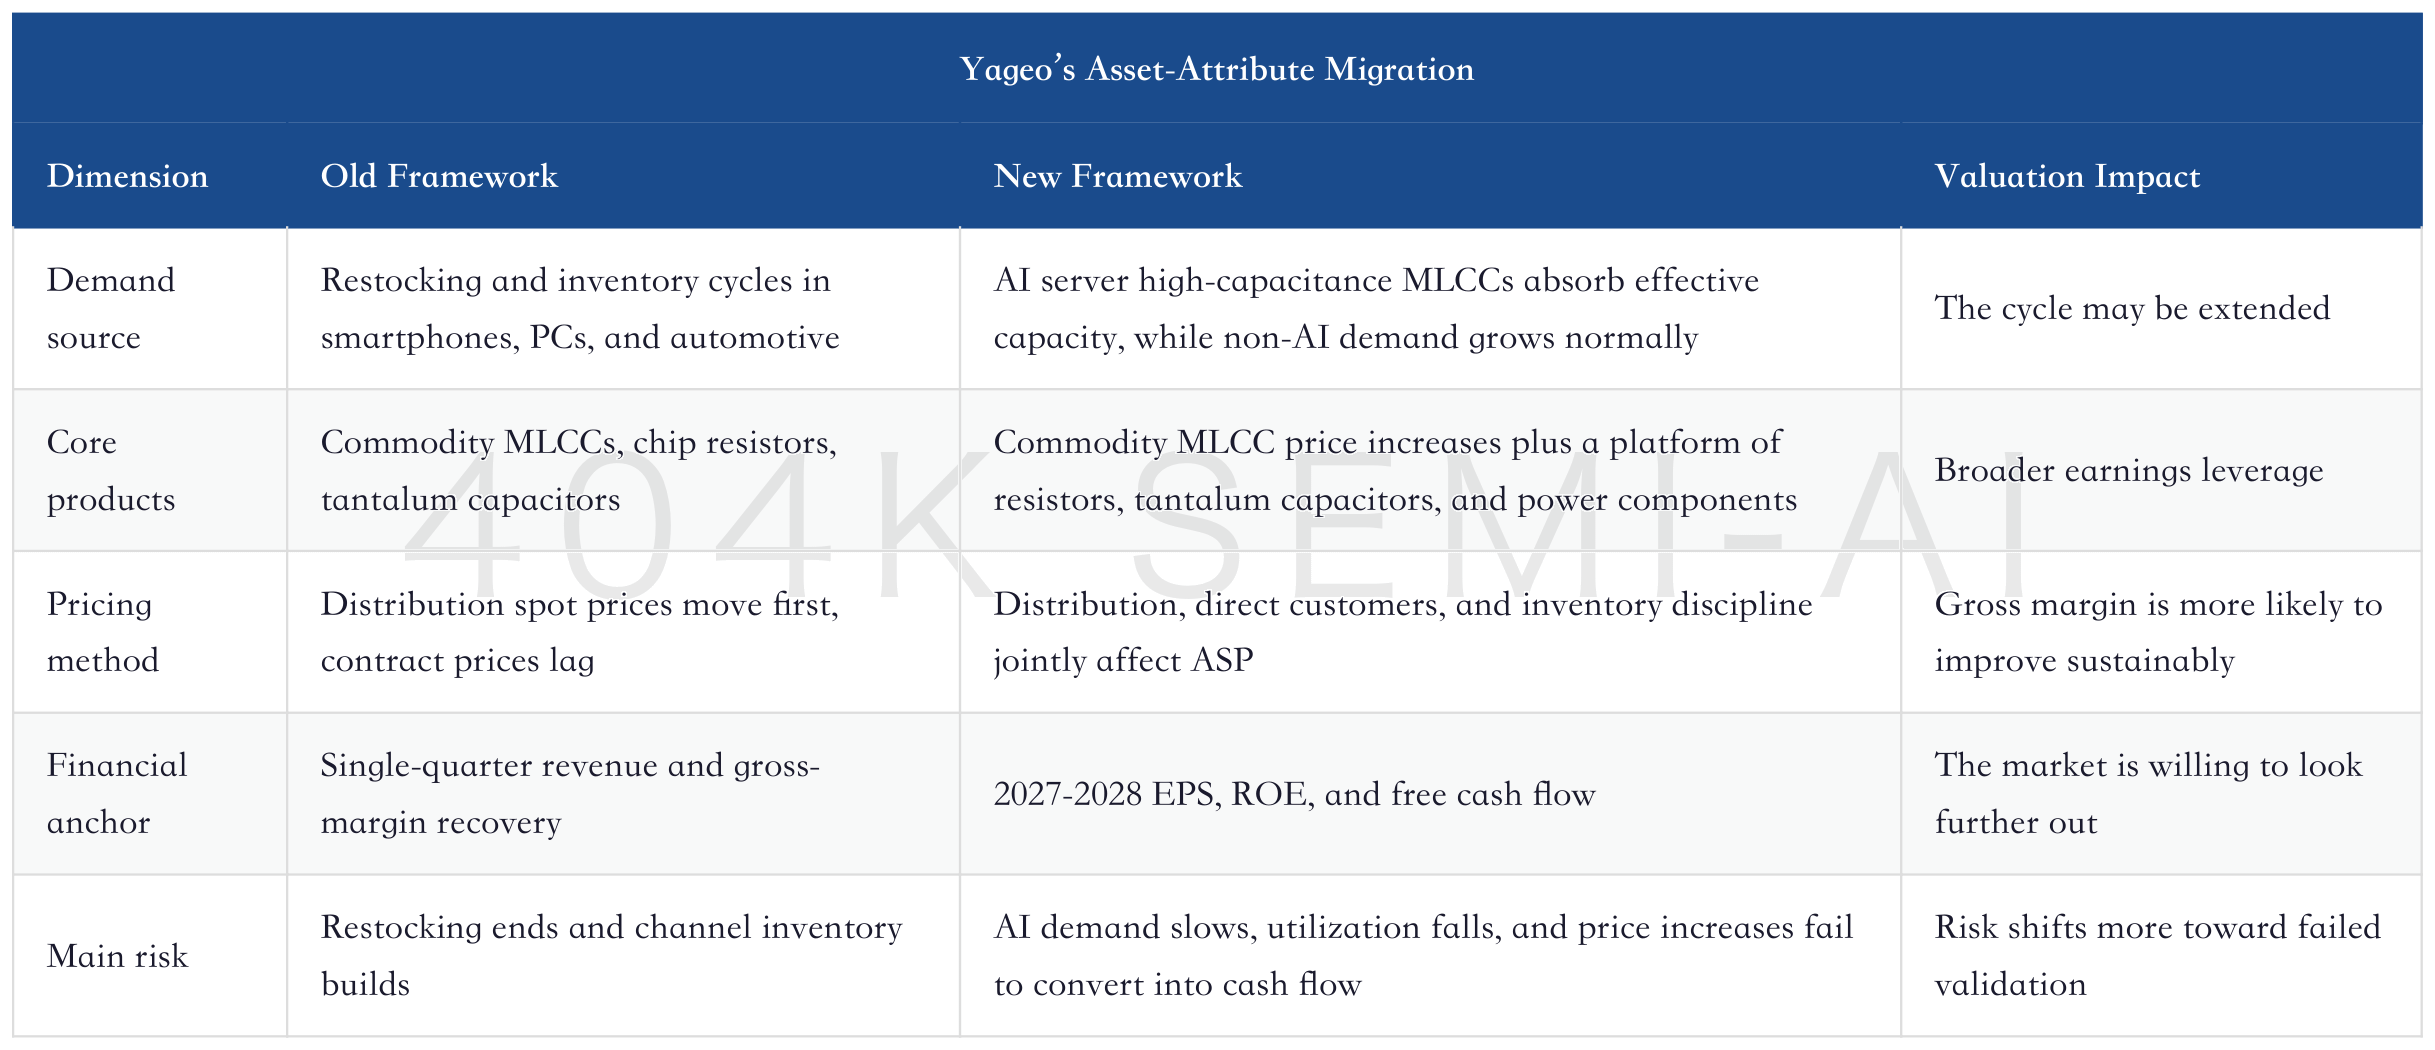
If this migration holds, Yageo cannot be valued solely on ordinary cyclical leverage from trough to peak. The valuation logic for an ordinary cyclical stock is “give it a higher P/E as the cycle improves, then gradually lower the multiple near the cycle peak.” The valuation logic for a high-ROE pricing platform is “as long as pricing discipline and cash flow can persist, the market is willing to assign greater weight to longer-dated earnings.” Goldman Sachs rolling its valuation base to 2028 is essentially a bet on the second logic.
But this migration has not been completed automatically. Yageo’s products still have standard-product characteristics. Customers will still look for substitutes and negotiate when prices rise. Channels may still amplify inventory volatility. To prove that the asset attribute has really changed, one cannot look only at the share price and target price. Three harder indicators must be tracked.
First, whether gross margin can hold. If 2027 gross margin merely spikes quickly and then falls back, this remains a cyclical stock. If gross margin can stay around 46%-51%, it indicates that pricing discipline is beginning to change the earnings center.
Second, whether free cash flow can keep pace with EPS. Goldman Sachs expects free cash flow to rise from NT$24.8bn in 2025 to NT$95.6bn in 2028. If EPS growth only comes from inventory and receivables while cash flow does not expand in tandem, the market will not assign a high P/B for long.
Third, whether multiple product lines can improve together. Commodity MLCC price increases can explain the initial leverage, but to support platform valuation, chip resistors, tantalum capacitors, magnetic components, and sensors must also show better pricing, gross margins, or customer synergies. If only the MLCC line surges, Yageo still looks more like a cyclical stock. If multiple products improve together, the platform attribute becomes more credible.
This is the most interesting point about Yageo now. It has not escaped cyclicality, but it already has evidence of asset-quality improvement. It is not yet the leading high-end AI component company, but it may become the commodity MLCC platform with the most concentrated earnings leverage after AI-driven capacity migration. The importance of the Goldman Sachs report is that it quantifies this migration into ASP, gross margin, ROE, and target price, rather than stopping at the narrative that “AI demand is strong.”
V. Goldman Sachs Model: ASP, Gross Margin, and EPS All Revised Up
The strongest part of Goldman Sachs’ model is that it links pricing, gross margin, and EPS into a full income statement. The problem with many price-increase reports is that they have only a pricing story and no financial landing point. This report directly translates commodity MLCC price revisions into revenue, gross margin, operating margin, ROE, and target price.
Start with revenue. Goldman Sachs has clearly shifted the future revenue curve upward. This is not the growth rate of an ordinary passive-component company in a mature market. The core drivers are a higher MLCC revenue mix and commodity MLCC price increases, with the specific figures reconciled in the income statement.
Next, margins. Goldman Sachs is not only raising revenue; it is also lifting operating margin, EBITDA margin, and the gross-margin center together. This change is the valuation core of the entire report.
Finally, EPS. Goldman Sachs’ EPS revisions are more aggressive than its revenue revisions, which shows that the price-increase assumption is not only expanding scale but also expanding profit. The fact that margin revisions are faster than revenue revisions is why Goldman Sachs is willing to raise its target price sharply.
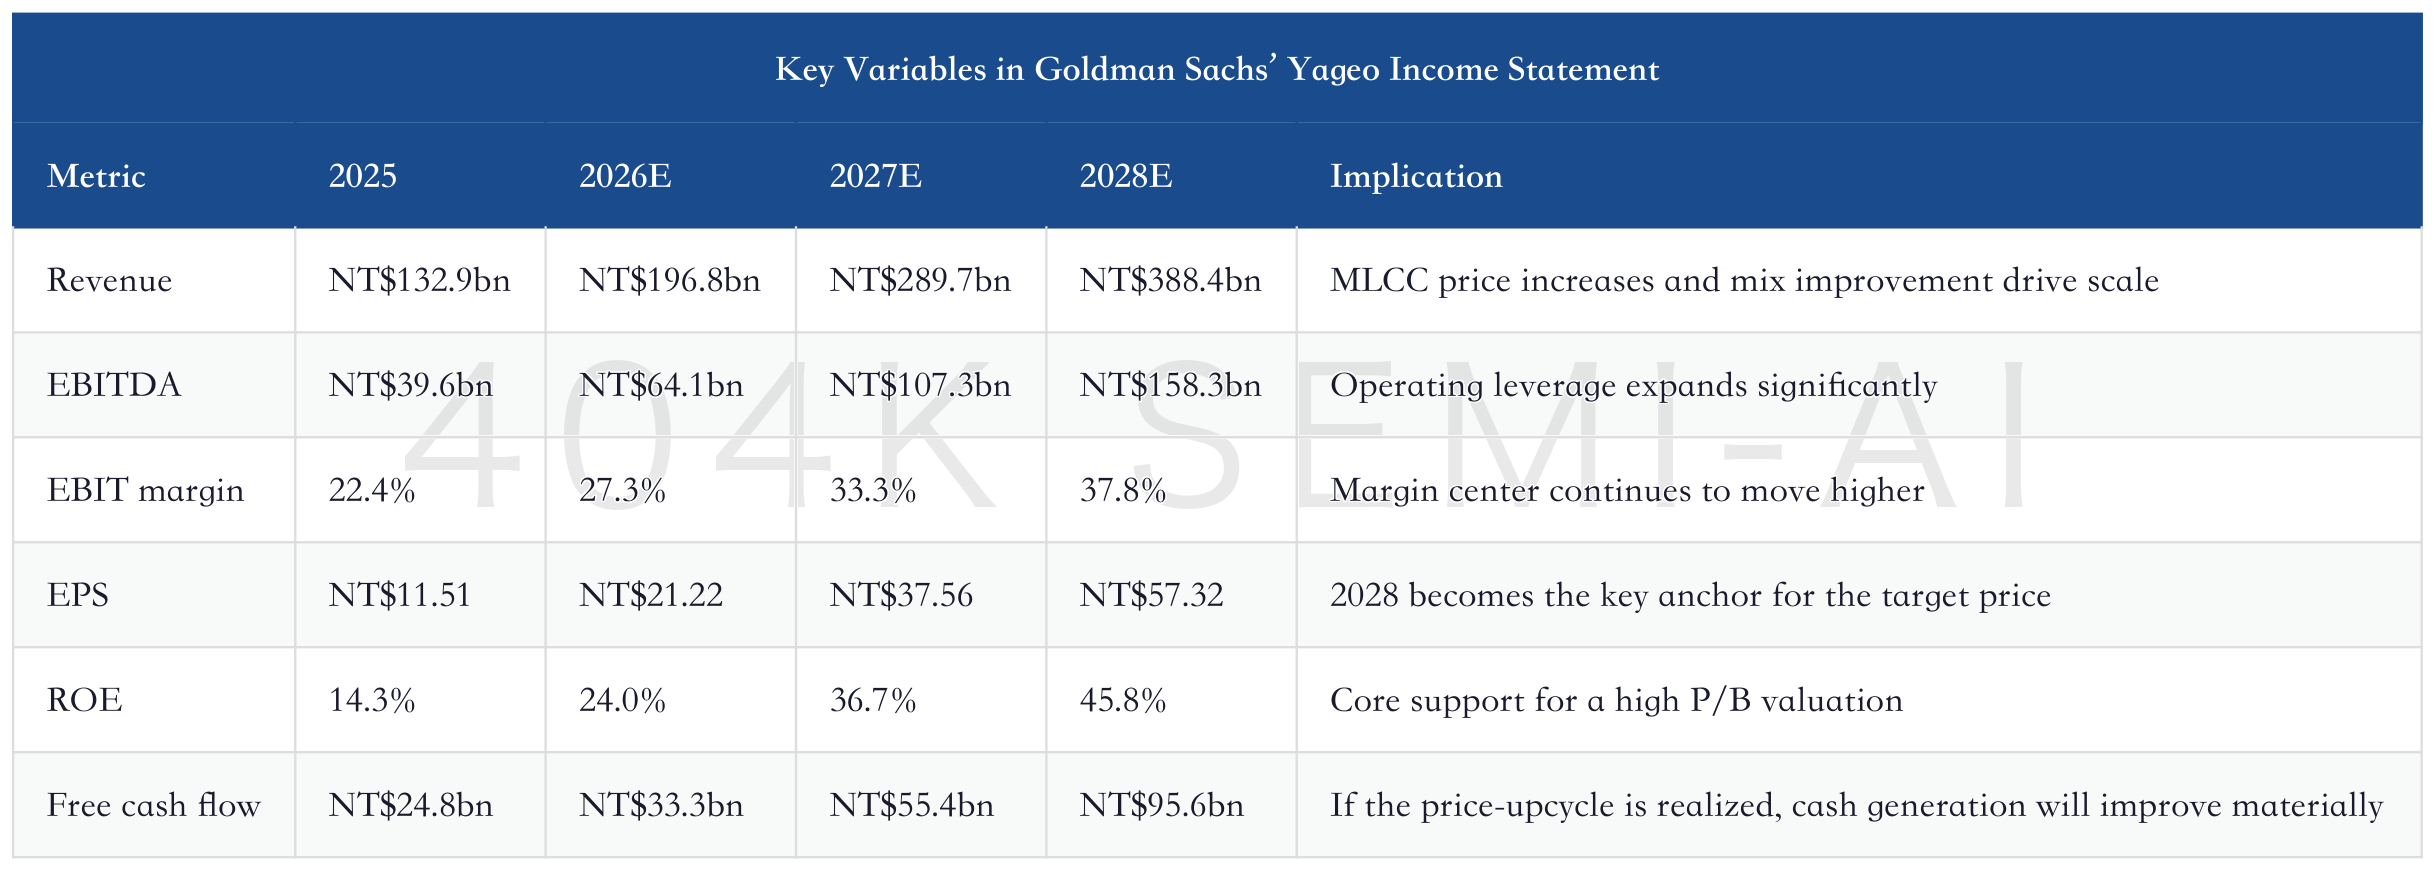
Among these figures, ROE is the most important. If Yageo is only a cyclical stock, it is difficult for P/B to remain high for long. If ROE rises from 14.3% to 45.8%, the market will be willing to assign a higher P/B. Goldman Sachs uses a 26x PB/ROE multiple for its target price, implying about 10.8x 2028E P/B, far above Yageo’s historical average P/B. Goldman Sachs believes this can be explained by the sharp improvement in ROE.
This requires discipline. A 45.8% ROE is not an easy number. It requires price increases, capacity utilization, cost control, inventory discipline, and acquisition integration all to work. If any link loosens, valuation will adjust before EPS does. In other words, Yageo’s core tension now is not “whether EPS will grow,” but “whether the market is willing to believe this high ROE can be sustained through 2028 or even longer.”
The gap between Goldman Sachs and consensus also shows where the disagreement lies. The market is not unaware of MLCC price increases; it simply has not pushed price-increase sustainability and commodity MLCC leverage as far as Goldman Sachs has. The real disagreement lies across four dimensions: pricing durability, revenue scale, gross margin, and ROE.
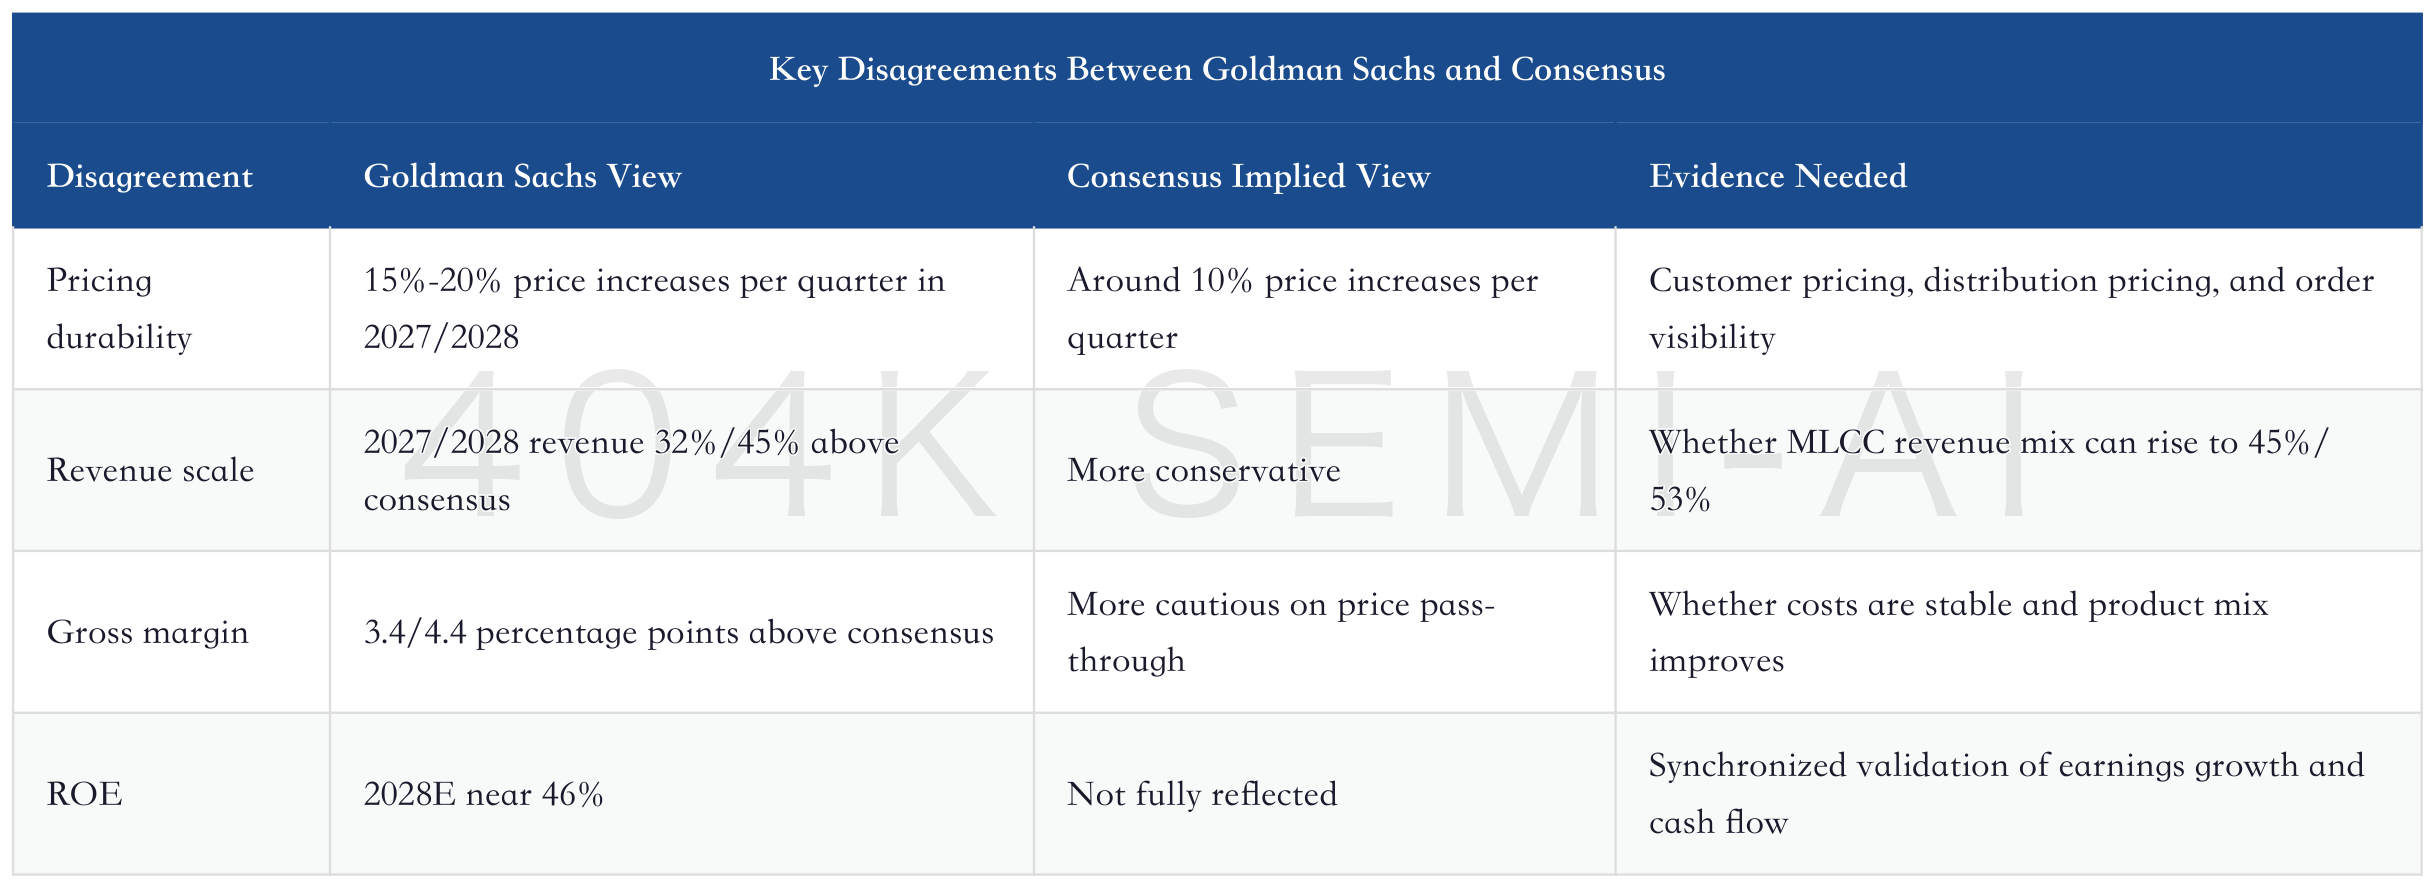
This is also what makes this update most worth writing about. Goldman Sachs is not simply repeating Morgan Stanley’s point that “Yageo’s price increases are faster.” It is explicitly betting that consensus will continue to chase up 2027-2028 estimates. As long as consensus has not caught up, there is room for the valuation trade. Once consensus catches up but the financials fail to deliver, the share price will become very fragile.
VI. Raising the Target Price from NT$346 to NT$1,490: Is It Expensive?
The biggest debate around Yageo is no longer “is it good?” but “is it expensive?” The stock has significantly outperformed the Taiwan Weighted Index over the past several windows. For a company that has already risen sharply, a NT$1,490 target price must be justified with a clear valuation framework.
Start with static multiples. Under Goldman Sachs’ model, Yageo is not cheap on current-year valuation; the forward valuation only starts to become explainable later. The issue is that the market will not wait until 2028 to price it. If investors believe EPS will keep being revised upward and ROE will move into a high range, today’s high P/E can be diluted by future earnings. Otherwise, the valuation is already crowded.
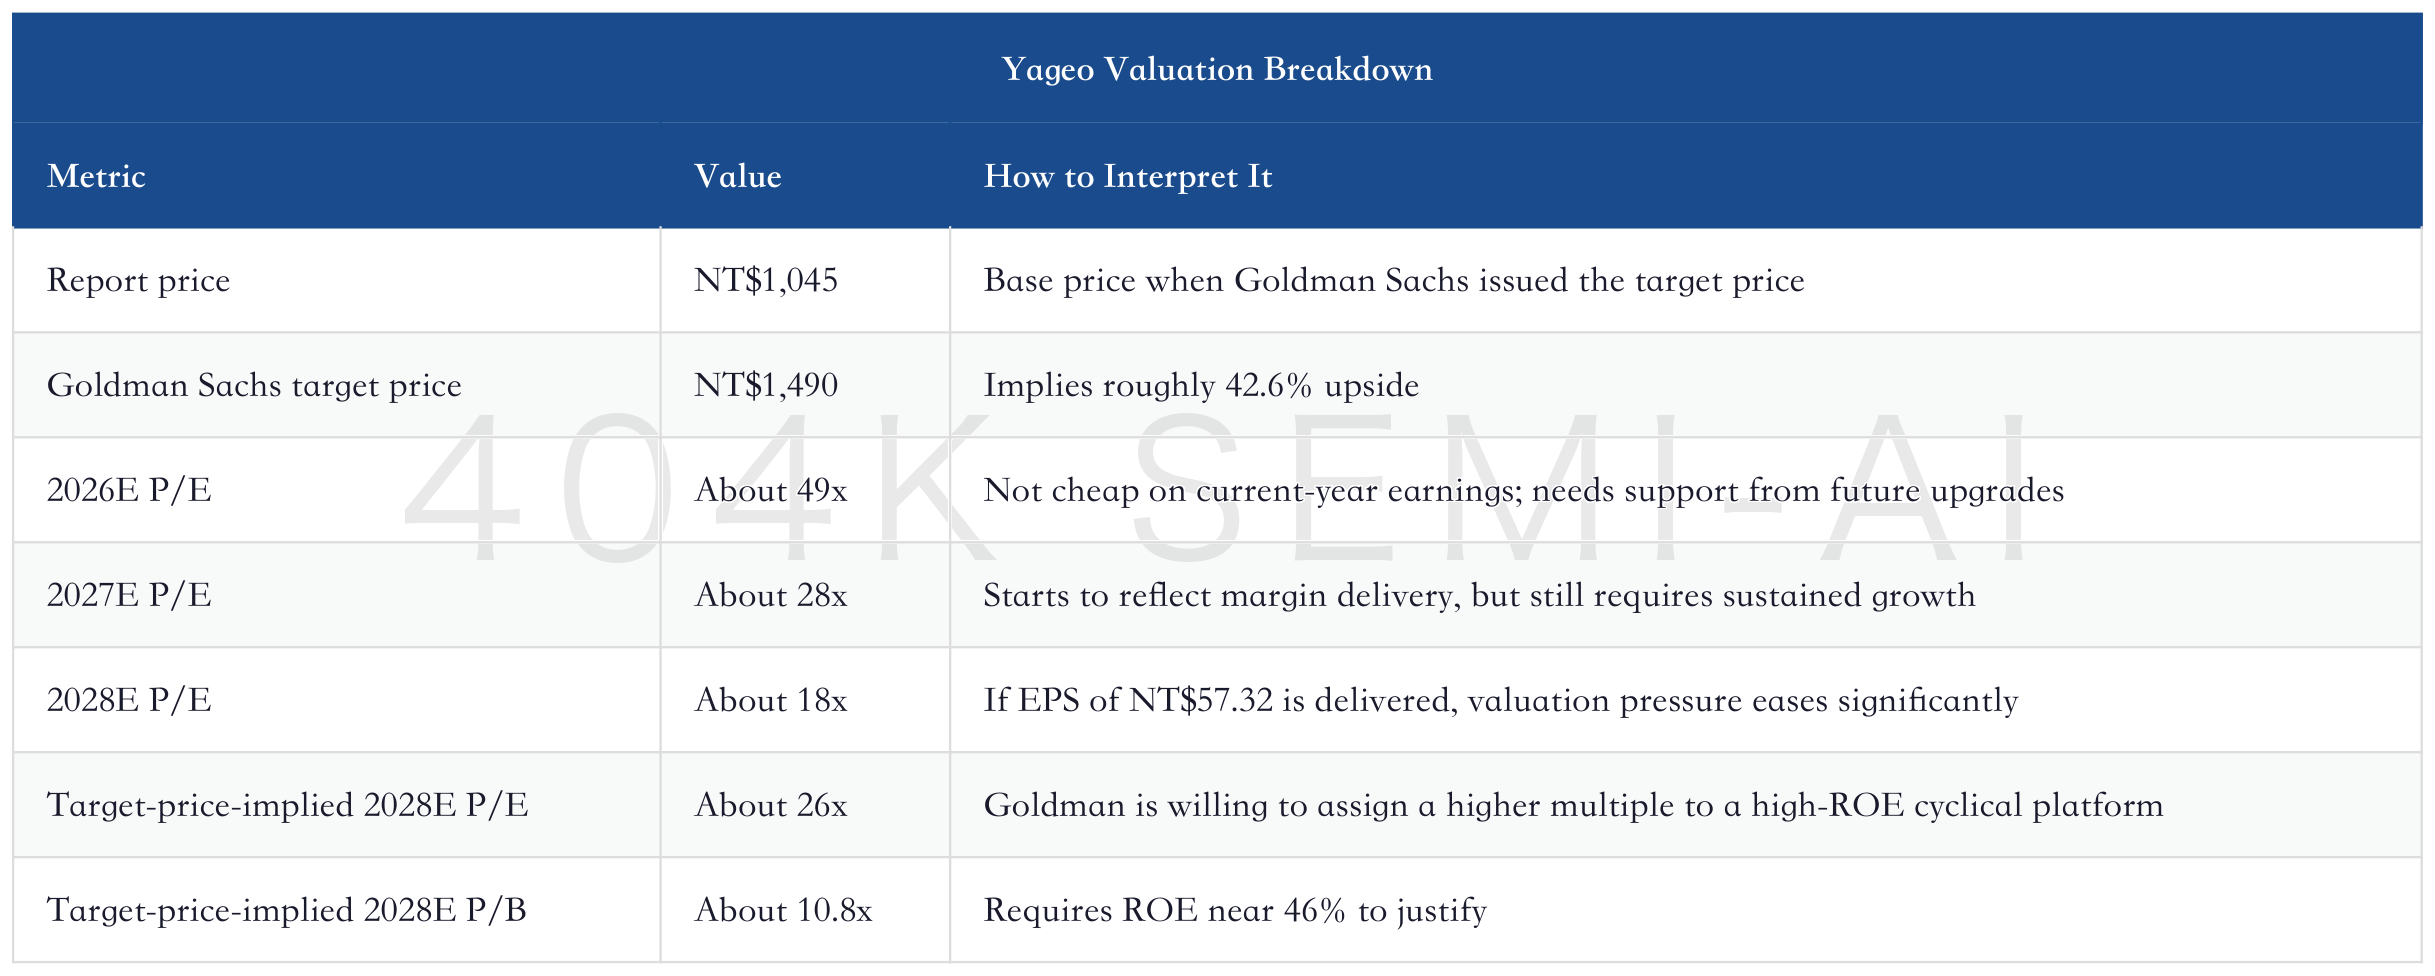
The key to this valuation is cycle duration. If commodity MLCC price hikes last only two quarters, the NT$1,490 target price will be hard to defend. If the price-upcycle can last 24-30 months, Yageo is not a trade on 2026 P/E, but on the 2028 income statement and high ROE. Goldman Sachs explicitly rolls the valuation base from 2H26-1H27 to 2028, on the grounds that AI server demand visibility is at least 2.5-3 years.
Why is the market willing to look out to 2028? Because AI server platform upgrades are not a one-off inventory restocking event. From GB300 to VR200, MLCC usage and content value per rack continue to rise. Demand for AI-grade MLCC is increasing, while Japanese and Korean suppliers continue allocating resources to high-end applications. Even if non-AI demand merely grows normally, it will face a tighter commodity MLCC market after supply migration. If this chain holds, 2028 is not a distant fantasy, but a reasonable window for the earnings peak of this cycle.
That said, a NT$1,490 target price is not low-risk. The 26x P/B/ROE multiple used by Goldman Sachs is equivalent to the peak range over the past 10 years and is close to the current valuations of Japanese and Korean MLCC suppliers. In other words, the market has begun pricing Yageo as an “industry leader re-rating” rather than an ordinary cyclical stock. If EPS upgrades slow, valuation compression will come first.
Yageo is better viewed through three scenarios.
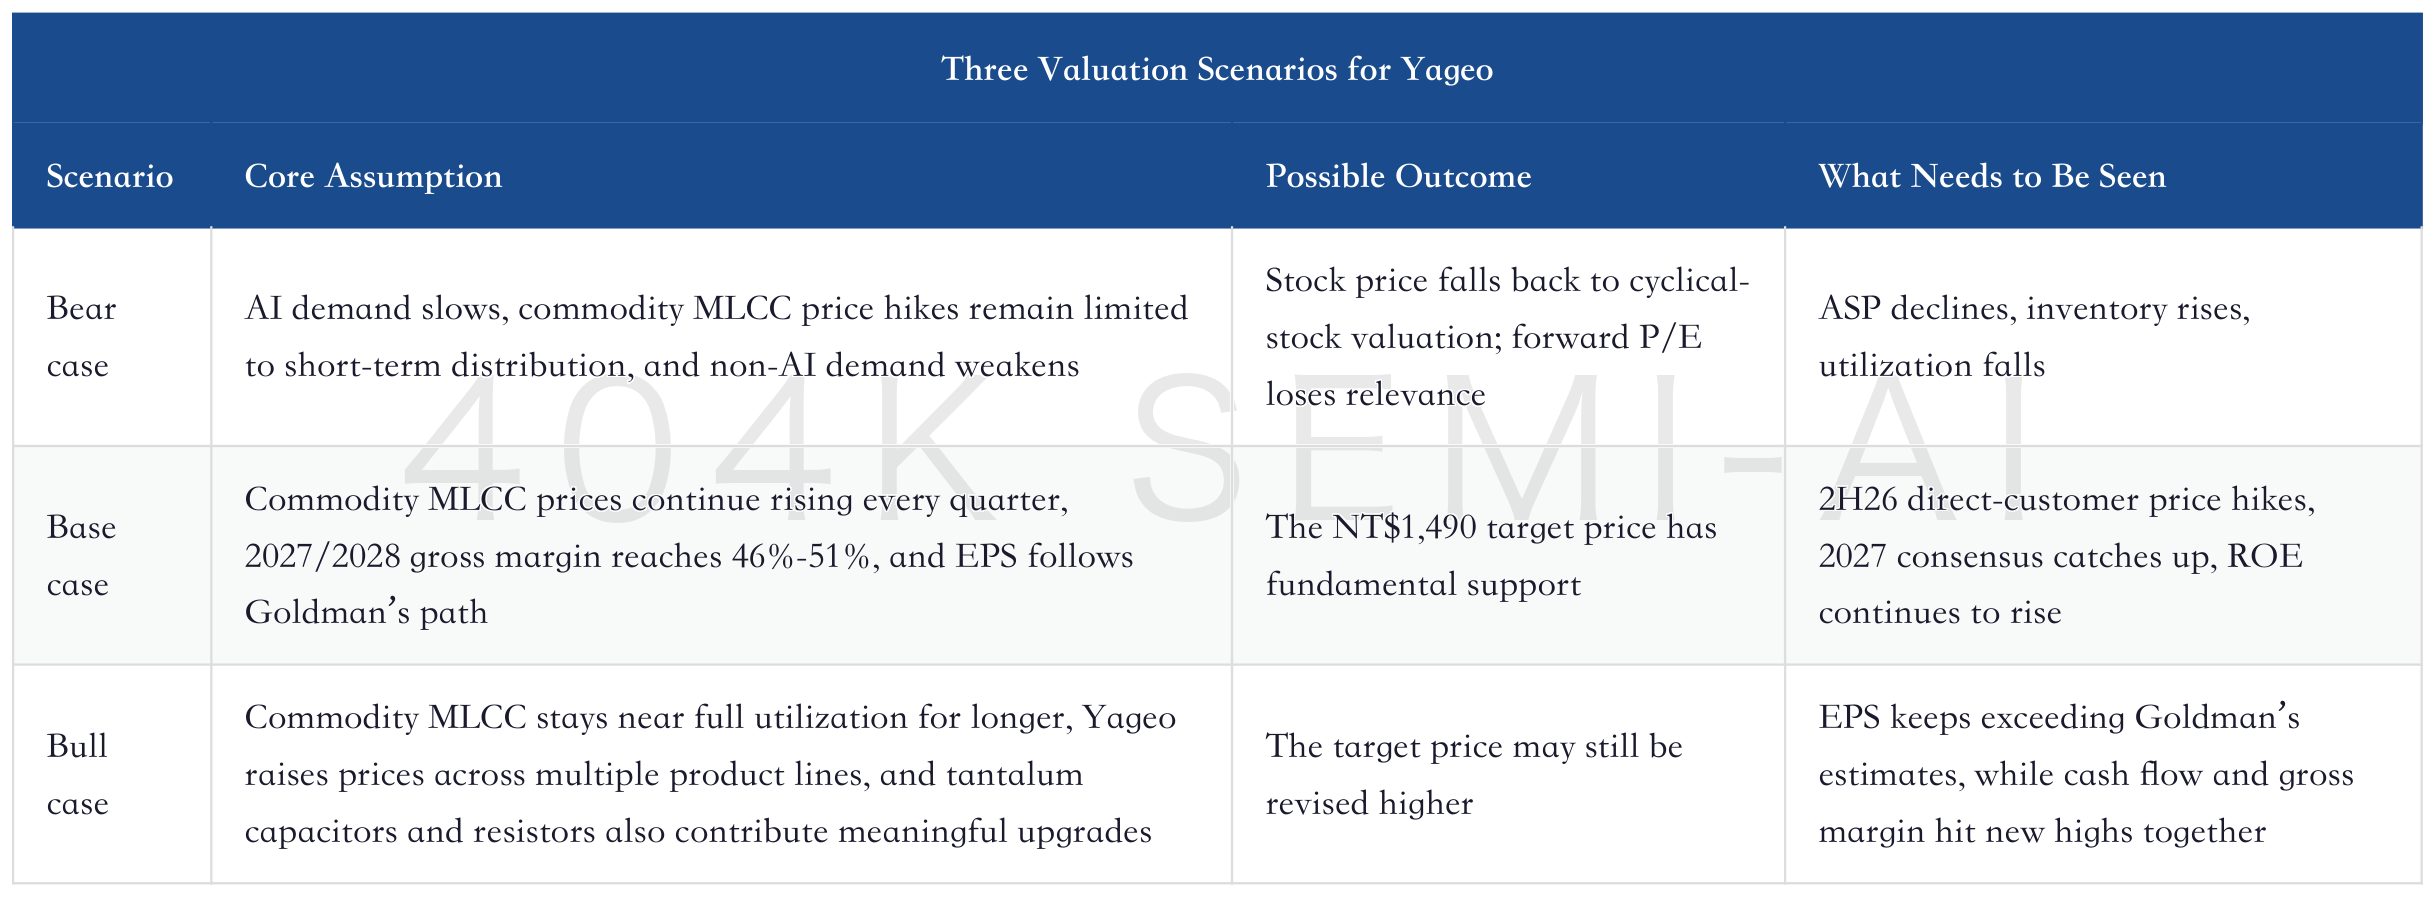
So the answer to “is it expensive?” is not simple. On 2026 numbers, yes. On Goldman’s 2028 EPS, not unreasonable. On the high P/B implied by the target price, the risk is not low. A more accurate statement is: Yageo has already moved out of the cheap zone. What investors are buying now is continued consensus upgrades and the persistence of commodity MLCC price hikes.
VII. Difference Versus Morgan Stanley’s Earlier Model: From High-Capacitance Crowding-Out to Commodity Full Utilization
Morgan Stanley’s Yageo report in mid-to-late June had already provided a key set of clues. It emphasized the crowding-out effect from high-capacitance MLCC demand, and revised up direct-customer pricing, forward EPS, and monthly earnings. Morgan Stanley focused more on “pricing power arriving faster and stronger than expected,” especially as monthly EPS had already proven that price hikes and utilization were entering reported earnings.
Yageo Deep-Dive Update: AI Demand Starts Tightening MLCC Supply; How Mid- and Low-Capacitance Price Hikes Rewrite the 2027-2028 Income Statement
Goldman Sachs’ incremental contribution this time is to quantify Yageo’s price-hike logic further, from “mid- and low-capacitance crowding-out” to “commodity MLCC near full utilization.” Goldman is not merely saying that high-end capacity is tight. It places non-AI MLCC utilization, the previous-cycle peak, and commodity MLCC ASP assumptions together to explain why Yageo’s pricing leverage can exceed traditional expectations.
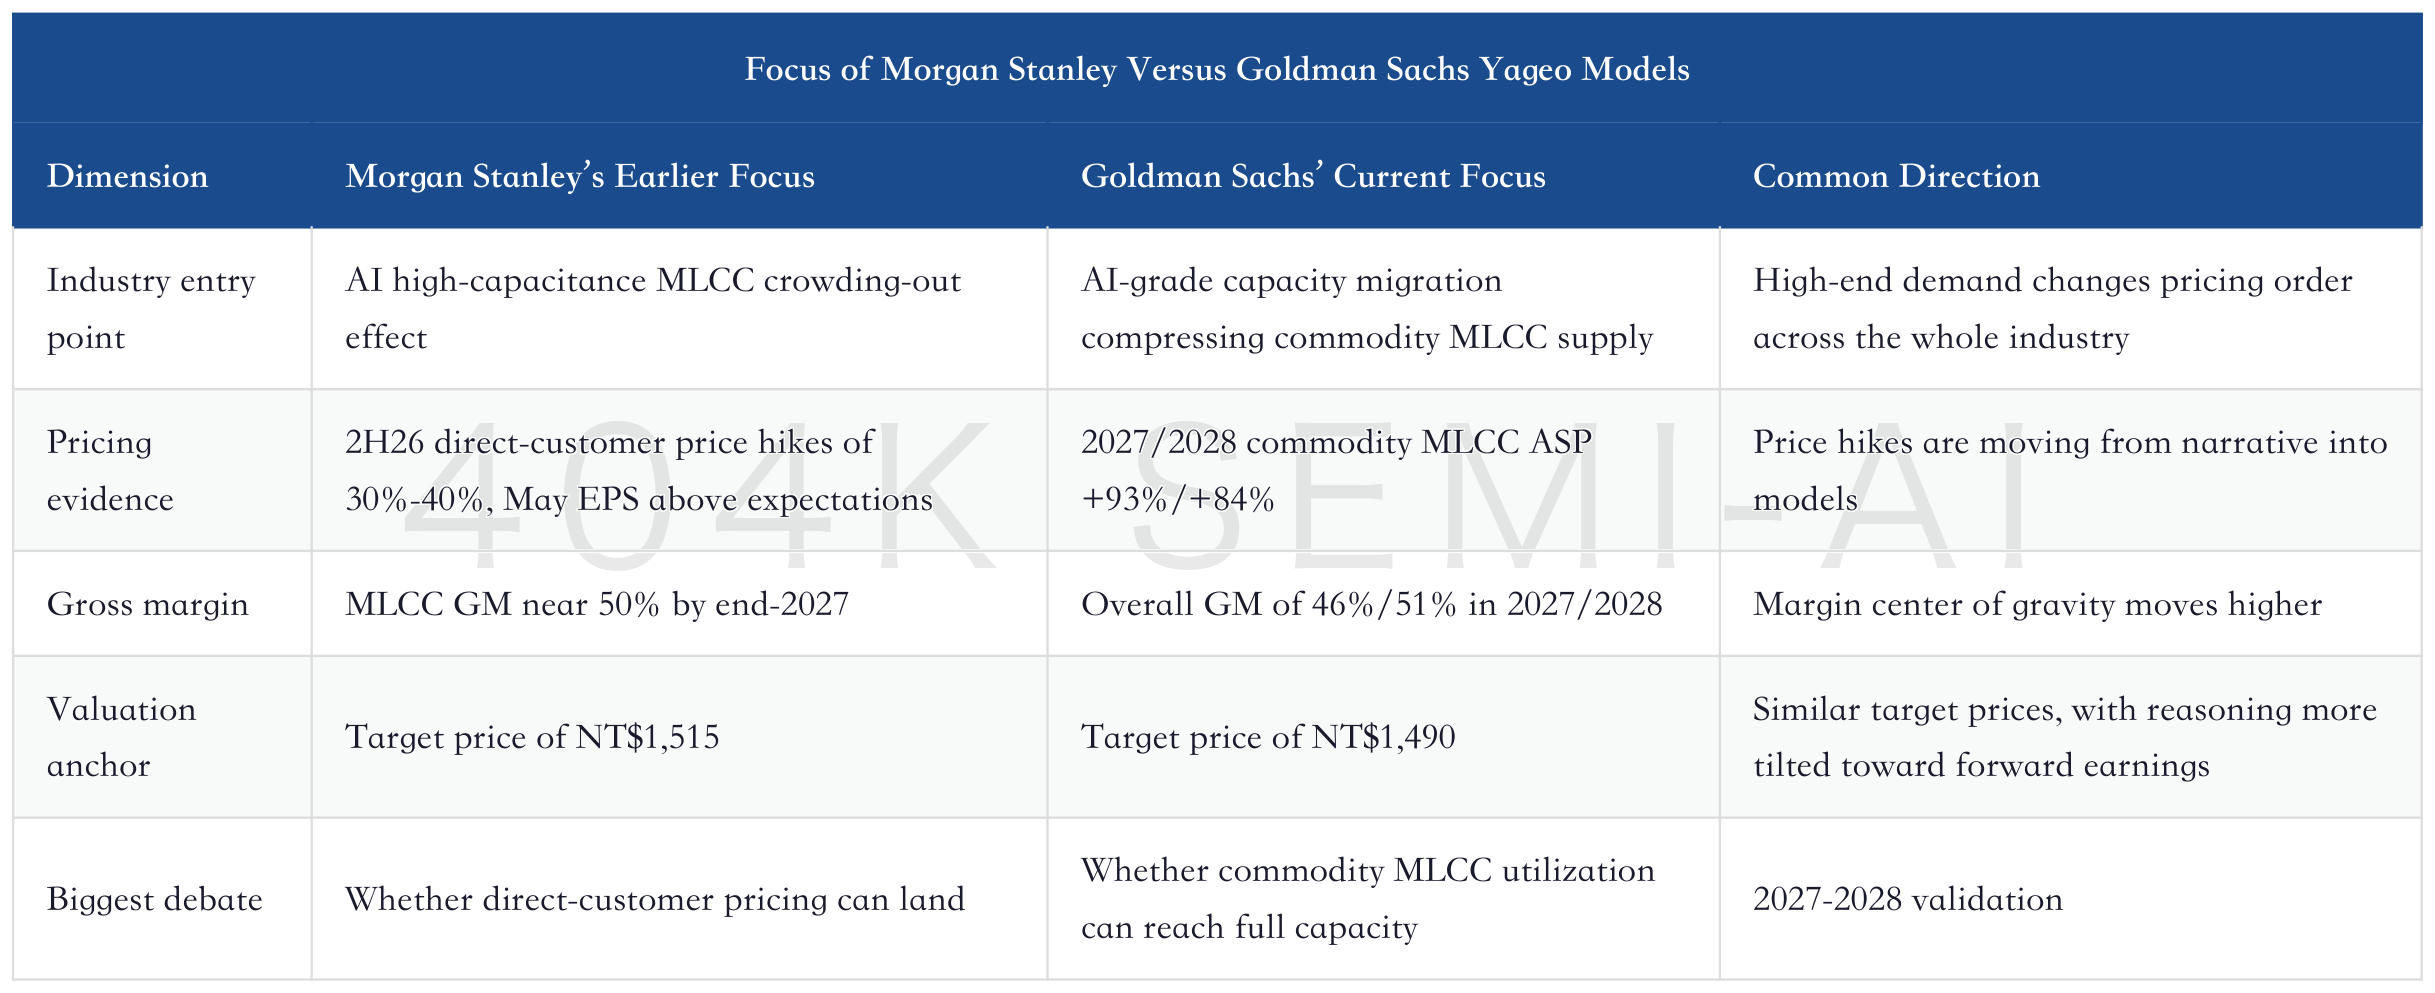
The two models validate each other, while also highlighting risks. Morgan Stanley provides earlier evidence from pricing and monthly earnings; Goldman Sachs provides a more complete supply-demand and income-statement framework. If 2H26 direct-customer price hikes land but commodity MLCC utilization does not continue rising in 2027, Yageo may only see a short-term earnings recovery. If, after 2H26 price hikes land, non-AI MLCC remains near full utilization in 2027, Yageo will have the conditions to be re-rated on 2028 EPS.
This is also why tracking Yageo cannot rely only on AI server shipments. Investors need to watch Japanese and Korean suppliers’ high-end capacity allocation, Yageo’s commodity MLCC prices, non-AI customer restocking, distribution inventory value, monthly EPS, and market consensus. No single data point is enough to prove Goldman’s target price. But if these signals strengthen together, the target price will no longer look abrupt.
VIII. Peer Comparison: Yageo Has Strong Leverage, but the Technical Anchor Is Not There
In this global MLCC cycle, not all companies are rising together. Murata Manufacturing is the technical anchor for high-capacitance AI MLCC. Samsung Electro-Mechanics offers combined leverage across MLCC, FC-BGA, and silicon capacitors. Taiyo Yuden is a higher-purity high-capacitance MLCC name, but with larger yield and earnings volatility. TDK is a diversified electronic components and power-chain platform. Yageo is the price-hike leverage play in commodity MLCC and passive components.
Japan Electronic Components Deep Dive: AI Servers Push MLCC from Cyclical Product to Compute Infrastructure
Yageo’s comparative advantage comes from “leverage” and “spillover,” not the strongest technical high ground. It is stronger in commodity MLCC capacity share, distribution channels, chip resistors, and tantalum capacitors. But in the most advanced high-capacitance AI server part numbers, it still cannot replace Murata and Samsung Electro-Mechanics. This distinction is important because it determines how Yageo’s valuation should be validated.
For Murata, the most important variables to track are high-capacitance MLCC capacity, AI customer qualifications, ASP mix, and component-business margins. For Samsung Electro-Mechanics, the key is whether MLCC, FC-BGA, and silicon capacitor orders are all delivered. For Yageo, the key is whether commodity MLCC prices can rise continuously, whether non-AI utilization is near full capacity, and whether chip resistors and tantalum capacitors follow with price increases. Different companies do not share the same evidence chain.
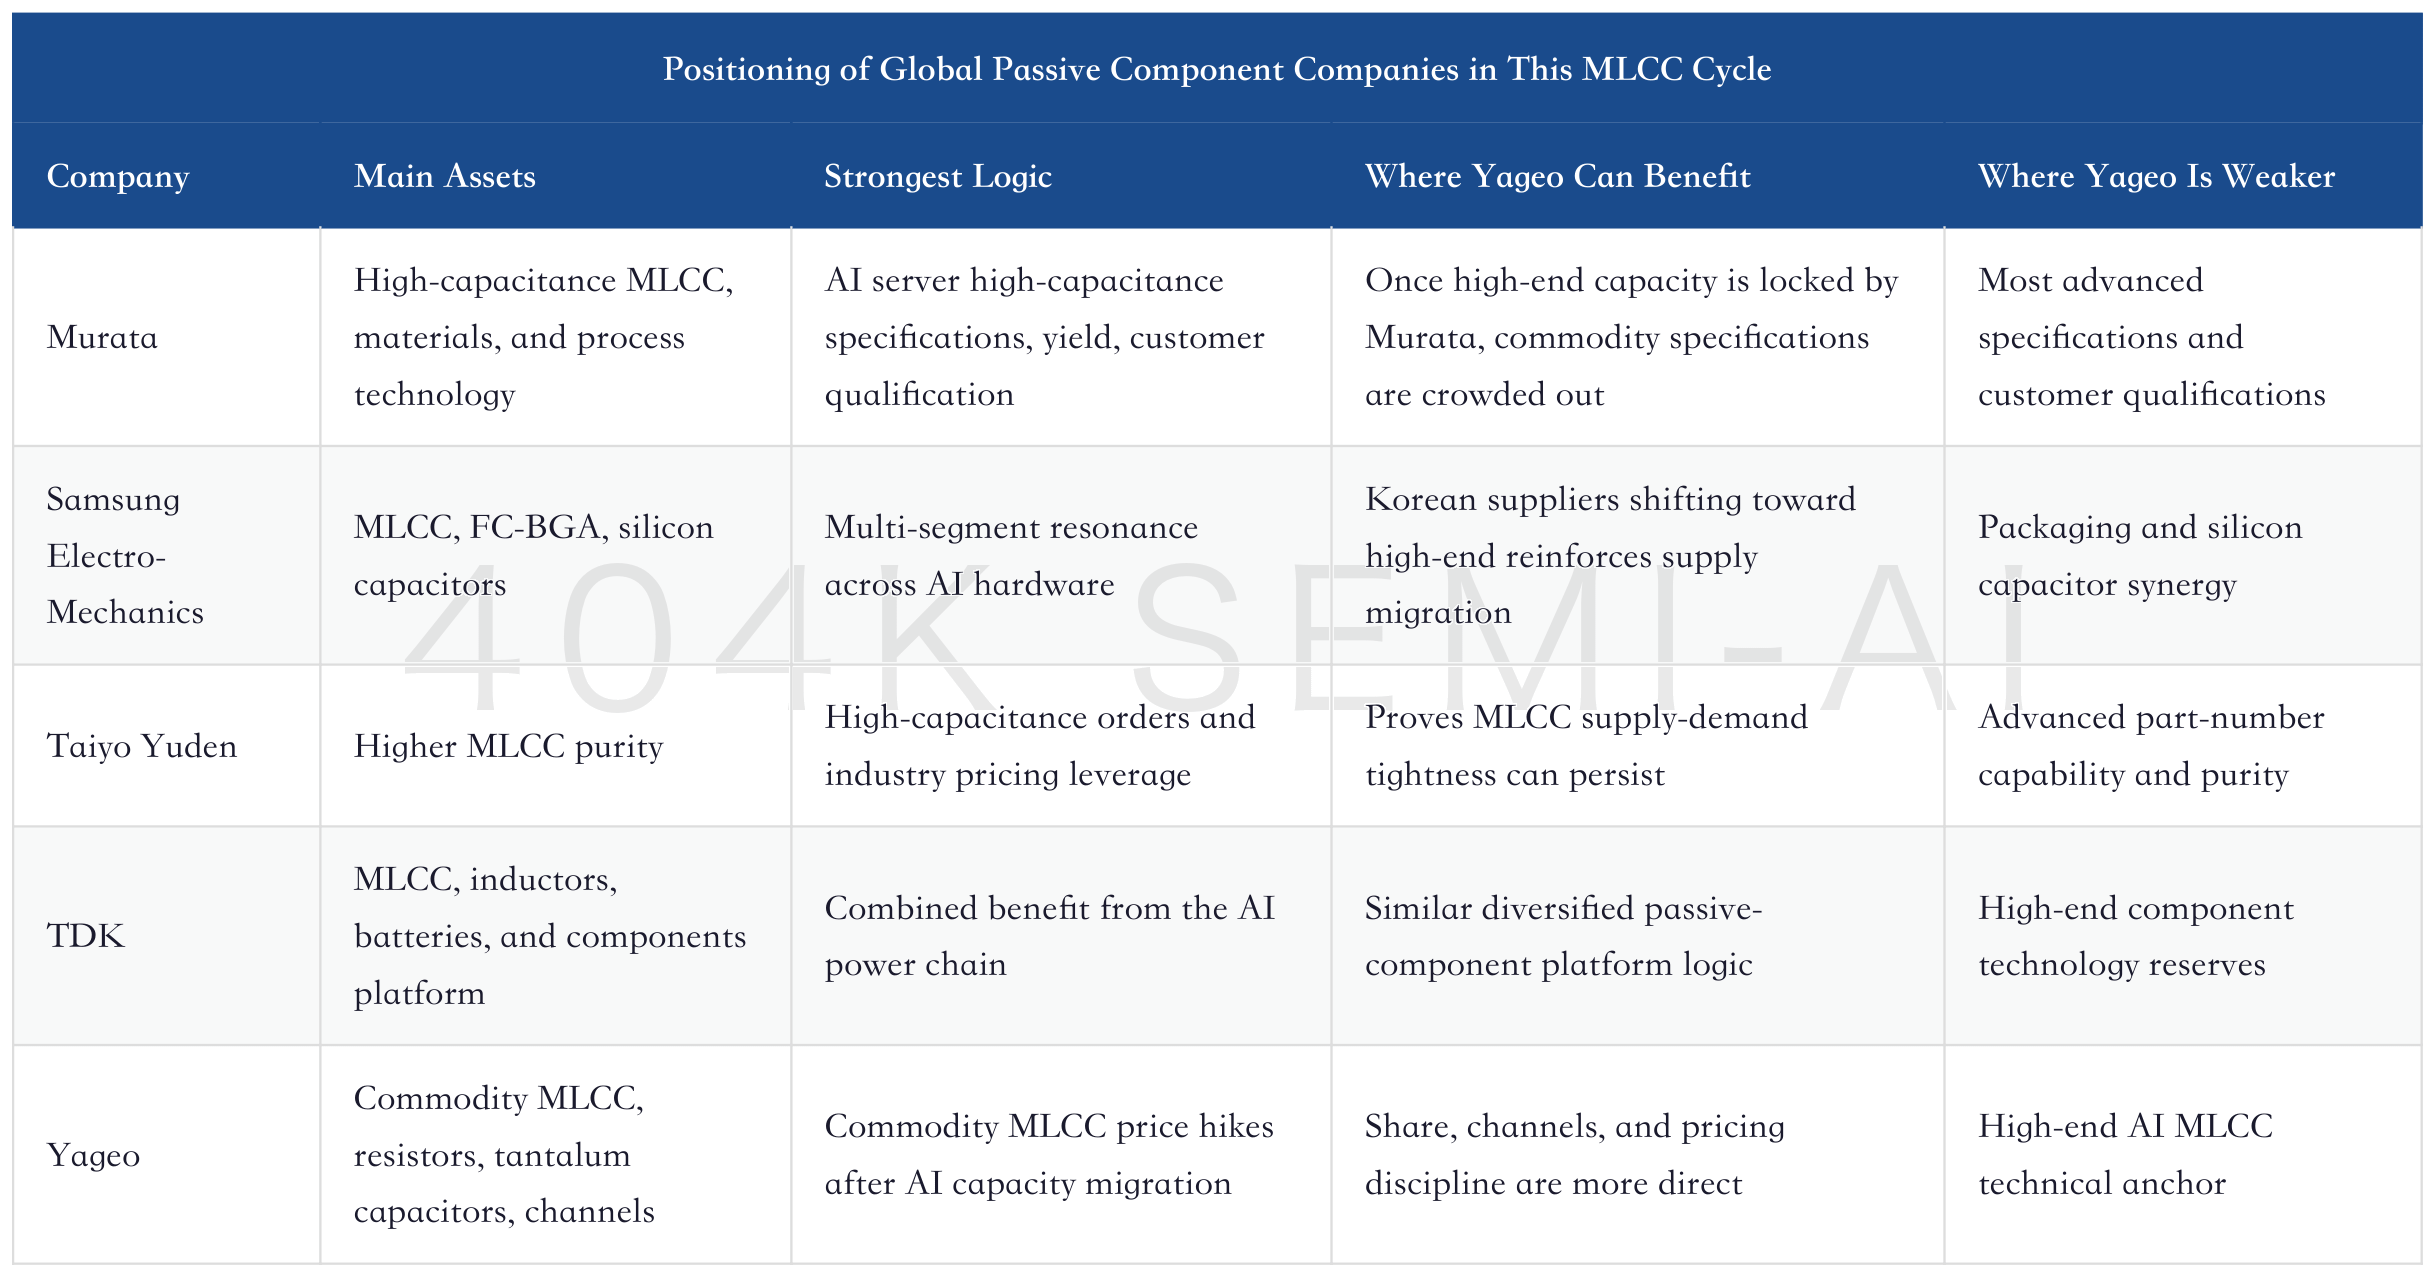
This ranking gives Yageo a more accurate position: not the first-layer technical anchor, but the second-layer king of pricing leverage. It does not need to prove leadership in every high-end part number. It only needs to prove that after high-end capacity is locked, commodity MLCC prices can rise for long enough, across enough categories, and flow through to gross margin.
This position also shapes its trading characteristics. Murata is more like a long-term quality asset, with potentially steadier gains. Samsung Electro-Mechanics and Yageo are more like earnings-upgrade assets, with higher volatility. Taiyo Yuden is more like a disagreement asset: strong leverage when price hikes are delivered, but also large drawdowns when yield and margins are unstable. Yageo’s advantage is concentrated earnings leverage; its weakness is that valuation is highly sensitive to pricing and inventory.
IX. Supply-Chain Mapping: Upstream Powders and Consumables Will Become Validation Windows
Although this Yageo update is a Taiwan company report, it also has clear read-throughs for A-share and broader Asian materials chains. If commodity MLCC price increases can persist, the impact will not stop at OEMs and passive-component vendors. Ceramic powders, electronic pastes, carrier tape, release film, nickel powder, and inductor materials should all see changes in utilization and price negotiations.
Sinocera is the most direct observation window on the powder side. High-capacitance MLCCs require more demanding powder particle size, dispersion, consistency, and dielectric performance, while AI-grade high-end part numbers will raise the materials barrier. Prior Sinocera reports had already framed the 5,000 tons of AI-grade MLCC powder and new ceramic-substrate orders as core validation points. If high-capacitance and commodity MLCCs strengthen at the same time, Sinocera’s thesis is not merely price increases in ordinary ceramic powders, but customer validation for high-end powders and ASP improvement.
Chaozhou Three-Circle is more like a high-end electronic ceramics platform, with MLCCs as well as options in ceramic substrates, SOFC, and other AI data-center power-supply-related areas. If AI servers continue to push power density higher, Three-Circle’s value is not just “domestic MLCC,” but a multi-line re-rating of high-end ceramic components and power ceramic materials.
Jiemei Technology and Boqian New Materials are better suited as signals of cyclical diffusion. If materials and consumables such as carrier tape, release film, and nickel powder begin to see price increases, full utilization, or accelerated ramp-up of new capacity, it would indicate that MLCC vendors are not merely announcing price hikes, but are actually raising operating rates, locking in materials, and expanding capacity. Conversely, if there is no utilization improvement at the upstream materials end, price increases at the OEM end may be more of a short-term distribution-channel behavior.
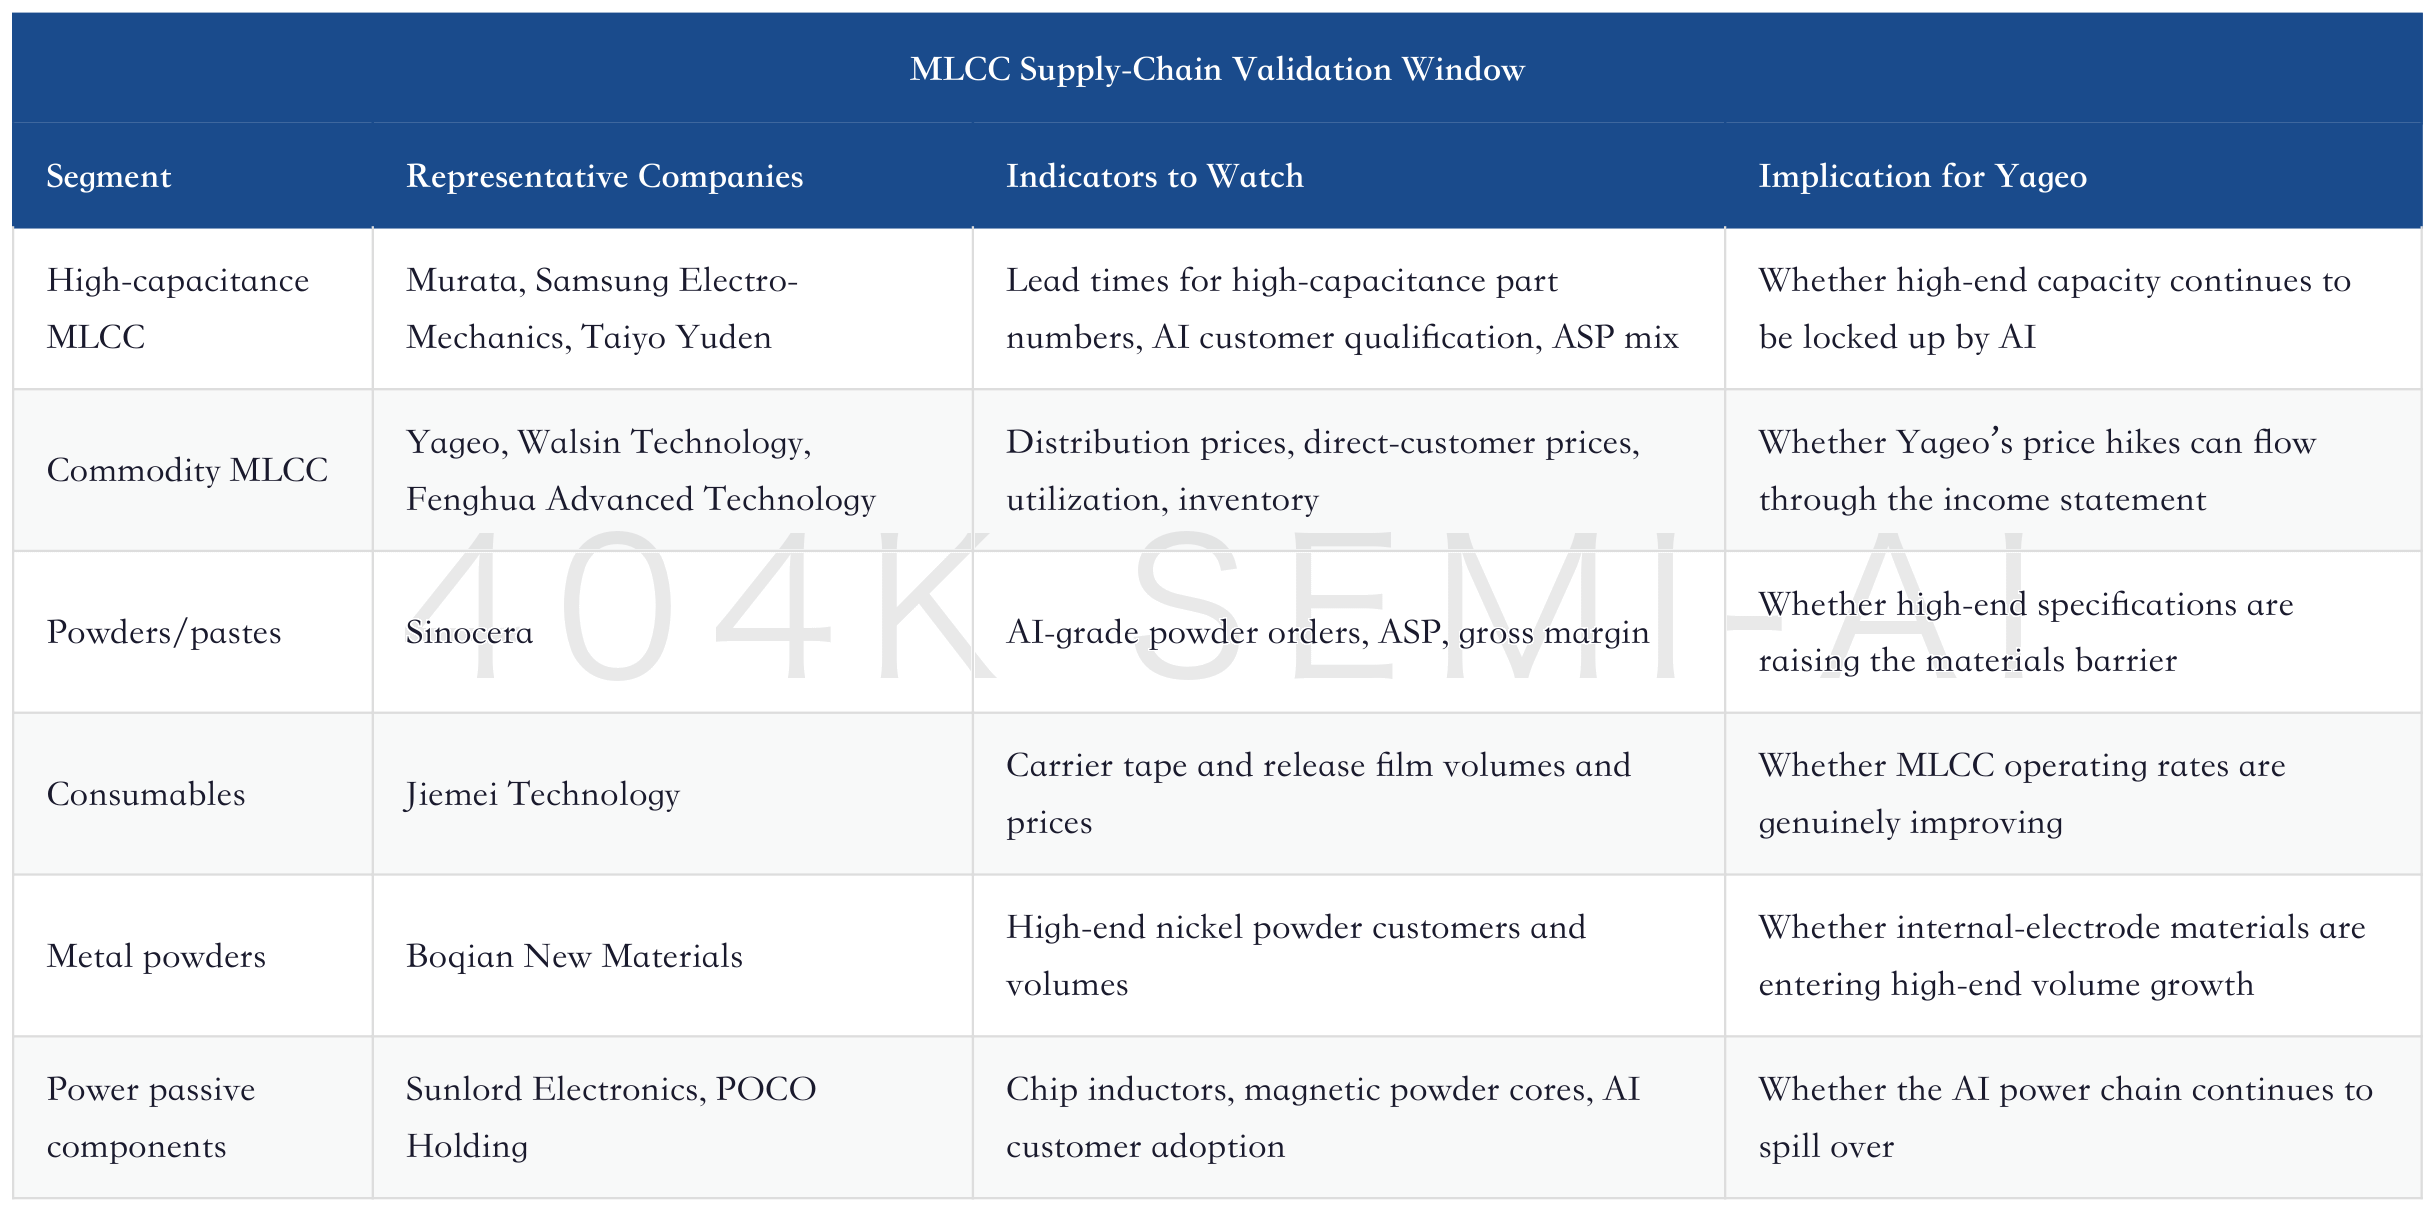
These mappings cannot replace research on Yageo itself. Yageo’s target price must be validated by its own ASP, EPS, and ROE; the A-share materials chain mainly provides cross-checks. If Yageo’s price increases are strong and powders, consumables, and materials also show utilization improvement, the cycle is healthier. If only Yageo’s share price is strong while supply-chain data fail to keep up, risk should be marked higher.
X. Disconfirmation Checklist: What Would Push Yageo Back to Cyclical-Stock Valuation
The biggest risk for Yageo now is not the absence of a story, but that the story is too smooth. The stock has already priced in part of the 2027-2028 earnings upgrades. Goldman Sachs’ target price implies further upside, but that upside requires continuous validation. If any key assumption loosens, the market could pull the valuation back from a high-ROE platform to an ordinary cyclical stock.
The first risk is a slowdown in AI server demand. If shipments of GB300, VR200, or subsequent platforms fall short of expectations, the migration of high-end MLCC capacity will slow. Japanese and Korean suppliers would no longer be as urgent in allocating capacity to AI, and commodity MLCC supply pressure would also ease. Yageo is not the highest-end AI anchor; the impact of slower AI demand would transmit to it in reverse through supply spillover.
The second risk is that OEM inventories fail to build. Goldman Sachs lists weaker-than-expected OEM inventory as one downside risk. Low inventory can support restocking, but if customers reduce procurement because of higher prices, or if weak end-demand limits restocking appetite, commodity MLCC price increases will be hard to sustain into 2027-2028.
The third risk is weaker IT end-demand. Goldman Sachs’ assumption for non-AI MLCC demand is not explosive growth, but roughly a 9% CAGR in 2025-2028. This growth requires smartphones, autos, industrial, and servers to remain broadly stable. If memory price increases squeeze OEM BOMs, PC and smartphone demand rolls over, or automotive electronics growth slows, non-AI commodity MLCC utilization will struggle to return to 100%.
The fourth risk is slower-than-expected M&A; integration. Yageo’s multi-product platform comes from assets including Kemet, Chilisin, Telemecanique, and Shibaura. Synergies do not occur automatically. If different product lines cannot share customers, pricing, channels, and supply chains, the platform valuation will be discounted. Goldman Sachs also lists slower-than-expected integration as a downside risk.
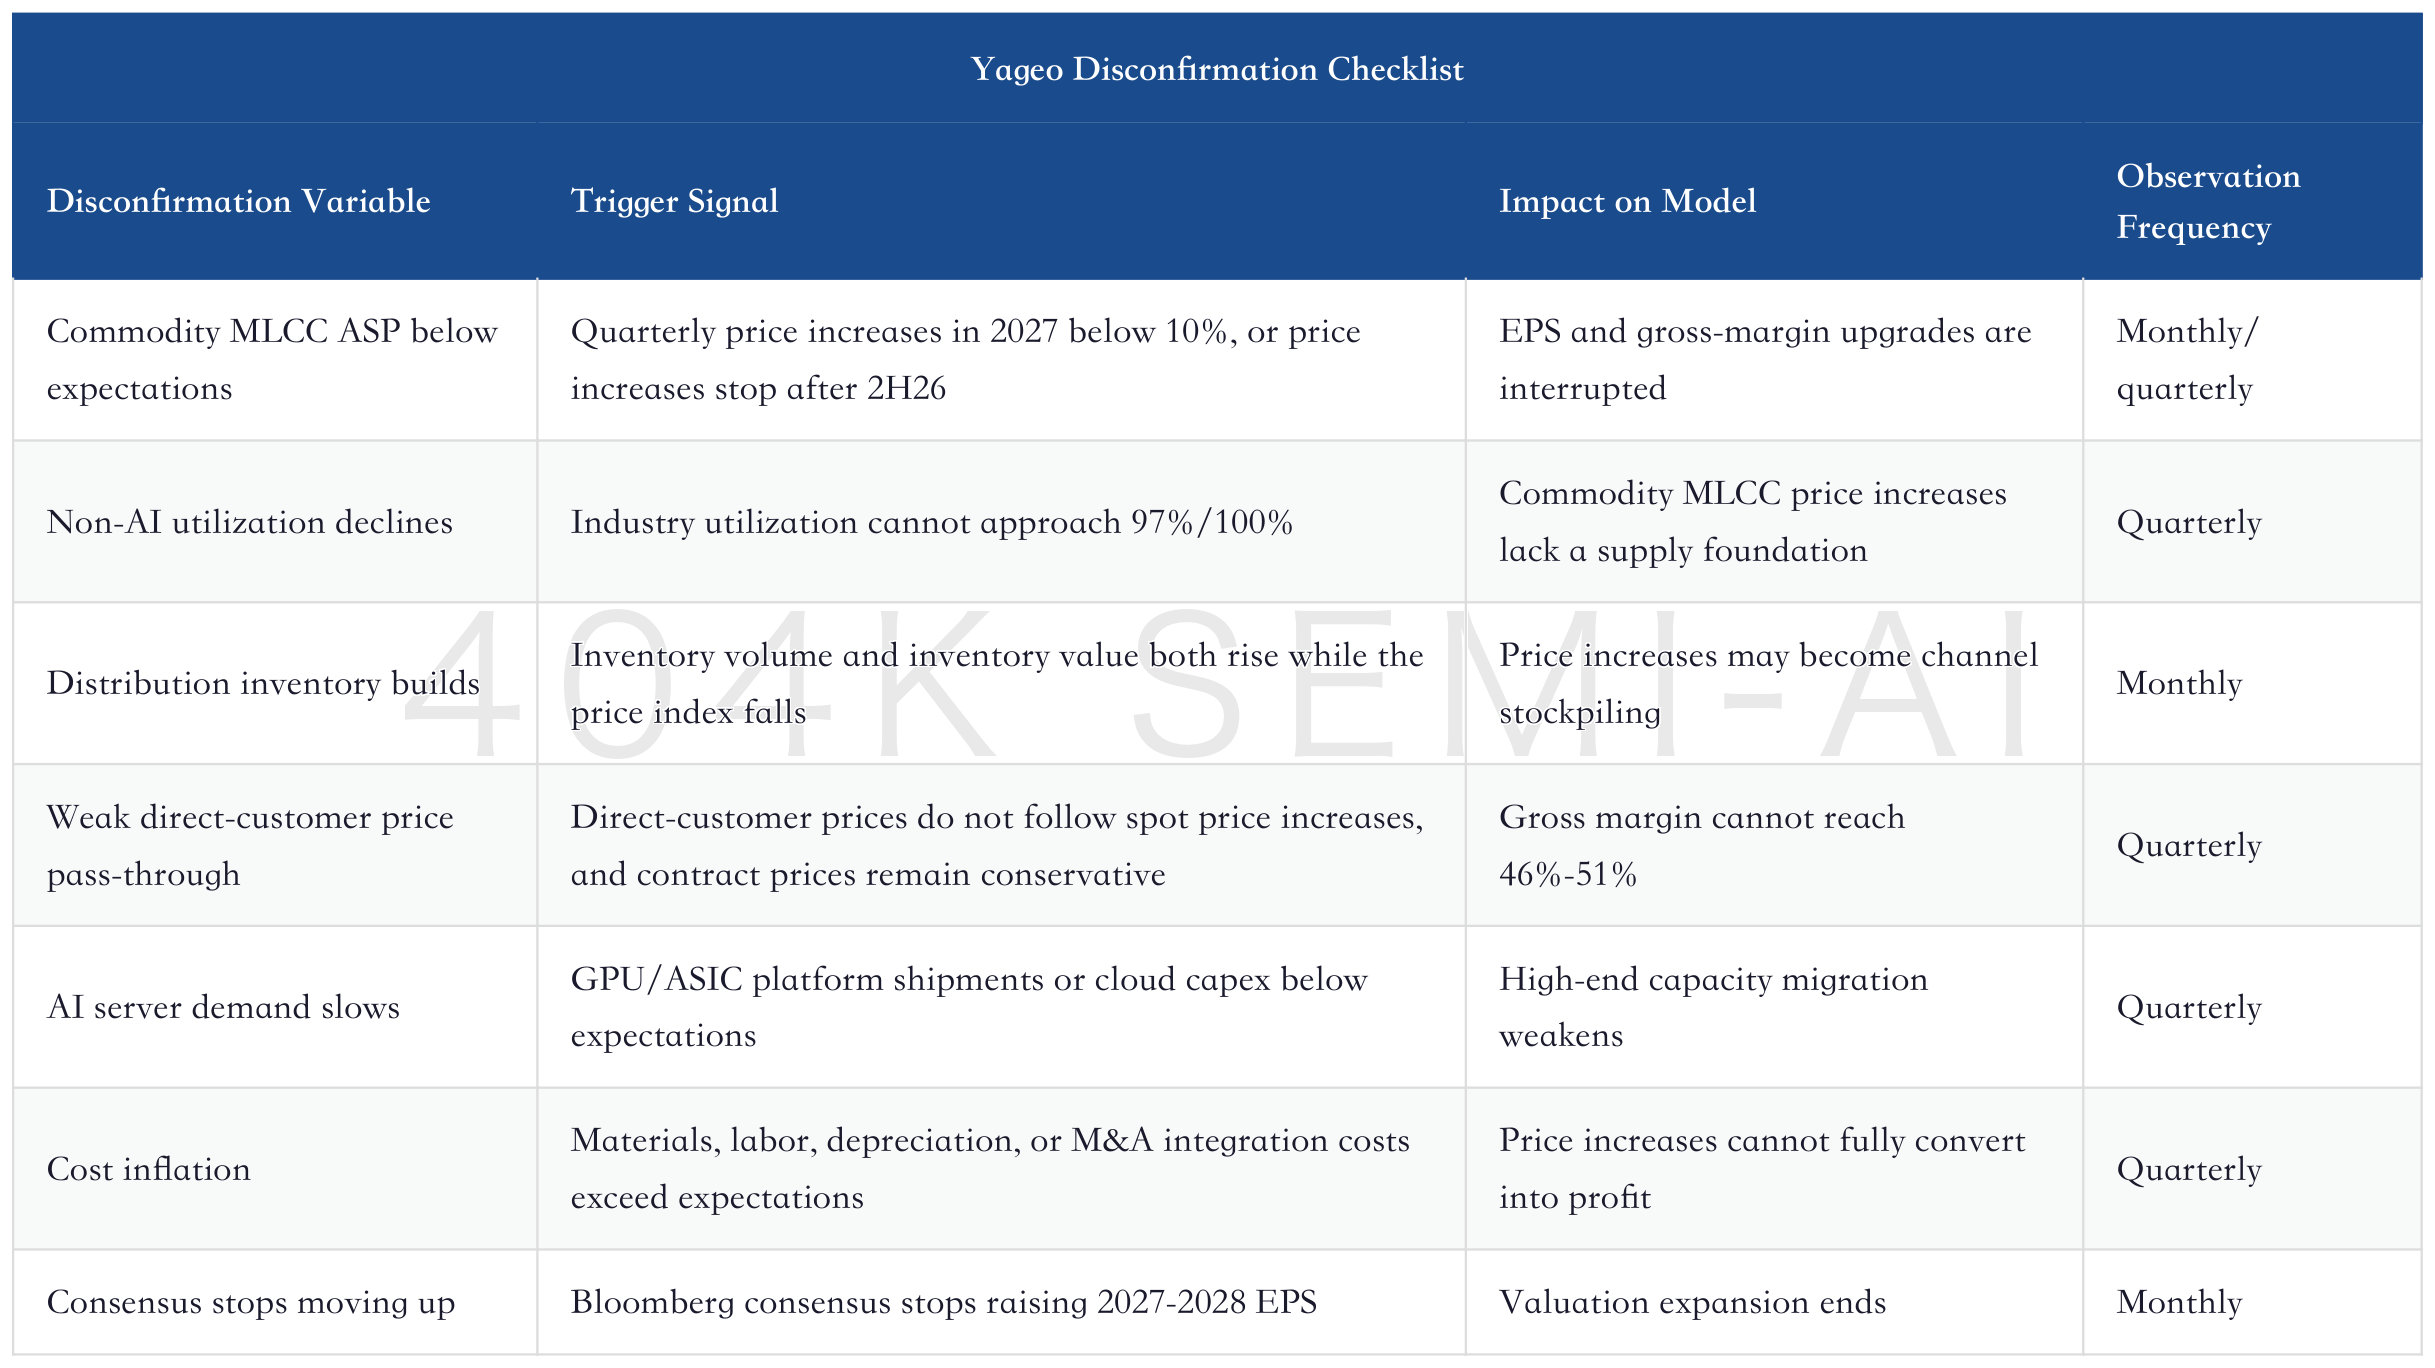
The most important signal to watch is “prices rising while inventory also rises.” If prices and inventory value rise together while inventory volume does not increase meaningfully, that indicates genuine tightness. If inventory volume also builds rapidly, customers and channels may be pulling orders forward. The former supports Yageo’s high valuation; the latter would push it back toward 2018-style cyclical risk.
There is another detail: Yageo’s share-price increase itself is a risk. The stock has risen more than 700% over the past 12 months, and the market will become increasingly demanding in its response to good news. Earnings upgrades that are not fast enough, target prices that stop moving higher, or a short-term weakening in industry data could all trigger valuation pullback. Going forward, the trade cannot be supported by the phrase “the industry is strong.” It must be supported by monthly EPS, ASP, utilization, and consensus upgrades.
XI. How to Track the Next Four Quarters
For Yageo, the next phase is not about one quarter, but a four-quarter validation chain. The best path would be: direct-customer prices continue to rise in 2H26; commodity MLCC ASP clearly enters the income statement by end-2026; non-AI MLCC utilization approaches full load in 2027; market consensus keeps raising 2027-2028 EPS; and Yageo’s ROE rises from 24% toward 36%-46%.
Tracking indicators can be divided into four layers.
The first layer is price. Focus on commodity MLCC ASP, distribution spot prices, direct-customer prices, and discount policies. Goldman Sachs assumes quarterly price increases of 15%-20% in 2027/2028, which is the hardest validation point. If quarterly price increases are only in the single digits, the foundation for the NT$1,490 target price would be weakened.
The second layer is capacity. Watch whether non-AI MLCC utilization moves toward 97%/100%, whether Japanese and Korean suppliers continue allocating capacity to AI applications, and whether Yageo maintains price discipline through utilization and channel inventory management. Nominal capacity expansion does not equal loose supply. The key question is whether effective capacity is still being absorbed by high-end part numbers.
