
目录
Executive Summary
I. How Significant Is the Reset? Cambricon Is Now Modeled as a Company with Annual Revenue of Roughly RMB300 Billion
II. Sources of Demand: Expanding from Chip Sales into Industry-Specific Computing Infrastructure
III. Why Are Margins Falling Despite Higher Revenue?
IV. 3Q26: Can RMB 8.248bn of Inventory Convert into RMB 8.178bn of Revenue?
V. Can Earnings Convert into Cash? The Growth Model’s Second Hurdle
VI. RMB 1,841 Price Target: A Lower Valuation Multiple, but a Higher Outcome
VII. The Competitive Focus: From Substitute Chips to Reusable Systems
VIII. What to Track: Four Areas of Broad-Based Improvement, Not a Single Narrative
Conclusion: The Price-Target Increase Reflects Greater Scale Potential, Not Higher Margin Expectations
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Goldman Sachs has materially raised Cambricon’s (688256.SH) revenue potential while sharply lowering its medium-term margin assumptions. Whether the RMB1,841 price target is justified depends on the company delivering scale, R&D; productivity, and cash flow in tandem.
Executive Summary
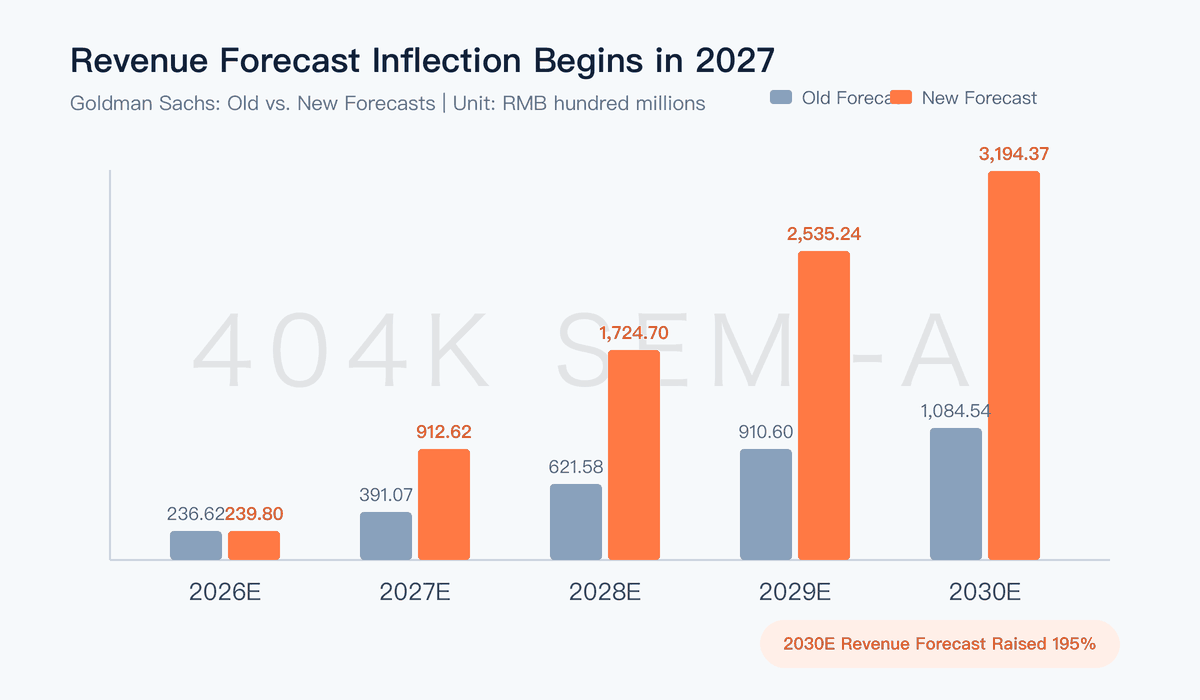
The price-target increase is driven primarily by a wholesale reset of revenue expectations from 2027 onward. Goldman Sachs raised its 2026 revenue forecast by just 1%, but lifted its 2027–2030 estimates by 133%, 177%, 178%, and 195%, respectively. The model assumes cloud-chip shipments will rise from 116,000 units in 2025 to 3.123 million in 2030, while average selling prices increase from US$7,776 to US$14,306, making both volume and pricing key revenue drivers.
The revenue upgrades do not translate into commensurate margin improvement. Goldman Sachs lowered its 2027 operating-margin forecast from 28.4% to 17.2% and its 2030 estimate from 30.7% to 19.0%. Cloud-service-provider bargaining power, volume discounts, and R&D; spending across chips, modules, motherboards, servers, and foundational software will absorb part of the operating leverage generated by scale.
3Q26 is the first critical validation point. Cambricon’s second-quarter revenue was RMB3.111 billion, up 8% sequentially, but inventory rose 83% sequentially to RMB8.248 billion, while raw-material inventory increased 779% year over year in the first half. Goldman Sachs consequently forecasts 3Q26 revenue of RMB8.178 billion. If deliveries and customer acceptance do not accelerate materially, the positive interpretation of the inventory build will weaken.
The RMB1,841 price target depends on Cambricon’s 2030 operating performance. Goldman Sachs applies a 27x valuation multiple to 2030 EBITDA of RMB61.129 billion and discounts the result back to 2027 using a 12.7% cost of equity. The target implies 82x forecast 2027 EPS, close to the historical average of 84x since July 2024, leaving limited room for error.
The key is whether four links in the chain can close. Shipments must convert into revenue, specification upgrades must support average selling prices, R&D; must create reusable software and systems capabilities, and earnings must convert into free cash flow. If all four materialize, the long-term model can become self-reinforcing; sustained weakness in any one area could amplify valuation volatility.
I. How Significant Is the Reset? Cambricon Is Now Modeled as a Company with Annual Revenue of Roughly RMB300 Billion
The most striking feature of Goldman Sachs’ new forecasts is that almost all the revision occurs after 2027. Its 2026 revenue estimate rises only 1%, from RMB23.662 billion to RMB23.98 billion. The 2027 forecast increases 133%, from RMB39.107 billion to RMB91.262 billion; the 2028 estimate rises 177%, from RMB62.158 billion to RMB172.47 billion; and the 2030 forecast increases 195%, from RMB108.454 billion to RMB319.437 billion.
The price-target revision therefore rests neither on the next quarter nor on full-year 2026, but on Cambricon’s commercial scale over the following four years. Revenue was RMB6.497 billion in 2025; Goldman Sachs forecasts RMB23.98 billion in 2026, RMB91.262 billion in 2027, and RMB172.47 billion in 2028. If the model proves correct, Cambricon will move through the RMB10 billion, tens-of-billions, and RMB100 billion revenue thresholds within three years.
Shipment volume is the first pillar supporting this trajectory. Goldman Sachs expects cloud-chip shipments to increase from 116,000 units in 2025 to 405,000 in 2026, 1.033 million in 2027, 1.859 million in 2028, and 3.123 million in 2030. A 26.9x increase over five years implies that Cambricon will evolve from supplying a small number of leading projects into a broader provider of cloud-computing infrastructure.
Average selling price is the second pillar. Goldman Sachs expects the cloud-chip ASP to rise from US$7,776 in 2025 to US$8,239 in 2026, jump to US$12,358 in 2027, and reach US$14,306 in 2030. Even as volumes scale rapidly, the model assumes continued pricing gains, underpinned by ongoing upgrades in product specifications, computing power, memory capacity, and bandwidth, as well as a richer mix of higher-value solutions.
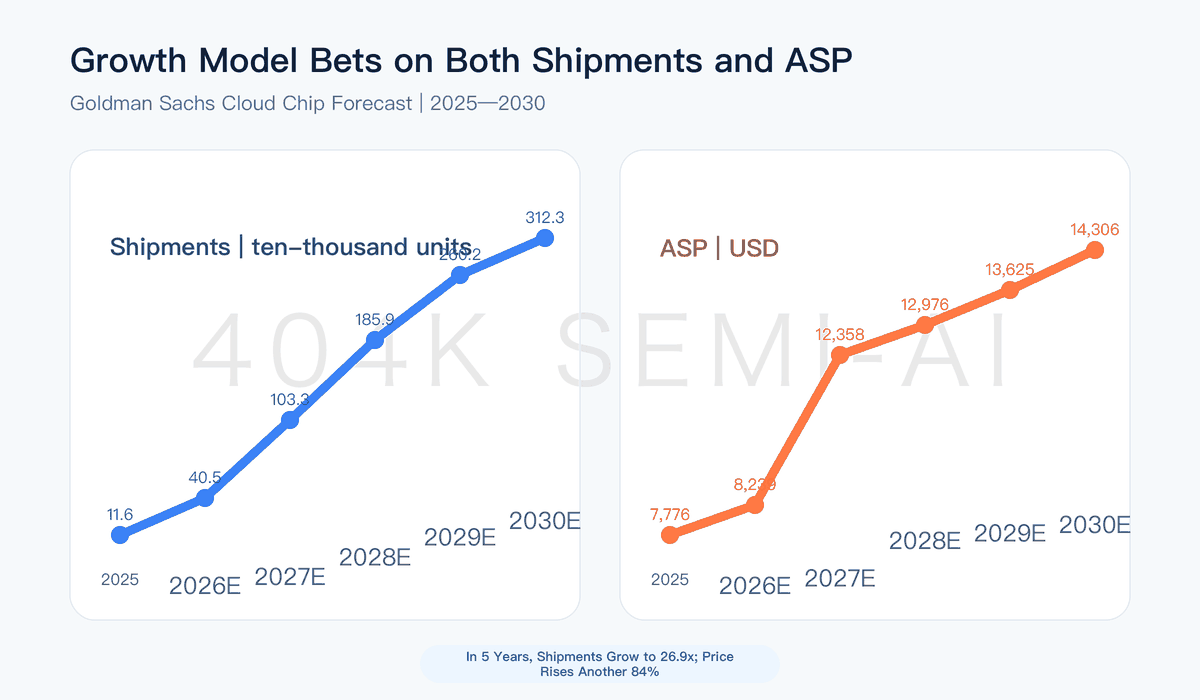
This is a demanding two-variable assumption. Large customers typically seek lower prices as procurement volumes grow. Goldman Sachs nevertheless assumes a rising blended ASP, which means the incremental value from product upgrades must consistently exceed volume discounts. If shipments materialize but pricing falls short, revenue will still grow but is unlikely to reach the long-term forecast of RMB319.437 billion. If pricing holds but supply is insufficient, growth will instead be constrained by deliveries.
II. Sources of Demand: Expanding from Chip Sales into Industry-Specific Computing Infrastructure
Goldman Sachs identifies two drivers of demand growth. The first is the expansion of China’s AI-computing requirements and domestic supply chain. Cambricon’s customers span foundation-model providers, server vendors, AI-software companies, cloud-service providers, energy and education organizations, financial institutions, telecom operators, hospitals, and internet companies. This broader customer base reduces dependence on a small number of research or stand-alone projects.
The second driver is the transition of AI applications from model training into specific business workflows. Financial institutions use Cambricon chips to optimize operations and service efficiency; internet companies deploy them for foundation models, multimodal AI, search, and recommendation. Smart-city applications include semantic search and structured video analysis. Mining use cases encompass visual cargo inspection, maintenance of powered equipment, and safety monitoring; transportation applications include incident detection; and retail applications cover footfall analytics, identification, inspections, theft prevention, and loss reduction.
Across these use cases, customers are increasingly purchasing deployable, industry-specific computing capacity rather than isolated chip specifications. Chips must be integrated into accelerator cards, servers, software platforms, and customer models, then validated for stability, energy consumption, throughput, and operational maintenance before they can generate repeatable revenue. A broader application footprint expands Cambricon’s addressable market, but greater diversity also raises the complexity of software adaptation and delivery.
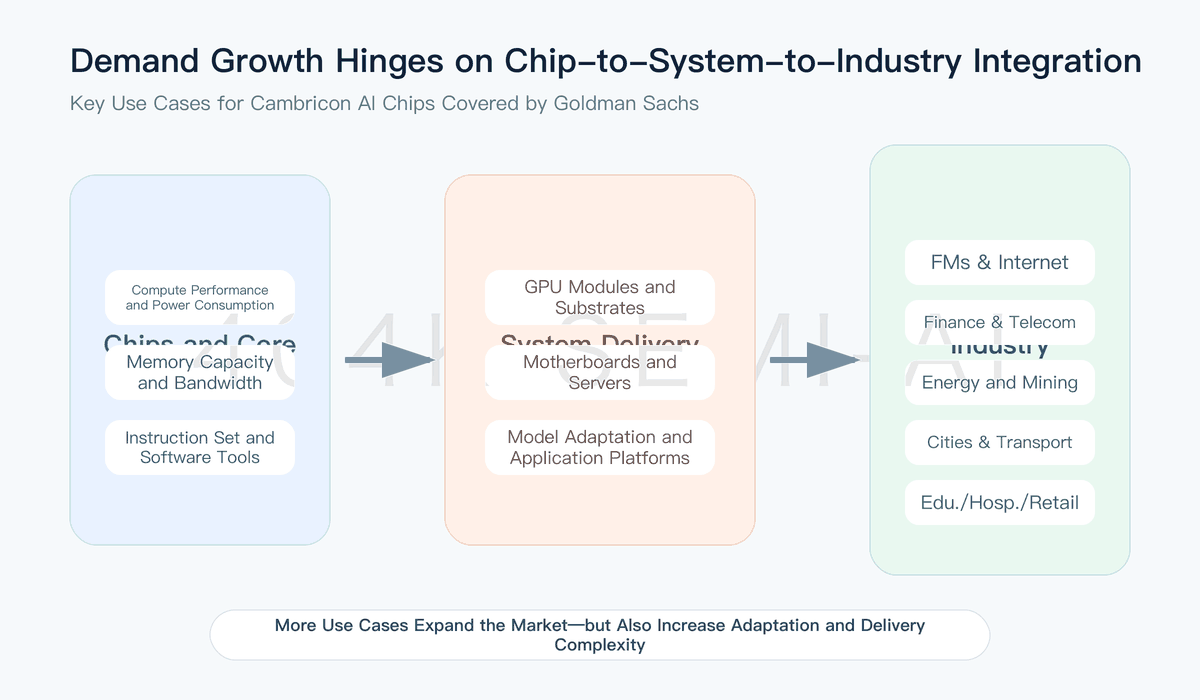
Cambricon’s product roadmap is evolving accordingly. Goldman Sachs notes that the company is still developing its next-generation intelligent-processor microarchitecture and instruction set, with a focus on optimizing the training and inference of natural-language-processing foundation models, video and image generation models, and industry models. It is also targeting improvements in computing capability, memory capacity, bandwidth, performance, power consumption, and die-area efficiency. Existing products have already been adapted for leading domestic models including Zhipu GLM, DeepSeek, Alibaba Qwen, Kimi, and MiniMax.
Model compatibility shortens the customer migration path. Peak chip performance becomes reliable throughput only after integration with frameworks, compilers, operator libraries, communications libraries, and operations tools. If Cambricon can convert optimizations developed for individual major customers into broadly reusable tools, R&D; will evolve from a one-off delivery cost into a platform capability. If every customer still requires extensive customization, rapid revenue growth will continue to drive higher R&D; and service costs.
III. Why Are Margins Falling Despite Higher Revenue?
The most important signal from Goldman Sachs’ revisions is the sharp divergence between scale and profitability. The old and new 2026 operating-margin forecasts are similar at 27.3% and 26.8%, respectively, but the gap widens rapidly from 2027. The new 2027 forecast is 17.2%, versus 28.4% previously; the 2028 estimate is 17.9%, versus 29.3%; and the 2030 forecast is 19.0%, versus 30.7%.
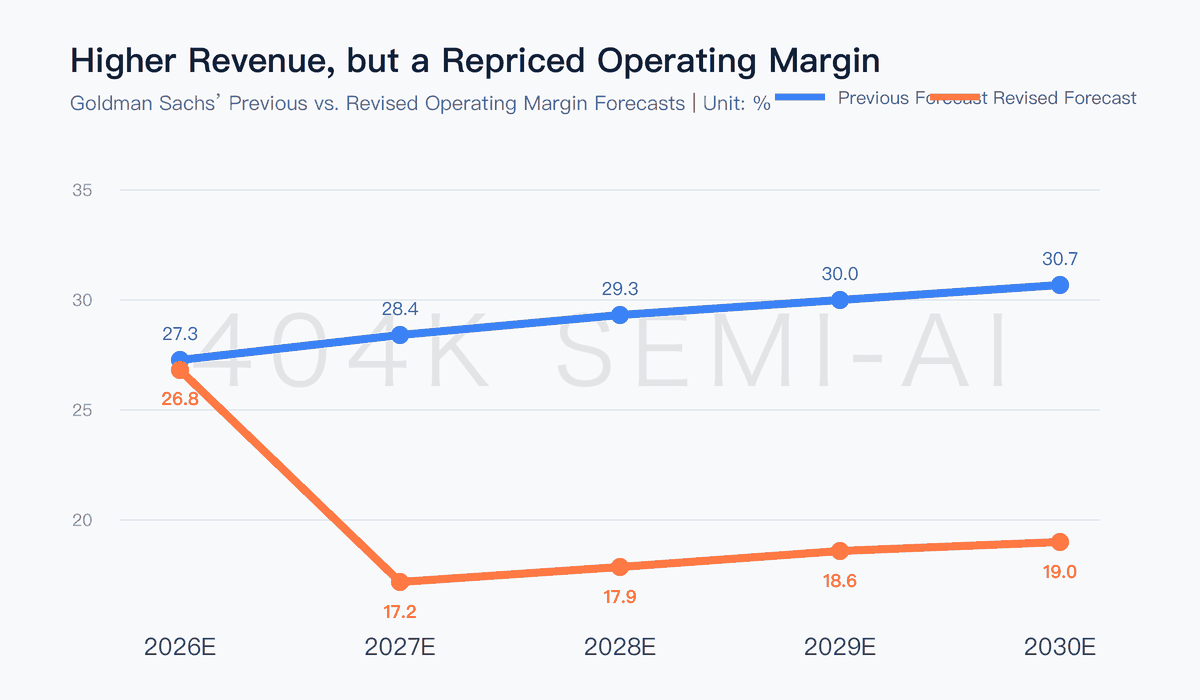
Gross-margin forecasts were also reduced, though more moderately. Goldman Sachs lowered its 2026 gross-margin estimate from 54.3% to 51.3%, its 2027 estimate from 54.0% to 51.0%, and its 2030 estimate from 52.5% to 50.0%. The operating-margin reduction of more than 10 percentage points indicates that the larger change occurs below gross profit, particularly in R&D; spending.
The first source of pressure is customer mix. As Chinese cloud-service providers increase their procurement volumes, their bargaining power strengthens, and large orders typically come with price discounts. Higher shipments will expand revenue, but the profit contribution per chip may not remain constant. Goldman Sachs’ retention of a long-term gross-margin assumption of approximately 50% suggests that it still sees meaningful product value and supply scarcity. Its lower margin forecasts simultaneously acknowledge that customers will capture part of the economics through volume purchasing.
The second source of pressure is the widening scope of R&D.; Cambricon’s required investment now extends beyond chip design to GPU modules, substrates, motherboards, server hardware, AI-application development platforms, and toolchains. Goldman Sachs expects R&D; expenses to rise from RMB1.351 billion in 2025 to RMB5.469 billion in 2026, RMB30.116 billion in 2027, and RMB55.19 billion in 2028. R&D; expenses would equal approximately 33% and 32% of revenue in 2027 and 2028, respectively, explaining why operating margins remain at only 17%–18% despite substantial revenue growth.
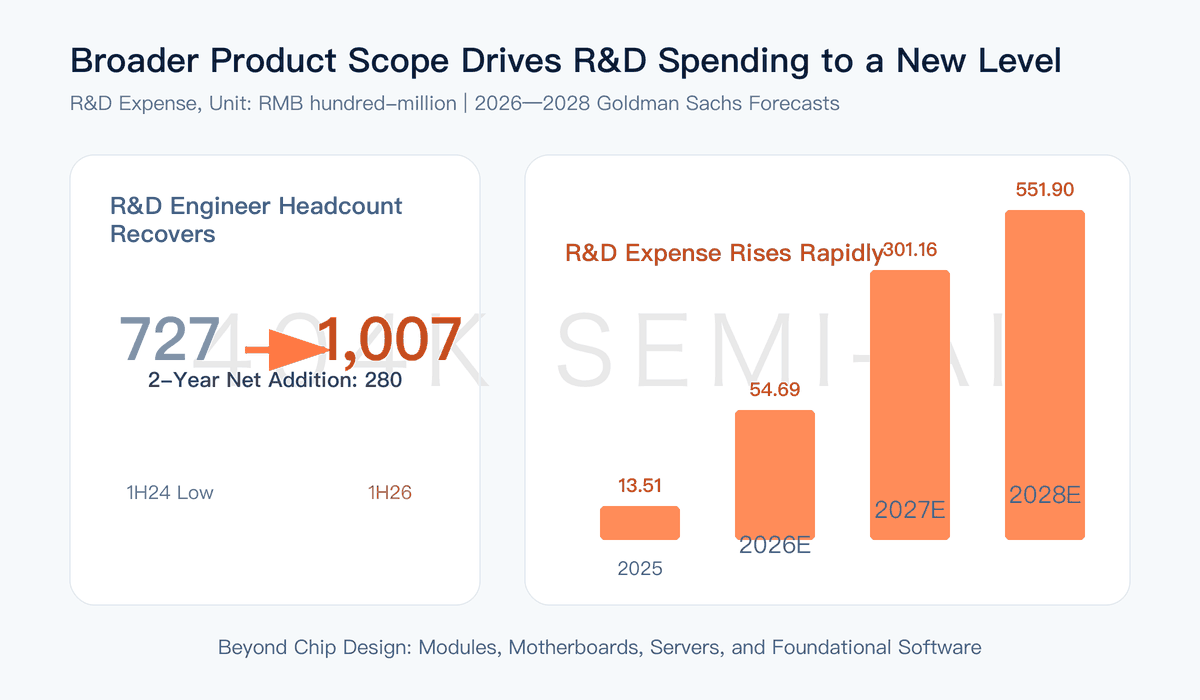
The R&D; workforce is also rebuilding. Cambricon experienced employee attrition in 2023 after being added to the US Entity List in December 2022. The number of R&D; engineers fell to 727 in the first half of 2024 before recovering to 1,007 in the first half of 2026. This rebuilding supports next-generation products and the software ecosystem, but also raises recurring costs. Investors need evidence that R&D; spending generates higher average selling prices, faster customer adoption, and reuse across customers—not merely a larger expense base.
The combination of higher revenue and lower margins is not contradictory. Goldman Sachs is effectively reframing Cambricon from a small, high-margin chip company into a much larger systems-oriented AI-computing supplier. The new model assigns greater value to the company’s potential market share and revenue ceiling, while recognizing that major-customer bargaining power and platform investment will absorb profits over an extended period. The core research question therefore shifts from whether demand exists to whether unit economics remain sufficiently attractive after the business reaches scale.
IV. 3Q26: Can RMB 8.248bn of Inventory Convert into RMB 8.178bn of Revenue?
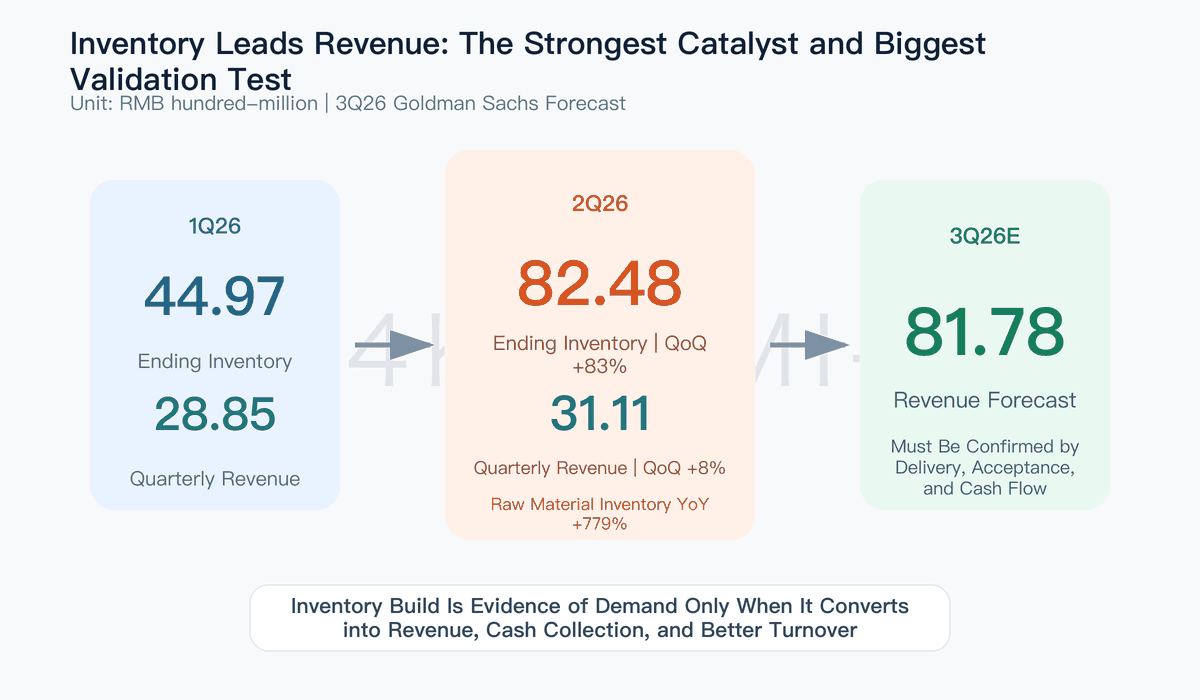
The first real-world test of the long-term forecast lies in the relationship between inventory and quarterly revenue. Cambricon generated RMB 2.885bn of revenue in 1Q26 and RMB 3.111bn in 2Q26, representing just 8% sequential growth—well below the 53% increase recorded in 1Q26. Goldman Sachs attributes the slowdown to customer procurement schedules and wafer supply.
Inventory sent the opposite signal over the same period. Inventory reached RMB 8.248bn at the end of 2Q26, up 83% from RMB 4.497bn at the end of 1Q26. The increase primarily reflected raw materials such as wafers, with raw-material inventory rising 779% year over year in 1H26. Goldman Sachs notes that changes in Cambricon’s inventory have historically led revenue by one quarter and therefore forecasts revenue of RMB 8.178bn in 3Q26, rising further to RMB 9.807bn in 4Q26.
This view has a sound industry rationale. Chips must pass through multiple stages—from wafers to packaging, boards, servers, software adaptation, and customer acceptance. Higher raw-material inventory indicates that Cambricon is securing future supply on its balance sheet; if orders and deliveries proceed normally, that inventory should convert into revenue in subsequent quarters. Improving advanced-node capabilities at domestic foundries could also increase available capacity.
The inventory signal nevertheless cuts both ways. Inventory of RMB 8.248bn already exceeds Cambricon’s full-year 2025 revenue of RMB 6.497bn, making it large enough to materially affect cash flow and impairment risk. Raw materials are tied to specific processes and product roadmaps; inventory turnover could lengthen if the company transitions to next-generation products, yields disappoint, customer acceptance is delayed, or competing solutions advance more quickly. Cambricon’s interim report had already shown an increase in inventory write-down provisions, underscoring that stockpiling is not risk-free.
Goldman Sachs’ bullish case forms a clear loop: inventory rises first, revenue is recognized rapidly in 3Q26 and 4Q26, and inventory days fall from 188.7 days in 2025 to 102.2 days in 2026 and 49.0 days in 2027. That is a substantial improvement. If 3Q26 revenue approaches RMB 8.178bn while inventory growth slows, goods shipped convert into revenue, and operating cash flow improves, inventory will be validated as preparation for delivery. If revenue remains near RMB 3bn, the market will reassess order timing, wafer utilization, and product-transition risk.
V. Can Earnings Convert into Cash? The Growth Model’s Second Hurdle
Goldman Sachs forecasts Cambricon’s net profit rising from RMB 2.059bn in 2025 to RMB 6.179bn in 2026, RMB 14.284bn in 2027, and RMB 27.265bn in 2028. Earnings grow more slowly than revenue, with the net margin falling from 31.7% in 2025 to 15.7% in 2027 before stabilizing at approximately 16%. This is consistent with assumptions for R&D; investment and procurement bargaining power.
The cash-flow trajectory provides a better test of growth quality. Goldman Sachs expects free cash flow to improve from -RMB 1.067bn in 2025 to RMB 2.443bn in 2026, RMB 11.13bn in 2027, and RMB 18.044bn in 2028. Both earnings and free cash flow increase, but free cash flow remains consistently below net profit, reflecting continued cash absorption by inventory, receivables, and capital expenditure.
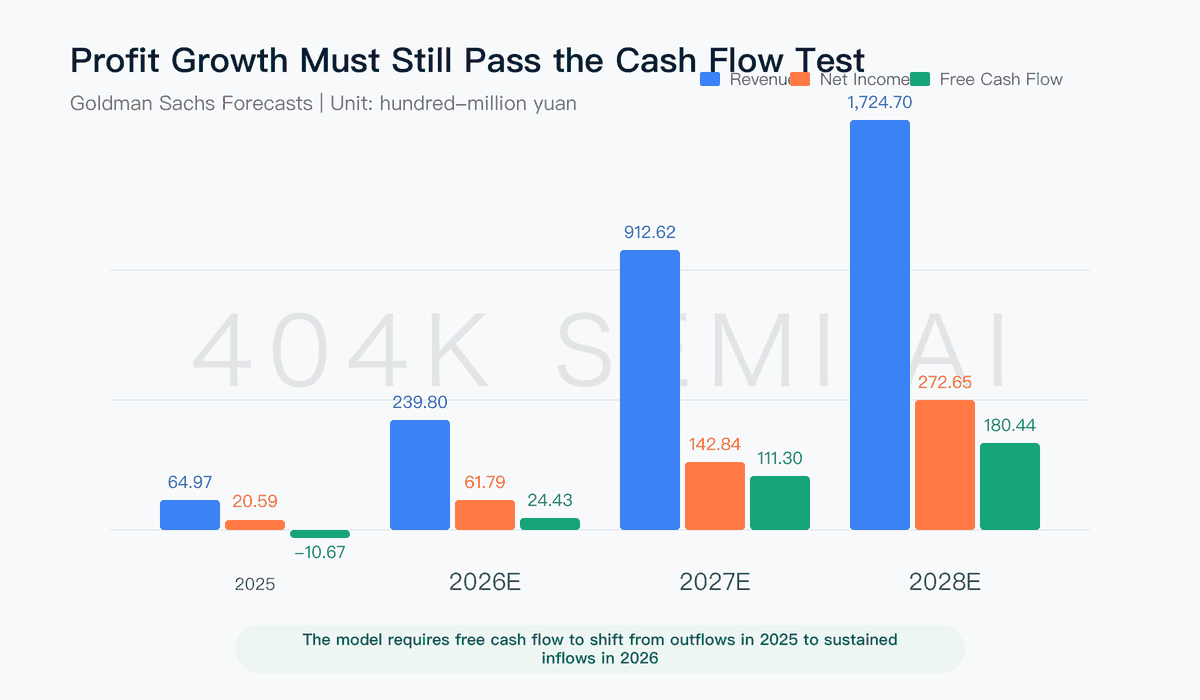
2026 is the critical inflection year. Cambricon must increase wafer and raw-material purchases, expand its R&D; workforce, and raise revenue from RMB 6.497bn to RMB 23.98bn. If operating cash flow can fund procurement, R&D;, and capital expenditure, growth will become self-financing. If profit growth remains largely confined to the income statement while cash continues to accumulate in inventory and prepayments, the company will require greater external financing capacity, and its valuation will become more sensitive to delivery delays.
Absolute inventory and inventory efficiency must also be distinguished. Goldman Sachs forecasts inventory rising from RMB 4.944bn in 2025 to RMB 8.49bn in 2026, RMB 16.012bn in 2027, and RMB 26.088bn in 2028. The absolute balance continues to grow, but revenue rises faster, driving a sustained decline in inventory days. The model therefore requires Cambricon to expand inventory while materially improving turnover efficiency. Revenue, inventory, and cash flow must be assessed together; any one metric in isolation would give a distorted picture.
VI. RMB 1,841 Price Target: A Lower Valuation Multiple, but a Higher Outcome
Goldman Sachs raised its price target for Cambricon from RMB 1,614.77 to RMB 1,841 while maintaining a positive view. Although the EV/EBITDA multiple was reduced from 43x to 27x, making the valuation assumption more conservative, the price target still increased because the 2030 EBITDA forecast was raised substantially.
The calculation has 4 steps. First, Goldman Sachs forecasts Cambricon’s 2030 EBITDA at RMB 61.129bn. Second, applying a 27x EBITDA multiple produces an enterprise value of approximately RMB 1.65tn. Third, the 2030 value is discounted back to 2027 using a 12.7% cost of equity, with net cash then added. Fourth, the resulting value per share is RMB 1,841.
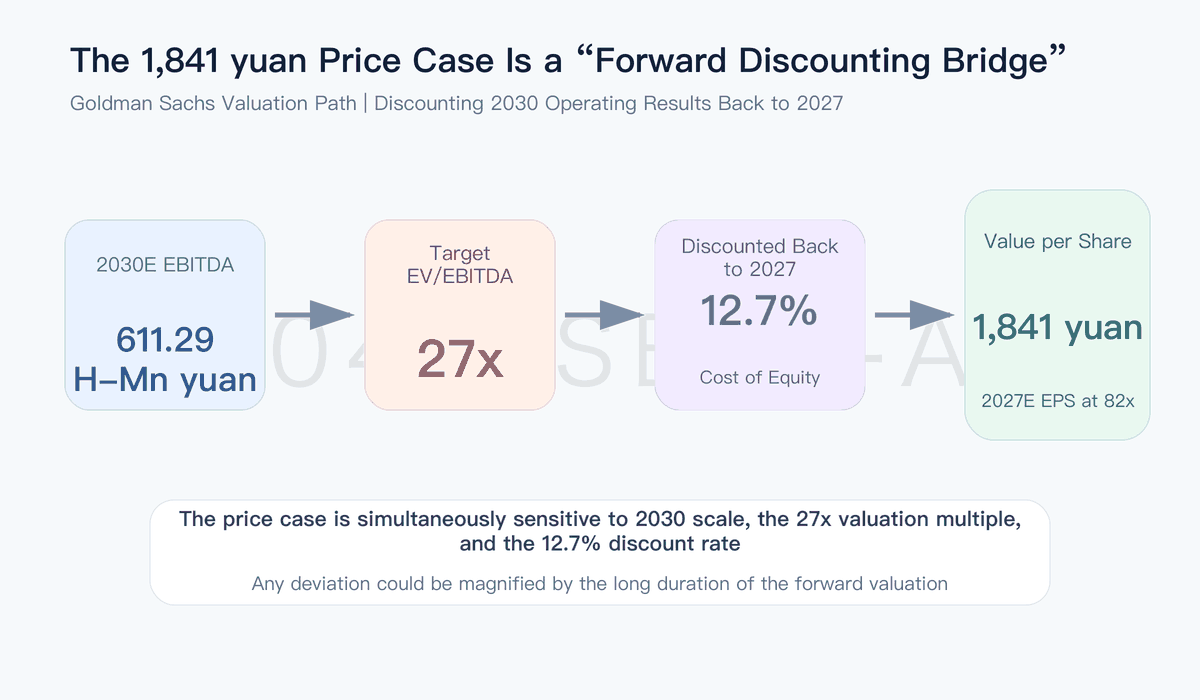
This methodology incorporates long-term market potential and operating scale into the valuation, making it appropriate for a company whose earnings are still changing rapidly. The trade-off is its long duration. The outcome is highly sensitive to 2030 EBITDA, the 27x valuation multiple, and the 12.7% discount rate. If long-term EBITDA falls short of the forecast or the market is no longer willing to pay 27x for 2030 growth, the valuation would face pressure from both variables.
RMB 1,841 represents 82x Cambricon’s forecast 2027 earnings per share, close to the company’s average 12-month forward P/E of 84x since July 2024. This comparison indicates that Goldman Sachs is not assuming a valuation above the historical midpoint; instead, higher earnings estimates drive the increase in per-share value. Nevertheless, 82x remains a demanding multiple, implying that the market will price in growth from 2028—2030 ahead of time and require sustained confirmation from quarterly results.
Based on the August 21, 2026 closing price of RMB 1,035 used in the report, RMB 1,841 implies 77.9% upside. This is a point-in-time calculation that should not be separated from the prevailing share price and forecasts. More important are the operating conditions underpinning the target: revenue above RMB 90bn in 2027 and RMB 300bn in 2030, a long-term gross margin of approximately 50%, an operating margin of approximately 19%, and sustained free-cash-flow growth. The higher the price target, the more operating variables must be delivered simultaneously.
VII. The Competitive Focus: From Substitute Chips to Reusable Systems
Competition facing Cambricon has moved to the system level. Customers compare not only chip performance, memory capacity, and bandwidth, but also software migration, cluster stability, cost per workload, delivery schedules, and operating efficiency. Leadership on a single specification does not guarantee commercial share; the ability to deploy systems quickly and operate them reliably is more closely aligned with purchasing decisions.
Goldman Sachs’ revenue upgrades imply that Cambricon will capture a larger share of China’s domestic AI-compute market while specification upgrades lift average selling prices. Achieving this requires the company to clear 3 technical and commercial hurdles. First, next-generation chips must complete design, manufacturing, and volume production on schedule. Second, foundational software must develop reusable compatibility with mainstream models, reducing customer migration costs. Third, modules, motherboards, servers, and software platforms must be delivered as an integrated system, preventing any single component from delaying deployment.
The 3 principal risks identified by Goldman Sachs all point to this chain. Constraints on wafer supply would directly reduce deliverable volumes; slower-than-expected cloud-chip development would weaken specification upgrades and average selling prices; and stronger-than-expected competition would simultaneously affect market share, pricing, and margins. Because the valuation depends on long-term scale, any risk persisting for several quarters would spread from revenue to earnings, cash flow, and valuation multiples.
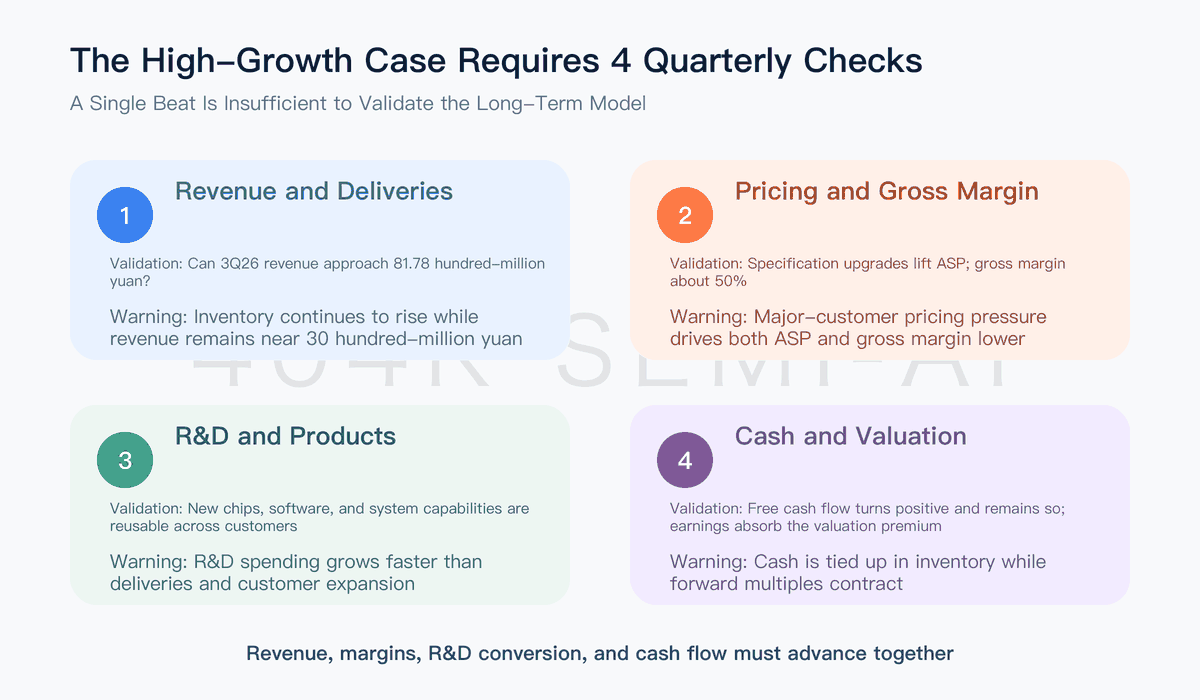
VIII. What to Track: Four Areas of Broad-Based Improvement, Not a Single Narrative
Over the next two quarters, revenue and deliveries will be the most important validation points. Goldman Sachs forecasts revenue of RMB8.178 billion in Q3 and RMB9.807 billion in Q4, significantly above RMB3.111 billion in Q2. If revenue accelerates while inventory turnover improves, that would support the view that inventory is a leading indicator of revenue. If inventory continues to rise without a step-change in revenue, supply, customer acceptance, and order quality will need to be reassessed.
The second area is pricing and gross margin. Goldman Sachs expects product upgrades to lift average selling prices over the long term while compressing gross margin to approximately 50%. This combination requires the value delivered by new products to offset procurement discounts granted to major customers. Average selling prices, gross margin, and customer concentration should be assessed together, rather than treating product upgrades and customer bargaining power as separate issues.
The third area is R&D; conversion. The number of R&D; engineers has recovered to 1,007, and R&D; expenses are forecast to increase rapidly. The next step is to see simultaneous improvement in new-product cadence, model compatibility, replication across customers, and system-delivery efficiency. If R&D; spending continues to rise without faster customer onboarding and delivery, operating margin could fall below Goldman Sachs’ new forecast.
The fourth area is cash flow. Earnings growth must progressively translate into operating and free cash flow; inventories and prepayments cannot continue growing faster than revenue indefinitely. Better cash flow would strengthen the company’s ability to self-finance growth, while persistent supply-chain working-capital absorption would increase financing needs and pressure market valuation.
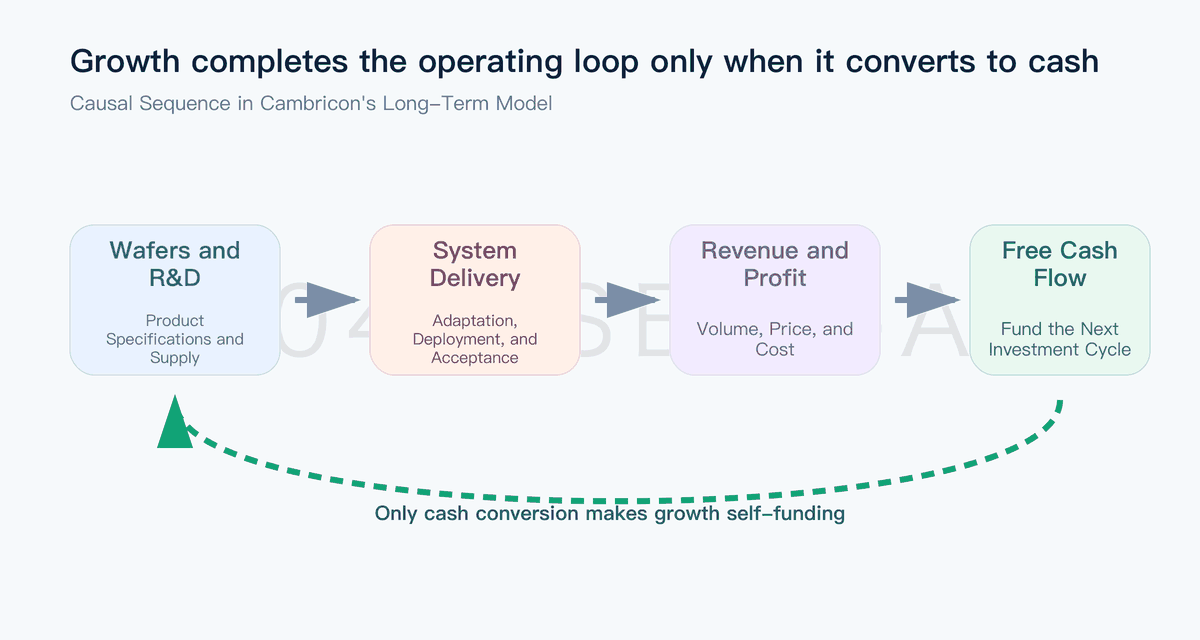
These four areas follow a clear sequence: wafers and R&D; produce the products; system delivery converts products into revenue; pricing and cost discipline convert revenue into profit; and profit ultimately converts into cash. Goldman Sachs’ new forecasts scale up every stage of this cycle, while also magnifying the consequences of any slowdown along the way.
Conclusion: The Price-Target Increase Reflects Greater Scale Potential, Not Higher Margin Expectations
Goldman Sachs’ incremental thesis on Cambricon can be summarized in one sentence: the company’s revenue ceiling has risen significantly, but scaling requires customer concessions and the assumption of broader system-level R&D; costs. The new model no longer depends on a long-term operating margin of approximately 30%. Instead, higher shipment volumes, rising average selling prices, and broader industry adoption allow an approximately 19% long-term operating margin to generate greater absolute profit.
This shifts the focus of the Cambricon investment case. Previously, the market was primarily assessing whether demand existed for domestic AI chips and whether the company’s products could gain customer adoption. The key questions now are whether Cambricon can deliver hundreds of thousands to millions of chips annually, sustain product upgrades while maintaining an approximately 50% gross margin, reuse its R&D; platform across customers, and convert high profits into free cash flow.
The RMB1,841 price target discounts Cambricon’s projected 2030 operating scale well in advance and therefore has limited sensitivity to any single quarter’s results. It can be justified by substantial revenue forecast upgrades, but would quickly come under pressure if shipments, pricing, R&D; conversion, or cash flow fall short. Q3 2026 will provide the first strong set of evidence: whether RMB8.248 billion of inventory can drive revenue close to RMB8.178 billion while improving turnover and cash flow.
Cambricon’s long-term opportunity lies in domestic AI-compute demand, compatibility with mainstream models, and expanding system capabilities. Valuation pressure arises because the same growth conditions must be delivered consistently. The ultimate test of the RMB1,841 price target is whether the RMB319.437 billion of revenue in the forecast model can be realized with sustainable margins and cash returns.