
Goldman Sachs DRAM Deep Update: DDR5 Price Increases, 2027 HBM Repricing, and Samsung's W2,450tn Investment
目录
Too Long; Didn't Read
1. Bottom Line First: DDR5 Is Current Profit, HBM Is the Next Pricing Anchor
2. Goldman Sachs' June DRAM Sentiment Indicator: Moderately Positive, but Components Are Already Hot
3. DDR5 Spot Premium: Prices Are Already Pressuring Contract Pricing
4. Korean Exports and the Server Chain: AI Demand Is Still Pulling Real Orders Higher
5. China Smartphones: Recovery Exists, but So Does Pricing Pressure
6. Nanya Technology and Supreme: Legacy Memory Continues to Add Leverage
7. 2027 HBM: Goldman Sachs Raises the Forward Pricing Anchor Materially
8. Samsung's W2,450tn Investment: Long-Term Commitment, Near-Term Supply Still Constrained by Capacity Gates
9. CapEx Discipline: The Market's Real Concern Is the Post-2028 Supply Shadow
10. Samsung Valuation: Goldman Sachs Is Focused on Memory Earnings, Long-Term Agreements, and Shareholder Returns
11. Long-Term Agreements and HBM Customer Lock-In: Can This Cycle See Less Inventory Swing?
12. Equipment Chain: Samsung's Long-Term Investment Gives WFE and Advanced Packaging Longer Order Visibility
13. Samsung, SK hynix, Micron, and Niche Vendors: Same Price Cycle, Different Valuation Logic
14. Three Worldviews: Price-Increase Cycle, AI-Memory New Normal, and Post-CapEx Cycle
15. Model Bridge: From DDR5 Spot Prices to Samsung Valuation, There Are Six Gates
16. Disconfirmation Checklist: Signals That Would Cool This Re-Rating
17. What to Watch Over the Next Four Quarters
18. Mapping to A-Shares and Hong Kong Stocks: Watch Legacy Memory, Equipment, and the AI-Server Chain
19. Data Framework: Price Moves First, Profit Follows, Inventory Tells the Truth Last
20. ROIC Validation: Samsung's Long-Term Investment Ultimately Returns to Capital Returns
21. HBM Supply Gates: Price Upgrades Ultimately Need Delivery
22. Price-Increase Quality Check: Contract Prices, Inventory, and Cash Flow Must All Pass
23. Scenario Framework: Base Case Watches Contract Prices, Bull Case Watches HBM, Stress Case Watches Inventory
24. Where This Memory Rally Is Easiest to Misread
25. Conclusion: The Memory Rally Has Entered the Stage of "From Price Realization to Forward Pricing"
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Goldman Sachs' June DRAM sentiment indicator shows that DDR5 spot price increases, Korean exports, and server-chain revenue continue to validate the memory upcycle; Samsung's W2,450tn long-term investment also brings supply discipline back to the foreground. This report unpacks DDR5, HBM, long-term agreements, CapEx, and equipment-chain transmission to assess whether this re-rating is being driven by price, cash flow, or long-term capacity constraints.
Too Long; Didn't Read
Near-term signals remain strong. Goldman Sachs' June DRAM sentiment indicator stayed moderately positive. DDR5 spot prices are up 20% from early May, while Korean DRAM exports and server ODM revenue continue to grow at high rates, indicating that AI servers, ASIC servers, and memory pricing are still jointly lifting industry momentum. This supports near-term earnings upgrades for memory stocks, but also reminds the market that the stronger prices become, the more end demand needs to be validated by quarterly data.
The DDR5 spot premium is a leading indicator for contract-price increases. DDR5 spot prices are at a 25% premium to May contract prices, while the DDR4 premium is even higher, indicating that customer restocking and tight supply are already reflected in transaction prices. If the spot premium persists, subsequent contract prices should follow; if the premium compresses quickly, the market will read the price increase as a short-term mismatch, and valuation upside for memory stocks will be pulled back.
2027 HBM repricing is the forward variable. Goldman Sachs raised its 2027 HBM price-growth assumption for Samsung Electronics from 14% to 44%, because strong conventional DRAM prices will affect next year's HBM pricing negotiations. When HBM supply remains tight and conventional DRAM prices are also rising, customers have less room to trade off capacity, performance, and delivery schedules.
Samsung's W2,450tn investment does not equal a near-term flood of supply. Samsung plans to invest W2,450tn from 2026 to 2040, including around W2,100tn in domestic semiconductors. Goldman Sachs believes that if R&D; is included, the implied long-term growth rate is 5%-6%, a reasonable range. Near-term supply remains constrained by HBM yield, advanced packaging, equipment lead times, and customer qualification.
Cash-flow quality will decide this memory re-rating. Samsung's valuation table shows that Goldman Sachs' 2026-2028 assumptions for earnings, free cash flow, and shareholder returns have all been lifted by the memory upcycle. What will truly sustain the valuation is simultaneous improvement in long-term agreement coverage, inventory quality, CapEx discipline, and HBM delivery capability.
Equipment and upstream materials will be repriced. If Samsung gradually deploys its long-term investment into fabs, HBM lines, packaging, and new display capacity, WFE, advanced packaging, testing, substrates, gases, and materials chains will all benefit. The risk is that CapEx accelerates too early, bringing post-2028 supply expectations forward into current valuations.
1. Bottom Line First: DDR5 Is Current Profit, HBM Is the Next Pricing Anchor
Read together, the core conclusion from these two Goldman Sachs reports is straightforward: the memory cycle is still moving upward, but the market is shifting from "are prices rising" to "how long can price increases last." The June DRAM sentiment indicator is not extremely bullish; it remains moderately positive. But the underlying components are already strong. DDR5 spot prices, Korean DRAM exports, server ODM revenue, Nanya Technology revenue, and channel checks all point to the same fact: supply-demand conditions remain tight.
More importantly, the meaning of the price increase is changing. In the earlier stage, the market watched DDR4 and DDR5 spot prices to confirm restocking and tight supply. Goldman Sachs now embeds conventional DRAM strength into its 2027 HBM price assumptions, showing that price increases in mainstream memory have begun to influence forward negotiations for high-end AI memory. This matters more than a single month's pricing data, because HBM usually involves large customers, long-cycle contracts, and higher capital intensity. Once pricing expectations rise, the valuation frameworks for Samsung Electronics, SK hynix, Micron, and the equipment chain all change.
Samsung Electronics' W2,450tn domestic investment plan, announced the same day, puts another issue on the table: if memory demand is truly entering a new AI-era cycle, will leading companies quickly lift CapEx and undermine supply discipline? Goldman Sachs' view is relatively measured. The plan runs through 2040 and may include R&D; spending, implying a reasonable long-term growth rate. In other words, it looks more like a long-term capacity and technology-roadmap statement; in the near term, the market still needs to watch HBM yield, equipment delivery, customer qualification, and cash flow.
The research judgment can be compressed into one sentence: the first stage of this DRAM re-rating is driven by DDR5 and DDR4 price increases, while the second stage depends on 2027 HBM pricing, long-term agreement coverage, and CapEx discipline among leaders such as Samsung. Looking only at spot prices can underestimate forward earnings leverage, while looking only at long-term investment can understate near-term supply constraints. The real focus should be whether price, delivery, inventory, and CapEx indicators move in the same direction.
2. Goldman Sachs' June DRAM Sentiment Indicator: Moderately Positive, but Components Are Already Hot
Goldman Sachs described its June DRAM sentiment indicator as moving in a "moderately positive direction." It is not maximally bullish, but the message is not weak. The indicator covers spot prices, server-chain revenue, Korean exports, Chinese smartphones, Nanya Technology, Supreme Electronics, the second derivative of Samsung's DRAM ASP, and channel feedback. This mix has one advantage: it looks at price, real demand, and end-market affordability at the same time.
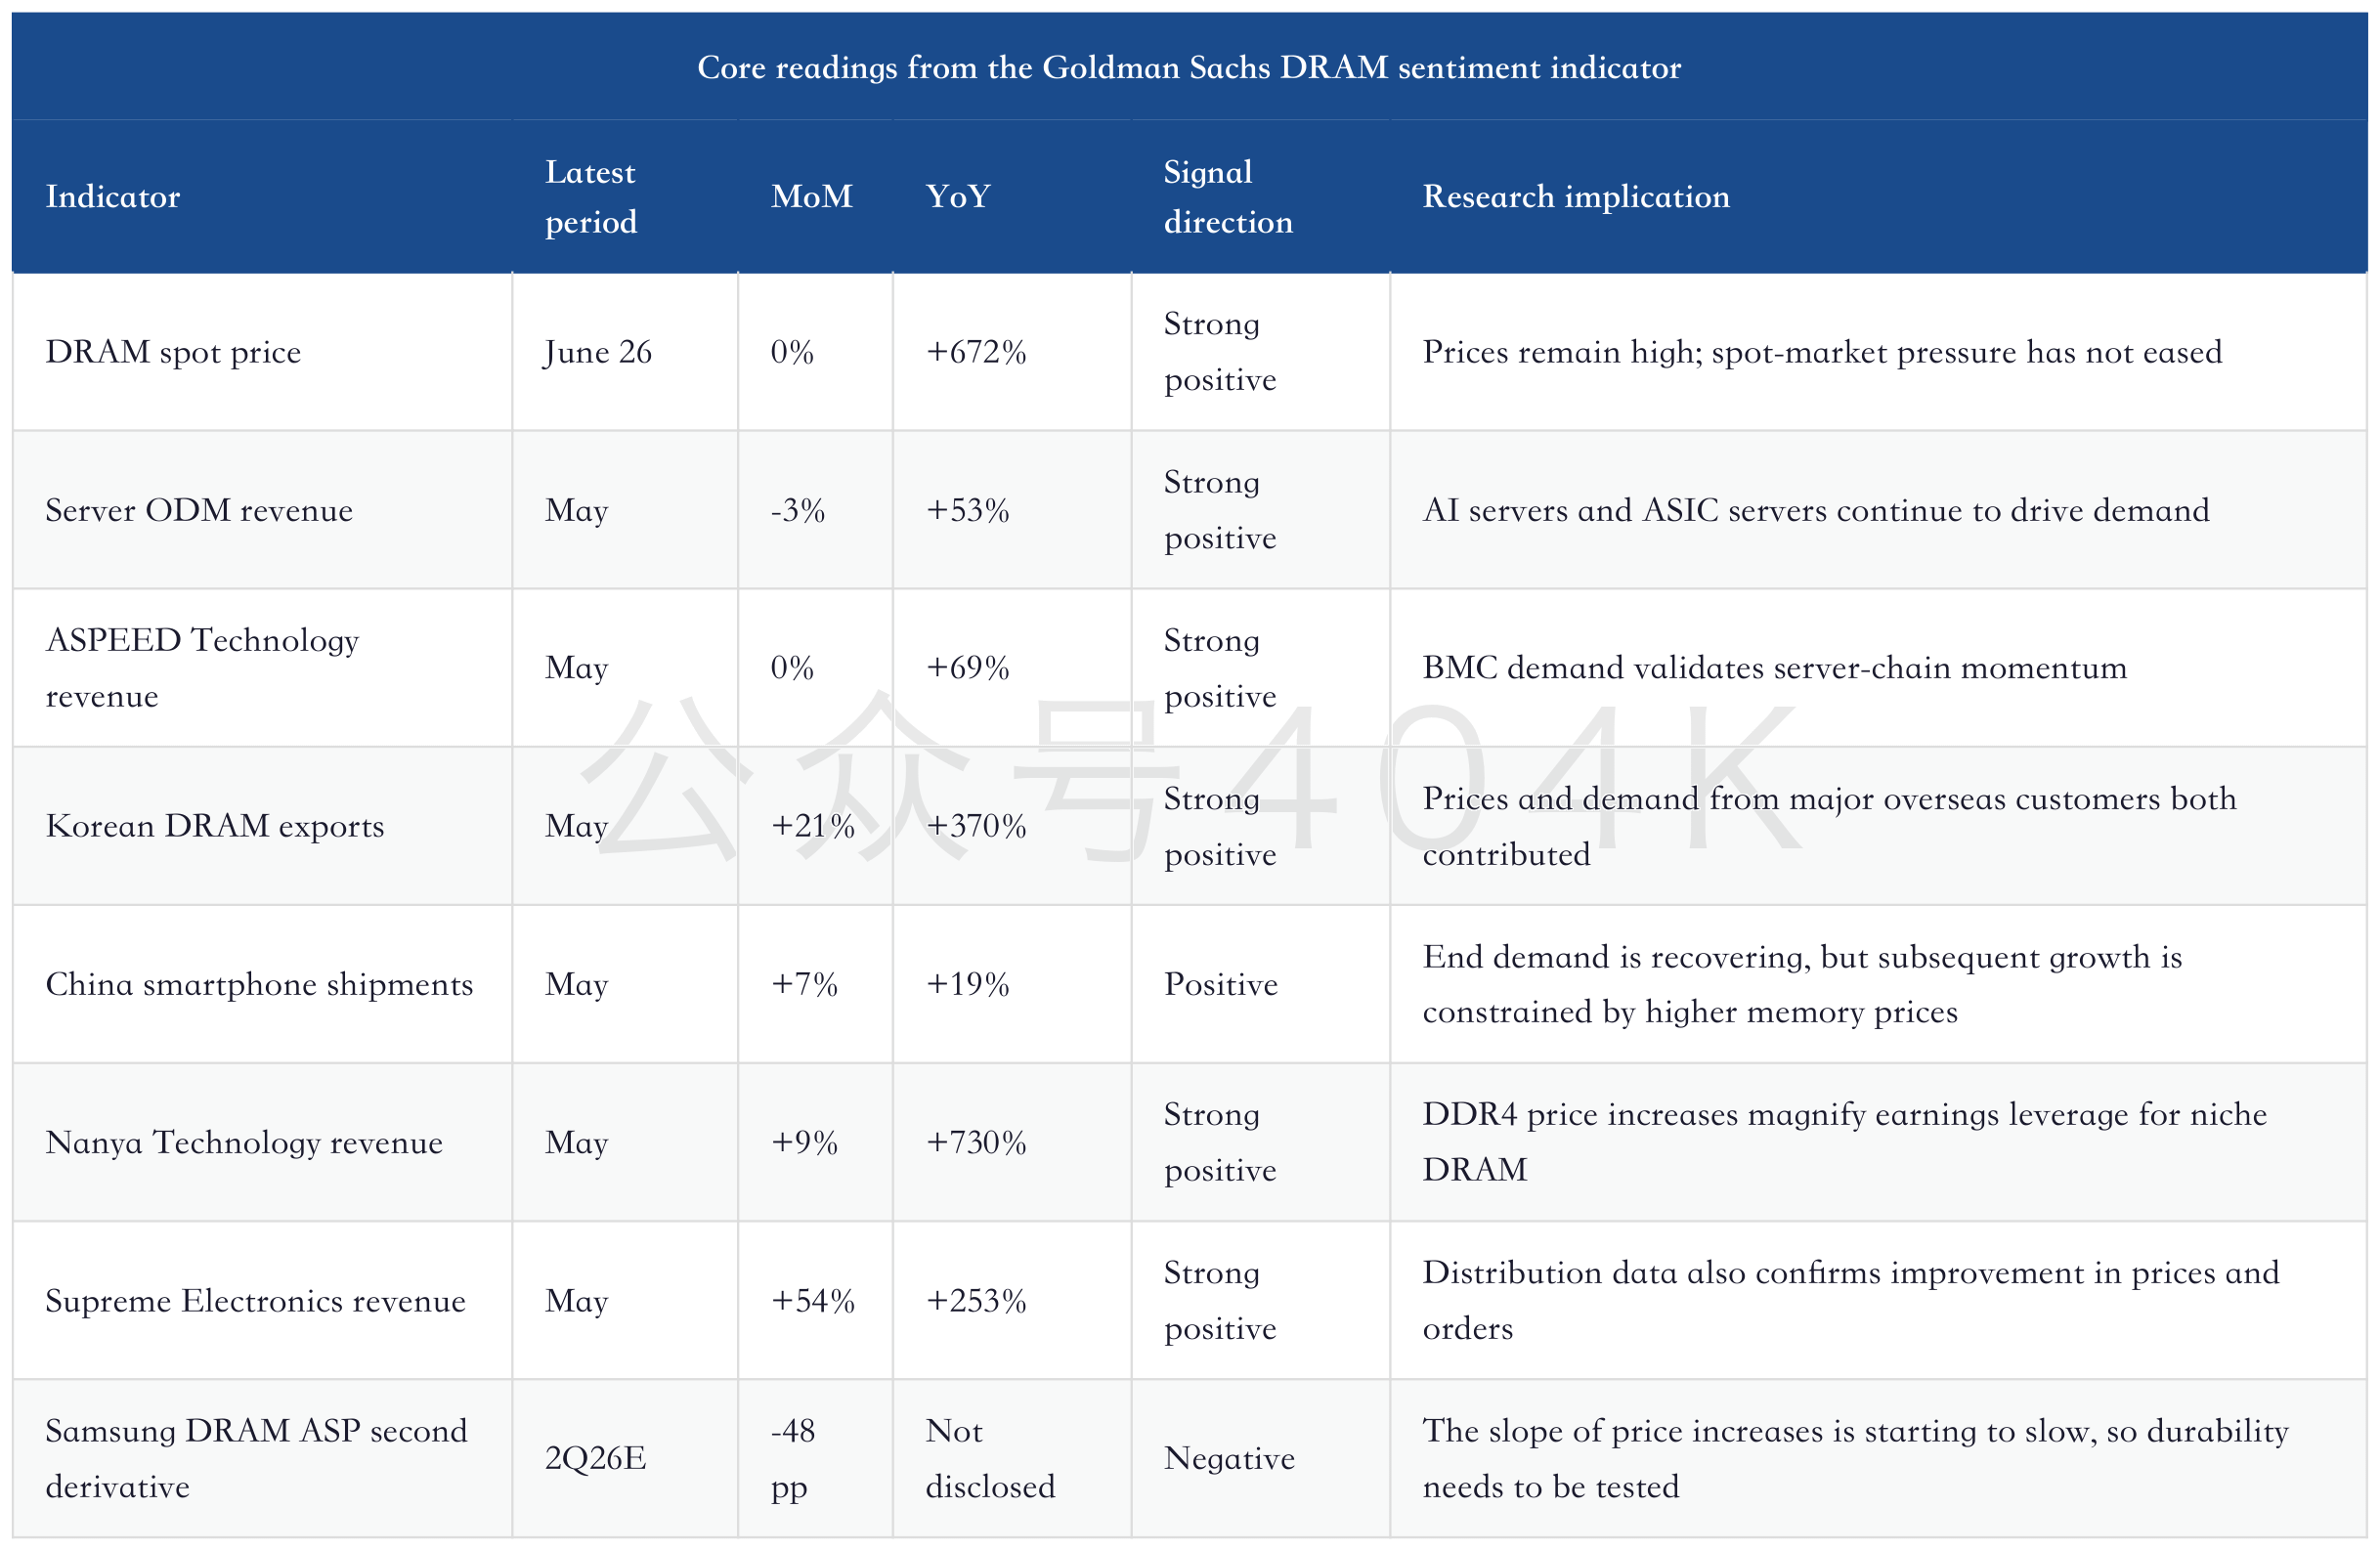
The key point in this table is the final row. Prices, revenue, and exports are all strong, but the second derivative of Samsung's DRAM ASP is negative. This means price increases are continuing, but the slope has moved from extreme acceleration toward deceleration. This is the kind of phase memory-stock valuations fear most: earnings are still being revised up, while the market starts to worry whether the next stage of growth will slow. Goldman Sachs maintains a moderately positive view precisely because strong demand and a slowing price slope are both present.
For investment research, this state is not contradictory; it is a common mid-cycle pattern. In the early stage, share prices trade on price leverage. In the middle stage, the focus shifts to earnings quality. Only in the late stage does the market turn primarily to inventory and supply expansion. The most important question has already shifted from "are DRAM prices rising" to "can the DDR5 spot premium flow into contract prices, and can forward HBM pricing take over." Only if both are true can the memory upcycle move from short-term price increases to a longer-term earnings step-up.
3. DDR5 Spot Premium: Prices Are Already Pressuring Contract Pricing
DDR5 is the cleanest near-term signal in this sentiment indicator. Goldman Sachs' report shows that DDR5 prices are up 20% since early May, and spot prices are at a 25% premium to May contract prices. DDR4 is also rising, with an even higher spot premium to contract prices. Spot prices leading contract prices usually means customer restocking, supply contraction, or longer lead times have first appeared in the spot market.
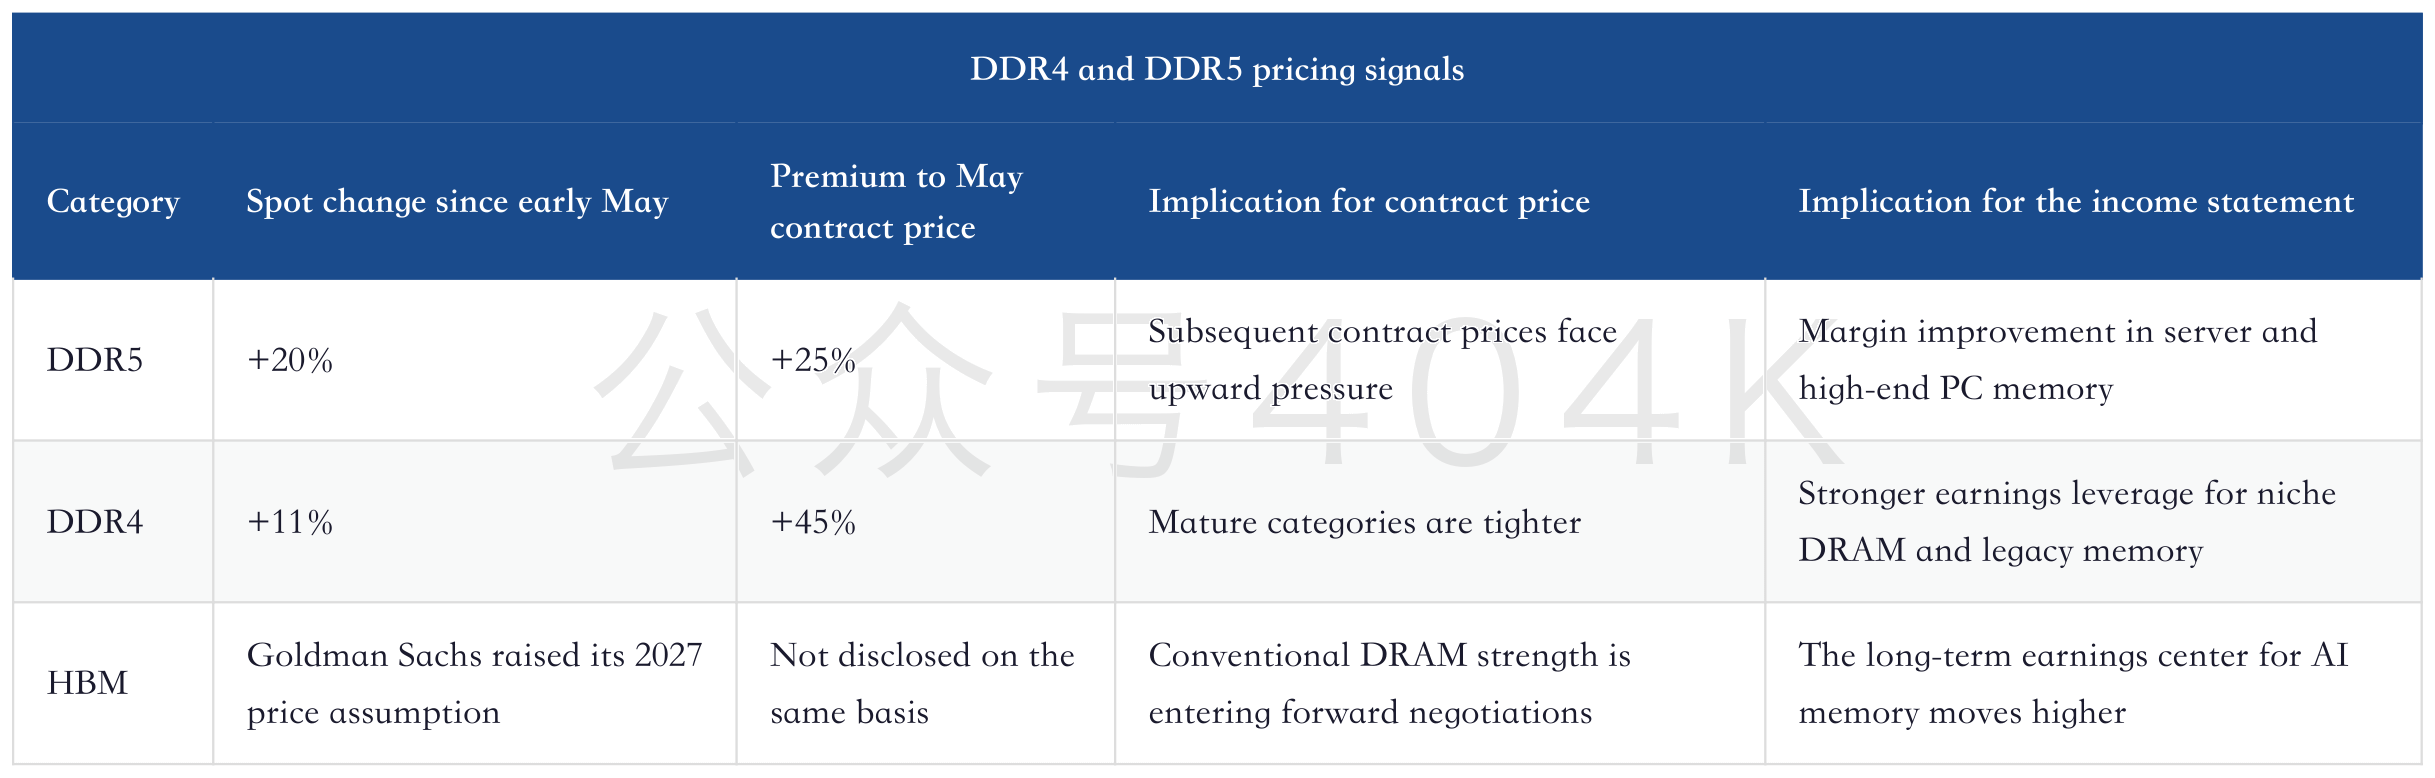
DDR5 price increases affect Samsung Electronics and the broader memory chain in two ways. The first is a direct income-statement impact. DDR5 penetration is rising in servers, PCs, and some high-end endpoints, and price increases lift product ASPs and gross margins. The second is a customer-behavior impact. When conventional DRAM prices strengthen, cloud providers and AI-server customers become more willing to sign long-term agreements, lock in supply, and plan next year's capacity earlier. That changes HBM negotiations.
This is also why Goldman Sachs puts DDR5 and HBM in the same report. HBM pricing appears to be a high-end AI-product issue, but the underlying constraints still involve DRAM wafers, advanced packaging, yield, and customer capacity reservations. The tighter conventional DRAM becomes, the more negotiating leverage HBM suppliers have. If conventional DRAM prices fall back, the upside space for HBM pricing will also be reassessed.
4. Korean Exports and the Server Chain: AI Demand Is Still Pulling Real Orders Higher
Looking only at price carries a risk: price increases may come from inventory disruption, or they may come from real demand. Goldman Sachs uses three sets of data - server ODMs, ASPEED Technology, and Korean DRAM exports - to validate the demand side. They correspond respectively to AI-server system shipments, server control chips, and cross-border DRAM shipments, allowing demand to be tested from different angles.
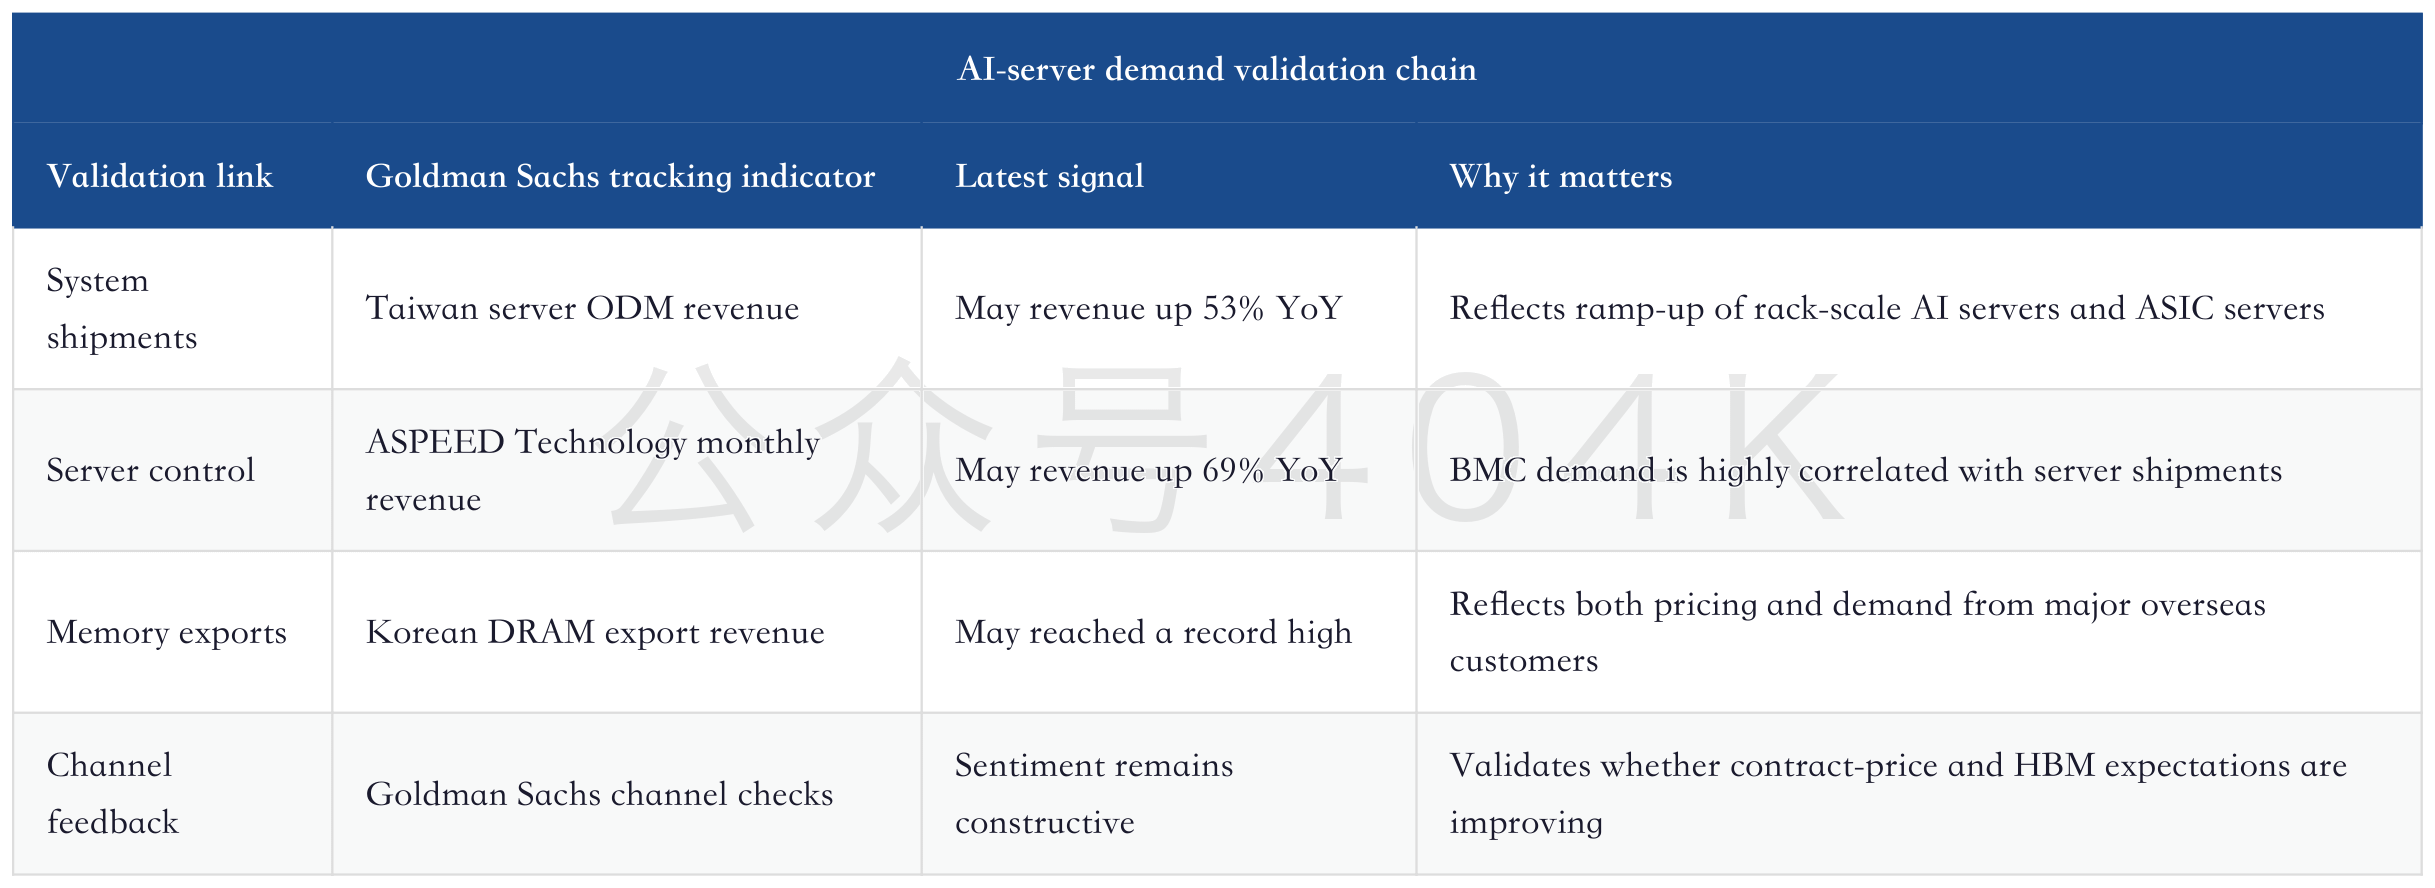
Korean DRAM exports are especially important. They reached another record high in May and were meaningfully above the previous peak, showing that memory momentum has entered cross-border export revenue rather than remaining in spot quotations. For Korean leaders, export data validates pricing, utilization, and major-customer demand at the same time. For the equipment chain, stronger exports increase visibility into future CapEx.
Server ODM and ASPEED Technology data point in the same direction. AI servers have expanded from GPU systems to rack-scale delivery and ASIC servers, so memory demand is no longer coming only from the NVIDIA chain. It is also coming from cloud providers' self-developed chips, networking equipment, and enterprise system upgrades. This diffusion can extend the DRAM demand curve because every type of AI computing platform requires higher memory capacity, higher bandwidth, and more stable supply.
5. China Smartphones: Recovery Exists, but So Does Pricing Pressure
China smartphone shipments rose YoY in May for a second consecutive month, a positive signal in the Goldman Sachs indicator. It shows that end consumption has not completely stalled and that higher memory prices have not immediately crushed demand. At the same time, Goldman Sachs' China team expects 2Q26 shipments to decline YoY, mainly because higher memory prices are weighing on end demand.
This tension is very important. DRAM price increases are positive for memory makers, but they are a cost pressure for downstream system vendors. Smartphones, PCs, and parts of consumer electronics are highly price-sensitive. Once memory costs rise beyond a certain level, brands may reduce configurations, delay procurement, or pass pressure on to consumers. If end-device shipments slow, memory price increases will shift from earnings leverage to demand pressure.
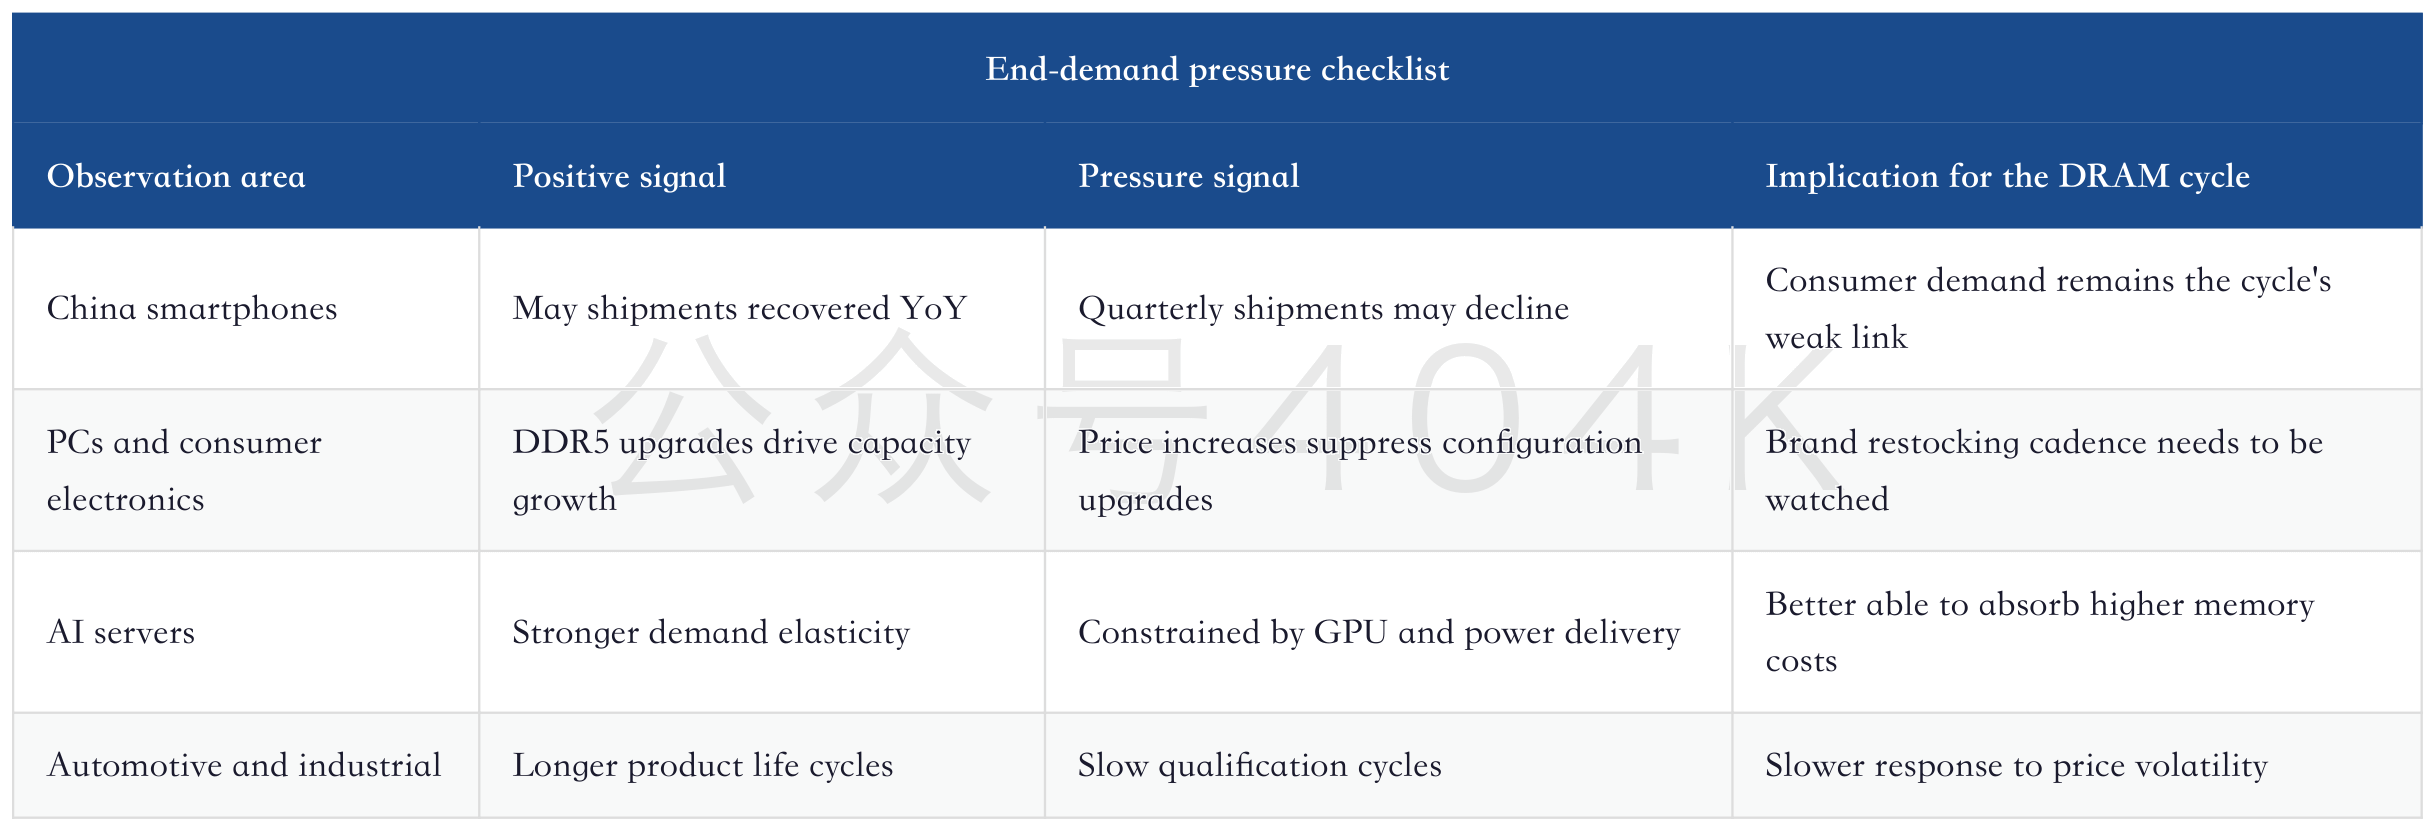
This means the quality of the rally in memory stocks must be assessed by category. AI-server and enterprise demand can better absorb memory price increases, while smartphones and PCs have weaker affordability. If demand over the next several quarters is supported only by AI servers, DRAM momentum can remain strong, but the market will pay more attention to suppliers' customer mix. If consumer demand also stabilizes, the breadth of the price cycle will improve.
6. Nanya Technology and Supreme: Legacy Memory Continues to Add Leverage
Nanya Technology's May revenue rose 730% YoY and has maintained high growth for several months, indicating that DDR4 and niche DRAM remain strong. Supreme Electronics' revenue also improved materially, with distribution data further confirming transmission through prices and orders. The importance of legacy memory is that it transmits the spillover effect from high-end AI demand into more mature categories.
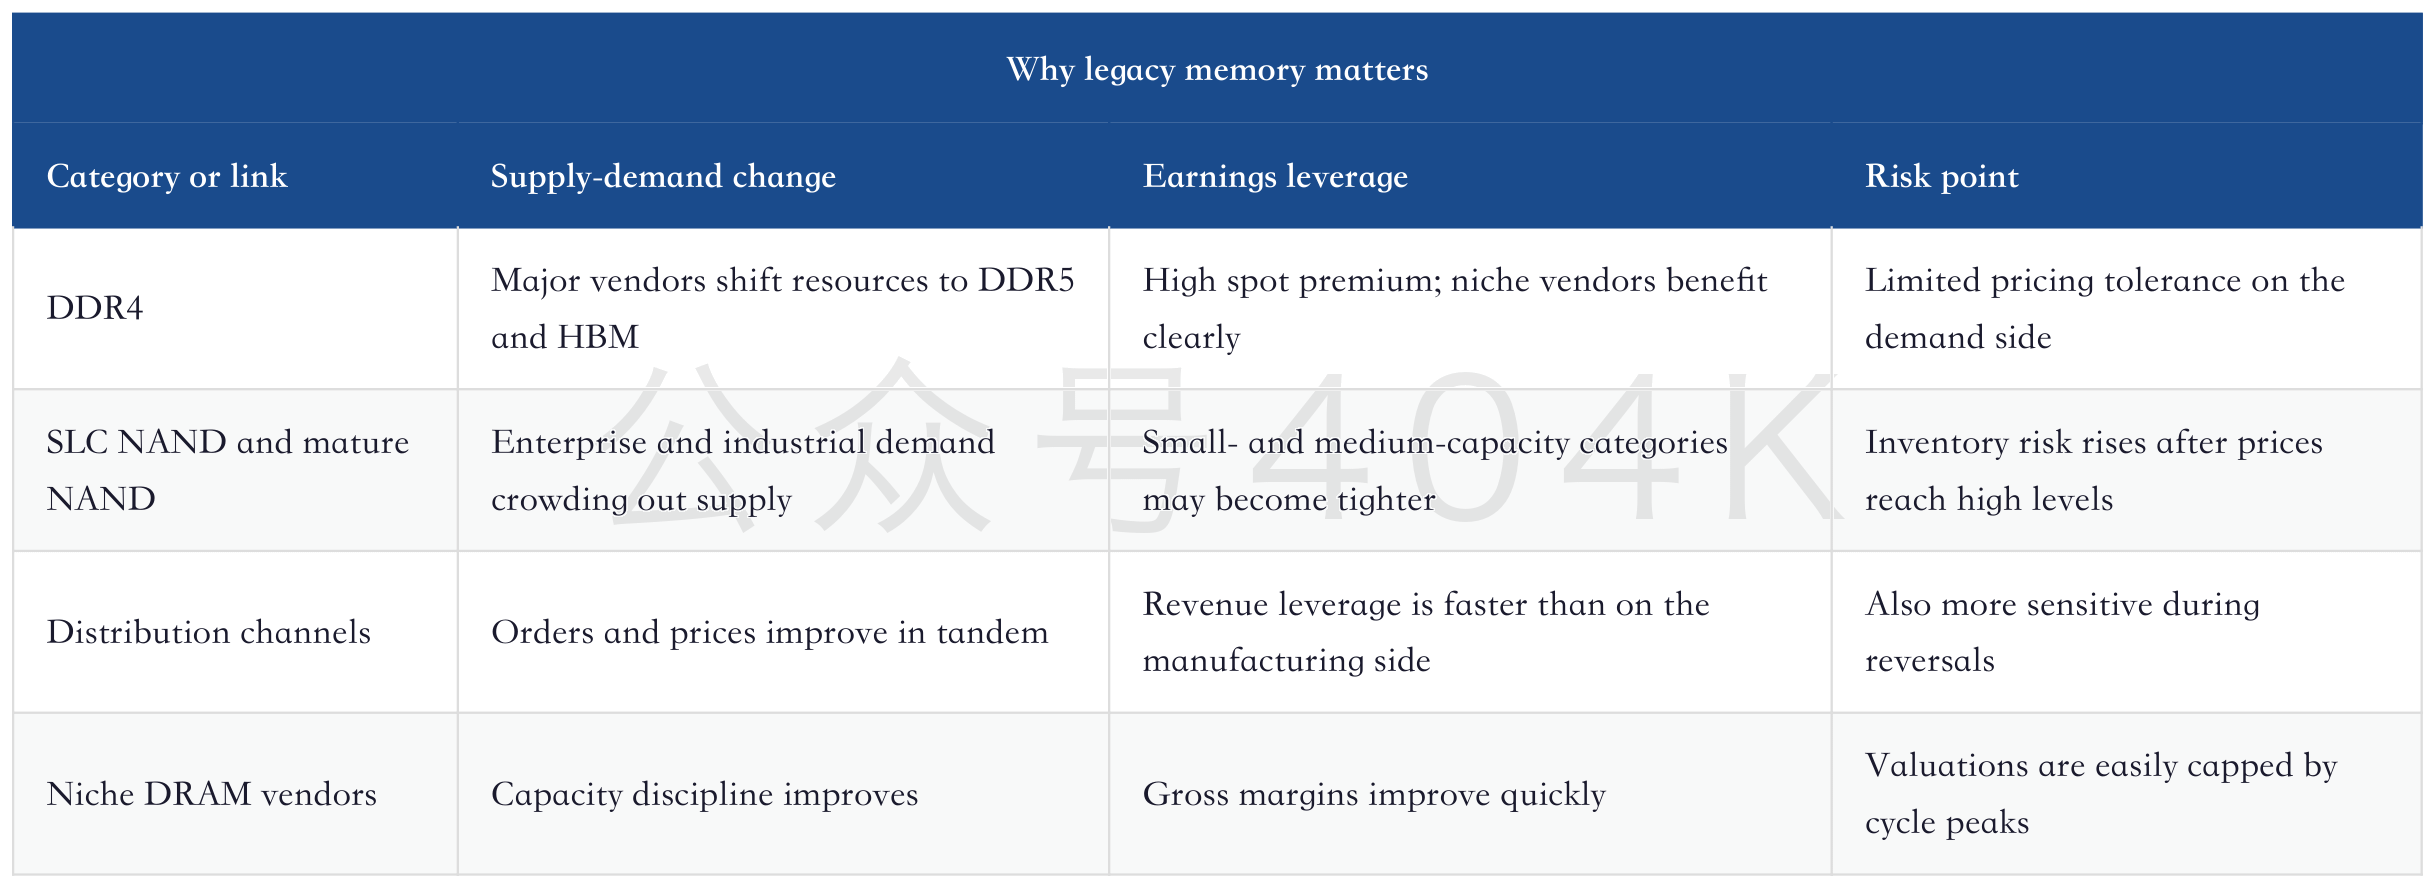
Legacy memory price increases explain why this rally is not concentrated only in HBM. HBM has the highest profit and the strongest strategic value, but DDR4, DDR5, SLC NAND, and distribution channels are faster thermometers for pricing changes. Goldman Sachs includes Nanya Technology and Supreme in its sentiment indicator precisely to avoid missing the pricing leverage in mature categories by focusing only on high-end AI memory.
Legacy memory also affects CapEx. If mature-category prices are strong, leading vendors may not be willing to rapidly add mature capacity in the near term because new supply could lower prices. But they will invest more actively in leading-edge nodes, HBM, and advanced packaging, directing resources toward products with higher gross margins and stronger customer lock-in. This makes "supply expansion" more structural rather than simultaneous expansion across all categories.
7. 2027 HBM: Goldman Sachs Raises the Forward Pricing Anchor Materially
The most informative statement from Goldman Sachs is its increase in Samsung Electronics' 2027 HBM price-growth assumption from 14% to 44%. On the surface, this is a model parameter change. In practice, it reflects a change in the HBM negotiation framework. The stronger conventional DRAM prices become, the harder it is for HBM customers to anchor negotiations to historical prices. The tighter HBM supply remains, the easier it is for suppliers to embed advanced packaging, yield ramp-up, and capacity-reservation costs into contracts.
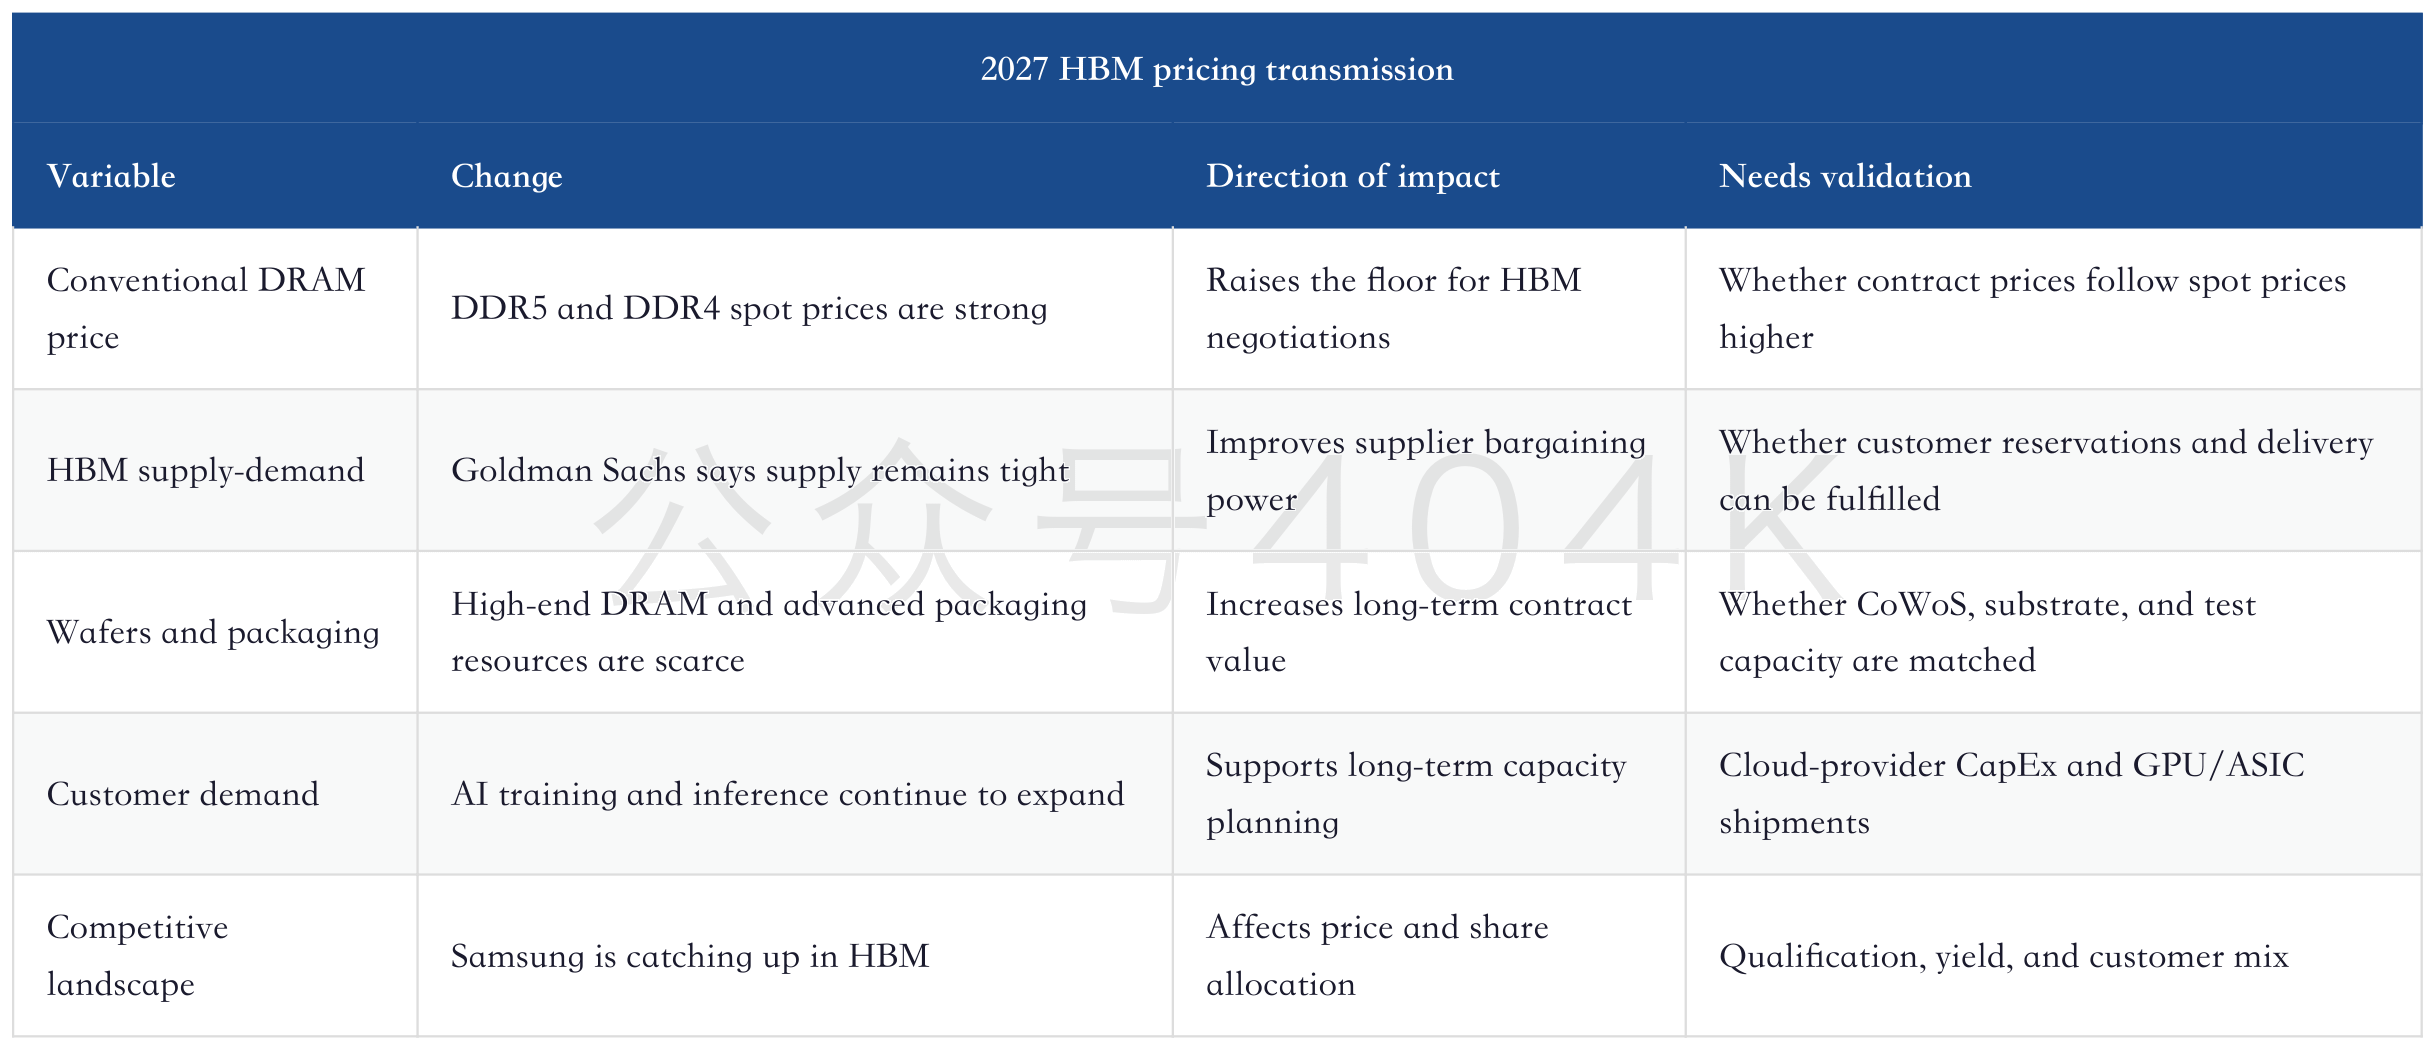
HBM is special because its price is jointly determined by customers, suppliers, and capacity resources. Customers need to lock in future supply, while suppliers need to invest advanced packaging and high-end DRAM resources. Negotiations between the two sides bring expectations for demand in the next one to two years into present valuations. Goldman Sachs' use of the phrase "tight HBM S/D" shows that its view on tight supply-demand has not loosened.
For Samsung Electronics, the upward revision to 2027 HBM pricing is especially important. Samsung has lagged SK hynix in HBM, and the market has long worried whether it can secure major-customer qualification and high-end share. If the HBM pricing center is higher, even a slower Samsung share ramp can amplify earnings leverage. If share and price improve together, valuation upside becomes larger.
8. Samsung's W2,450tn Investment: Long-Term Commitment, Near-Term Supply Still Constrained by Capacity Gates
Samsung Electronics announced W2,450tn of domestic investment for 2026-2040, including around W2,100tn for semiconductors, equal to 76% of the total. The numbers are large and can easily make the market worry about supply discipline. But Goldman Sachs' breakdown is more nuanced: the plan spans 15 years, may include R&D; spending, and most of the capital corresponds to existing fabs, advanced lines, HBM-related capacity, and new clusters.
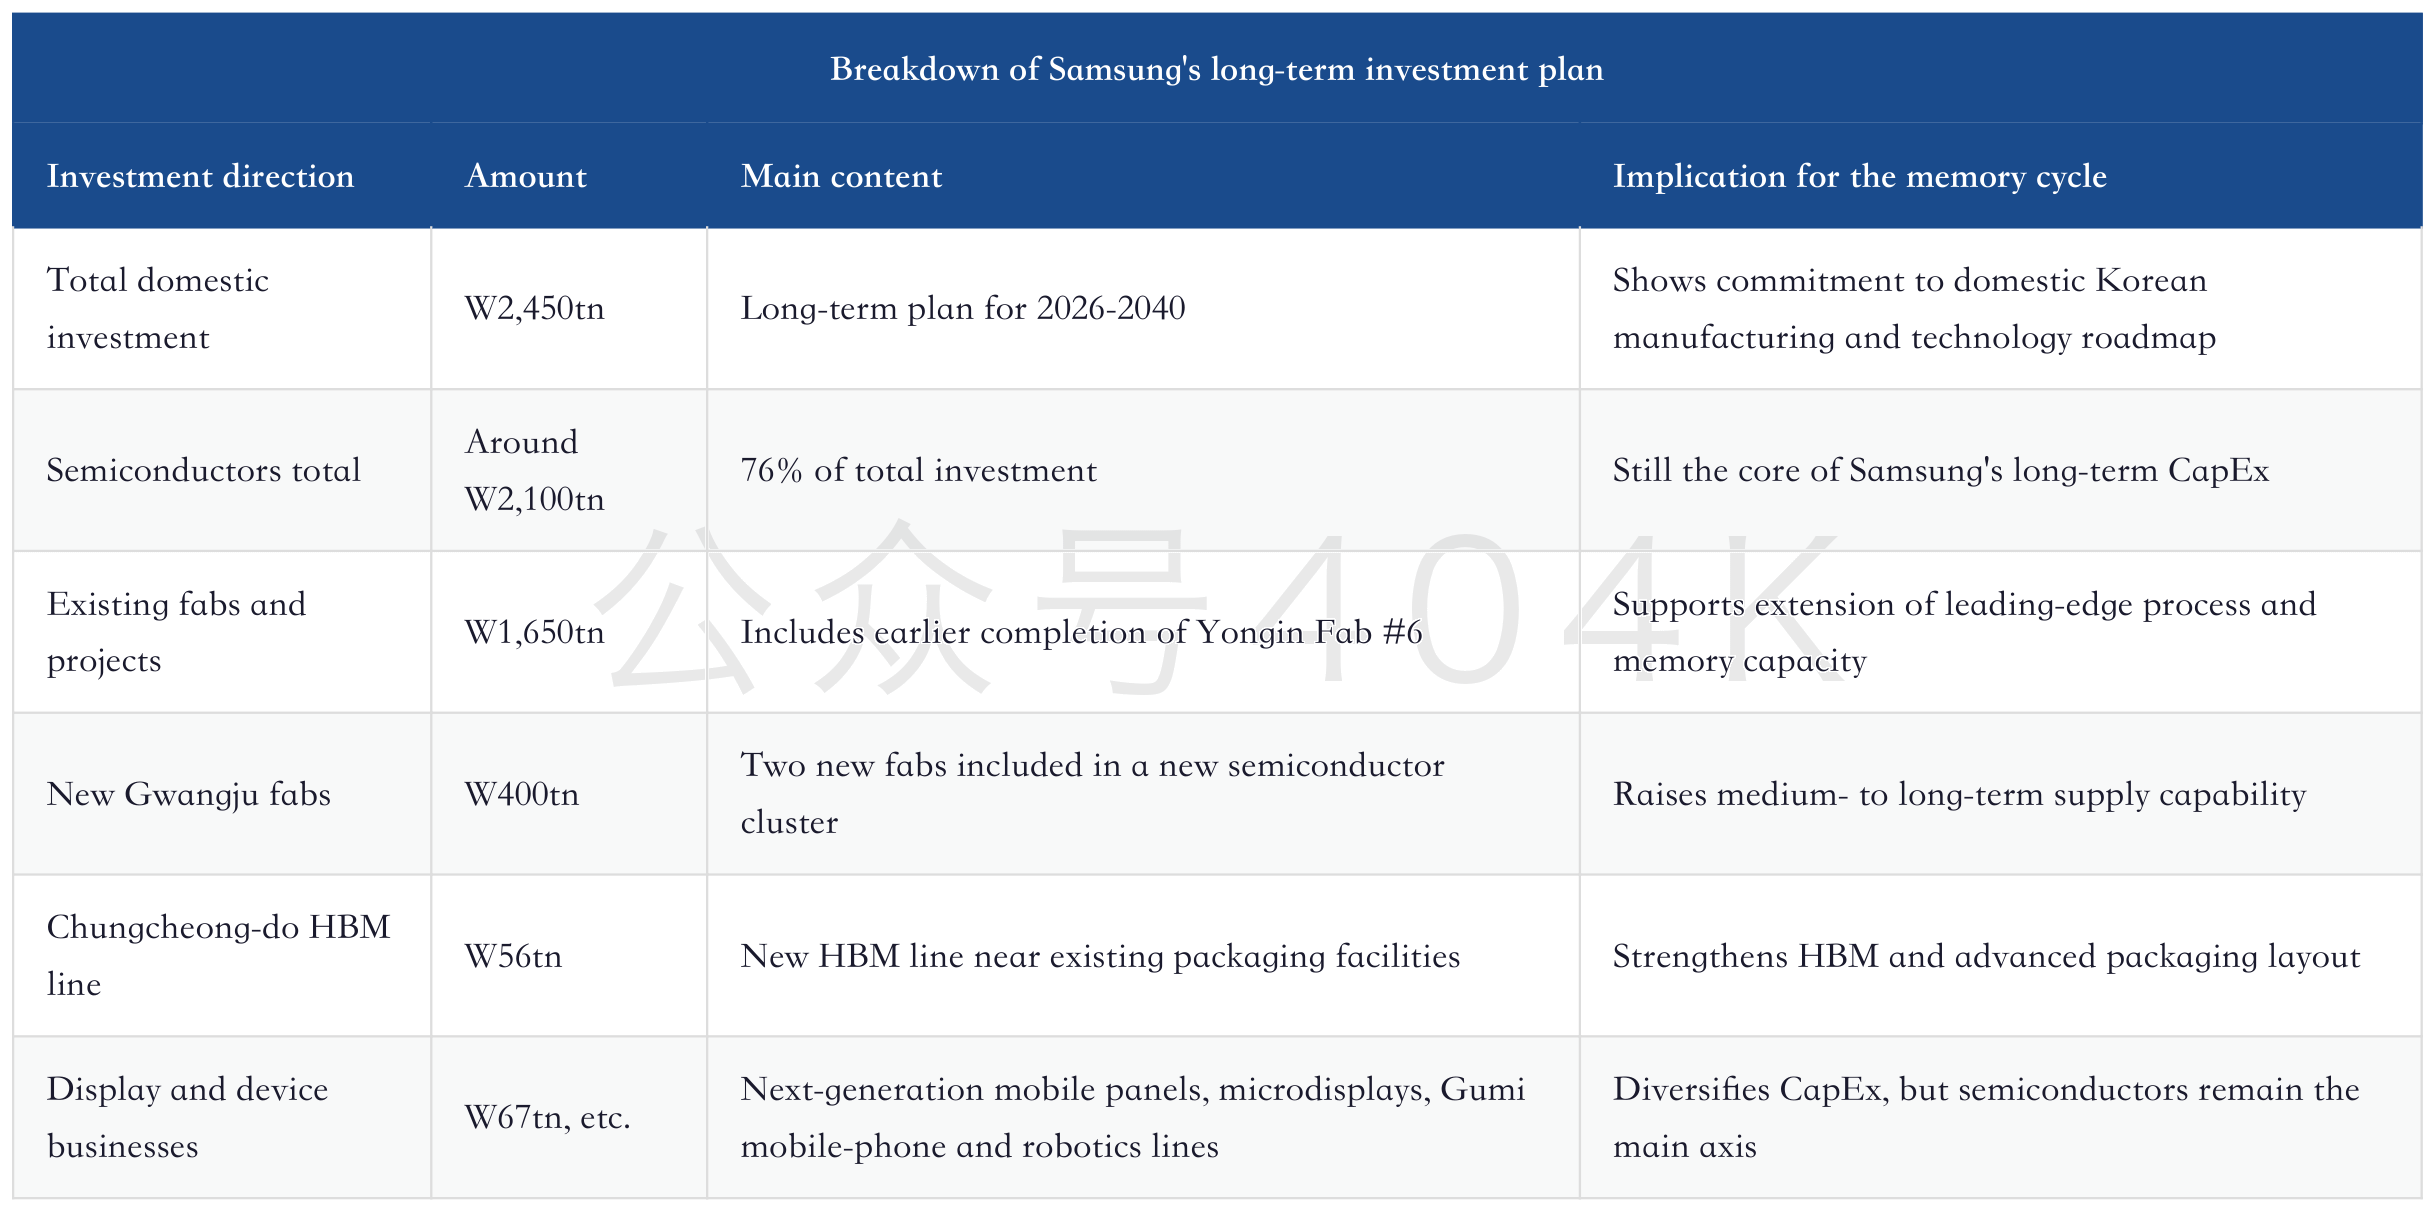
Goldman Sachs believes the plan's implied growth rate is reasonable, with the key being to view the investment on a long-term horizon. If R&D; is included, Samsung's domestic CapEx plus R&D; over the next 15 years averages around W163tn per year. In Goldman Sachs' existing forecasts, Samsung's consolidated CapEx plus R&D; for 2026-2028 is already at a high level. If domestic share is then assumed at around 80% and spending grows by roughly 6% after 2029, cumulative domestic investment approaches the announced scale.
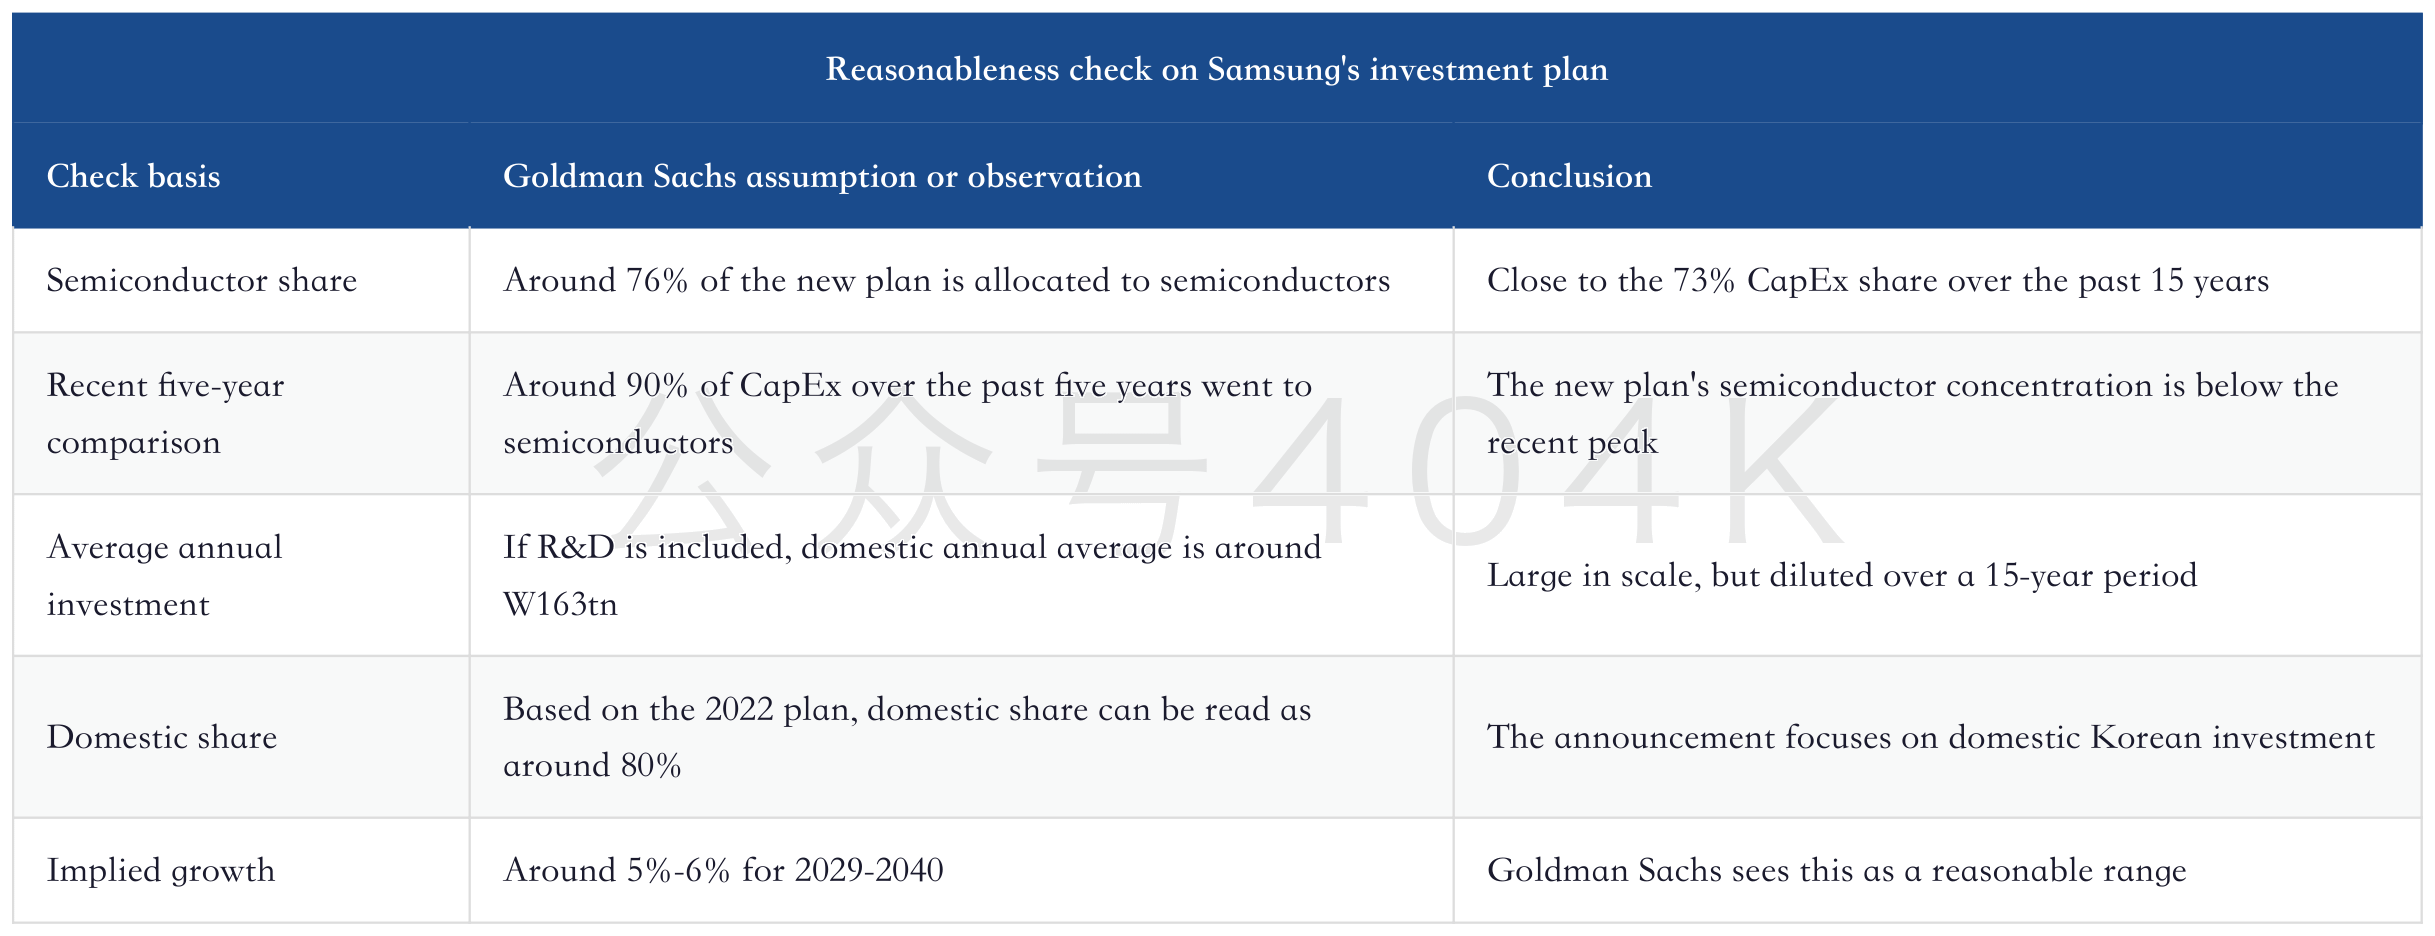
Two issues need to be separated here: long-term capacity commitment and near-term supply shock. Long-term investment plans improve forward visibility for equipment, materials, and advanced-packaging chains, but they do not immediately change 2026-2027 HBM supply-demand. Fab construction, equipment delivery, yield ramp-up, customer qualification, and contract lock-in all take time, especially because HBM is more constrained by advanced packaging and yield.
9. CapEx Discipline: The Market's Real Concern Is the Post-2028 Supply Shadow
Every memory upcycle faces the same question: once prices rise, will manufacturers start expanding capacity again? Samsung's W2,450tn plan is sensitive because it reinforces two narratives at the same time. The first is that AI memory demand is strong enough that leaders must prepare future supply. The second is that leaders are resuming CapEx, and supply may gradually increase over the next several years.
Both narratives are valid; timing is the key. In 2026-2027, the main supply bottlenecks are HBM, advanced packaging, yield, and customer qualification. Ordinary fab investment is unlikely to quickly change the outcome. After 2028, if CapEx keeps rising, equipment delivery is smooth, and customer-demand growth slows, supply pressure will become more visible. What the market needs to judge now is whether share prices reflect near-term pricing leverage or have already begun to reflect long-term supply risk.
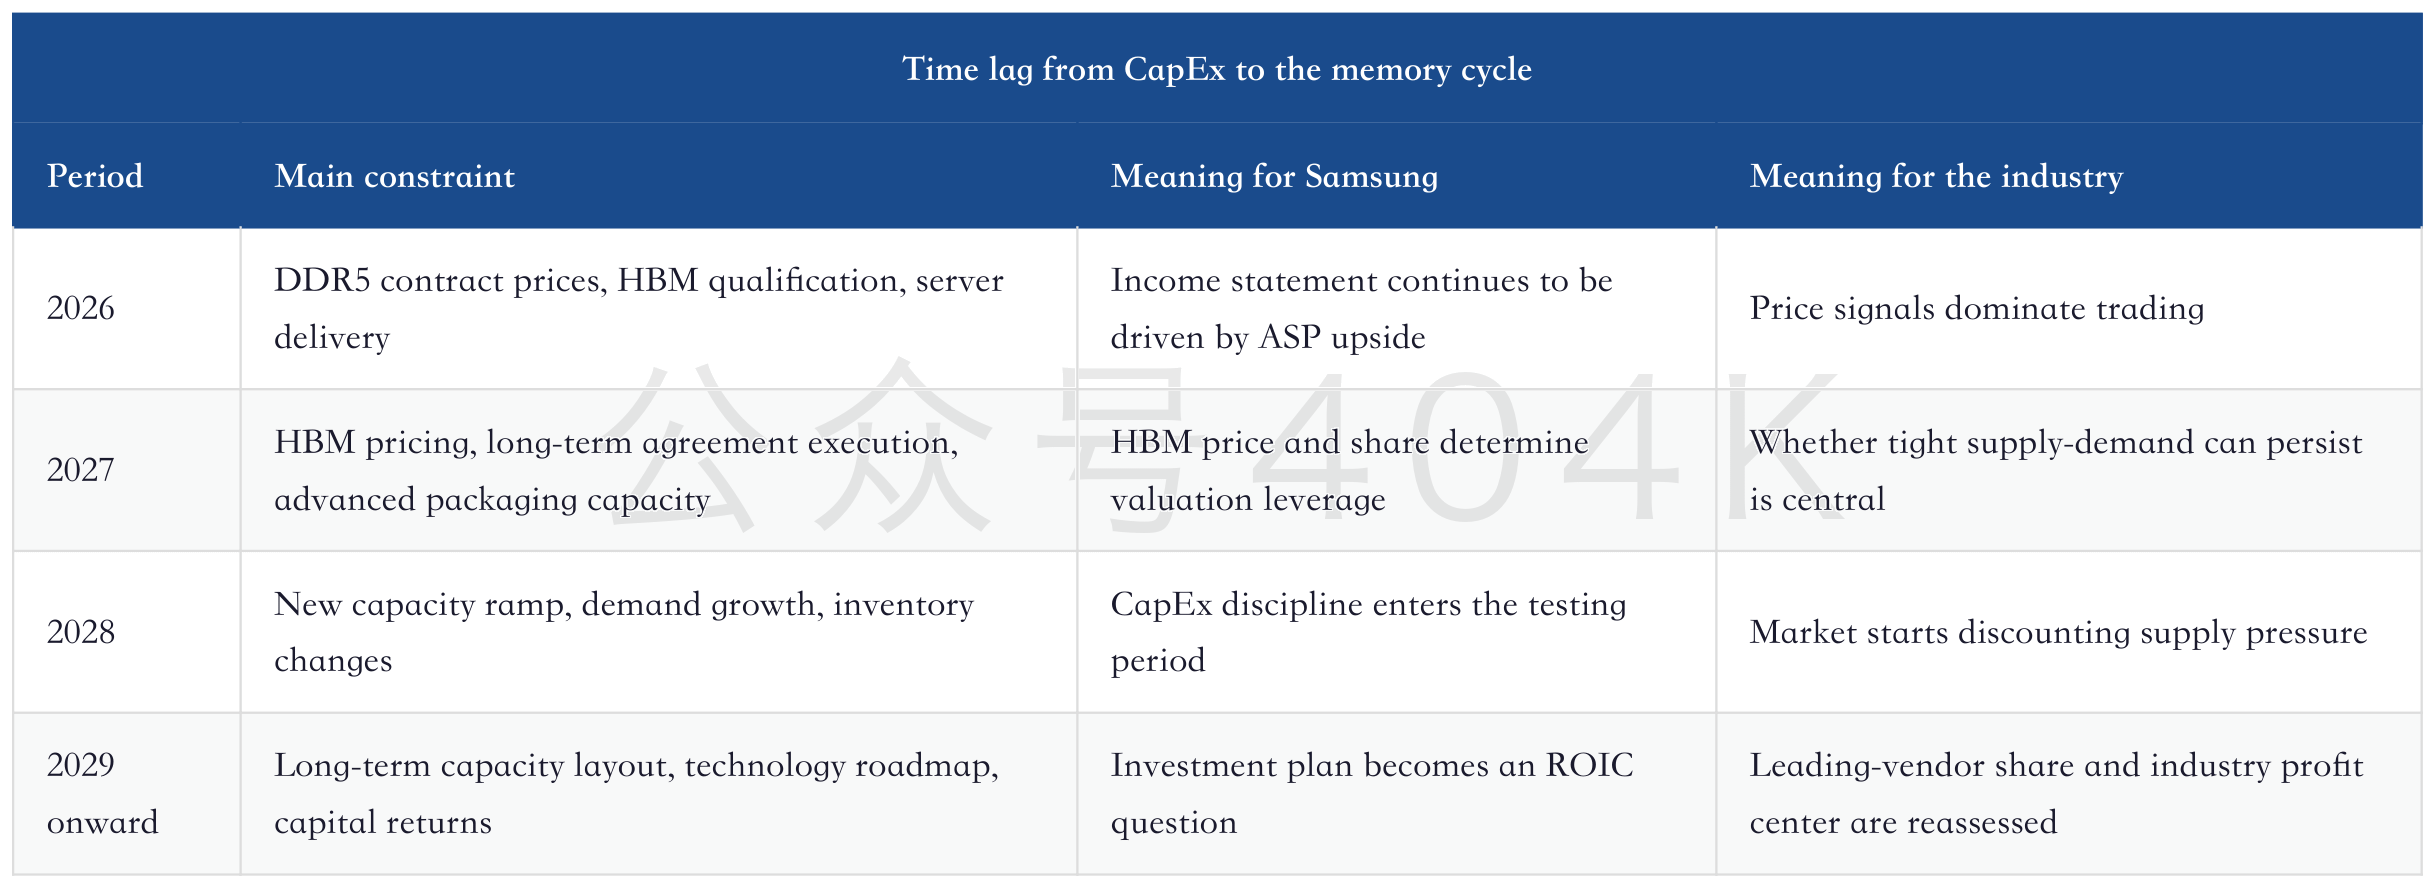
The easiest mistake in investment research is to treat a long-term CapEx plan as near-term capacity. Samsung's investment announcement does not mean DRAM supply increases immediately. But it will make the market ask questions about capital returns earlier. As long as prices are high, inventories are healthy, and free cash flow improves, long-term investment will be read as strategic investment. If prices fall, inventories build, and cash flow weakens, the same investment plan will be reinterpreted as supply risk.
10. Samsung Valuation: Goldman Sachs Is Focused on Memory Earnings, Long-Term Agreements, and Shareholder Returns
In its Samsung event note, Goldman Sachs maintained positive ratings on the common and preferred shares and set 12-month target prices of W480,000 for the common shares and W360,000 for the preferred shares. The report uses an EV/EBITDA-based SOTP framework, with the core also including the earnings leverage, free cash flow, and shareholder-return assumptions behind the target prices.
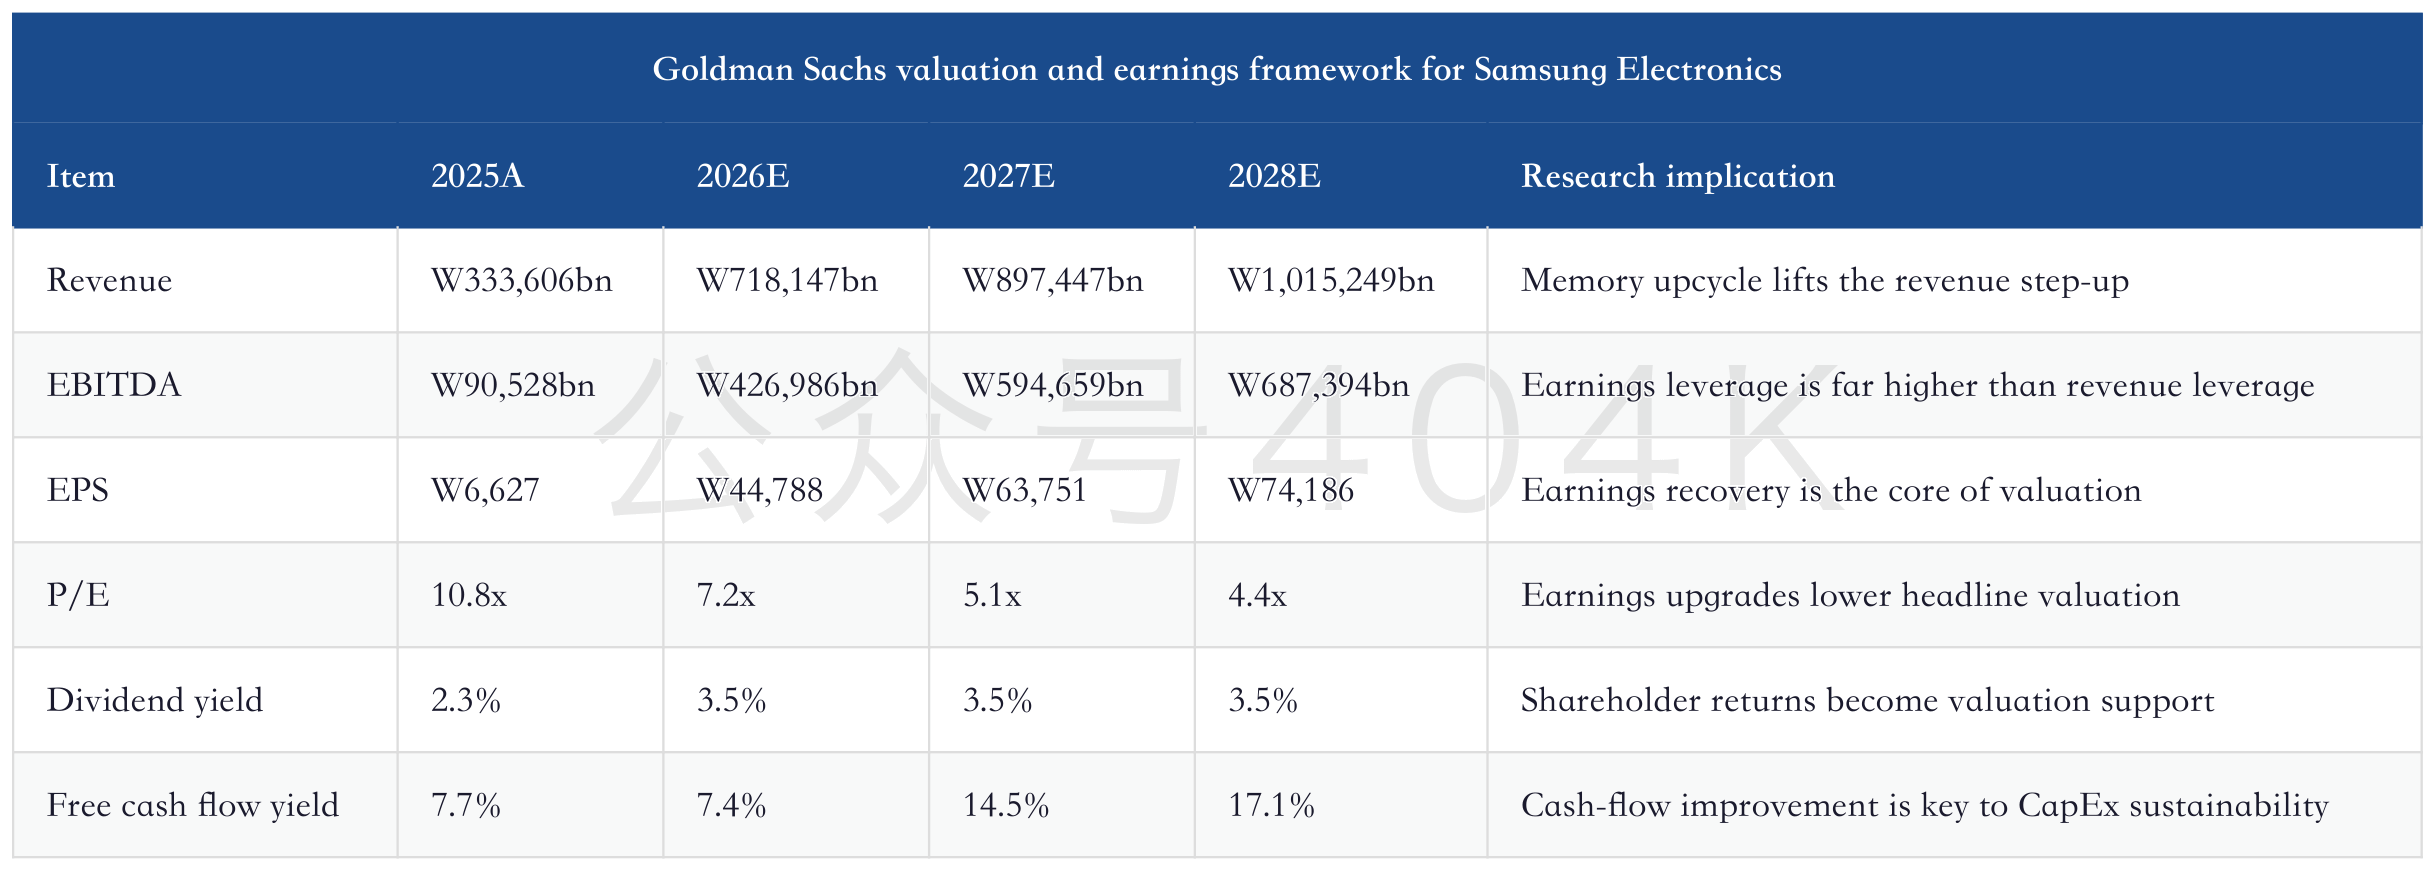
This table shows that Samsung's valuation leverage comes not only from price increases, but also from margin, cash flow, and capital returns. If DRAM and HBM prices remain high, Samsung's income statement will recover faster than its revenue line. If free cash flow follows, the company can both invest in HBM and advanced capacity and maintain shareholder returns. Goldman Sachs' emphasis on higher long-term agreement coverage indicates that it believes the strength of customer contract commitments in this cycle may be higher than in past cycles.
Samsung's risks are also clear. First, deterioration in memory supply-demand would directly hit prices and margins. Second, if smartphone margins compress, group earnings quality would suffer. Third, if mobile OLED share falls, support from non-memory businesses would weaken. For the market, the real debate is whether Samsung's memory improvement can offset CapEx and volatility in non-memory businesses.
11. Long-Term Agreements and HBM Customer Lock-In: Can This Cycle See Less Inventory Swing?
Goldman Sachs notes in its Samsung investment thesis that customer obligations in long-term agreements may be stronger than in the past. This is crucial. The classic problem in the memory industry has been the inventory cycle: customers place early orders when prices rise, then destock when prices fall, causing large swings in supplier profits. If long-term agreement coverage improves, memory vendors can lock in volumes, prices, and capacity allocation earlier.
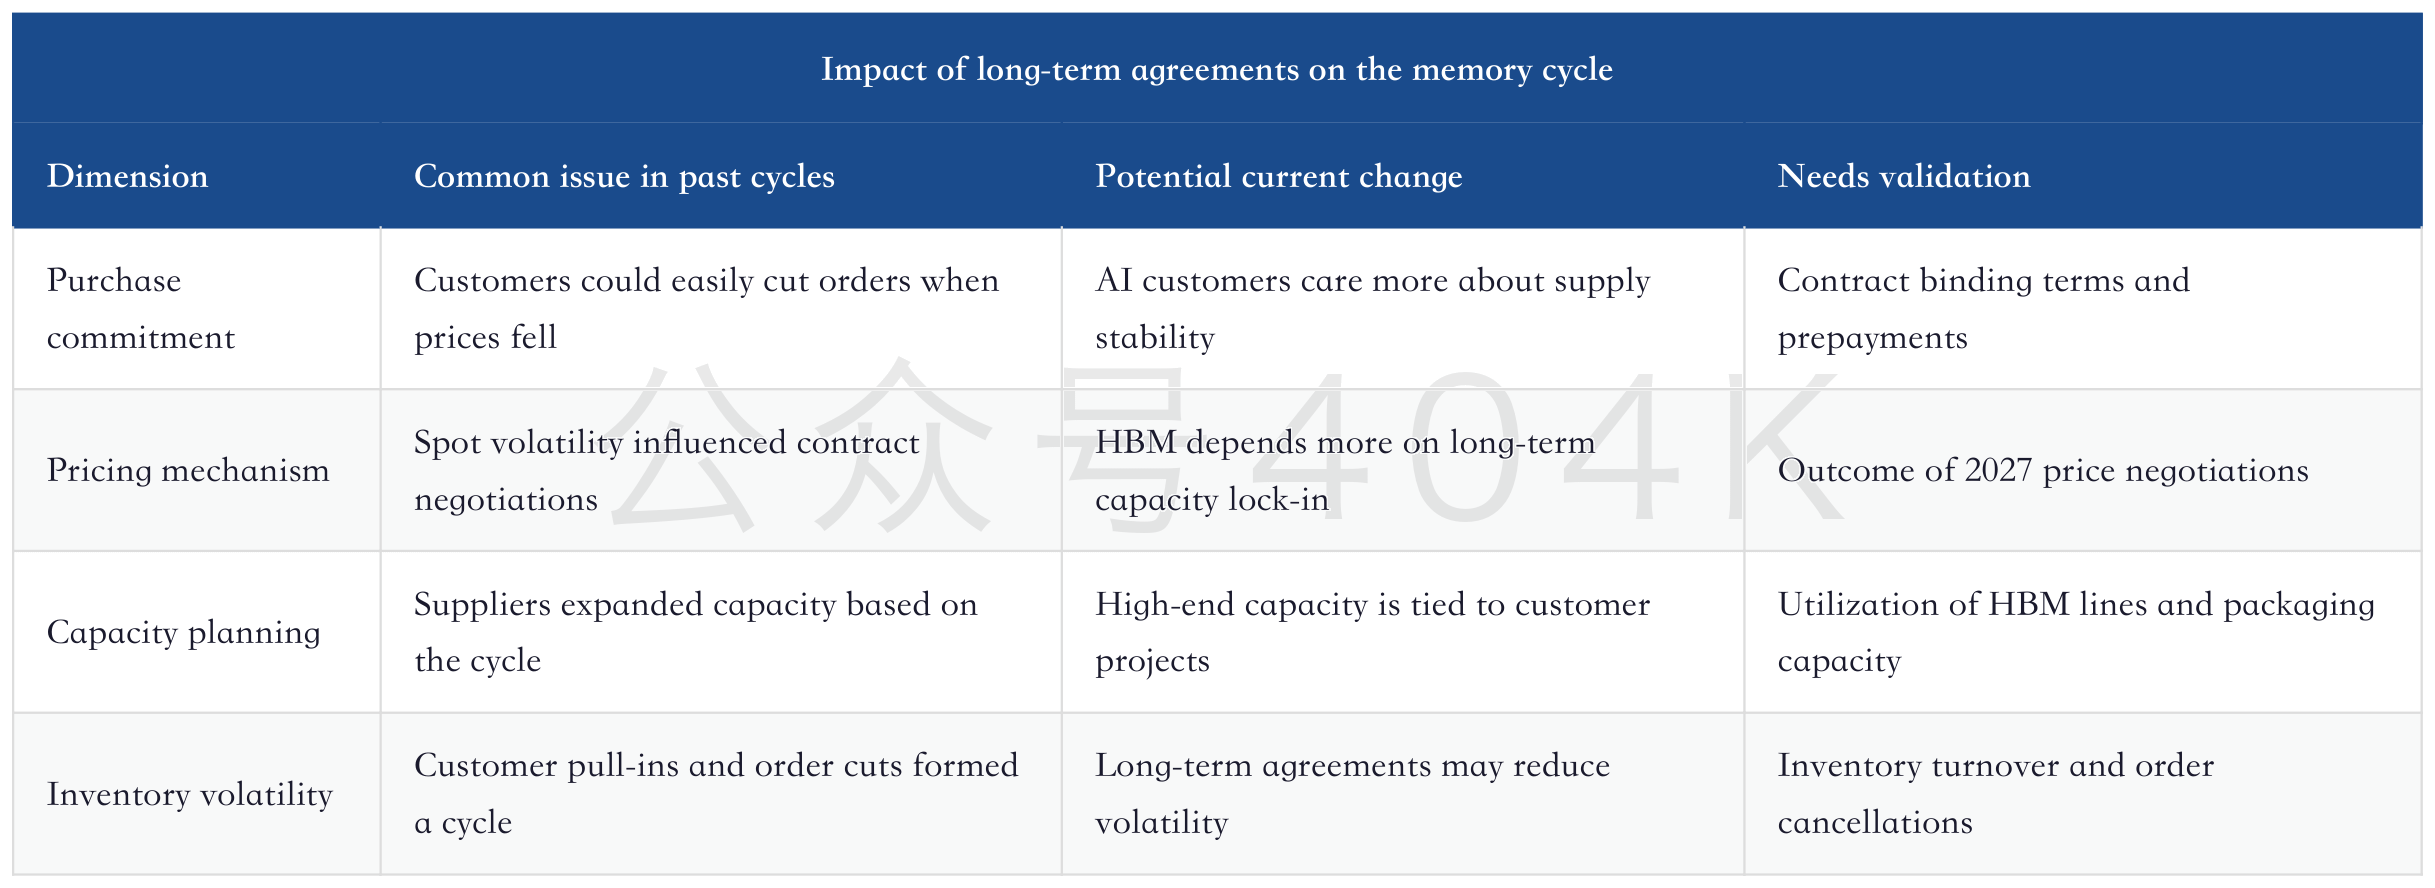
AI-server customers are different from ordinary consumer-electronics customers. Cloud providers care more about certainty in the delivery of training clusters and inference services. Memory shortages can affect system go-live and monetization of compute capacity, so they are more willing to lock in supply. HBM is also harder to substitute than standard DRAM, has a longer qualification cycle, and creates stronger supplier-customer binding. These factors may all reduce the amplitude of the traditional inventory cycle.
But long-term agreements do not eliminate the cycle. If customer CapEx contracts in the future, or if the pace of AI compute buildout slows, contracts will also be renegotiated. The more reliable research approach is to look at long-term agreements, shipments, inventory, and cash flow together. Long-term agreements improve earnings visibility, inventory and cash flow validate earnings quality, and pricing validates supply-demand tightness. Missing any one of the three affects valuation.
12. Equipment Chain: Samsung's Long-Term Investment Gives WFE and Advanced Packaging Longer Order Visibility
Samsung's W2,450tn plan may matter more directly for the equipment chain than for near-term DRAM prices. Fabs, HBM lines, advanced packaging, and new display lines all require equipment, materials, substrates, testing, and automation systems. Even if the investment cadence is extended, the long-term CapEx commitment will improve order visibility for the equipment chain.
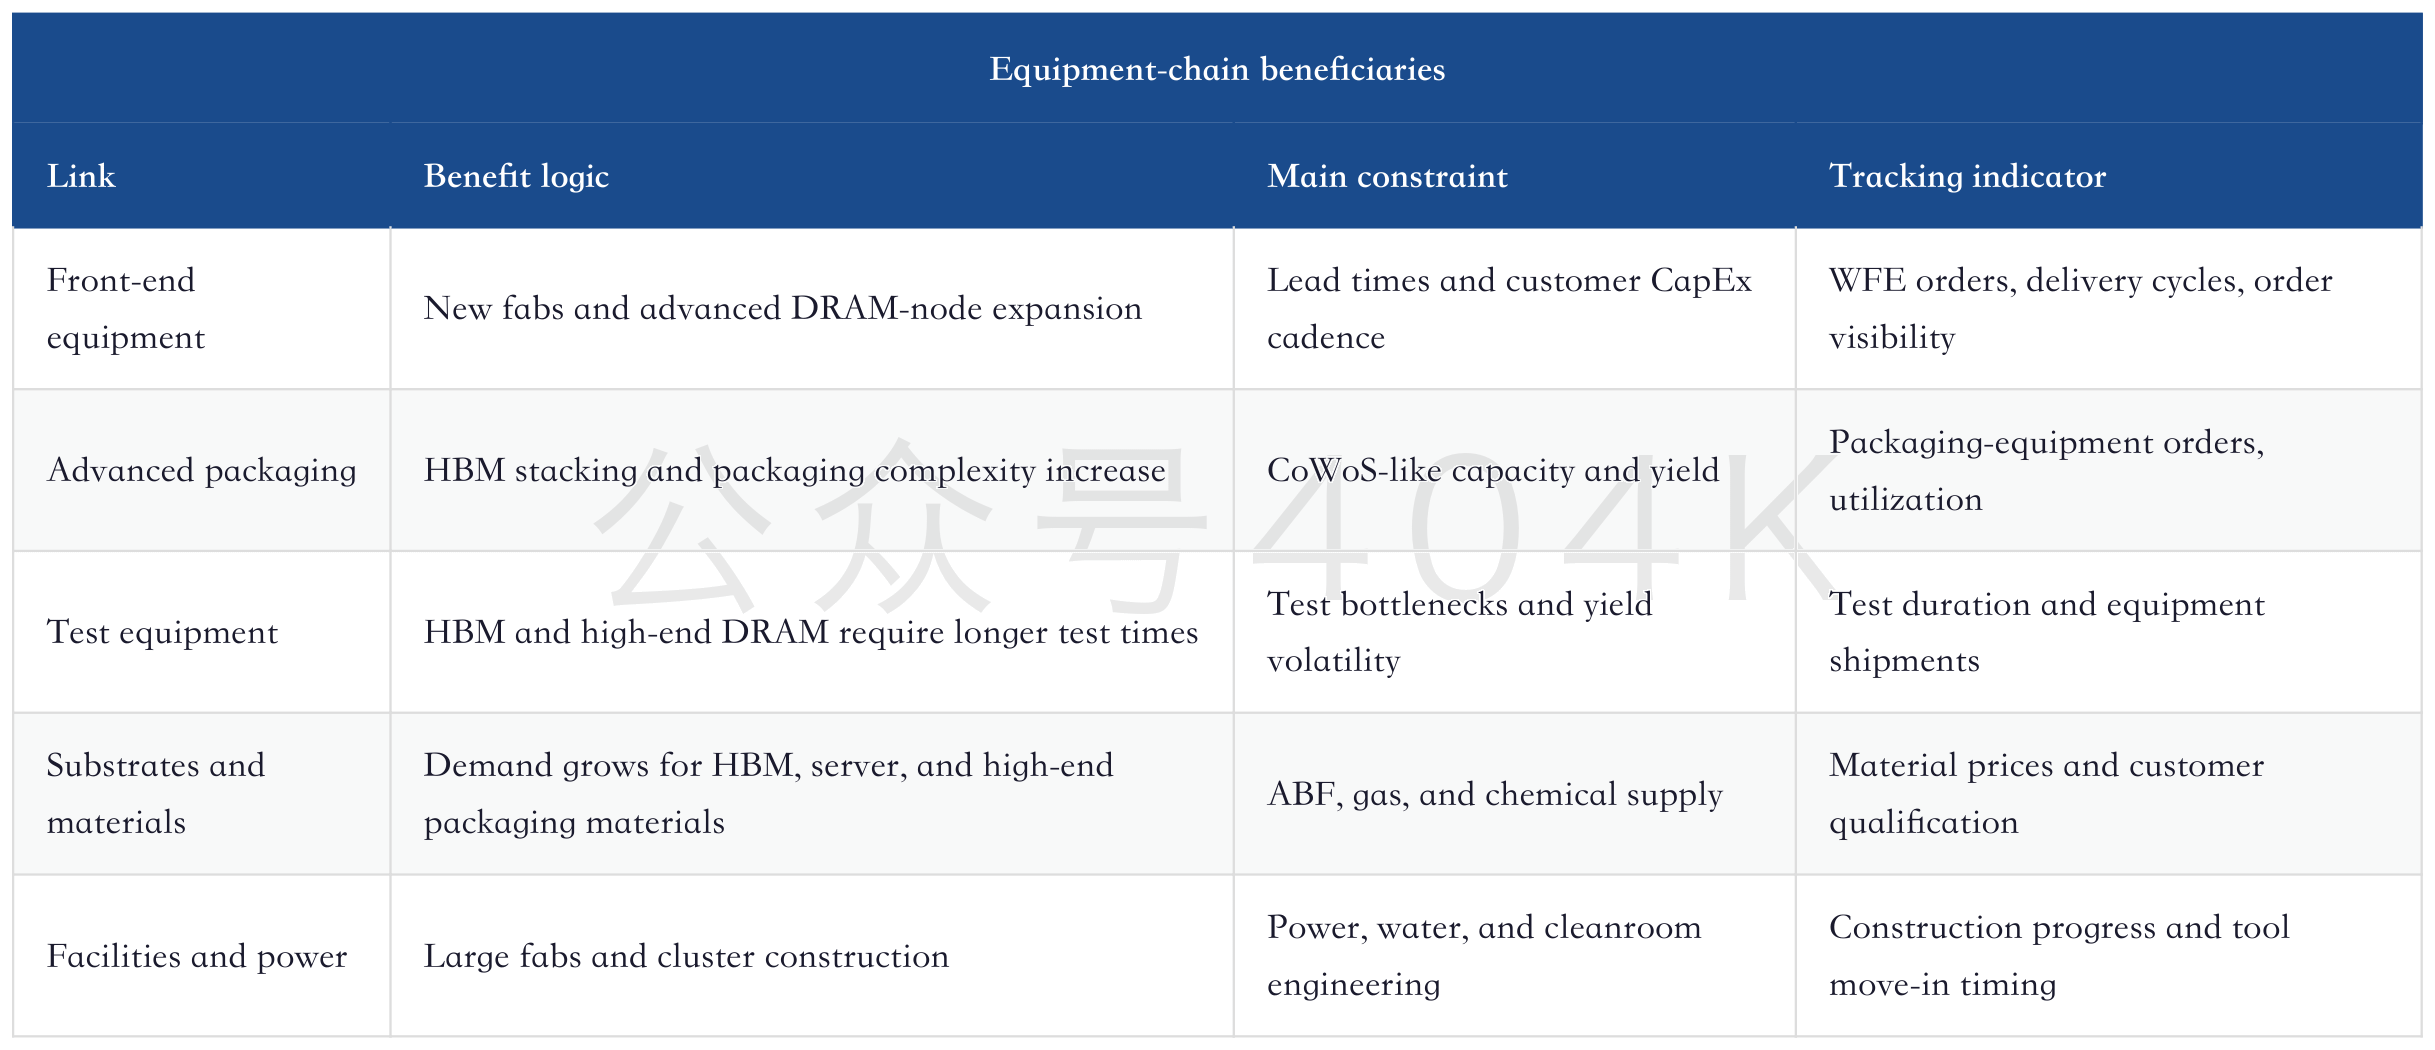
For equipment stocks, the best combination is strong prices, strong customer cash flow, and disciplined CapEx. Strong prices mean memory vendors are making money. Strong customer cash flow means investment capacity exists. Disciplined CapEx means expansion will not break the industry too quickly. Samsung's plan satisfies the first two conditions; the third will need to be validated by the subsequent order cadence.
The equipment chain will also be affected by changes in the HBM mix. HBM relies more than ordinary DRAM on advanced packaging, testing, and yield control. It has higher value per unit and a more complex equipment structure. As a result, even if total wafer capacity growth is not extreme, a higher HBM mix can drive higher equipment and materials content. This is one of the biggest differences between the AI memory cycle and the traditional memory cycle.
13. Samsung, SK hynix, Micron, and Niche Vendors: Same Price Cycle, Different Valuation Logic
In this memory upcycle, the logic differs materially by company. Samsung Electronics is about HBM catch-up, group cash flow, and long-term CapEx. SK hynix is about leading HBM share and AI-customer lock-in. Micron is about US AI customers, HBM qualification, and DDR5 earnings leverage. Niche vendors such as Nanya Technology are about DDR4 and legacy-memory price increases. Goldman Sachs' DRAM sentiment indicator connects these themes, but they should not be collapsed into a single trade.
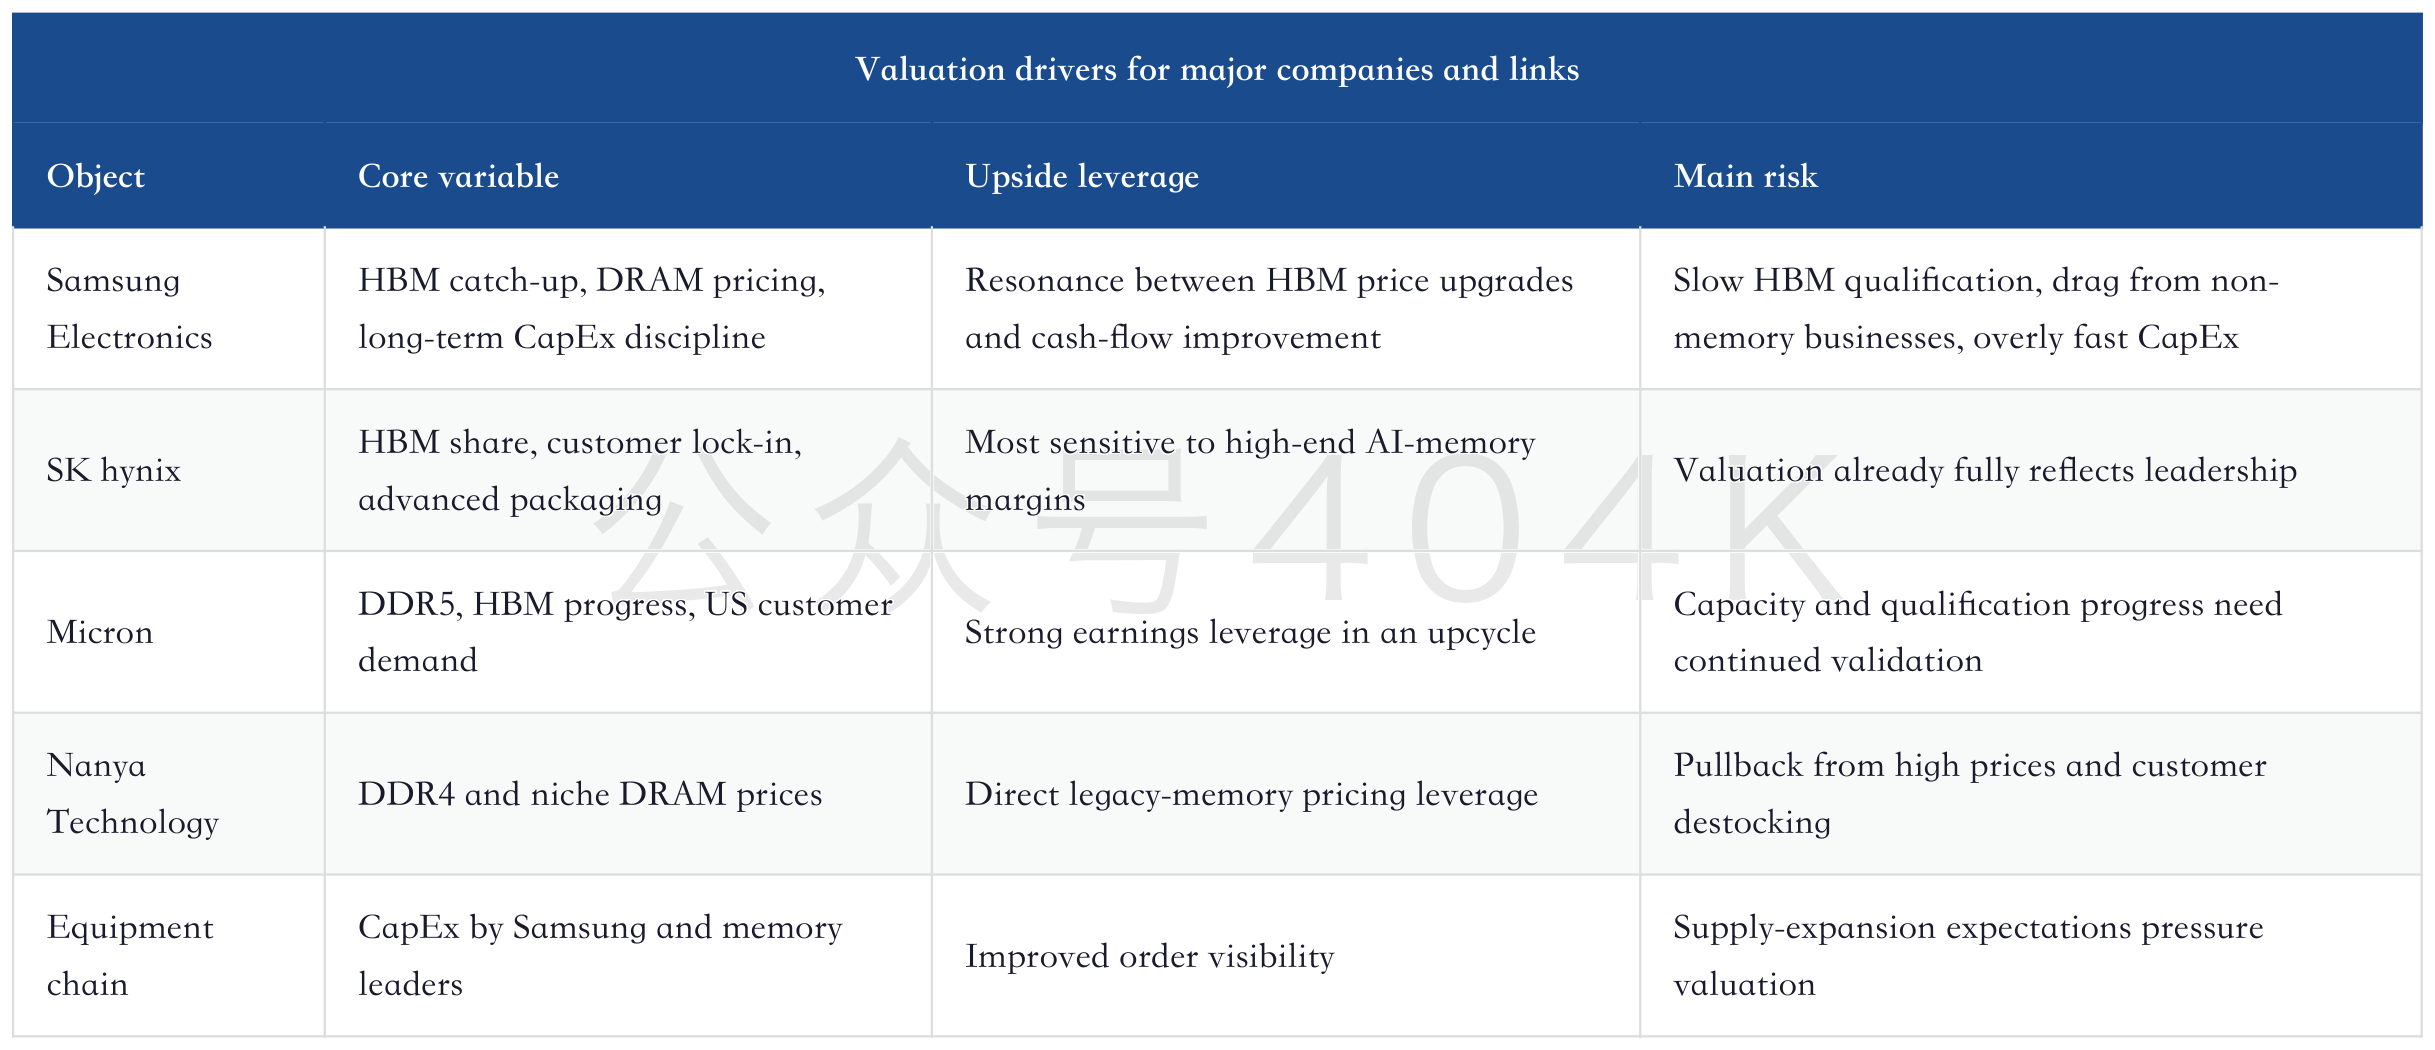
This order helps explain Goldman Sachs' report structure. It does not look only at Samsung or only at HBM. Instead, it combines conventional DRAM, legacy memory, the server chain, and channel feedback through the sentiment indicator. For the market, Samsung Electronics is more like a "full-spectrum memory asset": it has HBM catch-up leverage, benefits from ordinary DRAM price increases, and also carries long-term CapEx and diversified group businesses. Its strength is breadth, and its weakness is also breadth. A single variable cannot fully explain its share price.
14. Three Worldviews: Price-Increase Cycle, AI-Memory New Normal, and Post-CapEx Cycle
Over the next 12 to 24 months, the memory industry may switch among three worldviews. The first is a price-increase cycle: prices rise, inventories decline, earnings recover, and the market values the sector as traditional cyclicals. The second is an AI-memory new normal: HBM and DDR5 demand stays above supply, long-term agreements and customer lock-in improve earnings visibility, and the market treats memory leaders as core AI-infrastructure assets. The third is a post-CapEx cycle: leaders increase investment, forward supply pressure rises, and the market compresses valuations in advance.
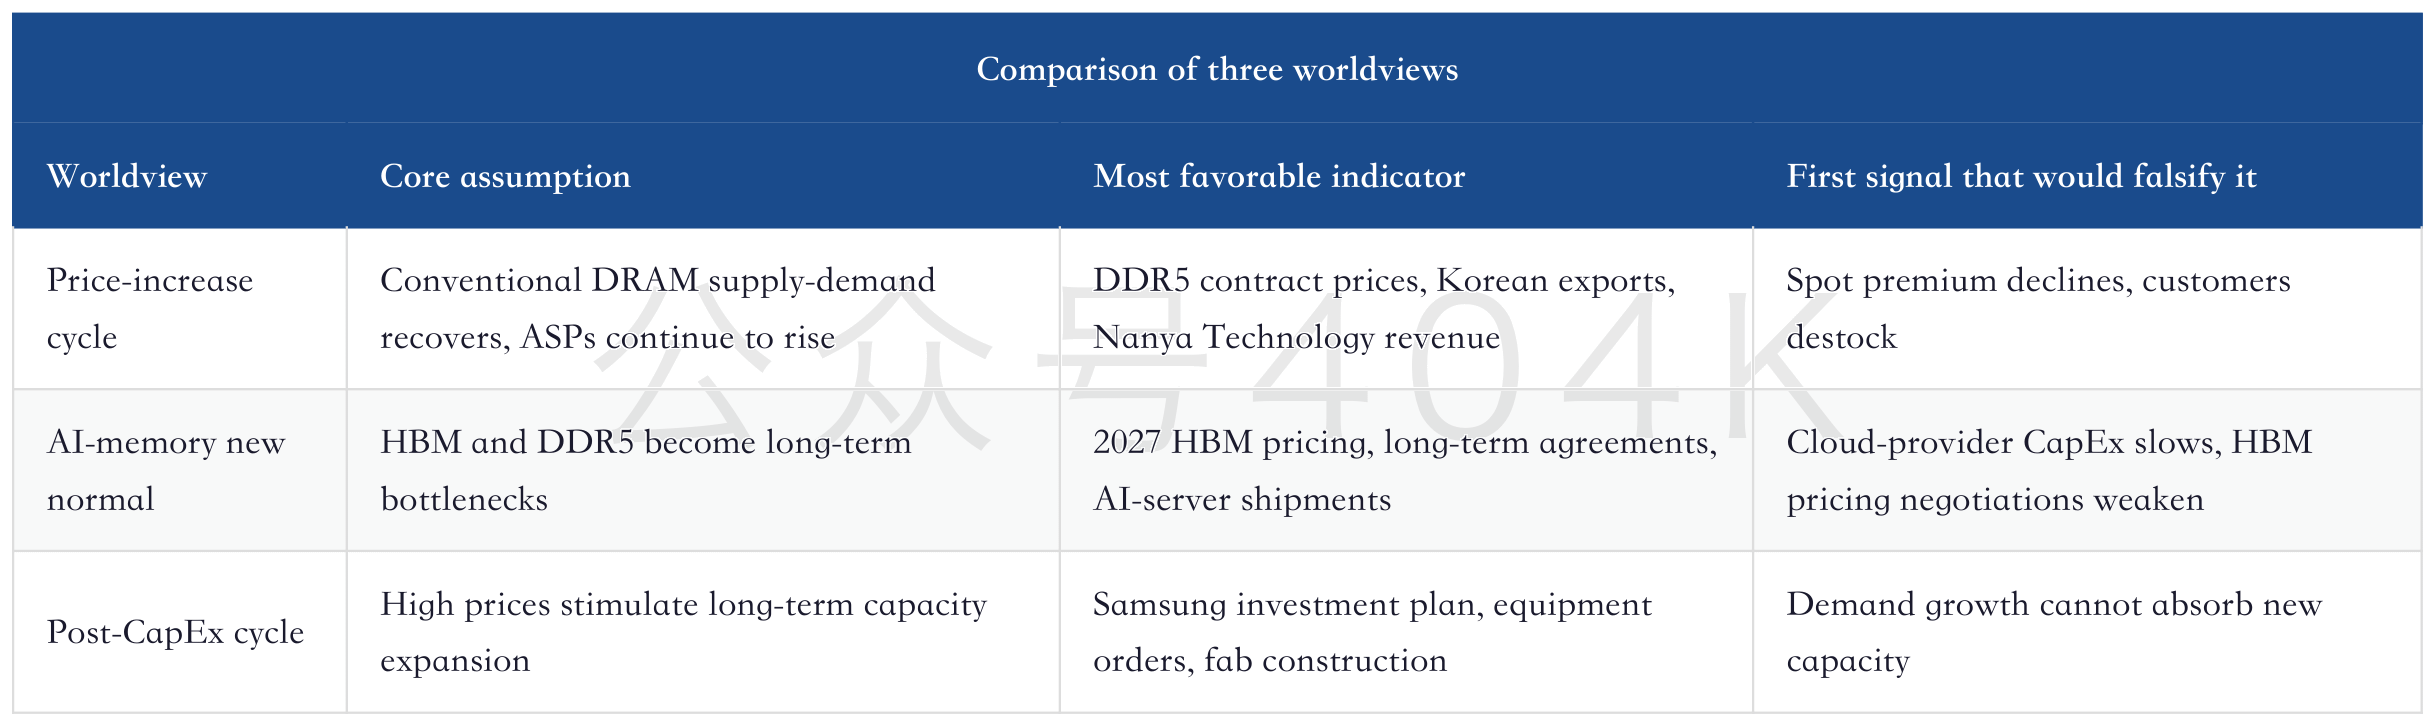
Current evidence better supports a crossover between the first two worldviews. DDR5 and DDR4 price increases show that the traditional cycle is still present, while the HBM price upgrade shows that the AI-memory new normal is being incorporated into models. The risk of a post-CapEx cycle has appeared, but it is not yet the near-term dominant factor, because new capacity takes time to come online and HBM bottlenecks are not only in fabs.
This framework also explains why memory stocks can be highly volatile. As long as price data remain strong, the market will value the sector through the price-increase cycle and the AI-memory new normal. Once CapEx becomes too fast, inventories rise, or end-device shipments weaken, the market can immediately switch to the post-CapEx-cycle worldview. Investment research needs to rotate dynamically among these three worldviews rather than use one story for every stage.
15. Model Bridge: From DDR5 Spot Prices to Samsung Valuation, There Are Six Gates
There is a clear model bridge between the two Goldman Sachs reports. DDR5 spot-price increases first affect expectations for contract prices. Contract prices enter the income statements of Samsung and peers. Income-statement improvement lifts cash flow. Cash flow supports CapEx and shareholder returns. CapEx then feeds back into future supply expectations. HBM price upgrades act as an amplifier on this bridge.
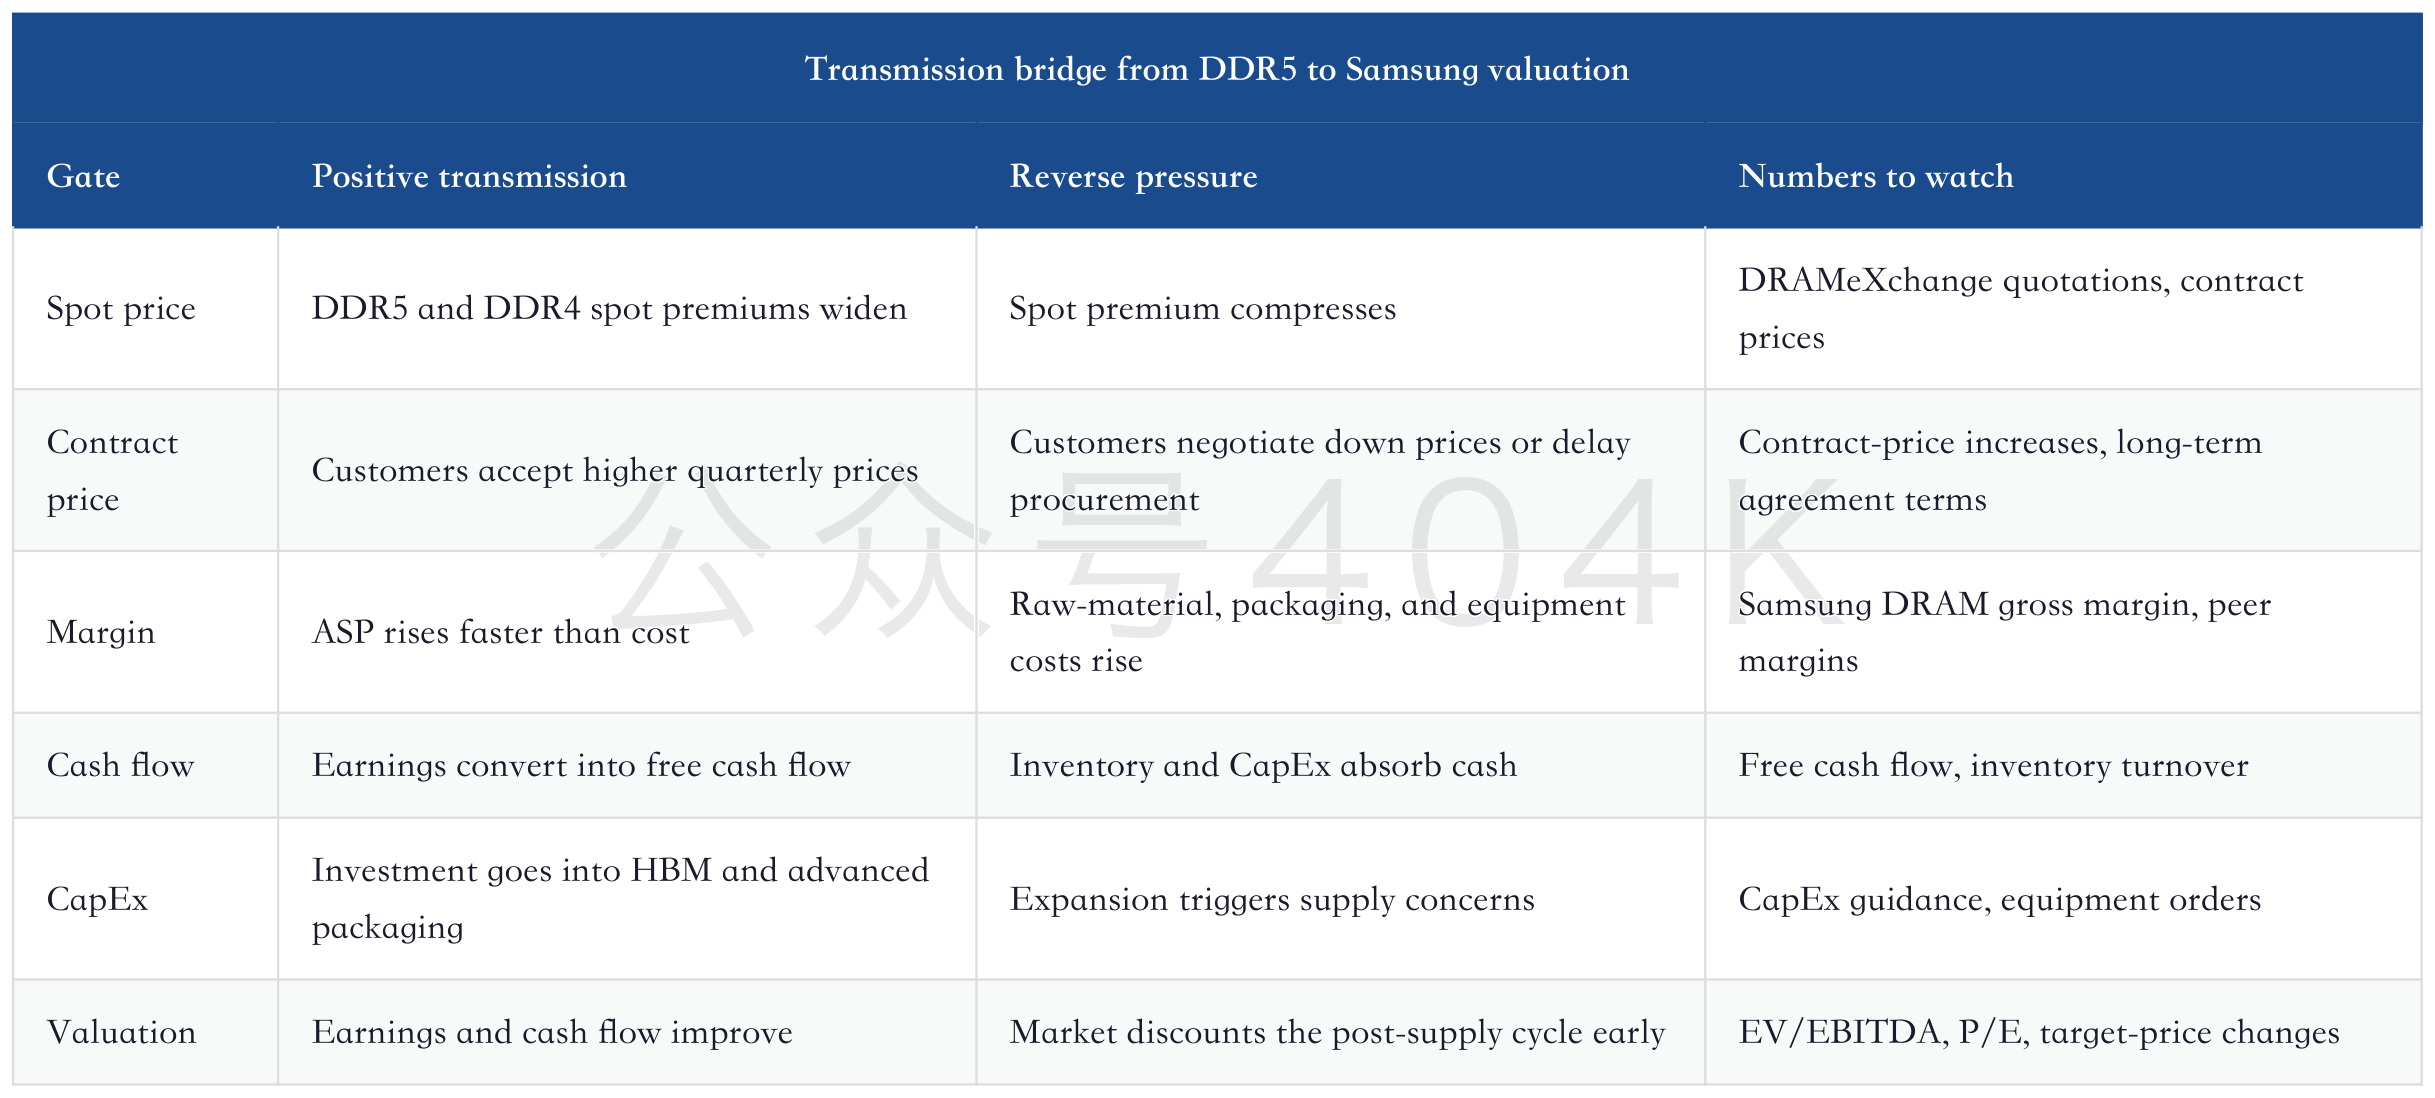
The weakest link in this bridge is usually cash flow. In upcycles, the memory industry can easily show attractive earnings while inventories rise and cash flow lags. If Samsung's earnings recovery is accompanied by free-cash-flow improvement, the market will be more willing to believe this cycle is higher quality. If earnings improvement is consumed by CapEx and inventory, the long-term investment plan will become valuation pressure.
HBM changes the slope of the bridge. Ordinary DRAM price increases mainly affect ASP. HBM price upgrades simultaneously affect product mix, customer lock-in, and long-term margins. If Samsung continues to advance in HBM qualification and share, valuation will focus more on the 2027 and 2028 earnings step-up. If HBM progress is below expectations, the market will put Samsung back into a conventional DRAM-cycle framework.
16. Disconfirmation Checklist: Signals That Would Cool This Re-Rating
The memory re-rating has obvious two-way leverage. Current prices, exports, and server-chain data are strong, but disconfirming signals need to be listed in advance. The most important disconfirmation is not one month of price volatility, but multiple indicators weakening at the same time: spot-premium compression, difficulty raising contract prices, inventory increases, weak smartphone and PC demand, lower-than-expected HBM pricing negotiations, and an overly fast Samsung CapEx cadence.
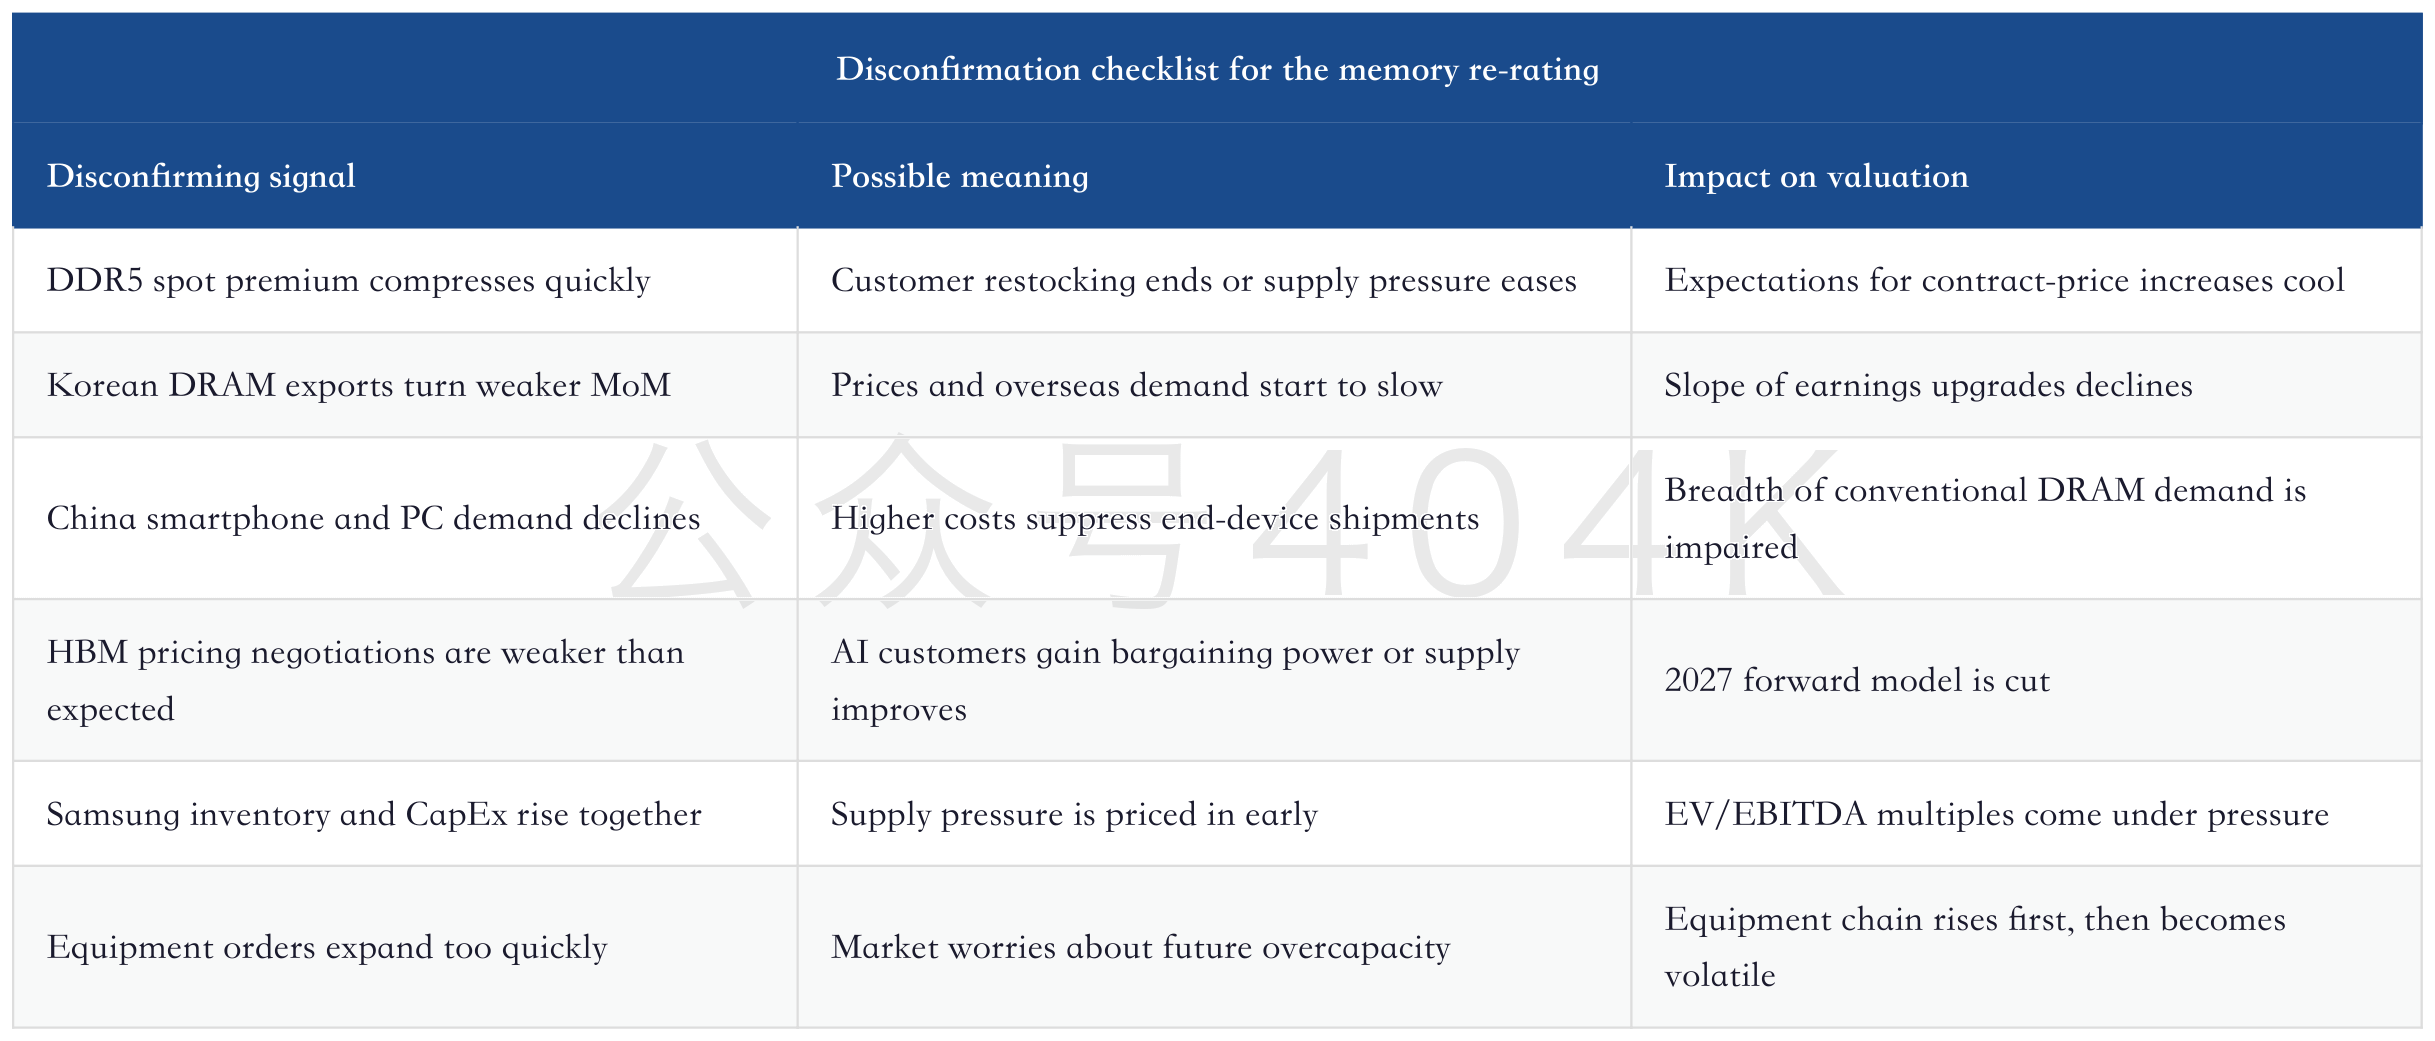
The purpose of this checklist is to avoid attributing every increase to "strong AI demand." Strong AI demand can explain the server chain and HBM, but it does not automatically guarantee healthy consumer demand, inventory, cash flow, and CapEx. A high-quality re-rating requires rising prices, real demand, controlled inventories, and disciplined CapEx. A low-quality re-rating relies only on price and sentiment.
17. What to Watch Over the Next Four Quarters
Over the next several quarters, the research focus has shifted from a single target price to several datasets that can validate one another. The first group is DDR5 and DDR4 contract prices, which validate whether spot premiums are entering customer contracts. The second group is Korean DRAM exports and server ODM revenue, which validates whether AI demand continues to translate into shipments. The third group is Samsung HBM qualification, shipments, and pricing, which validates the 2027 price assumption. The fourth group is inventory, cash flow, and CapEx, which validates earnings quality.
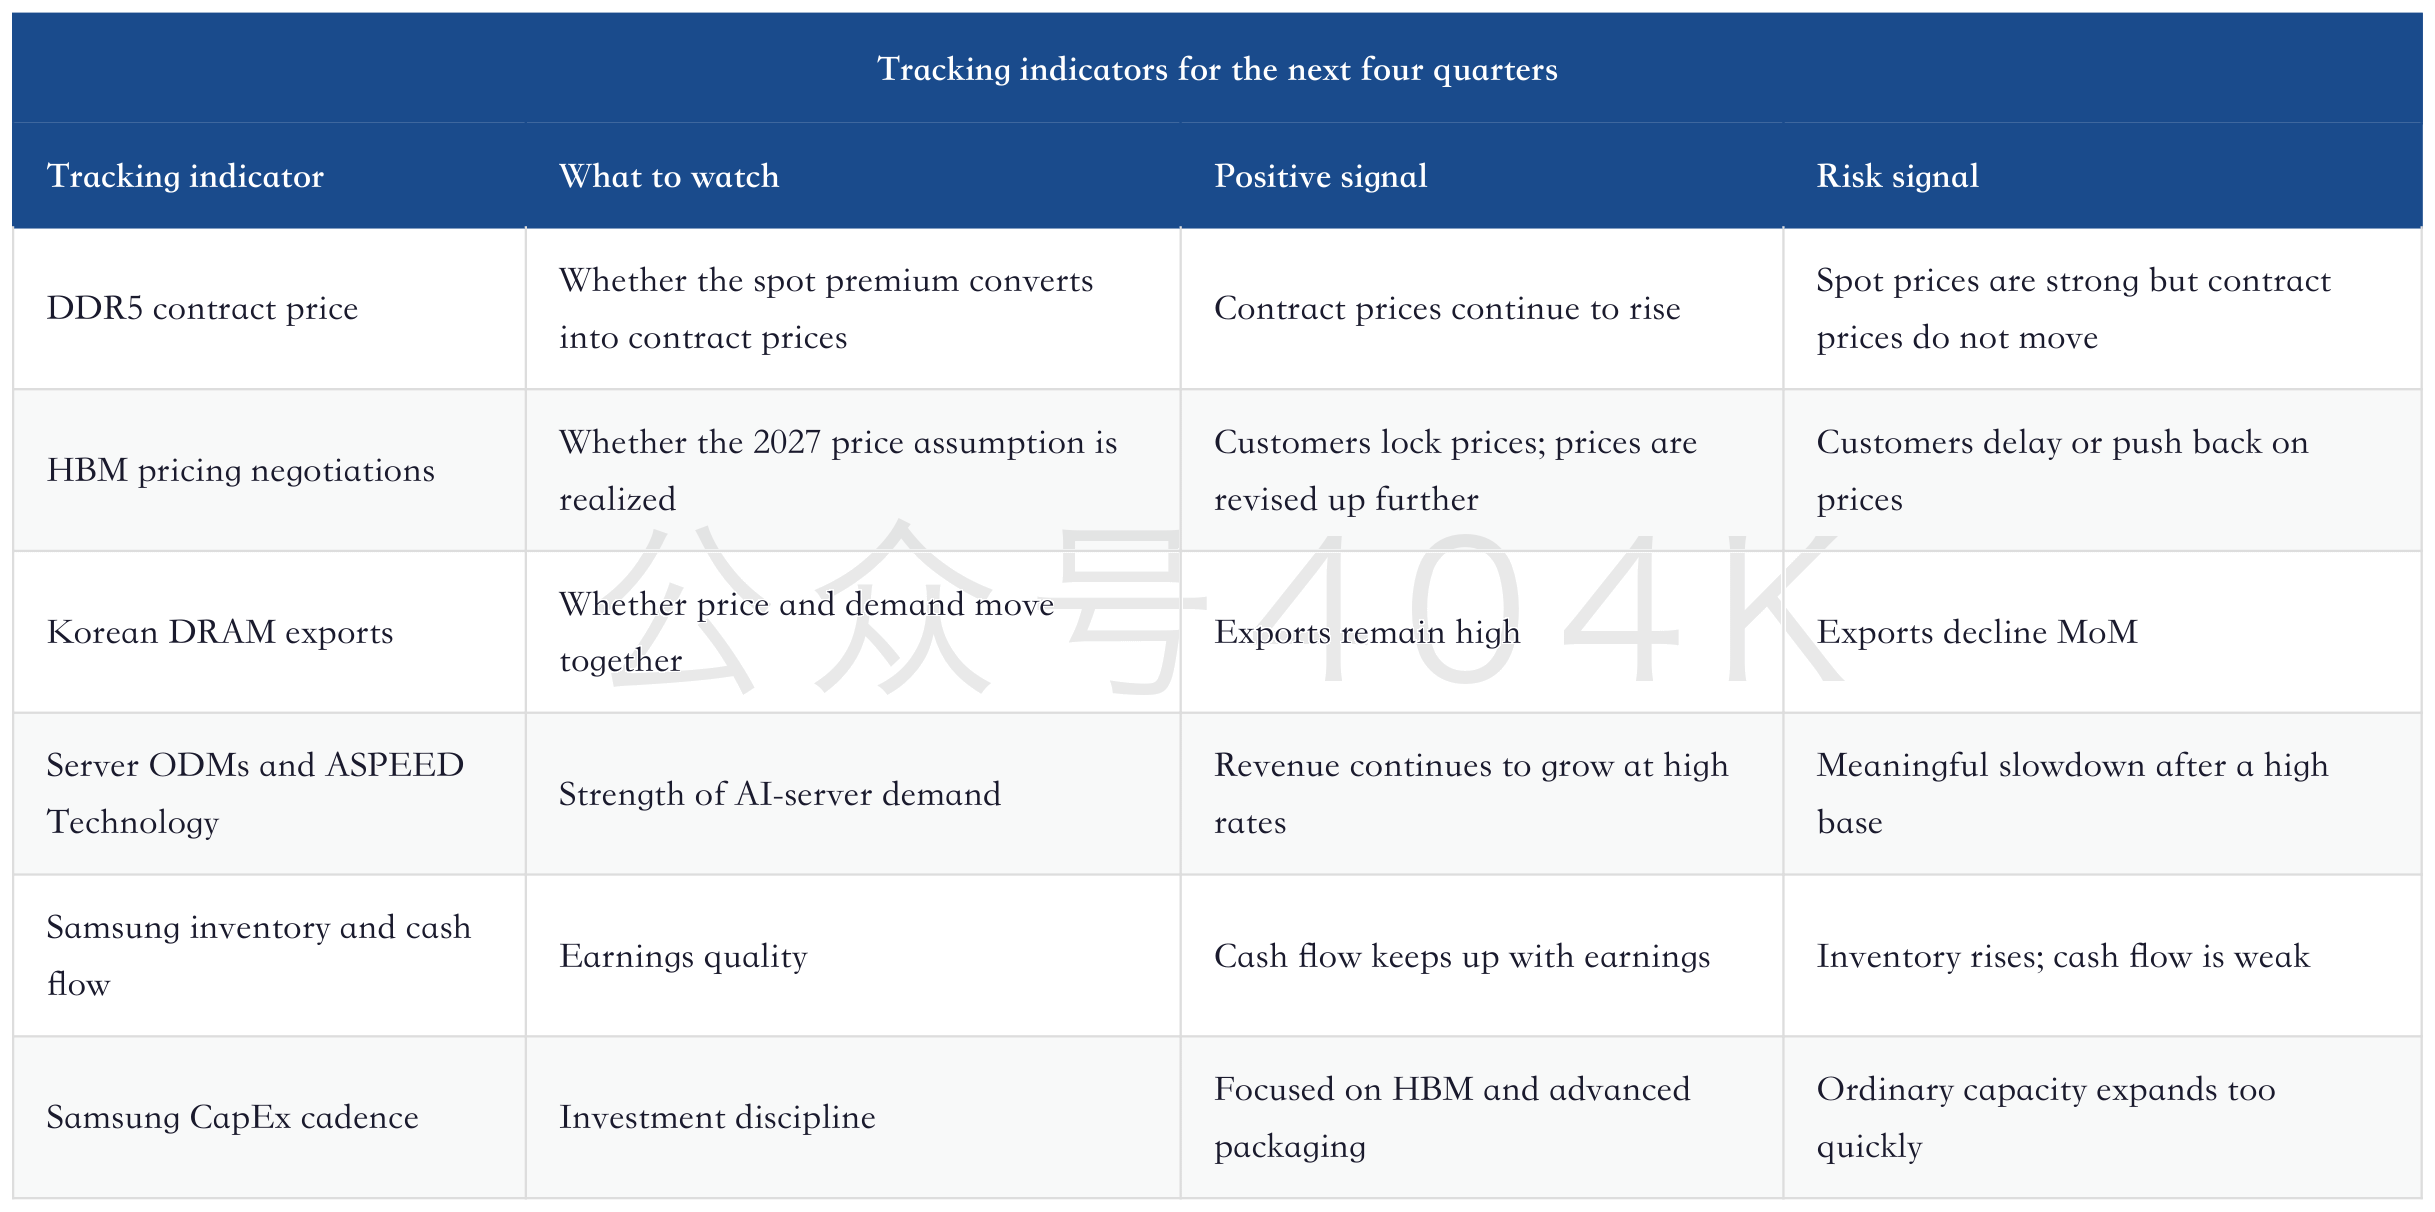
These six indicators need to be read together. If DDR5 contract prices rise, HBM pricing expectations continue to move up, Korean exports stay high, and Samsung's inventory and cash flow are healthy, the memory re-rating will be steadier. If prices rise but inventory and cash flow diverge, the market will first weaken the optimistic scenario and then return to conventional cyclical valuations.
18. Mapping to A-Shares and Hong Kong Stocks: Watch Legacy Memory, Equipment, and the AI-Server Chain
Although these two Goldman Sachs reports mainly focus on Korean memory and Samsung Electronics, they also map to the Chinese market. The first mapping is legacy-memory price increases: DDR4, SLC NAND, NOR, and niche DRAM are all affected by major vendors' resource migration. The second is the equipment chain: Samsung's long-term investment improves global WFE and advanced-packaging order visibility. The third is the AI-server chain: DDR5, HBM, PCB, optical modules, liquid cooling, and power supplies are all in the same CapEx cycle.
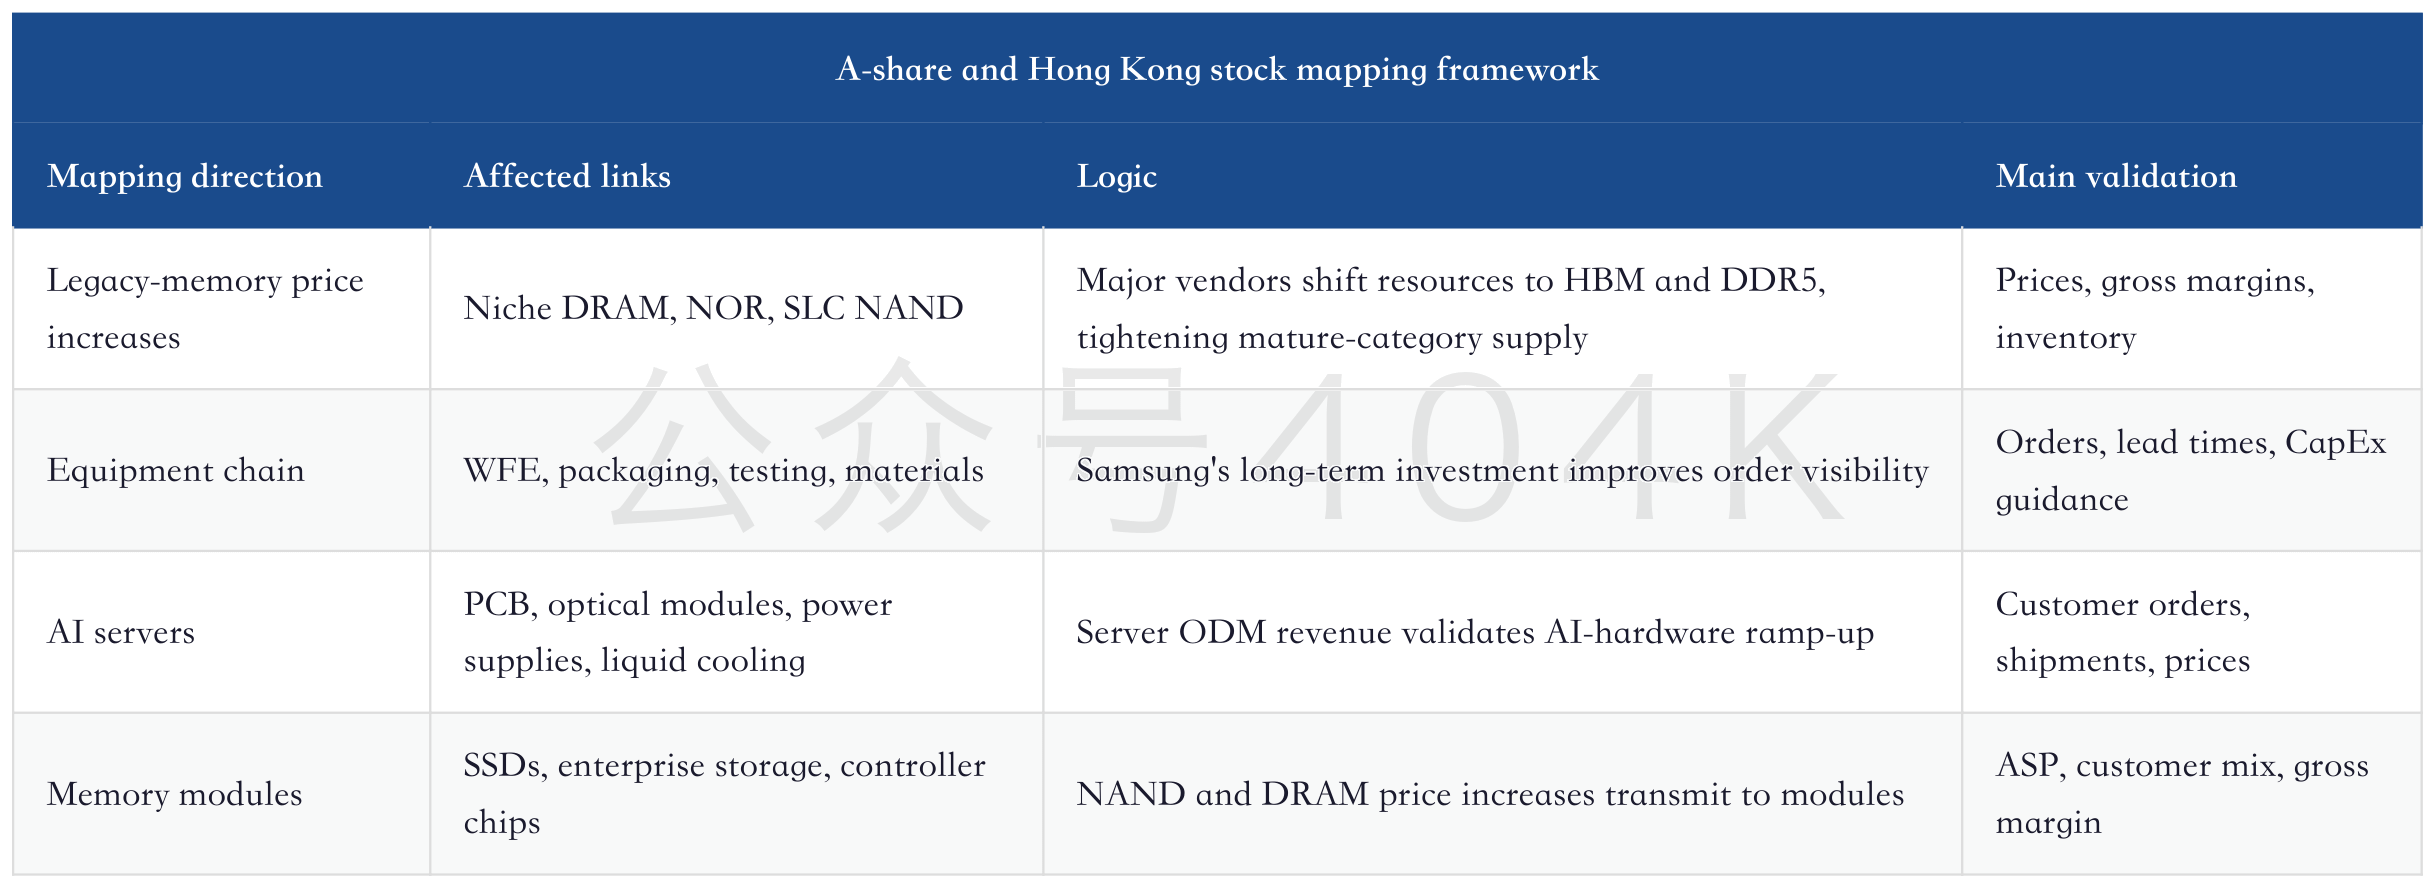
Simple analogies should be avoided when mapping. Samsung Electronics has HBM, DRAM, NAND, smartphones, displays, and fab-investment capabilities. Chinese-market related companies often correspond to only one segment. Legacy-memory companies are more affected by pricing and inventory, equipment-materials companies by CapEx, and the AI-server chain by cloud providers and system shipments. Only by separating these variables can investors judge which companies benefit from pricing, which benefit from orders, and which are only being carried by sentiment.
19. Data Framework: Price Moves First, Profit Follows, Inventory Tells the Truth Last
The easiest way to misjudge the memory cycle is to ignore the different response speeds of different data. Spot prices move fastest, contract prices usually lag, margins lag further, and inventory and cash flow confirm later. Goldman Sachs puts daily prices, monthly revenue, exports, the quarterly second derivative of ASP, and channel feedback into one sentiment indicator in order to place data with different speeds on the same dashboard.
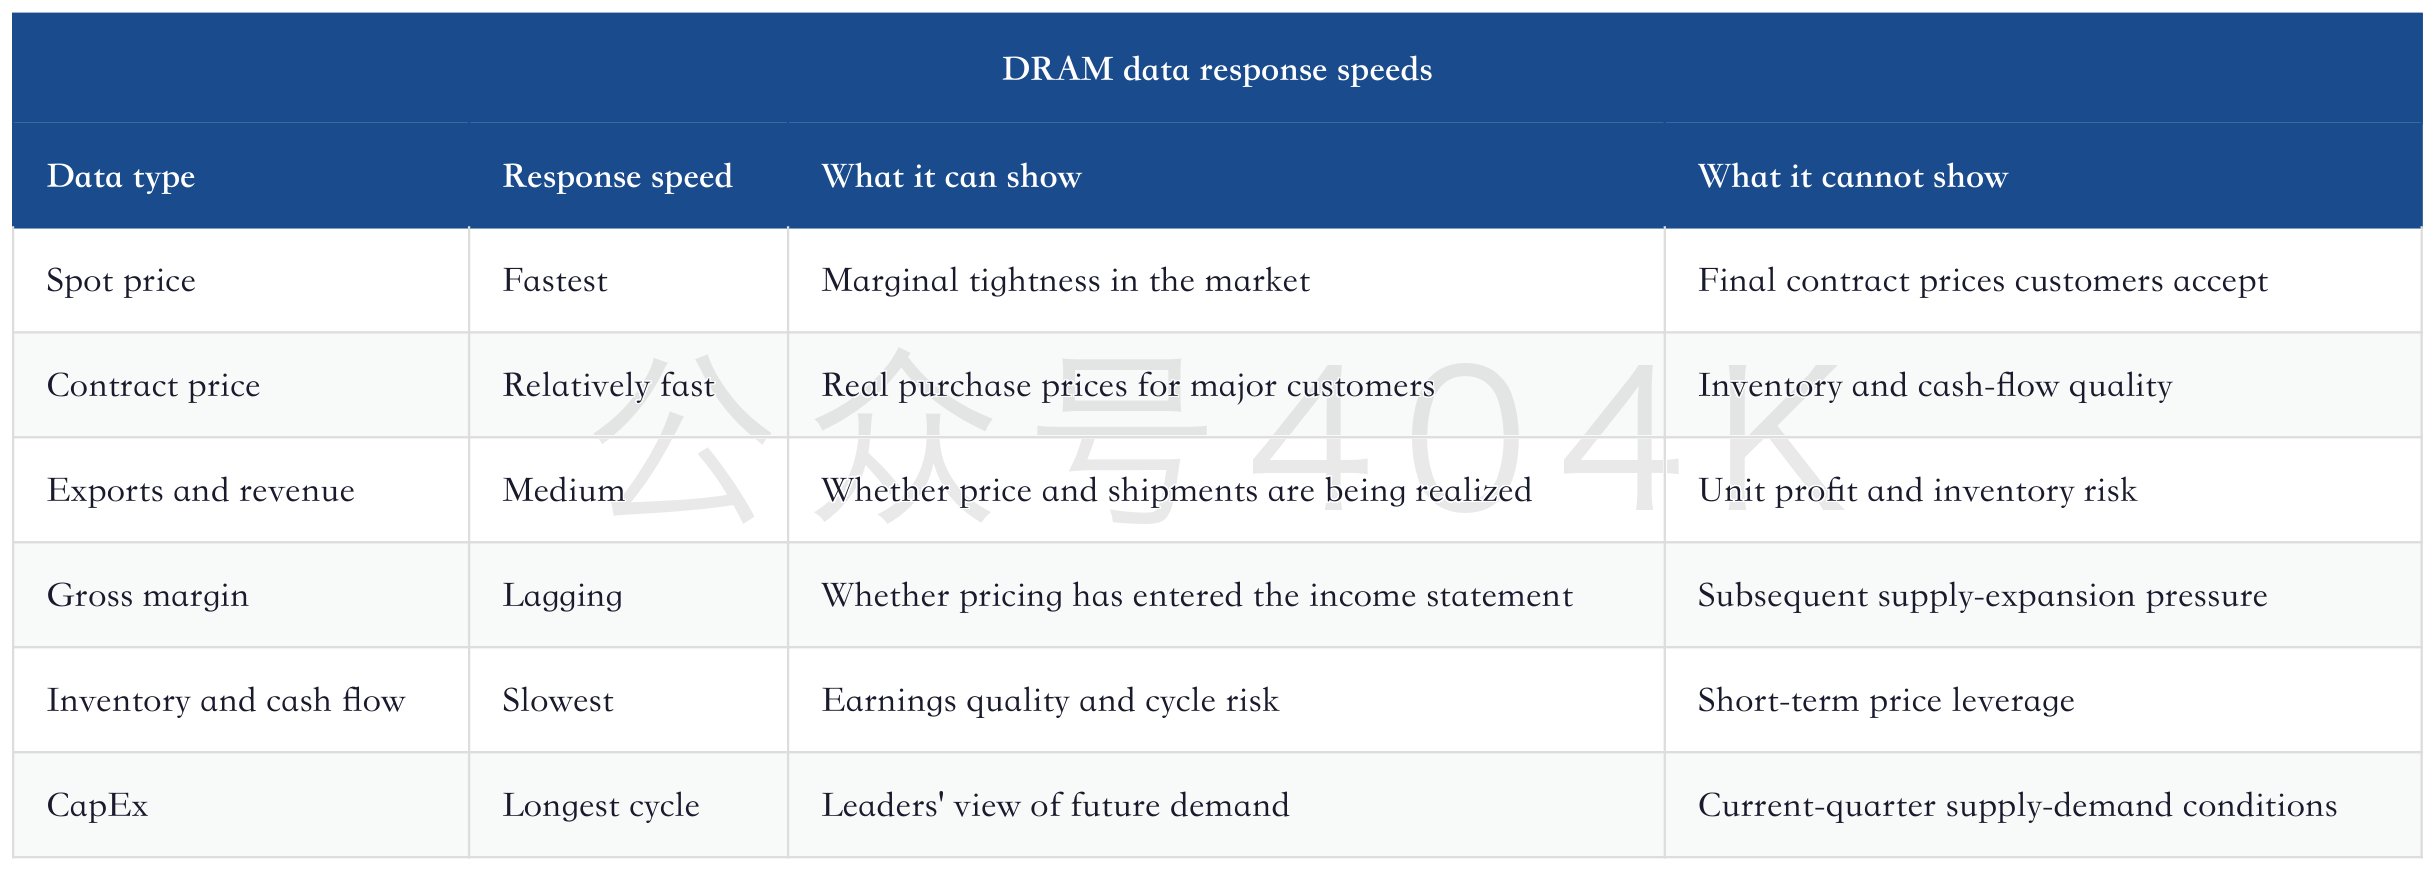
This sequence helps determine the stage of the rally. If spot prices rise first, contract prices then rise, and exports and revenue also strengthen, price transmission is working. If gross margins and cash flow continue to improve, price increases are becoming high-quality earnings. If inventories rise and cash flow fails to keep up, companies may be using stocking to pull forward earnings quality. Past memory cycles have repeatedly shown that inventory and cash flow are often more honest than revenue.
Current data are in the middle stage: prices and exports are already strong, and the server chain has also provided validation. The next items to watch are contract prices, margins, and inventory. Samsung especially needs to use cash flow to prove that this round of CapEx is sustainable. If Goldman Sachs' free-cash-flow assumptions are realized, long-term investment will be read by the market as strategic spending. If free cash flow is weaker than earnings, the W2,450tn plan will be reassessed.
This also explains why Goldman Sachs uses a moderately positive, rather than extremely positive, description even though the DRAM sentiment indicator is strong. Prices have already provided a sufficiently strong signal; the next step is for margins, contract prices, and inventory to continue delivering. What the market needs to buy into is that in the first half, price increases have happened, and in the second half, those price increases leave behind cash flow.
20. ROIC Validation: Samsung's Long-Term Investment Ultimately Returns to Capital Returns
The final question for Samsung's W2,450tn plan is capital returns. The semiconductor industry can earn very high profits in upcycles, but it can also bear depreciation pressure after oversupply. Goldman Sachs' view that the long-term growth rate is reasonable only answers whether the investment scale is excessive. It does not yet answer whether returns on investment can cover the cost of capital.
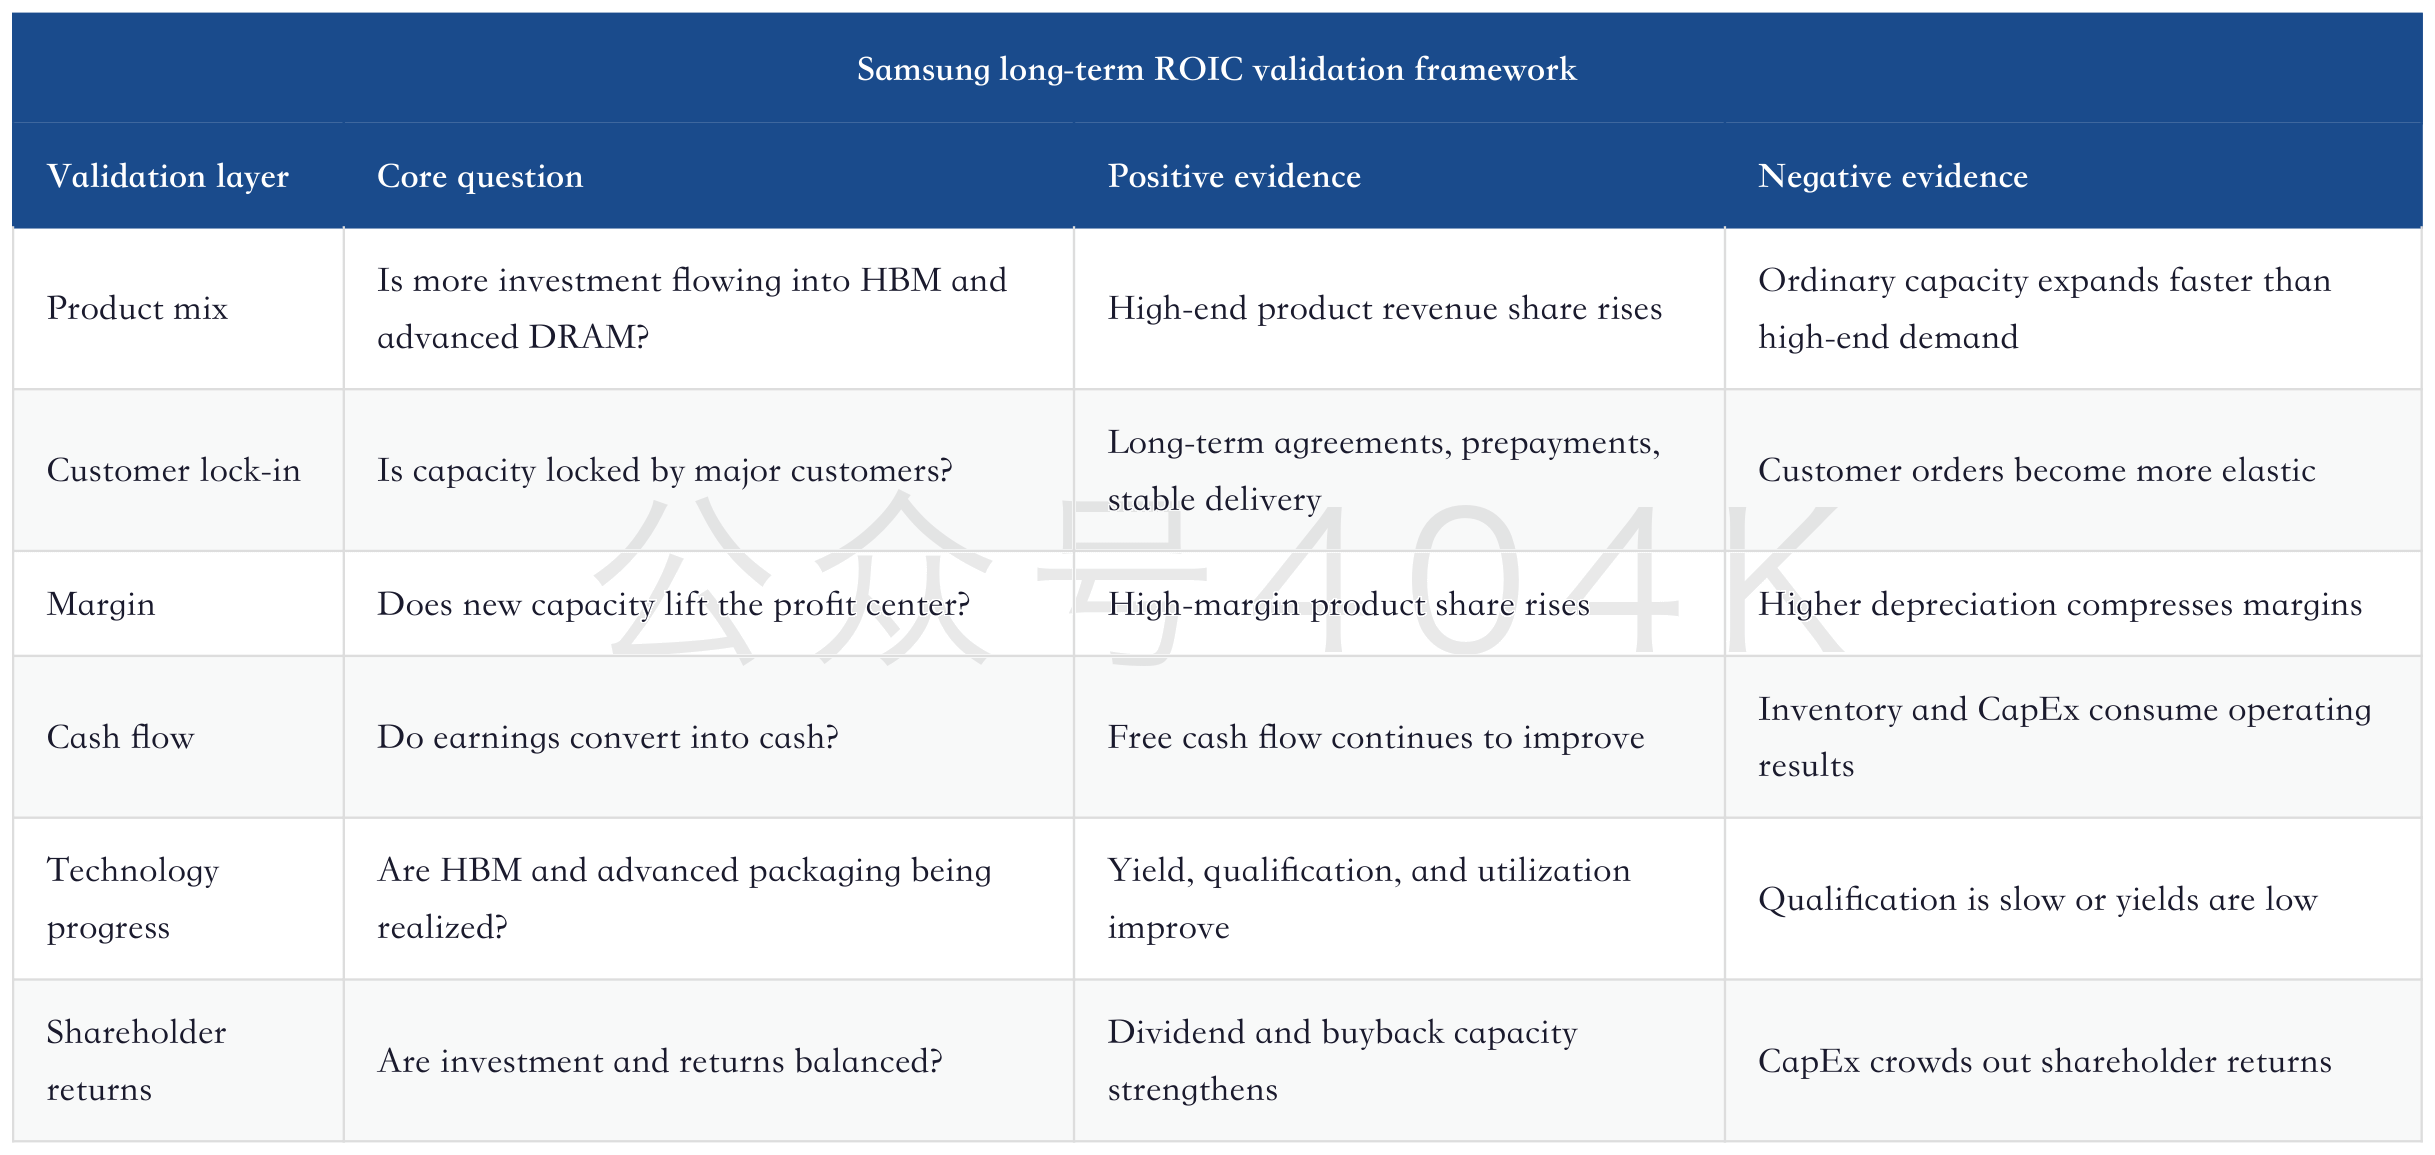
This framework is more useful than looking at investment scale alone. If Samsung directs resources into HBM, advanced packaging, and high-end DRAM, and locks in customers through long-term agreements, CapEx will raise the future profit center. If investment flows more toward ordinary capacity, or if high-end product qualification is difficult, new depreciation will pressure returns a few years later. The market's disagreement over Samsung's valuation is essentially a set of different judgments on this table.
ROIC also determines the quality of the equipment-chain rally. Higher equipment orders are positive for upstream company revenue, but if end-customer capital returns weaken, the sustainability of equipment orders will decline. A high-quality equipment rally requires memory customers to make money, generate good cash flow, and have a clear CapEx direction. A low-quality equipment rally relies only on a large investment announcement and has weaker durability.
From this perspective, the two Goldman Sachs reports do not conflict. The DRAM sentiment indicator shows that near-term profits are improving, while Samsung's long-term investment plan shows that leaders are willing to commit capital for future demand. What truly needs validation is whether near-term profits can turn into cash flow and whether long-term investment can turn into ROIC. Only if both links hold can the memory rally move from cyclical recovery to asset re-rating.
21. HBM Supply Gates: Price Upgrades Ultimately Need Delivery
HBM price upgrades cannot be assessed only through demand. AI customers are willing to pay a premium for certainty, but suppliers must deliver sufficient quantity, qualified yield, and stable performance. HBM supply gates can be roughly divided into four layers: high-end DRAM wafers, stacking and packaging, testing and yield, and customer qualification and software ecosystem. If any layer has a problem, price leverage will be discounted by delivery risk.
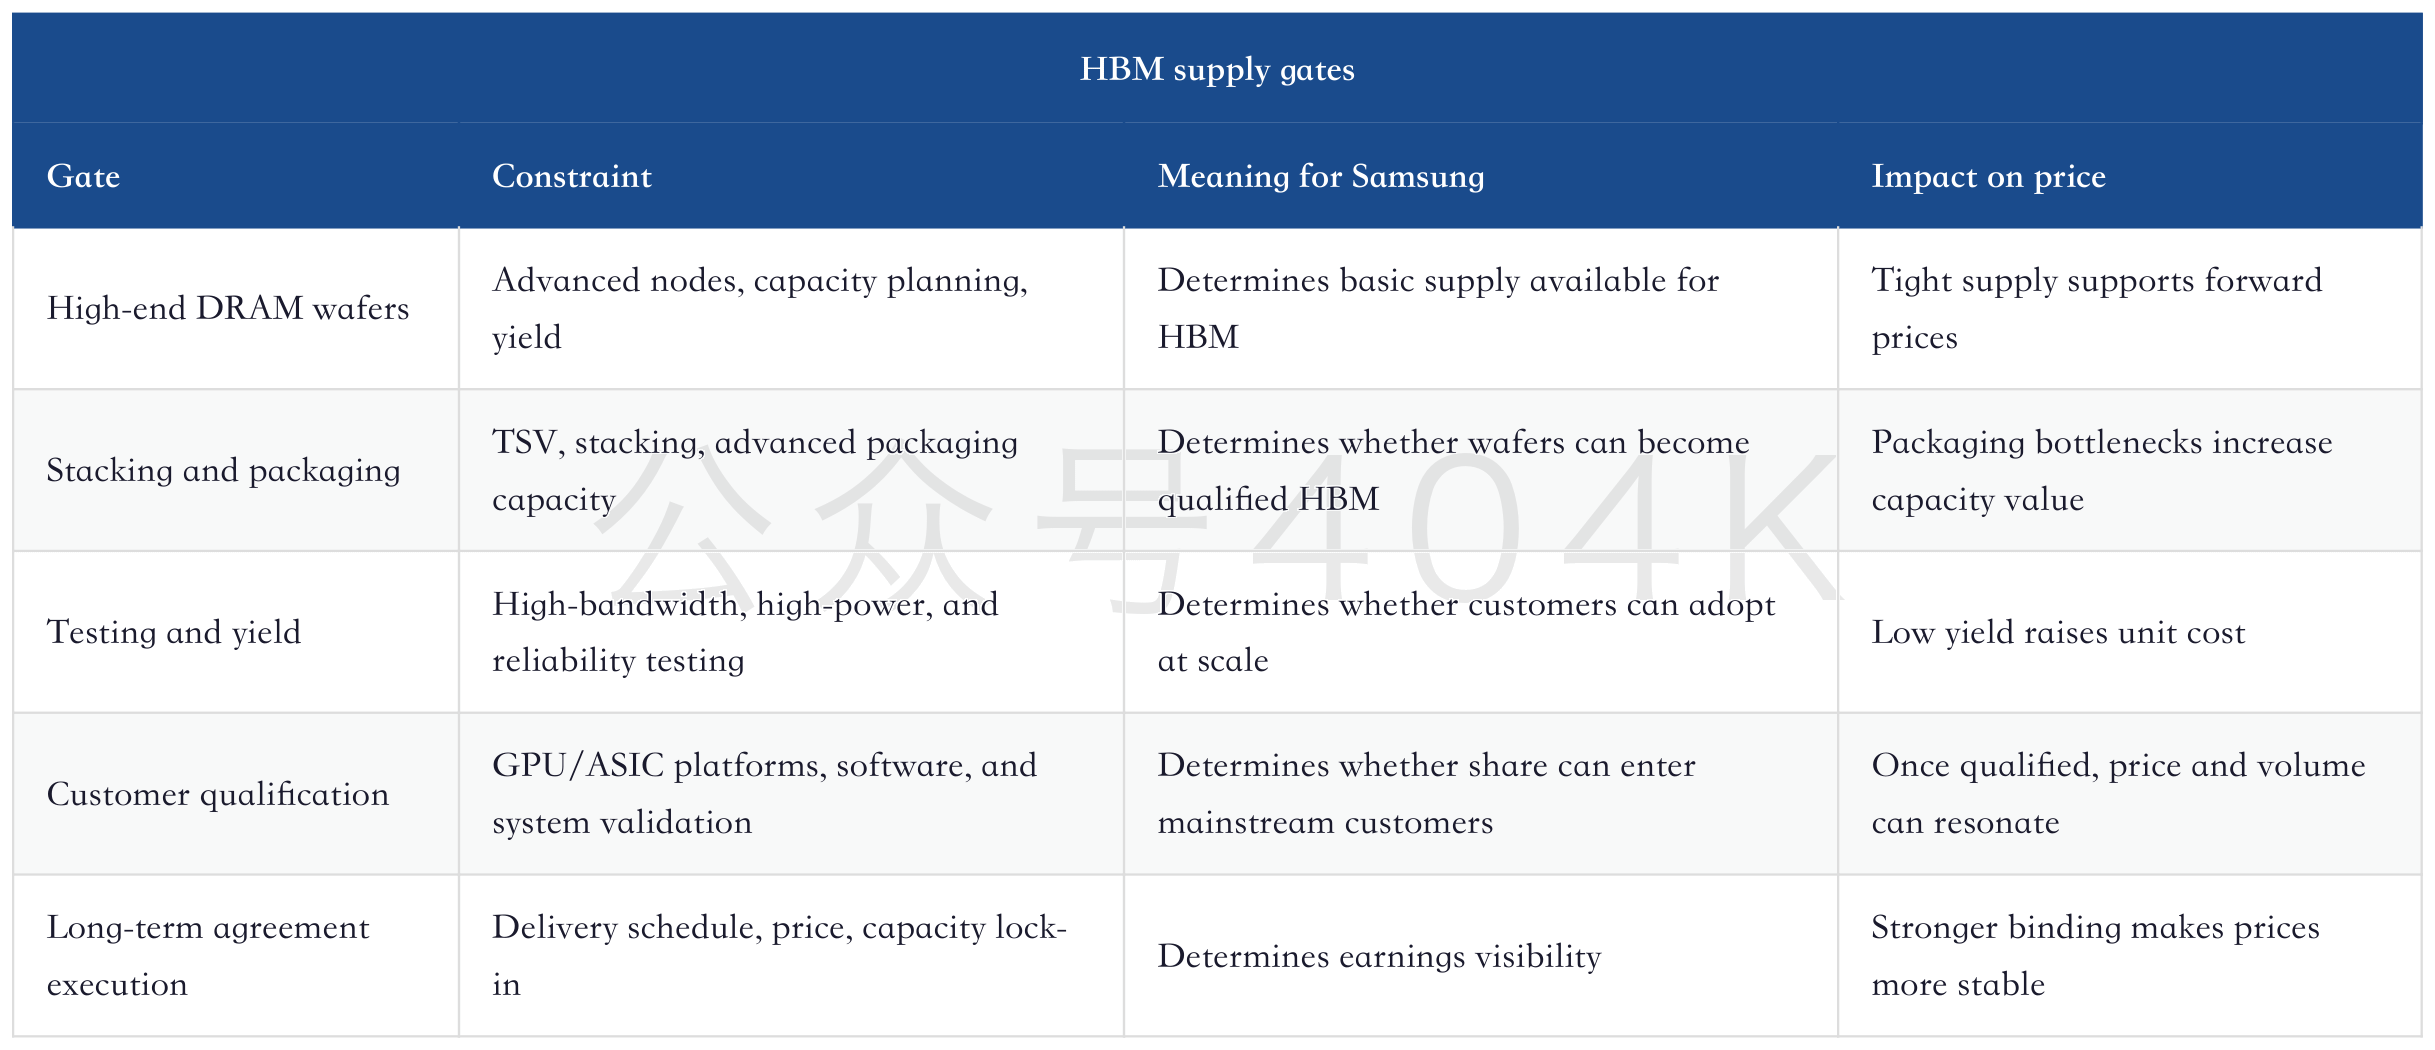
Samsung's core task is to turn HBM catch-up into deliverable customer share. Goldman Sachs' more optimistic 2027 HBM pricing gives Samsung greater earnings leverage, but the market will ultimately watch qualification, shipments, and yield. If price assumptions rise but delivery does not keep up, valuation will first reflect optimism and then be corrected by reality. If delivery and price are both realized, Samsung will move from a conventional DRAM recovery asset closer to a core AI-memory asset.
HBM also feeds back into ordinary DRAM. When leaders put more wafers, engineering resources, and packaging capability into HBM, supply elasticity for mature DRAM and parts of legacy memory is reduced. This is one of the underlying reasons DDR4, DDR5, and legacy memory prices are rising together. As long as HBM continues to absorb major vendors' capacity resources, supply constraints in mature categories can persist for longer.
22. Price-Increase Quality Check: Contract Prices, Inventory, and Cash Flow Must All Pass
DRAM price increases can be high quality or low quality. High-quality price increases come from real demand, customer lock-in, higher shipments, and healthy inventories. Low-quality price increases come from short-term restocking, channel hoarding, or supply disruption. The two may look similar in spot prices, but they diverge in contract prices, inventory, and cash flow.
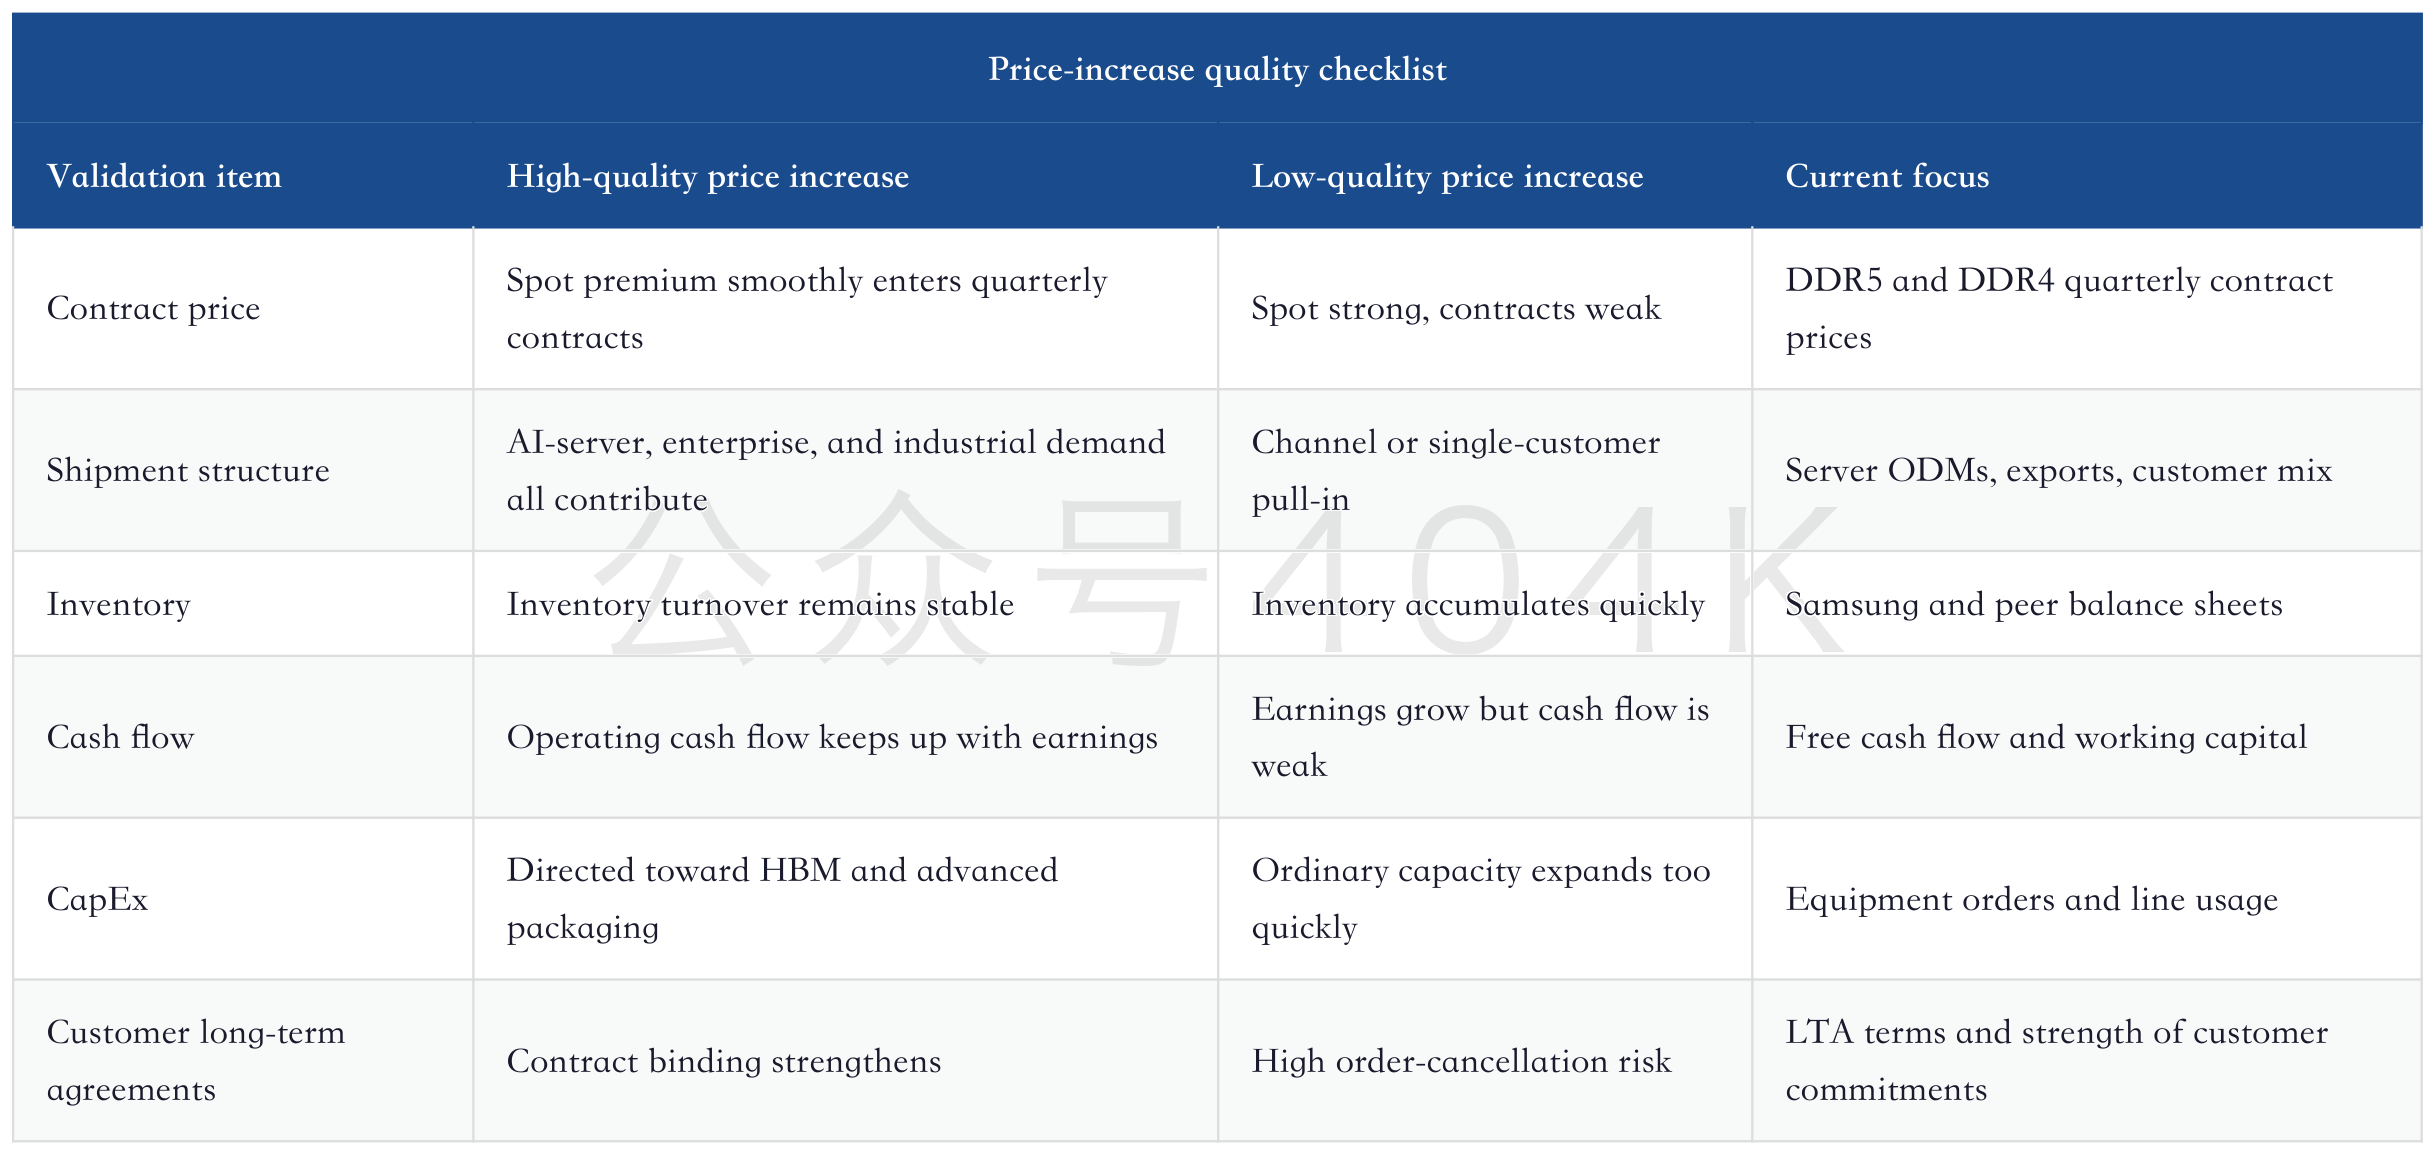
This table also explains why Goldman Sachs focuses on DDR5, HBM, and Samsung's long-term investment at the same time. DDR5 spot prices are the starting point for the price increase. HBM long-term agreements are the amplifier of price-increase quality. Samsung's investment plan is the result of whether price increases can turn into long-term capital returns. If the three match, the industry enters a high-quality upcycle. If they diverge, the rally shifts from earnings upgrades for leaders to repricing of supply risk.
For Samsung, the most important issue is to link investment scale with customer demand. If high-end DRAM, HBM, and advanced-packaging investments have clear customers, clear prices, and clear delivery schedules, the market will be willing to assign a higher valuation. If investment merely expands future capacity, the market will start worrying earlier about depreciation and price declines.
23. Scenario Framework: Base Case Watches Contract Prices, Bull Case Watches HBM, Stress Case Watches Inventory
Combined, the two Goldman Sachs reports form three scenario frameworks. The base case watches whether DDR5 and DDR4 spot premiums enter contract prices, determining whether 2026 earnings upgrades can continue. The bull case watches 2027 HBM pricing and Samsung's HBM delivery, determining whether the industry can move from an ordinary price-increase cycle into an AI-memory new normal. The stress case watches inventory, cash flow, and CapEx cadence, determining whether the market will switch early to a post-supply-cycle framework.
The core of the base case is contract prices following spot prices. DDR5 spot prices have already given a price-increase signal, and the DDR4 premium is higher. But entry into the income statement requires contract confirmation. If quarterly contract prices continue to rise, Korean exports remain high, and server ODM revenue does not stall, memory vendors' 2026 earnings upgrades will become more credible. In this scenario, the market will continue valuing the sector on income-statement improvement, but it will remain disciplined on long-term multiples because CapEx and supply risk have already been brought to the table by Samsung's investment plan.
The core of the bull case is HBM shifting from price upgrades to delivery upgrades. Goldman Sachs has materially raised Samsung's 2027 HBM price assumption, already showing a change in the forward pricing anchor. If Samsung's HBM qualification, yield, and customer share advance together, the market will reprice it from a conventional DRAM recovery asset into an AI-memory platform asset. This scenario would raise Samsung's own valuation and also drive value-content re-rating across advanced packaging, testing, substrates, equipment, and materials.
The core of the stress case is strong prices but weak quality. Spot prices can rise and earnings can improve, but if inventories rise at the same time, cash flow fails to keep up with earnings, and CapEx cadence accelerates, the market will worry that this upcycle is pulling forward future demand. The stress case usually hurts valuation multiples first and earnings estimates later. In other words, share prices may correct while earnings still look good because the market has already begun discounting the post-supply cycle.
These three scenarios will not necessarily unfold in sequence. The market will switch back and forth among different data points. When prices and exports are strong, the base case dominates. When HBM qualification and pricing continue to beat expectations, the bull case dominates. When inventory, cash flow, or CapEx diverges, the stress case dominates. The most practical research method is to place each new datapoint into these three frameworks and avoid being pulled around by a single month of prices or one CapEx headline.
For Samsung Electronics, the base case corresponds to DRAM earnings recovery, the bull case corresponds to successful HBM catch-up, and the stress case corresponds to doubts about CapEx returns. For the industry, the base case supports memory-stock earnings upgrades, the bull case supports an AI-memory valuation reset, and the stress case reminds the market that memory remains cyclical. Separating these three layers is the only way to understand why Goldman Sachs is emphasizing DDR5 pricing, 2027 HBM, and Samsung's long-term investment at the same time.
24. Where This Memory Rally Is Easiest to Misread
The first misread is to equate DDR5 spot-price increases directly with price increases across all memory categories. DDR5, DDR4, HBM, NAND, and SLC NAND have different supply-demand structures and different price-transmission speeds. DDR5 spot prices can lead contract prices, HBM depends more on customer lock-in and advanced packaging, and legacy memory is more affected by mature-capacity migration. Research needs to separate the categories.
The second misread is to treat Samsung's long-term investment as near-term supply pressure. W2,450tn sounds large, but the plan spans 15 years and may include R&D.; Near-term DRAM and HBM supply-demand are still determined by existing capacity, yield, customer qualification, and packaging capacity. Long-term investment will affect post-2028 supply expectations, while near-term pricing still depends on contracts and inventory.
The third misread is to look only at target-price or rating actions. Goldman Sachs' high target price for Samsung depends on memory earnings, long-term agreements, HBM progress, cash flow, and shareholder returns. If these variables are validated together, valuation has support. If only price increases remain, without cash-flow and inventory validation, valuation will return to a cyclical framework.
The fourth misread is to ignore pressure on the consumer side. AI-server demand is very strong, but smartphones and PCs remain sensitive to memory prices. If memory prices rise too quickly, device vendors will reduce configurations or delay procurement. Consumer demand is not the main driver of this rally, but it is an important constraint for testing whether price increases can transmit broadly.
25. Conclusion: The Memory Rally Has Entered the Stage of "From Price Realization to Forward Pricing"
The information from these two Goldman Sachs reports can be placed on a timeline: DDR5 and DDR4 spot prices have risen since May; the June DRAM sentiment indicator remains moderately positive; Korean DRAM exports and server-chain data remain strong; the 2027 HBM price assumption has been materially raised; and Samsung has announced a 15-year domestic investment plan. This timeline shows that the memory rally has moved from price recovery into forward pricing.
For Samsung Electronics, the short term is about DRAM and HBM earnings leverage, the medium term is about HBM qualification, customer long-term agreements, and free cash flow, and the long term is about whether the W2,450tn investment can translate into high ROIC while avoiding becoming ordinary capacity expansion. For the memory industry, the DDR5 spot premium is the leading indicator for contract prices, HBM price upgrades are the valuation amplifier, and CapEx discipline is the key to extending the cycle.
The final judgment is more direct: as long as DDR5 contract prices continue to follow, 2027 HBM pricing negotiations remain strong, and Korean exports and AI-server-chain data do not stall, memory stocks will continue to trade on a higher earnings step-up. If inventories rise after prices reach high levels, cash flow weakens, and Samsung's CapEx cadence becomes too fast, the market will shift early toward the post-supply cycle. Over the next several quarters, the most important work is no longer to find a bigger story, but to validate this story item by item through price, inventory, cash flow, and CapEx.Goldman Sachs DRAM Deep Update: DDR5 Price Increases, 2027 HBM Repricing, and Samsung’s W2,450tn Investment
目录
Too Long; Didn’t Read
1. Bottom Line First: DDR5 Is Current Profit, HBM Is the Next Pricing Anchor
2. Goldman Sachs’ June DRAM Sentiment Indicator: Moderately Positive, but Components Are Already Hot
3. DDR5 Spot Premium: Prices Are Already Pressuring Contract Pricing
4. Korean Exports and the Server Chain: AI Demand Is Still Pulling Real Orders Higher
5. China Smartphones: Recovery Exists, but So Does Pricing Pressure
6. Nanya Technology and Supreme: Legacy Memory Continues to Add Leverage
7. 2027 HBM: Goldman Sachs Raises the Forward Pricing Anchor Materially
8. Samsung’s W2,450tn Investment: Long-Term Commitment, Near-Term Supply Still Constrained by Capacity Gates
9. CapEx Discipline: The Market’s Real Concern Is the Post-2028 Supply Shadow
10. Samsung Valuation: Goldman Sachs Is Focused on Memory Earnings, Long-Term Agreements, and Shareholder Returns
11. Long-Term Agreements and HBM Customer Lock-In: Can This Cycle See Less Inventory Swing?
12. Equipment Chain: Samsung’s Long-Term Investment Gives WFE and Advanced Packaging Longer Order Visibility
13. Samsung, SK hynix, Micron, and Niche Vendors: Same Price Cycle, Different Valuation Logic
14. Three Worldviews: Price-Increase Cycle, AI-Memory New Normal, and Post-CapEx Cycle
15. Model Bridge: From DDR5 Spot Prices to Samsung Valuation, There Are Six Gates
16. Disconfirmation Checklist: Signals That Would Cool This Re-Rating
17. What to Watch Over the Next Four Quarters
18. Mapping to A-Shares and Hong Kong Stocks: Watch Legacy Memory, Equipment, and the AI-Server Chain
19. Data Framework: Price Moves First, Profit Follows, Inventory Tells the Truth Last
20. ROIC Validation: Samsung’s Long-Term Investment Ultimately Returns to Capital Returns
21. HBM Supply Gates: Price Upgrades Ultimately Need Delivery
22. Price-Increase Quality Check: Contract Prices, Inventory, and Cash Flow Must All Pass
23. Scenario Framework: Base Case Watches Contract Prices, Bull Case Watches HBM, Stress Case Watches Inventory
24. Where This Memory Rally Is Easiest to Misread
25. Conclusion: The Memory Rally Has Entered the Stage of “From Price Realization to Forward Pricing”
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Goldman Sachs’ June DRAM sentiment indicator shows that DDR5 spot price increases, Korean exports, and server-chain revenue continue to validate the memory upcycle; Samsung’s W2,450tn long-term investment also brings supply discipline back to the foreground. This report unpacks DDR5, HBM, long-term agreements, CapEx, and equipment-chain transmission to assess whether this re-rating is being driven by price, cash flow, or long-term capacity constraints.
Too Long; Didn’t Read
Near-term signals remain strong. Goldman Sachs’ June DRAM sentiment indicator stayed moderately positive. DDR5 spot prices are up 20% from early May, while Korean DRAM exports and server ODM revenue continue to grow at high rates, indicating that AI servers, ASIC servers, and memory pricing are still jointly lifting industry momentum. This supports near-term earnings upgrades for memory stocks, but also reminds the market that the stronger prices become, the more end demand needs to be validated by quarterly data.
The DDR5 spot premium is a leading indicator for contract-price increases. DDR5 spot prices are at a 25% premium to May contract prices, while the DDR4 premium is even higher, indicating that customer restocking and tight supply are already reflected in transaction prices. If the spot premium persists, subsequent contract prices should follow; if the premium compresses quickly, the market will read the price increase as a short-term mismatch, and valuation upside for memory stocks will be pulled back.
2027 HBM repricing is the forward variable. Goldman Sachs raised its 2027 HBM price-growth assumption for Samsung Electronics from 14% to 44%, because strong conventional DRAM prices will affect next year’s HBM pricing negotiations. When HBM supply remains tight and conventional DRAM prices are also rising, customers have less room to trade off capacity, performance, and delivery schedules.
Samsung’s W2,450tn investment does not equal a near-term flood of supply. Samsung plans to invest W2,450tn from 2026 to 2040, including around W2,100tn in domestic semiconductors. Goldman Sachs believes that if R&D; is included, the implied long-term growth rate is 5%-6%, a reasonable range. Near-term supply remains constrained by HBM yield, advanced packaging, equipment lead times, and customer qualification.
Cash-flow quality will decide this memory re-rating. Samsung’s valuation table shows that Goldman Sachs’ 2026-2028 assumptions for earnings, free cash flow, and shareholder returns have all been lifted by the memory upcycle. What will truly sustain the valuation is simultaneous improvement in long-term agreement coverage, inventory quality, CapEx discipline, and HBM delivery capability.
Equipment and upstream materials will be repriced. If Samsung gradually deploys its long-term investment into fabs, HBM lines, packaging, and new display capacity, WFE, advanced packaging, testing, substrates, gases, and materials chains will all benefit. The risk is that CapEx accelerates too early, bringing post-2028 supply expectations forward into current valuations.
1. Bottom Line First: DDR5 Is Current Profit, HBM Is the Next Pricing Anchor
Read together, the core conclusion from these two Goldman Sachs reports is straightforward: the memory cycle is still moving upward, but the market is shifting from “are prices rising” to “how long can price increases last.” The June DRAM sentiment indicator is not extremely bullish; it remains moderately positive. But the underlying components are already strong. DDR5 spot prices, Korean DRAM exports, server ODM revenue, Nanya Technology revenue, and channel checks all point to the same fact: supply-demand conditions remain tight.
More importantly, the meaning of the price increase is changing. In the earlier stage, the market watched DDR4 and DDR5 spot prices to confirm restocking and tight supply. Goldman Sachs now embeds conventional DRAM strength into its 2027 HBM price assumptions, showing that price increases in mainstream memory have begun to influence forward negotiations for high-end AI memory. This matters more than a single month’s pricing data, because HBM usually involves large customers, long-cycle contracts, and higher capital intensity. Once pricing expectations rise, the valuation frameworks for Samsung Electronics, SK hynix, Micron, and the equipment chain all change.
Samsung Electronics’ W2,450tn domestic investment plan, announced the same day, puts another issue on the table: if memory demand is truly entering a new AI-era cycle, will leading companies quickly lift CapEx and undermine supply discipline? Goldman Sachs’ view is relatively measured. The plan runs through 2040 and may include R&D; spending, implying a reasonable long-term growth rate. In other words, it looks more like a long-term capacity and technology-roadmap statement; in the near term, the market still needs to watch HBM yield, equipment delivery, customer qualification, and cash flow.
The research judgment can be compressed into one sentence: the first stage of this DRAM re-rating is driven by DDR5 and DDR4 price increases, while the second stage depends on 2027 HBM pricing, long-term agreement coverage, and CapEx discipline among leaders such as Samsung. Looking only at spot prices can underestimate forward earnings leverage, while looking only at long-term investment can understate near-term supply constraints. The real focus should be whether price, delivery, inventory, and CapEx indicators move in the same direction.
2. Goldman Sachs’ June DRAM Sentiment Indicator: Moderately Positive, but Components Are Already Hot
Goldman Sachs described its June DRAM sentiment indicator as moving in a “moderately positive direction.” It is not maximally bullish, but the message is not weak. The indicator covers spot prices, server-chain revenue, Korean exports, Chinese smartphones, Nanya Technology, Supreme Electronics, the second derivative of Samsung’s DRAM ASP, and channel feedback. This mix has one advantage: it looks at price, real demand, and end-market affordability at the same time.
The key point in this table is the final row. Prices, revenue, and exports are all strong, but the second derivative of Samsung’s DRAM ASP is negative. This means price increases are continuing, but the slope has moved from extreme acceleration toward deceleration. This is the kind of phase memory-stock valuations fear most: earnings are still being revised up, while the market starts to worry whether the next stage of growth will slow. Goldman Sachs maintains a moderately positive view precisely because strong demand and a slowing price slope are both present.
For investment research, this state is not contradictory; it is a common mid-cycle pattern. In the early stage, share prices trade on price leverage. In the middle stage, the focus shifts to earnings quality. Only in the late stage does the market turn primarily to inventory and supply expansion. The most important question has already shifted from “are DRAM prices rising” to “can the DDR5 spot premium flow into contract prices, and can forward HBM pricing take over.” Only if both are true can the memory upcycle move from short-term price increases to a longer-term earnings step-up.
3. DDR5 Spot Premium: Prices Are Already Pressuring Contract Pricing
DDR5 is the cleanest near-term signal in this sentiment indicator. Goldman Sachs’ report shows that DDR5 prices are up 20% since early May, and spot prices are at a 25% premium to May contract prices. DDR4 is also rising, with an even higher spot premium to contract prices. Spot prices leading contract prices usually means customer restocking, supply contraction, or longer lead times have first appeared in the spot market.
DDR5 price increases affect Samsung Electronics and the broader memory chain in two ways. The first is a direct income-statement impact. DDR5 penetration is rising in servers, PCs, and some high-end endpoints, and price increases lift product ASPs and gross margins. The second is a customer-behavior impact. When conventional DRAM prices strengthen, cloud providers and AI-server customers become more willing to sign long-term agreements, lock in supply, and plan next year’s capacity earlier. That changes HBM negotiations.
This is also why Goldman Sachs puts DDR5 and HBM in the same report. HBM pricing appears to be a high-end AI-product issue, but the underlying constraints still involve DRAM wafers, advanced packaging, yield, and customer capacity reservations. The tighter conventional DRAM becomes, the more negotiating leverage HBM suppliers have. If conventional DRAM prices fall back, the upside space for HBM pricing will also be reassessed.
4. Korean Exports and the Server Chain: AI Demand Is Still Pulling Real Orders Higher
Looking only at price carries a risk: price increases may come from inventory disruption, or they may come from real demand. Goldman Sachs uses three sets of data - server ODMs, ASPEED Technology, and Korean DRAM exports - to validate the demand side. They correspond respectively to AI-server system shipments, server control chips, and cross-border DRAM shipments, allowing demand to be tested from different angles.
Korean DRAM exports are especially important. They reached another record high in May and were meaningfully above the previous peak, showing that memory momentum has entered cross-border export revenue rather than remaining in spot quotations. For Korean leaders, export data validates pricing, utilization, and major-customer demand at the same time. For the equipment chain, stronger exports increase visibility into future CapEx.
Server ODM and ASPEED Technology data point in the same direction. AI servers have expanded from GPU systems to rack-scale delivery and ASIC servers, so memory demand is no longer coming only from the NVIDIA chain. It is also coming from cloud providers’ self-developed chips, networking equipment, and enterprise system upgrades. This diffusion can extend the DRAM demand curve because every type of AI computing platform requires higher memory capacity, higher bandwidth, and more stable supply.
5. China Smartphones: Recovery Exists, but So Does Pricing Pressure
China smartphone shipments rose YoY in May for a second consecutive month, a positive signal in the Goldman Sachs indicator. It shows that end consumption has not completely stalled and that higher memory prices have not immediately crushed demand. At the same time, Goldman Sachs’ China team expects 2Q26 shipments to decline YoY, mainly because higher memory prices are weighing on end demand.
This tension is very important. DRAM price increases are positive for memory makers, but they are a cost pressure for downstream system vendors. Smartphones, PCs, and parts of consumer electronics are highly price-sensitive. Once memory costs rise beyond a certain level, brands may reduce configurations, delay procurement, or pass pressure on to consumers. If end-device shipments slow, memory price increases will shift from earnings leverage to demand pressure.
This means the quality of the rally in memory stocks must be assessed by category. AI-server and enterprise demand can better absorb memory price increases, while smartphones and PCs have weaker affordability. If demand over the next several quarters is supported only by AI servers, DRAM momentum can remain strong, but the market will pay more attention to suppliers’ customer mix. If consumer demand also stabilizes, the breadth of the price cycle will improve.
6. Nanya Technology and Supreme: Legacy Memory Continues to Add Leverage
Nanya Technology’s May revenue rose 730% YoY and has maintained high growth for several months, indicating that DDR4 and niche DRAM remain strong. Supreme Electronics’ revenue also improved materially, with distribution data further confirming transmission through prices and orders. The importance of legacy memory is that it transmits the spillover effect from high-end AI demand into more mature categories.
Legacy memory price increases explain why this rally is not concentrated only in HBM. HBM has the highest profit and the strongest strategic value, but DDR4, DDR5, SLC NAND, and distribution channels are faster thermometers for pricing changes. Goldman Sachs includes Nanya Technology and Supreme in its sentiment indicator precisely to avoid missing the pricing leverage in mature categories by focusing only on high-end AI memory.
Legacy memory also affects CapEx. If mature-category prices are strong, leading vendors may not be willing to rapidly add mature capacity in the near term because new supply could lower prices. But they will invest more actively in leading-edge nodes, HBM, and advanced packaging, directing resources toward products with higher gross margins and stronger customer lock-in. This makes “supply expansion” more structural rather than simultaneous expansion across all categories.
7. 2027 HBM: Goldman Sachs Raises the Forward Pricing Anchor Materially
The most informative statement from Goldman Sachs is its increase in Samsung Electronics’ 2027 HBM price-growth assumption from 14% to 44%. On the surface, this is a model parameter change. In practice, it reflects a change in the HBM negotiation framework. The stronger conventional DRAM prices become, the harder it is for HBM customers to anchor negotiations to historical prices. The tighter HBM supply remains, the easier it is for suppliers to embed advanced packaging, yield ramp-up, and capacity-reservation costs into contracts.
HBM is special because its price is jointly determined by customers, suppliers, and capacity resources. Customers need to lock in future supply, while suppliers need to invest advanced packaging and high-end DRAM resources. Negotiations between the two sides bring expectations for demand in the next one to two years into present valuations. Goldman Sachs’ use of the phrase “tight HBM S/D” shows that its view on tight supply-demand has not loosened.
For Samsung Electronics, the upward revision to 2027 HBM pricing is especially important. Samsung has lagged SK hynix in HBM, and the market has long worried whether it can secure major-customer qualification and high-end share. If the HBM pricing center is higher, even a slower Samsung share ramp can amplify earnings leverage. If share and price improve together, valuation upside becomes larger.
8. Samsung’s W2,450tn Investment: Long-Term Commitment, Near-Term Supply Still Constrained by Capacity Gates
Samsung Electronics announced W2,450tn of domestic investment for 2026-2040, including around W2,100tn for semiconductors, equal to 76% of the total. The numbers are large and can easily make the market worry about supply discipline. But Goldman Sachs’ breakdown is more nuanced: the plan spans 15 years, may include R&D; spending, and most of the capital corresponds to existing fabs, advanced lines, HBM-related capacity, and new clusters.
Goldman Sachs believes the plan’s implied growth rate is reasonable, with the key being to view the investment on a long-term horizon. If R&D; is included, Samsung’s domestic CapEx plus R&D; over the next 15 years averages around W163tn per year. In Goldman Sachs’ existing forecasts, Samsung’s consolidated CapEx plus R&D; for 2026-2028 is already at a high level. If domestic share is then assumed at around 80% and spending grows by roughly 6% after 2029, cumulative domestic investment approaches the announced scale.
Two issues need to be separated here: long-term capacity commitment and near-term supply shock. Long-term investment plans improve forward visibility for equipment, materials, and advanced-packaging chains, but they do not immediately change 2026-2027 HBM supply-demand. Fab construction, equipment delivery, yield ramp-up, customer qualification, and contract lock-in all take time, especially because HBM is more constrained by advanced packaging and yield.
9. CapEx Discipline: The Market’s Real Concern Is the Post-2028 Supply Shadow
Every memory upcycle faces the same question: once prices rise, will manufacturers start expanding capacity again? Samsung’s W2,450tn plan is sensitive because it reinforces two narratives at the same time. The first is that AI memory demand is strong enough that leaders must prepare future supply. The second is that leaders are resuming CapEx, and supply may gradually increase over the next several years.
Both narratives are valid; timing is the key. In 2026-2027, the main supply bottlenecks are HBM, advanced packaging, yield, and customer qualification. Ordinary fab investment is unlikely to quickly change the outcome. After 2028, if CapEx keeps rising, equipment delivery is smooth, and customer-demand growth slows, supply pressure will become more visible. What the market needs to judge now is whether share prices reflect near-term pricing leverage or have already begun to reflect long-term supply risk.
The easiest mistake in investment research is to treat a long-term CapEx plan as near-term capacity. Samsung’s investment announcement does not mean DRAM supply increases immediately. But it will make the market ask questions about capital returns earlier. As long as prices are high, inventories are healthy, and free cash flow improves, long-term investment will be read as strategic investment. If prices fall, inventories build, and cash flow weakens, the same investment plan will be reinterpreted as supply risk.
10. Samsung Valuation: Goldman Sachs Is Focused on Memory Earnings, Long-Term Agreements, and Shareholder Returns
In its Samsung event note, Goldman Sachs maintained positive ratings on the common and preferred shares and set 12-month target prices of W480,000 for the common shares and W360,000 for the preferred shares. The report uses an EV/EBITDA-based SOTP framework, with the core also including the earnings leverage, free cash flow, and shareholder-return assumptions behind the target prices.
This table shows that Samsung’s valuation leverage comes not only from price increases, but also from margin, cash flow, and capital returns. If DRAM and HBM prices remain high, Samsung’s income statement will recover faster than its revenue line. If free cash flow follows, the company can both invest in HBM and advanced capacity and maintain shareholder returns. Goldman Sachs’ emphasis on higher long-term agreement coverage indicates that it believes the strength of customer contract commitments in this cycle may be higher than in past cycles.
Samsung’s risks are also clear. First, deterioration in memory supply-demand would directly hit prices and margins. Second, if smartphone margins compress, group earnings quality would suffer. Third, if mobile OLED share falls, support from non-memory businesses would weaken. For the market, the real debate is whether Samsung’s memory improvement can offset CapEx and volatility in non-memory businesses.
11. Long-Term Agreements and HBM Customer Lock-In: Can This Cycle See Less Inventory Swing?
Goldman Sachs notes in its Samsung investment thesis that customer obligations in long-term agreements may be stronger than in the past. This is crucial. The classic problem in the memory industry has been the inventory cycle: customers place early orders when prices rise, then destock when prices fall, causing large swings in supplier profits. If long-term agreement coverage improves, memory vendors can lock in volumes, prices, and capacity allocation earlier.
AI-server customers are different from ordinary consumer-electronics customers. Cloud providers care more about certainty in the delivery of training clusters and inference services. Memory shortages can affect system go-live and monetization of compute capacity, so they are more willing to lock in supply. HBM is also harder to substitute than standard DRAM, has a longer qualification cycle, and creates stronger supplier-customer binding. These factors may all reduce the amplitude of the traditional inventory cycle.
But long-term agreements do not eliminate the cycle. If customer CapEx contracts in the future, or if the pace of AI compute buildout slows, contracts will also be renegotiated. The more reliable research approach is to look at long-term agreements, shipments, inventory, and cash flow together. Long-term agreements improve earnings visibility, inventory and cash flow validate earnings quality, and pricing validates supply-demand tightness. Missing any one of the three affects valuation.
12. Equipment Chain: Samsung’s Long-Term Investment Gives WFE and Advanced Packaging Longer Order Visibility
Samsung’s W2,450tn plan may matter more directly for the equipment chain than for near-term DRAM prices. Fabs, HBM lines, advanced packaging, and new display lines all require equipment, materials, substrates, testing, and automation systems. Even if the investment cadence is extended, the long-term CapEx commitment will improve order visibility for the equipment chain.
For equipment stocks, the best combination is strong prices, strong customer cash flow, and disciplined CapEx. Strong prices mean memory vendors are making money. Strong customer cash flow means investment capacity exists. Disciplined CapEx means expansion will not break the industry too quickly. Samsung’s plan satisfies the first two conditions; the third will need to be validated by the subsequent order cadence.
The equipment chain will also be affected by changes in the HBM mix. HBM relies more than ordinary DRAM on advanced packaging, testing, and yield control. It has higher value per unit and a more complex equipment structure. As a result, even if total wafer capacity growth is not extreme, a higher HBM mix can drive higher equipment and materials content. This is one of the biggest differences between the AI memory cycle and the traditional memory cycle.
13. Samsung, SK hynix, Micron, and Niche Vendors: Same Price Cycle, Different Valuation Logic
In this memory upcycle, the logic differs materially by company. Samsung Electronics is about HBM catch-up, group cash flow, and long-term CapEx. SK hynix is about leading HBM share and AI-customer lock-in. Micron is about US AI customers, HBM qualification, and DDR5 earnings leverage. Niche vendors such as Nanya Technology are about DDR4 and legacy-memory price increases. Goldman Sachs’ DRAM sentiment indicator connects these themes, but they should not be collapsed into a single trade.
This order helps explain Goldman Sachs’ report structure. It does not look only at Samsung or only at HBM. Instead, it combines conventional DRAM, legacy memory, the server chain, and channel feedback through the sentiment indicator. For the market, Samsung Electronics is more like a “full-spectrum memory asset”: it has HBM catch-up leverage, benefits from ordinary DRAM price increases, and also carries long-term CapEx and diversified group businesses. Its strength is breadth, and its weakness is also breadth. A single variable cannot fully explain its share price.
14. Three Worldviews: Price-Increase Cycle, AI-Memory New Normal, and Post-CapEx Cycle
Over the next 12 to 24 months, the memory industry may switch among three worldviews. The first is a price-increase cycle: prices rise, inventories decline, earnings recover, and the market values the sector as traditional cyclicals. The second is an AI-memory new normal: HBM and DDR5 demand stays above supply, long-term agreements and customer lock-in improve earnings visibility, and the market treats memory leaders as core AI-infrastructure assets. The third is a post-CapEx cycle: leaders increase investment, forward supply pressure rises, and the market compresses valuations in advance.
Current evidence better supports a crossover between the first two worldviews. DDR5 and DDR4 price increases show that the traditional cycle is still present, while the HBM price upgrade shows that the AI-memory new normal is being incorporated into models. The risk of a post-CapEx cycle has appeared, but it is not yet the near-term dominant factor, because new capacity takes time to come online and HBM bottlenecks are not only in fabs.
This framework also explains why memory stocks can be highly volatile. As long as price data remain strong, the market will value the sector through the price-increase cycle and the AI-memory new normal. Once CapEx becomes too fast, inventories rise, or end-device shipments weaken, the market can immediately switch to the post-CapEx-cycle worldview. Investment research needs to rotate dynamically among these three worldviews rather than use one story for every stage.
15. Model Bridge: From DDR5 Spot Prices to Samsung Valuation, There Are Six Gates
There is a clear model bridge between the two Goldman Sachs reports. DDR5 spot-price increases first affect expectations for contract prices. Contract prices enter the income statements of Samsung and peers. Income-statement improvement lifts cash flow. Cash flow supports CapEx and shareholder returns. CapEx then feeds back into future supply expectations. HBM price upgrades act as an amplifier on this bridge.
The weakest link in this bridge is usually cash flow. In upcycles, the memory industry can easily show attractive earnings while inventories rise and cash flow lags. If Samsung’s earnings recovery is accompanied by free-cash-flow improvement, the market will be more willing to believe this cycle is higher quality. If earnings improvement is consumed by CapEx and inventory, the long-term investment plan will become valuation pressure.
HBM changes the slope of the bridge. Ordinary DRAM price increases mainly affect ASP. HBM price upgrades simultaneously affect product mix, customer lock-in, and long-term margins. If Samsung continues to advance in HBM qualification and share, valuation will focus more on the 2027 and 2028 earnings step-up. If HBM progress is below expectations, the market will put Samsung back into a conventional DRAM-cycle framework.
16. Disconfirmation Checklist: Signals That Would Cool This Re-Rating
The memory re-rating has obvious two-way leverage. Current prices, exports, and server-chain data are strong, but disconfirming signals need to be listed in advance. The most important disconfirmation is not one month of price volatility, but multiple indicators weakening at the same time: spot-premium compression, difficulty raising contract prices, inventory increases, weak smartphone and PC demand, lower-than-expected HBM pricing negotiations, and an overly fast Samsung CapEx cadence.
The purpose of this checklist is to avoid attributing every increase to “strong AI demand.” Strong AI demand can explain the server chain and HBM, but it does not automatically guarantee healthy consumer demand, inventory, cash flow, and CapEx. A high-quality re-rating requires rising prices, real demand, controlled inventories, and disciplined CapEx. A low-quality re-rating relies only on price and sentiment.
17. What to Watch Over the Next Four Quarters
Over the next several quarters, the research focus has shifted from a single target price to several datasets that can validate one another. The first group is DDR5 and DDR4 contract prices, which validate whether spot premiums are entering customer contracts. The second group is Korean DRAM exports and server ODM revenue, which validates whether AI demand continues to translate into shipments. The third group is Samsung HBM qualification, shipments, and pricing, which validates the 2027 price assumption. The fourth group is inventory, cash flow, and CapEx, which validates earnings quality.
These six indicators need to be read together. If DDR5 contract prices rise, HBM pricing expectations continue to move up, Korean exports stay high, and Samsung’s inventory and cash flow are healthy, the memory re-rating will be steadier. If prices rise but inventory and cash flow diverge, the market will first weaken the optimistic scenario and then return to conventional cyclical valuations.
18. Mapping to A-Shares and Hong Kong Stocks: Watch Legacy Memory, Equipment, and the AI-Server Chain
Although these two Goldman Sachs reports mainly focus on Korean memory and Samsung Electronics, they also map to the Chinese market. The first mapping is legacy-memory price increases: DDR4, SLC NAND, NOR, and niche DRAM are all affected by major vendors’ resource migration. The second is the equipment chain: Samsung’s long-term investment improves global WFE and advanced-packaging order visibility. The third is the AI-server chain: DDR5, HBM, PCB, optical modules, liquid cooling, and power supplies are all in the same CapEx cycle.
Simple analogies should be avoided when mapping. Samsung Electronics has HBM, DRAM, NAND, smartphones, displays, and fab-investment capabilities. Chinese-market related companies often correspond to only one segment. Legacy-memory companies are more affected by pricing and inventory, equipment-materials companies by CapEx, and the AI-server chain by cloud providers and system shipments. Only by separating these variables can investors judge which companies benefit from pricing, which benefit from orders, and which are only being carried by sentiment.
19. Data Framework: Price Moves First, Profit Follows, Inventory Tells the Truth Last
The easiest way to misjudge the memory cycle is to ignore the different response speeds of different data. Spot prices move fastest, contract prices usually lag, margins lag further, and inventory and cash flow confirm later. Goldman Sachs puts daily prices, monthly revenue, exports, the quarterly second derivative of ASP, and channel feedback into one sentiment indicator in order to place data with different speeds on the same dashboard.
This sequence helps determine the stage of the rally. If spot prices rise first, contract prices then rise, and exports and revenue also strengthen, price transmission is working. If gross margins and cash flow continue to improve, price increases are becoming high-quality earnings. If inventories rise and cash flow fails to keep up, companies may be using stocking to pull forward earnings quality. Past memory cycles have repeatedly shown that inventory and cash flow are often more honest than revenue.
Current data are in the middle stage: prices and exports are already strong, and the server chain has also provided validation. The next items to watch are contract prices, margins, and inventory. Samsung especially needs to use cash flow to prove that this round of CapEx is sustainable. If Goldman Sachs’ free-cash-flow assumptions are realized, long-term investment will be read by the market as strategic spending. If free cash flow is weaker than earnings, the W2,450tn plan will be reassessed.
This also explains why Goldman Sachs uses a moderately positive, rather than extremely positive, description even though the DRAM sentiment indicator is strong. Prices have already provided a sufficiently strong signal; the next step is for margins, contract prices, and inventory to continue delivering. What the market needs to buy into is that in the first half, price increases have happened, and in the second half, those price increases leave behind cash flow.
20. ROIC Validation: Samsung’s Long-Term Investment Ultimately Returns to Capital Returns
The final question for Samsung’s W2,450tn plan is capital returns. The semiconductor industry can earn very high profits in upcycles, but it can also bear depreciation pressure after oversupply. Goldman Sachs’ view that the long-term growth rate is reasonable only answers whether the investment scale is excessive. It does not yet answer whether returns on investment can cover the cost of capital.
This framework is more useful than looking at investment scale alone. If Samsung directs resources into HBM, advanced packaging, and high-end DRAM, and locks in customers through long-term agreements, CapEx will raise the future profit center. If investment flows more toward ordinary capacity, or if high-end product qualification is difficult, new depreciation will pressure returns a few years later. The market’s disagreement over Samsung’s valuation is essentially a set of different judgments on this table.
ROIC also determines the quality of the equipment-chain rally. Higher equipment orders are positive for upstream company revenue, but if end-customer capital returns weaken, the sustainability of equipment orders will decline. A high-quality equipment rally requires memory customers to make money, generate good cash flow, and have a clear CapEx direction. A low-quality equipment rally relies only on a large investment announcement and has weaker durability.
From this perspective, the two Goldman Sachs reports do not conflict. The DRAM sentiment indicator shows that near-term profits are improving, while Samsung’s long-term investment plan shows that leaders are willing to commit capital for future demand. What truly needs validation is whether near-term profits can turn into cash flow and whether long-term investment can turn into ROIC. Only if both links hold can the memory rally move from cyclical recovery to asset re-rating.
21. HBM Supply Gates: Price Upgrades Ultimately Need Delivery
HBM price upgrades cannot be assessed only through demand. AI customers are willing to pay a premium for certainty, but suppliers must deliver sufficient quantity, qualified yield, and stable performance. HBM supply gates can be roughly divided into four layers: high-end DRAM wafers, stacking and packaging, testing and yield, and customer qualification and software ecosystem. If any layer has a problem, price leverage will be discounted by delivery risk.
Samsung’s core task is to turn HBM catch-up into deliverable customer share. Goldman Sachs’ more optimistic 2027 HBM pricing gives Samsung greater earnings leverage, but the market will ultimately watch qualification, shipments, and yield. If price assumptions rise but delivery does not keep up, valuation will first reflect optimism and then be corrected by reality. If delivery and price are both realized, Samsung will move from a conventional DRAM recovery asset closer to a core AI-memory asset.
HBM also feeds back into ordinary DRAM. When leaders put more wafers, engineering resources, and packaging capability into HBM, supply elasticity for mature DRAM and parts of legacy memory is reduced. This is one of the underlying reasons DDR4, DDR5, and legacy memory prices are rising together. As long as HBM continues to absorb major vendors’ capacity resources, supply constraints in mature categories can persist for longer.
22. Price-Increase Quality Check: Contract Prices, Inventory, and Cash Flow Must All Pass
DRAM price increases can be high quality or low quality. High-quality price increases come from real demand, customer lock-in, higher shipments, and healthy inventories. Low-quality price increases come from short-term restocking, channel hoarding, or supply disruption. The two may look similar in spot prices, but they diverge in contract prices, inventory, and cash flow.
This table also explains why Goldman Sachs focuses on DDR5, HBM, and Samsung’s long-term investment at the same time. DDR5 spot prices are the starting point for the price increase. HBM long-term agreements are the amplifier of price-increase quality. Samsung’s investment plan is the result of whether price increases can turn into long-term capital returns. If the three match, the industry enters a high-quality upcycle. If they diverge, the rally shifts from earnings upgrades for leaders to repricing of supply risk.
For Samsung, the most important issue is to link investment scale with customer demand. If high-end DRAM, HBM, and advanced-packaging investments have clear customers, clear prices, and clear delivery schedules, the market will be willing to assign a higher valuation. If investment merely expands future capacity, the market will start worrying earlier about depreciation and price declines.
23. Scenario Framework: Base Case Watches Contract Prices, Bull Case Watches HBM, Stress Case Watches Inventory
Combined, the two Goldman Sachs reports form three scenario frameworks. The base case watches whether DDR5 and DDR4 spot premiums enter contract prices, determining whether 2026 earnings upgrades can continue. The bull case watches 2027 HBM pricing and Samsung’s HBM delivery, determining whether the industry can move from an ordinary price-increase cycle into an AI-memory new normal. The stress case watches inventory, cash flow, and CapEx cadence, determining whether the market will switch early to a post-supply-cycle framework.
The core of the base case is contract prices following spot prices. DDR5 spot prices have already given a price-increase signal, and the DDR4 premium is higher. But entry into the income statement requires contract confirmation. If quarterly contract prices continue to rise, Korean exports remain high, and server ODM revenue does not stall, memory vendors’ 2026 earnings upgrades will become more credible. In this scenario, the market will continue valuing the sector on income-statement improvement, but it will remain disciplined on long-term multiples because CapEx and supply risk have already been brought to the table by Samsung’s investment plan.
The core of the bull case is HBM shifting from price upgrades to delivery upgrades. Goldman Sachs has materially raised Samsung’s 2027 HBM price assumption, already showing a change in the forward pricing anchor. If Samsung’s HBM qualification, yield, and customer share advance together, the market will reprice it from a conventional DRAM recovery asset into an AI-memory platform asset. This scenario would raise Samsung’s own valuation and also drive value-content re-rating across advanced packaging, testing, substrates, equipment, and materials.
The core of the stress case is strong prices but weak quality. Spot prices can rise and earnings can improve, but if inventories rise at the same time, cash flow fails to keep up with earnings, and CapEx cadence accelerates, the market will worry that this upcycle is pulling forward future demand. The stress case usually hurts valuation multiples first and earnings estimates later. In other words, share prices may correct while earnings still look good because the market has already begun discounting the post-supply cycle.
These three scenarios will not necessarily unfold in sequence. The market will switch back and forth among different data points. When prices and exports are strong, the base case dominates. When HBM qualification and pricing continue to beat expectations, the bull case dominates. When inventory, cash flow, or CapEx diverges, the stress case dominates. The most practical research method is to place each new datapoint into these three frameworks and avoid being pulled around by a single month of prices or one CapEx headline.
For Samsung Electronics, the base case corresponds to DRAM earnings recovery, the bull case corresponds to successful HBM catch-up, and the stress case corresponds to doubts about CapEx returns. For the industry, the base case supports memory-stock earnings upgrades, the bull case supports an AI-memory valuation reset, and the stress case reminds the market that memory remains cyclical. Separating these three layers is the only way to understand why Goldman Sachs is emphasizing DDR5 pricing, 2027 HBM, and Samsung’s long-term investment at the same time.
24. Where This Memory Rally Is Easiest to Misread
The first misread is to equate DDR5 spot-price increases directly with price increases across all memory categories. DDR5, DDR4, HBM, NAND, and SLC NAND have different supply-demand structures and different price-transmission speeds. DDR5 spot prices can lead contract prices, HBM depends more on customer lock-in and advanced packaging, and legacy memory is more affected by mature-capacity migration. Research needs to separate the categories.
The second misread is to treat Samsung’s long-term investment as near-term supply pressure. W2,450tn sounds large, but the plan spans 15 years and may include R&D.; Near-term DRAM and HBM supply-demand are still determined by existing capacity, yield, customer qualification, and packaging capacity. Long-term investment will affect post-2028 supply expectations, while near-term pricing still depends on contracts and inventory.
The third misread is to look only at target-price or rating actions. Goldman Sachs’ high target price for Samsung depends on memory earnings, long-term agreements, HBM progress, cash flow, and shareholder returns. If these variables are validated together, valuation has support. If only price increases remain, without cash-flow and inventory validation, valuation will return to a cyclical framework.
The fourth misread is to ignore pressure on the consumer side. AI-server demand is very strong, but smartphones and PCs remain sensitive to memory prices. If memory prices rise too quickly, device vendors will reduce configurations or delay procurement. Consumer demand is not the main driver of this rally, but it is an important constraint for testing whether price increases can transmit broadly.
25. Conclusion: The Memory Rally Has Entered the Stage of “From Price Realization to Forward Pricing”
The information from these two Goldman Sachs reports can be placed on a timeline: DDR5 and DDR4 spot prices have risen since May; the June DRAM sentiment indicator remains moderately positive; Korean DRAM exports and server-chain data remain strong; the 2027 HBM price assumption has been materially raised; and Samsung has announced a 15-year domestic investment plan. This timeline shows that the memory rally has moved from price recovery into forward pricing.
For Samsung Electronics, the short term is about DRAM and HBM earnings leverage, the medium term is about HBM qualification, customer long-term agreements, and free cash flow, and the long term is about whether the W2,450tn investment can translate into high ROIC while avoiding becoming ordinary capacity expansion. For the memory industry, the DDR5 spot premium is the leading indicator for contract prices, HBM price upgrades are the valuation amplifier, and CapEx discipline is the key to extending the cycle.
The final judgment is more direct: as long as DDR5 contract prices continue to follow, 2027 HBM pricing negotiations remain strong, and Korean exports and AI-server-chain data do not stall, memory stocks will continue to trade on a higher earnings step-up. If inventories rise after prices reach high levels, cash flow weakens, and Samsung’s CapEx cadence becomes too fast, the market will shift early toward the post-supply cycle. Over the next several quarters, the most important work is no longer to find a bigger story, but to validate this story item by item through price, inventory, cash flow, and CapEx.