
目录
Executive Summary
From January’s Peak to Renewed Strength in August: A Relative Low After a Major Drawdown
The Core Issue: Can Real Rates Decline?
Why Traditional Valuation Models Say Gold Is Expensive—Yet Prices Do Not Revert to the Old Framework
Central-Bank Buying Provides a Floor, Not Daily Price Support
ETFs and Private Capital: The First Piece of an Upside Breakout Is in Place
Why Silver Is Not Simply “Cheaper Gold”
Three Second-Half Scenarios: Moving from the Middle Toward the Top of the Range
The Six Most Important Signals to Track Next
What Would Invalidate the Structural Bull Case
Conclusion: Gold Is Not Expensive Relative to Its January Peak, and a New Uptrend Is Seeking Confirmation
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Gold remained about one-quarter below its January peak of roughly $5,595 in early August. However, after five months of consolidation, both prices and fund flows are strengthening. The next key test is whether gold can break through the $4,306–$4,483 resistance zone.
Executive Summary
Gold should be assessed against two reference points. In a long-term historical context, roughly $4,100–$4,300 remains exceptionally expensive. But relative to January’s intraday peak of $5,595.47, gold was still about one-quarter lower in early August. It is no longer trading “near the peak,” but recovering from a deep drawdown.
The price action has unfolded in three stages: an accelerated surge to the January peak; a choppy decline from February through June, bottoming around $3,959–$4,002; and renewed strength from July into early August. In early July, the World Gold Council concluded that gold had completed a minor bottom and that the short-term trend might be turning higher. By August 6, the year-to-date decline had narrowed further to 2.3%, while precious-metals funds had recorded five consecutive weeks of inflows.
This remains a breakout “attempt,” not confirmation of a new bull market. $4,221 is the first resistance level, while $4,306 is the key retracement level for the decline since April. Only a sustained move through the dense $4,382–$4,483 resistance zone would indicate that the nearly six-month consolidation is developing into a medium-term trend reversal.
The primary variable for the second half is not whether the Federal Reserve will cut rates immediately, but whether real rates can decline. On July 29, the Fed held the federal funds target range at 3.50%–3.75%, while three members favored a 25-basis-point increase. Gold’s near-term opportunity cost therefore remains unfavorable.
Traditional models do show that gold is expensive, but they fail to capture central-bank reserve diversification, Asian physical demand, undisclosed official-sector purchases, and insurance against fiscal and monetary credibility risks. Gold’s valuation question has shifted from “what price is consistent with interest rates?” to “what premium are global investors willing to pay for insurance independent of sovereign credit?”
Central-bank buying provides a structural floor, not daily price support. Silver, by contrast, lacks central-bank demand, has thinner inventories, and trades in a smaller market. It is better viewed as a high-beta confirmation signal for a precious-metals rally than as a cheaper substitute for gold.
From January’s Peak to Renewed Strength in August: A Relative Low After a Major Drawdown
The path documented by the World Gold Council was extreme. The LBMA Gold Price reached $5,405/oz on January 29, 2026, while spot gold touched an intraday high of $5,595.47. On June 24–25, spot and the LBMA benchmark fell to $3,959.33 and $4,001.80, respectively. The maximum intraday drawdown was approximately 29% in less than five months. Weekly monitoring on July 6 showed gold rebounding 2.3% to $4,164 after five consecutive weekly declines, narrowing its year-to-date loss to 4.7%. By August 6, Bank of America’s cross-asset data showed gold’s year-to-date return improving further to -2.3%. Precious-metals funds attracted $900 million that week, marking five consecutive weeks of inflows.
Taken together, these figures describe the price structure more accurately than simply saying that “gold remains elevated.” The first stage was January’s accelerating blow-off move, when safe-haven demand, options activity, and trend-following capital pushed prices away from equilibrium. The second was a valuation and positioning reset from February through June, with prices oscillating lower before ultimately losing roughly one-quarter to three-tenths. The third began in July: the low near $4,000 did not extend further downward, while prices, momentum, and fund flows began recovering in tandem. Market commentary cited in the July news roundup likewise started from the premise that gold had fallen approximately 25% from its January peak, rather than defining current levels as being near the peak.
Any description of gold as “high” or “low” therefore requires a clear reference point. Relative to the long-term price range before 2024, gold is unquestionably still expensive. Relative to the extreme January 2026 peak, however, it is trading in the lower-to-middle portion of the range following a substantial drawdown. This distinction matters for new capital: investors are no longer assuming the same risk as chasing gold near $5,595. Instead, they must determine whether a bottom has formed and whether the breakout is credible after cyclical prices have already corrected by about one-quarter, even though long-term valuation remains expensive.
The technical structure has delivered its first positive signals. On July 6, the World Gold Council noted that gold had failed to sustain a break below $4,075, the 38.2% retracement of its long-term uptrend. The daily relative-strength indicator formed a bullish divergence, a minor bottom had been completed, and the short-term trend might be turning higher. The subsequent narrowing of the year-to-date decline and five consecutive weeks of precious-metals fund inflows indicate that the rebound is no longer merely a one-day safe-haven impulse. The report nevertheless emphasized that this may still be a recovery within a broader downtrend: $4,221 is the first resistance level, $4,306 is the critical dividing line, and $4,382–$4,483 is the more formidable cluster of moving-average and trend resistance.
This price action also disproves an overly simplistic narrative: geopolitical conflict does not necessarily cause gold to rally immediately. If conflict initially drives oil prices and inflation expectations higher, markets will reprice the risk of rate increases, lifting the dollar and real yields. At the same time, if equities and bonds come under pressure together, investors holding call options or highly leveraged positions may sell gold to raise liquidity. Safe-haven demand remains present, but can be suppressed in the short term by opportunity costs and deleveraging.
Goldman Sachs captured the balance accurately in April: “structurally bullish, tactically cautious” on gold. It still forecast $5,400 by year-end 2026, but acknowledged that an energy-supply shock or declines in bonds or equities could trigger further liquidation. The World Gold Council offered a more conservative framework for the second half. Using approximately $4,100 as the reference level, the consensus macroeconomic scenario implied a trading range of roughly ±5%. Weaker growth, rising risk, or a dovish shift in rate expectations could produce 5%–20% upside, while resilient growth, higher yields, and improving risk appetite could result in 5%–15% downside. The July news roundup’s expectation of a rebound toward $4,500 was also closer to a post-drawdown recovery target than a straightforward return to January’s record high. These are not conflicting price targets; they price different macroeconomic assumptions and different stages of the market cycle.
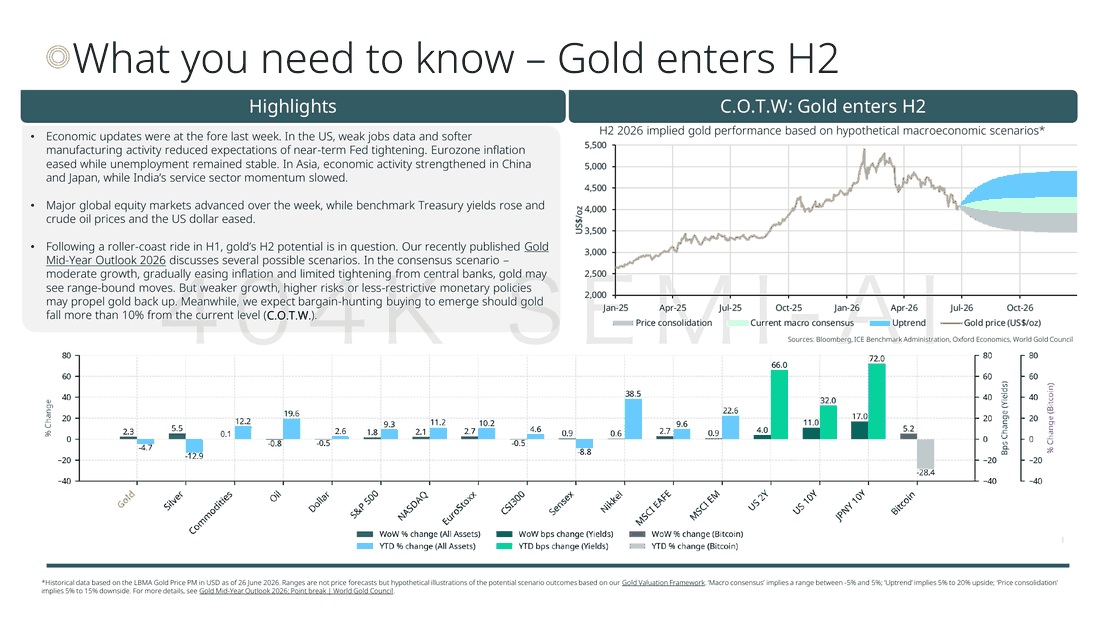
Figure 1: Gold reached a record high and suffered a deep drawdown in the first half of 2026; its second-half trajectory depends on the macroeconomic scenario. Source: World Gold Council, July 6, 2026, p. 2.
