
Global Memory Deep Dive Update: DRAM Up 74%, NAND Up 60%, LTAs and Profit Validation After the 3Q Slowdown
目录
Too Long; Didn’t Read
1. What the June Price Tracker Really Means: Price Increases Are Not Over, but the Fattest Part May Have Passed
2. DRAM: The Hardest Signals Are in Server DDR5 and Specialty DRAM
III. NAND: Pricing Still Rising, but Divergence Is Emerging Earlier Than in DRAM
IV. LTAs: From Sentiment Catalyst to Valuation Discount Rate
V. Consumer Demand Destruction: Not a Cycle Reversal, but Already the First Item on the Counter-Evidence List
VI. Company Ranking: Samsung Electronics, SK hynix, Micron, and SanDisk Remain Longs; Kioxia Looks More Like the Disconfirming Name
VII. Valuation Discipline: Low P/E Is Not Enough; Contracts and Cash Flow Are the Antidote to Cycle Discounts
VIII. Four Tracking Indicators: The Next Phase Is About Profit Quality, Not Just Price Increases
9. Investment View: Memory Has Not Reversed, but It Has Entered a Tougher Second Phase for Making Money
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Bernstein’s June global memory price tracker moves the memory trade into a more selective phase: 2QCY26 prices are still surging, but 3QCY26 increases are starting to slow. Long-term agreements (LTAs) are moving from narrative to valuation core. From here, the market will not only look for higher prices, but also for which companies can convert pricing into sustainable profits.
Too Long; Didn’t Read
2QCY26 price increases are already strong enough; the debate has shifted to the 3QCY26 slope. Bernstein’s June contract checks show conventional DRAM ASPs in 2QCY26 were roughly 74% above 1QCY26, while NAND was roughly 60% higher when SSDs are included. The trading focus has shifted from “will prices rise?” to “can higher prices sustain margins?”
DRAM looks more like a scarce asset than NAND. PC, server, mobile, and specialty DRAM all continued to reprice higher in June. Server DDR5 spot prices rose as much as 26.4% month-on-month, while specialty DRAM rose 105%-108% quarter-on-quarter in 2Q. By contrast, NAND wafer spot prices fell 3%-4%, suggesting NAND strength is more about eSSD and mobile contracts than a broad, indiscriminate market shortage.
LTAs are changing valuation, but terms matter more than whether a deal was signed. U.S. cloud customers have become priority supply accounts. Micron Technology appears more tilted toward longer-cycle contracts, with price caps potentially near 2QCY26 levels. Samsung Electronics and SK Hynix may have higher LTA price caps. Negotiations with Chinese cloud customers are extending into 3QCY26, likely on weaker terms than U.S. cloud customers. The key items to track are price floors, caps, volumes, duration, prepayments, and penalties for non-performance.
Consumer demand destruction is emerging, but has not overwhelmed AI servers. Smartphone OEMs have already adjusted production plans and memory content. Bernstein expects 2026 smartphone shipments to fall 16%, with 2QCY26 down more than 10%. But server DRAM, eSSD, network switches, autos, and AI-related legacy DRAM are still absorbing supply. Memory has not topped yet; the question is how much pricing ordinary consumer demand can bear.
Company ranking needs to shift from “pricing leverage” to “price ceilings and contract quality.” Bernstein remains constructive on Samsung Electronics, SK Hynix, Micron, and SanDisk, with target prices of KRW 440,000, KRW 3,300,000, USD 1,300, and USD 3,000, respectively. Kioxia is rated Underperform with a JPY 40,000 target price. This ranking is not simply about cheapness, but about exposure to DRAM/HBM, LTAs, eSSD, and Chinese NAND competition.
The four metrics to track most closely. First, whether 3QCY26 DRAM contracts can hold 13%-18% increases. Second, whether NAND eSSD continues to outperform wafers and mobile. Third, whether LTAs disclose hard terms. Fourth, whether consumer demand destruction spreads from smartphones and PCs into servers or cloud procurement. As long as AI servers and eSSD keep absorbing supply, pullbacks look more like valuation digestion. The true cycle-top signal would be LTAs softening, spot prices turning down, and customers rejecting price hikes at the same time.
1. What the June Price Tracker Really Means: Price Increases Are Not Over, but the Fattest Part May Have Passed
The first conclusion from Bernstein’s June global memory tracker is clear: 2QCY26 price strength continues to exceed traditional cycle experience. Conventional DRAM contract prices continued to rise month-on-month in June. On a sample-weighted basis, 2QCY26 prices were roughly 74% above 1QCY26, about 10 percentage points higher than what May contracts had implied. For NAND, if looking only at wafer and eMMC/UFS samples, 2QCY26 prices rose about 42%; but if client SSD and enterprise SSD are included, Bernstein believes a more reasonable industry measure is around 60%.
These numbers are already strong enough. The more important second-order message is that 3QCY26 prices will still rise, but the slope is clearly slowing. DRAM, PC DRAM, and mobile NAND are not shifting from rising to falling; they are shifting from aggressive repricing to a slower rate of increase. The segment-level increases are best checked in table form.
This is where the current memory trade is easiest to misread. If investors only look at 2QCY26 year-on-year and quarter-on-quarter moves, the conclusion looks very bullish. If they only look at slowing 3QCY26 increases, they may turn bearish too early. The more accurate reading is this: 2QCY26 lifted memory profits to a new level, and 3QCY26 will begin testing whether those profits can be locked in by LTAs, AI servers, eSSD, and supply discipline.
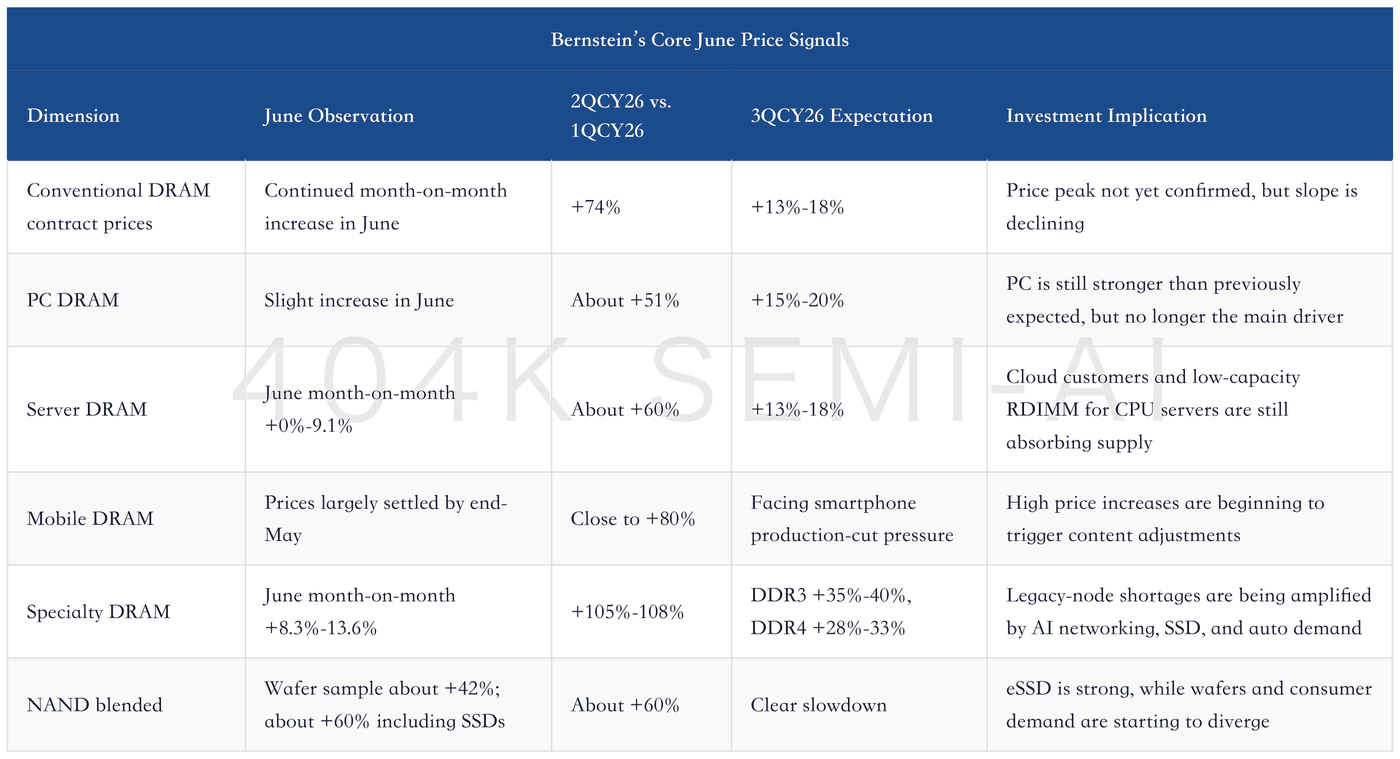
The point of this table is not that every number should be mechanically inserted into company models. It signals a change in valuation logic. Before 2QCY26, the market was mostly buying “price revisions.” Now price revisions have become consensus. The next phase is about “which prices will not fall back quickly.” That is why LTAs and product mix matter.
AI Drives a Sector-Wide Revaluation of Memory: Who Has the Strongest Pricing Power Across DRAM, NAND, SSD, and HDD, with Samsung, SK Hynix, SanDisk, Western Digital, and Seagate Earnings Cross-Validating the Thesis
The prior framework for a sector-wide memory revaluation still holds: AI is pushing HBM, system DRAM, eSSD, and the HDD capacity layer into higher demand centers at the same time. But the value of this tracker is that it connects the broad framework to monthly pricing evidence. It proves prices are still rising, while also reminding the market not to linearly extrapolate the steepest 2QCY26 slope into 2027.
2. DRAM: The Hardest Signals Are in Server DDR5 and Specialty DRAM
The most important thing in DRAM is not the 74% average increase, but the structure. PC DRAM is recovering, server DDR5 is strong, mobile pricing is up sharply, and specialty DRAM is even more extreme. The supply-demand logic behind each category is completely different.
PC DRAM continued to rise in June. DDR4 8Gb chip spot prices rose 5.6% month-on-month, while DDR5 16Gb chip spot prices rose 11.5%. This suggests the earlier pullback caused by channel inventory release has been absorbed, with spot prices strengthening again. But PC is not the core source of profits in this pricing cycle. Most PC OEMs completed 2QCY26 negotiations in April, and June contract price changes were relatively moderate. Demand resilience came from factors such as MacBook Neo and Microsoft promotions, making PC more of a support factor than the main axis.
Server DRAM matters more. Server DRAM contract prices rose 0%-9.1% month-on-month in June, with 2QCY26 around 60% above 1QCY26. More importantly, spot server DDR5 module prices rose 6.1%-26.4% in a single month. DDR5 was especially strong, and spot prices remain meaningfully above contract prices. This means server DRAM remains supply constrained. Suppliers are indeed shifting capacity from other applications into server DRAM, and some supply is coming from wafers released by delayed HBM4 ramp-up, but new supply is being absorbed quickly by cloud customers and CPU server demand.
Specialty DRAM is an easily underestimated signal. Specialty DRAM contract prices rose 8.3%-13.6% month-on-month in June, with 2QCY26 up 105%-108% versus 1QCY26. This is not because traditional consumer electronics suddenly boomed, but because legacy-node supply is increasingly dependent on Taiwanese suppliers, while AI network switches, server SSDs, and auto applications still require legacy DRAM. At the same time, consumer customers are starting to reduce specifications, trying to cut costs by using lower-density or older-generation products. Short supply, fragmented demand, and difficult customer migration have made specialty DRAM the representative “mature component shortage.”
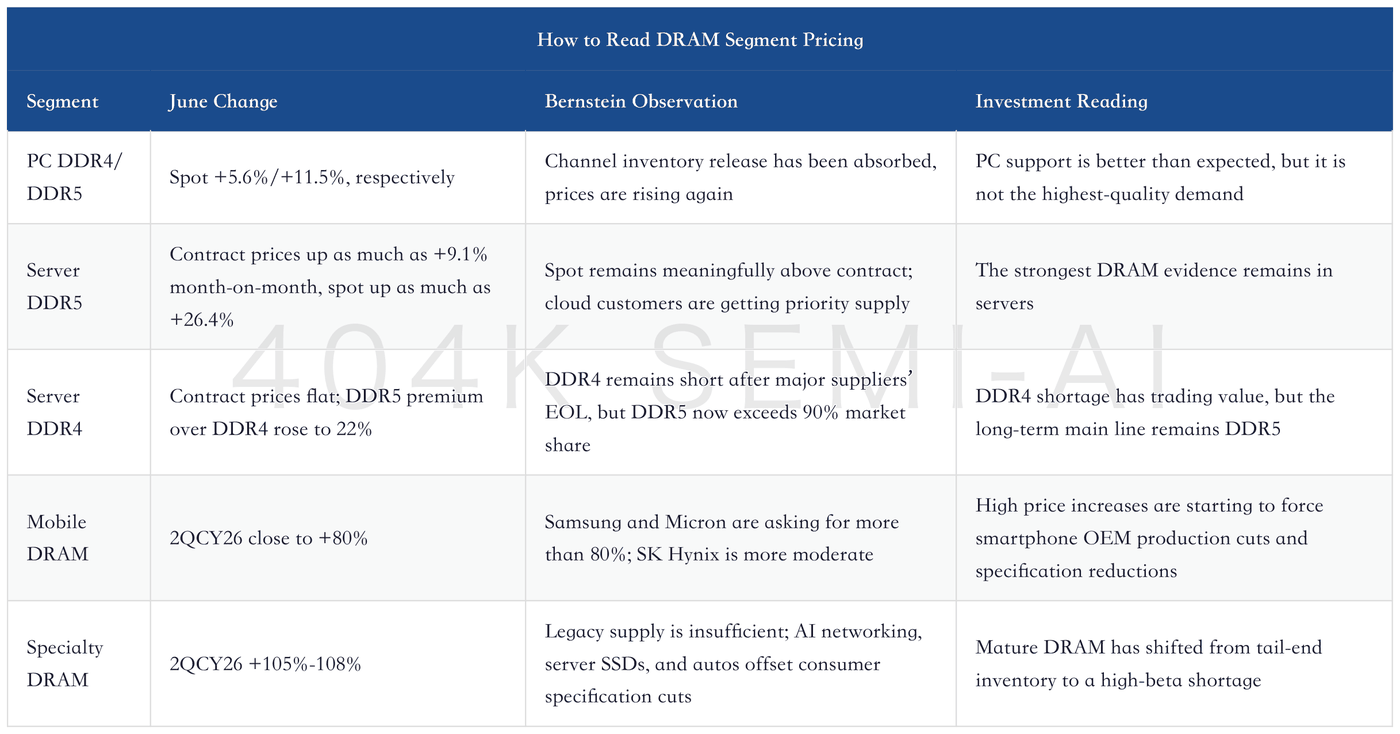
The investment implication for DRAM is therefore straightforward: looking only at “2Q price increases of 74%” misses structural differences; saying only “3Q is slowing” misses the continued tightness in server DDR5 and specialty DRAM. What really matters is whether server DDR5 contracts can hold after 3QCY26, whether LTA caps can move higher, and whether specification reductions in mobile and PC drag down the overall mix.
“price increase is still expected to decelerate into 3QCY26”
This short sentence matters more than the headline. It is not bearish; it is a reminder that the steepest part of margin expansion may already be entering the validation phase. If share prices continue to rise from here, they cannot rely only on prices surging further. They will need contract quality, product mix, and cash-flow quality.
III. NAND: Pricing Still Rising, but Divergence Is Emerging Earlier Than in DRAM
The June signals for NAND are more complex than for DRAM. On the surface, Bernstein estimates blended NAND pricing rose roughly 60% in 2QCY26, which is not weak. But on a disaggregated basis, wafer spot prices continued to fall 3%-4% in June, while wafer contract prices rose only 0.3%-3.7% MoM. What truly supported the industry average was mobile NAND and SSD, especially eSSD.
This suggests NAND is not experiencing an indiscriminate market-wide shortage. Wafer is only a small part of the NAND market, and spot wafer is even smaller, but it reflects module makers’ tolerance for high prices. By end-June, wafer spot prices were already 20%-25% below contract prices, and module makers had become cautious on wafer purchases, with procurement volumes declining. In other words, the NAND upcycle is not over, but lower-quality demand has started to say “no” to high prices.
What is really keeping NAND strong is UFS, mobile NAND, and SSD. TrendForce estimates mobile NAND prices rose 75%-80% in 2QCY26, while Bernstein believes SSD price increases may also be close to 70%, leading it to revise the overall NAND increase from the sample’s 42% to roughly 60%. This is consistent with the prior NAND industry update: AI eSSD and the data-center capacity layer are the highest-quality demand in this NAND cycle, while smartphones and ordinary consumer demand are more easily suppressed by high prices.
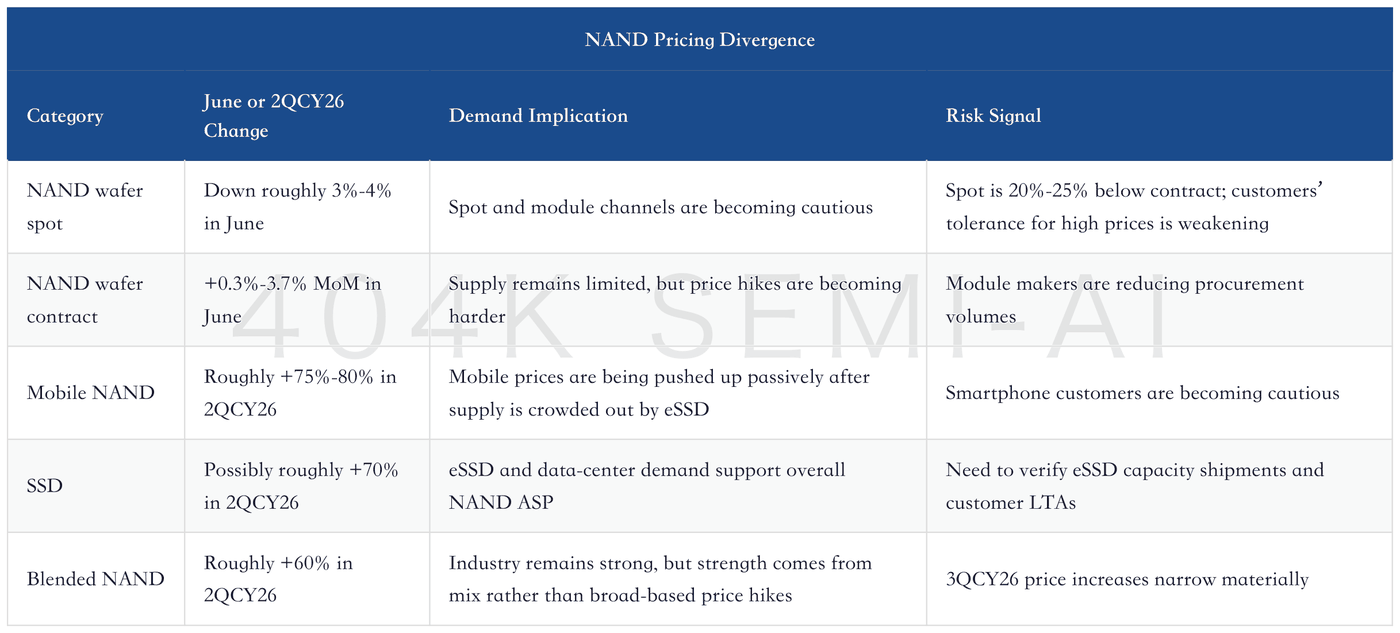
This is also why NAND requires more attention to supply discipline than DRAM. DRAM scarcity comes from HBM, server DDR5, legacy-node exits, and priority supply to cloud customers. NAND scarcity comes more from eSSD and manufacturers’ reluctance to shift resources back from DRAM/HBM to NAND. Once new NAND capacity or Chinese NAND competition accelerates, NAND is more likely than DRAM to revert to a cyclical framework.
NAND Industry Deep Dive: The Triple Test of AI eSSD Shortages, Supply Discipline, and New Capacity in 2028
The bullish case for NAND remains intact, but it is no longer “all NAND is rising.” A better description is that eSSD and high-capacity data-center demand continue to create shortages, while consumer-end demand and wafer are starting to encounter price ceilings. This divergence means NAND profitability at SanDisk, Kioxia, Samsung, Micron, and SK Hynix cannot be assessed only through industry average pricing; customer mix, eSSD qualifications, long-term agreement coverage, and the pace of new capacity also matter.
IV. LTAs: From Sentiment Catalyst to Valuation Discount Rate
The most valuable part of this report is not the price table, but the LTAs. Bernstein cites TrendForce’s observation that LTA negotiations with U.S. cloud providers are largely complete, while negotiations with Chinese cloud providers will continue into 3QCY26. More subtly, pricing ceilings may differ by supplier: Micron Technology prefers longer contract tenors, so its LTA price ceiling may be close to 2QCY26 prices; Samsung Electronics and SK Hynix may have higher ceilings.
This statement carries strong investment implications. An LTA is not simply “signing a long-term agreement.” It gives up and gains two things at the same time. What it gives up is some upside price elasticity; what it gains is revenue visibility and downside protection. If the price ceiling is too low, near-term profit may be lower than spot-price elasticity would imply. If the tenor is long enough, the floor price firm enough, and customer termination costs high enough, the valuation multiple can rise.
Therefore, the value of an LTA cannot be assessed only by coverage ratio. The real work is to break it into six variables: tenor, volume, price ceiling, price floor, prepayment, and take-or-pay or cancellation costs. A long tenor without a floor price does not reduce the cyclical discount. A floor price without minimum volume is also not firm enough. Only when volume, a floor price, and prepayment are all present does the contract approach “turning cyclical profit into discountable cash flow.”
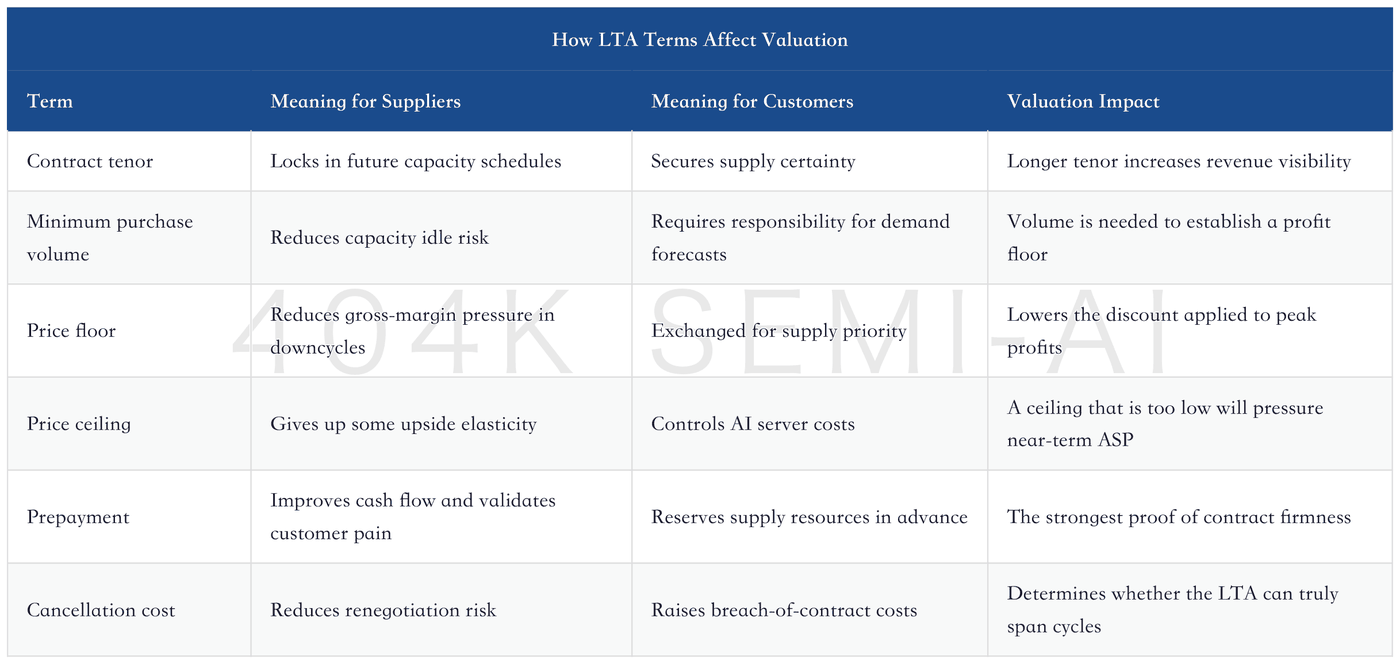
This is also the difference among Micron, Samsung Electronics, and SK Hynix. If Micron exchanges longer contracts for a price ceiling closer to 2QCY26 levels, near-term upside may be slightly lower, but revenue visibility is stronger. If Samsung Electronics and SK Hynix have higher price ceilings, near-term earnings elasticity is better, but contract tenor and customer commitments also need to be sufficiently firm. Terms from Chinese cloud providers may be less favorable than those from U.S. cloud providers, which would create tiering in supply guarantees and pricing terms.
“we don’t think spot prices will fall off a cliff”
This view explains why LTAs matter now. Suppliers do not believe spot prices will suddenly collapse, but they also know 3QCY26 price increases will slow. The best window to sign LTAs is often when customers still fear shortages, suppliers still have pricing power, but the price slope is starting to moderate.
V. Consumer Demand Destruction: Not a Cycle Reversal, but Already the First Item on the Counter-Evidence List
Bernstein’s wording on demand destruction is clear: consumer-end demand destruction will eventually happen. Smartphone OEMs have already adjusted production plans and memory content, and TrendForce expects 2026 smartphone shipments to decline 16%, with 2QCY26 down more than 10% YoY. With mobile DRAM and mobile NAND prices at these levels, customers will naturally reduce specifications, delay procurement, and lower inventory targets.
But this does not mean the memory cycle has reversed. There are two reasons. First, AI server and cloud demand is still absorbing supply, especially server DDR5, eSSD, and HBM-related capacity. Second, consumer-end specification downgrades may actually reinforce shortages in some legacy nodes, such as LPDDR4, DDR3/DDR4 specialty DRAM, and certain low-capacity mature products. When customers downgrade from high-end to lower-end specifications, total bit demand does not necessarily decline, but category-level price elasticity changes.
The truly dangerous scenario would be demand destruction spreading from the consumer side to the server side. Only if U.S. cloud providers reduce procurement, LTA terms soften, server DDR5 spot prices begin to fall below contract prices, and eSSD capacity shipments decline would the cycle move from “slower price increases” to “earnings downgrades.” We have not yet seen that evidence set.
