
Global Memory Deep Dive: 3Q26 DRAM Prices +21%, HBM4 Orders and NAND +10% Validation
目录
TL;DR
What This Report Actually Changes
Why DRAM Remains Stronger Than NAND
NAND Can Rise More Than 10%, but It Should Not Be Assessed Like DRAM
Why TSMC and ASML Provide Corroborating Evidence for Memory
Where Demand-Side Data Are Most Easily Misread
Investment View: The Bull Case Remains Intact, but the Path to Returns Has Changed
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
BofA’s latest channel checks shift the memory debate from “Will 3Q lose momentum?” to “How high will the post-deceleration pricing plateau be?” DRAM remains strong, while NAND and consumer markets have begun to diverge.
TL;DR
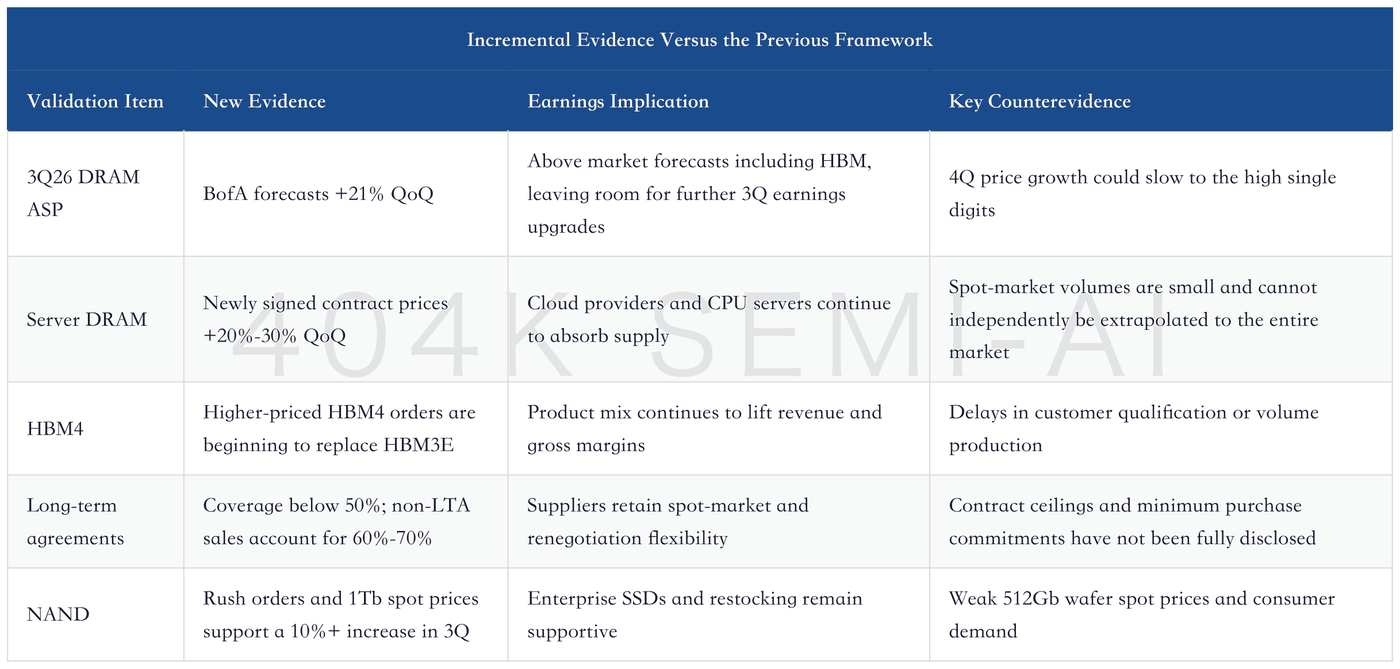
Concerns about 3Q26 DRAM results falling short may be premature. BofA forecasts a 21% QoQ increase in global DRAM average selling prices (ASPs), above TrendForce’s 13%-18% estimate for conventional DRAM and 8%-13% including high-bandwidth memory (HBM). Pricing momentum is clearly moderating from 2Q26, but server contract prices, July spot prices, and rush orders all indicate that the earnings plateau remains elevated.
Server DRAM and HBM4 provide the strongest demand evidence. Newly signed server DRAM contract prices rose 20%-30% QoQ, above market expectations of less than 20%; higher-priced HBM4 orders are beginning to replace HBM3E. AI demand is not only increasing HBM consumption but also crowding out conventional DRAM wafer capacity, keeping both DDR5 and mature DDR4 supply tight.
Long-term agreements have not fully capped price increases. BofA’s channel checks indicate that long-term agreements cover less than 50% of total shipments, while non-LTA sales still account for 60%-70%; even within LTAs, prices are rising 5%-10% QoQ. Memory earnings have not been capped by fixed pricing. The key variables are contract coverage, renegotiation frequency, and minimum purchase commitments.
NAND prices can still rise, but the evidence is weaker than for DRAM. Spot prices for 1Tb wafers rose 4% in one week, while rush orders from some OEMs support a more than 10% increase in 3Q26 NAND ASPs. However, 512Gb wafer spot prices remain weak, and contract prices rose only 1%-5% per month from April to July. NAND upside depends more on enterprise SSDs, inventory restocking, and product mix than on a market-wide shortage.
Capex is strong, but end demand is not uniformly improving. TSMC raised its 2026 capex guidance to US$60bn-US$64bn, while ASML also issued strong guidance for the second half. Korean semiconductor exports and the value of China’s integrated-circuit imports increased sharply, but Chinese smartphone shipments fell 4.3% YoY in 2Q26. Supply-chain conditions remain robust, while consumer tolerance for higher prices is entering a validation phase.
What This Report Actually Changes
The market had already accepted the sharp surge in memory prices during 2Q26. The debate was whether momentum would fade rapidly in 3Q26. BofA’s new evidence does not dispute that price increases are slowing; instead, it raises the post-deceleration plateau. Global DRAM ASPs could still rise 21% QoQ in 3Q26, rather than merely low single digits. NAND could also rise more than 10%, rather than immediately flattening or declining.
This distinction matters for earnings expectations. The strong 2Q26 increase is already embedded in the base. For share prices to continue rising, investors need more than a repetition of the “memory shortage” narrative; they need evidence that actual 3Q26 transaction prices remain above sell-side models. BofA’s data on server contract prices, non-LTA pricing, HBM4 orders, and emergency procurement provide precisely that evidence.
Global Memory Deep Dive: DRAM +74%, NAND +60%, LTA Contracts and Post-Deceleration 3Q Earnings Validation
The previous round of checks had already confirmed that 2Q26 price increases were steep and that 3Q26 momentum would slow. The value of this new report is that it shows a lower slope does not yet imply a collapsing price plateau. The memory trade is shifting from calling the direction to validating transaction prices and contract quality.
Why DRAM Remains Stronger Than NAND
Server DRAM is the most important incremental driver. BofA’s channel checks show that newly negotiated prices rose 20%-30% QoQ, above consensus expectations. Meanwhile, DDR5 and DDR4 spot prices have risen for eight consecutive weeks. Spot prices for 16Gb DDR5 and 16Gb DDR4 reached approximately US$49.2 and US$80.1, respectively, up 28% and 16% from the prior quarter. Spot supply represents only a low-single-digit share of global supply and therefore cannot directly represent all contract pricing. However, OEMs have begun using rush orders to replenish inventories, indicating that elevated prices are not merely indicative quotes in a small market.
HBM4 provides additional product-mix support. Rising orders for higher-priced HBM4 mean the same wafer input can generate more revenue. As memory manufacturers continue prioritizing HBM and server DRAM, supply of conventional DDR5, DDR4, and certain mature products will be slower to recover. DDR4 has even lost its discount to DDR5, reflecting the combined impact of discontinued production and customer restocking rather than natural clearance pricing during a technology transition.
Long-term agreements are also more flexible than the market assumes. BofA estimates that related shipments account for less than 50% of total volume, while non-LTA sales account for 60%-70%; prices on some LTA orders can still rise 5%-10% QoQ. Contracts improve revenue visibility without eliminating suppliers’ pricing flexibility. Future disclosures need to answer four questions: how much volume is covered, how often pricing is renegotiated, whether there is a price floor, and whether customers can cancel.
NAND Can Rise More Than 10%, but It Should Not Be Assessed Like DRAM
NAND signals improved in July, but the structure is less consistent than in DRAM. Spot prices for 1Tb wafers rose 4% in one week, while emergency procurement by some OEMs pointed to quarterly price changes exceeding 20%. BofA therefore believes 3Q26 NAND ASPs could still rise more than 10%. Client SSD pricing is also strong, with prices for 256GB, 512GB, and 1TB products in June 2026 roughly double their end-2025 levels.
However, the wafer market has not strengthened uniformly. In the first half of July, 512Gb wafer spot prices fell 1% WoW and 9% from the prior quarter. Contract prices were approximately US$26—around 10 times the February 2025 low—but increased by only 1%-5% per month from April through July. This indicates that NAND earnings support primarily comes from enterprise SSDs, mobile storage, and inventory restocking, while module manufacturers have become more cautious about purchasing high-priced bare wafers.
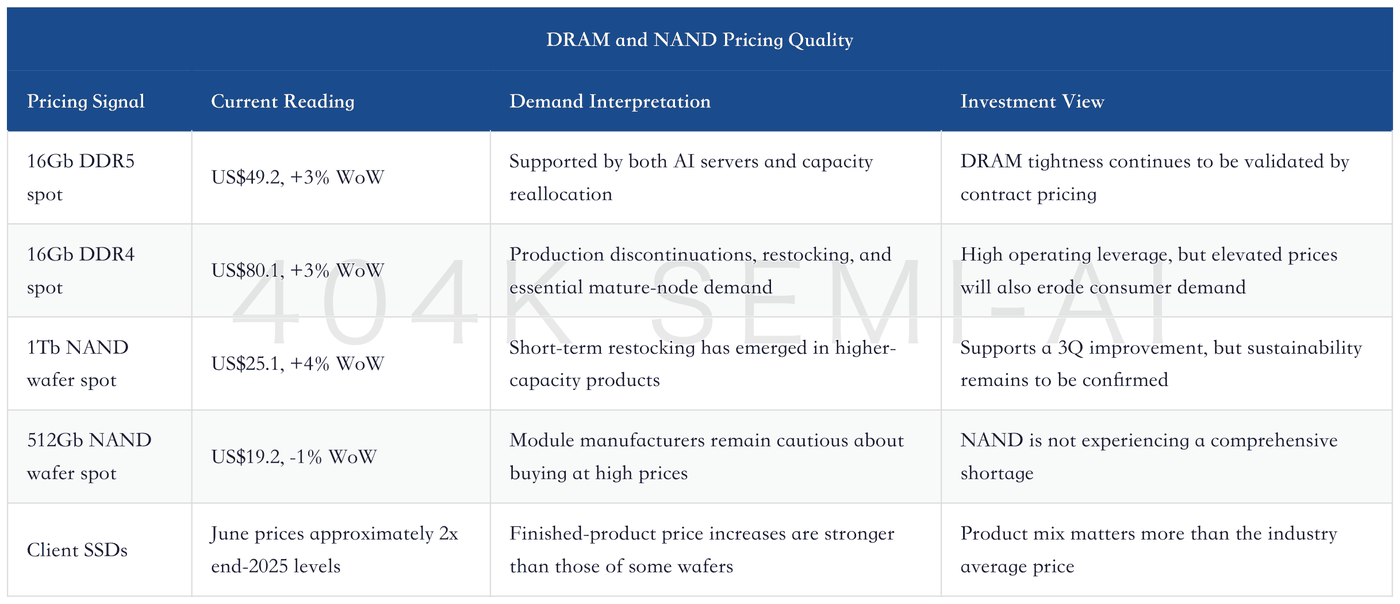
DRAM therefore resembles a market where capacity is being persistently crowded out by higher-value products, while NAND resembles one where high-value applications remain strong but conventional wafers are already diverging. If enterprise SSD capacity continues expanding, NAND earnings can rise further. If enterprise demand also begins resisting higher prices, wafer weakness will feed through to ASPs more quickly.
